TITLE
39
Taxation
PROPERTY
TAX
General and Administrative
Art. 1. General Provisions, 39-1-101 to
39-1-125.
Art. 1.5. Prepayment of Ad Valorem Taxes, 39-1.5-101
to 39-1.5-107.
Art. 2. Division of Property Taxation -
Administrator - Board, 39-2-101 to 39-2-131.
Exemptions
Art. 3. Exemptions, 39-3-101 to 39-3-211.
Deferrals
Art. 3.5. Tax Deferral for the Elderly and
Military Personnel, 39-3.5-101 to 39-3.5-119.
Art. 3.7. Property Tax Work-off Program for
the Elderly, 39-3.7-101 to 39-3.7-102.
Art. 3.9. Optional Nongaming Property Tax
Deferral Plan (Repealed).
Valuation and Taxation
Art. 4. Valuation of Public Utilities, 39-4-101
to 39-4-109.
Art. 4.1. Valuation and Assessment of Rail
Transportation Property (Repealed).
Art. 5. Valuation and Taxation, 39-5-101 to
39-5-205.
Art. 6. Valuation of Mines, 39-6-101 to
39-6-117.
Art. 7. Valuation of Oil and Gas Leaseholds
and Lands, 39-7-101 to 39-7-110.
Equalization
Art. 8. County Boards of Equalization,
39-8-101 to 39-8-109.
Art. 9. State Board of Equalization,
39-9-101 to 39-9-109.
Collection and Redemption
Art. 10. Collection, 39-10-101 to 39-10-116.
Art. 11. Sale of Tax Liens, 39-11-100.3 to
39-11-153.
Art. 11.5. Issuance of Treasurer's Deeds,
39-11.5-101 to 39-11.5-602.
Art. 12. Redemption, 39-12-102 to 39-12-113.
Conveyancing and Evidence of Title
Art. 13. Documentary Fee on Conveyances of
Real Property, 39-13-101 to 39-13-108.
Art. 14. Real Property Transfer Information,
39-14-101 to 39-14-103.
SPECIFIC
TAXES
General and Administrative
Art. 20. Enforcement of Tax Liens, 39-20-101
to 39-20-107.
Art. 21. Procedure and Administration,
39-21-101 to 39-21-405.
Income Tax
Art. 22. Income Tax, 39-22-101 to
39-22-5708.
Estate and Inheritance and
Succession Tax
Art. 23. Inheritance and Succession Tax
(Repealed).
Art. 23.5. Colorado Estate Tax, 39-23.5-101 to
39-23.5-117.
Art. 24. Interstate Compromise, Arbitration
- Inheritance Tax, 39-24-101 to 39-24-114.
Gift Tax
Art. 25. Gift Tax (Repealed).
Sales and Use Tax
Art. 26. Sales and Use Tax, 39-26-101 to
39-26-901.
Art. 26.1. Colorado Tourism Promotion Fund Tax
(Repealed).
Gasoline and Special Fuel Tax
Art. 27. Gasoline and Special Fuel Tax,
39-27-101 to 39-27-310.
Tobacco Tax
Art. 28. Cigarette Tax, 39-28-101 to
39-28-401.
Art. 28.5. Tax on Tobacco Products,
39-28.5-101 to 39-28.5-112.
Art. 28.6. Nicotine Products Tax, 39-28.6-101
to 39-28.6-112.
Controlled Substances Tax
Art. 28.7. Controlled Substances Tax
(Repealed).
Art. 28.8. Taxes on Marijuana and Marijuana
Products, 39-28.8-101 to 39-28.8-502.
Severance Tax
Art. 29. Severance Tax, 39-29-101 to
39-29-116.
Enterprise Zones
Art. 30. Urban and Rural Enterprise Zone
Act, 39-30-101 to 39-30-112.
Art. 30.5. Rural Jump-start Zone Act,
39-30.5-101 to 39-30.5-108.
Assistance for the Elderly or
Disabled
Art. 31. Property Tax - Rent - Heat or Fuel
- Assistance for the Elderly or Disabled, 39-31-101 to 39-31-105.
Rural Technology Enterprise Zone
Act
Art. 32. Rural Technology Enterprise Zone
Act, 39-32-101 to 39-32-107.
Alternative Fuels Rebate
Art. 33. Alternative Fuels Rebate
(Repealed).
Taxation Commission
Art. 34. Colorado Commission on Taxation
(Repealed).
Aviation Development Zone Act
Art. 35. Aviation Development Zone Act
(Repealed).
CHIPS Zone Act
Art. 36. CHIPS Zone Act, 39-36-101 to
39-36-107.
Firearms and Ammunition Excise Tax
Art. 37. Firearms and Ammunition Excise Tax,
39-37-101 to 39-37-302.
PROPERTY
TAX
General
and Administrative
Editor's
note: Articles 1
to 4, part 1 of article 5, and articles 6 to 12 of this title were numbered as
articles 1 to 12 of chapter 137, C.R.S. 1963. These articles and part 1 were
repealed and reenacted in 1964, resulting in the addition, relocation, or
elimination of sections as well as subject matter. For amendments to these
articles and part 1 prior to 1964, consult the Colorado statutory research
explanatory note beginning on page vii in the front of this volume.
ARTICLE
1
General
Provisions
39-1-101. Legislative declaration.
39-1-101.5. Legislative declaration - taxpayer
rights.
39-1-102. Definitions.
39-1-103. Actual value determined - when -
legislative declaration.
39-1-103.5. Restrictions on information.
39-1-103.8. Valuation for assessment - future
increases. (Repealed)
39-1-104. Valuation for assessment -
definitions.
39-1-104.1. Implementation costs - annual
revaluation. (Repealed)
39-1-104.2. Residential real property -
valuation for assessment - legislative declaration - definitions.
39-1-104.3. Partial real property tax
reductions - residential property - definitions - repeal. (Repealed)
39-1-104.4. Adjustment of residential rate.
(Repealed)
39-1-104.5. Severed mineral interest -
placement on tax roll.
39-1-104.6. Qualified-senior primary residence
real property - valuation for assessment - reimbursement to local governments
for reduced valuation - temporary mechanism for refunding excess state revenues
- legislative declaration - definitions.
39-1-104.7. Total program balancing adjustment
of residential rate - definitions. (Repealed)
39-1-105. Assessment date.
39-1-105.5. Reappraisal ordered based on
valuation for assessment study - state school finance payments.
39-1-106. Partial interests not subject to
separate tax.
39-1-107. Tax liens.
39-1-108. Payment of taxes - grantor and
grantee.
39-1-109. Taxes paid by mortgagee - effect.
39-1-110. Notice - formation of political
subdivision - boundary change of special district.
39-1-111. Taxes levied by board of county
commissioners.
39-1-111.5. Temporary property tax credits and
temporary mill levy rate reductions.
39-1-112. Taxes available - when.
39-1-113. Abatement and refund of taxes.
39-1-114. Who may administer oath.
39-1-115. Records prima facie evidence.
39-1-116. Penalty for divulging confidential
information.
39-1-117. Prior actions not affected.
39-1-118. Repeal of law levying state
property tax - disposition of funds.
39-1-119. Funds held for payment of taxes -
refund - reduction and increase of amounts - penalty.
39-1-119.5. Funds collected by lessors of
personal property for payments of taxes - refund - damages.
39-1-120. Filing - when deemed to have been
made.
39-1-121. Expression of rate of property
taxation in dollars per thousand dollars of valuation for assessment -
definitions.
39-1-122. Interim task force to study
property tax assessment - classification - land used for agricultural and other
purposes - 2010 interim - legislative declaration - repeal. (Repealed)
39-1-123. Property tax reimbursement -
property destroyed by natural cause - repeal. (Repealed)
39-1-124. Mailing required to be sent by
county assessor or treasurer - reasonable certainty mailing will not be
delivered.
39-1-125. Tax and levy rate information
publicly available.
39-1-101. Legislative declaration.
The
general assembly declares that its purpose in enacting articles 1 to 13 of this
title is to exercise the authority granted in section 3 of article X of the
state constitution wherein it is provided, among other things, that "the
actual value of all real and personal property not exempt from taxation under
this article shall be determined under general laws, which shall prescribe such
methods and regulations as shall secure just and equalized valuations for
assessment of all real and personal property not exempt from taxation under
this article". It further declares that it intends to fix the percentage
of such determined actual value at which all such property shall be assessed
for taxation. It further declares that the actual value of certain classes of
real property may not be able to be determined after appropriate consideration
of the three approaches to value; therefore, it is incumbent upon the general
assembly to provide for a means to determine the actual value of such taxable
property, and, to effect this result, the general assembly hereby finds and
declares that, when appropriate consideration of the three approaches to value
fails to derive an actual value for such property, the actual value of such
property shall be determined by comparison of the surface use of such property
to property with a similar surface use. It further declares that the actual
value of nonproducing oil, gas, and oil and gas mineral interests shall be
determined by the income approach capitalizing annual net rental income at an
appropriate market rate. To these ends, the provisions of said articles shall
be strictly construed.
Source:
L. 64: R&RE,
p. 675, § 1. C.R.S. 1963: § 137-1-2. L. 83: Entire section
amended, p. 1480, § 1, effective April 22. L. 85: Entire section
amended, p. 1209, § 1, effective May 9.
ANNOTATION
This article does not
require an assessor to reevaluate real property when an unusual condition
occurs in the middle of a tax year. Larimer County BOE v. 1303 Frontage,
2023 CO 28, 531 P.3d 1012.
"Actual value" of
residential property must be determined using means and methods applied
impartially to all the members of each class, in order to reconcile the
requirement of article X, § 20, of the constitution that the market approach be
used for valuation with the equalization requirement of article X, § 3. Podoll
v. Arapahoe County Bd. of Equaliz., 920 P.2d 861 (Colo. App. 1995), rev'd on
other grounds, 935 P.2d 14 (Colo. 1997).
Statute does not prohibit
general assembly from adopting other statutes concerning imposition of property
taxes. Senior Corp. v. Bd. of Assessment Appeals, 702 P.2d 732 (Colo.
1985).
Reclassification from
residential to commercial property was just and equal where property was
used as a community center in a planned community development despite fact that
model homes used for commercial purposes in same county are classified as
residential. Mission Viejo v. Douglas Cty. Bd. of Equaliz., 881 P.2d 462 (Colo.
App. 1994).
Valuation was not just and
equal where county could offer no reasonable explanation why there was a
32.8% increase in the assessed value of plaintiffs' residences but only a
10.73% average increase as to the vast majority of comparable residences.
Podoll v. Arapahoe County Bd. of Equaliz., 920 P.2d 861 (Colo. App. 1995),
rev'd on other grounds, 935 P.2d 14 (Colo. 1997).
In determining whether a
valuation for assessment is just and equal under the "designed for
use" standard, actual use is only one factor to be considered. Mission
Viejo v. Douglas Cty. Bd. of Equaliz., 881 P.2d 462 (Colo. App. 1994).
Applied in City &
County of Denver v. Sec. Life & Accident Co., 173 Colo. 248, 477 P.2d 369
(1970).
39-1-101.5. Legislative declaration -
taxpayer rights.
The
general assembly hereby finds and declares that section 3 of article X of the
state constitution was approved in 1982 by the voters of Colorado in order to
ensure the fair and uniform valuation for assessment of real and personal
property located in Colorado; that, since the adoption of said constitutional
amendment, the property tax system in Colorado has developed into an impersonal
system which is more concerned with the mechanisms to levy and collect such
property tax than with the fair and courteous treatment of the owners of real
and personal property who pay such tax; that the purpose of the property tax
system is to raise revenues to be used for purposes which benefit the citizens
of Colorado, including such property owners; that property owners accept their
civic responsibility to pay their fair share of taxes to be used for such
purposes; that all levels of government involved in the property tax system
should recognize that they exist to serve their citizens; and that the owners
of real and personal property should be accorded the respect and courtesy which
they deserve and should be provided such services which are necessary to assist
them in complying with the property tax laws of this state.
Source:
L. 88: Entire
section added, p. 1276, § 1, effective January 1, 1989.
39-1-102. Definitions.
As used in
articles 1 to 13 of this title 39, unless the context otherwise requires:
(1)
"Administrator" means the property tax administrator.
(1.1)
(a) "Agricultural and livestock products" means plant or animal
products in a raw or unprocessed state that are derived from the science and
art of agriculture, regardless of the use of the product after its sale and
regardless of the entity that purchases the product. "Agriculture",
for the purposes of this subsection (1.1), means farming, ranching, animal
husbandry, and horticulture.
(b) On
and after January 1, 2023, for the purposes of this subsection (1.1),
"agricultural and livestock products" includes crops grown within a
controlled environment agricultural facility in a raw or unprocessed state for
human or livestock consumption. For the purposes of this subsection (1.1)(b),
"agricultural and livestock products" does not include marijuana, as
defined in section 18-18-102 (18)(a), or any other nonfood crop agricultural
products.
(1.3)
"Agricultural equipment that is used on the farm or ranch or in a CEA
facility in the production of agricultural products":
(a)
Means any personal property used on a farm or ranch, as defined in subsections
(3.5) and (13.5) of this section, for planting, growing, and harvesting
agricultural products or for raising or breeding livestock for the primary
purpose of obtaining a monetary profit; and
(b)
Includes:
(I) Any
mechanical system used on the farm or ranch for the conveyance and storage of
animal products in a raw or unprocessed state, regardless of whether or not
such mechanical system is affixed to real property;
(II)
Silviculture personal property that is designed, adapted, and used for the
planting, growing, maintenance, or harvesting of trees in a raw or unprocessed
state;
(III)
Any personal property within a facility, whether attached to a building or not,
that is capable of being removed from the facility, and is used in direct
connection with the operation of a controlled environment agricultural
facility, which facility is used solely for planting, growing, or harvesting
crops in a raw or unprocessed state; and
(IV)
Any personal property within a greenhouse, whether attached to the greenhouse
or not, that is capable of being removed from the greenhouse and is used in
direct connection with the operation of a greenhouse, which greenhouse is used
solely for planting or growing crops in a raw or unprocessed state, and the
sole purpose of growing crops in the greenhouse is to obtain a monetary profit
from the wholesale of plant-based food for human or livestock consumption.
(1.6)
(a) "Agricultural land", whether used by the owner of the land or
a lessee, means one of the following:
(I) (A)
A parcel of land, whether located in an incorporated or unincorporated area and
regardless of the uses for which such land is zoned, that was used the previous
two years and presently is used as a farm or ranch, as defined in subsections
(3.5) and (13.5) of this section, or that is in the process of being restored
through conservation practices. Such land must have been classified or eligible
for classification as "agricultural land", consistent with this
subsection (1.6), during the ten years preceding the year of assessment. Such
land must continue to have actual agricultural use. "Agricultural
land" under this subparagraph (I) shall not include two acres or less of
land on which a residential improvement is located unless the improvement is
integral to an agricultural operation conducted on such land.
"Agricultural land" also includes the land underlying other
improvements if such improvements are an integral part of the farm or ranch and
if such other improvements and the land area dedicated to such other
improvements are typically used as an ancillary part of the operation. The use
of a portion of such land for hunting, fishing, or other wildlife purposes, for
monetary profit or otherwise, shall not affect the classification of
agricultural land. For purposes of this subparagraph (I), a parcel of land
shall be "in the process of being restored through conservation
practices" if: The land has been placed in a conservation reserve program
established by the natural resources conservation service pursuant to 7 U.S.C.
secs. 1 to 5506; or a conservation plan approved by the appropriate
conservation district has been implemented for the land for up to a period of
ten crop years as if the land has been placed in such a conservation reserve
program.
(B) A
residential improvement shall be deemed to be "integral to an agricultural
operation" for purposes of sub-subparagraph (A) of this subparagraph (I)
if an individual occupying the residential improvement either regularly
conducts, supervises, or administers material aspects of the agricultural
operation or is the spouse or a parent, grandparent, sibling, or child of the
individual.
(II) A
parcel of land that consists of at least forty acres, that is forest land, that
is used to produce tangible wood products that originate from the productivity
of such land for the primary purpose of obtaining a monetary profit, that is
subject to a forest management plan, and that is not a farm or ranch, as
defined in subsections (3.5) and (13.5) of this section. "Agricultural
land" under this subparagraph (II) includes land underlying any
residential improvement located on such agricultural land.
(III) A
parcel of land that consists of at least eighty acres, or of less than eighty
acres if such parcel does not contain any residential improvements, and that is
subject to a perpetual conservation easement, if such land was classified by
the assessor as agricultural land under subparagraph (I) or (II) of this
paragraph (a) at the time such easement was granted, if the grant of the
easement was to a qualified organization, if the easement was granted
exclusively for conservation purposes, and if all current and contemplated
future uses of the land are described in the conservation easement.
"Agricultural land" under this subparagraph (III) does not include
any portion of such land that is actually used for nonagricultural commercial
or nonagricultural residential purposes.
(IV) A
parcel of land, whether located in an incorporated or unincorporated area and
regardless of the uses for which such land is zoned, used as a farm or ranch,
as defined in subsections (3.5) and (13.5) of this section, if the owner of the
land has a decreed right to appropriated water granted in accordance with
article 92 of title 37, C.R.S., or a final permit to appropriated groundwater
granted in accordance with article 90 of title 37, C.R.S., for purposes other
than residential purposes, and water appropriated under such right or permit
shall be and is used for the production of agricultural or livestock products
on such land;
(V) A
parcel of land, whether located in an incorporated or unincorporated area and
regardless of the uses for which such land is zoned, that has been reclassified
from agricultural land to a classification other than agricultural land and
that met the definition of agricultural land as set forth in subparagraphs (I)
to (IV) of this paragraph (a) during the three years before the year of
assessment. For purposes of this subparagraph (V), the parcel of land need not
have been classified or eligible for classification as agricultural land during
the ten years preceding the year of assessment as required by subparagraph (I)
of this paragraph (a).
(b) (I)
Except as provided in subparagraph (II) of this paragraph (b), all other
agricultural property that does not meet the definition set forth in paragraph
(a) of this subsection (1.6) shall be classified as all other property and
shall be valued using appropriate consideration of the three approaches to
appraisal based on its actual use on the assessment date.
(II) On
and after January 1, 2015, "all other agricultural property" includes
greenhouse and nursery production areas used to grow food products,
agricultural products, or horticultural stock for wholesale purposes only that
originate above the ground.
(c) An
assessor must determine, based on sufficient evidence, that a parcel of land
does not qualify as agricultural land, as defined in subparagraph (IV) of
paragraph (a) of this subsection (1.6), before land may be changed from
agricultural land to any other classification.
(d)
Notwithstanding any other provision of law to the contrary, property that is
used solely for the cultivation of medical marijuana shall not be classified as
agricultural land.
(2)
"Assessor" means the elected assessor of a county, or his or her
appointed successor, and, in the case of the city and county of Denver, such
equivalent officer as may be provided by its charter, and, in the case of the
city and county of Broomfield, such equivalent officer as may be provided by
its charter or code.
(2.5)
"Bed and breakfast" means an overnight lodging establishment, whether
owned by a natural person or any legal entity, that is a residential dwelling
unit or an appurtenance thereto, in which the innkeeper resides, or that is a
building designed but not necessarily occupied as a single family residence
that is next to, or directly across the street from, the innkeeper's residence,
and in either circumstance, in which:
(a)
Lodging accommodations are provided for a fee;
(b) At
least one meal per day is provided at no charge other than the fee for the
lodging accommodations; and
(c)
There are not more than thirteen sleeping rooms available for transient guests.
(3)
"Board" means the board of assessment appeals.
(3.1)
"Commercial lodging area" means a guest room or a private or shared
bathroom within a bed and breakfast that is offered for the exclusive use of
paying guests on a nightly or weekly basis. Classification of a guest room or a
bathroom as a "commercial lodging area" shall be based on whether at
any time during a year such rooms are offered by an innkeeper as nightly or
weekly lodging to guests for a fee. Classification shall not be based on the
number of days that such rooms are actually occupied by paying guests.
(3.2)
"Conservation purpose" means any of the following purposes as set
forth in section 170 (h) of the federal "Internal Revenue Code of
1986", as amended:
(a) The
preservation of land areas for outdoor recreation, the education of the public,
or the protection of a relatively natural habitat for fish, wildlife, plants,
or similar ecosystems; or
(b) The
preservation of open space, including farmland and forest land, where such
preservation is for the scenic enjoyment of the public or is pursuant to a
clearly delineated federal, state, or local government conservation policy and
where such preservation will yield a significant public benefit.
(3.3)
"Controlled environment agricultural facility" or "CEA
facility" means a nonresidential structure and related equipment and
appurtenances that combines engineering, horticultural science, and
computerized management techniques to optimize hydroponics, plant quality, and
food production efficiency from the land's water for human or livestock
consumption. The sole purpose of growing crops in a CEA facility is to obtain a
monetary profit from the wholesale of plant-based food for human or livestock
consumption.
(3.5) [Editor's
note: This version of subsection (3.5) is effective until January 1, 2027.]
"Farm" means a parcel of land which is used to produce agricultural
products that originate from the land's productivity for the primary purpose of
obtaining a monetary profit.
(3.5) [Editor's
note: This version of subsection (3.5) is effective January 1, 2027.]
"Farm" means a parcel of land that is predominantly used to produce
agricultural products that originate from the land's productivity for the
primary purpose of obtaining a monetary profit.
(3.7)
"Fee simple estate" means the largest possible estate allowed by law,
an estate that has potentially infinite duration.
(4)
"Fixtures" means those articles which, although once movable
chattels, have become an accessory to and a part of real property by having
been physically incorporated therein or annexed or affixed thereto.
"Fixtures" includes systems for the heating, air conditioning,
ventilation, sanitation, lighting, and plumbing of such building.
"Fixtures" does not include machinery, equipment, or other articles
related to a commercial or industrial operation which are affixed to the real
property for proper utilization of such articles. In addition, for property tax
purposes only, "fixtures" does not include security devices and
systems affixed to any residential improvements, including but not limited to
security doors, security bars, and alarm systems.
(4.3)
"Forest land" means land of which at least ten percent is stocked by
forest trees of any size and includes land that formerly had such tree cover
and that will be naturally or artificially regenerated. "Forest land"
includes roadside, streamside, and shelterbelt strips of timber which have a
crown width of at least one hundred twenty feet. "Forest land"
includes unimproved roads and trails, streams, and clearings which are less
than one hundred twenty feet wide.
(4.4)
"Forest management plan" means an agreement which includes a plan to
aid the owner of forest land in increasing the health, vigor, and beauty of
such forest land through use of forest management practices and which has been
either executed between the owner of forest land and the Colorado state forest
service or executed between the owner of forest land and a professional
forester and has been reviewed and has received a favorable recommendation from
the Colorado state forest service. The Colorado forest service shall annually
inspect each parcel of land subject to a forest management plan to determine if
the terms and conditions of such plan are being complied with and shall report
by March 1 of each year to the assessor in each affected county the legal
descriptions of the properties and the names of their owners that are eligible
for the agricultural classification. The report shall also contain the legal
descriptions of those properties and the names of their owners that no longer
qualify for the agricultural classification because of noncompliance with their
forest management plans. No property shall be entitled to the agricultural
classification unless the legal description and the name of the owner appear on
the report submitted by the Colorado state forest service. The Colorado state
forest service shall charge a fee for the inspection of each parcel of land in
such amount for the reasonable costs incurred by the Colorado state forest
service in conducting such inspections. Such fee shall be paid by the owner of
such land prior to such inspection. Any fees collected pursuant to this
subsection (4.4) shall be subject to annual appropriation by the general
assembly.
(4.5)
"Forest management practices" means practices accepted by
professional foresters which control forest establishment, composition,
density, and growth for the purpose of producing forest products and associated
amenities following sound business methods and technical forestry principles.
(4.6)
"Forest trees" means woody plants which have a well-developed stem or
stems, which are usually more than twelve feet in height at maturity, and which
have a generally well-defined crown.
(5)
Repealed.
(5.5)
(a) "Hotels and motels" means improvements and the land associated
with such improvements that are used by a business establishment primarily to
provide lodging, camping, or personal care or health facilities to the general
public and that are predominantly used on an overnight or weekly basis; except
that "hotels and motels" does not include:
(I) A
residential unit, except for a residential unit that is a hotel unit;
(II) A
residential unit that would otherwise be classified as a hotel unit if the
residential unit is held as inventory by a developer primarily for sale to
customers in the ordinary course of the developer's trade or business, is
marketed for sale by the developer, and either has been held by the developer
for less than two years since the certificate of occupancy for the residential
unit has been issued or is not depreciated under the internal revenue code, as
defined in section 39-22-103 (5.3), while owned by the developer; or
(III) A
residential unit that would otherwise be classified as a hotel unit if the
residential unit has been acquired by a lender or an owners' association
through foreclosure, a deed in lieu of foreclosure, or a similar transaction,
is marketed for sale by the lender or owners' association and is not
depreciated under the internal revenue code, as defined in section 39-22-103
(5.3), while owned by the lender or owners' association.
(IV)
Repealed.
(b) If
any time share estate, time share use period, undivided interest, or other
partial ownership interest in any hotel unit is owned by any non-hotel unit
owner, then, unless a declaration or other express agreement binding on the
non-hotel unit owners and the hotel unit owners provides otherwise:
(I) The
hotel unit owners shall pay the taxes on the hotel unit not required to be paid
by the non-hotel unit owners pursuant to subparagraph (II) of this paragraph
(b).
(II)
Each non-hotel unit owner shall pay that portion of the taxes on the hotel unit
equal to the non-hotel unit owner's ownership or usage percentage of the hotel
unit multiplied by the property tax that would have been levied on the hotel
unit if the actual value and valuation for assessment of the hotel unit had
been determined as if the hotel unit was residential real property.
(III)
For purposes of determining the amount due from any hotel unit owner or
non-hotel unit owner pursuant to subparagraph (II) of this paragraph (b), the
assessor shall, upon the request of any hotel unit owner or non-hotel unit
owner, calculate the property tax that would have been levied on the hotel unit
if the actual value and valuation for assessment of the hotel unit had been
determined as if the hotel unit were residential real property. A hotel unit
owner or non-hotel unit owner may petition the county board of equalization for
review of the assessor's calculation pursuant to the procedures set forth in
section 39-10-114. Any appeal from the decision of the county board shall be
governed by section 39-10-114.5.
(c) As
used in this subsection (5.5):
(I)
"Condominium unit" means a unit, as defined in section 38-33.3-103
(30), C.R.S., and also includes a time share unit.
(II)
"Hotel unit owners" means any person or member of a group of related
persons whose ownership and use of a residential unit cause the residential
unit to be classified as a hotel unit.
(III)
"Hotel units" means more than four residential unit ownership
equivalents in a project that are owned, in whole or in part, directly, or
indirectly through one or more intermediate entities, by one person or by a
group of related persons if the person or group of related persons uses the
residential units or parts thereof in connection with a business establishment
primarily to provide lodging, camping, or personal care or health facilities to
the general public predominantly on an overnight or weekly basis. "Hotel
unit" means any residential unit included in hotel units. For purposes of
this subparagraph (III):
(A)
"Control" means the power to direct the business or affairs of an
entity through direct or indirect ownership of stock, partnership interests,
membership interests, or other forms of beneficial interests.
(B)
"Related persons" means individuals who are members of the same
family, including only spouses and minor children, or persons who control, are
controlled by, or are under common control with each other. Persons are not
related persons solely because they engage a common agent to manage or rent
their residential units, they are members of an owners' association or similar
group, they enter into a tenancy in common or a similar agreement with respect
to undivided interests in a residential unit, or any combination of the
foregoing.
(IV)
"Project" means one or more improvements that contain residential
units if the boundaries of the residential units are described in or determined
by the same declaration, as defined in section 38-33.3-103 (13), C.R.S.
(V)
"Residential unit" means a condominium unit, a single family
residence, or a townhome.
(VI)
"Non-hotel unit owner" means any owner of a time share estate, time
share use period, undivided interest, or other partial ownership interest in
any hotel unit who is not a hotel unit owner with respect to the hotel unit.
(VII)
"Residential unit ownership equivalent" means:
(A) In
the case of time share units, time share interests or time share use periods in
one or more time share units that in the aggregate entitle the owner of such
time share interests or time share use periods to three hundred sixty-five days
of use in any calendar year or three hundred sixty-six days of use in any
calendar year that is a leap year; and
(B) In
the case of residential units other than time share units, undivided interests
or other ownership interests in one or more such residential units that total
one hundred percent. For purposes of this sub-subparagraph (B), any undivided
interest or other ownership interest not stated in terms of a percentage of
total ownership shall be converted to a percentage of total ownership based on
the rights accorded to the holder of the undivided interest or other ownership
interest.
(VIII)
"Time share unit" means a condominium unit that is divided into time
share estates as defined in section 38-33-110 (5) or that is subject to a time
share use as defined in section 12-10-501 (4).
(5.6)
"Hotels and motels" as defined in subsection (5.5) of this section
shall not include bed and breakfasts.
(6)
"Household furnishings" means that personal property, other than
fixtures, in residential structures and buildings which is not used for the
production of income at any time.
(6.2)
"Hydroponics" means a system in which water soluble primary or
secondary plant nutrients or micronutrients, or a combination of such
nutrients, are placed in intimate contact with a plant's root system that is
being grown in water or an inert supportive medium that supplies physical
support for the roots.
(6.3)
"Improvements" means all structures, buildings, fixtures, fences, and
water rights erected upon or affixed to land, whether or not title to such land
has been acquired.
(6.8)
"Independently owned residential solar electric generation facility"
means personal property that:
(a) Is
located on residential real property;
(b) Is
owned by a person other than the owner of the residential real property;
(c) Is
installed on the customer's side of the meter;
(d) Is
used to produce electricity from solar energy primarily for use in the
residential improvements located on the residential real property; and
(e) Has
a production capacity of no more than one hundred kilowatts.
(7)
(Deleted by amendment, L. 2010, (HB 10-1267), ch. 425, p. 2198, § 1, effective
August 11, 2010.)
(7.1)
"Innkeeper" means the owner, operator, or manager of a bed and
breakfast.
(7.2)
"Inventories of merchandise and materials and supplies which are held for
consumption by a business or are held primarily for sale" means those
classes of personal property which are held primarily for sale by a business,
farm, or ranch, including components of personal property to be held for sale,
or which are held for consumption by a business, farm, or ranch, or which are
rented for thirty days or less. For the purposes of this subsection (7.2),
"personal property rented for thirty days or less" means personal
property rented for thirty days or less which can be returned at the option of
the person renting the property, in a transaction on which the sales or use tax
is actually collected before being finally sold, whether or not such personal
property is subject to depreciation. It is the purpose of the general assembly
to exempt "personal property rented for thirty days or less" from
property tax because of the similarity of such property to inventories of
merchandise held by retail stores. Further, the general assembly intends this
exemption to encompass a transaction under a rental agreement in which the
customer pays rent in order to use an item for a brief period of time; it is
not intended to encompass an equipment lease contract covering a specific
period of time and which includes financial penalties for early cancellation.
Except for "personal property rented for thirty days or less", the
term "inventories of merchandise and materials and supplies which are held
for consumption by a business or are held primarily for sale" does not
include personal property which is held for rent or lease or is subject to an
allowance for depreciation. For property tax years commencing on or after
January 1, 1984, the term does include inventory which is owned by and which is
in the possession of the manufacturer of such inventory unless:
(a)
Such inventory is in the possession of the manufacturer after having previously
been leased by the manufacturer to a customer; and
(b)
Such manufacturer has not designated such inventory for scrapping, substantial
reconditioning, renovating, or remanufacturing in accordance with its customary
practices. For the purposes of this paragraph (b), normal maintenance shall not
constitute substantial reconditioning, renovating, or remanufacturing.
(7.5)
Repealed.
(7.7)
"Livestock" includes all animals.
(7.8) "Manufactured
home" means any preconstructed building unit or combination of
preconstructed building units that:
(a)
Includes electrical, mechanical, or plumbing services that are fabricated,
formed, or assembled at a location other than the residential site of the
completed home;
(b) Is
designed and used for residential occupancy in either temporary or permanent
locations;
(c) Is
constructed in compliance with the "National Manufactured Housing
Construction and Safety Standards Act of 1974", 42 U.S.C. sec. 5401 et
seq., as amended;
(d)
Does not have motive power;
(e) Is
not licensed as a vehicle; and
(f) Is
eligible for a certificate of title pursuant to part 1 of article 29 of title
38, C.R.S.
(7.9)
"Minerals in place" means, without exception, metallic and
nonmetallic mineral substances of every kind while in the ground.
(8)
"Mobile home" means a manufactured home built prior to the adoption
of the "National Manufactured Housing Construction and Safety Standards
Act of 1974", 42 U.S.C. sec. 5401 et seq., as amended.
(8.3)
"Modular home" means any preconstructed factory-built building that:
(a) Is
ineligible for a certificate of title pursuant to part 1 of article 29 of title
38, C.R.S.;
(b) Is
not constructed in compliance with the "National Manufactured Housing
Construction and Safety Standards Act of 1974", 42 U.S.C. sec. 5401 et
seq., as amended; and
(c) Is
constructed in compliance with building codes adopted by the division of
housing in the department of local affairs.
(8.4)
"Natural cause" means fire, explosion, flood, tornado, action of the
elements, act of war or terror, or similar cause beyond the control of and not
caused by the party holding title to the property destroyed.
(8.5)
"Not for private gain or corporate profit" means the ownership and
use of property whereby no person with any connection to the owner thereof
shall receive any pecuniary benefit except for reasonable compensation for
services rendered and any excess income over expenses derived from the
operation or use of the property and all proceeds from the sale of the property
of the owner shall be devoted to the furthering of any exempt purpose.
(8.6)
(a) "Nursing home" means a nursing care facility, regardless of a
resident's length of stay, that is licensed by the department of public health
and environment under section 25-1.5-103 (1) and that meets the definition of a
nursing care facility as set forth in the department of public health and
environment regulations, including a nursing care facility that provides
convalescent care or rehabilitation services such as physical and occupational
therapy.
(b) As
used in this subsection (8.6), "nursing care facility" means a
licensed health care entity that is planned, organized, operated, and
maintained to provide supportive, restorative, and preventative services to
persons who, due to physical or mental disability, require continuous or
regular inpatient nursing care.
(8.7)
"Perpetual conservation easement" means a conservation easement in
gross, as described in article 30.5 of title 38, C.R.S., that qualifies as a
perpetual conservation restriction pursuant to section 170 (h) of the federal
"Internal Revenue Code of 1986", as amended, and any regulations
issued thereunder.
(9)
"Person" means natural persons, corporations, partnerships, limited
liability companies, associations, and other legal entities which are or may
become taxpayers by reason of the ownership of taxable real or personal
property.
(10)
"Personal effects" means such personal property as is or may be worn
or carried on or about the person, and such personal property as is usually
associated with the person or customarily used in personal hobby, sporting, or
recreational activities and which is not used for the production of income at
any time.
(11)
"Personal property" means everything that is the subject of ownership
and that is not included within the term "real property".
"Personal property" includes machinery, equipment, and other articles
related to a commercial or industrial operation that are either affixed or not
affixed to the real property for proper utilization of such articles. Except as
otherwise specified in articles 1 to 13 of this title, any pipeline,
telecommunications line, utility line, cable television line, or other similar
business asset or article installed through an easement, right-of-way, or
leasehold for the purpose of commercial or industrial operation and not for the
enhancement of real property shall be deemed to be personal property,
including, without limitation, oil and gas distribution and transmission
pipelines, gathering system pipelines, flow lines, process lines, and related
water pipeline collection, transportation, and distribution systems. Structures
and other buildings installed on an easement, right-of-way, or leasehold that
are not specifically referenced in this subsection (11) shall be deemed to be
improvements pursuant to subsection (6.3) of this section.
(12)
"Political subdivision" means any entity of government authorized by
law to impose ad valorem taxes on taxable property located within its
territorial limits.
(12.1) to
(12.4) Repealed.
(12.5)
"Professional forester" means any person who has received a
bachelor's or higher degree from an accredited school of forestry.
(13)
"Property" means both real and personal property.
(13.2)
"Qualified organization" means a qualified organization as defined in
section 170 (h)(3) of the federal "Internal Revenue Code of 1986", as
amended.
(13.5) [Editor's
note: This version of subsection (13.5) is effective until January 1, 2027.]
"Ranch" means a parcel of land which is used for grazing livestock
for the primary purpose of obtaining a monetary profit. For the purposes of
this subsection (13.5), "livestock" means domestic animals which are
used for food for human or animal consumption, breeding, draft, or profit.
(13.5) [Editor's
note: This version of subsection (13.5) is effective January 1, 2027.]
(a)
"Ranch" means a parcel of land that is predominantly used for grazing
livestock for the primary purpose of obtaining a monetary profit through a
pasture-based operation.
(b) For
the purposes of this subsection (13.5):
(I)
"Livestock" means domestic animals that are used for food for human
or animal consumption, breeding, draft, or profit; and
(II)
"Pasture-based operation" means a method of livestock management
where pasture-grazed livestock have regular access to open pasture and derive a
majority of their diet through grazing.
(14)
"Real property" means:
(a) All
lands or interests in lands to which title or the right of title has been
acquired from the government of the United States or from sovereign authority
ratified by treaties entered into by the United States, or from the state;
(b) All
mines, quarries, and minerals in and under the land, and all rights and
privileges thereunto appertaining; and
(c)
Improvements.
(14.3)
"Residential improvements" means a building, or that portion of a
building, designed for use predominantly as a place of residency by a person, a
family, or families. The term includes buildings, structures, fixtures, fences,
amenities, and water rights that are an integral part of the residential use.
The term also includes a manufactured home, a mobile home, a modular home, a
tiny home, and a nursing home as defined in subsection (8.6) of this section,
regardless of a resident's length of stay.
(14.4) (a)
(I) "Residential land" means a parcel of land upon which
residential improvements are located. The term also includes:
(A)
Land upon which residential improvements were destroyed by natural cause after
the date of the last assessment as established in section 39-1-104 (10.2);
(B) Two
acres or less of land on which a residential improvement is located where the
improvement is not integral to an agricultural operation conducted on such
land; and
(C) A
parcel of land without a residential improvement located thereon, if the parcel
is contiguous to a parcel of residential land that has identical ownership
based on the record title and contains a related improvement that is essential
to the use of the residential improvement located on the identically owned
contiguous residential land.
(II)
"Residential land" does not include any portion of the land that is
used for any purpose that would cause the land to be otherwise classified,
except as provided for in section 39-1-103 (10.5).
(III)
As used in this subsection (14.4):
(A)
"Contiguous" means that the parcels physically touch; except that
contiguity is not interrupted by an intervening local street, alley, or common
element in a common-interest community.
(B)
"Related improvement" means a driveway, parking space, or improvement
other than a building, or that portion of a building designed for use
predominantly as a place of residency by a person, a family, or families.
(b) (I)
Notwithstanding section 39-1-103 (5)(c) and except as provided in subparagraph
(II) of this paragraph (b), when residential improvements are destroyed,
demolished, or relocated as a result of a natural cause on or after January 1,
2010, that, were it not for their destruction, demolition, or relocation due to
such natural cause, would have qualified the land upon which the improvements
were located as residential land for the following property tax year, the
residential land classification shall remain in place for the year of
destruction, demolition, or relocation and the two subsequent property tax
years. The residential land classification may remain in place for additional
subsequent property tax years, not to exceed a total of five subsequent
property tax years, if the assessor determines there is evidence the owner
intends to rebuild or locate a residential improvement on the land. For
purposes of this determination, the assessor may consider, but shall not be
limited to considering, a building permit or other land development permit for
the land, construction plans for such residential improvement, efforts by the
owner to obtain financing for a residential improvement, or ongoing efforts to
settle an insurance claim related to the destruction, demolition, or relocation
of the residential improvement due to a natural cause.
(II)
The residential land classification of the land described in subparagraph (I)
of this paragraph (b) shall change according to current use if:
(A) A
new residential improvement or part of a new residential improvement is not
constructed or placed on the land in accordance with applicable land use
regulations prior to the January 1 after the period described in subparagraph
(I) of this paragraph (b), unless the property owner provides documentary
evidence to the assessor that during such period a good-faith effort was made
to construct or place a new or part of a new residential improvement on the
land but that additional time is necessary;
(B) The
assessor determines that the classification at the time of destruction,
demolition, or relocation as a result of a natural cause was erroneous; or
(C) A
change of use has occurred. For purposes of this sub-subparagraph (C), a change
of use shall not include the temporary loss of the residential use due to the
destruction, demolition, or relocation as a result of a natural cause of the
residential improvement.
(c) (I)
Notwithstanding section 39-1-103 (5)(c) and except as provided in subsection
(14.4)(c)(II) of this section, when residential improvements are destroyed,
demolished, or relocated on or after January 1, 2018, that, were it not for
their destruction, demolition, or relocation, would have qualified the land
upon which the improvements were located as residential land for the following
property tax year, the residential land classification shall remain in place
for the year of destruction, demolition, or relocation and one subsequent
property tax year if the assessor determines there is evidence that the owner
intends to rebuild or locate a residential improvement on the land. For
purposes of this determination, the assessor may consider, but is not limited
to considering, a building permit or other land development permit for the
land, construction plans for such residential improvement, or efforts by the
owner to obtain financing for a residential improvement.
(II)
The residential land classification of the land described in subsection
(14.4)(c)(I) of this section shall change according to current use if:
(A) A
new residential improvement or part of a new residential improvement is not
constructed or placed on the land in accordance with applicable land use
regulations prior to the January 1 after the period described in subsection
(14.4)(c)(I) of this section;
(B) The
assessor determines that the classification of the land at the time of the
destruction, demolition, or relocation was erroneous; or
(C) A
change of use has occurred. For purposes of this subsection (14.4)(c)(II)(C), a
change of use shall not include the temporary loss of the residential use due
to the destruction, demolition, or relocation of the residential improvement.
(14.5)
"Residential real property" means residential land and residential
improvements but does not include hotels and motels as defined in subsection
(5.5) of this section.
(15)
Repealed.
(15.5)
(a) "School" means:
(I) An
educational institution having a curriculum comparable to that of a publicly
supported elementary or secondary school or college, or any combination
thereof, and requiring daily attendance; or
(II) An
institution that is licensed as a child care center pursuant to part 3 of
article 5 of title 26.5 that is:
(A)
Operated by and as an integral part of a not-for-profit educational institution
that meets the requirements of subparagraph (I) of this paragraph (a); or
(B) A
not-for-profit institution that offers an educational program for not more than
six hours per day and that employs educators trained in preschool through
eighth grade educational instruction and is licensed by the appropriate state
agency and that is not otherwise qualified as a school under this paragraph (a)
or as a religious institution.
(b)
"School" includes any educational institution that meets the
requirements set forth in subparagraph (I) or (II) of paragraph (a) of this
subsection (15.5), even if such educational institution maintains hours of
operation in excess of the minimum hour requirements of section 22-32-109
(1)(n)(I), C.R.S.
(16)
"Taxable property" means all property, real and personal, not
expressly exempted from taxation by law.
(16.3)
"Tiny home" means a tiny home, as defined in section 24-32-3302 (35),
that is certified by the division of housing in the department of local affairs
to be designed for long-term residency and that is not registered in accordance
with article 3 of title 42.
(17)
"Treasurer" means the elected treasurer of a county or his or her
appointed successor, and, in the case of the city and county of Denver, such
equivalent officer as may be provided by its charter, in the case of the city
and county of Broomfield, such equivalent officer as may be provided by its
charter or code, and in the case of any home rule county, the treasurer or such
equivalent officer as provided by its charter.
(18)
"Works of art" means those items of personal property that are
original creations of visual art, including, but not limited to:
(a)
Sculpture, in any material or combination of materials, whether in the round,
bas-relief, high relief, mobile, fountain, kinetic, or electronic;
(b)
Paintings or drawings;
(c)
Mosaics;
(d)
Photographs;
(e)
Crafts made from clay, fiber and textiles, wood, metal, plastics, or any other
material, or any combination thereof;
(f)
Calligraphy;
(g)
Mixed media composed of any combination of forms or media; or
(h)
Unique architectural embellishments.
Source:
L. 64: R&RE,
p. 674, § 1. C.R.S. 1963: § 137-1-1. L. 65: p. 1095, § 1. L.
67: p. 945, § 1. L. 70: p. 379, § 8. L. 73: p. 237, § 17. L.
75: (8) repealed, p. 1473, § 30, effective July 18. L. 77: (7.5),
(12.3), and (12.4) added, p. 1728, §1, effective June 20; (8) RC&RE, p.
1740, § 1, effective January 1, 1978. L. 78: (12.1) added, p. 467, § 1,
effective July 1. L. 79: (12.1) amended, p. 1400, § 1, effective March
13; (12.1)(a) amended, p. 1059, § 9, effective June 20; (12.1) repealed, p.
1456, § 4, effective July 1, 1981. L. 80: (18) added, p. 711, § 1,
effective April 16. L. 81: (12.1)(d) R&RE, p. 1872, § 4, effective
June 29; (12.1)(a)(II) amended, § 5, effective July 1. L. 83: (15)
repealed, p. 1485, § 11, effective April 22; (1.1), (1.3), (1.6), (3.5), (5.5),
(7.2), (7.8), (13.5), and (14.3) to (14.5) added, (5) repealed, and (12.3)(b)
amended, pp. 1486, 1488, §§ 1, 6, 4, effective June 1. L. 84: (7.2)
amended, p. 983, § 1, effective May 8. L. 85: IP(7.2) amended and (7.9)
added, pp. 1215, 1210, §§ 1, 2, effective May 9. L. 87: (1.3) amended,
p. 1382, § 1, effective May 8; (7.5), (12.3), and (12.4) repealed, p. 1304, §
1, effective May 20. L. 88: (4) and (11) amended and (12.1) repealed,
pp. 1269, 1275, §§ 4, 14, effective May 29. L. 89: (15.5) added, p.
1482, § 3, effective April 23. L. 90: (1.6)(a) amended, (4.3) to (4.6)
and (12.5) added, p. 1706, § 1, effective April 16; (9) amended, p. 450, § 26,
effective April 18; (1.6)(a) and (13.5) amended and (8.5) added, pp. 1695,
1703, 1701, §§ 16, 37, 33, effective June 9. L. 91: IP(7.2) amended, p.
1980, § 1, effective April 20; (8) amended, p. 1394, § 2, effective April 27. L.
92: (4) amended, p. 2216, § 3, effective June 2. L. 94: (8) and
(14.3) amended, p. 2568, § 86, effective January 1, 1995. L. 95:
IP(1.6)(a) amended and (1.6)(a)(III), (3.2), (8.7), and (13.2) added, pp. 173,
174, §§ 1, 2, effective April 7. L. 97: (1.1) and (1.6) amended, p. 509,
§ 1, effective April 24. L. 98: (11) amended, p. 1276, § 1, effective
June 1. L. 99: (15.5) amended, p. 1299, § 1, effective June 3. L.
2000: (15.5)(a)(II) amended, p. 1499, § 1, effective August 2. L. 2001:
(2) and (17) amended, p. 268, § 14, effective November 15. L. 2002:
(5.5) amended, p. 1939, § 1, effective August 7; (2.5), (3.1), (5.6), and (7.1)
added, (5.5)(a)(IV) repealed, and (14.4) amended, pp. 1671, 1673, §§ 1, 3,
effective January 1, 2003. L. 2004: (1.6)(a)(I) amended, p. 1208, § 86,
effective August 4. L. 2008: (14.3) amended, p. 1914, § 129, effective
August 5. L. 2009: (7.7) and (8.3) added and (7.8), (8), and (14.3)
amended, (SB-040), ch. 9, p. 70, § 12, effective July 1; (8.5) amended, (SB
09-042), ch. 176, p. 779, § 1, effective August 5. L. 2010: (1.1)
amended, (SB 10-177), ch. 392, p. 1861, § 1, effective August 11; (1.6)(a)(III)
amended, (HB 10-1197), ch. 175, p. 634, § 1, effective August 11; (6.3) and
(6.8) added and (7) and (11) amended, (HB10-1267), ch. 425, p. 2198, § 1,
effective August 11. L. 2011: (8.4) added and (14.4) amended, (HB
11-1042), ch. 138, p. 479, § 1, effective May 4; (1.6)(d) added, (HB 11-1043),
ch. 266, p. 1213, § 23, effective July 1; (1.6)(a)(I) and (14.4) amended, (HB
11-1146), ch. 166, p. 571, § 1, effective January 1, 2012. L. 2013:
(14.4)(a) amended, (HB 13-1300), ch. 316, p. 1699, § 116, effective August 7. L.
2014: (8.5) amended, (HB 14-1349), ch. 230, p. 854, § 4, effective May 17;
(1.6)(b) amended, (SB 14-043), ch. 53, p. 248, § 1, effective August 6. L.
2016: (14.4)(b)(II)(A) amended, (SB 16-012), ch. 66, p. 169, § 1, effective
April 5. L. 2017: IP, (1.1), and (1.3) amended, (SB 17-302), ch. 311, p.
1675, § 1, effective June 2. L. 2018: (14.4)(c) added, (HB 18-1283), ch.
270, p. 1665, § 1, effective August 8. L. 2019: (5.5)(c)(VIII) amended,
(HB 19-1172), ch. 136, p. 1727, § 249, effective October 1. L. 2020:
(17) amended, (HB 20-1077), ch. 80, p. 324, § 5, effective September 14. L.
2021: (3.7) added, (HB 21-1312), ch. 299, p. 1791, § 3, effective July 1;
(14.4)(a) amended, (HB 21-1061), ch. 63, p. 252, § 1, effective September 7. L.
2022: IP(15.5)(a)(II) amended, (HB 22-1295), ch. 123, p. 865, § 124,
effective July 1; (1.1), IP(1.3), and (1.3)(b) amended and (3.3) and (6.2)
added, (HB 22-1301), ch. 198, p. 1321, § 1, effective August 10; (8.6) added
and (14.3) amended, (HB 22-1296), ch. 310, p. 2226, § 1, effective August 10;
(14.3) amended and (16.3) added, (HB 22-1242), ch. 172, p. 1139, § 34,
effective August 10. L. 2024, 2nd Ex. Sess.: (1.3)(b)(II) and
(1.3)(b)(III) amended and (1.3)(b)(IV) added, (HB 24B-1003), ch. 2, p. 24, § 1,
effective November 28. L. 2026: (3.5) and (13.5) amended, (SB 26-010),
ch. 2, p. 7, § 2, effective January 1, 2027.
Editor's
note: (1)
Amendments to subsection (1.6)(a) by House Bill 90-1229 harmonized with House
Bill 90-1018.
(2) Amendments to subsection
(14.4) by House Bill 11-1042 and House Bill 11-1146 were harmonized, effective
January 1, 2012.
(3) Amendments to this section
by HB 22-1242 and HB 22-1296 were harmonized.
(4) Section 3(2) of chapter 2
(SB 26-010), Session Laws of Colorado 2026, provides that the act changing this
section applies to property tax years commencing on or after January 1, 2027.
Cross
references: (1)
For the creation of the property tax administrator, see § 39-2-101.
(2) For the legislative
declaration in HB 21-1312, see section 1 of chapter 299, Session Laws of
Colorado 2021. For the legislative declaration in SB 26-010, see section 1 of
chapter 2, Session Laws of Colorado 2026.
ANNOTATION
I.
Personal Property.
II.
Property.
III.
Real Property.
I. PERSONAL PROPERTY.
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Membership or contract in
Associated Press is "personal property". Bd. of Comm'rs v. Rocky
Mt. News Printing Co., 15 Colo. App. 189, 61 P. 494 (1900).
Signs that can easily be
removed and kitchen and bath displays of a temporary nature are not fixtures
and are therefore personal property. Also, despite being affixed to or
permanently incorporated into a building, pneumatic and sensormatic systems
were primarily tied to a business and therefore were not fixtures and were
properly classified as personal property. Home Depot USA, Inc. v. Pueblo County
Bd. of Comm'rs, 50 P.3d 916 (Colo. App. 2002).
II. PROPERTY.
Bank deposits not
"property" of bank but are credits belonging to depositors.
Murray v. Bd. of Comm'rs, 67 Colo. 14, 185 P. 262 (1919).
III. REAL PROPERTY.
Law reviews. For
article, "In 'Case' You Missed It: Recent Real Estate Case Law
Highlights", see 50 Colo. Law. 36 (Apr. 2021). For article,
"Unraveling the Mystery of 'Residential Land'", see 50 Colo. Law. 52
(May 2021).
To determine the proper
classification of land for assessment, the trial court must make findings of
fact regarding conflicting evidence. C.A. Staack v. Bd. of County Comm'rs,
802 P.2d 1191 (Colo. App. 1990).
Primary factor to be considered
in determining proper classification of property for property tax purposes is
the actual use of the property on the relevant assessment date. Farny v. Bd. of
Equaliz., 985 P.2d 106 (Colo. App. 1999); Hogan v. Bd. of County Comm'rs, 2018
COA 86, 459 P.3d 629, aff'd on other grounds sub nom. Mook v. Bd. of County
Comm'rs of Summit, 2020 CO 12, 457 P.3d 568; HCPI/CO Springs v. El Paso Bd. of
Comm'rs, 2024 COA 82, 558 P.3d 636.
If a property owner's use of
the parcel on the assessment date satisfies the requirements for residential
classification, then it is irrelevant if the owner has future plans to sell the
parcel or make nonresidential use of it. Hogan v. Bd. of County Comm'rs, 2018
COA 86, 459 P.3d 629, aff'd on other grounds sub nom. Mook v. Bd. of County
Comm'rs of Summit, 2020 CO 12, 457 P.3d 568.
In determining a parcel's
proper classification for the present assessment year, the board of assessment
appeals may not reject a final decision previously rendered by an appropriate
tribunal as to the parcel's use during a previous tax year and re-visit that
issue. However, a decision with respect to a previous tax year is not
binding with respect to the issues presented in a protest of the assessment for
a later year. Von Hagen v. Bd. of Equaliz., 948 P.2d 92 (Colo. App. 1997).
The taxpayer has the burden
of proof to show any qualifying ranching or farming uses of land in support of
a claim for agricultural classification. Palmer v. Bd. of Equaliz., 957
P.2d 348 (Colo. App. 1998); Hepp v. Boulder County Assessor, 113 P.3d 1268
(Colo. App. 2005).
Property properly classified
as nonagricultural residential property. A 35-acre parcel that was subject
to a perpetual conservation easement and included a residence was properly
classified as residential. Under subsection (1.6)(a)(III), a parcel that
includes a residential improvement is only agricultural based on a perpetual
conservation easement if it consists of at least 80 acres. The parcel also did
not qualify for agricultural classification based on farming use under
subsection (1.6)(a)(I) because the owner did not establish three years of
agricultural use and did not qualify for agricultural classification based on
forestry use under subsection (1.6)(a)(II) because it was smaller than 40
acres. Andrew v. Teller County Bd. of Equaliz., 2012 COA 104, 284 P.3d 172.
To qualify as
"agricultural land" under subsection (1.6), the land must (1) be
presently used as a farm or ranch; (2) have been so used during the two-year
period prior to the assessment; (3) have been classified or eligible for
classification as agricultural land during the 10 years preceding the
assessment year; and (4) continue to have actual agricultural use. Boulder
County Bd. of Equaliz. v. M.D.C. Constr. Co., 830 P.2d 975 (Colo. 1992).
Second element of test applied
in Aberdeen Inv'rs v. Adams County, 240 P.3d 398 (Colo. App. 2009).
Definition of
"agricultural land" does not require that the use of the residential
improvements be related to the agricultural use of the land. C.A. Staack v.
Bd. of County Comm'rs, 802 P.2d 1191 (Colo. App. 1990).
Definition of
"agricultural land" does not differentiate between a lessee's primary
purpose in using the land and the landowner's primary purpose in acquiring and
maintaining ownership of the land, nor does the landowner need to profit or
intend to profit from agricultural operations on the land conducted by the
owner's lessees. Boulder Cty. Bd. of Equaliz. v. M.D.C. Const. Co., 830 P.2d
975 (Colo. 1992).
Lessees' use of property as
a ranch for the primary purpose of making a profit was the determinative factor
in qualifying property as agricultural land. Boulder Cty. Bd. of Equaliz.
v. M.D.C. Const. Co., 830 P.2d 975 (Colo. 1992).
Subsections (1.6) and (13.5)
require that, in order to qualify for agricultural tax treatment, the taxpayer
must prove that actual grazing of the parcel took place in the applicable tax
year unless the reason the land was not grazed related to a conservation
practice or unless the land in question is part of a larger agricultural unit
on which grazing or conservation practices have occurred during the relevant
tax years. Douglas County Bd. of Equaliz. v. Clarke, 921 P.2d 717 (Colo. 1996).
Whether a party's use
constitutes agricultural use is primarily a factual question, but an
interpretation of what the legislature intended when it required agricultural
use in order for the property to be classified as agricultural for tax purposes
is a question of law for the courts to decide. Douglas County Bd. of
Equaliz. v. Clarke, 921 P.2d 717 (Colo. 1996).
Initial question that the
board of assessment appeals must consider in reviewing a county assessor's
classification of land as agricultural is whether it is a segregated parcel
that should be treated as a single unit or whether it is part of an integrated
larger parcel. This is a factual determination, controlled by whether the land
is sufficiently contiguous to and connected by use with other land to qualify
it as part of a large unit or whether it is a parcel segregated by geography or
type of use from the balance of the unit. Douglas County Bd. of Equaliz. v.
Clarke, 921 P.2d 717 (Colo. 1996).
The plain meaning of the
phrase "used for grazing" is that livestock actually graze on the
land. There must be actual grazing on the parcel during each relevant tax
year to qualify for agricultural classification unless the land is subject to
non-use for conservation purposes. Douglas County Bd. of Equaliz. v. Clarke,
921 P.2d 717 (Colo. 1996).
In order for land that is
not used for grazing to qualify for conservation, the taxpayer must prove that
the non-use was reasonably related to the overall grazing operation. A
professionally prepared conservation plan is not required. The non-use must be
both purposeful and an integral part of the grazing operation. Neglect by the
landowner or lessee or basic unsuitability of the land for grazing will not
suffice. Douglas County Bd. of Equaliz. v. Clarke, 921 P.2d 717 (Colo. 1996);
Johnston v. Park County Bd. of Equaliz., 979 P.2d 578 (Colo. App. 1999).
Under subsection
(1.6)(a)(I), land can only qualify as agricultural land by virtue of being
"in the process of being restored through conservation practices"
if it has been subjected to a federally established conservation reserve
program or a conservation plan approved by an appropriate conservation district
as specified in that subsection. Hepp v. Boulder County Assessor, 113 P.3d 1268
(Colo. App. 2005).
There is no indication in
the text that the landowner must actually profit or intend to profit from
agricultural operations on the land conducted by the owner's lessees.
Boulder Cty. Bd. of Equaliz. v. M.D.C. Const. Co., 830 P.2d 975 (Colo. 1992).
Definition of
"ranch" does not require that the owner of the land own the livestock
grazing on his land to classify the land as agricultural. The owner may
lease the land for grazing, and, if such use is for the primary purpose of
obtaining a monetary profit from the grazing activity, it constitutes an
agricultural use. C.A. Staack v. Bd. of County Comm'rs, 802 P.2d 1191 (Colo.
App. 1990); Boulder Cty. Bd. of Equaliz. v. M.D.C. Const. Co., 830 P.2d 975
(Colo. 1992).
So long as a parcel of land
is used for grazing livestock for profit, it qualifies as a "ranch",
even if the owner of the property is not the one who is conducting the grazing
operation. Estes v. Bd. of Assessment Appeals, 805 P.2d 1174 (Colo. App. 1990).
"Trespass grazing"
does not meet the statutory requirements for agricultural classification as a
matter of law. In interpreting subsections (1.6)(a)(I) and (13.5), a court
must give appropriate deference to provisions of the property tax
administrator's reference manuals that expressly provide that "trespass
grazing" is an insufficient basis for finding that land is
"agricultural land". Besch v. Jefferson County Bd. of County Comm'rs,
20 P.3d 1195 (Colo. App. 2000).
The 10-year requirement for
agricultural land must be interpreted to mean that the land was classified, or
eligible for classification, as agricultural land at some time during the
preceding 10 years, not for the whole of that period. Hence, if a
property's agricultural use ceases, that property may, nevertheless, be again
classified as agricultural land if it is used for such purpose for three years
within 10 years from the date of the original abandonment of that use. Von
Hagen v. Bd. of Equaliz., 948 P.2d 92 (Colo. App. 1997).
Owner's intentions for
future use of his land may not be considered in classifying the property as
"agricultural land". C.A. Staack v. Bd. of County Comm'rs, 802
P.2d 1191 (Colo. App. 1990).
Focus of the statutory
definition of agricultural land is clearly on present and past surface use of
the land without regard to any future intent on the part of the owner to
develop the land for nonagricultural purposes. Boulder Cty. Bd. of Equaliz. v.
M.D.C. Const. Co., 830 P.2d 975 (Colo. 1992).
Land was held not to be
"agricultural land" because the primary use of the land during the
three years in question was not for farming with the intent to obtain a profit.
Arapahoe P'ship v. Bd. of County Comm'rs, 813 P.2d 766 (Colo. App. 1990).
The two-year requirement
that land be used as a farm or ranch does not require such use be continuous
during the prior two years; the plain language of the statute and
legislative intent only require that the land be used as such at some point
during both of the prior two tax years to the assessment. Aberdeen Inv'rs v.
Adams County, 240 P.3d 398 (Colo. App. 2009).
In determining whether the
two-year requirement that land be used as a farm or ranch was met, use that
begins mid-year suffices. Although January 1 is the relevant date for
classification purposes, use that began in July counts towards the two-year use
requirement. Aberdeen Inv'rs v. Adams County, 240 P.3d 398 (Colo. App. 2009).
Parcel of land did not
qualify as agricultural land for ad valorem tax purposes under the first
criterion of subsection (1.6). Subsection (1.6) requires that the land be
used as a farm or ranch currently and for the previous two years. It is the
actual use during the relevant time period that is dispositive. In 2006, the
actual use of the subject land was not as a farm, or as part of a farm, but as
a construction site. C.P. Bedrock, LLC v. Denver County Bd. of Equaliz., 259
P.3d 514 (Colo. App. 2011).
Parcel of land did not
qualify as being in the process of being restored through conservation
practices because it did not satisfy the condition of the second criterion in
subsection (1.6) that the parcel "has been placed in a conservation
reserve program". Under subsection (1.6) the appropriate government
agency must have at least approved the owner or lessee's application for
inclusion in the conservation reserve program at some point before the end of
the tax year. The government agencies in question did not approve the
application of the farmer lessee of the taxpayer to add the subject land to the
conservation program until 2007. Because the subject land was not placed in the
conservation program in 2006, the land was not "being restored through
conservation practices" under subsection (1.6)(a)(I) during the relevant
period. C.P. Bedrock, LLC v. Denver County Bd. of Equaliz., 259 P.3d 514 (Colo.
App. 2011).
Parcel of land also did not
meet the alternative condition of being subject to "a conservation plan
approved by the appropriate conservation district . . . for up to a period of
ten crop years". There was effectively no conservation plan covering
the subject land for 2006 or the years prior. Accordingly, the subject land did
not qualify as "agricultural land" under subsection (1.6)(a)(I) by
virtue of being "in the process of being restored through conservation
practices". Therefore, taxpayer cannot receive favorable tax treatment for
the subject land for the 2007 and 2008 tax years on this basis. C.P. Bedrock,
LLC v. Denver County Bd. of Equaliz., 259 P.3d 514 (Colo. App. 2011).
Where the administrative
agency and administrative law judge responsible for administering the tax code
disagree on the interpretation of a statute, the property tax
administrator's interpretation is not entitled to judicial deference if it was
not embodied in the assessor's reference library and is inconsistent with the
statutory text. Moreover, the board of assessment appeals' interpretation deserves
greater deference where its interpretation is consistent with its previous
opinions. Aberdeen Investors v. Adams County, 240 P.3d 398 (Colo. App. 2009).
Definition of
"farm" does not include land used for greenhouses, where the
agricultural products produced in the greenhouses do not originate from the
land's productivity. Accordingly, such land may not be classified and valued as
agricultural land for property tax purposes. Welby Gardens Co. v. Adams County
Bd. of Equaliz., 56 P.3d 1121 (Colo. App. 2002), aff'd, 71 P.3d 992 (Colo.
2003).
Subsection (1.6)(b) defines
"other agricultural property" generally and does not provide specific
guidance on how it should be valued. A court, therefore, should defer to
the administrative interpretations of the statute. Jefferson County Bd. of
County Comm'rs v. S.T. Spano Greenhouses, Inc., 155 P.3d 422 (Colo. App. 2006).
The provisions of the
assessor's reference library interpreting subsection (1.6)(b) require the land
component of other agricultural property to be valued based on comparable sales
of other agricultural land that is as similar as possible to the subject land
in size, location, and present use. Jefferson County Bd. of County Comm'rs v.
S.T. Spano Greenhouses, Inc., 155 P.3d 422 (Colo. App. 2006).
The grazing and boarding of
"pleasure horses" does not qualify as a "ranching" use.
Only the grazing of "livestock" for the purpose of obtaining a
monetary profit constitutes a "ranching" use, and horses may
constitute "livestock" only if they are used for food or for human or
animal consumption, breeding, draft, or profit. The taxpayer's profit motive
alone in boarding and grazing horses on his land is insufficient. Palmer v. Bd.
of Equaliz., 957 P.2d 348 (Colo. App. 1998).
Production of eggs in
self-contained unit within which the livestock does not touch the ground where
the eggs are sold for monetary profit as an agricultural product falls under
the statutory definition of a farm, and the eggs fall under the definition of
agricultural products. Morning Fresh Farms v. Bd. of Equaliz., 794 P.2d 1073
(Colo. 1990).
Reservoir rights used upon
land are taxable as real estate like improvements upon the land on which
they are applied. Antero & Lost Park Reservoir Co. v. Bd. of Comm'rs, 65
Colo. 375, 177 P. 148 (1918).
Water rights are included
within and constitute a part of the real estate upon which the water is
applied. Kendrick v. Twin Lakes Reservoir Co., 58 Colo. 281, 144 P. 884 (1914).
Mineral reservation not real
property. A right to prospect for and to remove minerals if found is not a
reservation of an estate in the real property involved, but a mere license,
subject to revocation before its exercise by the owner of the fee simple
estate. Radke v. Union P.R.R., 138 Colo. 189, 334 P.2d 1077 (1959).
Waterworks system deemed
realty. Water mains, pipes, and hydrants laid in the public streets and
alleys of a city, and the machinery connected therewith and necessary to the
operation of a waterworks plant, are realty for the purpose of taxation. Colo.
Fuel & Iron Co. v. Pueblo Water Co., 11 Colo. App. 352, 53 P. 232 (1898).
In Colorado, all real
property, except that which is expressly exempted by law, is subject to ad
valorem taxation. Mesa Verde Co. v. Montezuma County Bd. of Equaliz., 898
P.2d 1 (Colo. 1995).
Development rights are
property interests subject to taxation. Vill. at Treehouse v. Prop. Tax
Adm'r, 2014 COA 6, 321 P.3d 624.
Lessee of real property is
liable for property tax when the lessee is, for all practical purposes, the
owner of the real property. When the terms of a lease require the lessee to
construct, maintain, and insure an aircraft hangar facility on the leased land
at its own expense and give lessee the exclusive right to possess, use,
operate, receive revenue from, claim tax advantages from, and, with
authorization, assign or transfer the hangar facility, the lessee was properly
assessed property tax for its ownership of the hangar facility. Rare Air Ltd.
v. Prop. Tax Adm'r, 2019 COA 134, 459 P.3d 547.
Possessory interest of
concessionaire on national park land owned by the United States was an
"interest in land" and thus constituted "real property" as
defined in this section. Mesa Verde Co. v. Montezuma County Bd. of Equaliz.,
898 P.2d 1 (Colo. 1995).
Possessory interests in land
constitute real property as defined in subsection (14) and therefore also
constitute taxable property as defined in subsection (16). Bd. of County
Comm'rs v. Vail Assocs., Inc., 19 P.3d 1263 (Colo. 2001).
Reservoir dam not
"improvement". A reservoir dam is not subject to taxation as
realty as it is not an improvement upon the land on which it is situated.
Antero & Lost Park Reservoir Co. v. Bd. of Comm'rs, 65 Colo. 375, 177 P.
148 (1918).
Golf club membership not an
"interest in land". Rather, based on the terms of the membership
agreement, the membership was a license. Roaring Fork Club v. Pitkin Bd. of
Equaliz., 2013 COA 167, 342 P.3d 467.
Definition of
"residential land" contains no prescribed limit on the amount of
acreage that may be so classified. Rather, the size of a residential tract
must be determined on a case-by-case basis according to the amount of acreage
which is being used as a unit in conjunction with the residential improvements
on each particular property. Gyurman v. Weld County Bd. of Equaliz., 851 P.2d
307 (Colo. App. 1993); Farny v. Bd. of Equaliz., 985 P.2d 106 (Colo. App.
1999).
Based on a reading of the
constitutional definition of residential real property and this section
together, residential land must contain a residential dwelling unit and be
used as a unit in conjunction with the residential improvements on the
residential land. Fifield v. Pitkin County Bd. of Comm'rs, 2012 COA 197, 292
P.3d 1207.
Common ownership requires
identical parties. Contiguous parcels are under common ownership for
purposes of qualifying all of the parcels as residential land under subsection
(14.4) only if identical parties, and not merely overlapping parties, hold
record title to each contiguous parcel. Lannie v. Bd. of County Comm'rs of
Eagle County, 2020 COA 77, 471 P.3d 1207.
For purposes of subsection
(14.4)(a), a parcel that does not include a residential improvement is
"used as a unit" with a contiguous residential parcel under common
ownership if the parcels are used as though they are a greater, single
parcel of land and the landowner does not use the parcel for nonresidential
property uses. Sandra K. Morrison Trust v. Bd. of County Comm'rs, 2020 COA 74,
465 P.3d 582.
The plain meaning of
"integral" in subsection (14.4)(a) is that parts are formed as a
unit, not that all parts are necessary or essential. Hogan v. Bd. of County
Comm'rs, 2018 COA 86, 459 P.3d 629, aff'd sub nom. Mook v. Bd. of County
Comm'rs of Summit, 2020 CO 12, 457 P.3d 568.
The definition of
"residential land" in subsection (14.4)(a) unambiguously means that
two parcels must actually touch to be contiguous. Bringle Family Trust v.
Bd. of County Comm'rs, 2018 COA 64, 459 P.3d 615; Mook v. Bd. of County Comm'rs
of Summit, 2020 CO 12, 457 P.3d 568.
The definition of
"contiguous" in subsection (14.4)(a) refers only to parcels of land
that physically touch. Thus, residential land includes physically touching
parcels of land upon which residential improvements are located. Therefore, for
a multi-parcel assemblage to satisfy the contiguity requirement, a parcel of
land must physically touch another parcel containing a residential improvement.
Ziegler v. Park County Bd. of County Comm'rs, 2020 CO 13, 457 P.3d 584.
Definition of residential
land does not require active use of contiguous parcels. Hogan v. Bd. of
County Comm'rs, 2018 COA 86, 459 P.3d 629, aff'd sub nom. Mook v. Bd. of County
Comm'rs of Summit, 2020 CO 12, 457 P.3d 568.
Land on a parcel contiguous
to another commonly owned parcel with a residential dwelling unit need only
be used as a unit in conjunction with that residential dwelling unit or
associated residential improvement to qualify as residential land. Fifield v.
Pitkin County Bd. of Comm'rs, 2012 COA 197, 292 P.3d 1207.
A residential improvement is
not needed on each contiguous and commonly owned parcel of land for that parcel
to be "used as a unit". Ziegler v. Park County Bd. of County
Comm'rs, 2020 CO 13, 457 P.3d 584.
Subsection (14)(a) requires
a property owner to use contiguous residential and vacant parcels together as a
collective unit of property for only residential purposes to satisfy the
"used as a unit" requirement. The use of contiguous vacant parcels
does not have to be essential to the enjoyment or use of the residential
property. Ziegler v. Park County Bd. of County Comm'rs, 2020 CO 13, 457 P.3d
584.
Property tax assessors must
rely on county records when deciding whether properties are held under common
ownership for purposes of subsection (14.4). Mook v. Bd. of County Comm'rs
of Summit, 2020 CO 12, 457 P.3d 568.
Subsection (14.4) only
requires that landowners use a collective unit of property composed of
multiple, individual parcels, together with the residential improvements
located on that collective unit. Nothing in the statute mandates that
residential improvements exist on each parcel to be classified as residential
land. Mook v. Bd. of County Comm'rs of Summit, 2020 CO 12, 457 P.3d 568.
A residential dwelling must
be situated upon a lot zoned for residential use in order for the lot to
qualify as "residential real property" eligible for the
percentage ratio of valuation for assessment as determined in accordance with
Colo. Const., art. X, § 3(1)(b). Vail Assocs., Inc. v. Bd. of Assessment
Appeals, 765 P.2d 593 (Colo. App. 1988).
Definition of
"residential improvement" requires that a structure be designed for
use predominantly as a residence rather than simply "actually
used" as a residence. Mission Viejo v. Douglas Cty. Bd. of Equaliz., 881
P.2d 462 (Colo. App. 1994).
For purposes of
"residential improvements," the phrase "designed for use"
means that the building at the relevant time is devoted to or intended for
actual use predominantly as a place of residence. Mission Viejo Co. v. Douglas
County Bd. of Equaliz., 881 P.2d 462 (Colo. App. 1994); Manor Vail Condominium
Ass'n v. Bd. of Equaliz., 956 P.2d 654 (Colo. App. 1998); Farny v. Bd. of
Equaliz., 985 P.2d 106 (Colo. App. 1999).
Small structure built on
320-acre parcel qualified for residential classification since taxpayers
actually used structure predominantly as a place of residence and it was at
least minimally suitable for such residential purposes. Farny v. Bd. of Equaliz.,
985 P.2d 106 (Colo. App. 1999).
Restaurant and meeting rooms
were not residential improvements. Manor Vail Condominium Ass'n v. Bd. of
Equaliz., 956 P. 2d 654 (Colo. App. 1998).
Building originally designed
as a residence could be reclassified based on actual use. Fact that
building was originally designed as residence did not conclusively require
classification as a residential property under this section. Mission Viejo v.
Douglas Cty. Bd. of Equaliz., 881 P.2d 462 (Colo. App. 1994).
Plaintiff, a quasi-municipal
corporation and political subdivision of the state, was not a
"person" under subsection (9) and did not have standing to seek
damages pursuant to § 39-10-115 (3). Bear Creek Water & Sanitation Dist. v.
Bd. of County Comm'rs of Jefferson County, 902 P.2d 904 (Colo. App. 1995).
Vacant parcel of land did
not qualify for residential classification even though it was zoned for
residential use, adjacent to the taxpayer's residence, and used in conjunction
with the residence as part of the taxpayer's backyard because the adjacent
residential parcel was owned by the taxpayer's wife, not the taxpayer, and the
vacant parcel did not have a residential dwelling unit on it. Sullivan v. Bd.
of Equaliz., 971 P.2d 675 (Colo. App. 1998).
Residential classification
upheld for second home that was sometimes rented out on a short-term basis.
The board of assessment appeals' classification of the home as residential had
a reasonable basis in law and was supported by substantial evidence in the
record where the property: was designed for use as a residence and built for
personal use; the owners' intent was to use the property as a second residence
and an inheritance for their sons; short-term rentals were allowed primarily to
offset expenses and share the outdoors experience with visitors rather than to
profit; most rental activity occurred only during the summer; and the owners
themselves regularly used the property. O'Neil v. Conejos County Bd. of
Comm'rs, 2017 COA 30, 395 P.3d 1185.
Rehabilitation hospital
originally constructed and intended to be used as a rehabilitation hospital and
that is currently and actually used as a rehabilitation hospital is properly
classified as commercial property for tax purposes. Board of assessment
appeals erred in reversing county's classification and classifying
rehabilitation hospital as residential property because, although inpatient
overnight stays were provided, the hospital's predominate purpose and use are
commercial and not residential, and, under subsection (14.3), it is not
"designed for use predominantly as a place of residency". HCPI/CO
Springs v. El Paso Bd. of Comm'rs, 2024 COA 82, 558 P.3d 636. Applied
in Del Mesa Farms v. Bd. of Equaliz., 656 P.2d 661 (Colo. App. 1998).
39-1-103. Actual value determined -
when - legislative declaration.
(1) The
valuation for assessment of producing mines and nonproducing mining claims
shall be determined as provided in article 6 of this title.
(2) The
valuation for assessment of leaseholds and lands producing oil or gas shall be
determined as provided in article 7 of this title.
(3) The
actual value for property tax purposes of the operating property and plant of
all public utilities doing business in this state shall be determined by the
administrator, as provided in article 4 of this title.
(4) (a)
Repealed.
(b) The
valuation for assessment of mobile homes shall be determined as provided in
section 39-5-203.
(5) (a)
All real and personal property shall be appraised and the actual value thereof
for property tax purposes determined by the assessor of the county wherein such
property is located. The actual value of such property, other than agricultural
lands exclusive of building improvements thereon and other than residential
real property and other than producing mines and lands or leaseholds producing
oil or gas, shall be that value determined by appropriate consideration of the
cost approach, the market approach, and the income approach to appraisal. The
assessor shall consider and document all elements of such approaches that are
applicable prior to a determination of actual value. The actual value reflects
the value of the fee simple estate. Despite any orders of the state board of
equalization, no assessor shall arbitrarily increase the valuations for
assessment of all parcels represented within the abstract of a county or within
a class or subclass of parcels on that abstract by a common multiple in response
to the order of said board. If an assessor is required, pursuant to the order
of said board, to increase or decrease valuations for assessment, such changes
shall be made only upon individual valuations for assessment of each and every
parcel, using each of the approaches to appraisal specified in this subsection
(5)(a), if applicable. The actual value of agricultural lands, exclusive of
building improvements thereon, shall be determined by consideration of the
earning or productive capacity of such lands during a reasonable period of
time, capitalized at a rate of thirteen percent. Land that is valued as
agricultural and that becomes subject to a perpetual conservation easement
shall continue to be valued as agricultural notwithstanding its dedication for
conservation purposes; except that, if any portion of such land is actually
used for nonagricultural commercial or nonagricultural residential purposes,
that portion shall be valued according to such use. Nothing in this subsection
(5) shall be construed to require or permit the reclassification of
agricultural land or improvements, including residential property, due solely
to subjecting the land to a perpetual conservation easement. The actual value
of residential real property shall be determined solely by consideration of the
market approach to appraisal. A gross rent multiplier may be considered as a
unit of comparison within the market approach to appraisal. The valuation for
assessment of producing mines and of lands or leaseholds producing oil or gas
shall be determined pursuant to articles 6 and 7 of this title 39. In
establishing actual value, an assessor shall also consider:
(I)
Current use;
(II)
Existing zoning and other governmental land use or environmental regulations
and restrictions;
(III)
Multi-year leases or other contractual agreements affecting the use of or
income from the property;
(IV)
Easements and reservations of record; and
(V)
Covenants, conditions, and restrictions of record.
(b) If,
having considered the three approaches prescribed in paragraph (a) of this
subsection (5), at the sole discretion of the assessor the use of the three
approaches to value cannot accurately determine the actual value of any parcel
of taxable property, or in the opinion of the assessor the application of the
three approaches to value does not result in uniform, just, and equalized
valuation, then the actual value thereof shall be determined by comparison of
the surface use of such property with a similar surface use.
(c)
Except as provided in section 39-1-102 (14.4)(b) or 39-1-102 (14.4)(c) and in
subsections (5)(e) and (5)(f) of this section, once any property is classified
for property tax purposes, it shall remain so classified until such time as its
actual use changes or the assessor discovers that the classification is
erroneous. The property owner shall endeavor to comply with the reasonable
requests of the assessor to supply information which cannot be ascertained
independently but which is necessary to determine actual use and properly
classify the property when the assessor has evidence that there has been a
change in the use of the property. Failure to supply such information shall not
be the sole reason for reclassifying the property. Any such request for such
information shall be accompanied by a notice that states that failure on the
part of the property owner to supply such information will not be used as the
sole reason for reclassifying the property in question. Subject to the
availability of funds under the assessor's budget for such purpose, no later
than May 1 of each year, the assessor shall inform each person whose property
has been reclassified from agricultural land to any other classification of
property of the reasons for such reclassification including, but not limited
to, the basis for the determination that the actual use of the property has
changed or that the classification of such property is erroneous.
(d) If
a parcel of land is classified as agricultural land as defined in section
39-1-102 (1.6)(a)(III) and the perpetual conservation easement is terminated,
violated, or substantially modified so that the easement is no longer granted
exclusively for conservation purposes, the assessor may reassess the land
retroactively for a period of seven years and the additional taxes, if any,
that would have been levied on the land during the seven year period prior to
the termination, violation, or modification shall become due.
(e) (I)
Except as provided in subparagraph (II) of this paragraph (e) and in paragraph
(f) of this subsection (5), if a parcel of land is classified as agricultural
land as defined in section 39-1-102 (1.6) and the productivity of such parcel
of land is destroyed by a natural cause on or after January 1, 2012, so that,
were it not for the destruction of the productivity of the land by a natural
cause, the land would have qualified as agricultural land for the following
property tax year, the agricultural land classification shall remain in place
for the year of destruction and the four subsequent property tax years so long
as the assessor receives evidence from the owner that the owner is in the
process of rehabilitating the productivity of the land for agricultural use.
Such evidence includes, but is not limited to, removing debris, removing
contaminants, restoring fences and agricultural structures, reseeding,
providing water for livestock, or contouring the land suitable for agricultural
use.
(II)
The agricultural land classification of the land described in subparagraph (I)
of this paragraph (e) must change according to current use if:
(A) The
productivity of the land is not rehabilitated for agricultural use prior to the
January 1 after the period described in subparagraph (I) of this paragraph (e),
unless the property owner provides documentary evidence to the assessor that
during such period a good-faith effort was made to rehabilitate the
productivity of the land for agricultural use but that additional time is
necessary;
(B) The
assessor determines that the classification at the time of destruction of the
productivity of the land as a result of a natural cause was erroneous; or
(C) A
change of use has occurred. For purposes of this sub-subparagraph (C), a change
of use does not include the temporary loss of agricultural classification of
the land as a result of the destruction of the productivity of the land by a
natural cause.
(f) (I)
Except as provided in subparagraph (II) of this paragraph (f), if a parcel of
land is classified as agricultural land as defined in section 39-1-102
(1.6)(a)(II) and the productivity of the parcel of land is destroyed by a
natural cause on or after January 1, 2012, so that, were it not for the
destruction of the productivity of the land by a natural cause, the land would
have qualified as agricultural land for the following property tax year, the
agricultural land classification shall remain in place notwithstanding the
length of the rehabilitation period specified in subparagraph (I) of paragraph
(e) of this subsection (5) so long as the owner is in compliance with an
approved forest management plan and is on the list provided by the Colorado state
forest service as having such a plan.
(II)
The agricultural land classification of the land described in subparagraph (I)
of this paragraph (f) must change according to current use if:
(A) The
assessor determines that the classification at the time of destruction of the
productivity of the land as a result of a natural cause was erroneous; or
(B) A
change of use has occurred. For purposes of this sub-subparagraph (B), a change
of use does not include the temporary loss of agricultural classification of
the land as a result of the destruction of the productivity of the land by a
natural cause.
(6) and
(7) Repealed.
(8) In
any case in which sales prices of comparable properties within any class or
subclass are utilized when considering the market approach to appraisal in the
determination of actual value of any taxable property, the following
limitations and conditions shall apply:
(a) (I)
Use of the market approach shall require a representative body of sales,
including sales by a lender or government, sufficient to set a pattern, and
appraisals shall reflect due consideration of the degree of comparability of
sales, including the extent of similarities and dissimilarities among
properties that are compared for assessment purposes. In order to obtain a
reasonable sample and to reduce sudden price changes or fluctuations, all sales
shall be included in the sample that reasonably reflect a true or typical sales
price during the period specified in section 39-1-104 (10.2). Sales of personal
property exempt pursuant to the provisions of sections 39-3-102, 39-3-103, and
39-3-119 to 39-3-122 shall not be included in any such sample.
(II)
Because of the unique characteristics and limited number of oil shale mineral
interests, a minimum of five arm's-length sales of reasonably comparable oil
shale mineral interests shall be required to constitute a market for purposes
of utilization of the market approach to appraisal in determining the actual
value of nonproducing oil shale mineral interests.
(b)
Each such sale included in the sample shall be coded to indicate a typical,
negotiated sale, as screened and verified by the assessor.
(c) All
such coded, typical sales samples shall be supplied to the administrator for
the performance of his duties.
(d) In
no event shall a sales ratio be established or utilized for any class or
subclass of property unless and until there have been at least thirty such
coded, typical sales or at least five percent of all properties in such class
or subclass within the county have been sold and verified by the assessor as
coded, typical sales, whichever amount is greater. When such minimum
requirement has not been met but typical sales within any such class or
subclass indicate that valuations in the class or subclass are too high or too
low, such fact shall be reported to the state board of equalization, which
board may order an independent appraisal study in such county.
(e)
Repealed.
(f)
Such true and typical sales shall include only those sales which have been
determined on an individual basis to reflect the selling price of the real
property only or which have been adjusted on an individual basis to reflect the
selling price of the real property only.
(9) (a)
In the case of an improvement which is used as a residential dwelling unit and
is also used for any other purpose, the actual value and valuation for
assessment of such improvement shall be determined as provided in this
paragraph (a). The actual value of each portion of the improvement shall be
determined by application of the appropriate approaches to appraisal specified
in subsection (5) of this section. The actual value of the land containing such
an improvement shall be determined by application of the appropriate approaches
to appraisal specified in subsection (5) of this section. The land containing
such an improvement shall be allocated to the appropriate classes based upon
the proportion that the actual value of each of the classes to which the
improvement is allocated bears to the total actual value of the improvement.
The appropriate valuation for assessment ratio shall then be applied to the
actual value of each portion of the land and of the improvement.
(b) In
the case of land containing more than one improvement, one of which is a
residential dwelling unit, the determination of which class the land shall be
allocated to shall be based upon the predominant or primary use to which the
land is put in compliance with land use regulations. If multiuse is permitted
by land use regulations, the land shall be allocated to the appropriate classes
based upon the proportion that the actual value of each of the classes to which
the improvements are allocated bears to the combined actual value of the
improvements; the appropriate valuation for assessment ratio shall then be
applied to the actual value of each portion of the land.
(10)
Common property or common elements within a common interest community as
defined in the "Colorado Common Interest Ownership Act", article 33.3
of title 38, C.R.S., shall be appraised and valued pursuant to the provisions
of section 38-33.3-105, C.R.S.
(10.5)
(a) The general assembly hereby finds and declares that bed and breakfasts
are unique mixed-use properties; that all areas of a bed and breakfast, except
for the commercial lodging area, are shared and common areas that allow
innkeepers and guests to interact in a residential setting; that the land on
which a bed and breakfast is located and that is used in conjunction with the
bed and breakfast is primarily residential in nature; and that there appears to
exist a wide disparity in how assessors classify the different portions of bed
and breakfasts.
(b)
Therefore, notwithstanding any other provision of this article 1, a bed and
breakfast shall be assessed as provided in this subsection (10.5). The
commercial lodging area of a bed and breakfast shall be assessed at the rate
for lodging property. Any part of the bed and breakfast that is not a
commercial lodging area shall be considered a residential improvement and
assessed accordingly. The actual value of each portion of the bed and breakfast
shall be determined by the application of the appropriate approaches to
appraisal specified in subsection (5) of this section. The actual value of the
land containing a bed and breakfast shall be determined by the application of
the appropriate approaches to appraisal specified in subsection (5) of this
section. The land containing a bed and breakfast shall be assessed as follows:
(I) The
portion of land directly underneath a bed and breakfast shall be assessed
pursuant to the procedures pertaining to land set forth in subsection (9) of
this section.
(II)
There shall be a rebuttable presumption that all remaining land shall be
assessed as residential land. Such presumption shall only be overcome if there
is a nonresidential use not reasonably associated with the operation of the bed
and breakfast on some portion of the remaining land, in which case, such
portion of the remaining land shall be assessed as nonresidential land.
(III)
Subparagraphs (I) and (II) of this paragraph (b) shall not apply to
agricultural land.
(10.7)
(a) The general assembly hereby finds and declares that:
(I) A
nursing home is a unique residential property that is the residence of the
individuals living there at the time, regardless of their length of stay;
(II)
There is a discrepancy in how assessing officers classify nursing homes that
provide short-term services and nursing homes that provide longer-term services
for purposes of calculating property tax; and
(III)
Therefore, it is important for the general assembly to clarify that all nursing
homes, regardless of a resident's length of stay, must be classified as
residential real property.
(b) For
property tax years commencing on and after January 1, 2023, land used for a
nursing home and any improvements affixed to that land for the use of the
nursing home are classified and assessed as residential real property,
regardless of a resident's length of stay.
(11)
The general assembly hereby declares that consideration by assessing officers
of the cost approach, market approach, and income approach to the appraisal of
real property has resulted in valuations of minerals in place which are neither
uniform, nor just and equal, because of wide variations within the same
locality in quality and quantity of mineral deposits, if any, because of
uncertainty in the existence or extent of such deposits, because of difficulty
in measuring acquisition or replacement costs, or because of speculative value
judgments when minerals in place are not income producing. Therefore, in the
absence of preponderant evidence shown by the assessing officer that the use of
the cost approach, market approach, and income approach result in uniform and
just and equal valuation, minerals in place are not to be considered in
determining the actual value of real property.
(12) In
any case in which the income approach is utilized in the determination of the
actual value of any nonproducing oil shale mineral interests, the following
limitations and conditions shall apply:
(a) The
assessor shall capitalize the annual rental income for such nonproducing
mineral interests at a capitalization rate of thirteen percent. If nonproducing
mineral interests are unleased, the assessor shall use the annual rental as
defined in paragraph (b) of this subsection (12).
(b) For
the purposes of this subsection (12), "annual rental" means annual
rental payments, or other compensatory payments payable for the right to hold a
mineral interest, which payments are fixed and certain in amount and payable
periodically over a fixed period calculated on a twelve-month basis.
"Annual rental" shall be the representative annual rental for such
mineral interests leased within the county or the area, and "annual
rental" does not include royalty payments, advanced royalty payments, bonus
payments, or minimum royalty payments covering periods when the mineral
interests are not in production, even though said payments may be fixed and
certain in amount and payable periodically. For the purposes of this paragraph
(b), "royalty payments", "advanced royalty payments", and
"minimum royalty payments" mean payments attributable to a portion of
the current or future mineral production of a mineral interest, paid for the
privilege of producing minerals, and "bonus payments" means
compensation paid as consideration for the granting of a mineral lease or other
compensatory payments which are payable regardless of the extent of use of the
mineral interest and which are fixed and certain in amount and may be payable
in one or more periodical increments over a fixed period.
(13)
(a) The general assembly hereby finds and declares that, in the
consideration of the cost approach, market approach, and income approach to the
appraisal of personal property by assessing officers, the cost approach shall
establish the maximum value of property if all costs incurred in the
acquisition and installation of such property are fully and completely
disclosed by the property owner to the assessing officer.
(b)
Therefore, in the assessment of taxable personal property, the assessing
officer shall consider the value derived from the cost approach to be the
maximum value of the property if the property owner has timely filed his
declaration and the declaration contains all relevant information pertaining to
the valuation of the property and, also includes, a full disclosure of all
costs incurred in the acquisition and installation of all personal property
owned by or in the possession of the taxpayer.
(c)
Assessing officers shall consider the cost approach to the appraisal of
property, pursuant to the provisions of this subsection (13), in good faith and
shall deny the use of the cost approach only upon just cause that the
requirements set forth in this subsection (13) and in section 39-5-116 have not
been complied with by a taxpayer. If it is determined at any time that an
assessing officer wrongly denied the use of the cost approach, such assessing
officer shall be held liable for all costs incurred by the taxpayer in
protesting such assessment based on such denial. However, nothing in this
subsection (13) shall preclude the assessing officers from considering the
market approach or income approach to the appraisal of personal property when
such consideration would result in a lower value of the property and when such
valuation is based on independent information obtained by the assessing
officers.
(14)
(a) The general assembly hereby finds and declares that, in determining the
actual value of vacant land, there appears to exist a wide disparity in the
treatment of vacant land by the assessing officers of the various counties;
that the methods of appraisal currently being utilized by assessing officers
for such valuation remain unclear; and that such assessing officers are
provided detailed information concerning the appraisal of vacant land in the
manuals, appraisal procedures, and instructions prepared and published by the
administrator.
(b) The
assessing officers shall give appropriate consideration to the cost approach,
market approach, and income approach to appraisal as required by the provisions
of section 3 of article X of the state constitution in determining the actual
value of vacant land. When using the market approach to appraisal in
determining the actual value of vacant land as of the assessment date,
assessing officers shall take into account, but need not limit their
consideration to, the following factors: The anticipated market absorption
rate, the size and location of such land, the direct costs of development, any
amenities, any site improvements, access, and use. When using anticipated
market absorption rates, the assessing officers shall use appropriate discount
factors in determining the present worth of vacant land until eighty percent of
the lots within an approved plat have been sold and shall include all vacant
land in the approved plat. For purposes of such discounting, direct costs of
development shall be taken into account. The use of present worth shall reflect
the anticipated market absorption rate for the lots within such plat, but such
time period shall not generally exceed thirty years. For purposes of this
paragraph (b), no indirect costs of development, including, but not limited to,
costs relating to marketing, overhead, or profit, shall be considered or taken
into account.
(c) (I)
For purposes of this subsection (14), "vacant land" means any lot,
parcel, site, or tract of land upon which no buildings or fixtures, other than
minor structures, are located. "Vacant land" may include land with
site improvements. "Vacant land" includes land that is part of a
development tract or subdivision when using present worth discounting in the
market approach to appraisal; however, "vacant land" shall not
include any lots within such subdivision or any portion of such development
tract that improvements, other than site improvements or minor structures, have
been erected upon or affixed thereto. "Vacant land" does not include
agricultural land, producing oil and gas properties, severed mineral interests,
and all mines, whether producing or nonproducing.
(II)
For purposes of this subsection (14):
(A)
"Minor structures" means improvements that do not add value to the
land on which they are located and that are not suitable to be used for and are
not actually used for any commercial, residential, or agricultural purpose.
(B)
"Site improvements" means streets with curbs and gutters, culverts
and other sewage and drainage facilities, and utility easements and hookups for
individual lots or parcels.
(d) As
soon after the assessment date as may be practicable, the assessor shall mail
or deliver two copies of a subdivision land valuation questionnaire for each
approved plat within the county to the last-known address of the subdivision
developer known or believed to own vacant land within such approved plat. Such
questionnaire shall be designed to elicit information vital to determining the
present worth of vacant land within such approved plat. Such subdivision
developer or his agent shall answer all questions to the best of his ability,
attaching such exhibits or statements thereto as may be necessary, and shall
sign and return the original copy thereof to the assessor no later than the
March 20 subsequent to the assessment date. All information provided by the
subdivision developer in such questionnaire shall be kept confidential by the
assessor; except that the assessor shall make such information available to the
person conducting any valuation for assessment study pursuant to section
39-1-104 (16) and his employees and the property tax administrator and his
employees.
(e) If
any subdivision developer fails to complete and file one or more questionnaires
by March 20, then the assessor may determine the actual value of the taxable
vacant land within an approved plat which is owned by such subdivision
developer on the basis of the best information available to and obtainable by
the assessor.
(15)
The general assembly hereby finds and declares that assessing officers shall
give appropriate consideration to the cost approach, market approach, and
income approach to appraisal as required by section 3 of article X of the state
constitution in determining the actual value of taxable property. In the
absence of evidence shown by the assessing officer that the use of the cost
approach, market approach, and income approach to appraisal requires the
modification of the actual value of taxable property for the first year of a
reassessment cycle in order to result in uniform and just and equal valuation
for the second year of a reassessment cycle, the assessing officer shall
consider the actual value of any taxable property for the first year of a reassessment
cycle, as may have been adjusted as a result of protests and appeals, if any,
prior to the assessment date of the second year of a reassessment cycle, to be
the actual value of such taxable property for the second year of a reassessment
cycle.
(16)
(a) The general assembly hereby finds and declares that in the consideration
of the cost approach, market approach, and income approach to appraisal for the
valuation of superfund water treatment facilities, the cost approach to
appraisal does not adequately reflect characteristics specific to superfund
water treatment facilities that negatively impact the value of such facilities,
including, but not limited to, the lack of income producing ability and the
absence of any market for sale of superfund water treatment facilities.
Therefore, in the assessment of superfund water treatment facilities, the
income approach to appraisal shall be considered the primary indicator of value
and the cost approach or market approach to appraisal shall be used only if the
value determined under the cost approach or market approach is less than the
value determined under the income approach to appraisal. For the purposes of
determining the actual value of superfund water treatment facilities as of the
assessment date using the income approach to appraisal, the assessing officer
shall capitalize the actual income generated by the facility during the
calendar year preceding the assessment date at the rate of ten percent per
annum.
(b) For
purposes of this subsection (16), "superfund water treatment
facilities" means real and personal property that is:
(I)
Installed and constructed pursuant to an agreement with or an order of the
federal government or the state or any of its political subdivisions and to
satisfy the federal "Comprehensive Environmental Response, Compensation,
and Liability Act of 1980", 42 U.S.C. sec. 9601 et seq., as amended; and
(II)
Operated for the purpose of eliminating, reducing, controlling, or disposing of
pollutants, as defined in section 25-8-103 (15), C.R.S., that could alter the
physical, chemical, biological, or radiological integrity of state waters if
released into state waters.
(17)
(a) The general assembly declares that the valuation of possessory interests
in exempt properties is uncertain and highly speculative and that the following
specific standards for the appropriate consideration of the cost approach, the
market approach, and the income approach to appraisal in the valuation of
possessory interests must be provided by statute and applied in the valuation
of possessory interests to eliminate the unjust and unequalized valuations that
would result in the absence of specific standards:
(I) The
actual value of any possessory interest of the lessee or permittee of lands
owned by the United States and leased or permitted for use for ski area
recreational purposes in connection with a business conducted for profit shall
be determined by capitalizing at an appropriate rate the annual fee paid to the
United States by the lessee or permittee of such land for the use thereof in
the immediately preceding calendar year, adjusted to the level of value using a
factor or factors to be published by the administrator pursuant to the same
procedures and principles as are provided for property in section 39-1-104
(12.3)(a)(I). The rate used to capitalize any fee pursuant to this subparagraph
(I) shall include an appropriate rate of return, an appropriate adjustment for
the applicable property tax rate, and an appropriate adjustment to reflect the
portion of the fee, if any, required to be paid over by the United States to
the state of Colorado and its political subdivisions.
(II)
(A) Except for possessory interests in land leased or permitted for use for
ski area recreational purposes valued in accordance with subparagraph (I) of
this paragraph (a) and except as otherwise provided in subparagraph (III) of
this paragraph (a), the actual value of a possessory interest in land,
improvements, or personal property shall be determined by appropriate
consideration of the cost approach, the market approach, and the income
approach to appraisal. When the cost or income approach to appraisal is
applicable, the actual value of the possessory interest shall be determined by
the present value of the reasonably estimated future annual rents or fees
required to be paid by the holder of the possessory interest to the owner of
the underlying real or personal property through the stated initial term of the
lease or other instrument granting the possessory interest; except that the
actual value of a possessory interest in agricultural land, including land
leased by the state board of land commissioners other than land leased pursuant
to section 36-1-120.5, C.R.S., shall be the actual amount of the annual rent
paid for the property tax year. The rents or fees used to determine the actual
value of a possessory interest under the cost or income approach to appraisal
shall be the actual contract rents or fees reasonably expected to be paid to
the owner of the underlying real or personal property unless it is shown that
the actual contract rents or fees to be paid for the possessory interest being valued
are not representative of the market rents or fees paid for that type of real
or personal property, in which case the market rents or fees shall be
substituted for the actual contract rents or fees.
(B) The
rents or fees taken into account under the cost or income approach to appraisal
under sub-subparagraph (A) of this subparagraph (II) shall exclude that portion
of the rents and fees required to be paid for all rights other than the
exclusive right to use and possess the land, improvements, or personal
property. Such rents or fees to be excluded shall include, but shall not be
limited to, any portion of such rents or fees attributable to any of the
following: Nonexclusive rights to use and possess public property, such as
roads, rights-of-way, easements, and common areas; rights to conduct a
business, as determined in accordance with guidelines to be published by the
administrator; income of the holder of the possessory interest that is not
directly derived from and directly related to the use or occupancy of the
possessory interest; any amount paid under a timber sales contract or similar
agreement for the purchase of timber or for the right to acquire and remove
timber; and reimbursement to the owner of the underlying real or personal
property of the reasonable costs of operating, maintaining, and repairing the
land, improvements, or personal property to which the possessory interest
pertains, regardless of whether such costs are separately stated, provided that
the types of such costs can be identified with reasonable certainty from the
documents granting the possessory interest. The actual value of the possessory
interest so determined shall be adjusted to the taxable level of value using a
factor or factors to be published by the administrator pursuant to the same
procedures and principles as are provided for personal property in section
39-1-104 (12.3)(a)(I).
(III)
Subparagraphs (I) and (II) of this paragraph (a) shall not apply to any
management contract. In the case of a management contract, the possessory
interest shall be presumed to have no actual value. For purposes of this
subparagraph (III), "management contract" means a contract that meets
all of the following criteria:
(A) The
government owner of the real or personal property subject to the contract
directly or indirectly provides the management contractor all funds to operate
the real or personal property;
(B) The
government owns all of the real or personal property used in the operation of
the real or personal property subject to the contract;
(C) The
government maintains control over the amount of profit the management
contractor can realize or sets the prices charged by the management contractor,
or the management contractor's exclusive obligation is to operate and manage
the real or personal property for which the management contractor receives a
fee;
(D) The
government reserves the right to use the real or personal property when it is
not being managed or operated by the management contractor;
(E) The
management contractor has no leasehold or similar interest in the real or
personal property;
(F) To
the extent the management contractor manages a manufacturing process for the
government on the real property subject to the contract, the government owns
all or substantially all of the personal property used in the process; and
(G) The
real or personal property is maintained and repaired at the expense of the
government.
(b)
This subsection (17) shall not apply to and shall not be construed to affect or
change the valuation of public utilities pursuant to article 4 of this title,
the valuation of equities in state lands pursuant to section 39-5-106, the
valuation of mines pursuant to article 6 or any other article of this title, or
the valuation of oil and gas leaseholds and lands pursuant to article 7 of this
title.
(18)
(a) The general assembly hereby finds and declares that real property that
is located in a district in which limited gaming is authorized but that is not
used for limited gaming may be unfairly valued by comparison of said real
property with real property that is used for limited gaming. The general
assembly further finds that real property that is located in a gaming district
may be reasonably used for purposes other than limited gaming, that such
alternative uses may be beneficial in strengthening the economies of gaming
districts, and that such alternative uses should be encouraged. In addition,
the general assembly finds that applying the cost and market approaches to
appraisal in valuing real property that is located in a limited gaming district
but that is not used for limited gaming may result in an unfairly high
valuation of real property that is reasonably used for a purpose other than
limited gaming. Therefore, the provisions of this subsection (18) shall govern
the classification and valuation of real property that is located within a
gaming district but that is not used for limited gaming.
(b) For
property tax years beginning on or after January 1, 1999, if the actual use as
of the assessment date of any real property that is located in a limited gaming
district but that is not used for limited gaming is used as residential real
property, the real property shall be classified as residential real property,
and the assessing officer shall determine the actual value of said real
property as of the assessment date by applying the market approach to
appraisal. If, due to the limited number of real properties located within a
limited gaming district that are not used for limited gaming and that are used
as residential real property, comparable valuation data is not available from
within a limited gaming district to determine adequately the actual value of
real property located within said limited gaming district that is not used for
limited gaming and that is used as residential real property, notwithstanding
any law to the contrary, the assessing officer shall consider sales of
reasonably comparable residential real property located inside and outside of
any limited gaming district for purposes of utilization of the market approach
to appraisal in determining the actual value of said real property located
within a limited gaming district that is not used for limited gaming and that
is used as residential real property.
(c) For
property tax years beginning on or after January 1, 1999, if the actual use as
of the assessment date of any real property that is located in a limited gaming
district is not for limited gaming or as residential real property, including
but not limited to vacant land, the real property shall be classified as
nongaming real property, and the assessing officer shall determine the actual
value of said real property as of the assessment date by giving appropriate
consideration to the cost, market, and income approaches to appraisal. If, due
to the limited number of real properties located within a limited gaming
district that are not used for limited gaming or as residential real property,
comparable valuation data is not available from within a limited gaming
district to determine adequately the actual value of real property located
within said limited gaming district that is not used for limited gaming or as
residential real property, notwithstanding any law to the contrary, the
assessing officer shall:
(I)
Consider sales of reasonably comparable real property that is not used as
residential property located inside and outside of any limited gaming district
for purposes of utilization of the market approach to appraisal in determining
the actual value of real property located within a limited gaming district that
is not used for limited gaming or as residential real property; and
(II)
Consider reasonably comparable real property that is not used as residential
property located inside and outside of any limited gaming district for purposes
of utilization of the income approach to appraisal in determining the actual
value of real property located within a limited gaming district that is not
used for limited gaming or as residential real property.
(d) For
purposes of this subsection (18), real property is considered to be "used
for limited gaming" if the owner or lessee of the real property holds a
retail gaming license issued pursuant to part 5 of article 30 of title 44, and
if the owner or lessee actually uses the real property in offering limited
gaming for play or for administrative support services related to providing
limited gaming or makes the real property available for other uses by persons
who are engaged in limited gaming for play, including but not limited to using
the property for parking, for a restaurant, or for a hotel or motel.
Source:
L. 64: R&RE,
p. 676, § 1. C.R.S. 1963: § 137-1-3. L. 67: p. 945, §§ 2-4. L.
70: p. 380, § 9. L. 71: p. 1242, § 1. L. 73: pp. 237, 1429,
§§ 18, 1. L. 75: (6)(a)(I) amended, p. 1453, § 1, effective May 22;
(4)(b) repealed, p. 1473, § 30, effective July 18. L. 76: (5) amended,
p. 754, § 3, effective January 1, 1977. L. 77: (5) amended and (7) and
(8) added p. 1729, § 2, effective June 20; (4)(b) RC&RE, p. 1740, § 2,
effective January 1, 1978. L. 81: (5)(a) amended, p. 1829, § 1,
effective June 12. L. 83: (8)(d) amended, p. 1489, § 1, effective April
21; (9) added, p. 1492, § 1, effective April 21; (4)(a) and (5)(b) repealed and
(5)(a), IP(8), and (8)(a) amended, pp. 1485, 1480, §§ 11, 2, effective April
22; (6) repealed, p. 1488, § 6, effective June 1. L. 84: (8)(e) and
(8)(f) added, p. 986, § 1, effective March 16; (10) added, p. 987, § 1,
effective April 5. L. 85: (5)(b) RC&RE, (8)(a) amended, and (11) and
(12) added, pp. 1210, 1211, §§ 3, 4, effective May 9; (5)(a) amended, p. 1217,
§ 1, effective May 24. L. 87: (7) repealed, p. 1304, § 1, effective May
20; (13) added, p. 1415, § 2, effective June 16; (8)(e) amended, p. 1388, § 9,
effective June 20. L. 88: (14) added, p. 1281, § 4, effective January 1,
1989. L. 89: (8)(a)(I) amended, p. 1482, § 4, effective May 9; (14)(b)
and (14)(c)(I) amended, p. 1449, § 1, effective June 7. L. 90: (5)(c),
(14)(d), and (14)(e) added, (8)(a)(I) and (14)(b) amended, and (8)(e) repealed,
pp. 1701, 1688, 1705, §§ 34, 3, 2, 41, effective June 9; (15) added, p. 1697, §
22, effective January 1, 1991. L. 91: (8)(a)(I) amended, p. 2005, § 3,
effective June 6. L. 92: (14)(b) amended, p. 2215, § 1, effective June
2. L. 93: (10) amended, p. 654, § 22, effective April 30; (5)(c)
amended, p. 1743, § 2, effective July 1. L. 95: (8)(a)(I) amended, p. 8,
§ 2, effective March 9; (5)(a) amended and (5)(d) added, p. 174, § 3, effective
April 7. L. 96: (16) added, p. 130, § 1, effective March 25; (5)(a) and
(8)(a)(I) amended, p. 718, § 1, effective May 22; (14)(c) amended, p. 1198, §
1, effective June 1; (17) added, p. 1852, § 4, effective June 5. L. 97:
(17)(a)(II)(B) amended, p. 1030, § 63, effective August 6. L. 98: (18)
added, p. 110, § 1, effective March 23. L. 2000: (5)(a) amended, p.
1499, § 2, effective August 2. L. 2002: IP(17)(a) amended, p. 1008, § 1,
effective August 7; (10.5) added, p. 1672, § 2, effective January 1, 2003. L.
2003: (17)(a)(II)(A) amended, p. 1696, § 1, effective January 1, 2004;
(17)(a)(II)(B) amended, p. 2492, § 1, effective January 1, 2004. L. 2004:
(17)(a)(II)(A) amended, p. 1088, § 1, effective January 1, 2005. L. 2010:
(5)(a) amended, (HB 10-1197), ch. 175, p. 634, § 2, effective August 11. L.
2011: (5)(c) amended, (HB 11-1042), ch. 138, p. 480, § 2, effective May 4. L.
2015: (5)(c) amended and (5)(e) and (5)(f) added, (HB 15-1008), ch. 90, p.
258, § 1, effective April 10. L. 2018: (5)(c) amended, (HB 18-1283), ch.
270, p. 1666, § 2, effective August 8; (18)(d) amended, (SB 18-034), ch. 14, p.
249, § 45, effective October 1. L. 2021: IP(10.5)(b) amended, (SB 21-293),
ch. 301, p. 1812, § 11, effective June 23; (5)(a) amended, (HB 21-1312), ch.
299, p. 1791, § 4, effective July 1. L. 2022: (10.7) added, (HB
22-1296), ch. 310, p. 2227, § 2, effective August 10. L. 2023: (5)(a)
amended, (SB 23-304), ch. 259, p. 1496, § 1, effective August 7.
Cross
references: For
the legislative declaration in HB 21-1312, see section 1 of chapter 299,
Session Laws of Colorado 2021.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments," see 15 Colo. Law. 798
(1986). For article, "Legislative Update on Property Taxation and New
Arbitration Procedures", see 17 Colo. Law. 1751 (1988). For article,
"Taxation of Possessory Interests in Exempt Property Under S.B.
02-157", see 32 Colo. Law. 81 (Mar. 2003).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Standing to challenge
constitutionality of subsection (5). Members of board of county
commissioners, also empowered to sit as board of equalization to equalize
valuations, lack standing to challenge the constitutionality of ministerial
duties imposed by subsection (5). Bd. of County Comm'rs v. Fifty-first Gen. Ass'y,
198 Colo. 302, 599 P.2d 887 (1979).
The general assembly has
authority to address methods of valuation and differences between types of
possessory uses in assessing their value for taxation purposes. The
legislature has a determinative role in adopting valuation provisions
consistent with the state constitution and has exercised its authority in this
regard by adopting subsection (17). Bd. of County Comm'rs v. Vail Assocs.,
Inc., 19 P.3d 1263 (Colo. 2001).
Method of valuation is
legislative determination. The method by which valuation for taxation
purposes is to be formulated is a legislative function and is not a proper
subject for judicial determination. Bd. of County Comm'rs v. Bd. of Assess.
Appeals, 628 P.2d 156 (Colo. App. 1981); Leavell-Rio Grande v. Bd. of Assess.
Appeals, 753 P.2d 797 (Colo. App. 1988).
Subsection (17) became
effective upon a determination that the state constitution requires that
possessory interests in tax-exempt property be taxed. Bd. of County Comm'rs
v. Vail Assocs., Inc., 19 P.3d 1263 (Colo. 2001); Cantina Grill v. City &
County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd on other grounds, 2015 CO
15, 344 P.3d 870.
Subsection (17) does not
provide the authority for taxation of possessory interests or dictate whether
or not an interest is taxable. Possessory interests are, in and of
themselves, real property interests that are subject to property taxation
unless exempted. Subsection (17) addresses only the valuation of taxable
possessory interests. Rare Air Ltd. v. Prop. Tax Adm'r, 2019 COA 134, 459 P.3d
547.
Subsections (17)(a)(II)(A)
and (B) are not unconstitutionally overbroad. The statute's tax valuation
provisions do not infringe on any constitutionally protected right. Cantina
Grill v. City & County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd on
other grounds, 2015 CO 15, 344 P.3d 870.
Subsection (17)(a)(II)(B) is
not facially vague. The statute is not facially vague for failure to define
which possessory interests in tax-exempt property are taxable because it does
not impose a tax or define taxable interests. Rather, it merely creates a
methodology for valuing a taxable possessory interest in tax-exempt property.
Cantina Grill v. City & County of Denver, 2012 COA 154, 292 P.3d 1144,
aff'd on other grounds, 2015 CO 15, 344 P.3d 870.
Subsection (17)(a)(II)(B) is
not unconstitutionally vague as applied. The plaintiffs' possessory
interests are taxable. Therefore, it cannot be said that this statute,
comprising a set of tax valuation procedures, has been applied to their
properly taxable possessory interests in an unconstitutional manner. Cantina
Grill v. City & County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd on
other grounds, 2015 CO 15, 344 P.3d 870.
The "significant
incidents of ownership" of interests in tax-exempt property are a
predicate for taxation under the statutes and article X of the state
constitution. A possessory interest in tax exempt land is taxable provided
that the possessory interest satisfies a three-pronged test demonstrating
significant incidents of private ownership as determined by the possessor's
right to possession, use, enjoyment, and profits of the property. Bd. of County
Comm'rs v. Vail Assocs., Inc., 19 P.3d 1263 (Colo. 2001).
Three-pronged test
demonstrating significant incidents of private ownership. To be taxable,
the possessory interest must be such that (1) it provides a revenue-generating
capability to the private possessor independent of the government property
owner; (2) the private owner is able to exclude others from making the same use
of the interest; and (3) the private ownership is of sufficient duration to
realize a private benefit. Bd. of County Comm'rs v. Vail Assocs., Inc., 19 P.3d
1263 (Colo. 2001); Cantina Grill v. City & County of Denver, 2012 COA 154,
292 P.3d 1144, aff'd, 2015 CO 15, 344 P.3d 870.
Test applied in Cantina Grill
v. City & County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd, 2015 CO 15,
344 P.3d 870.
The possessory interests in concession
spaces held by several food and beverage concessionaires at Denver
International Airport are taxable under article X of the Colorado
constitution and property tax statutes because the concessionaires' interests
exhibit significant incidents of private ownership under the three-factor test
established in Bd. of County Comm'rs v. Vail Assocs., Inc. Specifically: (1)
the concessionaires' interests are sufficiently exclusive to qualify as real
property interests under the property tax statutes because the concessionaires
have the right to exclude others from using their respective concession spaces;
and (2) the concessionaires' revenue-generating capability is sufficiently
independent from the city that a tax on their possessory interests would not effectively
be a tax on the government. Cantina Grill v. Denver County Bd. of Equaliz.,
2015 CO 15, 344 P.3d 870.
Exclusivity refers to the
interest holder's ability to exclude others from the same use of the particular
area it occupies. The exclusivity factor is met because concessionaires
have the right to exclude others from using each of their concession spaces to
operate a concession business. That a competitor may operate a concession at a
nearby location has no bearing on this factor. Cantina Grill v. Denver County
Bd. of Equaliz., 2015 CO 15, 344 P.3d 870.
Because the exclusivity
factor focuses on whether the interest holder's use of a particular area it
occupies is sufficiently exclusive, the interest holder's inability to exclude
competition from other locations is not probative of exclusivity. Cantina
Grill v. Denver County Bd. of Equaliz., 2015 CO 15, 344 P.3d 870.
To be taxable under article
X of the Colorado constitution, the possessory interest must be sufficiently
exclusive to qualify as a real property interest as defined under the revenue
statutes. The exclusivity factor of the Vail Associates test ensures that
the interest to be taxed is indeed a property interest that is taxable under
article X and the revenue statutes. Cantina Grill v. Denver County Bd. of
Equaliz., 2015 CO 15, 344 P.3d 870.
Absolute exclusivity not
required under the second prong of the analysis. Though the possessory
interest necessarily involves some degree of exclusivity under the second prong
of the three-prong test, absolute exclusivity is not required. Cantina Grill v.
City & County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd, 2015 CO 15,
344 P.3d 870.
A possessory interest does
not depend on the ability to exclude competition. Cantina Grill v. City
& County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd, 2015 CO 15, 344
P.3d 870.
The proper inquiry is
whether others may make the same physical use of the possessory interest as
that of the leaseholder. Because a nonexclusivity provision permitting the
government owner to enter into agreements with other concessionaires to sell
similar items in other locations did not permit other concessionaires the right
to operate out of an existing concessionaire's locations, concessionaires'
possession and occupancy of the taxable possessory interests were sufficiently
exclusive under the second prong of the test. Cantina Grill v. City &
County of Denver, 2012 COA 154, 292 P.3d 1144, aff'd, 2015 CO 15, 344 P.3d 870.
The independence inquiry
does not turn on the source of revenue alone. The degree of control
exercised by the possessory interest holder, not merely its source of revenue,
is relevant to determining whether the possessory interest holder's
revenue-generating capability is sufficiently independent from the government.
Cantina Grill v. Denver County Bd. of Equaliz., 2015 CO 15, 344 P.3d 870.
The totality of the
circumstances must be examined to determine whether an interest holder's
revenue-generating capability is truly independent from the government, or
whether the interest holder is merely an agent of the government, such that any
tax on the interest holder would be a tax on the government. These
circumstances include, but are not limited to, whether: (1) the government pays
a fee to the interest holder for its operation of the property in question; (2)
the government controls the prices the interest holder can charge or restricts
the profits the interest holder can generate; (3) the interest holder provides
the supplies, equipment, and improvements necessary for the operation of the
property; (4) the interest holder is responsible for the expense of maintaining
and repairing the property; and (5) the interest holder has sufficient control
and supervision of its operation. Cantina Grill v. Denver County Bd. of
Equaliz., 2015 CO 15, 344 P.3d 870.
Requirement in subsection
(5)(a) that a property assessor give "appropriate consideration" to
the income, market, and cost approaches does not require complete and
documented calculations of each approach or an explanation of the reasons for
excluding those not used. ASARCO, Inc. v. Bd. of Comm'rs of Lake County, 916
P.2d 550 (Colo. App. 1995).
If the market and income
approaches to valuation are inapplicable or do not produce a meaningful
valuation for assessment purposes, it is appropriate for the assessor to use
only the cost approach. ASARCO, Inc. v. Bd. of Comm'rs of Lake County, 916 P.2d
550 (Colo. App. 1995).
Under the cost approach,
reproduction cost rather than replacement cost was held to be an appropriate
measure in light of the special purpose and regulatory specifications
applicable to an EPA-ordered water treatment facility. ASARCO, Inc. v. Bd. of Comm'rs
of Lake County, 916 P.2d 550 (Colo. App. 1995).
The comparable sales price,
rather than the manufacturer's cost, is the appropriate starting point for the
cost approach. Xerox Corp. v. Bd. of County Comm'rs, 87 P.3d 189 (Colo. App.
2003).
No requirement for assessor
or board to compare valuations with other counties to determine compliance with
article X, § 3, of the Colorado Constitution. The issue of just and equal
valuation among counties is not cognizable in an appeal to the board of an
assessor's valuation, and constitutional requirement does not require an
assessor or a board to compare valuations with those made for comparable properties
in other counties. Bd. of Assess. Appeals v. E.E. Sonnenberg, 797 P.2d 27
(Colo. 1990).
Actual value is the guiding
principle for the taxation of real property in Colorado. Arapahoe County
Bd. of Equaliz. v. Podoll, 935 P.2d 14 (Colo. 1997); San Miguel County Bd. of
Equaliz. v. Telluride Co., 947 P.2d 1381 (Colo. 1997).
Valuing similar property,
similarly situated is consistent with statutory and constitutional mandates to
achieve just and equalized values for purposes of taxation. Telluride Co.
v. County Bd. of Equaliz., 962 P.2d 313 (Colo. App. 1997).
Value determined as of date
of assessment. County assessor has the duty of determining the values of
properties as they existed on the date of the assessment. Colo. & Utah Coal
Co. v. Rorex, 149 Colo. 502, 369 P.2d 796 (1962).
Assessor's valuation
presumed correct. An assessor's ascertainment of the value of property for
taxation is presumed to be right. Colo. & Utah Coal Co. v. Rorex, 149 Colo.
502, 369 P.2d 796 (1962).
Assessors furnished guides
to aid in valuation. In order to promote uniformity and equality in
taxation, assessors are supplied with manuals which furnish them with guides
for determining valuations for tax purposes. Stalder v. Bd. of County Comm'rs,
147 Colo. 493, 364 P.2d 389 (1961); Colo. & Utah Coal Co. v. Rorex, 149
Colo. 502, 369 P.2d 796 (1962).
Clear and convincing
evidence must be adduced to overcome presumption of correctness of an
assessor's valuation of property for taxation. Colo. & Utah Coal Co. v.
Rorex, 149 Colo. 502, 369 P.2d 796 (1962).
Presumption of correction of
assessor's valuation overcome. May Stores Shopping Ctrs., Inc. v.
Shoemaker, 151 Colo. 100, 376 P.2d 679 (1962).
Presumption of correctness
of assessor's valuation rebutted where sufficient evidence presented of
assessor's failure to comply with requirements of subsection (5)(a).
Transamerican Realty Corp. v. Clifton, 817 P.2d 1049 (Colo. App. 1991).
Assessor held not to have
followed mandate of statute in determining "actual value".
Majestic Great W. Sav. & Loan Ass'n v. Reale, 30 Colo. App. 564, 499 P.2d
644 (1972).
Market value usually measure
of "actual value". In determining "actual value",
market value is usually taken as the measure, because most likely to be just
and least difficult of ascertainment. Fellows v. Grand Junction Sugar Co., 78
Colo. 393, 242 P. 635 (1925).
For determination of
"market value", see Union P. R. R. v. Hanna, 73 Colo. 162, 214 P.
550 (1923); Fellows v. Grand Junction Sugar Co., 78 Colo. 393, 242 P. 635
(1925); City & County of Denver v. Lewin, 106 Colo. 331, 105 P.2d 854
(1940); Stalder v. Bd. of County Comm'rs, 147 Colo. 493, 364 P.2d 389 (1961);
Colo. & Utah Coal Co. v. Rorex, 149 Colo. 502, 369 P.2d 796 (1962); May
Stores Shopping Ctrs., Inc. v. Shoemaker, 151 Colo. 100, 376 P.2d 679 (1962).
Trial court has no authority
to make an assessment or fix a valuation. Colo. & Utah Coal Co. v.
Rorex, 149 Colo. 502, 369 P.2d 796 (1962).
Review by the court is
therefore limited to the narrow ascertainment of agency abuse of discretion
by neglecting to abide by the statutes in the calculation of tax assessments.
Leavell-Rio Grande v. Bd. of Assess. Appeals, 753 P.2d 797 (Colo. App. 1988).
The language of the statute
is unambiguous and sets forth an exclusive and restrictive set of unusual
circumstances upon which the assessor may, in his discretion, rely in
calculating the actual value of commercial property. Leavell-Rio Grande v. Bd.
of Assess. Appeals, 753 P.2d 797 (Colo. App. 1988).
Factors, such as a depressed
economy, which encourage rent abatement, are not included within that list of
unusual circumstances. Leavell-Rio Grande v. Bd. of Assess. Appeals, 753
P.2d 797 (Colo. App. 1988).
Unusual conditions affecting
actual value are factors for consideration by the assessor in assessing real
property. Depreciation factors apply only to personal property. CF & I
Steel Corp. v. Patton, 765 P.2d 586 (Colo. App. 1988), rev'd on other grounds,
785 P.2d 605 (Colo. 1990).
Reasonable future use is
relevant to a property's current market value for tax assessment purposes.
Bd. of Assess. Appeals v. Arlberg Club, 762 P.2d 146 (Colo. 1988).
Highest and best future use
of land in its condition at the time of valuation may be considered in
determining present fair market value while speculative future uses may not be
taken into consideration. Bd. of Assess. Appeals v. Arlberg Club, 762 P.2d 146
(Colo. 1988).
Depreciation required to be
calculated annually from the base year to the date of assessment for
valuing personal business property. BQP Indus. v. State Bd. of Equaliz., 694
P.2d 337 (Colo. App. 1984).
Subsection (5)(a) requires
that, if an approach to value is applicable, assessor must give it
appropriate consideration in valuing property. Transamerican Realty Corp. v.
Clifton, 817 P.2d 1049 (Colo. App. 1991).
Subsection (5)(a) requires
only that "appropriate consideration" be given to the cost
approach, market approach, and income approach to appraisal when valuing
property for assessment. Montrose Prop. v. Bd. of Assess. Appeals, 738 P.2d 396
(Colo. App. 1987).
However, where an assessor gave
no consideration to the market or income approach to assessment of property
because of financial and time constraints, the evidence did not support a
conclusion that appropriate consideration was given to all three statutorily
recognized approaches. Sonnenberg & Sons v. Bd. of Assess. Appeals, 768
P.2d 748 (Colo. App. 1988), aff'd in part, rev'd in part on other grounds, 797
P.2d 27 (Colo. 1990).
In valuing in accordance with
constitutional and statutory requirements, the cost approach, market approach,
and income approach must be considered by the assessor, but one or more of the
three approaches may not be applicable in a particular case. The nature of the
property may rule out consideration of one or more approaches or there may be
insufficient data to allow all of the approaches to be used. 501 So. Cherry J.
Venture v. Arapahoe County, 817 P.2d 583 (Colo. App. 1991).
Assessor's failure to consider
income approach due to time constraints imposed in conducting major reappraisal
in county, in addition to failure to adequately document market or cost
approaches applied, violated statutory requirement to give "appropriate
consideration" to all applicable approaches to valuation. Transamerican
Realty Corp. v. Clifton, 817 P.2d 1049 (Colo. App. 1991).
In giving "appropriate
consideration", assessor must consider and document all applicable
approaches to valuation. Transamerican Realty Corp. v. Clifton, 817 P.2d
1049 (Colo. App. 1991).
"Appropriate
consideration" of the cost approach, market approach, and income approach
does not include consideration and documentation of inapplicable approaches. CF
& I Steel Corp. v. Patton, 765 P.2d 586 (Colo. App. 1988), rev'd on other
grounds, 785 P.2d 605 (Colo. 1990).
However, if an approach to
value is applicable, it must be given appropriate consideration by the
assessor, as well as by the board of assessment appeals (BAA), as the trier of
fact. Home Depot USA, Inc. v. Pueblo County Bd. of Comm'rs, 50 P.3d 916 (Colo.
App. 2002).
Assessor was required to
give appropriate consideration to the cost, market, and income approaches to
appraisal when valuing a nonproducing mine undergoing reclamation that
could not be classified as agricultural land. Hepp v. Boulder County Assessor,
113 P.3d 1268 (Colo. App. 2005).
Market value approach to
value mandates that appraiser determine the probable sales price for
property by considering what other comparable properties actually sold for in
the market place at or about the date for which a value is sought. Home Fed.
Sav. v. Larimer County, 857 P.2d 562 (Colo. App. 1993).
The income approach is an
important method for valuing office buildings, but it is not held as a
matter of law that any particular approach must be used under the statutory
scheme. The county assessor should determine proper valuation of taxpayer's
property after appropriate consideration of the three approaches designated by
the general assembly, after proper analysis of the applicable approaches, and
after systematic correlation to reach a final estimate of value. 501 So. Cherry
J. Venture v. Arapahoe County, 817 P.2d 583 (Colo. App. 1991).
Actual rent generated from a
lease is a valid factor to be considered in determining the actual or
market value of the property for purposes of assessment. Bd. of Assess. Appeals
v. City & County of Denver, 829 P.2d 1319 (Colo. App. 1991), aff'd, 848
P.2d 355 (Colo. 1993).
Resort's income from rental
management fees paid by condominium owners is excluded from valuation under the
income approach to valuation. When a resort includes a corporate-owned
hotel and separately owned condominium units, fees paid to a subsidiary of the
hotel owner by the condominium unit owners for rental management services are
not income that the hotel generates because the hotel and the condominium units
are legally separate and distinct parcels of property that must be separately
valued and appraised and the income used to pay the fees is derived from the
rental of the condominium units. Lodge Props. v. Eagle Bd. of Equaliz., 2022 CO
9, 504 P.3d 960.
Assessor's technical
violation of the notification and timing requirements of subsection (5)(c)
that does not prejudice taxpayers' substantive rights does not justify reversal
of an order of the BAA upholding the assessor's classification of taxpayers'
property. Johnston v. Park County Bd. of Equaliz., 979 P.2d 578 (Colo. App.
1999).
Applicability of subsection
(8)(d). Subsection (8)(d), requiring 30 sales of comparable properties
within county in order to establish sales ratio for properties within that
county, does not apply to the market valuation of property for property tax
purposes. Sonnenberg & Sons v. Bd. of Assess. Appeals, 768 P.2d 748 (Colo.
App. 1988), aff'd in part, rev'd in part on other grounds, 797 P.2d 27 (Colo.
1990).
Abuse of discretion by BAA
exists where board failed to consider evidence of value of similar properties
in other counties in Colorado and other states for purposes of property tax
assessment. Platinum Props. v. Assess. Appeals Bd., 738 P.2d 34 (Colo. App.
1987).
Under subsection (9), if
property is partially put to residential use and partially put to commercial
hotel use, a mixed-use classification and allocation is appropriate. The
primary factor to be considered in determining the proper classification for
tax purposes is the actual use of the property on the relevant assessment date.
E.R. Southtech, Ltd. v. BOE, 972 P.2d 1057 (Colo. App. 1998).
BAA's ruling assigning a
mixed-use classification to the subject property based on the breakdown of
stays of less than 30 days and stays of 30 days or more is supported by the
evidentiary record and has a reasonable basis in law. Thus, under the
applicable standard of review, the BAA's classification determination will not
be disturbed on review. E.R. Southtech, Ltd. v. BOE, 972 P.2d 1057 (Colo. App.
1998).
The determination as to the
appropriate allocation percentages to be assigned to the residential and
commercial uses of the property was a question of fact for the BAA to decide,
based on its evaluation of the evidence presented. Because the BAA's factual
determination in this regard is supported by competent and substantial evidence
in the record as a whole, its ruling will not be disturbed on appeal. E.R.
Southtech, Ltd. v. BOE, 972 P.2d 1057 (Colo. App. 1998).
Taxation of development
rights separately from the common elements does not contravene subsection (10).
The assignment of the development rights evinced the intent to sever title to
the development rights from the condominiums, including severance from the
common elements. Vill. at Treehouse v. Prop. Tax Adm'r, 2014 COA 6, 321 P.3d
624.
Cost cap valuation method
under subsection (13) does not apply to a public utility, which is assessed
under the valuation method established in part 4 of this article. Qwest v.
Colo. Div. of Prop. Taxation, 2013 CO 39, 304 P.3d 217.
The assessor and the BAA are
unambiguously required to give consideration to the factors set forth in
subsection (14)(b), when determining the actual value of vacant land using
the market approach. The assessor may not avoid this requirement by claiming
that 80% of the lots within the "market area" had been
"developed". When determining whether 80% of the lots of the
subdivision within which the vacant land is located have been sold, some
general concept of a "market area" may not be substituted for the
specific area included within the boundaries of the approved plat for that
subdivision. Sunbelt Serv. Corp. v. Bd. of Assess. Appeals, 802 P.2d 1199
(Colo. App. 1990).
Subsection (14)(b) does not
require the assessor to apply the anticipated market absorption rate. This
is true even though the assessor and the property tax administrator have
determined that the application of such rate is not appropriate. El Paso County
Bd. of Equaliz. v. Craddock, 850 P.2d 702 (Colo. 1993).
Although the anticipated
market absorption rate must be taken into account when assessing vacant
land, other factors may lead the assessor to conclude that the application of
such rate is not appropriate. El Paso County Bd. of Equaliz. v. Craddock, 850
P.2d 702 (Colo. 1993).
The factors listed in
subsection (14)(b) must be taken into account by assessors, but the general
assembly did not direct that assessors be limited to those factors. El Paso
County Bd. of Equaliz. v. Craddock, 850 P.2d 702 (Colo. 1993).
Trial court erred in
interpreting subsection (14)(b) as requiring both consideration and application
of the market absorption rate. Although the anticipated market absorption
rate must be considered, when assessing vacant land, its application is not
mandatory. The assessor may take into account other factors, including the
similarity of the tracts or their anticipated use, which may lead to the
conclusion that the application of the market absorption rate is not
appropriate. The assessor must document those factors, however, to allow
meaningful review of its decision. Resolution Trust Corp. v. Bd. of County
Comm'rs of Arapahoe County, 860 P.2d 1383 (Colo. App. 1993).
Market absorption rate is
intended to be used in conjunction with comparable sales data in order to
insure that the time and up-front costs connected with selling a quantity of
individual lots have been reflected in the valuation. Resolution Trust Corp. v.
Bd. of County Comm'rs, 904 P.2d 1363 (Colo. App. 1995).
BAA correctly interpreted
subsection (14) to include developer's profit and overhead in the cost of
development which may be deducted from the valuation of vacant land. Commercial
Fed. Sav. & Loan Ass'n v. Douglas County, 867 P.2d 17 (Colo. App. 1993).
Subsection (14) as in effect
prior to the 1992 amendment required assessors to take indirect costs into
account when valuing vacant land under the market approach. The 1992
amendment to this subsection was found to have changed, rather than clarified,
the earlier version of the statute because the legislative history does not
evince a clear intent to merely clarify the language of the statute. Douglas
County Bd. of Equaliz. v. Fid. Castle Pines, 890 P.2d 119 (Colo. 1995).
Subsection (14)(b),
prohibiting assessors from considering the indirect costs of development in
ascertaining the assessment value of vacant land under the present worth
valuation method does not violate article X, § 3, of the Colorado
Constitution, which requires the assessor to determine the actual value of
property. Fid. Castle Pines, Ltd. v. State, 948 P.2d 26 (Colo. App. 1997).
Subsection (14)(b) does not
violate article X, § 3, of the Colorado Constitution by creating a separate
class of commercial property, nor does it create an unreasonable classification
of commercial property. Fid. Castle Pines, Ltd. v. State, 948 P.2d 26
(Colo. App. 1997).
When the assessor presents
evidence of all three approaches to valuation, it would impose an onerous and
unnecessary burden also to require the taxpayer to provide those valuations.
Because neither the constitution nor the statute imposes such a requirement,
the court will not so interpret them. Principal Mut. Ins. v. Bd. of Equaliz.,
890 P.2d 273 (Colo. App. 1994).
Valuation based upon
assessor's formulation of an open space acquisition rate determined from a
sales average of unbuildable land in the county was appropriate when the
cost, market, and income approaches could not be used. Hughey v. Jefferson
County Bd. of Comm'rs, 921 P.2d 76 (Colo. App. 1996).
While equalization of the
basis for taxation is the end sought to be achieved by uniform laws and by
uniform means and methods of assessment, perfect uniformity in actual
assessment is not required under either this section or the constitution.
Crocog Co. v. Arapahoe County Bd. of Equaliz., 813 P.2d 768 (Colo. App. 1990);
Bishop v. Colo. Bd. of Assess. Appeals, 899 P.2d 251 (Colo. App. 1994).
Taxpayers who protest
property tax assessments have the burden of proving that the assessment is
incorrect. Leavell-Rio Grande v. Bd. of Assess. Appeals, 753 P.2d 797 (Colo.
App. 1988); 501 So. Cherry J. Venture v. Arapahoe County, 817 P.2d 583 (Colo.
App. 1991).
Property tax valuation
challenge. A taxpayer has the statutory right to challenge a property tax
valuation for each tax year under the protest and adjustment procedure and
possibly through de novo evidentiary proceedings before the BAA. Weingarten v.
Bd. of Assess. Appeals, 876 P.2d 118 (Colo. App. 1994).
Where the record shows that the
method used in determining an actual value for assessment purposes was one
specified by statute, taxpayers are precluded from protesting utilization of
such method. Leavell-Rio Grande v. Bd. of Assess. Appeals, 753 P.2d 797 (Colo.
App. 1988).
In order to adopt the
taxpayer's valuation, the court must find that the taxpayer's expert
complied with the property tax administrator's guidelines. Resolution Trust
Corp. v. Bd. of County Comm'rs of Arapahoe County, 860 P.2d 1383 (Colo. App.
1993).
Where neighboring property
was erroneously assessed during one tax year and the assessment was later
corrected, complaining taxpayer has no standing to seek an order mandating
a reassessment of the parcel erroneously assessed, and the court lacks
authority to grant such relief. Crocog Co. v. Arapahoe County Bd. of Equaliz.,
813 P.2d 768 (Colo. App. 1990); Bishop v. Colo. Bd. of Assess. Appeals, 899
P.2d 251 (Colo. App. 1994).
Subsection (5) reflects
legislative intent to allow reclassification upon a change of actual use.
Nothing in the statute indicates that the provisions of subsection (5) are
inapplicable to residential real property. Mission Viejo v. Douglas Cty. Bd. of
Equaliz., 881 P.2d 462 (Colo. App. 1994).
Abandoned and uninhabited
structure that did not contribute to the value of the property should be
disregarded rather than valued separately. Resolution Trust Corp. v. Bd. of
County Comm'rs of Arapahoe County, 860 P.2d 1383 (Colo. App. 1993).
Abandoned farmhouse on
otherwise vacant parcel was "minor structure" within the meaning of
administrative guidelines defining vacant land for purposes of determining
whether the market absorption rate applied to the parcel. Resolution Trust
Corp. v. Bd. of County Comm'rs, 904 P.2d 1363 (Colo. App. 1995).
Collateral estoppel does not
bind the assessor with respect to property tax exemptions except as to the tax
year actually at issue in the prior administrative proceedings. Guest
Mansions, Inc. v. Arapahoe County Bd. of Equaliz., 899 P.2d 944 (Colo. App.
1995).
Trial court did not err in
accepting mass appraisal method of valuation in valuing 20 vacant
residential lots. C.P. & Son v. Bd. of County Comm'rs, 953 P.2d 1303 (Colo.
App. 1998).
Tax-exempt areas outside
building footprints at a federally funded public airport were properly excluded
under subsection (17)(a)(II)(B) from valuation of leased parcels that were
taxable possessory interests. Such areas are to be included in the
valuation of a possessory interest in tax-exempt property only if the holder of
the possessory interest has an exclusive right to possess and use the areas
that is absolute and the areas included paved lanes running to and from
runways, terminals, aircraft hangars, and other facilities that the holder
could not exclude others from using under the terms of the lease. Denver
jetCenter, Inc. v. Arapahoe County Bd. of Equaliz., 148 P.3d 228 (Colo. App.
2006).
Applied in Golden Gate
Dev. v. Gilpin Cty. Bd., 856 P.2d 72 (Colo. App. 1993).
39-1-103.5. Restrictions on information.
The state
board of equalization or the administrator shall not require any person to
furnish financial information concerning commercial or industrial property,
except as to the value of the real property for rental purposes only. This
section shall not apply to public utilities.
Source:
L. 77: Entire
section added, p. 1731, § 3, effective June 20.
39-1-103.8. Valuation for assessment -
future increases. (Repealed)
Source:
L. 2020: Entire
section added, (SB 20-223), ch. 291, p. 1436, § 1, effective January 1, 2021. L.
2021: Entire section repealed, (SB 21-293), ch. 301, p. 1806, § 1,
effective June 23.
39-1-104. Valuation for assessment -
definitions.
(1) (a)
For property tax years commencing before January 1, 2025, the valuation for
assessment of all taxable property in the state is twenty-nine percent of the
actual value thereof as determined by the assessor and the administrator in the
manner prescribed by law, and that percentage shall be uniformly applied,
without exception, to the actual value, so determined, of the real and personal
property located within the territorial limits of the authority levying a
property tax, and all property taxes shall be levied against the aggregate
valuation for assessment resulting from the application of that percentage.
(b)
Notwithstanding subsection (1)(a) of this section, for the property tax years
commencing on January 1, 2023, and January 1, 2024, the valuation for
assessment of nonresidential property that is classified as lodging property is
temporarily reduced to twenty-seven and nine-tenths percent of an amount equal
to the actual value minus the lesser of thirty thousand dollars or the amount
that reduces the valuation for assessment to one thousand dollars.
(c)
This subsection (1) only applies to nonresidential property that is classified
as lodging property.
(1.5)
Repealed.
(1.6)
(a) Hotels, motels, bed and breakfasts, and personal property located at a
hotel, motel, or bed and breakfast are classified as lodging property, which is
a subclass of nonresidential property for purposes of the valuation for
assessment. Classification as a lodging property does not affect a partial
allocation as residential real property if a lodging property is a mixed-use
property.
(b)
Real and personal property valued under section 39-4-102 (1)(e) or (1.5) or
section 39-5-104.7 is classified as renewable energy production property, which
is a subclass of nonresidential property for purposes of the valuation for
assessment.
(c)
Real and personal agricultural property is a subclass of nonresidential
property for purposes of the valuation for assessment.
(1.8)
(a) For property tax years commencing before January 1, 2025, the valuation
for assessment of real and personal property that is classified as agricultural
property or renewable energy production property is twenty-nine percent of the
actual value thereof; except that, for property tax years commencing on January
1, 2022, January 1, 2023, and January 1, 2024, the valuation for assessment of
this property is temporarily reduced to twenty-six and four-tenths percent of
the actual value thereof.
(b) For
property tax years commencing before January 1, 2025, the valuation for
assessment of all nonresidential property that is not specified in subsection
(1) or (1.8)(a) of this section is twenty-nine percent of the actual value
thereof; except that, for the property tax years commencing on January 1, 2023,
and January 1, 2024, the valuation for assessment of this property is
temporarily reduced to:
(I) For
all of the property listed by the assessor under any improved commercial
subclass codes, twenty-seven and nine-tenths percent of an amount equal to the
actual value minus the lesser of thirty thousand dollars or the amount that
reduces the valuation for assessment to one thousand dollars; and
(II)
Twenty-seven and nine-tenths percent of the actual value of all other
nonresidential property that is not specified in subsections (1), (1.8)(a), and
(1.8)(b)(I) of this section.
(b.5)
Repealed.
(c) The
actual value of real and personal property specified in subsection (1.8)(a) or
(1.8)(b) of this section is determined by the assessor and the administrator in
the manner prescribed by law, and a valuation for assessment percentage is
uniformly applied, without exception, to the actual value, so determined, of
the various classes and subclasses of real and personal property located within
the territorial limits of the authority levying a property tax, and all
property taxes are levied against the aggregate valuation for assessment
resulting from the application of the percentage.
(d) As
used in this section, unless the context otherwise requires,
"nonresidential property" means all taxable real and personal
property in the state other than residential real property, producing mines, or
lands or leaseholds producing oil or gas. Nonresidential property includes the
subclasses of agricultural property, lodging property, and renewable energy
production property for purposes of the ratio of valuation for assessment.
(1.9)
(a) For the property tax year commencing on January 1, 2025, the valuation
for assessment for personal property and nonresidential real property is
twenty-seven percent of the actual value thereof.
(b) For
the property tax year commencing on January 1, 2026, the valuation for
assessment for personal property and nonresidential real property is twenty-six
percent of the actual value thereof; except that, for all property listed by
the assessor under any improved commercial subclass codes and all real or
personal property that is classified as agricultural property, the valuation
for assessment is twenty-five percent of the actual value thereof.
(c) For
property tax years commencing on or after January 1, 2027, the valuation for
assessment for personal property and nonresidential real property is
twenty-five percent of the actual value thereof.
(d) The
actual value of real and personal property specified in this subsection (1.9)
is determined by the assessor and the administrator in the manner prescribed by
law, and a valuation for assessment percentage is uniformly applied, without
exception, to the actual value, so determined, of the various classes and
subclasses of real and personal property located within the territorial limits
of the authority levying a property tax, and all property taxes are levied
against the aggregate valuation for assessment resulting from the application
of the percentage.
(2)
Repealed.
(3)
"Valuation for assessment", as used in this section and in articles 1
to 13 of this title, means the same as the term "assessed valuation"
as that term may appear in the laws of this state.
(4)
Except as provided in section 39-7-109, nonproducing severed mineral interests
are to be valued at twenty-nine percent of actual value in the same manner as
other real property specified in subsection (1.8)(b) of this section. Such
valuation shall be determined by the assessing officer only upon preponderant
evidence shown by such officer that the cost approach, market approach, and
income approach result in uniform and just and equal valuation.
(5) to
(10.1) Repealed.
(10.2)
(a) Except as otherwise provided in subsection (12) of this section,
beginning with the property tax year which commences January 1, 1989, a
reassessment cycle shall be instituted with each cycle consisting of two full
calendar years. At the beginning of each reassessment cycle, the level of value
to be used during the reassessment cycle in the determination of actual value
of real property in any county of the state as reflected in the abstract of
assessment for each year in the reassessment cycle shall advance by two years
over what was used in the previous reassessment cycle; except that the level of
value to be used for the years 1989 and 1990 shall be the level of value for
the period of one and one-half years immediately prior to July 1, 1988; except
that, if comparable valuation data is not available from such
one-and-one-half-year period to adequately determine the level of value for a
class of property, the period of five years immediately prior to July 1, 1988,
shall be utilized to determine the level of value. Said level of value shall be
adjusted to the final day of the data gathering period.
(b)
During the two years of each reassessment cycle, in preparation for
implementation in the succeeding reassessment cycle, the respective assessors
shall conduct revaluations of all taxable real property utilizing the level of
value for the period which will be used to determine actual value in such
succeeding reassessment cycle and the manuals and associated data published for
the period which will be used to determine actual value in such succeeding
reassessment cycle.
(c)
Repealed.
(d) For
the purposes of this article and article 9 of this title, "level of
value" means the actual value of taxable real property as ascertained by
the applicable factors enumerated in section 39-1-103 (5) for the
one-and-one-half-year period immediately prior to July 1 immediately preceding
the assessment date for which the administrator is required by this article to
publish manuals and associated data. Beginning with the property tax year
commencing January 1, 1999, if comparable valuation data is not available from
such one-and-one-half-year period to adequately determine such actual value for
a class of property, "level of value" means the actual value of
taxable real property as ascertained by said applicable factors for such
one-and-one-half-year period, the six-month period immediately preceding such
one-and-one-half-year period, and as many preceding six-month periods within
the five-year period immediately prior to July 1 immediately preceding the
assessment date as are necessary to obtain adequate comparable valuation data.
Said level of value shall be adjusted to the final day of the data-gathering
period.
(e)
Repealed.
(10.3)
Repealed.
(11) (a)
(I) It is the intent of the general assembly, as manifested in subsection
(10.2) of this section, that, when a change occurs in reassessment cycles as
prescribed in said subsection, new manuals and associated data will be
published by the administrator, pursuant to section 39-2-109 (1)(e), and that
said manuals and associated data and the level of value for the year that said
manuals and associated data are published shall be utilized by assessors in the
manner described in subsection (10.2) of this section for determining the
actual value of real property in each county of the state.
(II)
The general assembly hereby further finds and declares that it is the intent of
paragraph (b) of this subsection (11) to comply with the provisions of section
3 of article X of the state constitution, including the provision which
requires the enactment of "general laws, which shall prescribe such
methods and regulations as shall secure just and equalized valuations for
assessments of all real and personal property"; to reduce the confusion of
the owners of taxable property within the state concerning assessment
procedures and valuations of such property; to achieve valuations for
assessment which represent the current value of such property to the extent
which is equitably and practically possible; and to minimize the costs
associated with achieving such current valuations for assessment.
(b) (I)
The provisions of subsection (10.2) of this section are not intended to prevent
the assessor from taking into account, in determining actual value for the
years which intervene between changes in the level of value, any unusual
conditions in or related to any real property which would result in an increase
or decrease in actual value. If any real property has not been assessed at its
correct level of value, the assessor shall revalue such property for the
intervening year so that the actual value of such property will be its correct
level of value; however, the assessor shall not revalue such property above or
below its correct level of value except as necessary to reflect the increase or
decrease in actual value attributable to an unusual condition. For the purposes
of this paragraph (b) and except as otherwise provided in this paragraph (b),
an unusual condition which could result in an increase or decrease in actual
value is limited to the installation of an on-site improvement, the ending of
the economic life of an improvement with only salvage value remaining, the
addition to or remodeling of a structure, a change of use of the land, the
creation of a condominium ownership of real property as recognized in the
"Condominium Ownership Act", article 33 of title 38, C.R.S., any new
regulations restricting or increasing the use of the land, or a combination
thereof, the installation and operation of surface equipment relating to oil
and gas wells on agricultural land, any detrimental acts of nature, and any
damage due to accident, vandalism, fire, or explosion. When taking into account
such unusual conditions which would increase or decrease the actual value of a
property, the assessor must relate such changes to the level of value as if the
conditions had existed at that time.
(II)
The creation of a condominium ownership of real property by the conversion of
an existing structure shall be taken into account as an unusual condition as
provided for in subparagraph (I) of this paragraph (b) by the assessor, when at
least fifty-one percent of the condominium units, as defined in section
38-33-103 (1), C.R.S., in a multiunit property subject to condominium ownership
have been sold and conveyed to bona fide purchasers and deeds have been
recorded therefor.
(c)
Repealed.
(12)
(a) For the property tax years commencing on or after January 1, 1987,
producing mines shall be valued for assessment solely pursuant to article 6 of
this title.
(b) For
the property tax years commencing on or after January 1, 1987, oil and gas
leaseholds and lands shall be valued for assessment solely pursuant to section
39-7-102.
(c)
Repealed.
(12.1)
Repealed.
(12.2)
(a) Except as provided in subsection (12) of this section, for property tax
years commencing on or after January 1, 1987, the requirement stated in
subsections (10.2) and (11) of this section that the actual value of real
property be determined according to a specified year's level of value and
manuals and associated data published by the administrator for said specified
year pursuant to section 39-2-109 (1)(e) shall apply to the assessment of all
classes of real property, including but not limited to the following classes of
real property:
(I)
(Deleted by amendment, L. 87, p. 1390, § 2, effective April 1, 1987.)
(II)
(Deleted by amendment, L. 87, p. 1392, § 2, effective April 1, 1987.)
(III)
Operating property and plants of public utilities; and
(IV)
Agricultural land.
(V)
(Deleted by amendment, L. 87, p. 1385, § 1, effective June 20, 1987.)
(b)
This subsection (12.2) shall take effect January 1, 1987.
(12.3) (a)
(I) The actual value of personal property is determined by appropriate
consideration of such of the three approaches specified in section 39-1-103
(5)(a) as are applicable to the appraisal of such property and is based on the
property's value in use. Subject to review and approval pursuant to section
39-2-109 (1)(e), the administrator shall prepare and publish appraisal
procedures and instructions for the annual appraisal of such property that
include a definition of "value in use" and a factor or factors to
adjust the actual value for the current year of assessment to the level of
value applicable to real property.
(II) In
determining actual value, depreciation attributable to age shall not exceed
that for the actual age of the property on the assessment date. Physical,
functional, and economic obsolescence shall be considered in determining actual
value.
(b)
Repealed.
(12.4)
For property tax years commencing on and after January 1, 1987, the requirement
stated in subsections (10.2) to (11) of this section that the actual value of
real property be determined according to a specified year's level of value and
manuals and associated data published by the administrator for said specified
year pursuant to section 39-2-109 (1)(e) shall not apply to the assessment of
producing coal mines and other lands producing nonmetallic minerals.
(13) to
(15) Repealed.
(16) (a)
During each property tax year, the director of research of the legislative
council shall contract with a private person for a valuation for assessment
study to be conducted as set forth in this subsection (16). The study shall be
conducted in all counties of the state to determine whether or not the assessor
of each county has, in fact, used all manuals, formulas, and other directives
required by law to arrive at the valuation for assessment of each and every
class of real and personal property in the county. The person conducting the
study shall sample each class of property in a statistically valid manner, and
the aggregate of such sampling shall equal at least one percent of all
properties in each county of the state. The sampling shall show that the
various areas, ages of buildings, economic conditions, and uses of properties
have been sampled. Such study shall be completed, and a final report of the
findings and conclusions thereof shall be submitted to the state board of
equalization, by September 15 of the year in which the study is conducted.
(b)
During each property tax year, beginning with the property tax year which
commences January 1, 1985, in addition to the requirements set forth in
paragraph (a) of this subsection (16), the study shall set forth the aggregate
valuation for assessment of each county for the year in which the study is
conducted.
(c) The
person conducting any valuation for assessment study pursuant to this
subsection (16) and his employees shall, during the term of his contract, have
access to any document in the custody of the administrator or an assessor,
including, but not limited to, such documents as are held pursuant to sections
39-4-103, 39-5-120, and 39-14-102 (1)(c). The penalties in section 39-1-116
apply against the divulging at any time of any confidential information
obtained pursuant to this paragraph (c).
(d)
Repealed.
Source:
L. 64: R&RE,
p. 676, § 1. C.R.S. 1963: § 137-1-4. L. 65: p. 1096, § 2. L.
67: p. 946, § 5. L. 70: pp. 380, 388, §§ 10, 28. L. 73: p.
1430 § 1. L. 75: (5) and (6) added, pp. 863, 1474, §§ 2, 1, effective
July 1; (7) added, p. 1454, § 1, effective July 30. L. 76: (9) added, p.
755, § 5, effective July 1; (8) added, p. 755, § 4, effective January 1, 1977. L.
77: (10) R&RE and (11) and (12) added, pp. 1731, 1732, §§ 4, 5,
effective June 20. L. 79: (13) added, p. 1329, § 2, effective May 8; (6)
R&RE and (14) added, pp. 1403, 1327, §§ 1, 4, effective July 1; (2)
amended, p. 1402, § 1, effective January 1, 1980. L. 80: (10) amended,
p. 714, § 1, effective February 29; (9) amended, p. 711, § 1, effective April
16. L. 81: (13)(b) amended, p. 1836, § 1, effective June 4; (9)(a),
(10)(a), (10)(b), and IP(12) amended, p. 1830, § 2, effective June 12; (12)(c),
(12)(d), (12)(g), and (12)(h) amended, pp. 1848, 1854, §§ 4, 2, effective
January 1, 1982; (16) added, p. 1397, § 8, effective January 1, 1983. L. 82:
(11)(b) amended, p. 553, § 1, effective May 3; (16) amended, p. 457, § 2,
effective January 1, 1983. L. 83: (2), (7), and (12.3)(b) repealed and
(12.3)(a)(I) and (16) amended, pp. 1485, 1482, §§ 11, 3, effective April 22;
(10), (11)(a), (11)(b)(I), and (12)(h) amended and (10.1), (12.1), and (12.2)
added, pp. 1494, 1495, §§ 1, 2, effective April 28; (5) repealed, p. 2081, § 1,
effective January 1, 1984. L. 84: (15) repealed, p. 999, § 3, effective
January 1; (10), (10.1)(a), (12)(h), (12.1), IP(12.2)(a), and (12.2)(b)
amended, p. 988, § 1, effective February 23. L. 85: (4) amended, p.
1212, § 8, effective May 9. L. 86: (16)(a) amended, p. 1101, § 1,
effective March 26. L. 87: (16)(c) added, p. 1417, § 1, effective March
13; (12)(a) RC&RE and (12.2)(a) amended, p. 1390, §§ 1, 2, effective April
1; (12)(b) RC&RE and (12.2)(a) amended, p. 1392, §§ 1, 2, effective April
1; (1.5) added, p. 1384, § 1, effective April 16; (6), (13), and (14) repealed,
p. 1304, § 1, effective May 20; (9)(a), (9)(b), and (10) repealed, (10.1)
R&RE, (11)(b)(I) and (12.2)(a) amended, and (12)(c) and (12.4) added, pp.
1388, 1386, 1385, §§ 6(1), 3, 1, 5, 2, effective June 20; (1) amended, p. 1383,
§ 1, effective July 10; (10.3) added, p. 1387, § 4, effective January 1, 1991;
(9)(d) and (11)(c) added by revision, p. 1388, § 6(2). L. 88: (8)
repealed, (9)(c), (9)(d), (10.1)(b), (10.3)(a), (11)(a), (11)(b)(I), (11)(c),
and (12.3)(a) amended, (10.1)(d) R&RE, and (10.2) added, pp. 1275, 1269,
1273, 1270, §§ 14, 5, 6, 5, effective May 29; (1.5) R&RE, (16)(c) amended,
and (16)(d) added, pp. 1279, 1282, §§ 2, 5, effective January 1, 1989; L.
89: (11)(b)(I) amended, p. 1450, § 2, effective June 7; (10.3)(c) amended,
p. 1644, § 8, effective January 1, 1991. L. 90: (16)(d) repealed, p.
1840, § 19, effective May 31; (12)(c) repealed and (16)(a) and (16)(c) amended,
pp. 1705, 1689, §§ 41, 4, effective June 9. L. 91: (10.2)(c), (10.3)(a),
(11)(a)(I), (11)(b)(I), and (12.4) amended and (10.2)(e) and (11)(c) repealed,
pp. 2003, 2005, §§ 1, 5, effective June 6. L. 92: (11)(b)(I) amended, p.
2212, § 10, effective June 3. L. 93: (7) repealed, p. 1689, § 8,
effective June 6. L. 94: (11)(b)(I) amended, p. 309, § 1, effective
March 22. L. 95: (10.2)(c) and (10.3) repealed, p. 7, § 1, effective
March 9. L. 96: (11)(a)(I), IP(12.2)(a), (12.3)(a)(I), and (12.4)
amended, pp. 1198, 1199, §§ 1, 2, effective June 1. L. 99: (10.2)(d)
amended, p. 202, § 1, effective August 4. L. 2002: (16)(a) amended, p.
861, § 1, effective August 7. L. 2005: (IP)(12.2)(a) amended, p. 781, §
72, effective June 1. L. 2020: (1.5) repealed, (SB 20-223), ch. 291, p.
1436, § 2, effective January 1, 2021. L. 2021: (1) and (4) amended and
(1.6) and (1.8) added, (SB 21-293), ch. 301, p. 1806, § 2, effective June 23;
(12.3)(a)(I) amended, (HB 21-1312), ch. 299, p. 1792, § 5, effective July 1. L.
2022: (1), (1.8)(a), and (1.8)(b) amended, (SB 22-238), ch. 157, p. 987, §
1, effective May 16. L. 2024: IP(1.8)(b) and (1.8)(c) amended and
(1.8)(b.5) added, (SB 24-233), ch. 171, p. 911, § 2, effective October 1 (see
editor's note). L. 2024, 2nd Ex. Sess.: (1)(a), (1)(b), (1.8)(a),
IP(1.8)(b), and (1.8)(c) amended, (1.8)(b.5) repealed, and (1.9) added, (HB
24B-1001), ch. 1, pp. 12, 13, §§ 8, 9, effective October 1 (see editor's note).
Editor's
note: (1)
Subsection (12.1) provided for the repeal of subsections (12) and (12.1),
effective January 1, 1987. (See L. 84, p. 988.)
(2) Subsection (9)(d) provided
for the repeal of subsections (9)(c) and (9)(d), effective January 1, 1989.
(See L. 88, p. 1269.)
(3) Subsection (10.1)(d)
provided for the repeal of subsection (10.1), effective January 1, 1991. (See
L. 88, p. 1273.)
(4) Section 5(2) of chapter 291
(SB 20-223), Session Laws of Colorado 2020, provides that changes to this
section take effect on the date of the governor's proclamation or January 1,
2021, whichever is later, only if, at the November 2020 statewide election, a
majority of voters approve the ballot issue referred in accordance with section
2 of Senate Concurrent Resolution 20-001. The ballot issue, referred to voters
as amendment B, was approved on November 3, 2020, and was proclaimed by the
Governor on December 31, 2020. The vote count for the measure was as follows:
FOR: 1,740,395
AGAINST: 1,285,136
(5) Section 18 of chapter 1,
(HB 24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
amended section 14 of chapter 171, (SB 24-233), Session Laws of Colorado 2024,
to change the effective date of SB 24-233 to October 1, 2024, if both an
initiative that reduces valuations for assessment and an initiative that
requires voter approval for retaining property tax revenue that exceeds a limit
are withdrawn pursuant to § 1-40-134 from the statewide ballot for the general
election held on November 5, 2024. On September 4, 2024, the secretary of state
announced both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit were withdrawn from the 2024 general election ballot.
(6) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
Cross
references: (1)
For constitutional provisions concerning taxation, see article X of the state
constitution; for the provision that sets the valuation for assessment of
residential real property, see § 3 (1)(b) of article X of the state
constitution.
(2) For the legislative
declaration in HB 21-1312, see section 1 of chapter 299, Session Laws of
Colorado 2021.
ANNOTATION
Law reviews. For
article, "Property Tax Assessments in Colorado", see 12 Colo. Law.
563 (1983). For article, "Appealing Property Tax Assessments", see 15
Colo. Law. 798 (1986). For article, "Delinquent Oil and Gas Ad Valorem
Taxes: Protecting Property Interests", see 16 Colo. Law. 798 (1987).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
General assembly may
constitutionally classify movable structures differently than conventional
residences for tax purposes. Am. Mobile Home Ass'n v. Dolan, 191 Colo. 433, 553
P.2d 758 (1976).
When cyclical revaluation
plan deemed unconstitutional. A cyclical revaluation plan is violative of
constitutional equality and uniformity standards only where its implementation
results in intentional discrimination, arbitrary action, constructive fraud, or
grossly and relatively unfair assessments. Nuttall v. Leffingwell, 193 Colo.
137, 563 P.2d 356 (1977).
This section does not
constitute retrospective legislation in violation of constitution. A change
in the method of valuation during the year for which the assessment was made
does not constitute retrospective legislation. Martin v. Bd. of Assess.
Appeals, 707 P.2d 348 (Colo. 1985) (decided under law in effect prior to 1983
amendment).
It is duty of tax assessor
to tax uniformly. Citizens' Comm. for Fair Prop. Taxation v. Warner, 127
Colo. 121, 254 P.2d 1005 (1953).
All taxable property need
not be revalued before individual revaluations are entered on the tax
rolls. Nuttall v. Leffingwell, 193 Colo. 137, 563 P.2d 356 (1977).
Federal statute prohibiting
discriminatory tax treatment of airline property under provisions of this
section does not apply retroactively to property taxes assessed prior to
effective date of federal statute. State Bd. of Equaliz. v. Am. Airlines, 773
P.2d 1033 (Colo. 1989).
Depreciation required to be
calculated annually from the base year to the date of assessment for
valuing personal business property. BQP Industries v. State Bd. of Equaliz.,
694 P.2d 337 (Colo. App. 1984).
Statute does not permit
consideration of subsequent economic conditions in determining property's base
year value. Carrera Place v. Bd. of Equaliz., 761 P.2d 197 (Colo. 1988)
(decided under law in effect prior to 1987 amendments); MJB Motels v. Jefferson
Bd. of Equaliz., 2023 CO 26, 531 P.3d 1000.
Thus, additional hotel rooms
that had not yet been constructed during the base period could not be
considered in calculating the occupancy rate used to determine the actual value
of a hotel for purposes of property taxation. Padre Resort, Inc. v. Jefferson
County Bd. of Equaliz., 30 P.3d 813 (Colo. App. 2001).
It is proper for the board
to consider evidence of other sales of comparable property within the base
period which were similarly subject to long-term leases. Bd. of Assess.
Appeals v. City & County of Denver, 829 P.2d 1319 (Colo. App. 1991), aff'd,
848 P.2d 355 (Colo. 1993).
Evidence of property tax
valuations of the property for prior tax years is relevant to valuation
issues concerning the current tax year, especially when the prior tax year is
in the same reassessment cycle and the valuation is determined using the same
base period. Weingarten v. Bd. of Assess. Appeals, 876 P.2d 118 (Colo. App.
1994).
Comparative sales data must
be adjusted for time. In case where property owner appealed county
assessor's valuation of the property to the board of assessment appeals, the
board erred in reaching an alternative valuation without applying a time
adjustment to the comparable sales data on which it relied. Adjustment for time
under subsections (10.2)(a) and (10.2)(d) is not discretionary, but mandatory.
Kidder v. Chaffee County Bd., 312 P.3d 1181 (Colo. App. 2011).
Subsection (11)(b)(I)
provides an exception to the biennial property value reassessment cycle under
certain limited circumstances including "unusual conditions", which
conditions are expressly enumerated in statute. "Unusual conditions"
include "any detrimental act of nature" and "any new regulations
restricting or increasing the use of the land". To qualify for the
exception, the detrimental act of nature or the new regulations restricting the
use of the land must be "in or related to any real property". MJB
Motels v. Jefferson Bd. of Equaliz., 2023 CO 26, 531 P.3d 1000.
The COVID-19 pandemic was
not a "detrimental act of nature" under subsection (11)(b)(I).
The COVID-19 pandemic was not an "act of nature" because it did not
resemble natural events like earthquakes, floods, and tornadoes. Further, the
COVID-19 pandemic was not a condition "in or related to any real
property" because it did not infect the property itself. MJB Motels v.
Jefferson Bd. of Equaliz., 2023 CO 26, 531 P.3d 1000; Hunter Douglas v. City of
Broomfield BOE, 2023 CO 27, 531 P.3d 996; Larimer County BOE v. 1303 Frontage,
2023 CO 28, 531 P.3d 1012.
Public health orders issued
in response to the COVID-19 pandemic were not "regulations restricting the
use of the land" but rather were restrictions on the use of
improvements on the land, which improvements are not synonymous with the land
itself. MJB Motels v. Jefferson Bd. of Equaliz., 2023 CO 26, 531 P.3d 1000;
Hunter Douglas v. City of Broomfield BOE, 2023 CO 27, 531 P.3d 996; Larimer
County BOE v. 1303 Frontage, 2023 CO 28, 531 P.3d 1012.
District court did not err in
concluding, as a matter of law, that the COVID-19 pandemic and related public
health orders were not "unusual conditions" in or related to
taxpayers' commercial properties as contemplated by subsection (11)(b)(I). MJB
Motels v. Jefferson Bd. of Equaliz., 2023 CO 26, 531 P.3d 1000.
"Intervening year"
in subsection (11)(b)(I) refers to the singular year between reassessments.
Put another way, the intervening year is the second year of the two-year tax
cycle. Larimer County BOE v. 1303 Frontage, 2023 CO 28, 531 P.3d 1012.
"Intervening
year", for purposes of subsection (11)(b)(I), means the even-numbered tax
year interposed between the odd-numbered reappraisal year, except when the
legislature expressly specifies otherwise. Educhildren v. Douglas Bd. of
Equaliz., 2023 CO 29, 531 P.3d 986.
A county tax assessor may
not revalue property during an intervening year when an enumerated unusual
condition occurs after the assessment date of January 1 of the intervening
year. A county tax assessor must revalue properties in the intervening year
when an enumerated unusual condition occurs between January 1 at noon of the
first year of the two-year tax cycle (the odd-numbered reappraisal year) and
January 1 at noon of the intervening year. Educhildren v. Douglas Bd. of
Equaliz., 2023 CO 29, 531 P.3d 986.
Subsection (11)(b)(I) is a
legislative safety valve designed to protect taxpayers from certain
limited, more current, enumerated conditions that affect their property values
in the second year of a tax cycle that could not otherwise be accounted for.
Educhildren v. Douglas Bd. of Equaliz., 2023 CO 29, 531 P.3d 986.
Any qualifying unusual
condition will be considered as part of the regular valuation process for
subsequent reassessment cycles. Educhildren v. Douglas Bd. of Equaliz.,
2023 CO 29, 531 P.3d 986.
Correction of incorrect
value in intervening year required. When an assessor learns of an incorrect
assessment, subsection (11)(b)(I) requires the assessor to correct the
assessment in an intervening year in order to set the value at what it would
have been set at in the assessment year if the mistake had not occurred.
Further adjustments to the value, however, cannot be made in an intervening
year absent proof of an unusual condition. Thibodeau v. Denver County Bd.
Comm'rs, 2018 COA 124, 428 P.3d 706.
Although an assessor is not
prevented from taking into account any unusual conditions related to real
property which would result in an increase or decrease in actual value and
may revalue property for an intervening year to rectify an incorrect base value
assessment, an assessor may not revalue a property in an intervening year that
has been correctly assessed, except as necessary to reflect the increase or
decrease in actual value attributable to an unusual condition. Leavell-Rio
Grande v. Bd. of Assess. Appeals, 753 P.2d 797 (Colo. App. 1988).
An unusual condition must
have occurred before the second year in the reassessment cycle to trigger a
reassessment for the tax year. Larimer County BOE v. 1303 Frontage, 2023 CO
28, 531 P.3d 1012.
An unusual condition that
occurs in the middle of the second year of the two-year reassessment cycle does
not require an assessor to conduct a mid-year tax revaluation. Rather, it
is considered in the next year. Larimer County BOE v. 1303 Frontage, 2023 CO
28, 531 P.3d 1012.
The general assembly did not
intend for subsection (11)(b)(I) to act as an exception to the January 1
assessment date. Larimer County BOE v. 1303 Frontage, 2023 CO 28, 531 P.3d
1012.
The district court erred in
determining that the assessor was required to revalue the taxpayers' properties
during the intervening year as it would contravene the purpose of the statute,
incapacitate the property tax system, and render the statute absurd if
assessors were compelled to constantly revalue properties and decrease or
increase assessments in real time at any point during every two-year
reassessment cycle. Larimer County BOE v. 1303 Frontage, 2023 CO 28, 531 P.3d
1012.
Unusual conditions affecting
actual value are factors for consideration by the assessor in assessing real
property. Depreciation factors apply only to personal property. CF & I
Steel Corp. v. Patton, 765 P.2d 586 (Colo. App. 1988), rev'd on other grounds,
785 P.2d 605 (Colo. 1990).
Unusual conditions are set
forth in two distinct provisions, of which one is limited and exclusive and the
other is broadly inclusive. Where a contract for purchase and sale of the
subject property was entered into in an intervening year, resulting in a
difference in valuation of more than ten percent when compared with the
valuation in effect during the normally applicable base period, evidence of the
sale price was relevant under this section and should have been considered.
Roberts v. Bd. of Assess. Appeals, 883 P.2d 588 (Colo. App. 1994).
Unusual conditions
provisions apply to individual properties, not only to all properties in an
entire neighborhood of like properties. Roberts v. Bd. of Assess. Appeals, 883
P.2d 588 (Colo. App. 1994).
Taxpayers bear the burden to
prove that an unusual condition existed, that their subject property was
affected by that condition, and that the assessor's valuation was erroneous
when the taxpayers contested that value, but taxpayers are not required to
prove diminution in property values to compel assessor to revalue their
properties under subsection (11)(b)(I). Larimer County BOE v. 1303 Frontage,
2023 CO 28, 531 P.3d 1012.
Evidence relating to the
amount stipulated to in adjudicatory proceedings and not to the assessor's
original base period valuation was irrelevant as a matter of law to the unusual
condition exception. Lowe Denver Hotel Ass'n v. Arapahoe County Bd. of
Equaliz., 890 P.2d 257 (Colo. App. 1995).
The cost to cure
environmental contamination, when mandated by a governmental entity, should
be deducted from the valuation of the property for ad valorem tax purposes.
E.I. du Pont de Nemours & Co. v. Douglas County Bd. of Equaliz., 75 P.3d
1129 (Colo. App. 2003).
E.I. du Pont de Nemours &
Co. cited above does not address the exact manner in which governmentally
ordered remediation costs to cure environmental contamination are to be
deducted under the income approach, nor does it mandate any specific methodology,
or require the deduction of the entire cost of remediation. Here, methodology
of estimating annual income, subtraction of an annual cost to cure, and
application of a capitalization rate to arrive at a taxable value of property
capable of generating income is in conformity with the direct capitalization
method of the income approach and supported by competent evidence. Microsemi
Corp. v. Broomfield County Bd. of Equaliz., 200 P.3d 1123 (Colo. App. 2008).
A shut down of a portion of
a plant does not constitute a change in the use of the land. LaDuke v. CF
& I Steel Corp., 785 P.2d 605 (Colo. 1990).
The general assembly
intended to authorize assessors to make "corrective" intervening year
revaluations only when the assessor's original base period valuation for
the first year of the reassessment cycle is subsequently asserted to be
incorrect and, therefore, in need of correction. Lowe Denver Hotel Ass'n v.
Arapahoe County Bd. of Equaliz., 890 P.2d 257 (Colo. App. 1995).
Statute does not authorize
assessors to make intervening revaluations when the valuation for the first
year of the cycle has been determined in adjudicatory proceedings resulting
from taxpayer protests or appeals. Lowe Denver Hotel Ass'n v. Arapahoe County
Bd. of Equaliz., 890 P.2d 257 (Colo. App. 1995).
Section 39-1-103 (8)(a)(I),
not subsection (12.3) of this section, applies to the valuation of real
property. Since the 18-month time limitation for information used in
property valuation applies exclusively to real property, the computer pricing
guides used by the taxpayer need not conform to those time limitations. Bd. of
County Comm'rs v. IBM Credit Corp., 888 P.2d 250 (Colo. 1995).
Obsolescence may be a
relevant factor in determining the actual value of personal property. IBM
Credit Corp. v. Bd. of County Comm'rs, 870 P.2d 535 (Colo. App. 1993).
Under subsection (12.3), if
an approach to value is applicable, it must be given appropriate consideration
by the assessor, as well as by the board of assessment appeals, as the trier of
fact. Home Depot USA, Inc. v. Pueblo County Bd. of Comm'rs, 50 P.3d 916 (Colo.
App. 2002).
Applied in First Nat'l
Bank v. Bd. of Comm'rs, 36 Colo. 265, 84 P. 1111 (1906); Bd. of County Comm'rs
v. Bd. of Assess. Appeals, 628 P.2d 156 (Colo. App. 1981).
39-1-104.1. Implementation costs -
annual revaluation. (Repealed)
Source:
L. 87: Entire
section added, p. 1389, § 10, effective June 21. L. 95: Entire section
repealed, p. 9, § 5, effective March 9.
39-1-104.2. Residential real property -
valuation for assessment - legislative declaration - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Inflation" means the annual percentage change in the United States
department of labor's bureau of labor statistics consumer price index, or a
successor index, for Denver-Aurora-Lakewood for all items paid by urban
consumers.
(a.5)
"Local governmental entity" means a governmental entity authorized by
law to impose ad valorem taxes on taxable property located within its
territorial limits; except that the term excludes school districts.
(b)
"Multi-family residential real property" means residential real
property that is a duplex, triplex, or multi-structure of four or more units,
all of which are based on the class codes established in the manual published
by the administrator. "Multi-family residential real property" is a
subclass of residential real property for purposes of the ratio of valuation
for assessment.
(c)
"Qualified-senior primary residence real property" means property
that is classified as such under section 39-1-104.6.
(c.5)
"Statewide actual value growth" means, as determined pursuant to
subsection (8) of this section, an estimate by the administrator based upon the
information reported by county assessors pursuant to section 39-2-115 on August
25, 2025, of the difference in the total statewide actual value from the
property tax year commencing on January 1, 2024, and the total statewide actual
value from the property tax year commencing on January 1, 2025.
(d)
"Target percentage" means the percentage of aggregate statewide
valuation for assessment represented by the valuation for assessment which is
attributable to residential real property in the year immediately preceding the
year in which a change in the level of value occurs.
(2)
After careful consideration of all available information, the general assembly
hereby finds and declares that the action of the first session of the
fifty-sixth general assembly which set the ratio of valuation for assessment
for residential real property at eighteen percent has produced a deviation from
the intent of section 3 of article X of the state constitution which ensures
that the percentage of the aggregate statewide valuation for assessment which
is attributable to residential real property shall remain the same as it was in
the year immediately preceding the year in which a change occurs in the level
of value used in determining actual value. Therefore, the general assembly
finds that legislation is necessary for the following purposes: To adjust the
residential rate for 1988; to ensure that deviations from the constitutional
mandate set forth in section 3 of article X of the state constitution shall not
be perpetuated into this or any future year; and to provide a process for
future adjustments in the ratio of valuation for assessment for residential
real property.
(3) (a)
The general assembly, pursuant to the authority granted in section 3 of article
X of the state constitution, finds and declares that, for the property tax
years commencing on or after January 1, 1987, but before January 1, 1989, the
percentage of aggregate statewide valuation for assessment which is
attributable to residential real property fails to remain as it was in the
property tax year commencing January 1, 1986, when the aggregate statewide
valuation for assessment was based on the 1985 aggregate statewide valuation
for assessment plus the increased valuation for assessment attributable to new
construction and to increased volume of mineral and oil and gas production
which occurred during 1986. Therefore, for the property tax year commencing
January 1, 1988, the ratio of valuation for assessment for residential real
property shall be sixteen percent of actual value.
(b) The
general assembly, pursuant to the authority granted in section 3 of article X
of the state constitution, finds and declares that, for the property tax years
commencing on or after January 1, 1989, but before January 1, 1991, the
percentage of aggregate statewide valuation for assessment which is
attributable to residential real property fails to remain as it was in the
property tax year commencing January 1, 1988, when the aggregate statewide
valuation for assessment was based on the 1987 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 44.51 percent, for
the property tax years commencing on or after January 1, 1989, but before January
1, 1991, the ratio of valuation for assessment for residential real property
shall be fifteen percent of actual value.
(c) The
general assembly, pursuant to the authority granted in section 3 of article X
of the state constitution, finds and declares that, for the property tax years
commencing on or after January 1, 1991, but before January 1, 1993, the
percentage of aggregate statewide valuation for assessment which is
attributable to residential real property fails to remain as it was in the
property tax year commencing January 1, 1990, when the aggregate statewide
valuation for assessment was based on the 1989 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 44.57 percent, for
the property tax years commencing on or after January 1, 1991, but before January
1, 1993, the ratio of valuation for assessment for residential real property
shall be 14.34 percent of actual value.
(d)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 1993, but before January 1, 1995,
the percentage of aggregate statewide valuation for assessment which is
attributable to residential real property will fail to remain as it was in the
property tax year commencing January 1, 1992, when the aggregate statewide
valuation for assessment was based on the 1991 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 44.73 percent, the
ratio of valuation for assessment for residential real property shall be 12.86
percent of actual value for the property tax years commencing on or after
January 1, 1993, but before January 1, 1995.
(e)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 1995, but before January 1, 1997,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will fail to remain as it was in the
property tax year commencing January 1, 1994, when the aggregate statewide
valuation for assessment was based on the 1993 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 45.29 percent, the
ratio of valuation for assessment for residential real property shall be 10.36
percent of actual value for the property tax years commencing on or after
January 1, 1995, but before January 1, 1997.
(f)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 1997, but before January 1, 1999,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will fail to remain as it was in the
property tax year commencing January 1, 1996, when the aggregate statewide
valuation for assessment was based on the 1995 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 46.17 percent, the
ratio of valuation for assessment for residential real property shall be 9.74
percent of actual value for the property tax years commencing on or after
January 1, 1997, but before January 1, 1999.
(g)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 1999, but before January 1, 2001,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will fail to remain as it was in the
property tax year commencing January 1, 1998, when the aggregate statewide
valuation for assessment was based on the 1997 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 46.49 percent, the
ratio of valuation for assessment for residential real property shall be 9.74
percent of actual value for the property tax years commencing on or after
January 1, 1999, but before January 1, 2001.
(h)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2001, but before January 1, 2003,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will fail to remain as it was in the
property tax year commencing January 1, 2000, when the aggregate statewide
valuation for assessment was based on the 1999 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 46.61 percent, the
ratio of valuation for assessment for residential real property shall be 9.15
percent of actual value for the property tax years commencing on or after
January 1, 2001, but before January 1, 2003.
(i)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2003, but before January 1, 2005,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will not remain as it was in the
property tax year commencing January 1, 2002, when the aggregate statewide
valuation for assessment was based on the 2001 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 47.08 percent, the
ratio of valuation for assessment for residential real property shall be 7.96 percent
of actual value for the property tax years commencing on or after January 1,
2003, but before January 1, 2005.
(j)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2005, but before January 1, 2007,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will not remain as it was in the
property tax year commencing January 1, 2004, when the aggregate statewide
valuation for assessment was based on the 2003 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 47.22 percent, the
ratio of valuation for assessment for residential real property shall be 7.96 percent
of actual value for the property tax years commencing on or after January 1,
2005, but before January 1, 2007.
(k)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2007, but before January 1, 2009,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will not remain as it was in the
property tax year commencing January 1, 2006, when the aggregate statewide
valuation for assessment was based on the 2005 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 47.43 percent, the
ratio of valuation for assessment for residential real property shall be 7.96
percent of actual value for the property tax years commencing on or after
January 1, 2007, but before January 1, 2009.
(l)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2009, but before January 1, 2011,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will not remain as it was in the
property tax year commencing January 1, 2008, when the aggregate statewide
valuation for assessment was based on the 2007 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 46.82 percent, the
ratio of valuation for assessment for residential real property shall be 7.96 percent
of actual value for the property tax years commencing on or after January 1,
2009, but before January 1, 2011.
(m)
Pursuant to the authority granted in section 3 of article X of the state
constitution, the general assembly finds and declares that, for the property
tax years commencing on or after January 1, 2011, but before January 1, 2013,
the percentage of aggregate statewide valuation for assessment that is
attributable to residential real property will not remain as it was in the
property tax year commencing January 1, 2010, when the aggregate statewide
valuation for assessment was based on the 2009 aggregate statewide valuation
for assessment. Therefore, the administrator having determined pursuant to
subsection (4) of this section that the target percentage is 46.53 percent, the
ratio of valuation for assessment for residential real property shall be 7.96 percent
of actual value for the property tax years commencing on or after January 1,
2011, but before January 1, 2013.
(n)
Based on the determination by the administrator that the target percentage is
45.86 percent, the ratio of valuation for assessment for residential real
property is 7.96 percent of actual value for the property tax years commencing
on or after January 1, 2013, but before January 1, 2015.
(o)
Based on the determination by the administrator that the target percentage is
45.67 percent, the ratio of valuation for assessment for residential real
property is 7.96 percent of actual value for the property tax years commencing
on or after January 1, 2015, but before January 1, 2017.
(p)
Based on the determination by the administrator that the target percentage is
45.76 percent, the ratio of valuation for assessment for residential real
property is 7.2 percent of actual value for property tax years commencing on or
after January 1, 2017, but before January 1, 2019.
(q) For
property tax years commencing on or after January 1, 2019, and before January
1, 2025, the valuation for assessment for multi-family residential real
property is 7.15 percent of the actual value of the property; except that the
valuation for assessment of this property is temporarily reduced as follows:
(I) For
the property tax year commencing on January 1, 2022, the valuation for
assessment for multi-family residential real property is temporarily reduced to
6.8 percent of the actual value of the property; and
(II)
For the property tax years commencing on January 1, 2023, and January 1, 2024,
the valuation for assessment for multi-family residential real property is
temporarily reduced to 6.7 percent of the amount equal to the actual value of
the property minus the lesser of fifty-five thousand dollars or the amount that
causes the valuation for assessment of the property to be one thousand dollars.
(r) For
property tax years commencing on or after January 1, 2022, and before January
1, 2025, the valuation for assessment for all residential real property other
than multi-family residential real property is 7.15 percent of the actual value
of the property; except that the valuation for assessment of this property is
temporarily reduced as follows:
(I) For
the property tax year commencing on January 1, 2022, the valuation for
assessment for all residential real property other than multi-family
residential real property is temporarily reduced to 6.95 percent of the actual
value of the property; and
(II)
For the property tax years commencing on January 1, 2023, and January 1, 2024,
the valuation for assessment for all residential real property other than
multi-family residential real property is 6.7 percent of the amount equal to
the actual value of the property minus the lesser of fifty-five thousand
dollars or the amount that causes the valuation for assessment of the property
to be one thousand dollars.
(III)
Repealed.
(s) (I)
For property tax years commencing on or after January 1, 2025, but before
January 1, 2027, the valuation for assessment for qualified-senior primary
residence real property, including multifamily qualified-senior primary
residence real property, is:
(A) For
the property tax year commencing on January 1, 2025, if the state board of
equalization determines that the statewide actual value growth is less than or
equal to five percent, for the purpose of a levy imposed by a local
governmental entity, 6.25 percent of the amount equal to the actual value of
the property minus the lesser of fifty percent of the first two hundred
thousand dollars of that actual value or the amount that causes the valuation
for assessment of the property to be one thousand dollars;
(A.5)
For the property tax year commencing on January 1, 2025, if the state board of
equalization determines that the statewide actual value growth is greater than
five percent, for the purpose of a levy imposed by a local governmental entity,
6.15 percent of the amount equal to the actual value of the property minus the
lesser of fifty percent of the first two hundred thousand dollars of that
actual value or the amount that causes the valuation for assessment of the
property to be one thousand dollars;
(B) For
the property tax year commencing on January 1, 2026, if the state board of
equalization determines that the statewide actual value growth is less than or
equal to five percent, for the purpose of a levy imposed by a local
governmental entity, 6.8 percent of the amount equal to the actual value of the
property minus either fifty percent of the first two hundred thousand dollars
of that actual value plus the lesser of ten percent of the actual value of the
property or seventy thousand dollars as increased for inflation in the first
year of each subsequent reassessment cycle or the amount that causes the
valuation for assessment of the property to be one thousand dollars;
(B.5)
For the property tax year commencing on January 1, 2026, if the state board of
equalization determines that the statewide actual value growth is greater than
five percent, for the purpose of a levy imposed by a local governmental entity,
6.7 percent of the amount equal to the actual value of the property minus
either fifty percent of the first two hundred thousand dollars of that actual
value plus the lesser of ten percent of the actual value of the property or
seventy thousand dollars as increased for inflation in the first year of each
subsequent reassessment cycle or the amount that causes the valuation for
assessment of the property to be one thousand dollars;
(C) For
the property tax years commencing on January 1, 2025, and January 1, 2026, if
the state board of equalization determines that the statewide actual value
growth is less than or equal to five percent, for the purpose of a levy imposed
by a school district, 7.05 percent of the amount equal to the actual value of
the property minus the lesser of fifty percent of the first two hundred
thousand dollars of that actual value or the amount that causes the valuation
for assessment of the property to be one thousand dollars; except that the
valuation for assessment for the purpose of a levy imposed by a school district
may be temporarily reduced for a property tax year as set forth in section
29-1-1702.5; and
(D) For
the property tax years commencing on January 1, 2025, and January 1, 2026, if
the state board of equalization determines that the statewide actual value
growth is greater than five percent, for the purpose of a levy imposed by a
school district, 6.95 percent of the amount equal to the actual value of the
property minus the lesser of fifty percent of the first two hundred thousand
dollars of that actual value or the amount that causes the valuation for
assessment of the property to be one thousand dollars; except that the
valuation for assessment for the purpose of a levy imposed by a school district
may be temporarily reduced for a property tax year as set forth in section
29-1-1702.5.
(II)
(A) For the property tax year commencing on January 1, 2025, if the state
board of equalization determines that the statewide actual value growth is less
than or equal to five percent and if it is administratively infeasible to
calculate two different valuations for assessment for the same property based
on two different percentages of actual value, an assessor may determine the
value of a property under subsection (3)(s)(I)(C) of this section by
calculating 112.8 percent of an amount equal to 6.25 percent of the amount
equal to the actual value of the property minus the lesser of fifty percent of
the first two hundred thousand dollars of that actual value or the amount that
causes the valuation for assessment of the property to be one thousand dollars.
(B) For
the property tax year commencing on January 1, 2025, if the state board of
equalization determines that the statewide actual value growth is greater than
five percent and if it is administratively infeasible to calculate two
different valuations for assessment for the same property based on two
different percentages of actual value, an assessor may determine the value of a
property under subsection (3)(s)(I)(D) of this section by calculating 113.00813
percent of an amount equal to 6.15 percent of the amount equal to the actual
value of the property minus the lesser of fifty percent of the first two
hundred thousand dollars of that actual value or the amount that causes the
valuation for assessment of the property to be one thousand dollars.
(III)
The general assembly finds and declares that any modification to the valuation
for assessment established in this subsection (3)(s), exclusive of the
termination of any temporary reduction pursuant to section 29-1-1702.5, that
would result in a property tax increase would require prior voter approval
under section 20 (4)(a) of article X of the state constitution.
(t) (I)
For the property tax year commencing on January 1, 2025, if the state board of
equalization determines that the statewide actual value growth is less than or
equal to five percent, the valuation for assessment for all residential real
property other than qualified-senior primary residence real property is:
(A) For
the purpose of a levy imposed by a local governmental entity, 6.25 percent of
the actual value of the property; and
(B) For
the purpose of a levy imposed by a school district, 7.05 percent of the actual
value of the property; except that the valuation for assessment for the purpose
of a levy imposed by a school district may be temporarily reduced for a
property tax year as set forth in section 29-1-1702.5.
(II) If
it is administratively infeasible to calculate two different valuations for
assessment for the same property based on the same actual value, but with two
different percentages of that actual value, an assessor may determine the value
of a property under subsection (3)(t)(I)(B) of this section by calculating
112.8 percent of an amount equal to 6.25 percent of the actual value of the
property.
(III)
The general assembly finds and declares that any modification to the valuation
for assessment established in this subsection (3)(t), exclusive of the
termination of any temporary reduction pursuant to section 29-1-1702.5, that
would result in a property tax increase would require prior voter approval
under section 20 (4)(a) of article X of the state constitution.
(t.5)
(I) For the property tax year commencing on January 1, 2025, if the state
board of equalization determines that the statewide actual value growth is
greater than five percent, the valuation for assessment for all residential
real property other than qualified-senior primary residence real property is:
(A) For
the purpose of a levy imposed by a local governmental entity, 6.15 percent of
the actual value of the property; and
(B) For
the purpose of a levy imposed by a school district, 6.95 percent of the actual
value of the property; except that the valuation for assessment for the purpose
of a levy imposed by a school district may be temporarily reduced for a
property tax year as set forth in section 29-1-1702.5.
(II) If
it is administratively infeasible to calculate two different valuations for
assessment for the same property based on the same actual value, but with two
different percentages of that actual value, an assessor may determine the value
of a property under subsection (3)(t.5)(I)(B) of this section by calculating
113.00813 percent of an amount equal to 6.15 percent of the actual value of the
property.
(u) (I)
For property tax years commencing on or after January 1, 2026, if the state
board of equalization determines that the statewide actual value growth is less
than or equal to five percent, the valuation for assessment for all residential
real property other than qualified-senior primary residence real property is:
(A) For
the purpose of a levy imposed by a local governmental entity, 6.8 percent of
the amount equal to the actual value of the property minus the lesser of ten
percent of the actual value of the property, seventy thousand dollars as
increased for inflation in the first year of each subsequent reassessment
cycle, or the amount that causes the valuation for assessment of the property
to be one thousand dollars; and
(B) For
the purpose of a levy imposed by a school district, 7.05 percent of the amount
equal to the actual value of the property; except that the valuation for
assessment for the purpose of a levy imposed by a school district may be
temporarily reduced for a property tax year as set forth in section
29-1-1702.5.
(II)
For reassessment cycles commencing on or after January 1, 2027, the property
tax administrator shall publish the inflation adjusted value used to calculate
the valuation for assessment pursuant to subsection (3)(u)(I)(A) of this
section.
(III)
The general assembly finds and declares that any modification to the valuation
for assessment established in this subsection (3)(u), exclusive of the
termination of any temporary reduction pursuant to section 29-1-1702.5, that
would result in a property tax increase would require prior voter approval
under section 20 (4)(a) of article X of the state constitution.
(v) (I)
For property tax years commencing on or after January 1, 2026, if the state
board of equalization determines that the statewide actual value growth is
greater than five percent, the valuation for assessment for all residential
real property other than qualified-senior primary residence real property is:
(A) For
the purpose of a levy imposed by a local governmental entity, 6.7 percent of
the amount equal to the actual value of the property minus the lesser of ten
percent of the actual value of the property, seventy thousand dollars as
increased for inflation in the first year of each subsequent reassessment
cycle, or the amount that causes the valuation for assessment of the property
to be one thousand dollars; and
(B) For
the purpose of a levy imposed by a school district, 6.95 percent of the amount
equal to the actual value of the property; except that the valuation for
assessment for the purpose of a levy imposed by a school district may be
temporarily reduced for a property tax year as set forth in section
29-1-1702.5.
(II)
For reassessment cycles commencing on or after January 1, 2027, the
administrator shall publish the inflation-increased value used to calculate the
valuation for assessment pursuant to subsection (3)(v)(I)(A) of this section.
(III)
The general assembly finds and declares that any modification to the valuation
for assessment established in this subsection (3)(v), exclusive of the
termination of any temporary reduction pursuant to section 29-1-1702.5, that
would result in a property tax increase would require prior voter approval
under section 20 (4)(a) of article X of the state constitution.
(3.7) to
(7) Repealed.
(8) (a)
As soon as practicable upon receiving the information described in section
39-2-115 (1)(a.5), the administrator shall determine the statewide actual value
growth and report that determination to the state board of equalization, and
the state board of equalization shall certify the statewide actual value
growth, whether that growth is less than or equal to five percent, and
determine which of the valuations for assessment described in subsection (3) of
this section apply in property tax years commencing on or after January 1,
2025.
(b)
Upon the state board of equalization determining which of the valuations for
assessment determined pursuant to this section apply in property tax years
commencing on or after January 1, 2025, the state board of equalization shall
notify the administrator, and the administrator shall publish those valuations
for assessment on the website maintained by the division of property taxation
in the department of local affairs.
(c) The
general assembly finds and declares that any modification to the valuations for
assessment that the state board of equalization determines are applicable in
property tax years commencing on or after January 1, 2025, pursuant to this
subsection (8) that would result in a property tax increase would require prior
voter approval under section 20 (4)(a) of article X of the state constitution.
Source:
L. 88: Entire
section added, p. 1276, § 1, effective January 1, 1989. L. 89: (3) and
(7)(b) amended, p. 1450, § 3, effective June 7. L. 90: IP(7)(a) amended,
p. 1689, § 5, effective June 9. L. 91: (3)(c) added and (4)(a), (6)(d),
and (7)(b) amended, p. 1984, §§ 1, 2, effective April 11. L. 91, 2nd Ex.
Sess.: (7)(b) amended, p. 100, § 1, effective September 25; IP(7)(a) and
(7)(a)(II) amended, p. 101, § 1, effective October 7. L. 92: IP(7)(a)
and (7)(b) amended, p. 2215, § 2, effective June 3. L. 93: (3)(d) added
and (7) repealed, pp. 1876, 1689, §§ 1, 8, effective June 6. L. 95: (3)(e)
added, p. 583, § 1, effective May 22. L. 97: (3)(f) added, p. 1149, § 1,
effective May 28. L. 99: (3)(g) added, p. 505, § 1, effective April 30. L.
2001: (3)(h) added, p. 705, § 1, effective May 31. L. 2002: IP(6)
amended, p. 861, § 2, effective August 7. L. 2003: (3)(i) added, p.
1970, § 1, effective May 22. L. 2005: (3)(j) added, p. 632, § 1,
effective May 27. L. 2007: (3)(k) added, p. 1524, § 1, effective May 31.
L. 2009: (3)(l) added, (HB 09-1360), ch. 362, p. 1875, § 1, effective
June 1. L. 2011: (3)(m) added, (HB 11-1305), ch. 222, p. 956, § 1,
effective May 27. L. 2013: (3)(n) added, (HB 13-1319), ch. 324, p. 1815,
§ 1, effective May 28. L. 2015: (3)(o) added, (HB 15-1357), ch. 312, p.
1276, § 1, effective June 5. L. 2017: (3)(p) added, (HB 17-1349), ch.
358, p. 1885, § 1, effective June 5. L. 2019: (3)(p) amended and (3)(q)
added, (SB 19-255), ch. 433, p. 3745, § 1, effective June 3. L. 2020:
(3)(q) amended and (4), (5), and (6) repealed, (SB 20-223), ch. 291, p. 1436, §
3, effective January 1, 2021. L. 2021: (1)(a) amended and (3)(r) added,
(SB 21-293), ch. 301, p. 1808, § 3, effective June 23; (3)(q) amended, (SB
21-293), ch. 301, p. 1808, § 4, effective December 31 (see editor's note (2)). L.
2022: (3)(q) and (3)(r) amended, (SB 22-238), ch. 157, p. 988, § 2,
effective May 16. L. 2023: (3.7) added (SB 23-303), ch. 258, p. 1474, §
9, effective May 24. L. 2023, 1st Ex. Sess.: (3)(q), IP(3)(r),
(3)(r)(I), and (3)(r)(II) amended, (SB 23B-001), ch. 1, p. 1, § 1, effective
November 20. L. 2024: (1)(a.5) and (3)(s) added and IP(3)(q) and
IP(3)(r) amended, (SB 24-111), ch. 169, pp. 871, 870, §§ 3, 2, effective August
7; (1)(a), (1)(a.5), (1)(b), IP(3)(q), (3)(q)(I), (3)(q)(II), IP(3)(r),
(3)(r)(I), (3)(r)(II), and (3)(s) amended, (1)(c), (1)(d), (3)(t), and (3)(u)
added, and (3)(r)(III) repealed (SB 24-233), ch. 171, p. 914, § 4, effective
October 1 (see editor's note). L. 2024, 2nd Ex. Sess.: (1)(e), (3)(t.5),
(3)(u.5), and (8) added and (3)(s), (3)(t), (3)(u)(I), and (3)(u)(III) amended,
(HB 24B-1001), ch. 1, pp. 14, 16, §§ 10, 11, effective October 1 (see editor's
note). L. 2025: IP(3)(s)(I) amended, (SB 25-1296), ch. 202, p. 912, § 4,
effective May 16; IP(3)(s)(I) amended, (SB 25-026), ch. 362, p. 1966, § 11,
effective August 6.
Editor's
note: (1) Section
5(2) of chapter 291 (SB 20-223), Session Laws of Colorado 2020, provides that
changes to this section take effect on the date of the governor's proclamation
or January 1, 2021, whichever is later, only if, at the November 2020 statewide
election, a majority of voters approve the ballot issue referred in accordance
with section 2 of Senate Concurrent Resolution 20-001. The ballot issue,
referred to voters as amendment B, was approved on November 3, 2020, and was
proclaimed by the Governor on December 31, 2020. The vote count for the measure
was as follows:
FOR: 1,740,395
AGAINST: 1,285,136
(2) Section 15(3) of chapter
301 (SB 21-293), Session Laws of Colorado 2021, provides that section 4 of the
act changing subsection (3)(q) takes effect only if, at the November 2021
statewide election, a majority of voters do not approve a measure concerning
property tax reductions or if there is no such measure on the ballot for the
election, and, in either case, changes to subsection (3)(q) take effect on
December 31, 2021. The ballot issue, referred to voters as Proposition 120, was
rejected on November 2, 2021. The vote count for the measure was as follows:
FOR: 652,382
AGAINST: 866,197
(3) Subsection (3.7)(b)
provided for the repeal of subsection (3.7), effective July 1, 2024. (See L.
2023, p. 1474.)
(4) (a) Section 18 of chapter
1, (HB 24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
amended section 14 of chapter 171, (SB 24-233), Session Laws of Colorado 2024,
to change the effective date of SB 24-233 to October 1, 2024, if both an
initiative that reduces valuations for assessment and an initiative that
requires voter approval for retaining property tax revenue that exceeds a limit
are withdrawn pursuant to § 1-40-134 from the statewide ballot for the general
election held on November 5, 2024. On September 4, 2024, the secretary of state
announced both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit were withdrawn from the 2024 general election ballot.
(b) Section 18 of chapter 1,
(HB 24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
amending section 14 of chapter 171, (SB 24-233), Session Laws of Colorado 2024,
provides that changes to this section take effect only if SB 24-111 becomes
law. SB 24-111 became law and took effect August 7, 2024.
(5) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
(6) Amendments to subsection
(3)(s)(I) by HB 25-1296 and SB 25-026 were harmonized.
(7) (a) Subsection (1)(c.5) was
numbered as subsection (1)(e) in HB 24B-1001 but was renumbered on revision for
correct alphabetical order.
(b) Subsection (3)(v) was
numbered as subsection (3)(u.5) in HB 24B-1001 but was renumbered on revision
for ease of location.
Cross
references: For
the legislative declaration in HB 25-1296, see section 1 of chapter 202,
Session Laws of Colorado 2025.
39-1-104.3. Partial real property tax
reductions - residential property - definitions - repeal. (Repealed)
Source:
L. 2022: Entire
section added, (SB 22-238), ch. 157, p. 989, § 3, effective May 16; L. 2023,
1st Ex. Sess.: Entire section repealed, (SB 23B-001), ch. 1, p. 9, § 7,
effective November 20.
39-1-104.4. Adjustment of residential
rate. (Repealed)
Source:
L. 2022: Entire
section added, (SB 22-238), ch. 157, p. 989, § 4, effective May 16. L. 2023,
1st Ex. Sess.: IP(1) and (1)(a) amended, (SB 23B-001), ch. 1, p. 9, § 8,
effective November 20. L. 2024: Entire section repealed, (SB 24-233),
ch. 171, p. 918, § 5, effective October 1 (see editor's note).
Editor's
note: Section 18
of chapter 1, (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, amended section 14 of chapter 171, (SB 24-233), Session
Laws of Colorado 2024, to change the effective date of SB 24-233 to October 1,
2024, if both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit are withdrawn pursuant to § 1-40-134 from the statewide ballot
for the general election held on November 5, 2024. On September 4, 2024, the
secretary of state announced both an initiative that reduces valuations for
assessment and an initiative that requires voter approval for retaining
property tax revenue that exceeds a limit were withdrawn from the 2024 general
election ballot.
39-1-104.5. Severed mineral interest -
placement on tax roll.
Any owner
of the surface estate from which a mineral interest has been severed, on behalf
of himself and any other owners of such interest in the surface, may require
the assessor of the county wherein such real estate is situate to place such
severed mineral interest, without regard to value, on the tax roll of the
county if the owner of the surface estate provides proof of ownership of the
severed mineral interest and a record of the creation of the severed mineral
interest as shown by the records of the county clerk and recorder. Proof of
ownership and the record of creation of the severed mineral interest shall be
provided in the form of a certificate prepared by an attorney, a title
insurance company, or a title insurance agent authorized to do business in this
state.
Source:
L. 79: Entire
section added, p. 1405, § 1, effective July 1. L. 83: Entire section
amended, p. 512, § 3, effective May 16.
39-1-104.6. Qualified-senior primary
residence real property - valuation for assessment - reimbursement to local
governments for reduced valuation - temporary mechanism for refunding excess
state revenues - legislative declaration - definitions.
(1) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Local governmental entity" means a governmental entity authorized by
law to impose ad valorem taxes on taxable property located within its
territorial limits.
(b) (I)
"Owner-occupier" means an individual who:
(A) Is
an owner of record of residential real property that the individual occupies as
the individual's primary residence;
(B) Is
not an owner of record of the residential real property that the individual
occupies as the individual's primary residence, but either is a spouse or civil
union partner of an owner of record of the residential real property and who
also occupies the residential real property as the owner of record's primary
residence, or is the surviving spouse or partner of an individual who was an
owner of record of the residential real property and who occupied the
residential real property with the surviving spouse or partner as their primary
residence until the owner of record's death;
(C) Is
not an owner of record of the residential real property that the individual
occupies as the individual's primary residence, only because the property has
been purchased by or transferred to a trust, a corporate partnership, or any
other legal entity solely for estate planning purposes and is the maker of the
trust or a principal of the corporate partnership or other legal entity;
(D)
Occupies residential real property as the individual's primary residence and is
the spouse or civil union partner of a person who also occupies the residential
real property, who is not the owner of record of the property only because the
property has been purchased by or transferred to a trust, a corporate
partnership, or any other legal entity solely for estate planning purposes, and
who is the maker of the trust or a principal of the corporate partnership or
other legal entity; or
(E)
Occupies residential real property as the individual's primary residence and is
the surviving spouse or partner of a person who occupied the residential real
property with the surviving spouse or partner until the person's death, who was
not the owner of record of the property at the time of the person's death only
because the property had been purchased by or transferred to a trust, a
corporate partnership, or any other legal entity solely for estate planning
purposes prior to the person's death, and who was the maker of the trust or a
principal of the corporate partnership or other legal entity prior to the
person's death.
(II)
"Owner-occupier" also includes any individual who, but for the
confinement of the individual to a hospital, nursing home, or assisted living
facility, would occupy the residential real property as the individual's
primary residence and would meet one or more of the ownership criteria
specified in subsection (1)(b)(I) of this section, if the residential real
property:
(A) Is
temporarily unoccupied; or
(B) Is
occupied by the spouse, civil union partner, or a financial dependent of the
individual.
(c)
"Owner of record" means an individual whose name appears on a valid
recorded deed to residential real property as an owner of the property.
(d)
"Senior homestead exemption" means the property tax exemption for
qualifying seniors allowed by section 39-3-203 (1).
(e)
"Surviving spouse or partner" means an individual who was legally
married to another individual, or was a partner in a civil union with another
individual, at the time of the other individual's death and who has not
remarried or entered into another civil union.
(f)
"Total property tax revenue lost" means the amount of property tax
revenue lost for a property tax year by a local governmental entity due solely
to the reduced valuation for assessment of qualified-senior primary residence
real property, including multi-family qualified-senior primary residence real
property under section 39-2-104.2 (3)(s), as compared to the valuation for
assessment of residential real property, including multi-family residential
real property under this section, as calculated by each assessor, subject to
correction by the administrator, pursuant to subsection (9) of this section.
(2) Classification.
(a) For
property tax years commencing on or after January 1, 2025, but before January
1, 2027, residential real property that as of the assessment date is used as
the primary residence of an owner-occupier is classified as qualified-senior
primary residence real property, which is a subclass of residential real
property, if:
(I) The
owner-occupier completes and files an application in the manner required by
subsection (3) of this section;
(II)
The owner-occupier previously qualified for and received the senior homestead
exemption for a different property for a property tax year commencing on or
after January 1, 2020, and does not qualify for the senior homestead exemption
for the current property tax year; and
(III)
The circumstances that qualify the property for the classification have not
changed since the filing of the application.
(b)
Under no circumstances is the classification as qualified-senior primary
residence real property allowed for property taxes assessed during any property
tax year prior to the year in which an owner-occupier first files an
application in the manner required by subsection (3) of this section. If
ownership of residential real property that qualified as qualified-senior
primary residence real property as of the assessment date changes after the
assessment date, the classification is allowed only if an owner-occupier whose
status as an owner-occupier qualifies the property for the classification has
filed an application by the deadline specified in subsection (3)(a) of this
section.
(c) If
an individual owns and occupies a dwelling unit in a common interest community,
as defined in section 38-33.3-103 (8), as the individual's primary residence,
only the dwelling unit that the individual occupies as the individual's primary
residence may qualify as qualified-senior primary residence real property.
(d) For
purposes of this subsection (2), two individuals who are legally married or are
civil union partners but who own more than one parcel of residential real
property are deemed to occupy the same primary residence, and only that
property may be classified as qualified-senior primary residence real property.
If an individual is an owner-occupier of a residential real property and an
owner of record on another property along with a member of the individual's
family other than the individual's spouse, then the other family member may be
an owner-occupier of the other property.
(e) A
unit of real property that might otherwise be classified as multi-family
residential real property and that qualifies as qualified-senior primary
residence real property under this section is classified as multi-family
qualified-senior primary residence real property.
(3) Applications.
(a) For
a property to be classified as qualified-senior primary residence real
property, an individual must file with the assessor a completed application no
later than July 15 of the first property tax year for which the classification
is sought, through July 15, 2026. An application returned by mail is deemed
filed on the date it is postmarked.
(b) (I)
An applicant must complete an application for property to be classified as
qualified-senior primary residence real property on a form prescribed by the
administrator that includes the following information:
(A) The
applicant's name, mailing address, and social security number;
(B) The
address and schedule or parcel number of the property;
(C) The
name and social security number of the applicant's spouse or civil union
partner who occupies the property as the spouse or civil union partner's
primary residence;
(D) If
a trust is the owner of record of the property, the names of the maker of the
trust, the trustee, and the beneficiaries of the trust;
(E) If
a corporate partnership or other legal entity is the owner of record of the
property, the names of the principals or the corporate partnership or other
legal entity;
(F) A
statement that the applicant previously qualified for the senior homestead
exemption for a property tax year commencing on or after January 1, 2020, for a
different property than the property that the applicant currently occupies as
the applicant's primary residence;
(G) An
affirmation, in a form prescribed by the administrator, that the applicant
believes, under penalty of perjury in the second degree as defined in section
18-8-503, that all information provided by the applicant is correct; and
(H) Any
other information that the administrator reasonably deems necessary.
(II)
The administrator shall also include in the application a statement that an
applicant or, if applicable, the trustee has a legal obligation to inform the
assessor within sixty days of any change in the ownership or occupancy of the
residential real property for which classification as qualified-senior primary
residence real property has been applied for or allowed that would prevent the
classification from being allowed for the property.
(c) For
purposes of the application and related provisions in this section, real
property that is multi-family qualified-senior primary residence real property
is treated as qualified-senior primary residence real property.
(4) Penalties.
(a) In
addition to any penalties prescribed by law for perjury in the second degree,
an applicant who knowingly provides false information on an application or
attempts to claim more than one property as qualified-senior primary residence
real property for the same property tax year shall:
(I) Not
be able to claim the property as qualified-senior primary residence real
property for the property tax year;
(II)
Pay, to the treasurer of a county in which property was improperly classified
as qualified-senior primary residence real property due to the provision by the
applicant of false information or the filing of more than one application, an
amount equal to the amount of property taxes not paid as a result of the
improper classification as qualified-senior primary residence real property;
and
(III)
Upon conviction of perjury, be required to pay to the treasurer of any county
in which an invalid application was filed an additional amount equal to twice
the amount of the property taxes identified in subsection (4)(a)(II) of this
section plus interest, calculated at the annual rate calculated pursuant to
section 39-21-110.5 from the date the invalid application was filed until the
date the applicant makes the payment required by this subsection (4)(a)(III).
(b) If
an applicant or a trustee fails to inform the assessor within sixty days of any
change in the ownership or occupancy of residential real property for which
classification as a qualified-senior primary residence real property has been
applied for or allowed that would prevent the classification from being allowed
for the property as required by subsection (3)(b) of this section:
(I) The
classification is not allowed with respect to the residential real property for
the subsequent property tax year; and
(II)
The applicant or trustee shall pay, to the treasurer of any county in which the
classification was improperly allowed due to the applicant's or trustee's
failure to immediately inform the assessor of any change in the ownership or
occupancy of residential real property, an amount equal to the amount of
property taxes not paid as a result of the improper classification as
qualified-senior primary residence real property plus interest, calculated at
the annual rate specified in section 39-21-110.5 from the date on which the
change in the ownership or occupancy occurred until the date the applicant
makes the payment required by this subsection (4)(b)(II).
(c) Any
amount required to be paid to a treasurer pursuant to subsection (4)(a) or
(4)(b) of this section is deemed part of the lien of general taxes imposed on
the person required to pay the amount and has the priority specified in section
39-1-107 (2).
(5) Confidentiality.
(a)
Completed applications for classification as qualified-senior primary residence
real property are confidential; except that:
(I) (A)
An assessor or the administrator may release statistical compilations or
informational summaries of any information contained in the applications and
shall provide a copy of an application to the applicant who returned the
application and the treasurer of the same county as the assessor; and
(B) An
assessor or the administrator may introduce a copy of an application as
evidence in any administrative hearing or legal proceeding in which the
accuracy or veracity of the application is at issue so long as neither the
applicant's social security number nor any other social security number set
forth in the application is divulged;
(II) A
treasurer shall keep confidential each individual application received from an
assessor but may release statistical compilations or informational summaries of
any information contained in applications and may introduce a copy of an
application as evidence in any administrative hearing or legal proceeding in
which the accuracy or veracity of the application is at issue so long as
neither the applicant's social security number nor any other social security
number set forth in the application is divulged; and
(III)
The administrator may share information contained in an application for
classification of real property as qualified-senior primary residence real
property, including any social security number set forth in the application,
with the department of revenue to the extent necessary to enable the
administrator to verify that the applicant satisfies legal requirements for the
classification.
(b)
Notwithstanding the provisions of subsection (5)(a) of this section, the
administrator, an assessor, or a treasurer shall not give any other person any
listing of applicants or any other information that would enable a person to
easily assemble a mailing list of applicants for the qualified-senior primary
residence real property classification.
(c) In
accordance with section 25-2-103 (4.7), the administrator shall annually
provide to the state registrar of vital statistics of the department of public
health and environment a list, by name and social security number, of every
individual who had property classified as qualified-senior primary residence
real property for the immediately preceding year so that the registrar can
provide to the administrator a list of all the individuals on the list who have
died. No later than April 1, 2026, and no later than April 1, 2027, the
administrator shall forward to the assessor of each county the name and social
security number of each deceased individual who had residential real property
located within the county that was so classified for the immediately preceding
year so that the assessor can change the classification of the property, if
necessary.
(6) Notice.
(a) As
soon as practicable after January 1, 2025, and after January 1, 2026, each
county treasurer shall, at the treasurer's discretion, mail or electronically
send to each person whose name appears on the tax list and warrant as an owner
of residential real property notice of the qualified-senior primary residence
real property classification. The treasurer shall mail or electronically send
the notice each year on or before the date on which the treasurer mails the
property tax statement for the previous property tax year pursuant to section
39-10-103. The administrator shall prescribe the form of the notice, which must
include a statement of the eligibility criteria for the primary residence real
property and qualified-senior primary residence real property classifications
and instructions for obtaining a related application.
(b) To
reduce mailing costs, an assessor may coordinate with the treasurer of the same
county to include notice with the tax statement for the previous property tax
year mailed pursuant to section 39-10-103, or may include notice with the
notice of valuation mailed pursuant to section 39-5-121 (1)(a).
(7) Notice
of classification - appeal.
(a) (I)
Except as otherwise provided in subsection (7)(b) of this section, an assessor
shall only classify property as qualified-senior primary residence real
property if an applicant has timely returned an application in accordance with
subsection (3) of this section that establishes that the classification is
appropriate.
(II) If
the information provided on or with an application indicates that the applicant
is not entitled to the classification, or is insufficient to allow the assessor
to determine whether the property meets the classification, the assessor shall
deny the application and mail to the applicant a statement providing the
reasons for the denial and informing the applicant of the applicant's right to
contest the denial pursuant to subsection (7)(b) of this section. The assessor
shall mail the statement no later than August 1 of the property tax year for
which the application was filed.
(b) (I)
An applicant whose application has been denied may contest the denial by
requesting a hearing before the county commissioners sitting as the county
board of equalization no later than August 15 of the property tax year for
which the application was filed. The hearing shall be held on or after August 1
and no later than September 1 of the property tax year for which the
application was filed, and the decision of the county board of equalization is
not subject to further administrative appeal by either the applicant or the
assessor.
(II) [Editor's
note: This version of subsection (7)(b)(II) is effective until January 1, 2027.]
An individual who has not timely filed an application with the assessor by
March 15 may file a late application no later than the July 15 that immediately
follows that deadline. The assessor shall accept any such application but may
not accept any late application filed after July 15. A decision of an assessor
to disallow the filing of a late application after July 15 or to grant or deny
the classification to an applicant who has filed a late application after March
15 but no later than July 15 is final, and an applicant who is denied late
filing or classification of property as qualified-senior primary residence real
property may not contest the denial.
(II)
[Editor's note: This version of subsection (7)(b)(II) is effective
January 1, 2027.] An individual who has not timely filed an application
with the assessor by July 15 may file a late application no later than the
August 15 that immediately follows that deadline. The assessor shall accept any
such application but may not accept any late application filed after August 15.
A decision of an assessor to disallow the filing of a late application after
August 15 or to grant or deny the classification to an applicant who has filed
a late application after July 15 but no later than August 15 is final, and an
applicant who is denied late filing or classification of property as
qualified-senior primary residence real property may not contest the denial.
(III)
The county board of equalization may appoint independent referees to conduct
hearings requested pursuant to subsection (7)(b)(I) of this section on behalf
of the county board and to make findings and submit recommendations to the
county board for its final action.
(8) Reporting
to administrator.
(a) No
later than September 10, 2025, and no later than September 10, 2026, each
assessor shall forward to the administrator a report on the residential real
property in the assessor's county that qualifies for classification as
qualified-senior primary residence real property for the current property tax
year. For each unit of residential real property, the report must include:
(I) The
legal description of the property;
(II)
The schedule or parcel number for the property;
(III)
The name and social security number of the applicant who claimed the
classification for the property and, if applicable, the applicant's spouse or
civil union partner who occupies the property;
(IV) A
statement of what the valuation for assessment of the property would be if it
had not qualified as qualified-senior primary residence real property and the
valuation for assessment of the property as qualified-senior primary residence
real property; and
(V) Any
other information that the administrator reasonably deems necessary.
(b) (I)
The administrator shall examine the reports sent by each assessor pursuant to
subsection (8)(a) of this section to ensure that no applicant has applied for a
qualified-senior primary residence real property classification without meeting
all legal requirements for obtaining the classification. No later than November
1, 2025, and no later than November 1, 2026, if the administrator determines
that an applicant has applied for more than one property to be classified as
qualified-senior primary residence real property, the administrator shall
provide written notice to the applicant that the applicant has applied for more
than one such classification and is therefore not entitled to the
classification for any property. If the administrator determines that the
applicant and the applicant's spouse have applied for separate properties to be
classified as qualified-senior primary residence real property, that the
classification was applied for in violation of subsection (4) of this section,
that the applicant has claimed the classification for residential real property
that the applicant does not own and occupy as the applicant's primary residence
as required by subsection (2)(a) of this section, or that the applicant is
otherwise ineligible for the classification, the administrator shall provide
written notice to an applicant that the applicant is ineligible and the reason
for the ineligibility. The notice must also include a statement specifying the
deadline and procedures for protesting the denial of the classification or
classifications claimed.
(II) An
applicant whose application for a qualified-senior primary residence real
property classification is denied by the administrator pursuant to subsection
(8)(b)(I) of this section may file a written protest with the administrator no
later than November 15 of the year in which the classification was denied. A
written protest returned by mail is deemed filed on the date it is postmarked.
If the ground for the denial is that the applicant, or the applicant and the
applicant's spouse or civil union partner, claimed multiple classifications,
the sole ground for a protest is that the applicant, or the applicant and the
applicant's spouse or civil union partner, filed only one claim for the
classification, and the protest must specify the property identified by the
administrator in the notice denying the classification for which no
classification was claimed. If the ground for the denial is that the applicant
is not an owner-occupier of the residential real property for which the
classification is claimed, the sole grounds for a protest are that the
applicant actually is an owner-occupier and that the applicant qualifies for
the classification. If a protest is denied, the administrator shall mail the
applicant a written statement of the basis for the denial and a copy of each
classification application filed with an assessor that the applicant claimed
had not been filed.
(c) No
later than December 1, 2025, and no later than December 1, 2026, and after
examining the reports sent by each assessor, denying applications for
classification of property as qualified-senior primary residence real property,
and deciding protests in accordance with subsection (8)(b) of this section, the
administrator shall provide written notice to the assessor of each county in
which an application has been denied because the applicant was ineligible that
includes the identity of each denied applicant and the reason for each denial.
(d) No
later than January 10, 2026, and no later than January 10, 2027, each assessor
shall forward to the administrator a partial copy of the tax warrant for the
assessor's county that includes only property for which the assessor has
granted an application for classification as qualified-senior primary residence
real property. The administrator shall examine the tax warrants to ensure that
no additional classifications of property as qualified-senior primary residence
real property have been allowed since the administrator examined the reports
previously received from the assessors and that each assessor has removed from
the tax warrant all such classifications that the administrator previously
denied. No later than January 17, 2026, and no later than January 17, 2027, the
administrator shall notify each assessor and each treasurer of any such
classifications to be removed from the tax warrant.
(9) Reporting
and reimbursement of property tax revenue reductions.
(a) No
later than March 1, 2026, and no later than March 1, 2027, each treasurer shall
forward to the administrator a report on the properties in the assessor's
county that were classified as qualified-senior primary residence real property
for the previous property tax year. The administrator shall cross-check the
report as specified in subsection (9)(b) of this section before correcting it,
if necessary, and forwarding it to the state treasurer to enable the state
treasurer to issue a reimbursement warrant to each treasurer in accordance with
subsection (9)(c) of this section. The report must include:
(I) A
statement of the total reduction in valuation for assessment in the county
resulting from the classification of residential real property as
qualified-senior primary residence real property and the total property tax
revenue lost by local governmental entities within the county as a result of
that classification that must be reimbursed by the state;
(II)
With respect to each unit of residential real property that is classified as
qualified-senior primary residence real property:
(A) The
legal description of the property;
(B) The
schedule or parcel number for the property;
(C) The
name of the applicant who applied for and obtained the classification for the
property and each additional person who occupies the property;
(D) A
statement of what the valuation for assessment of the property would be if it
had not qualified as qualified-senior primary residence real property and the
valuation for assessment of the property as qualified-senior primary residence
real property and the amount of taxes due on the property; and
(E) Any
other information that the administrator reasonably deems necessary.
(b)
After receiving reports from each treasurer pursuant to subsection (9)(a) of
this section, the administrator shall cross-check the reports to identify any
classification of property as qualified-senior primary residence real property
allowed in a county that must be denied due to a failure of the individual
allowed the classification to satisfy all legal requirements for obtaining the
classification. The administrator shall remove any classification of property
as qualified-senior primary residence real property that must be denied from
the report in which it appears and shall forward all reports to the state
treasurer no later than the April 1 immediately following the receipt of the
reports by the administrator. In addition, if the administrator identifies any
classification of property as qualified-senior primary residence real property
that was improperly allowed for a prior property tax year for which the state
treasurer reimbursed a treasurer pursuant to subsection (9)(c) of this section
or identifies any classification properly allowed for such a prior property tax
year for which the state treasurer did not reimburse a treasurer, the
administrator shall advise the state treasurer to adjust the current year
reimbursement to the treasurer to correct the error. No later than that April
1, the administrator shall also notify the treasurer and assessor of each
county of all classifications of property as qualified-senior primary residence
real property removed from the report for the county and any resulting and
other adjustments to the amount of current year reimbursement to be paid by the
state treasurer to the treasurer.
(c) (I)
(A) No later than April 15, 2026, and no later than April 15, 2027, the
state treasurer shall issue a warrant to each treasurer for the amount needed
to fully reimburse all local governmental entities within the treasurer's
county for the total property tax revenue lost for the prior property tax year
that are payable during the year in which the state treasurer issues the
warrant. The reimbursement must be paid from the state general fund and is not
subject to the statutory limitation on state general fund appropriations set
forth in section 24-75-201.1.
(B) As
used in subsection (9)(c)(I)(A) of this section, "total property tax
revenue lost" includes only revenue lost as a result of classifications of
property as qualified-senior residential real property properly allowed in
accordance with the requirements of this section and does not include any
revenue lost as a result of such a classification being erroneously allowed.
(II)
Each treasurer shall distribute the total amount received from the state
treasurer pursuant to subsection (9)(c)(I)(A) of this section to the local
governmental entities within the treasurer's county as if the total property
tax revenue lost had been regularly paid. When a treasurer distributes that
amount, the treasurer shall provide each local governmental entity with a
statement of the amount distributed to the local governmental entity that
represents reimbursement received from the state for total property tax revenue
lost.
(III)
Notwithstanding the provisions of subsections (9)(c)(I) and (9)(c)(II) of this
section, the state treasurer shall reduce a local governmental entity's
reimbursement as necessary to prevent the local governmental entity from
exceeding its fiscal year spending limit under section 20 (7)(b) of article X
of the state constitution for the fiscal year.
(d) In
accordance with subsection (9)(b) of this section, for any property tax year
commencing on or after January 1, 2025, but before January 1, 2027, the state
treasurer shall not reimburse a treasurer for total property tax revenue lost
as a result of a classification of real property as qualified-senior primary
residence real property that was erroneously granted in the treasurer's county.
If, pursuant to subsection (9)(b) of this section, the administrator advises
the state treasurer that the state treasurer has provided either too much or
too little reimbursement to a treasurer for classifications of real property as
qualified-senior primary residence real property granted in the treasurer's
county for any prior property tax year commencing on or after January 1, 2025,
but before January 1, 2027, the state treasurer shall adjust the reimbursement
for the current property tax year as directed by the administrator in order to
correct the error.
(e)
Notwithstanding any provision of law to the contrary, the reports required by
this subsection (9) and their contents shall be kept confidential by an
assessor, a treasurer, the administrator, the state treasurer, or the state
auditor; except that said persons may provide the reports to each other as
required or authorized by law.
(10) Reimbursement
as refund of excess state revenues.
(a) The
general assembly hereby finds and declares that section 20 of article X of the
state constitution authorizes the state to use any reasonable method to make
required refunds of excess state revenues, and the payment by the state of
reimbursement to local governmental entities for total property tax revenue
lost as a result of the classification of real property as qualified-senior
primary residence real property, which classification directly reduces the tax
liability of taxpaying Colorado residents throughout the state, is a reasonable
method of making such refunds.
(b) For
any state fiscal year commencing on or after July 1, 2024, for which state revenues,
as defined in section 24-77-103.6 (6)(c), exceed the excess state revenues cap,
as defined in section 24-77-103.6 (6)(b)(I)(C) or (6)(b)(I)(D), and are
required to be refunded in accordance with section 20 of article X of the state
constitution, the lesser of all reimbursement paid by the state treasurer to
each treasurer as required by subsection (9)(c) of this section for the
property tax year that commenced during the state fiscal year or an amount of
such reimbursement equal to the amount of such excess state revenues above the
amount of such excess state revenues that are required to be refunded pursuant
to section 39-3-209 is a refund of such excess state revenues.
(c) As
used in this subsection (10), unless the context otherwise requires,
"revenue lost as a result of the classification of real property as
qualified-senior primary residence real property" means revenue that is
lost as a result of certain residential properties being classified as
"qualified-senior primary residence real property", and having a
valuation for assessment determined pursuant to section 39-1-104.2 (3)(s),
rather than being classified as "all residential real property other than
qualified-senior primary residence real property" and having a valuation
for assessment determined pursuant to section 39-1-104.2 (3)(t), (3)(t.5),
(3)(u), and (3)(v).
Source:
L. 2024: Entire
section added, (SB 24-111), ch. 169, p. 871, § 4, effective August 7; (10)(c)
added, (SB 24-233), ch. 171, p. 920, § 8, effective October 1 (see editor's
note). L. 2024, 2nd Ex. Sess.: (10)(c) amended, (HB 24B-1001), ch. 1, p.
19, § 12, effective October 1 (see editor's note). L. 2026: IP(2)(a),
(3)(a), (5)(c), (6)(a), IP(8)(a), (8)(b)(I), (8)(c), and (8)(d) amended, (SB
26-116), ch. 307, p. 1756, § 1, effective August 12; (7)(b)(II) amended, (SB
26-046), ch. 10, p. 39, § 1, effective January 1, 2027.
Editor's
note: (1) (a)
Section 18 of chapter 1, (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, amended section 14 of chapter 171, (SB 24-233), Session
Laws of Colorado 2024, to change the effective date of SB 24-233 to October 1,
2024, if both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit are withdrawn pursuant to § 1-40-134 from the statewide ballot
for the general election held on November 5, 2024. On September 4, 2024, the
secretary of state announced both an initiative that reduces valuations for
assessment and an initiative that requires voter approval for retaining
property tax revenue that exceeds a limit were withdrawn from the 2024 general
election ballot.
(b) Section 18 of chapter 1,
(HB 24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
amending section 14 of chapter 171, (SB 24-233), Session Laws of Colorado 2024,
provides that changes to this section take effect only if SB 24-111 becomes
law. SB 24-111 became law and took effect August 7, 2024.
(2) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
39-1-104.7. Total program balancing
adjustment of residential rate - definitions. (Repealed)
Source:
L. 2024: Entire
section added, (SB 24-233), ch. 171, p. 919, § 7, effective October 1 (see
editor's note). L. 2024, 2nd Ex. Sess.: Entire section repealed, (HB
24B-1001), ch. 1, p. 19, § 13, effective October 1 (see editor's note).
Editor's
note: (1) (a)
Section 18 of chapter 1, (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, amended section 14 of chapter 171, (SB 24-233), Session
Laws of Colorado 2024, to change the effective date of SB 24-233 to October 1,
2024, if both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit are withdrawn pursuant to § 1-40-134 from the statewide ballot
for the general election held on November 5, 2024. On September 4, 2024, the
secretary of state announced both an initiative that reduces valuations for
assessment and an initiative that requires voter approval for retaining
property tax revenue that exceeds a limit were withdrawn from the 2024 general
election ballot.
(b) Section 18 of chapter 1,
(HB 24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
amending section 14 of chapter 171, (SB 24-233), Session Laws of Colorado 2024,
provides that this section takes effect only if HB 24-1448 becomes law. HB
24-1448 became law and took effect May 23, 2024.
(2) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act repealing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
39-1-105. Assessment date.
All
taxable property, real and personal, within the state at twelve noon on the
first day of January of each year, designated as the official assessment date,
shall be listed, appraised, and valued for assessment in the county wherein it
is located on the assessment date. Personal property shall be listed and valued
separately from real property. Whenever construction of any new taxable
building within the boundaries of a county occurs subsequent to the assessment
date but before July 1 and such county has resolved to implement the procedures
set out in section 39-5-132, such building shall be listed, appraised, and
valued pursuant to section 39-5-132.
Source:
L. 64: R&RE,
p. 677, § 1. C.R.S. 1963: § 137-1-5. L. 85: Entire section
amended, p. 1226, § 2, effective January 1, 1986. L. 86: Entire section
amended, p. 1222, § 35, effective May 30.
Cross
references: For
property brought into the state after assessment date, see § 39-5-110; for
property destroyed after the assessment date, see § 39-5-117; for the procedure
for exclusion of property within a municipality from a special district and for
the effect of such an exclusion order, see §§ 32-1-502 and 32-1-503.
ANNOTATION
This section does not
mandate that January 1 is the date for determining tax exempt status for
property owned by a charitable organization and does not address when the
tax exempt status is to be determined. Family Tree Found. v. Prop. Tax Adm'r,
119 P.3d 581 (Colo. App. 2005).
Section applies to entire
property tax system. If general assembly intended to make an exception to
January 1 assessment date, it would have done so explicitly. Larimer County BOE
v. 1303 Frontage, 2023 CO 28, 531 P.3d 1012.
City acquired an interest in
the personal property prior to the date of the chapter 11 bankruptcy since
the statute provides that a lien for ad valorem personal property taxes arises
at 12 noon on the assessment date for the current year and such lien is a
perpetual lien. Although the interest was an inchoate lien, the city was
allowed to perfect it after the assessment date and thus have the lien relate
back to the assessment date. Therefore the personal property taxes were a
prepetition secured claim. In re W. States Distribs., Inc., 179 B.R. 666
(Bankr. D. Colo. 1995).
Applied in City &
County of Denver v. Bd. of Dirs., 37 Colo. App. 496, 549 P.2d 1090 (1976);
Martin v. Bd. of Assess. Appeals, 707 P.2d 348 (Colo. 1985); Padgett v. Routt
County Bd. of Equal., 857 P.2d 565 (Colo. App. 1993); Mission Viejo Co. v. Bd.
of Equaliz., 942 P.2d 1251 (Colo. App. 1996).
39-1-105.5. Reappraisal ordered based on
valuation for assessment study - state school finance payments.
(1) (a)
Repealed.
(b) (I)
Pursuant to section 39-1-104 (16)(b) for each property tax year beginning with
the property tax year which commences January 1, 1985, the annual study shall,
in addition to other requirements, determine and set forth the aggregate
valuation for assessment of each county for the year in which the study is
conducted.
(II)
(A) If the valuation for assessment of a county as reflected in its abstract
for assessment for any property tax year beginning with the property tax year
commencing January 1, 1985, is more than five percent below the valuation for
assessment for such county as determined by the study conducted during the same
property tax year, the state board of equalization shall cause to be performed
a reappraisal of any class or classes of property that the study shows were not
appraised consistent with the property tax provisions of the Colorado
constitution or the statutes. The reappraisal must be performed during the next
following year at the expense of the county; except that the state board of
equalization may waive the requirement that the county reimburse the state for
any costs incurred by the state in reappraising any class or classes of
property if the county presents the state board with a plan to use the money
retained to improve the functioning of the office of the county assessor. If
the county fails to implement the plan submitted in a timely manner as agreed
upon by the state board and the county, the state board shall revoke the waiver
and require the county to reimburse the state for reappraisal costs incurred by
the state. The reappraisal is the county's valuation for assessment with regard
to the reappraised class or classes for the year in which the reappraisal is
performed.
(B)
Even though a county's aggregate valuation for assessment as reflected in its
abstract for assessment for any property tax year beginning with the property
tax year commencing January 1, 1985, is not more than five percent below the
valuation for assessment for such county as determined by the study conducted
during the same property tax year, the state board of equalization shall cause
to be performed a reappraisal of any class or classes of property that the
study shows were not appraised consistent with the property tax provisions of
the Colorado constitution or the statutes. The reappraisal must be performed
during the next following year at the expense of the county; except that the
state board of equalization may waive the requirement that the county reimburse
the state for any costs incurred by the state in reappraising any class or
classes of property if the county presents the state board with a plan to use
the money retained to improve the functioning of the office of the county
assessor. The reappraisal is the county's valuation for assessment with regard
to the reappraised class or classes of property for the year in which the
reappraisal is performed.
(III)
Whenever a reappraisal is ordered pursuant to subparagraph (II) of this
paragraph (b), state equalization payments to school districts within the
county during the year in which the reappraisal is performed shall be based
upon the valuation for assessment as reflected in the county's abstract for
assessment for the year prior to the year in which the reappraisal is
performed. The state board of equalization shall order the county's board of
county commissioners to levy, and the board of county commissioners shall levy,
an additional property tax on all taxable property within the county. Such
additional property tax shall be levied at the same time as other property
taxes are levied during the year in which the reappraisal is performed. Such
additional property tax shall be in an amount which is sufficient to reimburse
the state for the excess state equalization payments made to school districts
within the county during the year in which the reappraisal is performed. The
county's board of county commissioners shall reimburse the state for such
excess state equalization payments. Such excess shall be that amount of the
state equalization payments actually paid by the state to the county during the
year in which the reappraisal is performed based on the incorrect valuation for
assessment as reflected in the county's abstract for assessment for the
immediately prior year which amount exceeds the state equalization payments the
state would have paid during the year in which the reappraisal is performed had
the valuation for assessment for the immediately prior year been determined by
the assessor consistent with the provisions of the Colorado constitution and
the statutes. In addition, the additional property tax shall be sufficient to
pay to the state, and the board of county commissioners shall pay to the state,
interest on such excess at the interest rate determined by the state banking
commissioner pursuant to section 39-21-110.5.
(IV) If
the valuation for assessment of a county as reflected in its abstract for
assessment for any property tax year beginning with the property tax year
commencing January 1, 1985, is more than five percent below the valuation for
assessment for such county as determined by the study conducted during the same
property tax year and if the state board of equalization fails to order a
reappraisal, state equalization payments to school districts within the county
during the year next following the year in which the study was performed shall
be based upon the valuation for assessment for the county as reflected in the
county's abstract for assessment for the year in which the study was conducted.
At the same time as other property taxes are levied during the year in which
such state equalization payments are made, the county's board of county
commissioners shall levy an additional property tax on all taxable property
within the county. Such additional property tax shall be in an amount
sufficient to reimburse the state for the difference between the amount the
state actually paid in state equalization payments during the year following
the year in which the study was performed and what the state would have paid
during such year had the state equalization payments been based on the
valuation for assessment as determined by the study. The county's board of
county commissioners shall reimburse the state for such difference.
(V) Any
finding made in 1988 pursuant to the provisions of subparagraph (II) of this
paragraph (b) shall be based primarily on data and information collected from
within the county in question, except where data is lacking or deficient. If
data from outside the county must be used, then that data must be from a
comparable area. If any finding made utilizing the study conducted for the
property tax year commencing on January 1, 1987, was based upon data and
information comparing taxable property in one county with taxable property in
the county subject to such finding, the state board of equalization shall
revise such finding so that any orders made pursuant to the provisions of
subparagraph (II) of this paragraph (b) are based solely on data and
information collected from within each affected county.
(2) Any
reimbursement made by a county to the state for the cost incurred by the state
in reappraising any class or classes of taxable property for property tax
purposes pursuant to subsection (1) of this section shall be made to the state
treasurer who shall credit the amount of the reimbursement to the state general
fund. For purposes of this section, the costs of salary and benefits for state
employees who work on reappraisals is not a reimbursable cost incurred by the
state.
Source:
L. 83: Entire
section added, p. 1506, § 4, effective June 2. L. 84: (2) added, p. 733,
§ 2, effective May 11. L. 87: (1)(b)(III) amended, p. 1394, § 1,
effective July 1. L. 88: (1)(b)(V) added, p. 1282, § 6, effective
January 1, 1989. L. 89: (1)(b)(III) amended, p. 1451, § 4, effective
June 7. L. 2004: (1)(a) repealed, p. 205, § 27, effective August 4. L.
2014: (1)(b)(II)(A), (1)(b)(II)(B), and (2) amended, (SB 14-083), ch. 44,
p. 216, § 1, effective August 6.
39-1-106. Partial interests not
subject to separate tax.
For
purposes of property taxation, it shall make no difference that the use,
possession, or ownership of any taxable property is qualified, limited, not the
subject of alienation, or the subject of levy or distraint separately from the
particular tax derivable therefrom. Severed mineral interests shall also be
taxed.
Source:
L. 64: R&RE,
p. 677, § 1. C.R.S. 1963: § 137-1-6. L. 73: p. 1430, § 2. L.
96: Entire section amended, p. 1850, § 2, effective June 5. L. 2002:
Entire section amended, p. 1008, § 2, effective August 7.
ANNOTATION
This section establishes a
unity rule for the assessment of property rather than requiring assessment
of the various interests in the property. Bd. of Assess. Appeals v. City &
County of Denver, 829 P.2d 1319 (Colo. App. 1991), aff'd, 848 P.2d 355 (Colo.
1993).
The unit assessment rule
established in this section has no application in the absence of multiple
taxpayers with interests in a single property. Rare Air Ltd. v. Prop. Tax
Adm'r, 2019 COA 134, 459 P.3d 547.
Taxation of development
rights does not violate the unit assessment rule. Because the assignment of
the development rights created separate interests in real estate as between the
interests of the individual unit owners, on the one hand, and those of the
owners of the development rights, on the other hand, separate taxation of those
interests does not violate the unit assessment rule. Vill. at Treehouse v.
Prop. Tax Adm'r, 2014 COA 6, 321 P.3d 624.
Section does not apply to
golf club membership that created a license and not an interest in land.
Roaring Fork Club v. Pitkin Bd. of Equaliz., 2013 COA 167, 342 P.3d 467.
39-1-107. Tax liens.
(1) The
lien of general taxes for the current year, including taxes levied pursuant to
section 39-5-132, shall attach to all taxable property, real and personal, at
12 noon on the assessment date.
(2)
Taxes levied on real and personal property, together with any delinquent
interest, advertising costs, and fees prescribed by law with respect to any
such taxes as may have become delinquent, shall be a perpetual lien thereon,
and such lien shall have priority over all other liens until such taxes,
delinquent interest, advertising costs, and fees shall have been paid in full.
(3)
Repealed.
(4) The
property tax on a possessory interest in real or personal property that is
exempt from taxation under this article shall be assessed to the holder of the
possessory interest and collected in the same manner as property taxes assessed
to owners of real or personal property; except that such property tax shall not
become a lien against the property. When due, the property tax shall be a debt
due from the holder of the possessory interest to the board of county
commissioners for the county in which such property is located or to such other
body as is authorized by law to levy property taxes, and shall be recoverable
by such board or body by direct action in debt on behalf of each governmental
entity for which a property tax levy has been made.
Source:
L. 64: R&RE,
p. 677, § 1. C.R.S. 1963: § 137-1-7. L. 67: p. 212, § 1. L.
75: (1) amended, p. 1462, § 1, effective January 1, 1976. L. 83: (3)
repealed, p. 1485, § 11, effective April 22. L. 85: (1) amended, p.
1226, § 3, effective January 1, 1986. L. 89: (1) amended, p. 1482, § 5,
effective April 23. L. 92: (2) amended, p. 2222, § 1, effective April 9.
L. 2002: (4) added, p. 1008, § 3, effective August 7. L. 2016:
(1) amended, (SB 16-189), ch. 210, p. 792, § 105, effective June 6.
Cross
references: For
receipts for taxes paid, see § 39-10-105; for the effect of issuance of
certificate of taxes due, see § 39-10-115; for sale of tax liens, see article
11 of this title 39.
ANNOTATION
I.
General Consideration.
II.
The Tax Lien.
III.
Priority of Tax Lien.
I. GENERAL CONSIDERATION.
Law reviews. For
article, "Taxation of Estates Pending Probate", see 6 Dicta 15 (Apr.
1929). For article, "Federal and State Tax Liens: A Question of
Priority", see 12 Colo. Law. 1967 (1983). For article, "An
Introduction to Tax Liens", see 13 Colo. Law. 399 (1984). For article,
"Survey of Colorado Tax Liens", see 14 Colo. Law. 1765 (1985). For
article, "Taxation of Possessory Interests in Exempt Property Under S.B.
02-157", see 32 Colo. Law. 81 (Mar. 2003).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Question of tax liens and
their priority is for legislative determination. In the absence of
legislative action so declaring, taxes are not a lien upon the property. People
v. City & County of Denver, 85 Colo. 61, 273 P. 883 (1928).
Revenue statutes are to be
construed in favor of the public. Gifford v. Callaway, 8 Colo. App. 359, 46
P. 626 (1896).
Applied in Bd. of
Comm'rs v. Denver & S. L. R. R., 88 Colo. 14, 291 P. 1020 (1930).
II. THE TAX LIEN.
Lien effective upon
assessment and levy. The tax lien provided does not become effective until
the property is assessed and the taxes levied, at which time the theretofore
inchoate lien relates back and attaches as of the date authorized for
assessment. Wolf v. Antonoff, 161 Colo. 473, 423 P.2d 840 (1967).
Lien embraces only specific
property levied upon. Chicago Bazaar Co. v. McNichols, 13 Colo. App. 154,
56 P. 672 (1899).
A tax lien against real
property in one county may not be attached to an improvement upon real property
in another county. When a motel which was subject to the plaintiff's tax
lien on real property in Garfield County was dismantled and moved to the City
and County of Denver, it became personal property which was no longer subject
to such lien. Israel v. Rifle Econolodge Joint Venture, 793 P.2d 658 (Colo.
App. 1990).
Except as to stocks in
merchandise. The lien attaches to an entire stock in merchandise, through
all its changes, so long as it remains in the hands of the person taxed.
Chicago Bazaar Co. v. McNichols, 13 Colo. App. 154, 56 P. 672 (1899) (decided
under former law).
Even stocks in merchandise
held by trustee in bankruptcy. Lien covers the stock of merchandise and
fixtures which subsequently came into the possession of the taxpayer's trustee
in bankruptcy. De Laney v. City & County of Denver, 185 F.2d 246 (10th Cir.
1950) (decided under former law).
Statutory mode of collection
must be pursued although tax deemed lien. If a specific mode is provided
whereby the land may be sold to satisfy a tax lien, no suit in equity to
enforce the sale can be maintained. The specific statutory mode of collection
must be pursued. Montezuma Valley Water Supply Co. v. Bell, 20 Colo. 175, 36 P.
1102 (1894).
Lien upon land without
regard to title. This section creates a lien upon real estate for the taxes
assessed against it: the assessment and all subsequent proceedings down to and
including the sale, are against the land without regard to title. Statton v.
People ex rel. Burr, 18 Colo. App. 85, 70 P. 157 (1902).
This section and § 39-10-115
to be construed together. This section and § 39-10-115, concerning
certificates of taxes due, should be construed together to mean simply that tax
due on real property shall be a perpetual lien upon the real estate until paid
or until the treasurer certifies payment. Burton v. City & County of
Denver, 99 Colo. 207, 61 P.2d 856 (1936).
No law limits phrase
"perpetual lien", or requires its foreclosure within a specified
time on peril of its loss. Bd. of Comm'rs v. Denver & S. L. R. R., 88 Colo.
14, 291 P. 1020 (1930).
Lien on personalty not lost
by issuance of tax receipt. Where the personal property in question
continues the property of the taxpayer owing the tax and remains in the same
jurisdiction, mere issuance of a tax receipt will not oust the lien of taxes,
where the county treasurer failed to collect interest on taxes owed. People ex
rel. King v. Myers, 16 Colo. App. 371, 65 P. 409 (1901).
Tax assessed for irrigation
district is lien upon the land upon which it is levied. Weghorst v. Clark,
66 Colo. 535, 180 P. 742 (1919).
Prospect of future taxes not
lien on property. The mere existence of a water and sanitation district and
the prospect of taxes in the future was not a lien, encumbrance, or defect on
the title to property. Edwards v. St. Paul Title Ins. Co., 39 Colo. App. 235,
563 P.2d 979 (1977).
City acquired an interest in
the personal property prior to the date of the chapter 11 bankruptcy since
the statute provides that a lien for ad valorem personal property taxes arises
at 12 noon on the assessment date for the current year and such lien is a
perpetual lien. Although the interest was an inchoate lien, the city was
allowed to perfect it after the assessment date and thus have the lien relate
back to the assessment date. Therefore the personal property taxes were a
prepetition secured claim. In re W. States Distribs., Inc., 179 B.R. 666
(Bankr. D. Colo. 1995).
III. PRIORITY OF TAX LIEN.
Priority of tax liens by
express provision. Although the general assembly has the power to declare
that tax liens shall be preferred, it must do so by express provision.
Otherwise, priority in time will determine. United States v. Elliott, 209 F.
Supp. 374 (D. Colo. 1962).
Lien for taxes superior to
all other liens. The lien of taxes attaches to the land without regard to
title and, consequently, is superior to all other liens. Statton v. People ex
rel. Burr, 18 Colo. App. 85, 70 P. 157 (1902).
No lien upon land for
personal tax cuts off prior valid lien upon the land. Bd. of Comm'rs v.
McDonald, 78 Colo. 519, 242 P. 682 (1926); United States v. Elliott, 209 F.
Supp. 374 (D. Colo. 1962).
Priority of debt due United
States federal question. Where the United States claims a priority, the
priority of a lien for general taxes must be determined under federal law.
United States v. Maes, 316 F. Supp. 1267 (D. Colo. 1969).
When county treasurer not
indispensable party. The county treasurer who issued certificate of sale to
tax sale purchaser is not an indispensable party to a proceeding challenging
priority of lien of secured party in property sold at tax sale where he claims
no interest in the property since the tax lien has been discharged and where
complete relief can be afforded without his presence as a party. John Deere
Indus. Equip. Co. v. Moorehead, 38 Colo. App. 220, 556 P.2d 91 (1976), rev'd on
other grounds, 194 Colo. 398, 572 P.2d 1207 (1977).
39-1-108. Payment of taxes - grantor
and grantee.
As between
the grantor and grantee of property other than property described in section
39-5-104.5, when the instrument of conveyance does not contain an express
agreement as to which party shall pay the taxes that may be levied on the
property conveyed in the year in which conveyed, if such conveyance is made
after the thirty-first day of December and before the first day of July next
following, the grantee shall pay such taxes; but if the conveyance is made
after the thirtieth day of June and before the first day of January next
following, the grantor shall pay such taxes.
Source:
L. 64: R&RE,
p. 677, § 1. C.R.S. 1963: § 137-1-8. L. 2020: Entire section
amended, (HB 20-1077), ch. 80, p. 324, § 6, effective September 14.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
"Taxes" not
limited to general property taxes. If it had been the intention of the
general assembly to limit application of this section to general property
taxes, it is reasonable to believe that the general assembly would have so
indicated by apt language. McCord Mercantile Co. v. McIntyre, 25 Colo. App.
376, 138 P. 59 (1914).
Section applies to
irrigation district taxes. McCord Mercantile Co. v. McIntyre, 25 Colo. App.
376, 138 P. 59 (1914).
Tax liability even where
assessment not yet completed. One conveying lands in September is liable
for tax of the same year even though, at the date of the conveyance, the
assessment had not been completed nor become a lien on the lands. Rambo v.
Armstrong, 45 Colo. 124, 100 P. 586 (1909).
Tax liability for successive
conveyances in last half of year. Where, at the end of the year, grantee,
who purchased property in the last half of the year, has parted with title to
that property and a third party owns it, there can be no recovery by grantee in
first deed against his grantor for tax assessed against the property in the
absence of allegations and proof that, in the course of the subsequent change
in ownership, the grantee in the first deed either has obligated himself to his
grantee to pay the taxes or otherwise sustained an equivalent loss. W. Dev.
& Realization Corp. v. Hext, 108 Colo. 312, 117 P.2d 313 (1941).
Grantee in last half of year
indemnified by implied contract. Contract implied by this section is to
indemnify grantee of a conveyance in the last half of the year against loss for
the payment of taxes on property which he owned and of which he had the use for
less than half a year. W. Dev. & Realization Corp. v. Hext, 108 Colo. 312,
117 P.2d 313 (1941).
Section is not applicable
where property is taken by condemnation proceedings. Fishel v. City &
County of Denver, 106 Colo. 576, 108 P.2d 236 (1940).
39-1-109. Taxes paid by mortgagee -
effect.
If the
mortgagor of real property fails or neglects to pay the taxes levied on such
property or permits such property to be sold for taxes, the mortgagee may pay
said taxes or redeem such property if sold for taxes, and any taxes so paid or
redeemed shall become and be a lien upon such real property until the same have
been repaid to the mortgagee. Upon payment of any such mortgage or in an action
to enforce the same, such mortgagee may demand the taxes so paid or redeemed,
with interest thereon at the same rate specified in the mortgage, and the same
shall be included in any judgment rendered on the mortgage. The term "mortgage"
includes deeds of trust, and the term "mortgagee" includes the
beneficiary of a deed of trust.
Source:
L. 64: R&RE,
p. 678, § 1. C.R.S. 1963: § 137-1-9. L. 73: p. 1417, § 100.
ANNOTATION
Law reviews. For
article, "Property Taxation of Oil and Gas Interests", see 24 Rocky
Mt. L. Rev. 170 (1952).
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Mortgagee must look to land
for reimbursement. Payment of taxes upon mortgaged land affords to the
mortgagee no personal action against the mortgagor, in the absence of a
covenant to this effect; he must look to the land for reimbursement. Gilmour v.
First Nat'l Bank, 21 Colo. App. 301, 121 P. 767 (1912).
Mortgagee entitled to credit
for amounts paid for taxes as against mortgagors in an action by mortgagors
for an accounting and to redeem. Dubois v. Bowles, 30 Colo. 44, 69 P. 1067
(1902).
Applied in Kansas City
Life Ins. Co. v. Prowers County Oil & Gas Co., 81 Colo. 177, 254 P. 438
(1927).
39-1-110. Notice - formation of
political subdivision - boundary change of special district.
(1) (a)
When any petition for the organization of a political subdivision is filed, the
clerk of any court or board or any other officer with whom the petition has
been filed shall immediately, in writing, notify the assessor and the board of
county commissioners of each county in which the proposed political subdivision
is to be located and the division of local government of the filing, and such
notice shall specify the boundaries of the proposed political subdivision. No
political subdivision shall levy a tax for the calendar year in which it has
been organized unless, prior to July 1 of said year, the assessor and the board
of county commissioners of each county within which such political subdivision
is located have been notified of its organization and have received from its
governing body the following:
(I)
Official notice that a tax will be levied for such year;
(II) A
legal description; and
(III) A
map of the political subdivision.
(b) No
levy for the calendar year in which a political subdivision has been organized
shall be made by the board of county commissioners or certified to the assessor
unless the political subdivision has complied with the provisions of paragraph
(a) of this subsection (1).
(1.5)
No political subdivision that is a special district shall levy a tax against
property included in the special district for the calendar year during which
such property was included unless, prior to May 1 of said year or, if such
property is included in the special district pursuant to section 32-1-401 (2),
C.R.S., prior to July 1 of said year, the court order of inclusion has been
filed with the county clerk and recorder of the county in which the inclusion
took place in accordance with the provisions of section 32-1-105, C.R.S.
(1.8) A
political subdivision that is a special district shall not levy a tax against
property excluded from the special district for the calendar year during which
such exclusion becomes effective if, prior to May 1 of said year, the court
order of exclusion has been filed with the county clerk and recorder of the
county in which the exclusion took place in accordance with the provisions of
section 32-1-105, C.R.S.
(2)
Whenever all or any portion of a political subdivision becomes part of another
county by reason of any change in county boundaries, the governing body of such
political subdivision shall, within thirty days after the effective date of
such change, notify, in writing, the assessor and the board of county
commissioners of the county, of which all or any portion of such political
subdivision has become a part, of its intention to levy a tax for the year in
which such change became effective.
(3) The
provisions of this section shall not apply to any school district, local
college district, health service district created pursuant to section
32-1-1003, C.R.S., or health assurance district created pursuant to section
32-1-1003.5, C.R.S.
(4) For
purposes of this section, "special district" means a special district
formed in accordance with the provisions of title 32, C.R.S.
Source:
L. 64: R&RE,
p. 678, § 1. C.R.S. 1963: § 137-1-10. L. 67: p. 946, § 6. L.
70: p. 380, § 11. L. 72: p. 620, § 162. L. 73: p. 1432, § 1. L.
85: (1) amended, p. 1022, § 10, effective July 1. L. 87: (1.5) and
(1.8) added, p. 1396, § 1, effective April 22. L. 90: (1) amended, p.
1436, § 8, effective January 1, 1991. L. 2003: (1), (1.5), (1.8), and
(2) amended and (4) added, p. 746, § 1, effective March 25. L. 2007: (3)
amended, p. 1201, § 19, effective July 1.
Cross
references: For
required notice for organization, dissolution, name change, or boundary change
of a special district, see § 32-1-105.
39-1-111. Taxes levied by board of
county commissioners.
(1) (a)
No later than December 22 in each year, the board of county commissioners in
each county of the state, or such other body in the city and county of Denver
as shall be authorized by law to levy taxes, or the city council of the city
and county of Broomfield, shall, either by an order to be entered in the record
of its proceedings or by written approval, levy against the valuation for
assessment of all taxable property located in the county on the assessment
date, and in the various towns, cities, school districts, and special districts
within such county, the requisite property taxes for all purposes required by
law.
(b)
Repealed.
(2) As
soon as such levies have been made, the board of county commissioners, or other
body authorized by law to levy taxes, or either group's authorized party shall
forthwith certify all such levies to the assessor, upon forms prescribed by the
administrator, and shall transmit a copy of such certification to the
administrator, to the division of local government, and to the department of
education, in an electronic or paper format.
(3) If
the board of county commissioners, or other body authorized by law to levy
taxes, or either group's authorized party fails to certify such levies to the
assessor, it is the duty of the assessor, upon direction of the division of
local government, to extend the levies of the previous year, subject to the
limitations prescribed in section 29-1-301.
(4) (a)
If the valuation for assessment for all or any part of any body authorized to
levy taxes has been divided for an urban renewal area, pursuant to section
31-25-107 (9)(a), the board of county commissioners shall make the same levy on
the portion of valuation for assessment divided under section 31-25-107
(9)(a)(II) as under section 31-25-107 (9)(a)(I) for payment of taxes according
to the provisions of section 31-25-107 (9)(a), so long as the division remains
in effect.
(b) If
the valuation for assessment for all or any part of any body authorized to levy
taxes has been divided for a county revitalization area, pursuant to section
30-31-109 (13)(a), the board of county commissioners shall make the same levy
on the portion of valuation for assessment divided under section 30-31-109
(13)(a)(II) as under section 30-31-109 (13)(a)(I) for payment of taxes
according to the provisions of section 30-31-109 (13)(a), so long as the
division remains in effect.
(5) (a)
If, after certification of the valuation for assessment pursuant to section
39-5-128 and notification of total actual value pursuant to section 39-5-121
(2)(b) but prior to December 10, changes in such valuation for assessment or
total actual value are made by the assessor, the assessor shall send a single
notification to the board of county commissioners or other body authorized by
law to levy property taxes, to the division of local government, and to the
department of education that includes all of such changes that have occurred
during said specified period of time. Upon receipt of such notification, such
board or body shall make adjustments in the tax levies to ensure compliance
with section 29-1-301, if applicable, and may make adjustments in order that
the same amount of revenue be raised. A copy of any adjustment to tax levies
shall be transmitted to the administrator and assessor. Nothing in this
subsection (5) shall be construed as conferring the authority to exceed
statutorily imposed mill levy or revenue-raising limits.
(b)
Repealed.
Source:
L. 64: R&RE,
p. 679, § 1. C.R.S. 1963: § 137-1-11. L. 69: p. 1115, § 1. L.
70: p. 380, § 12. L. 72: p. 620, § 163. L. 73: p. 1433, § 2. L.
75: (1) amended, p. 1456, § 1, effective July 14; (4) added, p. 1278, § 5,
effective July 16. L. 76: (1) amended, p. 686, § 3, effective July 1. L.
81: (5) added, p. 1397, § 7, effective June 19. L. 84: (5) amended,
p. 991, § 1, effective March 26. L. 87: (1) and (5) amended, p. 1410, §
13, effective April 22. L. 88: (1) amended, p. 823, § 36, effective May
24; (1) amended, p. 1283, § 8, effective January 1, 1989. L. 89: (1) and
(5) amended, p. 1452, § 5, effective June 7. L. 93: (2) and (5) amended,
p. 1282, § 3, effective June 6. L. 96: (5) amended, p. 719, § 2,
effective May 22. L. 2001: (1) amended, p. 268, § 15, effective November
15. L. 2021: (1), (2), and (3) amended, (HB 21-1267), ch. 257, p. 1513,
§ 2, effective September 7. L. 2023, 1st Ex. Sess.: (1) and (5) amended,
(SB 23B-001), ch. 1, p. 10, § 9, effective November 20. L. 2024: (4)
amended, (HB 24-1172), ch. 387, p. 2682, § 16, effective August 7. L. 2026:
(2) amended, (SB 26-046), ch. 10, p. 39, § 2, effective August 12.
Editor's
note: (1)
Amendments to subsection (1) by House Bill 88-1341 and Senate Bill 88-184 were
harmonized.
(2) Subsections (1)(b)(II) and
(5)(b)(II) provided for the repeal of subsections (1)(b) and (5)(b),
respectively, effective July 1, 2025. (See L. 2023, 1st Ex. Sess., p. 10.)
Cross
references: For
certification by boards of education of amounts that may be levied by boards of
county commissioners for school districts, see § 22-40-102; for the procedure
for levy and collection of taxes in a special district and the duty of county
officers to levy and collect the taxes, see §§ 32-1-1201 and 32-1-1202.
ANNOTATION
Law reviews. For
article, "A Calendar of Tax Procedure in Colorado", see 6 Dicta 17
(July 1929).
Action of board of county
commissioners under subsection (1) is purely ministerial. Bolt v. Arapahoe
County Sch. Dist. No. 6, 898 P.2d 525 (Colo. 1995).
Applied in City &
County of Denver v. Bd. of Dirs., 37 Colo. App. 496, 549 P.2d 1090 (1976).
39-1-111.5. Temporary property tax
credits and temporary mill levy rate reductions.
(1) In
order to effect a refund for any of the purposes set forth in section 20 of
article X of the state constitution, or to provide property tax relief by a
temporary reduction in property taxes due, any local government may approve and
certify a temporary property tax credit or temporary mill levy rate reduction
as set forth in this section. A district, as defined in section 22-54-103 (5),
may not reduce a mill levy below the minimum amounts provided in section
22-54-106. The procedures set forth in this section are deemed to be a
reasonable method for effecting refunds in accordance with section 20 of
article X of the state constitution and for providing temporary property tax
relief. A temporary reduction in property taxes due for the purpose of property
tax relief is subject to annual renewal.
(2)
Concurrent with the certification of its levy to the board of county
commissioners as required pursuant to section 39-5-128 (1), any local
government may certify a temporary property tax credit or temporary mill levy
rate reduction. The certification must include the local government's gross
mill levy, the temporary property tax credit or temporary mill levy rate
reduction expressed in mill levy equivalents, and the net mill levy, which must
be the gross mill levy less the temporary property tax credit or temporary mill
levy rate reduction. A district, as defined in section 22-54-103 (5), may not
certify a net mill levy below the minimum amounts provided in section
22-54-106.
(3)
Concurrent with certification to the assessor of all mill levies by the board
of county commissioners or other body authorized by law to levy taxes, or by
either group's authorized party, in accordance with section 39-1-111 (2), the
board of county commissioners shall certify any other local government's
temporary property tax credit or temporary mill levy rate reduction and any
temporary property tax credit or temporary mill levy rate reduction for the
county or city and county itself, itemized as set forth in subsection (2) of
this section.
(4)
Concurrent with the delivery to the treasurer of the tax warrant by the
assessor in accordance with section 39-5-129, the assessor shall, in addition
to all other information required to be set forth in the tax warrant, itemize
in the manner set forth in subsection (2) of this section any duly certified
temporary property tax credit or temporary mill levy rate reduction.
(5)
Upon receipt of any tax warrant reflecting a temporary property tax credit or
temporary mill levy rate reduction for any local government, the treasurer
shall be responsible for collecting taxes on behalf of the local government
based upon the local government's net adjusted mill levy. In addition to any
other information required by section 39-10-103, the tax statement must
indicate by footnote which, if any, local government mill levies in the tax
statement reflect a temporary property tax credit or temporary mill levy rate
reduction for the purpose of effecting a refund in accordance with section 20
of article X of the state constitution or for providing temporary property tax
relief.
Source:
L. 93: Entire
section added, p. 1686, § 1, effective June 6. L. 2021: (3) amended, (HB
21-1267), ch. 257, p. 1514, § 3, effective September 7. L. 2023: (1),
(2), and (5) amended, (SB 23-108), ch. 348, p. 2083, § 1, effective August 7.
39-1-112. Taxes available - when.
Except as
otherwise provided in article 1.5 of this title, all taxes levied pursuant to
the provisions of articles 1 to 13 of this title shall be available for
expenditure by the political subdivision for which levied during its fiscal
year as collected.
Source:
L. 64: R&RE,
p. 679, § 1. C.R.S. 1963: § 137-1-12. L. 81: Entire section
amended, p. 1841, § 2, effective May 28.
39-1-113. Abatement and refund of
taxes.
(1)
Except as otherwise provided in subsection (1.5) of this section, no decision
on any petition regarding abatement or refund of taxes, as provided for in
section 39-10-114, shall be made by the board of county commissioners unless a
hearing is had thereon, at which hearing the assessor and the taxpayer shall
have the opportunity to be present. The board may appoint independent referees
who are experienced in property valuation to conduct the hearing on behalf of
the board, to make findings, and to submit recommendations to the board for its
final decision.
(1.5) [Editor's
note: This version of subsection (1.5) is effective until January 1, 2027.]
Upon authorization by the board of county commissioners, the assessor may
review petitions for abatement or refund and settle by written mutual agreement
any such petition for abatement or refund in an amount of ten thousand dollars
or less per tract, parcel, or lot of land or per schedule of personal property.
Any abatement or refund agreed upon and settled pursuant to this subsection
(1.5) shall not be subject to the requirements of subsection (1) of this
section.
(1.5) [Editor's
note: This version of subsection (1.5) is effective January 1, 2027.]
Upon authorization by the board of county commissioners, the assessor may
review petitions for abatement or refund and settle by written mutual agreement
any such petition for abatement or refund in an amount of twenty thousand
dollars or less per tract, parcel, or lot of land or per schedule of personal
property. Any abatement or refund agreed upon and settled pursuant to this
subsection (1.5) shall not be subject to the requirements of subsection (1) of
this section.
(1.7)
Every petition for abatement or refund filed pursuant to section 39-10-114
shall be acted upon pursuant to the provisions of this section by the board of
county commissioners or the assessor, as appropriate, within six months of the
date of filing such petition.
(2) [Editor's
note: This version of subsection (2) is effective until January 1, 2027.]
(a)
Whenever any abatement or refund in an amount of ten thousand dollars or less
is recommended by the board of county commissioners, the board shall order the
abatement of taxes pro rata for all levies applicable to such property, or, in
the case of a refund, the board shall order the refund of taxes pro rata by all
jurisdictions receiving payment thereof.
(b)
Whenever any abatement or refund in an amount of ten thousand dollars or less
has been agreed upon and settled by the assessor pursuant to subsection (1.5)
of this section, the assessor shall order the abatement of taxes pro rata for
all levies applicable to such property, or, in the case of a refund, the
assessor shall order the refund of taxes pro rata by all jurisdictions
receiving payment thereof.
(2) [Editor's
note: This version of subsection (2) is effective January 1, 2027.]
(a)
Whenever any abatement or refund in an amount of twenty thousand dollars or
less is recommended by the board of county commissioners, the board shall order
the abatement of taxes pro rata for all levies applicable to such property, or,
in the case of a refund, the board shall order the refund of taxes pro rata by
all jurisdictions receiving payment thereof.
(b)
Whenever any abatement or refund in an amount of twenty thousand dollars or
less has been agreed upon and settled by the assessor pursuant to subsection
(1.5) of this section, the assessor shall order the abatement of taxes pro rata
for all levies applicable to such property, or, in the case of a refund, the
assessor shall order the refund of taxes pro rata by all jurisdictions
receiving payment thereof.
(3) [Editor's
note: This version of subsection (3) is effective until January 1, 2027.]
Whenever any abatement or refund in an amount in excess of ten thousand dollars
is recommended by the board of county commissioners, two copies of an
application therefor, reciting the amount of such abatement or refund and the
grounds upon which it should be allowed, shall be submitted to the
administrator for review pursuant to section 39-2-116. If an application is
approved, the board of county commissioners shall order the abatement of taxes
pro rata for all levies applicable to such property, or, in the case of a
refund, the board of county commissioners shall order the refund of taxes pro
rata by all jurisdictions receiving payment thereof.
(3) [Editor's
note: This version of subsection (3) is effective January 1, 2027.]
Whenever any abatement or refund in an amount in excess of twenty thousand
dollars is recommended by the board of county commissioners, the board shall
submit one copy of an application for abatement or refund in an electronic or
paper format, reciting the amount of such abatement or refund and the grounds
upon which it should be allowed, to the administrator for review pursuant to
section 39-2-116; except that the board of county commissioners is not required
to submit an application to the administrator in the case of an abatement or
refund caused by a valuation change to ensure matching values within the same
reassessment cycle. If an application is approved, the board of county
commissioners shall order the abatement of taxes pro rata for all levies
applicable to such property, or, in the case of a refund, the board of county
commissioners shall order the refund of taxes pro rata by all jurisdictions
receiving payment thereof.
(4)
(Deleted by amendment, L. 91, p. 1962, § 2, effective June 5, 1991.)
(5) (a)
If a hearing is required pursuant to subsection (1) of this section, the board
of county commissioners shall provide at least seven days' notice of the
scheduled hearing on a petition for abatement and refund of taxes to the person
signing such petition and the taxpayer if the taxpayer did not sign the
petition. Except as authorized in paragraph (b) of this subsection (5), notice
shall be provided by sending to such person through the United States mail
notification of the date, time, and place of the hearing.
(b) A
board of county commissioners may authorize by resolution a person required to
be notified by paragraph (a) of this subsection (5) or such person's agent to
elect to receive the notice by fax or electronic mail at a phone number or
electronic mail address supplied by such person. If no election is made by such
person, the board of county commissioners shall mail the required notice.
(6)
Notwithstanding any law to the contrary, for taxes levied on and after January
1, 1990, a taxpayer may file a petition for abatement or refund of taxes levied
on property if the valuation of such property was the subject of an arbitration
hearing pursuant to section 39-8-108.5 and the arbitrator presiding over such
hearing failed to deliver a decision to the taxpayer prior to the beginning
date of the period during which the assessor sits to hear all objections and
protests concerning the valuation of such property in the year following the
year in which such arbitration hearing was held.
Source:
L. 64: R&RE,
p. 679, § 1. C.R.S. 1963: § 137-1-13. L. 70: p. 381, § 13. L.
77: Entire section amended, p. 1733, § 6, effective June 20. L. 81:
Entire section amended, p. 1837, § 1, effective January 1, 1982. L. 87:
Entire section amended, p. 1397, § 1, effective May 6. L. 88: (1) to (3)
amended, pp. 1290, 1294, §§ 23, 27, effective May 23. L. 90: (2) and (3)
amended, p. 1703, § 38, effective June 9. L. 91: (1) and (4) amended and
(5) and (6) added, p. 1962, § 2, effective June 5. L. 92: (1), (2), (5),
and (6) amended and (1.5) and (1.7) added, p. 2205, § 1, effective June 3. L.
93: (1) amended, p. 1744, § 3, effective July 1. L. 96: (3) amended,
p. 649, § 1, effective May 1. L. 2003: (1) amended, p. 1347, § 1,
effective August 6. L. 2008: (2) and (3) amended, p. 1246, § 5,
effective August 5. L. 2010: (1.5), (2), and (3) amended, (HB 10-1117),
ch. 195, p. 841, § 1, effective August 11. L. 2016: (5) amended, (SB
16-172), ch. 280, p. 1148, § 1, effective June 10. L. 2026: (1.5), (2),
and (3) amended, (SB 26-046), ch. 10, p. 40, § 3, effective January 1, 2027.
Cross
references: For
approval of tax abatements or refunds by the property tax administrator, see §
39-2-116; for further restrictions relating to the abatement, refund, and
cancellation of taxes, see § 39-10-114.
ANNOTATION
Where this section and §
39-10-114 protect taxpayer's due process rights. Where taxpayer complained
that county assessor had failed to give the required timely notice of an
increased assessment, thus depriving him of his statutory right to litigate
validity of the assessment before paying tax, no federally guaranteed rights were
abridged because the abatement and refund procedures of this section and §
39-10-114 allowed plain, adequate, and complete remedy, thus fully protecting
the taxpayer's due process rights. Lamm v. Barber, 192 Colo. 511, 565 P.2d 538
(1977).
Prior to suit, taxpayer must
exhaust administrative remedies. The remedies contained in § 39-10-114,
relating to procedures for abatement or cancellation of taxes and this section
are complete and adequate; thus, prior to commencing suit on illegal taxation
issues, taxpayers are required to exhaust the administrative remedies detailed
in these sections. Davison v. Bd. of County Comm'rs, 41 Colo. App. 344, 585
P.2d 315 (1978); S. Cafeteria, Inc. v. Prop. Tax Adm'r, 677 P.2d 362 (Colo.
App. 1983).
By approving taxpayer's
petition "conditionally" or otherwise and submitting it to the
property tax administrator for further action, the board of county
commissioners' procedural rights as a party ended under the statutory scheme
governing abatement and refund proceedings. Huerfano County Bd. of County
Comm'rs v. Atl. Richfield Co., 976 P.2d 893 (Colo. App. 1999).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
When section applies.
This section applies to the refund of taxes paid under § 39-8-109 after a
taxpayer who sought administrative relief under § 39-5-122 prevailed before the
board of assessment appeals or the district court or when property taxes cannot
be challenged under § 39-5-122. Bd. of Assessment Appeals v. Benbrook, 735 P.2d
860 (Colo. 1987).
This section and § 39-10-114
provide a remedy for the abatement or refund of taxes that cannot be challenged
under § 39-5-122. Valley Country Club v. Bd. of Assessment Appeals, 778 P.2d
285 (Colo. App. 1989), rev'd on other grounds, 792 P.2d 299 (Colo. 1990).
The abatement procedure may
be used to provide taxpayer relief from the overassessment of his property
in situations where his knowledge of excessive charges is acquired subsequent
to the usual statutory deadlines for protest. Valley Country Club v. Bd. of
Assessment Appeals, 778 P.2d 285 (Colo. App. 1989), rev'd on other grounds, 792
P.2d 299 (Colo. 1990).
Board of assessment appeals
may conduct de novo review in reviewing taxpayer's appeal from property tax
administrator. Bd. of Assessment Appeals v. Valley Country Club, 792 P.2d 299
(Colo. 1990).
Illegal or erroneous tax.
Where one owner of a converted condominium, after pursuing administrative
remedies under § 39-5-122, obtained a declaration from district court that the
imposition of an increased tax on his converted condominium was illegal,
petitioners, as owners of identical condominiums were entitled to seek relief
under the abatement and refund provisions of this section and § 39-10-114
because the tax had been declared illegal. Bd. of Assessment Appeals v.
Benbrook, 735 P.2d 860 (Colo. 1987).
There is no need to
characterize the tax paid as wholly illegal before the taxpayer may obtain
abatement and refund. Bd. of Assessment Appeals v. Benbrook, 735 P.2d 860
(Colo. 1987).
Refund statute not
applicable where property has been assessed improperly because of taxpayer's
error in reporting and where taxpayer did not make a timely objection.
Coquina Oil v. Larimer Co. Bd. of Equal., 742 P.2d 932 (Colo. App. 1987),
aff'd, 770 P.2d 1196 (Colo. 1989); Aurora Plaza v. Bd. of Assessment Appeals,
770 P.2d 1204 (Colo. 1989); Amoco Prod. v. Bd. of Assessment Appeals, 770 P.2d
1207 (Colo. 1989).
Where error is due at least
in part to the taxing authority, a taxpayer can recover a refund under the
clerical error provision of this section, after the time to protest under §
39-5-122 has passed. Coquina Oil Corp. v. Bd. of Equaliz., 770 P.2d 1196 (Colo.
1989).
Applied in Bd. of County
Comm'rs v. District Court, 199 Colo. 338, 607 P.2d 999 (1980); Laredo Hous.
Apts., Ltd. v. Bd. of County Comm'rs, 628 P.2d 135 (Colo. App. 1980); Laredo
Hous. Apts., Ltd. v. Bd. of Assessment Appeals, 675 P.2d 23 (Colo. App. 1983).
39-1-114. Who may administer oath.
Whenever
any fact, matter, or thing is required by the provisions of articles 1 to 13 of
this title to be verified by oath or affirmation, any assessor, treasurer, or
county clerk and recorder, or a deputy of any of said officers may administer
such oath or affirmation. The deputy need not certify the oath in the name of
the principal.
Source:
L. 64: R&RE,
p. 679, § 1. C.R.S. 1963: § 137-1-14.
39-1-115. Records prima facie
evidence.
The
assessment rolls, the tax warrants, the entries made in the books of the
treasurer, and the lists of lands sold for taxes recorded by the treasurer or
the county clerk and recorder, or a certified copy thereof, shall be prima
facie evidence of all things appearing therein in all courts and places.
Source:
L. 64: R&RE,
p. 679, § 1. C.R.S. 1963: § 137-1-15.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Records conclusive unless
refuted. Where personalty, shown to have existed during the years in
question, but nevertheless omitted from the assessment rolls for those years,
is discovered and assessed, the owner who contends that the property was
properly omitted from the assessment rolls has the burden of proving his
contention, failing in which, the record evidence showing assessment must be
taken as conclusive. McGuire v. Schwartz, 101 Colo. 310, 73 P.2d 389 (1937).
Limitation on presumption
created by section. Where personalty discovered in decedent's possession at
the time of her death had not been reported in the personal property returns of
decedent in the year of her death or the preceding years, the presumption
created by this section will not support a presumption, advanced by the manager
of revenue, in a suit for personal property taxes, that decedent made false
returns concerning personalty which she, in fact, owned, nor does it shift the
burden of proof to the defendant executor of decedent's estate. Brodhead v.
Robinson, 127 Colo. 116, 254 P.2d 857 (1953).
This section does not apply
to copies of tax schedules. Bankers Trust Co. v. Int'l Trust Co., 108 Colo.
15, 113 P.2d 656 (1941).
39-1-116. Penalty for divulging
confidential information.
Except
when pursuant to an order of any court of competent jurisdiction or as
otherwise provided by law, any person who divulges or makes known in any way
the contents of any private document, as specified in section 39-4-103,
39-5-120, or 39-7-101 (4), to any person not authorized to have access to such
documents commits a petty offense.
Source:
L. 64: R&RE,
p. 680, § 1. C.R.S. 1963: § 137-1-16. L. 96: Entire section
amended, p. 110, § 2, effective January 1, 1997. L. 2021: Entire section
amended, (SB 21-271), ch. 462, p. 3294, § 688, effective March 1, 2022.
Cross
references: For
confidential records submitted by a public utility, see § 39-4-103; for
confidential personal property schedules, see § 39-5-120.
39-1-117. Prior actions not affected.
Nothing in
articles 1 to 13 of this title shall apply to or in any manner affect any valuation,
assessment, allocation, levy, tax certificate, tax warrant, tax sale, tax deed,
right, claim, demand, lien, indictment, information, warrant, prosecution,
defense, trial, cause of action, motion, appeal, judgment, sentence, or other
authorized act, done or to be done, or proceeding arising under or pursuant to
the laws in effect immediately prior to August 1, 1964, but the same shall be
governed by and conducted pursuant to the provisions of law in effect
immediately prior to August 1, 1964.
Source:
L. 64: R&RE,
p. 748, § 2. C.R.S. 1963: § 137-1-18.
39-1-118. Repeal of law levying state
property tax - disposition of funds.
After the
repeal of any law levying a general property tax for the state or for state
purposes takes effect, delinquent taxes collected by county treasurers as a
result of the levy imposed by any such repealed law shall, when received by the
state treasurer, be credited to the capital construction fund.
Source:
L. 71: p. 1243, §
1. C.R.S. 1963: § 137-1-21.
Cross
references: For
the creation of and provisions relating to the capital construction fund, see §
24-75-302.
39-1-119. Funds held for payment of
taxes - refund - reduction and increase of amounts - penalty.
(1)
Subject to section 39-3.5-105 (2), all funds in excess of those permitted to be
held by the federal "Real Estate Settlement Procedures Act of 1974",
12 U.S.C. sec. 2601 et seq., as amended from time to time, and any rules
promulgated to implement that federal law, as amended from time to time, held
in escrow for the payment of ad valorem taxes on property under any deed of
trust, mortgage, or other agreement encumbering or pertaining to real property
located in this state shall be refunded to the property owner at the time and
in the manner required by the federal law and rules. This subsection (1)
applies whether or not the federal law and rules would apply to the deed of
trust, mortgage, or other agreement in the absence of this subsection (1).
(2)
Payments into such escrow accounts for the payment of ad valorem taxes due in
subsequent years shall be adjusted annually, based upon the amount of taxes
paid on the subject property for the preceding year, but if such person
reasonably believes that substantial improvements have been made to such
property, which improvements were not included within the previous year's
assessment, a reasonable estimate of the taxes for such subsequent years may be
used as a basis for establishing the payments for such escrow account.
(2.5)
The amount of payments into such escrow accounts for the payment of ad valorem
taxes due in subsequent years shall be increased only upon official
notification of an increase in the amount of taxes levied on such property.
Such amounts shall not be increased based solely upon notification of an
increase in the valuation for assessment of such property.
(3) Any
person willfully failing to make a refund in violation of subsection (1) of
this section for any whole month or more shall be liable for interest at a rate
of six percent per annum and an equal amount as penalty.
Source:
L. 73: p. 1435, §
1. C.R.S. 1963: § 137-1-22. L. 74: (1) amended, p. 427, § 1,
effective March 19. L. 79: (1) amended, p. 1414, § 10, effective January
1, 1980. L. 80: (1) amended, p. 797, § 62, effective June 5. L. 87:
(2.5) added, p. 1389, § 11, effective June 20. L. 93: (1) amended, p.
346 § 2, effective April 12. L. 98: (1) amended, p. 828, § 51, effective
August 5. L. 2015: (1) amended, (SB 15-142), ch. 29, p. 71, § 1,
effective March 18.
39-1-119.5. Funds collected by lessors
of personal property for payments of taxes - refund - damages.
(1) If
a personal property lessee is required to make payment to a lessor pursuant to
the terms of any contract or other agreement entered into between the lessee
and lessor for the payment of personal property tax due on or after January 1,
2007, those payments shall be accounted for upon the termination of the lease
entered into between the lessee and lessor. If it is determined upon this
accounting that a refund is due to the lessee for overpayment of personal
property taxes, the lessor shall make such refund to the lessee on or before
August 31 of the year in which the tax is due.
(2) The
lessor shall base the accounting and refund on the actual property tax
liability due in each year of the lease period.
(3) Any
lessor who willfully fails to make a refund in violation of subsection (1) of
this section shall be liable to the lessee, in a civil action, in an amount
equal to the sum of three times the amount of actual damages sustained and in
the case of any successful action to enforce said liability, the costs of the
action together with reasonable attorney fees as determined by the court.
(4) Any
action brought under this section shall be commenced within three years after
the date on which the failure to refund occurred or within three years after
the lessee discovered or in the exercise of reasonable diligence should have
discovered the lessor's failure to refund. The period of limitation provided in
this section may be extended for a period of one year if the lessee proves that
failure to timely commence the action was caused by the lessor engaging in
conduct calculated to induce the lessee to refrain from or postpone the
commencement of the action.
Source:
L. 2006: Entire
section added, p. 311, § 1, effective April 4.
39-1-120. Filing - when deemed to have
been made.
(1) (a)
Any report, schedule, claim, tax return, statement, or other document required
or authorized under articles 1 to 9 of this title to be filed with or any
payment made to the state of Colorado or any political subdivision thereof
which is transmitted through the United States mail shall be deemed filed with
and received by the public officer or agency to which it was addressed on the
date shown by the cancellation mark stamped on the envelope or other wrapper
containing the document required to be filed.
(b) Any
such document which is mailed, but not received by the public officer or agency
to which it was addressed, or is received and the cancellation mark is not
legible, or is erroneous or omitted, shall be deemed to have been filed and
received on the date it was mailed if the sender establishes by competent
evidence that the document was deposited in the United States mail on or before
the date due for filing. In such cases of nonreceipt of a document by the
public officer or agency to which it was addressed, the sender shall file a
duplicate copy thereof within thirty days after written notification is given
to the sender by such public officer of the failure to receive such document.
(2) If
any report, schedule, claim, tax return, statement, remittance, or other
document is sent by United States registered mail, certified mail, or
certificate of mailing, a record authenticated by the United States postal
service of such registration, certification, or certificate shall be considered
competent evidence that the report, schedule, claim, tax return, statement,
remittance, or other document was mailed to the public officer or agency to
which it was addressed, and the date of the registration, certification, or
certificate shall be deemed to be the postmark date.
(3) If
the date for filing any report, schedule, claim, tax return, statement,
remittance, or other document falls upon a Saturday, Sunday, or legal holiday,
it shall be deemed to have been timely filed if filed on the next business day.
Source:
L. 77: Entire
section added, p. 1404, § 2, effective July 1. L. 79: (1)(a) amended, p.
1420, § 1, effective January 1, 1980.
ANNOTATION
Under the provisions of
subsection (1)(a), abatement and refund petitions transmitted by mail are
deemed "filed" on the date of mailing for the purposes of the
filing deadline set forth in § 39-10-114 (1)(a)(I)(A). Leprino v. Huddleston,
902 P.2d 962 (Colo. App. 1995).
39-1-121. Expression of rate of
property taxation in dollars per thousand dollars of valuation for assessment -
definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Communication" means any tax statement pursuant to section
39-10-103.
(b)
"Mill" means the rate of property taxation equivalent to the amount
of dollars per one thousand dollars of valuation for assessment of taxable real
or personal property.
(c)
"Valuation for assessment" means the actual value of any real or
personal property multiplied by the assessment percentages specified in law.
(2) The
general assembly hereby finds, determines, and declares that communications to
taxpayers regarding the imposition of property taxes expressed in mills can be
unduly confusing to the general public. The general assembly further finds,
determines, and declares that, for the convenience of taxpayers and to assist
citizens in better understanding the property taxation system, it is
advantageous for governmental entities levying property taxes to inform
taxpayers of such tax rates in terms of the amount of dollars per one thousand
dollars of valuation for assessment of taxable real or personal property.
(3) In
any communication to a taxpayer, any mill levy amounts stated shall be
converted into the amount of dollars per one thousand dollars of valuation for
assessment of taxable real or personal property.
Source:
L. 88: Entire
section added, p. 1273, § 7, effective July 1. L. 92: (1)(a) amended, p.
2181, § 52, effective June 2. L. 94: (1)(a) amended, p. 1197, § 103,
effective July 1. L. 2020: (1)(c) amended, (SB 20-223), ch. 291, p.
1438, § 4, effective January 1, 2021.
Editor's
note: Section 5(2)
of chapter 291 (SB 20-223), Session Laws of Colorado 2020, provides that
changes to this section take effect on the date of the governor's proclamation
or January 1, 2021, whichever is later, only if, at the November 2020 statewide
election, a majority of voters approve the ballot issue referred in accordance
with section 2 of Senate Concurrent Resolution 20-001. The ballot issue,
referred to voters as amendment B, was approved on November 3, 2020, and was
proclaimed by the Governor on December 31, 2020. The vote count for the measure
was as follows:
FOR: 1,740,395
AGAINST: 1,285,136
39-1-122. Interim task force to study
property tax assessment - classification - land used for agricultural and other
purposes - 2010 interim - legislative declaration - repeal. (Repealed)
Source:
L. 2010: Entire
section added, (HB 10-1293), ch. 357, p. 1699, § 1, effective June 7.
Editor's
note: Subsection
(7) provided for the repeal of this section, effective July 1, 2012. (See L.
2010, p. 1699.)
39-1-123. Property tax reimbursement -
property destroyed by natural cause - repeal. (Repealed)
Source:
L. 2014: Entire
section added, (HB 14-1001), ch. 222, p. 830, § 1, effective May 17. L.
2025: (1) and (2)(a)(II) amended and (7) added, (SB 25-259), ch. 126, p.
493, § 1, effective April 25.
Editor's
note: (1) For the
amendments in SB 25-259 in effect from April 25, 2025, to July 1, 2025, see
chapter 126, Session Laws of Colorado 2025. (L. 2025, p. 493.)
(2) Subsection (7) provided for
the repeal of this section, effective July 1, 2025. (See L. 2025, p. 493.)
39-1-124. Mailing required to be sent
by county assessor or treasurer - reasonable certainty mailing will not be
delivered.
If a
county assessor or treasurer has reasonable certainty that a mailing or notice
required to be sent pursuant to this title 39 will not be delivered to a
residential real property address by the United States postal service, the
county assessor or treasurer is not required to send the mailing or notice to
that residential real property address; except that this section does not apply
to notices required to be sent pursuant to sections 39-11-128 and 39-10-111.5
(6)(b).
Source:
L. 2020: Entire
section added, (HB 20-1077), ch. 80, p. 325, § 7, effective September 14.
39-1-125. Tax and levy rate
information publicly available.
(1) (a)
When each town, city, school district, special district, or other taxing
authority certifies its levy pursuant to section 39-5-128, it shall also
provide the following information for each levy that it imposes:
(I) The
rate of the levy;
(II)
The prior year levy and revenue collected from the levy;
(III)
The maximum levy that may be levied without further voter approval;
(IV)
The allowable annual growth in revenue collected from the levy;
(V) The
actual growth in revenue collected from the levy over the prior year;
(VI)
Whether revenue from the levy is allowed to be retained and spent as a
voter-approved revenue change pursuant to section 20 (7)(b) of article X of the
state constitution;
(VII)
Whether revenue from the levy is subject to the limit on annual revenue growth
in section 29-1-301 (1)(a);
(VIII)
Whether revenue from the levy is subject to any other limit on annual revenue
growth enacted by the taxing authority or other local government;
(IX)
Whether the levy must be adjusted, or whether a mill levy credit must be
allowed, to collect a certain amount of revenue for the tax year and, if
applicable, that amount of revenue; and
(X) Any
other information determined necessary by the department of local affairs.
(b) On
or before September 1, 2024, the department of local affairs shall determine
the process by which taxing authorities will provide the information listed in
subsection (1)(a) of this section.
(c) The
board of county commissioners or other body authorized by law to levy taxes
shall provide the information listed in subsection (1)(a) of this section, in
addition to the identity of the entity that fixes each levy rate, along with
its certification of levies pursuant to section 39-1-111.
(2) (a)
Upon receiving the certification of levies from the board of county
commissioners or other body authorized by law to levy taxes, or by either
group's authorized party, in accordance with section 39-1-111, counties shall,
in coordination with the property tax administrator, ensure that the
information listed in subsection (1)(a) of this section is publicly available
and accessible to persons that own taxable real property within the taxing
authority's territorial limits.
(b)
Counties shall ensure that the information in subsection (1)(a) of this section
is publicly available beginning on January 1, 2026. From December 31, 2024,
through December 31, 2025, counties shall ensure that the information in
subsection (1)(a) of this section is available upon request.
Source:
L. 2024: Entire
section added, (HB 24-1302), ch. 340, p. 2299, § 1, effective June 3.
ARTICLE
1.5
Prepayment
of Ad Valorem Taxes
39-1.5-101. Legislative declaration.
39-1.5-102. Definitions.
39-1.5-103. Authorization of prepayment of
taxes for capital improvements to local governments - no effect on obligation
to pay taxes to other local governments.
39-1.5-104. Prepayment - amounts - credits -
limitations.
39-1.5-105. Prepaid taxes subject to laws
governing financial affairs.
39-1.5-106. Relationship between prepaid taxes
and the limitation on local government levies.
39-1.5-107. Prepayment arrangement not a
general obligation indebtedness.
39-1.5-101. Legislative declaration.
The
general assembly hereby finds and declares that energy development operations
and mineral extraction or conversion operations should be authorized to prepay
ad valorem taxes to local governments for expenditure on capital improvements
in order to meet additional public service demands created by such operations.
Source:
L. 81: Entire
article added, p. 1839, § 1, effective May 28.
39-1.5-102. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Capital improvement" means any road or highway, school facility or
equipment, domestic, commercial, or industrial water facility, sewage facility,
police and fire protection facility or equipment, hospital facility or
equipment, or any other local government administrative or judicial facility
which a local government is authorized by law to acquire or construct.
(2)
"Local government" means a county, municipality as defined in section
31-1-101, C.R.S., school district, or special district which has the authority
to impose general property taxes.
(3)
"Operation" means the development, construction, and operation of any
facility for the production of energy or the extraction, processing,
conversion, or refining of minerals, including, but not limited to, a mine,
power plant, mill, retort, or related facility, or any combination thereof
under the same ownership, if the valuation for assessment of the taxable
property of the operation within the boundaries of a local government is
estimated to exceed fifty million dollars when the operation begins functioning.
Source:
L. 81: Entire
article, p. 1839, § 1, effective May 28.
39-1.5-103. Authorization of prepayment
of taxes for capital improvements to local governments - no effect on
obligation to pay taxes to other local governments.
(1) An
owner of an operation may prepay moneys to one or more local governments,
within the boundaries of which is located taxable property of the operation,
for credit against general property taxes which will be levied in the future
pursuant to articles 1 to 13 of this title. Said moneys shall be expended on
capital improvements which are directly or indirectly related to the additional
public service demands created by the operation.
(2) If
an operation prepays moneys for credit against general property taxes pursuant
to this article to one or more local governments, said prepayment shall not
vary the operation's obligations, under law, to pay general property taxes to
any local government which does not receive such prepayments.
Source:
L. 81: Entire
article added, p. 1840, § 1, effective May 28.
39-1.5-104. Prepayment - amounts -
credits - limitations.
(1) An
owner of an operation who elects to make prepayments under this article and the
governing body of a local government shall jointly determine and agree upon:
(a) The
total amount of prepayments to be made; except that the total amount of
prepayments shall not exceed twenty-five percent of the estimate of the
operation's projected tax liability to the local government over a twenty-year
period, commencing with the taxable year in which the valuation for assessment
of the operation is estimated to exceed fifty million dollars;
(b) The
amounts and intervals of prepayments and credits for such prepayments; except
that an annual prepayment credit shall not be allowed prior to the taxable year
in which the operation begins functioning or the valuation for assessment of
the operation exceeds fifty million dollars, whichever is earlier, nor shall it
exceed twenty-five percent of the taxes due from the operation to that local
government for the then current property tax year.
(2) The
owner of an operation, the governing body of the local government, the
assessor, the treasurer, and the division of property taxation in the
department of local affairs shall estimate when the operation's projected
valuation for assessment will exceed fifty million dollars and the amount
thereof for the ensuing twenty years, as well as the operation's projected
liability for general property taxes for the applicable period.
(3) The
governing body of the local government shall adopt a resolution or ordinance
which contains the total amount of taxes to be prepaid, the anticipated amounts
and anticipated intervals of prepayments and credits for such prepayments, and
the capital improvement or improvements upon which such prepaid taxes will be
expended.
(4) The
credit allowed in any taxable year for prepayments made under this article to
or for each local government or any fund or account within the fund thereof
shall be treated as an abatement of the property taxes due to such local
government for that year from said operation and shall not affect the
determination of the valuation for assessment thereof. The credit shall be
shown on the tax statement for that year as it applies to each local
government, fund, or fund account to which applied.
Source:
L. 81: Entire
article added, p. 1840, § 1, effective May 28.
39-1.5-105. Prepaid taxes subject to
laws governing financial affairs.
Moneys
received pursuant to this article are subject to such laws relating to
financial affairs, including budget, accounting, and auditing laws, as are or
may be made applicable to the local government which receives such moneys.
Source:
L. 81: Entire
article added, p. 1841, § 1, effective May 28.
39-1.5-106. Relationship between prepaid
taxes and the limitation on local government levies.
In
determining the amount of revenue which a local government is allowed to levy
under section 29-1-301, C.R.S., prepayments made under this article shall not
be deemed property tax revenue in the year of prepayment; however, tax
liability against which a credit is to be allowed shall be deemed property tax
revenue attributable to increased valuation for new construction or bond
revenue in accordance with section 29-1-302, C.R.S., in the year in which a
credit is to be allowed.
Source:
L. 81: Entire
article added, p. 1841, § 1, effective May 28.
39-1.5-107. Prepayment arrangement not a
general obligation indebtedness.
Any
arrangement for prepayment of ad valorem taxes under this article shall not be
construed to be a general obligation indebtedness.
Source:
L. 81: Entire
article added, p. 1841, § 1, effective May 28.
ARTICLE
2
Division
of Property Taxation - Administrator - Board
39-2-101. Division created - property tax
administrator.
39-2-102. Qualifications.
39-2-103. Exercise of power.
39-2-104. Oath of office.
39-2-105. Seal.
39-2-106. Employees - compensation.
39-2-107. Office - hearings.
39-2-108. Rules and regulations.
39-2-109. Duties, powers, and authority.
39-2-109.5. Computers for property assessment -
state assistance. (Repealed)
39-2-110. Annual school for assessors.
39-2-111. Complaints.
39-2-112. Assessor to appear - when.
39-2-113. Administrator may intervene.
39-2-114. Reappraisal - when - procedures.
39-2-115. Review of abstracts of assessment -
recommendations.
39-2-116. Approval of tax abatement or
refund.
39-2-117. Applications for exemption - review
- annual reports - procedures - rules - definition.
39-2-118. Recommendations to governor.
39-2-119. Annual report.
39-2-120. Powers of property tax
administrator.
39-2-121. Enforcement of orders.
39-2-122. Notice prior to injunction.
39-2-123. Board of assessment appeals created
- members - compensation.
39-2-124. Executive director to furnish
employees and clerical assistance.
39-2-125. Duties of the board - board of
assessment appeals cash fund - creation - accelerated appeal cash fund.
39-2-126. Delaying effect of decision - when.
39-2-127. Board of assessment appeals
meetings - proceedings - representation before board.
39-2-128. Board of assessment appeals may
issue orders.
39-2-129. Advisory committee to the property
tax administrator created.
39-2-130. Membership of the advisory
committee - terms - compensation - meetings.
39-2-131. Function of the committee - notice
of proposed changes - property tax materials - definition.
39-2-101. Division created - property
tax administrator.
There is
hereby created the division of property taxation in the department of local
affairs, the head of which shall be the property tax administrator, which
office is created by section 15 of article X of the state constitution. The
administrator shall be appointed by a majority vote of the state board of
equalization and shall serve for a term of five years and until a successor is
appointed and qualified. The administrator may be removed from office for cause
by a majority vote of the state board of equalization. The position of property
tax administrator shall be exempt from the state personnel system.
Source:
L. 70: R&RE,
p. 371, § 1. C.R.S. 1963: § 137-3-1. L. 84: Entire section
amended, p. 992, § 1, effective February 17.
Cross
references: For
the creation of the department of local affairs, see § 24-1-125.
39-2-102. Qualifications.
The person
appointed as property tax administrator shall possess knowledge of the subject
of property taxation and of the laws of this state relating thereto and shall
have demonstrated ability and experience in the field of property taxation. He
shall devote his full time to the performance of his duties as administrator
and shall hold no other office under the United States, the state, or any
political subdivision thereof.
Source:
L. 70: R&RE,
p. 371, § 1. C.R.S. 1963: § 137-3-2.
ANNOTATION
Fee title owners of
subdivision parcels, rather than the homeowners association that manages the
subdivision, are subject to real property taxation due to the covenants
that permit the association to restrict property access for nonpayment of
association assessments. Hinsdale County Bd. of Eq. v. HDH P'ship, 2019 CO 22,
438 P.3d 742.
Record title owners of real
property are the true owners of the property and are therefore responsible
for property taxes. Hinsdale County Bd. of Eq. v. HDH P'ship, 2019 CO 22, 438
P.3d 742.
39-2-103. Exercise of power.
The
division of property taxation and the property tax administrator are type 1
entities, as defined in section 24-1-105, and exercise their powers and perform
their duties and functions under the department of local affairs.
Source:
L. 70: R&RE,
p. 371, § 1. C.R.S. 1963: § 137-3-3. L. 2022: Entire section
amended, (SB 22-162), ch. 469, p. 3415, § 181, effective August 10.
Cross
references: (1)
For the creation of the department of local affairs, see § 24-1-125; for the
"Administrative Organization Act of 1968", see article 1 of title 24.
(2) For the short title (the
"Debbie Haskins 'Administrative Organization Act of 1968' Modernization
Act") in SB 22-162, see section 1 of chapter 469, Session Laws of Colorado
2022.
39-2-104. Oath of office.
Before
entering upon the duties of his office, the property tax administrator shall
take and subscribe to the constitutional oath of office, which oath or affirmation
shall be filed in the office of the secretary of state.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-4.
Cross
references: For
oath of office required of civil officers, see § 8 of article XII of the state
constitution.
39-2-105. Seal.
The
division of property taxation shall have an official seal with the words
"Property Tax Division - Department of Local Affairs" and such other
appropriate design as the property tax administrator may determine engraved
thereon, by which he shall authenticate proceedings conducted by him and of
which the courts shall take judicial notice.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-5.
39-2-106. Employees - compensation.
Pursuant
to the provisions of section 13 of article XII of the state constitution, the
property tax administrator may employ a secretary and such other clerical and
professional personnel as may be required to perform his duties. Compensation
of the property tax administrator and other employees and necessary expenses of
the division of property taxation shall be paid from annual appropriations made
to the division by the general assembly. Any costs of the property tax
administrator in implementing the assessment and levy procedures required
pursuant to section 39-5-132 shall be paid by the local taxing authorities
pursuant to said section.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-6. L. 85: Entire section
amended, p. 1226, § 4, effective January 1, 1986.
39-2-107. Office - hearings.
(1) The
property tax administrator shall maintain his office in the city of Denver but
may transact official business at any other place within the state. The office
shall be open during established hours each day, Saturdays, Sundays, and legal
holidays excepted.
(2) Any
hearings conducted by the administrator or the division shall be open to the
public, and full and correct minutes thereof shall be kept, and such minutes
shall be a public record open to public inspection.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-7.
39-2-108. Rules and regulations.
The
administrator shall adopt rules and regulations governing proceedings and
hearings pursuant to the provisions of article 4 of title 24, C.R.S., which
rules and regulations shall be subject to legislative review pursuant to
section 24-4-103 (8)(d), C.R.S.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-8. L. 77: Entire section
amended, p. 1733, § 8, effective June 20.
39-2-109. Duties, powers, and
authority.
(1) It
is the duty of the property tax administrator, and the administrator shall have
and exercise authority:
(a) To
value the property and plant of all public utilities doing business in this
state in the manner prescribed by law, which value shall be equalized in
accordance with the provisions of section 39-4-102 (3), and to prepare and
furnish all forms required to be filed with him by public utilities;
(b) To
assist and cooperate in the administration of all laws concerning the valuing
of taxable property, the assessment of same, and the levying of property taxes;
(c)
Repealed.
(d) To
approve the form and size of all personal property schedules, forms, and
notices furnished or sent by assessors to owners of taxable property, the form
of petitions for abatement or refund, the form of all field books, plat and
block books, maps, and appraisal cards used in the office of the assessor and
other forms and records used and maintained by the assessor and to require
exclusive use of such approved schedules, books, maps, appraisal cards, forms,
and records by all assessors to ensure uniformity;
(e) To
prepare and publish from time to time manuals, appraisal procedures, and
instructions, after consultation with the advisory committee to the property
tax administrator and the approval of the state board of equalization,
concerning methods of appraising and valuing land, improvements, personal
property, and mobile homes, and to require their utilization by assessors in
valuing and assessing taxable property. Said manuals, appraisal procedures, and
instructions must be based upon the three approaches to appraisal and the
procedures set forth in section 39-1-103 (5)(a). Such manuals, appraisal
procedures, and instructions are subject to legislative review, the same as
rules, pursuant to section 24-4-103 (8)(d).
(f) To
prepare and furnish to assessors all forms required to be completed by them and
filed with the property tax administrator;
(g) To
call, upon not less than ten days' prior notice, meetings of assessors at some
designated place in the state and, upon reasonable notice, to call group or
area meetings of two or more assessors;
(h) To
prepare and design a basic form for all assessors to use in the assessment of
real property which will set forth in detail information to be inserted
pertaining to the approaches to appraisal set forth in section 39-1-103 (5)(a);
(i) To
determine, whenever the administrator discovers that any taxable property of a
public utility or any taxable rail transportation property has been omitted
from the assessment roll of any year or series of years, the value of such
omitted property. The administrator shall notify the assessor of such discovery
and value. The assessor shall list the same on the assessment roll of the year
in which the discovery was made and shall notify the treasurer of any unpaid
taxes on such property for prior years.
(j)
Repealed.
(k) To
prepare and publish guidelines, after consultation with the advisory committee
to the property tax administrator and approval of the state board of
equalization, concerning the audit and compliance review of oil and gas
leasehold properties for property tax purposes, which must be utilized by
assessors, treasurers, and their agents. Such guidelines are subject to
legislative review, the same as rules, pursuant to section 24-4-103 (8)(d).
(l) To
resolve valuation disputes concerning property or property interests owned or
held by the Southern Ute Indian tribe as provided in the taxation compact set
forth in section 24-61-102, C.R.S.;
(m) To
establish the forms required pursuant to part 2 of article 29 of title 38,
C.R.S.;
(n) To
prepare and publish standardized forms, including a letter of authorization,
for all levels of property tax appeals and to develop and publish guidelines or
instructions for the use of the forms. According to the guidelines or
instructions published by the administrator, notarization of the forms is not
required so long as alternative indicia of reliability and authenticity are
available.
(2)
Repealed.
Source:
L. 70: R&RE,
p. 372, § 1. C.R.S. 1963: § 137-3-9. L. 73: p. 1437, § 1. L.
76: (1)(e) amended, p. 756, § 7, effective July 1. L. 77: (1)(h)
added, p. 1750, § 1, effective June 9; (1)(c) R&RE and (1)(e) amended, p.
1733, §§ 7, 9, effective June 20. L. 81: (1)(c) repealed, p. 1398, § 11,
effective January 1; (1)(a) amended, p. 1848, § 3, effective January 1, 1982. L.
82: (1)(e) amended, p. 555, § 1, effective January 1, 1984. L. 83:
(1)(e) R&RE, p. 1498, § 1, effective April 12; (1)(b) amended, p. 1489, §
2, effective April 21; (1)(h) amended, p. 1483, § 4, effective April 22; (1)(i)
and (1)(j) added, pp. 2082, 2083, §§ 1, 1, effective October 13. L. 90:
(1)(e) amended, p. 1699, § 26, effective June 9. L. 91: (1)(k) added, p.
1953, § 1, effective January 1, 1992. L. 96: IP(1) and (1)(d) amended,
p. 649, § 2, effective May 1; (1)(l) added, p. 1726, § 2, effective June 3. L.
99: (1)(l) amended, p. 629, § 40, effective August 4. L. 2004:
(1)(j) repealed, p. 206, § 28, effective August 4. L. 2008: (1)(m)
added, p. 452, § 10, effective July 1. L. 2022: (1)(e) and (1)(k)
amended and (2) added, (HB 22-1416), ch. 158, p. 995, § 1, effective August 10.
L. 2026: (1)(e) and (1)(k) amended, (1)(n) added, and (2) repealed, (SB
26-046), ch. 10, p. 40, § 4, effective August 12.
ANNOTATION
State property tax
administrator's assessors' reference library manuals are binding on county
assessors. Huddleston v. Grand County Bd. of Equaliz., 913 P.2d 15 (Colo.
1996).
39-2-109.5. Computers for property
assessment - state assistance. (Repealed)
Source:
L. 83: Entire
section added, p. 2083, § 2, effective October 13. L. 2004: Entire
section repealed, p. 206, § 29, effective August 4.
39-2-110. Annual school for assessors.
To further
improvement in appraisal and valuation procedures and methods and understanding
and knowledge thereof, the division of property taxation shall conduct annual
instruction and discussion sessions in the nature of a school for assessors,
their employees, and employees of the division for periods not exceeding
fifteen days in length. All costs of conducting such sessions shall be paid by
the division, and the necessary travel and subsistence expenses of assessors
and their employees while attending such sessions shall be paid by their
respective counties. All assessors shall attend this annual school. Each
assessor completing this school shall receive a certificate of achievement for
his effort.
Source:
L. 70: R&RE,
p. 373, § 1. C.R.S. 1963: § 137-3-10. L. 75: Entire section
amended, p. 1457, § 1, effective June 20.
Cross
references: For
the definition of "assessor", see § 39-1-102 (2).
39-2-111. Complaints.
The
administrator shall examine all complaints filed with him wherein it is alleged
that a class or subclass of taxable property in a county has not been appraised
or valued as required by law or has been improperly or erroneously valued or
that the property tax laws have in any manner been evaded or violated.
Complaints shall be in writing and may be filed only by a taxing authority in a
county or by any taxpayer. Complaints may be filed only with respect to
property located in the county in which the taxing authority levies taxes or in
which the taxpayer owns taxable property. If the administrator finds the
complaint is justified, he may use his findings as the basis for petitioning
the state board of equalization for an order of reappraisal pursuant to section
39-2-114.
Source:
L. 70: R&RE,
p. 373, § 1. C.R.S. 1963: § 137-3-11. L. 76: Entire section
amended, p. 757, § 9, effective January 1, 1977. L. 83: Entire section
amended, p. 1490, § 3, effective April 21.
39-2-112. Assessor to appear - when.
The
property tax administrator may require any assessor to appear before him at any
meeting to ascertain whether he has complied with the law in appraising and
valuing the taxable property located in his county.
Source:
L. 70: R&RE,
p. 373, § 1. C.R.S. 1963: § 137-3-12.
Cross
references: For
the valuation for assessment, see § 39-1-104.
39-2-113. Administrator may intervene.
(1) The
administrator is authorized to appear as a party in interest in any proceeding
before a court or other tribunal in which:
(a) An
abatement or refund of property taxes is sought; or
(b) A
question bearing on a statewide assessment policy is raised.
Source:
L. 70: R&RE,
p. 373, § 1. C.R.S. 1963: § 137-3-13. L. 76: Entire section
R&RE, p. 757, § 10, effective January 1, 1977.
Cross
references: For
abatement and refund of taxes, see §§ 39-1-113 and 39-10-114.
39-2-114. Reappraisal - when -
procedures.
(1)
Whenever the administrator petitions the state board of equalization for its
order of reappraisal of any class or subclass of taxable property for the
following taxable year, the administrator shall send a copy of such petition to
the assessor of the county in which such class or subclass of taxable property
is located. The petition of reappraisal shall include the reasons for such
reappraisal, and the administrator has the duty to establish to the
satisfaction of the state board of equalization the need for such reappraisal.
The state board of equalization shall conduct a hearing on such petition, at
which hearing the assessors shall attend and shall give such testimony and
present such evidence as the state board of equalization may require.
(2) At
the hearing on the petition for reappraisal, the affected county assessor shall
have the opportunity to appear, to produce testimony and evidence, and to
cross-examine witnesses. The decision of the state board of equalization shall
be delivered in writing no later than the close of business on November 15.
(3) If
such reappraisal is ordered by the state board of equalization, the property
tax administrator shall direct the staff of the division of property taxation,
working jointly with the assessor of such county, to reappraise such property,
and the value so determined shall be the actual value of the taxable property
in such county for the next taxable year. The results of the reappraisal shall
be filed with the property tax administrator no later than the close of
business on the last working day in May of the year in which the reappraised
values shall be effective, and a copy thereof shall be filed with the assessor.
(4) The
affected assessor, board of county commissioners, town, city, school district,
or special district, or any taxpayer resident therein, or any of them, may
appeal the reappraised value to the state board of equalization by petition
filed with the state board of equalization no later than the tenth day of June
next following. Upon appeal, the assessor and any other petitioner shall have
the right to appear, produce testimony and evidence, and cross-examine
witnesses.
(5) The
state board of equalization may affirm, rescind, or modify the reappraised
values appealed, and shall enter its written order thereof no later than the
first day of July next following.
Source:
L. 70: R&RE,
p. 373, § 1. C.R.S. 1963: § 137-3-14. L. 77: (1) R&RE, p.
1734, § 10, effective June 20. L. 81: (1) amended, p. 1398, § 10,
effective January 1. L. 83: Entire section amended, p. 1490, § 4,
effective April 21. L. 86: (2) amended, p. 1101, § 2, effective March
26. L. 89: (2) amended, p. 1452, § 6, effective June 7.
Cross
references: For
the duties of the board of assessment appeals, see § 39-2-125; for the
determination of actual value, see § 39-1-103.
ANNOTATION
Right to appeal reappraisal
limited. This section does not grant an affected assessor or a board of
county commissioners the right to appeal the reappraisal of property within his
or its county to the courts. Bd. of County Comm'rs v. Love, 172 Colo. 121, 470
P. 2d 861 (1970) (decided under former law).
39-2-115. Review of abstracts of
assessment - recommendations.
(1) (a)
No later than August 25 of each year, each county assessor shall file with the
property tax administrator one copy of an abstract of assessment of the county
in an electronic or paper format.
(a.5) and
(b) Repealed.
(2)
Upon receipt of the abstracts of assessment from the assessors of the several
counties of the state, the administrator shall examine and review each such
abstract. If he finds from the abstract of any county that any or all of the
various classes or subclasses of real and personal property located in such
county have not been valued for assessment by the use of all manuals, factors,
formulas, and other directives required by law, the administrator shall
determine the amount of increase or decrease in valuation for assessment of
such class or subclass necessary to conform to such requirements and shall file
a complaint with the state board of equalization specifying the amount
recommended to be added to or deducted from the valuation for assessment of
such class or subclass of property in such county for the following taxable
year.
(3) No
later than October 15 of each year, the property tax administrator shall
transmit the abstracts of assessment of the several counties to the state board
of equalization together with his recommendations.
Source:
L. 70: R&RE,
p. 374, § 1. C.R.S. 1963: § 137-3-15. L. 77: (2) R&RE, p.
1734, § 11, effective June 20. L. 83: (2) and (3) amended, p. 1491, § 5,
effective April 21. L. 86: (3) amended, p. 1102, § 3, effective March
26. L. 89: (1) and (3) amended, p. 1453, § 7, effective June 7. L.
93: (1) amended, p. 1283, § 4, effective June 6. L. 94: (1)(b)
amended, p. 1645, § 79, effective July 1. L. 96: (1)(b) repealed, p.
1199, § 3, effective June 1. L. 2024, 2nd Ex. Sess.: (1)(a.5) added, (HB
24B-1001), ch. 1, p. 20, § 14, effective October 1 (see editor's note). L.
2026: (1)(a) amended, (SB 26-046), ch. 10, p. 42, § 5, effective August 12.
Editor's
note: (1) Section
19 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, provides that the act changing this section takes effect
only if SB 24-233 takes effect and takes effect upon the effective date of SB
24-233. SB 24-233 took effect on October 1, 2024, due to an amendment to the
effective date of SB 24-233 by section 18 of chapter 1 (HB 24B-1001), Session
Laws of Colorado 2024, Second Extraordinary Session.
(2) Subsection (1)(a.5)(II)
provided for the repeal of subsection (1)(a.5), effective July 1, 2026. (See L.
2024, 2nd Ex. Sess., p. 20.)
ANNOTATION
Failure to provide hearing
and review not deprivation of property. The failure to provide a hearing
and a review of recommendations for increases or decreases in valuations for
assessment of real or personal property does not constitute a deprivation of
property without due process of law. People ex rel. State Bd. of Equalization
v. Hively, 139 Colo. 49, 336 P.2d 721 (1959) (decided under former law).
39-2-116. Approval of tax abatement or
refund.
The
administrator shall review each application submitted by the board of county
commissioners or the board of equalization of any county for abatement or
refund of taxes, and, if all of such application is found to be in proper form
and recommended in conformity with the law, the application shall be approved;
otherwise, it shall be disapproved, in which case the disapproval may be
appealed to the board pursuant to section 39-2-125 (1)(b). If only a portion of
such application is found to be in proper form and recommended in conformity
with the law, the administrator shall approve such part and disapprove the
remainder of the application, in which case the disapproved portion may be
appealed to the board pursuant to section 39-2-125 (1)(b).
Source:
L. 70: R&RE,
p. 374, § 1. C.R.S. 1963: § 137-3-16. L. 77: p. 1734, § 12. L.
81: p. 1842, § 1.
Cross
references: For
abatement and refund of taxes, see § 39-1-113; for abatement or cancellation of
taxes, see § 39-10-114.
ANNOTATION
Board of assessment appeals
may conduct de novo review in reviewing taxpayer's appeal from property tax
administrator. Bd. of Assessment Appeals v. Valley Country Club, 792 P.2d 299
(Colo. 1990).
By approving taxpayer's
petition "conditionally" or otherwise and submitting it to the
property tax administrator for further action, the board of county
commissioners' procedural rights as a party ended under the statutory scheme
governing abatement and refund proceedings. Huerfano County Bd. of County
Comm'rs v. Atlantic Richfield Co., 976 P.2d 893 (Colo. App. 1999).
39-2-117. Applications for exemption -
review - annual reports - procedures - rules - definition.
(1) (a)
(I) Every application filed on or after January 1, 1990, claiming initial
exemption of real and personal property from general taxation pursuant to the
provisions of sections 39-3-106 to 39-3-113.5, 39-3-116, and 39-3-127.7 must be
made on forms prescribed and furnished by the administrator, must contain such
information as specified in subsection (1)(b) of this section, and must be
signed by the owner of such property or the owner's authorized agent under the
penalty of perjury in the second degree and, except as otherwise provided in
this subsection (1)(a), must be accompanied by a payment of two hundred
dollars, adjusted for inflation or deflation, which must be credited to the
property tax exemption fund created in subsection (8) of this section. The
administrator shall examine and review each application submitted, and, if it
is determined that the exemption therein claimed is justified and in accordance
with the intent of the law, the exemption must be granted, the same to be
effective upon such date in the year of application as the administrator shall
determine, but the exemption shall not apply to any year prior to the year
preceding the year in which application is made. The decision of the
administrator must be issued in writing and a copy thereof furnished to the
applicant and to the assessor, treasurer, and board of county commissioners of
the county in which the property is located.
(II) On
all properties for which an application is pending in the office of the
administrator, taxes shall not be due and payable until such determination has
been made. Such property shall not be listed for the tax sale, and no
delinquent interest will be charged on any portion of the exemption that is
denied.
(III)
No later than June 1 of each year, the administrator shall provide to the
assessor, treasurer, and board of county commissioners of each county a list of
all applications for property tax exemption currently pending in the office of
the administrator.
(b) (I)
Any users of real and personal property for which exemption from general
taxation is requested pursuant to any of the provisions of sections 39-3-107 to
39-3-113.5 and 39-3-127.7 may be required to provide such information as the
property tax administrator determines to be necessary. If a claim is made for
an exemption under section 39-3-110, and the child care center is operated by a
person other than the owner of the property, then the other person, or the
other person's authorized agent, must:
(A)
Also sign the owner's application form required by subsection (1)(a)(I) of this
section, or any other form prescribed and furnished by the administrator, under
the penalty of perjury in the second degree; and
(B)
Provide the administrator with any requested information related to the
exemption.
(II)
Except as otherwise provided in this subsection (1)(b)(II), any application
filed pursuant to subsection (1)(a) of this section claiming exemption from
taxation pursuant to section 39-3-106 or 39-3-106.5 must contain the following
information: The legal description and address of the real property or the
address of the personal property being claimed as exempt; the name and address
of the owner of such property; the name and telephone number of the agent of
such property; the date the owner acquired such property; the date the owner
commenced using the property for religious purposes; a complete list of all
uses of the property other than by the owner thereof during the previous twelve
months; the total amount of gross income specified in section 39-3-106.5
(1)(b)(I) and the total amount of gross rental income resulting to the owner of
such property during the previous twelve months from uses for purposes other
than the purposes specified in sections 39-3-106 to 39-3-113.5 and 39-3-127.7;
and the total number of hours during the previous twelve months that such
property was used for purposes other than the purposes specified in sections
39-3-106 to 39-3-113.5 and 39-3-127.7. For purposes of this subsection
(1)(b)(II), if the owner did not own the property being claimed as exempt
during the entire twelve-month period prior to filing such application, the
application must contain the required information for that portion of the
twelve-month period for which such property was owned by the owner making application.
Such application must also include a declaration that sets forth the religious
mission and religious purposes of the owner of the property being claimed as
exempt and the uses of such property that are in the furtherance of such
mission and purposes. Such declaration must be presumptive as to the religious
purposes for which such property is used. If the administrator is unable to
determine whether the property qualifies for exemption based solely on the
information specified in this subsection (1)(b)(II), the administrator may
require additional information, but only to the extent that the additional
information is necessary to determine the exemption status of the property. The
administrator may challenge any declaration included in the application only
upon the grounds that the religious mission and purposes are not religious
beliefs sincerely held by the owner of such property, that the property being
claimed as exempt is not actually used for the purposes set forth in such
application, or that the property being claimed as exempt is used for private
gain or corporate profit.
(III)
Any application filed pursuant to paragraph (a) of this subsection (1) claiming
exemption from taxation pursuant to section 39-3-116 shall contain such
information specified in subparagraphs (I) and (II) of this paragraph (b) as is
applicable for the purposes for which such property is used.
(2) No
assessor shall classify any real or personal property as being exempt from
taxation pursuant to the provisions of sections 39-3-106 to 39-3-113.5,
39-3-116, or 39-3-127.7 in any year unless the application for exemption for
the current year has been reviewed and has been granted as provided for by law,
nor shall any assessor classify any real or personal property as being taxable
after having been notified in writing that such property has been determined to
be exempt from taxation by the property tax administrator.
(3) (a)
(I) On and after January 1, 1990, and no later than April 15 of each year,
every owner of real or personal property for which exemption from general
taxation has previously been granted shall file a report with the administrator
upon forms furnished by the division, containing such information relative to
the exempt property as specified in subsection (3)(b) of this section, and
signed under the penalty of perjury in the second degree. Each such annual
report must be accompanied by a payment of one hundred ten dollars, adjusted
for inflation or deflation, which must be credited to the property tax
exemption fund created in subsection (8) of this section. Each such annual
report filed later than April 15, but prior to July 1, must be accompanied by a
late filing fee of three hundred dollars, adjusted for inflation or deflation;
except that the administrator has the authority to waive all or a portion of
the late filing fee for good cause shown as determined by the administrator by
rules adopted pursuant to subsection (7) of this section. On and after January
1, 1990, every owner of real or personal property for which exemption from
general taxation has previously been granted pursuant to the provisions of
section 39-3-111 and that is used for any purpose other than the purposes
specified in sections 39-3-106 to 39-3-113.5 and 39-3-127.7 for less than two
hundred eight hours during the calendar year or if the use of the property for
such purposes results in annual gross rental income to such owner of less than
twenty-five thousand dollars must not be required to file any annual report
pursuant to the provisions of this subsection (3). In order to claim such
exemption, in lieu of such annual report, the owner shall annually file with
the administrator a declaration stating that the property is used for such
purposes for less than two hundred eight hours during the calendar year or that
such use results in annual gross rental income to the owner of less than
twenty-five thousand dollars.
(II) In
the event an annual report is not received by June 1 from an owner of real or
personal property for which an exemption was granted for the previous year
pursuant to the provisions of sections 39-3-107 to 39-3-113.5, 39-3-116, or
39-3-127.7, the administrator shall give notice in writing to such property
owner by June 15 that failure to comply by July 1 operates as a forfeiture of
any right to claim exemption of previously exempt property from general
taxation for the current year. Failure to timely file such annual report on or
before July 1 operates as a forfeiture of any right to claim exemption of such
property from general taxation for the year in which such failure occurs,
unless an application is timely filed and an exemption granted pursuant to the
provisions of subsection (1)(a) of this section. The administrator shall review
each report filed to determine if such property continues to qualify for
exemption, and, if it is determined that the property does not so qualify, the
owner of such property must be notified in writing of the disqualification, and
the assessor, treasurer, and board of county commissioners of the county in
which the property is located must also be so notified.
(III)
If an annual report is not received by June 1 from an owner of real or personal
property for which an exemption was granted for the previous year pursuant to
the provisions of section 39-3-106 or 39-3-106.5, the administrator shall give
notice in writing to such property owner by June 15 that failure to file a
delinquent report during a twelve-month period commencing the following July 1
shall operate as the forfeiture of any right to claim exemption of previously
exempt property from general taxation for the year in which such notice is
given. Upon the filing of the delinquent annual report, a late filing fee of
three hundred dollars, adjusted for inflation or deflation, shall be paid,
which must be credited to the property tax exemption fund created in subsection
(8) of this section; except that the administrator has the authority to waive
all or a portion of the late filing fee for good cause shown as determined by
the administrator by rules adopted pursuant to subsection (7) of this section. Failure
to file the delinquent annual report within the twelve-month period shall
result in the forfeiture of any right to claim exemption of such property from
general taxation for the year in which such failure to file the annual report
first occurred. The administrator shall review each report filed to determine
if the property continues to qualify for exemption, and, if it is determined
that the property does not so qualify, the owner of the property shall be
notified in writing of the disqualification, and the assessor, treasurer, and
board of county commissioners of the county in which the property is located
shall also be so notified.
(b) (I)
Any user of property which has been exempted pursuant to the provisions of
sections 39-3-107 to 39-3-113.5 and 39-3-127.7 may be required to provide such
information as the property tax administrator determines to be necessary in
order to ascertain whether the users and usages of the property are in
compliance with the provisions of said sections.
(II)
(A) Except as otherwise provided in subsection (3)(b)(II)(B) of this
section, any annual report filed pursuant to subsection (3)(a) of this section
claiming exemption from taxation pursuant to section 39-3-106 or 39-3-106.5
must contain the following information: The legal description or address of the
property being claimed as exempt; the name and address of the owner of such
property; a complete list of all uses of such property other than by the owner
thereof during the previous calendar year; the amount of total gross income
specified in section 39-3-106.5 (1)(b)(I) and the total amount of gross rental
income resulting from uses of such property that are not for the purposes set
forth in sections 39-3-106 to 39-3-113.5 and 39-3-127.7; and the total number
of hours that such property was used for purposes other than the purposes
specified in sections 39-3-106 to 39-3-113.5 and 39-3-127.7. Such annual report
must also include a declaration of the religious mission and purposes of the
owner of such property claimed as being exempt and the uses of such property
that are in the furtherance of such mission and purposes. Such declaration is
presumptive as to the religious mission and religious purposes of the owner of
such property. If the administrator is unable to determine whether the property
continues to qualify for exemption based solely on the information specified in
this subsection (3)(b)(II), the administrator may require additional
information, but only to the extent that the additional information is
necessary to determine the exemption status of the property. The administrator
may challenge any declaration included in such annual report only upon the
grounds that the religious mission and purposes are not religious beliefs
sincerely held by the owner of such property, that such property is not
actually used for the purposes set forth in the annual report, or that the
property being claimed as exempt is used for private gain or corporate profit.
(B) For
the purposes of sub-subparagraph (A) of this subparagraph (II), if the owner of
property being claimed as exempt did not own such property during the entire
previous calendar year, the annual report filed by such owner shall contain the
information required in sub-subparagraph (A) of this subparagraph (II) for that
portion of the previous calendar year during which such property was owned by
such owner.
(III)
Any annual report filed pursuant to paragraph (a) of this subsection (3)
claiming exemption from taxation pursuant to section 39-3-116 shall contain
such information specified in subparagraphs (I) and (II) of this paragraph (b)
as is applicable for the purposes for which such property is used.
(4) If,
subsequent to the time that exemption of any property was initially granted or
annually renewed, as provided in subsections (1) and (3) of this section, it is
determined that such exemption was granted or renewed as the result of false or
misleading information contained in the initial application, the annual report,
or any false information provided by owners or users of such property, then the
property tax administrator shall revoke the exemption, and taxes shall be
assessed against such property for the year or years affected by such false or
misleading information, and all delinquent interest provided by law shall apply
to such taxes.
(5) (a)
(I) If the administrator tentatively determines that the property does not
so qualify, except for the disqualification for failure to file an annual
report required in subsection (3) of this section, he shall notify, by
certified mail, the owner of such property of his tentative determination. The
administrator shall also notify the owner of the owner's right to a public
hearing, as provided for in subparagraph (II) of this paragraph (a).
(II)
Within thirty days after the issuance of a tentative determination, the owner
may request a public hearing regarding the determination. Upon the making of
such a request, the administrator or his designees shall provide said owner
with a public hearing at which said owner and any users of the property other
than the owner, if their use is relevant to the determination of whether the
property is exempt, shall be heard if they so desire. Such hearing shall be
held no later than ninety days following the issuance of the tentative
determination.
(III)
Upon the conclusion of such hearing, the administrator shall provide the owner
and any users sixty days within which to comply, so as to retain the exemption.
If the owner fails to comply within sixty days, the administrator shall notify
the owner in writing that the property has been disqualified.
(IV)
The owner may waive his right to a public hearing by filing with the
administrator a written statement that said right is waived. Upon receipt of
such waiver, the administrator shall issue a final determination, in writing,
which notifies the owner that the property does not qualify for exemption.
(V) If
the owner does not request a public hearing, as provided for in subparagraph
(II) of this paragraph (a), or does not file a waiver of his right to a public
hearing, as provided for in subparagraph (IV) of this paragraph (a), the
administrator shall provide the owner sixty days from the issuance of the
tentative determination to file any additional information relevant to the
determination of whether the property is exempt. At the conclusion of such
sixty-day period, the administrator shall issue a final determination, in
writing, which notifies the owner whether the property qualifies for exemption.
(b) An
appeal from any decision of the administrator may be taken by the board of
county commissioners of the county wherein such property is located, or by any
owner of taxable property in such county, or by the owner of the property for
which exemption is claimed if exemption has been denied or revoked in full or
in part. Any such appeal shall be taken to the board of assessment appeals
pursuant to the provisions of section 39-2-125 no later than thirty days
following the decision of the administrator.
(6) If
the decision of the board is against the petitioner, the petitioner may
petition the court of appeals for judicial review thereof according to the
Colorado appellate rules and the provisions of section 24-4-106 (11), C.R.S. If
the decision of the board is against the respondent, the respondent, upon the
recommendation of the board that it is a matter of statewide concern, may
petition the court of appeals for judicial review according to the Colorado
appellate rules and the provisions of section 24-4-106 (11), C.R.S.
(7) The
administrator shall adopt rules to implement the provisions of this section
pursuant to the provisions of article 4 of title 24, C.R.S., including any
rules necessary to specify what shall qualify as "good cause shown"
for purposes of waiving all or a portion of the late filing fees specified in
subparagraphs (I) and (III) of paragraph (a) of subsection (3) of this section.
(8) All
fees collected pursuant to this section shall be transmitted to the state
treasurer who shall credit such revenues to the property tax exemption fund,
which fund is hereby created in the state treasury. The moneys in the fund
shall be subject to annual appropriation by the general assembly for the direct
and indirect costs of the administration of this article.
(9) (a)
As used in this section, "inflation or deflation" means the annual
percentage change in the United States department of labor's bureau of labor
statistics consumer price index, or a successor index, for
Denver-Aurora-Lakewood for all items paid by urban consumers.
(b) The
administrator shall annually adjust for inflation or deflation the fees
required by subsections (1)(a)(I), (3)(a)(I), and (3)(a)(III) of this section.
The administrator shall round the adjusted amount upward or downward to the
nearest five dollars.
Source:
L. 70: R&RE,
p. 374, § 1. C.R.S. 1963: § 137-3-17. L. 72: p. 568, § 49. L.
83: (6) added, p. 2086, § 1, effective October 13. L. 86: (1) to (4)
amended, p. 1104, § 2, effective May 16. L. 87: (1)(a), (3)(a), and (5)
amended, pp. 1399, 1400, §§ 1, 2, effective July 1. L. 88: (1)(a) and
(3)(a) amended, p. 1292, § 25, effective May 23. L. 89: (1), (2), and
(3)(b) amended, p. 1482, § 6, effective April 23; (1) to (3) amended and (7)
added, p. 1486, § 4, effective June 7. L. 90: (6) amended, p. 1689, § 6,
effective June 9. L. 91: (1)(b)(II), (3)(b)(II), and (5)(a) amended, pp.
1960, 1955, §§ 7, 1, effective June 7. L. 92: (1)(a) and (4) amended, p.
2222, § 2, effective April 9. L. 2003: (1)(b)(II) and (3)(b)(II)(A)
amended, p. 866, § 1, effective April 7; (1)(a), (3)(a)(I), (3)(a)(III), and
(5)(b) amended and (8) added, p. 1465, § 3, effective July 1. L. 2009:
(1)(a) amended, (SB 09-042), ch. 176, p. 780, § 2, effective August 5. L.
2010: (1)(a)(I), (3)(a)(I), (3)(a)(III), and (7) amended, (HB 10-1386), ch.
328, p. 1516, § 1, effective July 1. L. 2011: (3)(a)(I) amended, (HB
11-1010), ch. 275, p. 1239, § 1, effective August 10. L. 2013:
(1)(a)(I), (1)(b)(I), (1)(b)(II), (2), (3)(a)(I), (3)(a)(II), (3)(b)(I), and
(3)(b)(II)(A) amended, (HB 13-1300), ch. 316, p. 1700, § 117, effective August
7. L. 2022: (1)(b)(I) amended, (HB 22-1006), ch. 289, p. 2066, § 3,
effective August 10. L. 2023: (1)(a)(I), IP(1)(b)(I), (1)(b)(II), (2),
(3)(a)(I), (3)(a)(II), (3)(b)(I), and (3)(b)(II)(A) amended, (HB 23-1184), ch.
260, p. 1499, § 1, effective August 7. L. 2024: (1)(a)(I), (3)(a)(I),
and (3)(a)(III) amended and (9) added, (HB 24-1411), ch. 82, p. 276, § 1,
effective July 1.
Cross
references: (1)
For perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
(2) For the legislative
declaration in HB 22-1006, see section 1 of chapter 289, Session Laws of
Colorado 2022.
ANNOTATION
Law reviews. For
article, "Property Tax Exemptions for Religious And Nonprofit
Organizations", see 18 Colo. Law. 1939 (1989). For article, "Colorado
State and Local Tax Exemptions for Charitable Organizations-Part I", see
28 Colo. Law. 57 (Nov. 1999). For article, "Affordable Housing Tax
Exemptions in Colorado", see 54 Colo. Law. 32 (Dec. 2025).
Exemption from property tax
is initiated at state level, rather than county level, by filing an
application for exemption with the property tax administrator. West-Brandt
Found., Inc. v. Carper, 199 Colo. 334, 608 P.2d 339 (1980).
Property tax exemptions are
determined on an annual basis under the property tax scheme, based on the
use of the property in each tax year. St. Mark Coptic Orthodox Church v. State
Bd. of Assessment Appeals, 762 P.2d 775 (Colo. App. 1988); Pilgrim Rest Baptist
Church, Inc. v. Prop. Tax Adm'r, 971 P.2d 270 (Colo. App. 1998).
Implicit within the property
tax scheme is a requirement that in order for the property to qualify for tax
exemption for that tax year, there must be at least some actual use of the
property for tax exempt purposes in that tax year. Pilgrim Rest Baptist Church,
Inc. v. Prop. Tax Adm'r, 971 P.2d 270 (Colo. App. 1998).
County not indispensable
party in appeal of exemption denial. The county in which the affected
property is located is not an indispensable party in an appeal to the state
board of assessment appeals (board) of the property tax administrator's denial
of exemption. West-Brandt Found., Inc. v. Carper, 199 Colo. 334, 608 P.2d 339
(1980).
The procedure for
determining the running of the thirty-day period in this section prevails
over § 24-4-105 which deals generally with administrative proceedings. Colo.
Rocky Mtn. Sch., Inc. v. Shriver, 689 P.2d 651 (Colo. App. 1984).
The presumption in
subsection (1)(b)(II) that stated uses were actually in furtherance of
taxpayer's religious purposes applies throughout the application process,
including at any stage of review. Grand County Bd. of Comm'rs v. Prop. Tax
Adm'r, 2016 COA 2, 401 P.3d 561.
And the presumption applies
to the board's review of the tax administrator's decision. Grand County Bd.
of Comm'rs v. Prop. Tax Adm'r, 2016 COA 2, 401 P.3d 561.
Under subsection (6), only
the district court in the county where the property is situated has subject
matter jurisdiction over appeals of administrative decisions concerning
exemptions. The district court in which the property was situated did not
have subject matter jurisdiction over a case on appeal because Plaintiff did
not timely perfect the review proceedings in said court. Instead, the complaint
for review was filed in another district court which did not have subject
matter jurisdiction and which attempted to transfer the case to the proper
district court. Mile High United Way v. Assessment App., 801 P.2d 3 (Colo. App.
1990) (decided under law in effect prior to 1990 amendments).
Legislative grant of
authority is granted to the administrator under the plain language of
subsection (6) to seek review of adverse board decision concerning property tax
years beginning on and after January 1, 1984. Maurer v. Young Life, 779 P.2d
1317 (Colo. 1989); Maurer v. Loyal Order of Moose Lodge, 779 P.2d 1345 (Colo.
1989); Maurer v. Denver Urban Economic Dev., 781 P.2d 111 (Colo. App. 1989).
Court of appeals has
jurisdiction to hear a property owner's appeal from the board's determination.
Giving consistent, harmonious, and sensible effect to the entire statutory
scheme, subsection (6) must be applied to grant an applicant for tax exemption
who receives a favorable ruling from the tax administrator and, therefore, does
not petition for board review, the right to seek judicial review of an adverse
decision of the board. Larimer County Bd. v. Prop. Tax Adm'r, 2013 COA 49M, 316
P.3d 60.
In finding that property
owner is not entitled to a religious purposes exemption, except for chapels and
religious activity center on its property, board did not apply proper legal
standards and therefore erred as a matter of law. In its analysis, the
board did not address property owner's declaration of religious purposes
contained in its application, the effect of the declaration's presumed
validity, or whether the presumption had been overcome. Because such
declarations are presumptive with regard to the religious purposes for which
property is used under subsection (1)(b)(II), the board erred as a matter of
law. Larimer County Bd. v. Prop. Tax Adm'r, 2013 COA 49M, 316 P.3d 60.
The correct inquiry is set
forth in this section and § 39-3-106. The tax administrator and then the board
must review the property owner's application and evidence to determine whether
the owner's use of the property is for a religious purpose, consistent with the
owner's declaration of religious mission and purpose. Larimer County Bd. v.
Prop. Tax Adm'r, 2013 COA 49M, 316 P.3d 60.
Board also did not apply
correct legal standard and, therefore, erred as a matter of law in finding that
property owner did not qualify for a charitable use exemption. Assuming
that the board correctly applied § 39-3-106.5 to determine that the property
owner exceeded the adjusted hours or gross rental income for non-exempt use to
entitle it to fully exempt status, the board then should have considered
whether the property owner was entitled to a partial charitable use exemption.
Based on the record, the board also did not properly consider whether the
property owner used the properties solely and exclusively for strictly
charitable purposes. Accordingly, the board did not apply the proper legal
standards when it found that the property owner did not qualify for a
charitable use exemption. Larimer County Bd. v. Prop. Tax Adm'r, 2013 COA 49M,
316 P.3d 60.
39-2-118. Recommendations to governor.
No later
than the first day of December of each year, the property tax administrator, in
cooperation with a committee from the Colorado assessors association, shall
submit to the governor for transmittal to the general assembly any
recommendations concerning the administration and enforcement of the property
tax laws which he deems necessary and in the public interest.
Source:
L. 70: R&RE,
p. 375, § 1. C.R.S. 1963: § 137-3-18.
39-2-119. Annual report.
As soon
after the end of each calendar year as may be practicable, the property tax
administrator shall prepare a report covering the activities of the division of
property taxation during such calendar year. Such report shall set forth the
aggregate valuation for assessment of all taxable property in the state and in
each county thereof, by classes and subclasses, for the two latest calendar
years, the levies imposed by each political subdivision during the preceding
calendar year, and the aggregate amount of taxes produced by such levies in the
state and each county thereof, together with such other information as the
administrator deems necessary. Such report shall be published in accordance
with the provisions of section 24-1-136, C.R.S. Copies of the report shall be
furnished to the governor and made available for distribution to the public.
Source:
L. 70: R&RE,
p. 375, § 1. C.R.S. 1963: § 137-3-19. L. 83: Entire section
amended, p. 844, § 78, effective July 1. L. 2002: Entire section
amended, p. 862, § 3, effective August 7.
39-2-120. Powers of property tax
administrator.
The
property tax administrator shall be authorized to certify official acts of the
division of property taxation, to administer oaths, issue subpoenas, compel
attendance of witnesses and the production of books, accounts, and records, and
to cause depositions to be taken. In case any person fails to comply with any
subpoena or refuses to testify on any matter upon which he may be lawfully
questioned, any court having jurisdiction in the matter may, upon application
of the property tax administrator, compel obedience in the manner provided by
law.
Source:
L. 70: R&RE,
p. 376, § 1. C.R.S. 1963: § 137-3-20.
39-2-121. Enforcement of orders.
The
property tax administrator may compel compliance with his unappealed orders or,
after approval by the board of assessment appeals of appealed orders, by
proceedings in mandamus, injunction, or by other appropriate civil remedies.
Source:
L. 70: R&RE,
p. 376, § 1. C.R.S. 1963: § 137-3-21.
39-2-122. Notice prior to injunction.
No
injunction shall be issued suspending or staying any order of the property tax
administrator except upon ten days' notice to the property tax administrator of
the application for such injunction and a hearing thereon.
Source:
L. 70: R&RE,
p. 376, § 1. C.R.S. 1963: § 137-3-22.
39-2-123. Board of assessment appeals
created - members - compensation.
(1) On
and after July 1, 1971, the Colorado tax commission shall be known as the board
of assessment appeals, which agency is hereby created within the department of
local affairs. The board shall be a quasi-judicial tribunal.
(2) The
board consists of three members, who shall be appointed by the governor with
the consent of the senate. Appointments to the board shall be for terms of four
years; except that the terms shall be staggered so that no more than two
members' terms expire in the same year. In order to allow for appeals to be
heard timely, up to six additional members may be appointed to the board by the
governor with the consent of the senate. Such additional members shall be
appointed for terms of one state fiscal year each. Members of the board shall
be experienced in property valuation and taxation and shall be public
employees, as defined in section 24-10-103 (4)(a), who are not subject to the
state personnel system laws. One of such members shall be or shall have been,
within the five years immediately preceding the date of initial appointment,
actively engaged in agriculture. On and after June 1, 1993, members shall be
licensed or certificated pursuant to the provisions of part 6 of article 10 of
title 12. Service on the board shall be at the pleasure of the governor, who
may appoint a replacement to serve for the unexpired term of any member. Such
replacement shall be appointed with the consent of the senate. Any other
vacancies on the board shall be filled by appointment by the governor with the
consent of the senate for the unexpired term.
(3) In
addition to any other compensation provided for by law, members of the board
shall be compensated one hundred fifty dollars per diem. In addition, members
of the board who do not reside in the Denver metropolitan area, which consists
of the counties of Adams, Arapahoe, Boulder, Clear Creek, Denver, Douglas,
Gilpin, and Jefferson, shall be reimbursed for their actual and necessary
travel expenses as determined by the executive director of the department of
local affairs. Per diem compensation not to exceed two hundred twenty days in
any calendar year shall be paid only when the board is in session or when any
member thereof conducts a hearing pursuant to section 39-2-127. The board shall
be in session when it determines that it is necessary or as directed by the
executive director of the department of local affairs.
(4) The
board of assessment appeals is a type 1 entity, as defined in section
24-1-105, and exercises its powers and performs its duties and functions under
the department of local affairs.
Source:
L. 70: R&RE,
p. 376, § 1. C.R.S. 1963: § 137-3-23. L. 76: (3) amended, p. 757,
§ 11, January 1, 1977. L. 77: (2) amended, p. 1735, § 13, effective June
20. L. 83: (3) amended, p. 1500, § 1, effective May 26. L. 85:
(3) amended, p. 1219, § 2, effective March 23; (3) amended, p. 1228, § 1,
effective July 1. L. 87: (2) amended, p. 913, § 30, effective June 15. L.
88: (2) amended, p. 1296, § 1, effective April 29. L. 89: (2)
amended, p. 1453, § 8, effective June 7. L. 91: (2) and (3) amended, p.
1977, § 1, effective July 1. L. 92: (2) amended, p. 2206, § 2, effective
June 3. L. 2013: (2) amended, (SB 13-146), ch. 388, p. 2258, § 1,
effective July 1; (2) amended, (SB 13-155), ch. 392, p. 2283, § 15, effective
July 1. L. 2019: (2) amended, (HB 19-1172), ch. 136, p. 1728, § 250,
effective October 1. L. 2022: (2) amended, (SB 22-013), ch. 2, p. 86, §
115, effective February 25; (4) amended, (SB 22-162), ch. 469, p. 3415, § 182,
effective August 10.
Editor's
note: (1)
Amendments to subsection (3) by House Bill 85-1105 and House Bill 85-1106 were
harmonized.
(2) Amendments to subsection
(2) by Senate Bill 13-146 and Senate Bill 13-155 were harmonized.
Cross
references: (1)
For the "Administrative Organization Act of 1968", see article 1 of
title 24.
(2) For the short title (the
"Debbie Haskins 'Administrative Organization Act of 1968' Modernization
Act") in SB 22-162, see section 1 of chapter 469, Session Laws of Colorado
2022.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments", see 15 Colo. Law. 798
(1986).
Board's rules and
regulations were not abolished by legislation abolishing existing board and
immediately creating a newly constituted one, nor was board required to
re-enact, ratify, or promulgate new rules and regulations, since annual
legislation by the general assembly specifically postponing the expiration of
the board's rules effectively postponed the rules of the "old" board
and continued their application under the "new" board. 1st Am. Sav.
Bank v. Boulder County, 888 P.2d 360 (Colo. App. 1994).
Board rule requiring parties
to exchange witness lists ten days prior to hearing has a legitimate
relationship to express statutory provisions since need for the rule is
paramount where the board's procedures do not allow discovery. 1st Am. Sav.
Bank v. Boulder County, 888 P.2d 360 (Colo. App. 1994).
Board abused its discretion
in denying the right to call a witness it had inadvertently omitted from its
witness list where taxpayer's attorney had implicit knowledge of the
witness and subject matter of the witness' testimony and no prejudice was
claimed if the testimony was allowed. 1st Am. Sav. Bank v. Boulder County, 888
P.2d 360 (Colo. App. 1994).
39-2-124. Executive director to
furnish employees and clerical assistance.
Clerical
assistance and such employees as are necessary shall be furnished for the board
by the executive director of the department of local affairs.
Source:
L. 70: R&RE,
p. 377, § 1. C.R.S. 1963: § 137-3-24.
39-2-125. Duties of the board - board
of assessment appeals cash fund - creation - accelerated appeal cash fund.
(1) The
board of assessment appeals shall perform the following duties, such
performance to be in accordance with the applicable provisions of article 4 of
title 24:
(a)
Adopt procedures of practice before and procedures of review by the board;
(b) (I)
Hear appeals from orders and decisions of the property tax administrator filed
not later than thirty days after the entry of any such order or decision.
(II)
Such hearings shall include evidence as to the rationale of such order or
decision and the detailed data in support thereof.
(c)
Hear appeals from decisions of county boards of equalization filed no later
than the later of:
(I)
September 1;
(II)
December 1, in a county that uses an alternate protest and appeal procedure
pursuant to section 39-5-122.7; or
(III)
Thirty days after the entry of the decision, if the taxpayer was notified
outside of the regular notification schedule described in section 39-5-121;
(d)
Repealed.
(e)
Hear appeals from determinations by county assessors when a county board of
equalization or an assessor has failed to respond within the time provided by
statute to an appeal properly filed by a taxpayer;
(f)
Hear appeals from decisions of boards of county commissioners filed not later
than thirty days after the entry of any such decision when a claim for refund
or abatement of taxes is denied in full or in part;
(g)
Repealed.
(h)
Collect any filing fee that shall accompany a taxpayer's request for a hearing
before the board pursuant to this section. All fees collected by the board
shall be transmitted to the state treasurer, who shall credit the same to the
board of assessment appeals cash fund, which fund is hereby created in the
state treasury and referred to in this paragraph (h) as the "cash
fund". All moneys credited to the cash fund shall be used in accordance
with the requirements of this section and shall not be deposited in or
transferred to the general fund of this state or any other fund. The moneys
credited to the cash fund shall be available for appropriation by the general
assembly to the board of assessment appeals in the annual general appropriation
act. In making the annual appropriation to the board of assessment appeals
under the annual general appropriation act, the general assembly shall consider
available revenues and reserve balances in the cash fund. Any interest earned
on amounts in the cash fund shall be credited to the cash fund. Any request for
a hearing before the board pursuant to sections 39-2-117 (5)(b), 39-4-108 (8),
39-8-108 (1), and 39-10-114.5 (1) shall be accompanied by a nonrefundable
filing fee as follows:
(I) For
any person other than a taxpayer pro se, a fee of one hundred one dollars and
twenty-five cents for each tract, parcel, or lot of real property and for each
schedule of personal property included in such request; except that, if any
request for a hearing before the board involves more than one tract, parcel, or
lot owned by the same taxpayer and involves the same issue regarding the
valuation of such real property, only one filing fee shall be required for such
request for a hearing.
(II)
For any person who is a taxpayer pro se, for the first two requests for a
hearing within a fiscal year, the taxpayer shall not be required to pay a
filing fee, and for each additional request within such fiscal year, a fee of
thirty-three dollars and seventy-five cents for each tract, parcel, or lot of
real property, and for each schedule of personal property included in such
request; except that, if any request for a hearing before the board involves
more than one tract, parcel, or lot owned by the same taxpayer and involves the
same issue regarding the valuation of such real property, only one filing fee
shall be required for such request for a hearing.
(1.5)
As used in this section, notwithstanding any other law, "taxpayer pro
se" includes the trustee of a trust.
(2)
Complaints filed by the property tax administrator shall be advanced on the
calendar and shall take precedence over other matters pending before the board.
(2.5)
(a) Along with complaints described in subsection (2) of this section, a
taxpayer's appeal concerning the valuation of rent-producing commercial real
property pursuant to section 39-8-108 (1) is advanced on the calendar and takes
precedence over other matters pending before the board, if:
(I) The
taxpayer files a written letter of objection and protest under section 39-5-122
(2) or 39-5-122.7 (2) and, on or before July 15 of the same calendar year, the
taxpayer provides to the assessor the information described in section 39-8-107
(5)(a)(I);
(II)
The taxpayer requests the prioritization under this subsection (2.5) at the
time the appeal is filed with the board; and
(III)
The assessor, upon issuing the written determination regarding the objection
and protest required by section 39-5-122 (2) or 39-5-122.7 (2), verifies that
the taxpayer has met the requirements of subsections (2.5)(a)(I) and
(2.5)(a)(II) of this section.
(b) The
board of assessment appeals may charge a fee to a taxpayer whose appeal is
advanced pursuant to this subsection (2.5). The fee must be:
(I)
Based upon the board of assessment appeals' actual costs in advancing the
taxpayer's appeal; and
(II)
Deposited in the accelerated appeal cash fund, which is created in the state
treasury. The state treasurer shall credit all interest and income derived from
the deposit and investment of money in the fund to the fund. Subject to annual
appropriation by the general assembly, the board of assessment appeals may
expend money from the fund to defray the costs associated with advancing a
taxpayer's appeal.
(3)
Effective January 1, 1983, the consideration of a property's market value in
the ordinary course of trade and the comparison of a property with other
properties of known or recognized value by the board when considering the
market approach to appraisal in its review of the determination of a property's
actual value are subject to the provisions of section 39-1-103 (8).
(4)
Repealed.
Source:
L. 70: R&RE,
p. 377, § 1. L. 71: p. 1245, § 1. C.R.S. 1963: § 137-3-25. L.
73: p. 1438, § 1. L. 76: (1)(c) amended, p. 757, § 12, effective
January 1, 1977. L. 77: (1)(f) amended and (3) added, p. 1735, §§ 14,
15, effective June 20. L. 79: (1)(g) added, p. 1461, § 1, effective July
1. L. 81: (1)(f) amended, p. 1843, § 1, effective May 18; (3) amended,
p. 1831, § 4, effective June 12. L. 83: (1)(d)(I) repealed, p. 1491, §
7, effective April 21; (3) amended, p. 1483, § 5, effective April 22; (1)(d) repealed,
p. 1508, § 5, effective June 2; (1)(f) amended, p. 2086, § 2, effective October
13. L. 84: (1)(c) amended, p. 1001, § 3, effective March 5. L. 85:
(1)(c) amended, p. 1219, § 1, effective March 24. L. 88: (1)(c) amended,
p. 1296, § 2, effective April 29. L. 90: (1)(c)(I) amended, p. 1709, §
1, effective May 22. L. 91: (1)(c)(I) amended, p. 1978, § 2, effective
July 1. L. 92: IP(1) amended and (1)(h) added, p. 2207, § 3, effective
June 3. L. 2002: (1)(g) repealed, p. 1361, § 15, effective July 1. L.
2003: IP(1) and (1)(h) amended, p. 1465, § 2, effective July 1. L. 2008:
(1)(h) amended, p. 2147, § 25, effective June 4. L. 2012: (1.5) added,
(HB 12-1307), ch. 216, p. 929, § 2, effective August 8. L. 2013: (1)(c)
and IP(1)(h) amended, (SB 13-146), ch. 388, p. 2259, § 2, effective July 1. L.
2022: (2.5) added, (HB 22-1416), ch. 158, p. 999, § 5, effective August 10.
L. 2025: (4) added, (SB 25-264), ch. 129, p. 509, § 45, effective April
25; (2.5)(b)(II) amended, (SB 25-265), ch. 130, p. 512, § 3, effective July 1. L.
2026: IP(1) and (1)(c) amended, (SB 26-046), ch. 10, p. 42, § 6, effective
August 12.
Editor's
note: Subsection
(4)(b) provided for the repeal of subsection (4), effective July 1, 2026. (See
L. 2025, p. 509.)
Cross
references: (1)
For the legislative declaration contained in the 2008 act amending subsection
(1)(h), see section 1 of chapter 417, Session Laws of Colorado 2008.
(2) For the legislative
declaration in the 2012 act adding subsection (1.5), see section 1 of chapter
216, Session Laws of Colorado 2012.
ANNOTATION
Law reviews. For
article, "Property Tax Assessments in Colorado", see 12 Colo. Law.
563 (1983). For article, "Appealing Property Tax Assessments", see 15
Colo. Law. 798 (1986). For article, "Property Tax Litigation Before the
Board of Assessment Appeals", see 35 Colo. Law. 87 (Aug. 2006).
Thirty-day requirements of
subsection (1)(c). The initial 30-day requirement in subsection (1)(c)
relates to the filing of the appeal, and the subsequent one to the rendering of
the decision following the hearing before the appeals board. Honeywell Info.
Systems v. Bd. of Assessment Appeals, 654 P.2d 337 (Colo. App. 1982).
The procedure for
determining the running of the 30-day period in this section prevails over
§ 24-4-105 which deals generally with administrative proceedings. Colo. Rocky
Mtn. Sch., Inc. v. Shriver, 689 P.2d 651 (Colo. App. 1984).
Board of assessment appeals
may conduct a de novo review in reviewing a taxpayer's appeal from property
tax administrator. Bd. of Assessment Appeals v. Valley Country Club, 792 P.2d
299 (Colo. 1990).
Board of assessment appeals
has jurisdiction to hear appeals from the county board. Language mandating
that the board hear appeals from the county board's denial of an abatement is
based, by necessity, on a concurrent right of the taxpayer to appeal such
denial to the board of assessment appeals. 5050 S. Broadway Corporation v.
Arapahoe County Bd. of Comm'rs, 815 P.2d 966 (Colo. App. 1991).
Date of presentation of
county board of equalization's resolutions constitutes date of entry for
purposes of computing 30-day time period. BQP Industries v. State Bd. of
Equalization, 694 P.2d 337 (Colo. App. 1984).
Non-compliance with the
30-day requirement of subsection (1)(c) should be avoided, but it will not
constitute reversible error in the absence of any demonstrated damage or
prejudice to the taxpayer. Burns v. Bd. of Assessment Appeals, 820 P.2d 1175
(Colo. App. 1991).
The board's action on
taxpayer's administrative appeal is not limited to review of any previous
action taken, rather the board is authorized to conduct de novo evidentiary
proceedings on the merits in every matter before it including administrative
appeals taken from boards of county commissioners in abatement and refund
proceedings. D.C. Burns Realty v. Jefferson County, 849 P.2d 900 (Colo. App.
1992).
Apart from timely filing
requirement, there are no other statutory jurisdictional requirements for
taking administrative appeals before the BAA. Fleisher-Smyth v. Bd. of
Assessment App., 865 P.2d 922 (Colo. App. 1993).
Applied in West-Brandt
Found., Inc. v. Carper, 199 Colo. 334, 608 P.2d 339 (1980); Lucchesi v. State,
807 P.2d 1185 (Colo. App. 1990).
39-2-126. Delaying effect of decision
- when.
If the
finality of a decision of the board of assessment appeals is suspended until
after the last day of the calendar year by a pending judicial review, the
property tax valuations for the current year shall be those established by the
administrator as to utilities under the provisions of article 4 of this title,
or by the county assessor or those approved by the county board of
equalization, subject to the refund provisions of section 39-8-109.
Source:
L. 70: R&RE,
p. 377, § 1. L. 71: p. 1245, § 2. C.R.S. 1963: § 137-3-26.
39-2-127. Board of assessment appeals
meetings - proceedings - representation before board.
(1) The
board of assessment appeals shall maintain its headquarters in the city and
county of Denver but may transact its official business at any other place
within the state. All its sessions shall be open to the public, and full and
correct minutes thereof shall be kept, and such minutes shall be a public
record open to public inspection.
(2) At
the direction of the chairman and with the agreement of the parties before the
board, one or more of the members of the board of assessment appeals may
conduct hearings in Denver or in a county of closer location to the subject
property, administer oaths, examine witnesses, receive evidence, issue
subpoenas, and render preliminary decisions subject to concurrence and
modification by agreement of at least two members of the board. An additional
board member may be added after a hearing to review the evidence and hearing
transcript or recording and render a decision in the event the board members
who conducted the hearing are unable to reach a decision.
(3)
Upon request of any member of the board, legal counsel provided by the office
of the attorney general shall attend hearings on appeals before the board and
shall advise the board as to matters of procedure, evidence, and law arising in
the course of such appeals. Upon the board's own motion, legal counsel shall
provide other legal services to the board. When the state property tax
administrator is a party to the appeal, such legal counsel shall not be the
same legal counsel who advises or represents the state property tax
administrator at proceedings before the board.
(4) Any
person who is a party in a proceeding before the board may appear on his or her
own behalf or be represented by an attorney admitted to practice law in this
state or by any other individual of his or her choice. A trust may be
represented by an attorney admitted to practice law in this state, by the
trustee of the trust, or by the trustee's designee.
(5) The
board may permit, in its discretion and upon prior written application, the
intervention of another affected party in a matter pending before the board.
The board may limit or restrict the participation of an intervenor in such
manner as the board, in its discretion, orders.
(6) The
board of assessment appeals shall issue a written decision for each appeal it
hears. Each such written decision must either be a summary decision or a full
decision; however, a summary decision may only be issued upon request for a
summary decision made by both parties before the board. A full decision must
contain specific findings of fact and conclusions of law. A summary decision
need not contain specific findings of fact and conclusions of law. If the board
has issued a summary decision, a party dissatisfied with the summary decision
may file a written request with the board for a full decision. The written
request must be received by the board within ten working days after the date on
which the summary decision was mailed. Timely filing of the written request
with the board is a prerequisite to review of the board's decision by the court
of appeals. Upon timely request for a full decision, the board shall issue a
full decision and enter it as the final decision in the appeal subject to judicial
review by the court of appeals as provided in section 39-8-108 (2) or
39-10-114.5 (2).
Source:
L. 70: R&RE,
p. 377, § 1. L. 71: p. 1245, § 3. C.R.S. 1963: § 137-3-27. L.
85: (2) amended and (3) added, p. 1221, § 1, effective July 1. L. 88:
(2) amended and (4) added, p. 1297, § 3, effective April 29. L. 2011:
(2) amended and (5) added, (HB 11-1011), ch. 15, p. 41, § 1, effective August
10. L. 2012: (4) amended, (HB 12-1307), ch. 216, p. 929, § 3, effective
August 8. L. 2013: (6) added, (SB 13-146), ch. 388, p. 2260, § 3,
effective July 1.
Cross
references: For
the legislative declaration in the 2012 act amending subsection (4), see
section 1 of chapter 216, Session Laws of Colorado 2012.
39-2-128. Board of assessment appeals
may issue orders.
The board
of assessment appeals may issue such orders as it deems necessary to ascertain
facts and to carry out its decisions, and any such order directed to a county
assessor or a county board of equalization shall be enforceable in the district
court of the county.
Source:
L. 70: R&RE,
p. 377, § 1. C.R.S. 1963: § 137-3-28. L. 83: Entire section
amended, p. 1491, § 6, effective April 21. L. 2013: Entire section
amended, (SB 13-146), ch. 388, p. 2260, § 4, effective July 1.
39-2-129. Advisory committee to the
property tax administrator created.
(1)
There is created in the department of local affairs the advisory committee to
the property tax administrator. The advisory committee is a type 1
entity, as defined in section 24-1-105, and exercises its powers and performs
its duties and functions under the department of local affairs.
(2)
Repealed.
Source:
L. 76: Entire
section added, p. 755, § 6, effective July 1. L. 86: Entire section
amended, p. 426, § 62, effective March 26. L. 93: (2) repealed, p. 675,
§ 12, effective May 1. L. 2022: (1) amended, (SB 22-162), ch. 469, p.
3415, § 183, effective August 10.
Cross
references: For
the short title (the "Debbie Haskins 'Administrative Organization Act of
1968' Modernization Act") in SB 22-162, see section 1 of chapter 469,
Session Laws of Colorado 2022.
39-2-130. Membership of the advisory
committee - terms - compensation - meetings.
(1)
Said advisory committee shall be comprised of the following five members, no
more than three of whom shall be affiliated with the same political party and
all of whom shall be appointed by the governor with the consent of the senate:
(a) One
assessor and one nonassessor appointed from the counties of seventy-five
thousand or more population according to the most recent federal census;
(b) One
assessor and one nonassessor appointed from the counties of less than
seventy-five thousand population according to the most recent federal census;
and
(c) One
nonassessor from the western slope.
(2) (a)
The governor shall appoint one of the nonassessor members as chairman of the
advisory committee.
(b) The
governor shall appoint the assessor members from among the certified assessors
recommended by the Colorado assessors association.
(3)
Initially, two members shall be appointed to the advisory committee for
two-year terms and three members for four-year terms. Thereafter, appointments
to the advisory committee shall be for terms of four years each. Vacancies on
the advisory committee shall be filled by appointment of the governor for the
unexpired term.
(4)
Members of said committee shall be compensated on a per diem allowance basis at
the rate of thirty-five dollars per day and shall be reimbursed for their
actual and necessary expenses. Per diem compensation, not to exceed thirty days
in any calendar year, shall be paid only when the advisory committee is in
session.
(5) The
advisory committee shall meet at least quarterly but may meet more frequently
upon call of the chairman and may hold hearings as deemed necessary. A quorum
of at least three members shall be required to conduct official business.
(6)
Repealed.
Source:
L. 76: Entire
section added, p. 755, § 6, effective July 1. L. 86: (6) added, p. 426,
§ 63, effective March 26. L. 93: (6) repealed, p. 1792, § 86, effective
June 6.
39-2-131. Function of the committee -
notice of proposed changes - property tax materials - definition.
(1) (a)
It is said committee's function and it shall have and exercise the authority,
prior to publication, to review:
(I)
Manuals or any part thereof, appraisal procedures, instructions, and guidelines
prepared and published by the administrator pursuant to section 39-2-109 (1)(e)
and based upon the approaches to appraisal set forth in section 39-1-103 (5)(a)
and pursuant to section 39-2-109 (1)(k); and
(II)
Forms, notices, and records approved or prescribed pursuant to the authority of
the property tax administrator set forth in section 39-2-109 (1)(d).
(b)
Upon completion of such review, said committee shall submit such manuals,
appraisal procedures, instructions, guidelines, forms, notices, and records and
its recommendations to the state board of equalization for approval or
disapproval pursuant to section 39-9-103 (10).
(2)
Repealed.
(3) (a)
At least two weeks prior to the advisory committee to the property tax
administrator reviewing a proposed change to the property tax materials in
accordance with subsection (1)(a) of this section, the property tax
administrator shall publish notice that includes:
(I) The
date, time, and place of the hearing; and
(II)
The proposed changes to the property tax materials.
(b) As
used in this subsection (3), "property tax materials" means the
manuals, appraisal procedures, instructions, and guidelines that the
administrator prepares and publishes under the authority conferred by section
39-2-109 (1)(e) and (1)(k).
Source:
L. 76: Entire
section added, p. 756, § 6, effective July 1. L. 83: Entire section
amended, p. 1483, § 6, effective April 22. L. 86: Entire section
amended, p. 426, § 64, effective March 26. L. 90: (1) amended, p. 1699,
§ 27, effective June 9. L. 91: (1) amended, p. 1953, § 2, effective
January 1, 1992. L. 93: (2) repealed, p. 1792, § 87, effective June 6. L.
2022: (3) added, (HB 22-1416), ch. 158, p. 997, § 2, effective August 10. L.
2026: (3)(b) amended, (SB 26-046), ch. 10, p. 43, § 7, effective August 12.
Exemptions
ARTICLE
3
Exemptions
PART 1
PROPERTY EXEMPT FROM TAXATION
39-3-101. Legislative declaration -
presumption of charitable purpose.
39-3-102. Household furnishings - exemption.
39-3-103. Personal effects - exemption.
39-3-104. Ditches, canals, and flumes - exemption.
39-3-105. Public libraries - governments -
school districts - exemption.
39-3-106. Property - religious purposes -
exemption - legislative declaration.
39-3-106.5. Tax-exempt property - incidental
use - exemption - limitations.
39-3-107. Property - not-for-profit schools -
exemption.
39-3-108. Property - nonresidential -
health-care facility - water company - charitable purposes - exemption -
limitations.
39-3-108.5. Property - community corrections
facility - exemption.
39-3-109. Residential property - integral
part of tax-exempt entities - charitable purposes - exemption - limitations.
39-3-110. Property - integral part of child
care center - charitable purposes - exemption - limitations.
39-3-111. Property - used by fraternal or
veterans' organization - charitable purposes - exemption - limitations.
39-3-111.5. Property - health-care services -
charitable purposes - exemption - limitations.
39-3-112. Residential property - orphanage -
low-income elderly or individuals with disabilities - homeless or abused -
low-income households - charitable purposes - exemption - limitations -
definitions.
39-3-112.5. Residential property - homeless -
charitable purposes - exempt - limitations.
39-3-113. Residential property - while being
constructed - charitable purposes - exemption - limitations.
39-3-113.5. Property acquired by nonprofit
housing provider for low-income housing - use for charitable purposes -
exemption - limitations - definitions.
39-3-114. Burden - claim for charitable
exemption.
39-3-114.5. Charitable exemption - owner
claiming federal tax credit - fee in lieu of school district tax. (Repealed)
39-3-115. Statutes not applicable.
39-3-116. Combination use of property -
charitable, religious, and educational purposes - exemption - limitations.
39-3-117. Cemeteries - not-for-profit -
exemption.
39-3-118. Intangible personal property -
exemption.
39-3-118.5. Business personal property -
exemption - exemption authority for local governments.
39-3-118.7. Community solar garden - partial business
personal property tax exemption - definitions.
39-3-119. Inventories - materials and
supplies - held for consumption or primarily for sale - exemption.
39-3-119.5. Personal property - exemption -
reimbursement to local governments - legislative declaration - definitions.
39-3-120. Livestock - exemption.
39-3-121. Agricultural and livestock products
- exemption.
39-3-122. Agricultural equipment used in
production of agricultural products - CEA facilities - exemption - definition.
39-3-123. Works of art, literary materials,
and artifacts - on loan - exemption - limitations - definitions.
39-3-124. Property used by state entity -
installment sales or lease agreement - financed purchase of an asset,
certificate of participation, or leveraged lease agreement - exemption -
definitions.
39-3-125. Church property - used as residence
- exemption - limitation. (Repealed)
39-3-126. Horticultural improvements -
exemption - limitation - exception.
39-3-126.5. Mobile homes - low-value -
exemption - legislative declaration - definition.
39-3-127. County fair property - exemption -
limitation.
39-3-127.5. Qualifying business entities -
participation in federal tax credit transactions - exemption - requirements -
definitions.
39-3-127.7. Community land trust property -
nonprofit affordable homeownership developer property - exemption -
requirements - legislative declaration - definitions.
39-3-128. Exempt property listed and valued.
39-3-129. Proportional valuation - exempt
property.
39-3-130. Change in tax status of property -
effective date - tax liability.
39-3-131. Entire property becomes tax-exempt.
39-3-132. Portion of property becomes
tax-exempt.
39-3-133. Payment of property taxes
extinguishes lien.
39-3-134. Condemnation by tax-exempt agency -
duties of treasurer.
39-3-135. Taxation of exempt property - taxes
not to become lien. (Repealed)
39-3-136. Legislative declaration - taxation
of exempt property - possessory interests. (Repealed)
39-3-137. Organizations with tax-exempt
status - forgiveness of taxes owed.
39-3-138. EV supply equipment - exemption.
39-3-139. Property tax relief for
communication services deployment - legislative declaration - definitions.
PART 2
PROPERTY TAX EXEMPTION FOR QUALIFYING SENIORS AND DISABLED VETERANS
39-3-201. Legislative declaration.
39-3-202. Definitions.
39-3-203. Property tax exemption -
qualifications.
39-3-204. Notice of property tax exemption.
39-3-205. Exemption applications - penalty
for providing false information - confidentiality.
39-3-206. Notice to individuals returning
incomplete or nonqualifying exemption applications - denial of exemption -
administrative remedies.
39-3-207. Reporting of exemptions -
reimbursement to local governmental entities.
39-3-208. Auditing of property tax exemption
program.
39-3-209. State expenditure for property tax
exemptions - mechanism for refunding of excess state revenue - legislative
declaration.
39-3-210. Reporting of property tax revenue
reductions - reimbursement of local governmental entities - definitions - local
government backfill cash fund - creation - repeal. (Repealed)
39-3-211. Reporting of assessed value
reductions - reimbursement of local governmental entities - local governmental
entity backfill cash fund - creation - legislative declaration - definitions -
repeal.
PART
1
PROPERTY
EXEMPT FROM TAXATION
39-3-101. Legislative declaration -
presumption of charitable purpose.
The
general assembly recognizes that only the judiciary may make a final decision
as to whether or not any given property is used for charitable purposes within
the meaning of the Colorado constitution; nevertheless, in order to guide
members of the public and public officials alike in the making of their
day-to-day decisions and to assist in the avoidance of litigation, the general
assembly hereby finds, declares, and determines that the uses of property that
are set forth in this part 1 as uses for charitable purposes benefit the people
of Colorado and lessen the burdens of government by performing services that
government would otherwise be required to perform. Therefore, property used for
such purposes shall be presumed to be used, or owned and used, as applicable,
solely and exclusively for strictly charitable purposes and not for private
gain or corporate profit, if applicable, and, consequently, property used for
such purposes is entitled to be exempt from the levy and collection of property
tax pursuant to the provisions of this part 1 and the Colorado constitution.
This legislative finding, declaration, determination, and presumption shall not
be questioned by the administrator and shall be entitled to great weight in any
and every court.
Source:
L. 89: Entire
article R&RE, p. 1470, § 1, effective April 23. L. 2002: Entire
section amended, p. 1032, § 66, effective June 1. L. 2022: Entire
section amended, (HB 22-1006), ch. 289, p. 2067, § 4, effective August 10.
Cross
references: For
the legislative declaration in HB 22-1006, see section 1 of chapter 289,
Session Laws of Colorado 2022.
ANNOTATION
Law reviews. For comment
on Young Life Campaign v. Chaffee County appearing below, see 29 Rocky Mt. L.
Rev. 143 (1956).
Annotator's note. The
cases annotated under this section were decided under § 39-3-101 (1)(g) as it
existed prior to the 1989 repeal and reenactment of this article.
For when home for aged
deemed charitable, see Stanbro v. Baptist Home Ass'n of Colo. for Aged, 172
Colo. 572, 475 P.2d 23 (1970).
Charity, in legal sense,
defined as gift. A charity, in the legal sense may be more fully defined as
a gift to be applied consistently with existing laws for the benefit of an
indefinite number of persons by erecting or maintaining public buildings or
works or otherwise lessening the burdens of government. Bd. of County Comm'rs
v. Denver & R. G. R. R. Employees' Relief Ass'n, 70 Colo. 592, 203 P. 850
(1922); Am. Water Works Ass'n v. Bd. of Assmt. Appeals, 38 Colo. App. 341, 563
P.2d 359 (1976).
Charitable exemptions to be
liberally construed. While charitable purpose as an end will be strictly
construed as long as the end is clearly established as charitable, the means
used to achieve that end will be liberally construed as a use for a charitable
purpose. West Brandt Found., Inc. v. Carper, 652 P.2d 564 (Colo. 1982).
Statutory provisions exempting
from taxation properties used for charitable purposes are liberally construed.
Horton v. Colo. Springs Masonic Bldg. Soc'y, 64 Colo. 529, 173 P. 61 (1918).
There is no requirement in
this section that the property be owned and used by the same entity. Maurer
v. Denver Urban Economic Dev., 781 P.2d 111 (Colo. App. 1989).
Tax exemptions must arise
directly from constitutional authorization; and, until such authorization
is granted, the legislative branch of the government is impotent. Young Life
Campaign v. Chaffee County, 134 Colo. 15, 300 P.2d 535 (1956).
There are no implied tax
exemptions. Young Life Campaign v. Chaffee County, 134 Colo. 15, 300 P.2d
535 (1956).
Exemptions from taxation are
to be strictly construed and cannot be enlarged by construction. Murray v.
Bd. of County Comm'rs, 28 Colo. 427, 65 P. 26 (1901); San Luis Power &
Water Co. v. Trujillo, 93 Colo. 385, 26 P.2d 537 (1933).
Water treatment facility, built
pursuant to a directive issued by the federal environmental protection agency,
was not among the types of property specifically exempted from taxation and
therefore was not exempt. ASARCO, Inc. v. Bd. of Comm'rs of Lake County, 916
P.2d 550 (Colo. App. 1995).
Charitable exemptions to be
liberally construed. While charitable purpose as an end will be strictly
construed as long as the end is clearly established as charitable, the means
used to achieve that end will be liberally construed as a use for a charitable
purpose. West Brandt Found., Inc. v. Carper, 652 P.2d 564 (Colo. 1982).
39-3-102. Household furnishings -
exemption.
(1)
Household furnishings, including free-standing household appliances,
wall-to-wall carpeting, an independently owned residential solar electric
generation facility, and security devices and systems that are not used for the
production of income at any time shall be exempt from the levy and collection
of property tax. If any household furnishings are used for the production of
income for any period of time during the taxable year, such household
furnishings shall be taxable for the entire taxable year. An independently
owned residential solar electric generation facility shall not be considered to
be used for the production of income unless the facility produces income for
the owner of the residential real property on which the facility is located. For
property tax purposes only, rebates, offsets, credits, and reimbursements
specified in section 40-2-124, C.R.S., shall not constitute the production of
income. For purposes of this subsection (1), for property tax purposes only,
security devices and systems shall include, but shall not be limited to,
security doors, security bars, and alarm systems.
(2) For
property tax years commencing on and after January 1, 1990, no work of art, as
defined in section 39-1-102 (18), which is not subject to annual depreciation
and which would otherwise be exempt under this section shall cease to be exempt
because it is stored or displayed on premises other than a residence.
Source:
L. 89: Entire
article R&RE, p. 1470, § 1, effective April 23; entire section amended, p.
1494, § 1, effective June 8. L. 92: (1) amended, p. 2216, § 4, effective
June 2. L. 2010: (1) amended, (HB 10-1267), ch. 425, p. 2199, § 2,
effective August 11.
Editor's
note: This section
is similar to former § 39-3-101 (1)(a) as it existed prior to 1989.
39-3-103. Personal effects -
exemption.
Personal
effects which are not used for the production of income at any time shall be
exempt from the levy and collection of property tax.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(b) as it existed prior to 1989.
39-3-104. Ditches, canals, and flumes
- exemption.
Ditches,
canals, and flumes which are owned and used by any person exclusively for
irrigating land owned by such person shall be exempt from the levy and
collection of property tax.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(c) as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-104 is similar to § 39-3-101 (1)(c) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Irrigation ditch system not
taxable separately from land irrigated. A ditch conveying water to a
reservoir, whence it is distributed solely for the irrigation of the lands of
those entitled to the ditch, is not subject to taxation, separate from the land
irrigated: neither is the reservoir nor the bed thereof. Shaw v. Bond, 64 Colo.
366, 171 P. 1142 (1918).
Unless rights retained in
ditch by third party. Where a ditch company retains an interest in the
ditch with water rights unsold, the ditch is not exempt from taxation. Murray
v. Bd. of Comm'rs, 28 Colo. 427, 65 P. 26 (1901).
Water rights deemed
improvement to the lands benefitted. Water rights, although represented by
stock in a mutual ditch company, are properly classified as an improvement to
the land benefitted by the availability of irrigation for purposes of valuation
of the real estate for taxes. Beaty v. Bd. of County Comm'rs, 101 Colo. 346, 73
P.2d 982 (1937).
39-3-105. Public libraries -
governments - school districts - exemption.
Property,
real and personal, of public libraries and of the state and its political
subdivisions, including school districts or any cooperative association
thereof, shall be exempt from the levy and collection of property tax.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(d) as it existed prior to 1989.
ANNOTATION
Property of the fire and
police pension association not exempt from taxation under this section. The
fire and police pension association (FPPA) is not a political subdivision as
defined in § 39-1-102 (12) and the general assembly has not specifically
exempted the FPPA's property from taxation as property of the state. City and
County of Denver v. Bd. of Assessment Appeals, 30 P.3d 177 (Colo. 2001).
39-3-106. Property - religious
purposes - exemption - legislative declaration.
(1)
Property, real and personal, which is owned and used solely and exclusively for
religious purposes and not for private gain or corporate profit shall be exempt
from the levy and collection of property tax.
(2) In
order to guide members of the public and public officials alike in the making
of their day-to-day decisions, to provide for a consistent application of the
laws, and to assist in the avoidance of litigation, the general assembly hereby
finds and declares that religious worship has different meanings to different
religious organizations; that the constitutional guarantees regarding
establishment of religion and the free exercise of religion prevent public
officials from inquiring as to whether particular activities of religious
organizations constitute religious worship; that many activities of religious
organizations are in the furtherance of the religious purposes of such
organizations; that such religious activities are an integral part of the religious
worship of religious organizations; and that activities of religious
organizations which are in furtherance of their religious purposes constitute
religious worship for purposes of section 5 of article X of the Colorado
constitution. This legislative finding and declaration shall be entitled to
great weight in any and every court.
(3) For
the purpose of claiming an exemption pursuant to this section, property that is
owned and used by a charitable trust that is exempt from taxation under section
501 (c)(3) of the federal "Internal Revenue Code of 1986", as
amended, shall be treated the same as property that is owned and used by any
other type of nonprofit organization.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23; entire section R&RE, p.
1485, § 1, effective June 7. L. 2004: (3) added, p. 506, § 3, effective
August 4.
Editor's
note: This section
is similar to former § 39-3-101 (1)(e) as it existed prior to 1989.
Cross
references: For
the constitutional provision regarding exemptions for property used for
religious worship, schools, or charitable purposes, see § 5 of article X of the
state constitution.
ANNOTATION
Annotator's note. Since
§ 39-3-106 is similar to § 39-3-101 (1)(e) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Exemption not perpetual.
The exemption provided by article X, § 5 of the state constitution is not
perpetual and does not run with the land but is dependent upon the use to which
the property is put. St. Mark Coptic Orthodox Church v. State Bd. of Assessment
Appeals, 762 P.2d 775 (Colo. App. 1988).
Distinction must be made
between charitable and religious exemptions. A religious group does not
have as a fundamental purpose the providing of services which the state would
otherwise have to provide since the state is constitutionally prohibited from
such religious involvement. General Conference of Church of God—7th Day v.
Carper, 192 Colo. 178, 557 P.2d 832 (1976).
Constitutionality of tax
exemptions for religious organizations. Tax exemptions for religious
organizations, in and of themselves, do not violate the establishment clause of
the federal constitution. General Conference of Church of God—7th Day v.
Carper, 192 Colo. 178, 557 P.2d 832 (1976).
But tax incentives that
inure only to the benefit of religious organizations solely by virtue of
their religious nature do violate the establishment clause. Catholic Health
Initiatives Colo. v. City of Pueblo, 207 P.3d 812 (Colo. 2009).
Subsection (2) is not
unconstitutional on the grounds that it violates the separation of powers
doctrine because it permits the general assembly to interpret and apply the
state's constitution. Although the final authority to construe the
constitution is vested in the judiciary, the general assembly may pass
legislation clarifying constitutional provisions. Subsection (2) merely
codifies and clarifies the principles of religious neutrality and
nonentanglement mandated by the federal and state constitutions and controlling
case law. Section 5 of article X of the state constitution exempts from
taxation property used for religious worship "unless otherwise provided by
general law", thus leaving it absolutely within the power of the
legislature to limit, modify, or abolish the exemptions provided by the
constitution. Grand County Bd. of Comm'rs v. Prop. Tax Adm'r, 2016 COA 2, 401
P.3d 561.
One seeking an exemption
must comply with the statutory prerequisites for qualification. St. Mark
Coptic Orthodox Church v. State Bd. of Assessment Appeals, 762 P.2d 775 (Colo.
App. 1988).
The test for determining
whether the exemption for property used for religious worship applies depends
upon the character of the use to which the property is put. St. Mark Coptic
Orthodox Church v. State Bd. of Assessment Appeals, 762 P.2d 775 (Colo. App.
1988); Maurer v. Young Life, 779 P.2d 1317 (Colo. 1989); Pilgrim Rest Baptist
Church, Inc. v. Property Tax Adm'r, 971 P.2d 270 (Colo. App. 1998).
The inquiry for exemption
purposes is whether a property is used for activities that further an
organization's religious purposes. The use of the property must be
considered in light of the property owner's religious mission and purposes.
Grand County Bd. of Comm'rs v. Prop. Tax Adm'r, 2016 COA 2, 401 P.3d 561.
If the answer is yes, the
property is used for religious worship and is exempt from taxation. Grand
County Bd. of Comm'rs v. Prop. Tax Adm'r, 2016 COA 2, 401 P.3d 561.
Property tax exemptions
based on religious use should not be narrowly construed, and each claim for
tax exemption must be resolved on the basis of its own facts under the
applicable legal standards. Maurer v. Young Life, 779 P.2d 1317 (Colo. 1989);
Bd. of Assessment Appeals v. AM/FM Int'l, 940 P.2d 338 (Colo. 1997); Pilgrim
Rest Baptist Church, Inc. v. Property Tax Adm'r, 971 P.2d 270 (Colo. App.
1998).
Implicit within the property
tax scheme is a requirement that in order for the property to qualify for tax
exemption for that tax year, there must be at least some actual use of the
property for tax exempt purposes in that tax year. Pilgrim Rest Baptist Church,
Inc. v. Property Tax Adm'r, 971 P.2d 270 (Colo. App. 1998).
Court declines to hold, as a
matter of law, that any particular frequency or quantity of use religious in
character is required to satisfy the constitutional and statutory standards for
an exemption based on religious use. Pilgrim Rest Baptist Church, Inc. v.
Property Tax Adm'r, 971 P.2d 270 (Colo. App. 1998).
Church failed to sustain its
burden of establishing its right to a tax exemption for maintenance
building and property on which it was located. First Christian Church v. Bd. of
Assmt. Appeals, 711 P.2d 721 (Colo. App. 1985).
Although board must examine
the use to which property is put and not the character of the owner, board
permissibly considered the character of the property owner in concluding that
properties were used for religious worship and reflection. Maurer v. Young
Life, 779 P.2d 1317 (Colo. 1989).
Board is permitted and
properly concluded that any nonreligious aspects of the activities
conducted on properties were incidental to the religious worship and reflection
purposes for which the owner claimed such properties were used. Maurer v. Young
Life, 779 P.2d 1317 (Colo. 1989).
Thus, social benefit
analysis inapplicable to religious groups. While a social benefit analysis
may have validity in the determination of charitable exemptions, it has no
place in the state's evaluation of its treatment of bona fide religious groups.
General Conference of Church of God—7th Day v. Carper, 192 Colo. 178, 557 P.2d
832 (1976).
For broad interpretation of
charitable and religious tax exemptions, see General Conference of Church
of God—7th Day v. Carper, 192 Colo. 178, 557 P.2d 832 (1976).
Religious group entitled to
presumption of use consistent with exemption. Where a church organization
has no objectives other than religious, charitable, and educational, it is
entitled to the benefit of the presumption that when its building is completed,
it will be used exclusively for religious purposes. McGlone v. First Baptist
Church, 97 Colo. 427, 50 P.2d 547 (1935).
In finding that property
owner is not entitled to a religious purposes exemption, except for chapels and
religious activity center on its property, board did not apply proper legal
standards and therefore erred as a matter of law. In its analysis, the
board did not address property owner's declaration of religious purposes
contained in its application, the effect of the declaration's presumed
validity, or whether the presumption had been overcome. Because such
declarations are presumptive with regard to the religious purposes for which
property is used under § 39-2-117 (1)(b)(II), the board erred as a matter of
law. Larimer County Bd. v. Prop. Tax Adm'r, 2013 COA 49M, 316 P.3d 60.
The correct inquiry is set
forth in this section and § 39-2-117. The tax administrator and then the board
must review the property owner's application and evidence to determine whether
the owner's use of the property is for a religious purpose, consistent with the
owner's declaration of religious mission and purpose. Larimer County Bd. v.
Prop. Tax Adm'r, 2013 COA 49M, 316 P.3d 60.
39-3-106.5. Tax-exempt property -
incidental use - exemption - limitations.
(1) If
any property, real or personal, which is otherwise exempt from the levy and
collection of property tax pursuant to the provisions of section 39-3-106, is
used for any purpose other than the purposes specified in sections 39-3-106 to
39-3-113.5, such property shall be exempt from the levy and collection of
property tax if:
(a) The
property is used for such purposes for less than two hundred eight hours,
adjusted for partial usage if necessary on the basis of the relationship that
the amount of time and space used for such other purpose bears to the total
available time and space, during the calendar year; or
(b) The
use of the property for such purposes results in either:
(I)
Less than ten thousand dollars of gross income to the owner of such property
which is derived from any unrelated trade or business, as determined pursuant
to the provisions of sections 511 to 513 of the federal "Internal Revenue
Code of 1986", as amended; or
(II)
Less than ten thousand dollars of gross rental income to the owner of such
property.
(1.5)
Notwithstanding the provisions of subsection (1) of this section, for property
tax years commencing on or after January 1, 1994, if any property, real or
personal, which is otherwise exempt from the levy and collection of property
tax pursuant to the provisions of section 39-3-106, is used for any purpose
other than the purposes specified in sections 39-3-106 to 39-3-113.5, such
property shall be exempt from the levy and collection of property tax if:
(a) The
property is used for such purposes for less than two hundred eight hours,
adjusted for partial usage if necessary on the basis of the relationship that
the amount of time and space used for such other purpose bears to the total
available time and space, during the calendar year; or
(b) The
use of the property for such purposes results in:
(I)
Less than ten thousand dollars of gross income to the owner of such property
which is derived from any unrelated trade or business, as determined pursuant
to the provisions of sections 511 to 513 of the federal "Internal Revenue
Code of 1986", as amended; and
(II)
Less than ten thousand dollars of gross rental income to the owner of such
property.
(2)
Except as otherwise provided in section 39-3-108 (3) and subsection (3) of this
section, if any property, real or personal, that is otherwise exempt from the
levy and collection of property tax pursuant to the provisions of sections
39-3-107 to 39-3-113.5 is used on an occasional, noncontinuous basis for any
purpose other than the purposes specified in sections 39-3-106 to 39-3-113.5,
such property shall be exempt from the levy and collection of property tax if:
(a) The
property is used for such purposes for less than two hundred eight hours,
adjusted for partial usage if necessary on the basis of the relationship that
the amount of time and space used for such other purpose bears to the total
available time and space, during the calendar year; or
(b) The
use of the property for such purposes results in less than twenty-five thousand
dollars of gross rental income to the owner of such property.
(3) The
requirement that property be used on an occasional basis in order to qualify
for the exemption set forth in subsection (2) of this section shall not apply
to property, real or personal, that is otherwise exempt from the levy and
collection of property tax pursuant to the provisions of section 39-3-111 that
is used for any purpose other than the purposes specified in sections 39-3-106
to 39-3-113.5.
Source:
L. 89: Entire
section added, p. 1486, § 2, effective June 7. L. 91: (2) added, p.
1956, § 2, effective June 7. L. 93: (1.5) added, p. 613, § 1, effective
April 30. L. 2004: (2)(b) amended, p. 359, § 1, effective August 4. L.
2011: IP(2) amended and (3) added, (HB 11-1010), ch. 275, p. 1240, § 2,
effective August 10. L. 2013: IP(1), IP(1.5), IP(2), and (3) amended,
(HB 13-1300), ch. 316, p. 1703, § 118, effective August 7.
ANNOTATION
The state board of
assessment appeals (board) did not apply correct legal standard and, therefore,
erred as a matter of law in finding that property owner did not qualify for a
charitable use exemption. Assuming that the board correctly applied this
section to determine that the property owner exceeded the adjusted hours or
gross rental income for non-exempt use to entitle it to fully exempt status,
the board then should have considered whether the property owner was entitled
to a partial charitable use exemption. The board also did not properly consider
whether the property owner used the properties solely and exclusively for
strictly charitable purposes. Accordingly, the board did not apply the proper
legal standards when it found that the property owner did not qualify for a
charitable use exemption. Larimer County Bd. v. Prop. Tax Adm'r, 2013 COA 49M,
316 P.3d 60.
39-3-107. Property - not-for-profit
schools - exemption.
Property,
real and personal, which is owned and used solely and exclusively for schools
which are not held or conducted for private or corporate profit shall be exempt
from the levy and collection of property tax. No requirement shall be imposed
that use of property which is otherwise exempt pursuant to the provisions of
this section shall benefit the people of Colorado in order to qualify for said
exemption. Any exemption claimed pursuant to the provisions of this section
shall comply with the provisions of section 39-2-117.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23. L. 90: Entire
section amended, p. 1711, § 1, effective June 9.
Editor's
note: This section
is similar to former § 39-3-101 (1)(f) as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-107 is similar to § 39-3-101 (1)(f) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Validity of section upheld.
The validity of this section exempting from taxation educational and charitable
institutions is upheld on the ground that if they were not in existence their
work would have to be carried on at the expense of the taxpayers. Kemp v.
Pillar of Fire, 94 Colo. 41, 27 P.2d 1036 (1933); United Presbyterian Ass'n v.
Bd. of County Comm'rs, 167 Colo. 485, 448 P.2d 967 (1968).
Educational and charitable
exemptions upheld on grounds of benefit to citizens. An institution or
nonprofit organization, either domestic or foreign, is entitled to the
constitutional and statutory tax exemption if its property in this state is
used solely and exclusively for schools or for strictly charitable purposes,
thus relieving Colorado taxpayers of the burden and expense of providing such
advantages to its citizens. Young Life Campaign v. Bd. of County Comm'rs, 134
Colo. 15, 300 P.2d 535 (1956).
Determination of exemption
based on all proper and appropriate uses. Because the fundamental object of
this section is to exempt school property used for educational purposes, the
uses permissible must necessarily embrace all which are proper and appropriate
to effect the objects of the institution claiming the benefits of the
exemption. Bishop & Chapter of Cathedral of St. John the Evangelist v.
Treasurer of Arapahoe County, 29 Colo. 143, 68 P. 272 (1901); Horton v.
Fountain Valley Sch., 98 Colo. 480, 56 P.2d 933 (1936).
Use incident to main purpose
insufficient to alter exempt status. A use incident to the main purpose for
which the property is held is not enough to lose tax exemption. Occupation of
part of school premises by a bishop and his family does not render the property
subject to taxation so long as his dominant purpose in residing therein is to
carry out the educational objects of the institution. Bishop & Chapter of
Cathedral of St. John the Evangelist v. Treasurer of Arapahoe County, 29 Colo.
143, 68 P. 272 (1901).
Exemption unaffected by
receipt of part tuition. The fact that some money is received from a few
students as part payment for their tuition, board, and lodging does not, in the
circumstances, deprive the property of its exempt character. Kemp v. Pillar of
Fire, 94 Colo. 41, 27 P.2d 1036 (1933).
39-3-108. Property - nonresidential -
health-care facility - water company - charitable purposes - exemption -
limitations.
(1)
Property, real and personal, which is owned and used solely and exclusively for
strictly charitable purposes and not for private gain or corporate profit shall
be exempt from the levy and collection of property tax if:
(a)
Such property is nonresidential;
(b)
Such property is licensed by the state of Colorado as a health-care facility;
or
(c)
Such property is used as an integral part of a nonprofit domestic water
company.
(1.3)
Nonresidential property that is owned and used solely and exclusively by a
qualified amateur sports organization shall be presumed to be owned and used
solely and exclusively for strictly charitable purposes. For purposes of this
subsection (1.3), the term "qualified amateur sports organization"
means any organization organized and operated exclusively to foster local,
statewide, national, or international amateur sports competition if such
organization is also organized and operated primarily to support and develop
amateur athletes for national or international competition in sports; except
that no part of the net earnings of such organization inure to the benefit of
any private shareholder or individual. So long as a qualified amateur sports
organization demonstrates that its membership is open to any individual who is
an amateur athlete, coach, trainer, manager, administrator, or official active
in such sport or to any amateur sports organization that conducts programs in
such sport, or both, the organization shall be presumed to provide public
benefits to an indefinite number of persons and to directly benefit the people
of Colorado whether or not the right to benefit may depend upon voluntary
membership in the organization.
(1.5)
No requirement shall be imposed that use of property which is otherwise exempt
pursuant to the provisions of this section shall benefit the people of Colorado
in order to qualify for said exemption.
(2) Any
exemption claimed pursuant to the provisions of subsection (1) of this section
shall comply with the provisions of section 39-2-117.
(3) (a)
When any property of a health-care facility, real or personal, or any portion
thereof, which is otherwise exempt from the levy and collection of property tax
pursuant to the provisions of paragraph (b) of subsection (1) of this section,
is used for any purpose other than the purposes specified in sections 39-3-106
to 39-3-113.5, such property or portion thereof shall be exempt from the levy
and collection of property tax if the use of the property or portion thereof
does not result in gross income derived from any unrelated trade or business to
the owner which is in excess of fifteen percent of the total gross revenues
derived from the operation of the property. Gross income derived from any
unrelated trade or business shall be determined pursuant to the provisions of
sections 511 through 513 of the federal "Internal Revenue Code of
1986", as amended.
(b) If
the use of any property or portion thereof results in gross income derived from
any unrelated trade or business in excess of fifteen percent of the total gross
revenues to the owner derived from the operation of the property, the
administrator shall determine the value of the nonexempt portion of the
property for property tax purposes.
Source:
L. 89: Entire
article R&RE, p. 1471, § 1, effective April 23. L. 90: (1.3), (1.5),
and (3) added, pp. 1711, 1702, §§ 2, 35, effective June 9. L. 2013:
(3)(a) amended, (HB 13-1300), ch. 316, p. 1703, § 119, effective August 7.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-108 is similar to § 39-3-101 (1)(g) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
One justification for
exempting charitable enterprises from taxation is that they perform
functions which tax-supported governmental entities would otherwise be required
to perform. W. Brandt Found., Inc. v. Carper, 652 P.2d 564 (Colo. 1982); Bd. of
Assessment Appeals v. AM/FM Int'l, 940 P.2d 338 (Colo. 1997).
Neither art. X, § 5 of the
state constitution nor this section defines "strictly charitable
purposes". Therefore it is for the judiciary to construe their meaning
on a case by case basis. Bd. of Assessment Appeals v. AM/FM Int'l, 940 P.2d 338
(Colo. 1997).
Court will not reverse a
decision of board of assessment appeals supported by the record finding
that an applicant's activities did not lessen a burden on government and that
the applicant operates on a quid pro quo basis. Bd. of Assessment Appeals v.
AM/FM Int'l, 940 P.2d 338 (Colo. 1997).
The sine qua non of
lessening the burdens of government is that the charitable work being done by
an entity, if not being done by that entity, must be undertaken at public
expense. Children's Hosp. Colo. v. Prop. Tax Adm'r, 2018 COA 91, 439 P.3d
43.
A child care center on a state
university campus is not a primary responsibility of government, nor does it
perform an activity for which government is responsible or that the government
would be forced to assume in the absence of the center's activities. Since the
child care center does not lessen the burdens of government, the exemption in
this section does not apply. Children's Hosp. Colo. v. Prop. Tax Adm'r, 2018
COA 91, 439 P.3d 43.
Claimant has burden of proof
to establish that activity has a charitable purpose and is used solely for such
purpose. Inst. for Research v. Bd. of Assessment Appeals, 748 P.2d 1346
(Colo. App. 1987).
Right to property tax
exemption for charitable use has not been established until it is shown
that property is nonresidential. Anderson Ranch Arts Found. v. Prop. Tax Adm'r,
729 P.2d 992 (Colo. 1986).
Nonresidential use not found
and therefore charitable exemption not applicable. Anderson Ranch Arts Found.
v. Prop. Tax Adm'r, 729 P.2d 992 (Colo. 1986).
The 15 percent provision
found in subsection (3)(a) does not apply unless the property first
qualifies as tax-exempt property under subsection (1)(b). Thus portions of
offices that were neither part of a licensed health care facility nor owned by
an entity that is a licensed health care facility were not exempt from property
taxation. Jefferson County Bd. of County Comm'rs v. Prop. Tax Adm'r., 989 P.2d
227 (Colo. App. 1999).
Exempt status unaffected by
receipt of money from beneficiaries. The fact that fees are charged for use
of facilities is not fatal to a claim for exemption. W. Brandt Found., Inc. v.
Carper, 652 P.2d 564 (Colo. 1982).
The national junior college
athletic association met all the statutory criteria to constitute a
"qualified amateur sports organization" under the provisions of
subsection (1.3). Nat'l Jr. Coll. Athletic v. Huddleston, 939 P.2d 509 (Colo.
App. 1997).
Gun club did not qualify for
a tax exemption pursuant to subsection (1.3), because it did not meet the
threshold requirement that it be "organized exclusively" to foster
amateur sports competition. Cherry Creek Gun Club, Inc. v. Huddleston, 119 P.3d
592 (Colo. App. 2005).
Evidence insufficient to
support claim for exemption. W. Brandt Found., Inc. v. Carper, 652 P.2d 564
(Colo. 1982).
39-3-108.5. Property - community
corrections facility - exemption.
(1)
Property, real and personal, which is owned and used solely and exclusively for
strictly charitable purposes and not for private gain or corporate profit shall
be exempt from the levy and collection of property tax if such property is
owned and used by a nonprofit community corrections agency for a community
correctional facility or program.
(2) As
used in this section:
(a)
"Community correctional facility or program" shall have the meaning
set forth in section 17-27-102 (3), C.R.S., for community corrections program.
(b)
"Nonprofit community corrections agency" means any person, agency,
corporation, association, or entity that:
(I) Is
exempt from federal income tax pursuant to the "Internal Revenue Code of
1986", as amended; and
(II)
Operates a community correctional facility or program.
(3) The
provisions of this section shall apply to property tax years beginning on or
after January 1, 1993.
Source:
L. 93: Entire
section added, p. 614, § 2, effective April 30. L. 95: (2)(a) amended,
p. 1108, § 54, effective May 31.
39-3-109. Residential property -
integral part of tax-exempt entities - charitable purposes - exemption -
limitations.
(1)
Property, real and personal, which is owned and used solely and exclusively for
strictly charitable purposes and not for private gain or corporate profit shall
be exempt from the levy and collection of property tax if such property is
residential and the structure and the land upon which such structure is located
are used as an integral part of a church, an eleemosynary hospital, an
eleemosynary licensed health-care facility, a school, or an institution whose
property is otherwise exempt from taxation pursuant to the provisions of this
part 1 and which is not leased or rented at any time to persons other than:
(a)
Persons who are attending such school as students; or
(b)
Persons who are actually receiving care or treatment from such hospital,
licensed health-care facility, or institution for physical or mental
disabilities and who, in order to receive such care or treatment, are required
to be domiciled within such hospital, licensed health-care facility, or
institution, or within affiliated residential units.
(2)
Persons residing within residential units specified in paragraph (b) of
subsection (1) of this section may submit to the administrator, on a form
prescribed by the administrator, a certificate signed by a physician licensed
to practice in the state of Colorado that the medical condition of such
individual requires the individual to reside in such residential unit. If a
person residing within such residential unit submits such signed certificate to
the administrator pursuant to the provisions of this subsection (2), the
portion of such residential property that is utilized by qualified occupants
shall be deemed to be property used solely and exclusively for strictly
charitable purposes and not for private gain or corporate profit and such
portion, but only such portion, shall be exempt under the provisions of
subsection (1) of this section. The determination as to what portion of such
structure is so utilized shall be made by the administrator on the basis of the
facts existing on the annual assessment date for such property, and the
administrator shall have the authority to determine a ratio which reflects the
value of the nonexempt portion of such structure in relation to the total value
of the whole structure and the land upon which such structure is located and
which is identical to the ratio of the number of residential units occupied by
nonqualified occupants to the total number of occupied residential units in
such structure.
(2.5)
No requirement shall be imposed that use of property which is otherwise exempt
pursuant to the provisions of this section shall benefit the people of Colorado
in order to qualify for said exemption.
(3) Any
exemption claimed pursuant to the provisions of this section shall comply with
the provisions of section 39-2-117.
Source:
L. 89: Entire
article R&RE, p. 1472, § 1, effective April 23. L. 90: (2.5) added,
p. 1712, § 3, effective June 9. L. 2002: IP(1) amended, p. 1032, § 67,
effective June 1.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
39-3-110. Property - integral part of
child care center - charitable purposes - exemption - limitations.
(1)
Property, real and personal, that is used solely and exclusively for strictly
charitable purposes is exempt from the levy and collection of property tax if
such property is used as an integral part of a child care center:
(a)
Which is licensed pursuant to part 3 of article 5 of title 26.5;
(b)
Which is maintained for the whole or part of a day for the care of five or more
children who are not sixteen years of age or older;
(c)
Which is not owned or operated for private gain or corporate profit;
(d) The
costs of operation of which, including salaries, are reasonable based upon the
services and facilities provided and as compared with the costs of operation of
any comparable public institution;
(e)
Which provides its services to an indefinite number of persons free of charge
or at reduced rates equal to five percent of the gross revenues of such child
care center or equal to ten percent of the amount of tuition charged by such
child care center to the financially needy or charges on the basis of ability
to pay;
(f) The
operation of which does not materially enhance, directly or indirectly, the
private gain of any individual except as reasonable compensation for services
rendered or goods furnished; and
(g) The
property of which is claimed for exemption does not exceed the amount of
property reasonably necessary for the accomplishment of the exempt purpose.
(h)
Repealed.
(1.5)
(a) No requirement shall be imposed that use of property, which is otherwise
exempt pursuant to the provisions of this section, shall benefit the people of
Colorado in order to qualify for said exemption.
(b) If
a child care center is operated by a person other than the owner of the
property, then the other person's use of the property is the sole basis for
determining whether the property meets the requirements for the exemption set
forth in subsection (1) of this section.
(c) To
the extent that real property taxes are shared and payable by one or more
tenants under the lease of property that are not the child care center, real
property taxes otherwise due but for the application of this section are deemed
taxes paid by the property owner or the landlord of a property leased in part
to the child care center.
(2) Any
exemption claimed pursuant to the provisions of subsection (1) of this section
shall comply with the provisions of section 39-2-117.
(3) The
provisions of subsection (1) of this section shall not apply to any child care
center which is operated for religious purposes and which is exempt from the
levy and collection of property tax pursuant to the provisions of section
39-3-106 or 39-3-106.5.
Source:
L. 89: Entire
article R&RE, p. 1473, § 1, effective April 23; (1)(e) amended and (3)
added, p. 1492, § 6, effective June 7. L. 90: (1.5) added, p. 1712, § 4,
effective June 9. L. 2022: IP(1) and (1)(a) amended, (HB 22-1295), ch.
123, p. 866, § 125, effective July 1; IP(1), (1)(f), (1)(g), and (1.5) amended
and (1)(h) repealed, (HB 22-1006), ch. 289, p. 2066, § 2, effective August 10.
Editor's
note: (1) This
section is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
(2) Amendments to subsection
IP(1) by HB 22-1066 and HB 22-1295 were harmonized.
Cross
references: For
the legislative declaration in HB 22-1006, see section 1 of chapter 289,
Session Laws of Colorado 2022.
ANNOTATION
One of the eight
requirements to qualify for a property tax exemption under this section
specifies that a child care center provides services to an indefinite number of
persons either for free or for a reduced rate or charges on the basis of
ability to pay. Children's Hosp. Colo. v. Prop. Tax Adm'r, 2018 COA 91, 439
P.3d 43.
Tax property division rules
define the phrase "charges on the basis of ability to pay" to mean
"that the total cost for each child is determined by a scale based on the
recipient's financial status." This interpretation is not erroneous, nor
does it lack reasonable basis in the law. Children's Hosp. Colo. v. Prop. Tax
Adm'r, 2018 COA 91, 439 P.3d 43.
39-3-111. Property - used by fraternal
or veterans' organization - charitable purposes - exemption - limitations.
Property,
real and personal, which is owned and used solely and exclusively for strictly
charitable purposes and not for private gain or corporate profit, shall be
exempt from the levy and collection of property tax if such property is used by
any fraternal organization, as defined in section 24-21-602 (18),
notwithstanding the requirement that such organization be in existence for a
period of five years, or by any veterans' organization, as defined in section
24-21-602 (43), notwithstanding the requirement that such organization be in
existence for a period of five years, and the net income derived from the use
of such property is irrevocably dedicated to any of the purposes specified in
sections 39-3-106 to 39-3-110, 39-3-112, or 39-3-113 and to the purpose of
maintaining and operating such organization. As used in this section, the term
"net income" means all items of revenue and gain minus all items of
loss and expense, including amounts reasonably anticipated for future needs, as
determined according to the usual method of accounting for such organization.
No requirement shall be imposed that use of property which is otherwise exempt
pursuant to this section shall benefit the people of Colorado in order to
qualify for said exemption. Any exemption claimed pursuant to the provisions of
this section shall comply with the provisions of section 39-2-117.
Source:
L. 89: Entire
article R&RE, p. 1473, § 1, effective April 23. L. 90: Entire
section amended, p. 1712, § 5, effective June 9. L. 2018: Entire section
amended, (HB 18-1375), ch. 274, p. 1725, § 93, effective May 29.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
ANNOTATION
Statutory presumption of use
for charitable purpose relieves fraternal organization only of its burden
to establish such use; however, once the finding of charitable purpose is made,
such organization has the burden of showing the irrevocable dedication of the
net income of such property to the enumerated statutory uses and purpose set
out in this section. Western Slavonic Ass'n v. Prop. Tax Adm'r, 835 P.2d 621
(Colo. App. 1992).
39-3-111.5. Property - health-care
services - charitable purposes - exemption - limitations.
(1)
Property, real and personal, which is owned and used solely and exclusively for
strictly charitable purposes and not for private gain or corporate profit shall
be exempt from the levy and collection of property tax if:
(a)
Such property is owned by a nonprofit corporation, whether organized under the
laws of this state or of another state;
(b)
Such property is occupied or used by one or more physician or dentist, or both,
licensed to practice medicine or dentistry, as applicable, under the laws of
this state for the purpose of the practice of medicine or dentistry;
(c)
Such health-care services are provided to patients who request such services
and the financially needy are only charged for such services based upon the
ability to pay; and
(d) The
board of county commissioners of the county in which such property is located
certifies that a need exists for the provision of such health-care services.
(2) The
limitations set forth in section 39-3-116 (1) and (2) shall not apply to the
use of property pursuant to the provisions of subsection (1) of this section.
(3) Any
exemption claimed pursuant to the provisions of this section shall comply with
the provisions of section 39-2-117.
Source:
L. 91: Entire
section added, p. 1956, § 3, effective June 7.
ANNOTATION
Annotator's note. Since
§ 39-3-111.5 is similar to § 39-3-101 (1)(g)(I)(D) as it existed prior to the
1989 repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Exempt status unaffected by
receipt of money from beneficiaries. An institution does not lose its
charitable character if it receives revenue from recipients of its bounty
sufficient to keep it in operation and further its charitable purposes. Bishop
& Chapter of St. John the Evangelist v. Treasurer of City & County of
Denver, 37 Colo. 378, 86 P. 1021 (1906); Horton v. Colo. Springs Masonic Bldg.
Soc'y, 64 Colo. 529, 173 P. 61 (1918); Bd. of County Comm'rs v. San Luis Valley
Masonic Ass'n, 80 Colo. 183, 250 P. 147 (1926); Am. Water Works Ass'n v. Bd. of
Assmt. Appeals, 38 Colo. App. 341, 563 P.2d 359 (1976).
Where patients asked to pay for
actual necessities furnished by home for consumptives, according to their
circumstances and the accommodations they receive, and where such compensation
does not exceed what is required for maintenance of the institution, it does
not render it less a charity. Bishop & Chapter of Cathedral of St. John the
Evangelist v. Treasurer of City & County of Denver, 37 Colo. 378, 86 P.
1021 (1906).
39-3-112. Residential property -
orphanage - low-income elderly or individuals with disabilities - homeless or
abused - low-income households - charitable purposes - exemption - limitations
- definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Area median income" means the median income of the county in which
the property is located in relation to family size, as published annually by
the United States department of housing and urban development.
(a.3)
"Disabled" means that an individual is unable to engage in any
substantial gainful activity by reason of any medically determinable physical
or mental impairment that can be expected to result in death or that has lasted
for a continuous period of not less than twelve months.
(a.5)
"Elderly or disabled low-income residential facility" means a
facility, a portion of which is operated as a residential facility for elderly
individuals or individuals with disabilities who meet the requirements of
sub-subparagraph (A) of subparagraph (II) of paragraph (a) of subsection (3) of
this section, which portion houses only such persons, exclusive of necessary
housing facilities for resident managerial personnel, and the rest of which is
operated as a health-care facility which is licensed by the state of Colorado.
(b)
"Family service facility" means a facility that is operated as a
residential facility for single-parent families; that houses only such
families, exclusive of necessary housing facilities for resident managerial
personnel; that provides, in addition to housing, counseling in such areas as
career development, parenting skills, and financial budgeting; and that is a
child care center licensed pursuant to section 26.5-5-309.
(b.3)
"Low-income household" means an individual or family whose total
income is no greater than thirty percent of the area median income.
(b.5)
"Low-income household residential facility" means a facility:
(I)
That is operated as a residential facility for low-income households;
(II)
For which the published rent schedule includes rents that a low-income
household can afford by expending no more than thirty percent of the low-income
household's total income for rent and utilities; and
(III)
For which the owner of the facility has shown that the rent for the facility
for which the exemption authorized in subsection (2) of this section applies is
lower than the rent for a comparable facility for which said exemption does not
apply by an amount equal to at least the value of said exemption.
(c)
"Transitional housing facility" means a facility that:
(I) Is
operated as a residential facility for single individuals or families, or both,
who are homeless, who have resided within the past six months in a shelter for
the homeless, or who have been abused, and whose incomes are as specified in
sub-subparagraph (A) of subparagraph (II) of paragraph (a) of subsection (3) of
this section;
(II)
Has as its purpose to facilitate the achievement of independent living by such
individuals and families within a twenty-four-month period; and
(III)
Provides counseling in such areas as career development, parenting skills, and
financial budgeting, whether at such facility or at another location.
(2)
Property, real and personal, which is owned and used solely and exclusively for
strictly charitable purposes and not for private gain or corporate profit shall
be exempt from the levy and collection of property tax if such property is
residential and is occupied, owned, and operated in accordance with the
requirements set forth in subsection (3) of this section.
(3) In
order for property to be exempt from the levy and collection of property tax
pursuant to subsection (2) of this section, the administrator must find,
pursuant to section 39-2-117, that:
(a) The
residential structure is:
(I)
Occupied as an orphanage; or
(II)
Occupied by:
(A)
Single individuals who are sixty-two years of age or older or who are disabled,
or a family, the head of which, or whose spouse, is sixty-two years of age or
older or is disabled, and whose incomes are within one hundred fifty percent of
the limits prescribed for similar individuals or families who occupy low-rent
public housing operated by a city or county housing authority which is nearest
in distance to such structure; or
(B)
Single-parent families whose incomes are as specified in sub-subparagraph (A)
of this subparagraph (II) and who occupy a family service facility which is
owned and operated by an organization which is exempt from federal income tax
pursuant to the provisions of section 501 (c)(3) of the "Internal Revenue
Code of 1986", as amended; or
(C)
Single individuals or families who occupy a transitional housing facility which
is owned and operated by an organization which is exempt from federal income
tax pursuant to the provisions of section 501 (c)(3) of the "Internal
Revenue Code of 1986", as amended; or
(D)
Low-income households who occupy a low-income household residential facility.
(b) The
residential structure is efficiently operated. Efficient operation is
determined by the following factors:
(I)
That the costs of operation, including salaries, are reasonable based upon the
services and facilities provided and as compared with the costs of operation of
any comparable public institution;
(II)
That such operations do not materially enhance, directly or indirectly, the
private gain of any individual except as reasonable compensation for services
rendered or goods furnished;
(III)
That the property on which the exemption is claimed does not exceed the amount
of property reasonably necessary for the accomplishment of the exempt purpose;
and
(IV)
That the owners and operators of the residential structure have no occupancy
requirement that discriminates upon the basis of race, creed, color, religion,
sex, sexual orientation, gender identity, gender expression, marital status,
national origin, or ancestry; however, if the owner or sponsoring organization
is a religious denomination, said owners or operators may give preference to
members of that denomination.
(c) The
property is owned:
(I) By
a nonprofit corporation of which:
(A) No
part of the net earnings of such corporation inures to the benefit of any
private shareholder; and
(B)
Property owned by such corporation is irrevocably dedicated to charitable,
religious, or hospital purposes and no portion of its assets will inure to the
benefit of any private person upon the liquidation, dissolution, or abandonment
of such corporation; or
(II)
(A) With respect to residential structures specified in subsections
(3)(a)(II)(A), (3)(a)(II)(C), and (3)(a)(II)(D) of this section during any
compliance period, as defined by section 42 (i)(1) of the "Internal
Revenue Code of 1986", as amended, including any extended use period
provided under section 42 of the "Internal Revenue Code of 1986", as
amended, by any domestic or foreign limited partnership of which any nonprofit
corporation that satisfies the provisions of subsection (3)(c)(I) of this section
is a general partner and that was formed for the purpose of obtaining, and has
been allocated, low-income housing credits pursuant to section 42 of the
"Internal Revenue Code of 1986", as amended.
(B) For
property tax years commencing prior to January 1, 2019, this subsection
(3)(c)(II) shall not apply if, during such compliance period, such domestic or
foreign limited partnership which owns the residential structure distributes
income or has income available for distribution to its partners or if the
residential structure is sold or otherwise disposed of during such compliance
period. If the administrator determines that, as specified in this subsection
(3)(c)(II)(B), income has been distributed or has been available for
distribution or the residential property has been sold or otherwise disposed
of, the administrator shall revoke the property tax exemption for the
residential property and property taxes shall be levied and collected against
the residential property which would have otherwise been levied and collected
from the date on which the exemption was initially granted plus all delinquent
interest as provided for by law.
(B.5)
For property tax years commencing on or after January 1, 2019, this subsection
(3)(c)(II) shall not apply if, during such compliance period, such domestic or
foreign limited partnership which owns the residential structure distributes
income or has income available for distribution to its partners or if the
residential structure is sold or otherwise disposed of during such compliance
period. If the administrator determines that, as specified in this subsection
(3)(c)(II)(B.5), income has been distributed or has been available for
distribution or the residential property has been sold or otherwise disposed
of, the administrator shall either revoke the property tax exemption for the
residential property as of the date income becomes available for distribution
or terminate the exemption as of the date the property is transferred.
(C) The
provisions of this subparagraph (II) shall apply to applications for exemption
made pursuant to section 39-2-117 which are filed on and after January 1, 1991,
or which are pending on said date; or
(III)
(A) With respect to residential structures specified in sub-subparagraphs
(A), (C), and (D) of subparagraph (II) of paragraph (a) of this subsection (3),
by any domestic or foreign limited partnership of which all of the general and
limited partners are nonprofit corporations that satisfy the provisions of
subparagraph (I) of this paragraph (c).
(B) The
provisions of this subparagraph (III) shall apply to applications for exemption
made pursuant to section 39-2-117 which are filed on or after January 1, 1993,
or which are pending on said date; or
(IV)
(A) With respect to elderly or disabled low-income residential facilities or
low-income household residential facilities, during any compliance period, as
defined by section 42 (i)(1) of the "Internal Revenue Code of 1986",
as amended, including any extended use period provided under section 42 of the
"Internal Revenue Code of 1986", as amended, by any domestic or
foreign limited partnership so long as each of the general partners of such
limited partnership is a for-profit corporation, seventy-five percent or more
of the outstanding voting stock of which is owned by, and seventy-five percent
or more of the members of the board of directors of which is elected by, one or
more nonprofit corporations that satisfy the provisions of subsection (3)(c)(I)
of this section and so long as such limited partnership was formed for the
purpose of obtaining, and the structure that is owned by such limited
partnership has been allocated, low-income housing credits pursuant to section
42 of the "Internal Revenue Code of 1986", as amended.
(B) The
provisions of this subparagraph (IV) shall not apply if, during any compliance
period: Any of the general partners of the domestic or foreign limited
partnership which owns the residential structure specified in sub-subparagraph
(A) of this subparagraph (IV) cease to meet the requirements specified in
sub-subparagraph (A) of this subparagraph (IV); the domestic or foreign limited
partnership which owns such residential structure distributes cash or other
property to its partners; or such residential structure is sold or otherwise
disposed of.
(C)
Upon a determination by the administrator that any of the events specified in
sub-subparagraph (B) of this subparagraph (IV) have occurred, the administrator
shall revoke the property tax exemption for the residential facility specified
in sub-subparagraph (A) of this subparagraph (IV), and property taxes shall be
levied and collected against such residential facility in the amount which
would have otherwise been levied and collected from the date on which such
exemption was initially granted, and all delinquent interest provided by law
shall apply to such taxes.
(D) The
provisions of this subparagraph (IV) shall apply to applications for exemption
made pursuant to section 39-2-117 which are filed on or after January 1, 1993,
or which are pending on such date.
(4) In
the event the occupants of the residential structure include both persons who
are qualified pursuant to paragraph (a) of subsection (3) of this section and
persons who are not qualified, the portion of such residential structure that
is utilized by qualified occupants shall be deemed to be property used solely
and exclusively for strictly charitable purposes and not for private gain or
corporate profit, and such portion, but only such portion, shall be exempt
pursuant to the provisions of subsection (2) of this section. The determination
as to what portion of such structure is so utilized shall be made by the
administrator on the basis of the facts existing on the annual assessment date
for such property, and the administrator shall have the authority to determine
a ratio which reflects the value of the nonexempt portion of such structure in
relation to the total value of the whole structure and the land upon which such
structure is located and which is identical to the ratio of the number of residential
units occupied by nonqualified occupants to the total number of occupied
residential units in such structure.
(4.5)
No requirement shall be imposed that use of property which is otherwise exempt
pursuant to the provisions of this section shall benefit the people of Colorado
in order to qualify for said exemption.
(5) Any
exemption claimed pursuant to the provisions of this section shall comply with
the provisions of section 39-2-117.
(6) For
purposes of processing applications received for the exemption authorized by
subsection (2) of this section for low-income household residential facilities,
the department of local affairs shall contract with an independent contractor
for the performance of the application processing services in accordance with
section 24-50-504, C.R.S. Said contract shall be limited to a term of one year
and shall commence when the exemption for low-income household residential
facilities first becomes available.
Source:
L. 89: Entire
article R&RE, p. 1473, § 1, effective April 23. L. 90: (4.5) added,
p. 1713, § 6, effective June 9. L. 91: (1)(c) added and (3)(a) and
(3)(c) amended, p. 1957, §§ 4, 5, effective June 7. L. 92: (3)(c)(II)(B)
amended, p. 2223, § 3, effective April 9. L. 93: (1)(a.5), (3)(c)(III),
and (3)(c)(IV) added and (3)(c)(II)(C) amended, p. 432, §§ 1, 2, effective
April 19. L. 95: (1)(c), (3)(c)(II)(A), and (3)(c)(III)(A) amended, p.
1391, § 1, effective June 5. L. 2001: (1)(a), (3)(c)(II)(A), (3)(c)(III)(A),
and (3)(c)(IV)(A) amended and (1)(a.3), (1)(b.3), (1)(b.5), (3)(a)(II)(D), and
(6) added, pp. 1520, 1521, §§ 1, 2, 3, effective August 8. L. 2008:
(3)(b)(IV) amended, p. 1604, § 34, effective May 29. L. 2014: (1)(a.5)
amended, (SB 14-118), ch. 250, p. 986, § 24, effective August 6. L. 2019:
IP(3) and (3)(c)(II)(B) amended and (3)(c)(II)(B.5) added, (HB 19-1319), ch.
200, p. 2164, § 4, effective September 1. L. 2021: IP(3) and (3)(b)(IV)
amended, (HB 21-1108), ch. 156, p. 897, § 45, effective September 7. L.
2022: (3)(c)(II)(A) and (3)(c)(IV)(A) amended, (HB 22-1392), ch. 412, p.
2911, § 1, effective June 7; (1)(b) amended, (HB 22-1295), ch. 123, p. 866, §
126, effective July 1.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
Cross
references: (1)
For the legislative declaration contained in the 2008 act amending subsection
(3)(b)(IV), see section 1 of chapter 341, Session Laws of Colorado 2008.
(2) For the legislative
declaration in HB 19-1319, see section 1 of chapter 200, Session Laws of
Colorado 2019.
(3) For the legislative
declaration in HB 21-1108, see section 1 of chapter 156, Session Laws of
Colorado 2021.
ANNOTATION
Law reviews. For
article, "Affordable Housing Tax Exemptions in Colorado", see 54
Colo. Law. 32 (Dec. 2025).
For when home for aged
deemed charitable, see Stanbro v. Baptist Home Ass'n of Colo. for Aged, 172
Colo. 572, 475 P.2d 23 (1970) (decided under former § 39-3-101 (1)(g)).
Subsection (4) is
inapplicable in determining whether transitional housing facilities qualify for
an exemption if unoccupied on January 1. Family Tree Found. v. Prop. Tax
Adm'r, 119 P.3d 581 (Colo. App. 2005).
39-3-112.5. Residential property -
homeless - charitable purposes - exempt - limitations.
(1)
Property, real and personal, which is used solely and exclusively for strictly
charitable purposes and not for private gain or corporate profit shall be
exempt from the levy and collection of property tax if such property is
residential, is owned by the United States, and is leased by a department or
agency of the United States to any nonprofit organization, whether organized
under the laws of this state or of another state, for the purpose of housing
single individuals or families, or both, who are homeless.
(2) Any
exemption shall be allowed pursuant to subsection (1) of this section only upon
the delivery to the administrator of a copy of such lease between the agency of
the United States and the nonprofit organization and a copy of the rental
agreement between the nonprofit organization and the individuals or families to
be housed in such property. Such exemption shall be allowed only for the period
of time that such residential property is actually used for said purpose, and
such nonprofit organization shall immediately notify the administrator when the
use of such residential property has changed.
(3) Any
exemption claimed pursuant to the provisions of this section shall comply with
the provisions of section 39-2-117.
Source:
L. 91: Entire
section added, p. 1959, § 6, effective June 7.
39-3-113. Residential property - while
being constructed - charitable purposes - exemption - limitations.
Property,
real and personal, which is owned and used solely and exclusively for strictly
charitable purposes and not for private gain or corporate profit shall be
exempt from the levy and collection of property tax if such property is
residential and consists of land and one or more structures which are in the
process of being constructed if such property is irrevocably committed to
residential use in accordance with the requirements set forth in section
39-3-109 (1) or 39-3-112 (2) and (3). The exemption provided by this section
shall terminate on the assessment date subsequent to the issuance of a permit
or other authority to occupy such structure or structures. Thereafter, such
property shall be subject to the provisions of sections 39-3-109 and 39-3-112.
No requirement shall be imposed that use of property which otherwise is exempt
pursuant to the provisions of this section shall benefit people of Colorado in
order to qualify for said exemption. Any exemption claimed pursuant to the
provisions of this section shall comply with the provisions of section
39-2-117.
Source:
L. 89: Entire
article R&RE, p. 1475, § 1, effective April 23. L. 90: Entire
section amended, p. 1713, § 7, effective June 9.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-113 is similar to § 39-3-101 (1)(g) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Prospective site of building
not exempt. Under this section and § 5 of art. X, Colo. Const., property
held with the intention of erecting thereon at some future time buildings for
purely charitable purposes is not exempt from taxation. City & County of
Denver v. George Washington Lodge Ass'n, 121 Colo. 470, 217 P.2d 617 (1950).
Requiring ownership as well
as use deemed within constitutional authorization. In requiring ownership,
as well as use for strictly charitable purposes, the general assembly acted
within its power, under § 5, art. X, Colo. Const., to vary, by general law,
such exemptions created by the constitution. First Nat'l Bank v. Bd. of County
Comm'rs, 189 Colo. 128, 538 P.2d 427 (1975).
When there is neither a present
charitable use nor the vestige of a building in which such use might be carried
on, there is no possible basis for exemption. Grace Calvary Church v. City
& County of Denver, 130 Colo. 290, 274 P.2d 983 (1954).
Where unfinished building
deemed within exemption. The fact that a building remains in an unfinished
state, due to inability to obtain funds to complete it, does not destroy the
property's tax exempt status, because of the uses, wholly consistent with the
operation of a hospital, to which it is being put pending its completion. City
& County of Denver v. Spears Free Clinic Hosp. for Poor Children, 142 Colo.
347, 350 P.2d 1057 (1960).
39-3-113.5. Property acquired by
nonprofit housing provider for low-income housing - use for charitable purposes
- exemption - limitations - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Area median income" means the median income of any county in which
property is located in relation to family size, as published annually by the
United States department of housing and urban development.
(a.5)
"Community land trust" means a nonprofit organization that is exempt
from taxation under section 501 (c)(3) of the federal "Internal Revenue
Code of 1986", as amended, and is designed to ensure long-term housing
affordability through a shared-equity model by acquiring and maintaining
ownership of real property, while selling the improvements to low-to-middle
income households for use as a primary residence.
(b)
"Indicators of intent" means off-site activities of a nonprofit
housing provider that establish the provider's specific intent to:
(I) Use
property for the purpose of constructing or rehabilitating housing to be sold
to low-income applicants; or
(II)
Sell the property to low-income applicants for the purpose of constructing or
rehabilitating housing for the low-income applicants.
(b.5)
"Land lease" means a long-term lease used in affordable homeownership
properties to lease the real property that is owned by a community land trust
or nonprofit affordable homeownership developer to the owner of the
improvements on the real property and preserve the improvements as an
affordable homeownership property.
(c)
"Low-income applicant" means:
(I) For
property tax years commencing before January 1, 2024, an individual or family
whose total income is no greater than eighty percent of the area median income
and who applies to a nonprofit housing provider to assist in the construction
and purchase of housing to be constructed by the provider; and
(II)
For property tax years commencing on or after January 1, 2024, an individual or
family who both apply to a nonprofit housing provider to purchase an affordable
for-sale unit and whose total income is at or below either:
(A) One
hundred percent of the area median income of households of the same size in the
county in which the housing is located; or
(B) One
hundred twenty percent of the area median income of households of the same size
in the county in which the housing is located, if the individual or family
resides in a county classified as a rural resort community by the division of
housing pursuant to section 29-4-1107 (1)(d).
(d)
"Nonprofit housing provider" means an organization that is exempt
from federal income tax pursuant to section 501 (c)(3) of the federal
"Internal Revenue Code of 1986", as amended, and that has a primary
organizational mission of:
(I)
Working with low-income applicants to construct or rehabilitate housing that
the organization then sells to the low-income applicants for their residential
use; or
(II)
Selling property or improvements to low-income applicants for the low-income
applicants' residential use.
(2) (a)
Subject to the limitations specified in subsection (3) of this section, for
property tax years commencing on or after January 1, 2011, real property
acquired by a nonprofit housing provider upon which the provider intends to
construct or rehabilitate housing to be sold to low-income applicants or which
the provider intends to sell to low-income applicants for their residential use
is deemed to be being used for strictly charitable purposes, regardless of
whether or not there is actual physical use of the property, and shall be
exempt from property taxation in accordance with section 5 of article X of the
state constitution.
(b) (I)
For property tax years commencing on or after January 1, 2024, the property tax
exemption described in this section applies from when the nonprofit housing
provider claims the exemption, through construction, rehabilitation, or
improvement of the property, until the provider sells, transfers, donates, or
leases the property.
(II) If
property is sold by a nonprofit housing provider to a low-income applicant, the
property may qualify for the property tax exemption described in this section
until a certificate of occupancy is issued for the property; except that
property may not qualify for the property tax exemption described in this
section more than one year after the provider sells the property to the
low-income applicant.
(c) (I)
For property tax years commencing on or after January 1, 2011, but before
January 1, 2024, in determining whether a nonprofit housing provider satisfies
the intent requirement of subsection (2)(a) of this section with respect to
particular property, the administrator may consider indicators of intent,
including but not limited to:
(A) The
establishment by the nonprofit housing provider of a committee or other
structure for the purpose of planning the construction or rehabilitation of
housing on the property;
(B)
Steps taken by the nonprofit housing provider to obtain any required local
government approvals for the construction or rehabilitation of housing on the
property;
(C)
Steps taken by the nonprofit housing provider to develop and implement a
financing plan for the construction or rehabilitation of housing on the
property;
(D) The
hiring of architects, contractors, or other professionals by the nonprofit
housing provider in preparation for the actual construction or rehabilitation
of housing on the property; and
(E) The
solicitation or acceptance by the nonprofit housing provider of applications
from low-income applicants for housing to be constructed or rehabilitated on
the property.
(II)
For property tax years commencing on or after January 1, 2024, in determining
whether a nonprofit housing provider satisfies the intent requirement of
subsection (2)(a) of this section with respect to particular property, the
administrator may consider indicators of intent, including but not limited to:
(A) A
land donation agreement between the landowner and the nonprofit housing
provider that outlines the purpose of the property donation;
(B) A
resolution by the nonprofit housing provider's board that designates the
property for construction or rehabilitation of for-sale affordable housing; or
(C) A
resolution by the nonprofit housing provider's board that approves the purchase
of the property for land banking with the purpose of constructing or
rehabilitating for-sale affordable housing.
(3) (a)
For property tax years commencing on or after January 1, 2011, but before
January 1, 2024, the property tax exemption described in this section is
subject to the following limitations:
(I) The
exemption may be allowed for a maximum of five consecutive property tax years,
beginning with the property tax year in which the nonprofit housing provider
obtained title to the property; and
(II) If
the nonprofit housing provider is allowed an exemption for any property tax
year and subsequently sells, donates, or leases the property to any person
other than a low-income applicant who assisted or will assist in the
construction of housing for the applicant's residential use on the property,
the provider shall be liable for all property taxes that the provider did not
previously pay due to the exemption.
(b) For
property tax years commencing on or after January 1, 2024, the property tax
exemption described in this section is subject to the following limitations:
(I) For
nonprofit housing providers who have not previously claimed the property tax
exemption, the exemption may be allowed for a maximum of ten consecutive
property tax years, beginning with the property tax year in which the nonprofit
housing provider claimed the exemption;
(II)
For nonprofit housing providers who have previously claimed the property tax
exemption, the exemption may be allowed for a maximum of five consecutive
property tax years, in addition to the five-year period described in subsection
(3)(a)(I) of this section; and
(III)
The nonprofit housing provider is liable for all property taxes that the
provider did not previously pay due to the exemption if the provider sells,
donates, or leases the property to anyone other than:
(A) A
low-income applicant who purchased the property; or
(B) A
community land trust or nonprofit housing provider intending to sell the
improvements on the property to a low-income applicant and lease the underlying
land to the low-income applicant through a land lease.
Source:
L. 2011: Entire
section added, (HB 11-1241), ch. 248, p. 1082, § 1, effective August 10. L.
2013: (1)(b), (1)(c), (1)(d), IP(2), and (3)(b) amended, (HB 13-1246), ch.
203, p. 845, § 1, effective August 7. L. 2023: (1)(a.5) and (1)(b.5)
added and (1)(c), (1)(d)(II), (2), and (3) amended (HB 23-1184), ch. 260, p.
1502, § 2, effective August 7.
ANNOTATION
Law reviews. For
article, "Affordable Housing Tax Exemptions in Colorado", see 54
Colo. Law. 32 (Dec. 2025).
39-3-114. Burden - claim for
charitable exemption.
The burden
shall be on the owner and operator of any residential property for which an
exemption is claimed pursuant to any of the provisions of sections 39-3-109 and
39-3-112 to show facts sufficient to support the exemption claimed. In
determining whether or not a particular property is entitled to such an
exemption provided for in any of said sections, the administrator may require
the owner or operator of such property to annually submit a complete financial
report on its operations and may require any occupants whose residential units
are claimed to qualify for such exemption to submit copies of their federal or
state income tax returns.
Source:
L. 89: Entire
article R&RE, p. 1475, § 1, effective April 23. L. 2009: Entire
section amended, (SB 09-042), ch. 176, p. 781, § 4, effective August 5.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g) as it existed prior to 1989.
ANNOTATION
Subsection (1)(g) not
violative of equal protection. There can be no doubt that the general
assembly intended to treat property owned and used by a charity differently
than property merely used by a charity. Since within these classes all persons
or entities are treated similarly, there is no violation of equal protection
under the fourteenth amendment. First Nat'l Bank v. Bd. of County Comm'rs, 189
Colo. 128, 538 P.2d 427 (1975) (decided under former law).
39-3-114.5. Charitable exemption - owner
claiming federal tax credit - fee in lieu of school district tax. (Repealed)
Source:
L. 2009: Entire
section added, (SB 09-042), ch. 176, p. 780, § 3, effective August 5. L.
2014: Entire section repealed, (HB 14-1349), ch. 230, p. 855, § 5,
effective May 17.
39-3-115. Statutes not applicable.
Nothing in
sections 39-3-106 to 39-3-114 shall apply to parts 2 and 5 of article 4 of
title 29, C.R.S.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23.
39-3-116. Combination use of property
- charitable, religious, and educational purposes - exemption - limitations.
(1)
Except as otherwise provided in this section, property, real and personal,
which is used, or owned and used, as applicable, by the owner thereof or by any
other person or organization solely and exclusively for any combination of the
purposes specified in sections 39-3-106 to 39-3-113.5, subject to the
limitations and requirements in said sections, is exempt from the levy and
collection of property tax. No requirement shall be imposed that use of
property that is otherwise exempt pursuant to any of said sections shall
benefit the people of Colorado in order to qualify for said exemption. Property
that is otherwise exempt pursuant to the provisions of this section is subject
to the provisions of section 39-3-129 relating to the proportional valuation of
exempt property if such property is partially leased, loaned, or otherwise made
available for a portion of any calendar year to any business conducted for
profit.
(2)
Except as set forth in subsection (2.5) of this section, in the event that such
property is used by any person or organization other than the owner:
(a) The
use of the property by the owner, if any, must qualify pursuant to the
provisions of this section or pursuant to any of the provisions of sections
39-3-106 to 39-3-113.5, and, in addition, the owner must qualify for an
exemption pursuant to the provisions of section 39-2-117;
(b) The
use of the property by the person or organization other than the owner is a use
described in the provisions of this section or in any of the provisions of
sections 39-3-106 to 39-3-113.5 or such person or organization is otherwise
exempt from the payment of property taxes; and
(c) The
amount received by the owner for the use of such property specified in sections
39-3-107 to 39-3-113.5, other than from any shareholder or member of the owner
or from any person or organization controlled by an organization which also
controls such shareholder or member, must not exceed one dollar per year plus
an equitable portion of the reasonable expenses incurred in the operation and
maintenance of the property so used. For purposes of this paragraph (c),
reasonable expenses include interest expenses, depreciation, long-term
maintenance expenses allowed in accordance with generally accepted accounting
principles, capital expenses dedicated to refurbishing the property, and
expenses incurred to allow the property to conserve energy, water, or other
natural resources, but do not include any amount expended to reduce debt.
(2.5)
Subsection (2) of this section does not apply to property that is used as an
integral part of a child care center operated by a person or organization other
than the owner of the property and that qualifies for an exemption under
section 39-3-110.
(3) Any
exemption claimed pursuant to the provisions of this section shall comply with
the provisions of section 39-2-117.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23; (2)(c) amended, p. 1486, §
3, effective June 7. L. 90: (1) amended, p. 1713, § 8, effective June 9.
L. 2013: (1) and (2) amended, (HB 13-1300), ch. 316, p. 1704, § 120,
effective August 7. L. 2014: (2)(c) amended, (HB 14-1074), ch. 26, p.
166, § 1, effective March 14. L. 2022: (1) and IP(2) amended and (2.5)
added, (HB 22-1006), ch. 289, p. 2067, § 5, effective August 10.
Editor's
note: This section
is similar to former § 39-3-101 (1)(g.1) as it existed prior to 1989.
Cross
references: For
the legislative declaration in HB 22-1006, see section 1 of chapter 289,
Session Laws of Colorado 2022.
ANNOTATION
Annotator's note. Since
§ 39-3-116 is similar to § 39-3-101 (1)(g.1) as it existed prior to the 1989
repeal and reenactment of this article, relevant cases construing that
provision have been included in the annotations to this section.
Rule of strict construction
not followed in all cases. While tax exemptions are normally subject to
strict construction and limitation, this rule of strict construction is not
applied with full vigor to charitable, religious, and educational exemptions.
Bishop & Chapter of Cathedral of St. John the Evangelist v. Treasurer of
Arapahoe County, 29 Colo. 143, 68 P. 272 (1901); Colo. Sem. v. Bd. of Comm'rs,
30 Colo. 507, 71 P. 410 (1903); Bishop & Chapter of Cathedral of St. John
the Evangelist v. Treasurer of City and County of Denver, 37 Colo. 378, 86 P.
1021 (1906); Pitcher v. Miss Wolcott Sch. Ass'n, 63 Colo. 294, 165 P. 608
(1917); Horton v. Colo. Springs Masonic Bldg. Soc'y, 64 Colo. 529, 173 P. 61
(1918); Bd. of Comm'rs v. San Luis Valley Masonic Ass'n, 80 Colo. 183, 250 P.
147 (1926); Denver Turnverein v. McGlone, 91 Colo. 473, 15 P.2d 709 (1932);
Kemp v. Pillar of Fire, 94 Colo. 41, 27 P.2d 1036 (1933); General Conference of
Church of God—7th Day v. Carper, 192 Colo. 178, 557 P.2d 832 (1976).
Each case must be resolved
on its own facts. While tax exemption statutes are generally strictly
construed, each case must be resolved on the basis of its own facts,
considering all its facts and circumstances and the intentions and purposes of
those in charge of the institution to which the property belongs, respecting
the use and occupation of such property. Bishop & Chapter of Cathedral of
St. John the Evangelist v. Treasurer of City & County of Denver, 37 Colo.
378, 86 P. 1021 (1906); United Presbyterian Ass'n v. Bd. of County Comm'rs, 167
Colo. 485, 448 P.2d 967 (1968); Am. Water Works Ass'n v. Bd. of Assmt. Appeals,
38 Colo. App. 341, 563 P.2d 359 (1976).
General assembly has power
to abolish tax exemptions granted. It is within the power of the general
assembly to abolish tax exemptions granted to religious, charitable, and
educational institutions. McGlone v. First Baptist Church, 97 Colo. 427, 50
P.2d 547 (1935).
39-3-117. Cemeteries - not-for-profit
- exemption.
Cemeteries
not used or held for private or corporate profit shall be exempt from the levy
and collection of property tax.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(h) as it existed prior to 1989.
39-3-118. Intangible personal property
- exemption.
Intangible
personal property shall be exempt from the levy and collection of property tax.
For purposes of this section, "intangible personal property" shall
include, but is not limited to, computer software.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23. L. 90: Entire
section amended, p. 1715, § 2, effective May 2.
Editor's
note: This section
is similar to former § 39-3-101 (1)(i) as it existed prior to 1989.
Cross
references: For
the legislative declaration contained in the 1990 act amending this section,
see section 1 of chapter 281, Session Laws of Colorado 1990.
ANNOTATION
Exemption does not apply to
a public utility, which is assessed under the valuation method established
in part 4 of this article. Qwest v. Colo. Div. of Prop. Taxation, 2013 CO 39,
304 P.3d 217.
39-3-118.5. Business personal property -
exemption - exemption authority for local governments.
(1) For
property tax years commencing on and after January 1, 1996, business personal
property shall be exempt from the levy and collection of property tax until
such business personal property is first used in the business after
acquisition.
(2) For
the property tax year commencing on January 1, 2021, any county, municipality,
or special district may exempt from its levy and collection of property tax up
to one hundred percent of any business personal property.
Source:
L. 95: Entire
section added, p. 1213, § 1, effective May 31. L. 2021: Entire section
amended, (SB 21-130), ch. 75, p. 299, § 2, effective April 29.
Cross
references: For
the legislative declaration in SB 21-130, see section 1 of chapter 75, Session
Laws of Colorado 2021.
39-3-118.7. Community solar garden -
partial business personal property tax exemption - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Community solar garden" has the same meaning as set forth in section
40-2-127 (2)(b)(I)(A), C.R.S.
(b)
"Subscriber" has the same meaning as set forth in section 40-2-127
(2)(b)(II), C.R.S.
(2) For
property tax years commencing on and after January 1, 2015, but before January
1, 2021, there is exempt from the levy and collection of property tax the
percentage of alternating current electricity capacity of a community solar
garden that is attributed to residential or governmental subscribers, or to
subscribers that are organizations that have been granted property tax
exemptions pursuant to sections 39-3-106 to 39-3-113.5.
Source:
L. 2014: Entire
section added, (HB 14-1101), ch. 172, p. 627, § 1, effective August 6.
39-3-119. Inventories - materials and
supplies - held for consumption or primarily for sale - exemption.
Inventories
of merchandise and materials and supplies that are held for consumption by any
business or are held primarily for sale shall be exempt from the levy and
collection of property tax. The property tax administrator shall publish in the
manuals, appraisal procedures, and instructions prepared and published pursuant
to section 39-2-109 (1)(e) a definition or description of the types of personal
property that are "held for consumption by any business" and
therefore exempt from the levy and collection of property tax pursuant to this
section.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23. L. 2000: Entire
section amended, p. 750, § 2, effective May 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(k) as it existed prior to 1989.
ANNOTATION
Television signal boxes and
filters owned by a television service provider and leased to customers are
exempt property. The property tax administrator's published guidelines for
the consumable personal property tax exemption allow for personal property to
be exempt from taxation if the acquisition cost of the property is $250 or
less. Because the value of each box and filter, or each combination of one box
and one filter, was less than $250 and the boxes and filters were produced by
different manufacturers and recorded as separate assets by the television
service provider, the boxes and filters are considered individual items worth
less than $250 rather than components of a larger system worth more than $250.
EchoStar Satellite, L.L.C. v. Arapahoe County Bd. of Equaliz., 171 P.3d 633
(Colo. App. 2007).
39-3-119.5. Personal property -
exemption - reimbursement to local governments - legislative declaration -
definitions.
(1) For
property tax years commencing on and after January 1, 1997, personal property
not otherwise exempt from property tax shall be exempt from the levy and
collection of property tax if the personal property would otherwise be listed
on a single personal property schedule and the actual value of such personal
property is less than or equal to the amount set forth in subsection (2) of
this section.
(2) (a)
The exemption created in subsection (1) of this section shall be up to and
including the following amounts:
(I) Two
thousand five hundred dollars for property tax years commencing prior to
January 1, 2009;
(II)
Four thousand dollars for property tax years commencing on January 1, 2009, and
January 1, 2010;
(III)
Five thousand five hundred dollars for property tax years commencing on January
1, 2011, and January 1, 2012;
(IV)
Seven thousand dollars for property tax years commencing on January 1, 2013,
and January 1, 2014;
(V)
Seven thousand three hundred dollars for property tax years commencing on
January 1, 2015, and January 1, 2016;
(VI)
Seven thousand four hundred dollars for property tax years commencing on
January 1, 2017, and January 1, 2018;
(VII)
Seven thousand seven hundred dollars for property tax years commencing on
January 1, 2019, and January 1, 2020;
(VIII)
Fifty thousand dollars for property tax years commencing on January 1, 2021,
and January 1, 2022; and
(IX)
Fifty-eight thousand dollars for property tax years commencing on or after
January 1, 2027.
(b) (I)
(A) Beginning with the property tax year commencing on January 1, 2023, but
before January 1, 2027, the amount of the exemption created in subsection (1)
of this section shall be adjusted biennially to account for inflation since the
amount of the exemption last changed pursuant to this subsection (2). On or
before November 1, 2022, and each even-numbered year thereafter but before
2027, the administrator shall calculate the amount of the exemption for the
next two-year cycle using inflation for the prior two calendar years as of the
date of the calculation. The adjusted exemption shall be rounded upward to the
nearest one hundred dollar increment. The administrator shall certify the
amount of the exemption for the next two-year cycle and publish the amount on
the website maintained by the division of property taxation in the department
of local affairs.
(B)
When calculating the exemption amount under subsection (2)(b)(I)(A) of this
section, the administrator shall do another calculation in the same manner but
starting from seven thousand nine hundred dollars instead of fifty-eight
thousand dollars. This amount is the alternative exemption amount.
(C) If,
under subsection (3)(f) of this section, the state treasurer notifies the
administrator that not all counties have received reimbursement warrants for
lost property tax revenue for the amounts specified in subsection (3)(d) of
this section, then beginning with the property tax year commencing on January 1
that follows the notification, and for all property tax years thereafter but
before property tax year 2027, the amount of the exemption in subsection (1) of
this section is the alternative exemption amount. Thereafter, but before
property tax year 2027, the alternative exemption is adjusted biennially to
account for inflation in the same manner as set forth in subsection
(2)(b)(I)(A) of this section, and the administrator shall certify the amount of
the exemption for the next two-year cycle and publish the amount on the website
maintained by the division of property taxation in the department of local
affairs.
(II) As
used in subsection (2)(b)(I) of this section, "inflation" means the
annual percentage change in the United States department of labor, bureau of
labor statistics, consumer price index for Denver-Aurora-Lakewood for all items
and all urban consumers, or its applicable predecessor or successor index.
(III)
This subsection (2)(b) is repealed, effective January 1, 2028.
(3) (a)
(I) For the property tax year commencing on January 1, 2021, each assessor
shall calculate the aggregate value of exempt business personal property within
the county based on the property that is listed on schedules for the property
tax year with a total value that is more than seven thousand nine hundred
dollars and less than or equal to fifty thousand dollars.
(II)
For the property tax year commencing on January 1, 2021, each treasurer shall
calculate the total property tax revenues lost by all local governmental
entities within the treasurer's county based on the exempt business personal
property amount calculated in accordance with subsection (3)(a)(I) of this
section.
(b) No
later than February 1, 2022, and each February 1 thereafter through February 1,
2027, the administrator shall calculate the percentage increase or decrease in
total valuation of business personal property in the state over the prior two
property tax years. The administrator shall publish the percentage increase or
decrease on the website maintained by the division of property taxation in the
department of local affairs.
(c) (I)
For the property tax years commencing on or after January 1, 2022, but before
January 1, 2027, each assessor shall calculate an estimate of the aggregate
value of exempt business personal property for the county and each local
governmental entity located within the county that is equal to the applicable
baseline exemption total adjusted by the growth factor for each property tax
year commencing on and after January 1, 2022 but before January 1, 2027.
(II)
For the property tax years commencing on or after January 1, 2022, but before
January 1, 2027, each treasurer shall calculate the total property tax revenues
lost by all local governmental entities within the treasurer's county based on
the estimate of exempt business personal property amount calculated in
accordance with subsection (3)(c)(I) of this section.
(III)
As used in this subsection (3)(c), unless the context otherwise requires:
(A)
"Baseline exemption total" means the aggregate value of the exempt
business personal property calculated in accordance with subsection (3)(a)(I)
of this section for a county or a local governmental entity located within the
county as of January 1, 2021.
(B)
"Growth factor" means the percentage increase or decrease that the
administrator publishes for a property tax year in accordance with subsection
(3)(b) of this section.
(d) No
later than March 1, 2022, and each March 1 thereafter through March 1, 2027,
each treasurer shall report the amount specified in subsection (3)(a)(II) or
(3)(c)(II) of this section, as applicable, and the basis for the amount to the
administrator, and the administrator may require a treasurer to provide
additional information as necessary to evaluate the amount reported. The
administrator shall confirm that the reported amount is correct or rectify the
amount, if necessary. The administrator shall then forward the correct amount
for each county to the state treasurer to enable the state treasurer to issue a
reimbursement warrant to each treasurer in accordance with subsection (3)(e) of
this section.
(e) No
later than April 15, 2022, and April 15 of each year thereafter through April
15, 2027, the state treasurer shall issue a warrant to be paid upon demand from
the general fund to each treasurer that is equal to the amount specified by the
administrator for the county under subsection (3)(d) of this section. Each
treasurer shall distribute the total amount received from the state treasurer
to the local governmental entities within the treasurer's county as if the
revenues had been regularly paid as property tax. When distributing the money,
the treasurer shall provide each local governmental entity with a statement of
the amount distributed to the local governmental entity that represents the
reimbursement received under this subsection (3)(e).
(e.5)
No later than April 15, 2028, and April 15 of each year thereafter, the state
treasurer shall issue a warrant to be paid upon demand from the general fund to
each treasurer that is equal to the amount specified by the administrator for
the county under subsection (3)(d) of this section for the 2026 property tax
year. Each treasurer shall distribute the total amount received from the state
treasurer to the local governmental entities within the treasurer's county as
if the revenues had been regularly paid as property tax. When distributing the
money, the treasurer shall provide each local governmental entity with a
statement of the amount distributed to the local governmental entity that
represents the reimbursement received under this subsection (3)(e.5).
(f) No
later than May 1, 2022, and May 1 of each year thereafter, the state treasurer
shall notify the administrator whether all counties have received a
reimbursement warrant for lost property tax revenue for the amounts specified
in subsection (3)(d) of this section.
(g) (I)
This subsection (3) does not apply if the amount of the exemption created in
subsection (1) of this section is the alternative exemption amount as required
by subsection (2)(b)(I)(C) of this section.
(II)
This subsection (3)(g) is repealed, effective January 1, 2028.
Source:
L. 96: Entire
section added, p. 1847, § 1, effective August 7. L. 2008: Entire section
amended, p. 947, § 1, effective August 5. L. 2018: (2)(b)(II) amended,
(HB 18-1375), ch. 274, p. 1722, § 79, effective May 29. L. 2021:
(2)(a)(III) and (2)(b)(I) amended and (2)(a)(V), (2)(a)(VI), (2)(a)(VII),
(2)(a)(VIII), and (3) added, (HB 21-1312), ch. 299, p. 1792, § 6, effective
July 1. L. 2026: (2)(a)(VII), (2)(a)(VIII), (2)(b)(I)(A), (2)(b)(I)(B),
(2)(b)(I)(C), (3)(b), (3)(c)(I), (3)(c)(II), (3)(d), (3)(e), and (3)(g) amended
and (2)(a)(IX), (2)(b)(III), and (3)(e.5) added, (SB 26-116), ch. 307, p. 1758,
§ 2, effective August 12.
Cross
references: For
the legislative declaration in HB 21-1312, see section 1 of chapter 75, Session
Laws of Colorado 2021.
ANNOTATION
Under both the plain
language and the legislative history of this section, the statutory $2,500 exemption
threshold must be applied on a "per schedule" basis and not on a
"per business location" basis. SecurityLink from Ameritech, Inc.
v. City & County of Denver, 32 P.3d 499 (Colo. App. 2000).
Where personal property
situated in multiple locations throughout the county was listed on a single
personal property schedule and the total valuation of all the property listed
on the schedule exceeded the $2,500 exemption threshold, neither the language
of the statute nor the legislative history supports the view that the general
assembly intended to exempt such property from taxation under these
circumstances. SecurityLink from Ameritech, Inc. v. City & County of
Denver, 32 P.3d 499 (Colo. App. 2000).
The plain language of this
section does not contemplate an exemption where property located at multiple
locations was encompassed in a single schedule and the total property value
per schedule far exceeded $2,500. TCI Satellite Entm't, Inc. v. Bd. of
Equaliz., 9 P.3d 1179 (Colo. App. 2000), aff'd, 31 P.3d 155 (Colo. 2001).
This section merely exempts
a taxpayer's otherwise non-exempt personal property in a particular county if
the aggregate value of such property does not exceed $2,500. Huddleston v.
Bd. of Equaliz., 31 P.3d 155 (Colo. 2001).
This exemption allowed by
this section must be applied on a per-schedule basis and this section
contemplates that all listings of personal property owned by a single taxpayer
in a single county will be treated as a single schedule. Huddleston v.
Montezuma County Bd. of Equaliz., 31 P.3d 155 (Colo. 2001).
39-3-120. Livestock - exemption.
Livestock
shall be exempt from the levy and collection of property tax.
Source:
L. 89: Entire
article R&RE, p. 1476, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(l) as it existed prior to 1989.
39-3-121. Agricultural and livestock
products - exemption.
Agricultural
and livestock products shall be exempt from the levy and collection of property
tax.
Source:
L. 89: Entire
article R&RE, p. 1477, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-101 (1)(m) as it existed prior to 1989.
39-3-122. Agricultural equipment used
in production of agricultural products - CEA facilities - exemption -
definition.
(1)
Agricultural equipment that is used on any farm or ranch in the production of
agricultural products is exempt from the levy and collection of property tax.
(2) On
and after January 1, 2023, agricultural equipment that is used in any CEA
facility or greenhouse is exempt from the levy and collection of property tax.
(3) On
and after January 1, 2024, but before January 2, 2029, personal property is
exempted from the levy and collection of property tax if the property is
machinery or equipment that is part of a solar energy generating system that is
used for agrivoltaics, and if the property:
(a)
Incorporates novel designs, technologies, or configurations that significantly
expand the potential for agricultural activities, including by:
(I)
Elevating the bottom edge height of the panels at least six feet above the
ground;
(II)
Utilizing translucent panels or panels with tubular or other innovative panel
geometry that supports agrivoltaics;
(III)
Incorporating alternative solar tracking algorithms that are tailored to
optimize vegetative growth;
(IV)
Incorporating extended row or panel spacing in a manner that enables
agricultural activities;
(V)
Incorporating modified wire management systems that support livestock,
including raising, lowering, or burying wiring;
(VI)
Incorporating innovative photovoltaic racking structures, including tensioned
wire racking systems, suspension-based systems, or other dynamic photovoltaic
racking systems or arrangements;
(VII)
Incorporating agricultural infrastructure that is typically found on a farm or
ranch operation, such as agricultural fences, water sources and distribution,
water troughs and tanks, corrals, livestock pens, or produce handling
equipment; or
(VIII)
Incorporating agricultural structures that are typically found on an
agricultural operation, such as a tractor shed, a barn, or structures for
equipment storage, produce washing, storage, processing, or chilling and
packaging;
(b) Is
constructed in a manner that minimizes soil compaction underneath and in
between panels; and
(c) Is
constructed to incorporate design strategies that are planned with the intent
to minimize the negative environmental impact of photovoltaic energy production
facilities on ecosystems, native vegetation, state and federally listed
species, wildlife migration corridors, and the species, habitats, and
ecosystems of greatest conservation need.
(4) As
used in this section, "agrivoltaics" has the meaning set forth in
section 35-1-114 (4)(a).
Source:
L. 89: Entire
article R&RE, p. 1477, § 1, effective April 23. L. 2022: Entire
section amended, (HB 22-1301), ch. 198, p. 1322, § 2, effective August 10. L.
2023: (2) amended, (SB 23-204), ch. 182, p. 890, § 1, effective August 7;
(3) and (4) added, (SB 23-092), ch. 218, p. 1131, § 5, effective August 7. L.
2024, 2nd Ex. Sess.: (2) amended, (HB 24B-1003), ch. 2, p. 25, § 2,
effective November 28.
Editor's
note: This section
is similar to former § 39-3-101 (1)(n) as it existed prior to 1989.
39-3-123. Works of art, literary
materials, and artifacts - on loan - exemption - limitations - definitions.
(1)
Works of art, literary materials, and artifacts shall be exempt from the levy
and collection of property tax if such works of art, literary materials, and
artifacts are loaned to and are in the custody and control of:
(a) The
state or a political subdivision thereof; or
(b) A
library or any art gallery or museum which is owned or operated by a charitable
organization whose property is irrevocably dedicated to charitable purposes and
whose assets shall not inure to the benefit of any private person upon the
liquidation, dissolution, or abandonment by the owner, and which uses such
works of art, literary materials, and artifacts for charitable purposes. This
exemption shall apply only for the period of time during which such works of
art, literary materials, and artifacts are actually on loan and shall be in
addition to such exemptions provided for in sections 39-3-108 to 39-3-113.5.
(2) Any
exemption claimed pursuant to the provisions of subsection (1) of this section
shall comply with the provisions of section 39-5-113.5.
(3) For
purposes of subsection (1) of this section:
(a)
"Artifacts" means items of personal property which are objects of
human workmanship and which have archaeological or historical significance.
(b)
"Charitable organization" means a charitable organization as defined
in section 39-26-102 (2.5).
(c)
"Charitable purposes" means public display, research, educational
study, maintenance of property, and preparation for display.
(d)
"Literary materials" means items of personal property including, but
not limited to, books, letters, diaries, records, documents, memoranda,
journals, magazines, and notes.
(e)
"Works of art" means works of art as defined in section 39-1-102
(18).
Source:
L. 89: Entire
article R&RE, p. 1477, § 1, effective April 23. L. 2013: (1)(b)
amended, (HB 13-1300), ch. 316, p. 1704, § 121, effective August 7.
Editor's
note: This section
is similar to former § 39-3-101 (1)(o) as it existed prior to 1989.
39-3-124. Property used by state
entity - installment sales or lease agreement - financed purchase of an asset,
certificate of participation, or leveraged lease agreement - exemption -
definitions.
(1) (a)
Property, real and personal, that is used by the state or any of its political
subdivisions pursuant to the provisions of any installment sales agreement,
financed purchase of an asset agreement, certificate of participation
agreement, or any other agreement whereby the state or such political
subdivision shall be entitled to acquire title to such property at the end of
the agreement term without cost or for only nominal consideration shall be
exempt from the levy and collection of property tax.
(b) (I)
(A) Subject to subsection (1)(b)(I)(B) of this section and except as
provided in subsection (1)(b)(I)(G) of this section, on and after January 1,
2009, the part of real property that is used by the state, a political
subdivision, or a state-supported institution of higher education pursuant to
the provisions of any lease or rental agreement for at least a one-year term,
with or without an option to purchase, and pursuant to which the subject real
property is used for purposes of the state, political subdivision, or
institution of higher education, as applicable, shall be exempt from the levy
and collection of property tax. If the state or any political subdivision or
state-supported institution of higher education enters into a lease or rental agreement
or is already in a lease or rental agreement on or after January 1, 2009, and
is exempt from the levy and collection of property tax pursuant to this
section, the state, political subdivision, or state-supported institution of
higher education, as applicable, shall file a copy of the lease or rental
agreement with the county assessor's office. The state or a political
subdivision or institution of higher education shall notify the county
assessor's office in the event that the lease or rental agreement is terminated
prior to the term stated in such lease or rental agreement. Nothing in this
subsection (1)(b) affects property tax exemptions allowed pursuant to section
8-82-104, 22-32-127, 29-4-227, 30-11-104.2, 31-15-802, or 43-1-214.
(B) The
state, a political subdivision, or a state-supported institution of higher
education shall reduce, deduct, or offset property taxes from rent due under
any lease or rental agreement pursuant to sub-subparagraph (A) of this
subparagraph (I). Upon receipt of a lease or rental agreement for the state, a
political subdivision, or a state-supported institution of higher education,
the county assessor shall send a notice to the landlord acknowledging receipt
of the lease or rental agreement. The notice shall identify the property, the
property address, and the parties to the lease or rental agreement.
(C) To
the extent that real property taxes are shared and payable by one or more
tenants under the lease of property that are not the state, a political
subdivision, or a state-supported institution of higher education, real
property taxes otherwise due but for the application of this paragraph (b)
shall be deemed taxes paid by the property owner or the landlord of a property
leased in part to the state, a political subdivision, or a state-supported
institution of higher education.
(D)
Only a tenant that is the state, a political subdivision, or a state-supported
institution of higher education shall receive any benefit related to the
tenant's property tax-exempt status pursuant to this paragraph (b).
(E) It
is the general assembly's intent that the application of this paragraph (b) be
cost-neutral in that the tax reduction and the rent reduction pursuant to this
paragraph (b) are equal.
(F) In
addition to the requirements listed in subsection (1)(b)(I)(A) of this section,
a metropolitan district that is a party to a lease or rental agreement that was
effective as of January 1, 2025, or later and was filed with the county
assessor's office in support of a claim for a property tax exemption in
accordance with subsection (1)(b)(I)(A) of this section shall also file with
the county assessor's office a statement describing: The metropolitan
district's use of the leased property; the metropolitan district's authority to
use the leased property for the metropolitan district's purposes; any use of
the leased property by a private person for private purposes; and any
disclosure filed by a member of the board of directors of the metropolitan district
in accordance with section 24-18-109 (3)(b), 24-18-110, 32-1-902, or 18-8-308.
(G) If
the statement described in subsection (1)(b)(I)(F) of this section includes a
disclosure that relates to the leased property and is filed by a member of the
board of directors of the metropolitan district in accordance with section
24-18-109 (3)(b), 24-18-110, 32-1-902, or 18-8-308, the county assessor shall,
within fourteen days of receipt of the statement, submit the statement to the
governing body that approved the metropolitan district's service plan and to
the metropolitan district. Within sixty-three days of receipt of the statement,
the governing body shall issue a written decision including findings of fact
and a conclusion as to whether the leased property is used for a public purpose
as required by subsection (1)(b)(I)(A) of this section. If the governing body
concludes that the leased property is not used for a public purpose as required
by subsection (1)(b)(I)(A) of this section, the leased property is not exempt
from taxation in accordance with subsection (1)(b)(I)(A) of this section, and
the county assessor shall implement the governing body's decision. A decision
of a governing body made pursuant to this section is not subject to appeal and
does not give rise to any private right of action.
(II) As
used in this subsection (1)(b), unless the context otherwise requires:
(A)
"Governing body" means the board of county commissioners or other
entity that approved the metropolitan district's service plan, or its
designees.
(B)
"Leased property" means a part of real property that is used by the
state, a political subdivision, or a state-supported institution of higher
education pursuant to the provisions of any lease or rental agreement for at
least a one-year term, with or without an option to purchase.
(C)
"Metropolitan district" means a metropolitan district created
pursuant to article 1 of title 32.
(D)
"State-supported institution of higher education" includes, but need
not be limited to, all postsecondary institutions in the state supported in
whole or in part by state funds, including community colleges, extension
programs of the state-supported universities and colleges, local district
colleges, area technical colleges, and the institutions governed by the regents
of the university of Colorado.
(2) A
leasehold interest in real or personal property that is owned by the state or
by a political subdivision of the state and that has been leased to a private
person, the use and possession of which has been leased back to the state or a
political subdivision of the state, shall be exempt from the levy and
collection of property tax during the term of the use and possession of the
property by the state or a political subdivision of the state. Property that is
the subject of a leveraged leasing agreement executed by the state or by a
political subdivision of the state shall be treated as tax-exempt property
owned by the state for purposes of any state or local tax.
(3) The
lease of property by a political subdivision of the state to a private person
and the sublease of the property back to the political subdivision of the state
pursuant to a leveraged leasing agreement shall not cause the private person to
whom the property has been leased to incur any liability in tort by virtue of
the private person's status as a lessor under the leveraged leasing agreement.
(4) A
leasehold interest in real or personal property that is owned by a private
person and that has been leased to the state or a political subdivision of the
state, the use and possession of which has been leased back to a private person
for private purposes, is taxable to the owner.
Source:
L. 89: Entire
article R&RE, p. 1477, § 1, effective April 23. L. 2003: Entire
section amended, p. 1720, § 3, effective May 14. L. 2008: (1) amended,
p. 1631, § 1, effective August 5. L. 2009: (1)(b)(I) amended, (HB
09-1365), ch. 320, p. 1710, § 1, effective June 1. L. 2016: (1)(b)(II)
amended, (HB 16-1082), ch. 58, p. 153, § 43, effective August 10. L. 2021:
(1)(a) amended, (HB 21-1316), ch. 325, p. 2062, § 77, effective July 1. L.
2025: (1)(b)(I)(A) and (1)(b)(II) amended and (1)(b)(I)(F), (1)(b)(I)(G),
and (4) added, (HB 25-1289), ch. 404, p. 2304, § 1, effective August 6.
Editor's
note: This section
is similar to former § 39-3-101 (1)(p) as it existed prior to 1989.
39-3-125. Church property - used as
residence - exemption - limitation. (Repealed)
Source:
L. 89: Entire
article R&RE, p. 1478, § 1, effective April 23; entire section repealed, p.
1492, § 9, effective June 7.
Editor's
note: Before its
repeal, this section was similar to former § 39-3-102 as it existed prior to
1989.
39-3-126. Horticultural improvements -
exemption - limitation - exception.
Any
increase in value of privately owned lands resulting from the planting of trees
shall not be taken into account in determining the actual value of such lands
for a period of thirty years from the date of planting such trees. This section
shall apply to all lands so planted; however, in the event that any trees
become sufficiently mature as to be of economic use and value prior to the
expiration of thirty years, any increase in use and value shall be thereafter
taken into account in determining the actual value of such lands.
Source:
L. 89: Entire
article R&RE, p. 1478, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-103 as it existed prior to 1989.
39-3-126.5. Mobile homes - low-value -
exemption - legislative declaration - definition.
(1) The
general assembly hereby finds and declares that:
(a)
Mobile homes are unique properties that are subject to the ad valorem tax as if
they are real property, but the tax is collected as if they are personal
property;
(b) The
actual value of mobile homes can be quite low compared to other residential
real property improvements;
(c) For
these low-value mobile homes, the actual collection costs attributable to a
county assessor and county treasurer may exceed the total amount of taxes
collected;
(d) If
the taxes owed on these mobile homes become delinquent, then all of the
additional collection costs may exceed the taxes owed; and
(e)
This exemption will only have a de minimis impact on local government revenues.
(2) As
used in this section, "mobile home" means a mobile home as defined in
section 39-1-102 (8) or a "manufactured home" as defined in section
39-1-102 (7.8) and, in either case, for which a certificate of title has been
issued pursuant to part 1 of article 29 of title 38 and that does not have a
certificate of permanent location pursuant to section 38-29-202.
(3) For
property tax years commencing on or after January 1, 2022, a mobile home with
an actual value that is less than or equal to twenty-eight thousand dollars is
exempt from the levy and collection of property tax.
Source:
L. 2022: Entire
section added, (HB 22-1223), ch. 308, p. 2219, § 1, effective August 10.
39-3-127. County fair property -
exemption - limitation.
Property,
real and personal, of any association duly organized pursuant to the laws of
this state for the purpose of holding county fairs to promote and advance the
interests of agriculture, horticulture, animal husbandry, home economics, and
the mechanical attributes thereof shall be exempt from the levy and collection
of property tax so long as such property is actually and exclusively used for
said purpose and not for pecuniary profit.
Source:
L. 89: Entire
article R&RE, p. 1478, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-104 as it existed prior to 1989.
39-3-127.5. Qualifying business entities
- participation in federal tax credit transactions - exemption - requirements -
definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Qualified business entity" means a limited partnership or a limited
liability company:
(I)
That is formed for the purpose of obtaining federal tax credits and that does
obtain such credits; and
(II)
The general partner or managing member of which is an entity that would qualify
for property tax exemption under sections 39-3-106 to 39-3-113.5.
(2) For
property tax years beginning on or after January 1, 2014, real and personal
property is exempt from the levy and collection of property tax if:
(a) The
property tax is owed by a qualified business entity; and
(b) The
property is used for the purposes described in sections 39-3-106 to 39-3-113.5
and 39-3-116.
(3) In
addition to any other requirement specified in this section, any exemption
claimed pursuant to the provisions of this section must also comply with
section 39-2-117.
Source:
L. 2014: Entire
section added, (HB 14-1349), ch. 230, p. 853, § 1, effective May 17.
39-3-127.7. Community land trust
property - nonprofit affordable homeownership developer property - exemption -
requirements - legislative declaration - definitions.
(1) (a)
The general assembly hereby finds and declares that:
(I) The
cost of homeownership has risen dramatically in Colorado: From December 2020 to
December 2022, the median home value in Colorado increased over thirty percent;
(II)
Entry-level homeownership options are increasingly unavailable, and community
land trusts and nonprofit affordable homeownership developers are playing an
increasingly large role in helping low- and middle-income Coloradans access
homeownership; and
(III)
Compared to tools used to incentivize affordable rental housing, such as the
low-income housing tax credit, there are fewer tools to incentivize the
creation of affordable for-sale housing.
(b)
Therefore, it is the intent of the general assembly to provide a limited
property tax exemption to community land trusts and nonprofit affordable
homeownership developers in certain circumstances.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Affordable homeownership property" means any dwelling that:
(I) Is
restricted by a deed that impacts ownership of the property, limits the
property's resale price, requires a long-term land lease with a community land
trust or nonprofit affordable homeownership developer, or imposes any other
restriction that limits the property such that it may only be purchased by
designated households, a community land trust, or a nonprofit affordable
homeownership developer;
(II) Is
sold to a household that at the time of purchase is at or below one hundred
percent of the area median income of households of that same size in the county
in which the housing is located; and
(III)
Is sold to a purchaser to be used as a primary residence.
(b)
"Community land trust" means a nonprofit organization that is exempt
from taxation under section 501 (c)(3) of the federal "Internal Revenue
Code of 1986", as amended, and is designed to ensure long-term housing
affordability through a shared-equity model by acquiring and maintaining
ownership of real property, while selling the improvements to low-to-middle
income households for use as a primary residence.
(c)
"Improvement" means a permanent change to real property that augments
the real property's value including but not limited to a single-family home,
townhome, or condominium.
(d)
"Land lease" means a long-term lease used in affordable homeownership
properties to lease the real property that is owned by a community land trust
or nonprofit affordable homeownership developer to the owner of the
improvements on the real property and preserve the improvements as an
affordable homeownership property.
(e)
"Nonprofit affordable homeownership developer" means an organization
that is exempt from federal income tax pursuant to section 501 (c)(3) of the
federal "Internal Revenue Code of 1986", as amended, and that has a
primary organizational mission of providing for-sale affordable housing units
to low-to-middle income households for use as a primary residence.
(3) (a)
For property tax years commencing on or after January 1, 2024, real property is
deemed to be used for a strictly charitable purpose, and is exempt from
property taxation in accordance with section 5 of article X of the state
constitution, if the real property:
(I) Is
held by either a community land trust or a nonprofit affordable homeownership
developer;
(II)
Has been split into a separate taxable parcel from the improvements; and
(III)
Is leased to the owner of the improvements as an affordable homeownership
property.
(b) The
real property described in subsection (3)(a) of this section is deemed to be
used for a strictly charitable purpose, and is exempt from property taxation in
accordance with section 5 of article X of the state constitution, until the
real property is no longer used as an affordable homeownership property.
(4) If
a community land trust or nonprofit affordable homeownership developer claims a
property tax exemption pursuant to this section for a real property and then
subsequently sells, donates, or leases that real property so that the real
property no longer qualifies as an affordable homeownership property, the
community land trust or nonprofit affordable homeownership developer is liable
for all property taxes for the real property for the property tax years when
the real property did not qualify as an affordable homeownership property and
during which the community land trust or nonprofit affordable homeownership
developer did not pay property taxes for the real property due to the property
tax exemption described in this section.
(5)
Improvements on real property that qualifies for the property tax exemption
described in this section are not exempt from property taxation.
(6) A
community land trust or nonprofit affordable home ownership developer that owns
real property that qualifies for the property tax exemption described in this
section shall submit the land lease for each real property that qualifies for
the property tax exemption described in this section to the appropriate county
assessor within twenty-five days of the initial execution of the land lease.
(7) (a)
Any community land trust or nonprofit affordable homeownership developer that
claims a property tax exemption pursuant to this section shall comply with the
provisions of section 39-2-117; except that, if the real property that is
allowed an exemption pursuant to this section has been subdivided, the owner of
such property or the owner's agent is only required to:
(I)
Submit one application for the exemption for all parcels in connection with the
subdivision pursuant to section 39-2-117 (1)(a), but the filing must be
accompanied by a payment in accordance with section 39-2-117 (1)(a)(I) in an
amount not to exceed the aggregate amount of payments that would be required if
individual applications were filed for each parcel; and
(II) If
the exemption is granted, file one annual report pursuant to section 39-2-117
(3)(a) for all parcels in connection with the subdivision, but the filing must
be accompanied by a payment in accordance with section 39-2-117 (3)(a) in an
amount not to exceed the aggregate amount of payments that would be required if
individual reports were filed for each parcel.
(b)
Notwithstanding subsection (7)(a)(II) of this section, if the real property
that is allowed an exemption pursuant to this section has been subdivided but
the subdivided parcel has been split into a separate taxable parcel from the
improvements and is leased to the owner of the improvements as an affordable
homeownership property, then the owner of such real property or the owner's
agent must file an individual annual report for the subdivided parcel in
accordance with section 39-2-117 (3)(a).
Source:
L. 2023: Entire
section added, (HB 23-1184), ch. 260, p. 1505, § 3, effective August 7. L.
2024: (7) amended, (HB 24-1308), ch. 295, p. 2016, § 14, effective August
7.
Cross
references: For
the legislative declaration in HB 24-1308, see section 1 of chapter 295,
Session Laws of Colorado 2024.
ANNOTATION
Law reviews. For
article, "Affordable Housing Tax Exemptions in Colorado", see 54
Colo. Law. 32 (Dec. 2025).
39-3-128. Exempt property listed and
valued.
It is the
duty of the assessor to list, appraise, and value all real property exempted
from the levy and collection of property tax pursuant to the provisions of
sections 39-3-106 to 39-3-113.5 or 39-3-116, and such information shall be
entered in the same detail as required for taxable property.
Source:
L. 89: Entire
article R&RE, p. 1478, § 1, effective April 23; entire section amended, p.
1492, § 8, effective June 7. L. 2013: Entire section amended, (HB
13-1300), ch. 316, p. 1705, § 122, effective August 7. L. 2016: Entire
section amended, (SB 16-189), ch. 210, p. 792, § 106, effective June 6.
Editor's
note: This section
is similar to former § 39-3-105 as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-128 is similar to § 39-3-105 as it existed prior to the 1989 repeal and
reenactment of this article, a relevant case construing that provision has been
included in the annotations to this section.
When taxpayer may institute
declaratory action to test right to exemption. Where property has been
exempted by law from taxation and where a municipality attempts to tax that
property, the taxpayer may institute a declaratory action to test the right of
his property to be exempted from such taxes. City & County of Denver v.
Spears Free Clinic Hosp. for Poor Children, 142 Colo. 347, 350 P.2d 1057
(1960).
Injunction may issue to
prevent collection of taxes on exempt property. City & County of Denver
v. Spears Free Clinic Hosp. for Poor Children, 142 Colo. 347, 350 P.2d 1057
(1960).
39-3-129. Proportional valuation -
exempt property.
(1)
Except as otherwise provided in subsection (2) of this section, whenever any
real property that was previously taxable becomes legally exempt from the levy
and collection of property tax or any real property that was previously legally
exempt from the levy and collection of property tax becomes taxable, the
valuation for assessment of the real property shall be a proportion of the
valuation for assessment of the real property for the entire taxable year based
upon the ratio of the portion of the taxable year in which the property is
taxable to the entire taxable year. In the event the real property is partially
leased, loaned, or otherwise made available to and used by a business conducted
for profit, the determination as to what portion of the real property is so
utilized shall be made by the administrator on the basis of the facts existing
on the annual assessment date for the real property. The administrator shall
have the authority to determine the actual value of the nonexempt portion of
the property in relation to the actual value of the entire property by using
the ratio of the square foot area of the property utilized by the business
conducted for profit to the total square foot area of the property. Where shown
to be more appropriate, in order to determine the relationship between the
actual value of the nonexempt portion of the property and the actual value of
the total property, the administrator may employ the ratio of the portion as
measured in hours of any calendar year in which the property is leased, loaned,
or otherwise made available to and used by any business conducted for profit to
the entire calendar year.
(2) The
provisions of subsection (1) of this section shall not be applicable to
household furnishings.
Source:
L. 89: Entire
article R&RE, p. 1478, § 1, effective April 23. L. 96: (1) amended,
p. 44, § 2, effective March 20; (1) amended, p. 1200, § 4, effective June 1.
Editor's
note: (1) This
section is similar to former § 39-3-106 as it existed prior to 1989.
(2) Amendments to subsection
(1) by Senate Bill 96-006 and House Bill 96-1113 were harmonized.
Cross
references: For
the legislative declaration contained in the 1996 act amending subsection (1),
see section 1 of chapter 16, Session Laws of Colorado 1996.
39-3-130. Change in tax status of
property - effective date - tax liability.
(1) (a)
(I) Whenever any real property that was previously taxable becomes legally
exempt from the levy and collection of property tax for any reason, the person
conveying the real property shall be relieved from all further tax obligations
with respect to the real property on the date title thereto is conveyed by
agreement or on the date title thereto is conveyed pursuant to a court order.
(II) On
and after January 1, 1996, whenever any personal property that was previously
taxable becomes legally exempt from the levy and collection of property tax for
any reason, the exempt status shall become effective on the assessment date
following the change in status. If the change in status occurred due to the
conveyance of the personal property, the person conveying the personal property
shall not be relieved of any tax obligation with respect to the personal
property for the property tax year in which the conveyance occurred.
(b) (I)
Except as otherwise provided in subsection (2) of this section, whenever any
real property that was previously exempt from the levy and collection of
property tax becomes taxable, the person acquiring title to the real property
shall be liable for subsequent tax obligations with respect to the real
property on the date title thereto is acquired by the person.
(II) On
and after January 1, 1996, except as otherwise provided in subsection (2) of
this section, whenever any personal property that was previously exempt from
the levy and collection of property tax becomes taxable, the taxable status
shall become effective on the assessment date following the change in status.
If the change in status occurred due to conveyance of the personal property,
the person acquiring title to the personal property shall not be liable for any
tax obligation with respect to the personal property for the property tax year
in which the conveyance occurred.
(2)
Whenever any personal property consisting of inventory, as defined in section
39-1-102 (7.2), becomes taxable because the personal property has become
subject to a lease or rental agreement, the lessor shall not be responsible for
any tax obligation on the property for the property tax year in which the
agreement was executed.
Source:
L. 89: Entire
article R&RE, p. 1479, § 1, effective April 23. L. 96: Entire
section amended, p. 45, § 3, effective March 20.
Editor's
note: This section
is similar to former § 39-3-107 as it existed prior to 1989.
Cross
references: For
the legislative declaration contained in the 1996 act amending this section,
see section 1 of chapter 16, Session Laws of Colorado 1996.
39-3-131. Entire property becomes
tax-exempt.
Whenever
any property which was previously taxable becomes exempt from the levy and
collection of property tax, the treasurer shall accept payment of property
taxes levied on such property for the current taxable year. The amount of such
property taxes shall be calculated on the basis of the property tax levy on
such property in the preceding taxable year and prorated to the date upon which
title to such property was conveyed.
Source:
L. 89: Entire
article R&RE, p. 1479, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-108 as it existed prior to 1989.
39-3-132. Portion of property becomes
tax-exempt.
Whenever
only a portion of a parcel, tract, or lot of real property which was previously
taxable becomes exempt from the levy and collection of property tax for any
reason, the treasurer may, upon the basis of an appraisal and computation of
the valuation for assessment of such property by the assessor, either collect
the property taxes thereon for the current taxable year, calculated on the
basis of the property tax levy on such property during the preceding taxable
year and prorated to the date upon which title to such property was conveyed,
or, if the treasurer is satisfied that there is sufficient taxable real
property remaining to satisfy any lien for the amount of property taxes payable
on such portion, he may defer collection of the property taxes until the
following taxable year. In the event the prorated taxes on such portion are
collected, the owner of the remainder of such real property shall be credited
with the full amount of taxes collected when the property tax levy for the
current taxable year has been fixed and made and the correct amount of property
taxes determined.
Source:
L. 89: Entire
article R&RE, p. 1479, § 1, effective April 23.
Editor's
note: This section
is similar to former § 39-3-109 as it existed prior to 1989.
ANNOTATION
Where proportionate part of
building exempt, proportionate part of lot exempt. If a certain
proportionate part of a building is exempted under an equitable apportionment
of its use as to charitable and noncharitable purposes, then a similar
equitable apportionment as to charitable and noncharitable uses must be made as
to the lot that supports it. Hanagan v. Rocky Ford Knights of Pythias Bldg.
Ass'n, 101 Colo. 545, 75 P.2d 780 (1938) (decided under former law).
39-3-133. Payment of property taxes
extinguishes lien.
Payment to
the treasurer of prorated property taxes for the current taxable year, as
provided for in sections 39-3-131 and 39-3-132, together with payment of any
other unpaid property taxes, delinquent interest, or charges thereon, shall
extinguish the lien for property taxes on such property, or a portion thereof;
however, if only a portion of any parcel, tract, or lot of real property
becomes exempt from the levy and collection of property tax and no property
taxes are collected at that time, the lien of property taxes levied or to be
levied shall attach to the remaining portion of such real property.
Source:
L. 89: Entire
article R&RE, p. 1479, § 1, effective April 23. L. 92: Entire
section amended, p. 2223, § 4, effective April 9.
Editor's
note: This section
is similar to former § 39-3-110 as it existed prior to 1989.
39-3-134. Condemnation by tax-exempt
agency - duties of treasurer.
In all
cases where an entire property, or a portion of any parcel, tract, or lot of
real property, is likely to become exempt from the levy and collection of
property tax through exercise of the power of eminent domain, the treasurer
shall be joined as a party respondent in any such eminent domain action, and,
upon joinder and notice of the proceedings, the treasurer shall assert a claim
for the amount of any prorated property taxes for the current taxable year on
such property, and all other unpaid property taxes, delinquent interest, or
charges thereon, with the clerk of the court in which the proceedings are
filed. Upon institution of any such proceedings, the lien of property taxes
levied and to be levied shall be transferred from the real property acquired or
sought to be acquired to any money awarded or to be awarded for the taking of
such real property. Nothing in this section shall require any treasurer to file
a claim in any such proceedings involving acquisition of only a portion of any
real property if the treasurer is satisfied that there is sufficient taxable
real property remaining after the taking of such portion to satisfy any lien
for the amount of property taxes payable on such portion taken.
Source:
L. 89: Entire
article R&RE, p. 1480, § 1, effective April 23. L. 92: Entire
section amended, p. 2224, § 5, effective April 9.
Editor's
note: This section
is similar to former § 39-3-111 as it existed prior to 1989.
ANNOTATION
Annotator's note. Since
§ 39-3-134 is similar to § 39-3-111 as it existed prior to the 1989 repeal and
reenactment of this article, relevant cases construing that provision have been
included in the annotations to this section.
Burden of joining county
treasurer in proceeding. This section places the burden of joining the
county treasurer on the condemning authority. Hayden v. Bd. of County Comm'rs,
41 Colo. App. 102, 580 P.2d 830 (1978).
Applied in Southworth v.
Dept. of Hwys., 176 Colo. 82, 489 P.2d 204 (1971).
39-3-135. Taxation of exempt property
- taxes not to become lien. (Repealed)
Source:
L. 89: Entire
article R&RE, p. 1480, § 1, effective April 23. L. 96: Entire
section repealed, p. 1851, § 3, effective June 5.
Editor's
note: Before its
repeal, this section was similar to former § 39-3-112 as it existed prior to
1989.
39-3-136. Legislative declaration -
taxation of exempt property - possessory interests. (Repealed)
Source:
L. 96: Entire
section added, p. 1849, § 1, effective June 5. L. 2002: (2) amended, p.
1032, § 68, effective June 1; entire section repealed, p. 1009, § 6, effective
August 7.
39-3-137. Organizations with
tax-exempt status - forgiveness of taxes owed.
(1)
Subject to the provisions of subsection (2) of this section, any organization
that, as of August 5, 2008, owes taxes that have been levied on real or
personal property shall not be required to pay the balance of the taxes owed on
or after August 5, 2008, if the organization meets the following requirements:
(a) The
organization is a religious, charitable, or educational organization exempt
from general taxation on real and personal property pursuant to sections
39-3-106 to 39-3-113.5 and 39-3-116;
(b) The
organization has, before August 5, 2008, filed an application for exemption and
been granted an exemption from general taxation on real and personal property
pursuant to section 39-2-117;
(c) The
organization has, before August 5, 2008, and after receiving an exemption from
property tax, filed an annual report required for the continuation of property
tax-exempt status pursuant to section 39-2-117 (3), but the report was
determined to be incomplete or otherwise incorrect when filed; and
(d) The
organization, as a result of the incomplete or incorrect report referenced in
paragraph (c) of this subsection (1), was denied tax-exempt status for one or
more property tax years and received a property tax bill for such year or
years.
(2) Any
waiver of the balance of taxes owed by an organization pursuant to subsection
(1) of this section shall be contingent upon the reestablishment of the
organization's tax-exempt status by the property tax administrator, as
authorized by the state board of equalization.
(3) The
state board of equalization may authorize the property tax administrator to
reestablish tax-exempt status for any organization that meets the criteria
specified in paragraphs (a) to (d) of subsection (1) of this section and that
paid all or any portion of a property tax bill for a year or years in which the
organization was denied tax-exempt status.
Source:
L. 2008: Entire
section added, p. 457, § 1, effective August 5. L. 2009: (2) and (3)
amended, (SB 09-042), ch. 176, p. 782, § 5, effective August 5. L. 2013:
(1)(a) amended, (HB 13-1300), ch. 316, p. 1705, § 123, effective August 7.
39-3-138. EV supply equipment -
exemption.
For
property tax years commencing on and after January 1, 2023, but before January
1, 2030, an electric vehicle charging system, as defined in section 38-12-601
(6)(a), is exempt from the levy and collection of property tax.
Source:
L. 2023: Entire
section added, (HB 23-1233), ch. 245, p. 1327, § 12, effective May 23.
Cross
references: For
the legislative declaration in HB 23-1233, see section 1 of chapter 245,
Session Laws of Colorado 2023.
39-3-139. Property tax relief for
communication services deployment - legislative declaration - definitions.
(1) The
general assembly finds and declares that:
(a) The
intended purpose of the tax relief created in this section is to encourage the
deployment of communication services infrastructure throughout the state,
particularly in rural, unserved, and underserved areas, and to create
incentives for investments in new communication services infrastructure in
addition to incentives already created by other state or federal law;
(b)
Financial incentives in the form of tax relief are necessary to attract
investment and free up resources for communication services deployment,
particularly in areas that have been designated as unserved or underserved. The
incentives can be particularly effective when offered at the local level by
counties that have the authority to approve the relief based on specific
criteria.
(c)
Providing tax relief stimulates economic development in the state and supports
the expansion of essential communication services to unserved and underserved
areas; and
(d)
Wireless telecommunications technologies, while seemingly independent,
critically rely on forms of broadband like fiber and landline networks for
essential functions, such as backhaul, which connects cell towers to the
internet backbone and which is often performed by nonwireless providers.
Therefore, the policies that impact broadband infrastructure must consider the
interconnectedness of all technologies, including the dependence of wireless
telecommunications on the broader ecosystem, to ensure effective and
comprehensive wireless and broadband access for all Coloradans.
(2) As
used in this section, unless the context otherwise requires:
(a)
"County" means a county or a city and county.
(b) (I)
"Qualified communication services facility" means any facility,
infrastructure, equipment, or other real or personal property used in the
provision of fixed broadband or mobile broadband internet access service, as
defined by the federal communications commission, and includes, but is not
limited to:
(A)
Asynchronous transfer mode switches;
(B)
Digital subscriber line access multiplexers;
(C)
Routers;
(D)
Servers;
(E)
Multiplexers;
(F)
Fiber optics; and
(G) Any
related equipment.
(II)
"Qualified communication services facility" includes any
infrastructure or equipment used to provide fixed or mobile wireless broadband
internet access service, including, but not limited to, macro cell towers and
microcell towers.
(c)
"Underserved area" means a geographic area in which broadband
internet access service is not available from more than one provider at speeds
meeting or exceeding the minimum broadband benchmarks established by the
federal communications commission for fixed broadband or mobile broadband. A
county shall determine whether an area is underserved by reference to the
federal communications commission broadband coverage maps available as of
January 1 in the calendar year in which the county and the taxpayer negotiate
an incentive payment or credit.
(d)
"Unserved area" means a geographic area in which broadband internet
access service is not available from any provider at speeds meeting or
exceeding the minimum broadband benchmarks established by the federal
communications commission for fixed broadband and mobile broadband. A county
shall determine whether an area is unserved by reference to the federal
communications commission broadband coverage maps available as of January 1 in
the calendar year in which the county and the taxpayer negotiate an incentive
payment or credit.
(3) (a)
Notwithstanding any law to the contrary, a county may negotiate an incentive
payment or credit with a taxpayer that establishes or expands a qualified
communication services facility in the county if the facility serves an
unserved or underserved area.
(b) The
burden is on a taxpayer seeking tax relief to demonstrate, to the satisfaction
of the county, that the area to be served by the proposed investment is an
unserved or underserved area. The taxpayer shall rely on the federal
communications commission broadband coverage maps available as of January 1 in
the calendar year in which the county and the taxpayer negotiate an incentive
payment or credit to make the determination.
(c) A
county shall not negotiate an incentive payment or credit that exceeds the
amount of the taxes levied by the county upon the taxable real property or
business personal property located at or within the qualified communication
services facility for the current property tax year.
(4) A
county shall exercise the authority granted under this section in a
nondiscriminatory, nonexclusive, and competitively neutral manner. To the
extent that a county awards an incentive payment or credit under this section,
the county shall award subsequent incentive payments or credits under similar
terms and conditions as the initial award and based on a proportionate level of
investment in a qualified communication services facility in the county.
(5) A
county that negotiates an agreement pursuant to this section shall inform any
municipality, special district as defined in section 32-1-103, and school
district in which the qualified communication services facility will be
established or expanded of the negotiations with the taxpayer.
(6) A
county may adjust the amount of its tax levy authorized pursuant to section
29-1-301 or pursuant to a county home rule charter, whichever is applicable, by
an additional amount that does not exceed the total amount of annual incentive
payments or credits that the county makes.
Source:
L. 2025: Entire
section added, (HB 25-1080), ch. 317, p. 1653, § 1, effective August 6.
PART
2
PROPERTY
TAX EXEMPTION FOR QUALIFYING SENIORS AND DISABLED VETERANS
39-3-201. Legislative declaration.
(1) The
general assembly hereby finds and declares that:
(a)
Section 3.5 of article X of the state constitution, which was approved by the
registered electors of the state at the 2000 general election and amended by
the registered electors of the state at the 2006 general election, provides
property tax exemptions for a qualifying senior and for a qualifying
"disabled veteran", defined, in accordance with the "people
first language" requirements of section 2-2-802, in section 39-3-202 (3.5)
as a "qualifying veteran with a disability" for purposes of this part
2;
(b) It
is within the legislative prerogative of the general assembly to enact
legislation to implement section 3.5 of article X of the state constitution
that will ensure compliance with the requirements of said section and
facilitate its operation;
(c) In
enacting legislation to implement section 3.5 of article X of the state
constitution the general assembly has attempted to interpret the provisions of
section 3.5 of article X of the state constitution in a manner that gives its
words their natural and obvious significance;
(d)
This part 2 reflects the considered judgment of the general assembly regarding
the meaning and implementation of the provisions of section 3.5 of article X of
the state constitution.
Source:
L. 2001: Entire
part added, p. 460, § 1, effective April 25. L. 2007: (1)(a) amended, p.
476, § 1, effective April 15. L. 2023: (1)(a) amended, (SB 23-036), ch.
345, p. 2068, § 1, effective June 5; (1)(a) amended, (SB 23-1052), ch. 131, p.
499, § 3, effective January 1, 2025.
Editor's
note: Subsection
(1)(a) was amended in HB 23-1052, effective January 1, 2025. However, those
amendments were superseded by the amendments to subsection (1)(a) by SB 23-036,
effective June 5, 2023.
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-202. Definitions.
As used in
this part 2, unless the context otherwise requires:
(1)
"Division" means the division of veterans affairs in the department
of military and veterans affairs.
(1.5)
"Exemption" means the property tax exemptions for qualifying seniors
and qualifying veterans with a disability allowed by section 39-3-203.
(2) (a)
"Owner-occupier" means an individual who:
(I) Is
an owner of record of residential real property that he or she occupies as his
or her primary residence;
(II) Is
not an owner of record of the residential real property that he or she occupies
as his or her primary residence, but is:
(A) The
spouse of an individual who is an owner of record of the residential real
property and who also occupies the residential real property as his or her
primary residence; or
(B) The
surviving spouse of an individual who was an owner of record of the residential
real property and who occupied the residential real property with the surviving
spouse as his or her primary residence until his or her death; or
(III)
Is not an owner of record of the residential real property that he or she
occupies as his or her primary residence, only because the property has been
purchased by or transferred to a trust, a corporate partnership, or any other
legal entity solely for estate planning purposes and is the maker of the trust
or a principal of the corporate partnership or other legal entity;
(IV)
(A) Occupies residential real property as his or her primary residence; and
(B) Is
the spouse of a person who also occupies the residential real property, who is
not the owner of record of the property only because the property has been
purchased by or transferred to a trust, a corporate partnership, or any other
legal entity solely for estate planning purposes, and who is the maker of the
trust or a principal of the corporate partnership or other legal entity; and
(V) (A)
Occupies residential real property as his or her primary residence; and
(B) Is
the surviving spouse of a person who occupied the residential real property
with the surviving spouse until his or her death, who was not the owner of
record of the property at the time of his or her death only because the
property had been purchased by or transferred to a trust, a corporate
partnership, or any other legal entity solely for estate planning purposes
prior to his or her death, and who was the maker of the trust or a principal of
the corporate partnership or other legal entity prior to his or her death.
(b)
"Owner-occupier" also includes any individual who, but for the
confinement of the individual to a hospital, nursing home, or assisted living
facility, would occupy residential real property as his or her primary
residence and would meet one or more of the ownership criteria specified in
paragraph (a) of this subsection (2), if the residential real property:
(I) Is
temporarily unoccupied; or
(II) Is
occupied by the spouse or a financial dependent of the individual.
(3)
"Owner of record" means an individual whose name appears on a valid
recorded deed to residential real property as an owner of the property.
(3.3)
"Proof of qualifying veteran with a disability status" means
documentary evidence from the United States department of veterans affairs that
an individual is a qualifying veteran with a disability, as defined in
subsection (3.5) of this section. The division shall develop guidelines that
specify the documentary evidence from the United States department of veterans
affairs that is required to establish proof of qualifying veteran with a
disability status.
(3.5)
"Qualifying veteran with a disability" means an individual who has
served on active duty in the United States armed forces, including a member of
the Colorado National Guard who has been ordered into the active military
service of the United States, has been separated therefrom under honorable
conditions, and has either established a service-connected disability that has
been rated by the United States department of veterans affairs as a one hundred
percent permanent disability through disability retirement benefits pursuant to
a law or regulation administered by the department, the United States
department of homeland security, or the department of the Army, Navy, or Air
Force or has individual unemployability status as determined by the United States
department of veterans affairs.
(4)
"Surviving spouse" means an individual who was legally married to
another individual at the time of the other individual's death and who has not
remarried.
Source:
L. 2001: Entire
part added, p. 461, § 1, effective April 25. L. 2007: (1) amended and
(1.5) and (3.5) added, p. 476, § 2, effective April 15. L. 2016: (3.5)
amended, (HB 16-1444), ch. 193, p. 682, § 1, effective July 1. L. 2023:
(1.5) and (3.5) amended and (3.3) added, (SB 23-036), ch. 345, p. 2068, § 2,
effective June 5; (1.5) and (3.5) amended, (HB 23-1052), ch. 131, p. 499, § 4,
effective January 1, 2025, (see editor's note).
Editor's
note: (1)
Amendments to subsection (3.5) by HB 23-1052 and SB 23-036 were harmonized,
effective only if a constitutional amendment to section 3.5 (1.5) of article X
of the state constitution that modifies the definition of "disabled
veteran" by changing the term to "veteran with a disability" and
including a veteran who has individual unemployability status as determined by
the United States department of veterans affairs is approved by the people at
the next general election and becomes law. The measure modifying the definition
of "disabled veteran" by changing the term to "veteran with a
disability" and including a veteran who has individual unemployability
status as determined by the United States department of veterans affairs was
referred to the voters as Amendment G. That measure was approved by a vote of
the registered electors of Colorado on November 5, 2024, and was proclaimed by
the governor on December 17, 2024, see L. 2025, p. 3631. Amendments to
subsection (3.5) by HB 23-1052 and SB 23-036 were effective January 1, 2025.
The vote count for the measure was as follows:
FOR: 2,212,022
AGAINST: 812,638
(2) Section 11(3) of chapter
131 (HB 23-1052), Session Laws of Colorado 2023, provides that the act amending
this section takes effect only if a constitutional amendment to section 3.5
(1.5) of article X of the state constitution that modifies the definition of
"disabled veteran" is approved at the general election to be held in
November 2024, and, in such case, takes effect January 1, 2025. The measure
modifying the definition of "disabled veteran" was referred to the
voters as Amendment G. That measure was approved by a vote of the registered
electors of Colorado on November 5, 2024, and was proclaimed by the governor on
December 17, 2024, see L. 2025, p. 3631. Amendments to this section were
effective January 1, 2025. The vote count for the measure was as follows:
FOR: 2,212,022
AGAINST: 812,638
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-203. Property tax exemption -
qualifications.
(1) For
the property tax year commencing January 1, 2002, for property tax years
commencing on or after January 1, 2006, but before January 1, 2009, and for
property tax years commencing on or after January 1, 2012, fifty percent of the
first two hundred thousand dollars of actual value of residential real property
that as of the assessment date is owner-occupied and is used as the primary
residence of the owner-occupier shall be exempt from taxation, and for property
tax years commencing on or after January 1, 2003, but before January 1, 2006,
and on or after January 1, 2009, but before January 1, 2012, fifty percent of
zero dollars of actual value of residential real property that as of the
assessment date is owner-occupied and is used as the primary residence of the
owner-occupier shall be exempt from taxation if:
(a) (I)
The owner-occupier is sixty-five years of age or older as of the assessment
date and has owned and occupied such residential real property as his or her
primary residence for the ten years preceding the assessment date; or
(II)
The owner-occupier is the surviving spouse of an owner-occupier who previously
qualified for a property tax exemption for the same residential real property
under subparagraph (I) of this paragraph (a); and
(b) The
owner-occupier has completed and filed an exemption application in the manner
required by section 39-3-205 and the circumstances that qualify the property
for the exemption have not changed since the filing of the application. Under
no circumstances shall an exemption be allowed for property taxes assessed
during any property tax year prior to the year in which an owner-occupier first
files an exemption application.
(1.5)
(a) For property tax years commencing on or after January 1, 2007, fifty
percent of the first two hundred thousand dollars of actual value of
residential real property that as of the assessment date is owner-occupied and
is used as the primary residence of an owner-occupier who is a qualifying
veteran with a disability shall be exempt from taxation if:
(I) The
owner-occupier has completed and filed an exemption application in the manner
required by section 39-3-205; and
(II)
The circumstances that qualify the property for the exemption have not changed
since the filing of the application.
(a.5)
For property tax years commencing on or after January 1, 2015, fifty percent of
the first two hundred thousand dollars of actual value of residential real
property that as of the assessment date is owner-occupied and is used as the
primary residence of an owner-occupier who is the surviving spouse of a
qualifying veteran with a disability who previously received an exemption under
subsection (1.5)(a) of this section is exempt from taxation.
(b)
Under no circumstances shall an exemption be allowed for property taxes
assessed during any property tax year prior to the year for which an
owner-occupier first files an exemption application.
(2)
Notwithstanding the provisions of paragraph (a) of subsection (1) and
subsection (1.5) of this section, if ownership of residential real property
that qualified for an exemption as of the assessment date changes after the
assessment date, an exemption shall be allowed only if an owner-occupier whose
status as an owner-occupier qualified the property for the exemption has filed
an exemption application by the deadline for filing exemption applications
specified in section 39-3-205 (1).
(3) An
individual who owns and occupies a dwelling unit in a common interest
community, as defined in section 38-33.3-103 (8), C.R.S., as his or her primary
residence, or who owns residential real property consisting of
multiple-dwelling units and occupies one of the dwelling units as his or her
primary residence, shall be allowed an exemption only with respect to the
dwelling unit that the individual occupies as his or her primary residence.
(4) No
more than one exemption per property tax year shall be allowed for a single
dwelling unit of residential real property, regardless of how many
owner-occupiers use the dwelling unit as their primary residence or whether one
or more owner-occupiers qualify for exemptions under both subsections (1) and
(1.5) of this section. The full amount of the exemption allowed by subsection
(1) or (1.5) of this section shall be allowed with respect to any single
dwelling unit of residential real property so long as any owner-occupier of the
dwelling unit satisfies the requirements of subsection (1) or (1.5) of this
section, and the fact that any other person who does not satisfy said
requirements is also an owner of record of the dwelling unit shall not affect the
amount of the exemption.
(5) For
purposes of this part 2, two individuals who are legally married, but who own
more than one piece of residential real property, shall be deemed to occupy the
same primary residence and may claim no more than one exemption.
(6) (a)
Notwithstanding the ten-year occupancy requirement set forth in subparagraph
(I) of paragraph (a) of subsection (1) of this section, an owner-occupier who
has not actually owned and occupied residential real property for which the
owner-occupier has claimed an exemption under said subsection (1) for the ten
years preceding the assessment date shall be deemed to have met the ten-year
requirement and shall be allowed an exemption under said subsection (1) with
respect to the property if:
(I) The
owner-occupier would have qualified for the exemption with respect to other
residential real property that the owner-occupier owned and occupied as his or
her primary residence before moving to the residential real property for which
an exemption is claimed but for the fact that the other property was condemned
by a governmental entity through an eminent domain proceeding; or
(I.5)
For property tax years commencing on or after January 1, 2015, the
owner-occupier would have qualified for the exemption with respect to other
residential real property that the owner-occupier owned and occupied as his or
her primary residence before moving to the residential real property for which
an exemption is claimed but for the fact that a natural disaster destroyed the
former primary residence or otherwise rendered it uninhabitable; and
(II)
The owner-occupier has not owned and occupied residential property as his or
her primary residence other than the residential real property for which an
exemption is claimed since the condemnation occurred.
(b) An
owner-occupier who claims an exemption with respect to residential real
property that he or she has not actually owned and occupied as his or her
primary residence for the ten years preceding the assessment date as permitted
by paragraph (a) of this subsection (6) shall provide to the assessor with whom
the owner-occupier files the exemption application any information that the
assessor may reasonably require to verify that the owner-occupier is entitled
to an exemption.
Source:
L. 2001: Entire
part added, p. 462, § 1, effective April 25. L. 2003: IP(1) amended, p.
1476, § 1, effective May 1. L. 2007: IP(1), (2), (4), and IP(6)(a)
amended and (1.5) added, p. 477, § 3, effective April 15. L. 2009: IP(1)
amended, (SB 09-276), ch. 437, p. 2426, § 1, effective June 4. L. 2010:
IP(1) amended, (SB 10-190), ch. 311, p. 1461, § 2, effective May 27. L.
2014: (1.5)(a.5) and (6)(a)(I.5) added and (6)(a)(I) amended, (HB 14-1373),
ch. 266, p. 1066, § 1, effective May 26. L. 2023: IP(1.5)(a) and
(1.5)(a.5) amended, (SB 23-036), ch. 345, p. 2069, § 3, effective June 5;
IP(1.5)(a) and (1.5)(a.5) amended, (HB 23-1052), ch. 131, p. 499, § 5,
effective January 1, 2025.
Editor's
note: Subsection
(1.5)(a.5) was amended in HB 23-1052, effective January 1, 2025. However, those
amendments were superseded by the amendments to subsection (1.5)(a.5) by SB
23-036, effective June 5, 2023.
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-204. Notice of property tax
exemption.
No later
than May 1, 2013, and no later than May 1 of each year thereafter in which an
assessor sends a notice of valuation pursuant to section 39-5-121 (1)(a) that
is not included with the tax bill, each assessor shall mail to each residential
real property address in the assessor's county notice of the exemption allowed
by section 39-3-203 (1). As soon as practicable after January 1, 2014, and as
soon as practicable after January 1 of each year thereafter, each county
treasurer shall, at the treasurer's discretion, mail or electronically send to
each person whose name appears on the tax list and warrant as an owner of
residential real property notice of the exemption allowed by section 39-3-203
(1). The treasurer must mail or electronically send the notice in each year on
or before the date on which the treasurer mails the property tax statement for
the previous property tax year pursuant to section 39-10-103. No later than May
1, 2008, and no later than each May 1 thereafter, each assessor also shall mail
to each residential property address in the assessor's county notice of the
exemption allowed by section 39-3-203 (1.5). No later than May 1, 2007, the
division shall mail to the residential property address of each person residing
in the state who the division believes is a qualifying veteran with a
disability notice of the exemption allowed by section 39-3-203 (1.5) for the
2007 property tax year. However, the sending of notice to a person by the
division does not constitute a determination that the person sent notice is
entitled to an exemption. The notice must be in a form prescribed by the
administrator, who shall consult with the division before prescribing the form
of the notice of the exemption allowed by section 39-3-203 (1.5), and must
include a statement of the eligibility criteria for the exemptions,
instructions for obtaining an exemption application, and, for applications for
exemptions for property tax years commencing on or after January 1, 2024,
instructions for obtaining proof of qualifying veteran with a disability
status. To reduce mailing costs, an assessor may coordinate with the treasurer
of the same county to include notice with the tax statement for the previous
property tax year mailed pursuant to section 39-10-103 or may include notice
with the notice of valuation mailed pursuant to section 39-5-121 (1)(a).
Source:
L. 2001: Entire
part added, p. 464, § 1, effective April 25. L. 2007: Entire section
amended, p. 478, § 4, effective April 15. L. 2013: Entire section
amended, (HB 13-1145), ch. 98, p. 314, § 1, effective April 4. L. 2023:
Entire section amended, (SB 23-036), ch. 345, p. 2069, § 4, effective June 5;
entire section amended, (HB 23-1052), ch. 131, p. 500, § 6, effective January
1, 2025.
Editor's
note: This section
was amended in HB 23-1052, effective January 1, 2025. However, those amendments
were superseded by the amendments to this section by SB 23-036, effective June
5, 2023.
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-205. Exemption applications -
penalty for providing false information - confidentiality.
(1) (a)
To claim the exemption allowed by section 39-3-203 (1), an individual shall
file with the assessor a completed exemption application no later than July 15
of the first property tax year for which the exemption is claimed. An
application returned by mail shall be deemed filed on the date it is
postmarked.
(b) [Editor's
note: This version of subsection (1)(b) is effective until January 1, 2027.]
To claim the exemption allowed by section 39-3-203 (1.5), an individual shall
file with the assessor a completed exemption application and proof of
qualifying veteran with a disability status no later than July 1 of the first
property tax year for which the exemption is claimed. An application returned
by mail shall be deemed filed on the date it is postmarked. An individual who
filed an exemption application with the division rather than with the assessor
as was required before this subsection (1)(b) was amended by Senate Bill
23-036, enacted in 2023, and who qualified for and received an exemption for a
property tax year commencing before January 1, 2024, retains the exemption and
is not required to submit a new application or proof of qualifying veteran with
a disability status to the assessor.
(b) [Editor's
note: This version of subsection (1)(b) is effective January 1, 2027.]
To claim the exemption allowed by section 39-3-203 (1.5), an individual shall
file with the assessor a completed exemption application and proof of
qualifying veteran with a disability status no later than July 15 of the first
property tax year for which the exemption is claimed. An application returned
by mail shall be deemed filed on the date it is postmarked. An individual who
filed an exemption application with the division rather than with the assessor
as was required before this subsection (1)(b) was amended by Senate Bill
23-036, enacted in 2023, and who qualified for and received an exemption for a
property tax year commencing before January 1, 2024, retains the exemption and
is not required to submit a new application or proof of qualifying veteran with
a disability status to the assessor.
(2) (a)
An exemption application shall be a form prescribed by the administrator, who
shall consult with the division before prescribing the form of the application
for the exemption allowed by section 39-3-203 (1.5), and shall require an
applicant to provide the following information:
(I) The
applicant's name, mailing address, date of birth, and social security number;
(II)
The address and schedule or parcel number of the residential real property for
which an exemption is claimed;
(III)
The name and social security number of each individual who occupies as his or
her primary residence the residential real property for which an exemption is
claimed;
(IV) If
a trust is the owner of record of the residential real property for which an
exemption is claimed, the names of the maker of the trust, the trustee, and the
beneficiaries of the trust;
(V) If
a corporate partnership or other legal entity is the owner of record of the
residential real property for which an exemption is claimed, the names of the
principals of the corporate partnership or other legal entity;
(VI) An
affirmation, in a form prescribed by the administrator, that the applicant
believes, under penalty of perjury in the second degree, as defined in section
18-8-503, C.R.S., that all information provided by the applicant is correct;
and
(VII)
Any other information that the administrator may reasonably require as
necessary for the proper and efficient administration of the exemption.
(b) The
exemption application shall also contain a statement that an applicant, or in
the case of residential real property for which the owner of record is a trust,
the trustee, has a legal obligation to inform the assessor within sixty days of
any change in the ownership or occupancy of residential real property for which
an exemption has been applied for or allowed that would prevent an exemption
from being allowed for the property.
(c) For
the exemption allowed by section 39-3-203 (1.5), the exemption application must
include proof of qualifying veteran with a disability status.
(2.5)
Repealed.
(3) (a)
In addition to any penalties prescribed by law for perjury in the second
degree, an applicant who knowingly provides false information on an exemption
application or files more than one exemption application in any property tax
year:
(I)
Shall not be entitled to an exemption;
(II)
Shall be required to pay, to the treasurer of any county in which an exemption
was improperly allowed due to the provision by the applicant of false
information or the filing by the applicant of more than one exemption
application, an amount equal to the amount of property taxes not paid as a
result of the exemption being improperly allowed; and
(III)
Shall, upon conviction of perjury, be required to pay to the treasurer of any
county in which an invalid exemption application was filed an additional amount
equal to twice the amount of the property taxes that would not have had to be
paid had the exemption application been valid plus interest. Interest shall be
calculated at the annual rate calculated pursuant to section 39-21-110.5 (2)
and (3) from the date the invalid exemption application was filed until the
date the applicant makes the payment required by this subparagraph (III).
(b) If
an applicant or a trustee fails to inform the assessor within sixty days of any
change in the ownership or occupancy of residential real property for which an
exemption has been applied for or allowed that would prevent an exemption from
being allowed for the property as required by paragraph (b) of subsection (2)
of this section:
(I) An
exemption shall not be allowed with respect to the residential real property;
and
(II)
The applicant or trustee shall be required to pay, to the treasurer of any
county in which an exemption was improperly allowed due to the applicant's or
trustee's failure to immediately inform the assessor of any change in the
ownership or occupancy of residential real property, an amount equal to the
amount of property taxes not paid as a result of the exemption being improperly
allowed plus interest. Interest shall be calculated at the annual rate
calculated pursuant to section 39-21-110.5 (2) and (3) from the date on which
the change in the ownership or occupancy occurred until the date the applicant
makes the payment required by this subparagraph (II).
(c) Any
amount required to be paid to a treasurer pursuant to paragraph (a) or (b) of
this subsection (3) shall be deemed part of the lien of general taxes imposed
on the person required to pay the amount and shall have the priority specified
in section 39-1-107 (2).
(4) (a)
Completed exemption applications shall be kept confidential; except that:
(I) (A)
An assessor may release statistical compilations or informational summaries of
any information contained in exemption applications and shall provide a copy of
an exemption application to the applicant who returned the application, the
treasurer of the same county as the assessor, the administrator, the state
treasurer, or the state auditor upon request or as otherwise required by this
part 2.
(B) An
assessor may introduce a copy of an exemption application as evidence in any
administrative hearing or legal proceeding in which the accuracy or veracity of
the exemption application is at issue so long as neither the applicant's social
security number nor any other social security number set forth in the
application are divulged.
(II) A
treasurer, the administrator, the state treasurer, or the state auditor shall
keep confidential each individual exemption application that it may receive
from an assessor but may release statistical compilations or informational
summaries of any information contained in exemption applications and may
introduce a copy of an exemption application as evidence in any administrative
hearing or legal proceeding in which the accuracy or veracity of the exemption
application is at issue so long as neither the applicant's social security
number nor any other social security number set forth in the application are
divulged.
(III)
The administrator may share information contained in an exemption application,
including any social security number set forth in the application, with the
department of revenue to the extent necessary to enable the administrator to
verify that the applicant satisfies legal requirements for claiming the
exemption.
(b)
Notwithstanding the provisions of paragraph (a) of this subsection (4), an
assessor, the division, a treasurer, the administrator, the state treasurer, or
the state auditor shall not give any other person any listing of individuals
who have applied for an exemption or any other information that would enable a
person to easily assemble a mailing list of individuals who have applied for an
exemption.
Source:
L. 2001: Entire
part added, p. 464, § 1, effective April 25. L. 2007: (1), IP(2)(a), and
(4) amended and (2.5) added, p. 478, § 5, effective April 15. L. 2011:
(2.5) amended, (HB 11-1226), ch. 73, p. 201, § 1, effective March 29. L.
2016: (4)(a)(III) added, (HB 16-1175), ch. 332, p. 1344, § 2, effective
June 10. L. 2023: (1)(b), (4)(a)(I), and (4)(a)(II) amended, (2)(c)
added, and (2.5) repealed, (SB 23-036), ch. 345, p. 2070, § 5, effective
January 1, 2024; (2.5) amended, (HB 23-1052), ch. 131, p. 500, § 7, effective
January 1, 2025. L. 2026: (1)(b) amended, (SB 26-046), ch. 10, p. 43, §
8, effective January 1, 2027.
Editor's
note: Subsection
(2.5) was amended in HB 23-1052, effective January 1, 2025. Those amendments
were superseded by the repeal of subsection (2.5) in SB 23-036, effective
January 1, 2024.
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-206. Notice to individuals
returning incomplete or nonqualifying exemption applications - denial of
exemption - administrative remedies.
(1) (a)
Except as otherwise provided in paragraph (a.5) of subsection (2) of this
section, an assessor shall only grant the exemption allowed to qualifying
seniors under section 39-3-203 (1) to an applicant who has timely returned an
exemption application in accordance with section 39-3-205 (1)(a) that
establishes that the applicant is entitled to the exemption.
(b) If
the information provided on or with an application for the exemption allowed to
qualifying seniors under section 39-3-203 (1) indicates that the applicant is
not entitled to the exemption, or is insufficient to allow the assessor to
determine whether or not the applicant is entitled to the exemption, the
assessor shall deny the application and mail to the applicant a statement
providing the reasons for the denial and informing the applicant of the
applicant's right to contest the denial pursuant to subsection (2) of this
section. The assessor shall mail the statement no later than August 1 of the
property tax year for which the exemption application was filed.
(1.5)
(a) Except as otherwise provided in subsection (2)(a.7) of this section, the
assessor shall only accept an application for the exemption allowed to
qualifying veterans with a disability under section 39-3-203 (1.5) if the
applicant timely returned the exemption application in accordance with section
39-3-205 (1)(b), and an assessor shall only grant the exemption if the
applicant submits proof of qualifying veteran with a disability status as
required by section 39-3-205 and the exemption application establishes that the
applicant meets the other requirements to be entitled to the exemption.
(b) If
the information provided on or with an application for the exemption allowed to
qualifying veterans with a disability under section 39-3-203 (1.5) indicates
that the applicant is not entitled to the exemption, or is insufficient to
allow the assessor to determine whether or not the applicant is entitled to the
exemption, the assessor shall deny the application and mail to the applicant a
statement providing the reasons for the denial and informing the applicant of
the applicant's right to contest the denial pursuant to subsection (2) of this
section. The assessor shall mail the statement no later than August 1 of the
property tax year for which the exemption application was filed.
(2) (a)
An applicant whose exemption application has been denied pursuant to subsection
(1)(b) or (1.5)(b) of this section may contest the denial by requesting a
hearing before the county commissioners sitting as the county board of
equalization no later than August 15 of the property tax year for which the
exemption application was filed. The hearing shall be held on or after August 1
and no later than September 1 of the property tax year for which the exemption
application was filed, and the decision of the county board of equalization is
not subject to further administrative appeal by either the applicant or the
assessor.
(a.5)
An individual who wishes to claim the exemption for qualifying seniors allowed
by section 39-3-203 (1), but who has not timely filed an exemption application
with the assessor by July 15, may file a late exemption application no later
than the August 15 that immediately follows that deadline. The assessor shall
accept any such application but may not accept any late application filed after
August 15. The assessor shall grant an exemption if an accepted late
application establishes that the applicant is entitled to the exemption. A
decision of an assessor to disallow the filing of a late application after
August 15 or to grant or deny an exemption to an applicant who has filed a late
application after July 15 but no later than August 15 is final, and an
applicant who is denied late filing or an exemption may not contest the denial.
(a.7) [Editor's
note: This version of subsection (2)(a.7) is effective until January 1, 2027.]
An individual who wishes to claim the exemption for qualifying veterans with a
disability allowed by section 39-3-203 (1.5), but who has not timely filed an
exemption application, may request that the assessor waive the application
deadline and allow the individual to file a late exemption application no later
than the August 1 that immediately follows the original application deadline.
The assessor may accept an application if, in the assessor's sole discretion,
the applicant shows good cause for not timely filing an application. If the
assessor accepts a late application, the assessor shall determine whether the
application should be granted or denied pursuant to subsection (1.5) of this
section and shall mail notice of its determination to the applicant no later
than the August 25 that immediately follows the late application deadline. A
decision of the assessor to allow or disallow the filing of a late application
or of an assessor to grant or deny an exemption to an applicant who has filed a
late application is final, and an applicant who is denied late filing or an
exemption may not contest the denial.
(a.7) [Editor's
note: This version of subsection (2)(a.7) is effective January 1, 2027.]
An individual who wishes to claim the exemption for qualifying veterans with a
disability allowed by section 39-3-203 (1.5), but who has not timely filed an
exemption application, may request that the assessor waive the application
deadline and allow the individual to file a late exemption application no later
than the August 15 that immediately follows the original application deadline.
The assessor may accept an application if, in the assessor's sole discretion,
the applicant shows good cause for not timely filing an application. If the
assessor accepts a late application, the assessor shall determine whether the
application should be granted or denied pursuant to subsection (1.5) of this
section and shall mail notice of its determination to the applicant no later
than the August 25 that immediately follows the late application deadline. A
decision of the assessor to allow or disallow the filing of a late application
or of an assessor to grant or deny an exemption to an applicant who has filed a
late application is final, and an applicant who is denied late filing or an
exemption may not contest the denial.
(b) The
county board of equalization may appoint independent referees to conduct
hearings requested pursuant to paragraph (a) of this subsection (2) on behalf
of the county board and to make findings and submit recommendations to the
county board for its final action.
Source:
L. 2001: Entire
part added, p. 466, § 1, effective April 25. L. 2002: (2) amended, p.
842, § 1, effective August 7. L. 2003: (1)(a) amended and (2)(a.5)
added, p. 2479, §§ 1, 2, effective June 5. L. 2007: (1), (2)(a), and
(2)(a.5) amended and (1.5) and (2)(a.7) added, pp. 480, 481, §§ 6, 7, effective
April 15. L. 2011: (1.5) and (2)(a.7) amended, (HB 11-1226), ch. 73, p.
202, § 2, effective March 29. L. 2013: (2)(a.5) amended, (HB 13-1145),
ch. 98, p. 315, § 2, effective April 4. L. 2016: (1)(b), (1.5)(b),
(2)(a), (2)(a.5), and (2)(a.7) amended, (HB 16-1175), ch. 332, p. 1345, § 3,
effective January 1, 2017. L. 2023: (1.5), (2)(a), and (2)(a.7) amended,
(SB 23-036), ch. 345, p. 2071, § 6, effective January 1, 2024; (1.5), (2)(a),
and (2)(a.7) amended, (HB 23-1052), ch. 131, p. 501, § 8, effective January 1,
2025. L. 2026: (2)(a.7) amended, (SB 26-046), ch. 10, p. 43, § 9,
effective January 1, 2027.
Editor's
note: Subsections
(2)(a) and (2)(a.7) were amended in HB 23-1052, effective January 1, 2025.
Those amendments were superseded by the amendments to subsections (2)(a) and
(2)(a.7) in SB 23-036, effective January 1, 2024.
Cross
references: For
the legislative declaration in HB 23-1052, see section 1 of chapter 131,
Session Laws of Colorado 2023.
39-3-207. Reporting of exemptions -
reimbursement to local governmental entities.
(1) No
later than October 10, 2002, and no later than each October 10 thereafter
through October 10, 2016, and no later than September 10, 2017, and no later
than each September 10 thereafter, each assessor shall forward to the
administrator a report on the exemptions allowed in his or her county for the
current property tax year. The report shall include:
(a) A
statement of the total amount of actual value of residential real property
within the county that is exempted from taxation;
(b)
With respect to each unit of residential real property for which an exemption
is allowed:
(I) The
legal description of the property;
(II)
The schedule or parcel number for the property;
(III)
The name and social security number of the applicant who claimed an exemption
for the property and each additional person who occupies the property; and
(IV) A
statement of the taxable and tax exempt value of the property; and
(c) For
reports issued for the 2007 property tax year and for each subsequent property
tax year, separate identification, in such form as the administrator may
require, of the units of residential real property within the county exempted
from taxation under section 39-3-203 (1.5) and of the total amount of actual
value of the property so exempted.
(2) (a)
(I) The administrator shall examine the reports sent by each assessor
pursuant to subsection (1) of this section to ensure that no applicant has
claimed an exemption without meeting all legal requirements for claiming the
exemption. No later than November 1, 2002, and no later than each November 1
thereafter, if the administrator determines that an applicant has claimed more
than one exemption, the administrator shall provide written notice to the
applicant that the applicant has claimed more than one exemption and is
therefore not entitled to any exemption. No later than November 1, 2016, and no
later than each November 1 thereafter, if the administrator determines that the
applicant and the applicant's spouse have claimed separate exemptions in
violation of section 39-3-203 (5), that the applicant has claimed an exemption
for residential real property that the applicant does not own and occupy as the
applicant's primary residence as required by section 39-3-203 (1), or that the
applicant is otherwise ineligible to claim an exemption, the administrator
shall provide written notice to the applicant that the applicant is ineligible
for the exemption and specify the reasons for the determination of
ineligibility. The notice shall also include a statement specifying the
deadline and procedures for protesting the denial of the exemption or
exemptions claimed.
(II) An
applicant whose claims for exemption are denied by the administrator pursuant
to subparagraph (I) of this paragraph (a) may file a written protest with the
administrator no later than November 15 of the year in which the exemption or
exemptions were denied. If the ground for the denial is that the applicant, or
the applicant and the applicant's spouse, claimed multiple exemptions, the sole
ground for a protest is that the applicant, or the applicant and the
applicant's spouse, filed only one claim for an exemption and the protest shall
specify property or properties identified by the administrator in the notice
denying exemptions for which no exemption was claimed. The administrator shall
request that any appropriate assessor check the assessor's records of exemption
applications to determine whether the applicant filed a disputed exemption
application and shall decide the protest accordingly. If the ground for the
denial is that the applicant is not an owner-occupier of the residential real
property for which an exemption is claimed, the sole grounds for a protest are
that the applicant actually is an owner-occupier or that the applicant
qualifies for an exemption for the property under section 39-3-203 (6). If a
protest is denied, the administrator shall mail the applicant a written
statement of the basis for the denial and a copy of each exemption application
filed with an assessor that the applicant claimed had not been filed.
(b) No
later than December 1, 2002, and no later than each December 1 thereafter, and
after examining the reports sent by each assessor, denying claims for
exemptions, and deciding protests in accordance with subsection (2)(a) of this
section, the administrator shall provide written notice to the assessor of each
county in which an exemption application has been denied because the applicant
filed multiple exemption applications with the identity of the applicant who
filed multiple exemption applications and the denial of the exemption. No later
than December 1, 2016, and no later than each December 1 thereafter, and after
examining the reports sent by each assessor, denying claims for exemptions, and
deciding protests in accordance with subsection (2)(a) of this section, the
administrator shall also provide written notice to the assessor of each county
in which an exemption application has been denied for any other reason with the
identity of the applicant and the denial of the exemption, specifying the reason
for the denial. No later than January 10, 2017, and no later than each January
10 thereafter; except that, for 2024, no later than January 24, each assessor
shall forward to the administrator a partial copy of the tax warrant for the
assessor's county that includes only property for which the assessor has
granted an exemption. The administrator shall examine the tax warrants to
ensure that no additional exemptions have been allowed since the administrator
examined the reports previously received from the assessors and that each
assessor has removed from the tax warrant all exemptions that the administrator
previously denied. No later than January 17, 2017, and no later than each
January 17 thereafter; except that, for 2024, no later than January 31, the
administrator shall notify each assessor and each treasurer of any exemptions
to be removed from the tax warrant.
(3) No
later than April 1, 2003, and no later than each April 1 thereafter through
April 1, 2016, to enable the state treasurer to issue a reimbursement warrant
to each treasurer in accordance with subsection (4) of this section, each
treasurer shall forward to the state treasurer a report on the exemptions
allowed in his or her county for the previous property tax year. No later than
March 1, 2017, and no later than March 1 of each year thereafter, each
treasurer shall forward the report to the administrator, who shall cross-check
it as specified in subsection (3.5) of this section before correcting it, if
necessary, and forwarding it to the state treasurer to enable the state
treasurer to issue a reimbursement warrant to each treasurer in accordance with
subsection (4) of this section. The report shall include:
(a) A
statement of the total amount of actual value of residential real property
within the county that was exempted from taxation and the total amount of
property tax revenues lost by local governmental entities within the county as
a result of the exemption that must be reimbursed by the state;
(b)
With respect to each unit of residential real property for which an exemption
was allowed:
(I) The
legal description of the property;
(II)
The schedule or parcel number for the property;
(III)
The name of the applicant who claimed an exemption for the property and each
additional person who occupies the property; and
(IV) A
statement of the taxable and tax exempt value of the property and the amount of
taxes due on the property; and
(c) For
reports issued for the 2007 property tax year and for each subsequent property
tax year, separate identification, in such form as the administrator may
require, of the units of residential real property within the county exempted
from taxation under section 39-3-203 (1.5), the total amount of actual value of
the property so exempted, and the total amount of property tax revenues lost by
local government entities within the county as a result of the exemption.
(3.5)
After receiving reports from each treasurer pursuant to subsection (3) of this
section, the administrator shall cross-check the reports to identify any
exemption allowed in a county that must be denied due to a failure of the
individual allowed the exemption to satisfy all legal requirements for claiming
the exemption. The administrator shall remove any exemption that must be denied
from the report in which it appears and shall forward all reports to the state
treasurer no later than the April 1 immediately following the receipt of the
reports by the administrator. In addition, if the administrator identifies any
exemption improperly allowed for a prior property tax year commencing on or
after January 1, 2016, for which the state treasurer reimbursed a treasurer
pursuant to subsection (4) of this section or identifies any exemption properly
allowed for such a prior property tax year for which the state treasurer did
not reimburse a treasurer, the administrator shall advise the state treasurer
to adjust the current year reimbursement to the treasurer to correct the error.
No later than that April 1, the administrator shall also notify the treasurer
and assessor of each county of the exemptions removed from the report for the
county and any resulting and other adjustments to the amount of current year
reimbursement to be paid by the state treasurer to the treasurer.
(3.7)
In accordance with section 25-2-103 (4.5), C.R.S., the administrator shall
annually provide to the state registrar of vital statistics of the department
of public health and environment a list, by name and social security number, of
every individual who received an exemption for the immediately preceding year
so that the registrar can provide to the administrator a list of all such
individuals who have died. No later than April 1, 2017, and no later than each
April 1 thereafter, the administrator shall forward to the assessor of each
county, the name and social security number of each deceased individual who
received an exemption for the immediately preceding year for residential real
property located within the county so that the assessor can terminate the
exemption for the property.
(4) (a)
(I) In accordance with section 3.5 of article X of the state constitution,
no later than April 15, 2003, and no later than each April 15 thereafter, the
state treasurer shall issue a warrant to each treasurer for the amount needed
to fully reimburse all local governmental entities within the treasurer's
county for the amount of property tax revenues lost as a result of the
application of the exemption to property taxes that accrued during the previous
property tax year and are payable during the year in which the state treasurer
issues the warrant. The reimbursement shall be paid from the state general fund
and shall not be subject to the statutory limitation on state general fund
appropriations set forth in section 24-75-201.1, C.R.S.
(II) As
used in this paragraph (a), with respect to exemptions allowed for property tax
years commencing on or after January 1, 2016, "property tax revenues lost
as a result of the application of the exemption" includes only those
revenues lost as a result of exemptions properly allowed in accordance with the
requirements of this part 2 and does not include any revenues lost as a result
of an exemption being erroneously allowed.
(b)
Each treasurer shall distribute the total amount received from the state
treasurer pursuant to paragraph (a) of this subsection (4) to the local
governmental entities within the treasurer's county as if the lost tax revenues
had been regularly paid. When a treasurer distributes said amount, the
treasurer shall provide each local governmental entity with a statement of the
amount distributed to the local governmental entity that represents
reimbursement received from the state for property tax revenues lost as a
result of the exemption. In accordance with section 3.5 of article X of the
state constitution, moneys distributed to a local governmental entity as
reimbursement for property tax revenues lost as a result of the exemption shall
not be included in the local governmental entity's fiscal year spending for
purposes of section 20 of article X of the state constitution.
(4.5)
In accordance with subsection (3.5) of this section, for any property tax year
commencing on or after January 1, 2016, the state treasurer shall not reimburse
a treasurer for property tax revenues lost as a result of an exemption
erroneously allowed in the treasurer's county. If, pursuant to subsection (3.5)
of this section, the administrator advises the state treasurer that the state
treasurer has provided either too much or too little reimbursement to a
treasurer for exemptions allowed in the treasurer's county for any prior
property tax year commencing on or after January 1, 2016, the state treasurer
shall adjust the reimbursement for the current property tax year as directed by
the administrator in order to correct the error.
(5)
Notwithstanding any provision of law to the contrary, the reports required by
this section and the contents thereof shall be kept confidential by an
assessor, a treasurer, the administrator, the state treasurer, or the state
auditor; except that said persons may provide the reports to each other as
required or authorized by law.
(6) to
(8) Repealed.
Source:
L. 2001: Entire
part added, p. 467, § 1, effective April 25. L. 2002: IP(1) amended, p.
842, § 2, effective August 7. L. 2007: (1)(c) and (3)(c) added and
(3)(b)(III) amended, p. 482, §§ 8, 9, effective April 15. L. 2012: (6)
added, (HB 12-1326), ch. 195, p. 777, § 4, effective May 22. L. 2016:
(6) amended, (HB 16-1161), ch. 35, p. 89, § 1, effective March 22; IP(1), (2),
IP(3), and (4)(a) amended and (3.5), (3.7), and (4.5) added, (HB 16-1175), ch.
332, p. 1346, § 4, effective June 10. L. 2020: (6) repealed, (HB
20-1387), ch. 174, p. 801, § 1, effective June 29. L. 2022: (7) added,
(HB 22-1205), ch. 436, p. 3070, § 1, effective August 10. L. 2023, 1st Ex.
Sess.: (2)(b) amended, (SB 23B-001), ch. 1, p. 10, § 10, effective November
20. L. 2024: (8) added, (HB 24-1052), ch. 473, p. 3321, § 1, effective
August 7.
Editor's
note: (1)
Subsection (7)(c) provided for the repeal of subsection (7), effective July 1,
2023. (See L. 2022, p. 3070.)
(2) Subsection (8)(c) provided
for the repeal of subsection (8), effective July 1, 2025. (See L. 2024, p.
3321.)
39-3-208. Auditing of property tax
exemption program.
The state
auditor shall periodically audit the property tax exemption program
administered pursuant to this part 2 to ensure that the program is operating in
compliance with section 3.5 of article X of the state constitution and this
part 2. In connection with an audit, the state auditor may suggest means of
improving the administration of the program. Upon request, an assessor, a
treasurer, the administrator, or the state treasurer shall provide the state
auditor with any exemption applications, reports, or other documents relevant
to the administration of the program.
Source:
L. 2001: Entire
part added, p. 469, § 1, effective April 25.
39-3-209. State expenditure for
property tax exemptions - mechanism for refunding of excess state revenue -
legislative declaration.
(1) The
general assembly hereby finds and declares that:
(a)
Although the exemptions allowed by this part 2 are exemptions from local
government property taxes, the state must reimburse local governments for the
net amount of property tax revenues lost as a result of the exemptions and
therefore bears the full cost of the exemptions;
(b)
Section 3.5 of article X of the state constitution authorizes the general
assembly to raise or lower the maximum amount of actual value of residential
real property of which fifty percent is exempt pursuant to this part 2;
(c) In
order to eliminate the cost of the exemption and fund other state needs, the
general assembly, as authorized by section 3.5 of article X of the state
constitution, has at times temporarily suspended the exemption for qualifying
seniors allowed by this part 2 by lowering to zero the maximum amount of actual
value of residential real property of which fifty percent is exempt;
(d) The
general assembly intends to allow seniors to rely on predictable and
sustainable exemptions by fully funding the property tax exemption for
qualifying seniors in the future, and it is more likely to be able to do so if
the cost of the exemption, which exclusively benefits taxpayers who reside in
Colorado, constitutes a refund of excess state revenues for state fiscal years
for which such refunds are required; and
(e)
Section 20 of article X of the state constitution authorizes the state to use
any reasonable method to make required refunds of excess state revenues, and
the payment by the state of reimbursement to local governments for the net
amount of property tax revenues lost as a result of the property tax exemptions
allowed by this part 2, which exemptions directly reduce the tax liability of
taxpaying Colorado residents throughout the state, is a reasonable method of
making such refunds.
(2) For
any state fiscal year commencing on or after July 1, 2017, for which state
revenues, as defined in section 24-77-103.6 (6)(c), exceed the excess state
revenues cap, as defined in section 24-77-103.6 (6)(b)(I)(C) or (6)(b)(I)(D),
and are required to be refunded in accordance with section 20 of article X of
the state constitution, the lesser of all reimbursement paid by the state
treasurer to each treasurer as required by section 39-3-207 (4) for the
property tax year that commenced during the state fiscal year or an amount of
such reimbursement equal to the amount of excess state revenues for the state
fiscal year that are required to be refunded is a refund of such excess state
revenues.
Source:
L. 2017: Entire
section added, (SB 17-267), ch. 267, p. 1467, § 24, effective May 30.
Cross
references: For
the legislative declaration in SB 17-267, see section 1 of chapter 267, Session
Laws of Colorado 2017.
39-3-210. Reporting of property tax
revenue reductions - reimbursement of local governmental entities - definitions
- local government backfill cash fund - creation - repeal. (Repealed)
Source:
L. 2022: Entire
section added, (SB 22-238), ch. 157, p. 990, § 5, effective May 16. L. 2023
(1)(a.3) and (2.5) added, and (1)(e) amended, (SB 23-303), ch. 258, p. 1487, §
14, effective May 24. L. 2023, 1st Ex. Sess.: (1)(a.2), (1)(d.5),
(1)(f.5), (2)(c), (2)(d), (2)(e), (4)(a.5), (4)(e), (4)(f), (4)(g), and (7)
added, and (2)(a)(I), (2)(b)(I), (2)(b)(II), (3), IP(4)(a)(I), IP(4)(a)(II),
(4)(a)(III), (4)(a)(IV), (4)(a)(V), (4)(b), and (5) amended, (SB 23B-001), ch.
1, p. 2, § 2, effective November 20. L. 2024: (4)(e) repealed, (HB
24-1302), ch. 340, p. 2300, § 2, effective June 3.
Editor's
note: Subsection
(6) provided for the repeal of this section, effective July 1, 2025. (See L.
2022, p. 990.)
39-3-211. Reporting of assessed value
reductions - reimbursement of local governmental entities - local governmental
entity backfill cash fund - creation - legislative declaration - definitions -
repeal.
(1) The
general assembly finds and declares that:
(a)
Most school districts rely on a combination of state and local sources of
revenue to pay for total program funding;
(b)
State revenue makes up the difference between the full amount of a school
district's total program funding and the amount of a school district's total
program funding that the school district pays for with its property tax
revenue;
(c) The
amount of state revenue necessary to make up the difference between the full
amount of a school district's total program funding and the amount of a school
district's total program funding that the school district pays for with its
property tax revenue is annually determined by the general assembly in the
annual public school finance act;
(d)
Therefore, it is the general assembly's expectation and intent that, although
school district property tax revenue is reduced by Senate Bill 24-233, the
general assembly will increase the amount of state revenue that it annually
distributes to school districts in order to maintain or increase school
district total program funding;
(e) The
general assembly will reimburse local governmental entities that rely on
property tax revenue other than school districts, at least in part, through the
reimbursement described in this section; and
(f) It
is the intent of the general assembly to review both the impact of the property
tax revenue reductions in Senate Bill 24-233 and the reimbursement described in
this section on local governmental entities to ensure that local governmental
entities can maintain the current level of critical services they provide.
(2) As
used in this section, unless the context otherwise requires:
(a)
"County" includes a city and county.
(b)
"Fund" means the local governmental entity backfill cash fund created
in subsection (7)(a) of this section.
(c)
"Local governmental entity" means a governmental entity authorized by
law to impose ad valorem taxes on taxable property located within its
territorial limits; except that the term excludes school districts.
(3) For
the property tax year commencing on January 1, 2024, each assessor shall:
(a)
Calculate the decrease, if any, in the total assessed value of real property
for each local governmental entity within the assessor's county between the
property tax year commencing on January 1, 2022, and the property tax year
commencing on January 1, 2024; and
(b)
Determine each local governmental entity's mill levy for the property tax year
commencing on January 1, 2022, excluding any mills levied to provide for the
payment of bonds and interest thereon or for the payment of any other
contractual obligation that has been approved by a majority of the local
governmental entity's voters voting thereon.
(3.5)
For the property tax year commencing on January 1, 2025, each assessor shall:
(a)
Calculate the decrease, if any, in the total assessed value of real property
for each local governmental entity within the assessor's county between the
property tax year commencing on January 1, 2024, and the property tax year
commencing on January 1, 2025, as a result of House Bill 24B-1001; and
(b)
Determine each local governmental entity's mill levy for the property tax year
commencing on January 1, 2024, excluding any mills levied to provide for the
payment of bonds and interest thereon or for the payment of any other
contractual obligation that has been approved by a majority of the local
governmental entity's voters voting thereon.
(4) No
later than March 1, 2025, an assessor shall report the amounts calculated
pursuant to subsection (3)(a) of this section, as applicable, the basis for the
amounts, and the mill levies determined pursuant to subsection (3)(b) of this
section to the administrator. No later than March 1, 2026, an assessor shall
report the amounts calculated pursuant to subsection (3.5)(a) of this section,
as applicable, the basis for the amounts, and the mill levies determined
pursuant to subsection (3.5)(b) of this section to the administrator. The
administrator may require an assessor to provide additional information as
necessary to evaluate the accuracy of the amounts reported. The administrator
shall confirm that the reported amounts are correct or rectify the amounts if
necessary. The administrator shall then forward the correct amounts for a
county to the state treasurer to enable the state treasurer to issue a
reimbursement warrant to a treasurer in accordance with subsection (5) of this
section.
(5) (a)
No later than April 15, 2025, the state treasurer shall issue a warrant, to be
paid upon demand from the fund, to each treasurer that is equal to the total
reimbursement amounts set forth in subsection (6) of this section for all local
governmental entities within the treasurer's county.
(a.5)
No later than April 15, 2026, the state treasurer shall issue a warrant, to be
paid upon demand from the fund, to each treasurer that is equal to the total
reimbursement amounts set forth in subsection (6.5) of this section for all
local governmental entities within the treasurer's county.
(b)
Each treasurer shall distribute the total amount received from the state
treasurer to the local governmental entities, excluding school districts,
within the treasurer's county as if the amount had been regularly paid as
property tax so that the local governmental entities receive the amounts
determined pursuant to subsections (6) and (6.5) of this section. If the total
amount received from the state treasurer is reduced pursuant to subsections
(6)(b) and (6.5)(b) of this section, each treasurer shall proportionally reduce
the amount distributed to each local governmental entity. When distributing the
total amount received from the state treasurer, each treasurer shall provide
each local governmental entity with a statement of the amount distributed to
the local governmental entity that represents the reimbursement received under
subsections (6) and (6.5)(b) of this section.
(6) (a)
For each local governmental entity that had a decrease in total assessed value
of real property from the property tax year commencing on January 1, 2022, to
the property tax year commencing on January 1, 2024, the amount of
reimbursement is an amount equal to that decrease in total assessed value
multiplied by the local governmental entity's mill levy for the property tax
year commencing on January 1, 2022, excluding any mills levied to provide for
the payment of bonds and interest thereon or for the payment of any other
contractual obligation that has been approved by a majority of the local
governmental entity's voters voting thereon.
(b)
Notwithstanding subsection (6)(a) of this section, if there is insufficient
money in the fund for the state treasurer to issue warrants pursuant to
subsection (5)(a) of this section in the amounts determined pursuant to
subsection (6)(a) of this section, the amounts of the warrants issued by the
state treasurer must be proportionally reduced.
(c) The
reimbursement amounts set forth in this section are based on the amounts that
the administrator reports to the treasurer in accordance with subsection (4) of
this section.
(6.5)
(a) For each local governmental entity that had a decrease in total assessed
value of real property from the property tax year commencing on January 1,
2024, to the property tax year commencing on January 1, 2025, as a result of
House Bill 24B-1001, the amount of reimbursement is an amount equal to that
decrease in total assessed value multiplied by the local governmental entity's
mill levy for the property tax year commencing on January 1, 2024, excluding
any mills levied to provide for the payment of bonds and interest thereon or
for the payment of any other contractual obligation that has been approved by a
majority of the local governmental entity's voters voting thereon.
(b)
Notwithstanding subsection (6.5)(a) of this section, if there is insufficient
money in the fund for the state treasurer to issue warrants pursuant to
subsection (5)(a.5) of this section in the amounts determined pursuant to
subsection (6.5)(a) of this section, the amounts of the warrants issued by the
state treasurer must be proportionally reduced.
(c) The
reimbursement amounts set forth in this section are based on the amounts that
the administrator reports to the treasurer in accordance with subsection (4) of
this section.
(7) (a)
The local governmental entity backfill cash fund is hereby created in the state
treasury. The fund consists of money transferred to the fund in accordance with
subsection (7)(b) of this section. The state treasurer shall credit all
interest and income derived from the deposit and investment of money in the
local governmental entity backfill cash fund to the fund.
(b) On
April 1, 2025, the state treasurer shall transfer from the sustainable
rebuilding program fund created in section 24-38.5-115 (7) to the local
governmental entity backfill cash fund ten million three hundred eleven
thousand two hundred thirty-three dollars.
(c) The
money in the fund is available for the state treasurer to pay the warrants
required to be issued in accordance with subsection (5) of this section.
(d)
After issuing every warrant required pursuant to subsection (5)(a.5) of this
section, the state treasurer shall credit any unexpended and unencumbered money
remaining in the fund at that time to the sustainable rebuilding program fund
created in section 24-38.5-115 (7).
(e)
Notwithstanding any provision of this section to the contrary, on June 12,
2026, the state treasurer shall transfer sixteen thousand seven hundred
forty-seven dollars from the fund to the general fund.
(8)
This section is repealed, effective July 1, 2027.
Source:
L. 2024: Entire
section added, (SB 24-233), ch. 171, p. 921, § 9, effective October 1 (see
editor's note). L. 2024, 2nd Ex. Sess.: (3.5), (5)(a.5), and (6.5) added
and (4), (5)(b), (7)(d), and (8) amended, (HB 24B-1001), ch. 1, p. 20, § 15,
effective October 1 (see editor's note). L. 2026: (7)(e) added, (HB
26-1405), ch. 396, p. 2486, § 31, effective June 4.
Editor's
note: (1) Section
18 of chapter 1, (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, amended section 14 of chapter 171, (SB 24-233), Session
Laws of Colorado 2024, to change the effective date of SB 24-233 to October 1,
2024, if both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit are withdrawn pursuant to § 1-40-134 from the statewide ballot
for the general election held on November 5, 2024. On September 4, 2024, the
secretary of state announced both an initiative that reduces valuations for
assessment and an initiative that requires voter approval for retaining
property tax revenue that exceeds a limit were withdrawn from the 2024 general
election ballot.
(2) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
Deferrals
ARTICLE
3.5
Tax
Deferral for the Elderly and Military Personnel
39-3.5-101. Definitions.
39-3.5-102. Deferral of tax on homestead -
qualifications - filing of claim.
39-3.5-103. Property entitled to deferral.
39-3.5-103.5. State treasurer - program
administration - rules. (Repealed)
39-3.5-104. Claim form - contents.
39-3.5-105. Listing of tax-deferred property -
tax as lien - interest accrual.
39-3.5-105.5. Loan of state money to taxpayers.
39-3.5-105.7. Prior deferrals to be treated as
loans.
39-3.5-106. State treasurer to pay county
treasurer an amount equivalent to deferred taxes.
39-3.5-107. Repayment of loans - release of
liens - disposition of payments.
39-3.5-108. Notice to taxpayer regarding duty
to claim deferral annually.
39-3.5-109. Failure to receive notices.
39-3.5-110. Events requiring repayment of loans
- notice to state treasurer.
39-3.5-111. Time for payment - delinquencies.
39-3.5-112. Election by spouse to continue tax
deferral.
39-3.5-113. Voluntary repayment of loans for
deferred tax.
39-3.5-114. Deferred tax certificates not to be
included in reserve or surplus. (Repealed)
39-3.5-115. Limitations on effect of article.
39-3.5-116. Deed or contract clauses preventing
application for deferral prohibited - clauses void. (Repealed)
39-3.5-117. Report. (Repealed)
39-3.5-118. Emergency property tax deferral for
depositors of troubled industrial banks. (Repealed)
39-3.5-119. Release of information identifying
individuals claiming deferral.
39-3.5-120. Expansion of deferral program -
consultation - repeal. (Repealed)
39-3.5-101. Definitions.
As used in
this article 3.5, unless the context otherwise requires:
(1)
"Homestead" means the owner-occupied residence of the taxpayer and
includes owner-occupied units in a condominium, townhouse, or similar structure
and an owner-occupied mobile home.
(1.5)
"Mobile home" means any wheeled vehicle, exceeding either eight feet
in width or thirty-two feet in length, excluding towing gear and bumpers,
without motive power, which is designed and commonly used for occupancy by
persons for residential purposes, in either temporary or permanent locations,
and which may be drawn over the public highways by a motor vehicle.
(1.8)
"Person called into military service" means a member of the Army
National Guard of the United States, the Army reserve, the Naval reserve, the
Marine Corps reserve, the Air National Guard of the United States, the Air
Force reserve, or the Coast Guard reserve who has been ordered to active duty
pursuant to 10 U.S.C. sec. 12301 (a) or 12302 for a period of more than thirty
consecutive days in a time of war or national emergency declared by the
congress or the president of the United States. "Active duty"
includes any period during which a person called into military service is
absent from duty on account of sickness, wounds, leave, or other lawful cause.
(2)
"Real property taxes" means all ad valorem taxes levied on a
homestead, including special assessments and all other charges which are
recoverable by law at the annual real estate tax sale, and includes special
assessments and all other charges which are recoverable by law at the personal
property tax sale of a mobile home, as provided in section 39-10-111.
(2.5)
Repealed.
(3)
"Tax-deferred property" means the property upon which real property
taxes are deferred pursuant to this article.
(3.5)
Repealed.
(4)
"Taxpayer" means a person who has filed or whose guardian,
conservator, or attorney-in-fact has filed a claim for deferral pursuant to
this article or persons who have jointly filed a claim for deferral under this
article.
Source:
L. 78: Entire
article added, p. 471, § 1, effective February 28, 1979. L. 79: (1) and
(4) amended, p. 1411, § 1, effective January 1, 1980. L. 88: (1) and (2)
amended and (1.5) added, p. 1283, § 9, effective January 1, 1989. L. 2003:
(1.8) added, p. 2112, § 1, effective May 22. L. 2021: IP amended and
(3.5) added, (SB 21-293), ch. 301, p. 1808, § 5, effective June 23. L. 2022:
(2.5) added, (SB 22-220), ch. 388, p. 2759, § 1, effective June 7. L. 2024:
(3.5) amended, (SB 24-233), ch. 171, p. 923, § 10, effective October 1 (see
editor's note). L. 2025: (2.5) and (3.5) repealed, (SB 25-261), ch. 425,
p. 2411, § 1, effective July 1.
Editor's
note: Section 18
of chapter 1, (HB 24B-1001), Session Laws of Colorado 2024, Second
Extraordinary Session, amended section 14 of chapter 171, (SB 24-233), Session
Laws of Colorado 2024, to change the effective date of SB 24-233 to October 1,
2024, if both an initiative that reduces valuations for assessment and an
initiative that requires voter approval for retaining property tax revenue that
exceeds a limit are withdrawn pursuant to section 1-40-134, C.R.S., from the
statewide ballot for the general election held on November 5, 2024. On
September 4, 2024, the secretary of state announced both an initiative that
reduces valuations for assessment and an initiative that requires voter
approval for retaining property tax revenue that exceeds a limit were withdrawn
from the 2024 general election ballot.
39-3.5-102. Deferral of tax on homestead
- qualifications - filing of claim.
(1) (a)
Subject to the provisions of this article 3.5, a person who is sixty-five years
of age or older or who is a person called into military service on January 1 of
the year in which the person files a claim under this section may elect to
defer the payment of real property taxes. To exercise this option, the taxpayer
must file a claim for deferral with the treasurer of the county in which the
taxpayer's homestead is located. The claim must be filed after January 1 and on
or before April 1 of each year in which the taxpayer claims the deferral.
(b)
Notwithstanding paragraph (a) of this subsection (1), a person called into
military service at any time between January 1, 2003, and June 30, 2003, may
defer the payment of real property taxes for the property tax year 2002 by
filing a claim pursuant to this section on or before June 30, 2003.
(c)
Repealed.
(2)
When a taxpayer who is sixty-five years of age or older or who is a person
called into military service files a valid claim for deferral under subsection
(1) of this section, it has the effect of:
(a)
Deferring the payment of the taxpayer's real property taxes for the calendar
year previous to the year in which the claim is filed;
(b)
Continuing the deferral of taxes which have been deferred under this article
for previous years which have not become delinquent pursuant to section
39-3.5-111;
(c)
Terminating and releasing the lien for the general taxes so deferred created by
section 39-1-107 and substituting therefor the lien for said deferred taxes
created by section 39-3.5-105.
(2.5)
(a) A person called into military service may defer only the real property
taxes payable in a year in which the person is a person called into military
service. A person who is no longer a person called into military service may
file a valid claim in a subsequent year to continue the deferral of taxes
payable in a year in which the person was a person called into military
service.
(b)
Repealed.
(3) If
a guardian, conservator, or attorney-in-fact has been appointed for a taxpayer
otherwise qualified to claim deferral of taxes under this article, the
guardian, conservator, or attorney-in-fact may act for such taxpayer in
claiming the deferral.
Source:
L. 78: Entire
article added, p. 472, § 1, effective February 28, 1979. L. 2003: (1)
and IP(2) amended and (2.5) added, p. 2112, § 2, effective May 22. L. 2021:
(1)(c) added and IP(2), (2)(a), and (2.5) amended, (SB 21-293), ch. 301, p.
1809, § 6, effective June 23. L. 2022: (1)(a) and (1)(c)(I) amended, (SB
22-220), ch. 388, p. 2759, § 2, effective June 7. L. 2025: (1)(a),
IP(2), (2)(a), and (2.5)(a) amended and (1)(c) and (2.5)(b) repealed, (SB
25-261), ch. 425, p. 2412, § 2, effective July 1.
39-3.5-103. Property entitled to
deferral.
(1) In
order to qualify for real property tax deferral under this article 3.5, the
property shall meet all of the following requirements at the time the claim is
filed and so long thereafter as payment is deferred:
(a) The
property must be the homestead of the taxpayer claiming the deferral.
(b) The
taxpayer claiming the deferral must, by himself or jointly with another person
residing in the homestead, own the fee simple estate or be purchasing the fee
simple estate under a recorded instrument of sale or own the mobile home or be
purchasing the mobile home under a recorded instrument of sale; except that
nonresidence of the joint owner in the homestead because of ill health of the
joint owner shall not prevent the taxpayer from meeting the requirement of this
paragraph (b).
(c) The
property for which the deferral is claimed must not be income-producing; except
that, for property tax years commencing on or after January 1, 2023, this
subsection (1)(c) does not apply if the taxpayer claiming the deferral is
sixty-five years of age or older, is a person called into military service, or
is the surviving spouse of a taxpayer who elects to continue the property tax
deferral pursuant to section 39-3.5-112.
(d)
Repealed.
(d.5)
(I) Either of the following applies to the property:
(A) The
owner of the property is a person who is sixty-five years of age or older, and
the total value of all liens of mortgages and deeds of trust on the property,
excluding any mortgage or deed of trust that the holder has agreed, on a form
designated by the state treasurer, to subordinate to the lien of the state for
deferred taxes, is less than or equal to seventy-five percent of the actual
value of the property, as determined by the county assessor; or
(B) The
owner of the property is a person called into military service and the total
value of all liens of mortgages and deeds of trust on the property, excluding
any mortgage or deed of trust that the holder has agreed, on a form designated
by the state treasurer, to subordinate to the lien of the state for deferred
taxes, is less than or equal to ninety percent of the actual value of the
property, as determined by the county assessor; except that, for property tax
years commencing on or after January 1, 2023, the limitation on the total value
of all liens of mortgages and deeds of trust on the property set forth in this
subsection (1)(d.5)(I)(B) does not apply if the owner of the property is a
person called into military service who has a home loan guaranteed by the
veterans administration of the United States.
(II)
For purposes of this subsection (1)(d.5), the actual value of the property
shall be the most recent appraisal by the county assessor as of the time the
claim for deferral is submitted to the county treasurer.
(e) All
real property taxes for years prior to the year for which the election is made
must be paid.
(f) The
cumulative value of the deferral provided in this section plus the interest
accrued on the deferral provided in section 39-3.5-105 (5) shall not exceed the
market value of the property less the value of all mortgages which constitute
liens upon the property and any other liens upon the property filed prior to
the date of recordation of the certificate for deferral.
Source:
L. 78: Entire
article added, p. 472, § 1, effective February 28, 1979. L. 79: Entire
section R&RE, p. 1411, § 2, effective January 1, 1980. L. 88: (1)(b)
amended and (1)(f) added, p. 1283, § 10, effective January 1, 1989. L. 2005:
(1)(d) amended and (1)(d.5) added, p. 877, § 1, effective June 1. L. 2021:
IP(1), IP(1)(d.5)(I), and (1)(d.5)(I)(B) amended, (SB 21-293), ch. 301, p.
1810, § 7, effective June 23. L. 2022: (1)(d.5)(II) amended, (SB
22-220), ch. 388, p. 2760, § 3, effective June 7. L. 2023: (1)(c) and
(1)(d.5)(I)(B) amended, (HB 23-1284), ch. 294, p. 1769, § 1, effective August
7. L. 2025: (1)(d.5)(I)(B) and (1)(d.5)(II) amended, (SB 25-261), ch.
425, p. 2413, § 3, effective July 1.
Editor's
note: Subsection
(1)(d)(II) provided for the repeal of subsection (1)(d), effective January 1,
2006. (See L. 2005, p. 877.)
39-3.5-103.5. State treasurer - program
administration - rules. (Repealed)
Source:
L. 2022: Entire
section added, (SB 22-220), ch. 388, p. 2760, § 4, effective June 7. L.
2025: Entire section repealed, (SB 25-261), ch. 425, p. 2413, § 4,
effective July 1.
39-3.5-104. Claim form - contents.
(1) A
taxpayer's claim for deferral must be in writing on a form prescribed by the
state treasurer and supplied by the county treasurer and must:
(a)
Describe the property;
(b)
Recite facts which establish eligibility for deferral under the provisions of
this article;
(c)
List all mortgages and deeds of trust which constitute liens upon the property,
together with the book and page number of the county records at which each is
recorded and the date of recordation;
(d)
List all mortgages which constitute liens upon a mobile home, together with the
street address and county where the record of any such mortgage is on file with
the authorized agent for the department of revenue;
(d.5)
On or after January 1, 2006, list the actual value of the property based on the
most recent appraisal by the county assessor;
(e)
Demonstrate that the cumulative value of the deferral plus the interest accrued
on the deferral does not exceed the market value of the property less the value
of all mortgages which constitute liens upon the property and any other liens
upon the property filed prior to the date of recordation of the certificate for
deferral.
(2) The
form prescribed by the state treasurer shall contain a statement, in bold-faced
type, that states substantially as follows:
IMPORTANT NOTICE TO PROPERTY OWNER:
YOU COULD LOSE YOUR PROPERTY IF THE CUMULATIVE AMOUNT OF THE DEFERRAL PLUS
INTEREST EXCEEDS THE MARKET VALUE OF YOUR PROPERTY LESS THE VALUE OF ANY LIENS.
Source:
L. 78: Entire
article added, p. 472, § 1, effective February 28, 1979. L. 79: Entire
section R&RE, p. 1412, § 3, effective January 1, 1980. L. 88:
(1)(d), (1)(e), and (2) added, p. 1284, §§ 12, 11, effective January 1, 1989. L.
2005: (1)(d.5) added, p. 878, § 2, effective June 1. L. 2022: IP(1)
amended, (SB 22-220), ch. 388, p. 2760, § 5, effective June 7. L. 2025:
IP(1) amended, (SB 25-261), ch. 425, p. 2413, § 5, effective July 1.
39-3.5-105. Listing of tax-deferred
property - tax as lien - interest accrual.
(1) If
eligibility for deferral of homestead property is established as provided in
this article 3.5, the county treasurer shall:
(a)
Enter in the county treasurer's records a notation that the property is
tax-deferred;
(b) (I)
Promptly, upon designation of the property as tax-deferred, issue a certificate
of deferral, on a form prescribed by the state treasurer, that includes the
name of the taxpayer, the description of the property, the amount of tax
deferred, and the year for which the deferral was granted. The county clerk and
recorder shall record the certificate in the county records and thereafter send
a copy of the certificate to the state treasurer. The county treasurer shall
give one copy of the certificate to the assessor and shall retain one copy in
the county treasurer's office.
(II)
Promptly, upon designation of a mobile home as tax-deferred, the owner of the
mobile home shall surrender title to the property to the county clerk and
recorder. The county clerk and recorder shall, pursuant to the provisions of
article 29 of title 38, make application with the department of revenue for
issuance of a new certificate of title with a record of the lien of the state
treasurer. This procedure shall be followed for each subsequent year that the
property is deferred. The county treasurer shall issue a certificate of
deferral, on a form prescribed by the state treasurer, that includes the name
of the taxpayer, the description of the property, the amount deferred, and the
tax year for which the deferral was granted, and shall send such certificate to
the state treasurer. The county treasurer shall give one copy of the
certificate to the county assessor and shall retain one copy in the county
treasurer's office. Upon satisfaction of the lien, the state treasurer shall
release the lien from the title.
(1.5)
Repealed.
(2)
Notwithstanding the requirements of section 39-1-119 (1), if a person holding
escrow funds for the payment of ad valorem taxes receives a copy of the
certificate of deferral relating to any tax-deferred property, he shall, no
later than thirty days after receiving said certificate, refund to the owner of
said property all funds held in escrow for the payment of ad valorem taxes on
said property which have been deferred.
(3)
Until otherwise required by this article, the county treasurer shall, in
subsequent years, continue to list the property as tax-deferred in the manner
provided in subsection (1) of this section.
(4) (a)
The lien for deferred taxes and interest shall attach on the date of
recordation of the certificate for deferral, shall be junior to any mortgage or
deed of trust recorded prior to the date of recording of such certificate,
shall have priority over all liens attaching subsequent to the date of
recording of such certificate, and shall not be foreclosed except as provided
in sections 39-3.5-110 to 39-3.5-112.
(b) The
lien for deferred taxes and interest for 1978 deferred taxes shall attach on
the date of recordation of the certificate of deferral, shall be junior to any
mortgage or deed of trust recorded prior to the date of recording of such
certificate, shall have priority over all liens attaching subsequent to the
date of recording of such certificate, and shall not be foreclosed except as
provided in sections 39-3.5-110 to 39-3.5-112.
(5) (a)
Repealed.
(b) On
and after May 1, 1999, interest shall accrue on all taxes deferred pursuant to
deferrals claimed prior to the 1999 calendar year at the rate of seven percent
per annum until the date on which such taxes are paid. Interest shall accrue on
all taxes deferred pursuant to deferrals claimed on and after January 1, 1999,
but prior to January 1, 2001, at the rate of seven percent per annum, beginning
May 1 of the calendar year in which the deferral is claimed, until the date on
which such taxes are paid.
(c)
Interest shall accrue on all taxes deferred pursuant to all deferrals claimed
on and after January 1, 2001, at a rate equivalent to the rate per annum on the
most recently issued ten-year United States treasury note, rounded to the
nearest one-tenth of one percent, as reported by the "Wall Street
Journal", as of February 1 of the calendar year in which such deferral is
claimed. Interest shall accrue on taxes deferred at the rate specified in this
paragraph beginning May 1 of the calendar year in which the deferral is claimed
until the date on which such taxes are paid.
(6) No
later than January 1 of each year, the state treasurer shall provide to each
county treasurer a list by owner and address of each property in the
treasurer's county that is subject to one or more property tax deferral liens
pursuant to this article 3.5 and the total amount of the lien or liens on the
property as of April 30 of the prior year.
Source:
L. 78: Entire
article added, p. 473, § 1, effective February 28, 1979. L. 79: Entire
section R&RE, p. 1412, § 4, effective January 1, 1980. L. 88: (1)(b)
amended, p. 1284, § 13, effective January 1, 1989. L. 98: (5) amended,
p. 679, § 1, effective August 5. L. 2000: (5)(b) amended and (5)(c)
added, p. 905, § 1, effective May 25. L. 2022: (1) amended and (1.5)
added, (SB 22-220), ch. 388, p. 2760, § 6, effective June 7. L. 2025:
(1) amended, (1.5) repealed, and (6) added, (SB 25-261), ch. 425, p. 2413, § 6,
effective July 1.
Editor's
note: Subsection
(5)(a)(II) provided for the repeal of subsection (5)(a), effective May 1, 1999.
(See L. 98, p. 679.)
39-3.5-105.5. Loan of state money to
taxpayers.
(1)
Upon approval by the state treasurer of a taxpayer's application to participate
in the property tax deferral program, the state treasurer shall make a loan to
the taxpayer in the amount certified as deferred in the taxpayer's certificate
of deferral. The loan shall be disbursed to a county treasurer on behalf of the
taxpayer pursuant to section 39-3.5-106 and shall be made from the moneys on
deposit in the state treasury that are not immediately required to be
disbursed.
(2)
Interest on a loan for property tax deferral shall accrue at the rate specified
in section 39-3.5-105 (5). The interest shall accrue beginning May 1 of the
calendar year in which the deferral is claimed until the date on which the loan
is repaid.
Source:
L. 2002: Entire
section added, p. 637, § 1, effective July 1. L. 2022: (2) amended, (SB
22-220), ch. 388, p. 2761, § 7, effective June 7.
39-3.5-105.7. Prior deferrals to be
treated as loans.
All
deferred real property tax paid by the state treasurer to a county treasurer
prior to July 1, 2002, shall be reclassified as an investment in a loan to a
taxpayer that was disbursed to a county treasurer on behalf of the taxpayer,
and all provisions of this article shall apply to the loan.
Source:
L. 2002: Entire
section added, p. 637, § 1, effective July 1.
39-3.5-106. State treasurer to pay
county treasurer an amount equivalent to deferred taxes.
(1)
Pursuant to section 39-3.5-105.5, the state treasurer shall loan the amount
certified as deferred in the certificate of deferral to a taxpayer deferring
property taxes under this article. By April 30, 2003, and by each April 30
thereafter, the state treasurer shall pay the amount of each taxpayer's loan to
the county treasurer in which the taxpayer's homestead property is located. The
total amount paid by the state treasurer shall be distributed by the county
treasurer in the same manner the tax would have been if regularly paid.
(2) The
state treasurer shall maintain an account for each tax-deferred property and
shall accrue interest, beginning May 1 of the calendar year in which the
deferral was claimed, on the amount certified as deferred in the certificate of
deferral. The state treasurer shall ensure that each account for tax-deferred
property complies with this article.
(3)
Repealed.
Source:
L. 78: Entire
article added, p. 474, § 1, effective February 28, 1979. L. 79: (2)
R&RE, p. 1413, § 5, effective January 1, 1980. L. 88: (2) amended,
p. 1285, § 14, effective January 1, 1989. L. 91: (1) and (2) amended, p.
1952, § 1, effective January 1, 1992. L. 2002: (1) amended, p. 638, § 2,
effective July 1. L. 2022: (3) added, (SB 22-220), ch. 388, p. 2761, §
8, effective June 7. L. 2025: (3) repealed, (SB 25-261), ch. 425, p.
2414, § 7, effective July 1.
39-3.5-107. Repayment of loans - release
of liens - disposition of payments.
(1) On
and after the date of payment by the state treasurer to the county treasurer as
provided in section 39-3.5-106, the right to receive repayment of a loan for
deferred taxes and to enforce the lien created by deferral shall be vested in
the state treasurer.
(2) If
repayment of a loan for deferred taxes is tendered to the county treasurer, the
county treasurer shall accept payment, give the payer a receipt for the
payment, and promptly transmit the money collected to the state treasurer.
(3)
Promptly upon receiving repayment of a loan for deferred taxes, the state
treasurer shall issue a release of the deferred tax lien, which release shall
be given or sent to the person making payment. Copies of the release shall be
sent to the treasurer and the assessor.
(4) All
interest received in payment for a loan for deferred taxes shall be credited to
the general fund by the state treasurer.
Source:
L. 78: Entire
article added, p. 474, § 1, effective February 28, 1979. L. 2002: Entire
section amended, p. 638, § 3, effective July 1. L. 2022: (2) amended,
(SB 22-220), ch. 388, p. 2761, § 9, effective June 7. L. 2025: (2)
amended, (SB 25-261), ch. 425, p. 2415, § 8, effective July 1.
39-3.5-108. Notice to taxpayer regarding
duty to claim deferral annually.
At the
time the treasurer sends the annual property tax notice to any taxpayer who has
claimed a deferral of property taxes in the previous calendar year, the
treasurer shall enclose a deferral notice. The deferral notice must be
substantially in the following form:
To: (name of taxpayer)
If you want to defer the
collection of ad valorem property taxes on your homestead for the assessment
year ending on December 31, ______, you must file a claim for deferral not
later than April 1, ______, with the office of the county treasurer. Forms for
filing the claims are available at the county treasurer's office.
If you fail to
file your claim for deferral on or before April 1, ______, your real property
taxes will be due and payable in accordance with the schedule set out in the
enclosed notice.
If you change your
permanent address at any time during the assessment year ending on December 31,
______, you must notify the county treasurer.
Source:
L. 78: Entire
article added, p. 474, § 1, effective February 28, 1979. L. 2022: Entire
section amended, (SB 22-220), ch. 388, p. 2762, § 10, effective June 7. L.
2025: Entire section amended, (SB 25-261), ch. 425, p. 2415, § 9, effective
July 1.
39-3.5-109. Failure to receive notices.
Failure to
receive the notice provided for in this article 3.5 is not a defense in any
proceeding for the collection of taxes or for the foreclosure of a tax lien. A
county treasurer is not personally liable for failure to give such notices.
Source:
L. 78: Entire
article added, p. 475, § 1, effective February 28, 1979. L. 2022: Entire
section amended, (SB 22-220), ch. 388, p. 2762, §11, effective June 7. L.
2025: Entire section amended, (SB 25-261), ch. 425, p. 2415, § 10,
effective July 1.
39-3.5-110. Events requiring repayment
of loans - notice to state treasurer.
(1) All
loans for deferred real property taxes, including accrued interest, shall
become payable subject to sections 39-3.5-111 and 39-3.5-112 when:
(a) The
taxpayer who claimed the tax deferral dies;
(b) The
property on which the taxes were deferred is sold or becomes subject to a
contract of sale, or title to the property is transferred to someone other than
the taxpayer who claimed the tax deferral;
(c) The
property is no longer the homestead of the taxpayer who claimed the deferral,
except in the case of a taxpayer required to be absent from such tax-deferred
property by reason of ill health or because the property is uninhabitable as a
result of natural causes;
(d) The
tax-deferred property no longer meets the requirement of section 39-3.5-103
(1)(c);
(d.5)
The tax-deferred property no longer meets the requirement of section 39-3.5-103
(1)(f), except in the case of a property whose value has decreased as a result
of natural causes; and
(e) The
location of the tax-deferred mobile home has changed either within the county
or to another county.
(1.5)
The exceptions related to natural causes set forth in subsections (1)(c) and
(1)(d.5) of this section apply for three years from the date of the natural
cause or until the date that the property is no longer valued as vacant
residential land, whichever date is sooner.
(2)
When the assessor or treasurer has reason to believe any of the circumstances
enumerated in this section has occurred, he shall promptly notify the state
treasurer.
Source:
L. 78: Entire
article added, p. 475, § 1, effective February 28, 1979. L. 79: (1)(d)
amended, p. 1413, § 6, effective January 1, 1980. L. 88: (1)(d) amended
and (1)(e) added, p. 1285, § 15, effective January 1, 1989. L. 2002:
IP(1) amended, p. 638, § 4, effective July 1. L. 2022: (1)(c) and (1)(d)
amended and (1)(d.5) and (1.5) added, (SB 22-220), ch. 388, p. 2762, § 12,
effective June 7.
39-3.5-111. Time for payment -
delinquencies.
(1)
Whenever any of the circumstances listed in section 39-3.5-110 occurs:
(a) No
further tax deferrals may be claimed on the property until all loans for unpaid
taxes, including previously deferred taxes and interest, have been paid.
(b) All
loans for deferred taxes and accrued interest shall be due and payable ninety
days after the circumstance occurs, except as provided in subsection (2) of
this section and in section 39-3.5-112.
(2) Any
provision of this section to the contrary notwithstanding, when the taxpayer
dies a loan for deferred taxes and accrued interest shall be due and payable
one year after the taxpayer's death.
(3) If
a loan for deferred taxes and accrued interest is not paid on the due date,
such amounts are delinquent as of that date, and the state treasurer may
foreclose the deferred tax lien.
(4)
Foreclosure by the state treasurer of deferred tax liens shall be in the same
manner as provided by law for the foreclosure of judgment liens. At the
foreclosure sale, the state treasurer or his representative shall bid on behalf
of the state of Colorado the amount of the deferred tax lien.
(5) If
the owner of the tax-deferred property elects to do so, he or she may convey
the property to the state of Colorado in lieu of paying a loan for deferred
taxes and accrued interest. Upon completion of such conveyance, all deferred
tax liens upon the property shall be extinguished, and all liability for
payment of a loan for deferred taxes and accrued interest shall be released.
(6) The
lien for deferred taxes shall be subject to and may be extinguished in a proper
foreclosure of a mortgage or deed of trust recorded prior to the date of
recording of the certificate of tax deferral. In any such foreclosure, any
notice that is required to be sent to the state by reason of the state's
holding of a lien for deferred taxes shall be sent to the state treasurer. All
other procedural matters for such foreclosure, including notice and time
limits, shall be as provided in the law pursuant to which the foreclosure is
brought.
(7)
Whenever the state forecloses a lien for deferred taxes, the interest in the
property obtained thereby shall be subject to foreclosure proceedings by the
holder of a mortgage or deed of trust recorded prior to the date of recording
of the certificate of tax deferral.
Source:
L. 78: Entire
article added, p. 475, § 1, effective February 28, 1979. L. 79: (4)
amended and (6) and (7) added, p 1666, § 139, effective July 19; (1)(b) amended
and (5) added, p. 1413, § 7, effective January 1, 1980. L. 2002: (1),
(2), (3), and (5) amended, p. 638, § 5, effective July 1. L. 2022: (3)
amended, (SB 22-220), ch. 388, p. 2763, § 13, effective June 7.
39-3.5-112. Election by spouse to
continue tax deferral.
(1)
Notwithstanding the provisions of section 39-3.5-110, when one of the
circumstances listed in section 39-3.5-110 (1)(a) or (1)(c) occurs, the spouse
of the taxpayer may elect to continue the property in its tax-deferred status
if:
(a) The
spouse of the taxpayer is or will be sixty years of age or older when the
circumstance occurs; and
(b) The
property is the homestead of the spouse of the taxpayer and meets the
requirements of section 39-3.5-103 (1)(b) and (1)(c).
(1.5)
(a) Notwithstanding the provisions of section 39-3.5-110 (1)(a), when a
taxpayer who claimed a tax deferral pursuant to this article 3.5 dies, the loan
for deferred real property taxes, including accrued interest, shall not become
payable if:
(I) The
taxpayer was a person called into military service or was a person eligible for
deferral under section 39-3.5-102 (1)(c);
(II)
The taxpayer is survived by a spouse; and
(III)
The property is the homestead of the surviving spouse and meets the
requirements of section 39-3.5-103 (1)(b) and (1)(c).
(b) If
paragraph (a) of this subsection (1.5) applies, a loan for deferred real
property taxes, including accrued interest, shall become payable when the
spouse of the taxpayer dies, in addition to the events set forth in section
39-3.5-110.
(2) The
election granted under subsection (1) of this section shall be filed in the
same manner as a claim for deferral is filed under section 39-3.5-102, not
later than ninety days from the date the circumstance occurs. Thereafter, the
property shall continue to be treated as tax-deferred property, and the county
treasurer and state treasurer shall withdraw any action taken under section
39-3.5-111. When the property has been continued in its tax-deferred status by
the spouse of the taxpayer, the spouse may continue the property in its
tax-deferred status in subsequent years by filing a claim, as provided in
section 39-3.5-104, annually if the property continues to be eligible for
tax-deferred status.
Source:
L. 78: Entire
article added, p. 475, § 1, effective February 28, 1979. L. 79: IP(1)
and (2) amended, p. 1414, § 8, effective January 1, 1980. L. 2005: (1.5)
added, p. 878, § 3, effective June 1. L. 2021: IP(1.5)(a) and
(1.5)(a)(I) amended, (SB 21-293), ch. 301, p. 1810, § 8, effective June 23.
39-3.5-113. Voluntary repayment of loans
for deferred tax.
(1)
Subject to subsection (2) of this section, all or part of a loan for deferred
taxes and accrued interest may, at any time, be paid by the taxpayer, his or
her spouse, guardian, conservator, attorney-in-fact, personal representative,
next of kin, heir-at-law, or child, or any person having or claiming a legal or
equitable interest in the property. If the deferred tax lien is paid, in whole
or in part, by a mortgagee or the beneficiary of a deed of trust or seller
under contract, the amount paid may be added to the unpaid balance of the
mortgage or deed of trust but shall be added to the last payment due under said
mortgage or deed of trust or contract, without amortization.
(2) Any
payment made under this section shall be applied first to accrued interest and
then to a loan for deferred taxes. Such payment does not affect the deferred
tax status of the property. Voluntary payment does not give the person paying
the taxes any interest in the property.
Source:
L. 78: Entire
article added, p. 476, § 1, effective February 28, 1979. L. 2002: Entire
section amended, p. 639, § 6, effective July 1.
39-3.5-114. Deferred tax certificates
not to be included in reserve or surplus. (Repealed)
Source:
L. 78: Entire
article added, p. 476, § 1, effective February 28, 1979. L. 2002: Entire
section repealed, p. 639, § 7, effective July 1.
39-3.5-115. Limitations on effect of
article.
Nothing in
this article is intended to or shall be construed to prevent the collection, by
foreclosure or otherwise, of personal property or other taxes which become a
lien against tax-deferred property.
Source:
L. 78: Entire
article added, p. 476, § 1, effective February 28, 1979.
39-3.5-116. Deed or contract clauses
preventing application for deferral prohibited - clauses void. (Repealed)
Source:
L. 78: Entire
article added, p. 476, § 1, effective February 28, 1979. L. 79: Entire
section repealed, p. 1414, § 11, effective January 1, 1980.
39-3.5-117. Report. (Repealed)
Source:
L. 78: Entire
article added, p. 477, § 1, effective February 28, 1979. L. 79: Entire
section amended, p. 1414, § 9, effective January 1, 1980. L. 88: Entire
section amended, p. 1308, § 2, effective May 29. L. 92: Entire section
amended, p. 2182, § 53, effective June 2. L. 2002: Entire section
repealed, p. 862, § 4, effective August 7.
39-3.5-118. Emergency property tax
deferral for depositors of troubled industrial banks. (Repealed)
Source:
L. 88: Entire
section added, p. 1307, § 1, effective May 29.
Editor's
note: Subsection
(7) provided for the repeal of this section, effective June 30, 1990. (See L.
88, p. 1307.)
39-3.5-119. Release of information
identifying individuals claiming deferral.
(1)
Notwithstanding the provisions of part 2 of article 72 of title 24, C.R.S., or
any other provision of law to the contrary, county treasurers and the state
treasurer shall deny requests from individuals, corporations, or other private
entities to inspect or produce the names, addresses, phone numbers, social
security numbers, or other information identifying individuals who claim
deferrals pursuant to this article.
(2)
Nothing in this section shall be construed to prohibit individuals from
examining records recorded in county records by the county clerk and recorder
nor shall it be construed to prohibit the disclosure of information:
(a)
Required in connection with granting or denying a claim for deferral;
(b)
Required in connection with an administrative, judicial, or other legal
proceeding;
(c)
Required in connection with the conveyance, sale, or encumbrance of a specific
property;
(d)
When the information is contained in a statistical compilation or other
informational summary that does not disclose individual identifying
information; or
(e)
When the individual claiming the exemption has agreed to the disclosure.
Source:
L. 2001: Entire
section added, p. 296, § 1, effective August 8.
39-3.5-120. Expansion of deferral
program - consultation - repeal. (Repealed)
Source:
L. 2021: Entire
section added, (SB 21-293), ch. 301, p. 1810, § 9, effective June 23.
Editor's
note: Subsection
(2) provided for the repeal of this section, effective July 1, 2022. (See L.
2021, p. 1810.)
ARTICLE
3.7
Property
Tax Work-off Program for the Elderly
39-3.7-101. Definitions.
39-3.7-102. Property tax work-off program -
creation - terms.
39-3.7-101. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Homestead" means the owner-occupied residence of the taxpayer and
includes owner-occupied units in a condominium, townhouse, or similar
structure.
(1.5)
"Person with a disability" means any person with a physical
impairment or an intellectual and developmental disability as defined in
section 25.5-10-202, C.R.S.
(2)
"Property tax work-off program" means any program established
pursuant to the provisions of this article.
(3)
"Real property taxes" means all ad valorem taxes levied on a
homestead, including special assessments and all other charges which are
recoverable, by law, at the annual real estate tax sale.
(4)
"Taxing entity" means any county, city and county, city, town, school
district, or special district within the state of Colorado.
Source:
L. 91: Entire
article added, p. 1995, § 1, effective April 11. L. 2003: (1.5) added,
p. 841, § 1, effective August 6. L. 2013: (1.5) amended, (HB 13-1314),
ch. 323, p. 1813, § 54, effective March 1, 2014.
39-3.7-102. Property tax work-off
program - creation - terms.
(1) Any
taxing entity that levies and collects real property taxes may establish a
property tax work-off program in accordance with this article 3.7 that allows
any taxpayer who is sixty years of age or older, is a first responder with a
permanent occupational disability as defined in section 33-4-104.5 (2), or who
is otherwise a person with a disability to perform work for the taxing entity
in lieu of the payment of any real property taxes, or any portion thereof, due
and owing on the homestead of such taxpayer for any given property tax year.
(2) In
order to qualify for participation in any property tax work-off program created
pursuant to the provisions of this article, the following requirements shall be
satisfied at the time the application is filed and so long thereafter as the
taxpayer may participate in such property tax work-off program:
(a) The
property on which the property taxes are due and owing is the homestead of the
taxpayer making application.
(b) The
taxpayer making application must, singly or jointly with another person
residing in the homestead, own the fee simple estate or be purchasing the fee
simple estate under a recorded instrument of sale; except that nonresidence of
the joint owner in the homestead because of ill health of the joint owner shall
not prevent the taxpayer from meeting the requirements of this paragraph (b).
(c) The
property on which the property taxes are due and owing is not income-producing.
(3) The
number of hours of work to be performed by a taxpayer pursuant to any property
tax work-off program shall be based upon the calculation of the amount of
property taxes, or portion thereof, to be worked off divided by the minimum
wage as set by federal law.
(4) A
property tax work-off program shall be created upon the adoption of a
resolution or ordinance, whichever is appropriate, by the governing body of
such taxing entity. Such resolution or ordinance shall be in accordance with
the provisions of this article and shall include, but shall not be limited to,
the following: Procedures for application for participation in such property
tax work-off program; the maximum number of taxpayers allowed to participate in
such property tax work-off program; procedures for verification of work
performed; procedures for the issuance of checks to taxpayers for the amount of
property tax worked off by such taxpayers pursuant to such property tax
work-off program; and such other provisions which such taxing entity deems
reasonable and necessary for the implementation and operation of such property
tax work-off program.
(4.5)
For each property tax year in which a taxpayer participates in a property tax
work-off program pursuant to the provisions of this section, the taxing entity
which has established such program shall issue a check or checks to such
taxpayer which shall be made payable only to the appropriate county treasurer.
The taxpayer shall be responsible for the delivery of the check or checks to
the county treasurer in order for such amount to be credited to the property
tax which is due and owing on the homestead of the taxpayer for such property
tax year.
(5) Any
taxing entity which establishes a property tax work-off program pursuant to the
provisions of this article shall make information regarding such program
available to the taxpayers of the taxing entity.
(6) Any
taxpayer who is a first responder with a permanent occupational disability as
defined in section 33-4-104.5 (2) or who is otherwise a person with a
disability, and who applies to participate in a property tax work-off program
pursuant to this article 3.7 shall, upon application, submit either a signed
and dated letter from the fire and police pension association verifying that
the taxpayer is a first responder with a permanent occupational disability or a
signed and dated letter from a Colorado licensed health-care professional
verifying that the taxpayer is a person with a disability. Any taxing entity
that establishes a property tax work-off program pursuant to this section has
the authority to further define the term "person with a disability"
for purposes of determining eligibility for the property tax work-off program.
The definition may restrict, but must not expand, the class of individuals who
are eligible to participate in the property tax work-off program pursuant to
this section.
Source:
L. 91: Entire
article added, p. 1995, § 1, effective April 11. L. 92: (4) amended and
(4.5) added, p. 2242, § 1, effective March 16. L. 2003: (1) amended and
(6) added, p. 841, § 2, effective August 6. L. 2019: (1) and (6)
amended, (HB 19-1080), ch. 222, p. 2251, § 3, effective August 2.
ARTICLE
3.9
Optional
Nongaming Property Tax Deferral Plan
39-3.9-101 to 39-3.9-106. (Repealed)
Editor's
note: (1) This
article was added in 1993 and was not amended prior to its repeal in 1996. For
the text of this article prior to 1996, consult the Colorado statutory research
explanatory note and the table itemizing the replacement volumes and
supplements to the original volume of C.R.S. 1973 beginning on page vii in the
front of this volume.
(2) Section 39-3.9-106 provided
for the repeal of this article, effective December 31, 1996. (See L. 93, p.
346.)
Valuation
and Taxation
ARTICLE
4
Valuation
of Public Utilities
39-4-101. Definitions.
39-4-102. Valuation of public utilities -
legislative declaration - definition.
39-4-103. Schedules of property -
confidential records - late filing penalties.
39-4-104. Inspection of records of utility.
39-4-105. Production of records.
39-4-106. Valuation of utilities -
apportionment.
39-4-107. Statement of valuation to counties.
39-4-108. Complaint - hearing - decision.
39-4-109. Judicial review.
39-4-110. Certification and assessment of
pollution control property. (Repealed)
39-4-101. Definitions.
As used in
this article 4, unless the context otherwise requires:
(1)
"Aircraft" means any contrivance now known or hereafter invented,
used, or designed for navigation or flight through the air and designed to
carry at least one person.
(2)
"Airline company" means any operator who engages in the carriage by
aircraft of persons or property as a common carrier for compensation or hire,
or the carriage of mail, or any aircraft operator who operates regularly
between two or more points and publishes a flight schedule. "Airline
company" shall not include operators whose aircraft are all certified for
a gross takeoff weight of twelve thousand five hundred pounds or less and who
do not engage in scheduled or mail carriage service.
(2.3)
"Biomass energy facility" means a new facility first placed in
production on or after January 1, 2010, that uses real and personal property,
including leaseholds and easements, to generate and deliver to the
interconnection meter any source of electrical or mechanical energy by
combusting only biomass or biosolids derived from the treatment of wastewater
and that is not primarily designed to supply electricity for consumption on
site.
(2.4)
(a) Except as provided in subsection (2.4)(b) of this section, "clean
energy resource" has the same meaning as set forth in section 40-2-125.5
(2)(b).
(b)
"Clean energy resource", for purposes of property taxation under this
section, does not include nuclear energy.
(2.5)
Repealed.
(2.6)
"Energy storage system" means commercially available technology that
is capable of retaining electricity, storing the energy for a period of time,
and delivering the electricity after storage by chemical, thermal, mechanical,
or other means. "Energy storage system" does not include a solar
energy facility, as defined in subsection (3.5) of this section, or a wind
energy facility, as defined in subsection (4) of this section.
(2.7)
"Geothermal energy facility" means a new facility first placed in
production on or after January 1, 2010, that uses real and personal property,
including but not limited to leaseholds and easements, to generate and deliver
to the interconnection meter any source of electrical or mechanical energy by
harnessing the heat energy of groundwater or the ground and that is not
primarily designed to supply electricity for consumption on site.
(3) (a)
"Public utility" means, for property tax years commencing on or after
January 1, 1987, every sole proprietorship, firm, limited liability company,
partnership, association, company, or corporation, and the trustees or
receivers thereof, whether elected or appointed, that does business in this
state as a railroad company, airline company, electric company, small or low
impact hydroelectric energy facility, geothermal energy facility, biomass
energy facility, wind energy facility, solar energy facility, energy storage
system, clean energy resource, rural electric company, telephone company,
telegraph company, gas company, gas pipeline carrier company, domestic water
company selling at retail except nonprofit domestic water companies, pipeline
company, coal slurry pipeline, or private car line company.
(b) On
and after January 1, 2010, for purposes of this article 4, "public
utility" does not include any affiliate or subsidiary of a sole
proprietorship, firm, limited liability company, partnership, association,
company, or corporation of any type of company described in subsection (3)(a)
of this section that is not doing business in the state primarily as a railroad
company, airline company, electric company, small or low impact hydroelectric
energy facility, geothermal energy facility, biomass energy facility, wind
energy facility, solar energy facility, energy storage system, clean energy
resource, rural electric company, telephone company, telegraph company, gas
company, gas pipeline carrier company, domestic water company selling at retail
except nonprofit domestic water companies, pipeline company, coal slurry
pipeline, or private car line company. Valuation and taxation of any such
affiliate or subsidiary of a public utility as defined in subsection (3)(a) of
this section shall be assessed pursuant to article 5 of this title 39.
(3.3)
(a) "Small or low impact hydroelectric energy facility" means a
new facility first placed in production on or after January 1, 2010, that uses
real and personal property, including but not limited to leaseholds and
easements, to generate and deliver to the interconnection meter any source of
electrical or mechanical energy by harnessing the kinetic energy of water, that
is not primarily designed to supply electricity for consumption on site, and
that is:
(I) A
new facility that is a small facility that has a nameplate rating of ten
megawatts or less; or
(II) A
new facility that has a nameplate rating of more than ten megawatts and that:
(A) Is
an addition to water infrastructure such as a reservoir, a ditch, or a pipeline
that existed before January 1, 2010;
(B)
Does not result in any change in the quantity or timing of diversions or
releases for purposes of peak power generation;
(C)
Includes measures to prevent fish mortality in facilities on on-stream
reservoirs and natural waterways; and
(D)
Does not cause any violation of state water quality standards when operated; or
(III) A
new facility that has a nameplate rating of more than ten megawatts and that:
(A) Is
placed into production as part of new water infrastructure such as a reservoir,
a ditch, or a pipeline constructed on or after January 1, 2010, and operated
for primary beneficial uses of water other than solely for production of
electricity;
(B)
Includes measures to prevent fish mortality in facilities on reservoirs and
natural waterways; and
(C)
Does not cause any violation of state water quality standards when operated.
(b) For
purposes of this subsection (3.3), "new facility" includes a combined
facility that is a combination of a facility placed in production before
January 1, 2010, that uses real and personal property to generate and deliver
to the interconnection meter any source of electric or mechanical energy by
harnessing the kinetic energy of water and that is not primarily designed to
supply energy for consumption on site and an addition or energy efficiency
improvement to the facility first placed in production on or after January 1,
2010, if the addition or efficiency improvement increases the electrical or
mechanical energy-producing capacity of the combined facility by at least
twenty-five percent over the capacity of the facility placed in production before
January 1, 2010, alone.
(3.5)
(a) "Solar energy facility" means a new facility first placed in
production on or after January 1, 2009, that uses real and personal property,
including one or more solar energy devices, as defined in section 38-32.5-100.3
(2), leaseholds, and easements, to generate and, except as provided in
subsection (3.5)(b) of this section, deliver to the interconnection meter any
source of electrical, thermal, or mechanical energy in excess of two megawatts
by harnessing the radiant energy of the sun, including any connected device for
which the primary purpose is to store energy, and that is not primarily
designed to supply electricity for consumption on site.
(b)
"Solar energy facility" includes facilities for agrivoltaics, as
defined in section 35-1-114 (4)(a), and for floatovoltaics, as defined in
section 37-60-115 (12)(c)(III).
(4)
"Wind energy facility" means a new facility first placed in
production on or after January 1, 2006, that uses property, real and personal,
including one or more wind turbines, leaseholds, and easements, to generate and
deliver to the interconnection meter any source of electrical or mechanical
energy in excess of two megawatts by harnessing the kinetic energy of the wind,
including any connected device for which the primary purpose is to store
energy.
Source:
L. 64: R&RE,
p. 688, § 1. C.R.S. 1963: § 137-4-1. L. 76: Entire section
amended, p. 768, § 1, effective April 26; entire section amended, p. 759, § 16,
effective July 1, 1977. L. 81: (2.5) added and (3) amended, p. 1854, §§
3, 4, effective January 1, 1982; (3) amended, p. 1847, § 1, effective January
1, 1982. L. 82: (2.5) amended, p. 628, § 41, effective April 2. L.
83: (2.5) and (3) amended, p. 1496, § 3, effective April 28. L. 84:
(2.5) and (3) amended, p. 989, § 2, effective February 23; (2.5) and (3)
amended, p. 997, § 2, effective May 22. L. 90: (3) amended, p. 450, §
27, effective April 18. L. 2000: (3) amended, p. 1738, § 2, effective
June 1. L. 2006: (3) amended and (4) added, p. 889, § 1, effective May
9. L. 2008: (4) amended, p. 1319, § 2, effective May 27. L. 2009:
(3) amended and (3.5) added, (SB 09-177), ch. 186, p. 812, § 1, effective April
22. L. 2010: (3) amended and (3.3) added, (SB 10-019), ch. 382, p. 1784,
§ 1, effective June 8; (2.3) added and (3) amended, (SB 10-177), ch. 392, p.
1862, § 3, effective August 11; (2.4) added and (3) amended, (SB 10-174), ch.
189, p. 813, § 8, effective August 11. L. 2021: IP, (2.4), (3), (3.5),
and (4) amended and (2.6) and (2.7) added, (SB 21-020), ch. 51, p. 215, § 1,
effective September 7. L. 2023: (3.5) amended, (SB 23-092), ch. 218, p.
1132, § 6, effective August 7. L. 2025: (2.4) amended, (HB 25-1040), ch.
45, p. 209, § 4, effective August 6.
Editor's
note: (1)
Subsection (2.5) provided for the repeal of subsection (2.5), effective January
1, 1987. (See L. 84, p. 989.)
(2) Amendments to this section
by House Bill 76-1235 and House Bill 76-1025 were harmonized. Amendments to
subsection (3) by House Bill 81-1309 and Senate Bill 81-025 were harmonized.
Amendments to subsections (2.5) and (3) by House Bill 84-1051 and Senate Bill
84-214 were harmonized. Amendments to subsection (3) by Senate Bill 10-019,
Senate Bill 10-174, and Senate Bill 10-177 were harmonized.
Cross
references: For
the legislative intent contained in the 2008 act amending subsection (4), see
section 9 of chapter 302, Session Laws of Colorado 2008. For the legislative
declaration in HB 25-1040, see section 1 of chapter 45, Session Laws of
Colorado 2025.
ANNOTATION
Since the general assembly
failed to define "telephone company" as used in the definition of
"public utility" in this section, it must be assumed that the general
assembly intended to give the term its usual and ordinary meaning. Transponder
Corp. of Denver v. Propty. Tax Adm'r, 681 P.2d 499 (Colo. 1984); U.S.
Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo. 1986).
Because the company directly
facilities two-way communication between a significant number of unrelated
persons or businesses, the company is a "telephone company". U.S.
Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo. 1986).
"Public
utilities". There is no evidence that the general assembly intended to
limit its definition of "public utility" for property tax purposes to
those companies that are regulated monopolies. U.S. Transmission Sys. v. Bd. of
Assmt. Appeals, 715 P.2d 1249 (Colo. 1986).
Because the petitioner was
doing business as a "telephone company" within the state of Colorado
it was a public utility subject to unitary valuation for property tax
assessment. U.S. Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249
(Colo. 1986).
A nonfacilities-based
reseller of long distance telephone services is a telephone company within the
meaning of subsection (3)(a). OPEX Commc'ns, Inc. v. Prop. Tax Adm'r, 166
P.3d 225 (Colo. App. 2007).
Applied in State Pers.
Bd. v. District Court, 637 P.2d 333 (Colo. App. 1981).
39-4-102. Valuation of public
utilities - legislative declaration - definition.
(1) The
administrator shall determine the actual value of the operating property and
plant of each public utility as a unit, giving consideration to the following
factors and assigning such weight to each of such factors as in the
administrator's judgment will secure a just value of such public utility as a
unit:
(a) The
tangible property comprising its plant, whether the same is situated within
this state or both within and without this state, exclusive of any tangible
property situated without this state which is not directly connected with the
business in which such public utility is engaged within this state;
(b) Its
intangibles, such as special privileges, franchises, contract rights and
obligations, and rights-of-way; except that licenses granted by the federal
communications commission to a wireless carrier, as defined in section
29-11-101, C.R.S., shall not be considered, nor shall the value of such
licenses be reflected, in the administrator's valuation of the carrier's
tangible property;
(c) Its
gross and net operating revenues during a reasonable period of time not to
exceed the most recent five-year period, capitalized at indicative rates;
(d) The
average market value of its outstanding securities during the preceding
calendar year, if such market value is determinable;
(e) (I)
When determining the actual value of a renewable energy facility that primarily
produces more than two megawatts of alternating current electricity, the
administrator shall:
(A)
Consider the additional incremental cost per kilowatt of the construction of
the renewable energy facility, taking into account the nameplate capacity of
any energy storage system in addition to generation capacity, over that of the
construction cost of a comparable nonrenewable energy facility, inclusive of
the cost of all property required to generate and deliver energy to the
interconnection meter, that primarily produces alternating current electricity
to be an investment cost and shall not include the additional incremental cost
in the valuation of the facility; and
(B) Not
add value to a renewable energy facility for any renewable energy credits
created by the production of alternating current electricity.
(II)
For purposes of this paragraph (e), "renewable energy" has the
meaning provided in section 40-1-102 (11), C.R.S., but shall not include energy
generated from a small or low impact hydroelectric energy facility, a
geothermal energy facility, a biomass energy facility, a wind energy facility,
or a solar energy facility.
(III)
(A) For purposes of determining the actual value of a renewable energy
facility as specified in subparagraph (I) of this paragraph (e), an owner or
operator of a facility shall provide a copy of the facility's current power
purchase agreement to the administrator by April 1 of each assessment year as
an attachment to the statement required as specified in section 39-4-103 (1);
except that, if a copy of the current power purchase agreement was previously
provided either by the owner or operator or by the purchaser of power and there
is no material change in the facility's current power purchase agreement, the
owner or operator of a facility shall not be required to provide a copy of the
agreement.
(B) If
the owner or operator of a facility does not provide a copy of the facility's
current power purchase agreement as specified in sub-subparagraph (A) of this
subparagraph (III), the administrator shall have the authority to request a
copy of the current power purchase agreement from the purchaser of power
generated at the facility; except that, if a copy of the current power purchase
agreement was previously provided either by the owner or operator or by the
purchaser of power and there is no material change in the facility's current
power purchase agreement, the purchaser of power shall not be required to
provide a copy of the agreement.
(C) All
power purchase agreements provided to the administrator pursuant to this
subparagraph (III) shall be considered private documents and shall be available
only to the administrator and the employees of the division of property
taxation in the department of local affairs.
(1.5)
The administrator shall determine the actual value of a small or low impact
hydroelectric energy facility, a geothermal energy facility, a biomass energy
facility, a wind energy facility, or a solar energy facility as follows:
(a) The
general assembly hereby declares that initial consideration by the
administrator of the cost approach and market approach to the appraisal of a
wind energy facility or a solar energy facility results in valuations that are
neither uniform nor just and equal because of wide variations in the production
of energy from wind turbines and solar energy devices, as defined in section
38-32.5-100.3 (2), because of the uncertainty of wind and sunlight available
for energy production, and because constructing a wind energy facility or a
solar energy facility is significantly more expensive than constructing any
other utility production facility. The general assembly further declares that
it is also appropriate to initially value small or low impact hydroelectric
energy facilities, geothermal energy facilities, and biomass energy facilities,
which also have high construction costs relative to their ongoing operational
costs, using the income approach. Therefore, in the absence of preponderant
evidence shown by the administrator that the use of the cost approach and
market approach results in uniform and just and equal valuation, a small or low
impact hydroelectric energy facility, a geothermal energy facility, a biomass
energy facility, a wind energy facility, or a solar energy facility shall be
initially valued based solely upon the income approach.
(b) (I)
For a property tax year that a tax factor applies, the actual value of a small
or low impact hydroelectric energy facility, a geothermal energy facility, a
biomass energy facility, a wind energy facility, or a solar energy facility is
an amount equal to a tax factor times the selling price at the interconnection
meter. For a property tax year that a tax factor does not apply, the
administrator shall determine the actual value of the facility giving
appropriate consideration to the cost, income, and market approaches; except
that the actual value shall not exceed the depreciated value floor calculated
using the cost basis method of taxation as determined by the administrator for
a renewable energy facility pursuant to subsection (1)(e) of this section.
(II) As
used in this article, "interconnection meter" means the meter located
at the point of delivery of energy to the purchaser.
(III)
As used in this paragraph (b), "selling price at the interconnection
meter" means the gross taxable revenues realized by the taxpayer from the
sale of energy at the interconnection meter.
(IV) As
used in this subsection (1.5)(b), "tax factor" means a factor
annually established by the administrator. For a facility that begins
generating energy before January 1, 2021, the tax factor is a number that when
applied to the selling price at the interconnection meter results in
approximately the same tax revenue over a twenty-year period on a nominal
dollar basis that would have been collected using the cost basis method of
taxation as determined by the administrator for a renewable energy facility
pursuant to subsection (1)(e) of this section. For a facility that begins
generating energy on or after January 1, 2021, the tax factor is a number that,
when applied to the selling price at the interconnection meter, results in
approximately the same tax revenue over a thirty-year period on a nominal
dollar basis that would have been collected using the cost basis method of
taxation as determined by the administrator for a renewable energy facility
pursuant to subsection (1)(e) of this section. After the first twenty or thirty
years of a facility's life, as applicable, a tax factor is not applied. For a
renewable energy facility that begins generating energy before January 1, 2012,
the administrator shall include only the cost of all property required to
generate and deliver renewable energy to the interconnection meter that does
not exceed the cost of property required to generate nonrenewable energy. For a
renewable energy facility that begins generating energy on or after January 1,
2012, the administrator shall include only the cost of all property required to
generate, store, and deliver renewable energy to the interconnection meter that
does not exceed the cost of property required to generate and deliver
nonrenewable energy to the interconnection meter.
(V) For
purposes of calculating the tax factor as required in subparagraph (IV) of this
paragraph (b), an owner or operator of a small or low impact hydroelectric
energy facility, a geothermal energy facility, a biomass energy facility, a
wind energy facility, or a solar energy facility shall provide a copy of the
small or low impact hydroelectric energy facility's, geothermal energy
facility's, biomass energy facility's, wind energy facility's, or solar energy
facility's current power purchase agreement to the administrator by April 1 of
each assessment year. The administrator shall also have the authority to
request a copy of the current power purchase agreement from the purchaser of
power generated at a small or low impact hydroelectric energy facility, a
geothermal energy facility, a biomass energy facility, a wind energy facility,
or a solar energy facility. All agreements provided to the administrator
pursuant to this subparagraph (V) shall be considered private documents and
shall be available only to the administrator and the employees of the division
of property taxation in the department of local affairs.
(c) The
location of a small or low impact hydroelectric energy facility, a geothermal
energy facility, a biomass energy facility, a wind energy facility, or a solar
energy facility on real property shall not affect the classification of that
real property for purposes of determining the actual value of that real
property as provided in section 39-1-103.
(d)
Pursuant to section 39-3-118.5, no actual value for any personal property used
in a small or low impact hydroelectric energy facility, a geothermal energy
facility, a biomass energy facility, a wind energy facility, or a solar energy
facility shall be assigned until the personal property is first put into use by
the facility. If any item of personal property is used in the facility and is
subsequently taken out of service so that no small or low impact hydroelectric
energy, geothermal energy, biomass energy, wind energy, or solar energy is
produced from that facility for the preceding calendar year, no actual value
shall be assigned to that item of more than five percent of the installed cost
of the item for that assessment year.
(e) The
administrator shall determine the actual value of an energy storage system or
clean energy resource in a manner similar to the method used for a small or low
impact hydroelectric energy facility, a wind energy facility, a geothermal
energy facility, a biomass energy facility, or a solar energy facility under
subsection (1)(e) of this section and this subsection (1.5).
(2) If,
in the judgment of the administrator, the books and records of any public
utility accurately reflect its tangible property, its intangibles, and its
earnings within this state during the most recent five-year period, the
administrator may determine from such books and records the actual value of its
property and plant within this state and need not determine the entire value of
its property and plant both within and without this state.
(3) (a)
For property tax years 1982 through 1986, there shall be applied to the actual
value of each public utility an equalization factor to adjust the actual value
for the current year of assessment as determined by the administrator pursuant
to subsections (1) and (2) of this section to the public utility's level of
value in 1981.
(b) For
property tax years commencing on or after January 1, 1987, there shall be
applied to the actual value of each public utility an equalization factor to
adjust the actual value for the current year of assessment as determined by the
administrator pursuant to subsections (1) and (2) of this section to the public
utility's level of value in the appropriate year that is prescribed in section
39-1-104 (10.2) and that is used to determine the actual value of properties
that are subject to said applicable subsection.
(c)
Appraisal procedures, instructions, and factors utilized by the administrator
in carrying out the provisions of this section shall be subject to legislative
review, the same as rules and regulations, pursuant to section 24-4-103 (8)(d),
C.R.S.
(d) The
administrator shall certify to the public utility any difference in valuation
resulting from the application of this section. Said certification shall be
part of the evidence presented in determining rate structures by any applicable
rate-setting body.
Source:
L. 64: R&RE,
p. 688, § 1. C.R.S. 1963: § 137-4-2. L. 67: p. 948, § 12. L.
70: p. 382, § 15. L. 81: (3) added, p. 1847, § 2, effective January
1, 1982. L. 83: (3)(a) and (3)(b) amended, p. 1496, § 4, effective April
28. L. 84: (3)(a) and (3)(b) amended, p. 989, § 3, effective February
23. L. 91: (3)(b) amended, p. 2005, § 4, effective June 6. L. 95:
(3)(b) amended, p. 8, § 3, effective March 9. L. 98: (1)(b) amended, p.
1267, § 1, effective June 1. L. 2001: IP(1) amended and (1)(e) added, p.
1523, § 1, effective August 8. L. 2004: (1)(b) amended, p. 1208, § 87,
effective August 4. L. 2006: (1)(e) amended and (1.5) added, p. 890, §
2, effective May 9. L. 2008: (1)(e) and (1.5)(b)(V) amended, p. 1319, §
3, effective May 27; (1)(b) amended, p. 685, § 5, effective August 5. L.
2009: (1)(e)(II), IP(1.5), (1.5)(a), (1.5)(b)(I), (1.5)(b)(IV),
(1.5)(b)(V), (1.5)(c), and (1.5)(d) amended, (SB 09-177), ch. 186, p. 813, § 2,
effective April 22. L. 2010: (1)(e)(II), IP(1.5), (1.5)(a), (1.5)(b)(I),
(1.5)(b)(V), (1.5)(c), and (1.5)(d) amended, (SB 10-019), ch. 382, p. 1786, §
2, effective June 8; (1)(e)(I)(A) and (1.5)(b)(IV) amended, (HB 10-1431), ch.
372, p. 1743, § 1, effective August 11; (1)(e)(II), IP(1.5), (1.5)(a),
(1.5)(b)(I), (1.5)(b)(V), (1.5)(c), and (1.5)(d) amended, (SB 10-174), ch. 189,
p. 814, § 9, effective August 11; (1)(e)(II), IP(1.5), (1.5)(a), (1.5)(b)(I),
(1.5)(b)(V), (1.5)(c), and (1.5)(d) amended, (SB 10-177), ch. 392, p. 1862, §
4, effective August 11. L. 2021: (1)(e)(I)(A), (1.5)(a), (1.5)(b)(I),
and (1.5)(b)(IV) amended and (1.5)(e) added, (SB 21-020), ch. 51, p. 216, § 2,
effective September 7.
Editor's
note: Amendments
to subsection (1)(e)(II), the introductory portion to subsection (1.5), and
subsections (1.5)(a), (1.5)(b)(I), (1.5)(b)(V), (1.5)(c), and (1.5)(d) by
Senate Bill 10-019, Senate Bill 10-174, and Senate Bill 10-177 were harmonized.
Cross
references: For
the legislative intent contained in the 2008 act amending subsections (1)(e)
and (1.5)(b)(V), see section 9 of chapter 302, Session Laws of Colorado 2008.
ANNOTATION
Different valuation method
for public utilities is constitutional. While a public utility may have a
different tax burden compared to a competitor that is not a public utility,
this difference does not violate the state and federal equal protection clauses
or the uniform taxation clause, art. X, § 3(1)(a), of the state constitution.
Qwest v. Colo. Div. of Prop. Taxation, 2013 CO 39, 304 P.3d 217.
No statutory conflict.
The requirement of this section that a public utility's intangibles be
considered when valuing such utility's operating property and plant as a unit
does not necessarily conflict with the general exemption for intangible
personal property pursuant to § 39-3-101 (1)(i). U.S. Transmission Sys. v. Bd.
of Assmt. Appeals, 715 P.2d 1249 (Colo. 1986) (decided under former law).
Board of assessment appeals
was not required, as a matter of law, to include financing costs in the
valuation of plaintiff's property. The method by which the property tax
administrator arrived at her valuation was authorized under this section. Colo.
Interstate Gas Co. v. Huddleston, 28 P.3d 958 (Colo. App. 2000).
Public utility not entitled
to the intangible property exemption or the cost cap valuation method.
Instead, a public utility must be valued under the factors listed in this
section. Qwest v. Colo. Div. of Prop. Taxation, 2013 CO 39, 304 P.3d 217.
"Operating property and
plant" includes the tangible property comprising the plant and the
intangible rights of the utility that directly contribute to the utility's
operations. U.S. Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249
(Colo. 1986).
Property taxation of a public
utility in Colorado is not precluded simply because the only portion of the
public utility's operating property and plant found within this state is the
intangible rights derived from rental of telephone circuits. U.S. Transmission
Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo. 1986).
Telephone circuits leased by
petitioner from other telecommunication companies in Colorado constituted
intangible rights held by a public utility as part of its operating property
and plant and as such were property considered in determining petitioner's
property tax assessment. U.S. Transmission Sys. v. Bd. of Assmt. Appeals, 715
P.2d 1249 (Colo. 1986).
Value of the "operating
property and plant". The statute reflects the view that the true
measure of value of the property of a public utility is its worth as an
integrated and operating unit rather than the sum of the values of the various
components making up that unit. Therefore, the fact that petitioner's property
rights in the circuits leased from other telecommunication companies has no
independent market value is not dispositive of such property's assessment
value. U.S. Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo.
1986).
The operating property and
plant to be valued as a unit consists of the public utility's property and
plant used in carrying on its business. Such valuation also includes
intangible rights derived from other property and plant even if owned by a
parent company or other subsidiary if they contribute directly to the operation
of the public utility as an ongoing concern. United Parcel Serv. of Am., Inc.
v. Huddleston, 981 P.2d 223 (Colo. App. 1999).
The general assembly did not
intend to equate "actual value" with "market value".
Actual value is not the same as market value and the terms cannot be used
interchangeably. Colo. Interstate Gas Co. v. Huddleston, 28 P.3d 958 (Colo.
App. 2000).
The general assembly's intent
is apparent from its use of the term "actual value" when referring to
the overall property value, and use of "market value" to refer only
to the value of a public utilities outstanding securities during the calendar
year preceding valuation. Colo. Interstate Gas Co. v. Huddleston, 28 P.3d 958
(Colo. App. 2000).
Applied in Salt River
Project v. Bd. of Assmt. Appeals, 719 P.2d 368 (Colo. App. 1986).
39-4-103. Schedules of property -
confidential records - late filing penalties.
(1) (a)
Except as otherwise provided in this paragraph (a), no later than April 1 of
each year, each public utility doing business in this state shall file with the
administrator, on a form provided by the administrator, a statement, signed by
an officer of such public utility under the penalties of perjury in the second
degree, containing such information concerning itself and all of its property,
wherever situated, as the administrator may reasonably require for the purpose
of determining the actual value of such public utility in this state and for
apportioning the valuation for assessment of such public utility among the
several counties of this state. Upon good cause shown, the administrator may
grant an extension for filing such statement to any public utility. Any
extension granted pursuant to this paragraph (a) shall be for a reasonable
amount of time as determined by the administrator.
(b)
Such statement shall include a specific identification of each and every item
of property owned, leased, or used which is not included in the rendition of
the operating property and plant and the county in which each item is located.
(1.5)
(a) If a public utility fails to complete a statement of property and
legally postmark it for return by April 1, the administrator shall impose on
such public utility a late filing penalty in the amount of one hundred dollars
for each calendar day the statement of property remains delinquent; except that
the late filing penalty shall not exceed three thousand dollars. If, by June 1,
the public utility continues to be delinquent in filing a statement of
property, the administrator shall, in addition to imposing a late filing
penalty, determine the actual value of such utility on the basis of the best
information available. All late filing penalties shall be credited to the
general fund.
(b) If
any public utility fails to file a completed statement of property, or includes
in a filed statement of property any information concerning the public utility
property which is false, erroneous, or misleading, or fails to include in the
statement of property any taxable property owned by the public utility, then
the administrator may determine the actual value of such taxable property on
the basis of the best information available.
(c) If
a public utility fails to file a statement of property and does not file a
petition or complaint pursuant to section 39-4-108 regarding the actual value
of its taxable property as determined on the basis of the best information
available pursuant to this subsection (1.5), the public utility shall be deemed
to have waived any right to file an abatement or refund petition regarding such
actual value pursuant to section 39-10-114.
(2) All
such statements filed with the administrator shall be considered private
documents and shall be available only to the administrator, the employees of
the division of property taxation, assessors, and county treasurers.
Source:
L. 64: R&RE,
p. 689, § 1. C.R.S. 1963: § 137-4-3. L. 70: p. 382, § 16. L.
72: p. 569, § 50. L. 76: (1) amended, p. 759, § 17, effective July
1, 1977. L. 87: (1.5) added, p. 1404, § 1, effective January 1, 1988. L.
89: (1)(a) amended, p. 1465, § 29, effective January 1, 1990. L. 90:
(1.5)(a) amended, p. 1696, § 17, effective June 9. L. 93: (1.5)(a)
amended, p. 1687, § 2, effective June 6. L. 96: (1.5)(c) added, p. 650,
§ 3, effective May 1. L. 2020: (2) amended, (HB 20-1077), ch. 80, p.
325, § 8, effective September 14.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
39-4-104. Inspection of records of
utility.
The
division of property taxation, through the administrator, and its employees,
shall have the right at any time, upon demand, to inspect the books, accounts,
and records of any public utility doing business in this state for the purpose
of verifying the information contained in its filed statement and to examine
under oath any officer, employee, or agent of such public utility. Any person
making such demand upon a public utility on behalf of the administrator shall
produce and exhibit his authority to make such inspection or examination.
Source:
L. 64: R&RE,
p. 689, § 1. C.R.S. 1963: § 137-4-4. L. 70: p. 382, § 17.
39-4-105. Production of records.
By order
or subpoena, the administrator may require the production of any books,
accounts, or records of any public utility doing business in this state, or
verified copies of the same, for examination, and any public utility failing or
refusing to comply with any such order or subpoena shall forfeit and pay to the
state the sum of one hundred dollars for each day it so fails or refuses.
Source:
L. 64: R&RE,
p. 690, § 1. C.R.S. 1963: § 137-4-5. L. 70: p. 383, § 18.
39-4-106. Valuation of utilities -
apportionment.
(1)
Repealed.
(2) In
the specific case of a telegraph company, the administrator shall:
(a)
Determine, as of the last day of December of each year, the actual value of
such company as a unit, or of its property and plant within this state, in the
manner provided in section 39-4-102;
(b)
Allocate to this state, if the actual value of such company is determined as a
unit, that proportion of such actual value as in his judgment accurately
represents the value of the property and plant of such company within this
state, utilizing commonly recognized methods of allocation as in his judgment
are just and equitable;
(c)
Compute the valuation for assessment of such company in this state as provided
in section 39-1-104;
(d)
Apportion the valuation for assessment of such company in this state among the
several counties of this state in such proportion as in his judgment will
fairly represent the valuation for assessment within each such county,
utilizing commonly recognized methods of apportioning as in his judgment are
just and equitable.
(3) In
the specific case of a telephone company, the administrator shall:
(a)
Determine, as of the last day of December of each year, the actual value of
such company as a unit, or of its property and plant within this state, in the
manner provided in section 39-4-102;
(b)
Allocate to this state, if the actual value of such company is determined as a
unit, that proportion of such actual value as in his judgment accurately
represents the value of the property and plant of such company within this
state, utilizing commonly recognized methods of allocation as in his judgment
are just and equitable;
(c)
Compute the valuation for assessment of such company in this state as provided
in section 39-1-104;
(d)
Apportion the valuation for assessment of such company in this state among the
several counties of this state in such proportion as in his judgment will
fairly represent the valuation for assessment within each such county,
utilizing commonly recognized methods of apportioning as in his judgment are
just and equitable.
(4)
Repealed.
(5) In
the specific case of a pipeline company engaged in the transportation of gas,
oil, or petroleum products or coal slurry or other coal products in pipelines
through or in this state, the administrator shall:
(a)
Determine, as of the last day of December of each year, the actual value of the
property of such company within this state, either in the manner provided in
section 39-4-102 or, with respect to its pipelines, on a diameter per inch per
mile basis and its land, improvements, pump and compressor stations, and
miscellaneous equipment, wherever situated, being valued separately in the same
manner as all other real and personal property;
(b)
Compute the valuation for assessment of such company in this state as provided
in section 39-1-104;
(c)
Apportion the valuation for assessment of such company in this state among the
several counties of the state in such proportion as in his judgment will fairly
represent the valuation for assessment within each such county, utilizing
commonly recognized methods of apportioning as in his judgment shall be just
and equitable.
(6) The
administrator shall determine the actual value of all other public utilities
doing business in this state in the manner provided in section 39-4-102 and
shall apportion the valuation for assessment thereof, computed as provided in
section 39-1-104, among the several counties of this state in which property of
such public utilities is located in such proportion as in his judgment will
fairly represent the valuation for assessment within each such county,
utilizing commonly recognized methods of apportioning as in his judgment are
just and equitable.
(7) (a)
In the specific case of a railroad company, the administrator shall:
(I)
Determine, as of the last day of December of each year, the actual value of
such company as a unit or the actual value of its property and plant within
this state, in the manner provided in section 39-4-102;
(II)
Ascertain the total mileage of all railroad track of such company, wherever
situated, if the actual value of such company is determined as a unit;
(III)
Ascertain the total mileage of all railroad track of such company situated
within this state and in the several counties thereof;
(IV)
Ascertain the total mileage of all railroad main track of such company situated
within this state and in the several counties thereof;
(V)
Allocate to this state, if the actual value of such company is determined as a
unit, that proportion of such actual value that the total mileage of all
railroad track of such company situated within this state bears to the total
mileage of all railroad track of such company, wherever situated;
(VI)
Compute the valuation for assessment of such company in this state as provided
in section 39-1-104;
(VII)
Apportion the valuation for assessment of such company within this state among
the several counties of this state in the proportion that the actual mileage of
railroad main track within each such county bears to the total mileage of all
railroad main track of such company within this state.
(b)
This subsection (7) is effective January 1, 1987.
(8) (a)
In the case of cars owned by a sleeping car company, a railroad express
company, or a private car line company, the administrator shall:
(I)
Ascertain the total railroad track miles made by all such cars within this
state and in the several counties thereof during the preceding calendar year;
(II)
Determine the actual value of all such cars, using commonly recognized methods
of valuation;
(III)
Compute the valuation for assessment of all such cars as provided in section
39-1-104;
(IV)
Apportion the valuation for assessment of all such cars among the several
counties of the state in such proportion as in his judgment will fairly
represent the valuation for assessment within each such county.
(b)
This subsection (8) is effective January 1, 1987.
Source:
L. 64: R&RE,
p. 690, § 1. C.R.S. 1963: § 137-4-6. L. 70: p. 383, § 19. L.
76: IP(5) amended, p. 768, § 2, effective April 26. L. 81: (1) and
(4) repealed, p. 1855, § 7, effective January 1, 1982; (7) and (8) added, p.
1854, § 5, effective January 1, 1987. L. 83: (7)(b) and (8)(b) amended,
p. 1497, § 5, effective April 28. L. 84: (7)(b) and (8)(b) amended, p.
990, § 4, effective February 23.
ANNOTATION
No commerce clause
violation. Where the utility's intangible property, in-state circuits
leased by the utility to transmit calls in and out of state, provides a
sufficient nexus between the utility and the state to support a tax, and where
the tax was apportioned in the tax administrator's judgment to represent the
value of the utility's property and plant within the state, the resulting
valuation for assessment did not violate the commerce clause. U.S. Transmission
Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo. 1986).
Allocation formula for
apportioning the unitary value of a telephone company's property to Colorado.
In the absence of a showing of significant prejudice by petitioner, the board's
employment of a single factor allocation formula based on gross revenues was in
compliance with the tax administrator's statutory charge to apportion fairly
the value of the property and plant to represent the value attributable to the
state. U.S. Transmission Sys. v. Bd. of Assmt. Appeals, 715 P.2d 1249 (Colo.
1986).
39-4-107. Statement of valuation to
counties.
No later
than July 1 in each year, the administrator shall advise both the assessor of
each county wherein property of a public utility is located and the public
utility itself of the valuation of such public utility in such county, and such
amount shall be entered on the tax roll of such county by the assessor in the
same manner as though determined by the assessor.
Source:
L. 64: R&RE,
p. 692, § 1. C.R.S. 1963: § 137-4-7. L. 70: p. 384, § 20. L.
89: Entire section amended, p. 1465, § 30, effective June 7. L. 93:
Entire section amended, p. 1687, § 3, effective June 6. L. 96: Entire
section amended, p. 719, § 3, effective May 22.
39-4-108. Complaint - hearing -
decision.
(1) Any
public utility, being of the opinion that the actual value of its property and
plant as determined by the administrator is illegal, erroneous, or not uniform
with the actual value of like property similarly situated, as determined by the
administrator, may, no later than July 15, file a petition or complaint with
the administrator, setting forth such illegality, error, or lack of uniformity.
(2) Any
assessor or board of county commissioners, being of the opinion that the actual
value of the property and plant of any public utility as determined by the
administrator is illegal, erroneous, or not uniform with the actual value of
like property similarly situated, as determined by the administrator, or that
the amount of valuation of any public utility has not been correctly
apportioned among the counties entitled thereto may, no later than July 15,
file a petition or complaint with the administrator setting forth such
illegality, error, lack of uniformity, or incorrect apportionment.
(3)
Upon the filing of any petition or complaint provided for in this section, the
administrator shall cause notice of such filing to be given to the assessor and
the board of county commissioners of any county directly affected and to any
public utility directly affected, as may appear from such petition or
complaint. Such notice shall be mailed at least five days prior to the meeting
with the administrator at which such petition or complaint will be heard.
(4) The
administrator shall, on the first working day after notices of valuation are
mailed and on succeeding days if necessary, hear all such petitions and
complaints. In case there are several petitions or complaints filed involving
like questions, the same may be consolidated for the purpose of hearing and
determination. The administrator shall hear all evidence presented and listen
to arguments touching upon the matters concerning which the petition or
complaint was filed. He shall have power to subpoena and compel the attendance
of witnesses and to require the production of any books or records deemed
necessary to arrive at a proper determination of the matter. Upon good cause,
any hearing may be adjourned from time to time, but in no event beyond July 27.
Hearings conducted under this section shall be informal, and a verbatim record
need not be made, as required under section 24-4-105 (13), C.R.S.
(5) The
administrator shall render his decision upon any petition or complaint, in
writing, no later than August 1 and shall transmit a copy thereof to all
parties affected.
(6) If
the administrator grants the petition, in whole or in part, the administrator
shall make the appropriate corrections or changes in the valuation of such
public utility, or in the apportionment thereof, and shall certify the same to
the assessor of the county affected thereby. Such decision shall control all
proceedings thereafter, the same as though originally certified by the
administrator.
(7) If
the administrator denies the petition, in whole or in part, all costs and
expenses incurred in conducting the hearing shall be chargeable to the
petitioner and shall be enforceable and collectible as in the case of other
claims and demands.
(8)
Further proceedings brought by a party adversely affected by the
administrator's decision shall be before the board of assessment appeals under
the provisions of section 39-2-125 or before the Denver district court for a
trial de novo with no presumption in favor of any pending valuation, and no
judicial review shall be available to any party under the provisions of section
39-4-109 until the board or the district court has rendered its decision.
Source:
L. 64: R&RE,
p. 692, § 1. C.R.S. 1963: § 137-4-8. L. 70: p. 384, § 21. L.
89: (1), (2), (4), and (5) amended, p. 1465, § 31, effective June 7. L.
93: (1), (2), (4), and (5) amended, p. 1688, § 4, effective June 6. L.
96: (2), (6), and (8) amended, p. 720, § 4, effective May 22. L. 2000:
(8) amended, p. 1739, § 3, effective June 1.
ANNOTATION
This section provides no
basis for the contention that the abatement and refund scheme is
inapplicable to state-assessed public utility property or that the protest and
adjustment scheme is the exclusive method for adjusting property tax disputes
involving such property. Huerfano County Bd. of County Comm'rs v. Atlantic
Richfield Co., 976 P.2d 893 (Colo. App. 1999).
The protest and adjustment
procedure under this section is a separate and independent procedural system
from the abatement and refund procedure and is governed by a different statute.
Huerfano County Bd. of County Comm'rs v. Atlantic Richfield Co., 976 P.2d 893
(Colo. App. 1999).
Applied in People v.
Nichols, 34 Colo. App. 276, 527 P.2d 941 (1974).
39-4-109. Judicial review.
(1) Any
petitioner or any other public utility, assessor, or board of county
commissioners adversely affected or the administrator may appeal any decision
of the board of assessment appeals or the district court denying a petition in
whole or in part to the court of appeals. No new or additional evidence may be
introduced in the court of appeals unless such other public utility, assessor,
or board of county commissioners adversely affected has had no opportunity to
present such evidence at the hearing before the board of assessment appeals or
at the trial in the district court; otherwise, the cause shall be heard on the
record of the board of assessment appeals or the district court, which shall be
certified by it to the court in which the appeal was taken. Whenever any new or
additional evidence is introduced, the court, in its discretion, may remand the
case to the board of assessment appeals or the district court for rehearing.
(2) An
appeal may be taken to the court of appeals according to the Colorado appellate
rules and the provisions of section 24-4-106 (11), C.R.S., after the decision
of the board of assessment appeals or the district court is issued, but, if the
appeal is taken by the public utility actually owning the property involved in
the petition to the board of assessment appeals or the district court, such
public utility shall pay the full amount of all taxes levied upon the valuation
for assessment of its property and plant to the treasurer of the county in
which the same is located prior to taking its appeal.
(3) If,
upon appeal to the court of appeals, the petitioner is sustained, in whole or
in part, then, upon presentation to the treasurer to whom the taxes were paid
of a certified copy of the order modifying the valuation for assessment of its
property and plant, the treasurer shall forthwith make the appropriate refund
of taxes, together with refund interest at the same rate as delinquent interest
as specified in section 39-10-104.5, and the petitioner shall also be entitled
to a refund of costs incurred in the hearing before the board of assessment
appeals or the trial in the district court and in the appeal to the court or
such portion thereof as the court may decree; but, if judgment is for the board
of assessment appeals, then the board of assessment appeals shall receive its
costs from the appellant. Such refund interest shall only accrue from the date
on which payment of taxes was received by the treasurer from the petitioner.
Source:
L. 64: R&RE,
p. 694, § 1. C.R.S. 1963: § 137-4-9. L. 70: p. 385, § 22. L.
83: (1) and (2) amended, p. 2086, § 3, effective October 13. L. 90:
Entire section amended, p. 1690, § 7, effective June 9. L. 92: (3)
amended, p. 2224, § 6, effective April 9; (3) amended, p. 2185, § 66, effective
June 2. L. 93: (3) amended, p. 305, § 5, effective April 7. L. 2000:
Entire section amended, p. 1739, § 4, effective June 1.
Cross
references: For
the legislative declaration contained in the 2000 act amending this section,
see section 1 of chapter 358, Session Laws of Colorado 2000.
39-4-110. Certification and assessment
of pollution control property. (Repealed)
Source:
L. 78: Entire
section added, p. 468, § 2, effective July 1. L. 79: (3) added, p. 1456,
§ 4, effective June 22. L. 81: (3) R&RE, p. 1872, § 5, effective
June 29. L. 88: Entire section repealed, p. 1275, § 14, effective May
29, 1988.
ARTICLE
4.1
Valuation
and Assessment of Rail Transportation Property
39-4.1-101 to 39-4.1-110. (Repealed)
Editor's
note: (1) This
article was added in 1981. For amendments to this article prior to its repeal
in 1987, consult the Colorado statutory research explanatory note and the table
itemizing the replacement volumes and supplements to the original volume of
C.R.S. 1973 beginning on page vii in the front of this volume.
(2) Section 39-4.1-110 provided
for the repeal of this article, effective January 1, 1987. (See L. 84, p. 990.)
ARTICLE
5
Valuation
and Taxation
PART 1
REAL AND PERSONAL PROPERTY
39-5-101. Duties of assessor.
39-5-102. When schedules required -
nonresident owners listed.
39-5-103. Property described.
39-5-103.5. Maps of parcels of land in the
county.
39-5-104. Valuation of property.
39-5-104.5. Valuation of personal property.
39-5-104.7. Valuation of real and personal
property that produces alternating current electricity from a renewable energy
source.
39-5-105. Improvements - water rights -
valuation.
39-5-106. Purchase of state land.
39-5-107. Personal property schedule.
39-5-108. Schedule sent to taxpayer - return.
39-5-108.5. Furnished residential real property
rental advertisements - information to be provided to the assessor -
legislative declaration.
39-5-109. Inventory schedules - valuation.
(Repealed)
39-5-110. Property brought into state after
assessment date - removal before next assessment date.
39-5-111. Livestock, agricultural products -
not valued, when. (Repealed)
39-5-112. Livestock - apportionment of value.
(Repealed)
39-5-113. Movable equipment - apportionment
of value.
39-5-113.3. Oil and gas drilling rigs -
apportionment of value.
39-5-113.5. Works of art - apportionment of
value.
39-5-114. Unclassified property shown on
schedule.
39-5-115. Taxpayer to furnish information -
affidavit on mineral leases.
39-5-116. Failure to file schedule - failure
to fully and completely disclose.
39-5-117. Property improvements destroyed
after assessment date.
39-5-118. Failure to receive schedule -
validity of valuation.
39-5-119. Refusal to answer - court order.
39-5-120. Tax schedules endorsed and filed -
availability for inspection.
39-5-121. Notice of valuation - legislative
declaration - definition - repeal.
39-5-121.5. Valuation - inspection of data by
taxpayers.
39-5-122. Taxpayer's remedies to correct
errors.
39-5-122.1. Appeal from illegal increase in
valuation of property resulting from order of state board. (Repealed)
39-5-122.5. Taxpayer's remedies - property tax
credit for incorrect valuations used for property tax levied in 1987 for
collection in 1988. (Repealed)
39-5-122.7. Alternate protest and appeal
procedure for specified counties.
39-5-122.8. Pilot alternate protest procedure -
city and county of Denver - repeal. (Repealed)
39-5-123. Abstract of assessment or amended
abstract of assessment.
39-5-124. Property tax administrator to
examine abstract.
39-5-125. Omission - correction of errors.
39-5-126. Wrongful return by assessor.
39-5-127. Correction of assessments.
39-5-128. Certification of valuation for
assessment.
39-5-129. Delivery of tax warrant - public
inspection.
39-5-130. Informality not to invalidate.
39-5-131. Certification and valuation of
pollution control property. (Repealed)
39-5-132. Assessment and taxation of new
construction.
39-5-133. 2011 modification of statutory
definition of "agricultural land" - TABOR election - adjustment of
district mill levy.
39-5-134. Controlled environment agricultural
facility - valuation - affidavit - definition - repeal.
PART 2
MOBILE HOMES
39-5-201. Legislative declaration.
39-5-202. Taxation of mobile homes -
effective date.
39-5-203. Mobile homes - determination of
value.
39-5-204. Notification concerning mobile
homes in a county for part of a year.
39-5-205. Relocation of a mobile home -
collection of taxes.
39-5-206. Payments to counties, cities,
towns, and special districts in lieu of taxes for calendar year 1978.
(Repealed)
PART
1
REAL
AND PERSONAL PROPERTY
Editor's
note: This part 1
was repealed and reenacted in 1964. For historical information concerning the
repeal and reenactment, see the editor's note before the article 1 heading.
39-5-101. Duties of assessor.
The
assessor shall list all taxable real and personal property located within his
county on the assessment date, other than that comprising the property and
plant of public utilities.
Source:
L. 64: R&RE,
p. 694, § 1. C.R.S. 1963: § 137-5-1. L. 73: p. 237, § 19. L.
75: Entire section amended, p. 1467, § 12, effective July 18. L. 81:
Entire section amended, p. 1855, § 6, effective January 1, 1982. L. 94:
Entire section amended, p. 1646, § 80, effective July 1.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Office of county assessor
created by constitution. The office of county assessor in each county was
created by the constitution, but the duties thereof are prescribed by
legislative acts. Bartlett & Co. v. Bd. of County Comm'rs, 152 Colo. 388,
382 P.2d 193 (1963).
Legislative duties must
comply with constitution. County assessors have specific duties to perform
in conformity with legislative directions and, in performing such duties, they
must comply with the general admonition of § 3 of art. X, Colo. Const., with
the ultimate goal of securing just and equalized valuations. Bartlett & Co.
v. Bd. of County Comm'rs, 152 Colo. 388, 382 P.2d 193 (1963).
Applied in Bd. of County
Comm'rs v. Colo. Bd. of Assmt. Appeals, 628 P.2d 156 (Colo. App. 1981).
39-5-102. When schedules required -
nonresident owners listed.
(1)
Ownership of real property shall be ascertained by the assessor from the
records of the county clerk and recorder, and owners of real property shall not
be required to file schedules listing the same; but any person having or
claiming to have an undivided interest in any real property, or any inchoate,
possessory, or equitable interest therein, or any other estate less than the
fee, or any lien on any real property may file a schedule with the assessor,
specifying such interest.
(2)
When the ownership of any real or personal property cannot be ascertained by
the assessor after due diligence, he may list such property under the legend
"owner unknown".
(3) The
assessor shall furnish annually by the first day of June to the executive
director of the department of revenue a list of the names and addresses of all
nonresidents of the state as shown by the assessor's records as of the previous
assessment date to have owned real or personal property within the county.
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-2. L. 69: p. 1132, § 1.
39-5-103. Property described.
In listing
tracts or parcels of real property, the assessor shall identify the same by
section, or part of a section, township, and range, and, if such part of a
section is not a legal subdivision, then by some other description sufficient
to identify the same. In listing town or city lots, he shall describe the same
by number of lot and block, or otherwise, in accordance with the system of
numbering or describing used by the town or city in which said lots are
located.
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-3.
39-5-103.5. Maps of parcels of land in
the county.
(1)
Prior to January 1, 1981, each assessor shall prepare and maintain full,
accurate, and complete maps showing the parcels of land in his county. The maps
shall include a master county index map, together with applicable township,
section, and quarter-section maps, depending on density. Guidelines shall be
established by the administrator to produce uniformity throughout the state.
The guidelines shall include the definition of a parcel, the development of a
parcel numbering system, map size, map scale, and suggestions for minimum
information to be plotted.
(2) In
fulfilling the duty imposed upon him by subsection (1) of this section, the
assessor may employ other mapping resources or maps available to him.
Source:
L. 76: Entire
section added, p. 770, § 1, effective July 1.
39-5-104. Valuation of property.
Each tract
or parcel of land and each town or city lot shall be separately appraised and
valued, except when two or more adjoining tracts, parcels, or lots are owned by
the same person, in which case the same may be appraised and valued either
separately or collectively. When a single structure, used for a single purpose,
is located on more than one town or city lot, the entire land area shall be
appraised and valued as a single property.
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-4.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Record title owners of real
property are the true owners of the property and are therefore responsible
for property taxes. Hinsdale County Bd. of Eq. v. HDH P'ship, 2019 CO 22, 438
P.3d 742.
Separate assessments for
estates owned by different persons. This section requires separate
assessment where separate estates are owned by different persons. If the
separate estate of an owner of an oil interest is held to be included in a
description by section number of the surface without more to identify the severed
interest, the result would be that the estate in oil is taxed without notice to
the owner. Mitchell v. Espinosa, 125 Colo. 267, 243 P.2d 412 (1952).
This section permits single
assessment of several adjoining lots if returned by the same person.
Crisman v. Johnson, 23 Colo. 264, 47 P. 296 58 Am. St. R. 224 (1896).
Lots are presumed to be
adjoining if so assessed. As public policy requires that all presumptions
should be in favor of the legality of an assessment, where a complaint in an
action protesting an assessment does not allege that the lots were not
adjoining, the presumption is that they were. Bd. of County Comm'rs v.
Yingling, 14 Colo. App. 449, 60 P. 582 (1900).
Fee title owners of
subdivision parcels, rather than the homeowners association that manages the
subdivision, are subject to real property taxation due to the covenants
that permit the association to restrict property access for nonpayment of
association assessments. Hinsdale County Bd. of Eq. v. HDH P'ship, 2019 CO 22,
438 P.3d 742.
Resort's income from rental
management fees paid by condominium owners is excluded from valuation under the
income approach to valuation. When a resort includes a corporate-owned
hotel and separately owned condominium units, fees paid to a subsidiary of the
hotel owner by the condominium unit owners for rental management services are
not income that the hotel generates because the hotel and the condominium units
are legally separate and distinct parcels of property that must be separately
valued and appraised and the income used to pay the fees is derived from the
rental of the condominium units. Lodge Props. v. Eagle Bd. of Equaliz., 2022 CO
9, 504 P.3d 960.
39-5-104.5. Valuation of personal
property.
(1) On
and after January 1, 1996, personal property shall be valued as of the
assessment date, and the tax shall apply for the full assessment year without
regard to any destruction, conveyance, relocation, or change in tax status
occurring after the assessment date. The owner of taxable personal property on
the assessment date shall be responsible for the property tax assessed for the
full property tax year without proration.
(2)
Repealed.
Source:
L. 96: Entire
section added, p. 45, § 5, effective March 20. L. 2020: (2) repealed,
(HB 20-1077), ch. 80, p. 325, § 9, effective September 14.
Cross
references: For
the legislative declaration contained in the 1996 act enacting this section,
see section 1 of chapter 16, Session Laws of Colorado 1996.
39-5-104.7. Valuation of real and
personal property that produces alternating current electricity from a
renewable energy source.
(1) (a)
Except as provided in paragraph (b) of this subsection (1), on and after
January 1, 2008, all real and personal property used to produce two megawatts
or less of alternating current electricity from a renewable energy source shall
be valued by the assessor in the county where the property is located in
accordance with valuation procedures developed by the administrator.
(b) The
valuation requirements specified in paragraph (a) of this subsection (1) shall
not apply to small or low impact hydroelectric energy facilities, geothermal
energy facilities, biomass energy facilities, solar energy facilities, or wind
energy facilities, as those terms are defined in section 39-4-101.
(2) In
developing the valuation procedures specified in subsection (1)(a) of this
section:
(a)
Except as set forth in subsection (2)(b) of this section, the administrator
shall utilize the procedures adopted for determining the actual value of a
renewable energy facility as specified in section 39-4-102 (1)(e); and
(b) For
a facility that would qualify as a solar energy facility as defined in section
39-4-101 (3.5) but it generates and delivers less than two megawatts of energy,
the administrator shall utilize the procedures for determining the actual value
of a solar energy facility as specified in section 39-4-102 (1.5) for property
tax years commencing on or after January 1, 2021.
(3) A
taxpayer shall notify the taxpayer's county assessor when the taxpayer installs
real and personal property used to produce two megawatts or less of alternating
current electricity from a renewable energy source; except that, if the
taxpayer obtains a building permit under the jurisdiction of a local government
for the installation, the notification required in this subsection (3) shall
not be necessary.
Source:
L. 2008: Entire
section added, p. 1318, § 1, effective May 27. L. 2009: (1)(b) amended,
(SB 09-177), ch. 186, p. 814, § 3, effective April 22. L. 2010: (1)(b)
amended, (SB 10-019), ch. 382, p. 1787, § 3, effective June 8; (1)(b) amended,
(SB 10-174), ch. 189, p. 815, § 10, effective August 11; (1)(b) amended, (SB
10-177), ch. 392, p. 1864, § 5, effective August 11. L. 2021: (2)
amended, (SB 21-020), ch. 51, p. 218, § 3, effective September 7.
Editor's
note: Amendments
to subsection (1)(b) by Senate Bill 10-019, Senate Bill 10-174, and Senate Bill
10-177 were harmonized.
Cross
references: For
the legislative intent contained in the 2008 act enacting this section, see
section 9 of chapter 302, Session Laws of Colorado 2008.
39-5-105. Improvements - water rights
- valuation.
(1)
Improvements shall be appraised and valued separately from land, except
improvements other than buildings on land which is used solely and exclusively
for agricultural purposes, in which case the land, water rights, and
improvements other than buildings shall be appraised and valued as a unit.
(1.1) (a)
(I) Water rights, together with any dam, ditch, canal, flume, reservoir,
bypass, pipeline, conduit, well, pump, or other associated structure or device
as defined in article 92 of title 37, C.R.S., being used to produce water or
held to produce or exchange water to support uses of any item of real property
specified in section 39-1-102 (14), other than for agricultural purposes, shall
not be appraised and valued separately but shall be appraised and valued with
the item of real property served as a unit.
(II)
For purposes of this section, valuing the water rights and the item of real
property served by the water rights "as a unit" means that any
increase in value of the property served with water made available directly, or
by exchange, by the use of any dam, ditch, pipeline, canal, flume, reservoir,
bypass, conduit, well, pump, or other associated structure or device, as
defined in article 92 of title 37, C.R.S., shall be included in the valuation
of the real property served by the water rights.
(b) The
general assembly finds and declares that the value of water rights, and any
dam, ditch, pipeline, canal, flume, reservoir, bypass, conduit, well, pump, or
other associated structure or device, as defined in article 92 of title 37,
C.R.S., used or held to produce or exchange water, for taxation purposes,
should be recognized as a contribution to the value of all of the interests in
the entire property served thereby and that the separate valuation of such
water rights could result in double taxation. The provision of this subsection
(1.1) shall not be construed to exempt any water rights from taxation but shall
be construed as setting forth procedures for the valuation thereof.
(2) and
(3) Repealed.
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-5. L. 75: Entire section
amended, p. 1474, § 2, effective July 1. L. 76: Entire section amended,
p. 771, § 1, effective May 26; (1) amended, p. 760, § 18, effective January 1,
1977. L. 77: (3) added, p. 1753, § 1, effective June 19. L. 79:
(1) amended, p. 1404, § 2, effective July 1. L. 83: (1.1) added, p.
1503, § 1, effective May 25. L. 87: (2) and (3) repealed, p. 1304, § 1,
effective May 20. L. 96: (1.1) amended, p. 468, § 1, effective April 23.
Cross
references: For
manner of determination of actual value of agricultural lands, see § 39-1-103
(5).
39-5-106. Purchase of state land.
The equity
in land purchased from the state under contract shall, during the term of such
contract, be appraised and valued in the same manner as though held in fee by
the purchaser, and any improvements on such land shall be appraised and valued
in the same manner as other improvements.
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-6.
39-5-107. Personal property schedule.
(1) All
taxable personal property shall be listed on a form of schedule approved by the
administrator and prepared and furnished by the assessor. Such schedule shall
be so designed as to show the owner's name, address, social security number or
federal employer identification number, and the location and general
description of the owner's taxable personal property, divided into the various
subclasses, and shall provide sufficient space for the furnishing of such
information, derived from the books of account, records, or Colorado income tax
returns of the owner of such property, as may be required by the assessor to
determine the actual value of such property.
(2)
There shall be subjoined to such schedule the following declaration:
"I declare, under
the penalty of perjury in the second degree, that this schedule, together with
any accompanying exhibits or statements, has been examined by me and to the
best of my knowledge, information, and belief sets forth a full and complete
list of all taxable personal property owned by me, or in my possession, or
under my control, located in .... county, Colorado, on the assessment date of
this year; that such property has been reasonably described and its value
fairly represented; and that no attempt has been made to mislead the assessor
as to its age, quality, quantity, or value.
........................ Owner
........................ Date ....................... Agent"
Source:
L. 64: R&RE,
p. 695, § 1. C.R.S. 1963: § 137-5-7. L. 72: p. 569, § 51. L.
73: p. 238, § 20. L. 75: (1) amended, p. 1468, § 13, effective July
18. L. 84: (1) amended, p. 984, § 2, effective May 8. L. 89: (1)
amended, p. 1483, § 7, effective April 23. L. 96: (1) amended, p. 46, §
4, effective March 20. L. 99: (1) amended, p. 276, § 1, effective August
4.
Cross
references: (1)
For perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
(2) For the legislative
declaration contained in the 1996 act amending this section, see section 1 of
chapter 16, Session Laws of Colorado 1996.
ANNOTATION
Applied in City &
County of Denver v. Sec. Life & Accident Co., 173 Colo. 248, 447 P.2d 369
(1970).
39-5-108. Schedule sent to taxpayer -
return.
As soon
after the assessment date as may be practicable, the assessor shall mail or
deliver one copy of the personal property schedule to the place of business or
to the residence of each person known or believed to own taxable personal
property located in the county, or to the agent of such person. Such person or
his or her agent shall list in such schedule all taxable personal property
owned by him or her, or in his or her possession, or under his or her control
located in said county on the assessment date, attaching such exhibits or
statements thereto as may be necessary, and shall sign and return the original
copy thereof to the assessor no later than the April 15 next following.
Exhibits and statements attached to the personal property schedule shall be
deemed sufficient for the purposes of the schedule if such exhibits or
statements clearly list the property, the cost of the property, and the date
the property was acquired.
Source:
L. 64: R&RE,
p. 696, § 1. C.R.S. 1963: § 137-5-8. L. 67: pp. 948, 952, §§ 13,
26. L. 79: Entire section amended, p. 1416, § 1, effective June 21. L.
81: Entire section amended, p. 1831, § 5, effective June 12. L. 2000:
Entire section amended, p. 751, § 3, effective May 23. L. 2008: Entire
section amended, p. 948, § 2, effective August 5.
39-5-108.5. Furnished residential real
property rental advertisements - information to be provided to the assessor -
legislative declaration.
(1) The
general assembly hereby finds and declares that:
(a)
Each assessor is required by law to discover and assess taxable personal
property in the assessor's county and to provide each person known or believed
to own taxable personal property in the county with a personal property
schedule;
(b)
Each owner of taxable personal property is required by law to list the owner's
taxable personal property on the personal property schedule, and the receipt of
a personal property schedule from the assessor provides notice to a property
owner that the property owner may own taxable personal property, which helps to
ensure that:
(I)
More property owners comply with state property tax laws;
(II)
The property tax burden is more fairly distributed; and
(III)
The amount of property tax revenues lost by local governments due to property
owners' lack of knowledge regarding the taxable status of certain personal
property is minimized;
(c)
Personal property that is used to furnish residential real property is exempt
from property taxation so long as it is not used for the production of income
at any time, but generally becomes subject to taxation if the residential real
property is offered for rent on a furnished basis or otherwise used for
business purposes;
(d) In
certain areas of the state, a high proportion of residential real property is
advertised for rent on a furnished basis directly by property owners or by real
estate agents, property management companies, lodging companies, and internet
and print-based listing services that act as agents for multiple property
owners and advertise multiple properties for rent, and because the
advertisements typically do not precisely identify the property offered for
rent by address or the owner's name:
(I) It
is difficult for each assessor to accurately identify which parcels of
furnished residential real property are being offered for rent and to which
owners of furnished residential real property the assessor should provide
personal property schedules; and
(II)
This difficulty impairs the fairness and efficiency of the property tax system
and reduces property tax collections by making it more likely that owners of
furnished residential real property rented to others will, in some cases
deliberately and in many other cases due to a lack of notice regarding state
property tax laws, fail to pay property taxes due on personal property used to
furnish the residential real property; and
(e) It
is therefore necessary and appropriate to require the owner of furnished
residential real property or an agent of the owner who advertises the property
for rent to provide identifying information regarding the property to the
assessor of the county in which the property is located upon the request of the
assessor made no more than twice during any year as specified in this section
or as mutually agreed to by the assessor and the owner or agent pursuant to
paragraph (b) of subsection (2) of this section.
(2) (a)
Upon the request of the assessor of any county or city and county made no more
than twice during any year:
(I) A
property owner who advertises for rent furnished residential real property that
is located within the county or city and county shall provide to the assessor a
list that identifies each property so advertised by address; and
(II) An
agent who advertises for rent on behalf of a property owner furnished
residential real property that is located within the county or city and county
shall provide to the assessor a list that identifies each property so
advertised by owner and address.
(b) An
assessor and a property owner or agent may mutually agree that the owner or
agent shall annually provide to the assessor by a specified date the
information that an assessor may require to be provided pursuant to paragraph
(a) of this subsection (2).
(3) For
purposes of this section, "agent" means a real estate broker, as
defined in section 12-10-201 (6)(a), a property management company, a lodging
company, an internet website listing service, a print-based listing service, or
any other person that either separately or as part of a package of services
advertises furnished residential real property in the state for rent on behalf
of the owner of the property in exchange for compensation.
Source:
L. 2009: Entire
section added, (HB 09-1110), ch. 162, p. 698, § 1, effective August 5. L.
2019: (3) amended, (HB 19-1172), ch. 136, p. 1728, § 251, effective October
1.
39-5-109. Inventory schedules -
valuation. (Repealed)
Source:
L. 64: R&RE,
p. 697, § 1. C.R.S. 1963: § 137-5-9. L. 65: p. 1096, § 3. L.
67: p. 801, § 1. L. 73: p. 1439, § 1. L. 75: (5)(b) amended,
p. 225, § 86, effective July 16. L. 76: (6)(b) amended p. 760, § 19,
effective January 1, 1977. L. 83: Entire section repealed, p. 1485, §
11, effective April 22.
39-5-110. Property brought into state
after assessment date - removal before next assessment date.
(1)
Whenever any taxable personal property is brought from outside the state into
any county of the state at any time after the assessment date in any year, the
owner shall list the property on the personal property schedule sent to the
taxpayer pursuant to section 39-5-108.
(2) If
any taxable personal property located in the state on the assessment date or
brought into the state at any time after the assessment date is removed from
the state before the next following assessment date, the owner of the property
shall not be relieved of any tax obligation with respect to the property as a
result of the transfer of the property for the property tax year in which the
transfer occurred.
(3)
Repealed.
(4)
Notwithstanding any other provision of this section, oil and gas drilling rigs
shall be valued pursuant to section 39-5-113.3.
Source:
L. 64: R&RE,
p. 698, § 1. C.R.S. 1963: § 137-5-10. L. 67: p. 949, § 14. L.
83: (3) repealed, p. 1485, § 11, effective April 22. L. 87: (2)
amended, p. 1412, § 1, effective April 23. L. 96: (1) and (2) amended,
p. 47, § 6, effective March 20; (4) added, p. 1200, § 5, effective June 1.
Cross
references: (1)
For the assessment date, see § 39-1-105.
(2) For the legislative
declaration contained in the 1996 act amending subsections (1) and (2), see
section 1 of chapter 16, Session Laws of Colorado 1996.
39-5-111. Livestock, agricultural
products - not valued, when. (Repealed)
Source:
L. 64: R&RE,
p. 699, § 1. C.R.S. 1963: § 137-5-11. L. 75: (2) amended and (3)
added, p. 1476, § 1, effective April 9. L. 76: (2) amended, p. 760, §
20, effective January 1, 1977. L. 83: Entire section repealed, p. 1485,
§ 11, effective April 22.
39-5-112. Livestock - apportionment of
value. (Repealed)
Source:
L. 64: R&RE,
p. 699, § 1. C.R.S. 1963: § 137-5-12. L. 67: p. 949, § 15. L.
76: Entire section repealed, p. 765, § 33, effective January 1, 1977.
39-5-113. Movable equipment -
apportionment of value.
(1) Any
person owning any portable or movable equipment which is apt to be located or
maintained in two or more counties of the state during any calendar year shall
indicate in a statement accompanying his personal property schedule the kind
and description and a serial number, if available, of such equipment, the
counties in which such equipment is apt to be located or maintained, and the
estimated period of time during the calendar year in which such equipment is
apt to be so located and maintained.
(2) The
assessor of the county in which such equipment is located on the assessment
date shall determine its value and shall apportion such value between the
counties affected and the school districts thereof, in the proportion that the
periods of time during which such equipment may be located or maintained in
such counties bear to the full calendar year. He shall furnish a copy of such
valuation and apportionment to the owner of such equipment or to his agent and
shall also transmit a copy thereof to the assessor of each county affected as
his authority to list the apportioned value of such equipment on the assessment
roll of his county. For purposes of making such apportionment, the valuation of
the portable or movable equipment made by the assessor of the county of
original assessment shall be used by all county assessors involved.
(3) If,
subsequent to the making of such apportionment of value, any such equipment is
removed to a county not initially included in such apportionment or if any such
equipment is located or maintained in any county for a period of time different
from that used in the initial apportionment, then an amended apportionment of
value shall be requested by the assessor of any county so affected. Such
assessor shall furnish a copy of such requested amended apportionment to the
owner of such equipment or to his agent and shall also transmit a copy thereof
to the assessor of each county affected, as his authority to list such
reapportioned value on the assessment roll of his county. Failure of a county
assessor to request such an amended apportionment shall permit the original
apportionment of value to stand, and no other county assessor shall assess such
equipment as is listed in the original apportionment for any period during the
year of the original assessment. If such amended apportionment of value is received
by any assessor after he has filed his annual abstract of assessment with the
administrator, then either an abatement or an additional assessment shall be
made, as the case may be.
(4)
Repealed.
Source:
L. 64: R&RE,
p. 700, § 1. C.R.S. 1963: § 137-5-13. L. 65: p. 1099, § 1. L.
76: (4) repealed, p. 765, § 33, effective January 1, 1977. L. 90:
(2) amended, p. 1696, § 18, effective June 9.
39-5-113.3. Oil and gas drilling rigs - apportionment
of value.
(1) As
soon after the assessment date as may be practicable, the assessor shall
determine those oil or gas drilling rigs that were operating, stored, or
maintained in the county during the preceding calendar year and shall mail or
deliver two copies of a declaration to the place of business or drilling
operation or to the residence of each person known or believed to own such
rigs, or to the agent of such person. Such person or his agent shall list in
such declaration all oil or gas drilling rigs owned by him, or in his
possession, or under his control that were located in said county during the
previous calendar year, attaching thereto the drilling logs of the respective
rigs showing their various locations and corresponding dates. In addition, such
person or his agent shall provide to the assessor of the first county in
Colorado listed on each rig's log an inventory of that rig's equipment
sufficient to determine a valuation for assessment. The original copy of the
declaration shall be signed and returned to the assessor no later than the
April 15 next following.
(2) The
assessor, upon receiving such inventory and notification that his county was
the first location of the rig in Colorado, shall determine its value and shall
apportion such value between the counties in which the drilling rig was located
during the preceding year and the districts thereof, in the proportion that the
periods of time during which such equipment was located or maintained in such
counties bear to the full calendar year. On or before June 15, the assessor
shall furnish a copy of such valuation and apportionment to the owner of such
equipment or to his agent and shall also transmit a copy thereof to the
assessor of each county affected, together with a copy of the drilling log for
that rig. For purposes of making such apportionment, the valuation of the oil
or gas drilling rig made by the assessor of the first Colorado county on the
log shall be used by all county assessors involved. In the subsequent counties,
the assessor shall accept the returned declaration with the rig's name and location
data as a proper filing.
(3) The
values so apportioned shall be included in the affected counties' abstracts of
assessment filed pursuant to section 39-5-123.
(4)
This section shall apply to the apportionment of value of oil or gas drilling
rigs and not the provisions of section 39-5-113.
(5) For
purposes of this section "oil and gas drilling rigs" shall be defined
by the property tax administrator pursuant to section 39-2-109 (1)(e), which
definitions shall be uniform and consistent throughout the state.
Source:
L. 86: Entire
section added, p. 1107, § 1, effective January 1, 1987. L. 88: (2)
amended, p. 1297, § 4, effective April 29. L. 90: (2) amended, p. 1696,
§ 19, effective June 9.
39-5-113.5. Works of art - apportionment
of value.
(1) Any
persons owning any works of art which are apt to be displayed in any county of
the state during any calendar year shall indicate in a statement accompanying
their personal property schedule the kind and description of such works of art
and the estimated period of time during the calendar year in which such works
of art are to be so displayed and shall provide to the assessor proof of
exemption pursuant to the provisions of sections 39-3-123 and 39-26-102 (2.5).
Failure to file a statement results in forfeiture of a claim for exemption in
that calendar year.
(2) The
assessor of the county in which such works of art are displayed shall determine
its value in the proportion that the periods of time during which such works of
art may be displayed bear to the full calendar year. He shall furnish a copy of
such valuation to the owner of such works of art or to his agent.
Source:
L. 84: Entire
section added, p. 999, § 2, effective January 1. L. 89: (1) amended, p.
1484, § 8, effective April 23. L. 90: (2) amended, p. 1697, § 20,
effective June 9.
39-5-114. Unclassified property shown
on schedule.
If any
person owns, holds, or controls any kind or character of taxable personal
property which is not specifically classified on the personal property
schedule, he shall note such property therein, and such notation shall be held
to be a sufficient description thereof for purposes of valuing the same,
without further enumeration or description; but if the assessor so requests,
such person shall disclose of what said property consists and its uses in
detail.
Source:
L. 64: R&RE,
p. 702, § 1. C.R.S. 1963: § 137-5-14.
39-5-115. Taxpayer to furnish
information - affidavit on mineral leases.
(1) At
any time prior or subsequent to April 15 of each year, the assessor may request
any person known or believed to own taxable property located in his county to
furnish such information or to make available for examination such records as
may be required by him to determine the actual value of such property.
(2)
Within ten days after the execution of a mineral lease, a lessor shall file
with the assessor an affidavit stating the annual net rental payable under such
lease for the purposes of determining the actual value of such mineral interest
where the income approach to appraisal is utilized by the assessor. Such
affidavit shall constitute a private document and shall be available on a
confidential basis as provided in section 39-5-120.
(3) (a)
For property tax years commencing on or after January 1, 2027, any person who,
in connection with nonresidential property, willfully makes and subscribes any
information required by this section that is verified by a written declaration
certifying the truth and accuracy of the information but that is not true and
accurate as to every material matter commits a petty offense.
(b) For
property tax years commencing on or after January 1, 2027, any person who, in
connection with nonresidential property, willfully aids or assists in, or
procures, counsels, or advises the preparation or presentation of any
information required by this section that is fraudulent or false, commits a
petty offense.
(c)
Conviction of a petty offense pursuant to this subsection (3) is limited to the
person who files or assists in filing information that is not true and accurate
as specified in subsection (3)(a) of this section or information that is
fraudulent or false as specified in subsection (3)(b) of this section.
(d) Any
person convicted of a petty offense under this subsection (3) shall be
sentenced in accordance with section 18-1.3-503.
(e) The
county attorney is authorized to file and prosecute any action arising under
this subsection (3) in the county court of the county in which the property is
located.
Source:
L. 64: R&RE,
pp. 315, 702, §§ 294, 1. C.R.S. 1963: § 137-5-15. L. 75: Entire
section amended, p. 226, § 87, effective July 16. L. 79: Entire section
amended, p. 1416, § 2, effective June 21. L. 81: Entire section amended,
p. 1832, § 6, effective June 12. L. 85: Entire section amended, p. 1213,
§ 11, effective May 9. L. 2026: (3) added, (HB 26-1233), ch. 360, p.
2164, § 1, effective August 12.
39-5-116. Failure to file schedule -
failure to fully and completely disclose.
(1) If
any person owning taxable personal property to whom one or more personal
property schedules have been mailed, or upon whom the assessor or his deputy
has called and left one or more schedules, fails to complete and return the
same to the assessor by the April 15 next following, unless by such date such
person has requested an extension of filing time as provided for in this
section, the assessor shall impose a late filing penalty in the amount of fifty
dollars or, if a lesser amount, fifteen percent of the amount of tax due on the
valuation for assessment determined for the personal property for which any
delinquent schedule or schedules are required to be filed. Any person who is
unable to properly complete and file one or more of such schedules by April 15
may request an extension of time for filing, for a period of either ten or
twenty days, which request shall be in writing and shall be accompanied by
payment of an extension fee in the amount of two dollars per day of extension
requested. A single request for extension shall be sufficient to extend the
filing date for all such schedules which a person is required to file in a
single county. Any person who fails to file one or more schedules by the end of
the extension time requested shall be subject to a late filing penalty as
though no extension had been requested. Further, if any person fails to
complete and file one or more schedules by April 15 or, if an extension is
requested, by the end of the requested extension, then the assessor may determine
the actual value of such person's taxable personal property on the basis of the
best information available to and obtainable by him and shall promptly notify
such person or his agent of such valuation. Extension fees and late filing
penalties shall be fees of the assessor's office. Penalties, if unpaid, shall
be certified to the treasurer for collection with taxes levied upon the
person's property.
(2) (a)
If any person owning taxable personal property to whom two successive personal
property schedules have been mailed or upon whom the assessor or his deputy has
called and left one or more schedules fails to make a full and complete
disclosure of his personal property for assessment purposes, the assessor,
after notifying the person of his failure to make such a full and complete
disclosure and allowing such person ten days from the date of notification to
comply, shall, upon discovery, determine the actual value of such person's
taxable property on the basis of the best information available to and
obtainable by him and shall promptly notify such person or his agent of such
valuation. The assessor shall impose a penalty in an amount of up to twenty-five
percent of the valuation for assessment determined for the omitted personal
property. Penalties, if unpaid, shall be certified to the treasurer for
collection with taxes levied upon the person's personal property. A person
fails to make a full and complete disclosure of his personal property pursuant
to this paragraph (a) if he includes in a filed schedule any information
concerning his property which is false, erroneous, or misleading or fails to
include in a schedule any taxable property owned by him.
(b) Any
person who makes full and complete disclosure on the first personal property
schedules issued to him on or after August 1, 1987, shall not be assessed a
penalty for property previously omitted from the assessment rolls under this
article.
(c) Any
person subject to paragraph (a) of this subsection (2) shall have the right to
pursue the administrative remedies available to taxpayers under this title,
dependent upon the basis of his claim.
Source:
L. 64: R&RE,
p. 702, § 1. C.R.S. 1963: § 137-5-16. L. 76: p. 761, § 21. L.
79: p. 1416, § 3. L. 80: p. 498, § 2. L. 81: p. 1832, § 7. L.
82: p. 549, § 14. L. 87: Entire section amended, p. 1414, § 1,
effective August 1. L. 88: (2)(a) amended, p. 1273, § 8, effective
August 1.
39-5-117. Property improvements
destroyed after assessment date.
Whenever
any improvements are destroyed or demolished subsequent to the assessment date
in any year, it is the duty of the owner thereof or the owner's agent to
promptly notify the assessor of such destruction or demolition and the date
upon which the same occurred. In all such cases, such improvements shall be
valued by the assessor at the proportion of its valuation for the full calendar
year that the period of time in such year prior to its destruction or
demolition bears to the full calendar year. Failure of the owner thereof or of
the owner's agent to so notify the assessor prior to the date taxes are levied
shall be considered a waiver, and no proportionate valuation by the assessor
shall then be required.
Source:
L. 64: R&RE,
p. 702, § 1. C.R.S. 1963: § 137-5-17. L. 96: Entire section
amended, p. 47, § 7, effective March 20.
Cross
references: (1)
For the assessment date, see § 39-1-105.
(2) For the legislative
declaration contained in the 1996 act amending this section, see section 1 of
chapter 16, Session Laws of Colorado 1996.
39-5-118. Failure to receive schedule
- validity of valuation.
No
determination of the actual value of any taxable personal property made by the
assessor shall be rendered invalid by reason of his failure to secure or
receive the personal property schedule required to be completed and returned to
him prior to his determination of such value.
Source:
L. 64: R&RE,
p. 702, § 1. C.R.S. 1963: § 137-5-18.
ANNOTATION
Statute did not unconstitutionally
violate taxpayers' due process rights where the statutory scheme provided a
protest procedure which the taxpayers choose to forego and the taxpayers own
actions, not those of any governmental entity, have allegedly deprived the
taxpayers of their property. Prop. Tax Adm'r v. Prod. Geophysical, 860 P.2d 514
(Colo. 1993).
The purpose of this section
is to prevent an invalidation of an assessment solely on the ground that a
taxpayer has failed to return a property tax schedule or that the assessor, for
any other reason, has failed to receive the schedule. Prop. Tax Adm'r v. Bd. of
Assessment Appeals, 837 P.2d 244 (Colo. App. 1992).
Challenges based on
overvaluation. Although taxpayers challenged the amount of taxes assessed
as excessive, this was not an "overvaluation" as the term is used in
§ 39-10-114 because, due to the taxpayers' wrongful inaction, the assessor's
BIA valuations are presumed to be valid. Therefore, for purposes of §
39-10-114, the assessor's valuation cannot be considered an overvaluation, and
§ 39-10-114 may not be asserted by a taxpayer to avoid the provisions of this
section and the protest procedure under § 39-5-122. Prop. Tax Adm'r v. Prod.
Geophysical, 860 P.2d 514 (Colo. 1993).
39-5-119. Refusal to answer - court
order.
Whenever
any person refuses to be interviewed by the assessor or his deputy or refuses
to answer any pertinent questions relative to taxable property owned by him, or
in his possession, or under his control, then, in the discretion of the
district court having jurisdiction in the county and upon affidavit of the
assessor or his deputy showing such refusal to be interviewed or to answer such
questions, such person shall be cited before such court and shall be required
by the court then and there to submit to such interview and to answer such
questions. All costs of such proceedings shall be assessed by the court against
such person, and judgment and execution shall be entered therefor as in other
civil cases.
Source:
L. 64: R&RE,
p. 703, § 1. C.R.S. 1963: § 137-5-19. L. 67: p. 949, § 16.
39-5-120. Tax schedules endorsed and
filed - availability for inspection.
All
personal property schedules and exhibits or statements attached thereto
returned to or secured by the assessor shall be endorsed with the name of the
person whose taxable personal property is listed therein and shall be filed in
either alphabetical or numerical order and retained for a period of six years,
after which time they may be destroyed. Such schedules and accompanying
exhibits or statements shall be considered private documents and shall be
available on a confidential basis only to the assessor and the employees of his
office, the treasurer and the employees of his office, the annual study
contractor hired pursuant to section 39-1-104 (16) and his employees, the
executive director of the department of revenue and the employees of his
office, the administrator and the employees of his office, and the person whose
taxable personal property is listed therein. Such exhibits or statements shall
be available on a confidential basis to the board and the county board of
equalization when information contained in such documents is pertinent to an
appeal or protest.
Source:
L. 64: R&RE,
p. 703, § 1. C.R.S. 1963: § 137-5-20. L. 70: p. 389, § 1. L.
75: Entire section amended, p. 226, § 88, effective July 16. L. 76:
Entire section amended, p. 761, § 22, effective January 1, 1977. L. 87:
Entire section amended, p. 1417, § 2, effective March 13.
39-5-121. Notice of valuation -
legislative declaration - definition - repeal.
(1) (a)
(I) [Editor's note: This version of subsection (1)(a)(I) is effective
until January 1, 2027.] No later than May 1 in each year, the assessor
shall mail to each person who owns land or improvements a notice setting forth
the valuation of such land or improvements. For agricultural property, the
notice must separately state the actual value of such land or improvements in
the previous year, the actual value in the current year, and the amount of any
adjustment in actual value. For all other property, the notice must state the
total actual value of such land and improvements together in the previous year,
the total actual value in the current year, and the amount of any adjustment in
total actual value. The notice must not state the valuation for assessment of
such land or improvements or combination of land and improvements. Based upon
the classification of such taxable property, the notice must also set forth the
appropriate ratio of valuation for assessment to be applied to said actual
value prior to the calculation of property taxes for the current year and that
any change or adjustment of the ratio of valuation for assessment must not
constitute grounds for the protest or abatement of taxes. The notice must
state, in bold-faced type, that the taxpayer has the right to protest any
adjustment in valuation, the classification of the property that determines the
assessment percentage to be applied, and the dates and places at which the
assessor will hear such protest. The notice must also set forth the following:
That, to preserve the taxpayer's right to protest, the taxpayer shall notify
the assessor either in writing or in person of the taxpayer's objection and
protest; that such notice must be delivered, postmarked, or given in person no
later than June 8; and that, after such date, the taxpayer's right to object
and protest the adjustment in valuation is lost. The notice must be mailed
together with a form that, if completed by the taxpayer, allows the taxpayer to
explain the basis for the taxpayer's valuation of the property. Such form may
be completed by the taxpayer to initiate an appeal of the assessor's valuation.
However, in accordance with section 39-5-122 (2), completion of this form does
not constitute the exclusive means of appealing the assessor's valuation. For
the years that intervene between changes in the level of value, if the
difference between the actual value of such land or improvements in the
previous year and the actual value of such land or improvements in the
intervening year as set forth in such notice constitutes an increase in actual
value of more than seventy-five percent, the assessor shall mail together with
the notice an explanation of the reasons for such increase in actual value.
(1) (a)
(I) [Editor's note: This version of subsection (1)(a)(I) is effective
January 1, 2027.] No later than May 1 in each year, the assessor shall
mail to each person who owns land or improvements a notice setting forth the
valuation of such land or improvements. For agricultural property, the notice
must separately state the actual value of such land or improvements in the
previous year, the actual value in the current year, and the amount of any
adjustment in actual value. For all other property, the notice must state the
total actual value of such land and improvements together in the previous year,
the total actual value in the current year, and the amount of any adjustment in
total actual value. The notice must not state the valuation for assessment of
such land or improvements or combination of land and improvements. Based upon
the classification of such taxable property, the notice must also set forth the
appropriate ratio of valuation for assessment to be applied to said actual
value prior to the calculation of property taxes for the current year and that
any change or adjustment of the ratio of valuation for assessment does not
constitute grounds for the protest or abatement of taxes. The notice must
state, in bold-faced type, that the taxpayer has the right to protest any
adjustment in valuation, the classification of the property that determines the
assessment percentage to be applied, and the dates and places at which the
assessor will hear such protest. The notice must also set forth the following:
That, to preserve the taxpayer's right to protest, the taxpayer shall notify
the assessor either in writing or in person of the taxpayer's objection and
protest; that such notice must be delivered, postmarked, or given in person no
later than June 1; and that, after such date, the taxpayer's right to object
and protest the adjustment in valuation is lost. The notice must be mailed
together with a form that, if completed by the taxpayer, allows the taxpayer to
explain the basis for the taxpayer's valuation of the property. Such form may
be completed by the taxpayer to initiate an appeal of the assessor's valuation.
However, in accordance with section 39-5-122 (2), completion of this form does
not constitute the exclusive means of appealing the assessor's valuation. For
the years that intervene between changes in the level of value, if the
difference between the actual value of such land or improvements in the
previous year and the actual value of such land or improvements in the
intervening year as set forth in such notice constitutes an increase in actual
value of more than seventy-five percent, the assessor shall mail together with
the notice an explanation of the reasons for such increase in actual value.
(II)
Repealed.
(b) (I)
Commencing as provided in subparagraph (II) of this paragraph (b), the notice
of valuation for the first year of each reassessment cycle that is mailed to
each person who owns land or improvements pursuant to paragraph (a) of this
subsection (1) shall include, in addition to the information specified in
paragraph (a) of this subsection (1), an itemized listing of the land and
improvements and the characteristics that are germane to the value of such land
and improvements.
(II) In
a county with a population in excess of fifty thousand people, the information
specified in subparagraph (I) of this paragraph (b) shall be included in
notices of valuation mailed on or after January 1, 2001. In a county with a
population of twenty-five thousand people or more but not more than fifty
thousand people, the information specified in subparagraph (I) of this
paragraph (b) shall be included in notices of valuation mailed on or after
January 1, 2003. In a county with a population of less than twenty-five
thousand people, the information specified in subparagraph (I) of this
paragraph (b) shall be included in notices of valuation mailed on or after
January 1, 2005.
(c) For
property tax years commencing on or after January 1, 2025, the assessor shall
not include the appropriate ratio of valuation for assessment in the notice
setting forth the valuation for land or improvements.
(1.2) A
notice of valuation included with the tax bill shall fulfill the requirements
of subsection (1) of this section. The general assembly hereby finds and
declares that the notice procedure set forth in this subsection (1.2)
facilitates the efficient and economic operation of local governments,
consistent with the expressed purpose of section 20 of article X of the state
constitution to reasonably restrain most of the growth of government, and still
fulfills the purposes of section 20 (8)(c) of said article X in the intervening
year of each reassessment cycle when there is no change in value for the
property in such year.
(1.5) (a)
(I) [Editor's note: This version of subsection (1.5)(a)(I) is
effective until January 1, 2027.] No later than June 15 each year, the
assessor shall mail to each person who owns taxable personal property a notice
setting forth the valuation of the personal property. The notice must state the
actual value of such personal property in the previous year, the actual value
in the current year, and the amount of any adjustment in actual value. The
notice must not state the valuation for assessment of the personal property.
The notice must also set forth the ratio of valuation for assessment to be
applied to said actual value prior to the calculation of property taxes for the
current year. With the approval of the board of county commissioners, the assessor
may include in the notice an estimate of the taxes owed for the current
property tax year. If such an estimate is included, the notice must clearly
state that the tax amount is merely an estimate based upon the best available
information. The notice must state, in bold-faced type, that the taxpayer has
the right to protest any adjustment in valuation but not the estimate of taxes
if such an estimate is included in the notice, and the dates and places at
which the assessor will hear protests. The notice must also set forth the
following: To preserve the taxpayer's right to protest, the taxpayer shall
notify the assessor either by mail or in person of the taxpayer's objection and
protest; that the notice must be postmarked or physically delivered no later
than June 30; and that, after such date, the taxpayer's right to object and
protest the adjustment in valuation is lost. The notice must be mailed together
with a form that, if completed by the taxpayer, allows the taxpayer to explain
the basis for the taxpayer's valuation of the property. The form may be
completed by the taxpayer to initiate an appeal of the assessor's valuation.
However, in accordance with section 39-5-122 (2), completion of this form does
not constitute the exclusive means of appealing the assessor's valuation.
(1.5) (a)
(I) [Editor's note: This version of subsection (1.5)(a)(I) is
effective January 1, 2027.] Except as provided in subsection
(1.5)(a)(III) of this section for a county that uses an alternate protest and
appeal procedure pursuant to section 39-5-122.7, no later than June 15 each
year, the assessor shall mail to each person who owns taxable personal property
a notice setting forth the valuation of the personal property. The notice must
state the actual value of such personal property in the previous year, the
actual value in the current year, and the amount of any adjustment in actual
value. The notice must not state the valuation for assessment of the personal
property. The notice must also set forth the ratio of valuation for assessment
to be applied to said actual value prior to the calculation of property taxes
for the current year. With the approval of the board of county commissioners,
the assessor may include in the notice an estimate of the taxes owed for the
current property tax year. If such an estimate is included, the notice must
clearly state that the tax amount is merely an estimate based upon the best
available information. The notice must state, in bold-faced type, that the
taxpayer has the right to protest any adjustment in valuation but not the
estimate of taxes if such an estimate is included in the notice, and the dates
and places at which the assessor will hear protests. The notice must also set
forth the following: To preserve the taxpayer's right to protest, the taxpayer
shall notify the assessor either by mail or in person of the taxpayer's
objection and protest; that the notice must be postmarked or physically
delivered no later than June 30; and that, after such date, the taxpayer's
right to object and protest the adjustment in valuation is lost. The notice
must be mailed together with a form that, if completed by the taxpayer, allows
the taxpayer to explain the basis for the taxpayer's valuation of the property.
The form may be completed by the taxpayer to initiate an appeal of the
assessor's valuation. However, in accordance with section 39-5-122 (2),
completion of this form does not constitute the exclusive means of appealing
the assessor's valuation.
(II)
Repealed.
(III) [Editor's
note: Subsection (1.5)(a)(III) is effective January 1, 2027.] For a
county that uses an alternate protest and appeal procedure pursuant to section
39-5-122.7, no later than July 15 each year, the assessor shall mail to each
person who owns taxable personal property a notice setting forth the valuation
of the personal property. The notice must state the actual value of such
personal property in the previous year, the actual value in the current year,
and the amount of any adjustment in actual value. The notice must not state the
valuation for assessment of the personal property. The notice must also set
forth the ratio of valuation for assessment to be applied to said actual value
prior to the calculation of property taxes for the current year. With the
approval of the board of county commissioners, the assessor may include in the
notice an estimate of the taxes owed for the current property tax year. If such
an estimate is included, the notice must clearly state that the tax amount is merely
an estimate based upon the best available information. The notice must state,
in bold-face type, that the taxpayer has the right to protest any adjustment in
valuation but not the estimate of taxes if such an estimate is included in the
notice, and the dates and places at which the assessor will hear protests. The
notice must also set forth the following: To preserve the taxpayer's right to
protest, the taxpayer shall notify the assessor either by mail or in person of
the taxpayer's objection and protest; that the notice must be postmarked or
physically delivered no later than July 31; and that, after said date, the
taxpayer's right to object and protest the adjustment in valuation is lost. The
notice must be mailed together with a form that, if completed by the taxpayer,
allows the taxpayer to explain the basis for the taxpayer's valuation of the
property. The form may be completed by the taxpayer to initiate an appeal of
the assessor's valuation. However, in accordance with section 39-5-122 (2),
completion of this form does not constitute the exclusive means of appealing
the assessor's valuation.
(b) (I)
Notwithstanding subsection (1.5)(a) of this section, for taxable real property
and personal property on oil and gas leaseholds or lands for which the operator
has filed the statement required by section 39-7-101 (1), the assessor shall
send the notice of valuation only to the operator, who shall accept it. The
acceptance of the notice of valuation by the operator shall not be construed as
an indication that the operator agrees with the amount of the actual value of
the property stated in the notice or as obligating the operator to pay the tax
attributable to property in which the operator has no ownership interest. Upon
the written request of the county treasurer, the operator shall submit to the
treasurer a written statement containing the name and address of each person
who has an ownership interest in the property. If the operator fails to submit
the statement within thirty days after receiving the request, the operator
shall pay a penalty to the treasurer in the amount of one hundred dollars or
the amount of tax due on the property, whichever is less.
(II) As
used in this article 5, "well or unit operator" means the operator of
each wellsite or, if there is no operator, the owner who filed the statement
with the assessor pursuant to section 39-7-101.
(1.7)
Notwithstanding any other provision of law, a taxpayer may request to receive
by electronic transmission the notices of valuation required by subsections (1)
and (1.5) of this section. The taxpayer shall submit along with the request an
electronic address to which the assessor may send future notices of valuation.
The assessor, upon receipt of such request by a taxpayer to receive notices of
valuation electronically, may send all future notices of valuation by
electronic transmission to the electronic address supplied by the taxpayer;
except that, if a taxpayer subsequently requests to cease the electronic
transmission of such notices and requests to receive future notices of
valuation by mail, the assessor shall comply with the request. Failure of a
taxpayer to receive the electronic notice of valuation shall not preclude
collection by the treasurer of the amount of taxes due from and payable by the
taxpayer.
(1.8)
(a) Notwithstanding any other provision of law, the assessor may mail
abbreviated notices of valuation on a postcard. The property tax administrator
shall approve the form of the abbreviated notice of valuation as required in
section 39-2-109 (1)(d).
(b) At
a minimum, the postcard must:
(I)
Provide an accurate summary of the valuation information required under
subsections (1) and (1.5) of this section;
(II)
Provide contact information for the assessor's office;
(III)
Include a link to the assessor's website where taxpayers can access the long
form notice of valuation that includes all of the information required under
subsections (1) and (1.5) of this section; and
(IV)
State that the taxpayer may request to cease the transmission of the notice of
valuation by postcard and may instead request to receive future long form
notice of valuation mailed in an envelope.
(c) If
the taxpayer would prefer to not use the link to the assessor's website to
access the long form notice of valuation, the taxpayer may contact the
assessor's office and request a long form notice of valuation be mailed
instead.
(d) If
a taxpayer makes a request described in subsection (1.8)(b)(IV) of this
section, the assessor shall comply.
(e)
Failure of a taxpayer to receive the notice of valuation by postcard does not
preclude collection by the treasurer of the amount of taxes due from and
payable by the taxpayer.
(2) (a)
The assessor shall, no later than August 25 of each year, notify each taxing
entity subject to the provisions of section 29-1-301, C.R.S., the division of
local government, and the department of education of the total valuation for
assessment of land and improvements within the entity and shall also report:
The amount of the total valuation for assessment attributable to annexation or
inclusion of additional land, and the improvements thereon, and personal
property connected therewith, within the taxing entity for the preceding year;
the amount attributable to new construction and personal property connected
therewith, as defined by the administrator in manuals prepared pursuant to
section 39-2-109 (1)(e), within the taxing entity for the preceding year; the
amount attributable to increased volume of production for the preceding year by
a producing mine if said mine is wholly or partially within the taxing entity
and if such increase in volume of production causes an increase in the level of
services provided by the taxing entity; and the amount attributable to
previously legally exempt federal property that becomes taxable if such
property causes an increase in the level of services provided by the taxing
entity.
(b) In
addition to the information specified in paragraph (a) of this subsection (2),
the assessor shall, no later than August 25 of each year, notify each taxing
entity except school districts of the total actual value of all real property
within the taxing entity and the total actual value of all real property within
the taxing entity from construction of taxable real property improvements,
minus destruction of similar improvements, and additions to, minus deletions
from, taxable real property, in accordance with the manner prescribed by the
administrator in manuals prepared pursuant to section 39-2-109 (1)(e).
(3)
Repealed.
(4) (a)
[Editor's note: This version of subsection (4)(a) is effective until
January 1, 2027.] Any notice of valuation required by subsections (1)
and (1.5) of this section sent to the owner of any real property must include
the following statement: "If a property owner does not timely object to
their property's valuation by June 8 under section 39-5-122, C.R.S., they may
file a request for an abatement under section 39-10-114, C.R.S., by contacting
the county assessor."
(4) (a)
[Editor's note: This version of subsection (4)(a) is effective January 1,
2027.] Any notice of valuation required by subsections (1) and (1.5) of
this section sent to the owner of any real property must include the following
statement: "If a property owner does not timely object to their property's
valuation by June 1 under section 39-5-122, they may file a request for an
abatement under section 39-10-114 by contacting the county assessor."
(b) Any
notice of valuation required by subsections (1) and (1.5) of this section sent
to the owner of commercial property must include contact information for the
relevant county assessor along with the following statement: "If you would
like information about the approach used to value your property, please contact
your county assessor."
Source:
L. 64: R&RE,
p. 703, § 1. C.R.S. 1963: § 137-5-21. L. 67: p. 952, § 26. L.
76: Entire section amended, p. 687, § 4, effective July 1; (1) amended, p.
762, § 23, effective January 1, 1977. L. 81: (1) amended and (1.5)
added, p. 1833, § 8, effective June 12; (2) amended, p. 1395, § 3, effective
January 1, 1985. L. 83: (2) amended, p. 2073, § 4, effective October 13;
(2) amended, p. 2052, § 24, effective October 14; (2) amended, pp. 2074, 2052,
§§ 5, 25, effective January 1, 1985. L. 87: (2) amended, p. 1188, § 4,
effective March 12. L. 88: (1) and (1.5) amended, p. 1298, § 5,
effective April 29; (1) and (1.5) amended, p. 1285, § 17, effective May 23. L.
89: Entire section amended, p. 1453, § 9, effective June 7. L. 90:
(1) amended, p. 1690, § 8, effective January 1, 1991. L. 92: (2)
amended, p. 2182, § 54, effective June 2; (1) and (1.5) amended, p. 2207, § 4,
effective January 1, 1993. L. 93: (2) amended, pp. 1282, 1688, §§ 2, 5,
effective June 6. L. 96: (1), (1.5), and (2)(a) amended, p. 113, § 1,
effective March 25; (1) and (1.5) amended and (1.2) added, p. 720, § 5,
effective May 22. L. 99: (1) amended, p. 704, § 1, effective May 20. L.
2002: (1)(a) amended, p. 41, § 1, effective August 7. L. 2006: (1.5)
amended, p. 33, § 1, effective March 13. L. 2008: (1.5)(a) amended, p.
948, § 3, effective August 5. L. 2010: (1.7) added, (HB 10-1117), ch.
195, p. 842, § 2, effective August 11. L. 2013: (1)(a) and (1.5)(a)
amended, (HB 13-1113), ch. 11, p. 26, § 1, effective March 8. L. 2020:
(1)(a)(I) and (1.5)(a)(I) amended and (1)(a)(II) and (1.5)(a)(II) repealed, (SB
20-136), ch. 70, p. 290, § 33, effective September 14. L. 2021: (1.8)
added, (SB 21-019), ch. 14, p. 88, § 2, effective March 21; (1)(a)(I) amended
and (3) added, (SB 21-293), ch. 301, p. 1811, § 10, effective June 23. L.
2022: (1.5)(b) amended, (SB 22-026), ch. 58, p. 265, § 1, effective March
30; (1)(a)(I) amended and (4) added, (HB 22-1416), ch. 158, p. 997, § 3,
effective August 10. L. 2024: (1)(a)(I) amended, (HB 24-1302), ch. 340,
p. 2301, § 3, effective June 3. L. 2024, 2nd Ex. Sess.: (1)(c) added,
(HB 24B-1001), ch. 1, p. 22, § 16, effective October 1 (see editor's note). L.
2026: (1)(a)(I), (1.5)(a)(I), and (4)(a) amended and (1.5)(a)(III) added,
(SB 26-046), ch. 10, p. 44, § 10, effective January 1, 2027.
Editor's
note: (1)
Amendments to subsection (2) by House Bill 83-1580 and Senate Bill 83-414 were
harmonized. Amendments to subsection (2) by Senate Bill 93-255 and House Bill
93-1321 were harmonized. Amendments to subsections (1) and (1.5) by House Bill
96-1131 and House Bill 96-1063 were harmonized.
(2) Subsection (3)(b) provided
for the repeal of subsection (3), effective July 1, 2023. (See L. 2021, p.
1811.)
(3) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
Cross references: (1) For the legislative
declaration in SB 20-136, see section 1 of chapter 70, Session Laws of Colorado
2020.
(2) For the legislative
declaration in SB 21-019, see section 1 of chapter 14, Session Laws of Colorado
2021.
ANNOTATION
Law reviews. For
article, "Property Tax Assessments in Colorado", see 12 Colo. Law.
563 (1983). For article, "Appealing Property Tax Assessments", see 15
Colo. Law. 798 (1986).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Assessor's compliance with
section condition precedent to tax levy. A compliance with this section by
the county assessor is a condition precedent to the validity of a tax levy.
Goldsmith v. Standard Chem. Co., 77 Colo. 1, 233 P. 1110 (1925).
The assessor cannot ignore
law and deprive taxpayer of rights. The omission of an assessor to give the
statutory notice of a change in a tax schedule to a taxpayer is a denial of a
substantial right; the assessor cannot, by ignoring the law, deprive the
taxpayer of a right expressly fixed by these sections. Goldsmith v. Standard
Chem. Co., 77 Colo. 1, 233 P. 1110 (1925).
Proper discharge of duties
is rebuttable presumption. A rebuttable presumption exists that public
officials, including county assessors, properly discharge their statutory
duties. Canyon Crest Villas S. v. Bd. of County Comm'rs, 36 Colo. App. 409, 542
P.2d 395 (1975).
Section deemed mandatory
when taxpayer denied hearing. The requirements of this section and §§
39-8-103 and 39-8-104 are to be construed as mandatory only in specific
instances where it is clearly shown on behalf of an aggrieved taxpayer, that,
on account of noncompliance with these statutory requirements by the county
officials charged therewith, the taxpayer has been deprived of an opportunity
for a hearing, or other right important to him. Northcutt v. Burton, 127 Colo.
145, 254 P.2d 1013 (1953); Rico Argentine Mining Co. v. Bd. of County Comm'rs,
215 F. Supp. 208 (D. Colo. 1963).
No deprivation of relief by
failure to file timely notice. The failure to provide timely notice of the
correct amount of an increase in valuation does not deprive taxpayer of the
right to administrative or judicial relief. Modular Cmtys., Inc. v. McKnight,
191 Colo. 101, 550 P.2d 866 (1976).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
39-5-121.5. Valuation - inspection of
data by taxpayers.
At the
written request of any taxpayer or any agent of such taxpayer and subject to
such confidentiality requirements as provided by law, the assessor shall,
within seven working days after receipt of said request, make available to the
taxpayer or agent the data used by the assessor in determining the actual value
of any property owned by such taxpayer. At the assessor's election, the
assessor may either mail, fax, or send by electronic transmission to the
address, phone number, or electronic address supplied by said taxpayer or agent
such data. Such data shall include but shall not be limited to the data derived
from the declarations filed pursuant to the provisions of article 14 of this
title and confidential data, provided that such confidential data shall be
presented in such a manner that the source cannot be identified. Upon receipt
of such request, the assessor shall notify the taxpayer or agent of the
estimated cost of providing such information, payment of which shall be made
prior to providing such information. Upon providing such information, the
assessor may include a bill for the reasonable cost above the estimated cost
and up to the statutory maximum which shall be due and payable upon receipt by
the taxpayer or agent.
Source:
L. 89: Entire
section added, p. 1466, § 33, effective June 7. L. 90: Entire section
amended, p. 1700, § 29, effective June 9. L. 2000: Entire section
amended, p. 1500, § 3, effective August 2.
39-5-122. Taxpayer's remedies to
correct errors.
(1) (a)
[Editor's note: This version of subsection (1)(a) is effective until
January 1, 2027.] On or before May 1 of each year, the assessor shall
give public notice in at least one issue of a newspaper published in the
assessor's county that, beginning on the first working day after notices of
adjusted valuation are mailed to taxpayers, the assessor will sit to hear all
objections and protests concerning valuations of taxable real property
determined by the assessor for the current year; that, for a taxpayer's
objection and protest to be heard, notice must be given to the assessor; and
that such notice must be postmarked, delivered, or given in person by June 8.
The notice must also state that objections and protests concerning valuations
of taxable personal property determined by the assessor for the current year
will be heard commencing June 15; that, for a taxpayer's objection and protest
to be heard, notice must be given to the assessor; and that such notice must be
postmarked or physically delivered by June 30. If there is no such newspaper,
then such notice must be conspicuously posted in the offices of the assessor,
the treasurer, and the county clerk and recorder and in at least two other
public places in the county seat. The assessor shall send news releases
containing such notice to radio stations, television stations, and newspapers
of general circulation in the county.
(1) (a)
[Editor's note: This version of subsection (1)(a) is effective January 1,
2027.] On or before May 1 of each year, the assessor shall give public
notice in at least one issue of a newspaper published in the assessor's county
that, beginning on the first working day after notices of adjusted valuation
are mailed to taxpayers, the assessor will sit to hear all objections and
protests concerning valuations of taxable real property determined by the
assessor for the current year; that, for a taxpayer's objection and protest to
be heard, notice must be given to the assessor; and that such notice must be
postmarked, delivered, or given in person by June 1. The notice must also state
that objections and protests concerning valuations of taxable personal property
determined by the assessor for the current year will be heard commencing June
15; that, for a taxpayer's objection and protest to be heard, notice must be
given to the assessor; and that such notice must be postmarked or physically
delivered by June 30 or, for a county that uses an alternate protest and appeal
procedure pursuant to section 39-5-122.7, by July 31. If there is no such
newspaper, then such notice must be conspicuously posted in the offices of the
assessor, the treasurer, and the county clerk and recorder and in at least two
other public places in the county seat. The assessor shall send news releases
containing such notice to radio stations, television stations, and newspapers
of general circulation in the county.
(b)
Repealed.
(2) [Editor's
note: This version of subsection (2) is effective until January 1, 2027.]
If any person is of the opinion that the person's property has been valued too
high, has been twice valued, or is exempt by law from taxation or that property
has been erroneously assessed to such person, the person may appear before the
assessor and object, complete the form mailed with the person's notice of
valuation pursuant to section 39-5-121 (1) or (1.5), or file a written letter
of objection and protest by mail with the assessor's office before the last day
specified in the notice, stating in general terms the reason for the objection
and protest. Reasons for the objection and protest may include, but shall not
be limited to, the installation and operation of surface equipment relating to
oil and gas wells on agricultural land. Any change or adjustment of any ratio
of valuation for assessment shall not constitute grounds for an objection. If
the form initiating an appeal or the written letter of objection and protest is
filed by mail, it shall be presumed that it was received as of the day it was
postmarked. If the form initiating an appeal or the written letter of objection
and protest is hand-delivered, the date it was received by the assessor shall
be stamped on the form or letter. As stated in the public notice given by the
assessor pursuant to subsection (1) of this section, the taxpayer's
notification to the assessor of the taxpayer's objection and protest to the
adjustment in valuation must be delivered, postmarked, or given in person by
June 8 in the case of real property. In the case of personal property, the
notice must be postmarked or physically delivered by June 30. All such forms
and letters received from protesters shall be presumed to be on time unless the
assessor can present evidence to show otherwise. The county shall not prescribe
the written form of objection and protest to be used. The protester shall have
the opportunity on the days specified in the public notice to present the
protester's objection in writing or protest in person and be heard, whether or
not there has been a change in valuation of such property from the previous
year and whether or not any change is the result of a determination by the
assessor for the current year or by the state board of equalization for the
previous year. If the assessor finds any valuation to be erroneous or otherwise
improper, the assessor shall correct the error. If the assessor declines to
change any valuation that the assessor has determined, the assessor shall
provide reasons in writing on the form described in section 39-8-106, shall
insert the information otherwise required by the form, and shall mail two
copies of the completed form to the person presenting the objection and protest
so denied on or before the last regular working day of the assessor in June in
the case of real property and on or before July 10 in the case of personal
property; except that, if a county uses an alternate protest and appeal
procedure pursuant to section 39-5-122.7, the assessor shall mail the copies on
or before August 15 in the case of both real and personal property.
(2) [Editor's
note: This version of subsection (2) is effective January 1, 2027.] If
any person is of the opinion that the person's property has been valued too
high, has been twice valued, or is exempt by law from taxation or that property
has been erroneously assessed to such person, the person may appear before the
assessor and object, complete the form mailed with the person's notice of
valuation pursuant to section 39-5-121 (1) or (1.5), or file a written letter
of objection and protest by mail with the assessor's office before the last day
specified in the notice, stating in general terms the reason for the objection
and protest. Reasons for the objection and protest may include, but shall not
be limited to, the installation and operation of surface equipment relating to
oil and gas wells on agricultural land. Any change or adjustment of any ratio
of valuation for assessment shall not constitute grounds for an objection. If
the form initiating an appeal or the written letter of objection and protest is
filed by mail, it shall be presumed that it was received as of the day it was
postmarked. If the form initiating an appeal or the written letter of objection
and protest is hand-delivered, the date it was received by the assessor shall
be stamped on the form or letter. As stated in the public notice given by the
assessor pursuant to subsection (1) of this section, the taxpayer's
notification to the assessor of the taxpayer's objection and protest to the
adjustment in valuation must be delivered, postmarked, or given in person by
June 1 in the case of real property. In the case of personal property, the
notice must be postmarked or physically delivered by June 30; except that, for
a county that uses an alternate protest and appeal procedure pursuant to section
39-5-122.7, the notice must be postmarked or physically delivered by July 31.
All such forms and letters received from protesters shall be presumed to be on
time unless the assessor can present evidence to show otherwise. The county
shall not prescribe the written form of objection and protest to be used. The
protester shall have the opportunity on the days specified in the public notice
to present the protester's objection in writing or protest in person and be
heard, whether or not there has been a change in valuation of such property
from the previous year and whether or not any change is the result of a
determination by the assessor for the current year or by the state board of
equalization for the previous year. If the assessor finds any valuation to be
erroneous or otherwise improper, the assessor shall correct the error. If the
assessor declines to change any valuation that the assessor has determined, the
assessor shall provide reasons in writing on the form described in section
39-8-106, shall insert the information otherwise required by the form, and
shall mail one copy of the completed form to the person presenting the
objection and protest so denied on or before the last regular working day of
the assessor in June in the case of real property and on or before July 10 in
the case of personal property; except that, if a county uses an alternate
protest and appeal procedure pursuant to section 39-5-122.7, the assessor shall
mail the copies on or before August 15 in the case of both real and personal
property.
(2.5)
If the property that is the subject of an objection and protest is
rent-producing commercial real property located in a county that uses an
alternate protest and appeal procedure pursuant to section 39-5-122.7, then, on
or before July 15, the taxpayer shall provide to the assessor the information
described in section 39-8-107 (5)(a)(I).
(3) Any
person whose objection and protest has been denied in writing by the assessor
may appeal to the county board of equalization in the manner provided in
article 8 of this title.
(4) [Editor's
note: This version of subsection (4) is effective until January 1, 2027.]
The assessor shall continue the assessor's hearings from day to day until all
objections and protests have been heard, but all such hearings must be
concluded by June 8 in the case of real property and July 5 in the case of
personal property.
(4) [Editor's
note: This version of subsection (4) is effective January 1, 2027.] The
assessor shall continue the assessor's hearings from day to day until all
objections and protests have been heard, but all such hearings must be
concluded by June 1 in the case of real property and June 30 in the case of
personal property; except that, for a county that uses an alternate protest and
appeal procedure pursuant to section 39-5-122.7, the hearings must be concluded
by July 31 in the case of personal property.
(5) (a)
Any written statement given by any assessor which consists only of a denial of
any objection and protest or which consists of a statement referring to
compliance by the county with the requirements of valuation for assessment
study shall not be sufficient to satisfy the requirements of subsection (2) of
this section concerning the statement of reasons why an objection and protest
is denied.
(b) Any
information presented by the taxpayer regarding the value of his property shall
be considered by the assessor in determining whether an adjustment in value is
warranted.
(6) If,
during the appeal process described in this section, the assessor discovers any
error that impacts the valuation of a class or subclass of property, then,
pursuant to section 39-8-102 (1), the assessor shall recommend to the county
board of equalization an adjustment to the valuation of the class or subclass
of property to correct the error.
Source:
L. 64: R&RE,
p. 703, § 1. C.R.S. 1963: § 137-5-22. L. 73: p. 1441, § 1. L.
76: (1), (2), and (4) amended, p. 762, § 24, effective January 1, 1977. L.
77: (2) amended, p. 1735, § 16, effective June 20. L. 81: (1), (2),
and (4) amended, p. 1833, § 9, effective June 12. L. 84: (2) amended, p.
1000, § 1, effective March 5. L. 88: (1), (2), and (4) amended, p. 1300,
§ 6, effective April 29; (2) amended, p. 1287, § 18, effective May 23. L.
89: (1) and (2) amended, p. 1455, § 10, effective June 7. L. 90: (1),
(2), and (4) amended and (5) added, p. 1691, § 9, effective January 1, 1991. L.
92: (2) amended, pp. 2209, 2213, §§ 5, 11, effective June 3. L. 98:
(2) amended, p. 468, § 2, effective July 1. L. 2002: (1) and (2)
amended, p. 42, § 2, effective August 7. L. 2005: (2) amended, p. 390, §
1, effective April 27. L. 2008: (1) and (2) amended, p. 949, § 4,
effective August 5. L. 2013: (1) amended, (HB 13-1113), ch. 11, p. 28, §
2, effective March 8. L. 2019: (2) amended and (2.5) added, (HB
19-1175), ch. 43, p. 147, § 1, effective March 21. L. 2020: (1)(a)
amended and (1)(b) repealed, (SB 20-136), ch. 70, p. 292, § 34, effective
September 14. L. 2021: (2) amended, (SB 21-293), ch. 301, p. 1812, § 12,
effective June 23. L. 2022: (1)(a) and (2) amended and (6) added, (HB
22-1416), ch. 158, p. 998, § 4, effective August 10. L. 2025: (2),
(2.5), and (4) amended, (HB 25-1324), ch. 445, p. 2558, § 1, effective June 4. L.
2026: (1)(a), (2), and (4) amended, (SB 26-046), ch. 10, p. 46, § 11,
effective January 1, 2027.
Editor's
note: Amendments
to subsection (2) by sections 5 and 11 of Senate Bill 92-50 were harmonized.
Cross
references: For
the legislative declaration in SB 20-136, see section 1 of chapter 70, Session
Laws of Colorado 2020.
ANNOTATION
Law reviews. For
article, "A Calendar of Tax Procedure in Colorado", see 6 Dicta 17
(July 1929). For article, "Some Aspects of Colorado Taxpayers'
Remedies", see 23 Rocky Mt. L. Rev. 145 (1950). For article,
"Property Tax Assessments in Colorado", see 12 Colo. Law. 563 (1983).
For article, "Appealing Property Tax Assessments", see 15 Colo. Law.
798 (1986). For article, "Property Tax Litigation Before the Board of
Assessment Appeals", see 35 Colo. Law. 87 (Aug. 2006).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Statutes fixing meeting
times deemed directory. Statutes fixing times for meetings and other
functions of state officials are merely directory; the alleged noncompliance
therewith on the part of said officials being matters nonprejudicial to
complainants, they are not subject to attack on their part. Citizens' Comm. for
Fair Prop. Taxation v. Warner, 127 Colo. 121, 254 P.2d 1005 (1953).
Steps in assessment process
which are for benefit of taxpayer are mandatory. Sperry Rand Corp. v. Bd.
of County Comm'rs, 31 Colo. App. 444, 503 P.2d 356 (1972).
The statutory requirements set
forth in this section are mandatory only if an aggrieved taxpayer can show that
noncompliance by county officials has deprived him of an opportunity for a
hearing or other right which he might otherwise have had. Modular Cmtys., Inc.
v. McKnight, 191 Colo. 101, 550 P.2d 866 (1976).
The provisions of § 39-8-106
and this section are remedial. Kortz v. Ellingson, 181 F. Supp. 857 (D.
Colo. 1960).
Property tax valuation
challenge. A taxpayer has the statutory right to challenge a property tax
valuation for each tax year under the protest and adjustment procedure and
possibly through de novo evidentiary proceedings before the board of assessment
appeals. Weingarten v. Bd. of Assessment Appeals, 876 P.2d 118 (Colo. App.
1994).
Subsection (2) is
unambiguous and authorizes an assessor to raise a property valuation after
a taxpayer has filed a protest challenging the original valuation of the
property. San Miguel County Bd. of Equaliz. v. Telluride Co., 947 P.2d 1381
(Colo. 1997).
Aggrieved person must
conform to provisions of section. This section gives to an aggrieved
property owner a remedy which, in its absence, he would not have by prescribing
a special procedure to which the person seeking to avail himself of its
provisions must conform. It cannot by construction be extended to embrace cases
not falling within its letter or spirit. Bd. of County Comm'rs v. Denver Union
Water Co., 32 Colo. 382, 76 P. 1060 (1904).
If an assessment is erroneous
or excessive, the right to relief can be lost through failure to pursue the
proper statutory remedy. Citizens' Comm. for Fair Prop. Taxation v. Warner, 127
Colo. 121, 254 P.2d 1005 (1953).
When burden on taxpayer to
show illegal tax. Where a taxpayer claims a refund of taxes, paid under
protest, for over-valuation in successive years, and where the facts show that
the initial over-valuation based on the type of construction was neither
illegal nor invalid, the taxpayer has burden, if proceeding under this section,
of showing that the tax was illegally laid, erroneous in its entirety, and
incapable of adjustment. City & County of Denver v. Athmar Park Bldg. Co.,
151 Colo. 424, 378 P.2d 638 (1963).
There is no need to
characterize the tax paid as wholly illegal before claiming a refund. Bd. of
Assessment Appeals v. Benbrook, 735 P.2d 860 (Colo. 1987) (overruling prior
cases).
Administrative remedies to
be exhausted before court action permissible. Exhaustion of administrative
remedies, as provided by this section and § 39-8-106 is a requisite precedent
to the maintenance of a court action. Citizens' Comm. for Fair Prop. Taxation
v. Warner, 127 Colo. 121, 254 P.2d 1005 (1953).
The trial court is without
jurisdiction to permit condominium owners to bring a class action challenging
the assessor's routine increase in valuation of all condominiums upon their
conversion where most owners had not pursued the remedy provided by this
section. Hoffman v. Bd. of Assessment Appeals, 683 P.2d 783 (Colo. 1984).
Until relief under this
section is sought, a taxpayer cannot appeal. Bordner v. Bd. of County
Comm'rs, 92 Colo. 81, 18 P.2d 323 (1932).
A taxpayer is not entitled to
bring C.R.C.P. 106 proceeding without first having filed its protest and
pursued the proper administrative remedies. Honeywell Info. Sys. v. Bd. of
Assessment Appeals, 654 P.2d 337 (Colo. App. 1982).
No deprivation of relief by
failure to provide timely notice. The failure to provide timely notice of
the correct amount of an increase in valuation does not deprive taxpayer of the
right to administrative or judicial relief. Modular Cmtys., Inc. v. McKnight,
191 Colo. 101, 550 P.2d 866 (1976).
Provisions on abatement and
refund of taxes apply to relief sought under this section. When a taxpayer
who seeks administrative relief under this section prevails before the board of
assessment appeals or the district court and such board or court's decision
occurs after the challenged property tax is due, §§ 39-1-113 and 39-10-114
apply to the refund of taxes paid under § 39-8-109. Bd. of Assessment Appeals
v. Benbrook, 735 P.2d 860 (Colo. 1987).
Because the term
"erroneous valuation for assessment" in § 39-10-114 on abatement of
taxes and "excessive valuation" under the protest and adjustment
provisions of this section refer to the same process of assessment, the
remedies available to the taxpayer regarding abatements apply to refunds
ordered pursuant to this section. Bd. of Assessment Appeals v. Benbrook, 735
P.2d 860 (Colo. 1987).
No choice of remedies.
The legislature's perpetuation of procedures and remedies for protest and
adjustment separate and distinct from procedures and remedies for abatement and
refund indicates that a taxpayer who seeks redress under one procedure cannot
claim the remedy of the other procedure if the taxpayer ultimately prevails.
Gates Rubber Co. v. Bd. of Equaliz., 770 P.2d 1189 (Colo. 1989).
For the assessor's yearly
property valuations of which the taxpayer has received notice, this section
is the appropriate route of protest. Sections 39-1-113 and 39-10-114 provide a
remedy for the abatement or refund of property taxes that cannot be challenged
under this section. Valley Country Club v. Bd. of Assessment Appeals, 778 P.2d
285 (Colo. App. 1989), rev'd on other grounds, 792 P.2d 299 (Colo. 1990).
If a taxpayer receives no
notice of a higher assessment and therefore is unable to file a timely
protest under this section, the taxpayer may instead apply for abatement or
refund under §§ 39-1-113 and 39-10-114. Valley Country Club v. Bd. of
Assessment Appeals, 778 P.2d 285 (Colo. App. 1989), rev'd on other grounds, 792
P.2d 299 (Colo. 1990).
If appeal is directed at
assessor and made prior to levy, it is correct to follow procedure
specified in this section, rather than that for abatement and refund. B.A.
Leasing Corp. v. State Bd. of Equal., 745 P.2d 254 (Colo. App. 1987), aff'd sub
nom. Gates Rubber Co. v. Bd. of Equaliz., 770 P.2d 1189 (Colo. 1989).
Where property has been
assessed improperly because of an error capable of adjustment, this section
must be followed and the procedure in §§ 39-1-113 and 39-10-114 for abatement
or refund is not available. Schmidt-Tiago Const. Co. v. Propty. Tax Adm'r, 687
P.2d 528 (Colo. App. 1984); Alpenrose Unit Week Ass'n v. Bd. of Assessment
Appeals, 713 P.2d 932 (Colo. App. 1985).
Where assessor failed to
give timely notice of property valuation, proper remedy is not to
invalidate tax but to allow taxpayer to seek abatement of the tax increase
pursuant to § 39-10-114. Bea Kay Real Estate Corp. v. Aragon, 782 P.2d 837
(Colo. App. 1989).
Burden of proof that
assessment incorrect. A taxpayer who protests a property tax assessment
bears the burden of proving, by a preponderance of the evidence, that the
assessment is incorrect. Honeywell Info. Sys. v. Bd. of Assessment Appeals, 654
P.2d 337 (Colo. App. 1982).
Challenges based on
overvaluation. Although taxpayers challenged the amount of taxes assessed
as excessive, this was not an "overvaluation" as the term is used in
§ 39-10-114 because, due to the taxpayers' wrongful inaction, the assessor's
BIA valuations are presumed to be valid. Therefore, for purposes of §
39-10-114, the assessor's valuation cannot be considered an overvaluation, and
§ 39-10-114 may not be asserted by a taxpayer to avoid the provisions of §
39-5-118 and the protest procedure under this section. Prop. Tax Adm'r v. Prod.
Geophysical, 860 P.2d 514 (Colo. 1993).
Application of abatement
procedure to personal property taxes. The protest procedure set forth in
this section, as opposed to the abatement procedure set forth in § 39-10-114,
is the exclusive method for challenging personal property BIA evaluations.
Prop. Tax Adm'r v. Prod. Geophysical, 860 P.2d 514 (Colo. 1993); Spectra Pub.
v. Prop. Tax Adm'r, 860 P.2d 520 (Colo. 1993).
Taxpayer may seek an
abatement and refund under § 39-10-114 even though taxpayer initially
protested valuation of the property under this section, because the taxpayer
did not base its petition for abatement on the ground of overvaluation but on
the arbitrator's clerical error. Landmark Petroleum v. County Comm'rs, 870 P.2d
610 (Colo. App. 1993).
A party may seek review of
only the total valuation for assessment and not of the component parts of that
total. The statutes speak only of the right to appeal the value or the
valuation assessment set by the assessor. Notably absent from the statutes is
language that would permit a party to limit the scope of the protest by
appealing only a portion or component of the assessed value. Cherne v. Bd. of
Equaliz., 885 P.2d 258 (Colo. App. 1994).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
Applied in Laredo Hous.
Apt., Ltd. v. Bd. of County Comm'rs, 628 P.2d 135 (Colo. App. 1980); Laredo
Hous. Apts., Ltd. v. Bd. of Assessment Appeals, 675 P.2d 23 (Colo. App. 1983);
S. Cafeteria, Inc. v. Propty. Tax Adm'r, 677 P.2d 362 (Colo. App. 1983);
Telluride Airport Auth. v. Bd. of Equaliz., 789 P.2d 201 (Colo. App. 1989);
Lucchesi v. State, 807 P.2d 1185 (Colo. App. 1990).
39-5-122.1. Appeal from illegal increase
in valuation of property resulting from order of state board. (Repealed)
Source:
L. 77: Entire
section added, p. 1736, § 17, effective June 20; entire section repealed, p.
1736, § 17, effective January 1, 1978.
39-5-122.5. Taxpayer's remedies -
property tax credit for incorrect valuations used for property tax levied in
1987 for collection in 1988. (Repealed)
Source:
L. 88: Entire
section added, p. 1288, § 21, effective May 23. L. 94: (3) amended, p.
824, § 54, effective April 27. L. 97: Entire section repealed, p. 1032,
§ 71, effective August 6.
39-5-122.7. Alternate protest and appeal
procedure for specified counties.
(1) [Editor's
note: This version of subsection (1) is effective until January 1, 2027.]
The governing body of any county may, at the request of the assessor, elect to
use an alternate protest and appeal procedure to determine objections and
protests concerning valuations of taxable property. The election shall not be
made unless the assessor has requested the use of the alternative protest and
appeal procedure. The election shall be made on or before May 1 of each year
and shall be effective for all objections and protests concerning valuations of
taxable property for the year. The governing body of the county shall provide
notice of the election to the board of assessment appeals and to the district
court in such county.
(1) [Editor's
note: This version of subsection (1) is effective January 1, 2027.] The
governing body of any county may, at the request of the assessor, elect to use
an alternate protest and appeal procedure to determine objections and protests
concerning valuations of taxable real or personal property. The election must
not be made unless the assessor has requested the use of the alternative
protest and appeal procedure. The election must be made on or before May 1 of
each year and is effective for all objections and protests concerning
valuations of taxable real or personal property for the year. The governing
body of the county shall provide notice of the election to the board of
assessment appeals and to the district court in such county.
(2) In
the event that a county elects to follow an alternative protest and appeal
procedure as authorized by subsection (1) of this section, the assessor shall
issue any written determination regarding the objection and protest by the date
specified in section 39-5-122 (2).
(3) For
purposes of this section, "county" shall include a city and county.
(4) [Editor's
note: This version of subsection (4) is effective until January 1, 2027.]
Notwithstanding subsection (1) of this section, beginning January 1, 2024,
counties with a population greater than three hundred thousand, as determined
pursuant to the most recently published population estimates from the state
demographer appointed by the executive director of the department of local
affairs, shall in any year of general reassessment of real property that is
valued biennially by an assessor pursuant to section 39-1-104 (10.2) use an
alternative protest and appeal procedure to determine objections and protests
concerning valuations of taxable property. When following an alternative
protest and appeal procedure pursuant to this subsection (4), the assessor
shall issue any written determination regarding the objection and protest by
the date specified in section 39-5-122 (2).
(4) [Editor's
note: This version of subsection (4) is effective January 1, 2027.]
Notwithstanding subsection (1) of this section, beginning January 1, 2024,
counties with a population greater than three hundred thousand, as determined
pursuant to the most recently published population estimates from the state
demographer appointed by the executive director of the department of local
affairs, shall in any year of general reassessment of real property that is
valued biennially by an assessor pursuant to section 39-1-104 (10.2) use an
alternative protest and appeal procedure to determine objections and protests
concerning valuations of taxable real property. When following an alternative
protest and appeal procedure pursuant to this subsection (4), the assessor
shall issue any written determination regarding the objection and protest by
the date specified in section 39-5-122 (2).
Source:
L. 98: Entire
section added, p. 467, § 1, effective July 1. L. 2005: (1) and (2)
amended, p. 391, § 2, effective April 27. L. 2023: (4) added, (SB
23-304), ch. 259, p. 1497, § 2, effective August 7. L. 2026: (1) and (4)
amended, (SB 26-046), ch. 10, p. 47, § 12, effective January 1, 2027.
39-5-122.8. Pilot alternate protest
procedure - city and county of Denver - repeal. (Repealed)
Source:
L. 2013: Entire
section added, (HB 13-1113), ch. 11, p. 29, § 3, effective March 8.
Editor's
note: Subsection
(3) provided for the repeal of this section, effective December 31, 2018. (See
L. 2013, p. 29.)
39-5-123. Abstract of assessment or
amended abstract of assessment.
(1) (a)
Upon conclusion of hearings by the county board of equalization, as provided in
article 8 of this title 39, the assessor shall complete the assessment roll of
all taxable property within the assessor's county, and, no later than August 25
in each year or no later than November 21 in each year in any county that uses
an alternate protest and appeal procedure pursuant to section 39-5-122.7, the
assessor shall prepare therefrom the abstract of assessment and in person, and
not by deputy, shall subscribe the assessor's name, under oath, to the
following statement, which shall be a part of such abstract:
I, .............., the assessor of
.............. county, Colorado, do solemnly swear that in the assessment roll
of such county I have listed and valued all taxable property located therein
and that such property has been assessed for the current year in the manner
prescribed by law and that the foregoing abstract of assessment is a true and
correct compilation of each schedule.
...................
(b)
Upon completion by the assessor of the abstract of assessment, the chairman of
the board of county commissioners shall examine such abstract and shall sign
the following statement, which shall be a part of such abstract:
I, ................, chairman of
the ............. county board of county commissioners, certify that the county
board of equalization has concluded its hearings, pursuant to the provisions of
article 8 of this title, that I have examined the abstract of assessment, and
that all valuation changes ordered by the county board of equalization have
been incorporated therein.
...................
(2) The
assessor shall file, in an electronic or paper format, one copy of the abstract
of assessment with the administrator, and, appended thereto, the assessor shall
also file the aggregate valuation for assessment of all taxable property in the
county, each municipality, and each school district within the county, by
classes and subclasses, on a form prescribed by the administrator.
(3)
Along with the abstract of assessment, the assessor shall file with the
property tax administrator information relating to the valuation for assessment
for residential real property, including new construction, increased volume of
mineral and oil and gas production, and any other data determined by the
administrator as necessary to determine the valuation for assessment for such
property.
(4)
Repealed.
Source:
L. 64: R&RE,
p. 704, § 1. C.R.S. 1963: § 137-5-23. L. 67: p. 949, § 17. L.
76: Entire section amended, p. 773, § 1, effective April 30. L. 88:
(3) added, p. 1288, § 19, effective May 23. L. 89: (1) amended, p. 1457,
§ 11, effective June 7. L. 93: (1) and (2) amended, p. 1283, § 5,
effective June 6. L. 2000: (1)(a) amended, p. 1500, § 4, effective
August 2. L. 2024: (4) added, (HB 24-1179), ch. 2, p. 4, § 1, effective
February 15. L. 2025: (1)(a) amended, (HB 25-1324), ch. 445, p. 2559, §
2, effective June 4. L. 2026: (1)(a) and (2) amended, (SB 26-046), ch.
10, p. 48, § 13, effective August 12.
Editor's
note: (1) For
subsection (4) as added by HB 24-1179 in effect from February 15, 2024, to July
1, 2024, see chapter 2, Session Laws of Colorado 2024. (L. 2024, p. 4.)
(2) Subsection (4)(d) provided
for the repeal of subsection (4), effective July 1, 2024. (See L. 2024, p. 4.)
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Failure to subscribe to
assessment rolls does not invalidate assessment. This section, providing
that the assessment rolls shall be authenticated by the assessor attaching a
prescribed oath to the assessment book, does not mean that a failure to
subscribe the oath invalidates the assessment, or that a tax deed is void
because the assessment roll was not authenticated by the assessor as required
by this section. Duggan v. McCullough, 27 Colo. 43, 59 P. 743 (1899).
After assessment submitted,
assessor's duties become ministerial. After county assessor has completed
his assessment and submitted his assessment roll to the county board of
equalization, his quasi-judicial functions end, and his duties thereafter to be
performed are purely ministerial. Bd. of County Comm'rs v. Love, 172 Colo. 121,
470 P.2d 861 (1970).
39-5-124. Property tax administrator
to examine abstract.
(1)
When the abstract of assessment has been subscribed and sworn to by the
assessor and by the chairman of the board of county commissioners, the assessor
shall transmit, in electronic or paper format, one copy thereof to the
administrator.
(2)
Upon receipt of such abstract, the administrator shall examine the same without
delay and, if it is found correct as to form, shall certify such fact to the
assessor, and such certification shall be conclusive evidence of the fact,
time, and place of filing such abstract. If such abstract is found incorrect as
to form, the administrator shall return the same to the assessor for
correction.
Source:
L. 64: R&RE,
p. 705, § 1. C.R.S. 1963: § 137-5-24. L. 93: (1) amended, p.
1284, § 6, effective June 6. L. 2026: (1) amended, (SB 26-046), ch. 10,
p. 48, § 14, effective August 12.
39-5-125. Omission - correction of
errors.
(1)
Except as otherwise provided in subsection (3) of this section, whenever it is
discovered that any taxable property has been omitted from the assessment roll
of any year or series of years, the assessor shall immediately determine the
value of such omitted property and shall list the same on the assessment roll
of the year in which the discovery was made and shall notify the treasurer of
any unpaid taxes on such property for prior years.
(2)
Omissions and errors in the assessment roll, when it can be ascertained
therefrom what was intended, may be supplied or corrected by the assessor at
any time before the tax warrant is delivered to the treasurer or by the
treasurer at any time after the tax warrant has come into his hands.
(3) If
taxable personal property that has been omitted from the assessment roll of any
year or series of years is discovered due to a property owner or an agent of a
property owner who advertises for rent furnished residential real property
providing information to the assessor pursuant to section 39-5-108.5 (2), the
assessor shall not notify the treasurer of any unpaid taxes on the taxable
personal property for prior years and the property owner or agent shall not be
liable for any such unpaid taxes for prior years.
(4) If
omitted property is added by the assessor or the treasurer for a prior
assessment year, then a petition for abatement or refund may be filed at any
time after the taxes are levied and an amended tax bill has been generated, but
before two years after January 1 of the year following the year in which the
taxes are levied.
Source:
L. 64: R&RE,
p. 705, § 1. C.R.S. 1963: § 137-5-25. L. 2009: (1) amended and
(3) added, (HB 09-1110), ch. 162, p. 700, § 2, effective August 5. L. 2017:
(4) added, (HB 17-1049), ch. 148, p. 495, § 2, effective August 9.
ANNOTATION
I.
General Consideration.
II.
Property Omitted from Rolls.
III.
Errors in Rolls.
I. GENERAL CONSIDERATION.
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
This section expressly
authorizes assessor and treasurer to correct errors in the assessment roll
at any time, before or after the treasurer receives the tax warrant. Modular
Cmtys., Inc. v. McKnight, 191 Colo. 101, 550 P.2d 866 (1976); RTV, L.L.C. v.
Grandote Int'l Ltd., 937 P.2d 768 (Colo. App. 1996).
Under this section and §
39-10-101 (2)(a)(I), both the assessor and the treasurer may retroactively
correct errors that caused property to be omitted from the assessment roll
and tax list and warrant. Marsico Cap. Mgmt. v. Denver Bd. of County Comm'rs,
2013 COA 90, 342 P.3d 462.
Treasurer making correction
must exercise reason and sound judgment. Haley v. Elliott, 20 Colo. 379, 38
P. 771 (1894).
This section does not
obviate the necessity of notice required by § 39-5-122. Gale v. Statler, 47
Colo. 72, 105 P. 858 (1909).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
Applied in Haley v.
Elliot, 20 Colo. 379, 38 P. 771 (1894); Chase v. Boar of County Comm'rs, 37
Colo. 268, 86 P. 1011 (1906); City & County of Denver v. Pitcher, 54 Colo.
203, 129 P. 1015 (1913); San Luis Power & Water Co. v. Trujillo, 93 Colo.
385, 26 P.2d 537 (1933).
II. PROPERTY OMITTED FROM ROLLS.
As used in this section, the
word "omitted" means to have been left out or unmentioned.
Bachelor Gulch Operating v. Bd. of County Comm'rs, 2013 COA 46, 316 P.3d 43.
Assessor must account for
omitted taxes and arrearages. The assessor has power and it is his duty,
under this section, when it is discovered that certain special taxes upon
particular property have been omitted from the assessment book, to place the
same upon his book with all arrearages which should have been assessed in
former years, notwithstanding the property had been regularly listed and the
omission consisted only in failing to extend the special tax levy. Aggers v.
People ex rel. Town of Montclair, 20 Colo. 348, 38 P. 386 (1894).
List property omitted by
owner. In the event of a failure by the owner to list his property, it is
made the duty of the assessor to do so. Bd. of County Comm'rs v. Yingling, 14
Colo. App. 449, 60 P. 582 (1900).
Assessor has the authority
to assess taxes retroactively on property previously omitted from the
assessment rolls, including the "value of improvements" located on
land. Chew v. Bd. of Assmt. Appeals, 673 P.2d 1028 (Colo. App. 1983); RTV,
L.L.C. v. Grandote Int'l Ltd., 937 P.2d 768 (Colo. App. 1996).
This section and § 39-10-101
(2)(a) authorize retroactive assessments of additional property taxes only
against "omitted property", not "omitted value".
Section 39-10-107 authorizes retroactive assessments of additional property
taxes against "omitted value" on oil and gas leaseholds. Cabot
Petroleum Corp. v. Yuma County Bd. of Equaliz., 847 P.2d 152 (Colo. App. 1992),
rev'd on other grounds, 856 P.2d 844 (Colo. 1993); In Stitches, Inc. v. Denver
County Bd. of County Comm'rs, 62 P.3d 1080 (Colo. App. 2002); Jet Black, LLC v.
Routt County Bd. of County Comm'rs, 165 P.3d 744 (Colo. App. 2006); Kinder
Morgan v. Montezuma County Bd., 2015 COA 72, 399 P.3d 735, aff'd, 2017 CO 72,
396 P.3d 657.
Tenant improvements that
were not included in assessment rolls due to assessor error were "omitted
property" not merely "omitted value" and therefore could be
taxed retroactively. Marsico Cap. Mgmt. v. Denver Bd. of County Comm'rs, 2013
COA 90, 342 P.3d 462.
This section is inapplicable
to property that is subdivided during the course of a particular tax year,
because such property has not been "omitted". Such property is
deemed either to have existed as of the assessment date, in which case it was
appraised as part of the parent parcel, or to not have existed, in which case
it was not "omitted" because it was not a property that existed but
was not captured on assessment rolls. Bachelor Gulch Operating v. Bd. of County
Comm'rs, 2013 COA 46, 316 P.3d 43.
The value of previously
omitted common area parcels could be added on a proportional basis to ownership
parcels even though the ownership parcels had previously been assessed at a
lower value. Jet Black, LLC v. Routt County Bd. of County Comm'rs, 165 P.3d 744
(Colo. App. 2006).
III. ERRORS IN ROLLS.
Subsection (2) addresses
errors in the assessment roll, not errors in the notice of valuation. An
assessor, therefore, could not include a valuation that was corrected from the
notice of valuation in the assessment roll. Yen, LLC v. Jefferson County Bd. of
Comm'rs, 2021 COA 107, 498 P.3d 1140.
Dollar mark omitted before
valuation figures may be supplied. Where in the copy of an assessment roll
the dollar mark ($) was omitted before the valuation figures, it is one of
those omissions or informalities which the assessor or treasurer is authorized
to correct. Haley v. Elliott, 20 Colo. 379, 38 P. 771 (1894).
39-5-126. Wrongful return by assessor.
Whenever
any assessor willfully and knowingly omits any taxable property in his county
from the assessment roll, or willfully and knowingly values any taxable
property in his county contrary to the manner prescribed by law, and willfully
and knowingly subscribes and swears to an abstract of assessment reflecting
such omissions and containing such unlawful valuations, he is guilty of perjury
in the second degree and, upon conviction thereof, shall be punished according
to law.
Source:
L. 64: R&RE,
p. 705, § 1. C.R.S. 1963: § 137-5-26. L. 67: p. 950, § 18. L.
72: p. 570, § 52.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
39-5-127. Correction of assessments.
Whenever
the state board of equalization makes any change in the abstract of assessment
of any county or orders an increase or decrease in the valuation of any class
or subclass of property located therein, the assessor shall make the necessary
changes in the abstract of assessment of the next succeeding taxable year
required to carry out such order; except that, whenever the state board of
equalization changes the valuation of any class or subclass of property
pursuant to section 39-9-103 (7), the assessor shall make the necessary changes
in the abstract of assessment of the current taxable year required to carry out
such order.
Source:
L. 64: R&RE,
p. 705, § 1. C.R.S. 1963: § 137-5-27. L. 77: Entire section
amended, p. 1755, § 1, effective July 23. L. 83: Entire section amended,
p. 2092, § 1, effective September 23.
ANNOTATION
Applied in Lamm v.
Barber, 192 Colo. 511, 565 P.2d 538 (1977).
39-5-128. Certification of valuation
for assessment.
(1) (a)
No later than August 25 of each year, the assessor shall certify to the
department of education, to the clerk of each town and city, to the secretary
of each school district, and to the secretary of each special district within
the assessor's county the total valuation for assessment of all taxable
property located within the territorial limits of each such town, city, school
district, or special district and shall notify each such clerk, secretary, and
board to officially certify the levy of such town, city, school district, or
special district to the board of county commissioners no later than December
15. The assessor shall also certify to the secretary of each school district
the actual value of the taxable property in the district.
(b)
Repealed.
(1.5)
Along with the certification required by subsection (1) of this section, the
assessor shall also provide:
(a) The
aggregate value of exempt business personal property specified in section
39-3-119.5 (3)(a)(I) for the property tax year commencing on January 1, 2021,
within the territorial limits of each town, city, school district, or special
district; and
(b) The
amount calculated under section 39-3-119.5 (3)(c)(I) for the estimate of the
aggregate value of exempt business personal property for each property tax year
beginning with the property tax year commencing on January 1, 2022, within the
territorial limits of each town, city, school district, or special district.
(2)
Repealed.
(3) (a)
If the valuation for assessment for all or part of any such political
subdivision has been divided for an urban renewal area, pursuant to section
31-25-107 (9)(a), any certification under this section must be based upon that
portion of the valuation for assessment under section 31-25-107 (9)(a)(I) so
long as the division remains in effect.
(b) If
the valuation for assessment for all or part of any such political subdivision
has been divided for a county revitalization area, pursuant to section
30-31-109 (13)(a), any certification under this section must be based upon that
portion of the valuation for assessment under section 30-31-109 (13)(a)(I), so
long as the division remains in effect.
Source:
L. 64: R&RE,
p. 705, § 1. C.R.S. 1963: § 137-5-28. L. 67: p. 950, § 19. L.
75: (3) added, p. 1278, § 6, effective July 16. L. 76: (1) amended,
p. 687, § 5, effective July 1. L. 86: (1) amended, p. 1030, § 15,
effective January 1, 1987. L. 87: (1) amended and (2) repealed, p. 1411,
§§ 14, 15, effective April 22. L. 88: (1) amended, p. 1288, § 20,
effective May 23. L. 89: (1) amended, p. 1457, § 12, effective June 7. L.
93: (1) amended, p. 1689, § 6, effective June 6. L. 94: (1) amended,
p. 807, § 10, effective April 27. L. 96: (1) amended, p.115, § 2,
effective March 25. L. 2021: (1.5) added, (HB 21-1312), ch. 299, p.
1795, § 7, effective July 1. L. 2023, 1st Ex. Sess.: (1) amended, (SB
23B-001), ch. 1, p. 11, § 11, effective November 20. L. 2024: (3)
amended, (HB 24-1172), ch. 387, p. 2682, § 17, effective August 7.
Editor's
note: Subsection
(1)(b)(II) provided for the repeal of subsection (1)(b), effective July 1,
2025. (See L. 2023, 1st Ex. Sess., p. 11.)
Cross
references: For
the legislative declaration in HB 21-1312, see section 1 of chapter 299,
Session Laws of Colorado 2021.
39-5-129. Delivery of tax warrant -
public inspection.
(1) As
soon as practicable after the requisite taxes for the year have been levied but
in no event later than January 10 of each year, the assessor shall deliver the
tax warrant under the hand and official seal of the assessor to the treasurer,
which shall be made readily available to the general public during the
collection year in a convenient location in the courthouse. The assessor shall
retain one or more true copies thereof, which shall be made readily available
to the general public during the collection year in a convenient location in
the courthouse. Such tax warrant shall set forth the assessment roll, reciting
the persons in whose names taxable property in the county has been listed, the
class of such taxable property and the valuation for assessment thereof, the
several taxes levied against such valuation, and the amount of such taxes
extended against each separate valuation. At the end of the warrant, the
aggregate of all taxes levied shall be totaled, balanced, and prorated to the
several funds of each levying authority, and the treasurer shall be commanded
to collect all such taxes.
(2)
Repealed.
Source:
L. 64: R&RE,
p. 706, § 1. C.R.S. 1963: § 137-5-29. L. 67: p. 950, § 20. L.
88: Entire section amended, p. 1097, § 2, effective April 6. L. 89:
Entire section amended, p. 1457, § 13, effective June 7. L. 2023, 1st Ex.
Sess.: Entire section amended, (SB 23B-001), ch. 1, p. 11, § 12, effective
November 20.
Editor's
note: Subsection
(2)(b) provided for the repeal of subsection (2), effective July 1, 2025. (See
L. 2023, 1st Ex. Sess., p. 11.)
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
This section is directory
and not mandatory. To hold that all county tax collections are void because
an assessor fails to deliver the tax list and warrant on the appointed day
would in large measure emasculate the tax structure. People ex rel. Dunbar v.
Hively, 140 Colo. 265, 344 P.2d 443 (1959).
Tax collector must have some
authority or warrant for collection. All the authorities agree that the
collector of taxes, by whatever title called, must have some authority or
warrant for their collection; or, in lieu thereof, his acts are trespasses.
City of Highlands v. Johnson, 24 Colo. 371, 51 P. 1004 (1897).
When taxes due and payable.
It was seemingly the intention of the general assembly to make all taxes due
and payable from the time the tax list and warrant were delivered to the
treasurer, and to fix the ultimate date of such delivery as of the first of
January after the levy; from this date the treasurer was commanded to collect
said taxes. Cristler v. Beardsley, 25 Colo. App. 369, 138 P. 68 (1914).
Applied in Haley v.
Elliot, 20 Colo. 379, 38 P. 771 (1894); Moore v. Gas Sec. Co., 278 F. 111 (8th
Cir. 1921).
39-5-130. Informality not to
invalidate.
No
informality in complying with the requirements of section 39-5-129 shall render
any proceedings for the collection of taxes invalid. The assessor shall take
the receipt of the treasurer for the tax warrant, and such warrant shall be
full and complete authority for the treasurer to collect all taxes therein set
forth.
Source:
L. 64: R&RE,
p. 706, § 1. C.R.S. 1963: § 137-5-30.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Technical objections,
without merit, shall not interfere with collection of the public revenue,
as the assessor or treasurer may correct any defect in form on the assessment
list or tax roll. Haley v. Elliott, 20 Colo. 379, 38 P. 771 (1894).
Defective description of
realty does not affect tax on personalty. Where, in an assessment roll,
there is a defective description of the realty, the validity of the tax against
the personalty is not necessarily affected. Haley v. Elliott, 20 Colo. 379, 38
P. 771 (1894).
This section does not
obviate necessity of notice required by § 39-5-122. Gale v. Statler, 47
Colo. 72, 105 P. 858 (1909).
39-5-131. Certification and valuation
of pollution control property. (Repealed)
Source:
L. 78: Entire
section added, p. 468, § 3, effective July 1. L. 79: (1), (3), (4), and
(8) amended and (9) added, pp. 1455, 1456, §§ 2, 4, effective June 22. L.
81: (9) R&RE, p. 1872, § 6, effective June 29. L. 88: Entire
section repealed, p. 1275, § 14, effective May 29.
39-5-132. Assessment and taxation of
new construction.
(1) The
general assembly hereby finds and declares that it is a matter of statewide
concern that revenues from property taxes on newly constructed buildings may
need to be put to special use in order to accommodate the capital needs
resulting from such new construction, especially to accommodate the capital
needs of the public schools in this state. The general assembly further
declares that it is essential that such revenue be available as soon as
possible after the time such new construction is put to use. The general
assembly further finds and declares that the board of county commissioners is
the appropriate governmental unit to determine the extent of the growth within
the county and the finding of severe growth impact shall be at the sole
discretion of the board.
(2) (a)
(I) (A) If the board of county commissioners determines that a county is
becoming severely impacted by residential growth, the board of county
commissioners shall make a finding of severe growth impact based upon the rate
of increase in the county of the number of residential units being constructed
within the county and an increase in pupil enrollment in school districts
within the county such that at least one school district in the county meets
the growth criteria described in sub-subparagraph (E) of this subparagraph (I),
and other factors which indicate patterns of growth and growth impact, and
shall, on or before January 1, resolve to implement the assessment and levy
procedures required under this section. When a board of county commissioners
makes such resolution, the provisions of this section shall apply countywide
notwithstanding any law to the contrary. The board of county commissioners
shall not make a finding of severe growth impact unless the number of
residential units in the county will increase by over two percent during the
county's current fiscal year. The board of county commissioners may negotiate
with taxing authorities in the county to provide the costs of implementing the
assessment and levy procedures required under this section. Notwithstanding any
other provision of law to the contrary, any such taxing authority is hereby
authorized to use moneys from its general fund to provide the costs specified
in this subparagraph (I) and to deposit any moneys received as reimbursement
pursuant to subsection (4) of this section into its general fund.
(B)
Whenever construction occurs on any new taxable building within the boundaries
of a county after January 1 of a given year, the assessor shall value the
building on July 1 of that year, and the assessor shall add the valuation for
assessment thereof to the abstract of assessment for such tax year, except that
portion of the valuation for assessment as is excluded by paragraph (b) of this
subsection (2). If the building is complete on July 1, such valuation for
assessment shall be prorated at the same ratio as the number of months it is
completed bears to the full year. Otherwise, the valuation added to the
abstract shall be one-half of the difference between the valuation for
assessment on January 1 and the valuation for assessment on July 1. For the
purposes of this section, the total valuation for assessment of all newly
constructed taxable buildings in a county as calculated pursuant to this
subsection (2) shall be known as the "growth valuation for
assessment" for such county. For purposes of this section, completion
shall be considered to be when a certificate of occupancy is issued, when the
building is ready for use, or after the final inspection, at the sole
discretion of the county assessor. As used in this section,
"building" means a roofed and walled real property improvement, and
any uncertainty concerning whether or not a particular real property
improvement is a building within the meaning of this definition shall be
resolved by the property tax administrator.
(C) The
assessor shall give written notification of the valuation of such newly
constructed taxable building to the taxpayer. The notice shall, at a minimum,
set forth the valuation on the assessment date, the prorated valuation of the
newly constructed taxable building, and the total valuation for the property
tax year. The notice shall also advise the taxpayer that he may protest and
appeal the valuation of the newly constructed taxable building at the same time
and in the same manner, pursuant to section 39-5-122, as the total valuation of
his property for the next property tax year may be appealed. If the taxpayer is
successful in the protest or appeal, the amount in excess shall be refunded
directly to the taxpayer by the county treasurer.
(D) In
order to promote the most efficient administration of this section, each county
or municipality shall ensure that any office or agency that received
information relative to the state of completion of new taxable buildings shall
promptly transmit such information to the county assessor. After January 1,
1987, the property tax administrator shall transmit to the assessor in August
of each year both the assessed value of any newly constructed buildings owned
by public utility companies and their state of completion on July 1 as well as
their value on the previous January 1.
(E) The
growth criteria for school districts for purposes of sub-subparagraph (A) of
this subparagraph (I) shall be whether the commissioner of education or the
commissioner's designee certifies that the pupil enrollment of the district for
the past three years, as determined on October 1 of each year in accordance
with former section 22-53-103 (7) or section 22-54-103 (10), has increased by
three percent or more over each preceding year for those districts with pupil
enrollments of at least one thousand pupils or by twenty-five or more pupils
each year for those districts with pupil enrollments of less than one thousand
pupils.
(II)
All general property taxes which are levied on all other taxable real and
personal property within a county in the tax year during which such
construction occurs shall also be levied against the growth valuation for
assessment of such county for collection the following year. Revenues raised
from taxes levied on such growth valuation for assessment shall be credited to
the county's capital growth fund, which each board of county commissioners
shall establish, for use and distribution pursuant to subsection (4) of this
section. The actual value and valuation for assessment of such newly
constructed taxable building for subsequent years shall be the actual value and
valuation for assessment as determined by the provisions of law other than this
section, and tax revenues attributable thereto shall be distributed as provided
by law without regard to this section.
(b) The
provisions of this section shall not apply to that portion of the valuation for
assessment of a newly constructed taxable building and the land underlying such
building which is contained in the abstract of assessment on the assessment
date.
(c) If
the newly constructed taxable building is a residential unit, the assessment
percentage to be applied to the land underlying such building shall be based on
a residential classification of the land. If the land underlying such building
was classified as vacant land, the classification shall be changed to
residential on the abstract of assessment for the tax year in which the
assessor added the valuation of the newly taxable residential building to the
abstract for assessment.
(3) By
August 25 of each year, the assessor shall notify the board of county
commissioners of the amount of the growth valuation for assessment of the
county for that tax year, the percentage that such growth valuation for
assessment bears to the total valuation for assessment of the county for such
tax year, the portion of such growth valuation for assessment that is
attributable to newly constructed taxable buildings within the boundaries of
each taxing authority in the county, and the percentage that such portion bears
to the total valuation for assessment of each taxing authority in which such
newly constructed taxable buildings are located.
(4)
Upon collection of taxes on the growth valuation for assessment in the first
year, the board of county commissioners shall reimburse the county general fund
and the taxing authorities which contributed to the costs of implementing the
procedures specified pursuant to this section and shall also pay into the
county general fund the projected budgeted costs of implementation in this
second year. The remaining moneys shall be distributed to the taxing
authorities as next specified in this subsection (4). In the second and
subsequent years that procedures are implemented pursuant to this section, the
board of county commissioners, after depositing into the county general fund
the projected budgeted costs of administering this section in the current year,
shall distribute the moneys in the county's capital growth fund to the taxing
authorities where the newly constructed taxable building is actually located in
the same manner as all other property tax revenues collected on similar taxable
buildings are distributed; except that such moneys shall be used by the taxing
authority for capital expenditures only and not for operating expenses. Every
taxing authority receiving funds pursuant to this subsection (4) shall make
capital expenditures so that they benefit the taxing authority within the
county levying on the growth valuation for assessment pursuant to this section,
unless such governing body finds a compelling reason for making expenditures so
that they benefit the taxing authority within another county.
(5)
Money received by a school district pursuant to this section must be deposited
in the district's capital reserve fund and must not be included in calculating
the amount of revenue that a district is entitled to receive from the property
tax levy for the general fund of the district under the "Public School
Finance Act of 2025", article 54 of title 22.
(6)
When the board of county commissioners determines that a county is no longer
being severely impacted by residential growth, the board of county
commissioners shall so find and shall, on or before January 1, resolve to end
implementation of the assessment and levy procedures required under this
section.
(7)
Nothing in this section affects tax increment financing implemented pursuant to
sections 31-25-107 (9), 30-31-109 (13), and 31-25-807 (3), nor the distribution
of specific ownership taxes pursuant to section 42-3-107 (24).
Source:
L. 85: Entire
section added, p. 1223, § 1, effective July 1. L. 88: (5) amended, p.
824, § 37, effective May 24. L. 90: (2)(a)(I)(C), (2)(a)(I)(D), and (3)
amended, p. 1693, § 10, effective June 9. L. 94: (2)(a)(I)(A) and (5)
amended and (2)(a)(I)(E) added, pp. 807, 825, §§ 11, 55, effective April 27;
(7) amended, p. 2568, § 87, effective January 1, 1995. L. 96: (3)
amended, p.17, § 3, effective February 22. L. 2002: (2)(c) added, p.
843, § 3, effective August 7. L. 2005: (7) amended, p. 1183, § 35,
effective August 8. L. 2024: (5) amended, (HB 24-1448), ch. 236, p.
1538, § 64, effective May 23; (7) amended, (HB 24-1172), ch. 387, p. 2683, §
18, effective August 7.
39-5-133. 2011 modification of
statutory definition of "agricultural land" - TABOR election -
adjustment of district mill levy.
(1) (a)
The requirements of paragraph (b) of this subsection (1) shall only apply:
(I) To
a district, as defined in section 20 (2)(b) of article X of the state
constitution, that has not obtained voter approval to retain and spend revenues
in excess of the fiscal year spending and property tax revenue limits imposed
on the district by section 20 (7)(b) and (7)(c) of article X of the state
constitution sufficient to allow the retention of all additional property tax
revenues; and
(II)
Where the district has additionally determined, on the basis of the best
available information, that implementation of the modification of the
definition of "agricultural land" required by House Bill 11-1146,
enacted in 2011, will cause a net property tax revenue gain to the district
sufficient to cause the district to exceed such limits.
(b) In
the case of a district that meets the requirements specified in paragraph (a)
of this subsection (1), the district may place before the voters of the
district at any election at which such ballot issue may be placed on the ballot
the question of whether the district may retain and spend revenues in excess of
the limits imposed on the district by section 20 (7)(b) and (7)(c) of article X
of the state constitution sufficient to allow the retention of the net property
tax revenue gain to the district resulting from the implementation of the
modification of the definition of "agricultural land" required by
House Bill 11-1146, enacted in 2011.
(c) If
a majority of the voters of the district fail to approve the ballot issue
specified in paragraph (b) of this subsection (1), or if no ballot issue has
been submitted to the voters, the district shall adjust the number of mills
levied by the district to eliminate any net property tax revenue gain to the
district resulting from the modification of the definition of
"agricultural land" required by House Bill 11-1146, enacted in 2011.
(2)
Notwithstanding any other provision of law, the provisions of subsection (1) of
this section shall not apply to any district, regardless of whether or not it
satisfies the requirements of paragraph (a) of subsection (1) of this section,
that has determined, on the basis of the best available information, that
implementation of the modification of the definition of "agricultural
land" required by House Bill 11-1146, enacted in 2011, will not cause a
net property tax revenue gain to the district.
Source:
L. 2011: Entire
section added, (HB 11-1146), ch. 166, p. 572, § 2, effective January 1, 2012.
39-5-134. Controlled environment
agricultural facility - valuation - affidavit - definition - repeal.
(1) As
used in this section, "controlled environment agricultural facility"
or "CEA facility" has the same meaning as specified in section
39-1-102 (3.3).
(2) A
CEA facility is valued for assessment purposes as all other agricultural
property using the cost, market, and income approaches to value.
(3) If
the sole use of the CEA facility is not the growing of crops for human or
livestock consumption, then the property is classified and valued for
assessment purposes based on actual use.
(4) As
part of the personal declaration the owner of a CEA facility signs and returns
to the county assessor pursuant to sections 39-5-107 and 39-5-108, the owner
shall include an affidavit executed by the owner in which the owner affirms
that the CEA facility meets the requirements of section 39-1-102 (3.3),
including the requirements that the facility optimizes hydroponics and that the
sole purpose of the CEA facility is to obtain a monetary profit from the
wholesale of plant-based food for human or livestock consumption. If the crop
grown in the CEA facility is hemp, the owner must also include a copy of a
license to verify to the assessor that the crop is not marijuana.
(5)
Notwithstanding any other provision of law, a CEA facility shall not violate
the terms and conditions of any applicable water court decree issued pursuant
to article 92 of title 37 and shall not materially injure water rights or
conditional water rights granted under article 92 of title 37.
(6)
This section is repealed, effective July 1, 2029.
Source:
L. 2022: Entire
section added, (HB 22-1301), ch. 198, p. 1322, § 3, effective August 10.
PART
2
MOBILE
HOMES
Editor's
note: This part 2
was repealed in 1975 and was subsequently recreated and reenacted in 1977,
resulting in the addition, relocation, and elimination of sections as well as
subject matter. For amendments to this part 2 prior to 1975, consult the
Colorado statutory research explanatory note and the table itemizing the
replacement volumes and supplements to the original volume of C.R.S. 1973
beginning on page vii in the front of this volume.
39-5-201. Legislative declaration.
(1) The
general assembly hereby finds and declares that the present method of taxation
of mobile homes, the specific ownership tax, is inappropriate; that mobile
homes are more properly taxed by a change from such method to an ad valorem
method of taxation similar to the method of taxation of conventional housing.
(2)
Uniform treatment of mobile homes is hereby declared to be an exclusive matter
of statewide concern. No home rule city, city, county, or other local
government shall impose a license or any other special fees on the ownership or
occupancy of mobile homes that is not similarly imposed on conventional homes.
(3)
Repealed.
Source:
L. 77: Entire part
RC&RE, p. 1740, § 3, effective January 1, 1978. L. 78: (3) added, p.
478, § 1, effective March 10. L. 79: (1) amended, p. 1640, § 51,
effective July 19. L. 83: (3) repealed, p. 1485, § 11, effective April
22.
39-5-202. Taxation of mobile homes -
effective date.
Commencing
January 1, 1978, mobile homes shall be subject to ad valorem taxation under the
provisions of articles 1 to 9 of this title as if they were real property but
shall be subject to the provisions of article 10 of this title concerning the
collection of taxes as if they were personal property.
Source:
L. 77: Entire part
RC&RE, p. 1741, § 3, effective January 1, 1978.
39-5-203. Mobile homes - determination
of value.
(1) For
the property tax year beginning January 1, 1983, and for each property tax year
thereafter, the actual value of a mobile home shall be determined by the
assessor in accordance with the provisions of sections 39-1-103 (5) and
39-1-104 (10.2) for the determination of the actual value of real property.
(2)
Repealed.
(3) (a)
The valuation for assessment of each mobile home shall be computed on the same
basis as the valuation for assessment of all taxable property; except that
mobile homes shall be exempt from property taxation while located on sales
display lots of mobile home dealers and listed as inventories of merchandise by
such mobile home dealers. It is the duty of the seller of a mobile home to
provide to the buyer a tax certificate and an itemized list of household
furnishings, as defined in section 39-3-102 and which are included in the
selling price of the mobile home, at the time of sale.
(b) A
person who knowingly fails to provide an itemized list of household furnishings
as required by this subsection (3) commits a civil infraction; except that,
upon conviction of a second or subsequent such offense, such person commits a
petty offense and shall be punished as provided in section 18-1.3-503.
Source:
L. 77: Entire part
RC&RE, p. 1741, § 3, effective January 1, 1978. L. 78: (3) amended,
p. 478, § 2, effective March 10. L. 80: (2)(b) and (3) amended, p. 498,
§ 3, effective July 1. L. 82: (2)(a) amended, p. 557, § 1, effective
January 1, 1983; (1) amended and (2) repealed, pp. 555, 556, §§ 2, 3, effective
January 1, 1984. L. 83: (1) R&RE and (2) repealed, pp. 1498, 1499,
§§ 2, 3, effective April 12; (3) amended, p. 1484, § 9, effective April 22. L.
87: (1) amended, p. 1388, § 8, effective January 1, 1991. L. 88: (1)
amended, p. 1274, § 9, effective January 1, 1993. L. 89: (3)(a) amended,
p. 1484, § 9, effective April 23. L. 94: (3) amended, p. 707, § 15,
effective April 19. L. 95: (1) amended, p. 9, § 4, effective March 9. L.
2002: (3)(b) amended, p. 1555, § 345, effective October 1. L. 2021:
(3)(b) amended, (SB 21-271), ch. 462, p. 3294, § 689, effective March 1, 2022.
Cross
references: (1)
For the power of county commissioners to levy taxes, see § 39-1-111; for
household furnishings being exempt from taxation, see § 39-3-102.
(2) For the legislative
declaration contained in the 2002 act amending subsection (3)(b), see section 1
of chapter 318, Session Laws of Colorado 2002.
39-5-204. Notification concerning
mobile homes in a county for part of a year.
(1) (a)
Any person who brings a mobile home into a county after the assessment date of
any year shall immediately notify the assessor of the location of the mobile
home within the county.
(b)
Repealed.
(c) For
property tax years commencing on or after January 1, 1999:
(I) The
assessor shall list and value a mobile home brought into a county from another
county in this state after the assessment date for any year as of the
assessment date of the following year.
(II)
The assessor shall list and value a mobile home brought into a county from
outside this state after the assessment date at such proportion of its value
for the full calendar year as the number of calendar months remaining in such
year bears to twelve; but, if the mobile home is brought into the county from
outside this state before the sixteenth day of any calendar month, such month
shall be considered as a full calendar month, and, if the mobile home is
brought into the county from outside this state on or after the sixteenth day
of any calendar month, such month shall be disregarded.
Source:
L. 77: Entire part
RC&RE, p. 1741, § 3, effective January 1, 1978. L. 98: Entire
section amended p. 439, § 1, effective August 5.
Editor's
note: Subsection
(1)(b)(II) provided for the repeal of subsection (1)(b), effective January 1,
2000. (See L. 98, p. 439.)
39-5-205. Relocation of a mobile home
- collection of taxes.
(1) Any
person who intends to remove his or her mobile home from a county or from one
location in a county to a new location in the same county shall notify the
treasurer of this fact, and all property taxes levied or assessed on such
mobile home shall thereupon become due and payable if the mobile home is to be
removed from the county. Upon the request of the treasurer, the assessor shall
certify to such person the valuation for assessment of the mobile home for the
current year.
(2)
Repealed.
(3) For
property tax years commencing on or after January 1, 1999:
(a) If
a mobile home located in a county on the assessment date is to be removed from
the county to another county in this state before the next following assessment
date, all property taxes levied or assessed on such mobile home shall, upon the
mobile home owner providing notice of such removal to the treasurer pursuant to
subsection (1) of this section, become due and payable for the current property
tax year without proration.
(b) If
a mobile home located in a county on the assessment date is to be removed from
this state before the next following assessment date, all property taxes levied
or assessed on such mobile home shall, upon the mobile home owner providing
notice of such removal to the treasurer pursuant to subsection (1) of this
section, become due and payable. The value to be placed on the property by the
assessor pursuant to this paragraph (b) shall be such proportion of its value
for the full calendar year as the number of calendar months in such year the
mobile home was located in the original location bears to twelve; but, if the
mobile home is to be removed from its original location before the sixteenth
day of any calendar month, such month shall be disregarded, and, if the mobile
home is to be removed from its original location on or after the sixteenth day
of any calendar month, such month shall be considered as a full calendar month.
(4) If
the levy for the current year has not then been fixed and made, the levy for
the previous year shall be used by the treasurer to determine the amount of
taxes due pursuant to this section. At such time as the levy for the current
year has been fixed and made, the amount of any taxes collected on the property
in excess of the amount correctly due and payable shall be refunded by the
treasurer to the owner of the property forthwith; but, in all cases where the
amount of taxes so collected is less than the amount correctly due and payable,
the amount uncollected shall be considered an erroneous assessment and shall be
reported with other erroneous assessments in the manner prescribed by law.
Source:
L. 77: Entire part
RC&RE, p. 1741, § 3, effective January 1, 1978. L. 91: Entire
section amended, p. 1697, § 7, effective July 1. L. 98: Entire section
amended, p. 440, § 2, effective August 5.
Editor's
note: Subsection
(2)(b) provided for the repeal of subsection (2), effective January 1, 2000.
(See L. 98, p. 440.)
39-5-206. Payments to counties,
cities, towns, and special districts in lieu of taxes for calendar year 1978.
(Repealed)
Source:
L. 77: Entire part
RC&RE, p. 1741, § 3, effective January 1, 1978. L. 79: Entire
section repealed, p. 1641, § 52, effective July 19.
ARTICLE
6
Valuation
of Mines
39-6-101. Definitions.
39-6-102. Abstract and map of mining claims.
(Repealed)
39-6-103. Listing of mining claims and mines.
39-6-104. Classification of mines.
39-6-105. Producing mines defined.
39-6-106. Valuation for assessment of
producing mines.
39-6-107. Valuation of improvements - machinery.
39-6-108. Failure to file statement.
39-6-109. Assessor to examine books -
records.
39-6-110. False statements - penalty.
39-6-111. Valuation of mines other than
producing mines.
39-6-111.5. Calendar for notice of valuation
and appeals for mines.
39-6-112. Valuation of tunnels.
39-6-113. Mine in more than one county.
39-6-114. Mines and tunnels in more than one
subdivision of a county.
39-6-115. Collection.
39-6-116. Nonproducing unpatented mining
claims - definitions.
39-6-117. County boards of equalization -
authority.
39-6-101. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Mine" means one or more mining claims or acres of other land,
including all excavations therein from which ores, metals, or mineral
substances of every kind are removed, except drilled wells producing sulfur and
oil, gas, and other liquid or gaseous hydrocarbons, and all mining improvements
within such excavations, together with all rights and privileges thereunto
appertaining.
(2)
"Mining claims" means lode, placer, millsite, and tunnelsite claims,
whether entered for patent, patented, or unpatented, regardless of size or
shape.
(3)
"Ore" includes, without limitation, metallic and nonmetallic mineral
substances of every kind, except those specifically excluded under section
39-6-104.
(4)
"Other land" means any parcel of real property which is not a mining
claim.
Source:
L. 65: R&RE,
p. 1101, § 1. C.R.S. 1963: § 137-6-1. L. 85: (4) added, p. 1211,
§ 5, effective May 9.
39-6-102. Abstract and map of mining
claims. (Repealed)
Source:
L. 65: R&RE,
p. 1101, § 1. C.R.S. 1963: § 137-6-1. L. 93: Entire section
repealed, p. 440, § 7, effective July 1.
39-6-103. Listing of mining claims and
mines.
(1) The
assessor shall list all mining claims and mines located within his county on
the assessment date, including for each claim the name of the lode, placer,
millsite, or tunnelsite, the United States mineral survey number, if any, the
name of the mining district in which such claim is located, and the number of
acres contained in such claim. If a claim is not patented, the numbers of the
book and page at which the location of such claim is recorded in the county
records shall be used in place of the United States mineral survey number. If
two or more mining claims are included in one patent with one United States
survey number, the assessor shall list together such mining claims with the one
survey number and the total number of acres contained therein. In listing
mining claims, abbreviations of words and figures may be used. If other land is
part of such mine, then the numbers of the book and page at which the
conveyance deed is recorded on the legal description of such other land shall
be used in place of the United States mineral survey number.
(2)
Whenever, to the knowledge of the assessor, contiguous mining claims are worked
or operated through or by means of the same shafts, tunnels, or other openings,
they shall be listed as one unit; and whenever, to the knowledge of the
assessor, contiguous placer claims are worked or operated by means of the same
ditch or other works, they shall be listed as one unit, including such ditch or
other works; and whenever, to the knowledge of the assessor, contiguous other
land is used in the same manner as the claims referred to in this subsection
(2), it shall also be listed as one unit.
(3) The
mining property of a mine shall include mining claims and all other lands and
interests therein, whether owned by federal, state, or lesser governmental
subdivisions or otherwise and whether owned in fee or held by discovery and
location or under easement, lease, license, or other arrangement with the owner
thereof, unless otherwise provided for in this article.
Source:
L. 65: R&RE,
p. 1102, § 1. C.R.S. 1963: § 137-6-2. L. 85: (1) and (2) amended,
p. 1211, § 6, effective May 9.
39-6-104. Classification of mines.
All mines,
except mines worked or operated primarily for coal, asphaltum, rock, limestone,
dolomite, or other stone products, sand, gravel, clay, or earths, shall, for
the purpose of valuation for assessment, be divided into two classes: Producing
and nonproducing.
Source:
L. 65: R&RE,
p. 1102, § 1. C.R.S. 1963: § 137-6-3.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Classification of property
for taxation permissible. So long as classification is based upon the
nature of property justifying it, there is nothing to forbid legislative
classification for the purposes of taxation or to prevent the fixing of
valuation of different classes by different methods, provided that, by the
method prescribed for a particular class of property, the burden of taxation is
uniformly imposed upon that class, is just and equitable, and does not exempt
it from bearing its fair proportion of the burden of taxation, as compared with
other classes of property. In re House Bill No. 270, 9 Colo. 635, 21 P. 476
(1886); Foster v. Hart Consol. Mining Co., 52 Colo. 459, 122 P. 48 (1912).
39-6-105. Producing mines defined.
All mines
whose gross proceeds during the preceding calendar year have exceeded the
amount of five thousand dollars shall be classified as producing mines, and all
others shall be classified as nonproducing mines. Mines shall be classified in
the manner provided for in this article regardless of the processing method,
the ultimate use, or the consumption of the ores or minerals for which they are
primarily worked or operated.
Source:
L. 65: R&RE,
p. 1102, § 1. C.R.S. 1963: § 137-6-4.
39-6-106. Valuation for assessment of
producing mines.
(1)
Every person owning or operating any mine classified as a producing mine shall,
no later than April 15 of each year, prepare, sign under the penalty of perjury
in the second degree, and file with the assessor of the county wherein such
mine is located a statement showing:
(a) The
name of such mine and a list of mining claims and any other lands comprising
the mining property of such mine, together with the total number of acres
contained in each claim or parcel so listed;
(b) The
name of the owner thereof, together with the name of the operator thereof, and
the address of each;
(c) The
total number of acres contained in such mine and, if such mine is located in
more than one county, the total number of acres contained in such mine in each
county;
(d) The
number of tons of ore extracted therefrom during the calendar year immediately
preceding and, if the value of the products derived from the ore is used in
determining gross value, the number of tons, pounds, or ounces of products
derived from the ore;
(e) The
gross value from production of the ore extracted during said calendar year,
which means and includes the amount for which ore or the first salable products
derived therefrom were or could be sold by the owner or operator of a mine, as
determined using actual gross selling prices;
(f) The
costs of extracting such ore, excluding the compensation of any officer or
agents not actively and continuously engaged in or about the mine;
(g) The
costs of treatment, reduction, transportation, and sale of such ore or the
first salable products derived therefrom;
(h) The
gross proceeds from production of such ore, which means and includes the value
of the ore immediately after extraction, which value may be determined by
deducting from gross value all costs of treatment, reduction, transportation,
and sale of such ore or the first salable products derived therefrom;
(i) The
net proceeds from production of such ore, which means and includes the amount
determined by deducting from the gross proceeds all costs of extracting such
ore.
(1.4)
(a) The owner or operator of a producing mine may request permission to
state an average figure for the items required by paragraphs (d) to (i) of
subsection (1) of this section based on any three-year, five-year, or ten-year
period immediately preceding January 1 of the year in which the statement must
be filed. The same reporting method shall be used for all annual statements
filed in a single year pertaining to a particular mine.
(b) (I)
The owner or operator may make an initial request pursuant to this subsection
(1.4) by filing the request with the board of county commissioners of each
county in which the mine is located at least forty-five days prior to the
reporting date specified in the introductory portion to subsection (1) of this
section and attaching a copy of the request to the annual statement filed
pursuant to subsection (1) of this section with the county assessor of each
county in which the mine is located.
(II)
The owner or operator may make subsequent changes in the reporting method
pursuant to this subsection (1.4) by filing a request for a change in the
reporting method with the board of county commissioners and the county assessor
of every county in which the mine is located at least forty-five days prior to
the reporting date specified in the introductory portion to subsection (1) of
this section.
(III)
The board of county commissioners of each county which receives a request
pursuant to this subsection (1.4) shall approve or deny the request at least
thirty days prior to the reporting date specified in the introductory portion
to subsection (1) of this section. Failure of a board of county commissioners
to approve or deny the request within the thirty days shall be deemed an
approval of the request.
(c)
Once an owner or operator has made the initial election allowed by this
subsection (1.4), the owner or operator shall file all subsequent annual
statements pursuant to subsection (1) of this section using the same reporting
method. The owner or operator shall not alter the reporting method until the
board of county commissioners for every county in which the mine is located
authorizes the use of the alternate method.
(d) The
fact that authorization to alter the reporting method has not been received
from all or any of the boards of county commissioners for the counties in which
the mine is located shall not relieve the owner or operator from the obligation
to file the annual statement pursuant to subsection (1) of this section with
all counties in which the mine is located.
(1.7)
As used in subsection (1) of this section, unless the context otherwise
requires:
(a) (I)
"Costs" means those costs directly attributable to the operation of
the producing mine and to the treatment, reduction, transportation, or sale of
the ore and includes, but is not limited to, allocation of:
(A) The
costs of capital assets, which only include those expenditures listed on the
fixed asset records of the mine;
(B)
Preproduction development costs amortized over the life of the mine; and
(C)
Off-site costs directly attributable to the operation of the producing mine or
to the treatment, reduction, transportation, or sale of the ore; however, in no
event shall off-site costs include compensation of any officer or agent not
actively and continuously engaged in or about the mine.
(II)
Allocation of the costs of capital assets pursuant to this paragraph (a) shall
be done in accordance with generally accepted accounting principles. No change
in the allocation method may be made without the prior approval of the county
boards of equalization in all counties in which the mine is located.
(b)
"Costs" does not include:
(I) Any
amounts designated as profit or margin which are attributable to any part of
the treatment, reduction, transportation, or sale of the ore; or
(II)
Any amounts which have been or could have been deducted previously as part of
the valuation of the producing mine pursuant to this section.
(2) On
the basis of the information contained in such statement, the assessor shall
value such mine for assessment at an amount equal to twenty-five percent of the
gross proceeds, but if the net proceeds exceed twenty-five percent of the gross
proceeds, then such mine shall be valued for assessment at the amount of such
net proceeds.
(3) If
any mining claim or other land is owned by the same person operating a
producing mine which is contiguous to said claim and if, during the preceding
calendar year, ore was actually extracted from said claim or other land or
transported through such claim or other land by cut or tunnel or if any phase
of the operation of said producing mines was conducted on such claim or other
land, then such claim or other land shall be deemed to be a part of such
producing mine and assessed therewith. All other claims or other land under the
same ownership shall be valued in the same manner as other real property, on an
acreage basis, regardless of surface contiguity.
(4) If
any mining claim comprising part of the mining property of a producing mine is
not patented or entered for patent, then the possessory interest therein shall
be the subject of taxation.
(5) Any
increase in the valuation of a producing mine shall constitute an addition to
taxable real property for purposes of the definition of "local
growth" contained in section 20 (2)(g) of article X of the state
constitution.
(6)
This section shall apply to and affect only the valuation of producing mines
pursuant to this article.
Source:
L. 65: R&RE,
p. 1103, § 1. C.R.S. 1963: § 137-6-5. L. 72: p. 570, § 53. L.
85: (3) amended, p. 1212, § 7, effective May 9. L. 94: (1)(c) to
(1)(e), (1)(g), and (1)(h) amended and (1.4), (1.7), (5), and (6) added, p.
1203, § 1, effective May 19. L. 2000: (1.4)(a) amended, p. 671, § 1,
effective August 2.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
This section is
constitutional. Tallon v. Vindicator Consol. Gold Mining Co., 59 Colo. 316,
149 P. 108 (1915).
Valuation set by assessor
presumed to be right. The power to determine the valuation of the mining
property for taxation is lodged in the assessor; and, when he has acted and
determined the value, he is presumed to be right. Standard Chem. Co. v. Curtis,
77 Colo. 10, 233 P. 1112 (1925).
Thus, burden of proof is on
taxpayer to establish allegation of excessive assessment. Standard Chem.
Co. v. Curtis, 77 Colo. 10, 233 P. 1112 (1925).
Ore mined by lessees becomes
property of lessees. City & County of Denver v. Sec. Life &
Accident Co., 173 Colo. 248, 477 P.2d 369 (1970).
Tax levied by this section
levied on possessory right. The tax under this section is not laid alone on
a producing mine or mining claim, but also may be upon the possessory rights
therein. Rummel v. Musgrave, 142 Colo. 249, 350 P.2d 825 (1960).
Thus, lessee of federal
government may be taxed on his mining rights. Under this section, the
possessory and leasehold rights of private citizens in uranium claims on lands
of the United States may legally be assessed by the state, though title to the
lands on which the claims are located is in the United States and is part of
the public lands. Rummel v. Musgrave, 142 Colo. 249, 350 P.2d 825 (1960).
Margin allocation cannot be
deducted as part of the costs of treatment, reduction, transportation, and sale
of ore pursuant to this section. Huddleston v. Grand County Bd. of
Equaliz., 913 P.2d 15 (Colo. 1996).
39-6-107. Valuation of improvements -
machinery.
All
machinery and equipment and personal property shall be listed on a personal
property schedule which shall be submitted as set forth in section 39-5-107 and
valued for assessment by the assessor. Improvements, except mining improvements
within a mine excavation, shall be listed separately and valued for assessment
by the assessor.
Source:
L. 65: R&RE,
p. 1104, § 1. C.R.S. 1963: § 137-6-6. L. 94: Entire section
amended, p. 1206, § 2, effective May 19.
ANNOTATION
Machinery, equipment,
personal property, and above-the-ground improvements are to be valued
pursuant to this section and not deducted as a cost in calculating gross
proceeds or net proceeds pursuant to § 39-6-106. Amax v. Grand County Bd. of
Equaliz., 892 P.2d 409 (Colo. App. 1994), rev'd on other grounds sub nom.
Huddleston v. Grand County Bd. of Equaliz., 913 P.2d 15 (Colo. 1996).
39-6-108. Failure to file statement.
If any
person owning, operating, or managing any producing mine fails or refuses to
prepare and file the statement required in section 39-6-106 or 39-6-113, or
both, then the assessor shall list such property and shall value the same for
assessment on the basis of the best information available to and obtainable by
him.
Source:
L. 65: R&RE,
p. 1104, § 1. C.R.S. 1963: § 137-6-7.
39-6-109. Assessor to examine books -
records.
(1) The
assessor has the authority and right at any time to examine the books,
accounts, and records of any person owning, managing, or operating a producing
mine in order to verify the statement filed by such person, and, if from such
examination the assessor finds such statement or any material part thereof to
be willfully false or misleading, the assessor shall proceed to value such
producing mine for assessment as though no statement had been filed.
(2)
Upon the request of the assessor, the owner or operator of a producing mine
shall provide to the assessor all documentation supporting the amounts reported
on the statement filed by such owner or operator.
(3) The
division of property taxation shall set forth guidelines for the implementation
of this section.
Source:
L. 65: R&RE,
p. 1104, § 1. C.R.S. 1963: § 137-6-8. L. 94: Entire section
amended, p. 1206, § 3, effective May 19.
39-6-110. False statements - penalty.
If any
person required to file such statements willfully and knowingly subscribes to
any false statement contained therein, he is guilty of perjury in the second
degree and upon conviction shall be punished according to law.
Source:
L. 65: R&RE,
p. 1104, § 1. C.R.S. 1963: § 137-6-9. L. 72: p. 570, § 54.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
39-6-111. Valuation of mines other
than producing mines.
(1)
Mines excepted from the provisions of section 39-6-104 shall be valued for
assessment in the same manner as other real property.
(2) All
mines which are classified as nonproducing mines shall be valued for assessment
in the same manner as other real property.
(3)
Such valuation shall be determined under this section by the assessing officer
only upon preponderant evidence shown by such officer that the cost approach,
market approach, and income approach result in uniform and just and equal
valuation.
Source:
L. 65: R&RE,
p. 1105, § 1. C.R.S. 1963: § 137-6-10. L. 70: p. 392, § 1. L.
85: (2) amended and (3) added, p. 1213, § 9, effective May 9.
ANNOTATION
Assessor was required to
give appropriate consideration to the cost, market, and income approaches to
appraisal when valuing a nonproducing mine undergoing reclamation that
could not be classified as agricultural land. Hepp v. Boulder County Assessor,
113 P.3d 1268 (Colo. App. 2005).
39-6-111.5. Calendar for notice of
valuation and appeals for mines.
Notwithstanding
any other provision, all producing and nonproducing mines valued pursuant to
this article shall follow the schedule for personal property set forth in this
title regarding notices of valuation and appeals of valuation.
Source:
L. 2000: Entire
section added, p. 1501, § 5, effective August 2.
39-6-112. Valuation of tunnels.
(1) A
tunnel excavated for the mere purpose of exploration and discovery of mines on
the public domain shall be deemed to be real property and shall be listed and
valued for assessment by the name thereof unless it becomes a part of a
producing mine, in which case it shall be considered a parcel thereof. A tunnel
excavated for the drainage of, or the exploration of, or for giving access to
the mines of those excavating such tunnel shall be deemed an appurtenance to
such mines. A tunnel excavated for the drainage of, or the operation of, or for
giving access to mines of persons other than those excavating such tunnel shall
be deemed real property and shall be listed and valued for assessment by the
name thereof.
(2)
Whenever any such tunnel not appurtenant to or a parcel of a mine is situated
partly in one county and partly in another county or counties or in lesser
political subdivisions, the valuation thereof shall be apportioned between such
counties by allocating the total value thereof between such counties or lesser
political subdivisions in the proportion that the length of the center line
thereof within each such county or lesser political subdivision bears to the
total length thereof.
Source:
L. 65: R&RE,
p. 1105, § 1. C.R.S. 1963: § 137-6-11.
39-6-113. Mine in more than one
county.
(1) (a)
Whenever a mine is situated partly in one county and partly in another county
or counties or in lesser political subdivisions, a copy of the statement
provided for in section 39-6-106, together with a copy of a list of all
machinery and equipment located within the mine, if the mine is a producing
mine, shall be filed with the assessor of each such county. Any such producing
mine shall be valued for assessment in accordance with the provisions of
section 39-6-106 (2) at an amount agreed upon by the assessors of such
counties, and, in the case of any appeal of a protest of such valuation in
either or both counties, the county boards of equalization of such counties
shall confer and attempt to reach agreement on the valuation.
(b) If
the mine is not a producing mine, all machinery and equipment located within
the mine shall nevertheless be valued at an amount agreed upon by the assessors
of such counties and apportioned between such counties by allocating the total
value thereof between such counties or lesser political subdivisions in the
proportion that the acreage of all the mining property of the mine, determined
as provided for in sections 39-6-103 and 39-6-106, within such county or lesser
political subdivision bears to the total acreage thereof as so determined, as
if the mine were itself a producing mine.
(2)
Whenever any producing mine, worked or operated by means of an integrated
mining system and comprised of consolidated mining property, is situated partly
in one county and partly in another county or counties or in lesser political
subdivisions, the valuation thereof and of all machinery and equipment located
within or upon the mine shall be apportioned between such counties or lesser
political subdivisions in the proportion that the acreage of all the mining
property of the mine, determined as provided for in sections 39-6-103 and
39-6-106, within such county or lesser political subdivision bears to the total
acreage thereof as so determined. The assessor of each county shall list and
value for assessment the portion of such mine which is situated in such county
at the amount determined for such portion by such apportionment, and taxes
levied on such valuation for assessment by the board of county commissioners of
such county shall be collected by the treasurer of such county as provided by
law.
(3)
Where a mine is situated partly in one county and partly in another county or
counties or in lesser political subdivisions, the owner, operator, or manager
thereof shall, no later than April 15 of each year, prepare and file with the
assessor of each such county a statement showing the number of acres within
each such county contained in the lands comprising the mining property of the
mine, determined as provided for in sections 39-6-103 and 39-6-106, but the
statement need not be filed if no changes have occurred since such a statement
was filed.
(4) (a)
Nothing in subsection (3) of this section shall be construed to require the
owner, operator, or manager of a mine to file an additional statement if the
statement filed pursuant to section 39-6-106 sets forth the number of acres of
the mine in each county.
(b)
Nothing in subsection (3) of this section shall be construed to relieve the
owner, operator, or manager of a mine from any reporting responsibilities
imposed under section 39-6-106, including the required contents of the
statement filed with the assessor.
Source:
L. 65: R&RE,
p. 1105, § 1. C.R.S. 1963: § 137-6-12. L. 92: (1) amended, p.
971, § 14, effective June 1. L. 93: (1)(b), (2), and (3) amended, p.
441, § 10, effective July 1. L. 94: (3) amended and (4) added, p. 1206,
§ 4, effective May 19.
39-6-114. Mines and tunnels in more
than one subdivision of a county.
Whenever
any mine or tunnel is situated partly in one lesser political subdivision of a
county and partly in another such subdivision of the same county, the assessor
of the county shall apportion the value thereof between such lesser political
subdivisions in the manner provided for in sections 39-6-112 and 39-6-113.
Source:
L. 65: R&RE,
p. 1106, § 1. C.R.S. 1963: § 137-6-13.
39-6-115. Collection.
Beginning
January 1, 1980, when taxes on mines and mining claims are due, such taxes
shall be a debt due from the owner or user and shall be recoverable by the
treasurer by direct action in debt. The treasurer may also collect such debt as
if the property were personal property.
Source:
L. 79: Entire
section added, p. 1418, § 1, effective April 25.
39-6-116. Nonproducing unpatented
mining claims - definitions.
"Unpatented
mining claims", as used in section 3 (1)(b) of article X of the state
constitution, includes mining claims located under the federal mining laws, 30
U.S.C. sec. 22 et seq., for which a patent has not been issued; and such term
also includes leasehold interests in real property obtained under the federal
"Mineral Lands Leasing Act of 1920", 30 U.S.C. sec. 181 et seq.
Source:
L. 89: Entire
section added, p. 1495, § 1, effective May 1.
39-6-117. County boards of
equalization - authority.
Nothing in
this article shall be construed to affect the authority of county boards of
equalization to raise, lower, or adjust any valuation for assessment appearing
in the assessment roll as provided in section 39-8-102 (1).
Source:
L. 94: Entire
section added, p. 1207, § 5, effective May 19.
ARTICLE
7
Valuation
of Oil and Gas Leaseholds and Lands
39-7-101. Statement of owner or operator.
39-7-102. Valuation for assessment.
39-7-102.5. Calendar for notice of valuation
and appeals.
39-7-102.7. Notice of valuation - public
record.
39-7-103. Surface and subsurface equipment
valued separately.
39-7-104. Failure to file statement.
39-7-105. Assessor to examine books, records.
39-7-106. False statement - penalty.
39-7-107. Oil and gas lands in more than one
county.
39-7-108. Collection.
39-7-109. Valuation of severed nonproducing
oil or gas mineral interests.
39-7-110. Oil and gas operator - definition.
39-7-101. Statement of owner or
operator.
(1)
Every operator of, or if there is no operator, every person owning any oil or
gas leasehold or lands within this state, either as a single lease or as a
unit, that are producing or are capable of producing oil or gas on the
assessment date of any year, shall, no later than the fifteenth day of April of
each year, prepare, sign under the penalty of perjury in the second degree, and
file in person or by mail with the assessor of the county in which the wellhead
producing the oil and gas leaseholds or lands is located a statement for the
lease or unit. For purposes of this article, irrespective of the physical
location of the producing leaseholds or lands, the point of taxation is the
same as the point of valuation, which is the wellhead. The statement must be
made on a form prescribed by the administrator, showing:
(a) The
wellhead location thereof and the name thereof, if there is a name;
(b) The
name, address, and fractional interest of the operator thereof;
(c) The
number of barrels of oil, or the quantity of gas measured in thousands of cubic
feet, sold or transported from the wellhead during the calendar year
immediately preceding, after separately reporting the number of barrels of oil,
or the quantity of gas measured in thousands of cubic feet, delivered to the
United States government or any agency thereof, the state of Colorado or any
agency or political subdivision thereof, or any Indian tribe as royalty during
the calendar year immediately preceding;
(d) The
selling price at the wellhead. As used in this article, "selling price at
the wellhead" means the net taxable revenues realized by the taxpayer for
sale of the oil or gas, whether such sale occurs at the wellhead or after
gathering, transportation, manufacturing, and processing of the product. The
net taxable revenues shall be equal to the gross lease revenues, minus
deductions for gathering, transportation, manufacturing, and processing costs
borne by the taxpayer pursuant to guidelines established by the administrator.
(e) The
name, address, and fractional interest of each interest owner taking production
in kind and the proportionate share of total unit revenue attributable to each
interest owner who is taking production in kind;
(f) A
declaration made under the penalty of perjury in the second degree that
includes the following:
(I) A
statement that the owner or operator has personally examined the statement
described in this section and that such statement sets forth, to the best of
the owner's or operator's knowledge and belief, the information required by
this section; and
(II) A
statement by the owner or operator as follows:
No representations are made as to
the accuracy of the value of any portion of the production from subject
property that is taken in kind by any owner other than the undersigned.
(1.5)
Any nonoperating interest owner in an oil or gas well may, on or before the
fifteenth day of March each year, submit to the operator by certified mail a
report of the actual net taxable revenues received at the wellhead and the
actual exempt revenues received at the wellhead by such owner for production
taken in kind from the property during the calendar year immediately preceding.
Operators shall use the information reported pursuant to this subsection (1.5)
to determine the selling price at the wellhead. If any nonoperating interest
owner fails to provide to the unit operator the information required under this
subsection (1.5) by March 15 of each year, such operator shall use the selling
price at the wellhead received by such operator for such operator's share of
production from such unit in place of such nonreported information, and the
amount of tax for which such nonreporting, nonoperating interest owner is
liable shall be calculated based on the selling price at the wellhead reported
by the operator.
(2) (a)
If a statement of an owner or operator is not received or postmarked on or
before the fifteenth day of April of each year, the assessor may impose on such
owner or operator a late filing penalty in the amount of one hundred dollars
for each calendar day the statement is delinquent; except that such late filing
penalty shall not exceed three thousand dollars in any calendar year. The
assessor may grant an extension of time for filing a statement to any operator
or owner. Any extension, and its length, shall be granted solely at the
discretion of the assessor.
(b)
This subsection (2) is effective January 1, 1997.
(3) (a)
The assessor may require the owner or operator to submit written documentation
supporting the information provided in the statement. Such documentation shall
be supplied within thirty days after either the date of the postmark on the
assessor's written request for such documentation or the date that an owner or
operator is required to file a statement pursuant to subsection (1) of this
section, whichever is later. Any owner or operator who willfully fails or
refuses to comply with the assessor's request for written documentation may be
assessed a fine of one hundred dollars for each day of such willful failure or
refusal. The total amount of all fines that may be assessed by an assessor
against an owner or operator in any calendar year shall not exceed three
thousand dollars, regardless of the number of leases or units owned or operated
by such owner or operator or the number and length of such willful failures or
refusals by such owner or operator.
(b)
This subsection (3) is effective January 1, 1997.
(4) All
statements and documentation filed with the assessor shall be considered
private documents and shall be available on a confidential basis only to the
assessor, the administrator, the annual study contractor hired pursuant to
section 39-1-104, the executive director of the department of revenue, the
county treasurer, and their employees. Such statements and documentation shall
be available on a confidential basis to the board of assessment appeals and the
county board of equalization when information in such statements and
documentation is pertinent to an appeal or protest.
(5) (a)
Fines imposed pursuant to this section shall be fees of the office of the
county assessor. Any unpaid fines imposed pursuant to this section shall be
certified to the county treasurer by January 1 of each year and shall be
included in the delinquent owner's or operator's property tax statement issued
pursuant to section 39-10-103.
(b)
This subsection (5) is effective January 1, 1997.
Source:
L. 64: R&RE,
p. 710, § 1. C.R.S. 1963: § 137-7-1. L. 69: p. 1120, § 1. L.
72: p. 570, § 55. L. 81: (1)(c) and (1)(d) amended, p. 1857, § 1,
effective January 1, 1982. L. 93: (1)(d) amended and (1)(e) and (2)
added, pp. 241, 242, §§ 1, 2, effective March 31. L. 96: Entire section
amended, p. 107, § 1, effective March 25. L. 2007: (4) amended, p. 498,
§ 1, effective April 16. L. 2009: (3)(a) amended, (HB 09-1161), ch. 44,
p. 166, § 1, effective August 5. L. 2014: IP(1), (1)(a), and (1)(c)
amended, (HB 14-1371), ch. 400, p. 2012, § 1, effective August 6. L. 2020:
(4) amended, (HB 20-1077), ch. 80, p. 325, § 10, effective September 14.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
ANNOTATION
Selling price for the
purposes of this article means the actual amount received by the seller.
This amount most closely reflects the market value in the ordinary course of
trade and is consistent with the requirement that actual value of real property
be determined for tax assessment purposes. Yuma County Bd. of Equaliz. v. Cabot
Petroleum, 856 P.2d 844 (Colo. 1993).
Where the selling price cannot
be determined within a short period of time, it is incumbent upon owners and
operators of oil and gas leaseholds and lands to report in mandatory annual
statements any dispute concerning the selling price or the fact that the owner
or operator have agreed to delayed payments. Yuma County Bd. of Equaliz. v.
Cabot Petroleum, 856 P.2d 844 (Colo. 1993).
Processing costs occurring
on oil leasehold site are properly deducted from the sale price of the oil in
valuing the unprocessed material at the wellhead under subsection (1)(d) of
this section and art. X, § 3 (1)(b), of the state constitution. The
legislature, consistent with the constitution, intended "wellhead" to
mean the physical location where the extracted material emerges from the
ground. The statute defines "selling price at the wellhead" as the
"next taxable revenues realized by the taxpayer for sale of the oil or
gas, whether such sale occurs at the wellhead or after gathering,
transportation, manufacturing, and processing of the product". In
determining whether on-site processing costs are properly deductible in
arriving at the wellhead value of the unprocessed material, the essential
practice and lesson of the industry is that there is no market for the material
until the initial steps of processing the unprocessed material have occurred.
Here, the selling price of the separated oil was established at the storage
tanks. Because gathering, processing, and transportation occurred before the
product was valued at the tank battery, those costs are properly deductible in
arriving at the value of the "unprocessed material" at the wellhead.
Wash. County Bd. of Equaliz. v. Petron Dev. Co., 109 P.3d 146 (Colo. 2005).
In disallowing taxpayer's
deductions, county's determination that "gathering, processing, and
transportation" expenses could not be deducted unless they occurred
"away from" or "beyond" the leasehold property surrounding
the well would result in non-uniform treatment of similarly situated taxpayers
within the same class and is contrary to both subsection (1)(d) of this section
and art. X, § 3 (1)(b), of the state constitution. County was required to
allow for deduction of processing costs on the leasehold site to comply with
the constitutional and statutory provisions. Wash. County Bd. of Equaliz. v.
Petron Dev. Co., 109 P.3d 146 (Colo. 2005).
Statutory definition of
"selling price at the wellhead" required assessor to allow deductions
for gathering, transportation, manufacturing, and processing costs incurred
between the wellhead and the point of sale of crude oil. Article X, § 3 (1)(b),
of the Colorado Constitution requires valuation of an oil leasehold to be based
upon the value of unprocessed oil, and removal of water from and injection of
chemicals into oil between the wellhead and the point of sale constituted
processing even though the oil remained crude oil. Petron Dev. Co. v. Wash.
County Bd. of Equaliz., 91 P.3d 408 (Colo. App. 2003), aff'd on other grounds,
109 P.3d 146 (Colo. 2005).
Moreover, a definition of
"well site" that includes an entire oil or gas leasehold violates the
uniformity of taxation requirement. Leaseholds vary in size and number of
wells, and the definition would force oil and gas producers with larger
leaseholds who are able to gather, transport, manufacture, and process material
entirely on their leaseholds to pay higher taxes by preventing them from
deducting the costs of those activities. Petron Dev. Co. v. Wash. County Bd. of
Equaliz., 91 P.3d 408 (Colo. App. 2003), aff'd on other grounds, 109 P.3d 146
(Colo. 2005).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
39-7-102. Valuation for assessment.
(1)
Except as provided in subsection (2) of this section, on the basis of the
information contained in such statement, the assessor shall value such oil and
gas leaseholds and lands for assessment, as real property, at an amount equal
to eighty-seven and one-half percent of:
(a) The
selling price of the oil or gas sold from each wellhead during the preceding
calendar year, after excluding the selling price of all oil or gas delivered to
the United States government or any agency thereof, the state of Colorado or
any agency thereof, or any political subdivision of the state as royalty during
the preceding calendar year;
(b) The
selling price of oil or gas sold in the same field area for oil or gas
transported from the premises which is not sold during the preceding calendar
year, after excluding the selling price of all oil or gas delivered to the
United States government or any agency thereof, the state of Colorado or any
agency thereof, or any political subdivision of the state as royalty during the
preceding calendar year.
(2) In
order to promote the initiation or continuation of secondary recovery, tertiary
recovery, or recycling projects which conserve and avoid waste of oil and gas,
the assessor shall value oil and gas leaseholds and lands employing such
projects for assessment as provided in subsection (1) of this section but at an
amount equal to seventy-five percent of:
(a) The
selling price of the oil or gas sold therefrom during the preceding calendar
year, after excluding the selling price of all oil or gas delivered to the
United States government or any agency thereof, the state of Colorado or any
agency thereof, or any political subdivision of the state as royalty during the
preceding calendar year;
(b) The
selling price of oil or gas sold in the same field area for oil or gas
transported from the premises which is not sold during the preceding calendar
year, after excluding the selling price of all oil or gas delivered to the
United States government or any agency thereof, the state of Colorado or any
agency thereof, or any political subdivision of the state as royalty during the
preceding calendar year.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-2. L. 69: p. 1120, § 2. L.
77: Entire section amended, p. 1852, § 2, effective January 1, 1978. L.
81: Entire section amended, p. 1857, § 2, effective January 1, 1982. L.
2014: (1)(a) amended, (HB 14-1371), ch. 400, p. 2013, § 2, effective August
6.
ANNOTATION
The valuation formula
specified by this section is intended to gauge the value of oil in the ground
and is not a tax on the amount of oil actually produced. Petron Dev. Co. v.
Washington County Bd. of Equaliz., 91 P.3d 408 (Colo. App. 2003).
39-7-102.5. Calendar for notice of
valuation and appeals.
Notwithstanding
any other provisions to the contrary, lands and leaseholds valued pursuant to
this article shall follow the schedule for personal property set forth in this
title regarding notices of valuation and appeals of valuation.
Source:
L. 88: Entire
section added, p. 1301, § 7, effective April 29.
39-7-102.7. Notice of valuation - public
record.
The
assessor shall retain a copy of all notices of valuation for lands and
leaseholds valued pursuant to this article, and such copies shall be public
records that are available for inspection in accordance with part 2 of article
72 of title 24, C.R.S.
Source:
L. 2007: Entire
section added, p. 498, § 2, effective April 16.
39-7-103. Surface and subsurface
equipment valued separately.
All
surface oil and gas well equipment and submersible pumps and sucker rods
located on oil and gas leaseholds or lands shall be separately valued for
assessment as personal property, and such valuation may be at an amount
determined by the assessors of the several counties of the state, approved by
the administrator, and uniformly applied to all such equipment wherever
situated in the state. All other subsurface oil and gas well equipment,
including casing and tubing, shall be valued as part of the leasehold or land
under section 39-7-102.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-3. L. 76: Entire section
amended, p. 775, § 1, effective January 1, 1977.
39-7-104. Failure to file statement.
If any
person owning or operating any oil and gas leaseholds or lands producing or
capable of producing oil or gas on the assessment date fails or refuses to
prepare and file the statement required by the provisions of section 39-7-101,
then the assessor shall list such property and value the same for assessment on
the basis of the best information available to and obtainable by him.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-4.
ANNOTATION
This section authorizes
retroactive assessments for ad valorem taxes when the taxpayer has caused
the incorrect valuation of a gas leasehold. Yuma County Bd. of Equalization v.
Cabot Petroleum, 856 P.2d 844 (Colo. 1993).
39-7-105. Assessor to examine books,
records.
The
assessor has the authority and right at any time to examine the books,
accounts, and records of any person owning or operating such oil and gas
leaseholds and lands in order to verify the statement filed by such person,
and, if from such examination he finds such statement or any material part
thereof to be willfully false and misleading, he shall proceed to value such
oil and gas leaseholds or lands for assessment as though no statement had been
filed.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-5.
ANNOTATION
This section authorizes
retroactive assessments for ad valorem taxes when the taxpayer has caused
the incorrect valuation of a gas leasehold. Yuma County Bd. of Equalization v.
Cabot Petroleum, 856 P.2d 844 (Colo. 1993).
39-7-106. False statement - penalty.
If any
person required to file such statement willfully and knowingly subscribes to
any false statement contained therein, he is guilty of perjury in the second
degree and upon conviction shall be punished according to law.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-6. L. 72: p. 570, § 56.
Cross
references: For
perjury in the second degree and the penalty therefor, see §§ 18-8-503 and
18-1.3-501.
39-7-107. Oil and gas lands in more
than one county.
(1)
Whenever any oil and gas leaseholds or lands appear to be situated in more than
one county, the production value is assigned to the county in which the
wellhead is located.
(2)
Whenever the wellheads of a group of contiguous oil and gas leaseholds or lands
operated as a unit are situated in more than one county, the person making the
statement required by section 39-7-101 shall assign to each wellhead that
portion of the production value from the unit as is assigned by the unit
agreement.
(3)
Whenever unit production occurs from wellheads in more than one county, a copy
of the statement required by the provisions of section 39-7-101 shall be filed
with the assessor of each affected county.
Source:
L. 64: R&RE,
p. 711, § 1. C.R.S. 1963: § 137-7-7. L. 2014: Entire section
amended, (HB 14-1371), ch. 400, p. 2013, § 3, effective August 6.
39-7-108. Collection.
Beginning
January 1, 1980, when taxes on oil and gas leaseholds and lands are due, such
taxes shall be a debt due from the owner or the unit operator as the case may
be and shall be recoverable by the treasurer by direct action in debt; except
that such taxes treated as debt due from a fractional interest owner shall not
exceed the amount of taxes for which the fractional owner is liable, as
provided in section 39-10-106. The treasurer may also collect such debt as if
the property were personal property.
Source:
L. 79: Entire
section added, p. 1418, § 2, effective April 25.
39-7-109. Valuation of severed
nonproducing oil or gas mineral interests.
(1) The
actual value of severed nonproducing oil or gas or oil and gas mineral
interests shall be determined by the income approach capitalizing the annual
net rental income for such nonproducing mineral interests at an appropriate
market rate. If such severed mineral interests are unleased, the assessor shall
use the average per acre annual rental of all such mineral interests under
lease in the county or in the area to determine the actual value thereof.
(2) For
the purposes of this section, "annual rental" means annual rental
payments, or other compensatory payments payable for the right to hold a
mineral interest, which payments are fixed and certain in amount and payable
periodically over a fixed period calculated on a twelve-month basis.
"Annual rental" shall be the representative annual rental for such
mineral interests leased within the county or the area, and "annual
rental" does not include royalty payments, advanced royalty payments,
bonus payments, or minimum royalty payments covering periods when the mineral
interests are not in production, even though said payments may be fixed and
certain in amount and payable periodically. For the purposes of this subsection
(2), "royalty payments", "advanced royalty payments", and
"minimum royalty payments" are payments attributable to a portion of
the current or future mineral production of a mineral interest, paid for the
privilege of producing minerals, and "bonus payments" means
compensation paid as consideration for the granting of a mineral lease or other
compensatory payments which are payable regardless of the extent of use of the
mineral interest and which are fixed and certain in amount and may be payable
in one or more periodical increments over a fixed period.
Source:
L. 85: Entire
section added, p. 1213, § 10, effective May 9.
39-7-110. Oil and gas operator -
definition.
(1) As
used in this article 7, "well or unit operator" means the operator of
each wellsite or, if there is no operator, the owner who filed the statement
with the assessor pursuant to section 39-7-101.
(2)
Notwithstanding any other provision of law, the partial interests of oil and
gas fractional interest owners are not subject to separate valuation by the
assessor and shall be represented by the well or unit operator of each
wellsite. The well or unit operator is the sole point of contact for all
notification, review, audit, protest, abatement, and appeal procedures.
Source:
L. 2022: Entire
section added, (SB 22-026), ch. 58, p. 265, § 2, effective March 30.
Equalization
ARTICLE
8
County
Boards of Equalization
39-8-101. County board of equalization -
quorum.
39-8-102. Duties of county board of
equalization.
39-8-103. Notice of change in valuation.
39-8-104. Notice of meeting.
39-8-105. Reports of assessor.
39-8-106. Petitions for appeal.
39-8-107. Hearings on appeal.
39-8-108. Decision - review - opportunity to
submit case to arbitration.
39-8-108.5. Arbitration of property valuations
- arbitrators - qualifications - procedures.
39-8-108.7. Review of decision - effect of
stipulation by taxpayer - repeal. (Repealed)
39-8-109. Effects of board of assessment
appeals or district court decision.
39-8-101. County board of equalization
- quorum.
The board
of county commissioners of each county of the state, except the city and county
of Denver and the city and county of Broomfield, shall comprise the board of
equalization of such county. In the city and county of Denver, the board of
equalization shall be comprised of such of its officers as may be provided by
its charter. In the city and county of Broomfield, the board of equalization
shall be the city council or a board or commission appointed by the city
council. A majority of the board shall constitute a quorum, and no official
action shall be taken at any meeting of the board unless a quorum is present.
Source:
L. 64: R&RE,
p. 712, § 1. C.R.S. 1963: § 137-8-1. L. 2001: Entire section
amended, p. 269, § 16, effective November 15.
Cross
references: For
constitutional grant of powers to county boards of equalization, see § 15 of
article X of the state constitution.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments", see 15 Colo. Law. 798
(1986).
Applied in West-Brandt
Found., Inc. v. Carper, 199 Colo. 334, 608 P.2d 339 (1980).
39-8-102. Duties of county board of
equalization.
(1) The
county board of equalization shall review the valuations for assessment of all
taxable property appearing in the assessment roll of the county, directing the
assessor to supply any omissions which may come to its attention. It shall
correct any errors made by the assessor, and, whenever in its judgment justice
and right so require, it shall raise, lower, or adjust any valuation for
assessment appearing in the assessment roll to the end that all valuations for
assessment of property are just and equalized within the county.
(2) (a) to
(h) Repealed.
(i) The
county board of equalization shall have the authority to appoint independent
referees who are experienced in property valuation to conduct hearings pursuant
to subsection (1) of this section on behalf of the county board of equalization
and to make findings and submit recommendations to the county board of
equalization for its final action. However, no person shall be appointed as an
independent referee pursuant to the provisions of this paragraph (i) in any
county during any property tax year in which such person represents or has
represented any taxpayer in such county in any matter relating to the protest
and appeal of property valuation or to the abatement or refund of property
taxes. In addition, no person appointed as an independent referee pursuant to
the provisions of this paragraph (i) shall represent any taxpayer who appeared
in any hearing before such independent referee in any matter subsequent to such
hearing relating to the protest and appeal of property valuation or to the
abatement or refund of property taxes.
(j) and
(k) Repealed.
(3)
(Repeal provision deleted by revision.)
(4)
Repealed.
Source:
L. 64: R&RE,
p. 714, § 1. C.R.S. 1963: § 137-8-8. L. 77: Entire section
amended, p. 1758, § 1, effective June 1; (4) added, p. 1736, § 18, effective
June 20. L. 79: (2)(i) amended, p. 1641, § 53, effective July 19. L.
81: (4) repealed, p. 1835, § 14, effective June 12. L. 92: (2)(i)
amended, p. 2209, § 6, effective June 3.
Editor's
note: Subsection
(3) provided for the repeal of subsections (2)(a) to (2)(h), (2)(j), and
(2)(k), effective January 1, 1978, and is therefore deleted by revision as
obsolete. (See L. 77, p. 1758.)
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Equalization system is not
in conflict with due process of law. People ex rel. State Bd. of Equaliz.
v. Hively, 139 Colo. 49, 336 P.2d 721 (1959).
Boards to adjust property
values. The constitutional duty imposed upon the state board of
equalization is to adjust and equalize the property values among the several
counties of the state. Since these duties having been imposed upon these
agencies by § 15 of art. X, Colo. Const., the general assembly is powerless to
take them away or confer them upon another. People ex rel. State Bd. of
Equaliz. v. Pitcher, 56 Colo. 343, 138 P. 509 (1914), aff'd, 239 U.S. 441
(1915).
Equalization and assessment
distinguished. The process of equalization relates to the raising or
lowering of the total valuation placed upon a class or subclass of property in
the aggregate. Assessment, on the other hand, constitutes the process of
placing a value for tax purposes upon the property of a particular taxpayer.
Wenner v. Bd. of Assessment Appeals, 866 P.2d 172 (Colo. App. 1993).
The broad powers granted by
subsection (1) include those incidental powers necessary to effectuate an
equalization of any disparities which affect the uniformities of the tax
assessed. Where board directed the assessor to revalue properties to correct a
disparity, board did not exceed its statutory authority. Wenner v. Bd. of
Assessment Appeals, 866 P.2d 172 (Colo. App. 1993).
Applied in Am.
Mobilehome Ass'n v. Dolan, 191 Colo. 433, 553 P.2d 758 (1976).
39-8-103. Notice of change in
valuation.
The county
clerk and recorder shall notify each person affected of any change in the
valuation of his property ordered by the board and shall furnish the assessor
with a copy of such notice.
Source:
L. 64: R&RE,
p. 714, § 1. C.R.S. 1963: § 137-8-9. L. 90: Entire section
amended, p. 1697, § 21, effective June 9.
39-8-104. Notice of meeting.
(1)
Except as provided in subsection (2) of this section, prior to July 1 of each
year, the county clerk and recorder shall give notice in at least one issue of
a newspaper published in the assessor's county that beginning on July 1, the
county board of equalization will sit in the county's regular public meeting
location or other appropriate public meeting place to review the assessment
roll of all taxable property located in the county, as prepared by the
assessor, and to hear appeals from determinations of the assessor.
(2) (a)
Prior to a date established by the county board of equalization, but no later
than September 1, the county clerk and recorder in a county that uses an
alternate protest and appeal procedure pursuant to section 39-5-122.7 shall
give notice in at least one issue of a newspaper published in the county that
beginning such date the county board of equalization will sit in the county's
regular public meeting location or other appropriate public meeting place to
review the assessment roll of all taxable property located in the county, as
prepared by the assessor, and to hear appeals from determinations of the
assessor.
(b)
Prior to August 1, 2017, and prior to each August 1 thereafter, the county
clerk and recorder shall give notice in at least one issue of a newspaper
published in his or her county of any date or dates between August 1 and
September 1 on which the county commissioners, sitting as the county board of
equalization, shall hear contests of property tax exemption denials as required
by section 39-3-206 (2).
(2.5)
Repealed.
(3) If
there is no newspaper, then such notice shall be conspicuously posted in the
offices of the county clerk and recorder, the treasurer, and the assessor and
in at least two other public places in the county seat.
Source:
L. 64: R&RE,
p. 712, § 1. C.R.S. 1963: § 137-8-2. L. 81: Entire section
amended, p. 1834, § 10, effective June 12. L. 89: Entire section
amended, p. 1458, § 14, effective June 7. L. 98: Entire section amended,
p. 469, § 3, effective July 1. L. 2001: (2) amended, p. 469, § 2,
effective April 25. L. 2009: (1) and (2)(a) amended, (SB 09-292), ch.
369, p. 1986, § 134, effective August 5. L. 2013: (1) amended and (2.5)
added, (HB 13-1113), ch. 11, p. 31, § 4, effective March 8. L. 2016:
(2)(b) amended, (HB 16-1175), ch. 332, p. 1349, § 5, effective January 1, 2017.
L. 2020: (1) amended and (2.5) repealed, (SB 20-136), ch. 70, p. 292, §
35, effective September 14. L. 2025: (2)(a) amended, (HB 25-1324), ch.
445, p. 2559, § 3, effective June 4.
Cross
references: For
the legislative declaration in SB 20-136, see section 1 of chapter 70, Session
Laws of Colorado 2020.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Publication of meeting dates
for taxpayer's benefit. The directions given the county board of
equalization as to the required dates of meetings are for the benefit of the
taxpayer, to give him notice, and opportunity to be heard, as it is mandatory
upon a taxpayer to make his complaint before the board at the time provided by
this section. Tarabino Real Estate Co. v. Sandoval, 115 Colo. 336, 173 P.2d 459
(1946).
When provisions of section
to be construed as mandatory. The requirements of this section are to be
construed as mandatory only in specific instances where it is clearly shown on
behalf of an aggrieved taxpayer, that, on account of noncompliance with these
statutory requirements by the county officials charged therewith, the taxpayer
has been deprived of an opportunity for a hearing or of some other right
important to him. Northcutt v. Burton, 127 Colo. 145, 254 P.2d 1013 (1953);
Citizens' Comm. for Fair Prop. Taxation v. Warner, 127 Colo. 121, 254 P.2d 1005
(1953).
Absent grievance, taxpayer
cannot complain of lack of notice. An owner, who has no grievance, cannot
complain that a proper notice of the meeting of the board for the purpose of
equalizing was not given. Citizens' Comm. for Fair Prop. Taxation v. Warner,
127 Colo. 121, 254 P.2d 1005 (1953).
39-8-105. Reports of assessor.
(1) At
a meeting of the county board of equalization on or before each September 15 in
a county that uses an alternate protest and appeal procedure pursuant to
section 39-5-122.7, or on or before each July 15 in all other counties, the
assessor shall report the valuation for assessment of all taxable real property
in the county. The assessor shall submit a list of all persons who have
appeared before the assessor to present objections or protests concerning real
property and the action taken in each case.
(2) At
the meeting of the board described in subsection (1) of this section, the
assessor shall also report the valuation of all taxable personal property in
the county and shall note any valuations for assessment of portable or movable
equipment which have been apportioned pursuant to section 39-5-113. The
assessor shall submit a list of all persons in the county who have failed to
return any schedules and shall report the action taken in each case. The
assessor shall also submit a list of persons who have appeared before him or
her to present objections or protests and the action taken in each case.
Source:
L. 64: R&RE,
p. 712, § 1. C.R.S. 1963: § 137-8-3. L. 67: p. 951, § 21. L.
76: Entire section amended, p. 763, § 25, effective January 1, 1977. L.
81: Entire section R&RE, p. 1834, § 11, effective June 12. L. 88:
(2) amended, p. 1301, § 8, effective April 29. L. 90: (1) amended, p.
1694, § 11, effective January 1, 1991. L. 98: (1) amended, p. 469, § 4,
effective July 1. L. 2009: (2) amended, (SB 09-292), ch. 369, p. 1987, §
135, effective August 5. L. 2014: Entire section amended, (HB 14-1020),
ch. 5, p. 86, § 1, effective February 19. L. 2025: (1) amended, (HB
25-1324), ch. 445, p. 2560, § 4, effective June 4.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
County assessor is under
duty to assess all taxable property for taxation, regardless of whether a
reappraisal thereof has been completed; although he is not required to await
completion of reappraisal before making up his tax roll, he is under obligation
nevertheless, in the interest of uniformity, to determine his valuations in
conformity with reappraisal standards insofar as this might reasonably be
accomplished under the circumstances. Citizens' Comm. for Fair Prop. Taxation
v. Warner, 127 Colo. 121, 254 P.2d 1005 (1953).
After report is made,
assessor's quasi-judicial functions end. When the county assessor has
completed his assessment and submits his assessment roll to the county board of
equalization, his quasi-judicial functions and his duties, thereafter to be
performed, are purely ministerial. People ex rel. State Bd. of Equaliz. v.
Pitcher, 61 Colo. 149, 156 P. 812 (1916).
39-8-106. Petitions for appeal.
(1) The
county board of equalization shall receive and hear petitions from any person
whose objections or protests have been refused or denied by the assessor. A
petition must be in a form approved by the property tax administrator pursuant
to section 39-2-109 (1)(d), the contents of which must include the following:
(a) A
statement informing the person of the person's right to appeal, the time and
place at which the county board of equalization will hear appeals from
determinations of the assessor, and that, by mailing or delivering one copy of
the form to the county board of equalization that is received or postmarked on
or before July 15 of that year for real property and July 20 of that year for
personal property or, if a county uses an alternate protest and appeal
procedure pursuant to section 39-5-122.7, on or before September 15 of that
year for both real and personal property, the person will be deemed to have
filed a petition for hearing with the county board of equalization. The date
the form is received by the county board of equalization shall be stamped on
the form. All forms shall be presumed to be on time unless the county board of
equalization can present evidence to show otherwise.
(b) A
requirement that the assessor's office set forth the following information on
the face of the form:
(I) A
description of the property claimed to be excessively, erroneously, or
illegally valued;
(II)
The actual value placed upon it by the assessor;
(III) A
specific and detailed statement of the grounds delineated in this subparagraph
(III), upon which the assessor relied to justify such valuation. The grounds
are appropriate consideration of the approaches to appraisal set forth in
section 39-1-103 (5)(a) and classification of the property. For agricultural
lands, the grounds are: Earning or productive capacity; classification; and
capitalization rate.
(IV)
The assessor's written statement refusing to change such valuation; and
(V) The
actual value placed upon it by the person whose objection and protest has been
denied.
(c)
Space for the person whose objection and protest has been denied to state the
grounds on which he relied and to indicate the manner, if any, in which he
disagrees with the assessor's statement of the information described in
paragraph (b) of this subsection (1).
(1.5)
In addition to any other requirements set forth in subsection (1) of this
section, any petition for appeal relating to real property shall contain the
actual value of such real property, stated in terms of a specific dollar
amount, which is being offered as the correct valuation. Nothing in this
subsection (1.5) shall be construed to exempt paid representatives of taxpayers
from the requirements of part 6 of article 10 of title 12, if applicable.
(1.7)
Any person who objects to the application of the term "integral to an
agricultural operation" to their property in accordance with section
39-1-102 (1.6)(a)(I) and (14.4) and whose objections or protests have been
denied by the assessor may submit a petition for appeal to the county board of
equalization to the same extent as any other protest or objection for which an
appeal to the board is provided under law and shall satisfy all requirements
for the prosecution of such appeal as provided by law.
(2) (a)
Upon receiving a petition in the form described in subsection (1) of this
section, the county board of equalization or its authorized agent shall note
the filing of the petition, set a time for hearing of said petition, and,
except as provided in paragraph (b) of this subsection (2), notify the
petitioner by mail of such time for hearing.
(b) A
board of county commissioners may authorize by resolution a petitioner or a
petitioner's agent to elect to receive the notice required in paragraph (a) of
this subsection (2) by fax or electronic mail at a phone number or electronic
mail address supplied by the petitioner or the petitioner's agent. If no
election is made by the petitioner or the petitioner's agent, the county board
of equalization shall mail the required notice.
(3) If
the assessor fails or refuses to comply with the provisions of section
39-5-122, this section, or both, relating to said form, the objecting person
shall not be deprived of his right of appeal to the county board of
equalization. The objecting person may present his objections and protests in
person or by counsel, orally or by letter or other informal writing, on any day
during the meeting of the county board of equalization held for the purpose of
hearing appeals. The said failure or refusal of the assessor shall not, in any
manner, deprive the objecting person of his right to a full, fair, and complete
hearing of his objections and protests by the county board of equalization.
Source:
L. 64: R&RE,
p. 713, § 1. C.R.S. 1963: § 137-8-4. L. 73: p. 1441, § 2. L.
75: (1)(b)(III) amended, p. 1455, § 2, effective July 30. L. 76:
(1)(a) and (1)(b)(III) amended, p. 763, §§ 26, 27, effective January 1, 1977. L.
81: (1)(a) amended, p. 1834, § 12, effective June 12. L. 83:
(1)(b)(III) amended, p. 2087, § 4, effective October 13. L. 88: (1)(a)
amended, p. 1301, § 9, effective April 29. L. 89: (1)(a) amended, p.
1458, § 15, effective June 7. L. 90: (1)(a), (1)(b)(II), and (1)(b)(V)
amended, p. 1694, § 12, effective January 1, 1991. L. 92: (1)(a) amended
and (1.5) added, p. 2210, § 7, effective June 3. L. 98: IP(1) and (1)(a)
amended, p. 469, § 5, effective July 1. L. 2005: IP(1) and (1)(a)
amended, p. 391, § 3, effective April 27. L. 2011: (1.7) added, (HB
11-1146), ch. 166, p. 573, § 3, effective January 1, 2012. L. 2013:
IP(1) amended, (HB 13-1113), ch. 11, p. 31, § 5, effective March 8. L. 2016:
(2) amended, (SB 16-172), ch. 280, p. 1148, § 2, effective June 10. L. 2019:
(1.5) amended, (HB 19-1172), ch. 136, p. 1728, § 252, effective October 1. L.
2020: IP(1) amended, (SB 20-136), ch. 70, p. 293, § 36, effective September
14. L. 2025: (1)(a) amended, (HB 25-1324), ch. 445, p. 2560, § 5,
effective June 4.
Cross
references: For
the legislative declaration in SB 20-136, see section 1 of chapter 70, Session
Laws of Colorado 2020.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments", see 15 Colo. Law. 798
(1986).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Evaluation of property
presumed correct. The evaluation of property for taxation, as determined by
the assessor, is presumed to be right. Stalder v. Bd. of County Comm'rs, 147
Colo. 493, 364 P.2d 389 (1961).
Standard of proof required
of taxpayer. Clear and convincing evidence is the degree of proof required
of a taxpayer to overcome the presumption that an assessment is correct.
Majestic Great W. Sav. & Loan Ass'n v. Reale, 30 Colo. App. 564, 499 P.2d
644 (1972).
It is not necessary to show an
assessment is manifestly excessive, fraudulent, or oppressive. Majestic Great
W. Sav. & Loan Ass'n v. Reale, 30 Colo. App. 564, 499 P.2d 644 (1972).
Prerequisites to appeal.
The appearance before the assessor under § 39-5-122 with "objection and
protest", which are then "refused or denied", is a prerequisite
to an appeal to the county board of equalization. Modular Cmtys., Inc. v.
McKnight, 36 Colo. App. 38, 536 P.2d 1168 (1975), aff'd, 191 Colo. 101, 550
P.2d 866 (1976).
"Petitioner"
refers to taxpayer. In this section and § 39-8-108, the term
"petitioner" refers to taxpayer. Adams County Bd. of County Comm'rs
v. Union P. R. R., 34 Colo. App. 156, 525 P.2d 1202 (1974).
This section and § 39-5-122
afford remedy at law. Section 39-5-122 and this section afford a plain,
speedy, and efficient remedy at law. Kortz v. Ellingson, 181 F. Supp. 857 (D.
Colo. 1960).
Effect of taxpayer's failure
to follow statutory remedy. If an assessment is erroneous, or excessive,
the right to relief can be lost through failure to pursue the proper statutory
remedy. Citizens' Comm. for Fair Prop. Taxation v. Warner, 127 Colo. 121, 254
P.2d 1005 (1953).
A party who fails to invoke the
remedy under this section cannot be heard to complain of errors in the
valuation of his property after a sale has been made and the tax deed issued.
Barnett v. Jaynes, 26 Colo. 279, 57 P. 703 (1899).
The law has provided a forum —
namely, the board of equalization — whose duty it is, at the instance of anyone
aggrieved, to correct errors in the assessment roll returned by the assessor.
Having failed to avail himself of the plain, speedy, and adequate remedy thus
afforded, to correct his assessment upon these grounds, or, at least, present
these questions to the board, he cannot resort to proceedings in certiorari for
that purpose. People ex rel. Hallett v. Bd. of Comm'rs, 27 Colo. 86, 59 P. 733 (1899).
Taxpayer may seek review at
each stage of decision-making process. It is evident from the provisions of
this section and § 39-8-108 that the general assembly contemplated that at each
stage of the decision-making process, the taxpayer could seek review of an
adverse decision. Adams County Bd. of County Comm'rs v. Union P. R. R., 34
Colo. App. 156, 525 P.2d 1202 (1974).
A party may seek review of
only the total valuation for assessment and not of the component parts of that
total. The statutes speak only of the right to appeal the value or the
valuation assessment set by the assessor. Notably absent from the statutes is
language that would permit a party to limit the scope of the protest by
appealing only a portion or component of the assessed value. Cherne v. Bd. of
Equaliz., 885 P.2d 258 (Colo. App. 1994).
Right to protest property
valuations is not limited to person who is owner of property on record as of
the first day of the tax year, and any person who is an owner of the
property for any portion of the assessment period has standing to protest such
valuations. Tenney v. Bd. of Assessment Appeals, 856 P.2d 89 (Colo. App. 1993).
Protest after meeting of
board is too late. A protest against an alleged erroneous assessment is too
late when made after the board of equalization has held its meetings. Miller v.
Bd. of County Comm'rs, 92 Colo. 425, 21 P.2d 714 (1933).
Jurisdiction of board of
county commissioners is plenary on review. In re Hover Motors, 120 Colo.
511, 212 P.2d 99 (1949).
Judicial review of decision
by state board of assessment appeals limited. Neither the county board of
commissioners nor the county assessor may seek judicial review of a decision by
the state board of assessment appeals. Adams County Bd. of County Comm'rs v.
Union P. R. R., 34 Colo. App. 156, 525 P.2d 1202 (1974).
Applied in Mardi, Inc.
v. City & County of Denver, 151 Colo. 28, 375 P.2d 682 (1962).
39-8-107. Hearings on appeal.
(1) (a)
At the hearing upon a petition, the assessor or the assessor's authorized
representative shall be present and shall produce information to support the
basis and amount of the assessor's valuation of the property. The board shall
hear and consider all testimony and examine all exhibits produced or introduced
by either the petitioner or the assessor, with no presumption in favor of any
pending valuation, and may subpoena witnesses to testify. The petitioner shall
pay the costs of producing the petitioner's witnesses, and the county shall pay
the costs of producing the assessor's witnesses. On the basis of the testimony
produced and the exhibits introduced, the board shall grant or deny the
petition, in whole or in part, and shall notify the petitioner and the assessor
in writing.
(b) (I)
If the board denies the petition, in whole or in part, the written notice must
inform the petitioner of the right to appeal the denial to the district court
or the board of assessment appeals pursuant to section 39-8-108 (1) or submit
the case to arbitration pursuant to section 39-8-108.5 no later than the later
of:
(A)
September 1;
(B)
December 1, in a county that uses an alternate protest and appeal procedure
pursuant to section 39-5-122.7; or
(C)
Thirty days after the entry of the denial, if the petitioner was notified
outside of the regular notification schedule described in section 39-5-121.
(II)
The notice must state that, if the appeal is to the board of assessment
appeals, the hearing before the board of assessment appeals will be the last
hearing at which testimony, exhibits, or any other type of evidence may be
introduced by either party and that, if there is an appeal to the court of
appeals pursuant to section 39-8-108 (2), the record from the hearing before
the board of assessment appeals and no new evidence will be the basis for the
court's decision. The phone number and address of the board of assessment
appeals must also be included on the notice. The notice must also state, in
general terms, how to pursue arbitration and that, if a taxpayer submits the
case to arbitration, the decision reached under such process will be final and
not subject to review. If a referee heard the case, the board shall, at the
written request of any taxpayer or any agent of such taxpayer within seven
working days after receipt of said request, make available to the taxpayer or
agent the referee's findings and recommendations. At the board's election, the
board may either mail, fax, or send by electronic transmission the findings and
recommendations of the referee to the address, phone number, or electronic
address supplied by said taxpayer or agent. Upon receipt of such request, the
board shall notify the taxpayer or agent of the estimated cost of providing the
findings and recommendations of the referee, payment of which must be made
prior to providing such findings and recommendations. Upon providing the
findings and recommendations of the referee, the board may include a bill for
the reasonable cost above the estimated cost and up to the statutory maximum
which is due and payable upon receipt by the taxpayer or agent.
(2) (a)
The county board of equalization shall continue its hearings from time to time
until all petitions have been heard, but all such hearings shall be concluded
and decisions rendered thereon by the close of business on August 5 of that
year; except that, in a county that uses an alternate protest and appeal
procedure pursuant to section 39-5-122.7, all such hearings shall be concluded
and decisions rendered thereon by the close of business on November 1 of that
year. Except as authorized in subsection (2)(b) of this section, any decision
shall be mailed to the petitioner within five business days of the date on
which such decision is rendered.
(b) A
board of county commissioners may authorize by resolution a petitioner or a
petitioner's agent to elect to receive the decision rendered by the board as
required in paragraph (a) of this subsection (2) by fax or electronic mail at a
phone number or electronic mail address supplied by the petitioner or the
petitioner's agent. If no election is made by the petitioner or the
petitioner's agent, the county board of equalization shall mail the decision.
(3) At
the written request of any taxpayer or any agent of a taxpayer and subject to
confidentiality requirements as provided by law, the assessor shall, within
three working days after receipt of a request, make available to the taxpayer
or agent the data used by the assessor in determining the actual value of any
property owned by a taxpayer. At the assessor's election, the assessor may
either mail, fax, or send by electronic transmission to the address, phone
number, or electronic address supplied by a taxpayer or agent any requested
data. The assessor shall provide to a taxpayer making the request the data
derived from the declarations filed pursuant to the provisions of article 14 of
this title 39, the primary method and rates used to value the property, and any
confidential data, provided that the confidential data is presented in such a
manner that the source cannot be identified. Upon receipt of the request, the
assessor shall notify the taxpayer or agent of the estimated cost of providing
the information, payment of which shall be made prior to providing the
information. Upon providing the information, the assessor may include a bill
for the reasonable cost above the estimated cost and up to the statutory
maximum which shall be due and payable upon receipt by the taxpayer or agent.
(4) The
assessor may not rely on any confidential information which is not available
for review by the taxpayer, unless such confidential data is presented in such
a manner that the source cannot be identified.
(5) (a)
(I) On and after August 10, 2011, in addition to any other requirements
under law, any petitioner appealing either a valuation of rent-producing
commercial real property to the board of assessment appeals pursuant to section
39-8-108 (1) or a denial of an abatement of taxes pursuant to section 39-10-114
shall provide to the county board of equalization or to the board of county
commissioners of the county in the case of an abatement, and not to the board
of assessment appeals, the following information, if applicable:
(A)
Property-specific actual annual rental income for two full years including the
base year for the relevant property tax year;
(B)
Property-specific tenant reimbursements for two full years including the base
year for the relevant property tax year;
(C)
Property-specific itemized expenses for two full years including the base year
for the relevant property tax year; and
(D)
Property-specific rent roll data as of the valuation date, including the name
of any tenants, the address, unit, or suite number of the subject property,
lease start and end dates, option terms, base rent, square footage leased, and
vacant space for two years including the year of the valuation date and the
prior year.
(II)
The petitioner shall provide the information required by subsection (5)(a)(I)
of this section within ninety days after the appeal has been filed with the
board of assessment appeals; except that a petitioner who has already provided
information to an assessor in accordance with section 39-5-122 (2.5) is not
required to provide any additional information under this subsection (5)(a).
(b) (I)
The assessor, the county board of equalization, or the board of county
commissioners of the county, as applicable, shall, upon request made by the
petitioner, provide to a petitioner who has filed an appeal with the board of
assessment appeals not more than ninety days after receipt of the petitioner's
request, the following information:
(A) The
primary method used by the county to determine the value of the subject
property; and
(B) The
rates used by the county to determine the value of the subject property under
the method identified in accordance with subsection (5)(b)(I)(A) of this
section.
(II)
The party providing the information to the petitioner pursuant to subparagraph
(I) of this paragraph (b) shall redact all confidential information contained
therein.
(c) If
a petitioner fails to provide the information required by subparagraph (I) of
paragraph (a) of this subsection (5) by the deadline specified in subparagraph
(II) of said paragraph (a), the county may move the board of assessment appeals
to compel disclosure and to issue appropriate sanctions for noncompliance with
such order. The motion may be made directly by the county attorney and shall be
accompanied by a certification that the county assessor or the county board of
equalization has in good faith conferred or attempted to confer with such
petitioner in an effort to obtain the information without action by the board
of assessment appeals. If an order compelling disclosure is issued under this
paragraph (c) and the petitioner fails to comply with such order, the board of
assessment appeals may make such orders in regard to the noncompliance as are
just and reasonable under the circumstances, including an order dismissing the
action or the entry of a judgment by default against the petitioner. Interest
due the taxpayer shall cease to accrue as of the date the order compelling
disclosure is issued, and the accrual of interest shall resume as of the date
the contested information has been provided by the taxpayer.
(d) In
the notice of determination, the county board of equalization shall inform a
taxpayer of the taxpayer's obligation to provide the information required by
paragraph (a) of this subsection (5).
(e) The
county board of equalization and the board of county commissioners receiving
any information provided by a petitioner pursuant to subparagraph (I) of
paragraph (a) of this subsection (5) that is exempt from disclosure under
either section 24-72-204 (3)(a)(IV), C.R.S., or another provision of the
"Colorado Open Records Act", part 2 of article 72 of title 24,
C.R.S., shall keep such information confidential; except that such information
may be disclosed to the administrator and the employees of his or her office,
the board of assessment appeals, the county board of equalization, the board of
county commissioners of the county in which the subject property is located,
the office of the county assessor, or a person retained to appraise or provide
value consultation in connection with the subject property where such
information is pertinent to an appeal.
(f)
Nothing in this subsection (5) shall be construed to apply to a public utility
whose valuation for property tax purposes is determined by the administrator in
accordance with the provisions of article 4 of this title.
(6)
Repealed.
Source:
L. 64: R&RE,
p. 713, § 1. C.R.S. 1963: § 137-8-5. L. 67: p. 951, § 22. L.
88: (1) amended, p. 1302, § 10, effective April 29. L. 89: (2)
amended, p. 1458, § 16, effective June 7. L. 90: (1) amended and (3) and
(4) added, pp. 1701, 1700, §§ 32, 30, effective June 9. L. 93: (2)
amended, p. 1689, § 7, effective June 6. L. 96: (1) amended, p. 722, §
6, effective May 22. L. 98: (2) amended, p. 470, § 6, effective July 1. L.
2000: (1) and (3) amended, p. 1501, § 6, effective August 2. L. 2011:
(5) added, (SB 11-119), ch. 130, p. 453, § 1, effective August 10. L. 2013:
(6) added, (HB 13-1113), ch. 11, p. 32, § 6, effective March 8. L. 2016:
(2) amended, (SB 16-172), ch. 280, p. 1149, § 3, effective June 10. L. 2019:
(5)(a)(I)(D), (5)(a)(II), and (5)(b)(I) amended, (HB 19-1175), ch. 43, p. 148,
§ 2, effective March 21. L. 2020: (6) repealed, (SB 20-136), ch. 70, p.
293, § 37, effective September 14. L. 2023: (3) amended, (SB 23-304),
ch. 259, p. 1497, § 3, effective August 7. L. 2025: (2)(a) amended, (HB
25-1324), ch. 445, p. 2560, § 6, effective June 4. L. 2026: (1) amended,
(SB 26-046), ch. 10, p. 48, § 15, effective August 12; (1) and (5)(a)(I)
amended, (HB 26-1233), ch. 360, p. 2165, § 2, effective August 12.
Editor's
note: Amendments
to subsection (1) by SB 26-046 and HB 26-1233 were harmonized.
Cross
references: For
the legislative declaration in SB 20-136, see section 1 of chapter 70, Session
Laws of Colorado 2020.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments", see 15 Colo. Law. 798
(1986).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Board's hearings are
quasi-judicial. The board of equalization hearings, as distinguished from
an assessor's search for pertinent information, though generally informally
conducted, are quasi-judicial. May Stores Shopping Centers, Inc. v. Shoemaker,
151 Colo. 100, 376 P.2d 679 (1962).
Its decisions must be based
on proper evidence. Hearings before the board of equalization and decisions
must be based on evidence properly before it. May Stores Shopping Centers, Inc.
v. Shoemaker, 151 Colo. 100, 376 P.2d 679 (1962).
Proceedings before the board
of assessment appeals are de novo in nature and an appeal of a
classification decision of the board is thus limited to review of the propriety
of the board's classification decision without regard to the prior decision of
the county assessor. Johnston v. Park County Bd. of Equaliz., 979 P.2d 578 (Colo.
App. 1999).
Records must be kept of
proceedings by the board of equalization and decisions must be based upon
the evidence properly before the board. May Stores Shopping Centers, Inc. v.
Shoemaker, 151 Colo. 100, 376 P.2d 679 (1962).
Section does not require
board to issue formal findings of fact or conclusions of law. Carrara Place
v. Bd. of Equaliz., 761 P.2d 197 (Colo. 1988).
Secret or informal hearings
or meetings with assessor cannot be basis of a board of equalization's
actions. May Stores Shopping Centers, Inc. v. Shoemaker, 151 Colo. 100, 376
P.2d 679 (1962).
Subsection (2) requires that
the board's decision be mailed only to the taxpayer. While it may be the
common and better practice to notify an agent appearing for the taxpayer, the
board nevertheless complied with this requirement upon mailing its decision
directly to the taxpayer at the taxpayer's address of record. Tri-Havana LLC v.
Arapahoe County Bd. of Equaliz., 961 P.2d 604 (Colo. App. 1998).
Timely commencement of
action. Assessor and his successors in office were necessary and proper
parties to proceedings before the board of equalization and thus were proper
parties to the trial de novo in district court, and plaintiffs, by joining the
same party-opponents who had been involved in the proceedings before the board,
commenced their action in a timely manner. B.C., Limited, et al. v. Krinhop,
815 P.2d 1016 (Colo. App. 1991).
Board's failure to act
within time limits prescribed in subsection (2) did not invalidate the board's
actions where taxpayers' rights were not abridged. Wenner v. Bd. of
Assessment Appeals, 866 P.2d 172 (Colo. App. 1993).
A board of equalization
(BOE) board member may not be called in a proceeding before the board of
assessment appeals (BAA) to explain a BOE decision, or how it was reached,
in the absence of a clear showing of illegal or unlawful action, misconduct,
bias, or bad faith on the part of the decision makers. Gilpin County BOE v.
Russell, 941 P.2d 257 (Colo. 1997).
A BOE board member's
testimony at a BAA proceeding is barred by the mental process rule. Gilpin
County BOE v. Russell, 941 P.2d 257 (Colo. 1997).
Applied in Majestic
Great W. Sav. & Loan Ass'n v. Reale, 30 Colo. App. 564, 499 P.2d 644
(1972).
39-8-108. Decision - review -
opportunity to submit case to arbitration.
(1) (a)
If the county board of equalization grants a petition, in whole or in part, the
assessor shall adjust the valuation accordingly; but, if the petition is
denied, in whole or in part, the petitioner may appeal the valuation set by the
assessor or, if the valuation is adjusted as a result of a decision of the
county board of equalization, the adjusted valuation to the board of assessment
appeals or to the district court of the county wherein the petitioner's
property is located for a trial de novo, or the petitioner may submit the case
to arbitration pursuant to the provisions of section 39-8-108.5. Such appeal or
submission to arbitration must be taken no later than the later of:
(I)
September 1;
(II)
December 1, in a county that uses an alternate protest and appeal procedure
pursuant to section 39-5-122.7; or
(III)
Thirty days after the date the denial was mailed pursuant to section 39-8-107
(2), if the petitioner was notified outside of the regular notification
schedule described in section 39-5-121.
(b) Any
decision rendered by the county board of equalization must state that the
petitioner has the right to appeal the decision of the county board to the
board of assessment appeals or to the district court of the county wherein the
petitioner's property is located or to submit the case to arbitration and, to
preserve such right, the time by which such appeal or submission to arbitration
must be made. Any request by a taxpayer for a hearing before the board of
assessment appeals must be accompanied by a nonrefundable filing fee in an
amount specified in section 39-2-125 (1)(h). In addition, any request by a
taxpayer for a hearing before the board of assessment appeals must be stamped
with the date on which such request was received by the board. All such
requests are presumed to be on time unless the board can present evidence to
show otherwise.
(c) For
property tax years commencing on or after January 1, 2027, if a nonresidential
property owner appeals a decision to the board of assessment appeals pursuant
to subsection (1)(a) of this section, the governing body of the county may file
a motion with the board of assessment appeals noting the county's preference
that the case be heard in the district court of the county in which the
property is located. The county must file its motion within forty-two days
after the filing of the petition with the board of assessment appeals. The
petitioner must respond with their election within twenty-one days after the
county's motion. The filing of such a motion does not alter the venue of the
case, and the board of assessment appeals retains jurisdiction unless the
petitioner elects to withdraw the appeal and file in district court pursuant to
applicable law.
(2) If
the petitioner has appealed to the board of assessment appeals and the decision
of the board of assessment appeals is against the petitioner, the petitioner
may petition the court of appeals for judicial review according to the Colorado
appellate rules and the provisions of section 24-4-106 (11), C.R.S. If the
decision of the board is against the respondent, the respondent, upon the
recommendation of the board that it either is a matter of statewide concern or
has resulted in a significant decrease in the total valuation of the respondent
county, may petition the court of appeals for judicial review according to the
Colorado appellate rules and the provisions of section 24-4-106 (11), C.R.S. In
addition, on and after June 7, 1989, if the decision of the board is against
the respondent, the respondent may petition the court of appeals for judicial
review of alleged procedural errors or errors of law within thirty days of such
decision when the respondent alleges procedural errors or errors of law by the
board of assessment appeals. If the board does not recommend its decision to be
a matter of statewide concern or to have resulted in a significant decrease in
the total valuation of the respondent county, the respondent may petition the
court of appeals for judicial review of such questions within thirty days of
such decision. Any decision issued by the board of assessment appeals shall
inform the petitioner or respondent, as may be appropriate, of the right to
petition the court of appeals for judicial review.
(3) If
the decision of the county board of equalization has been appealed to the
district court, the decision of the court shall be subject to appellate review
according to the Colorado appellate rules and the provisions of section
24-4-106 (9), C.R.S.
(4) If
the taxpayer submits his case to arbitration pursuant to the provisions of
section 39-8-108.5, the decision reached under such process shall be final and
not subject to review.
(5) In
any appeal authorized by this section or by section 39-5-122, 39-5-122.7, or
39-10-114:
(a)
Repealed.
(a.5)
The valuation may not be adjusted to a value of more than five percent above
the valuation set by the county board of equalization pursuant to section
39-8-107, except as specifically permitted pursuant to section 39-5-125;
(b) The
assessor's valuation of similar property similarly situated shall be credible
evidence;
(c) The
respondent may not rely on any confidential information which is not available
for review by the taxpayer unless such confidential data is presented in such a
manner that the source cannot be identified;
(d)
Upon request, the respondent shall make available to the taxpayer two working
days prior to any appeal hearing data supporting the assessor's valuation. Such
request shall be accompanied by data supporting the taxpayer's valuation.
Nothing in this subsection (5)(d) shall be construed to prohibit the
introduction at such appeal hearing of any data discovered as a result of the
exchange of data required by this subsection (5)(d);
(e) In
using the market approach to determine the value of residential real property,
if the assessor has knowledge of the conversion from one residential use to a
different residential use, such conversion shall create a rebuttable
presumption that the sale of such property is not a comparable sale for
purposes of establishing the value of a property having a similar prior
residential use.
(6) In
any appeal or submission to arbitration authorized by this section, there shall
be no presumption in favor of any pending valuation.
Source:
L. 64: R&RE,
p. 713, § 1. C.R.S. 1963: § 137-8-6. L. 70: p. 386, § 23. L.
77: (2) amended, p. 1736, § 19, effective June 20. L. 83: (2)
amended, p. 2087, § 5, effective October 13. L. 85: Entire section
amended and (2) amended, pp. 1228, 1230, §§ 2, 1, effective July 1. L. 88:
(1) and (2) amended, (3) R&RE, and (4) added, pp. 1302, 1303, §§ 11, 12,
effective April 29. L. 89: (1) and (2) amended, p. 1458, § 17, effective
June 7. L. 90: (2) amended and (5) added, pp. 1694, 1700, §§ 13, 31,
effective June 9. L. 92: (1), (2), and (5)(d) amended, p. 2210, § 8,
effective June 3. L. 96: (1), (2), and (5)(a) amended and (6) added, p.
723, § 7, effective May 22. L. 2002: IP(5) amended and (5)(e) added, p.
843, § 4, effective August 7. L. 2003: (1) amended, p. 1467, § 4,
effective July 1. L. 2021: (5)(a) repealed, (HB 21-1083), ch. 25, p.
112, § 1, effective April 7. L. 2022: (5)(a.5) added, (HB 22-1416), ch.
158, p. 1000, § 6, effective August 10. L. 2026: (1) amended, (SB
26-046), ch. 10, p. 49, § 16, effective August 12; (1) and (5)(d) amended, (HB
26-1233), ch. 360, p. 2166, § 3, effective August 12.
Editor's
note: (1)
Amendments to subsection (2) by House Bill 85-1106 and Senate Bill 85-85 were
harmonized.
(2) Amendments to subsection
(1) by SB 26-046 and HB 26-1233 were harmonized.
Cross
references: For
right to judicial review under the "State Administrative Procedure
Act", see § 24-4-106.
ANNOTATION
Law reviews. For
article, "Appealing Property Tax Assessments", see 15 Colo. Law. 798
(1986).
"Petitioner"
refers to taxpayer. In § 39-8-106 and this section, the term
"petitioner" refers to taxpayer. Adams County Bd. of County Comm'rs
v. Union P. R. R., 34 Colo. App. 156, 525 P.2d 1202 (1974).
Subsection (2) expressly
authorizes a county board of equalization to seek judicial review of procedural
errors or errors of law made by the board of assessment appeals. A board of
equalization is the "respondent" in proceedings before the board of
assessment appeals. SecurityLink from Ameritech, Inc. v. City & County of
Denver, 32 P.3d 499 (Colo. App. 2000).
The board of equalization
may seek judicial review of a decision of the board of assessment appeals
within 45 days of the final order, but only if the board of assessment
appeals recommended that the case involved an issue of statewide concern or
that the ruling would result in a significant decrease in the total valuation
of the count. Absent such a recommendation, the board of equalization was
required to seek judicial review within 30 days of the final order. Steamboat
Ski & Resort Corp. v. Routt County Bd. of Equaliz., 23 P.3d 1258 (Colo.
App. 2001).
Property tax valuation
challenge. A taxpayer has the statutory right to challenge a property tax
valuation for each tax year under the protest and adjustment procedure and
possibly through de novo evidentiary proceedings before the board of assessment
appeals. Weingarten v. Bd. of Assess. Appeals, 876 P.2d 118 (Colo. App. 1994).
Taxpayer may seek review at
each stage of decision-making process. It is evident from § 39-8-106 and
this section that the general assembly contemplated that at each stage of the
decision-making process the taxpayer could seek review of an adverse decision.
Adams County Bd. of County Comm'rs v. Union P. R. R., 34 Colo. App. 156, 525
P.2d 1202 (1974).
Lessee does not have
standing to challenge a property tax valuation of leased property. Traer
Creek-EXWMT LLC v. Eagle County Bd. of Equaliz., 2017 COA 16, 401 P.3d 569.
A party may seek review of
only the total valuation for assessment and not of the component parts of that
total. The statutes speak only of the right to appeal the value or the
valuation assessment set by the assessor. Notably absent from the statutes is
language that would permit a party to limit the scope of the protest by
appealing only a portion or component of the assessed value. Cherne v. Bd. of
Equaliz., 885 P.2d 258 (Colo. App. 1994).
Joinder of indispensable
parties. Part of the perfection of an action for judicial review includes
the joinder of indispensable parties. Cissell v. Bd. of Assess. Appeals, 38
Colo. App. 560, 564 P.2d 124 (1977).
Statute specifying judicial
review in the district court of the county in which the property is located
applies only when, prior to payment of any taxes, the taxpayer seeks an
adjustment of taxes assessed against property and is not applicable when the
taxpayer has paid taxes on property and proceeds for a tax refund. Gunnison
County v. Bd. of Assess. Appeals, 693 P.2d 400 (Colo. App. 1984).
Subsection (2) limits
judicial review to certain specific circumstances. Where the case does not
involve a matter of statewide concern or result in a significant decrease in
the total assessed valuation of the taxing entity, and the board of assessment
appeals' ruling is supported by the evidence, no judicial review is authorized.
Denver v. Bd. of Assess. Appeals, 802 P.2d 1109 (Colo. App. 1990).
1989 amendment to statutory
appeal procedures demonstrated intent of general assembly to expand
circumstances under which taxing authority may initiate an appeal of an adverse
decision of the board of assessment appeals. Farny v. Bd. of Equaliz., 985 P.2d
106 (Colo. App. 1999).
A claim that evidence is
legally insufficient to support the board's decision is a claim based on an
alleged "error of law" and is appealable by the taxing authority to
the court of appeals pursuant to subsection (2). Farny v. Bd. of Equaliz., 985
P.2d 106 (Colo. App. 1999).
A failure by the board to
apply the correct legal standards or to abide by the statutory scheme would
constitute an error reviewable by the court. Clarke v. Douglas County Bd.
of Equaliz., 899 P.2d 240 (Colo. App. 1994), rev'd on other grounds, 921 P.2d
717 (Colo. 1996).
Section does not give state
property tax administrator the right to appeal from adverse decisions
pertaining to exemption from taxes. Maurer v. Young Life, 751 P.2d 653 (Colo.
App. 1987), aff'd in part, rev'd in part on other grounds, 779 P.2d 1317 (Colo.
1989); Maurer v. Loyal Order of Moose Lodge, 779 P.2d 1345 (Colo. 1989).
Taxpayer failed to preserve
property-classification issue for review when he did not appeal or
cross-appeal from board of assessment appeals' ruling on that issue. Gyurman v.
Weld County Bd. of Equaliz., 851 P.2d 307 (Colo. App. 1993).
Thirty-day time limit for
filing appeal with the board of assessment appeals begins to run on the date of
the mailing of the board of equalization's decision directly to the taxpayer.
Tri-Havana LLC v. Arapahoe County Bd. of Equaliz., 961 P.2d 604 (Colo. App.
1998).
Thirty-day time limit for
filing appeal with court of appeals in tax assessment cases is applicable
only if initial appeal was made directly to district court with no intervening
appeal to state board of assessment appeals. Denver v. Bd. of Assess. Appeals,
748 P.2d 1306 (Colo. App. 1987).
Apart from timely filing
requirement, there are no other statutory jurisdictional requirements for
taking administrative appeals before the board of assessment appeals.
Fleisher-Smyth v. Bd. of Assess. App., 865 P.2d 922 (Colo. App. 1993).
Proceedings before the board
of assessment appeals are de novo in nature and an appeal of a
classification decision of the board is thus limited to review of the propriety
of the board's classification decision without regard to the prior decision of
the county assessor. Johnston v. Park County Bd. of Equaliz., 979 P.2d 578 (Colo.
App. 1999).
Trial de novo under this
section does not mean review but means an entirely independent
determination of the facts. Arapahoe P'ship v. Bd. of County Comm'rs, 813 P.2d
766 (Colo. App. 1990).
Taxpayers protesting a tax
assessment in the trial de novo must prove by a preponderance of the evidence
that the assessment is incorrect. Arapahoe P'ship v. Bd. of County Comm'rs,
813 P.2d 766 (Colo. App. 1990).
The board of assessment
appeals is not bound by any valuation methodology or results from a prior
ruling valuing the taxpayer's property. Lawrence v. Bd. of Equaliz., 989
P.2d 232 (Colo. App. 1999).
The board of equalization
was a necessary party to de novo proceedings in district court, but
dismissal of the action was not the appropriate remedy for nonjoinder of the
board; rather the court should join the necessary party or allow plaintiff an
opportunity to do so. B.C., Ltd. v. Krinhop, 815 P.2d 1016 (Colo. App. 1991).
Dismissal without prejudice
of appeal for trial de novo may constitute a final, appealable order if,
during the pendency of the appeal, a limitations period has expired and the
case may not be refiled because it is time-barred. Wyler/Pebble Creek Ranch v.
Colo. Bd. of Assess. Appeals, 883 P.2d 597 (Colo. App. 1994).
Trial court's consideration
of assessor's reference library, consisting of manuals and directives, was
not inconsistent with the conduct of a trial de novo. Amax v. Grand County Bd.
of Equaliz., 892 P.2d 409 (Colo. App. 1994), rev'd on other grounds sub nom.
Huddleston v. Grand County Bd. of Equaliz., 913 P.2d 15 (Colo. 1996).
Protest and adjustment
procedures are separate and independent from abatement and refund procedures.
An appeal for a trial de novo under this section is not an "alternate
petition" for abatement or refund under § 39-10-114 (1)(a)(I).
Wyler/Pebble Creek Ranch v. Colo. Bd. of Assess. Appeals, 883 P.2d 597 (Colo.
App. 1994).
Applied in BA Leasing
Corp. v. Bd. of Assess. Appeals, 653 P.2d 80 (Colo. App. 1982); Laredo Hous.
Apts., Ltd. v. Bd. of Assm't. Appeals, 675 P.2d 23 (Colo. App. 1983); Arapahoe
Cty. Bd. of Equaliz. v. Podoll, 935 P.2d 14 (Colo. 1997).
39-8-108.5. Arbitration of property
valuations - arbitrators - qualifications - procedures.
(1) (a)
In order to give taxpayers an alternative to pursuing an appeal of the county
board of equalization's decision through either the board of assessment appeals
or the district court, an arbitration process shall be established. The board
of county commissioners shall develop a list of persons who shall be qualified
to act as arbitrators of property valuation disputes. Such list shall be kept
in the office of the county clerk and recorder.
(b)
Except as otherwise provided in subsection (1)(c) of this section, persons on
the list maintained pursuant to subsection (1)(a) of this section must be, in
addition to any other qualifications deemed necessary by the board, experienced
in the area of property taxation and licensed or certificated pursuant to part
6 of article 10 of title 12.
(c) No
person shall act as an arbitrator of property valuation disputes in any county
during any property tax year in which such person represents or has represented
any taxpayer in any matter relating to the protest and appeal of property
valuation or to the abatement or refund of property taxes.
(2) (a)
(I) Any taxpayer who plans to pursue arbitration shall notify the board of
the taxpayer's intent no later than the later of:
(A)
September 1;
(B)
December 1, in a county that uses an alternate protest and appeal procedure
pursuant to section 39-5-122.7; or
(C)
Thirty days after the county board of equalization's decision, if the taxpayer
was notified outside of the regular notification schedule described in section
39-5-121.
(II)
The taxpayer and the county board of equalization shall select an arbitrator
from the list prepared pursuant to subsection (1) of this section within
fifteen days of the notice of the taxpayer's intent to pursue arbitration or
within thirty days from the date the list of arbitrators is made available in
any given year, whichever is later. In the absence of agreement by the taxpayer
and the county board of equalization within said specified time period, the
district court of the county in which the property is located shall select an
arbitrator from said list.
(b) If
a taxpayer acts pursuant to paragraph (a) of this subsection (2), the county
board of equalization shall be required to participate in arbitration and to
accept the arbitrator selected.
(3) (a)
Arbitration hearings shall be at a time and place set by the arbitrator with
the mutual consent of the taxpayer and the county board of equalization. The
arbitration hearing shall be held within sixty days from the date the
arbitrator was selected.
(b)
Procedure at arbitration hearings shall be informal, and strict rules of
evidence shall not be applied except as necessitated in the opinion of the
arbitrator by the requirements of justice. All questions of law and fact shall
be determined by the arbitrator.
(b.5)
The taxpayer shall produce information to support his contention that the
property should be valued differently. The assessor shall produce information
to support the basis and amount of his valuation of the property. Both the
information of the assessor and the information of the taxpayer shall be
considered by the arbitrator in making his decision.
(c) The
arbitrator may issue or cause to be issued subpoenas for the attendance of
witnesses and for the production of books, records, documents, and other
evidence and shall have the power to administer oaths. Subpoenas so issued
shall be served and, upon application to the district court by the taxpayer or
the county board of equalization or the arbitrator, enforced in the manner
provided by law for the service and enforcement of subpoenas in civil actions.
(d) The
taxpayer and the county board of equalization shall be entitled to attend,
personally or with counsel, and participate in the proceedings. Such
participation may include the filing of briefs and affidavits. Upon agreement
of both parties, the proceedings may be confidential and closed to the public.
(e) No
record of the proceedings is required.
(f) The
arbitrator's decision shall be made in accordance with applicable Colorado
property tax laws. The arbitrator's decision shall be in writing and signed by
the arbitrator.
(g) The
arbitrator shall deliver a copy of his decision to the parties personally or by
registered mail within ten days of the hearing. Such decision shall be final
and not subject to review.
(4) An
arbitrator shall be immune from civil liability arising from participation as
an arbitrator and for all communications, findings, opinions, and conclusions
made in the course of his duties under this section.
(5) (a)
An arbitrator's expenses and fees shall not exceed one hundred fifty dollars
per case concerning residential real property. For cases concerning any taxable
property other than residential real property, an arbitrator's expenses and
fees shall be an amount agreed upon by the taxpayer and the county board of
equalization.
(b) The
arbitrator's fees and expenses, not including counsel fees, incurred in the
conduct of the arbitration shall be paid as provided in the decision.
(6) Any
decision of the county board of equalization regarding a 1987 property
valuation which has been appealed to either the board of assessment appeals or
the district court and which has not been heard or adjudicated may be submitted
to arbitration pursuant to this section at the request of the taxpayer.
Source:
L. 88: Entire
section added, p. 1303, § 13, effective April 29; (6) amended, p. 1274, § 11,
effective May 29. L. 90: (3)(b.5) added and (3)(f) amended, p. 1697, §
23, effective June 9. L. 92: IP(1)(b) and (2)(a) amended and (1)(c)
added, p. 2212, § 9, effective June 3. L. 2013: IP(1)(b) amended, (SB
13-155), ch. 392, p. 2284, § 16, effective July 1. L. 2014: (1)(b)
amended, (SB 14-080), ch. 89, p. 336, § 1, effective August 6. L. 2019:
(1)(b) amended, (HB 19-1172), ch. 136, p. 1729, § 253, effective October 1. L.
2026: (2)(a) amended, (SB 26-046), ch. 10, p. 50, § 17, effective August
12.
39-8-108.7. Review of decision - effect
of stipulation by taxpayer - repeal. (Repealed)
Source:
L. 88: Entire
section added, p. 1274, § 10, effective May 29.
Editor's
note: Subsection
(2) provided for the repeal of this section, effective July 1, 1989. (See L.
88, p. 1274.)
39-8-109. Effects of board of
assessment appeals or district court decision.
(1) If
upon appeal the appellant is sustained, in whole or in part, then the appellant
shall provide a copy of the order or judgment of the board of assessment
appeals or district court, as the case may be, to the county assessor. If the
order or judgment has been appealed, then the appellant shall present to the
county assessor a copy of the original order or judgment of the board of
assessment appeals or district court and copies of all further decisions of the
board of assessment appeals, district court, court of appeals, and supreme
court. Upon presentation to the treasurer by the county assessor of a copy of
the order or judgment of the board of assessment appeals or district court, as
the case may be, and, if the case has been appealed, copies of all further
decisions of the board of assessment appeals, district court, court of appeals,
and supreme court, modifying the valuation for assessment of the property, the
appellant, identified as the petitioner or plaintiff on the order or judgment
of the board of assessment appeals or district court, shall forthwith receive
the appropriate refund of taxes and delinquent interest thereon, together with
refund interest at the same rate as delinquent interest as specified in section
39-10-104.5. Such refund interest shall only accrue from the date on which
payment of taxes and delinquent interest thereon was received by the treasurer.
Such refund shall be paid to the appellant even if the appellant is not the
current owner of the property. The appellant and the county shall each be
responsible for their respective costs in said court or board of assessment
appeals, as the case may be.
(2) In
the event that the treasurer refunds taxes and interest to the appellant based
on a modification of the valuation for assessment of the property pursuant to
subsection (1) of this section, the treasurer shall be entitled to
reimbursement for the refund of taxes and interest pro rata by all
jurisdictions receiving payment thereof and may request reimbursement from the
jurisdictions or offset the reimbursements against subsequent payments. The
provisions of this subsection (2) shall not apply to a city and county.
Source:
L. 64: R&RE,
p. 713, § 1. C.R.S. 1963: § 137-8-7. L. 70: p. 386, § 24. L.
89: Entire section amended, p. 1466, § 32, effective June 7. L. 90:
Entire section amended, p. 1719, § 7, effective June 7; entire section amended,
p. 1087, § 55, effective July 1. L. 92: Entire section amended, p. 2224,
§ 7, effective April 9; entire section amended, p. 2185, § 67, effective June
2. L. 93: Entire section amended, p. 306, § 6, effective April 7. L.
2002: Entire section amended, p. 843, § 5, effective August 7. L. 2005:
Entire section amended, p. 153, § 1, effective April 5. L. 2008: Entire
section amended, p. 1247, § 6, effective August 5. L. 2010: (1) amended,
(SB 10-138), ch. 155, p. 533, § 1, effective August 11.
ANNOTATION
When refund of taxes sought.
When a taxpayer's appeal of the imposition of an increased tax on his property
is sustained and the board or court's decision occurs after the challenged
property tax is due, §§ 39-1-113 and 39-10-114 apply to the refund of taxes
paid under this section. Bd. of Assess. Appeals v. Benbrook, 735 P.2d 860
(Colo. 1987).
When appeal is brought under
§ 39-8-101 et seq., this section provides that the taxpayer receive a
refund together with interest thereon at the rate of 6% per annum. B.A. Leasing
Corp. v. State Bd. of Equal., 745 P.2d 254 (Colo. App. 1987), aff'd sub nom.
Gates Rubber Co. v. Bd. of Equalization, 770 P.2d 1189 (Colo. 1989).
Whether or not to award
costs to a successful appellant remains within the discretionary powers of the
board of assessment appeals. Jefferson County Bd. of Equaliz. v. Gerganoff,
241 P.3d 932 (Colo. 2010).
Applied in Am.
Mobilehome Ass'n v. Dolan, 191 Colo. 433, 553 P.2d 758 (1976).
ARTICLE
9
State
Board of Equalization
39-9-101. State board of equalization.
39-9-102. Meetings of state board of
equalization.
39-9-103. Duties of state board - enforcement
- reappraisal orders.
39-9-104. Correction of errors.
39-9-105. Certification of valuations for
assessment.
39-9-106. Supervision and administration of
property tax laws.
39-9-107. Assessment roll to conform.
39-9-108. Judicial review - interest during
review.
39-9-109. Power of state board - waiver of
deadline.
39-9-101. State board of equalization.
(1) The
state board of equalization shall consist of the governor or his designee, the
speaker of the house of representatives or his designee, the president of the
senate or his designee, and two members appointed by the governor with the
consent of the senate. Each of the appointed members shall be a qualified
appraiser or a former assessor or a person who has knowledge and experience in
property taxation. Said board shall elect a chairman and a vice-chairman; the
vice-chairman shall act as chairman in the absence of the chairman.
(2)
Except as otherwise provided in section 2-2-326, each member is entitled to
receive a per diem allowance of fifty dollars for each day spent attending
meetings or hearings of the state board of equalization or otherwise spent
discharging the member's duties as a member of the board; except that a member
shall not receive the per diem allowance provided for in this subsection (2)
for any day for which the member receives a per diem allowance from the state
under any other statute and except that a member shall not receive the per diem
allowance provided for in this subsection (2) if the member receives a salary
from the state for a full-time position with the state. Except as otherwise
provided in section 2-2-326, each member of the board is entitled to receive
reimbursement for actual and necessary expenses incurred in performing the
member's duties as a member of the board. The members appointed by the governor
serve at the pleasure of the governor but shall not serve for more than four
consecutive years unless reappointed by the governor and reconfirmed by the
senate at the conclusion of the four years. Vacancies in either of the
appointed positions on the board shall be filled by appointment by the governor
with the consent of the senate for the unexpired term.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-9-1. L. 83: Entire section
amended, p. 1504, § 1, effective June 2. L. 2014: (2) amended, (SB
14-153), ch. 390, p. 1965, § 29, effective June 6. L. 2022: (2) amended,
(SB 22-013), ch. 2, p. 87, § 116, effective February 25. L. 2023: (2)
amended, (HB 23-1301), ch. 303, p. 1843, § 85, effective August 7.
Cross
references: For
constitutional grant of powers to the state board of equalization, see § 15 of
article X of the state constitution.
39-9-102. Meetings of state board of
equalization.
(1) The
state board of equalization shall meet at a place designated by the chairman,
at such times as the chairman may deem necessary.
(2) All
sessions of said board shall be conducted in public, and a full and correct
record of its proceedings shall be kept, which record shall be a public
document and available for public inspection. Opportunity shall be afforded any
person to appear before said board to present facts and information for its
consideration.
(3) Two
weeks before each meeting of the state board of equalization, a news release
stating the time and location of the meeting shall be sent throughout the state
to radio stations, television stations, and newspapers of general circulation.
Not later than two weeks before each meeting, the board shall also mail notice
to each assessor and board of county commissioners of a county with regard to
the nature of any action it may take pertaining to current year valuations for
assessment.
Source:
L. 64: R&RE,
p. 714, § 1. C.R.S. 1963: § 137-9-2. L. 76: (3) added, p. 763, §
28, effective January 1, 1977. L. 83: (1) amended, p. 2092, § 2,
effective September 23. L. 84: (3) amended, p. 1001, § 2, effective
March 5. L. 86: (1) amended, p. 1102, § 4, effective March 26.
ANNOTATION
Law reviews. For
article, "A Calendar of Tax Procedure in Colorado", see 6 Dicta 17
(July 1929).
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Statutory provisions
mandatory. Boards of equalization are solely creatures of statute, and,
when it is provided that they must meet at a certain time and place and
complete the equalization by a certain day, it means exactly what it says; and
they lack jurisdiction in acting in violation thereof. Holly Sugar Corp. v. Bd.
of Comm'rs, 10 F.2d 506 (8th Cir. 1926).
Public nature of hearings
does not mean public may participate in all deliberations. The requirement
that the proceedings be held in public is much like that which compels a judge
to conduct business in open court. He is not compelled to allow the public to
participate in his deliberations. People ex rel. State Bd. of Equaliz. v.
Hively, 139 Colo. 49, 336 P.2d 721 (1959).
Board may consider any type
of evidence. In the absence of a statutory mandate, boards of equalization
are not required to examine witnesses, or base their action upon any particular
kind of evidence, but may proceed in their own way, and upon any information
satisfactory to them. Holly Sugar Corp. v. Bd. of Comm'rs, 10 F.2d 506 (D.
Colo. 1926).
39-9-103. Duties of state board -
enforcement - reappraisal orders.
(1) The
state board of equalization shall order reappraisals of classes as provided in
section 39-1-105.5, make other orders as provided in said section, and perform
such other duties as are provided for in said section.
(2) The
state board of equalization shall conduct hearings on petitions filed by the
administrator for the reappraisal of one or more classes or subclasses of
taxable property pursuant to section 39-2-114. The state board of equalization
shall also conduct hearings upon complaints filed by the administrator, upon
his own motion or upon petition by any tax-levying authority in this state,
concerning valuation for assessment of one or more classes or subclasses of
taxable property if a reappraisal has not been conducted or ordered pursuant to
the provisions of section 39-2-114. Decisions of the state board of
equalization shall be subject to judicial review as provided in section
24-4-106, C.R.S.
(3)
Said board may compel compliance with its orders by proceedings in the nature
of mandamus, by injunction, or by other appropriate civil remedies.
(4) It
is the duty of the state board of equalization to examine and review the
valuations for assessment of taxes upon the various classes and subclasses of
taxable real and personal property located in the several counties of the state
as reflected in the abstract of assessment of each county, the decisions of the
board of assessment appeals, the recommendations of the administrator, and,
effective January 1, 1983, the study conducted by the director of research of
the legislative council pursuant to section 39-1-104 (16).
(5) The
decisions of the board of assessment appeals which affect the valuation of
classes or subclasses of property may be reversed or modified by the state
board of equalization, and such action shall be taken only if a written appeal
has, within thirty days of the board of assessment appeals' decision, been
lodged with the state board of equalization by one of the parties to the
proceedings before the board of assessment appeals. Decisions of the state
board of equalization shall be subject to judicial review as provided in
section 24-4-106, C.R.S.
(6) The
state board of equalization shall conduct hearings upon complaints filed by the
property tax administrator, upon his own motion or upon petition by any
tax-levying authority in this state, concerning alleged dereliction of duty on
the part of a county assessor.
(7) The
state board of equalization shall review abstracts of assessment and may, by
order, change the valuation for assessment of any class or subclass of property
which was changed by a county board of equalization.
(8) The
state board of equalization may promulgate such rules and regulations as are
necessary for the implementation of its duties and responsibilities. Such rules
and regulations shall be promulgated pursuant to and be subject to the
provisions of section 24-4-103, C.R.S.
(9)
Repealed.
(10)
(a) It is the function of the state board of equalization and it shall have
and exercise the authority, prior to publication but subsequent to review by
the advisory committee to the property tax administrator pursuant to section
39-2-131 (1), to review and approve or disapprove, within thirty days after
receipt from said advisory committee to the property tax administrator:
(I)
Manuals or any part thereof, appraisal procedures, instructions, and guidelines
prepared and published by the administrator pursuant to section 39-2-109 (1)(e)
and based upon the approaches to appraisal set forth in section 39-1-103 (5)(a)
and pursuant to section 39-2-109 (1)(k); and
(II)
Forms, notices, and records approved or prescribed pursuant to the authority of
the property tax administrator set forth in section 39-2-109 (1)(d).
(b) Any
manuals, appraisal procedures, instructions, guidelines, forms, notices, or
records which are not approved or disapproved by the state board of
equalization within said thirty days shall be automatically approved; except
that, if within said thirty days the state board of equalization schedules a
hearing on such manuals, appraisal procedures, instructions, guidelines, forms,
notices, or records, such automatic approval shall not occur unless the state
board of equalization does not approve or disapprove such manuals, appraisal
procedures, instructions, guidelines, forms, notices, or records within thirty
days after the conclusion of such hearing.
Source:
L. 64: R&RE,
p. 714, § 1. C.R.S. 1963: § 137-9-3. L. 70: p. 386, § 25. L.
76: (5) added, p. 763, § 29, effective June 10. L. 77: (3) amended,
(5) R&RE, and (6), (7), and (8) added, pp. 1736, 1738, §§ 20, 21, effective
June 20; (3) amended, p. 1755, § 2, effective July 23. L. 81: (5)
amended, p. 1834, § 13, effective June 12; (1) amended, p. 1398, § 12,
effective January 1, 1983. L. 83: Entire section R&RE, p. 1505, § 2,
effective June 2; (7) and (8) added, p. 2093, § 3, effective September 23. L.
88: (9) added, p. 1290, § 22, effective May 23. L. 90: (10) added,
p. 1699, § 28, effective June 9. L. 91: (10) amended, p. 1954, § 3,
effective January 1, 1992. L. 93: (9) repealed, p. 1690, § 9, effective
June 6. L. 96: (10) amended, p. 948, § 2, effective July 1.
Editor's
note: Amendments
to subsection (3) by House Bill 77-1242 and House Bill 77-1452 were harmonized.
Cross
references: For
right of judicial review under the "State Administrative Procedure
Act", see § 24-4-106.
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
State board has power of
equalization but not assessment. Union P.R.R. v. Bd. of Comm'rs, 35 F.2d
785 (1929); Bohen v. Bd. of Comm'rs, 109 Colo. 283, 124 P.2d 606 (1942); BQP
Industries v. State Bd. of Equaliz., 694 P.2d 337 (Colo. App. 1984).
State board can review the
abstract of assessment of a particular county for errors upon
recommendation of the property tax administrator when the administrator finds
that classes or subclasses of property located in a county have not been
correctly valued for assessment as required by law. Writer Corp. v. State Bd.
of Equaliz., 771 P.2d 13 (Colo. App. 1988).
Courts are powerless to
control right legally exercised. So long as the right to adjust and
equalize the valuation of real and personal property is legally exercised,
courts are powerless to control the results. MacGinnis v. Denver Land Co., 90
Colo. 72, 6 P.2d 919 (1931).
It would be impractical and
impossible to hold individual hearings following the giving of individual
notices at the equalization stage of tax proceedings. Even if time would allow
it, individual hearings would, nevertheless, defeat the system, the purpose of
which is to equalize valuations on a statewide basis. People ex rel. State Bd.
of Equaliz. v. Hively, 139 Colo. 49, 336 P.2d 721 (1959).
County assessor obligated to
execute board's mandate. A county assessor has no standing to question the
validity of the action of the state board of equalization, but he is obligated
to carry out the mandate of the board. People ex rel. State Bd. of Equaliz. v.
Hively, 139 Colo. 49, 336 P.2d 721 (1959).
Applied in People ex
rel. State Bd. of Equaliz. v. Pitcher, 61 Colo. 149, 156 P. 812 (1916); Laredo
Hous. Apts., Ltd. v. Bd. of County Comm'rs, 628 P.2d 135 (Colo. App. 1980);
Laredo Hous. Apts., Ltd. v. Bd. of Assmt. Appeals, 675 P.2d 23 (Colo. App.
1983).
39-9-104. Correction of errors.
The state
board of equalization shall correct any obvious error appearing in any county
abstract of assessment, whether made by the assessor or by the administrator.
The state board of equalization shall not change any matter pertaining to the
actual value of any class or subclass except as provided in section 39-9-103
(7); except that, in the taxable year following the year of reappraisal ordered
by the state board of equalization, such board may change any matter pertaining
to the actual value, and such change shall be made by the assessor in the
abstract of assessment of such current taxable year.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-9-4. L. 70: p. 387, § 26. L.
77: Entire section amended, p. 1756, § 3, effective July 23. L. 83:
Entire section amended, p. 2093, § 4, effective September 23.
39-9-105. Certification of valuations
for assessment.
(1) No
later than December 20 of each year, the state board of equalization shall
complete its review of the abstracts of assessment of the several counties of
the state, and the chair of the state board of equalization shall thereupon
certify to the assessor of each county a statement of the changes, if any,
ordered by said board in the abstract of his or her county for the current
taxable year and for the next succeeding taxable year and shall also return the
abstract of assessment for the current taxable year to each county.
(2)
Repealed.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-9-5. L. 77: (1) amended, p. 1756,
§ 4, effective July 23. L. 83: (1) amended, p. 1506, § 3, effective June
2. L. 86: (1) amended, p. 1102, § 5, effective March 26. L. 89:
(1) amended, p. 1459, § 18, effective June 7. L. 93: (2) repealed, p.
444, § 1, effective April 19. L. 2000: (1) amended, p. 1502, § 7,
effective August 2.
39-9-106. Supervision and
administration of property tax laws.
The state
board of equalization shall have supervision of the administration of all laws
concerning the valuation and assessment of taxable property and the levying of
property taxes.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-9-6.
39-9-107. Assessment roll to conform.
Whenever
the state board of equalization orders any change in the valuation for
assessment of any class or subclass of taxable real or personal property
located in a county, the assessor thereof shall make the proper adjustment in
individual schedules so that the assessment roll of his county conforms with
the statement of changes ordered by said board and certified by the chairman of
said board.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-9-7. L. 77: Entire section
amended, p. 1756, § 5, effective July 23. L. 83: Entire section amended,
p. 2093, § 5, effective September 23.
ANNOTATION
Applied in Lamm v.
Barber, 192 Colo. 511, 565 P.2d 538 (1977).
39-9-108. Judicial review - interest
during review.
Decisions
of the state board of equalization shall be subject to judicial review, as
provided in section 24-4-106, C.R.S. Such review shall include the issues of
compliance with applicable law and constitutional provisions governing
valuation for assessment for property tax purposes and the validity of any
valuation for assessment study conducted pursuant to the provisions of section
39-1-104 (16). Parties adversely affected or aggrieved shall include any
taxpayer or assessor or the governing body of any taxing jurisdiction. In any
case in which excess state equalization payments are made to school districts
within the county during the time such review is pending, interest shall be
paid to the state on the amount of such excess. Such interest shall be paid for
the period of time from the date of the decision of the state board of
equalization to the date of the final determination of all judicial review.
Such interest shall be computed at the rate determined by the state bank
commissioner pursuant to section 39-21-110.5.
Source:
L. 83: Entire
section added, p. 2093, § 6, effective September 23. L. 88: Entire
section amended, p. 1282, § 7, effective May 23. L. 2001: Entire section
amended, p. 1288, § 85, effective June 5.
39-9-109. Power of state board -
waiver of deadline.
(1) to
(4) Repealed.
(5)
Acting by majority vote and when the state board of equalization determines
that the interests of justice and equity would be served, the board may
authorize the waiver of the July 1 filing deadline described in section
39-2-117 (3)(a) for any annual report required to be filed pursuant to section
39-2-117 if the report is not filed by the filing deadline or if the report is
filed by the filing deadline but is incomplete or otherwise incorrect when
filed. When authorizing a waiver, the state board may determine a deadline for
filing the report, after which the waiver is invalid. The deadline for filing
the report must not be sooner than thirty days after the date that the state
board authorizes the waiver.
(6)
Notwithstanding the provisions of section 39-2-117 (1)(a), acting by majority
vote, the state board of equalization may authorize the property tax
administrator to make an exemption effective for not more than the time allowed
pursuant to section 39-10-101 (2)(b)(II) when the property has been added back
to the tax roll as omitted property and would otherwise have met all criteria
for exemption during that time.
Source:
L. 89: Entire
section added, p. 1491, § 5, effective June 7. L. 95: (5) added, p. 602,
§ 1, effective May 22. L. 2003: (1) to (4) repealed, p. 867, § 2,
effective April 7. L. 2008: (5) amended, p. 458, § 2, effective August
5. L. 2013: (5) amended and (6) added, (HB 13-1246), ch. 203, p. 846, §
2, effective August 7.
Collection
and Redemption
ARTICLE
10
Collection
39-10-101. Collection of taxes.
39-10-102. When taxes payable.
39-10-103. Tax statement.
39-10-104. Payment dates - optional payment
dates - failure to pay - penalty - repeal. (Repealed)
39-10-104.5. Payment dates - optional payment
dates - failure to pay - delinquency.
39-10-105. Receipt for taxes.
39-10-106. Payment of taxes on fractional
interests in lands.
39-10-107. Apportionment of taxes, delinquent
interest - payment.
39-10-108. Treasurer responsible for state tax
levies. (Repealed)
39-10-109. Delinquent tax list - notice.
39-10-110. Publication of delinquent taxes.
39-10-110.5. Partial payment of delinquent
personal property taxes.
39-10-111. Distraint, sale of personal
property.
39-10-111.5. Mobile homes - tax lien sale -
redemption - public auction.
39-10-112. Action to collect unpaid taxes.
39-10-113. Removal or transfer of personal
property - collection of taxes.
39-10-113.5. Improvements valued and taxed
separately - collection of taxes.
39-10-114. Abatement - cancellation of taxes.
39-10-114.5. Decision - review - judicial
review.
39-10-115. Certificate of taxes due.
39-10-116. Civil penalty for checks not paid
upon presentment.
39-10-101. Collection of taxes.
(1)
Upon receipt of the tax list and warrant from the assessor, the treasurer shall
proceed to collect the taxes therein levied, and such tax list and warrant
shall be his authority and justification against any illegality in procedure
prior to his receiving the same.
(2) (a)
(I) If, after the tax list and warrant has been received by the treasurer,
the treasurer discovers that any taxable property then located in the
treasurer's county has been omitted from the tax list and warrant for the
current year or for any prior year and has not been valued for assessment, the
treasurer shall forthwith list and value such property for assessment in the
same manner as the assessor might have done and shall enter such valuation for
assessment on the tax list and warrant and extend the levy. Such entry shall be
designated as an additional assessment and shall be valid for all purposes, the
same as though performed by the assessor.
(II)
Notwithstanding subparagraph (I) of this paragraph (a) or section 39-5-125,
neither the assessor nor the treasurer shall treat any possessory interest in
exempt property as taxable property omitted from the tax list and warrant for
any property tax year prior to 2001.
(b) (I)
Except as provided in subparagraph (II) of this paragraph (b), the taxes for
any period, together with interest thereon, imposed by this section shall not
be assessed, nor shall any lien be filed or distraint warrant issued or suit
for collection be instituted or any other action to collect the same be
commenced, more than six years after the date on which the tax was or is
payable. Except as otherwise provided in paragraph (d) of this subsection (2),
interest shall not be charged prior to the date on which additional assessment
is made.
(II)
Effective January 1, 1996, the taxes for any period, together with interest thereon,
imposed by this section shall not be assessed, nor shall any lien be filed or
distraint warrant issued or suit for collection be commenced, more than two
years after the date on which the tax was or is payable when the failure to
collect the tax is due to an error or omission of a governmental entity. The
provisions of this subparagraph (II) shall not apply to taxes imposed on oil
and gas leaseholds and lands.
(c) In
the case of fraudulent action with intent to evade tax, the tax, together with
interest thereon, may be assessed, or proceedings for the collection of such
taxes may be begun, at any time.
(d)
Taxes levied upon additional assessments on mines and on oil and gas leaseholds
and lands which had been previously omitted from the tax list and warrant due
to the failure of an owner or operator of any mine or of any oil and gas
leaseholds and lands to comply with section 39-6-106, 39-6-113, or 39-7-101
shall be subject to the delinquent interest provisions of section 39-10-104.5.
Delinquent interest shall be calculated to accrue from the date the taxes were
due pursuant to section 39-1-105 and section 39-6-106, 39-6-113, or 39-7-101.
This paragraph (d) shall apply to omitted property or production but shall not
apply to valuation disputes, protests, or appeals therefrom filed pursuant to
section 39-5-122.
(3) If
on the tax list and warrant there is any error in the name of a person owing
taxes, the treasurer may correct such error and collect the taxes from the
person intended.
(4) and
(5) Repealed.
Source:
L. 64: R&RE,
p. 715, § 1. C.R.S. 1963: § 137-10-1. L. 73: p. 238, § 21. L.
75: (4) repealed, p. 1473, § 30, effective July 18; (2) amended, p. 1478, §
2, effective July 30. L. 90: (5) added, p. 1719, § 9, effective June 7. L.
92: (2)(b) amended and (2)(d) added, p. 2238, § 1, effective April 10. L.
94: (5) repealed, p. 753, § 1, effective April 20. L. 95: (2)(b)
amended, p. 35, § 1, effective March 17. L. 96: (2)(b)(II) amended, p.
18, § 4, effective February 22; (2)(a) amended p. 1855, § 5, effective June 5. L.
2002: (2)(a)(II) amended, p. 1009, § 4, effective August 7.
ANNOTATION
Law reviews. For
article, "A Calendar of Tax Procedure in Colorado", see 6 Dicta 17
(July 1929).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Statutory procedures
established for collection of real estate taxes are exclusive. Skidmore v.
O'Rourke, 152 Colo. 470, 383 P.2d 473 (1963).
They are comprehensive and
detailed. This article, outlining the steps to be taken by county
treasurers to obtain the amount of taxes levied, is very comprehensive and
detailed. Skidmore v. O'Rourke, 152 Colo. 470, 383 P.2d 473 (1963).
Under this section and §
39-5-125, both the assessor and the treasurer may retroactively correct errors
that caused property to be omitted from the assessment roll and tax list and
warrant. Marsico Cap. Mgmt. v. Denver Bd. of County Comm'rs, 2013 COA 90, 342
P.3d 462.
Subsection (2)(a) of this
section and § 39-5-125 authorize retroactive assessments of additional property
taxes only against "omitted property", not "omitted value".
Section 39-10-107 authorizes retroactive assessments of additional property
taxes against "omitted value" on oil and gas leaseholds. Cabot
Petroleum Corp. v. Yuma County Bd. of Equaliz., 847 P.2d 152 (Colo. App. 1992),
rev'd on other grounds, 856 P.2d 844 (Colo. 1993); In Stitches, Inc. v. Denver
County Bd. of County Comm'rs, 62 P.3d 1080 (Colo. App. 2002); Jet Black, LLC v.
Routt County Bd. of County Comm'rs, 165 P.3d 744 (Colo. App. 2006); Kinder
Morgan v. Montezuma County Bd., 2015 COA 72, 399 P.3d 735, aff'd, 2017 CO 72,
396 P.3d 657.
Authority to charge
delinquent interest upon additional assessments previously omitted from the tax
list and warrant due to the failure of an owner to comply with § 39-6-106
did not create a new duty on taxpayers, but only substituted a new remedy, and
therefore the 1992 amendment authorizing such interest was constitutional, and
not a law retrospective in its operation. Shell Western E&P, Inc. v. Bd. of
County Comm'rs of Dolores County, 923 P.2d 251 (Colo. App. 1995).
Under the doctrine of
equitable tolling, county taxpayer cannot assert statute of limitations as a
defense when taxpayer fails to file the tax declaration schedules required
by statute. Shell Western E&P v. Dolores County Bd. of Comm'rs, 948 P.2d
1002 (Colo. 1997).
Requiring the payment of
interest from a time prior to the effective date of this section is not
unconstitutional when the tax obligation upon which the interest accrued
was assessed after this section's effective date. Shell Western E&P v.
Dolores County Bd. of Comm'rs, 948 P.2d 1002 (Colo. 1997).
39-10-102. When taxes payable.
(1) (a)
Repealed.
(b) (I)
Except as otherwise provided in article 1.5 of this title, all property taxes
shall become due and payable on January 1 of the year following that in which
they are levied and shall become delinquent on June 16 of said year.
(II)
This paragraph (b) is effective January 1, 1992.
(2)
Except as otherwise provided in article 1.5 of this title 39, the treasurer
shall accept payment of taxes tendered by any person and, upon request of the
person who tendered the payment of taxes or the person's agent, issue a receipt
therefor at any time after the tax list and warrant have been received by the
treasurer.
Source:
L. 64: R&RE,
p. 716, § 1. C.R.S. 1963: § 137-10-2. L. 81: Entire section
amended, p. 1841, § 3, effective May 28. L. 90: (1) amended, p. 1716, §
1, effective June 7; (1) amended, p. 1085, § 49, effective July 1. L. 2020:
(2) amended, (HB 20-1077), ch. 80, p. 325, § 11, effective September 14.
Editor's
note: Subsection
(1)(a)(II) provided for the repeal of subsection (1)(a), effective January 1,
1992. (See L. 90, p. 1716.)
ANNOTATION
Law reviews. For
article, "One Year Review of Constitutional Law", see 40 Den. L. Ctr.
J. 134 (1963).
39-10-103. Tax statement.
(1) (a)
As soon as practicable after January 1, the treasurer shall, at the treasurer's
discretion, mail or send electronic notification to each person whose name
appears on the tax list and warrant a statement or true and actual notice of
electronic statement availability, as applicable, showing the total amount of
taxes payable by such person, which statement shall separately list the amount
of taxes levied on real and personal property and shall recite the actual value
of the property and the amount of valuation for assessment upon which such
taxes were levied. If any of the personal property upon which taxes are to be
levied is a mobile home, the tax statement shall contain the following notice:
"This property may not be moved without a valid permit or prorated tax
receipt and a transportable manufactured home permit from the county
treasurer's office. Violators shall be prosecuted." Failure of any person
to receive such statement or true and actual notice of an electronic statement,
as applicable, shall not preclude collection by the treasurer of the amount of
taxes due from and payable by such person. Such statement shall include a
notice that, if such person desires a receipt for payment of taxes, the person
shall request such receipt. The statement may also state what each mill levy
would have been for each taxing district for the prior tax year based upon the
current year's valuation for assessment.
(b) On
and after January 1, 1988, each taxpayer's statement required by paragraph (a)
of this subsection (1) shall also separately list the mill levies and the
amount of taxes to be credited to the county, municipalities, school districts,
special districts, and other districts within the county which are applicable
to his property. This paragraph (b) shall be applicable for statements for 1987
taxes payable in 1988 and for each statement thereafter.
(c)
Repealed.
(d) For
property tax years commencing on or after January 1, 2025, the treasurer shall
not include the amount of valuation for assessment upon which taxes are levied
upon the taxpayer.
(2)
Each tax notice must contain information regarding the actual school district
general fund mill levy and the school district general fund mill levy in
absence of funds estimated to be received by school districts pursuant to the
"Public School Finance Act of 2025", article 54 of title 22, and the
estimated funds to be received for the general funds of districts from the
state.
(3)
Repealed.
(4)
Notwithstanding any other provision of law, a taxpayer may request to receive
by electronic transmission the statement required by subsection (1) of this
section. The taxpayer shall submit along with the request an electronic address
to which the treasurer may send future statements. The treasurer, upon receipt
of such request by a taxpayer to receive statements electronically, may send
all future statements by electronic transmission to the electronic address
supplied by the taxpayer; except that, if a taxpayer subsequently requests to
cease the electronic transmission of such statements and requests to receive
future statements by mail, the treasurer shall comply with the request. Failure
of a taxpayer to receive the electronic statement shall not preclude collection
by the treasurer of the amount of taxes due from and payable by the taxpayer.
Source:
L. 64: R&RE,
p. 716, § 1. C.R.S. 1963: § 137-10-3. L. 77: Entire section
amended, p. 1761, § 2, effective June 2; entire section amended, p. 1739, § 22,
effective June 20. L. 78: Entire section amended, p. 373, § 10,
effective July 1. L. 85: (1) amended, p. 1232, § 1, effective April 5. L.
88: (2) amended, p. 824, § 38, effective May 24. L. 89: (2) amended,
p. 971, § 23, effective June 7. L. 90: (3) added, p. 1716, § 2,
effective June 7; (3) added, p. 1085, § 50, effective July 1, 1990. L. 91:
(1)(a) amended, p. 1695, § 2, effective July 1. L. 94: (2) amended, p.
825, § 56, effective April 27; (2) amended, p. 1646, § 81, effective May 31. L.
96: (1)(a) amended, p. 724, § 8, effective May 22. L. 2004: (3)
repealed, p. 207, § 30, effective August 4. L. 2010: (1)(a) amended and
(4) added, (HB 10-1117), ch. 195, p. 842, § 3, effective August 11. L. 2015:
(1)(b) amended, (SB 15-264), ch. 259, p. 967, § 87, effective August 5. L.
2020: (2) amended, (HB 20-1077), ch. 80, p. 326, § 12, effective September
14. L. 2023, 1st Ex. Sess.: (1)(c) added, (SB 23B-001), ch. 1, p. 12, §
13, effective November 20. L. 2024: (2) amended, (HB 24-1448), ch. 236,
p. 1538, § 65, effective May 23. L. 2024, 2nd Ex. Sess.: (1)(d) added,
(HB 24B-1001), ch. 1, p. 22, § 17, effective October 1 (see editor's note).
Editor's
note: (1)
Amendments to this section by House Bill 77-1324 and House Bill 77-1452 were
harmonized. Amendments to subsection (3) by Senate Bill 90-211 superseded by
House Bill 90-1314. Amendments to subsection (2) by House Bill 94-1001 and
Senate Bill 94-206 were harmonized.
(2) Section 19 of chapter 1 (HB
24B-1001), Session Laws of Colorado 2024, Second Extraordinary Session,
provides that the act changing this section takes effect only if SB 24-233
takes effect and takes effect upon the effective date of SB 24-233. SB 24-233
took effect on October 1, 2024, due to an amendment to the effective date of SB
24-233 by section 18 of chapter 1 (HB 24B-1001), Session Laws of Colorado 2024,
Second Extraordinary Session.
(3) Subsection (1)(c)(II)
provided for the repeal of subsection (1)(c), effective July 1, 2025. (See L.
2023, 1st Ex. Sess., p. 12.)
39-10-104. Payment dates - optional
payment dates - failure to pay - penalty - repeal. (Repealed)
Source:
L. 64: R&RE,
p. 716, § 1. C.R.S. 1963: § 137-10-4. L. 71: p. 327, § 3. L.
73: p. 1433, § 3. L. 77: (1), (2), (3), and (5) amended and (6)
added, p. 1763, § 1, effective April 7; (1)(b), (2)(b), (3)(b), and (5)(b)
repealed, p. 1763, § 1, effective March 1, 1978. L. 79: (6) repealed, p.
1641, § 54, effective July 19; (2)(a), (3)(a), and (5)(a) amended and (7) and
(8) added, pp. 1420, 1421, 1423, §§ 1, 2, 3, effective January 1, 1980. L.
81: (9) added, p. 1860, § 1, effective March 20; (7) amended, p. 1859, § 1,
effective March 27. L. 83: (1)(a) amended and (5.5) added, p. 1509, § 1,
effective May 23. L. 90: (10) added, p. 1717, § 3, effective June 7;
(10) added, p. 1085, § 51, effective July 1.
Editor's
note: Subsection
(10) provided for the repeal of this section, effective January 1, 1992. (See
L. 90, pp. 1085, 1717.)
39-10-104.5. Payment dates - optional
payment dates - failure to pay - delinquency.
(1) The
provisions of this section, as amended, are effective January 1, 1994.
(2)
Except as provided in subsections (6) and (7) of this section, at the option of
the taxpayer, property taxes may be paid in full or in two equal installments,
the first such installment to be paid on or before the last day of February and
the second installment to be paid no later than the fifteenth day of June.
(3) (a)
(I) If the first installment is not paid on or before the last day of
February, then delinquent interest on the first installment shall accrue at the
rate of one percent per month from the first day of March until the date of
payment; except that, if payment of the first installment is made after the
last day of February but not later than thirty days after the mailing by the
treasurer of the tax statement, or true and actual notification of an
electronic statement, pursuant to section 39-10-103 (1)(a), no such delinquent
interest shall accrue. If the second installment is not paid by the fifteenth
day of June, delinquent interest on the second installment shall accrue at the
rate of one percent per month from the sixteenth day of June until the date of
payment. Interest on the first installment shall continue to accrue at the same
time that interest is accruing on the unpaid portion of the second installment.
The taxpayer shall continue to have the option of paying delinquent property
taxes in two equal installments until one day prior to the sale of the tax lien
on such property pursuant to article 11 of this title 39.
(II)
Repealed.
(b)
Notwithstanding the provisions of paragraph (a) of this subsection (3), if the
full amount of taxes is paid in a single payment on or before the last day of
April, then no delinquent interest shall accrue on any portion of the taxes. If
the full amount of taxes is paid in a single payment after the last day of
April, interest shall be added to the full amount of taxes due in the amount of
one percent per month which shall accrue from the first day of May until the
date of payment.
(c)
Interest shall be calculated on delinquent taxes as provided in paragraphs (a)
and (b) of this subsection (3) as specified in the following table:
|
Required Date
of Payment
|
Last Day of
February
|
June 15
|
April 30
|
|
Month Paid
|
Half Tax Option
|
Full Tax Option*
|
|
|
1st Installment
|
2nd Installment
|
|
|
March
|
1%
|
________
|
________
|
|
April
|
2%
|
________
|
________
|
|
May
|
3%
|
________
|
1%
|
|
June 1 - 15
|
4%
|
________
|
2%
|
|
June 16 - 30
|
4%
|
1%
|
2%
|
|
July
|
5%
|
2%
|
3%
|
|
August
|
6%
|
3%
|
4%
|
|
September
|
7%
|
4%
|
5%
|
|
October
|
8%
|
5%
|
6%
|
|
November
|
9%
|
6%
|
7%
|
|
December
|
10%
|
7%
|
8%
|
*Total taxes less than $25.00 must
be paid using the Full Tax Option.
(d) (I)
If a court of competent jurisdiction finds that the taxpayer has committed a
petty offense under section 39-5-115 (3), the taxpayer is not entitled to
penalty interest pursuant to this subsection (3).
(II)
The board of assessment appeals does not have authority to determine whether a
taxpayer has forfeited the right to penalty interest. A determination of
whether a taxpayer has forfeited the right to penalty interest is made solely
by the court in connection with a prosecution for willful misinformation.
(4)
(Deleted by amendment, L. 93, p. 303, § 1, effective April 7, 1993.)
(5) In
computing the amount of delinquent interest due under this section, portions of
months shall be counted as whole months.
(6)
There shall be no installment payment of property taxes totaling less than
twenty-five dollars, and such taxes shall be paid in full no later than the
last day of April. If such taxes are not paid prior to the last day of April,
delinquent interest on the amount thereof shall accrue at the rate of one
percent per month from the first day of May until the date of payment.
(7) The
treasurer shall be authorized to accept funds paid by the seller and accepted
by the dealer as a partial payment of taxes which have not yet been levied and
which are not yet due but which have been prorated between the buyer and the
seller at the time of the sale of a mobile home. A dealer shall remit taxes
collected under this subsection (7) to the treasurer within ten days.
(8) Any
payment under this section shall be deemed received by the treasurer on the
date that the installment or full payment, including any penalties or fees due,
is actually received in the treasurer's office, and actual receipt will be
presumed as of the date of the United States postal service postmark. Where a
payment is received through the mail or a common carrier but has no United
States postal service postmark and the payment is actually received in the
treasurer's office no later than five days after the due date, the treasurer
shall record the date of payment as the due date of the payment. Where the
payment is received through the mail or a common carrier but has no United
States postal service postmark and the payment is actually received in the
treasurer's office six or more days after the due date, the treasurer shall
record the date of payment as the date the payment was received. If the date
for filing any tax return or remittance falls upon a Saturday, Sunday, or legal
holiday, it shall be deemed to have been timely filed if filed on the next
business day.
(9) An
additional charge may be added to any delinquent taxes totaling less than fifty
dollars including all delinquent interest and other charges. Such charge shall
be for the purpose of covering the administrative costs and fees incurred by
the county in collecting such delinquencies and shall be determined by the
board of county commissioners or such other body as authorized by the city and
county of Denver or as authorized by the city council of the city and county of
Broomfield. Such charge shall not exceed twenty-five dollars in any case and
shall be limited to such amount less than twenty-five dollars as may be
necessary to limit the total charges against such property, including taxes,
delinquent interest, and the charge authorized by this subsection (9), to no
more than fifty dollars. Charges imposed under the authorization of this
subsection (9) shall be a lien under section 39-1-107.
(10)
The treasurer may refrain from collecting any penalty, delinquent interest, or
costs where the amount to be collected is fifty dollars or less. Nothing in
this subsection (10) shall be construed as releasing any person from the
payment of any tax, assessment, penalty, delinquent interest, or costs or any
other moneys which are due and owing and which the treasurer is authorized by
law to collect.
(11)
Repealed.
(12)
Notwithstanding any other provision of law, a county treasurer may accept an
estimated prepayment of property taxes due for the current tax year prior to
the treasurer's receipt of the tax warrant pursuant to section 39-5-129. The
treasurer has broad authority to establish the conditions and terms under which
estimated prepayments will be accepted.
(13) to
(15) Repealed.
Source:
L. 90: Entire
section added, pp. 1085, 1717, §§ 52, 4, effective January 1, 1992. L. 92:
(3) to (6), (9), and (10) amended, p. 2226, § 9, effective April 9. L. 93:
(1) to (4) amended, p. 303, § 1, effective April 7; (2) amended and (11) added,
p. 346, § 3, effective April 12. L. 94: (8) amended, p. 753, § 2,
effective April 20. L. 98: (11) repealed, p. 829, § 52, effective August
5. L. 2000: (3)(a) amended, p.81, § 1, effective March 10. L. 2001:
(9) amended, p. 269, § 17, effective November 15. L. 2005: (8) amended,
p. 254, § 1, effective April 14. L. 2006: (10) amended, p. 26, § 1,
effective March 13. L. 2010: (8) amended, (HB 10-1046), ch. 16, p. 77, §
1, effective March 5; (3)(a) amended, (HB 10-1117), ch. 195, p. 843, § 4,
effective August 11. L. 2016: (2) amended, (SB 16-189), ch. 210, p. 793,
§ 107, effective June 6. L. 2020: (13) added, (HB 20-1421), ch. 108, p.
423, § 1, effective June 14; (12) added, (HB 20-1077), ch. 80, p. 326, § 13,
effective September 14. L. 2021: (14) added, (SB 21-279), ch. 365, p. 2406,
§ 1, effective June 28. L. 2023, 1st Ex. Sess.: (3)(a) amended, (SB
23B-001), ch. 1, p. 12, § 14, effective November 20. L. 2024: (15)
added, (SB 24-183), ch. 303, p. 2060, § 2, effective May 31. L. 2026:
(3)(d) added, (HB 26-1233), ch. 360, p. 2167, § 4, effective August 12.
Editor's
note: (1)
Amendments to subsection (2) by Senate Bill 93-90 and House Bill 93-1040 were
harmonized.
(2) Subsection (13)(b) provided
for the repeal of subsection (13), effective December 31, 2020. (See L. 2020,
p. 423.)
(3) Subsection (14)(d) provided
for the repeal of subsection (14), effective December 31, 2021. (See L. 2021,
p. 2406.)
(4) Subsection (3)(a)(II)(B)
provided for the repeal of subsection (3)(a)(II), effective July 1, 2025. (See
L. 2023, 1st Ex. Sess., p. 12.)
(5) Subsection (15)(b) provided
for the repeal of subsection (15), effective September 1, 2025. (See L. 2024,
p. 2060.)
ANNOTATION
Law reviews. For
article, "Collecting Pre- and Post-Judgment Interest in Colorado: A
Primer", see 15 Colo. Law. 753 (1986). For article, "An Update of
Appendices from Collecting Pre- and Post-Judgment Interest in Colorado",
see 15 Colo. Law. 990 (1986).
39-10-105. Receipt for taxes.
(1)
Upon request of an individual taxpayer or the taxpayer's agent, the treasurer
shall issue and shall mail, if additionally requested, a receipt for each
payment of taxes received, which shall state the amount of taxes paid and any
delinquent interest thereon, the year or portion thereof for which such taxes
apply, the property upon which such taxes are paid, and a notation of any taxes
levied thereon for prior years which are unpaid and delinquent. A copy of the
statement specified in section 39-10-103, when stamped "paid" by the
treasurer, shall suffice for such receipt. The apportionment of the total tax
levy may be printed or stamped on the reverse side of each tax receipt issued
or may be separately furnished to the taxpayer. The mortgagee or beneficiary of
a deed of trust is not required to retain a tax receipt for the property which
is the subject of the mortgage or the deed of trust.
(1.5)
In lieu of issuing and mailing individual receipts, the treasurer may issue and
mail a certified listing of taxes paid and any delinquent interest thereon, the
year or portion thereof for which such taxes apply, and sufficient
identification of the property upon which such taxes are paid to those
taxpayers or their agents for combined tax payments on ten or more assessed
parcels.
(2) The
treasurer shall retain in the office as part of the records thereof a copy of
every receipt issued by the treasurer for taxes paid, which copies shall be
recorded or filed in the order of issuance. The original tax receipt, or a copy
thereof, or a copy of any entry in the treasurer's records concerning the same
shall, when certified by the treasurer or the treasurer's deputy, be received
in all places as prima facie evidence of payments of the taxes. For purposes of
this section, "copy" means a reproduction of the original by any
means, including, but not limited to, a photograph, a microfilm or optical
imaging record, a computer disk image, or any other means of record retention
chosen by the treasurer.
(3)
Repealed.
Source:
L. 64: R&RE,
p. 717, § 1. C.R.S. 1963: § 137-10-5. L. 71: p. 327, § 4. L.
75: (1.5) added, p. 1479, § 3, effective July 1. L. 77: (1) and
(1.5) amended, p. 1761, § 3, effective June 2. L. 92: (1) and (1.5)
amended, p. 2226, § 10, effective April 9. L. 94: (1) and (2) amended,
p. 754, § 3, effective April 20. L. 2020: (3) repealed, (HB 20-1077),
ch. 80, p. 326, § 14, effective September 14.
39-10-106. Payment of taxes on
fractional interests in lands.
(1)
Where oil, gas, or other hydrocarbon wells or fields belonging to multiple
owners are operated as a unit, the owner of each fractional interest in such
units shall be liable for the same proportion of the tax levied against the
total unit that his net taxable revenues received therefrom bears to the total
net taxable revenues received from such unit. In the event a fractional
interest owner who takes production in kind does not provide the information to
the operator which is required under section 39-7-101 (1.5), such fractional
interest owner's tax liability shall be calculated using the net taxable
revenues reported by the operator.
(2) The
unit operator shall collect from the owners of the fractional interests and
remit to the treasurer of the county in which the unit is located the tax
levied against the entire unit. The unit operator may deduct and withhold from
royalty payments or any other payments made to any fractional interest owner,
either in kind or in money, the estimated amount of the tax to be paid by such
fractional interest owner. Any difference between the estimated tax so withheld
and the actual tax payable by any owner of a fractional interest may be
accounted for by adjustments in royalty or other payments made to such owner
subsequent to the time the actual tax is determined. Failure of the unit
operator to remit to the treasurer the tax levied against the entire unit shall
make the unit operator liable for such tax.
(3) At
the request of any unit operator who does not disburse payments to fractional
interest owners, the first purchaser shall collect the tax from the fractional
interest owners as provided for in this section and transfer such proceeds to
the unit operator who shall in turn be responsible for remitting to the
treasurer the total tax levied against the entire unit.
(3.5)
(a) Except as otherwise provided in paragraph (b) of this subsection (3.5),
the unit operator shall place in an account in a federally insured bank or
savings and loan association located in the state of Colorado which requires
two signatures, one of which shall be the signature of the county treasurer of
the county in which the unit is located, in order to make a withdrawal, an
amount equal to the tax collected from the owners of fractional interests in
the unit by the unit operator pursuant to the provisions of this section plus
the proportional share of tax levied on the fractional interest in the unit
owned by the unit operator. Such account shall be owned by the owners of
fractional interests in the unit, but the unit operator shall be responsible
for managing such account. The moneys shall be deposited in such account within
thirty days from the date the unit operator receives payment for the sale of
any oil or gas from such lease.
(b) The
treasurer may waive the requirement of placing the tax in such account or fund
as required in paragraph (a) of this subsection (3.5) and allow the unit
operator to file a statement with the treasurer declaring that a sufficient
amount of moneys or other assets is available to ensure the payment of the tax
if:
(I) The
unit operator has made timely payment of the tax to the treasurer during the
previous three property tax years;
(II)
The unit operator has been in operation in the county for less than three
property tax years and has made timely payment of the tax to the treasurer
during such period of time; or
(III)
The unit operator has been in operation in the county for less than one
property tax year.
(c)
Upon the completion of all production of oil and gas from the unit and after
all wells within the unit are plugged and abandoned, all moneys remaining in
the account after full payment of all ad valorem taxes due on the unit shall be
distributed to the owners of fractional interests in the unit based upon each
owner's proportional contribution to the moneys remaining in the account. Any
interest accruing to the account shall be credited to the account and shall be
distributed with such other moneys in the account as specified in this
paragraph (c).
(4) (a)
Failure of the unit operator or first purchaser to collect the tax as provided
in this section shall not preclude the treasurer from utilizing lawful
collection and enforcement remedies and procedures against the owner of any
fractional interest to collect the tax owed by such owner; but an owner shall
not be subject to penalty or interest upon the tax owed unless he fails to
remit such tax within twenty days after notification to him by the treasurer of
the default of the first purchaser or unit operator.
(b) (I)
When the tax has been collected from the owners of fractional interests by the
unit operator pursuant to the provisions of this section but the unit operator
fails to remit such tax collected, the unit operator shall remain liable for
the amount of tax owed. The treasurer shall send a notice by registered mail to
the first purchaser of the amount of such delinquent taxes and the name of the
unit operator owing such delinquent tax. After receiving such notice, the first
purchaser shall withhold payments to the unit operator owing the taxes of any
of the proceeds of the sale of any oil and gas from such lease. The first
purchaser shall remit such withheld payments to the treasurer until the amount
of such taxes and penalties are paid in full, after which the first purchaser
may resume such payments to the unit operator for such oil and gas.
(II) If
the first purchaser fails to collect the tax after receiving notice from the
treasurer pursuant to the provisions of this paragraph (b) or when the tax has
been collected by the first purchaser pursuant to the provisions of this
section but the first purchaser fails to transfer the tax to the unit operator
pursuant to subsection (3) of this section or to the treasurer pursuant to
subparagraph (I) of this paragraph (b), the first purchaser shall remain liable
for the amount of tax owed. The treasurer may utilize lawful collection and
enforcement remedies and procedures against any first purchaser to collect the
amount of such taxes and penalties owed by such first purchaser.
(III)
The tax liability of the owner of any fractional interest in such unit whose
proportionate share of tax was withheld from royalty or working interest
payments by the unit operator or the first purchaser but was not remitted by
the unit operator or by the first purchaser to the treasurer shall be deemed
satisfied to the extent of the amount withheld, and such owner shall not be
subject to any collection and enforcement remedies and procedures provided by
law for the collection of such delinquent tax for which an amount was withheld
from royalty or working interest payments pursuant to the provisions of this
section. Any unit operator or first purchaser who has collected the tax from
the fractional interest owners pursuant to the provisions of this section but
has failed to remit such tax collected commits a class 2 misdemeanor.
(IV)
Upon audit, the unit operator shall not be liable for any tax or any penalty
interest levied against any amount of production taken in kind from the
property for which the fractional interest owner taking production in kind
provided inaccurate information regarding net taxable revenues to be used for
tax reporting.
(4.5)
(a) If the unit operator fails to remit the proportional share of tax levied
on the fractional interest in the unit owned by the unit operator, the
treasurer shall send a notice by registered mail to the first purchaser of the
name of the unit operator owing such tax and the amount the first purchaser
shall withhold from any of the unit operator's proceeds of the sale of any oil
and gas from such lease. After receiving such notice, the first purchaser shall
withhold payments to the unit operator of any of the proceeds of the sale of
any oil and gas from such lease. The first purchaser shall remit such withheld
payments to the treasurer until the amount of such tax and penalties are paid
in full, after which the first purchaser may resume such payments to the unit
operator for such oil and gas.
(b) The
tax liability of the unit operator whose proportional share of tax levied on
the fractional interest in the unit owned by the unit operator was withheld
from payments by the first purchaser pursuant to paragraph (a) of this
subsection (4.5) but was not remitted by the first purchaser to the treasurer
shall be deemed satisfied to the extent of the amount withheld, and such unit
operator shall not be subject to any collection and enforcement remedies and
procedures provided by law for the collection of such delinquent tax for which
an amount was withheld by a first purchaser from oil and gas sale proceeds
pursuant to the provisions of this section.
(c) If
the first purchaser fails to collect the tax or when the tax has been collected
by the first purchaser pursuant to the provisions of this subsection (4.5) but
the first purchaser fails to transfer the tax to the treasurer pursuant to
paragraph (a) of this subsection (4.5), the first purchaser shall remain liable
for the amount of tax owed. The treasurer may utilize lawful collection and
enforcement remedies and procedures against any first purchaser to collect the
amount of such taxes and penalties owed by such first purchaser.
(5) For
the purposes of this section, "unit" means any single oil, gas, or
other hydrocarbon well or field which has multiple ownership, or any
combination of oil, gas, or other hydrocarbon wells, fields, and properties
consolidated into a single operation, whether by a formal agreement or
otherwise; "owner" means the holder of any interest or interests in
such properties or units, including royalty interest; and "first
purchaser" means either the first purchaser to buy oil or gas from a new
producing well or the current purchaser of oil or gas from a producing well.
Source:
L. 64: R&RE,
p. 717, § 1. C.R.S. 1963: § 137-10-6. L. 69: p. 1121, § 3. L.
71: p. 1247, § 1. L. 79: p. 1418, § 3. L. 87: (3.5) and (4.5)
added and (4) amended, p. 1419, § 1, effective May 20. L. 88: (3.5)(a),
(3.5)(c), and (4)(b)(III) amended and (3.5)(b) R&RE, p. 1309, §§ 2, 1,
effective April 14; (4)(b)(III) amended, p. 1437, § 38, effective June 11. L.
93: (1) and (3.5)(c) amended and (4)(b)(IV) added, pp. 242, 243, §§ 3, 4,
effective March 31. L. 99: (1) amended, p. 629, § 41, effective August 4.
L. 2021: (4)(b)(III) amended, (SB 21-271), ch. 462, p. 3294, § 690,
effective March 1, 2022.
ANNOTATION
Law reviews. For
article, "Delinquent Oil and Gas Ad Valorem Taxes: Protecting Property
Interests", see 16 Colo. Law. 798 (1987).
The county's sale of
fractional interests was improper where the unit operator collected the
amount due for taxes from the fractional interest owners, but illegally failed
to remit the taxes. The language of this section unambiguously reveals the
general assembly's intent to hold unit operators liable in this situation.
Roehrs v. County of Morgan, 991 P.2d 322 (Colo. App. 1999).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
39-10-107. Apportionment of taxes,
delinquent interest - payment.
(1) (a)
Notwithstanding any other provision of law, all taxes collected by the
treasurer shall be apportioned, credited, and distributed to the county and the
several towns, cities, school districts, and special districts within the
county on the tenth day of each month for all taxes collected during the
immediately preceding month; except that:
(I) If
the amount of taxes collected for the month equals less than one hundred
dollars for any town, city, school district, or special district, the treasurer
may elect to distribute the amount on a quarterly basis to the town, city,
school district, or special district; and
(II) If
the amount of taxes collected for the month equals less than fifty dollars for
any town, city, school district, or special district, the treasurer may elect
to distribute the amount on an annual basis to the town, city, school district,
or special district.
(b) Any
prior years' taxes collected during any given year on oil and gas leaseholds
and lands that had previously been omitted from the assessment roll due to
underreporting of the selling price or the quantity of oil and gas sold
therefrom shall be placed in escrow by the treasurer to be apportioned,
credited, and distributed during January of the subsequent year.
(c)
Prior to being apportioned, credited, and distributed, all taxes collected by
the treasurer shall be reduced by an amount equal to the costs incurred by the
treasurer and the assessor; except that such costs shall not include any
contingency fee paid to any person for the audit review and collection of such
prior years' taxes as such contingency fees are prohibited. Prior to being
apportioned, credited, and distributed, all taxes shall be reduced by an amount
equal to an entity's pro rata share of any tax refunds granted subsequent to
distribution by the treasurer if the amount has not otherwise been returned by
the entity; except that this requirement to reduce taxes shall not apply to a
city and county. All delinquent interest shall be apportioned, credited, and
distributed in the same manner.
(2)
Repealed.
(3)
Whenever any school district elects, pursuant to law, to have the moneys of
such district paid over to the district treasurer, the treasurer of any county
wherein such school district is located shall, no later than the tenth day of
each month, pay over to the district treasurer all taxes collected for said
school district during the month immediately preceding; except that, on and
after January 1, 1992, the county treasurer shall make an additional payment to
the district treasurer during the months of March, May, and June, which payment
shall consist of all taxes collected through the twentieth day of the
respective month if the county has a population of at least five thousand
persons and which payment shall consist of all taxes collected through the
eighteenth day of the respective month if the county has a population of less
than five thousand persons. Such additional payment shall be made no later than
the twenty-fourth day of said month.
(4) No
later than the tenth day of each month, the treasurer shall prepare and submit
to the board of county commissioners and to the proper officer of each town,
city, school district, and special district within his county a statement
showing the amount collected by him for each such entity during the month
immediately preceding from each separate levy imposed for such entity. No later
than the tenth day of January of each year, he shall prepare and submit a
similar statement showing the amount collected during the entire calendar year
immediately preceding from each separate levy imposed for such entity.
Source:
L. 64: R&RE,
p. 718, § 1. C.R.S. 1963: § 137-10-7. L. 79: (1) amended, p.
1421, § 4, effective January 1, 1980. L. 84: (1) amended, p. 1002, § 3,
effective March 16. L. 90: (3) amended, p. 1718, § 5, effective June 7;
(1) amended, p. 1704, § 40, effective June 9; (3) amended, p. 1087, § 53,
effective July 1. L. 91: (1) amended, p. 1954, § 4, effective January 1,
1992. L. 91, 2nd Ex. Sess.: (3) amended, p. 57, § 2, effective October
11. L. 92: (1) amended, p. 2227, § 11, effective April 9. L. 2008:
(1) amended, p. 26, § 1, effective August 5; (1) amended, p. 1248, § 7,
effective August 5. L. 2015: IP(1)(a) amended and (2) repealed, (SB
15-264), ch. 259, p. 967, § 88, effective August 5.
Editor's
note: Amendments
to subsection (1) by House Bill 08-1059 and House Bill 08-1349 were harmonized.
ANNOTATION
Retroactive assessments of
additional property taxes on oil and gas leaseholds can occur where value
is omitted from an annual statement due to the underreporting of the selling
price or quantity of oil and gas sold therefrom, even without evidence of
omitted property or willfully false and misleading annual statements. Kinder
Morgan v. Montezuma County Bd., 2015 COA 72, 399 P.3d 735, aff'd, 2017 CO 72,
396 P.3d 657.
By providing special procedures
for handling oil and gas taxes that had been retroactively assessed based on
underreported selling price or volume, the general assembly demonstrated its
intent for such taxes to be retroactively assessed. Kinder Morgan v. Montezuma
County Bd. of Comm'rs, 2017 CO 72, 396 P.3d 657.
39-10-108. Treasurer responsible for
state tax levies. (Repealed)
Source:
L. 64: R&RE,
p. 719, § 1. C.R.S. 1963: § 137-10-8. L. 2015: Entire section
repealed, (SB 15-264), ch. 259, p. 967, § 89, effective August 5.
39-10-109. Delinquent tax list -
notice.
(1)
Repealed.
(2) (a)
As soon as practicable after June 15, the treasurer shall prepare a list of all
persons delinquent in the payment of taxes on personal property and shall notify
each such person by mail of the amount of delinquent personal property taxes
and delinquent interest due and owing thereon to and including the last day of
the month in which such notice is mailed. Such notice shall also state that,
unless payment of the amount of such unpaid personal property taxes and
delinquent interest thereon are paid by August 31, publication of such
delinquency will be made during the month of September.
(b)
This subsection (2) is effective January 1, 1992.
(3) (a)
The treasurer shall provide notice pursuant to subsection (2) of this section
and any other notice or statement required by law in connection with the
collection of delinquent taxes on mobile homes, as described in section
39-10-111.5 (1), written in English and Spanish, and shall also include a
statement explaining how and where the mobile home owner may obtain language
translation or interpretation services from the county.
(b) The
treasurer shall provide notice written in accordance with subsection (3)(a) of
this section by sending the notice by mail and by personal service to the
mobile home owner at the mobile home, in accordance with section 39-10-111.5
(2)(a).
Source:
L. 64: R&RE,
p. 719, § 1. C.R.S. 1963: § 137-10-9. L. 65: p. 1108, § 1. L.
90: Entire section amended, p. 1718, § 6, effective June 7; entire section
amended, p. 1087, § 54, effective July 1. L. 92: (2)(a) amended, p.
2227, § 12, effective April 9. L. 94: (2)(a) amended, p. 754, § 4,
effective April 20. L. 2026: (3) added, (HB 26-1120), ch. 268, p. 1520,
§ 1, effective June 1.
Editor's
note: Subsection
(1)(b) provided for the repeal of subsection (1), effective January 1, 1992.
(See L. 90, p. 1087.)
39-10-110. Publication of delinquent
taxes.
During the
month of September, the treasurer shall publish for one time only in a
newspaper published in his county a notice listing the names and addresses of
all persons whose taxes on personal property are unpaid and delinquent, with
the amount of such taxes and delinquent interest thereon to and including the
last day of September, plus the fee prescribed in section 30-1-102, C.R.S. Such
notice shall recite that, if the amount of such delinquent taxes, delinquent
interest, and fee is not paid by the last day of September, the personal
property upon which such taxes were levied shall be subject to distraint,
seizure, and sale. If there is no newspaper published in the county, then the
treasurer shall conspicuously post copies of such notice in the county
courthouse, in the treasurer's office, and in at least one other public place
in the county seat.
Source:
L. 64: R&RE,
p. 719, § 1. C.R.S. 1963: § 137-10-10. L. 65: p. 1108, § 2. L.
71: p. 327, § 5. L. 92: Entire section amended, p. 2228, § 13,
effective April 9. L. 93: Entire section amended, p. 305, § 2, effective
April 7.
39-10-110.5. Partial payment of
delinquent personal property taxes.
(1)
Notwithstanding any other provision of law to the contrary, the treasurer may
accept partial payments for delinquent personal property taxes so long as the
owner of the personal property has entered into a written payment plan with the
treasurer. The payment plan shall specify the total amount due, including the
amount of tax levied and any applicable interest, penalties, or fees; the
amount of each payment; and payment due dates. The total amount due under a
payment plan shall be paid in full no later than twenty-four months from the
date the owner of the personal property enters into a written payment plan with
the treasurer.
(2) The
treasurer shall keep a copy of the payment plan until the owner of the personal
property has paid the total amount identified in the payment plan. Once the
owner of the personal property has paid the total amount due, the treasurer
shall mark the plan "paid in full".
(3) The
treasurer may terminate the payment plan if the owner of the personal property
fails to abide by the terms and conditions of the plan.
Source:
L. 98: Entire
section added, p. 238, § 1, effective April 10.
39-10-111. Distraint, sale of personal
property.
(1) (a)
At any time after the first day of October, the treasurer shall enforce
collection of delinquent taxes on personal property by commencing a court
action for collection or employing a collection agency as provided in section
39-10-112 or by distraining, seizing, and selling the property; except that
this section does not apply to the collection of delinquent taxes on mobile
homes or manufactured homes. The treasurer shall enforce the collection of
delinquent taxes on mobile homes or manufactured homes pursuant to section
39-10-111.5. Whenever a distraint warrant is issued, it shall be served by the
sheriff or a commissioned deputy or, at the discretion of the sheriff, by a
private server of process hired for the purpose. Any cost incurred as a result
of hiring a private server of process shall be paid by the sheriff's office,
and the cost shall not exceed the amount specified in section 30-1-104 (1)(a).
(b)
When personal property upon which a distraint warrant has been issued or which
is subject to such warrant by reason of delinquency has been removed to another
county in the state, the treasurer of the county levying the tax may issue a
certificate to the treasurer of the county to which the property has been
removed, reciting the amount of taxes and delinquent interest unpaid and a
description of the property to be distrained.
(c) The
treasurer receiving such certificate shall thereupon proceed to distrain,
seize, and sell such property in the same manner as if the property were
originally taxed in his county and shall remit the net proceeds, after payment
of any sheriff's fees and other costs of seizure and sale, to the treasurer who
certified the delinquency to him.
(2)
Whenever any personal property is distrained and seized, the treasurer or his
deputy shall make a list of such property and deliver a copy thereof to the
owner of such property or to his or her agent, together with a statement of the
amount demanded and notice of the time and place fixed for the sale of such
property.
(3) No
later than one hundred eighty days after the seizure of any personal property
pursuant to this section, the treasurer shall publish a notice containing a
description of the seized property, the reason for its being offered for sale,
and the time and place fixed for the sale in a newspaper published in the
county. If there is no such newspaper, the treasurer shall conspicuously post
copies of such notice in the county courthouse and in at least two other public
places in the county seat.
(4) The
time fixed for the sale shall be not more than ten days from the date the
notice is first published, but the sale may be adjourned from time to time if
there are no bidders or if the treasurer deems such adjournment advisable for
any reason, but in no event shall the sale be postponed for more than thirty
days from the date the notice is first published.
(5) At
the time and place fixed for the sale, the treasurer or deputy treasurer shall
proceed to sell such property at public auction, offering it at a minimum
price, which shall include the taxes, delinquent interest, and costs of making
the seizure and advertising the sale. If the amount bid at the sale is not
equal to the fixed minimum price, the treasurer or deputy treasurer may declare
the property purchased by the county at the fixed minimum price, and it shall
thereafter be sold within one hundred fifty days in such manner as may be
determined by the board of county commissioners.
(6) (a)
In any county wherein the treasurer has insufficient personnel to conduct said
sale, upon demand of the treasurer, the sheriff shall conduct such sale,
collect the proceeds thereof, and pay the same over to the treasurer. In such
event, the sheriff shall receive such fees as are provided in section 30-1-104,
C.R.S.
(b) The
treasurer may enter into a contract to employ the services of any professional
auctioneer or auction company to conduct such sale, collect the proceeds
thereof, and pay the same over to the treasurer, when the treasurer deems such
services to be appropriate and to be in the best interests of the public. Such
contract shall be awarded by competitive bid, but the treasurer may reject any
or all bids or parts of bids. The auctioneer or auction company conducting such
sale shall provide the treasurer with an itemized list of all property sold,
the amount paid for such property sold, and each purchaser's name and address.
The fees of the auctioneer or auction company shall be paid by the treasurer
from the proceeds of the sale.
(7) In
all cases of sale, the treasurer shall issue a certificate of sale to each
purchaser, and such certificate shall be prima facie evidence of the right of
the treasurer to make such sale and conclusive evidence of the regularity of
the proceedings in conducting and making such sale. The treasurer's certificate
shall transfer to the purchaser all right, title, and interest of the owner in
and to the property sold.
(8) Any
surplus of the sale proceeds remaining over and above the taxes, delinquent
interest, and costs of making the seizure and advertising the sale shall be
paid over to the owner and a written account of the sale furnished him.
(9) If,
prior to the time fixed for the sale, the amount demanded is paid to the
treasurer, the property distrained upon and seized shall be restored to the
owner thereof.
(10)
Repealed.
(11) If
taxes become delinquent upon the personal property of any public utility, as
defined in article 4 of this title, the treasurer of the county in which the
taxes are delinquent shall commence a court action for collection or employ a
collection agency as provided in section 39-10-112 or distrain and sell any of
the personal property of the utility wherever found in the manner that other
personal property is to be distrained and sold for the nonpayment of taxes;
except that, for taxes imposed pursuant to article 1 of title 32, C.R.S., that
equal or exceed one hundred mills in any one year, only the personal property
that is the subject of the taxes and located within the special district at the
time of assessment of the taxes shall be subject to levy or distraint for the
payment of the delinquent taxes.
(12)
Repealed.
(13)
When a county seizes property that is used in a business, the county shall not
continue to operate the business.
Source:
L. 64: R&RE,
p. 719, § 1. C.R.S. 1963: § 137-10-11. L. 67: p. 212, § 2. L.
70: p. 389, § 2. L. 77: (7) amended and (10) added, p. 1742, § 4,
effective January 1, 1980. L. 78: (2) and (10) amended, pp. 478, 480, §§
3, 4, effective March 10. L. 79: (11) added, p. 1421, § 5, effective
January 1, 1980. L. 80: (10) amended, p. 499, § 4, effective July 1. L.
82: (10) amended, p. 550, § 15, effective July 1. L. 90: (10)
amended, p. 1698, § 24, effective June 9. L. 91: (5) and (6) amended, p.
1972, § 3, effective March 27; (10) amended and (12) added, p. 1697, § 8,
effective July 1. L. 92: (1)(b), (5), (8), and (10) amended, p. 2228, §
14, effective April 9. L. 93: (1)(a) amended, p. 305, § 3, effective
April 7. L. 94: (4) amended, p. 754, § 5, effective April 20. L. 95:
(11) amended, p. 128, § 2, effective April 7. L. 96: (1)(a) and (11)
amended, p. 13, § 1, effective February 22. L. 2000: (10) amended, p.
1637, § 15, effective June 1. L. 2004: (3) and (5) amended and (13)
added, p. 158, § 1, effective August 4. L. 2017: (1)(a), (2), and (7)
amended and (10) and (12) repealed, (HB 17-1354), ch. 215, pp. 837, 840, §§ 1,
3, effective August 9.
Cross
references: For
recordation of tax sales of mobile homes by the county treasurer and the fee
therefor as part of redemption cost, see § 39-11-114.
ANNOTATION
Law reviews. For
article, "Delinquent Oil and Gas Ad Valorem Taxes: Protecting Property
Interests", see 16 Colo. Law. 798 (1987).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Service of distraint warrant
no delegation of power to collect taxes. The service of a distraint warrant
does not constitute a delegation of power to collect by the treasurer to the
sheriff. Goldsmith v. McAnally, 92 Colo. 384, 20 P.2d 1009 (1933).
Personal property tax sale
extinguishes prior liens. A personal property tax sale under the provisions
of subsection (7) extinguishes all prior liens and encumbrances. Moorehead v.
John Deere Indus. Equip. Co., 194 Colo. 398, 572 P.2d 1207 (1977).
Section 39-10-113 and
subsection (11) of this section do not authorize the distraint, seizure, and
sale of the taxable personal property of a lessor to satisfy the personal
property tax of the lessee. In re W. Pac. Airlines, 273 F.3d 1288 (10th
Cir. 2001).
County treasurer not
indispensable party in proceeding challenging lien priority. In a tax sale,
the county treasurer who issued the certificate of sale to purchaser of tax
sale was not an indispensable party under C.R.C.P. 19(a) to a proceeding
challenging priority of lien of a secured party in the property sold at the tax
sale, since complete relief could be and was afforded without the treasurer's
presence as a party. John Deere Indus. Equip. Co. v. Moorehead, 38 Colo. App.
220, 556 P.2d 91 (1976), rev'd on other grounds, 194 Colo. 398, 572 P.2d 1207
(1977).
39-10-111.5. Mobile homes - tax lien sale
- redemption - public auction.
(1)
This section applies to the collection of delinquent taxes on mobile homes for
which a certificate of title has been issued pursuant to part 1 of article 29
of title 38 and that does not have a certificate of permanent location pursuant
to section 38-29-202. For purposes of this section, "mobile home"
includes a manufactured home.
(2) (a)
Commencing on and after July 1, 2026, any time after the first day of October,
the treasurer may enforce collection of delinquent taxes on mobile homes by
distraining, seizing, selling, or striking off to the county pursuant to
subsection (6)(e) a tax lien on the mobile home.
(b)
Repealed.
(c) The
treasurer receiving such certificate shall proceed to sell or strike off to the
county a tax lien on such mobile home in accordance with this section and in
the same manner as if it were originally taxed in the treasurer's county. The
treasurer shall remit the net proceeds, after payment of any sheriff's fees and
other costs of the tax lien sale, to the treasurer who certified the
delinquency for distribution in accordance with this section.
(2.5)
Repealed.
(3)
Whenever a mobile home is subject to a tax lien sale, the treasurer, the
treasurer's deputy, or an authorized agent of the treasurer shall send to the
owner of the mobile home, at the owner's last-known address, or to the occupant
of the mobile home, if different from the owner, and to any lienholder of
record, a statement of the amount of the owner's delinquency and notice that if
the delinquency is not paid by the date specified in the notice, which shall
not be less than sixty calendar days from the date of mailing of the notice,
the treasurer will advertise and sell a tax lien on the mobile home at a public
auction or the county's annual tax lien sale or will strike off a tax lien on
the mobile home to the county on the date specified in the notice. A statement
sent to the owner of the mobile home pursuant to this subsection (3) must
comply with the requirements of section 39-11-102.
(4) The
treasurer may, at their discretion, sell tax liens on mobile homes, may strike
off to the county the tax liens by making them county-held, or may determine
the taxes to be uncollectible and recommend cancellation by the board of county
commissioners in accordance with section 39-10-114 (2)(a). If a tax lien on a
mobile home will be sold, the sale shall be in accordance with article 11 of
this title 39. The treasurer shall issue a certificate of purchase as provided
in section 39-11-117 to the purchaser of a tax lien on a mobile home or to the
county if the tax lien on a mobile home is county-held.
(5)
Redemptions of mobile homes that are subject to tax liens pursuant to
subsection (4) of this section must be in accordance with subsection (6) of
this section and articles 11.5 and 12 of this title 39.
(6) (a)
(I) Except as provided in subsection (6)(a)(II) of this section, a mobile
home owner has the exclusive right to redeem a mobile home that is subject to a
tax lien at any time within three years from the date of the tax lien sale upon
payment to the treasurer of the amount of taxes, delinquent interest, fees, and
costs for which the tax lien on the mobile home was sold, interest on such
amount from the date of the sale at the rate that is determined pursuant to
section 39-12-103 (3), and all taxes due and payable on the mobile home
subsequent to the tax lien sale. At any time within three years from the date
of the tax lien sale, a mobile home owner may redeem a mobile home that is
subject to the tax lien at any time before the execution of a certificate of
ownership pursuant to subsection (6)(c) of this section by making payment in
accordance with this subsection (6)(a)(I). The county may, in its discretion,
reduce the amount of costs required to be paid by the mobile home owner for the
sale of a county-held tax lien to redeem the mobile home pursuant to this
subsection (6)(a)(I).
(II) An
individual who both owns a mobile home and is a person with a legal disability
at the time a certificate of ownership to the owner's mobile home is issued has
the right to redeem the mobile home at any time within nine years from the date
of issuance of the certificate of ownership in accordance with section
39-12-104.
(b)
Upon redemption pursuant to subsection (6)(a) of this section, the treasurer
shall issue a certificate of redemption and disburse the redemption money
including to the purchaser or lawful holder of the certificate of purchase, if
applicable, in accordance with article 12 of this title 39.
(c) If
the owner has not exercised the right of redemption pursuant to subsection
(6)(a) of this section, at any time at least three years from the date of the
tax lien sale, the purchaser or lawful holder of the certificate of purchase
may apply to the treasurer for a certificate of ownership for the mobile home.
Upon receipt of an application, the treasurer shall notify the owner of the
mobile home and any lienholder of record by personal delivery or by mail to the
person's last-known address, that an application for public auction of a
certificate of option for treasurer's certificate of ownership has been
received and that, following public auction, the winning bidder may be issued a
treasurer's certificate of ownership for the mobile home, unless payment is
made for redemption. The treasurer shall conduct a public auction of a
certificate of option for treasurer's certificate of ownership consistent with
the provisions for public auction, including overbid, of a certificate of
option for treasurer's deed in article 11.5 of this title 39.
(d) The
treasurer shall disburse any surplus proceeds resulting from the public auction
deemed overbid proceeds, as defined in section 39-11.5-112, to the persons
entitled to receive them in accordance with statute.
(e) (I)
(A) If a mobile home that is subject to a tax lien or stricken off to the
county pursuant to this section is located on real property that is not owned
by the owner of the mobile home, the underlying landowner has a right of first
refusal to pay the delinquent taxes owed on the mobile home and all statutory
fees, costs, and expenses incurred by the treasurer in connection to the tax
lien sale process; except that an owner of a mobile home park, as defined in
section 38-12-201.5 (6), does not have a right of first refusal as described in
this subsection (6)(e) unless the owner of the mobile home park is an
association of mobile home owners.
(B) For
purposes of this subsection (6)(e), "underlying landowner" means the
owner of the real property upon which the mobile home is located.
(II) No
more than thirty calendar days but not less than ten calendar days prior to the
date of the tax lien sale provided for in subsection (3) of this section, the
treasurer shall send notice by mail to the underlying landowner at the address
shown in the records of the county assessor or treasurer, including, at a
minimum:
(A) The
amount of delinquent taxes, fees, costs, and expenses due in connection with
the mobile home;
(B) The
time, date, and place of the tax lien sale; and
(C) The
underlying landowner's right of first refusal under subsection (6)(e)(I) of
this section.
(III)
An underlying landowner may exercise the landowner's right of first refusal by
paying to the treasurer the full amount described in the subsection
(6)(e)(II)(A) of this section no later than two business days prior to the date
of the tax lien sale.
(IV) If
an underlying landowner exercises their right of first refusal pursuant to
subsection (6)(e)(III) of this section the treasurer shall:
(A)
Cancel the tax lien sale;
(B)
Issue to the underlying landowner evidence of payment and satisfaction of the
delinquent taxes and costs; and
(C)
Issue a certificate of purchase to the underlying landowner pursuant to section
39-11-117, evidencing satisfaction of the delinquent taxes and costs.
(V) If
an underlying landowner does not exercise their right of first refusal, the
treasurer shall proceed with the tax lien sale or county strike off as
otherwise provided in this section.
(VI)
This subsection (6)(e) does not create a right of first refusal for any person
other than the underlying landowner and does not affect the rights of secured
parties or lienholders, if any, except as expressly provided in this section.
(f) (I)
If the treasurer does not issue a certificate of purchase for a tax lien on a
mobile home pursuant to subsection (4) of this section, or if the purchaser or
lawful holder of a certificate of purchase or the owner of the mobile home is
unable to obtain a certificate of title pursuant to section 42-6-117 due to the
lack of proof of ownership or failure to satisfy bonding requirements, the
treasurer may declare the tax lien stricken off to the county.
(II)
Except as provided in subsection (6)(f)(IV) of this section, when a tax lien is
stricken off to the county pursuant to this subsection (6)(f), the most recent
mobile home owner may redeem the mobile home after one year but no later than
three years from the date of strike off by paying the amount of delinquent
taxes, interest, fees, and costs.
(III)
If the owner does not redeem the mobile home within the three-year redemption
period and after notice to the last-known owner and any lienholder of record in
accordance with section 39-10-109 and providing an opportunity to be heard, the
treasurer or county assessor may declare the mobile home abandoned for purposes
of this section. Upon this declaration, the assessor may remove the mobile home
from the county tax roll and the treasurer may authorize the underlying
landowner or the county to remove and dispose of the mobile home in accordance
with county abandoned property procedures.
(IV)
(A) If an occupant of a mobile home establishes proof of ownership, but
their ownership is not of record, then the redemption period for the most
recent mobile home owner is the one-year period provided by law. If the mobile
home has not been redeemed, the treasurer may issue the occupant a certificate
of ownership for the mobile home. The certificate of ownership constitutes
sufficient evidence of ownership for purposes of obtaining a certificate of
title pursuant to section 42-6-117, without a requirement for additional public
notice or a public auction process. A certificate of ownership issued to an
occupant has the same legal effect as a title issued pursuant to section
39-11.5.-115. The treasurer may collect a fee as authorized by section 42-4-510
(2)(a).
(B) For
purposes of this subsection (6)(f), "occupant" means a person
residing in a mobile home as their primary residence as established by at least
two documents, including a current utility bill for service to the mobile home
in the occupant's name; a current government-issued identification document
listing the mobile home as physical address; a current lease, lot rental
agreement, or written permission from the underlying landowner; official mail
to the occupant at the mobile home address; or, a sworn affidavit of occupancy
signed under penalty of perjury.
(C) A
person who fails to establish that they are the occupant of the mobile home in
accordance with the requirements of subsection (6)(f)(IV)(B) of this section
may not assert any right as an occupant pursuant to this subsection (6)(f).
(7)
Repealed.
Source:
L. 2017: Entire
section added, (HB 17-1354), ch. 215, p. 838, § 2, effective August 9. L.
2020: (6)(a)(I) and (7) amended, (HB 20-1077), ch. 80, p. 326, § 15,
effective September 14. L. 2024: (2)(a) amended and (2.5) added, (SB
24-183), ch. 303, p. 2059, § 1, effective May 31. L. 2026: (2)(a),
(2)(c), (3), (4), (5), and (6) amended and (2)(b) and (7) repealed, (HB
26-1120), ch. 268, p. 1520, § 2, effective June 1.
Editor's
note: Subsection
(2.5)(c) provided for the repeal of subsection (2.5), effective September 1,
2025. (See L. 2024, p. 2059.)
39-10-112. Action to collect unpaid
taxes.
(1) (a)
In order to collect delinquent personal property taxes and any delinquent
interest thereon, the treasurer may, at the treasurer's option, sue the owner
of the personal property in any court in the treasurer's county having
jurisdiction, enter into a contract to employ the services of any collection
agency that is duly licensed pursuant to section 5-16-119 or 5-16-120, or
distrain, seize, and sell the personal property as provided in section
39-10-111.
(b) Any
contract to employ the services of any duly licensed collection agency shall be
awarded by competitive bid, but the treasurer may reject any or all bids or
parts of bids. The fees of the collection agency shall be paid by the treasurer
from the moneys recovered by the collection agency, but in no event shall the
fees paid to the collection agency exceed one-third of the amount recovered.
(2)
(Deleted by amendment, L. 96, p. 14, § 2, effective February 22, 1996.)
(3)
Upon the trial of any court action brought pursuant to subsection (1) of this
section, a certificate from the treasurer, reciting the amount of the taxes and
any delinquent interest thereon and that the same has not been paid, shall be
prima facie evidence that the amount claimed is due and unpaid, and judgment
shall be given for the amount thereof, together with all costs, and execution
shall issue as in other cases. Whenever the treasurer sues in court, the county
attorney shall perform all legal work involved if requested by the treasurer,
and the costs of the action shall be paid by the county.
(4)
Nothing in this section shall be construed as relieving the treasurer of the
duties of the office of county treasurer.
(5) and
(6) Repealed.
Source:
L. 64: R&RE,
p. 721, § 1. C.R.S. 1963: § 137-10-12. L. 91: Entire section
amended, p. 1973, § 4, effective March 27. L. 92: (1)(a)(I)(A) and (2)
amended, p. 2229, § 15, effective April 9. L. 94: Entire section
amended, p. 755, § 6, effective April 20. L. 96: Entire section amended,
p. 14, § 2, effective February 22. L. 2017: (1)(a) amended, (HB
17-1238), ch. 260, p. 1175, § 24, effective August 9. L. 2020: (5)
added, (HB 20-1421), ch. 108, p. 423, § 2, effective June 14. L. 2021:
(6) added, (SB 21-279), ch. 365, p. 2407, § 2, effective June 28.
Editor's
note: (1)
Subsection (5)(b) provided for the repeal of subsection (5), effective December
31, 2020. (See L. 2020, p. 423.)
(2) Subsection (6)(d) provided
for the repeal of subsection (6), effective December 31, 2021. (See L. 2021, p.
2407.)
39-10-113. Removal or transfer of
personal property - collection of taxes.
(1) (a)
If at any time after the lien of general taxes has attached the treasurer
believes for any reason that any taxable personal property may be removed from
the county or may be dissipated or distributed, so that taxes to be levied for
the current year may not be collectible, the treasurer may at once proceed to
collect the taxes and, if the treasurer deems it necessary, may distrain,
seize, and sell the personal property to enforce collection. Upon the
treasurer's request, the assessor shall certify to the treasurer the valuation
for assessment of the personal property for the current year. If the levy for
the current year has not then been fixed and made, the levy for the previous
year shall be used to determine the amount of taxes due.
(b)
Repealed.
(2)
Whenever the assessor notifies the treasurer of the valuation of any taxable
personal property, as provided in section 39-5-110 (2), which property the
assessor believes might be removed from the county, the treasurer may proceed
to collect the taxes on the property by commencing a court action for
collection or employing a collection agency as provided in section 39-10-112 or
by distraining, seizing, and selling the personal property as provided in
section 39-10-111 if either the treasurer or the assessor deems it necessary.
If the levy for the current year has not then been fixed and made, the levy for
the previous year shall be used to determine the amount of taxes due.
(3) At
such time as the levy for the current year has been fixed and made, the amount
of any taxes collected on personal property pursuant to the provisions of
subsection (1) of this section in excess of the amount correctly due and
payable shall be refunded to the owner of such property forthwith; but in all
cases where the amount of taxes so collected is less than the amount correctly
due and payable, the amount uncollected shall be considered an erroneous
assessment and shall be reported with other erroneous assessments in the manner
prescribed by law.
Source:
L. 64: R&RE,
p. 721, § 1. C.R.S. 1963: § 137-10-13. L. 67: p. 951, § 23. L.
70: p. 390, § 3. L. 83: (2) amended, p. 1484, § 8, effective April
22. L. 91: (1)(b) repealed, p. 270, § 9, effective July 1. L. 96:
(1) and (2) amended, p. 14, § 3, effective February 22. L. 2020: (1)(a)
and (2) amended, (HB 20-1077), ch. 80, p. 327, § 16, effective September 14.
ANNOTATION
Section 39-10-111 (11) and
this section do not authorize the distraint, seizure, and sale of the taxable
personal property of a lessor to satisfy the personal property tax of the
lessee. In re W. Pac. Airlines, 273 F.3d 1288 (10th Cir. 2001).
"Any taxable personal
property" means any taxable personal property of the taxpayer. In re
W. Pac. Airlines, 273 F.3d 1288 (10th Cir. 2001).
39-10-113.5. Improvements valued and
taxed separately - collection of taxes.
(1)
Notwithstanding any law to the contrary and except as otherwise provided in
this section, if taxes become delinquent upon improvements that have been
valued and taxed separately from land, the treasurer of the county in which
such taxes are delinquent may proceed to collect such taxes pursuant to the
provisions of sections 39-10-111, 39-10-112, and 39-10-113 as if such
improvements were personal property. The provisions of this section shall not
apply to mobile homes, improvements other than buildings on land that is used
solely and exclusively for agricultural purposes, and water rights, together
with any dam, ditch, pipeline, canal, flume, reservoir, bypass, conduit, well,
pump, or other associated structure or device, as defined in article 92 of title
37, C.R.S., being used to produce water or held to produce or exchange water to
support uses of any item of real property specified in section 39-1-102 (14),
including water rights used for agricultural purposes.
(2) (a)
The provisions of this section shall not apply to any property classified by
the assessor for property tax purposes as commercial property unless the
treasurer:
(I)
Finds that the improvements may be moved, dissipated, or distributed;
(II)
Determines that the taxes may be uncollectible;
(III)
Sets forth the reasons for such finding and determination in writing and either
serves such writing upon the owner of such improvements or, if the owner cannot
be located within the state, posts such writing conspicuously upon such
improvements.
(b)
Upon compliance with the requirements set forth in paragraph (a) of this
subsection (2), the treasurer may proceed to collect such taxes pursuant to the
provisions of subsection (1) of this section.
Source:
L. 92: Entire
section added, p. 2235, § 1, effective April 10. L. 96: (1) amended, p.
469, § 2, effective April 23.
39-10-114. Abatement - cancellation of
taxes.
(1) (a)
(I) (A) Except as otherwise provided in subsections (1)(a)(I)(D) and
(1)(a)(I)(E) of this section, if taxes have been levied erroneously or
illegally, whether due to erroneous valuation for assessment, irregularity in
levying, clerical error, or overvaluation, the treasurer shall report the
amount thereof to the board of county commissioners, which shall proceed to
abate such taxes in the manner provided by law. The assessor shall make such
report if the assessor discovers that taxes have been levied erroneously or
illegally. If such taxes have been collected by the treasurer, the board of
county commissioners shall authorize refund of the same in the manner provided
by law. Except as provided in subsections (1)(a)(I)(E) and (1)(a)(I)(F) of this
section and section 39-5-125 (4), in no case shall an abatement or refund of
taxes be made unless a petition for abatement or refund is filed within two
years after January 1 of the year following the year in which the taxes were
levied. For purposes of this subsection (1)(a)(I)(A), "clerical
error" shall include, but shall not be limited to, any clerical error made
by a taxpayer in completing personal property schedules pursuant to the
provisions of article 5 of this title. Notwithstanding any other law to the
contrary, for purposes of this subsection (1)(a)(I)(A), "erroneous
valuation" shall include, but shall not be limited to: Any
reclassification of property from agricultural land to any other classification
of property for the property tax year commencing January 1, 1996, if the
property in question qualifies for classification as agricultural land as
determined pursuant to section 39-1-102 (1.6), as amended by Senate Bill
97-039, enacted at the first regular session of the sixty-first general
assembly; and any denial of exemption from taxation for property claimed as
agricultural and livestock products for the property tax year commencing
January 1, 1996, if the property in question qualifies as agricultural and
livestock products as determined pursuant to section 39-1-102 (1.1), as amended
by Senate Bill 97-039, enacted at the first regular session of the sixty-first
general assembly.
(B) The
assessor shall certify the proportional amount of the total amount of
abatements and refunds granted pursuant to the provisions of this section to
the appropriate taxing entities at the same time as the certification of
valuation for assessment pursuant to section 39-5-128. Any taxing entity may
adjust the amount of its tax levy authorized pursuant to the provisions of
section 29-1-301 by an additional amount that does not exceed the proportional
share of the total amount of abatements and refunds made pursuant to this
section. After calculating the amount of property tax revenues necessary to
satisfy the requirements of the "Public School Finance Act of 2025",
article 54 of title 22, any school district shall add an amount equal to the
proportional share of the total amount of abatements and refunds granted
pursuant to the provisions of this section prior to the setting of the mill
levy for such school district. Any additional amount added pursuant to the
provisions of this subsection (1) must not be included in the total amount of
revenue levied in the year for the purposes of computing the limit for the
succeeding year pursuant to the provisions of section 29-1-301. When a final
determination is made granting an abatement or refund pursuant to the
provisions of this section, the abatement or refund granted must be payable at
such time as determined by the board of county commissioners after consultation
with affected taxing entities but no later than upon the payment of property
taxes for the property tax year in which the final determination was made. For
the purposes of this subsection (1)(a)(I)(B), a taxing entity's proportional
share of the total amount of abatements and refunds granted must be based upon
the amount of tax levied by a taxing entity on the real property in proportion
to the total amount of tax levied on the real property by such taxing entities.
(B.5)
Notwithstanding the provisions of sub-subparagraph (B) of this subparagraph
(I), no school district shall be required to levy additional amounts for
abatements and refunds which are the result of any protests or appeals of
valuation upon which final orders or judgments rendered by a court of competent
jurisdiction have been issued and which reduce the valuation for assessment of
the district by more than twenty percent. Any school district which is
currently levying for abatements, refunds, or both and which would not be
required to levy such amounts if this sub-subparagraph (B.5) had been in effect
for the tax year in which the court orders or judgments were issued shall have
no further obligation to levy for uncollected amounts.
(C) The
change or adjustment of any ratio of valuation for assessment shall not constitute
grounds for abatement of taxes as provided in subsection (1)(a)(I)(A) of this
section.
(D) An
abatement or refund of taxes must not be made based upon the ground of
overvaluation of property if an objection or protest to such valuation has been
made and a notice of determination has been mailed to the taxpayer pursuant to
section 39-5-122; except that this prohibition does not apply to personal
property when a notice of determination has been mailed to the taxpayer, an
objection or protest is withdrawn or not pursued, and the county assessor has
undertaken an audit of such personal property that shows that a reduction in
value is warranted.
(E)
Notwithstanding the periods of limitation for filing a petition for and
determining the amount of an abatement or refund of taxes provided in
sub-subparagraphs (A) and (D) of this subparagraph (I), when an audit of prior
years' taxes for the period described in section 39-10-101 (2)(b) discloses
that taxes are due and owing on personal property or on mines and on oil and
gas leaseholds, such taxes shall be subtracted from any overpayment of such
taxes determined to be due pursuant to this subparagraph (I) for any years
during such period and prior to computing delinquent interest.
(F)
Notwithstanding the periods of limitation for filing a petition for and
determining the amount of an abatement or refund of taxes provided in
sub-subparagraph (A) or (D) of this subparagraph (I), an abatement or refund of
taxes may be made to any common interest community for property taxes levied
for property tax years commencing on or after January 1, 1985, but prior to
January 1, 1996, on property not valued in accordance with section 39-1-103
(10), if a petition for abatement or refund is filed on or before June 1, 1997.
(II)
Repealed.
(b) Any
taxes illegally or erroneously levied and collected, and delinquent interest
thereon, are refunded pursuant to this section, together with refund interest
at the same rate as that provided for delinquent interest set forth in section
39-10-104.5; except that refund interest shall not be paid if the taxes were
erroneously levied and collected as a result of an error made by the taxpayer
in completing personal property schedules pursuant to the provisions of article
5 of this title 39. For abatements or refunds made pursuant to a petition for
abatement or refund filed prior to January 1, 2018, refund interest accrues
from the date payment of taxes and delinquent interest thereon was received by
the treasurer from the taxpayer; except that refund interest accrues from the
date a complete abatement petition is filed if the taxes were erroneously
levied and collected as a result of an error or omission made by the taxpayer
in completing the statements required pursuant to the provisions of article 7
of this title 39 and the county pays the abatement or refund within the time
frame set forth in subsection (1)(a)(I)(B) of this section. For abatements or
refunds made pursuant to a petition for abatement or refund filed on or after
January 1, 2018, refund interest accrues from the date a complete abatement
petition is filed. Beginning January 1, 2020, refund interest accrues from the
date a complete abatement petition is filed or the date payment of taxes was
received by the treasurer, whichever is later.
(c)
Notwithstanding any other provision of this section, if a county, board of
assessment appeals, court of competent jurisdiction, or the property tax
administrator determines that a property is exempt from taxation under sections
39-3-106 to 39-3-113.5 or section 39-3-116, and if the county, board, court, or
administrator finds competent evidence that said property became or remained
subject to taxation for a period as a result of an error or omission made by
the taxpayer, then the county, the board of assessment appeals, court of
competent jurisdiction, or the property tax administrator may award refund
interest or any other type of interest for not greater than two property tax
years. Any interest awarded pursuant to this paragraph (c) shall be at the same
rate as provided in section 39-10-104.5.
(2) (a)
Any taxes levied on personal property, including but not limited to mobile
homes, which are determined to be uncollectible after a period of one year
after the date of their becoming delinquent may be canceled by the board of
county commissioners.
(b)
When any real property has been stricken off to a county by virtue of a tax
lien sale and there has been no transfer by the county of a certificate of
purchase thereon, the treasurer may determine the taxes on such property are
uncollectible after a period of five years from the date of the taxes becoming
delinquent, and the board of county commissioners may cancel the taxes. The
cancellation of the taxes on a property shall not affect the rights of the
county under article 11 of this title 39 to subsequently transfer any
certificate of purchase nor the county's right to receive a treasurer's deed
under article 11.5 of this title 39 and to exercise its rights thereunder with
respect to the property for which taxes are cancelled by the board of county
commissioners.
(3) The
treasurer shall keep a complete record of all taxes abated, refunded, or
determined to be uncollectible and canceled by the board of county
commissioners as provided in subsection (2) of this section. The treasurer
shall file an annual report with the administrator by August 25 of each year
that shall include all taxes abated, refunded, or determined to be
uncollectible and canceled. Such report shall include the name of each owner of
taxable property granted such abatement, refund, or cancellation of property
taxes, the amount of property taxes abated, refunded, or canceled, and the date
such abatement, refund, or cancellation was granted. The treasurer shall also
file an annual report with the department of revenue by August 10 of each year
that shall include all taxes on personal property abated or refunded. Such
report shall include the name of each owner of taxable personal property
granted such abatement or refund of personal property taxes, the schedule
number that was the basis for the imposition of the taxes abated or refunded,
if applicable, the amount of personal property taxes abated or refunded, and
the date such abatement or refund was granted.
Source:
L. 64: R&RE,
p. 722, § 1. C.R.S. 1963: § 137-10-14. L. 70: p. 390, § 4. L.
80: (2)(a) amended, p. 500, § 5, effective July 1. L. 81: (1)
amended, p. 1837, § 2, effective January 1, 1982. L. 88: (1)(a) and (3)
amended, p. 1290, § 24, effective May 23. L. 89: (1)(a)(I)(A) amended,
p. 1459, § 19, effective June 7. L. 90: (1)(b) amended, p. 1719, § 8,
effective June 7; (1)(a)(I)(B) amended and (1)(a)(I)(D) added, p. 1702, § 36,
effective June 9; (1)(b) amended, p. 1088, § 56, effective July 1. L. 91:
(1)(a)(I)(A), (1)(a)(I)(B), and (1)(a)(I)(D) amended, p. 1963, § 3, effective
June 5. L. 92: (1)(b) and (2)(a) amended, pp. 2230, 2236, §§ 16, 2,
effective April 9; (1)(a)(I)(A) and (1)(a)(I)(D) amended and (1)(a)(I)(E)
added, p. 2239, § 2, effective April 10; (1)(b) amended, p. 2186, § 68,
effective June 2. L. 93: (1)(b) amended, p. 306, § 7, effective April 7;
(1)(a)(I)(B.5) added, p. 998, § 1, effective June 2. L. 94: (1)(a)(I)(B)
amended, p. 825, § 57, effective April 27. L. 96: (1)(a)(I)(A) and (3)
amended, p. 115, § 3, effective March 25; (1)(a)(I)(A) and (1)(b) amended and
(1)(a)(I)(F) added, p. 573, § 1, effective April 25; (1)(a)(I)(D) and
(1)(a)(I)(E) amended, p. 650, §§ 4, 5, effective May 1. L. 97:
(1)(a)(I)(A) amended, p. 511, § 2, effective April 24. L. 2000: (3)
amended, p. 751, § 4, effective May 23. L. 2002: (1)(b) amended, p. 843,
§ 6, effective August 7. L. 2003: (1)(b) amended, p. 919, § 1, effective
August 6. L. 2009: (1)(c) added, (HB 09-1265), ch. 47, p. 170, § 1,
effective August 5. L. 2013: (1)(a)(I)(D) amended, (HB 13-1113), ch. 11,
p. 32, § 7, effective March 8; (1)(c) amended, (HB 13-1300), ch. 316, p. 1705,
§ 124, effective August 7. L. 2017: (1)(a)(I)(A) and (1)(b) amended, (HB
17-1049), ch. 148, p. 494, § 1, effective August 9. L. 2020:
(1)(a)(I)(D) amended, (SB 20-136), ch. 70, p. 293, § 38, effective September
14; (1)(b) amended, (HB 20-1077), ch. 80, p. 327, § 17, effective September 14.
L. 2021: (1)(a)(I)(C) amended, (SB 21-293), ch. 301, p. 1813, § 13,
effective June 23. L. 2024: (1)(a)(I)(B) amended, (HB 24-1448), ch. 236,
p. 1538, § 66, effective May 23. L. 2026: (2)(b) amended, (SB 26-144),
ch. 135, p. 602, § 4, effective June 1.
Editor's
note: (1)
Subsection (1)(a)(II)(B) provided for the repeal of subsection (1)(a)(II),
effective January 1, 1989. (See L. 88, p. 1290.)
(2) Amendments to subsection
(1)(a)(I)(A) by House Bill 96-1131 and House Bill 96-1290 were harmonized.
(3) Section 55(1) of chapter
135 (SB 26-144), Session Laws of Colorado 2026, provides that the act changing
this section applies to any fee imposed, assessed, or collected by a county
treasurer on or after June 1, 2026.
Cross
references: (1)
For the authorization for school districts to apply to the state contingency
reserve for assistance relating to abatements and refunds of taxes, see §
22-54-117; for the administrative procedure for abatement of taxes, see §
39-1-113; for approval of tax abatements and rebates by the property tax
administration, see § 39-2-116.
(2) For the legislative
declaration in SB 20-136, see section 1 of chapter 70, Session Laws of Colorado
2020.
ANNOTATION
I.
General Consideration.
II.
Obligations and Rights.
III.
Equity Jurisdiction.
I. GENERAL CONSIDERATION.
Law reviews. For
article, "A Calendar of Tax Procedure in Colorado", see 6 Dicta 17
(July 1929). For article, "The Tax Refund Statute Speaks", see 10
Dicta 196 (1933). For article, "The Reluctant Taxpayer: His Remedy by
Injunction", see 15 Dicta 137 (1938). For article, "Some Aspects of
Colorado Taxpayers' Remedies", see 23 Rocky Mt. L. Rev. 145 (1950). For
article, "Property Tax Assessments in Colorado", see 12 Colo. Law.
563 (1983). For article, "Legislative Update on Property Taxation and New
Arbitration Procedures", see 17 Colo. Law. 1751 (1988).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Subsection (1)(a)(I)(B) is
consistent with art. X, § 20 of the state constitution. Bolt v. Arapahoe
County Sch. Dist. No. 6, 898 P.2d 525 (Colo. 1995).
Court of appeals' review of
order of board of assessment appeals (BAA) as to illegality of excess mill levy
neither violates the separation of powers nor constitutes an advisory opinion.
The State Administrative Procedure Act specifically empowers the judicial
branch to review executive action. Parties may appeal a BAA decision to the
court of appeals under § 39-10-114.5 (2). Statutory interpretations are not
excluded from these appeals. Prospect 34, LLC v. Gunnison County Bd., 2015 COA
160, 363 P.3d 819.
The advisory opinion doctrine
does not preclude an appellate court from considering an issue because it is
involved in a pending but entirely separate district court action. The excess
mill levy question presents an actual controversy, not one based on
hypothetical or uncertain facts. Prospect 34, LLC v. Gunnison County Bd., 2015
COA 160, 363 P.3d 819.
Purpose of section.
Recognizing the law and appreciating the necessity of prompt payment of the
public revenue as an essential prerequisite to efficient government, the
general assembly enacted this section. Bd. of Comm'rs v. Atchison, T. & S.
F. Ry., 52 Colo. 609, 125 P. 528 (1912).
Action under this section
not forum to attack voidable judgment. A judgment ordering a tax levy for
payment of another judgment alleged to have been procured by fraud and
collusion is binding upon the taxpayers, unless and until the alleged voidable
judgment is set aside in a direct proceeding brought for that purpose. An
action under this section to recover taxes paid is not such direct proceeding.
Atchison, T. & S. F. Ry. v. Bd. of Comm'rs, 95 Colo. 435, 37 P.2d 761
(1934).
Since no specific method for
judicial review of the board's ruling under this section is provided, the
State Administrative Procedure Act, §§ 24-4-101 et seq., applies and judicial
review is proper in the city and county of Denver. Gunnison County v. Bd. of
Assess. Appeals, 693 P.2d 400 (Colo. App. 1984).
Protest and adjustment
procedures are separate and independent from abatement and refund procedures.
An appeal for a trial de novo under § 39-8-108 is not an "alternate
petition" for abatement or refund under subsection (1)(a)(I) of this
section. Wyler/Pebble Creek Ranch v. Colo. Bd. of Assess. Appeals, 883 P.2d 597
(Colo. App. 1994).
Taxpayer's petition for
abatement and refund is not precluded by subsection (1)(a)(I)(D) because it is
based upon an erroneous valuation for assessment, which is a legal issue,
rather than overvaluation, which is a factual issue. Taxpayer's abatement
petition asserts that, as a matter of law, absent unusual conditions that are
not at issue, the assessments for 1999 and 2000 must be the same, and the
argument requires a legal, rather than a factual, determination. Boulder
Country Club v. Boulder County Bd. of Comm'rs, 97 P.3d 119 (Colo. App. 2003).
This section does not
contain a provision for abatement or refund of property taxes paid by a
taxpayer through self-reporting of personal property it knows does not exist.
Boulder County Bd. of Comm'rs v. HealthSouth Corp., 246 P.3d 948 (Colo. 2011).
The power of the BAA to
order taxes abated under subsection (1)(a)(I)(A) extends to taxpayer's
assertion that the tax at issue exceeded the maximum mill levy allowed in
special district's service plan. The phrase "irregularity in
levying" encompasses an unlawful or illegal mill levy. Prospect 34, LLC v.
Gunnison County Bd., 2015 COA 160, 363 P.3d 819.
Refund interest is interest
paid to the taxpayer by the county to compensate the taxpayer for having paid
erroneously levied taxes; therefore refund interest begins to accrue until
the taxpayer pays the tax, and not on the date of a lien sale. Dove Valley Bus.
Park Assocs. v. Bd. of County Comm'rs of Arapahoe County, 923 P.2d 242 (Colo.
App. 1995), aff'd on other grounds, 945 P.2d 395 (Colo. 1997).
Applied in Lowden v. Bd.
of Comm'rs, 101 Colo. 52, 69 P.2d 779 (1937); Laredo Hous. Apts., Ltd. v. Bd.
of County Comm'rs, 628 P.2d 135 (Colo. App. 1980); Laredo Hous. Apts., Ltd. v.
Bd. of Assmt. Appeals, 675 P.2d 23 (Colo. App. 1983); Lucchesi v. State, 807 P.2d
1185 (Colo. App. 1990).
II. OBLIGATIONS AND RIGHTS.
This is substantive law,
giving a new right; this section has nothing to do directly with the law of
procedure. Union P. R. R. v. Bd. of Comm'rs, 222 F. 651 (8th Cir. 1915), rev'd
on other grounds, 247 U.S. 282 (1918).
This section imposes upon
county commissioners duty of refunding taxes which have been paid and are
found to be illegal. Singer Sewing Mach. Co. v. Benedict, 229 U.S. 481 (1913);
Union P. R. R. v. Bd. of County Comm'rs, 247 U.S. 282 (1918).
Correlative right upon
taxpayer to maintain action for refund. This section confers upon the
taxpayer a correlative right to enforce the county commissioners' duty of
refunding taxes by an action at law. Singer Sewing Mach. Co. v. Benedict, 229
U.S. 481 (1913); Union P. R. R. v. Bd. of County Comm'rs, 247 U.S. 282 (1918).
Taxpayer has right to maintain
suit at law in state court for recovery of a tax not legally laid, or growing
out of an illegal assessment, or the validity of which he has right to
question. Baker v. Atchison, T. & S. F. Ry., 106 F.2d 525 (10th Cir. 1939);
Northcutt v. Burton, 127 Colo. 145, 254 P.2d 1013 (1953), overruled in Bd. of
Assess. Appeals v. Benbrook, 735 P.2d 860 (Colo. 1987).
Property owner's remedy for
levy of excessive tax. In Colorado, the remedy of a property owner for the
levy of an excessive tax is to pay under protest and to bring an action against
the county to recover the same. Holly Sugar Corp. v. Bd. of Comm'rs, 10 F.2d
506 (D. Colo. 1926).
Tax must be illegal and void
for recovery in action at law. An error as to valuation of property for
taxation, even if excessive, does not render the tax illegal and void, which is
necessary in order to recover in an action at law. S. Broadway Nat'l Bank v.
City & County of Denver, 51 F.2d 703 (10th Cir. 1931).
Excessive application of
tax. An equity in school lands is a property right notwithstanding it may
have no cash value. If the land is of no value, an assessment thereon for tax
purposes would be merely excessive and not illegal. Bordner v. Bd. of Comm'rs,
92 Colo. 81, 18 P.2d 323 (1932).
Taxpayer's burden to show
illegal assessment. Where one attempts to maintain a proceeding for a tax
refund pursuant to this section, he has the burden of showing that the tax was
illegally laid, is erroneous in its entirety, and is incapable of adjustment.
Weidenhaft v. Bd. of County Comm'rs, 131 Colo. 432, 283 P.2d 164 (1955).
When section provides
taxpayer relief from overassessment. The provisions of this section provide
taxpayer relief from the overassessment of his property in situations where his
knowledge of the excessive charge is acquired subsequent to the usual statutory
deadlines for protests. Modular Cmtys., Inc. v. McKnight, 191 Colo. 101, 550
P.2d 866 (1976).
The term "erroneous
valuation for assessment" in this section and "excessive
valuation" under the protest adjustment provisions of § 39-5-122 refer to
the same process of assessment, and the remedies available to the taxpayer under
this section apply to refunds ordered pursuant to § 39-8-109. Bd. of Assess.
Appeals v. Benbrook, 735 P.2d 860 (Colo. 1987).
This section and § 39-1-113
provide a remedy for the abatement or refund of taxes that cannot be challenged
under § 39-5-122. Valley Country Club v. Bd. of Assess. Appeals, 778 P.2d 285
(Colo. App. 1989), rev'd on other grounds, 792 P.2d 299 (Colo. 1990).
Section does not provide
rights for tax lien purchasers. Hughey v. Jefferson County Bd. of Comm'rs,
921 P.2d 76 (Colo. App. 1996).
The abatement procedure may
be used to provide taxpayer relief from the overassessment of his property
in situations where his knowledge of excessive charges is acquired subsequent
to the usual statutory deadlines for protest. Valley Country Club v. Bd. of
Assess. Appeals, 778 P.2d 285 (Colo. App. 1989), rev'd on other grounds, 792
P.2d 299 (Colo. 1990).
Subject to specified
exception, relief under subsection (1)(a)(I)(A) is not available for taxes
levied prior to January 1, 1988. Capital Assoc. Intern. v. Arapahoe
Com'rs., 802 P.2d 1180 (Colo. App. 1990).
Prior to suit, taxpayer must
exhaust administrative remedies. The remedies contained in this section and
§ 39-1-113 are complete and adequate; thus, prior to commencing a suit on
illegal taxation issues, taxpayers are required to exhaust the administrative
remedies detailed in these sections. Davison v. Bd. of County Comm'rs, 41 Colo.
App. 344, 585 P.2d 315 (1978); S. Cafeteria, Inc. v. Propty. Tax Adm'r, 677
P.2d 362 (Colo. App. 1983).
Administrative remedies
available under this article cannot be dispensed with. First Nat'l Bank v. Bd.
of County Comm'rs, 264 U.S. 450 (1924).
Invocation of administrative
remedies must be alleged. A complaint is fatally defective where it does
not contain the indispensable allegation that administrative remedies have been
invoked. Bordner v. Bd. of Comm'rs, 92 Colo. 81, 18 P.2d 323 (1932).
County is liable to one who
pays tax imposed without authority of law. An unsatisfied judgment
recovered by the taxpayer against the collector is no bar to his action against
the county, even though the collector made no return to the county and
converted the money to his own use. Spaulding Mfg. Co. v. Bd. of Comm'rs, 63 Colo.
438, 168 P. 34 (1917).
Illegal or erroneous tax.
Where one owner of a converted condominium, after pursuing administrative
remedies under § 39-5-122, obtained a declaration from district court that the
imposition of an increased tax on his converted condominium was illegal,
petitioners, as owners of identical condominiums, were entitled to seek relief
under the abatement and refund provisions of § 39-1-113 and this section
because the tax had been declared illegal. Bd. of Assess. Appeals v. Benbrook,
735 P.2d 860 (Colo. 1987); Am. Airlines v. Bd. of Equaliz., 749 P.2d 986 (Colo.
App. 1987), rev'd on other grounds, 773 P.2d 1033 (Colo. 1989).
There is no need to
characterize the tax paid as wholly illegal before the taxpayer may obtain
abatement and refund. Bd. of Assess. Appeals v. Benbrook, 735 P.2d 860 (Colo.
1987).
The administrator's
determination that 1989 property tax was excessive does not render the tax
illegal or otherwise erroneous and did not thereby provide an avenue for
taxpayer to obtain an abatement of 1990 taxes because there was no evidence of
changed or unusual conditions between 1989 and 1990. Yale Invs., Inc. v. Prop.
Tax Adm'r, 897 P.2d 890 (Colo. App. 1995).
Where assessor failed to
give timely notice of property valuation, proper remedy is not to
invalidate tax but to allow taxpayer to seek abatement of the tax increase
pursuant to this section. Bea Kay Real Estate Corp. v. Aragon, 782 P.2d 837
(Colo. App. 1989).
While subsection
(1)(a)(I)(D) bars a petition for abatement only in those situations in which
the determination of the prior protest "has been mailed to the
taxpayer", there was sufficient evidence to show the determination was
mailed to an agent of the taxpayer and as such was authorized to receive the
notice on behalf of the taxpayer. Yale Invs., Inc. v. Prop. Tax Adm'r, 897 P.2d
890 (Colo. App. 1995).
Abatement and refund allowed
for illegally or erroneously levied taxes based on overvaluation caused by
taxpayer error. Where overvaluation of property and consequent overpayment
of property tax results solely from the taxpayer's inadvertent error, the
taxpayer has a right to seek abatement and refund under subsection
(1)(a)(I)(A). OXY USA Inc. v. Mesa County Bd. of Comm'rs, 2017 CO 104, 405 P.3d
1142.
Where error is due at least
in part to the taxing authority, a taxpayer can recover a refund under the
clerical error provision of this section, after the time to protest under §
39-5-122 has passed. Coquina Oil Corp. v. Bd. of Equaliz., 770 P.2d 1196 (Colo.
1989).
Section does not enlarge
right to contest an overvaluation. It expresses an intent merely to
restrict the statute of limitations as to abatement claims. 5050 S. Broadway
Corp. v. Arapahoe County Bd. of Comm'rs, 815 P.2d 966 (Colo. App. 1991).
Clerical error doesn't
encompass the mistakes of an assessor who makes factual errors in property
valuations. A challenge to a valuation that involves a claim that comparable
properties used were overvalued is not clerical error. 5050 S. Broadway Corp.
v. Arapahoe County Bd. of Comm'rs, 815 P.2d 966 (Colo. App. 1991).
Nor taxpayer's error in failing
to insure that recorded deed correctly described land conveyed. Citibank v. Bd.
of Assess. Appeals, 826 P.2d 871 (Colo. 1992).
Taxpayer may seek an
abatement and refund under this section even though taxpayer initially
protested valuation of the property under § 39-5-122, because the taxpayer did
not base its petition for abatement on the ground of overvaluation but on the
arbitrator's clerical error. Landmark Petroleum v. Bd. of County Comm'rs, 870
P.2d 610 (Colo. App. 1993).
When arbitrator made a
clerical error in an award and award does not reflect the valuation
intended by the arbitrator, a taxpayer may file for an abatement and refund.
Arbitrator attempted to remedy the error within a reasonable time by reporting
the error within two days of entering the award. Landmark Petroleum v. Bd. of
County Comm'rs, 870 P.2d 610 (Colo. App. 1993).
Taxpayer sufficiently
demonstrated an injury to a legally protected right when he sought relief
for an alleged overvaluation of property. Utah Motel Assocs. v. Denver County
Bd. of Comm'rs, 844 P.2d 1295 (Colo. App. 1992).
Abatement is not the only
remedy for overvaluation of property when property has filed a timely
protest to assessor's valuation and appealed. Tenney v. Bd. of Assess. Appeals,
856 P.2d 89 (Colo. App. 1993).
Challenges based on
overvaluation. Although taxpayers challenged the amount of taxes assessed
as excessive, this was not an "overvaluation" as the term is used in
this statute because, due to the taxpayers' wrongful inaction, the assessor's
BIA valuations are presumed to be valid. Therefore, for purposes of this
statute, the assessor's valuation cannot be considered an overvaluation, and
this section may not be asserted by a taxpayer to avoid the provisions of §
39-5-118 and the protest procedure under § 39-5-122. Prop. Tax Adm'r v. Prod.
Geophysical, 860 P.2d 514 (Colo. 1993).
Application of abatement
procedure to personal property taxes. The protest procedure set forth in §
39-5-122, as opposed to the abatement procedure set forth in this section, is
the exclusive method for challenging personal property BIA evaluations. Prop.
Tax Adm'r v. Prod. Geophysical, 860 P.2d 514 (Colo. 1993); Spectra Pub. v.
Prop. Tax Adm'r, 860 P.2d 520 (Colo. 1993).
Taxpayer did not lack
standing to file for abatement even though he was the purchaser of the
property on which the taxes were due and did not himself pay the taxes. Utah
Motel Assocs. v. Denver County Bd. of Comm'rs, 844 P.2d 1295 (Colo. App. 1992).
A nonoperating fractional
interest owner does not have a legally protected interest in the valuation and
taxation of their oil and gas leasehold and land and, therefore, lacks
standing to challenge a retroactive assessment and property tax increase. Colo.
Prop. Tax Adm'r v. CO2 Comm., 2023 CO 8, 527 P.3d 371.
The four-year time
limitation for bringing suit under § 20 of article X of the Colorado
Constitution (TABOR) does not affect the two-year time limitation set forth in
this section. Prop. Tax Adjustment Specialists, Inc. v. Mesa County Bd. of
Comm'rs, 956 P.2d 1277 (Colo. App. 1998).
In calculating the two-year
limitation for filing a personal property tax abatement petition pursuant
to subsection (1)(a)(I)(A), the day from which the two-year period runs is
excluded and the last day is included. If the last day is a holiday, the period
is extended one day. Golden Aluminum v. Weld County Comm'rs, 867 P.2d 190
(Colo. App. 1993).
Two-year limitation period
may not be applied to park and recreation district that was required to pay
taxes due from the previous owner of land but did not receive various notices
required by statute. S. Suburban Park & Recreation Dist. v. Bd. of Assess.
Appeals, 894 P.2d 771 (Colo. App. 1994).
Refunds and abatements for
tax years before 1990 are time barred, unless a petition was filed prior to
January 2, 1992. Woodmoor Imp. v. Prop. Tax Adm'r, 895 P.2d 1087 (Colo. App.
1994).
No violation of the
prohibition against retrospective laws existed in court's application of
two-year statute of repose, rather than prior six-year statute, to homeowners'
association's petition for abatement and refund. Woodmoor Imp. v. Prop. Tax
Adm'r, 895 P.2d 1087 (Colo. App. 1994).
It is appropriate for court
to give deference to contemporaneous construction of statute by the agency
charged with its administration. The property tax administrator had issued
a memorandum to county tax assessors to the same effect as the court's holding.
Bd. of Assess. Appeals v. Country Club, 792 P.2d 299 (Colo. 1990); Utah Motel
Assocs. v. Denver County Bd. of Comm'rs, 844 P.2d 1295 (Colo. App. 1992).
Statutes governing abatement
and refund procedure do not address whether multiple abatement-refund petitions
are permissible regarding same property for same tax year, but second
abatement-refund action differing from first only in that taxpayer sought a
further valuation reduction is barred under principles of res judicata or claim
preclusion. Red Junction, LLC v. Mesa County Bd. of County Comm'rs, 174 P.3d
841 (Colo. App. 2007).
For neglect of taxpayer
barring relief, see Miller v. Bd. of County Comm'rs, 92 Colo. 425, 21 P.2d
714 (1933); E. A. Stephens & Co. v. Bd. of Equaliz., 104 Colo. 556, 92 P.2d
732 (1939).
III. EQUITY JURISDICTION.
Remedy afforded by this
section is suit at law and is available in the federal courts the same as
in state courts. Union P. R. R. v. Bd. of Comm'rs, 222 F. 651 (8th Cir. 1915),
rev'd on other grounds, 247 U.S. 282 (1918).
This section affords an
adequate remedy at law in case of an illegal or erroneous levy. Denver & R.
G. R. R. v. Bd. of Comm'rs, 69 Colo. 212, 193 P. 555 (1920); Union Nat'l Bank
v. Bd. of Comm'rs, 75 Colo. 298, 225 P. 851 (1924).
Equity will not entertain
jurisdiction unless there exists some recognized equitable ground for the
granting of relief. Denver & R. G. R. R. v. Bd. of Comm'rs, 69 Colo. 212,
193 P. 555 (1920).
Exceptional circumstances
required. Upon a full consideration of public interest, of judicial
pronouncement in general upon the subject involved, and of this section, which
affords a complete remedy in a proper case, it is rarely possible, and then
under most exceptional and unusual circumstances, that a cause of action to
restrain the collection of taxes can be stated of which equity will or ought to
take cognizance. Grater v. Logan High Sch. Dist., 64 Colo. 600, 173 P. 714
(1918).
Injunctive interference in
collection of public revenues opposed. Public interest, judicial
announcement, and statutory enactment are opposed to injunctive interference in
the collection of the public revenues. Bd. of Comm'rs v. Atchison, T. & S.
F. Ry., 52 Colo. 609, 125 P. 528 (1912); Tallon v. Vindicator Consol. Gold
Mining Co., 59 Colo. 316, 149 P. 108 (1915); Nile Irrigation Dist. v. English,
60 Colo. 406, 153 P. 760 (1915); Kendrick v. A. Y. & Minnie Mining &
Milling Co., 63 Colo. 214, 164 P. 1161 (1917).
Tax must be prima facie void
before equity will interfere. It is a prerequisite, before a court of
equity will interfere to restrain the collection of taxes, as a general rule,
though there may be some exceptions, that the tax must be prima facie void.
Tallon v. Vindicator Consol. Gold Mining Co., 59 Colo. 316, 149 P. 108 (1915).
Principles of equity did not
prohibit application of two-year statute of repose where homeowners'
association failed to allege that assessor concealed facts or otherwise
prevented it from filing a timely petition, was aware of its status as a
nonprofit association, received yearly tax assessments, and failed to file a
petition for abatement until eight months after due date. Woodmoor Imp. v.
Prop. Tax Adm'r, 895 P.2d 1087 (Colo. App. 1994).
39-10-114.5. Decision - review - judicial
review.
(1) If
the board of county commissioners, pursuant to section 39-10-114 (1), or the
property tax administrator, pursuant to section 39-2-116, denies the petition
for refund or abatement of taxes in whole or in part, the petitioner may appeal
to the board of assessment appeals pursuant to the provisions of section
39-2-125 within thirty days of the entry of any such decision.
(2) If
the petitioner has appealed to the board of assessment appeals and the decision
of the board of assessment appeals is against the petitioner, the petitioner
may petition the court of appeals for judicial review according to the Colorado
appellate rules and the provisions of section 24-4-106 (11), C.R.S. If the
decision of the board is against the respondent, the respondent, upon the
recommendation of the board that it either is a matter of statewide concern or
has resulted in a significant decrease in the total valuation for assessment of
the county wherein the property is located, may petition the court of appeals
for judicial review according to the Colorado appellate rules and the
provisions of section 24-4-106 (11), C.R.S. In addition, if the decision of the
board is against the respondent, the respondent may petition the court of
appeals for judicial review of alleged procedural errors or errors of law when
the respondent alleges procedural errors or errors of law by the board of
assessment appeals. If the board does not recommend its decision to be a matter
of statewide concern or to have resulted in a significant decrease in the total
valuation for assessment of the county in which the property is located, the
respondent may petition the court of appeals for judicial review of such
questions.
Source:
L. 90: Entire
section added, p. 1695, § 14, effective June 9. L. 96: (2) amended, p.
651, § 6, effective May 1.
ANNOTATION
The 30-day time period
begins on the date notice was mailed to the taxpayer's last known address when
nondelivery of notice attributable to taxpayer's own failure to provide a
current address. Ward v. Douglas County Bd. of Comm'rs, 886 P.2d 310 (Colo.
App. 1994).
Taxpayer fully exhausted the
available administrative remedies, giving the state board of assessment appeals
(BAA) jurisdiction to consider the appeal, even though taxpayer did not
attend the county hearing or present evidence, where taxpayer timely filed a
petition for refund or abatement of real property taxes with the county and
received notice of a hearing; after the mandatory hearing, received notice of
the county's denial of the petition and was informed that it had the right to
appeal the board's decision to the BAA; and taxpayer then filed a timely
petition with the BAA. Isbill Assocs., Inc. v. Jefferson County Bd. of County
Comm'rs, 894 P.2d 52 (Colo. App. 1995).
Under the abatement and
refund scheme, only taxpayers are authorized to appeal actions of the property
tax administrator to the board of assessment appeals, and then only to the
extent the petition has been denied. By approving taxpayer's petition
"conditionally" or otherwise and submitting it to the property tax
administrator for further action, the board of county commissioners' procedural
rights as a party ended under the statutory scheme governing abatement and
refund proceedings. Huerfano County Bd. of County Comm'rs v. Atlantic Richfield
Co., 976 P.2d 893 (Colo. App. 1999).
The abatement and refund
procedure under this section is a separate and independent procedural system
than the protest and adjustment procedure and is governed by a different
statute. Huerfano County Bd. of County Comm'rs v. Atlantic Richfield Co., 976
P.2d 893 (Colo. App. 1999).
Court of appeals' review is
limited to the propriety of the board of assessment appeals'
determinations, not those of the assessor. Home Depot USA, Inc. v. Pueblo
County Bd. of Comm'rs, 50 P.3d 916 (Colo. App. 2002).
Applied in Prop. Tax
Adjustment Specialists, Inc. v. Mesa County Bd. of Comm'rs, 956 P.2d 1277
(Colo. App. 1998).
39-10-115. Certificate of taxes due.
(1)
Upon request, the treasurer shall certify in writing the full amount of taxes
due upon any parcel of real property or mobile home in his or her county, and
all outstanding sales for unpaid taxes as shown by the records of his or her
office or the records of the department of revenue, with the amount required
for redemption of such sales, if the same still are redeemable. The treasurer
shall include on such certificate of taxes due an itemized list of the mill
levies and amount of taxes and assessments imposed by each taxing jurisdiction
and a statement that information regarding special taxing districts and the
boundaries of such districts may be on file or deposit with the board of county
commissioners, the county clerk and recorder, or the county assessor. A fee
shall be collected for each such certificate issued by him or her, as provided
in section 30-1-102, C.R.S.
(2)
When signed by the treasurer, such certificate, showing payment of all taxes
due and the redemption of all outstanding tax sales, shall be conclusive
evidence for all purposes and against all persons that the parcel of real
property or mobile home therein described was, at the time, free and clear of
all property taxes due to the county and from all tax sales except tax sales
whereon the time for redemption had already expired and the purchaser had
received a deed.
(3) Any
loss resulting to any person from an error in a tax certificate issued by the
treasurer shall be paid by the county represented by the treasurer issuing such
certificate.
(4) No
person other than the treasurer or an authorized agent of the treasurer shall
issue any property tax certificate.
Source:
L. 64: R&RE,
p. 722, § 1. C.R.S. 1963: § 137-10-15. L. 69: p. 1122, § 1. L.
71: p. 327, § 6. L. 82: (1) amended, p. 551, § 16, effective July 1.
L. 83: (2) amended, p. 2053, § 26, effective October 14. L. 90:
(4) added, p. 1643, § 2, effective May 22. L. 91: (1) amended, p. 794, §
23, effective January 1, 1992. L. 2000: (1) amended, p. 1638, § 16,
effective June 1. L. 2020: (2) amended, (HB 20-1077), ch. 80, p. 328, §
18, effective September 14.
ANNOTATION
Law reviews. For comment
on Burton v. City & County of Denver appearing below, see 9 Rocky Mt. L.
Rev. 289 (1937). For comment on Denver v. Highlander Boy Found. appearing
below, see 11 Rocky Mt. L. Rev. 124 (1939).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Section is constitutional.
This section does not violate the provisions of §§ 3, 8, 9, and 10 of art. X,
Colo. Const., nor §§ 25 and 38 of art. V, Colo. Const. Burton v. City &
County of Denver, 99 Colo. 207, 61 P.2d 856 (1936).
Plaintiff, a quasi-municipal
corporation and political subdivision of the state, was not a person under
§ 39-1-102 (9) and did not have standing to seek damages pursuant to subsection
(3) of this section. Bear Creek Water and Sanitation Dist. v. Bd. of County
Comm'rs of Jefferson County, 902 P.2d 904 (Colo. App. 1995).
Applied in Nat'l Sur.
Co. v. Canon, 62 Colo. 401, 163 P. 284 (1917); City & County of Denver v.
Highlander Boy Found., 102 Colo. 365, 79 P.2d 361 (1938).
39-10-116. Civil penalty for checks not
paid upon presentment.
The
treasurer shall assess a penalty up to the amount authorized in section
13-21-109 (1)(b), C.R.S., against any person who issues a check to the
treasurer in payment of taxes, interest, fees, or other charges collectible by
the treasurer that is not paid upon its presentment. The penalty provided in
this section shall be assessed in addition to any other penalties or interest
provided by law.
Source:
L. 79: Entire
section added, p. 1421, § 6, effective January 1, 1980. L. 88: Entire
section amended, p. 1106, § 2, effective January 1, 1989. L. 95: Entire
section amended, p. 36, § 2, effective March 17.
ARTICLE
11
Sale
of Tax Liens
39-11-100.3. Definitions.
39-11-101. Notice to delinquent owner.
39-11-102. Treasurer to publish and post
notice.
39-11-103. Treasurer to make affidavit of
posting.
39-11-104. Publisher's affidavit - form.
39-11-105. Selection of newspaper publishing
notice.
39-11-106. Advertising and tax lien sale fees.
39-11-107. Erroneous assessments - abatement.
39-11-108. Manner of conducting tax lien sale
- definitions.
39-11-109. Time of tax lien sale.
39-11-110. When tax lien sale can be held.
39-11-111. Method of payment.
39-11-112. Erroneous name or assessment in
wrong county - effect.
39-11-113. Abbreviations, letters, and figures
may be used.
39-11-114. Record of sales of tax liens on
property.
39-11-115. To whom tax lien shall be sold.
39-11-116. Procedure when purchaser fails to
pay.
39-11-117. Certificate of purchase.
39-11-118. Certificate of purchase assignable.
39-11-119. Subsequent payment by holder.
39-11-120. Certificate of purchase -
application for tax lien for treasurer's deed - lost or wrongfully withheld -
county held.
39-11-121. Municipalities, prior sales
validated.
39-11-122. Transfer of certificates of
purchase by counties.
39-11-123. Transfer of certificates of
purchase - irrigation or drainage district taxes.
39-11-124. Counties, prior sales validated.
39-11-125. Disposal of certificates of
purchase by districts.
39-11-126. Agreement with county
commissioners.
39-11-127. Irrigation or drainage districts,
prior sales validated.
39-11-128. Condition precedent to deed -
notice.
39-11-129. Tax deed - issuance, execution, requirements.
(Repealed)
39-11-130. Fees included in redemption money.
(Repealed)
39-11-131. Notice of application for deed.
(Repealed)
39-11-132. Prior notices or requests
containing more than one parcel - validation. (Repealed)
39-11-133. Suit to quiet title. (Repealed)
39-11-134. Defects in tax deed, effect.
(Repealed)
39-11-135. Form of tax deed. (Repealed)
39-11-136. Treasurer to execute deed - effect.
(Repealed)
39-11-137. Validation of acknowledgments of
tax deeds. (Repealed)
39-11-138. When successor of treasurer shall
act.
39-11-139. Posting list of county-held tax
liens and county-acquired treasurer's deeds.
39-11-140. Treasurer's deed recorded - entry.
39-11-141. Action to determine validity of
certificate of purchase.
39-11-142. Disposition of certificates of
purchase held by counties.
39-11-143. Appraisal - county may retain,
lease, or sell - definitions.
39-11-144. County property, prior sales
validated.
39-11-145. Proceeds of sales.
39-11-146. Lien of special assessment not
affected.
39-11-147. Treasurer to report payments.
39-11-148. Limitations on certificates of
purchase - special improvement liens.
39-11-149. Sales en masse valid.
39-11-150. Sales of tax liens on severed
mineral interests.
39-11-151. County officials and employees may
not acquire a tax lien by tax lien sale.
39-11-152. Combined sale of delinquent tax
liens and special assessment liens.
39-11-153. Interaction with other law.
39-11-100.3. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Date of sale" means the date on which a tax lien sale ends.
(2)
"Electronic funds transfer" means a transfer of funds initiated by
using electronic means, including automated clearing house, credit or debit
card, or wire transfer. "Electronic funds transfer" does not include
a transaction originated by check, draft, or similar paper instrument.
(2.5)
"Immediate family" means a spouse, parent, grandparent, child,
grandchild, or sibling of an individual and includes a spouse of any immediate
family member.
(2.7)
"Investor" means an individual, business entity, trust, or other
entity that may purchase a tax lien on property at a tax lien sale.
(3)
"Negotiable paper" means a bank check, draft, express or post office
money order, or cashier's checks approved by the treasurer.
(4)
"Property" or "properties" means lands or town lots that
may be subject to a tax lien, including real property, manufactured homes,
mobile homes, modular homes, tiny homes, or severed minerals or mining claims.
(5)
"Tax lien sale" or "sale" means a public sale conducted by
the county treasurer pursuant to this article 11 at which a tax lien for
delinquent property taxes is sold and a certificate of purchase is issued to
the successful bidder.
Source:
L. 2005: Entire
section added, p. 1234, § 1, effective June 3. L. 2026: (1), (2), and
(4) amended and (2.5), (2.7), and (5) added, (SB 26-144), ch. 135, p. 602, § 6,
effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-101. Notice to delinquent owner.
The
treasurer shall make a list of all property the tax liens on which are subject
to tax lien sale, describing such property as the same is described on the tax
roll. Except as otherwise provided in section 39-2-117 (1)(a), no later than
September 1 of each year, the treasurer shall send a notice by first-class
mail, to the person's last-known mailing address, to each person by whom taxes
for the previous year are known to be due and unpaid. The notice must indicate
the amount of the person's delinquency and state that if the amount of the
delinquency is not paid by the date specified in the notice, which shall not be
less than fifteen calendar days from the date of mailing of the notice, the
treasurer will advertise and sell a tax lien on the person's property on the
date specified in the notice at tax lien sale for the delinquent taxes,
interest, and applicable fees. If such list is not made until after September
1, the tax lien sale held thereunder shall not be void by reason thereof.
Source:
L. 64: R&RE,
p. 723, § 1. C.R.S. 1963: § 137-11-1. L. 85: Entire section
amended, p. 1234, § 1, effective July 1. L. 88: Entire section amended,
p. 1293, § 26, effective May 23. L. 92: Entire section amended, p. 2230,
§ 17, effective April 9. L. 94: Entire section amended, p. 756, § 7,
effective April 20. L. 96: Entire section amended, p. 116, § 4,
effective March 25. L. 2005: Entire section amended, p. 1234, § 2,
effective June 3. L. 2007: Entire section amended, p. 18, § 1, effective
February 20. L. 2026: Entire section amended, (SB 26-144), ch. 135, p.
603, § 7, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: For
time when tax lien attaches, see § 39-1-107.
ANNOTATION
Law reviews. For note,
"Tax Deeds in Colorado", see 18 Rocky Mt. L. Rev. 393 (1946).
Substantial departure from
section as to land description voids sale. Where the assessment roll upon
which the tax sale was based described the tract in question as containing 160
acres, the notice of tax sale, as published, described the tract as 36 acres,
and the notice posted by the treasurer described it as 60 acres, there was a
substantial departure from this section which is fatal to the validity of the
sale. Callbreath v. Hapney, 24 Colo. App. 202, 132 P. 1143 (1913) (decided
under former law).
39-11-102. Treasurer to publish and
post notice.
(1)
Except as set forth in subsection (3) of this section, the treasurer shall
cause the notice described in subsection (2) of this section to be published in
the newspaper selected pursuant to section 39-11-105, the first publication
being at least four weeks before the date of sale, and shall post a written or
printed notice in a conspicuous place in the office of the treasurer for not
less than four weeks before the date of sale. If there is no newspaper
published in the county, a like notice shall be given by posting one written or
printed notice for the above length of time on or near the outer door of the
treasurer's office. When publication is made in a weekly newspaper, the notice
shall be published in three successive weekly issues. When publication is made
in a daily newspaper, the notice shall be published only three times, once each
week, on the same day of the week.
(2) The
notice of tax lien sale must contain:
(a) A
description of the properties on which the tax liens are subject to sale;
(b) The
date, time, and place of the tax lien sale, including the electronic address if
the tax lien sale is conducted by means of the internet or other electronic
medium;
(c) The
location of computer workstations that are available to the public and
information about how to obtain instructions on accessing the tax lien sale and
submitting bids if the tax lien sale is conducted by means of the internet or
other electronic medium; and
(d) If
the tax lien sale is conducted by means of the internet or other electronic
medium, a statement that the bidding rules for the tax lien sale will be posted
on the internet or other electronic medium used to conduct the tax lien sale at
least two weeks before the date of sale.
(3)
Repealed.
Source:
L. 64: R&RE,
p. 723, § 1. C.R.S. 1963: § 137-11-2. L. 94: Entire section
amended, p. 756, § 8, effective April 20. L. 2005: Entire section
amended, p. 1235, § 3, effective June 3. L. 2022: (1) amended and (3)
added, (HB 22-1223), ch. 308, p. 2220, § 2, effective August 10. L. 2026:
(2) amended and (3) repealed, (SB 26-144), ch. 135, p. 603, § 8, effective June
1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Purpose of this section
is to give the fullest publicity to the notice of tax sale and list of
delinquent taxes. Pelton v. Muntzing, 24 Colo. App. 1, 131 P. 281 (1913).
Treasurer to see that notice
stays posted. This section contemplates a single act of posting a notice by
the treasurer in a certain place within a prescribed time and imposes on him
the further duty to see that it remains so posted until the day of sale. Pelton
v. Muntzing, 24 Colo. App. 1, 131 P. 281 (1913).
39-11-103. Treasurer to make affidavit
of posting.
The
treasurer shall also make, or cause to be made, an affidavit showing the
posting of such list and notice, all of which affidavits shall be deposited by
the treasurer with the county clerk and recorder to be filed and entered by the
county clerk and recorder in the reception book or other permanent record of
said office and there carefully preserved.
Source:
L. 64: R&RE,
p. 723, § 1. C.R.S. 1963: § 137-11-3. L. 94: Entire section
amended, p. 756, § 9, effective April 20.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Legislative intent to create
record. This section manifests a legislative intent that affidavits should
become a permanent, enduring record of the fact of publication of the tax list.
Herr v. Graden, 22 Colo. App. 511, 127 P. 319 (1912), rev'd on other grounds,
59 Colo. 372, 148 P. 863 (1915).
Purpose for requiring
deposit of affidavits is to furnish proof. The sole purpose for requiring
the deposit of affidavits with the county clerk is to preserve and furnish
proof that the requisite notices of the sales of property for delinquent taxes
were given in the manner required by law, when that question becomes material.
Bertha Gold Mining & Milling Co. v. Burr, 31 Colo. 264, 73 P. 36 (1903);
Johnson v. Cork, 106 Colo. 72, 102 P.2d 471 (1940).
The evident purpose of this
section is to make the affidavit exclusive evidence of a compliance with the
section with reference to notice by publication. This is in accordance with the
fundamental rule that where proof by written evidence is required, oral
evidence will not be received, unless in case of loss or destruction of the
writing. Rustin v. Merchants' & Miners' Tunnel Co., 23 Colo. 351, 47 P. 300
(1896).
Affidavits are not required
to be filed at any particular time, nor does the failure to file them
before the issuance of a tax deed render such deed invalid. Bertha Gold Mining
& Milling Co. v. Burr, 31 Colo. 264, 73 P. 36 (1903); Sternberger v.
Moffat, 44 Colo. 520, 99 P. 560 (1908).
They must show substantial
compliance with requirements. It is evident that the affidavit must be
sufficiently certain and specific to reasonably show that, in fact, the
requirements of this article relative to the contents of the notice have been
substantially complied with, and that the notice posted referred to some
particular sale. Am. Bond & Inv. Co. v. Hopkins, 46 Colo. 460, 104 P. 1040
(1909).
Absence of affidavit is
prima facie proof that proper notice was not given. Proof that affidavits
are not on file with the county clerk would prima facie establish the tax deed
invalid, not, however, upon the ground that they had not been filed, but
because their absence would be prima facie proof that the requisite notices of sale
had not been given. Bertha Gold Mining & Milling Co. v. Burr, 31 Colo. 264,
73 P. 36 (1903); Am. Bond & Inv. Co. v. Hopkins, 46 Colo. 460, 104 P. 1040
(1909).
Applied in Norris v.
Kelsey, 23 Colo. App. 555, 130 P. 1088 (1913); Colpitts v. Fastenau, 117 Colo.
594, 192 P.2d 524 (1948).
39-11-104. Publisher's affidavit -
form.
(1)
Every publisher or printer who publishes such list and notice, immediately
after the last publication thereof, shall transmit to the treasurer of the
proper county an affidavit of such publication made by such publisher, printer,
or some other person to whom the fact of publication is known, and no publisher
or printer may be paid for such publication if the publisher or printer fails
to transmit such affidavit within fourteen calendar days after the last
publication.
(2)
Such affidavit shall be substantially in the following form:
"I,
.............., publisher (or printer) of the .............., a ..............
newspaper, printed and published in the county of .................. and state
of Colorado, do hereby certify that the foregoing notice and list were
published in said newspaper, once in each week, for ...... successive weeks,
the last of which publications was made prior to the ................ day of
................, A.D. 20...., and that copies of each number of said paper in
which said notice and list were published were delivered by carriers or
transmitted by mail to each of the subscribers of said paper, according to the
accustomed mode of business in this office.
....................,
Publisher (or Printer) of the ...................
|
STATE
OF COLORADO
|
)
|
|
|
)
ss.
|
|
County
of ........................................
|
)
|
The above certificate of
publication was subscribed and sworn to before me by the above named
.................., who is personally known to me to be the identical person
described in the above certificate, on the .................. day of ..................,
A.D. 20.... .
.................................
(SEAL)"
Source:
L. 64: R&RE,
p. 723, § 1. C.R.S. 1963: § 137-11-4. L. 2026: (1) amended, (SB
26-144), ch. 135, p. 604, § 9, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
I.
General Consideration.
II.
Form and Sufficiency of Affidavit.
I. GENERAL CONSIDERATION.
Law reviews. For note,
"Analysis of Basic Statutes on Legal Publications", see 19 Rocky Mt.
L. Rev. 380 (1947).
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Purpose of affidavit
requirement. The purpose of this section, requiring the affidavit and its
careful preservation by the county clerk is to make it exclusive evidence of
the fact and manner of the publication. Except, perhaps, in case of its
destruction, no other kind of proof can be substituted for it. Paine v.
Palmborg, 20 Colo. App. 432, 79 P. 330 (1905); Herr v. Graden, 33 Colo. 527, 81
P. 242 (1905); Sternberger v. Moffat, 44 Colo. 520, 99 P. 560 (1908).
Proper affidavit is
prerequisite to valid tax deed. An affidavit of publication of notice of
sale made in conformity with this section and filed in the proper office is a
prerequisite to a valid tax deed. Charlton v. Kelly, 24 Colo. 273, 50 P. 1042
(1897); Concord Corp. v. Huff, 144 Colo. 72, 355 P.2d 73 (1960).
Affidavit of publisher's
foreman competent proof of publication. The foreman for the publisher of
the paper in which the tax sale notice is published would know whether the
notice and list had been published. His affidavit, therefore, is competent
proof to establish the publication of the tax sale notice. Herr v. Graden, 59
Colo. 372, 148 P. 863 (1915).
Applied in Bertha Gold
Mining & Milling Co. v. Burr, 31 Colo. 264, 73 P. 36 (1903); Gilbreath v.
Doe, 24 Colo. App. 205, 132 P. 1146 (1913).
II. FORM AND SUFFICIENCY OF
AFFIDAVIT.
The prescribed form includes
all allegations deemed necessary. When the prescribed form is used, it
includes all allegations which the general assembly deemed necessary for the
purpose. Herr v. Graden, 22 Colo. App. 511, 127 P. 319 (1912), rev'd on other
grounds, 59 Colo. 372, 148 P. 863 (1915).
The statutory form of
affidavit need not be literally followed, but there can be no excuse for
disregarding its substantial requisites. Morris v. St. Louis Nat'l Bank, 17
Colo. 231, 29 P. 802 (1892).
Affidavit failing to show
publication of time and place of sale is insufficient. An affidavit of
publication of notice of a tax sale which states that the list of lands for
sale was published for four successive weeks in a weekly newspaper, but which
fails to show that the notice of the time and place of sale was published, is
insufficient to support a tax sale. Paine v. Palmborg, 20 Colo. App. 432, 79 P.
330 (1905).
Affidavit failing to show
required number of publications is insufficient. An affidavit of
publication of notice of a tax sale which states that the notice was published
in a daily paper on September 6, and that the last publication was made prior
to October 1, is insufficient, as it shows only one publication, while §
39-11-102 requires the publication to be made once a week for four consecutive
weeks. Paine v. Palmborg, 20 Colo. App. 432, 79 P. 330 (1905).
Affidavit failing to show
proper delivery of papers is insufficient. Unless the affidavit of
publication of notice of a tax sale shows that copies of each number of the
paper in which the notice was published were delivered or transmitted to each
subscriber of the paper according to the accustomed mode of business of the
office, it is insufficient, and a sale based thereon is invalid. Rustin v.
Merchants' & Miners' Tunnel Co., 23 Colo. 351, 47 P. 300 (1896); Lambert v.
Shumway, 36 Colo. 350, 85 P. 89 (1906).
39-11-105. Selection of newspaper
publishing notice.
It is the
duty of the board of county commissioners of each county to select a newspaper
of general circulation published or having general circulation in said county,
in which the treasurer shall publish the delinquent tax list of his county, and
for such service the board shall allow payment not exceeding the rate as
provided by law.
Source:
L. 64: R&RE,
p. 724, § 1. C.R.S. 1963: § 137-11-5.
ANNOTATION
Law reviews. For comment
on Blue River Co. v. Rizzuto appearing below, see 30 Rocky Mt. L. Rev. 234
(1958).
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
This section is mandatory,
not directory. Blue River Co. v. Rizzuto, 135 Colo. 472, 312 P.2d 1023
(1957).
Selection of newspaper for
publication is jurisdictional. The selection or designation of a newspaper
for the publication of delinquent tax lists is jurisdictional. Blue River Co.
v. Rizzuto, 135 Colo. 472, 312 P.2d 1023 (1957).
Selection of official county
newspaper is sufficient compliance. Publishing the delinquent tax lists in
a newspaper which had been duly selected by the county commissioners as the
official county newspaper, without specific reference to publication of
delinquent tax lists, is a sufficient compliance with this section. Linville v.
Russell, 168 Colo. 459, 452 P.2d 18 (1969).
Absent a selection, the
proceedings and sale are void. Blue River Co. v. Rizzuto, 135 Colo. 472,
312 P.2d 1023 (1957).
County may change selection
of newspaper before publication. A county may rescind the selection of a
newspaper to publish notice of tax sale and delinquent tax list, but not after
publication has been made. Bd. of Comm'rs v. Wood, 80 Colo. 279, 250 P. 860
(1926).
County is not required to
ask for bids for publication of notices of tax sale and delinquent tax
list. Bd. of Comm'rs v. Wood, 80 Colo. 279, 250 P. 860 (1926).
Expense of publication must
be paid by county. The expense of the publication of the notice of tax sale
and delinquent tax list must be paid by the county. Bd. of Comm'rs v. Wood, 80
Colo. 279, 250 P. 860 (1926).
39-11-106. Advertising and tax lien
sale fees.
(1) To
the amount of delinquent taxes there must be added a fee to cover the cost of
advertising, as provided in section 30-1-102. If the tax lien sale is conducted
by means of the internet or other electronic medium, the treasurer may add a
fee to cover the cost of conducting the tax lien sale.
(2) The
treasurer of each county shall deliver the treasurer's list of all property for
which tax liens are to be advertised for sale to the publisher or printer at
least ten calendar days before the date of the first publication.
Source:
L. 64: R&RE,
p. 724, § 1. L. 65: p. 1110, § 1. C.R.S. 1963: § 137-11-6. L.
67: p. 212, § 3. L. 71: p. 328, § 7. L. 85: (2) amended, p.
1234, § 2, effective July 1. L. 91: (2) amended, p. 1972, § 2, effective
March 27. L. 2005: (1) amended, p. 1236, § 4, effective June 3. L.
2026: Entire section amended, (SB 26-144), ch. 135, p. 604, § 10, effective
June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-107. Erroneous assessments -
abatement.
It is the
duty of the treasurer of each county, before making sale of tax liens on any
property for unpaid taxes, to carefully examine and compare the delinquent list
with the assessment roll and block books in the treasurer's office, and to omit
from such sale the tax liens on all property doubly or erroneously assessed,
insofar as the treasurer is able to ascertain the same, and to make an itemized
report to the board of county commissioners of the county showing such double
or erroneous assessment. The board of county commissioners, on receipt of such
itemized report, by resolution to be entered in its proceedings, shall abate
the taxes levied upon such double or erroneous assessments.
Source:
L. 64: R&RE,
p. 725, § 1. C.R.S. 1963: § 137-11-7. L. 85: Entire section
amended, p. 1235, § 3, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 604, § 11, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
County treasurer has an
independent duty to carefully examine the county assessor's delinquent tax
list. A county treasurer has a independent duty to compare the county
assessor's delinquent tax list to the treasurer's own records to prevent an
erroneous tax lien from being sold. Arnold v. Brent, 2024 COA 104, 561 P.3d
426.
39-11-108. Manner of conducting tax
lien sale - definitions.
(1) On
the day designated in the notice of sale, the treasurer shall commence the sale
of the tax liens on those properties on which the taxes, interest, and fees
have not been paid and shall continue the same from day to day, Saturdays and
Sundays excepted, until the tax liens on each parcel are sold. Where two or
more properties are valued and assessed as one parcel, the treasurer shall sell
a single tax lien on such properties. The tax lien sale must be held at the
treasurer's office or at another location in the county designated by the
treasurer, and all properties offered at the sale on the same date of sale must
be offered for sale at the same location; except that the sale may be conducted
by means of the internet or other electronic medium.
(2) A
tax lien sale conducted by means of the internet or other electronic medium to
sell property under this article 11 must allow members of the public to submit
bids by computer and permit the treasurer to accept bids for as long as the
treasurer deems necessary. The county and its employees acting in their
official capacity in preparing, conducting, and executing a tax lien sale of
property under this article 11 are not liable for the failure of a device that
prevents a person from participating in a sale under this article 11. As used
in this subsection (2), "device" includes, but is not limited to,
computer hardware, a computer network, a computer software application, and an
internet website.
(3) If
there is no bid for any tax lien offered, the offering of such tax lien must
remain open until all the tax liens are offered for sale and the sale is ended
or until the treasurer is satisfied that no more sales can be effected,
whereupon it is the treasurer's duty to strike off to the county, city, town,
or city and county the tax liens on those properties remaining unsold, for the
amount of such taxes, delinquent interest, and fees thereon. When the treasurer
strikes off a tax lien on any property, the treasurer shall issue to the
county, city, town, or city and county a certificate of purchase. No taxes
levied against any properties for which a county has purchased a tax lien under
the provisions of this section are payable until the same have been derived by
the county from the sale of a tax lien on such properties or from the
redemption of such properties.
Source:
L. 64: R&RE,
p. 725, § 1. C.R.S. 1963: § 137-11-8. L. 85: Entire section
amended, p. 1235, § 4, effective July 1. L. 92: Entire section amended,
p. 2230, § 18, effective April 9. L. 2005: Entire section amended, p.
1236, § 5, effective June 3. L. 2026: Entire section amended, (SB
26-144), ch. 135, p. 605, § 12, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
I.
General Consideration.
II.
Sale in Entirety or Parcels.
III.
Purchase by County.
I. GENERAL CONSIDERATION.
Law reviews. For
comment, "The Effect of Certified Realty Corp. v. Smith on Mortgage
Foreclosure in Colorado", see 52 U. Colo. L. Rev. 301 (1981).
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Purpose of section. The
purpose of this section is to give a reasonable opportunity to all desiring to
bid, and to make sure that there are no bidders present before striking any
property off to the county. Bennett v. Shotwell, 118 Colo. 206, 194 P.2d 335
(1948).
Section requires strict
compliance. This section authorizing the sale of property for taxes must be
strictly complied with or the proceedings will be void. Charlton v. Toomey, 7
Colo. App. 304, 43 P. 454 (1896), rev'd on other grounds, 24 Colo. 278, 50 P.
1042 (1897).
Void tax deed cannot be
supported by evidence aliunde. A tax deed, void on its face because of its
showing a fatal irregularity in the conduct of the sale, cannot be supported or
validated by evidence aliunde that the sale was conducted in conformity with
this section. Page v. Gillett, 47 Colo. 289, 107 P. 290 (1910).
Proof of damages is
unnecessary where statute governing sale is violated. Once it is shown that
a positive mandate or statute has been ignored in connection with a tax sale,
the grantor under a tax deed flowing therefrom will not be heard to say that
his adversary must go further and prove the damages he has suffered as a result
of the violation of the statute. Newcomb v. Henderson, 22 Colo. App. 167, 122
P. 1125 (1912).
Formal rereading of notice
of sale at reoffering not required. The requirement of this section is only
that the treasurer shall reoffer the property the next day. It does not require
the formal rereading of the notice of sale or legal description of the
property. Bennett v. Shotwell, 118 Colo. 206, 194 P.2d 335 (1948).
Failure to show first
offering date not invalidation of deed. A tax deed is not invalid because
of its failure to disclose the day upon which the land involved was first
offered for sale for delinquent taxes. Ford v. Genereux, 104 Colo. 17, 87 P.2d
749 (1939).
Applied in City &
County of Denver v. Keeler, 48 Colo. 54, 108 P. 998 (1910); Sherman v. Greeley
Bldg. & Loan Ass'n, 66 Colo. 288, 181 P. 975 (1919).
II. SALE IN ENTIRETY OR PARCELS.
Object of separate
valuation, assessment, and sale is to create a lien upon each tract for its
own assessment and levy. It is manifest that this is not done if the sale is en
masse for a gross sum. Page v. Gillett, 47 Colo. 289, 107 P. 290 (1910).
The only land which the
treasurer may sell jointly is such as the assessor can jointly value and
assess, namely, adjoining parcels, returned by the same person. Page v.
Gillett, 47 Colo. 289, 107 P. 290 (1910); Gilbreath v. Doe, 24 Colo. App. 205,
132 P. 1146 (1913).
Sale in parcels of body of
land assessed as a whole is violation of this section and one contesting
the sale is not required to prove that he has sustained damage by this
violation of the statute. Newcomb v. Henderson, 22 Colo. App. 167, 122 P. 1125
(1912).
Sale en masse for taxes of
noncontiguous lands for a gross sum is void; and a tax deed which, upon its
face, shows that the sale was made in this manner is void. Page v. Gillett, 47
Colo. 289, 107 P. 290 (1910).
A tax deed is not
objectionable because it conveys several noncontiguous tracts of land.
Barnett v. Jaynes, 26 Colo. 279, 57 P. 703 (1899).
III. PURCHASE BY COUNTY.
County becomes purchaser
only in default of outside bid. Before land may be legally bid in by the
county, it must, after being first offered, be continually offered from day to
day until the sale is concluded, and the county can only become a purchaser of
the entire tract in default of an outside bid, after the same has been offered
each day. Empire Ranch & Cattle Co. v. Howell, 23 Colo. App. 265, 129 P.
245 (1913).
Certificate of purchase must
be dated as of sale date. The certificate of purchase issued to the county
for land struck off to it at the tax sale must be dated as of the day of the
sale. Dalander v. Karr, 21 Colo. App. 170, 121 P. 136 (1912).
Tax deed cannot issue while
certificate of purchase outstanding. A tax deed cannot issue on property so
long as an outstanding tax certificate of purchase is still held by the county
and a deed issued in such circumstances will be held invalid. Cowen v. Driscoll
Constr. Co., 97 Colo. 74, 47 P.2d 390 (1935).
Taxes are not paid by
striking off the land to the county. Hecox v. Teller County, 198 F. 634
(8th Cir. 1912).
Unnecessary for county to
pay taxes until property sold. It is not necessary for the county, after
the purchase of a tax sale certificate, to pay any taxes that may have become
due subsequent to the issuance of said tax sale certificate, until the county
has sold the property which it has acquired by virtue of the treasurer's deed.
Rock v. Fastenau, 122 Colo. 41, 219 P.2d 781 (1950).
39-11-109. Time of tax lien sale.
The sale
of tax liens on property upon which taxes remain delinquent must commence on or
before the second Monday in December of each year.
Source:
L. 64: R&RE,
p. 725, § 1. C.R.S. 1963: § 137-11-9. L. 85: Entire section
amended, p. 1235, § 5, effective July 1. L. 2005: Entire section
amended, p. 1237, § 6, effective June 3. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 605, § 13, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Tax deed void if based on
sale held later than time designated. A tax deed based on a sale held later
than the time designated in this section where there is no explanation for the
delay is void. Kingore v. Wallace, 85 Colo. 381, 276 P. 332 (1929); Ireland v.
Gunnison Mt. Coal & Coke Co., 87 Colo. 193, 286 P. 280 (1930); Hochmuth v.
Norton, 90 Colo. 453, 9 P.2d 1060 (1932); Sierra Mining Co. v. Lucero, 118
Colo. 180, 194 P.2d 302 (1948).
A deed that is otherwise
void may be reformed in some circumstances. Where the tax sale was lawfully
conducted, the deed was duly recorded, and the deed contained only a technical
defect, equity permits the reformation of the deed based on extrinsic evidence
on the validity of the underlying tax sale. Bd. of Comm'rs v. Timroth, 87 P.3d
102 (Colo. 2004).
39-11-110. When tax lien sale can be
held.
If, from
any cause, the tax lien on property cannot be duly advertised and offered for
sale on or before the second Monday of December, the treasurer shall hold the
tax lien sale on any subsequent day in which it can be held, allowing time for
the publication of notice as provided in section 39-11-102.
Source:
L. 64: R&RE,
p. 725, § 1. C.R.S. 1963: § 137-11-10. L. 85: Entire section
amended, p. 1236, § 6, effective July 1. L. 2005: Entire section
amended, p. 1237, § 7, effective June 3. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 605, § 14, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Intent of section to save
late tax sales. This section is intended to save from invalidity a tax sale
made after the second Monday in December where it is impossible to commence the
sale on that day. City & County of Denver v. Bach, 92 Colo. 594, 22 P.2d
1114 (1933).
If a deed shows reason for
delayed sale, it is not void. Where a tax deed shows on its face that the
sale was held on a day subsequent to that designated by § 39-11-109, without a
recital of any cause for the delay such as would authorize a sale on the
subsequent day, the deed shows its falsity; but the deed is not void where it
contains a recital of sufficient cause for the delay. Richardson v. Halbekann,
97 Colo. 175, 48 P.2d 1014 (1935).
A deed that does not recite
the cause for the delay may be reformed through the use of extrinsic evidence
in some circumstances. Where the tax sale was lawfully conducted, the deed was
duly recorded, and the deed contained only a technical defect, equity permits
the reformation of the deed based on extrinsic evidence on the validity of the
underlying tax sale. Bd. of Comm'rs v. Timroth, 87 P.3d 102 (Colo. 2004).
39-11-111. Method of payment.
When the
treasurer sells any tax lien on any property for delinquent taxes, the
treasurer may accept payment of the purchase price in the form of cash, bank
check, post office money order, cashier's check, or electronic funds transfer,
subject to the treasurer's bidding rules.
Source:
L. 64: R&RE,
p. 726, § 1. C.R.S. 1963: § 137-11-11. L. 85: Entire section
amended, p. 1236, § 7, effective July 1. L. 2005: Entire section
amended, p. 1237, § 8, effective June 3. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 606, § 15, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Part payment with bonds and
warrants. A purchaser at a tax sale of lands included within an irrigation
district may pay in part with bonds and warrants of the district under the
provisions of § 37-41-109. Tew v. Phillips, 73 Colo. 408, 216 P. 525 (1923)
(decided under former law).
39-11-112. Erroneous name or assessment
in wrong county - effect.
(1)
When tax liens on any properties are offered for sale for any delinquent taxes,
it is not necessary to sell the same as the property of any person. No sale of
any tax lien on any property for delinquent taxes is considered invalid because
charged on the roll in any other name than that of the rightful owner, or
charged as unknown; but the tax lien and such property in other respects must
be sufficiently described on the tax roll to identify the same, and the taxes
for such property must be due and unpaid at the time of the tax lien sale.
(2)
When any property lying in one county is erroneously taxed and a tax lien on
such property is sold for delinquent taxes in another county, the county so
erroneously taxing and selling a tax lien on property for delinquent taxes is
liable to the owner of the property for any expense or damage caused to such
owner by the erroneous tax lien sale.
Source:
L. 64: R&RE,
p. 726, § 1. C.R.S. 1963: § 137-11-12. L. 85: Entire section
amended, p. 1236, § 8, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 606, § 16, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Description must enable
purchaser to know what is for sale. The assessment is made with a view to a
possible sale, and the property should, therefore, be so described as to enable
the owner to know what land is charged with the tax, and also to enable a
possible purchaser to know what land is offered for sale. Hence the description
should be sufficient in itself to identify the land or, if reference to a map
on record is required, that should be indicated in the assessment. Stough v.
Reeves, 42 Colo. 432, 95 P. 958 (1908).
Description by block number
without a map is insufficient. The description of a parcel of land, in
connection with tax sales, as a portion of an entire larger tract simply by
number and block, without any reference to a map, is not sufficient prima facie
evidence to identify the portion assessed. Stough v. Reeves, 42 Colo. 432, 95
P. 958 (1908).
39-11-113. Abbreviations, letters, and
figures may be used.
In all
advertisements for the sale of tax liens on property for delinquent taxes and
in entries required to be made by the assessor, county clerk and recorder,
treasurer, or other officers in lists, books, rolls, certificates, receipts,
deeds, or notices, letters, figures, and abbreviations may be used to denote
townships, ranges, sections, parts of sections, lots, blocks, dates and amounts
of taxes, delinquent interest, and costs.
Source:
L. 64: R&RE,
p. 726, § 1. C.R.S. 1963: § 137-11-13. L. 85: Entire section
amended, p. 1236, § 9, effective July 1. L. 92: Entire section amended,
p. 2231, § 19, effective April 9. L. 2026: Entire section amended, (SB
26-144), ch. 135, p. 606, § 17, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-114. Record of sales of tax liens
on property.
(1) The
treasurer shall make a correct record of all sales of tax liens on property for
delinquent taxes in a well-bound book or other permanent record to be kept by
the treasurer for that purpose. Said book must contain:
(a) The
date of sale;
(b) A
description of the property on which the tax liens are subject to sale;
(c) The
name of the owner thereof, if known;
(d) The
name of the purchaser;
(e) The
total amount of taxes, delinquent interest, and costs at time of sale;
(f)
Columns for amount of subsequent taxes paid by the purchaser and the date of
payment;
(g) To
whom assigned and the date of assignment;
(h) to
(j) Repealed.
(2) The
treasurer shall also note in the tax list, opposite the description of the
property for which a tax lien is sold, the fact and date of the tax lien sale.
(3)
Repealed.
Source:
L. 64: R&RE,
p. 726, § 1. C.R.S. 1963: § 137-11-14. L. 82: (3) added, p. 551,
§ 17, effective July 1. L. 85: IP(1), (1)(b), (2), and (3) amended, p.
1237, § 10, effective July 1. L. 92: (1)(e) amended, p. 2231, § 20,
effective April 9. L. 94: IP(1) and (2) amended, p. 756, § 10, effective
April 20. L. 96: (2) amended, p. 1393, § 12, effective July 1. L. 98:
(3) amended, p. 1347, § 81, effective June 1. L. 2000: (3)(a) amended,
p. 1638, § 17, effective June 1. L. 2026: IP(1), (1)(b), and (2) amended
and (1)(h), (1)(i), (1)(j), and (3) repealed, (SB 26-144), ch. 135, p. 606, §
18, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: For
tax sale procedure and redemption of a mobile home, see § 39-10-111.5.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Record is best evidence of
facts contained in it. The tax sale record, being one required by law to be
kept by the treasurer, is not only competent, but the best evidence of the
facts required to be stated therein, including the date of sale. Knowles v.
Martin, 20 Colo. 393, 38 P. 467 (1894); Empire Ranch & Cattle Co. v.
Lanning, 49 Colo. 458, 113 P. 491 (1911); Mulqueen v. Lanning, 53 Colo. 146,
124 P. 577 (1912).
39-11-115. To whom tax lien shall be
sold.
(1)
When the taxes levied for the preceding year or years on any properties remain
unpaid, the tax liens on such properties offered at tax lien sale at the times
provided by law must be sold to the persons who pay therefor the taxes,
delinquent interest, and fees then due thereon or who further pay the largest
amount in excess of said taxes, delinquent interest, and fees. The excess
amount must be credited to the county general fund. Each tax lien must be sold
for an entire piece of property. The taxes, delinquent interest, and fees draw
interest at the rates fixed by law, and, when the tax liens on any properties
are bid in by the county, city, town, or city and county, the amount for which
they are bid in draw interest at the same rates. Property for which a tax lien
is sold may be redeemed in the manner provided by law.
(2) In
order that the tax lien sale may be conducted in an efficient and equitable
manner, the treasurer is hereby granted broad powers to set bidding rules
governing the tax lien sale. Such powers include, but are not limited to, the
following:
(a)
Recognition of buyers in numerical sequence, in rotation, or in the order in
which bids are made;
(b)
Determining the order in which tax liens are sold, without regard to the order
in which they appear in the published notice of sale;
(c)
Setting minimum bid increases; and
(d)
Setting a minimum total of taxes, delinquent interest, and costs below which
competitive bids will not be accepted.
(3) The
treasurer may combine and sell as a unit parcels which are contiguous or are
contained within one subdivision.
(4) The
treasurer shall announce bidding rules at the beginning of the tax lien sale,
and the rules announced apply to all bidders throughout the sale. If the tax
lien sale is conducted by means of the internet or other electronic medium, the
treasurer shall post the internet bidding rules on the medium for at least two
weeks before the date of sale. The internet bidding rules posted apply to all
bidders throughout the sale.
Source:
L. 64: R&RE,
p. 727, § 1. L. 65: p. 1112, §§ 1, 2. C.R.S. 1963: § 137-11-15. L.
67: p. 213, § 4. L. 85: Entire section amended, p. 1237, § 11,
effective July 1. L. 87: Entire section amended, p. 1422, § 1, effective
May 8. L. 92: (1) and (2)(d) amended, p. 2231, § 21, effective April 9. L.
2005: (1), IP(2), and (4) amended, p. 1237, § 9, effective June 3. L.
2026: (1), IP(2), and (4) amended, (SB 26-144), ch. 135, p. 607, § 19,
effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
County treasurer has no
authority to sell tax lien on undivided partial interest in real property.
Under the plain language of subsection (1), which requires a tax lien to
"be sold for an entire piece of property", a tax lien may not be sold
for three-quarters interest in a property where the interests in the real
property are undivided, even if they are distinct or have separate parcel
identification numbers. Arnold v. Brent, 2024 COA 104, 561 P.3d 426.
39-11-116. Procedure when purchaser
fails to pay.
If a
person bidding fails to pay the amount due, the treasurer may again offer the
tax lien on such property for sale if the tax lien sale has not closed, and, if
the sale has closed, the treasurer may again advertise it specially in the same
manner as in the original advertisement and for not less than one week, after
which the treasurer may again offer and sell the tax liens on the property as
provided in section 39-11-115; or at the treasurer's option, the treasurer may
recover the amount bid by civil action brought in the name of the county in any
court of competent jurisdiction. In a tax lien sale conducted by means of the
internet or other electronic medium, if a person bidding fails to pay the
amount due, the treasurer may offer the tax lien, without additional
advertisement, to another bidder, whether or not the tax lien sale has closed;
or at the treasurer's option, the treasurer may recover the amount bid by civil
action brought in the name of the county in any court of competent
jurisdiction. The treasurer may prohibit a person who fails to pay the amount
due from bidding on sales under this article for up to five years.
Source:
L. 64: R&RE,
p. 727, § 1. C.R.S. 1963: § 137-11-16. L. 85: Entire section
amended, p. 1238, § 12, effective July 1. L. 2005: Entire section
amended, p. 1238, § 10, effective June 3. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 608, § 20, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-117. Certificate of purchase.
The
treasurer shall prepare, sign, and retain for safekeeping or deliver to the
purchaser of a tax lien on any property sold for the payment of delinquent
taxes a certificate of purchase describing the property on which the taxes and
fees were paid by the purchaser, as the property was described in the record of
sales, and also stating the rate of interest and the total amount of all taxes,
delinquent interest, and fees on each property for which the tax lien was sold,
as described in the record of sales, and that payment thereof has been made,
with columns for subsequent taxes. For each certificate so delivered, the
purchaser shall pay a fee to the treasurer as provided in section 30-1-102.
Source:
L. 64: R&RE,
p. 727, § 1. C.R.S. 1963: § 137-11-17. L. 69: p. 1122, § 2. L.
71: p. 328, § 8. L. 75: Entire section amended, p. 1479, § 4,
effective July 1. L. 85: Entire section amended, p. 1238, § 13,
effective July 1. L. 92: Entire section amended, p. 2231, § 22,
effective April 9. L. 96: Entire section amended, p. 1393, § 13, July 1.
L. 2005: Entire section amended, p. 1238, § 11, effective June 3. L.
2026: Entire section amended, (SB 26-144), ch. 135, p. 608, § 21, effective
June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: For
certificate of sale for personal property, see § 39-10-111. For certificate of
sale for a mobile home, see § 39-10-111.5.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
County treasurer is entitled
to fee for issuing certificate of purchase. Sherman v. Greeley Bldg. &
Loan Ass'n, 66 Colo. 288, 181 P. 975 (1919).
Fee becomes property of
collecting officer. A fee which is provided for a specified public service
presumably becomes the property of the officer authorized to collect it,
subject to the power of the proper public authority to limit the amount
retainable by the officer to a certain sum. Moffat Tunnel Imp. Dist. v.
McGuire, 103 Colo. 539, 87 P.2d 753 (1939).
39-11-118. Certificate of purchase
assignable.
Such
certificate of purchase shall be assignable by endorsement, and an assignment
thereof, when entered upon the record of sales in the offices of the county
clerk and recorder and the treasurer, shall vest in the assignee or his legal
representative all the right and title of the original purchaser.
Source:
L. 64: R&RE,
p. 728, § 1. C.R.S. 1963: § 137-11-18.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Assignee becomes lawful
holder of certificate even if assignment not recorded. The assignee of a
certificate of purchase, who in good faith and for a valuable consideration
purchases the interest of his assignor and receives from him the certificate
bearing his indorsement, with the intent of transferring to the assignee the
right and title represented thereby, would become the lawful holder of the
certificate of sale, even though the assignment was not recorded as provided in
this section. White Cap Mining Co. v. Resurrection Mining Co., 115 Colo. 396,
174 P.2d 727 (1946).
Assignment of certificate
carries rights of original purchaser. The assignment of a tax sale
certificate carries with it and vests in the assignee all the rights of the
original purchaser. Bd. of Comm'rs v. Whelen, 28 Colo. 435, 65 P. 38 (1901).
39-11-119. Subsequent payment by
holder.
Any person
desiring to pay any subsequent taxes on any properties for which the person
holds the certificates of purchase shall produce such certificates to the
treasurer, or, if certificates are retained by the treasurer, the treasurer
shall notify the person of the amount due. Upon receipt of payment, the
treasurer shall record the amount of the subsequent tax and the date of payment
on the permanent record. The treasurer may receive a fee for such services, as
provided in section 30-1-102 (1)(j).
Source:
L. 64: R&RE,
p. 728, § 1. C.R.S. 1963: § 137-11-19. L. 69: p. 1122, § 3. L.
71: p. 328, § 9. L. 75: Entire section amended, p. 1479, § 5,
effective July 1. L. 83: Entire section amended, p. 1230, § 20,
effective July 1. L. 94: Entire section amended, p. 757, § 11, effective
April 20. L. 96: Entire section amended, p. 1393, § 14, effective July
1. L. 2026: Entire section amended, (SB 26-144), ch. 135, p. 608, § 22,
effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include a case decided under this section as it existed
prior to its 1964 repeal and reenactment.
Payment of subsequent taxes
is permissive, not mandatory. This section provides for the payment of
subsequent taxes by the holder of a tax certificate, and it clearly appears
that the right to pay subsequent taxes is permissive, not mandatory. Bennett v.
Shotwell, 118 Colo. 206, 194 P.2d 335 (1948).
Payment of subsequent taxes
on land in irrigation district. One holding a tax purchase certificate for
lands in an irrigation district is entitled to pay subsequent taxes with
interest coupons of the district maturing in a year for which the tax is
levied. Orchard Mesa Farms Co. v. Canon, 61 Colo. 347, 157 P. 192 (1916).
39-11-120. Certificate of purchase -
application for tax lien for treasurer's deed - lost or wrongfully withheld -
county held.
(1) and
(2) (Deleted by amendment, L. 2026.)
(3)
Whenever any certificate given by the treasurer for a tax lien on any property
sold for delinquent taxes is lost or wrongfully withheld from the rightful
owner thereof and the property has not been redeemed, the board of county
commissioners may receive evidence of the loss or wrongful detention and, upon
satisfactory proof of such fact, may cause a certificate of such proof and
finding, properly attested by the county clerk and recorder under the seal of
the county, to be delivered to the rightful claimant, and the county clerk and
recorder shall duly make a record thereof in the recorded proceedings of the
board.
(4)
Whenever any tax lien on any property is bid in by or for the county, city,
town, or city and county at any tax lien sale, and a certificate of purchase is
made to the county, city, town, or city and county therefor, the treasurer of
the county, city, town, or city and county may sell, assign, and deliver the
certificate to any person who desires to purchase the same upon payment to the
treasurer of the amount for which said tax lien was bid in by the county, city,
town, or city and county with interest and costs accrued thereon from the date
of sale, together with a fee for making such assignment, as provided in section
30-1-102, and the taxes assessed thereon since the date of the tax lien sale
or, in the case of a county, city, town, or city and county, for the sum as the
board of county commissioners or other board authorized to perform the duties
of a board of county commissioners at any regular or special meeting may decide
and authorize by order duly entered in the recorded proceedings of the board.
Source:
L. 64: R&RE,
p. 728, § 1. C.R.S. 1963: § 137-11-20. L. 71: p. 329, § 10. L.
75: (2) amended, p. 1480, § 6, effective July 1. L. 85: (1), (3),
and (4) amended, p. 1238, § 14, effective July 1. L. 2024: (1) and (4)
amended, (HB 24-1056), ch. 165, p. 782, § 1, effective July 1. L. 2026:
Entire section amended, (SB 26-144), ch. 135, p. 609, § 23, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
I.
General Consideration.
II.
Assignment by the County.
I. GENERAL CONSIDERATION.
Law reviews. For
article, "Property Law", see 32 Dicta 420 (1955). For article,
"Delinquent Oil and Gas Ad Valorem Taxes: Protecting Property
Interests", see 16 Colo. Law. 798 (1987).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Purchaser has right to
demand deed any time after three years from sale. Pelton v. Muntzing, 24
Colo. App. 1, 131 P. 281 (1913).
Purchaser may set process in
motion before expiration of time. A purchaser at a tax sale may set into
motion the machinery to obtain a deed before the end of the 3-year period of
redemption although the tax deed may not properly be issued until the
expiration of the time fixed. Knutson v. Dickson, 105 Colo. 42, 94 P.2d 691
(1939).
Subsequently assessed taxes
must be paid prior to issuance of deed. One who purchases a tax purchase
certificate is not entitled to a deed until he has paid all taxes subsequently
assessed upon the lands. Schneider v. Hurt, 25 Colo. App. 335, 138 P. 422
(1914), aff'd, 61 Colo. 104, 156 P. 600 (1916); Henrie v. Greenlees, 71 Colo.
528, 208 P. 468 (1922).
Single tender for more than
one certificate permitted. A single tender to the county by the purchaser
is sufficient, even though the transaction covers several certificates, on
several parcels of land, issued pursuant to sales in different years. Lackey v.
Killey, 80 Colo. 408, 252 P. 351 (1927).
Tax deed may convey more
than one tract of land, whether they are contiguous or noncontiguous.
Johnson v. Cork, 106 Colo. 72, 102 P.2d 471 (1940).
Recordation of assignment is
unnecessary to deed's validity. Recording the assignment of a tax sale
certificate is not a necessary prerequisite to the validity of the deed issued
thereon. White Cap Mining Co. v. Resurrection Mining Co., 115 Colo. 396, 174
P.2d 727 (1946).
Tax lien extinguished by
issuance of deed from subsequent sale. A tax lien held by virtue of a
certificate issued as result of sale is extinguished by the issuance of a tax
deed by the county on a subsequent sale. Benedict v. Coriolanus Corp., 30 Colo.
App. 306, 491 P.2d 985 (1971).
Issuance of subsequent
corrective tax deed authorized. The county treasurer has authority to issue
a second tax deed, for the purpose of correcting a former defective deed, at
any time before redemption, and, if he refuses to do so, mandamus will lie to
compel him. Duggan v. McCullough, 27 Colo. 43, 59 P. 743 (1899).
Speculation in tax
certificates allowed. One has the right to speculate in tax certificates if
one complies with the law concerning their purchase and assignment. Lackey v.
Killey, 80 Colo. 408, 252 P. 351 (1927).
Interplay of this section
and § 39-11-122. Subsection (4) authorizes the county treasurer to sell any
tax certificate for full value without requiring any action by the county
commissioners. Only if the amount to be received is less than such full amount
does an order by the commissioners become necessary, in which case § 39-11-122
applies. RTV, L.L.C. v. Grandote Int'l Ltd., 937 P.2d 768 (Colo. App. 1996).
Applied in Bottom v.
Young, 52 Colo. 533, 125 P. 500 (1912); Vandermeulen v. Burwell, 22 Colo. App.
486, 125 P. 131 (1912); Fishel v. City & County of Denver, 105 Colo. 120,
95 P.2d 1 (1939); Swofford v. Colo. Nat'l Bank, 628 P.2d 184 (Colo. App. 1981).
II. ASSIGNMENT BY THE COUNTY.
This section does not
contemplate the issuance of a deed to the county. Hecox v. Teller County,
198 F. 634 (8th Cir. 1912); Bennett v. Shotwell, 118 Colo. 206, 194 P.2d 335
(1948).
There is no limitation on
time within which assignment may be made, provided that the assignment of
the certificate by the treasurer and board of county commissioners is after the
expiration of three years from the date of the certificate. Lovelace v. Tabor
Mines & Mills Co., 29 Colo. 62, 66 P. 892 (1901).
Board cannot make actual
assignment. While this section confers upon the board of county
commissioners the authority to determine the sum at which the certificate may
be sold, it does not further extend the authority of the board but leaves the
duty of making the assignment in the hands of the county treasurer. Empire
Ranch & Cattle Co. v. Neikirk, 23 Colo. App. 392, 128 P. 468 (1913).
Board has no power to prefer
customers. In fixing a sum less than the face value at which tax
certificates may be assigned, the board of county commissioners has no power to
prefer purchasers. Radetsky v. Palmer, 70 Colo. 146, 199 P. 490 (1921).
Power of board of county
commissioners is limited to fixing of price at which each certificate shall
be sold and it neither extends to a bulk sale for a lump sum nor to the
selection of a particular purchaser. Bd. of Comm'rs v. Utah-Colorado Land &
Livestock Co., 101 Colo. 372, 73 P.2d 987 (1937).
Owner of land sold for taxes
not entitled to notice of assignment. The rights of an owner of land sold
for taxes cannot be affected by mandamus to compel assignment of the
certificate of purchase by the county, and there is no reason for giving him
notice of such an assignment. Lackey v. Killey, 80 Colo. 408, 252 P. 351
(1927).
39-11-121. Municipalities, prior sales
validated.
All sales
of such certificates made by any treasurer or ex officio treasurer of any city,
town, or city and county, antecedent to or without the passage of any ordinance
prescribing the terms of such sales, are hereby approved, affirmed, ratified,
and validated as of their respective dates.
Source:
L. 64: R&RE,
p. 729, § 1. C.R.S. 1963: § 137-11-21.
39-11-122. Transfer of certificates of
purchase by counties.
Any county
in this state having in its possession or under its control certificates of
purchase resulting from the sale of a tax lien on property for the nonpayment
of general taxes may assign, sell, or transfer those certificates of purchase
in such manner, at such times, and on such terms as may be determined by
resolution of the board of county commissioners of the county. Thereafter the
county must execute and deliver the instruments as necessary to fully convey
all interest of the county in or to the certificates of purchase.
Source:
L. 64: R&RE,
p. 730, § 1. C.R.S. 1963: § 137-11-22. L. 85: Entire section
amended, p. 1239, § 15, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 610, § 24, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Constitutionality. This
section does not violate the provisions of § 24 of art. V, Colo. Const.,
relating to amendments to laws by reference to title only. District Landowners
Trust v. Adams County, 104 Colo. 146, 89 P.2d 251 (1939).
Purpose of section. To
make the authority of the board of county commissioners more definite and
certain, and to clarify their position with reference to tax sale certificates,
the general assembly enacted this section. Bennett v. Shotwell, 118 Colo. 206,
194 P.2d 335 (1948).
Object of sale is to collect
revenue. While the purpose of the law in divesting the estate of a
landowner, upon sale for delinquent taxes, is to coerce the negligent and
unwilling citizen to obey the law by payment of his taxes, the sole object of
the state in making the sale is to collect its revenue. Knutson v. Dickson, 105
Colo. 42, 94 P.2d 691 (1939).
Recordation of assignment
unnecessary. It is not necessary that the assignment of the certificates of
purchase be entered upon the records of sale in the office of the county clerk
in order to vest complete title thereto in the assignee. White Cap Mining Co.
v. Resurrection Mining Co., 115 Colo. 396, 174 P.2d 727 (1946).
No inconsistency or
repugnancy exists between this section and § 39-11-120, pertaining to the
disposition of certificates held by the county when taxes thereon are tendered
in full; therefore, there is no repeal by either direction or implication.
Knutson v. Dickson, 105 Colo. 42, 94 P.2d 691 (1939); RTV, L.L.C. v. Grandote
Int'l Ltd., 937 P.2d 768 (Colo. App. 1996).
Interplay of this section
and § 39-11-120. Section 39-11-120 (4) authorizes the county treasurer to
sell any tax certificate for full value without requiring any action by the
county commissioners. Only if the amount to be received is less than such full
amount does an order by the commissioners become necessary, in which case this
section applies. RTV, L.L.C. v. Grandote Int'l Ltd., 937 P.2d 768 (Colo. App.
1996).
Board may name individual
purchaser. Under this section, a resolution of a board of county
commissioners authorizing the sale of a certificate to a named individual, and
not to the first person offering to pay the amount fixed by the board, is
valid. White Cap Mining Co. v. Resurrection Mining Co., 115 Colo. 396, 174 P.2d
727 (1946).
The board has the power to
fix the price at which individual tax sale certificates of purchase held by
the county may be assigned by the treasurer. Bd. of Comm'rs v. Utah-Colorado
Land & Livestock Co., 101 Colo. 372, 73 P.2d 987 (1937).
Applied in McMillan v.
Bd. of Comm'rs, 113 Colo. 387, 157 P.2d 146 (1945).
39-11-123. Transfer of certificates of
purchase - irrigation or drainage district taxes.
Any county
having in its possession or under its control certificates of purchase
resulting from the sale of a tax lien on property for the nonpayment of
irrigation or drainage district taxes or assessments, by agreement with the
board of directors of the district involved, may assign or transfer those
certificates of purchase as provided in section 39-11-122.
Source:
L. 64: R&RE,
p. 730, § 1. C.R.S. 1963: § 137-11-23. L. 85: Entire section
amended, p. 1239, § 16, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 610, § 25, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Constitutionality. This
section does not violate the provisions of § 24 of art. V, Colo. Const.,
relating to amendments to laws by reference to title only. District Landowners
Trust v. Adams County, 104 Colo. 146, 89 P.2d 251 (1939) (decided under former
law).
39-11-124. Counties, prior sales
validated.
All
assignments, sales, or transfers of certificates of purchase by counties made
before August 1, 1964, are validated and confirmed.
Source:
L. 64: R&RE,
p. 730, § 1. C.R.S. 1963: § 137-11-24.
ANNOTATION
Constitutionality. This
section does not violate the provisions of § 24 of art. V, Colo. Const.,
relating to amendments to laws by reference to title only. District Landowners
Trust v. Adams County, 104 Colo. 146, 89 P.2d 251 (1939) (decided under former
law).
39-11-125. Disposal of certificates of
purchase by districts.
Any
irrigation or drainage district having in its possession or under its control
certificates of purchase resulting from the sale of a tax lien on property for
the nonpayment of irrigation or drainage district taxes or assessments may
assign, sell, or transfer those certificates of purchase in such manner, at
such times, and on such terms as may be determined by resolution adopted by the
board of directors of the district, and thereupon the district shall execute
and deliver such instruments as may be necessary to fully convey all interest
in or to those certificates of purchase.
Source:
L. 64: R&RE,
p. 730, § 1. C.R.S. 1963: § 137-11-25. L. 85: Entire section
amended, p. 1239, § 17, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 610, § 26, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-126. Agreement with county
commissioners.
Any
irrigation or drainage district having in its possession or under its control
certificates of purchase resulting from the sale of a tax lien on property for
the nonpayment of general taxes may, by agreement with the board of county
commissioners of the county in which the property is situated, assign or
transfer those certificates of purchase as provided in section 39-11-125.
Source:
L. 64: R&RE,
p. 731, § 1. C.R.S. 1963: § 137-11-26. L. 85: Entire section
amended, p. 1240, § 18, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 611, § 27, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-127. Irrigation or drainage
districts, prior sales validated.
All
assignments, sales, or transfers of certificates of purchase by irrigation or
drainage districts made before August 1, 1964, are validated and confirmed.
Source:
L. 64: R&RE,
p. 731, § 1. C.R.S. 1963: § 137-11-27.
39-11-128. Condition precedent to deed
- notice.
(1)
Before any lawful holder of a certificate of purchase, or assignee of a lawful
holder of a certificate of purchase for a tax lien on any property sold for
taxes or special assessments due either to the state or any county or
incorporated town or city within the same at any sale of tax liens for
delinquent taxes levied or assessments authorized by law is entitled to a deed
for the property subject to the tax lien, the lawful holder or the lawful
holder's assignee shall file with the treasurer an application for a
treasurer's deed. Upon receipt of an application for a treasurer's deed, the
treasurer shall then comply with the procedures set forth in article 11.5 of
this title 39.
(a) and
(b) (Deleted by amendment, L. 2026.)
(2)
(Deleted by amendment, L. 2026.)
Source:
L. 64: R&RE,
p. 731, § 1. C.R.S. 1963: § 137-11-28. L. 71: p. 329, § 11. L.
85: IP(1) and (1)(a) amended, p. 1240, § 19, effective July 1. L. 96:
(1)(b) amended, p. 116, § 5, effective March 25. L. 2024: IP(1) amended,
(HB 24-1056), ch. 165, p. 783, § 2, effective July 1. L. 2026: Entire
section amended, (SB 26-144), ch. 135, p. 611, § 28, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: For
publication of legal notices generally, see part 1 of article 70 of title 24.
ANNOTATION
I.
General Consideration.
I. GENERAL CONSIDERATION.
Law reviews. For
article, "Inadequacy of Notice Provision for Obtaining Treasurers'
Deeds", see 25 Dicta 144 (1948). For article, "Property Law",
see 32 Dicta 420 (1955). For comment on Mitchell v. Espinosa appearing below,
see 25 Rocky Mt. L. Rev. 101 (1952). For article, "Delinquent Oil and Gas
Ad Valorem Taxes: Protecting Property Interests", see 16 Colo. Law. 798
(1987).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
The evident purpose of this
section and § 39-5-104 is to forbid the issuance of a deed where the
property is of substantial value, without giving notice to those interested,
and particularly to one having the right of redemption. Bogue v. Miles, 107
Colo. 320, 111 P.2d 1055 (1941); Swofford v. Colo. Nat'l Bank, 628 P.2d 184
(Colo. App. 1981).
The purpose of this section
is to afford record owners an opportunity to redeem their property before it is
lost through a treasurer's deed. Parkison v. Burley, 667 P.2d 780 (Colo.
App. 1983); Cordell v. Klingsheim, 2014 COA 133, 412 P.3d 629, rev'd on other
grounds, 2016 CO 18, 379 P.3d 270.
Due process does not require
that a property owner receive actual notice before the government may take his
or her property. Rather, due process requires the government to provide
notice that is reasonably calculated, under all of the circumstances, to
apprise interested parties of the pendency of the action at issue and to afford
them an opportunity to present their objections. Klingsheim v. Cordell, 2016 CO
18, 379 P.3d 270.
Due process satisfied for
several reasons. First, the treasurer sent tax deed notices by certified mail
as required by subsection (1). Second, the notices were sent to the address
listed in the tax rolls as the property owners' current address, which was an
address they had used for the previous five years at their express request.
Third, the notices were not returned as undelivered or undeliverable, but
rather were received and signed for by a person with the same last name as the
intended recipients and who lived at an adjacent address. Finally, the notices
were actually received by the person whom the record property owners
anticipated would receive such notices on their behalf. Klingsheim v. Cordell,
2016 CO 18, 379 P.3d 270.
Due process does not require
that each record owner residing at the same address be mailed a separate notice
of a pending tax sale. County treasurer made "diligent inquiry"
as required by subsection (1)(a) when mailing notices to both record owners, a
married couple residing at the same address, in one envelope to the same
address. Cordell v. Klingsheim, 2018 COA 80, 434 P.3d 741.
The requirements of this
section are jurisdictional. Sheesley v. Voorhees, 24 Colo. App. 428, 134 P.
1008 (1913); Brown v. Davis, 103 Colo. 110, 83 P.2d 326 (1938); Siler v. Inv.
Sec. Co., 125 Colo. 438, 244 P.2d 877 (1952); Concord Corp. v. Huff, 144 Colo.
72, 355 P.2d 73 (1960); Turkey Creek, LLC v. Rosania, 953 P.2d 1306 (Colo. App.
1998).
There must be full
compliance with statutory requirements relating to notice of application
for issuance of a treasurer's deed, and, if a noncompliance with any such
statutory direction is shown, the treasurer's deed will be adjudged invalid.
Siler v. Inv. Sec. Co., 125 Colo. 438, 244 P.2d 877 (1952); Concord Corp. v.
Huff, 144 Colo. 72, 355 P.2d 73 (1960).
Tax deed is invalid absent
full compliance of statutory requirements relating to the issuance of the
deed. Siddoway v. Ainge, 34 Colo. App. 210, 526 P.2d 669 (1974), aff'd, 189
Colo. 173, 538 P.2d 110 (1975).
Satisfaction of requirements
question of fact. The determination of whether each requirement of this
section relating to issuance of tax deeds by county treasurers has been
sufficiently satisfied is a question for the trier of fact. Siddoway v. Ainge,
189 Colo. 173, 538 P.2d 110 (1975); Turkey Creek, LLC v. Rosania, 953 P.2d 1306
(Colo. App. 1998); Wells Fargo v. Olivas, 2017 COA 158, 410 P.3d 1284.
Deed, although proper, is
not evidence of acts necessary. Even though the deed be conceded to be fair
on its face so as to make it prima facie evidence of facts occurring before or
at the time of the sale, it constitutes no evidence of the acts which the cash
purchaser is required to perform, or the treasurer for him, after the sale and
before a deed can be lawfully executed. Sheesley v. Voorhees, 24 Colo. App.
428, 134 P. 1008 (1913).
Written request for unsigned
tax deed immaterial. It is immaterial that a written request for a tax deed
is unsigned where demand for the deed was actually made on the treasurer.
Sanderford v. Walker Inv. Co., 84 Colo. 203, 269 P. 14 (1928).
Treasurer may issue a
correction deed. Where there was some mistake of the county treasurer which
made a former deed irregular or defective, a correction deed should be issued.
White Cap Mining Co. v. Resurrection Mining Co., 115 Colo. 396, 174 P.2d 727
(1946).
Applied in Johnson v.
Cork, 106 Colo. 72, 102 P.2d 471 (1940); Lake Canal Reservoir Co. v. Beethe,
227 P.3d 882 (Colo. 2010).
II. NOTICE.
A.
In General.
B.
Service.
A. In General.
No tax deed may be issued
until notice is given. Notice to all persons having an interest or title of
record to land sold for taxes is a prerequisite to the issuance of a tax deed
therefor. French v. Golston, 105 Colo. 578, 100 P.2d 581 (1940).
Parties claiming tax title
must prove notice. It is incumbent upon the parties claiming title under a
tax deed to prove either that the statutory notice was given or that the
assessed valuation rendered it unnecessary to give such notice before the deed
would be admissible in evidence. Jackson v. Larson, 24 Colo. App. 548, 136 P.
81 (1913).
Title void. Under this
section, proof of notice is necessary, and the notice must state the truth,
failing in which, the deed will be void. Young v. Rohan, 77 Colo. 70, 234 P.
694 (1925); Staples v. Todd, 108 Colo. 386, 117 P.2d 1005 (1941); Tewell v.
Galbraith, 119 Colo. 412, 205 P.2d 229 (1949).
A plaintiff attacking the
validity of a tax deed on the ground of defective notice has the burden of
presenting evidence of the defect. Wells Fargo v. Olivas, 2017 COA 158, 410
P.3d 1284.
Tax deed not void for
issuance after date in notice. A tax deed is not void for the reason that
it is executed and issued after the date fixed by the notice for issuance of
the treasurer's deed. Mitchell v. Espinosa, 125 Colo. 267, 243 P.2d 412 (1952).
For when notice is false and
defective, see Bottom v. Young, 52 Colo. 533, 125 P. 500 (1912); Flader v.
Campbell, 120 Colo. 66, 207 P.2d 1188 (1949).
Where party contesting
issuance of tax deed had actual notice and the opportunity to redeem the tax
certificates prior to the tax deeds being issued and did not avail himself
of such opportunity, such party has not demonstrated any injury to his right to
notice under this section. Turkey Creek, LLC v. Rosania, 953 P.2d 1306 (Colo.
App. 1998).
Despite alleged defects and
the failure to follow strictly the publication requirements, party
contesting the issuance of tax deeds lacks standing to contest the validity of
the tax deeds under either paragraph (a) or (b) of subsection (1). Turkey
Creek, LLC v. Rosania, 953 P.2d 1306 (Colo. App. 1998).
B. Service.
Treasurer's duty to serve
notice. This section makes it the duty of the treasurer to serve the notice
or cause it to be served. Richardson v. Halbekann, 97 Colo. 175, 48 P.2d 1014
(1935).
This section contemplates
that service is complete when the county treasurer registers and deposits
in the United States mails the statutory notice directed to the proper
postoffice address of the party to be notified. Ford v. Genereux, 104 Colo. 17,
87 P.2d 749 (1939).
Publication required only
when actual notice not possible. The evident intent of the general assembly
was to require publication only in the event that actual notice cannot be given
to the owner and to persons having an interest of record in the land. Henrie v.
Greenlees, 71 Colo. 528, 208 P. 468 (1922).
Notice by publication was
sufficient where the record interest holder's correct address was not
available in the county records. Schmidt v. Langel, 874 P.2d 447 (Colo. App.
1993).
This section creates a
window in which the treasurer must publish the notice: sometime between
five and three months before the deed is issued, the treasurer must publish
three notices, once each week. Red Flower, Inc. v. McKown, 2016 COA 160, 411
P.3d 1094.
Service on general partner
imputes notice to the limited partners. Because the general partner had
authority to act for the limited partnership and received appropriate notice of
the sale and application for deed, the general partner's notice and knowledge
are imputed to each limited partner. BMS P'ship v. Winter Park Devil's Thumb
Inv. Co., 910 P.2d 61 (Colo. App. 1995), aff'd on other grounds, 926 P.2d 1253
(Colo. 1996).
Limited partner not entitled
to notice of time for issuance of tax deed because limited partner does not
own an interest in real property owned by the limited partnership. Winter Park
Devil's Thumb Inv. Co. v. BMS P'ship, 926 P.2d 1253 (Colo. 1996).
When premises are actually
occupied by a person, the county treasurer may serve notice on the occupant at
the property, but the treasurer is not required to conduct a "diligent
inquiry" to notify actual possessors or occupants. However, when an
occupant does not actually occupy the premises or is not on the premises, the
county treasurer is only required to make a "diligent inquiry" to
determine the person's whereabouts and then to notify him or her of the sale.
Red Flower, Inc. v. McKown, 2016 COA 160, 411 P.3d 1094.
A tenant occupying the
premises must be served with notice, and service on the record owner,
without service on the tenant in possession, is not a compliance with
subsection (1)(a). Brown v. Davis, 103 Colo. 110, 83 P.2d 326 (1938); Taylor v.
Lutin, 106 Colo. 170, 102 P.2d 484 (1940).
"Persons having an
interest or title of record". "Persons having an interest or
title of record", referred to in subsection (1)(a), is equivalent to
"record owners", and that language is held to exclude even holders of
known but unrecorded contracts of sale. Godfrit v. Judd, 116 Colo. 489, 182
P.2d 907 (1947).
Failure to serve notice to
record owner invalidates deed. Where a diligent inquiry of the records of
the clerk and recorder of the county by the treasurer or by the purchaser under
a treasurer's deed would have disclosed that a bank had an interest of record
in the property and, since the bank was entitled to be served with notice by
the treasurer under this section, where the bank did not receive such notice,
the treasurer's deed was invalid. Swofford v. Colo. Nat'l Bank, 628 P.2d 184
(Colo. App. 1981).
The original beneficiaries
of a note and deed of trust secured by real property, who subsequently
transferred the note and deed to a bank as security for indebtedness by an
agreement purporting to assign all right, title, and interest in the deed, did
not retain an interest in the real property sufficient to warrant notice of
pending issuance of a treasurer's deed. Columbus Invs. v. Lewis, 48 P.3d 1222
(Colo. 2002).
Section does not contemplate
service on wife. The requirement of subsection (1)(a) that the county
treasurer shall serve "notice of such purchase" on every person in
actual possession of the land does not necessitate service on a wife living
with her husband and occupying the premises involved. Ford v. Genereux, 104
Colo. 17, 87 P.2d 749 (1939).
This section directs the
treasurer to make diligent inquiry to learn the address of the record owner
and serve notice upon him at that address if it can be learned. Bald Eagle
Mining & Ref. Co. v. Brunton, 165 Colo. 28, 437 P.2d 59 (1968).
This section imposes a duty of
diligent inquiry upon the county treasurer. Siddoway v. Ainge, 34 Colo. App.
210, 526 P.2d 669 (1974), aff'd, 189 Colo. 173, 538 P.2d 110 (1975).
This statute places a duty
on a treasurer before a notice is sent. Specifically, subsection (1)
requires a treasurer to make diligent inquiry to learn the address of the
record owner and serve notice upon him or her at that address if it can be
learned. Klingsheim v. Cordell, 2016 CO 18, 379 P.3d 270.
A treasurer owes a duty of
further diligent inquiry after an initial notice has been sent only when the
facts known to the treasurer show that the taxpayer could not have received the
notice of the pending tax sale. When the circumstances make clear that the
taxpayer could not have received the notice, such as if it is returned
undelivered or undeliverable, the treasurer must undertake further diligent
inquiry to attempt to provide notice. When, in contrast, the facts known to the
treasurer do not establish that the taxpayer could not have received the
notice, then no duty of further diligent inquiry arises. Klingsheim v. Cordell,
2016 CO 18, 379 P.3d 270.
A treasurer is not obliged
to ensure actual receipt of the required notice, but to make reasonably
diligent attempts to deliver the notice. Subsection (1) contemplates either
personal service or service by registered or certified mail, and neither of
these methods requires that the notice be placed personally in the recipient's
hands. Klingsheim v. Cordell, 2016 CO 18, 379 P.3d 270.
Treasurer held to have not
acted with diligence in failing to determine address of record owners prior
to issuing a tax deed. Parkison v. Burley, 667 P.2d 780 (Colo. App. 1983).
Deed is voidable absent
diligent inquiry. Where, upon application to a county treasurer for
issuance of a treasurer's deed, no "diligent inquiry", required by
subsection (1)(a), is made by that official to ascertain the address of the
person in whose name the property sold for taxes was taxed, and such
"diligent inquiry" would have disclosed the correct address of the
owner, and where no notice of application for the tax deed was served upon or
received by the owner because of the failure of the official to make
"diligent inquiry", and where no statute of limitations is involved,
the treasurer's deed will be voided upon the complaint of the owner who thus
was deprived of notice concerning the application for issuance of the
treasurer's deed. Siler v. Inv. Sec. Co., 125 Colo. 438, 244 P.2d 877 (1952);
Wittemyer v. Cole, 689 P.2d 720 (Colo. App. 1984).
A tax deed issued without the
treasurer conducting diligent inquiry pursuant to this section is voidable and
subject to being set aside by a court. When such a deed is voided, a tenant in
common who redeems the property does so for the benefit of all cotenants.
Sandstrom v. Solen, 2016 COA 29, 370 P.3d 669.
Tax deed was voidable because,
as a matter of law, the treasurer did not exercise reasonable diligence in
seeking an alternative address after a notice was returned as undeliverable.
Wells Fargo v. Olivas, 2017 COA 158, 410 P.3d 1284.
Treasurer need not check
records of secretary of state to be diligent. To constitute diligent
inquiry upon the part of the county treasurer, he was not obliged to go to the
records in the office of the secretary of state to ascertain the address of the
corporation in whose name the property was taxed or its officers. White Cap
Mining Co. v. Resurrection Mining Co., 115 Colo. 396, 174 P.2d 727 (1946).
Failure of record owner to
report change of address irrelevant. Failure of the record owner to advise
the county assessor's office regarding his change of address is not relevant in
determining whether county treasurer complied with his duty under this statute
to make a diligent inquiry. Siddoway v. Ainge, 34 Colo. App. 210, 526 P.2d 669
(1974), aff'd, 189 Colo. 173, 538 P.2d 110 (1975).
Treasurer not required to
search unrelated correspondence files for correct address, especially when
treasurer had not been put on notice that the address in the subject property
records was incorrect. Siddoway v. Ainge, 189 Colo. 173, 538 P.2d 110 (1975).
Treasurer cannot blindly
rely on assessor's rolls for correct address. Blind reliance on erroneous
assessor's rolls, when the correct address was easily available to the
treasurer, does not satisfy the diligence requirements of subsection (1)(a),
nor does it permit forfeiture of property when the owner of the property does
not receive notice of the impending forfeiture because of the lack of diligent
inquiry on the part of the treasurer. Bald Eagle Mining & Ref. Co. v.
Brunton, 165 Colo. 28, 437 P.2d 59 (1968).
"Diligent inquiry"
requires the county treasurer to inquire into information available within
county records, but the county treasurer need not inquire into every
possible source for the record interest holder's correct address. As a matter
of law, the treasurer exercised due diligence by reexamining the county records
for an alternative address when the original notice was returned. Schmidt v.
Langel, 874 P.2d 447 (Colo. App. 1993).
Treasurer must use
reasonable diligence to look for an alternative address when a notice is
returned as undeliverable. The treasurer should re-examine the records of
the subject property and, in the event that an alternative address does not
emerge, conduct a reasonable search of the county's available electronic
records. The treasurer was not entitled to assume that a notice sent to a
different entity with a similar name effected notice to the entity from which
notice was returned as undeliverable. Wells Fargo v. Olivas, 2017 COA 158, 410
P.3d 1284.
The records a treasurer is
required to search to find an alternative address after a notice is returned
may vary with the treasurer's ability to search them. The treasurer was
required to conduct a reasonable search of the county's available electronic
records. But a full and complete search of all the county records may not be
required if it is impracticable. Wells Fargo v. Olivas, 2017 COA 158, 410 P.3d
1284.
For nonrecord owners who are
not in possession, see DeCola v. Bochatey, 161 Colo. 95, 420 P.2d 395
(1966); Ponzio v. Arapahoe Inv. Enter., 161 Colo. 102, 420 P.2d 398 (1966).
39-11-129. Tax deed - issuance,
execution, requirements. (Repealed)
Source:
L. 64: R&RE,
p. 732, § 1. C.R.S. 1963: § 137-11-29. L. 85: Entire section
amended, p. 1240, § 20, effective July 1. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 29, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-130. Fees included in redemption
money. (Repealed)
Source:
L. 64: R&RE,
p. 732, § 1. C.R.S. 1963: § 137-11-30. L. 85: Entire section
amended, p. 1241, § 21, effective July 1. L. 2017: Entire section
amended, (HB 17-1019), ch. 17, p. 56, § 1, effective March 8. L. 2026:
Entire section repealed, (SB 26-144), ch. 135, p. 612, § 30, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-131. Notice of application for
deed. (Repealed)
Source:
L. 64: R&RE,
p. 733, § 1. C.R.S. 1963: § 137-11-31. L. 85: Entire section
amended, p. 1241, § 22, effective July 1. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 31, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-132. Prior notices or requests containing
more than one parcel - validation. (Repealed)
Source:
L. 64: R&RE,
p. 733, § 1. C.R.S. 1963: § 137-11-32. L. 75: Entire section
repealed, p. 1480, § 8, effective July 1.
39-11-133. Suit to quiet title.
(Repealed)
Source:
L. 64: R&RE,
p. 733, § 1. C.R.S. 1963: § 137-11-33. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 32, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-134. Defects in tax deed, effect.
(Repealed)
Source:
L. 64: R&RE,
p. 734, § 1. C.R.S. 1963: § 137-11-34. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 33, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-135. Form of tax deed. (Repealed)
Source:
L. 64: R&RE,
p. 734, § 1. C.R.S. 1963: § 137-11-35. L. 69: p. 1124, § 1. L.
85: Entire section amended, p. 1241, § 23, effective July 1. L. 92:
Entire section amended, p. 2232, § 23, effective April 9. L. 2026:
Entire section repealed, (SB 26-144), ch. 135, p. 612, § 34, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-136. Treasurer to execute deed -
effect. (Repealed)
Source:
L. 64: R&RE,
p. 736, § 1. C.R.S. 1963: § 137-11-36. L. 85: (1)(f) and (1)(g)
amended, p. 1243, § 24, effective July 1. L. 93: (3) added, p. 305, § 4,
effective April 7. L. 2001: (3) amended, p. 10, § 1, effective August 8;
(3) amended, p. 308, § 1, effective August 8. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 35, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-137. Validation of
acknowledgments of tax deeds. (Repealed)
Source:
L. 64: R&RE,
p. 737, § 1. C.R.S. 1963: § 137-11-37. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 612, § 36, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-138. When successor of treasurer
shall act.
If any
treasurer dies, resigns, or is removed from office or the treasurer's term of
office expires after selling any tax liens on any property for delinquent taxes
and before executing a certificate of purchase, certificate of option for
treasurer's deed, or treasurer's deed for the same, the treasurer's successor
in office shall execute the certificate of purchase, certificate of option for
treasurer's deed, or deed in the same manner that the treasurer making the tax
lien sale might have done.
Source:
L. 64: R&RE,
p. 737, § 1. C.R.S. 1963: § 137-11-38. L. 85: Entire section
amended, p. 1243, § 25, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 612, § 37, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-139. Posting list of county-held
tax liens and county-acquired treasurer's deeds.
No later
than the fifteenth day of January of each year, each county treasurer shall
deliver to the county clerk and recorder of the county treasurer's county a
list showing all certificates of purchase issued and held in the name of the
county and a list of all property the title to which has been acquired by the
county through issuance of a treasurer's deed following public auction in
accordance with article 11.5 of this title 39. A copy of the list described in
this section must be posted in a conspicuous place in the courthouse for not
less than thirty days.
Source:
L. 67: p. 803, §
5. C.R.S. 1963: § 137-11-49. L. 93: Entire section amended, p.
440, § 8, effective July 1. L. 2026: Entire section amended, (SB
26-144), ch. 135, p. 612, § 38, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-140. Treasurer's deed recorded -
entry.
When any
treasurer's deed is filed for record, the county clerk and recorder shall also
enter the name of the grantee in the proper column of the record of property
for which a tax lien was sold for delinquent taxes.
Source:
L. 64: R&RE,
p. 737, § 1. C.R.S. 1963: § 137-11-39. L. 85: Entire section
amended, p. 1243, § 26, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 613, § 39, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-141. Action to determine validity
of certificate of purchase.
Whenever
any county or city and county in this state holds certificates of purchase
which are believed by the board of county commissioners to be void for
irregularity in the assessment of property or sale of a tax lien on property or
otherwise, the board of county commissioners of the county or city and county
may institute an action in the district court of the county, under the
provisions of article 51 of title 13, to have the matter determined as to
whether those certificates of purchase are void. These actions must be brought
in the name of the board of county commissioners. Any number of certificates of
purchase may be included in one action, and the fee owners of record of the tax
liens on the property on account of the sale of which the certificates of
purchase were issued must be made defendants in the action. If any defendant is
a nonresident of the state or cannot be found, service of summons may be had
upon that defendant in accordance with the provisions of rule 4 of the Colorado
rules of civil procedure. If the court, by its decree, finds and determines
that any such certificate of purchase is void, then the tax lien on the
property on account of the sale of which the certificate of purchase was issued
must be resold for taxes at the next succeeding tax lien sale for delinquent
taxes; and if the irregularity on account of which the certificate of purchase
was held void is in the assessment of the property, then the board of county
commissioners shall direct the assessor to reassess the certificate of
purchase, and, if the delinquent taxes are not thereafter duly paid pursuant to
that reassessment, the tax lien on the property must likewise be sold at the
next tax lien sale following the reassessment. No appeal lies from the final
decree of the court in cases brought under this section. No costs of the action
may be assessed against any defendant who files a disclaimer or fails to appear
in the action.
Source:
L. 64: R&RE,
p. 737, § 1. C.R.S. 1963: § 137-11-40. L. 85: Entire section
amended, p. 1244, § 27, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 613, § 40, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-142. Disposition of certificates
of purchase held by counties.
(1) In
cases where a tax lien on property has been struck off to the county at a tax
lien sale and the county has held the certificate of purchase for three years
or more, the board of county commissioners may apply for public auction for
treasurer's deed and receive a treasurer's deed in the same manner as is
provided by law in the case of certificates of purchase held by investors in
accordance with article 11.5 of this title 39.
(2) In
cases where the county has held the certificate of purchase for three years or
more and the property is not located within the limits of any incorporated town
or city within the county, the county may include in one request or demand any
or all separate parcels of property for which it holds certificates of purchase
for tax lien sales in any one year, and the board of county commissioners may
apply for public auction for treasurer's deed and receive treasurer's deeds
therefor.
(3)
Repealed.
(4) In
all cases, the owner of the property must have the right of redemption of the
property as provided by law.
(5)
Repealed.
(6) (a)
In all cases where a tax lien on property has been struck off to the county at
a tax lien sale and the county has held the certificate of purchase for five
years or more without obtaining a treasurer's deed as provided in this section
and article 11.5 of this title 39, then the treasurer shall declare the
certificate of purchase void and of no effect.
(b)
Repealed.
(c)
Upon being presented with the list of tax liens, the board of county
commissioners shall determine that the tax liens were struck off to the county,
that the certificates of purchase relating thereto have been held by the county
for five years or more, and that no treasurer's deed has been obtained or
applied for as provided in this section and article 11.5 of this title 39. Upon
making that determination, the board of county commissioners may declare that
the certificates of purchase are void, and an order to that effect must be duly
entered in the recorded proceedings of the board, which order must direct the
treasurer to cancel such certificates of purchase.
(d)
Upon receipt of an order or resolution of the board of county commissioners
declaring that any certificates of purchase are void, the treasurer shall
record that order or resolution in the public records and shall cancel all
certificates of purchase specified in that order.
(e) Any
action concerning a determination and declaration by a board of county
commissioners made pursuant to this subsection (6) must be commenced within one
year after the date of the board's order, or said action shall be forever
barred.
(7) The
treasurer shall at least once each year prepare and present, at any regular or
special meeting of the board of county commissioners, a list of all tax liens
on all property struck off to the county and all certificates of purchase
relating thereto, which certificates of purchase have been held by the county
for three years or more without obtaining a treasurer's deed or being otherwise
disposed of under this article 11 or article 11.5 of this title 39.
Source:
L. 64: R&RE,
p. 738, § 1. C.R.S. 1963: § 137-11-41. L. 67: p. 802, § 2. L.
85: (1) and (6)(a) to (6)(c) amended, p. 1244, § 28, effective July 1. L.
2020: (1) amended, (6)(b) repealed, and (7) added, (HB 20-1077), ch. 80, p.
328, § 19, effective September 14. L. 2024: (1), (2), (3), (6)(a),
(6)(c), and (7) amended, (HB 24-1056), ch. 165, p. 783, § 3, effective July 1. L.
2026: (1), (2), (4), (6)(a), (6)(c), (6)(d), (6)(e), and (7) amended and
(3) and (5) repealed, (SB 26-144), ch. 135, p. 613, § 41, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-143. Appraisal - county may
retain, lease, or sell - definitions.
(1)
Whenever property is conveyed by a treasurer to the county by treasurer's deed
under article 11.5 of this title 39, the assessor shall annually value the same
in the manner prescribed by law for taxable property and shall notify the board
of county commissioners of such valuation.
(2) The
board of county commissioners has the power to retain for public projects,
rent, lease, or sell property as provided in this section.
(2.5)
If the board of county commissioners retains property for a present or future
public project, as defined in section 30-20-301 (2), it shall pass a resolution
describing the project for which the property is retained. The board of county
commissioners may rent or lease any property retained for a present or future
public project in accordance with subsection (3) of this section. For purposes
of this section, using property to generate revenue for the county is not a
public project.
(3) The
board of county commissioners may lease such property to an affiliated entity,
but no lease shall be for a period exceeding five years. For purposes of this
subsection (3), "affiliated entity" means a nonprofit entity with
which the county enters into a contract for the delivery of goods or services
to the county or to third parties on behalf of the county.
(4) (a)
Any property that is not retained or leased in accordance with subsection (2.5)
or (3) of this section must be sold at public sale by the board of county commissioners
within one year after the property is conveyed to the county; except that the
board of county commissioners may reject any bid that is less than the value of
the property as determined by the assessor. Prior to offering the property for
sale, the board of county commissioners shall obtain from the assessor a
certificate as to the current actual value and the valuation for assessment of
the property. A notice of such sale must be posted in a public place in the
county courthouse at least thirty days before the date of sale, and the notice
of sale must also be advertised in two issues of a newspaper of general
circulation in the county in which the property is situated, said newspaper
notices must appear one week apart and within the thirty days as above
provided. The notice must reserve the right upon the part of the board of
county commissioners to reject any bid that is less than the value determined
by the assessor. The notice must be substantially in the following form:
NOTICE
Public notice is
hereby given that the following property acquired by the County of
.............., Colorado, by treasurer's deed, to wit:
(description of property)
will, according to law, be offered
at public sale at the county courthouse, .............., Colorado, on the
.............. day of .............., 20...., at the hour of .... to the
highest and best bidder. The board of county commissioners reserves the right
to reject any bid that is less than the current actual value fixed by the
county assessor.
..............................................
County Clerk and Recorder.
(a.5)
The notice of sale posted pursuant to subsection (4)(a) of this section must
contain a statement substantially in the following form: "If this property
is at least fifty years old, it may be eligible for inclusion in the state
register of historic properties or designation as a landmark. This property may
be eligible for certain rehabilitation grants and incentives."
(b) The
property must be sold at public sale for the highest and best bid for any
property, as determined in the discretion of the board of county commissioners;
except that the board of county commissioners may reject any bid that is less
than the value of the property as determined by the assessor. The property may
be sold in lots or parcels and upon terms of payment as the board of county
commissioners deems acceptable, but no deed may be issued until the purchaser
has made payment in full. Upon written application of any person, the board of
county commissioners shall offer for sale the property requested by the person
to be sold; except that no property may be divided for the purpose of the
requested sale unless the board of county commissioners specifically permits
the division. The board of county commissioners may, prior to the sale of any
property, reserve or grant streets, alleys, or roads or utilities or other
easements, public or private, under terms and conditions as it may deem
advisable.
(5)
Such deeds shall be issued by a commissioner to convey, duly appointed by the
board of county commissioners, which commissioner shall act upon the direction
of the board of county commissioners, but such deed shall be issued without
covenants of warranty.
(6)
This section does not apply to any city and county having a population of more
than three hundred thousand. Sales and leases by such city and county must be
made in compliance with the applicable provisions of its charter or ordinances.
Source:
L. 64: R&RE,
p. 739, § 1. C.R.S. 1963: § 137-11-42. L. 2004: (1), (2), (3),
and (4) amended and (2.5) added, p. 159, § 2, effective August 4. L. 2026:
(1), (2), (2.5), (3), (4), and (6) amended, (SB 26-144), ch. 135, p. 615, § 42,
effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-144. County property, prior sales
validated.
All sales
of property made by the board of county commissioners of any county must be
deemed valid, and these sales are confirmed if they were made at either public
or private sale and made by deed issued by a duly appointed commissioner to
convey upon direction of the board of county commissioners.
Source:
L. 64: R&RE,
p. 741, § 1. C.R.S. 1963: § 137-11-43. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 617, § 43, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-145. Proceeds of sales.
All net
proceeds from the sale, lease, or other disposition of property so conveyed to
the county by the commissioner must be paid to the treasurer of the county, and
the treasurer shall distribute the proceeds to the various taxing jurisdictions
in which the property is situated in the same proportion that the ad valorem
taxes levied by each taxing jurisdiction in the preceding calendar year bears
to the total of all ad valorem taxes levied on the property in the preceding
calendar year.
Source:
L. 64: R&RE,
p. 741, § 1. C.R.S. 1963: § 137-11-44. L. 69: p. 1127, § 1. L.
2026: Entire section amended, (SB 26-144), ch. 135, p. 617, § 44, effective
June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-146. Lien of special assessment
not affected.
Nothing in
sections 39-11-143 to 39-11-145 affects in any manner or degree whatsoever the
lien of any special assessment to which property and the conveyance thereof by
the treasurer is subject under law.
Source:
L. 64: R&RE,
p. 741, § 1. C.R.S. 1963: § 137-11-45. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 617, § 45, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-147. Treasurer to report
payments.
A complete
report of all payments made to and accepted by the treasurer under sections
39-11-142, 39-11-143, and 39-11-145 must be made, a copy of which must be sent
to the board of county commissioners of the county, to the administrator, and
to the controller at the end of each month.
Source:
L. 64: R&RE,
p. 741, § 1. C.R.S. 1963: § 137-11-46. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 618, § 46, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-148. Limitations on certificates
of purchase - special improvement liens.
(1) No
lien upon property created by a certificate of purchase issued by a treasurer
on account of any delinquent property taxes or any special assessment may
remain a lien for a period longer than seven years after the issuance thereof,
except as provided in subsection (3) of this section. This section does not
apply to any certificate of purchase issued to and held by the county, city,
city and county, or district levying the tax or special assessment; except
that, in the event of an assignment of the certificate of purchase issued to
and held by the county, city, city and county, or district, the lien of the
certificate of purchase must cease seven years after the date of its issuance
subject only to the provisions of subsection (3) of this section. Notwithstanding
any other provision of this section, a lien on property created by a tax lien
sale certificate of purchase issued prior to January 1, 2026, may remain a lien
for a period of fifteen years after the date of issuance.
(2) No
treasurer's deed may issue after public auction in connection with any tax lien
sale evidenced by certificate of purchase where the certificate of purchase has
ceased to be a lien pursuant to the provisions of this section and application
for public auction for the treasurer's deed is not pending at the time of the
expiration of the limitation period provided for in this section.
(3) In
the event of an assignment of a certificate of purchase that is seven years old
at the time of assignment or will become seven years old within one year from
the date of such assignment, the assignee thereof is entitled to a treasurer's
deed in the manner provided by law if the assignee or other legal holder of the
certificate institutes proceedings to procure a treasurer's deed by filing an
application for public auction for treasurer's deed with the treasurer for the
same, as provided in article 11.5 of this title 39, within one year from the
date of the assignment.
(4)
Whenever a lien created by a certificate of purchase has expired, the treasurer
shall immediately issue a certificate of cancellation describing the property
included in the certificate of purchase and giving the date of cancellation,
and shall also make proper entries in the book of sales in the treasurer's
office as follows: "Canceled by provision of section 39-11-148,
C.R.S.", with the date of the entry. The treasurer shall also present
every certificate of cancellation to the county clerk and recorder who shall
enter the same in the record of property for which a tax lien was sold for
delinquent taxes and endorse the date of entry on the certificate of
cancellation and file the same, and the certificate and the record thereof must
be prima facie evidence of the cancellation of the certificate of purchase and
of the release of the lien of the certificate on the property described
therein. If a tax lien was sold, in whole or in part, due to a delinquent
special assessment, the treasurer shall notify the governmental entity imposing
the special assessment of the cancellation of the lien. Failure to record the
certificate of cancellation must not extend the lien created by the certificate
of purchase. The treasurer and county clerk and recorder are not entitled to
any fees or surcharges for issuing a certificate of cancellation or making
entries in their books under the provisions of this subsection (4).
(5)
Whenever a lien created pursuant to a certificate of purchase becomes
unenforceable pursuant to section 31-25-1119, the treasurer shall immediately
issue a certificate of cancellation describing the property included in the
certificate of purchase indicating the date of cancellation and shall make the
appropriate entries in the book of sales in the treasurer's office, as follows:
"Canceled by provision of sections 31-25-1119 and 39-11-148, C.R.S.",
with the date of the entry. The treasurer may present every certificate of
cancellation to the county clerk and recorder who shall enter the same in the
record of property for which a tax lien was sold for delinquent taxes and
endorse the date of entry on the certificate of cancellation and file the same,
and the certificate and the record thereof is prima facie evidence of the
cancellation of the certificate of purchase and of the release of the lien of
the certificate on the property therein described. Failure to record the
certificate of cancellation does not extend the lien created by the certificate
of purchase. The treasurer and county clerk and recorder are not entitled to
any fees for issuing and recording a certificate of cancellation or for making
entries in their books under the provisions of this subsection (5).
Source:
L. 64: R&RE,
p. 742, § 1. C.R.S. 1963: § 137-11-47. L. 67: p. 802, §§ 3, 4. L.
81: (5) amended, p. 1627, § 40, effective July 1. L. 85: (4) and (5)
amended, p. 1245, § 29, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 618, § 47, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-149. Sales en masse valid.
If two or
more noncontiguous properties or portions thereof have not been separately
valued and assessed or, having been separately valued and assessed, whether
having a common ownership or not, have had tax liens sold en masse for a gross
sum for the nonpayment of taxes and charges, then, after seven years from the
date of any tax lien sale, the assessment and tax lien sale and any certificate
of purchase issued must be deemed valid and legal and considered so in all
actions, suits, or proceedings in which is involved the validity of any such
assessment, tax lien sale, certificate of purchase, or treasurer's deed issued
in accordance with article 11.5 of this title 39. Nothing in this section
alters, amends, or repeals section 39-11-148.
Source:
L. 64: R&RE,
p. 743, § 1. C.R.S. 1963: § 137-11-48. L. 85: Entire section
amended, p. 1246, § 30, effective July 1. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 619, § 48, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Law reviews. For
article, "Curative Statutes of Colorado Respecting Titles to Real
Estate", see 26 Dicta 321 (1949).
39-11-150. Sales of tax liens on
severed mineral interests.
Sales of
tax liens for delinquent taxes due on severed mineral interests must take place
at the same place and time and under the same circumstances as in this article
11, but, where the surface estate ownership is coterminous with the severed
mineral interest, the owner of the surface estate has the right of first
refusal to purchase the tax lien on the severed mineral interest, and the
surface owner must be allowed to pay all delinquent taxes due and owing for the
severed mineral interest in lieu of the proceeds that would be collected from a
sale of a tax lien on the severed mineral interest. The treasurer shall notify
the surface owner, by mail, at the owner's last-known mailing address, of the
right of refusal at least ten days prior to the sale of a tax lien on the
severed mineral interest. The surface owner has until two business days prior
to the tax lien sale to exercise the right of first refusal. If the surface
owner does not exercise the right of first refusal, the tax lien on such
severed mineral interest is sold. No action for the recovery of a severed
mineral interest for which a certificate of purchase was issued under the
provisions of this article 11 lies unless brought within the same time period
as that limiting actions for the recovery of property pursuant to section
39-12-101.
Source:
L. 73: p. 1430, §
3. C.R.S. 1963: § 137-11-50. L. 85: Entire section amended, p.
1246, § 31, effective July 1. L. 2026: Entire section amended, (SB
26-144), ch. 135, p. 620, § 49, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
ANNOTATION
Law reviews. For
article, "Severed Minerals as a Deterrent to Land Development", see
51 Den. L.J. 1 (1974).
This section does not give a
reciprocal right of first refusal to the owner of a severed mineral interest to
obtain a tax lien on the surface. Notch Mountain Corp. v. Elliott, 898 P.2d
550 (Colo. 1995).
39-11-151. County officials and
employees may not acquire a tax lien by tax lien sale.
(1) (a)
(Deleted by amendment, L. 2026.)
(b) No
tax lien sold for delinquent taxes on a property pursuant to this article 11
may be sold to an elected or appointed county official, to a county employee,
or to a member of the immediate family of such person or to the agent of any
such county official or employee during the time the official or employee holds
office or is employed.
(2) The
purchase of any tax lien is exempt from the provisions of this section under
the following circumstances:
(a) If
the property was owned by the county official or county employee, or by a
member of the immediate family of any such person, immediately prior to the
sale of a tax lien on the property for delinquent taxes;
(b) If
the property is situated within a county other than the county to which the
county official or employee is elected, appointed, or employed;
(c) If
the property is a severed mineral interest and, at the time of the sale, the
county official or county employee is the owner of the surface estate which is
coterminous with the severed mineral interest; or
(d) If
the county official or employee had a legal interest in the property prior to a
tax lien sale on the property for delinquent taxes.
(3) Any
county official, county employee, or member of the immediate family of any such
person, or the agent of any such county official or employee, who knowingly
purchases any tax lien in violation of the provisions of this section commits a
class 2 misdemeanor and must be punished as provided in section 18-1.3-501.
Source:
L. 75: Entire
section added, p. 1481, § 1, effective June 29. L. 85: (1) and (2)
amended, p. 1246, § 32, effective July 1. L. 94: Entire section amended,
p. 757, § 12, effective April 20. L. 2002: (3) amended, p. 1555, § 346,
effective October 1. L. 2021: (3) amended, (SB 21-271), ch. 462, p.
3295, § 691, effective March 1, 2022. L. 2026: Entire section amended,
(SB 26-144), ch. 135, p. 620, § 50, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: (1)
For other provisions relating to standards of conduct for public officers and
employees, see article 18 of title 24.
(2) For the legislative
declaration contained in the 2002 act amending subsection (3), see section 1 of
chapter 318, Session Laws of Colorado 2002.
39-11-152. Combined sale of delinquent
tax liens and special assessment liens.
Whenever
provision is made in this article for the sale of a tax lien on property, such
sale must include the sale of any lien for delinquent special assessments on
such property which have been certified to the county treasurer for collection.
The separate sale of liens for delinquent general taxes and for delinquent
special assessments on property is hereby prohibited.
Source:
L. 93: Entire
section added, p. 81, § 1, effective March 26. L. 2026: Entire section
amended, (SB 26-144), ch. 135, p. 621, § 51, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act changing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
39-11-153. Interaction with other law.
Notwithstanding
any law to the contrary, on or after July 1, 2024, a purchaser, lawful holder,
or treasurer shall follow the procedures established in article 11.5 of this
title 39 and shall not follow the procedures established in this article 11
concerning the issuance of a deed. Notwithstanding any law to the contrary, on
or after July 1, 2024, a treasurer shall not issue a deed pursuant to this
article 11.
Source:
L. 2024: Entire
section added, (HB 24-1056), ch. 165, p. 784, § 4, effective July 1.
ARTICLE
11.5
Issuance
of Treasurer's Deeds
PART 1
PUBLIC AUCTION
39-11.5-101. Definitions.
39-11.5-102. Lawful holder - application for treasurer's
deed - fee.
39-11.5-103. Review of application - recording.
39-11.5-104. Notice of application - title
review - mailing list.
39-11.5-105. Notice of public auction - mailing
- publication - posting.
39-11.5-106. Property owner redemption
procedure.
39-11.5-107. Bid required - form of bid.
39-11.5-108. Fees and costs.
39-11.5-109. Public auction - timing of -
electronic bid.
39-11.5-110. Public auction - location -
announcement - records - definition.
39-11.5-111. Continuance of public auction -
effect of bankruptcy - withdrawal of application.
39-11.5-112. Treatment of overbid - agreement to
assist in recovery of overbid.
39-11.5-113. Use of electronic documents
authorized.
39-11.5-114. Rescission of public auction.
39-11.5-115. Unclaimed refunds - disposition.
39-11.5-116. Abbreviations, letters, and figures
may be used.
PART 2
SEVERED MINERALS - RIGHT OF FIRST REFUSAL
39-11.5-201. County-held severed mineral rights
- procedure - form.
PART 3
REPURCHASE - CLAIM FOR OVERBID MONEY
39-11.5-301. Repurchase - procedure.
39-11.5-302. Effect of repurchase.
39-11.5-303. Claim for overbid money -
procedure.
39-11.5-304. Lessee, easement holder, and
installment contract vendor considered as lienors - installment land contract
vendee considered as owner.
PART 4
CERTIFICATE OF OPTION FOR A TREASURER'S DEED
39-11.5-401. Certificate of option for a
treasurer's deed - issuance - priority.
39-11.5-402. Certificate of repurchase -
issuance.
39-11.5-403. Certificate of repurchase -
assignment.
39-11.5-404. Certificate as prima facie
evidence.
PART 5
ISSUANCE OF TREASURER'S DEED AND NATURE OF TITLE
39-11.5-501. Title vests upon expiration of
repurchase period - treasurer's deed - definition.
39-11.5-502. Form of treasurer's deed.
39-11.5-503. Treasurer's deed as evidence of
compliance.
39-11.5-504. Effect of treasurer's deed on
certain classes of persons.
39-11.5-505. Omitted party - definitions.
PART 6
CURATIVE PROVISIONS
39-11.5-601. Curative provisions.
39-11.5-602. Interaction with other law.
PART
1
PUBLIC
AUCTION
39-11.5-101. Definitions.
As used in
this article 11.5, unless the context otherwise requires:
(1)
"Application for treasurer's deed" means an application from a lawful
holder pursuant to section 39-11.5-102 related to a tax lien under this article
11.5.
(2)
"Business day" means any day the treasurer's office is open to the
public for conducting official business. Business days do not include weekends,
Colorado legal holidays, or any day the office is closed pursuant to county
policy or emergency order.
(3)
"Certificate of option for a treasurer's deed" means a certificate
issued by a treasurer to the successful purchaser at the public auction
pursuant to section 39-11.5-401.
(4)
"Certificate of purchase" means a certificate prepared by a treasurer
that is issued to the purchaser of a tax lien sale in accordance with section
39-11-117.
(5)
"Certificate of redemption" means a certificate prepared by a
treasurer after property subject to a tax lien sale is redeemed by the owner
prior to public auction in accordance with section 39-11.5-106.
(6)
"Certificate of repurchase" means a certificate prepared by a
treasurer when a lawful holder repurchases a certificate of option for a
treasurer's deed after the public auction in accordance with section
39-11.5-402.
(7)
"Claim for overbid money" means a claim for overbid money form as
specified in section 39-11.5-303.
(8)
"Fees and costs" means all fees pursuant to section 30-1-102 and all charges,
expenses, and costs described in section 39-11.5-108.
(9)
"Investor" has the meaning set forth in section 39-11-100.3 (2.7).
(10)
"Junior lien" means a lien or encumbrance upon the property for which
the amount due and owing thereunder is subordinate to the tax lien that was
duly recorded in the office of the county clerk and recorder prior to the
recording of the application for public auction for treasurer's deed.
(11)
"Junior lienor" means a person who is a beneficiary, holder, or
grantee of a junior lien or that person's assignee or attorney.
(12)
"Lawful holder" means a person in possession of a certificate of
purchase for a tax lien issued in accordance with article 11 of this title 39,
or the assignee, transferee, or attorney for such holder.
(13)
"Mailing list" means a mailing list assembled by the treasurer
pursuant to section 39-11.5-105.
(14)
"Nonmaterial misstatement" means a minor or inconsequential error or
omission that does not significantly affect the meaning, validity, or
enforceability of a document or other record containing the nonmaterial
misstatement.
(15)
"Notice of public auction" means a notice of public auction created
and sent by the treasurer in accordance with section 39-11.5-104.
(16)
"Overbid" means the amount of money a property is sold for at a
public auction in excess of the total property tax debt amount, including the
amount of money owed to the lawful holder of the certificate of purchase and
the fees and costs incurred by the treasurer in complying with this article
11.5.
(17)
"Posting" means placement of the notice of public auction that meets
the requirements set forth in section 39-11.5-105 (4), in a conspicuous
location on the property.
(18)
"Property" means a property subject to a tax lien, the certificate of
purchase for which is held by the lawful holder.
(19)
"Property owner", "current owner", or "owner"
means a person that currently holds title to, or has a recorded contractual
right to purchase, the property that is subject to a tax lien.
(20)
"Public auction" or "auction" means a public sale conducted
by the treasurer pursuant to this article 11.5.
(21)
"Publish", "publication", "republish", or
"republication" means placement by a treasurer of a legal notice that
meets the requirements set forth in section 24-70-103, containing a notice of
public auction, omitting the copies of the statutes, in a newspaper selected by
the treasurer that is in the county or counties where the property to be
auctioned is located.
(22)
"Purchaser" means a person to whom the treasurer awards the
certificate of option for a treasurer's deed as the winning bidder at the
public auction who timely submits proper funds, or, if no valid bids are
received at the public auction, the lawful holder who does not file a
withdrawal of the application for public auction for treasurer's deed pursuant
to section 39-11.5-401.
(23)
"Redemption statement" means a statement provided to the property
owner by the treasurer as described in section 39-11.5-106 (2).
(24)
"Surface owner" means a person or entity that holds title to, or a
recorded contractual right to purchase, the surface estate of a parcel of real
property.
(25)
"Tax lien" means a lien on a property sold for special assessments,
taxes, or special assessments and taxes due either to the state or any county
or incorporated town or city for which the treasurer issued a certificate of
purchase to the lawful holder.
(26)
"Treasurer" has the meaning set forth in section 39-1-102 (17) as
applied to the county in which a property is located.
(27)
"Treasurer's deed" means a deed or, in the case of a manufactured
home, mobile home, modular home, or tiny home, a certificate of ownership,
issued by the treasurer as described in section 39-11.5-501 in the form
specified in section 39-11.5-502 or 39-11.5-503.
Source: L. 2026: Entire article
R&RE, (SB 26-144), ch. 135, p. 622, § 53, effective June 1.
39-11.5-102. Lawful holder - application
for treasurer's deed - fee.
(1)
After August 1 of the third calendar year following the date of a tax lien
sale, a lawful holder may apply for a treasurer's deed for the property
described in the certificate of purchase in accordance with this section.
(2) (a)
A lawful holder must file an application for treasurer's deed in substantially
the following form:
application for treasurer's deed
to the county treasurer
of___________county, Colorado:
Treasurer's deed number ___________
The undersigned, as the lawful
holder of treasurer's tax lien sale certificate(s) of purchase no.(s) ________
issued pursuant to the tax lien sale held on the ____ day of ________, 20__,
for the taxes and/or special assessments in the amount of $________ for the tax
year(s) ______ hereby requests that the county treasurer, give notice and take
such proceedings as are required by law so that the undersigned may be entitled
to a treasurer's deed to the property described in the certificate of purchase,
more particularly described as follows, to-wit:
legal description:
Situated in the county of
___________, state of Colorado.
Property address: __________
Account/schedule number: __________
Parcel number: ___________
Current assessed owner: ___________
Lawful holder name: ___________
Lawful holder address: ___________
Lawful holder city, state, and zip
code: ___________
Lawful holder signature:
___________
Date: ___________
Current year taxes: _____________
Jr lien endorsements: ____________
Investment balance of tax lien:
____________
(b) A
lawful holder must submit a certificate of purchase, or a recorded copy
thereof, if recorded by the treasurer at the time of the tax lien sale, for
each property included in an application for treasurer's deed and any
assignments of each certificate of purchase in accordance with this section.
(c) Any
number of properties not exceeding twenty-five, whether contiguous or
noncontiguous, when held under one title of ownership, or whether included in
an irrigation district or not so included, and although tax liens for the
property were separately sold at the tax lien sale or covered by more than one
tax sale certificate, may be included and described in one application for a
treasurer's deed as provided for in this subsection (2). These properties, not
exceeding twenty-five in number, may also be included and described in a single
application for a treasurer's deed notice and are in conformity with this
article 11.5 in all other respects. The notice of public auction must
prominently display the name of the person in whose name the property was taxed
or specially assessed for the year in which the tax lien was sold. This name
must appear at or near the beginning of the notice and in close proximity to
the reference to the tax lien sale certificate number and the description of
the property involved. The information in the notice must be sufficient to
allow identification of the property with the name of the person assessed if
all certificates included in a single notice for public auction are held by the
same person.
(3) In
the event that the amount of the tax lien balance or any nonmaterial
misstatement is erroneously set forth in the application for a treasurer's
deed, the error does not affect the validity of the application for treasurer's
deed, the notice of public auction, the publication, the posting, the public
auction, the certificate of option for a treasurer's deed described in section
39-11.5-401, the certificate of redemption described in section 39-11.5-106
(4), the certificate of repurchase described in section 39-11.5-402, the
treasurer's deed as described in section 39-11.5-501, or any other document
executed in connection therewith.
(4) (a)
A lawful holder of a certificate of purchase who has applied for a treasurer's
deed pursuant to this section may assign or transfer the certificate of
purchase at any time during the pendency of the public auction process. Upon
receipt of written notice signed by the lawful holder, or the lawful holder's
attorney, evidencing the assignment or transfer of the certificate of purchase
and identifying the assignee or transferee, the treasurer shall proceed with
the public auction as if the assignee or transferee were the original
applicant.
(b) The
assignment or transfer of a certificate of purchase during the pendency of the
treasurer's deed process must be deemed made without recourse unless otherwise
agreed in a written statement signed by the assignor or transferor. The lawful
holder of a certificate of purchase, certificate of option for a treasurer's
deed, or certificate of repurchase who assigns or transfers their certificate
has no duty or liability to the assignee or transferee or to any third party
for any act or omission with respect to the provisions of this article 11.5
after the date of assignment or transfer.
(5) (a)
The treasurer may require the lawful holder to make a deposit of up to one
thousand dollars plus the amount of fees permitted pursuant to section 30-1-102
(1.7), at the time the application for treasurer's deed is accepted, to be
applied against the fees and costs of the treasurer in proceeding pursuant to
this article 11.5.
(b) The
treasurer may charge and accept a lesser fee amount than is permitted by
section 30-1-102 (1.7)(a)(I), for an application for a treasurer's deed when
the assessed value of the property in the application at the time of accepting
the application for treasurer's deed is five hundred dollars or less.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 624, § 53, effective June 1.
39-11.5-103. Review of application -
recording.
(1) The
treasurer may accept an application for a treasurer's deed. If accepted, the
treasurer shall review the application as soon as practicable but not later
than forty-five calendar days from the date of acceptance to determine whether
it complies with the requirements of this article 11.5.
(2) If
the treasurer determines that an application complies with the requirements of
this article 11.5, the treasurer shall collect from a lawful holder all
delinquent taxes owed and endorse all subsequent certificates of purchase for
tax liens on such property and shall verify that all subsequent taxes have been
paid in full by the lawful holder.
(3) The
treasurer shall record an application for a treasurer's deed and the
certificate of purchase, and all endorsements, within ten business days
following the treasurer's determination that all subsequent taxes have been
paid in full.
(4) The
recorded document must be retained in the county's public records in the county
where the property is located.
Source: L. 2026: Entire article
R&RE, (SB 26-144), ch. 135, p. 626, § 53, effective June 1.
39-11.5-104. Notice of application -
title review - mailing list.
(1) (a)
No more than ten calendar days after recording an application for a treasurer's
deed pursuant to section 39-11.5-102(2), the treasurer shall mail by first
class mail a notice of application for a treasurer's deed to the owner of
record of the property address set forth in the application for a treasurer's
deed.
(b) The
treasurer shall notify the owner of a manufactured home, mobile home, modular
home, or tiny home and any lienholder of record, by first class mail to the
owner's last-known mailing address, that an application for a treasurer's deed
for the home has been recorded by the treasurer on behalf of the lawful holder
of the certificate of purchase pursuant to section 39-11.5-103. The treasurer
shall thereafter proceed in like manner as is provided by law in the case of
certificates of purchase held by an investor.
(c) If
the property described in the application for a treasurer's deed consists of a
severed mineral interest and the tax lien is held by the county, the treasurer
shall proceed in the manner provided in this article 11.5, except that all fees
may be waived.
(2) Not
more than thirty calendar days after recording the application for a
treasurer's deed as set forth in section 39-11.5-103, the treasurer shall order
a title search or begin a review of relevant county records of the county clerk
and recorder concerning the property.
(3) The
title search described in subsection (2) of this section must be received or a
review of relevant county records of the county clerk and recorder concerning
the property must be completed no later than one hundred eighty calendar days
from the date of the recording of the application of public auction.
(4) Not
more than thirty business days after either receiving the title company's
search or completing a review of relevant county records of the county clerk
and recorder concerning the property, the treasurer shall create a mailing list
containing the names and addresses of:
(a) The
owner of the property at the time of the tax lien sale, at the property
address, and the last-known mailing address associated with the property as
shown in the records of the treasurer;
(b) The
owner of the property at the time of the tax lien sale, at the owner's
last-known mailing address as shown in the records of the treasurer, if
different than the property address;
(c) The
lawful holder of the certificate of purchase, or any assignees or transferees
of the certificate of purchase;
(d) The
occupant of the property, addressed to "occupant" at the address of
the property, if the property is commercial, residential, agricultural real
property, or a manufactured home, mobile home, modular home, or tiny home;
(e) The
lessee of the property, addressed to "lessee" at the address of the
property, if the property is commercial, residential, agricultural real
property, or a manufactured home, mobile home, modular home, or tiny home and
if the lease is recorded;
(f) The
current owner of the property, if different than the owner, at the time of the
tax lien sale; and
(g) All
junior lienors, as shown in the records of the county clerk and recorder, whose
liens were duly recorded in the records of the county clerk and recorder, prior
to the recording of the application for treasurer's deed.
(5) If
a recorded instrument does not specify the address of the party purporting to
have an interest in the property under the recorded instrument, that party is
not entitled to notice and any interest in the property under such instrument
is extinguished upon the execution and delivery of a treasurer's deed pursuant
to section 39-11.5-501.
(6) If
any notice sent pursuant to this section is returned as undeliverable, the
county treasurer shall conduct a reasonable search to locate and notify the
intended recipient within thirty calendar days of receipt of the returned mail
as undeliverable.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 627, § 53, effective June 1.
39-11.5-105. Notice of public auction -
mailing - publication - posting.
(1) No
more than ten business days after the treasurer has created the mailing list
pursuant to section 39-11.5-104, the treasurer shall mail by first class mail a
notice of public auction to the persons set forth in the mailing list.
(2) The
notice of public auction required to be mailed pursuant to this section must
contain:
(a) The
year for which the unpaid taxes were purchased;
(b) The
date of tax lien sale;
(c) The
name of the original purchaser at the tax lien sale;
(d) Any
assignments of the certificate of purchase;
(e) The
name of the owner of the property at the time of the tax lien sale;
(f) The
name of the lawful holder at time of recording of application for treasurer's
deed;
(g) The
legal description of the property and site address, if applicable;
(h) The
date and time of the originally scheduled public auction;
(i) The
location of the public auction, including the information required by
subsection (3) of this section, if applicable;
(j) The
publication date, if applicable; and
(k)
Legible copies of sections 39-11.5-106, 39-11.5-110, 39-11.5-112, and
39-11.5-301.
(3) If
the public auction is conducted by means of the internet or other electronic
medium, then the notice of public auction required to be mailed pursuant to
this section must include a statement of or directions where to obtain the
following:
(a) The
web address for the public auction;
(b) The
location of computer workstations available to the public;
(c)
Instructions on accessing the public auction and submitting bids; and
(d)
Bidding rules for the public auction will be posted on the treasurer's website
or the electronic medium used to conduct the auction at least fourteen calendar
days before the date of the public auction.
(4) (a)
No less than thirty calendar days prior to the first scheduled public auction
date, if the valuation for assessment of the property that is the subject of
the public auction, at the time of the recording of the application for
treasurer's deed, is five hundred dollars or more, the treasurer shall commence
publication of the notice of public auction, omitting the statutes, for three
weeks, which means publication once each week for three successive weeks in a
newspaper that is published daily, weekly, or semiweekly in the county where
the property is located.
(b) If
there is not a newspaper that satisfies the criteria identified in subsection
(4)(a) of this section, the treasurer shall post the notice of public auction,
omitting the statutes required by subsection (2)(k) of this section,
conspicuously in the offices of the county clerk and recorder, the treasurer,
and the assessor, in at least two other public places in the county seat, and
shall post the notice on the treasurer's website.
(c) The
fees and costs allowed for publication of the notice of public auction must be
as provided by law for the publication of legal notices or advertising.
(d) The
notice of public auction must be in substantially the following format:
NOTICE OF PUBLIC AUCTION
Notice is given that on [date], at
[location], the county Treasurer will conduct a public auction for a
treasurer's deed due to delinquent property taxes.
[insert legal description]
[insert property address]
Interested bidders must register.
More information at (website or treasurer's office phone number).
(5) (a)
No more than ten business days after mailing the notice of public auction, if
the assessed value of the property that is the subject of the public auction,
at the time of the recording of the application for treasurer's deed, is less
than five hundred dollars, or the property is a manufactured home, mobile home,
modular home, or tiny home, then the treasurer shall post the notice of public
auction, omitting the statutes required by subsection (2)(k) of this section,
on the treasurer's website.
(b) No
more than ten business days after mailing the notice of public auction, if an
application for treasurer's deed consists of multiple properties not exceeding
twenty-five, contiguous or noncontiguous, and the assessed value of each
property individually, at the time of the recording of the application for
treasurer's deed, is less than five hundred dollars, the treasurer shall post
the notice of public auction, omitting the statutes required by subsection
(2)(k) of this section, on the treasurer's website.
(6) No
less than thirty calendar days prior to the first scheduled public auction
date, the treasurer shall post, in a conspicuous location on a property; except
that the treasurer is not required to make the post required by this subsection
(6) if a property is severed mineral rights. For a manufactured home, mobile
home, modular home, or tiny home, the treasurer shall provide notice, including
a statement of taxes due for the owner to redeem, in accordance with subsection
(2) of this section.
(7) The
treasurer shall make, or cause to be made, an affidavit showing the posting of
the notice of public auction pursuant to this section. The treasurer shall
retain affidavits in the treasurer's records pursuant to the county retention
policy.
Source: L. 2026: Entire article
R&RE, (SB 26-144), ch. 135, p. 628, § 53, effective June 1.
39-11.5-106. Property owner redemption
procedure.
(1) (a)
A property owner is entitled to redeem a property if, no later than seven
calendar days prior to the currently scheduled public auction date, the
property owner files an intent to redeem the property with the treasurer.
(b) If
a property owner is deceased or incapacitated on or after the date and time of
the recording of the application for treasurer's deed, the property owner's
heirs, personal representative, legal guardian, or conservator, whether or not
that person's interest is shown in the records, upon providing satisfactory
proof to a treasurer, may file an intent to redeem and or redeem the
certificate of purchase as provided in this section.
(2) (a)
No later than three business days following the timely filing of an intent to
redeem, the treasurer shall provide a redemption statement to a property owner
pursuant to this section in a statement specifying the amount, itemized and in
substantially the same form as a bid pursuant to section 39-11.5-107.
(b) A
fee not exceeding twenty-five dollars may be charged to a property owner for
filing an intent to redeem or requesting an updated redemption statement under
this section.
(3) (a)
A redemption statement is effective for ten business days or until noon the day
before the currently scheduled public auction date, whichever occurs first.
(b) A
property owner may redeem a property at any time before the expiration of a
redemption statement by paying the treasurer, by the method of payment
specified by the treasurer, the amount required to redeem as specified in
subsection (2) of this section.
(c)
Upon receipt of the redemption payment, the treasurer shall notify the lawful
holder of the redemption and execute a withdrawal of the application for
treasurer's deed pursuant to section 39-11.5-111 (3).
(d) No
later than the tenth business day after receiving the redemption payment, the
treasurer shall record the withdrawal of the application for treasurer's deed
along with the certificate of redemption in the county records.
(e) The
treasurer shall disburse all redemption proceeds to the persons entitled to
receive them.
(4) No
more than ten business days after receiving the redemption payment, the
treasurer shall record a certificate of redemption pursuant to this subsection
(4) if a certificate of purchase or tax lien was recorded separately at the
time of the tax lien sale.
(5) All
fees and costs of the treasurer for actions performed under this section and
the cost of recording the certificate of redemption and withdrawal of the
application of public auction are part of the treasurer's costs for purposes of
this article 11.5.
(6) If
an aggrieved person contests the amount set forth in the redemption statement
prepared by the treasurer pursuant to subsection (2) of this section and a
court determines that the treasurer made a material misstatement in the
redemption statement with respect to the amount due and owing to the lawful
holder, the court shall, in addition to other relief, award to the aggrieved
person the aggrieved person's court costs and reasonable attorney fees and
costs.
(7) (a)
A property owner shall redeem the entire property. No partial redemption shall
be permitted under this section.
(b) The
priority of liens other than the tax lien for purposes of this section must be
determined without consideration of the fact that another lien relates to only
a portion of the property or to a partial interest therein.
(8)
Following expiration of the period for which the redemption statement is
effective, but no less than seven calendar days prior to the date of the public
auction, the property owner may make a written request to the treasurer for an
update of the amount necessary to redeem. Upon receipt by the treasurer of a
written request for updated redemption figures, subsection (3) of this section
applies.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 631, § 53, effective June 1.
39-11.5-107. Bid required - form of bid.
(1) (a)
A treasurer shall prepare, no later than seven calendar days prior to the
scheduled auction date, a bid form for a lawful holder's approval. The bid form
must be approved by a lawful holder and submitted to the treasurer no later
than noon on the second business day prior to the scheduled public auction, as
provided in this section, and must set forth all money due and owing to the
lawful holder, including all treasurer fees and costs.
(b) If
a lawful holder does not submit an approved bid form by the deadline specified
in subsection (1)(a) of this section, a treasurer shall prepare and submit a
bid form setting forth all money due and owing to the lawful holder, including
all treasurer fees and costs.
(2) A
lawful holder need not personally attend a public auction.
(3) A
bid must specify the following amounts, itemized in substantially the following
form:
BID
Treasurer of the county (or city
and county) of_____________ , state of Colorado.
Date: _______________
Treasurer's deed number:
_____________
Lawful holder/treasurer, whose
mailing address is_______________________ , bids the sum of $____________ in
your public auction to be held on the ____ day of__________ , 20__ .
Street address of property being
sold, if applicable: ______________________
The following is an itemization of
all amounts due the lawful holder of the tax lien.
Statutory rate of interest on tax
lien as of the date of public auction: __________
(Inapplicable items may be
omitted):
Amount due on tax lien $
______________________
Interest $______________________
Endorsement(s) $
______________________
Current years taxes
$______________________
Category subtotal $
______________________
Treasurer fees and costs:
Treasurer statutory fee $
______________________
Treasurer software costs
$___________________
Title commitments or abstractor
costs $______________________
Mailings $______________________
Publication costs $
______________________
Posting costs $
______________________
Electronic auction costs $
______________________
Certificate of option for a
treasurer's deed recording cost $ ________________
Treasurer deed fee $
______________________
Deed recording cost $
______________________
Other (describe)
$______________________
Category subtotal: $
______________________
Bid $ ______________________ (Total
due lawful holder)
Name of the lawful holder or
attorney for the holder: (if bid submitted by lawful holder or an attorney for
the lawful holder)
Lawful holder/or attorney:
______________
Attorney registration number:
__________
Attorney address: __________
Attorney business telephone:
__________
(4)
Upon receipt of an approved bid form from a lawful holder, or submission of a
bid form by a treasurer pursuant to subsection (1)(b) of this section, a
treasurer shall make such information available to the general public.
(5) A
treasurer shall enter a bid by reading the bid amount set forth on the bid form
and the name of the person that submitted the bid, or by posting or providing
that bid information at the time and place designated for the public auction.
(6) A
lawful holder must bid no less than the amount of the total debt, as determined
by the treasurer, for the certificate of purchase being sold. The failure of a
lawful holder to bid the amount required by this section does not affect the
validity of the auction.
(7)
Other than a bid by a lawful holder not exceeding the total amount due, as
shown on the bid form pursuant to subsection (3) of this section, the payment
of any amount bid at an auction must be received by a treasurer no later than
the date and time of the auction, or at an alternative time after the auction
and on the day of the auction, as specified in writing by the treasurer. A bid
payment must be made in the form specified by the treasurer. If a treasurer has
not received full payment of the bid amount from the highest bidder at an
auction in accordance with this subsection (7), the next highest bidder who
timely tenders the full amount of the bid under this subsection (7) is deemed
the successful bidder at the auction pursuant to section 39-11.5-110 (4).
(8) A
treasurer may establish written policies relating to all aspects of a public
auction that are consistent with the provisions of this article 11.5. The
written policies must be made available to the general public.
(9) If
a property is sold to a third-party bidder or a lawful holder as a competitive
bidder, a treasurer may collect up to three hundred dollars from the successful
bidder for performing actions related to processing the public auction pursuant
to section 30-1-102 (1.7)(a)(XIV).
(10) If
a lawful holder is the highest bidder with a bid amount that exceeds the total
amount due to the lawful holder as shown on the bid form created pursuant to
this section, a lawful holder is required to pay only the excess of the bid
over the amount due. A lawful holder shall pay the excess amount to the
treasurer within three business days after the public auction.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 632, § 53, effective June 1.
39-11.5-108. Fees and costs.
(1) All
fees pursuant to section 30-1-102 and costs incurred under this article 11.5
are fees and costs of the public auction chargeable as additional amounts owing
under the certificate of purchase. The amounts must be deducted from the
proceeds of any public auction or, if there are no cash proceeds from a public
auction adequate to pay the fees and costs to the extent of the inadequacy, the
lawful holder must pay the fees and costs. The treasurer may decline to issue a
treasurer's deed pursuant to section 39-11.5-501 until all money due to the
treasurer has been paid.
(2)
Fees and costs include, but are not limited to, the following amounts of money
that have been paid or incurred:
(a)
Costs and expenses allowable under the tax lien;
(b) All
expenses actually incurred by the treasurer conducting the public auction,
publication costs, posting costs, statutory notice costs and postage, and title
fees;
(c) Any
general or special taxes or ditch or water assessments levied or accrued
against the property and any governmental or quasi-governmental lien, fine,
penalty, or assessment against the property, if paid pursuant to this article
11.5; and
(d)
Sums due on any prior lien or encumbrance on the property that constitutes a
lien prior to the tax lien being auctioned; except that, any principal that
would not have been due prior to the public auction must not be included in the
sum due pursuant to this subsection (2)(d) unless paid pursuant to this article
11.5.
(3) In
the case of a property owner redemption made pursuant to section 39-11.5-106,
lawful holders' fees and costs specifying the amount, itemized in substantially
the same form as a bid pursuant to section 39-11.5-107 including treasurer fees
and costs must be included in the statement of redemption.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 634, § 53, effective June 1.
39-11.5-109. Public auction - timing of -
electronic bid.
(1) The
initial public auction held pursuant to this article 11.5 must be scheduled for
no less than thirty calendar days nor more than sixty calendar days after the
date of mailing the notice of public auction.
(2) If
a public auction is conducted electronically, a bid must be increased
electronically in increments incorporated in an electronic program used by the
treasurer to conduct the electronic auction up to the maximum bid if one or
more third parties submit competing bids for the property.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 635, § 53, effective June 1.
39-11.5-110. Public auction - location -
announcement - records - definition.
(1) (a)
The treasurer shall conduct the public auction at any door or entrance to, or
in any room in any building temporarily or permanently used as, a courthouse or
at or within any building where the office of the county clerk and recorder or
the office of the treasurer is located, which place must be specifically
designated in the notice of public auction; except that a public auction may
also be conducted by means of the internet or other electronic medium. The
county, the treasurer, and employees of the county or the treasurer, acting in
their official capacities in preparing, conducting, and executing a public
auction under this article 11.5 by means of the internet or another electronic
medium, are not liable for the failure of a device that prevents a person from
participating in a public auction under this article 11.5.
(b) As
used in subsection (1)(a) of this section, "device" includes, but is
not limited to, any computer hardware, computer network, computer software
application, or website.
(c) A
notice of public auction must designate the actual place of the auction or, if
the public auction is conducted by means of the internet or another electronic
medium, the information prescribed by section 39-11.5-105 (3).
(2) (a)
At a public auction, a treasurer must read only the treasurer's deed number;
the name of the lawful holder; the street address or, if none, the legal
description of the property; the first and last publication dates of the notice
of public auction, if applicable; and, in accordance with the bid form
submitted pursuant to section 39-11.5-107 (3), the amount of the bid and the
name of the person who submitted the bid.
(b) In
lieu of reading the information required by subsection (2)(a) of this section,
a treasurer may post the information at the location of the public auction,
provide a written copy of the information to all persons present at the public
auction, or post the information on the internet or other electronic medium, if
the public auction is conducted by means of the internet or another electronic
medium.
(3) (a)
A treasurer, acting in their individual capacity, must not bid at a public
auction held pursuant to this section.
(b)
This subsection (3) does not apply where the property subject to tax lien is
mineral rights and a treasurer is the surface owner of said mineral rights.
(4) At
any time before the commencement of a public auction, a treasurer may, for good
cause shown, prohibit a person from participating in a public auction. Good
cause may include, but is not limited to, failure to comply with auction
procedures or policies established by the treasurer, or engaging in disruptive,
abusive, fraudulent, or threatening behavior. A treasurer may prohibit a person
from participating in any public auction conducted under this article 11.5 for
a period of not more than five years.
(5) (a)
If a person bidding fails to pay the amount due, a treasurer may offer a
certificate of option for a treasurer's deed, without additional advertisement,
to another bidder, whether or not the public auction has closed; or may again
offer and sell a certificate of purchase on such property; or, at a treasurer's
option, the treasurer may recover the amount bid by civil action brought in the
name of the county in any court of competent jurisdiction.
(b) In
a public auction conducted by means of the internet or other electronic medium,
if a person bidding fails to pay the amount due, a treasurer may offer the
certificate of option for a treasurer's deed, without additional advertisement,
to another bidder, whether or not the public auction has closed; or may again
offer and sell a certificate of purchase on the property; or at a treasurer's
discretion, the treasurer may recover the amount bid by civil action brought in
the name of the county in any court of competent jurisdiction.
(c) A
treasurer may prohibit a person who fails to pay the amount due from bidding on
public auctions under this article 11.5 for not more than five years.
(6)
Whenever a treasurer sells property, the treasurer shall create and send for
recording in the records of the office of the clerk a certificate of option for
treasurer's deed pursuant to section 39-11.5-401.
Source: L. 2026: Entire article
R&RE, (SB 26-144), ch. 135, p. 635, § 53, effective June 1.
39-11.5-111. Continuance of public
auction - effect of bankruptcy - withdrawal of application.
(1) (a)
For any reason deemed by a treasurer to be good cause or upon written request
by a lawful holder, at any time before commencement of a public auction, a
treasurer may continue a public auction to a later date by making, at the time
and place designated for the public auction, an oral announcement of the time
and place of such continuance, or by posting or providing a notice of the
continuance at the time and place designated for the public auction, which
notice must include the time and place to which the public auction is
continued. Except as provided in subsection (2)(b)(I) of this section, a public
auction that is not held on the then-scheduled public auction date and is not
continued from the then-scheduled public auction date pursuant to this
subsection (1)(a) is deemed to have been continued for a period of one week,
and from week to week thereafter in like manner, until the public auction is
held or otherwise continued pursuant to this subsection (1)(a). A treasurer
must not continue a public auction to a date later than twelve months from the
originally designated date in the notice of public auction, except as provided
in subsection (2) of this section.
(b) At
the request of a lawful holder or upon a treasurer's own initiative, a
treasurer shall correct any errors in a published notice of public auction and
shall continue the then-scheduled public auction to a future date within the
period of continuance allowed by this subsection (1) to permit a corrected
notice of public auction to be published or the original notice of public
auction to be republished pursuant to section 39-11.5-105 (4). If a treasurer
failed to publish the notice of public auction as required by section
39-11.5-105 (4), the treasurer shall continue the then-scheduled public auction
to a future date within the period of continuance allowed by subsection (1)(a)
of this section. A future public auction date to which a treasurer continues a
public auction pursuant to this subsection (1)(b) must be no later than thirty
calendar days after the third publication of a corrected notice of public
auction or republication of the notice of public auction. The treasurer shall
mail by first class mail a copy of the notice of public auction, or corrected
notice of public auction if the original notice of public auction was
erroneous, to the persons and addresses on the mailing list no more than ten
calendar days after the first corrected publication or republication and no
less than forty-five calendar days prior to the newly scheduled public auction
in the same manner as set forth in section 39-11.5-105.
(2) (a)
If all publications of a notice of public auction prescribed by section
39-11.5-105 (4) or 13-56-201 (1) have been completed before any injunction or
bankruptcy petition is filed which automatically stays the treasurer from
conducting the public auction, the treasurer shall announce, post, or provide
notice of that fact on the then-scheduled public auction date, take no action
at the then-scheduled public auction, and allow the public auction to be
automatically continued from week to week in accordance with subsection (1)(a)
of this section, unless otherwise requested in writing prior to any such public
auction by the lawful holder.
(b) (I)
If the publications of a notice of public auction prescribed by section
39-11.5-105 (4) or 13-56-201 (1) have not commenced, or if all the publications
have not been completed, before the date that an injunction or a bankruptcy
petition is filed which automatically stays the treasurer from conducting the
public auction, the treasurer shall immediately cancel any remaining
publications of the notice of public auction and, on the date set for the
public auction, announce, post, or provide a notice that the public auction has
been enjoined or has been stayed by the automatic stay provisions of the
federal bankruptcy code of 1978, title 11 of the United States Code, as
amended. The public auction may not be continued under subsection (1)(a) of
this section.
(II)
(A) Upon the termination of any injunction or upon the entry of a bankruptcy
court order dismissing the bankruptcy case, abandoning the property being sold,
closing the bankruptcy case, or granting relief from the automatic stay
provisions of the federal bankruptcy code of 1978, title 11 of the United
States Code, as amended, and upon receipt of a request of a lawful holder to
restart the treasurer's deed process, the treasurer shall rerecord the
application for treasurer's deed and proceed with all additional treasurer's
deed procedures provided by this article 11.5 as though the treasurer's deed
process had just commenced.
(B) If
a request to restart the public auction is not received by a treasurer within
one year from the date of the termination of any injunction or the entry of a
bankruptcy court order dismissing the bankruptcy case, abandoning the property
being sold, closing the bankruptcy case, or granting relief from the automatic
stay, the public auction is deemed withdrawn according to subsection (3)(b) of
this section.
(III)
If a public auction is held in violation of the automatic stay provisions of
the federal bankruptcy code of 1978, title 11 of the United States Code, as
amended, and an order is subsequently entered by a bankruptcy court of
competent jurisdiction dismissing the bankruptcy, abandoning the property being
sold, or closing the bankruptcy case, or an order is subsequently entered
granting relief from the automatic stay provided by the federal bankruptcy
code, then the certificate of purchase must immediately be deemed reinstated,
and the certificate of purchase must have the same priority as if the public
auction had not occurred. Immediately upon reinstatement, the application for
treasurer's deed shall be deemed revived.
(IV) If
a lawful holder notifies a treasurer in writing of the entry of an order
dismissing the bankruptcy case, abandoning the property being sold, closing the
bankruptcy case, or granting relief from the automatic stay provided by the
federal bankruptcy code of 1978, title 11 of the United States Code, as
amended, no later than fifty calendar days prior to the last possible public
auction date pursuant to subsections (1)(a) and (2)(e) of this section, the
treasurer shall set a new public auction date at least twenty-four calendar
days but not more than forty-nine calendar days after the date on which the
treasurer receives this notice. No later than ten business days after receiving
the notice, the treasurer shall mail by first class mail an amended notice of
public auction containing the date of the rescheduled public auction to each
person appearing on the mailing list. No later than twenty calendar days after
receiving the notice, but no less than ten calendar days prior to the new
public auction, the treasurer shall publish the amended notice of public
auction, omitting the copies of the statutes one time only in a newspaper of
general circulation in the county where the property is located, subject to the
following limitations:
(A) If
the assessed value of a property at the time of the rerecording of an
application for treasurer's deed is less than five hundred dollars, no
publication is required; or
(B) If
there is no newspaper of general circulation in a county where a property is
located, a treasurer shall post a notice conspicuously in the offices of the
county clerk and recorder, the treasurer, and the assessor, and in at least two
other public places in the county seat.
(V) If
a lawful holder does not notify a treasurer in writing of the entry of an order
dismissing the bankruptcy case, abandoning the property being sold, closing the
bankruptcy case, or granting relief from the automatic stay provided by the
federal bankruptcy code of 1978, title 11 of the United States Code, as
amended, within the time allowed under subsection (2)(b)(IV) of this section,
the treasurer shall administratively withdraw the application for treasurer's
deed pursuant to subsection (3)(b) of this section upon receipt of the order
dismissing the bankruptcy case, abandoning the property being sold, closing the
bankruptcy case, or granting relief from the automatic stay provided by the
federal bankruptcy code of 1978, title 11 of the United States Code, as
amended.
(VI)
All fees and costs of providing and publishing the amended notice of public
auction and publication are part of the treasurer's deed costs.
(c) If
a public auction is set aside by court order, unless the court order specifies
otherwise, the following procedures apply:
(I)
Upon receipt of the court order, the treasurer's fee specified in section
30-1-102 (1.7)(a)(XII), and the costs of recording the court order as specified
in this subsection (2)(c), the treasurer shall attach to the order a copy of
the certificate of option for a treasurer's deed, any assignments thereof, and,
if applicable, the treasurer's deed, each marked "null and void", and
record the order together with these documents.
(II)
Upon recording of the court order, the certificate of option for a treasurer's
deed is deemed canceled as if the public auction had not occurred, and the
certificate of purchase is deemed fully reinstated with the same lien priority
as if the public auction had not occurred.
(III)
Within ten calendar days after receiving all documents, fees, and costs
specified in this subsection (2)(c), the treasurer shall mail by first class
mail a copy of the court order to each person entitled to receive the notice of
public auction pursuant to section 39-11.5-104.
(IV)
(A) After the recording of a court order, the lawful holder or the assignee
may notify the treasurer in writing to reschedule the public auction within one
year of the issuance of the order. The treasurer shall set a new public auction
date at least thirty calendar days but not more than forty-five calendar days
after the date on which the treasurer receives notice to schedule a new public
auction subject to the requirements of subsections (1)(a) and (2)(e) of this
section, but not earlier than the scheduled auction date as of the date of the
court order.
(B) No
more than ten calendar days after receiving notice to schedule a new public
auction, the treasurer shall mail by first class mail a notice of public
auction setting forth the rescheduled public auction date to each person
entitled to receive the notice of public auction pursuant to section
39-11.5-104.
(C) No
more than twenty calendar days after receiving notice to schedule a new public
auction, but no less than ten calendar days prior to the new public auction
date, the treasurer shall publish the notice of public auction one time only.
The publication must be in the format specified for publication by section
39-11.5-105 (4) and is subject to the same limitations set forth in subsections
(2)(b)(IV)(A) and (2)(b)(IV)(B) of this section.
(D) All
fees and costs of a treasurer for actions performed under this section and the
cost of recording the court order and documents incorporated into the court
order by attachment are part of the treasurer's deed costs.
(E)
After a public auction has been set aside and subsequently rescheduled pursuant
to this subsection (2)(c)(IV), the public auction may be continued in
accordance with subsections (1)(a) and (2)(e) of this section.
(F) If
a written request to reschedule a public auction in accordance with this
subsection (2) is not received by the treasurer within one year of the issuance
of an order, an application for treasurer's deed must be withdrawn according to
subsection (3)(b) of this section.
(V)
Nothing in this section prevents a lawful holder from seeking a rescission of
sale pursuant to section 39-11.5-114 if the requirements in that section are
met.
(d) The
period for which a public auction may be continued under this subsection (2)
must be in addition to the twelve-month period of continuance provided by
subsection (1) of this section.
(3) (a)
If a lawful holder files with a treasurer, prior to a public auction, a written
withdrawal of an application for treasurer's deed, the treasurer's deed
proceedings terminate. The treasurer shall record the withdrawal and collect
all fees and costs owed and incurred, including a withdrawal fee in the amount
authorized by section 30-1-102 (1.7)(a)(VIII).
(b) If
there is no public auction and if a withdrawal is not filed within forty-five
calendar days after the last possible public auction date permitted by law, a
treasurer may transmit by mail or electronic transmission to a lawful holder a
notice that a withdrawal of their application for treasurer's deed may be
recorded by the treasurer unless a response is received by the treasurer within
thirty calendar days after the date the treasurer's notice is transmitted. If a
response is received by the treasurer and no withdrawal is filed within
forty-five days after the notice is transmitted, the treasurer may record a
withdrawal of the application for treasurer's deed. If no response is received
by the treasurer within thirty calendar days after the notice is transmitted,
the treasurer may record a withdrawal of the application for treasurer's deed
at any time after the expiration of the thirty-day notice period. If a
withdrawal is recorded during the pendency of an automatic stay imposed on a
public auction based on any proceeding filed under the federal bankruptcy code
of 1978, title 11 of the United States Code, as amended, the withdrawal is void
and of no force and effect, and the treasurer shall mail by first class mail to
all persons on the mailing list a notice that the withdrawal of application for
treasurer's deed occurred during the pendency of an injunction or bankruptcy
stay and is void and of no force and effect. The treasurer shall cause the
notice to be recorded in the office of the county clerk and recorder of the
county where the property described in the notice is located. The lawful holder
shall pay all unpaid fees and costs owed and incurred by the treasurer, as well
as a withdrawal fee in the amount authorized by section 30-1-102 (1.7)(a)(VIII).
The amount due must accrue interest at the rate provided by law. Until all
amounts due and owing are paid, a treasurer is entitled to hold all
documentation in the treasurer's possession and to withhold all other services
requested by a lawful holder with respect to a certificate of option for a
treasurer's deed.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 637, § 53, effective June 1.
39-11.5-112. Treatment of overbid -
agreement to assist in recovery of overbid.
(1)
Upon the expiration of the claim for overbid money period provided in section
39-11.5-301, any remaining overbid must be paid in order of recording priority
to junior lienors, who have duly filed a claim for overbid money pursuant to
section 39-11.5-303, in each case up to the unpaid amount of each such junior
lienor's lien plus allowable fees and costs. A junior lienor holding a lien
that is not entitled to claim an overbid money by virtue of being recorded
after the application for treasurer's deed or a lienor that has not timely
filed a claim for overbid money pursuant to section 39-11.5-303 does not have
any claim to any portion of the overbid. After payment to all junior lienors
entitled to receive a portion of the overbid pursuant to this section, any
remaining overbid money must be paid to the property owner.
(2) (a)
If a treasurer maintains a website for their office, the treasurer shall
include the following statement on the website:
NOTICE TO A PROPERTY OWNER: If your
property goes to a public auction and is purchased for more than the total owed
to the lawful holder and to all other junior lien holders, please contact the
treasurer's office after the public auction because you may have money due to
you.
(b) To
pay the property owner as required pursuant to this subsection (2), a treasurer
shall send a notice to the property owner. If the amount of remaining overbid
is equal to or greater than twenty-five dollars, the treasurer shall make
reasonable efforts to identify the property owner's current mailing address.
The treasurer shall mail by first-class mail to the property owner a notice
regarding the remaining overbid to the best available address no later than
thirty calendar days after the expiration of the claim for overbid money period
as provided in section 39-11.5-303 (2).
(c) Any
agreement to pay compensation to recover or assist in recovering an unclaimed
overbid transferred to the administrator under this section or to the county
treasurer per a county resolution is enforceable if the compensation to be paid
under the terms of the agreement does not exceed ten percent of the amount of
the overbid money and if entered into at least two years after the date of the
transfer.
(3) (a)
The treasurer shall hold any unclaimed remaining overbid from a public auction
in escrow for two years from the date of the public auction. The treasurer is
answerable to any person legally entitled to the money without interest at any
time within the two-year period. Any interest earned on the escrowed money must
be paid to the county at least annually. Remaining overbid claims that are for
less than twenty-five dollars and that are not claimed within six months from
the date of the public auction must be paid to the general fund of the county,
and the money paid to the general fund of the county becomes the property of
the county. Remaining overbid claims for amounts that are equal to or greater
than twenty-five dollars and that are not claimed within two years from the
date of the public auction may be unclaimed property for purposes of the
"Revised Uniform Unclaimed Property Act", article 13 of title 38, and
must be transferred to the state treasurer in accordance with article 13 of
title 38. After unclaimed remaining overbid money is transferred to the state
treasurer or to the general fund of the county, the treasurer is discharged
from any further liability or responsibility for the money.
(b) If
the unclaimed remaining overbid money exceeds five hundred dollars and has not
been claimed by any person entitled thereto within sixty calendar days after
the expiration of the claim for overbid money period provided by section
39-11.5-303 (2), the treasurer shall, within ninety calendar days after the
expiration of the claim for overbid money period, publish a notice, one time
only, in a newspaper of general circulation in the county where the property is
located. The notice must contain the name of the property owner, the property
owner's address as given in the certificate of purchase, and the legal
description and street address, if any, of the property sold at the public
auction. The notice must state that an overbid was realized from the public
auction and that, unless the overbid is claimed by the property owner or other
person entitled thereto within two years after the public auction, the money
will be transferred to the state treasurer for disposition in accordance with
the "Revised Uniform Unclaimed Property Act", article 13 of title 38.
The treasurer shall also mail by first-class mail a copy of the notice to the
property owner at the best available address.
(c) The
fees and costs of publication and mailing required pursuant to this subsection
(3) must be paid from the overbid escrowed by the treasurer.
Source: L. 2026: Entire article
R&RE, (SB 26-144), ch. 135, p. 642, § 53, effective June 1.
39-11.5-113. Use of electronic documents
authorized.
Consistent
with the "Uniform Electronic Transactions Act", article 71.3 of title
24, any document or record related to a public auction may be accepted by the
treasurer in an electronic format or may be made available to the public by the
treasurer in an electronic format. The treasurer shall establish and uniformly
apply written policies for determining whether and the extent to which the
treasurer shall accept documents or records in electronic form; except that the
treasurer shall not require the use of an electronic format for any purpose
under this article 11.5 except as necessary for sales conducted by means of the
internet or another electronic medium.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 643, § 53, effective June 1.
39-11.5-114. Rescission of public
auction.
(1) (a)
If the successful purchaser at a public auction is a lawful holder, then the
lawful holder may rescind the public auction without obtaining a court order by
filing with the treasurer no later than three business days after the date of
the public auction a notice of rescission of public auction stating that the
public auction is being rescinded. The notice of rescission must include the
treasurer's deed number, the date of the public auction, the name of the person
to whom the certificate of option for a treasurer's deed was issued, the name
of the assignee, if any, the recording date and reception number or book and
page number for the recorded certificate of option for a treasurer's deed, and
the legal description of the property sold. The notice must be signed and
properly acknowledged by the lawful holder or assignee or signed by their
attorney.
(b)
Upon receipt of a notice of rescission of a public auction, any assignment of
the certificate of option for a treasurer's deed, the treasurer's fee for the
rescission specified in section 30-1-102 (1.7)(a)(IX), and the costs of
recording the notice of rescission of a public auction, the treasurer shall
record the notice of rescission of the public auction in the county records.
(2)
Upon recording of a notice of rescission of public auction by a treasurer, a
certificate of option for a treasurer's deed is deemed canceled as if the
public auction had not occurred, and the certificate of purchase is deemed
fully reinstated with the same lien priority as if the public auction had not
occurred. The treasurer shall confirm the reinstatement by endorsement on the
certificate of purchase submitted pursuant to section 39-11.5-102.
(3)
Within ten calendar days after receipt of all documents and fees and costs
specified in subsection (1)(b) of this section, the treasurer shall mail by
first-class mail a copy of the notice of rescission of the public auction to
each person who was entitled to receive the notice of the public auction
pursuant to section 39-11.5-104.
(4) (a)
After the recording of a notice of rescission of public auction, a lawful
holder or the assignee may notify the treasurer in writing to reschedule the
public auction. The treasurer shall set a new public auction at least thirty
calendar days but not more than forty-five calendar days after the date on
which the treasurer receives notice to schedule a new public auction, subject
to the requirements of section 39-11.5-109.
(b) No
later than ten calendar days after receiving notice to schedule a new public
auction, the treasurer shall mail by first-class mail a notice of public
auction setting forth the rescheduled public auction date to each person who
was entitled to receive the notice of public auction pursuant to section
39-11.5-104.
(c) No
more than twenty calendar days after receiving notice to schedule a new public
auction, but no less than ten calendar days prior to the newly scheduled public
auction date, the treasurer shall publish the notice of public auction one time
only, subject to the following limitations:
(I) If
the assessed value of a property at the time a treasurer receives notice to
schedule a new public auction is less than five hundred dollars, no publication
is required; or
(II) If
there is no newspaper of general circulation in the county where the property
is located, then the treasurer shall post the notice for public auction
conspicuously in the offices of the county clerk and recorder, the treasurer,
and the assessor and in at least two other public places in the county seat.
(d) All
fees and costs of a treasurer for actions performed under this section and the
cost of recording the notice of rescission of public auction must be part of
the treasurer's deed costs.
(e)
After a public auction has been rescinded and rescheduled pursuant to this
subsection (4), the public auction may be continued in accordance with section
39-11.5-111 (1)(a).
(f) If
a written request to reschedule the public auction is not received by a
treasurer within one year of the recording of a notice of rescission, an
application for treasurer's deed must be withdrawn.
(5)
Nothing in this section prevents any person from seeking a rescission of a
public auction through a court of competent jurisdiction.
(6)
Claims for damages by any person arising out of a rescission of a public
auction pursuant to this section are limited to the reasonable actual expenses
of the person and must not include any speculative or expectation damages,
awards, or claims of any kind, whether legal or equitable.
(7) The
endorsement of the treasurer pursuant to subsection (2) of this section must be
in substantially the following form:
The undersigned, as treasurer for
the county of _______________, state of Colorado, by this endorsement, hereby
confirms the reinstatement of this certificate of purchase in accordance with
the requirements of section 39-11.5-113, Colorado revised statutes.
Date:
Signature:
Treasurer
For the county of ____________,
State of Colorado.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 643, § 53, effective June 1.
39-11.5-115. Unclaimed refunds -
disposition.
Money
payable as a refund for overpayment of a redemption pursuant to part 1 of this
article 11.5 that remains unclaimed by the property owner for two years after
the money became payable is presumed abandoned and may be reported and paid to
the state treasurer in accordance with sections 38-13-401 and 38-13-603.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 645, § 53, effective June 1.
39-11.5-116. Abbreviations, letters, and
figures may be used.
In all
advisements for the public auction and in entries required to be made by the
assessor, county clerk and recorder, treasurer, or other county officers in
lists, books, rolls, certificates, receipts, deeds, or notices, the assessor,
county clerk and recorder, treasurer, or other county officer may use letters,
figures, and abbreviations to denote townships, ranges, sections, parts of
sections, lots, blocks, dates and amounts of taxes, delinquent interest, and
costs.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 646, § 53, effective June 1.
PART
2
SEVERED
MINERALS - RIGHT OF FIRST REFUSAL
39-11.5-201. County-held severed mineral
rights - procedure - form.
(1) Any
county in this state having in its possession certificates of purchase
resulting from a tax lien sale for nonpayment on severed minerals may after
three years file an application for treasurer's deed in the same manner as a
lawful holder of a certificate of purchase.
(2) No
less than thirty calendar days prior to an originally scheduled public auction
date, a treasurer may mail by first-class mail a copy of a notice of public
auction along with a right of first refusal form to the record owner of the
surface property. The right of first refusal form must be substantially in the
following form:
Notice by surface owner to exercise
right of first Refusal
To ___________________ county
treasurer
Under the right of first refusal
granted to me by section 39-11.5-201, Colorado revised statutes, I
_____________ (full name) do now exercise the option to purchase the severed
minerals with the following legal description: insert legal description
located at _______________________
(address), if applicable
In the amount of $________________
(insert full amount due to redeem severed mineral rights)
Which I shall pay on or before
________________ date (date shall be set at ten business days or noon the day
before the currently scheduled public auction, whichever occurs first).
Witness my signature this ______
day of __________________, 20___.
___________________
Signature of surface owner(s)
(3) (a)
A surface owner has fourteen calendar days from the date of the mailing by the
treasurer to file the form exercising the right of first refusal.
(b) If
no response is received from a surface owner by the deadline in this section,
the option of first refusal expires.
(c)
Upon receipt of a right of first refusal payment, a treasurer shall execute and
record a withdrawal of the application for treasurer's deed pursuant to section
39-11.5-111 (3).
(d) No
more than ten business days after receipt of a right of first refusal payment,
a treasurer shall execute and record a certificate of redemption pursuant to
section 39-11.5-106 (4).
(e) No
more than ten business days after receipt of a right of first refusal payment,
a treasurer shall execute and record a treasurer's deed pursuant to section
39-11.5-501.
(f) All
fees and costs of a treasurer for actions performed under this section and the
cost of recording the certificate of redemption, withdrawal of the application
for treasurer's deed, and treasurer's deed may be waived by the treasurer.
(4) If
an aggrieved person contests the amount set forth in the right of first refusal
statement prepared by a treasurer pursuant to subsection (2) of this section
and a court determines that the treasurer made a material misstatement on the
first refusal statement with respect to the amount due and owing to the county,
the court shall, in addition to other relief, award to the aggrieved person the
aggrieved person's court costs and reasonable attorney fees and costs.
(5) A
surface owner shall purchase the entire severed mineral property located
beneath their property. No partial purchase is permitted under this section.
The priority of liens for purposes of this section must be determined without
consideration of the fact that the lien relates to only a portion of the
property or to a partial interest therein.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 646, § 53, effective June 1.
PART
3
REPURCHASE
- CLAIM FOR OVERBID MONEY
39-11.5-301. Repurchase - procedure.
(1) A
lawful holder is entitled to repurchase a certificate of option for a
treasurer's deed if the following requirements are met to the satisfaction of
the treasurer:
(a) The
lawful holder was not the successful purchaser at the public auction;
(b) No
later than three business days after the date of the public auction, the lawful
holder filed a notice of intent to repurchase; and
(c) A
fee pursuant to section 30-1-102 (1.7)(a)(III) is received by the treasurer in
the form specified by the treasurer.
(2) No
more than one business day after an intent to repurchase is received, a
treasurer shall notify the certificate of option for a treasurer's deed holder
that an intent to repurchase has been filed.
(3) No
later than noon two business days following a notification of the certificate
of option for a treasurer's deed holder of the filing of an intent to
repurchase, a certificate of option for a treasurer's deed holder must provide
a signed and acknowledged repurchase statement to the treasurer limited to:
(a) The
amount indicated on the certificate of option for a treasurer's deed that
exceeds the total debt owed to the lawful holder;
(b)
Interest calculated from the date of the public auction through the end of the
eighth business day after the public auction, the amount of which is based on
the interest rate used on the bid pursuant to section 39-11.5-107 (3); and
(c) Any
fees and costs incurred as deemed reasonable by the treasurer.
(4) If
a certificate of option for a treasurer's deed holder fails to provide a
repurchase statement to a treasurer by the deadline, the treasurer shall
provide a repurchase statement to a lawful holder limited to the amounts
required in subsections (3)(a) and (3)(b) of this section, by the end of the
second business day after the notification of the certificate of option for a
treasurer's deed holder pursuant to subsection (3) of this section. The
repurchase statement may be sent to a lawful holder by mail, facsimile, or
other electronic means.
(5) At
any time after a treasurer has provided a lawful holder the repurchase
statement, but no later than noon on the eighth business day following the
public auction, the lawful holder may repurchase the certificate of option for
a treasurer's deed by paying the treasurer the amount required to repurchase in
the form specified by the treasurer.
(6)
Upon receipt of the repurchase funds, the treasurer shall:
(a)
Notify the certificate of option for a treasurer's deed holder;
(b)
Execute and record a certificate of repurchase pursuant to section 39-11.5-402;
and
(c)
Disburse all repurchase proceeds to the certificate of option for a treasurer's
deed holder in the amount on the repurchase statement with interest through the
date repurchase proceeds were received from the lawful holder. Any additional
interest paid must be refunded to the lawful holder.
(7) All
fees and costs of a treasurer for actions performed under this section and the
cost of recording the certificate of repurchase are part of the treasurer's
deed costs.
(8) If
an aggrieved person contests the amount set forth in the statement prepared by
a treasurer pursuant to subsection (4) of this section and a court determines
that the treasurer made a material misstatement on the repurchase statement
with respect to the amount due and owing to the holder of the certificate of
option for a treasurer's deed, the court shall, in addition to other relief,
award to the aggrieved person the aggrieved person's court costs and reasonable
attorney fees and costs.
(9) (a)
A lawful holder shall repurchase the entire property. No partial repurchase
shall be permitted under this section.
(b) The
priority of liens for purposes of this section must be determined without
consideration of the fact that the other lien relates to only a portion of the
property or to a partial interest therein.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 647, § 53, effective June 1.
39-11.5-302. Effect of repurchase.
If the
lawful holder makes a repurchase, the certificate of repurchase, duly recorded,
operates as an assignment to the lawful holder of the estate and interest
acquired by the purchaser at the public auction, subject to the rights of
omitted parties, as defined in section 39-11.5-505, and persons who may be
entitled subsequently to file a claim for overbid money.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 649, § 53, effective June 1.
39-11.5-303. Claim for overbid money -
procedure.
(1) A
junior lienor is entitled to make a claim for overbid money if the following
requirements are met to the satisfaction of the treasurer:
(a) The
junior lienor's lien appears by instruments that were duly recorded in the
office of the clerk and recorder of the county prior to the recording of the
application for treasurer's deed. If a junior lien was recorded in an incorrect
county, the junior lienholder's rights under this section are valid only if the
lien is rerecorded in the correct county at least fifteen calendar days prior
to the actual date of the public auction.
(b) If
a junior lien is assigned, the rights of the assignee of the junior lien to
make a claim for overbid money are valid only if the assignment of the junior
lien as described in subsection (1)(a) of this section is duly recorded in the
office of the clerk and recorder of the county at least fifteen calendar days
prior to the actual date of the public auction;
(c) The
junior lienor has, within eight business days after the public auction, filed a
claim for overbid money with the treasurer; and
(d) The
junior lienor has attached to the claim for overbid money:
(I) The
original or a recorded copy of the instrument and any assignment of the junior
lien to the person attempting to claim overbid money. If the original
instrument is delivered to the treasurer, the treasurer shall return the
instrument to the junior lienor and retain a copy.
(II) A
signed and properly acknowledged statement, or a signed statement by the junior
lienor's attorney, setting forth the amount of the lienor's junior lien,
including per diem interest, through the end of the eighth business day after
the public auction with the same specificity and itemization as required in
section 39-11.5-107.
(2) No
fee may be charged to a junior lienholder for filing a claim for overbid money
pursuant to this section.
(3) Any
time after the ninth business day but no later than the fifteenth business day
from the date of the public auction, any remaining overbid money must be paid
in order of recording priority to junior lienors, determined as of the
recording of the application for treasurer's deed, who have duly filed a claim
for overbid money, in each case up to the unpaid amount of the lien plus fees
and costs. After payment to all junior lienors entitled to receive a portion of
the overbid pursuant to this section, any remaining overbid money must be paid
to the property owner.
(4) Any
redemption rights granted under federal law are separate and distinct from a
claim for overbid money rights granted pursuant to this part 3. All liens that
are junior to the certificate of purchase pursuant to this article 11.5 must be
divested by the public auction under this article 11.5, subject to the claim
for overbid money provided in this part 3. The treasurer conducting a public
auction under this article 11.5 is not designated to receive redemptions under
federal law.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 649, § 53, effective June 1.
39-11.5-304. Lessee, easement holder, and
installment contract vendor considered as lienors - installment land contract
vendee considered as owner.
(1) (a)
For the purposes of this article 11.5, a lessee of or the holder of an easement
encumbering property is considered a junior lienor, but without any lien
amount, and is subject to all requirements in this article 11.5 with respect to
junior lienors.
(b) The
notice to the lessee or lessees who have unrecorded possessory interests in the
property being sold as provided for by this article 11.5 and article 37 of this
title 39 by virtue of any tax lien sale or by virtue of an execution and levy
must be mailed to the lessee or lessees of a single-family residence or a
multiple-unit residential dwelling. The notice must be in writing and sent by
first-class mail. Notice is complete upon mailing to the lessee at the address
of the premises or by addressing such notice to "Lessee" followed by
the address.
(c)
Nothing in this section affects any rights under this article 11.5 of a lessee
whose residential lease is recorded.
(2) For
the purposes of this article 11.5, an installment land contract vendor of
property is considered a junior lienor for the unpaid portion of the purchase
price, interest, and other amounts provided under the installment land contract
and is subject to all requirements in this article 11.5 with respect to junior
lienors; but the installment land contract vendor shall not be considered an
owner as to any portion of such property.
(3) For
the purposes of this article 11.5, an installment land contract vendee of
property is considered an owner except as to any portion of such property that
the vendee may thereafter have transferred, as evidenced by a recorded
instrument, and the vendee is subject to all requirements in this article 11.5
with respect to owners.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 650, § 53, effective June 1.
PART
4
CERTIFICATE
OF OPTION FOR A TREASURER'S DEED
39-11.5-401. Certificate of option for a
treasurer's deed - issuance - priority.
(1) No later
than three business days from the date of a public auction, a treasurer shall
execute and record in each county where a property or a portion thereof is
located a certificate of option for a treasurer's deed containing:
(a) The
names of the property owner;
(b) The
description of the property;
(c) The
sum paid for the property;
(d) The
name and mailing address of the purchaser;
(e) A
statement that the purchaser or assignee of the certificate of option for a
treasurer's deed is entitled to a treasurer's deed at the expiration of the
repurchase period provided under part 3 of this article 11.5 unless a
repurchase is made;
(f) The
treasurer's deed number;
(g) The
date of the public auction; and
(h) An
attached exhibit that is a copy of the mailing list created for the public
auction pursuant to section 39-11.5-105 and any amendment to that mailing list,
which exhibit must be recorded with the certificate of option for treasurer's
deed.
(2) The
failure of a treasurer to comply with this section does not affect the validity
of a public auction or vesting of title in the name of the holder of the
certificate of option for a treasurer's deed or certificate of repurchase.
(3) The
lien represented by a certificate of option for a treasurer's deed has the same
priority as the certificate of purchase sold at a tax lien sale.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 651, § 53, effective June 1.
39-11.5-402. Certificate of repurchase -
issuance.
(1) No
later than three business days following a treasurer's receipt of repurchase
money paid pursuant to section 39-11.5-301, the treasurer shall execute and
record in each county where the property, or a portion thereof, is located a
certificate of repurchase containing:
(a) The
name of the purchaser;
(b) The
name and address of the lawful holder;
(c) The
repurchase amount paid;
(d) The
date of the public auction;
(e) The
legal description of the property;
(f) The
treasurer's deed number; and
(g) A
statement that the lawful holder or assignee of the certificate of repurchase
shall be entitled to a treasurer's deed under part 3 of this article 11.5.
(2) The
failure of a treasurer to comply with this section does not affect the validity
of the public auction or the rights of the grantee of a treasurer's deed.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 652, § 53, effective June 1.
39-11.5-403. Certificate of repurchase -
assignment.
(1) (a)
A certificate of option for a treasurer's deed or a certificate of repurchase
that is issued to any person under this part 4 is assignable by endorsement
thereon or by separate assignment, and the assignee must be treated for all
purposes as the original holder of the certificate of option for a treasurer's
deed or certificate of repurchase.
(b) A
separate assignment of a certificate of option for a treasurer's deed or
certificate of repurchase must contain:
(I) The
name and address of the assignee;
(II)
The name and address of the assignor;
(III)
The legal description of the property subject to the assigned certificate;
(IV)
The name of the property owner; and
(V) The
treasurer's deed number.
(2) A
fee not to exceed twenty-five dollars may be charged by the treasurer to the
assignor or assignee for filing an endorsement or separate assignment with the
treasurer under this section.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 652, § 53, effective June 1.
39-11.5-404. Certificate as prima facie
evidence.
A
certificate of option for a treasurer's deed or certificate of repurchase or a
recorded copy thereof is deemed to be prima facie evidence of all statements or
recitals contained therein.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 653, § 53, effective June 1.
PART
5
ISSUANCE
OF TREASURER'S DEED AND NATURE OF TITLE
39-11.5-501. Title vests upon expiration
of repurchase period - treasurer's deed - definition.
(1)
Upon the expiration of the repurchase period allowed to the lawful holder under
part 3 of this article 11.5 or, upon the close of the eighth business day after
the public auction, title to the property vests in the holder of the
certificate of option for a treasurer's deed, or in the holder of the
certificate of repurchase in the case of a repurchase. Subject to the right to
claim overbid money pursuant to section 39-11.5-303 and the provisions of
section 38-41-212 (2), the title is free and clear of all liens and
encumbrances junior to the certificate of purchase. No later than ten business
days after both title vests and the treasurer has received all statutory fees
and costs, the treasurer shall execute and record a treasurer's deed pursuant
to section 39-11.5-502 to the holder of the certificate of option for a
treasurer's deed or, in the case of repurchase, to the holder of the
certificate of repurchase, confirming the transfer of title to the property.
Failure of the treasurer to execute and record the treasurer's deed or to
record the treasurer's deed within the time specified in this subsection (1)
does not affect the validity of the treasurer's deed or the vesting of title.
(2)
Notwithstanding any provision of law to the contrary, a treasurer may not
include an assignee as a grantee in a treasurer's deed, unless the following
requirements are met:
(a) The
treasurer has received a recorded copy of the assignment executed in accordance
with section 39-11.5-403 within ten business days from the date of the public
auction; and
(b) The
assignment was dated, signed, and notarized or recorded prior to the time title
vests.
(3)
Execution of a treasurer's deed pursuant to this section does not affect the
existence of any public or private roads, rights-of-way, conservation
easements, other easements, or equitable servitudes that run with property and
have both benefits and burdens, all as claimed or existing prior to the
execution of the treasurer's deed.
(4) As
used in this section, "repurchase periods" means the periods of time
during which the lawful holder may repurchase the certificate of option for a
treasurer's deed, as described in section 39-11.5-301 (5).
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 653, § 53, effective June 1.
39-11.5-502. Form of treasurer's deed.
The
treasurer's deed executed by a treasurer after a public auction may be in
substantially the following form:
The following described real
property is the subject of this treasurer's deed:
treasurer's deed number:
____________
legal description:
also known by street address as:
assessor schedule/account no:
________________
original assessed owner:
_____________________
The taxes assessed upon this
property for the years - remained due and unpaid at the date of the public tax
lien sale ("sale");
The __________ county treasurer, by
virtue of the authority vested in them by law, conducted the tax lien sale on
_____________(month, day, year) in substantial conformity with statutory
requirements;
A tax lien certificate of purchase
was issued to_______________, ("lawful holder") for this property for
the payment of the taxes, delinquent interest, and costs then due and remaining
unpaid;
More than three years have elapsed
since the date of the tax lien sale, the property owner's statutory redemption
period has expired, and the property has not been redeemed;
The lawful holder filed an
application for treasurer's deed for the above-described property on
_______________ (month, day, year). The application was recorded on
________________ (month, day, year), in the real estate records of
_____________ county, Colorado at reception no. _________________;
The treasurer provided notice of
the public auction as required by law and then proceeded to hold a public
auction on ___________________ (month, day, year). At the public auction,
________________________ ("purchaser"), whose address is ___________________,
county of _____________, state of ______________, bid the sum of $___________
for said property. Being the person who submitted the winning bid at the public
auction and who timely submitted proper funds, the treasurer awarded a
certificate of option for a treasurer's deed to the purchaser;
The lawful holder subsequently
repurchased the certificate of option for a treasurer's deed by paying to the
treasurer the amount the purchaser paid at the public auction, with interest
from the date of sale, along with all applicable fees or costs. The repurchase
was made on_______________ (month, day, year) and, after the repurchase of the
above-described property, the lawful holder is entitled to a treasurer's deed;
or
On ________________(month, day,
year),_________________("purchaser") assigned the certificate of
option for a treasurer's deed on the property, along with all rights, title,
and interest, to ________________("assignee") located _________________________
(assignee mailing address). Then, ________________(month, day, year),
______________(assignee), assigned the same certificate of option for a
treasurer's deed and all associated rights, title, and interest to
__________________(second assignee), located at _________________________________
(second assignee mailing address), if applicable.
All statutory provisions
prescribing the prerequisites to obtaining a treasurer's deed have been
fulfilled at this time.
Now, therefore, in consideration of
the above, I, _____________________, treasurer of __________ county convey to
____________________________ (name or purchaser, lawful holder, or assignee)
whose address is ___________________, county of _____________, State of
____________ all right, title, and interest in the property, subject to any
encumbrances and restrictions of record.
Executed on:___________________
_____________________, treasurer of
__________ county, state of Colorado
(SEAL)
____________________________________________(Signature)
By:
When recorded, return to county
treasurer
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 654, § 53, effective June 1.
39-11.5-503. Treasurer's deed as evidence
of compliance.
A
treasurer's deed executed by a treasurer or other official pursuant to this
article 11.5 is prima facie evidence of compliance with all statutory
requirements for the public auction and execution of the treasurer's deed and
evidence of the truth of the recitals contained in the treasurer's deed.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 655, § 53, effective June 1.
39-11.5-504. Effect of treasurer's deed
on certain classes of persons.
(1) All
executed certificates of purchase by a treasurer may be requested to have a
treasurer's deed in the manner provided by section 39-11.5-102, notwithstanding
the fact that property may be owned or consist of the estate of a deceased
person, a mentally incompetent person, or an incapacitated person and
notwithstanding the death, mental incompetency, or incapacity of one or more of
the owners of the property covered by the certificate of purchase.
(2) Any
such treasurer's deed process is good against a mentally incompetent or an
incapacitated person and against the heirs-at-law, legatees, devisees,
creditors, conservators, guardians, personal representatives, executors, and
administrators of any decedent or mentally incompetent or incapacitated person
and all persons claiming by, through, or under the decedent or mentally
incompetent or incapacitated person. The treasurer shall give notice of such
treasurer's deed proceedings, as provided by law, to the property owner at the
address, as though living and mentally competent, to all persons having
interests then of record, and to the lessee or lessees of the premises as
provided in section 39-11.5-104 (4). The treasurer shall not be required to give
notice of such treasurer's deed proceedings to any heir-at-law, legatee,
devisee, creditor, conservator, guardian, personal representative, executor, or
administrator of any decedent or mentally incompetent or incapacitated person
or to any person claiming by, through, or under any decedent or mentally
incompetent or incapacitated person unless the claim or interest of the person
then appears on record.
(3) The
interest and claim in and to the real estate of all mentally incompetent or
incapacitated persons and of all persons claiming by, through, or under any
mentally incompetent or incapacitated person, or decedent, including minors and
incapacitated persons, is terminated and concluded by the treasurer's deed
process unless they redeem from the treasurer within the time prescribed by
law.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 655, § 53, effective June 1.
39-11.5-505. Omitted party - definitions.
(1) As
used in this section, "omitted party" means any person who, prior to
the recording of an application for treasurer's deed for a property, has either
acquired a record interest in the property or has obtained a valid possessory
interest in and is in actual possession of the property, which interest is
junior to the certificate of purchase and would otherwise be extinguished by
the treasurer's deed.
(2) (a)
The interest of an omitted party in property that is the subject of a
treasurer's deed process may be terminated if the omitted party, or anyone
claiming by, through, or under an omitted party, in a civil action commenced at
any time after a public auction, by any interested person, as defined in
subsection (2)(c) of this section, by an omitted party, or by anyone claiming
by, through, or under an omitted party, is afforded rights to claim overbid
money upon such terms that the court may deem equitable under the
circumstances, which terms shall not, however, be more favorable than the
person's statutory rights. The court shall give full consideration to whether
the omitted party or anyone claiming by, through, or under an omitted party was
given or had actual notice or knowledge of the treasurer's deed process and was
given an opportunity to exercise statutory rights to claim overbid money.
(b) For
purposes of this section, the lien that is the subject of the public auction
shall not be extinguished by merger with the title to the property acquired
pursuant to section 39-11.5-501 until the interest of any omitted party has
been affirmed pursuant to subsection (3) of this section or has been terminated
as provided in subsection (2)(a) of this section or by operation of law. An
omitted party, or anyone claiming by, through, or under an omitted party,
cannot extinguish the lien that is subject to the public auction by enforcement
of the lien of the omitted party.
(c) As
used in this section, "interested person" means a lawful holder of a
certificate of purchase, a holder of a certificate of option for a treasurer's
deed or certificate of repurchase issued pursuant to section 39-11.5-401 or
39-11.5-402, a property owner pursuant to section 39-11.5-501, or a person
claiming an interest in the property by, through, or under such lawful holder
or property owner.
(d) An omitted
party, or anyone claiming by, through, or under an omitted party, only has a
remedy to claim overbid money as set forth in this subsection (2). An
interested person is not able to extinguish an omitted party's interest except
as set forth in this subsection (2) or by written waiver or agreement signed by
the omitted party or anyone claiming by, through, or under an omitted party.
(3) If
an interested person files with a treasurer at any time after a public auction
a document affirming an omitted party's interest in a property, subject to the
terms, conditions, and provisions of the recorded instrument from which the
omitted party's interest is derived, or in the case of an omitted party that is
a lessee, subject to the terms and conditions of the lease, whether written or
oral, the interest of the omitted party in the property shall not be affected
by the public auction, and the omitted party shall have no claim to any overbid
money.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 656, § 53, effective June 1.
PART
6
CURATIVE
PROVISIONS
39-11.5-601. Curative provisions.
(1) If
a treasurer fails to comply with any of the notice deadlines set forth in this
article 11.5, unless the public auction has already been withdrawn by the
lawful holder or their attorney, following written notice to the lawful holder
or their attorney, the treasurer may rerecord the application for treasurer's
deed, and the treasurer shall thereafter comply with all the notice deadlines
from the last recording date as set forth on the rerecorded application for
treasurer's deed as though the treasurer's deed process had been commenced on
that date.
(2) In
the event of an error contained in any certificate of option for a treasurer's
deed, certificate of repurchase, treasurer's deed, or other recorded document
prepared by the office of the treasurer, the treasurer may correct such error
by executing and recording a scrivener's error affidavit as set forth in
section 38-35-109 (5).
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 657, § 53, effective June 1.
39-11.5-602. Interaction with other law.
Notwithstanding
any law to the contrary, on or after June 1, 2026, a purchaser, lawful holder,
or treasurer shall follow the procedures established in this article 11.5 and
shall not follow the procedures established in article 11 of this title 39
concerning the issuance of a deed. Notwithstanding any law to the contrary, on
or after June 1, 2026, a treasurer shall not issue a deed pursuant to article
11 of this title 39.
Source:
L. 2026: Entire
article R&RE, (SB 26-144), ch. 135, p. 657, § 53, effective June 1.
ARTICLE
12
Redemption
39-12-101. Limitation of actions for recovery
of land. (Repealed)
39-12-102. Action to recover mining property.
39-12-103. Redemption made - interest.
39-12-104. Redemption of real property of
person under disability.
39-12-105. Certificate of redemption.
39-12-106. Entry by county clerk and recorder
of redemption certificate. (Repealed)
39-12-107. Fee for entering certificate.
(Repealed)
39-12-108. Payment of redemption money.
39-12-109. Payment upon surrender of tax
certificate.
39-12-110. Payment when certificate lost.
39-12-111. Land wrongfully sold - repayment.
39-12-112. Allowance for erroneous
assessments.
39-12-113. Redemption of proportionate
interest.
39-12-101. Limitation of actions for
recovery of land. (Repealed)
Source:
L. 64: R&RE,
p. 743, § 1. C.R.S. 1963: § 137-12-1. L. 85: Entire section
amended, p. 1247, § 33, effective July 1. L. 2026: Entire section
repealed, (SB 26-144), ch. 135, p. 621, § 52, effective June 1.
Editor's
note: Section
55(1) of chapter 135 (SB 26-144), Session Laws of Colorado 2026, provides that
the act repealing this section applies to any fee imposed, assessed, or
collected by a county treasurer on or after June 1, 2026.
Cross
references: For
limitation of actions with respect to persons under disability, see article 81
of title 13.
39-12-102. Action to recover mining
property.
No action
shall be maintained for the recovery of mining or placer claims unless such
action is brought within a period of two years from the commencement of actual
possession obtained under tax deed.
Source:
L. 64: R&RE,
p. 744, § 1. C.R.S. 1963: § 137-12-2.
ANNOTATION
Statutes of limitations
provide sufficient protection for purchasers under tax deeds. The statutes
of limitations, appearing in §§ 38-41-111, 39-12-101, and this section, provide
sufficient protection for the purchasers of property under tax deeds without
further limitations being imposed by the courts. Until the applicable periods
of limitation have expired, tax deeds, even though valid on their face, are
subject to attack for irregularities in the proceedings. Bald Eagle Mining
& Ref. Co. v. Brunton, 165 Colo. 28, 437 P.2d 59 (1968).
Applied in White Cap
Mining Co. v. Resurrection Mining Co., 115 Colo. 396, 174 P.2d 727 (1946)
(decided under former law).
39-12-103. Redemption made - interest.
(1)
Real property for which a tax lien was sold under the provisions of article 11
of this title as a result of delinquent taxes may be redeemed by the owner
thereof or his agent, assignee, or attorney, or by any person having a legal or
equitable claim therein, or by a holder of a tax sale certificate; except that
such holder may redeem such real property from any sale of a tax lien thereof
made subsequent to the time of the issuance of the tax sale certificate upon
which he is relying, and the amount paid for the redemption of the subsequent
certificate of purchase shall be endorsed as subsequent taxes paid on the
certificate upon which he is relying.
(2) An
undivided interest may be redeemed upon payment of a ratable share of the sum
required to redeem the whole even though a tax lien for the whole has been
sold. In case a tax lien on any tract of land sold for delinquent taxes under
the provisions of article 11 of this title belongs to two or more separate and
distinct parties in severalty, the treasurer, when satisfied of the fact and
upon application of any one of the parties or his agent, assignee, or attorney
and upon payment of the proper proportional amount, shall issue a certificate
of redemption for such party's interest in said land.
(3) The
redemption may be made at any time before the execution of a treasurer's deed
to the purchaser or his heirs or assigns upon payment to the treasurer, to be
held by him subject to the order of the purchaser, of the amount of taxes,
delinquent interest, and costs for which the tax lien on the property was sold,
with redemption interest thereon from the date of sale at the rate which is
determined as provided in this subsection (3), together with the amount of all
taxes accruing on such real property after the sale, paid by the purchaser and
endorsed on his certificate of purchase, with redemption interest at the rate
which is determined as provided in this subsection (3) on such taxes so
endorsed on the certificate of purchase. Any payment under this section shall
be deemed received by the treasurer on the date that it is actually received in
the treasurer's office. The annual rate of redemption interest shall be nine
percentage points above the discount rate, which discount rate shall be the rate
of interest a commercial bank pays to the federal reserve bank of Kansas City
using a government bond or other eligible paper as security, and shall be
rounded to the nearest full percent. The commissioner of banking shall
establish the annual rate of redemption interest based upon the computation
specified immediately above. Such annual rate of redemption interest shall be
so established as of September 1, 1981, to become effective October 1, 1981.
Thereafter, on September 1 of each year, the annual rate of redemption interest
shall be established in the same manner, to become effective on October 1 of
the same year.
(4) If
subsequent taxes are paid before the time when they would become delinquent,
interest shall be computed only from the time of their delinquency. Such taxes
shall bear interest at the annual rate set forth in subsection (3) of this
section, and no more, from the time when the purchaser becomes entitled to a
deed up to the time of issuance of such deed.
(5) All
statutory fees paid by the purchaser in connection with such certificate shall
bear the same rate of interest as the original amount for which the tax lien on
the property was sold, the same to be prorated among the several tracts
described in said certificates.
(6) In
computing the amount of interest due, portions of months shall be counted as
whole months.
Source:
L. 64: R&RE,
p. 744, § 1. C.R.S. 1963: § 137-12-3. L. 69: p. 1126, § 2. L.
71: p. 330, § 12. L. 79: (3) amended, p. 1421, § 3, effective
January 1, 1980. L. 81: (3) amended, p. 1861, § 1, effective September
1. L. 85: (1) to (5) amended, p. 1247, § 34, effective July 1. L. 89:
(4) amended, p. 1467, § 34, effective June 7. L. 92: (3) amended, p.
2233, § 24, effective April 9.
ANNOTATION
Law reviews. For
article, "Delinquent Oil and Gas Ad Valorem Taxes: Protecting Property
Interests", see 16 Colo. Law. 798 (1987). For article, "Keeping the
Surplus? Examining Colorado's Real Property Tax Lien System in Light of Tyler
v. Hennepin County", see 53 Colo. Law. 28 (Jan.-Feb. 2024).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
The policy underlying the
right of redemption is the general policy of the law that no man shall
forfeit his estate because of his inability to meet engagements on the day
prescribed by law for their payment. Because the law favors redemption,
redemption statutes are construed liberally to afford property owners ample
opportunity to redeem. Dove Valley Bus. Park v. County Comm'rs, 945 P.2d 395
(Colo. 1997).
In Colorado, delinquent
taxpayers have no constitutional right to redemption. Instead, redemption
is a statutory privilege created by the general assembly, which may be
exercised only as provided by statute. Dove Valley Bus. Park v. County Comm'rs,
945 P.2d 395 (Colo. 1997).
Section is to be liberally
construed in favor of the redemptioner. Bean v. Westwood, 101 Colo. 288, 73
P.2d 386 (1937).
Attempted redemption by
person having no interest in the property is ineffectual and may be set
aside by the holder of a valid certificate of purchase obtained at a tax sale.
Saunders v. Bankston, 31 Colo. App. 551, 506 P.2d 1253 (1972).
One having lease and option
to purchase may redeem. One having a lease and an option to purchase land,
having exercised his option and received a deed from the reputed owner, thereby
acquires an equitable claim to the property under which he has the right to
redeem it from a tax sale. Bean v. Westwood, 101 Colo. 288, 73 P.2d 386 (1937).
Assignee with security
interest in property entitled to redeem. An assignee of a note, which note
carries with it a security interest in real property, has a right to redeem and
has an interest in the property. Swofford v. Colo. Nat'l Bank, 628 P.2d 184
(Colo. App. 1981).
One with a lien interest in
land may redeem from tax sale. Miller v. First Nat'l Bank, 164 Colo. 449,
435 P.2d 899 (1968).
Lienor's acquisition of
title cannot cut off other lienor. Equity will not permit one lienor to
acquire a tax title while cutting off other lienor but will treat his purchase
of the tax title as a payment of the taxes by a redemption, thereby giving him
a preferred lien to the extent paid out to redeem. Miller v. First Nat'l Bank,
164 Colo. 449, 435 P.2d 899 (1968).
Amount payable on redemption
not purchase price, but amount of tax involved. Where, at a tax sale, a
certificate of purchase is issued to the county which thereafter is sold for a
price fixed by a resolution of the board of county commissioners, the amount
payable on redemption is not the sum paid by the purchaser as established by
the board but the amount of the tax involved, which sums may be very different.
Tarabino Real Estate Co. v. Dunlavy, 105 Colo. 523, 99 P.2d 926 (1940).
Redemption interest is a
statutorily determined penalty exacted from the taxpayer for the privilege of
redemption. Dove Valley Bus. Park v. County Comm'rs, 945 P.2d 395 (Colo.
1997).
The plain language of
subsection (3), which explicitly warns a taxpayer that redemption interest will
accrue based on the amount of taxes paid by the purchaser, did not provide
the taxpayers with any basis to conclude that if they failed to pay their
property taxes in a timely manner, and later redeemed their property, that the
redemption interest on the amount paid by the purchaser would not apply to
them. Dove Valley Bus. Park v. County Comm'rs, 945 P.2d 395 (Colo. 1997).
Colorado scheme does not
guarantee predeprivation relief; however, due process requirements were met
since the taxpayers received their "full refund" - the over assessed
tax plus refund interest - even though redemption interest, which due process
does not extend to, was not refunded. Dove Valley Bus. Park v. County Comm'rs,
945 P.2d 395 (Colo. 1997).
County was not unjustly
enriched by the payment of redemption interest calculated on the basis of
an assessment determined to be excessive at a date after the county conducted
the tax lien sale. Dove Valley Bus. Park v. County Comm'rs, 945 P.2d 395 (Colo.
1997).
County treasurer acts in a
quasi-judicial capacity in matters concerning redemption of property from
tax sales. Johnson v. Dunkel, 132 Colo. 383, 288 P.2d 343 (1955).
Treasurer receives
redemption money as agent of purchaser. Subsection (3) provides that the
redemption money may be paid to the treasurer, but that officer holds it
subject to the order of the purchaser; therefore, he receives it not as the
agent of the state or county but as the agent of the purchaser. Statton v.
People ex rel. Burr, 18 Colo. App. 85, 70 P. 157 (1902).
No mandamus to release land
except upon payment of entire sale amount. Where land covered by a deed on
trust is sold for taxes, part of which were assessed against the land and part
of which were assessed as the personal tax of the owner, in a proper
proceeding, the beneficiary of the trust deed is entitled to a release as to
his interest in the land from the tax sale by payment only of the amount
properly chargeable against the land, but mandamus will not lie against the
county treasurer to compel him to release the land from the tax sale except
upon payment of the entire amount for which it was sold, with interest and
penalties. The proper remedy would be a proceeding in equity against the holder
of the certificate of purchase. Statton v. People ex rel. Burr, 18 Colo. App.
85, 70 P. 157 (1902).
Action to set aside voidable
tax deed not within section. In an action to set aside a voidable tax deed,
interest on taxes paid on the land by the holder on the deed is not computed
according to this section, but according to § 39-12-101. Phillips v. City &
County of Denver, 115 Colo. 532, 175 P.2d 805 (1946).
Owner of severed mineral
rights underlying property may not redeem. Although both common law and the
deed in question gave the owner of severed mineral interests the right to use a
reasonable amount of the surface estate for mineral development, such right was
not a "legal or equitable claim" within the meaning of subsection
(1). To hold otherwise would allow the mineral owner to augment his ownership,
which is not a right recognized as part of the redemption process. Notch Mtn.
Corp. v. Elliott, 898 P.2d 550 (Colo. 1995).
The right to bring an equitable
action cannot be considered synonymous with an equitable claim in the property.
Notch Mtn. Corp. v. Elliott, 898 P.2d 550 (Colo. 1995).
Redemption does not transfer
title to the redemptioner, but rather prevents a transfer of title by tax deed.
Notch Mtn. Corp. v. Elliott, 898 P.2d 550 (Colo. 1995).
Title to a severed mineral
interest is not conveyed under a tax deed issued for delinquent taxes levied
against the surface estate. Notch Mtn. Corp. v. Elliott, 898 P.2d 550 (Colo.
1995).
Limited partner does not
have a right to redeem real property owned by the limited partnership
because limited partner has no legal or equitable interest in the real
property. Winter Park Devil's Thumb Inv. Co. v. BMS P'ship, 926 P.2d 1253
(Colo. 1996).
Right of redemption
distinguished from right of co-owner to pay delinquent taxes. Unlike the
right of an interest holder to redeem, the right granted to certain co-owners
to pay delinquent taxes under § 38-41-110 does not result in issuance of a
redemption certificate or acquisition of an interest in the delinquent
co-owner's estate. Rather, the paying co-owner is granted the right to
foreclose the lien for unpaid taxes. Notch Mtn. Corp. v. Elliott, 898 P.2d 550
(Colo. 1995).
Applied in Harrison v.
City & County of Denver, 102 Colo. 98, 76 P.2d 1110 (1938); French v.
Golston, 105 Colo. 578, 100 P.2d 581 (1940); Eshe v. Clough, 116 Colo. 266, 179
P.2d 979 (1947); Boyle v. Culp, 159 Colo. 423, 412 P.2d 543 (1966).
39-12-104. Redemption of real property
of person under disability.
(1)
When the owner of real property for which a tax deed was issued under the
provisions of article 11 of this title as a result of delinquent taxes is under
legal disability at the time of execution and delivery of a tax deed therefor,
such person shall have the right to make redemption of such property at any
time within nine years from the date of the recording of such tax deed. In the
event that the disability of such person is removed or ceases within such
nine-year period, such redemption must be asserted and take place within a
period of not more than two years after the removal or cessation of such legal
disability. All redemptions under this section shall take place within nine
years of the recording of the tax deed, irrespective of the time that such
disability was removed or ceased.
(2) In
order to make such redemption, such owner, or some person in his behalf, shall
pay to the treasurer the sum for which the tax lien on such real property was
sold, and the cost of the tax deed and the recording of the same, with interest
thereon from the date of such sale at the rate of fifteen percent per annum,
and all other taxes, costs, and charges which remain unpaid on such real
property at the time of making such redemption, levied or accrued thereon
subsequent to the assessment date of the taxes for which the tax lien was sold,
and all other taxes levied subsequent to the date of such sale, which have been
paid by the person to whom the tax lien on said real property was sold, or by
any other person claiming under him, with interest thereon at the rate of
fifteen percent per annum from the date of such payment, insofar as such
payments can be ascertained from the books and records in the office of such
treasurer. If the person to whom the tax lien on such real property was sold,
or any other person claiming under him, has made improvements, the person
redeeming said real property shall pay the then present value of such
improvements. The improvements shall be appraised by three disinterested
persons appointed by the board of county commissioners. For all the money so
paid, the treasurer shall give a certificate of redemption to the persons
making such payment. From the time of making the redemption, the deed given
upon the same shall be void as against such owner. In the event a redemption is
not made within the periods of time provided for in this section, all rights of
redemption shall cease and be forever barred as to all persons.
Source:
L. 64: R&RE,
p. 745, § 1. C.R.S. 1963: § 137-12-4. L. 85: Entire section
amended, p. 1248, § 35, effective July 1.
ANNOTATION
Law reviews. For
article, "Curative Statutes of Colorado Respecting Titles to Real
Estate", see 26 Dicta 321 (1949). For article, "Summary of Denver
Bar-Sponsored Bills Passed by General Assembly", see 28 Dicta 173 (1951).
For article, "Due Process in Involuntary Civil Commitment and Incompetency
Adjudication Proceedings: Where Does Colorado Stand?", see 46 Den. L.J.
516 (1969).
For purposes of subsection
(1), an "owner of real property" who "is under legal
disability" includes an individual who a court has determined is
incapacitated and who does not have a legal guardian who can advocate on the
individual's behalf. Actarus, LLC v. Johnson, 2019 COA 122, 451 P.3d 1270.
For purposes of subsection (1),
the phrase "under legal disability" encompasses an individual who,
because of a mental impairment, lacks the capacity to manage their affairs and
adequately protect their interests in an underlying tax sale proceeding. An
individual may have a legal disability even if the individual is not a minor,
insane, or suffering from an intellectual and developmental disability within
the meaning of § 25.5-10-202 (26)(a). LT Income, LLC v. Purnell, 2025 COA 74,
578 P.3d 843.
The right to redemption
under subsection (1) does not require that there be a prior adjudication of
the property owner's legal disability or a court proceeding underway to
determine their legal disability, nor does it require that the determination of
their legal disability occur before the treasurer's deed is executed and
delivered. LT Income, LLC v. Purnell, 2025 COA 74, 578 P.3d 843.
The recordation of a validly
issued treasurer's deed does not extinguish a qualifying homeowner's right to
redeem the property, but a homeowner's legal disability does not prevent
the placement of a tax lien, the sale of that lien, or the subsequent issuance
of a treasurer's deed. Actarus, LLC v. Johnson, 2019 COA 122, 451 P.3d 1270; LT
Income, LLC v. Purnell, 2025 COA 74, 578 P.3d 843.
39-12-105. Certificate of redemption.
(1)
Upon application of any party to redeem any real property for which a tax lien
was sold or a tax deed was issued under the provisions of article 11 of this
title, and being satisfied that such party has a right to redeem the same, and
upon the payment of the proper amount, the treasurer shall issue to such party
a certificate of redemption, describing the tract redeemed as in the
certificate of sale and giving the date of redemption, the amount paid, and by
whom redeemed and shall make the proper entries in the book of sales in the
treasurer's office.
(2) For
each certificate so delivered, the treasurer shall be entitled to a fee as
provided in section 30-1-102, C.R.S.
Source:
L. 64: R&RE,
p. 746, § 1. C.R.S. 1963: § 137-12-5. L. 69: p. 1123, § 4. L.
71: p. 330, § 13. L. 75: (2) amended, p. 1480, § 7, effective July
1. L. 85: (1) amended, p. 1249, § 36, effective July 1. L. 96:
(1) amended, p. 1393, § 15, effective July 1.
39-12-106. Entry by county clerk and
recorder of redemption certificate. (Repealed)
Source:
L. 64: R&RE,
p. 746, § 1. C.R.S. 1963: § 137-12-6. L. 85: Entire section
amended, p. 1249, § 37, effective July 1. L. 96: Entire section
repealed, p. 1395, § 16, effective July 1.
39-12-107. Fee for entering
certificate. (Repealed)
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-7. L. 83: Entire section
amended, p. 1231, § 21, effective July 1. L. 96: Entire section
repealed, p. 1395, § 17, effective July 1.
39-12-108. Payment of redemption money.
All moneys
received by the treasurer for the redemption of lands under the provisions of
section 39-12-104 shall be paid over to the person to whom the tax lien on such
land was sold or a tax deed was issued, or those claiming under him, on his
deliverance to the treasurer, for the use of the person redeeming the same, a
quitclaim deed of all the title to such land acquired under the sale, duly
executed and acknowledged.
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-8. L. 85: Entire section
amended, p. 1250, § 38, effective July 1.
39-12-109. Payment upon surrender of
tax certificate.
On demand
of any person entitled to redemption money in his hands, the treasurer shall
pay the same to any such person, upon his surrendering to him the tax certificate
to such land or lot as has been redeemed. If only a portion of the land or lots
described in the tax certificate has been redeemed, the treasurer shall endorse
on such certificate the portion redeemed and the amount of money paid to each
person and shall take a receipt therefor.
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-9.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Section is applicable to
property sold for special municipal improvement taxes. House v. Bd. of
Comm'rs, 89 Colo. 196, 300 P. 998 (1931).
County treasurer is not
entitled to a commission on money paid into his hands for the redemption of
land sold to individuals for delinquent taxes nor to any fee for entering on
his books an assignment of a certificate of purchase. Mitchell v. Wheeler, 20
Colo. App. 159, 77 P. 361 (1904).
39-12-110. Payment when certificate
lost.
If there
is a loss or wrongful detention of such certificate and the land therein
described has been redeemed, the owner thereof may exhibit to the treasurer
evidence of such loss or detention, and, upon his making the same to appear
satisfactory to the treasurer and upon his executing a bond with sufficient
surety that he will refund such redemption money, with twenty-five percent per
annum interest thereon, if any person thereafter shows his right thereto, the
treasurer shall pay such redemption money to the person so executing such bond.
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-10.
39-12-111. Land wrongfully sold -
repayment.
(1)
When, by mistake or error of the treasurer, county clerk and recorder, or
assessor or from double assessment, a tax lien has been sold on land upon which
no tax was due at the time, the county shall reimburse the purchaser in the
amount paid by him in connection with the purchase of the tax lien on such
land, together with interest from the date of purchase at the rate which is
determined as provided in this section. Reimbursement shall be made from the
various funds to which the tax was originally distributed; except that interest
shall be paid from the county general fund. The treasurer, county clerk and
recorder, or assessor, as the case may be, and his sureties on his official
bond shall be liable to the county for such amounts reimbursed as a result of
sales made only through willful misconduct.
(2) (a)
The annual rate of interest shall be two percentage points above the discount
rate, which discount rate shall be the rate of interest a commercial bank pays
to the federal reserve bank of Kansas City using a government bond or other
eligible paper as security, and shall be rounded to the nearest full percent.
(b)
Notwithstanding any other provision of this subsection (2), the rate of
interest shall be no lower than eight percent per annum compounded annually.
(3) The
commissioner of banking shall establish the annual rate of interest based upon
the computation specified in subsection (2) of this section. Such annual rate
of interest shall be so established as of September 1, 1981, to become
effective October 1, 1981. Thereafter, on September 1 of each year, the annual
rate of interest shall be established in the same manner, to become effective
on October 1 of the same year.
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-11. L. 67: p. 951, § 24. L.
69: p. 1128, § 1. L. 81: Entire section amended, p. 1862, § 2,
effective September 1. L. 85: (1) amended, p. 1250, § 39, effective July
1. L. 88: (2) amended, p. 1294, § 28, effective May 23.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
"Assessor"
defined. The word "assessor" in subsection (1) means the
assessing power. Bd. of Comm'rs v. Floaten, 66 Colo. 540, 181 P. 122 (1919).
Nothing in this article
limits its intendment to general taxes; the word "tax" may
include a special improvement tax as well as a general tax. House v. Bd. of
Comm'rs, 89 Colo. 196, 300 P. 998 (1931).
Purchaser at tax sale buys
at his peril in absence of special statute. Bd. of County Comm'rs v.
Lavington, 91 Colo. 252, 14 P.2d 493 (1932).
Counties liable where
property not subject to taxation. Counties are not liable for void sales
except where the property was not subject to taxation, or, by reason of a
double assessment, no tax was due. Elder v. Bd. of County Comm'rs, 33 Colo.
475, 81 P. 244 (1905).
Where property erroneously
sold for special municipal improvement tax. Where the property of a railway
company is erroneously sold for a special municipal improvement tax, the county
is held liable for a return of the purchase price, notwithstanding the fact
that the money received has been turned over to the municipal corporation.
House v. Bd. of Comm'rs, 89 Colo. 196, 300 P. 998 (1931).
Assignee of purchaser may
sue county. The assignment of a tax sale certificate carries with it and
vests in the assignee all the rights of the original purchaser. Where the
original purchaser had a right of action against the county to recover the
purchase money, the same right vests in the assignee without a specific
assignment of the right of action. Bd. of Comm'rs v. Whelen, 28 Colo. 435, 65
P. 38 (1901).
Applied in Larimer
County v. Nat'l State Bank, 11 Colo. 564, 19 P. 537 (1888); Richardson v. City
of Denver, 17 Colo. 398, 30 P. 333 (1892); Bd. of Comm'rs v. Yingling, 14 Colo.
App. 449, 60 P. 582 (1900).
39-12-112. Allowance for erroneous
assessments.
The state
treasurer shall allow each treasurer to take credit for the amount of state tax
that may have been refunded to the taxpayer as double or erroneous assessments
or refunded to the purchaser of a tax lien on real estate which lien was
erroneously sold.
Source:
L. 64: R&RE,
p. 747, § 1. C.R.S. 1963: § 137-12-12. L. 85: Entire section
amended, p. 1250, § 40, effective July 1.
39-12-113. Redemption of proportionate
interest.
(1) Any
person who has or claims an interest in or a lien upon all or any part of any
undivided or divided estate or interest in any piece or parcel of land or lot
for which a tax lien was sold pursuant to article 11 of this title may redeem
such undivided or divided estate or interest by paying to the treasurer his
proportionate part of the amount required to redeem the whole. In such case the
treasurer shall issue to such party a certificate of redemption for his
interest in such land or lot, as provided by law.
(2) In
the event that the treasurer cannot definitely ascertain the amount required to
redeem the portion sought to be redeemed, he shall request the assessor to
determine the valuation for assessment on such portion sought to be redeemed as
of the original assessment date for the tax upon which the sale of the tax lien
was based. Such assessor shall furnish such valuation for assessment to the
treasurer forthwith. The treasurer shall thereupon ascertain such proportionate
redemption amount as that amount which bears the same proportion to the amount
required to redeem the entire piece or parcel of land or lot for which a tax
lien was sold as such valuation for assessment so furnished bears to the
original valuation for assessment of the entire piece or parcel of land or lot
for which a tax lien was sold.
Source:
L. 64: R&RE,
p. 748, § 1. C.R.S. 1963: § 137-12-13. L. 85: Entire section
amended, p. 1251, § 41, effective July 1.
ANNOTATION
Annotator's note. The
following annotations include cases decided under this section as it existed
prior to its 1964 repeal and reenactment.
Tenant in common may pay tax
upon share of land. A tenant in common of lands may, under subsection (1),
pay the tax upon his share thereof, though the tax is assessed upon the whole
estate, and he may redeem his interest from a previous tax sale of the whole.
Hallett v. Alexander, 50 Colo. 37, 114 P. 490 (1911).
A tenant need not discharge
tax upon cotenant's interest. A tenant in common is under no necessity to
discharge the tax upon the interest of his cotenant and will not be allowed a
lien thereon for such payment made without the request of the cotenant. Hallett
v. Alexander, 50 Colo. 37, 114 P. 490 (1911).
Section inapplicable to
undivided interest separately assessed and sold. This section has no
applicability where an undivided interest has been separately listed, assessed,
and sold; to effectuate a redemption thereof, the owner of the undivided
interest is obliged to pay the entire redemption money upon that interest.
Garbanati v. Patterson, 37 Colo. 230, 85 P. 845 (1906).
Conveyancing
and Evidence of Title
ARTICLE
13
Documentary
Fee on Conveyances of Real Property
39-13-101. Legislative declaration.
39-13-101.5. Definitions.
39-13-102. Documentary fee imposed - amount -
to whom payable - legislative declaration - definition.
39-13-103. Evidence of payment of fee.
39-13-104. Exemptions.
39-13-105. No deed recorded unless documentary
fee paid.
39-13-106. Unlawful acts - penalty.
39-13-107. Assessor to compile continuing
record.
39-13-108. Disposition of fees.
39-13-101. Legislative declaration.
(1) The
general assembly declares that, in enacting laws relating to the general
property tax, it has provided that certain property in each county of the state
shall be appraised and the actual value thereof determined by the assessor and
that one of the several factors to be considered by him in determining the
actual value of any property shall be "comparison with other properties of
known or recognized value".
(2) It
further declares that such comparison may be best effected if there is
available to the assessor a continuing record of the consideration paid or to
be paid by purchasers of real property evidenced, prior to recording, on the
document conveying title to such property and recorded in the office of the
county clerk and recorder in the several counties of the state in the manner
provided by law and that this article is enacted to provide a means of
developing such continuing record and making such record available for use
primarily by assessors.
Source:
L. 67: p. 942, §
1. C.R.S. 1963: § 137-13-1.
39-13-101.5. Definitions.
As used in
this article 13, unless the context otherwise requires:
(1)
"Documentary fee" means the fee imposed pursuant to section 39-13-102
(1).
Source:
L. 2025: Entire
section added, (SB 25-275), ch. 377, p. 2103, § 313, effective August 6.
39-13-102. Documentary fee imposed -
amount - to whom payable - legislative declaration - definition.
(1)
There is imposed and shall be paid, by every person offering for recording in
the office of the county clerk and recorder any deed or instrument in writing
wherein or whereby title to real property situated in this state is granted or
conveyed, a documentary fee measured by the consideration paid or to be paid
for such grant or conveyance, which documentary fee shall be in addition to any
other fee fixed by law for the recording of such deed or instrument in writing.
(2) The
amount of documentary fee payable in each case shall be as follows:
(a)
When there is no consideration or when the total consideration paid by the
purchaser, inclusive of the amount of any lien or encumbrance against the real
property granted or conveyed and all charges and expenses required to be paid
for the making of such grant or conveyance is five hundred dollars or less, no
documentary fee shall be payable.
(b)
When the total consideration paid by the purchaser, inclusive of the amount of
any lien or encumbrance against the real property granted or conveyed and all
charges and expenses required to be paid for the making of such grant or
conveyance exceeds five hundred dollars, the documentary fee payable shall be
computed at the rate of one cent for each one hundred dollars, or major
fraction thereof, of such consideration.
(3) All
documentary fees shall be payable to and collected by the county clerk and
recorder.
(4) In
those cases in which real property located in two or more counties is granted
or conveyed in a single transaction, each county clerk and recorder shall
collect a portion of the total documentary fee referred to in subsection (2) of
this section in the same ratio that the consideration fairly attributable to
the part of such property located in his county bears to the total
consideration. The allocation of the total consideration between counties is to
be made by the person offering such deed or instrument in writing for
recording.
(5) (a)
For the purpose of determining the documentary fee in accordance with
subsection (2) of this section, the amount of consideration paid for the grant
or conveyance of residential real property, inclusive of liens, charges, and
expenses, is the amount listed on the grant or conveyance document; except
that, if there is no consideration amount listed on the grant or conveyance
document or the amount listed is five hundred dollars or less, and there is a
related declaration filed in accordance with section 39-14-102, then the amount
of consideration paid is the total sales price listed on the declaration.
(b) In
determining the amount of consideration paid for the grant or conveyance of
commercial or industrial real property, inclusive of liens, charges, and
expenses, the total amount of the sales price to the purchaser shall be deemed
to be paid for the grant or conveyance of real property unless evidence of the
separate consideration paid for personal property is submitted as shown on the
purchaser's use tax return as filed with the department of revenue or unless
evidence of such separate consideration is shown on the declaration filed
pursuant to the provisions of section 39-14-102.
(c) Any
such evidence submitted under paragraph (a) or (b) of this subsection (5) shall
not be recorded or filed by the county clerk and recorder and shall not be
subject to public inspection but shall be sent to the county assessor. Such
evidence shall be used by the assessor as required by section 39-13-107 but
shall be kept confidential and shall not be subject to public inspection.
(d)
Solely for the purpose of computing the documentary fee, the property conveyed
by a deed or other instrument will be regarded as residential unless the deed
or other instrument includes a conspicuous statement or notation that the
property is not to be regarded as residential. This provision does not
authorize the alteration of a deed or other instrument after it has been
executed.
(6) (a)
A county may designate a portion of the money collected from the documentary
fee, other than the portion that is used to offset administrative costs related
to recording and maintaining real property deeds and instruments, to be
transferred to the county government or a housing authority for the purpose of
developing, preserving, or acquiring affordable housing that:
(I) Is
within the jurisdiction of the county government or housing authority;
(II) Is
aligned with demonstrated community needs; and
(III)
Will be available to individuals experiencing homelessness.
(b) The
general assembly finds and declares that:
(I) As
the volume of real estate transactions has increased significantly, real estate
prices and costs have also increased, impacting the availability and
affordability of housing in Colorado; and
(II)
Local governments should be permitted to use the documentary fee to offset the
administrative costs associated with recording and maintaining real property
deeds and instruments and the costs of building and maintaining affordable
housing.
Source:
L. 67: p. 942, §
1. C.R.S. 1963: § 137-13-2. L. 68: p. 33, § 4. L. 84: (5)
added, p. 1004, § 1, effective July 1; (2)(a) and (2)(b) amended, p. 1004, § 1,
effective January 1, 1985. L. 89: (5)(a) and (5)(b) amended, p. 1462, §
21, effective July 1. L. 2016: (5)(a) amended and (5)(d) added, (HB
16-1145), ch. 108, p. 310, § 1, effective April 15. L. 2025: (1)
amended, (SB 25-275), ch. 377, p. 2104, § 314, effective August 6. L. 2026:
(6) added, (HB 26-1202), ch. 300, p. 1696, § 3, effective August 12.
39-13-103. Evidence of payment of fee.
Each
county clerk and recorder shall evidence payment of the documentary fee imposed
in this article in the recording annotation or by imprinting, typing, stamping,
or writing in ink on the margin or other blank portion of every document to
which such fee applies the words "State Documentary Fee", the amount
of documentary fee paid, and the date upon which paid, which impression or
notation shall be made on such document before it is recorded.
Source:
L. 67: p. 943, §
1. C.R.S. 1963: § 137-13-3. L. 68: p. 32, § 1. L. 2014:
Entire section amended, (HB 14-1073), ch. 30, p. 178, § 10, effective July 1.
39-13-104. Exemptions.
(1) The
documentary fee imposed in this article shall not apply to:
(a) Any
deed wherein the United States or any agency or instrumentality thereof or the
state of Colorado or any political subdivision thereof is either the grantor or
the grantee; except that, at the time such entity offers a deed for recording
in the office of the county clerk and recorder, it shall file an affidavit with
the clerk stating the consideration paid or to be paid for such grant or
conveyance. If the entity imprints, types, stamps, or writes in ink on the
margin or other blank portion of the document the consideration paid or to be
paid for such grant or conveyance, it shall be deemed to satisfy the
requirements of an affidavit.
(b) Any
deed granting or conveying title to real property in consequence of a gift of
such property;
(c) Any
public trustee's deed executed pursuant to the provisions of section 38-38-501,
C.R.S.;
(d) Any
treasurer's deed executed in accordance with the provisions of article 11 of
this title;
(e) Any
sheriff's deed;
(f) Any
instrument which confirms or corrects a deed previously recorded;
(g) Any
deed granting or conveying title to cemetery lots;
(h) Any
executory contract for the sale of real property of less than three years'
duration under which the vendee is entitled to or does take possession thereof
without acquiring title thereto nor to any assignment or cancellation of any
such contract;
(i) Any
lease of real property or assignment or transfer of an interest in any such
lease;
(j) Any
document given to secure payment of an indebtedness;
(k) Any
document granting or conveying a future interest in real property;
(l) Any
decree or order of a court of record determining or vesting title;
(m) Any
document necessary to transfer title to property as a result of the death of an
owner thereof;
(n)
Repealed.
(o) Any
rights-of-way and easements.
(2)
Exemption from payment of the documentary fee imposed in this article must be
claimed at the time a deed or instrument is offered for recording.
Source:
L. 67: p. 943, §
1. C.R.S. 1963: § 137-13-4. L. 68: p. 32, § 2. L. 85:
(1)(n) repealed, p. 1214, § 12, effective May 9. L. 89: (1)(a) amended,
p. 1496, § 1, effective March 15. L. 91: (1)(c) amended, p. 1925, § 56,
effective June 1.
39-13-105. No deed recorded unless
documentary fee paid.
No deed or
instrument in writing to which a documentary fee applies shall be recorded
until and unless the documentary fee payable thereon has been paid and evidence
of its payment has been imprinted, typed, stamped, or written in ink thereon as
provided in section 39-13-103. Any county clerk and recorder who willfully and
knowingly records any document to which a documentary fee applies without
having first collected such fee and evidenced payment thereof as provided in
this article is guilty of a misdemeanor and, upon conviction thereof, shall be
punished by a fine of fifty dollars.
Source:
L. 67: p. 944, §
1. C.R.S. 1963: § 137-13-5. L. 68: p. 32, § 3.
39-13-106. Unlawful acts - penalty.
(1) It
is unlawful for any person to commit the following acts:
(a) To
fail or refuse to pay the documentary fee imposed in this article when such
payment is required;
(b) To
willfully and knowingly recite to the county clerk and recorder a consideration
greater or less than the actual consideration referred to in section 39-13-102
(2)(a) and (2)(b) in connection with the granting or conveying of title to real
property by any deed or instrument in writing to which the documentary fee
applies.
(2) Any
person who commits either of the acts set forth in subsection (1) of this
section commits an unclassified misdemeanor and, upon conviction thereof, shall
be punished by a fine of not less than fifty dollars nor more than five hundred
dollars.
Source:
L. 67: p. 944, §
1. C.R.S. 1963: § 137-13-6. L. 2021: (2) amended, (SB 21-271),
ch. 462, p. 3295, § 692, effective March 1, 2022.
39-13-107. Assessor to compile
continuing record.
It is the
duty of each assessor to examine at least once each year all documents recorded
in his county upon which a documentary fee has been paid and to determine in
each case the consideration upon which such fee was computed and paid. He shall
compile and maintain in his office a continuing record of all such
considerations to assist him in appraising property and determining the actual
value thereof as required by the provisions of section 39-1-103 (5).
Source:
L. 67: p. 944, §
1. C.R.S. 1963: § 137-13-7.
39-13-108. Disposition of fees.
All
documentary fees collected by the county clerk and recorder shall be deposited
with the treasurer at least once each month and credited by him in the manner
prescribed by law.
Source:
L. 67: p. 944, §
1. C.R.S. 1963: § 137-13-8.
ARTICLE
14
Real
Property Transfer Information
39-14-101. Definitions.
39-14-102. Filing of declaration - information
available to county assessor.
39-14-103. Manufactured home declaration -
information available to county assessor.
39-14-101. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Authorized agent" shall have the same meaning as set forth in
section 38-29-102 (1), C.R.S.
(1.5)
"Conveyance" means any transfer of a real property interest or
manufactured home for some consideration in money or money's worth.
(2)
"Conveyance document" means any document upon which a documentary fee
is imposed pursuant to section 39-13-102.
(3)
"Declaration" means a form prescribed by the property tax
administrator, and approved by the state board of equalization after review by
the advisory committee to the property tax administrator as provided in section
39-9-103 (10), that contains information to assist the assessor in determining
the value of real property and manufactured homes required to be furnished
under this article pursuant to section 39-14-102 or 39-14-103.
(4)
"Manufactured home" shall have the same meaning as set forth in
section 39-1-102 (7.8).
(5)
"Manufactured home title application" means an application for a new
certificate of title in accordance with the provisions of part 1 of article 29
of title 38, C.R.S., that is made after a sale or transfer described in section
38-29-112 (1) or 38-29-114 (1), C.R.S.
(6)
"Verification of application form" shall have the same meaning as set
forth in section 38-29-102 (13), C.R.S.
Source:
L. 89: Entire
article added, p. 1460, § 20, effective July 1. L. 96: (3) amended, p.
949, § 3, effective July 1. L. 2008: (1) and (3) amended and (1.5), (4),
(5), and (6) added, p. 452, § 11, effective July 1. L. 2009: (1.5) and
(4) amended, (SB 09-040), ch. 9, p. 71, § 13, effective July 1.
39-14-102. Filing of declaration -
information available to county assessor.
(1) (a)
On or after July 1, 1989, any conveyance document presented for recordation
shall be accompanied by a declaration prescribed by the property tax
administrator. Said declaration shall be completed and signed by either the
grantor or the grantee.
(b) (I)
If the declaration required in this subsection (1) does not accompany a
conveyance document at the time such conveyance document is presented for
recordation, the county clerk and recorder shall promptly record the conveyance
document and shall notify the county assessor that such conveyance document was
not accompanied by such declaration.
(II)
Upon receiving such notice from the county clerk and recorder pursuant to
subparagraph (I) of this paragraph (b), the county assessor shall send written
notice to the grantee specified in such conveyance document that the grantee
shall provide the declaration to the county assessor within thirty days of the
date the notice was mailed. If the grantee fails to provide such declaration
within thirty days after the date the notice was mailed, the county assessor
may impose upon such grantee a penalty of twenty-five dollars or a penalty
equal to twenty-five one-thousandths of one percent of the sale price of the
real property transferred pursuant to the conveyance document, whichever amount
is greater. In each subsequent year in which the grantee fails to file the
declaration, the assessor may impose said specified penalty unless the real
property has been subsequently conveyed. Any penalty imposed pursuant to this
subparagraph (II) shall be a fee of the office of the county assessor.
(III)
Any unpaid penalties which were imposed pursuant to subparagraph (II) of this
paragraph (b) shall be certified to the county treasurer by January 1 of each
year and shall be included in the statement sent to the grantee pursuant to
section 39-10-103 for property taxes levied against the real property.
(c) The
county clerk and recorder shall not record or file any declaration made
pursuant to the provisions of this section; however, the county clerk and
recorder shall enter upon such declaration the date of recordation and
reception number of the conveyance document presented for recordation. The
county clerk and recorder shall transmit any declaration made pursuant to the
provisions of this section to the county assessor. The county assessor shall
make any declaration made pursuant to the provisions of this section available
for inspection by any taxpayer who was the grantee specified in the conveyance
document which such declaration accompanied or who filed such declaration, the
person conducting any valuation for assessment study pursuant to section
39-1-104 (16) and his employees, and the property tax administrator and his
employees.
(2) No
declaration made pursuant to the provisions of this section which accompanies a
conveyance document or is filed separately shall be deemed to provide
constructive notice of information contained therein for purposes of article 35
of title 38, C.R.S.
(3)
(Deleted by amendment, L. 96, p. 949, § 4, effective July 1, 1996.)
(4)
Each county assessor shall maintain a data bank consisting of information which
has been derived from the declarations filed pursuant to the provisions of this
article. Such information shall be used to properly adjust sales for sales
ratio analysis and for determining the actual value of the real property
transferred and the actual value of other real property, as well as other
purposes deemed appropriate by the county assessor.
Source:
L. 89: Entire
article added, p. 1460, § 20, effective July 1. L. 90: (1)(c) amended,
p. 1698, § 25, effective June 9. L. 96: (1)(a), (1)(b)(II), and (3)
amended, p. 949, § 4, effective July 1.
39-14-103. Manufactured home
declaration - information available to county assessor.
(1) (a)
On or after July 1, 2008, but before July 1, 2009, any manufactured home title
application that is submitted to an authorized agent shall be accompanied by a
declaration prescribed by the property tax administrator. On or after July 1,
2009, upon conveyance of any manufactured home, a new title application that is
submitted to an authorized agent shall be accompanied by a declaration
prescribed by the property tax administrator. The declaration shall be
completed and signed by the purchaser or transferee.
(b) (I)
If the declaration required in this subsection (1) does not accompany a
manufactured home title application at the time such application is presented
to the authorized agent, the authorized agent shall notify the county assessor
that such application was not accompanied by such declaration.
(II)
Upon receiving the notice from the authorized agent pursuant to subparagraph
(I) of this paragraph (b), the county assessor shall send written notice to the
purchaser or transferee specified in the manufactured home title application
that the purchaser or transferee shall provide the declaration to the county
assessor within thirty days after the date the notice was mailed. If the
purchaser or transferee fails to provide such declaration within thirty days
after the date the notice was mailed, the county assessor may impose upon such
purchaser or transferee a penalty of twenty-five dollars or a penalty equal to
twenty-five one-thousandths of one percent of the sale price of the
manufactured home, whichever amount is greater. In each subsequent year in
which the purchaser or transferee fails to file the declaration, the assessor
may impose said specified penalty unless the manufactured home has been
subsequently conveyed. Any penalty imposed pursuant to this subparagraph (II)
shall be a fee of the office of the county assessor.
(III)
Any unpaid penalties that were imposed pursuant to subparagraph (II) of this
paragraph (b) shall be certified to the county treasurer by January 1 of each
year and shall be included in the statement sent to the purchaser or transferee
pursuant to section 39-10-103 for property taxes levied against the
manufactured home.
(c) The
authorized agent shall not record or file any declaration made pursuant to the
provisions of this section; however, the authorized agent shall enter upon such
declaration the date of recordation and reception number of the verification of
application form related to the manufactured home title application. The county
clerk and recorder shall transmit any declaration made pursuant to the
provisions of this section to the county assessor. The county assessor shall
make any declaration made pursuant to the provisions of this section available
for inspection by any taxpayer who was specified in the manufactured home title
application or who filed such declaration, the person conducting any valuation
for assessment study pursuant to section 39-1-104 (16) and his or her
employees, and the property tax administrator and his or her employees.
(2) No
declaration made pursuant to this section that accompanies a manufactured home
title application or is filed separately shall be deemed to provide
constructive notice of information contained therein for purposes of article 35
of title 38, C.R.S.
(3)
Each county assessor shall maintain a data bank consisting of information that
has been derived from the declarations filed pursuant to this section. Such
information shall be used to properly adjust sales for sales ratio analysis and
for determining the actual value of the manufactured home transferred and the
actual value of other manufactured homes, as well as other purposes deemed
appropriate by the county assessor.
(4) A
manufactured home that has become real property in accordance with the
provisions of part 1 of article 29 of title 38, C.R.S., shall be subject to the
provisions of section 39-14-102.
Source:
L. 2008: Entire
section added, p. 453, § 12, effective July 1. L. 2009: (1)(a) amended,
(SB 09-040), ch. 9, p. 71, § 14, effective July 1.
SPECIFIC
TAXES
General
and Administrative
ARTICLE
20
Enforcement
of Tax Liens
39-20-101. Not applicable to general or
inheritance taxes.
39-20-102. Civil action to enforce lien.
39-20-103. When holder of prior lien may file
action.
39-20-104. Certificate of discharge subject to
lien.
39-20-105. Certificate of discharge to part of
property.
39-20-106. How values determined.
39-20-107. Certificate of release conclusive.
39-20-101. Not applicable to general or
inheritance taxes.
The
provisions of this article shall not apply to liens for general taxes or inheritance
taxes.
Source:
L. 43: p. 509, §
7. CSA: C. 142, § 280(7). CRS 53: § 138-7-1. C.R.S. 1963:
§ 138-6-1.
ANNOTATION
Law reviews. For
article, "Trusts and Estates", see 30 Dicta 435 (1953).
39-20-102. Civil action to enforce
lien.
In any
case where there has been a refusal or neglect to pay any tax due the state of
Colorado and a statement or notice has been filed which, under law, creates a
lien upon any real property for such tax, the executive director of the
department of revenue may cause a civil action to be filed in the district
court of the county in which is situated any real property which is subject to
said lien to enforce the lien of the state of Colorado for such tax upon the
real property situated in that county or in any other county in the state which
may be subject to such lien or to subject any real property or any right,
title, or interest in real property to the payment of such tax. The court shall
adjudicate all matters involved in such action and may decree a sale of the
real property and distribute the proceeds of such sale according to the
findings of the court in respect to the interest of the parties and of the
state of Colorado. The proceedings in such action and the manner of sale, the
period for and manner of redemption from such sale, and the execution of a deed
of conveyance shall be in accordance with the law and practice relating to
foreclosures of mortgages upon real property. In any such action, the court may
appoint a receiver of the real property involved in such action if equity so
requires.
Source:
L. 43: p. 507, §
1. CSA: C. 142, § 280(1). CRS 53: § 138-7-2. C.R.S. 1963:
§ 138-6-2.
Cross
references: For
foreclosure of mortgages and redemption procedures, see articles 38, 39, and 40
of title 38; for appointment and qualification of receivers, see C.R.C.P. 66.
39-20-103. When holder of prior lien
may file action.
(1) A
person having a lien upon or any interest in any real estate referred to in
section 39-20-102 under or by virtue of any instrument that has been duly filed
of record, in the office of the county clerk and recorder of the county where
the real estate is located, prior to the filing of the statement or notice that
created a lien upon such real property for taxes or any person purchasing such
real estate at a sale to satisfy such prior lien or interest may make written
request to the executive director of the department of revenue to file a civil
action as provided in section 39-20-102. If no civil action has been commenced
as provided in section 39-20-102 within two months after receipt by the
executive director of the written request, the person or purchaser may file a
civil action in the district court of any county where any such real property
is situated asking for a final determination of all claims of the state of
Colorado to and all liens of the state of Colorado upon the real estate in question.
Service of the process in such action upon the state of Colorado shall be made
upon the executive director of the department of revenue or upon one of his or
her deputies. Permission is given for the state of Colorado to be so sued. The
court shall in such civil action adjudicate the matters involved therein in the
same manner as in the case of civil actions filed under section 39-20-102.
(2)
Except for liens with priority pursuant to section 39-22-604, a lien for taxes
due the state of Colorado may be divested by a foreclosure pursuant to article
38 of title 38, C.R.S., in the same manner as other lienors with liens upon the
property being foreclosed. The state of Colorado shall have the same redemption
rights as other lienors in such a foreclosure. A person foreclosing a deed of
trust or other lien with priority over a lien for taxes due the state of
Colorado in a foreclosure under article 38 of title 38, C.R.S., shall not be
required to make a written request or to commence a civil action pursuant to
subsection (1) of this section.
Source:
L. 43: p. 507, §
2. CSA: C. 142, § 280(2). CRS 53: § 138-7-3. C.R.S. 1963:
§ 138-6-3. L. 2006: Entire section amended, p. 1479, § 34, effective
July 1.
39-20-104. Certificate of discharge
subject to lien.
If any
property, real or personal, under the law, is subject to a lien for the payment
of any tax due the state of Colorado, the executive director of the department
of revenue may issue a certificate of discharge of any part of the property
subject to the lien if he finds that the fair market value of that part of such
property remaining subject to the lien is at least double the amount of the
liability remaining unsatisfied in respect to such tax and the amount of all
prior liens upon such property.
Source:
L. 43: p. 508, §
3. CSA: C. 142, § 280(3). CRS 53: § 138-7-4. C.R.S. 1963:
§ 138-6-4.
39-20-105. Certificate of discharge to
part of property.
If any
property, real or personal, under the law, is subject to a lien for the payment
of any tax due the state of Colorado, the executive director of the department
of revenue may issue a certificate of discharge of any part of the property
subject to the lien if there is paid over to the executive director, in part
satisfaction of the liability in respect to such tax, an amount determined by
the executive director, which shall not be less than the value, as determined
by him, of the interest of the state of Colorado in the part to be so
discharged.
Source:
L. 43: p. 508, §
4. CSA: C. 142, § 280(4). CRS 53: § 138-7-5. C.R.S. 1963:
§ 138-6-5.
39-20-106. How values determined.
In
determining the values mentioned in section 39-20-105, the executive director
of the department of revenue shall give consideration to the fair market value
of the part to be so discharged and to such lien thereon as has priority to the
lien of the state of Colorado.
Source:
L. 43: p. 508, §
5. CSA: C. 142, § 280(5). CRS 53: § 138-7-6. C.R.S. 1963:
§ 138-6-6.
39-20-107. Certificate of release
conclusive.
A
certificate of release or of partial discharge issued under section 39-20-104
shall be held conclusive that the lien of the state of Colorado upon the
property released therein is extinguished.
Source:
L. 43: p. 509, §
6. CSA: C. 142, § 280(6). CRS 53: § 138-7-7. C.R.S. 1963:
§ 138-6-7.
ARTICLE
21
Procedure
and Administration
PART 1
GENERAL PROVISIONS
39-21-101. Definitions.
39-21-102. Scope.
39-21-103. Hearings.
39-21-104. Rejection of claims.
39-21-104.5. Frivolous submissions.
39-21-105. Appeals.
39-21-105.5. Notice - first-class mail -
definition.
39-21-106. Compromise.
39-21-107. Limitations.
39-21-108. Refunds.
39-21-109. Interest on underpayment,
nonpayment, or extensions of time for payment of tax.
39-21-110. Interest on overpayments - repeal.
39-21-110.5. Rate of interest to be fixed.
39-21-111. Jeopardy assessment and demands.
39-21-112. Duties and powers of executive
director - reporting of information related to local lodging tax and sales or
use tax on building or construction materials - definitions - repeal.
39-21-113. Reports and returns - rule -
repeal.
39-21-114. Methods of enforcing collection.
39-21-114.5. Surrender of property subject to
levy - definition.
39-21-115. Reciprocity with other states for
collection of taxes provided.
39-21-116. Closing agreements.
39-21-116.5. Penalties - repeal.
39-21-117. Saving clause.
39-21-118. Criminal penalties - repeal.
39-21-119. Filing with executive director -
when deemed to have been made.
39-21-119.5. Mandatory electronic filing of
returns - mandatory electronic payment - penalty - waiver - definitions.
39-21-120. Signature and filing alternatives
for tax returns.
39-21-121. Unclaimed property offset -
definition.
39-21-122. Revenue impact of 2010 tax
legislation - tracking by department. (Repealed)
PART 2
TAX AMNESTY PROGRAM
39-21-201 to
39-21-202. (Repealed)
PART 3
TAX PROFILE AND EXPENDITURE REPORT
39-21-301. Legislative declaration.
39-21-302. Definitions.
39-21-303. Tax profile and expenditure report.
39-21-304. Tax expenditure - tax preference
performance statement - tax expenditure repeal requirement.
39-21-305. Tax expenditure - state auditor
evaluation.
39-21-306. State auditor report - federal tax
law and changes that impact the state tax base.
PART 4
LEGISLATIVE OVERSIGHT COMMITTEE CONCERNING TAX POLICY
39-21-401. Legislative declaration.
39-21-402. Definitions.
39-21-403. Legislative oversight committee
concerning tax policy - creation - duties - report - repeal.
39-21-404. Task force concerning tax policy -
creation - membership - duties.
39-21-405. Repeal of part.
PART
1
GENERAL
PROVISIONS
39-21-101. Definitions.
As used in
this article, unless the context otherwise requires:
(1)
"Department" means the department of revenue.
(2)
"Executive director" or "executive director of the department of
revenue" means the executive director of the department of revenue and
includes the head of any group, division, or subordinate department, as
appointed in accordance with article 35 of title 24, C.R.S., whenever the
executive director specifically authorizes the group, division, or subordinate
department head to act on his or her behalf.
(3)
"Person" includes any individual, firm, corporation, partnership,
limited liability company, joint venture, estate, trust, or group or
combination acting as a unit.
(4)
"Taxpayer" includes a person against whom a deficiency is being
asserted, whether or not he has paid any of the tax in issue prior thereto.
Source:
L. 65: p. 1148, §
2. C.R.S. 1963: § 138-9-15. L. 76: (1) amended and (1.5) added,
p. 777, § 2, effective July 1. L. 77: Entire section R&RE, p. 1765,
§ 1, effective June 19. L. 90: (3) amended, p. 450, § 28, effective
April 18. L. 93: (2) amended, p. 1239, § 13, effective July 1. L.
2000: (2) amended, p. 1639, § 18, effective June 1.
ANNOTATION
Applied in Toncray v.
Dolan, 197 Colo. 382, 593 P.2d 956 (1979).
39-21-102. Scope.
(1)
Unless otherwise indicated, the provisions of this article 21 apply to the
taxes or fees imposed by articles 22 to 37 of this title 39 and article 60 of
title 34, section 21 of article X of the state constitution, article 3 of title
42, part 5 of article 3 of title 44, articles 11 and 20 of title 30, article 4
of title 43, article 2 of title 40, and part 2 of article 20 of title 8.
(2) The
provisions of this article 21 apply to the taxes imposed pursuant to articles
3, 4, and 32 of title 44, but only to the extent that the provisions of this
article 21 are not inconsistent with the provisions of articles 3, 4, and 32 of
title 44.
(3)
Repealed.
(4) The
provisions of this article apply to grants authorized pursuant to article 31 of
this title to the extent that such provisions are not inconsistent with the
provisions of said article 31.
(5) The
provisions of this article apply to the taxes or fees imposed pursuant to
articles 1, 2, 11, and 25 of title 29, C.R.S., but only to the extent that the
provisions of this article are not inconsistent with the provisions of articles
1, 2, 11, and 25 of title 29, C.R.S.
(6) The
provisions of this article apply to the taxes or fees imposed pursuant to title
32, C.R.S., but only to the extent that the provisions of this article are not
inconsistent with the provisions of title 32, C.R.S.
(7) The
provisions of this article 21 apply to the fees imposed pursuant to part 3 of
article 38.5 of title 24, article 7.5 of title 25, and the fees collected
pursuant to section 40-10.1-607.5, but only to the extent that the provisions
of this article 21 are not inconsistent with the provisions of part 3 of
article 38.5 of title 24, article 7.5 of title 25, and section 40-10.1-607.5.
(8) The
provisions of this article 21 apply to the fees imposed pursuant to the
provisions of article 61 of title 33 and the fees imposed by the provisions of
section 43-4-1204, but only to the extent that the provisions of this article
21 are not inconsistent with the provisions of article 61 of title 33 and the
provisions of section 43-4-1204.
(9)
This article 21 applies to the fees imposed pursuant to sections 40-17-104 and
40-17.5-104, but only to the extent that this article 21 is not inconsistent
with sections 40-17-104 and 40-17.5-104.
Source:
L. 65: p. 1131, §
2. C.R.S. 1963: § 138-9-1. L. 72: p. 620, § 164. L. 77:
Entire section amended, p. 841, § 2, effective July 1; entire section amended,
pp. 1766, 1852, §§ 1, 3, effective January 1, 1978. L. 79: Entire
section amended, p. 1499, § 20, effective January 1, 1980. L. 86: Entire
section amended, p. 1109, § 3, effective July 1. L. 87: Entire section
amended, p. 486, § 31, effective July 1. L. 89: (1) amended, p. 1594, §
4, effective July 1, 1993. L. 90: (1) amended, p. 1721, § 1, effective
May 1; (1) amended, p. 1721, § 2, effective July 1, 1993. L. 93: (2)
amended, p. 1239, § 14, effective July 1. L. 2001: (3) added, p. 777, §
7, effective June 1. L. 2004: (4) added, p. 399, § 1, effective August
4. L. 2005: (1) amended, p. 911, § 13, effective June 2; (1) amended, p.
926, § 14, effective June 2. L. 2009: (3) repealed, (HB 09-1053), ch.
159, p. 689, § 10, effective August 5. L. 2014: (1) amended and (5) and
(6) added, (HB 14-1107), ch. 134, p. 465, § 2, effective April 25. L. 2015:
(1) amended, (SB 15-264), ch. 259, p. 967, § 90, effective August 5. L.
2018: (1) amended, (HB 18-1025), ch. 152, p. 1081, § 19, effective October
1; (2) amended, (HB 18-1024), ch. 26, p. 325, § 22, effective October 1. L.
2021: (7) added, (SB 21-260), ch. 250, p. 1401, § 12, effective June 17. L.
2024: (8) added, (SB 24-230), ch. 184, p. 1023, § 7, effective May 16; (1)
amended, (HB 24-1450), ch. 490, p. 3424, § 75, effective August 7; (1) amended,
(HB 24-1349), ch. 423, p. 2902, § 7, effective December 17 (see editor's note).
L. 2025: (9) added, (HB 25-1154), ch. 230, p. 1086, § 26, effective
January 1, 2026. L. 2026: (9) amended, (HB 26-1115), ch. 17, p. 81, § 4,
effective March 26.
Editor's
note: (1)
Amendments to this section by House Bill 77-1076 harmonized with Senate Bill
77-100 and Senate Bill 77-1448.
(2) Amendments to subsection
(1) by HB 24-1349 and HB 24-1450 were harmonized, effective on the date of the
official declaration of the vote thereon by the governor only if, at the
November 2024 statewide election, a majority of voters approve the ballot issue
referred in accordance with § 39-37-201. The ballot issue, referred to the
voters as Proposition KK, was approved on November 5, 2024, and was proclaimed
by the Governor on December 17, 2024, see L. 2025, p. 3636. The vote count for
the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
(3) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: (1)
For the legislative declaration contained in the 2005 act amending subsection
(1), see section 1 of chapter 241, Session Laws of Colorado 2005.
(2) For the legislative
declaration in SB 21-260, see section 1 of chapter 250, Session Laws of
Colorado 2021.
ANNOTATION
Section 39-21-107 applicable
where use taxes assessed, no return filed. It is the intent of the general
assembly that § 39-21-107, rather than § 39-26-210, should be the controlling
statute of limitations where use taxes are assessed but no return is filed. Dye
Constr. Co. v. Dolan, 41 Colo. App. 293, 589 P.2d 497 (1978).
Inapplicable to violations
of liquor code. The prohibition against fraud found in § 39-21-118 does not
apply to violations of the liquor code. People v. Luciano, 662 P.2d 480 (Colo.
1983).
The general assembly
intended the controlled substances tax to be subject to the provisions of this
article, and, since taxpayer failed to pursue administrative remedies set
forth therein, the court was without jurisdiction to hear taxpayer's complaint.
Huff v. Tipton, 810 P.2d 236 (Colo. App. 1991).
39-21-103. Hearings.
(1) As
soon as practicable after any tax return or the return showing the value of oil
and gas is filed, the executive director shall examine it and shall determine
the correct amount of tax. If the tax found due is greater than the amount
theretofore assessed or paid, a notice of deficiency shall be mailed to the
taxpayer by first-class mail as set forth in section 39-21-105.5.
(1.5) (a)
(I) Repealed.
(II)
The department shall examine a risk-based sample of the information provided by
collegeinvest under subsection (1.5)(a)(I) of this section to substantiate that
any distribution from a collegeinvest account was made for the reasons
specified in section 39-22-104 (4)(i)(III), and shall determine the correct
amount of tax for any taxpayer that made unqualified distributions. If the tax
that is found due is greater than the amount assessed or paid, the department
shall notify the taxpayer as set forth in subsection (1) of this section.
(b) For
income tax years commencing on or after January 1, 2021, the executive director
shall regularly examine a risk-based sample of the information provided by
collegeinvest under section 39-22-104 (4)(i)(V) to substantiate that any
distribution from a collegeinvest account was made for the reasons specified in
section 39-22-104 (4)(i)(III), and shall determine the correct amount of tax
for any taxpayer that made unqualified distributions. If the tax that is found
due is greater than the amount assessed or paid, the department shall notify
the taxpayer as set forth in subsection (1) of this section.
(c) The
executive director shall provide a report of the examinations required under
subsection (1.5)(b) of this section, consistent with section 39-21-113 (5), as
part of the department's presentation to its committee of reference at a
hearing held pursuant to section 2-7-203 (2)(a) of the "State Measurement
for Accountable, Responsive, and Transparent (SMART) Government Act".
(2) The
taxpayer may request a hearing on the proposed tax by application to the
executive director within thirty days of the mailing of a notice of deficiency.
(3) The
request for hearing shall set forth the taxpayer's reasons for and the amount
of the requested changes in the deficiency.
(3.5)
If the executive director determines that a request for a hearing related to
the tax set forth in part 1 of article 22 of this title is a frivolous
submission and rejects the request pursuant to section 39-21-104.5, the
taxpayer shall not be entitled to a hearing before the executive director and
the provisions of section 39-21-104.5 shall apply.
(4) The
executive director of the department of revenue shall notify the taxpayer in
writing of the time and place for such hearing thirty days prior thereto. The
hearing must be held at a location designated by the executive director in
either Adams, Arapahoe, Boulder, Broomfield, Denver, Douglas, or Jefferson
county, or, at the election of the taxpayer, by video conference; except that,
if the taxpayer resides or has their principal place of business in Colorado
and the disputed deficiency is either two hundred dollars or less, or involves
sales and use taxes regardless of the amount, then the hearing may be held, at
the election of the taxpayer, in the district office of the department nearest
to the place where the taxpayer resides or has their principal place of
business in Colorado.
(4.5)
If the taxpayer and the executive director agree that the disposition of the
taxpayer's requested changes requires the resolution of a question of law
arising under the United States or Colorado constitutions, the executive
director shall memorialize the agreement and send the taxpayer a notice of the
agreement by first-class mail as set forth in section 39-21-105.5. If a notice
is sent pursuant to this subsection (4.5), a taxpayer may elect to waive a
hearing pursuant to this section and appeal the notice of deficiency directly
to the district court pursuant to section 39-21-105 within thirty days after
the mailing of the notice.
(5)
After a hearing under this section, the taxpayer shall not be entitled to a
second hearing before the executive director of the department of revenue on
the matters set forth in his previous request for hearing.
(6) (a)
Except as provided in paragraph (b) of this subsection (6), the hearing shall
be held before the executive director of the department of revenue.
(b) In
cases where the disputed deficiency is more than two hundred dollars and
involves an income tax, the hearing may be held before such qualified person
within the department specifically authorized by the executive director to act
on the executive director's behalf to hear such dispute. In cases where the
disputed deficiency is two hundred dollars or less or involves a sales, use, or
gift tax, the hearing may be held before such person within the department as
the executive director shall designate.
(c) The
executive director or the executive director's delegate is authorized to
administer oaths and take testimony. At the hearing, the taxpayer may assert
any facts, make any arguments, and file any briefs and affidavits the taxpayer
believes pertinent to the case.
(7) In
lieu of the request for hearing within the time provided by this section, the
taxpayer may, at his election, file a written brief and such other written
materials or documents as he deems appropriate and request that the executive
director of the department of revenue reconsider the deficiency without a
hearing. The executive director shall reconsider the deficiency in the same
manner as if the written material submitted had been presented at a hearing
pursuant to this section. The submission of written material shall be
considered for all purposes the same as a request for and submission of the
material at a hearing.
(8) (a)
Based on the evidence presented at the hearing or filed in support of the
taxpayer's contentions or after the expiration of thirty days from the mailing
of the notice of deficiency, if no request for hearing or brief has been filed
by the taxpayer, the executive director of the department of revenue shall make
a final determination within the time specified in paragraph (b) of this
subsection (8) and shall send the taxpayer a notice of final determination
accompanied by notice and demand for payment by first-class mail as set forth
in section 39-21-105.5.
(b) The
executive director shall make a final determination within sixty days of the
hearing. Such deadline may be extended:
(I) By
up to an additional sixty days by mutual agreement between the executive
director and the taxpayer; or
(II) By
the executive director in the executive director's discretion if the final
determination raises issues that require additional information or time to
analyze in order to make the determination. The executive director may
authorize successive extensions of a deadline to make a particular
determination; however, no individual extension authorized pursuant to this
subparagraph (II) shall exceed sixty days. Prior to authorizing each extension
of a deadline pursuant to this subparagraph (II), the executive director shall
mail a written notice of the extension and the specific reasons therefor to the
taxpayer.
(c) The
executive director may modify the tax, penalty, and interest questioned at the
hearing and may approve a refund; except that no additional tax shall be
assessed for less than one dollar. Unless an appeal is taken as provided in
section 39-21-105, the tax, together with interest thereon and penalties, if
any, shall be paid within thirty days after mailing of the notice and demand
for payment by the executive director.
Source:
L. 65: p. 1131, §
2. C.R.S. 1963: § 138-9-2. L. 73: p. 1417, § 101. L. 77:
(1), (4), and (6) amended, p. 841, § 3, effective July 1; (1) amended, pp.
1766, 1852, §§ 2, 4, effective January 1, 1978. L. 79: (1) amended, p.
1499, § 21, effective January 1, 1980. L. 86: (1) amended, p. 1110, § 4,
effective July 1. L. 89: (1) amended, p. 1594, § 5, effective July 1,
1993. L. 90: (1) amended, p. 1721, § 3, effective May 1; (1) amended, p.
1722, § 4, effective July 1, 1993. L. 96: (1) and (8) amended, p. 163, §
1, effective July 1. L. 2001: (1) amended, p. 777, § 8, effective June
1. L. 2002: (4.5) added and (6) and (8) amended, p. 256, § 1, effective
July 1. L. 2003: (3.5) added, p. 661, § 1, effective March 20. L.
2009: (1) amended, (HB 09-1053), ch. 159, p. 689, § 11, effective August 5.
L. 2021: (4) amended, (SB 21-223), ch. 93, p. 375, § 1, effective May 4;
(1.5) added, (HB 21-1311), ch. 298, p. 1768, § 2, effective June 23. L.
2024: (1) amended, (HB 24-1349), ch. 423, p. 2902, § 8, effective December
17 (see editor's note). L. 2026: (1.5)(a)(I) repealed and (1.5)(c)
amended, (HB 26-1295), ch. 121, p. 527, § 27, effective August 12.
Editor's
note: (1)
Amendments to subsection (1) by House Bill 77-1076, Senate Bill 77-100, and
Senate Bill 77-144 were harmonized.
(2) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: For
the legislative declaration in HB 21-1311, see section 1 of chapter 298,
Session Laws of Colorado 2021.
ANNOTATION
Law reviews. For
article, "Taxation", which discusses Tenth Circuit decisions dealing
with the fifth amendment privilege in tax proceedings, see 61 Den. L.J. 384
(1984).
Annotator's note. Notes
from People ex rel. Dunbar v. Maytag, 129 Colo. 316, 270 P.2d 782 (1954),
decided under former § 39-25-115, which dealt with objections to the amount of
gift tax, are included in the annotations to this section.
Director of revenue is
vested with the full authority to determine tax liability, subject to the
right of appeal to the district court, and the further right of review pursuant
to the provisions of § 39-21-105. Ray v. State, 123 Colo. 144, 226 P.2d 804
(1950).
Decision of director final
against state. After the tax liability determined hereby is paid under
protest, the decision of the director of revenue is apparently final against
the state, for § 39-21-105 makes available only the remedy to be pursued in the
event the taxpayer is dissatisfied with the director's decision. Cal. Co. v.
State, 141 Colo. 288, 348 P.2d 382 (1959).
Section sets forth a
statutory procedure available to a donor if he is dissatisfied with the
assessment or the gift tax determined by the commissioner (now executive
director). People ex rel. Dunbar v. Maytag, 129 Colo. 316, 270 P.2d 782 (1954).
Section affords the taxpayer
a plain, speedy, and adequate remedy and a full opportunity to be heard as
to the quantum of the tax and the alleged irregularities leading up to the
fixation of tax liability. Liebhardt v. Dept. of Rev., 123 Colo. 369, 229 P.2d
655 (1951).
Taxpayer's sole remedy under
this section. If the donor is dissatisfied with the commissioner's (now
executive director's) determination of the gift tax, his sole and only remedy
is under the provisions of this section. People ex rel. Dunbar v. Maytag, 129
Colo. 316, 270 P.2d 782 (1954).
Section provides a clear
opportunity to be heard without condition. Reed v. Dolan, 195 Colo. 193,
577 P.2d 284 (1978).
Section is applicable only
where there has been assessment and tax determination by the inheritance
tax commissioner (now executive director), and the objections therein provided
are limited to questions of erroneous valuation, appraisement, or objections or
petitions in a court of competent jurisdiction within three months after the
gift tax has been determined. People ex rel. Dunbar v. Maytag, 129 Colo. 316,
270 P.2d 782 (1954).
No "return" filed
without information with respect to income on form. Where a Colorado income
tax form contains no information with respect to income, the taxpayer has not
filed a "return" within the meaning of subsection (1) and he is not
within the class of persons protected by this section who are entitled to a
determination of tax due after a return has been filed. People v. Vickers, 199
Colo. 305, 608 P.2d 808 (1980).
Failure to exhaust statutory
remedies constitutes waiver. The failure to interpose objections in the
manner and at the time prescribed by law, and to exhaust the statutory remedies
afforded the taxpayer, constitutes a waiver of such objections. Liebhardt v.
Dept. of Rev., 123 Colo. 369, 229 P.2d 655 (1951).
The taxpayer's failure to
pursue the proper administrative courses available to him as possible remedies
bars him from later attacking the final determination and notice of tax
deficiency. Manka v. Martin, 614 P.2d 875 (Colo. 1980).
The general assembly
intended the controlled substances tax to be subject to the provisions of this
article, and, since taxpayer failed to pursue administrative remedies set
forth therein, the court was without jurisdiction to hear taxpayer's complaint.
Huff v. Tipton, 810 P.2d 236 (Colo. App. 1991).
Where partnership is
assessed for use tax and incurs liability owing to its failure to protest
liability, taxpayer who is general partner of a limited partnership is
jointly and severally liable therefor. AF Prop. v. Dept. of Rev., 852 P.2d 1267
(Colo. App. 1992).
When issue of material fact
existed as to whether general partnership had been assessed with a use tax,
trial court erred in entering motion for summary judgment in favor of
individual partner on grounds that partner could not be held jointly and
severally liable for deficiency owed by partnership. AF Prop. v. Dept. of Rev.,
852 P.2d 1267 (Colo. App. 1992).
Applied in People v.
Vesely, 41 Colo. App. 325, 587 P.2d 802 (1978); Montgomery Ward & Co. v.
State, Dept. of Rev., 628 P.2d 85 (1981); Montgomery Ward & Co. v. Dept. of
Rev., 675 P.2d 318 (Colo. App. 1983).
39-21-104. Rejection of claims.
(1)
Upon rejection, in whole or in part, of a claim for refund filed by a taxpayer,
with respect to any tax set forth in section 39-21-103 (1), the executive
director of the department of revenue shall send a notice of rejection to the
taxpayer in writing by first-class mail as set forth in section 39-21-105.5;
and, within thirty days from the mailing thereof, the taxpayer may request a
hearing or file a brief with the executive director, except where the claim is
for refund of a deficiency in taxes assessed after hearing or determination on
written brief had under the provisions of section 39-21-103. Thereafter, both
the taxpayer and the executive director shall proceed as provided in section
39-21-103 with respect to the hearing or determination on written brief. Upon
reaching a decision upon the claim for refund after hearing had thereon or
consideration of the written brief, the executive director shall send to the
taxpayer, by first-class mail as set forth in section 39-21-105.5, notice of
final determination of claim for refund, stating therein the grounds for
allowance or rejection in whole or in part.
(2) If
the executive director determines that a request for a hearing related to the
tax set forth in part 1 of article 22 of this title is a frivolous submission
and rejects the request pursuant to section 39-21-104.5, the taxpayer shall not
be entitled to a hearing before the executive director and the provisions of
section 39-21-104.5 shall apply.
Source:
L. 65: p. 1133, §
2. C.R.S. 1963: § 138-9-3. L. 77: Entire section amended, pp.
742, 841, §§ 2, 4, effective July 1. L. 96: Entire section amended, p.
164, § 2, effective July 1. L. 2003: Entire section amended, p. 661, §
2, effective March 20. L. 2004: (1) amended, p. 383, § 1, effective
April 8.
Editor's
note: Amendments
to this section by House Bill 77-1164 and Senate Bill 77-100 were harmonized.
39-21-104.5. Frivolous submissions.
(1) As
used in this part 1, unless the context otherwise requires, "frivolous
submission" means a request for a hearing related to the tax set forth in
part 1 of article 22 of this title made pursuant to section 39-21-103 or
39-21-104 that is based on a position that was previously rejected in a
published opinion by a Colorado or federal court.
(2) If
the executive director determines that a request for a hearing made pursuant to
section 39-21-103 or 39-21-104 is a frivolous submission, the executive
director may reject the request. If the executive director does not reject the
request, the provisions of section 39-21-103 or 39-21-104 shall apply.
(3) If
the executive director rejects a taxpayer's request for a hearing:
(a) The
executive director shall notify the taxpayer in writing within a reasonable
time after receiving the taxpayer's request that the taxpayer's request has
been rejected; and
(b) The
executive director shall make a final determination within a reasonable time
after receiving the taxpayer's request for a hearing and shall send the
taxpayer a notice of final determination accompanied by a notice and demand for
payment by first-class mail as set forth in section 39-21-105.5.
(4) A
taxpayer may appeal the final determination of the executive director in accordance
with the provisions of section 39-21-105.
(5)
Unless an appeal is taken as provided in section 39-21-105, the tax, together
with interest thereon and penalties, if any, shall be paid within thirty days
after mailing of the notice and demand for payment by the executive director.
Source:
L. 2003: Entire
section added, p. 662, § 3, effective March 20.
39-21-105. Appeals.
(1) The
taxpayer may appeal the final determination of the executive director issued
pursuant to section 39-21-103, 39-21-104, or 39-21-104.5 within thirty days
after the mailing of such determination. Jurisdiction to hear and determine
such appeals is in the district courts of this state.
(2) (a)
Venue is in the district court of the county where the taxpayer resides or has
his or her principal place of business. If the taxpayer has neither a residence
nor a principal place of business within the state, venue is in the Denver
district court.
(b) The
district court shall try the case de novo, reviewing all questions of law and
fact, such review being conducted in accordance with the Colorado rules of
civil procedure. The taxpayer shall present his or her case in the same manner
as the plaintiff in other civil actions and the normal rules of evidence shall
apply. The taxpayer has the burden of proof with respect to the issues raised
in the written notice described in subsection (3) of this section except as to
the issue of whether the taxpayer has been guilty of fraud with intent to evade
tax. The burden of proof is on the executive director of the department of
revenue or his or her delegate to show that a petitioner is liable as a
transferee of property of a taxpayer but not to show that the taxpayer was
liable for the tax. The district court may affirm, modify, or reverse the
determination of the executive director and may enter judgment on its findings.
(3) A
taxpayer appeals a final determination of the executive director by filing,
with the clerk of the district court of the proper county, a copy of the notice
of final determination received by the taxpayer, together with a written notice
stating that the taxpayer appeals to the district court and alleging the
pertinent facts upon which such appeal is grounded.
(4)
Within fifteen days after filing an appeal to the district court from a
decision pursuant to section 39-21-104.5, the taxpayer shall file with the
district court a surety bond in twice the amount of the taxes, interest, and
other charges stated as due in the final determination by the executive
director which are contested on appeal. The taxpayer may, at his or her option,
satisfy the surety bond requirement by deposit in a savings account or deposit
account held in, or purchase a certificate of deposit issued by, a state or
national bank or by a state or federal savings and loan association, in
accordance with the provisions of section 11-35-101 (1), C.R.S., an amount
equal to twice the amount of the taxes, interest, and other charges stated as
due in the final determination by the executive director.
(5) Any
taxpayer may, at his or her option, deposit the disputed amount with the
executive director of the department of revenue within fifteen days after
filing an appeal to the district court. If such amount is so deposited, no
further interest accrues on the deficiency contested during the pendency of the
action. At the conclusion of the action, after appeal to the supreme court or
the court of appeals or after the time for such appeal has expired, the funds
deposited must be, at the direction of the court, either retained by the
executive director and applied against the deficiency or returned in whole or
in part to the taxpayer with interest at the rate imposed under section
39-21-110.5. The taxpayer does not need to make a claim for refund of amounts
deposited with the executive director of the department of revenue in order for
such amounts to be repaid in accordance with the direction of the court.
(6)
Upon filing of the written notice described in subsection (3) of this section,
the executive director of the department of revenue is deemed to be a party to
the appeal, and the clerk of the district court shall docket the cause as a
civil action. The appellant shall cause summons to be issued and cause the same
to be served upon the executive director, in accordance with the manner
provided by law in civil cases. Notice of the date of trial must be mailed to
the taxpayer and to the executive director, at least twenty days before the
date of the trial.
(7) The
final decision made in an appeal of an executive director's final determination
must be entered as a judgment, as in other civil cases, against the taxpayer or
against the executive director as the case may be.
(8) (a)
The decision of the district court is reviewable by the supreme court or the
court of appeals as is otherwise provided by law; except that C.R.C.P. 62 (d)
and C.R.C.P. 121 section 1-23 shall not apply. Except as provided in paragraph
(b) of this subsection (8), if the taxpayer wishes to seek review of a district
court ruling that is adverse to the taxpayer in part or in whole, no later than
fifteen days after the ruling the taxpayer shall:
(I)
File with the district court a surety bond in twice the amount of the taxes,
interest, and other charges stated as due in the district court ruling, which
are contested on appeal;
(II)
Deposit in a savings account or deposit account held in, or purchase a
certificate of deposit issued by, a state or national bank or by a state or
federal savings and loan association, in accordance with the provisions of
section 11-35-101 (1), C.R.S., an amount equal to twice the amount of the
taxes, interest, and other charges stated in the district court ruling; or
(III)
Deposit the amount stated as due in the district court ruling with the
executive director.
(b) If
the taxpayer has posted a bond, made a deposit, or deposited the disputed
amount with the executive director as specified in subsections (4) and (5) of
this section, such previous payment or posting is continued in effect and no
further payment or posting may be required.
(c)
Upon the taxpayer fulfilling the appeal requirements specified in paragraph (a)
of this subsection (8), collection on the judgment is stayed during the
pendency of the action.
(d) If
the taxpayer deposits the amount stated as due in the district court ruling
with the executive director as specified in subparagraph (III) of paragraph (a)
of this subsection (8), no further interest shall accrue on the amount
deposited during the pendency of the action. At the conclusion of the action,
after appeal to the supreme court or after the time for such appeal has
expired, the funds deposited must be, at the direction of the court, either
retained by the executive director and applied against the deficiency or
returned in whole or in part to the taxpayer with interest at the rate imposed
under section 39-21-110.5. The taxpayer does not need to make a claim for
refund of amounts deposited with the executive director in order for such amounts
to be repaid in accordance with the direction of the court.
Source:
L. 65: p. 1133, §
2. C.R.S. 1963: § 138-9-4. L. 69: p. 272, § 18. L. 81: (4)
amended, p. 1863, § 1, effective June 8. L. 84: (4) amended, p. 1006, §
1, effective March 26. L. 2001: (1) amended, p. 434, § 2, effective
April 20. L. 2003: (1) amended, p. 662, § 4, effective March 20. L.
2010: (1) amended, (SB 10-212), ch. 412, p. 2034, § 6, effective July 1. L.
2016: Entire section amended, (SB 16-036), ch. 292, p. 1179, § 1, effective
August 10.
Cross
references: For
service of summons and entry of judgment in civil cases, see C.R.C.P. 4 and 58.
ANNOTATION
Required bond
constitutional. The mandatory bond requirement of subsection (4) does not
violate the taxpayer's constitutional right to due process. Callow v. Dept. of
Rev., 197 Colo. 513, 594 P.2d 1051 (1979).
Director of revenue is
vested with the full authority to determine tax liability, subject to the
right of appeal to the district court, and the further right of review pursuant
to the provisions of this section. Ray v. State, 123 Colo. 144, 226 P.2d 804
(1950).
Decision of director final
against state. Since the tax provisions create the administrative machinery
for determining tax liability, and since the only available remedy is that
provided for the taxpayer, the decision of the director is final against the
state, and the director's waiver of penalty and penalty interest is binding on
the department. Dye Constr. Co. v. Dolan, 41 Colo. App. 293, 589 P.2d 497
(1978).
Failure to appeal within 30
days precludes judicial review. Where the taxpayer, when served with the
notice of determination and assessment and demand for payment, declines to
avail himself of his statutory administrative remedies, in that he fails to
request a hearing before the director, offer additional evidence concerning his
tax liability, post the statutory bond, or appeal to the district court from
the determination of the director, the director's decision becomes final 30
days after notice thereof is mailed to the taxpayer, and it thereupon becomes
no longer subject to judicial review. Liebhardt v. Dept. of Rev., 123 Colo.
369, 229 P.2d 655 (1951).
Mailing notice to the
taxpayer's attorneys does not start the 30-day period, and an appeal is
timely when commenced within 30 days of mailing notice to the taxpayer pursuant
to § 39-21-104. Adolph Coors Co. v. Charnes, 690 P.2d 893 (Colo. App. 1984).
Subsection (2)(b) requires
the trial court to try the case de novo, reviewing all questions of law and
fact, such review being conducted in accordance with the Colorado rules of
civil procedure. M & J Leasing v. Dir. of Dept. of Rev., 796 P.2d 28 (Colo.
App. 1990).
Courts may not dispense with
the bond requirement when reviewing questions of law pursuant to subsection
(2)(b). For both questions of law and fact, the bond is to obtain security
for the payment of taxes. Overstreet v. Dept. of Rev., 178 P.3d 1259 (Colo.
App. 2007).
Trial court's reliance on
facts stipulated at administrative hearing was erroneous. M & J Leasing
v. Dir. of Dept. of Rev., 796 P.2d 28 (Colo. App. 1990).
Statutes requiring appeal
bonds are ordinarily a valid exercise of legislative power, since they do
not restrict or deny the "right" of appeal but merely regulate the
manner of exercising it. Reed v. Dolan, 195 Colo. 193, 577 P.2d 284 (1978);
Callow v. Dept. of Rev., 197 Colo. 513, 594 P.2d 1051 (1979).
No conflict is found between
this section and § 24-4-106 (5) where none plainly appears. Dept. of Rev.
v. District Court, 193 Colo. 553, 568 P.2d 1157 (1977).
This section does not expressly
prohibit the entry of a stay as authorized by § 24-4-106 (5). Dept. of Rev. v.
District Court, 193 Colo. 553, 568 P.2d 1157 (1977).
Trial court had jurisdiction
as a matter of law to waive bond requirement for indigent taxpayer and proceed
to adjudicate merits of appeal concerning use tax deficiency where
undisputed evidence in affidavit form was proffered to the trial court reciting
tax payer's inability to post bond or make deposit required by statute. AF
Prop. v. Dept. of Rev., 852 P.2d 1267 (Colo. App. 1992).
Subsection (4) does not
authorize a taxpayer to toll the statutory period for obtaining a surety bond
by filing a motion to waive the surety bond requirement and then filing a
motion to reconsider. Overstreet v. Dept. of Rev., 178 P.3d 1259 (Colo. App.
2007).
This section does not
prohibit a trial court from tolling post-judgment interest earlier than at the
conclusion of the action. In fact, the statute is silent concerning early
satisfaction of a judgment. Subsection (4)(b) simply mandates that the judgment
shall be paid, at the very latest, at the conclusion of the action. It does not
state that the conclusion of the action is the only time when the judgment may
be satisfied. Coors Brewing Co. v. City of Golden, 2013 COA 92, 411 P.3d 767.
Where partnership is
assessed for use taxes and incurs liability owing to its failure to protest
liability, taxpayer, as general partner of a limited partnership, is
jointly and severally liable therefor. AF Prop. v. Dept. of Rev., 852 P.2d 1267
(Colo. App. 1992).
When issue of material fact
existed as to whether general partnership had been assessed with a use tax,
trial court erred in entering motion for summary judgment in favor of
individual partner on grounds that partner could not be held jointly and
severally liable for deficiency owed by partnership. AF Prop. v. Dept. of Rev.,
852 P.2d 1267 (Colo. App. 1992).
Applied in B.P.O.E.
Lodge No. 804 v. Dept. of Rev., 41 Colo. App. 88, 582 P.2d 1068 (1978); Dye
Constr. Co. v. Dolan, 41 Colo. App. 293, 589 P.2d 497 (1978); Kraftco Corp. v.
Charnes, 636 P.2d 1300 (Colo. App. 1981); Sky Chefs v. City & County of
Denver, 653 P.2d 402 (Colo. 1982); Overstreet v. Dept. of Rev., 178 P.3d 1259
(Colo. App. 2007); Am. Multi-Cinema v. City of Aurora, 2020 COA 4, 471 P.3d
1139.
39-21-105.5. Notice - first-class mail -
definition.
(1)
Except as provided in subsection (2) of this section, any notice required to be
given to any taxpayer pursuant to the scope of this article as set forth in
section 39-21-102 is sufficient if mailed, postpaid by first-class mail to the
last-known address of the taxpayer. The first-class mailing of any notice
pursuant to the scope of this article as set forth in section 39-21-102 creates
a presumption that such notice was received by the taxpayer if the department
maintains a record of the notice and maintains a certification that the notice
was deposited in the United States mail by an employee of the department.
Evidence of the record of the notice mailed to the last-known address of the
taxpayer as shown by the records of the department and a certification of
mailing by first-class mail by a department employee is prima facie proof that
the notice was received by the taxpayer.
(2)
Notwithstanding subsection (1) of this section, and notwithstanding any other
provision of law that requires written correspondence to be sent by first-class
mail to a taxpayer, the department may promulgate rules to establish procedures
that allow a taxpayer to voluntarily elect to receive any notice or other
communication by electronic means pursuant to the established procedures. The
procedures must be designed to ensure that to the greatest degree reasonably
possible the party viewing the notice or communication is the taxpayer for whom
the notice or communication is intended. An electronically transmitted notice
or communication is sufficient to satisfy any requirement of mailing if sent in
accordance with the procedures. If the department maintains a record of the
recipient viewing the notice or communication, the record creates a presumption
of receipt by the taxpayer and is prima facie proof that the notice or
communication was received by the taxpayer.
(3) For
purposes of this section, the term "taxpayer" includes the agent or
personal representative of the estate of the taxpayer.
Source:
L. 96: Entire
section added, p. 164, § 3, effective July 1. L. 2014: Entire section
amended, (HB 14-1107), ch. 134, p. 464, § 1, effective April 25.
39-21-106. Compromise.
(1) The
executive director or the executive director's delegate may compromise any
civil or criminal case arising under any tax or charge administered pursuant to
this article 21 prior to reference to the department of law for prosecution or
defense; and the attorney general or the attorney general's delegate shall,
upon the written direction of the executive director, compromise any such case
after reference to the department of law for prosecution or defense.
(2)
Whenever a compromise of two thousand five hundred dollars or more is made by
the executive director or his delegate in any case, there shall be placed on
file in the office of the executive director or his delegate the opinion of the
director with his reasons therefor, which may include financial inability of
the taxpayer to pay a greater amount, with a statement of:
(a) The
amount of tax assessed;
(b) The
amount of interest, additional amount, addition to the tax, or assessable
penalty imposed by law on the person against whom the tax is assessed; and
(c) The
amount paid in accordance with the terms of the compromise.
(3)
Notwithstanding the provisions of subsection (2) of this section, no such
opinion shall be required with respect to the compromise of any civil case in
which the unpaid amount of tax assessed, including any interest, additional
amount, addition to the tax, or assessable penalty, is less than two thousand
five hundred dollars.
Source:
L. 65: p. 1135, §
2. C.R.S. 1963: § 138-9-5. L. 72: p. 621, § 165. L. 77:
(1) amended, p. 842, § 5, effective July 1; (1) amended, pp. 1766, 1852, §§ 3,
5, effective January 1, 1978. L. 79: (1) amended, p. 1499, § 22,
effective January 1, 1980. L. 86: (1) amended, p. 1110, § 5, effective
July 1. L. 89: (1) amended, p. 1594, § 6, effective July 1, 1993. L.
90: (1) amended, p. 1722, § 5, effective May 1; (1) amended, p. 1722, § 6,
effective July 1, 1993. L. 2001: (1) amended, p. 778, § 9, effective June
1. L. 2009: (1) amended, (HB 09-1053), ch. 159, p. 689, § 12, effective
August 5. L. 2024: (1) amended, (HB 24-1349), ch. 423, p. 2902, § 9,
effective December 17 (see editor's note).
Editor's
note: (1)
Amendments to subsection (1) by House Bill 77-1076, Senate Bill 77-100, and
Senate Bill 77-144 were harmonized.
(2) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
39-21-107. Limitations.
(1)
Except as provided in this section, section 29-2-208 (2)(a)(III), and section
29-2-302 (5)(b), and unless such time is extended by waiver, the amount of any
tax or of any charge on oil and gas production, and the penalty and interest
applicable to the tax or charge, shall be assessed within three years after the
return was filed, whether or not such return was filed on or after the date
prescribed, and no assessment shall be made or credit taken and no notice of
lien shall be filed, nor distraint warrant issued, nor suit for collection
instituted, nor any other action to collect the same commenced after the
expiration of such period; except that a written proposed adjustment of the tax
liability by the department issued prior to the expiration of such period shall
extend the limitation of this subsection (1) for one year after a final
determination or assessment is made. No lien shall continue after the
three-year period provided for in this subsection (1), except for taxes
assessed before the expiration of such period, notice of lien with respect to
which has been filed prior to the expiration of such period, and except for
taxes on which written notice of any proposed adjustment of the tax liability
has been sent to the taxpayer during such three-year period, in which case the
lien shall continue for one year only after the expiration of such period or
after the issuance of a final determination or assessment based on the proposed
adjustment issued prior to the expiration of the three-year period. This
subsection (1) does not apply to income tax or to any tax imposed under article
23.5 of this title 39.
(2) In
the case of an income tax imposed by article 22 of this title 39, unless such
time is extended by waiver and except as provided in subsection (2.5) of this
section, section 39-22-601 (6)(e), and section 39-22-601.5, the assessment of
any tax, penalties, and interest shall be made within one year after the
expiration of the time provided for assessing a deficiency in federal income
tax or changing the reported federal taxable income of a partnership, limited
liability company, or fiduciary; except that a written proposed adjustment of
the tax liability by the department must extend the limitation of this
subsection (2) for one year after a final determination or assessment is made.
An assessment of income taxes having been made according to law must be good
and valid and collection thereof may be enforced at any time within six years
from the date of said assessment.
(2.5)
Any limitations applicable to taxes, penalties, interest, fines, or charges
within the scope of this article 21, as set forth in section 39-21-102, are
suspended:
(a) For
any period during which the taxpayer's assets are in the control or custody of
a court in any proceeding before any court of the United States or any state,
and for six months thereafter; or
(b) For
any period during which the department is prohibited from collecting by reason
of a case under title 11 of the United States Code, and for six months
thereafter.
(3) For
purposes of this section, a tax return filed before the last day prescribed by
law or by regulation promulgated pursuant to law for the filing thereof shall
be considered as filed on such last day.
(4) In
the case of failure to file a return or the filing of a false or fraudulent
return with intent to evade tax, the tax may be assessed and collected at any
time.
(5)
Where, before the expiration of the time prescribed in this section for the
assessment of tax, both the executive director of the department of revenue or
his delegate and the taxpayer have consented in writing to an assessment after
such time, the tax may be assessed at any time prior to the expiration of the
period agreed upon. The period so agreed upon may be extended by subsequent
agreements in writing made before the expiration of the period previously
agreed upon.
(6)
Nothing in this section shall be construed to limit any right accrued or revive
any liability barred by any statute enacted on or before July 1, 1965.
Source:
L. 65: p. 1136, §
2. C.R.S. 1963: § 138-9-6. L. 73: p. 1417, § 102. L. 77:
(2) amended, p. 1770, § 1, effective May 18; (1) amended, pp. 1767, 1853, §§ 4,
6, effective January 1, 1978. L. 79: (1) amended, p. 1500, § 23,
effective January 1, 1980. L. 83: (1) and (2) amended, p. 1510, § 1,
effective May 26. L. 86: (1) amended, p. 1110, § 6, effective July 1. L.
89: (1) amended, p. 1594, § 7, effective July 1, 1993. L. 90: (2)
amended, p. 450, § 29, effective April 18; (1) amended, p. 1722, § 7, effective
May 1; (1) amended, p. 1723, § 8, effective July 1, 1993. L. 92: (1)
amended, p. 2247, § 1, effective July 1. L. 2001: (1) amended, p. 778, §
10, effective June 1. L. 2002: (1) amended, p. 1361, § 16, effective
July 1. L. 2009: (1) amended, (HB 09-1053), ch. 159, p. 690, § 13,
effective August 5. L. 2017: (1) amended, (SB 17-112), ch. 144, p. 483,
§ 3, effective April 18. L. 2019: (2) amended and (2.5) added, (SB
19-035), ch. 64, p. 230, § 1, effective August 2. L. 2023: (2) amended,
(SB 23-1277), ch. 290, p. 1754, § 4, effective August 7. L. 2024: (1)
amended, (SB 24-230), ch. 184, p. 1023, § 8, effective May 16; (1) amended, (SB
24-025), ch. 144, p. 579, § 39, effective July 1, 2025; (1) amended, (HB
24-1349), ch. 423, p. 2902, § 10, effective (see editor's note).
Editor's
note: (1)
Amendments to subsection (1) by Senate Bill 77-144 and House Bill 77-1076 were
harmonized.
(2) Amendments to subsection
(1) by SB 24-025 and SB 24-230 were harmonized, effective July 1, 2025.
(3) Subsection (1) was amended
in HB 24-1349, which was to take effect only if a majority of voters approved
the ballot issue referred in accordance with § 39-37-201. However, those
amendments in HB 24-1349 were superseded by the amendment of subsection (1) in
SB 24-230, effective May 16, 2024.
ANNOTATION
Law reviews. For
article, "Taxation", see 32 Dicta 418 (1955).
Section applicable where use
taxes assessed, no return filed. It is the intent of the general assembly
that this section, rather than § 39-26-210, should be the controlling statute
of limitations where use taxes are assessed but no return is filed. Dye Constr.
Co. v. Dolan, 41 Colo. App. 293, 589 P.2d 497 (1978).
The limitation period under
subsection (2) is four years. Pursuant to subsection (3), the limitation
period commences on the entirety of a conservation easement credit on April 15
of the calendar year following the tax year for which the credit was first
claimed. Markus v. Brohl, 2014 COA 146, 412 P.3d 647.
Previously barred
liabilities not revived. The general assembly intended to provide that
liabilities which had already been barred by other statutory provisions on the
date when this section became effective were not revived by subsection (6). Dye
Constr. Co. v. Dolan, 41 Colo. App. 293, 589 P.2d 497 (1978).
Applied in CF&I
Steel Corp. v. Charnes, 637 P.2d 324 (Colo. 1981); Kraftco Corp. v. Charnes,
636 P.2d 1300 (Colo. App. 1981).
39-21-108. Refunds.
(1) (a)
(I) In the case of income tax imposed by article 22 of this title 39, except
as provided in section 39-22-601.5, the taxpayer must file any claim for refund
or credit for any year not later than the period provided for filing a claim
for refund of federal income tax plus one year. The department shall not pay
any refund for which the claim is filed later than the period provided for the
payment of a refund of federal income tax plus one year. However, no refund or
credit of income tax may be made to any taxpayer who fails to file a return
pursuant to section 39-22-601 within four years from the date the return was
required to be filed. Except in the case of failure to file a return or the
filing of a false or fraudulent return with intent to evade tax and otherwise
notwithstanding any provision of law, the statute of limitations relating to
claims for refund or credit for any year shall not expire prior to the
expiration of the time within which a deficiency for such year could be
assessed.
(II) In
the case of the charge on oil and gas production imposed by article 60 of title
34, the production fee for clean transit imposed by section 43-4-1204, the
production fee for wildlife and land remediation imposed by section 33-61-103,
the passenger-mile tax imposed by article 3 of title 42, and the severance tax
imposed by article 29 of this title 39, the payer shall file any claim for
refund or credit for any period not later than three years after the date of
payment.
(III)
Claims for refund of other taxes covered by this article 21 must be made within
the time limits expressly provided for the specific taxes involved. This
subsection (1) does not apply to sales and use taxes.
(b)
Repealed.
(c)
Except as provided in section 39-21-105, no suit for refund may be commenced.
(2) If
the executive director discovers from the examination of a return within the
time periods provided for the filing of refunds, or upon claim duly filed by
the taxpayer, or upon final judgment of a court that the tax, penalty, or
interest paid by any taxpayer is in excess of the amount due or has been
illegally or erroneously collected, then the executive director shall issue in
favor of the taxpayer his voucher to the controller for the refund of such
illegally collected tax, penalty, or interest, regardless of whether or not
such sum was paid under protest, together with interest provided in section
39-21-110. Upon receipt of such voucher properly executed and endorsed, the
controller shall issue his warrant for the payment to the taxpayer out of the
reserve provided therefor; but the controller shall keep in his files a
duplicate of said voucher and also a statement which shall set forth the reason
why such refund has been ordered.
(3) (a)
(I) (A) Whenever it is established that any taxpayer has, for any period
open under the statutes, overpaid a tax administered pursuant to this article
21 or that any taxpayer is allowed a refund pursuant to part 20 of article 22
of this title 39 and that: There is an unpaid balance of tax and interest
accrued, according to the records of the executive director, owing by such
taxpayer for any other period; there is an amount required to be repaid to the
unemployment compensation fund pursuant to section 8-81-101 (4), the amount of
which has been determined to be owing as a result of a final agency
determination or judicial decision or that has been reduced to judgment by the
division of unemployment insurance in the department of labor and employment;
there is any unpaid child support debt as set forth in section 14-14-104, or
child support arrearages that are the subject of enforcement services provided
pursuant to section 26-13-106, as certified by the department of human
services; there are any unpaid obligations owing to the state as set forth in
section 26-2-133, for overpayment of public assistance or medical assistance
benefits, the amount of which has been determined to be owing as a result of
final agency determination or judicial decision or that has been reduced to
judgment, as certified by the department of human services; there are any
unpaid obligations owing to the state as set forth in section 26.5-4-119, for
overpayment of child care assistance, the amount of which has been determined
to be owing as a result of final agency determination or judicial decision or
that has been reduced to judgment as certified by the department of early
childhood; there is any unpaid loan or other obligation due to a
state-supported institution of higher education as set forth in section
23-5-115, the amount of which has been determined to be owing as a result of a
final agency determination or judicial decision or that has been reduced to
judgment, as certified by the appropriate institution; there is any unpaid loan
due to the student loan division of the department of higher education as set
forth in section 23-3.1-104 (1)(p), the amount of which has been determined to
be owing as a result of a final agency determination or judicial decision or
that has been reduced to judgment, as certified by the division; there is any
unpaid loan due to the collegeinvest division of the department of higher
education as set forth in section 23-3.1-206, the amount of which has been
determined to be owing as a result of a final agency determination or judicial
decision or that has been reduced to judgment; there is any outstanding
judicial fine, fee, cost, or surcharge as set forth in section 16-11-101.8, or
judicial restitution as set forth in section 16-18.5-106.8, the amount of which
has been determined to be owing as a result of a final judicial department
determination or certified by the judicial department as a judgment owed the
state or a victim; or there is any unpaid debt owing to the state or any agency
thereof by such taxpayer, and that is found to be owing as a result of a final
agency determination or the amount of which has been reduced to judgment and as
certified by the state agency, so much of the overpayment of tax plus interest
allowable thereon as does not exceed the amount of such unpaid balance or
unpaid debt must be credited first to the unpaid balance of tax and interest
accrued and then to the unpaid debt, and any excess of the overpayment must be
refunded. If the taxpayer elects to designate the taxpayer's refund as a credit
against a subsequent year's tax liability, the amount allowed to be so credited
must be reduced first by the unpaid balance of tax and interest accrued and
then by the unpaid debt. If the taxpayer filed a joint return, the executive
director shall notify the other taxpayer named on the joint return that the
portion of the overpayment that is generated by the other taxpayer's income
will be refunded upon receipt of a request detailing said amount.
(B)
With respect to debts for any unpaid loan or other obligation due to a
state-supported institution of higher education as set forth in section
23-5-115, C.R.S., or any unpaid loan due to the student loan division of the
department of higher education as set forth in section 23-3.1-104 (1)(p),
C.R.S., or any unpaid loan due to the collegeinvest division of the department
of higher education as set forth in section 23-3.1-206, C.R.S., a debtor must
be afforded his or her due process rights prior to a final agency
determination.
(II)
Any moneys withheld for payment of an unemployment compensation benefit debt
pursuant to this subsection (3) shall be deposited with the state treasurer and
credited to the unemployment compensation fund. For persons required to repay
benefit overpayments in accordance with section 8-81-101 (4)(a), C.R.S., the
executive director of the department of revenue shall provide to said division
the taxpayers' names and associated amounts deposited with the state treasurer.
(III)
Any moneys withheld for payment of a child support debt or child support
arrearages pursuant to this subsection (3) shall be deposited in the family
support registry created pursuant to section 26-13-114, C.R.S., for
disbursement by the department of human services. For all names and amounts
certified by the department of human services pursuant to section 26-13-111,
C.R.S., the executive director of the department of revenue shall provide to
the department of human services the taxpayers' names and associated amounts
deposited with the state treasurer and any other identifying information as
required by the department of human services.
(IV)
Any moneys withheld for payment of an institution of higher education debt
pursuant to this subsection (3) shall be deposited with the state treasurer for
disbursement by the state treasurer to the appropriate institution. For each
person whose name and amount is certified by the appropriate institution
pursuant to section 23-5-115, C.R.S., the executive director of the department
of revenue shall provide to the appropriate institution the name, address, and
social security number or federal employer identification number, whichever is
applicable, of the taxpayer whose refund is being offset, the amount of the
offset, and any other identifying information as required by the institution.
(V) Any
money withheld for payment of an unpaid debt owing to the state pursuant to
this subsection (3) shall be deposited with the state treasurer for
disbursement by the controller. For each person whose name and amount is
certified by a state agency pursuant to section 24-30-202.4, the executive
director of the department of revenue shall provide to the controller the name,
address, and social security number or federal employer identification number,
whichever is applicable, of the taxpayer whose refund is being offset, the
amount of the offset, and any other identifying information as required by the
controller.
(VI)
Any moneys withheld for payment of a student loan division debt pursuant to
this subsection (3) shall be deposited with the state treasurer for
disbursement by the state treasurer to the division. For each person whose name
and amount is certified by the division pursuant to section 23-3.1-104 (1)(p),
C.R.S., the executive director of the department of revenue shall provide to
the division the name, address, and social security number or federal employer
identification number, whichever is applicable, of the taxpayer whose refund is
being offset, the amount of the offset, and any other identifying information
as required by the division.
(VII)
(A) Money withheld for payment of obligations owed the department of human
services for overpayment of public assistance benefits pursuant to this
subsection (3) must be deposited with the state treasurer for disbursement by
the department of human services. For all names and associated amounts
certified by the department of human services pursuant to section 26-2-133, the
executive director of the department of revenue shall provide to the department
of human services the names of taxpayers and the associated amounts deposited
with the state treasurer and any other identifying information as required by
the department of human services.
(B)
Money withheld for payment of obligations owed the department of health care
policy and financing for overpayment of public assistance benefits paid
pursuant to this subsection (3) must be deposited with the state treasurer for
disbursement by the department of health care policy and financing. For all
names and associated amounts certified by the department of health care policy
and financing pursuant to section 25.5-1-139, the executive director of the
department of revenue shall provide to the department of health care policy and
financing the names of taxpayers and the associated amounts deposited with the
state treasurer and any other identifying information required by the
department of health care policy and financing.
(VIII)
Any moneys withheld for payment of an obligation certified by the judicial
department pursuant to section 16-11-101.8 or 16-18.5-106.8, C.R.S., shall be
transferred to the judicial department. At the time of the offset, the
executive director shall notify the taxpayer of the offset and shall provide to
the judicial department the name, address, and social security number or
federal employer identification number, whichever is applicable, of the
taxpayer whose refund is being offset, the amount of the offset, and any other
identifying information as required by the judicial department.
(IX)
Any money withheld for payment of obligations owed to the department of early
childhood for overpayment of child care assistance benefits pursuant to this
subsection (3) shall be deposited with the state treasurer for disbursement by
the department of early childhood. For all names and associated amounts
certified by the department of early childhood pursuant to section 26.5-4-119,
the executive director of the department of revenue shall provide to the
department of early childhood the names of taxpayers and the associated amounts
deposited with the state treasurer and any other identifying information as
required by the department of early childhood.
(b) In
the event there are debts for overpayments of unemployment insurance pursuant
to section 8-81-101 (4), debts for unpaid child support, as set forth in
section 26-13-111, debts for overpayment of public assistance or medical
assistance benefits, as set forth in section 26-2-133, debts for overpayment of
child care assistance, as set forth in section 26.5-4-119, debts for any unpaid
loan or other obligation due to a state-supported institution of higher
education, as set forth in section 23-5-115, debts for any unpaid loan due to
the student loan division of the department of higher education, as set forth
in section 23-3.1-104 (1)(p), any amounts owed for judicial fines, fees, costs,
or surcharges, as set forth in section 16-11-101.8, any amounts owed for
judicial restitution, as set forth in section 16-18.5-106.8, and other unpaid
debts owing to the state or any agency thereof, as set forth in this subsection
(3), then credit to the unpaid debts shall be prorated on the basis of the
ratio of the amount of each such unpaid debt as compared to the total amount of
unpaid debts.
(4)
Notwithstanding the provisions of subsection (1) of this section, in the case
of the severance tax imposed by article 29 of this title, when an increase in
the value of any product is subject to the approval or affected by the actions
of any agency of the United States, or the state of Colorado, or any court, the
increased value shall be subject to this tax. In the event that the increase in
value is disapproved or reduced as the direct or indirect result of the actions
of any agency of the United States, the state of Colorado, or any court, either
in whole or in part, then the amount of tax which has been paid on the
disapproved or reduced part of the value shall be considered excess tax. Within
one year following the final determination of value, any person who has paid
any such excess tax may apply for a refund, and the executive director, upon
proper finding, shall have the authority and duty to refund the amount of
excess tax paid. Any refund may, at the discretion of the executive director, be
made in the form of a credit against future tax payments.
(5) (a)
On and after October 1, 2002, any warrant representing a refund of income tax
imposed by article 22 of this title 39 or a grant for property taxes, rent, or
heat or fuel expenses assistance allowed by article 31 of this title 39 that is
not presented for payment within six months from its date of issuance shall be
void. On and after October 1, 2002, upon the cancellation of a warrant in
accordance with the standard operating procedures of the department or the
state controller, the department shall forward to the state treasurer the name
of the taxpayer as it appears on the warrant, the taxpayer identification
number, the taxpayer's last-known address, the amount of the canceled warrant,
and an amount of money equal to the amount specified in the warrant so that the
state treasurer may make the refund pursuant to the "Revised Uniform
Unclaimed Property Act", article 13 of title 38.
(b) The
department may reclaim from the unclaimed property fund and credit to the
appropriate state revenue fund any amount forwarded by the department to the
state treasurer pursuant to paragraph (a) of this subsection (5) that was based
on a warrant representing an erroneous refund or grant. If the state treasurer
issued an erroneous refund or grant to the person named on the warrant, the
treasurer shall provide proof of that payment to the department and the
department may assess that amount pursuant to section 39-21-103 (1).
(6)
Repealed.
(7) (a)
On and after October 1, 2010, any warrant representing a refund issued by the
department, excluding refunds addressed by subsection (5) of this section, that
is not presented for payment within six months from its date of issuance shall
be void. On and after October 1, 2010, upon the cancellation of a warrant in
accordance with the standard operating procedures of the department or the
state controller, the department shall forward to the state treasurer the name
of the taxpayer as it appears on the warrant, the taxpayer identification
number, the taxpayer's last-known address, the amount of the canceled warrant,
and an amount of money equal to the amount specified in the warrant so that the
state treasurer may make the refund pursuant to the "Revised Uniform
Unclaimed Property Act", article 13 of title 38.
(b) The
department may reclaim from the unclaimed property fund and credit to the
appropriate state revenue fund any amount forwarded by the department to the
state treasurer pursuant to paragraph (a) of this subsection (7) that was based
on a warrant representing an erroneous refund or grant. If the state treasurer
issued an erroneous refund or grant to the person named on the warrant, the
treasurer shall provide proof of that payment to the department, and the
department may assess that amount pursuant to section 39-21-103 (1).
Source:
L. 65: p. 1137, §
2. C.R.S. 1963: § 138-9-7. L. 67: pp. 847, 848, §§ 1, 2. L.
71: p. 1265, § 1. L. 77: (1)(a) amended and (4) added, pp. 1767,
1853, §§ 5, 7, effective January 1, 1978. L. 82: (3) amended, p. 558, §
1, effective April 6. L. 83: (3) amended, p. 794, § 5, effective June 3;
(3) amended, p. 654, § 2, effective June 10; (3) amended, p. 438, § 2,
effective June 15. L. 84: (3)(a) amended and (3)(b)(IV) added, pp. 1008,
1010, §§ 3, 4, effective March 29; (3) amended, p. 1011, § 1, effective April
27; (3)(b)(IV) repealed and (3)(b) amended, pp. 1125, 1126, §§ 47, 48,
effective June 7. L. 85: (3)(a)(I), (3)(a)(VI), and (3)(b) amended, p.
1366, § 39, effective June 28; (3)(a)(I), (3)(a)(III), and (3)(b) amended, p.
602, § 22, effective July 1. L. 88: (3)(a)(I) amended, p. 637, § 19,
effective July 1. L. 89: (3)(a)(I) and (3)(b) amended and (3)(a)(VII)
added, p. 1195, § 4, effective June 7; (3)(a)(I) amended, p. 799, § 34,
effective July 1; (1)(a) amended, p. 1595, § 8, effective July 1, 1993. L. 94:
(3)(a)(I), (3)(a)(III), and (3)(a)(VII) amended, p. 3135, § 299, effective July
1. L. 96: (1)(a) amended, p. 164, § 4, effective July 1. L. 98:
(3)(a)(II) amended, p. 91, § 5, effective March 23. L. 98, 2nd Ex. Sess.:
(3)(a)(I) amended, p. 7, § 4, effective September 16. L. 99: (3)(a)(I)
amended, p. 1317, § 5, effective August 4. L. 2001: (1)(a) and (3)(a)(I)
amended, p. 778, § 11, effective June 1; (1)(a) amended, p. 233, § 2, effective
August 8; (5) added, p. 619, § 4, effective August 8. L. 2002: (3)(a)(I)
amended, p. 99, § 1, effective August 7. L. 2004: (1)(a) amended, p.
383, § 2, effective April 8; (3)(a)(I) amended, p. 576, § 35, effective July 1;
(1)(b) repealed, p. 207, § 31, effective August 4; (3)(a)(I)(A) and (3)(b)
amended and (3)(a)(VIII) added, p. 1259, § 4, effective August 4; (6) added, p.
315, § 3, effective August 4. L. 2009: (1)(a) and (3)(a)(I)(A) amended,
(HB 09-1053), ch. 159, p. 690, § 14, effective August 5; (3)(a)(III),
(3)(a)(IV), (3)(a)(V), and (3)(a)(VI) amended, (HB 09-1137), ch. 308, p. 1662,
§ 14, effective September 1. L. 2010: (6) repealed, (SB 10-212), ch.
412, p. 2032, § 1, effective July 1; (7) added, (SB 10-186), ch. 309, p. 1454,
§ 1, effective August 11. L. 2011: (1)(a) amended, (HB 11-1303), ch.
264, p. 1175, § 91, effective August 10. L. 2012: (3)(a)(I)(A) amended,
(HB 12-1120), ch. 27, p. 112, § 31, effective June 1. L. 2013:
(3)(a)(I)(A) amended, (SB 13-247), ch. 296, p. 1584, § 4, effective August 7. L.
2014: (3)(a)(I)(A) amended, (SB 14-019), ch. 10, p. 96, § 2, effective
February 27. L. 2019: (5)(a) and (7)(a) amended, (SB 19-088), ch. 110,
p. 470, § 18, effective July 1, 2020. L. 2021: (3)(a)(I)(A) and
(3)(a)(V) amended, (SB 21-055), ch. 12, p. 78, § 15, effective March 21. L.
2022: (3)(a)(I)(A) and (3)(b) amended and (3)(a)(IX) added, (HB 22-1295),
ch. 123, p. 866, § 127, effective July 1. L. 2023: (1)(a) amended, (HB
23-1277), ch. 290, p. 1754, § 5, effective August 7. L. 2024:
(3)(a)(I)(A) amended, (SB 24-228), ch. 170, p. 899, § 8, effective May 14;
(1)(a) amended and (1)(c) added, (SB 24-230), ch. 184, p. 1024, § 9, effective
May 16; (3)(a)(I)(A) amended, (HB 24-1349), ch. 423, p. 2903, § 11, effective
December 17 (see editor's note). L. 2026: (3)(a)(VII) amended, (HB
26-1429), ch. 374, p. 2321, § 22, effective June 4.
Editor's
note: (1)
Amendments to subsection (1)(a) by House Bill 77-1076 and Senate Bill 77-144
were harmonized.
(2) Amendments to subsection
(3) by Senate Bill 83-107 and Senate Bill 83-296 harmonized with House Bill
83-1445.
(3) Amendments to subsection
(3) by Senate Bill 84-171 and Senate Bill 84-32 were harmonized.
(4) Amendments to subsection
(3)(a)(I) and (3)(b) by Senate Bill 85-170 and House Bill 85-1380 were
harmonized.
(5) Amendments to subsection
(3)(a)(I) by House Bill 89-1180 and Senate Bill 89-153 were harmonized.
(6) Amendments to subsection
(1)(a) by Senate Bill 01-125 and House Bill 01-1304 were harmonized.
(7) Amendments to subsection
(3)(a)(I)(A) by House Bill 04-1350 and Senate Bill 04-253 were harmonized.
(8) The effective date for
amendments to subsection (3)(a)(I)(A) by House Bill 12-1120 (chapter 27,
Session Laws of Colorado 2012) was changed from August 8, 2012, to June 1,
2012, by House Bill 12S-1002 (First Extraordinary Session, chapter 2, p. 2432,
Session Laws of Colorado 2012.)
(9) Section 9 of chapter 10 (SB
14-019), Session Laws of Colorado 2014, provides that changes to this section
by the act apply to income tax years commencing on or after January 1, 2013,
and any other income tax years that are open under § 39-21-107 or 39-21-108.
(10) Amendments to subsection
(3)(a)(I)(A) by HB 24-1349 and SB 24-228 were harmonized, effective on the date
of the official declaration of the vote thereon by the governor only if, at the
November 2024 statewide election, a majority of voters approve the ballot issue
referred in accordance with § 39-37-201. The ballot issue, referred to the
voters as Proposition KK, was approved on November 5, 2024, and was proclaimed
by the Governor on December 17, 2024, see L. 2025, p. 3636. The vote count for
the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
(11) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: For
the legislative declaration contained in the 2001 act amending subsection
(1)(a), see section 1 of chapter 95, Session Laws of Colorado 2001. For the
legislative declaration in HB 26-1429, see section 1 of chapter 374, Session
Laws of Colorado 2026.
ANNOTATION
Law reviews. For
article, "Taxation", which discusses Tenth Circuit decisions dealing
with interception of tax refunds for reimbursement of state child support, see
63 Den. U. L. Rev. 455 (1986).
Trial court erred in
allowing state department of revenue to determine the form of the remedy for
collecting an unconstitutional tax. It is the obligation of the trial
court, after declaring the collected tax unconstitutional, to provide it with a
remedy. Buckley Powder Co. v. State, 924 P.2d 1133 (Colo. App. 1996), aff'd in
part, rev'd in part on other grounds, 945 P.2d 841 (Colo. 1997).
Issue of whether the state's
offset of tax refunds against debts to the state was illegal did not involve
statutory interpretation. Initially, it would have required resolution of
the factual issue of whether the debts had been reduced to judgment pursuant to
subsection (3)(a)(I). This factual determination is within the ambit of the
administrator in the hearing. Kendal v. Cason, 791 P.2d 1227 (Colo. App. 1990).
Subsection (2) provides for
a refund of all taxes overpayed by military retirees as a result of § 39-22-104
(4)(g) (now repealed) which was found to be unconstitutional. Kuhn v. State
Dept. of Rev., 817 P.2d 101 (Colo. 1991).
Subsection (1)(a)
effectively creates a four-year statute of repose. When read in combination
with the applicable federal statute, the result is that no taxpayer may seek a
refund of taxes in Colorado that were paid more than four years prior to the
filing of a claim for a refund. Kuhn v. State Dept. of Rev., 897 P.2d 792
(Colo. 1995).
"Discovery rule"
inapplicable. Unlike the usual type of statutory limitation period, which
begins to run when the plaintiff knows or should have known of both the injury
and its cause, subsection (1)(a) bars a claim after the specified period
regardless of the date on which the claimant discovers the error or omission
that gave rise to the claim. Kuhn v. State Dept. of Rev., 897 P.2d 792 (Colo.
1995).
39-21-109. Interest on underpayment,
nonpayment, or extensions of time for payment of tax.
(1) If
any tax or charge administered pursuant to this article 21 is not paid on or
before the last date prescribed for payment, interest on such amount at the
rate imposed under section 39-21-110.5, except as provided in subsection (1.5)
of this section, shall be paid for the period from such last date to the date
paid. The last date prescribed for payment shall be determined without regard
to any extension of time for payment and shall be determined without regard to
any notice and demand for payment issued, by reason of jeopardy, prior to the
last date otherwise prescribed for such payment. In the case of a tax in which
the last date for payment is not otherwise prescribed, the last date for
payment shall be deemed to be the date the liability for the tax arises, and in
no event shall it be later than the date notice and demand for the tax is made
by the executive director of the department of revenue or the executive
director's delegate.
(1.5)
If payment of or an agreement to pay the amount of any tax described in
subsection (1) of this section is made within thirty days of notice of
underpayment, nonpayment, or extension of time, the executive director shall
waive the imposition of the three points in excess of the prime rate described
in section 39-21-110.5 (2) on such amount unless the executive director
determines that there has been a willful neglect or failure to pay such tax.
(2)
Interest prescribed under this section shall be paid upon notice and demand and
shall be assessed, collected, and paid in the same manner as the tax to which
it is applicable.
(3) If
any portion of a tax is satisfied by credit of an overpayment, then no interest
shall be imposed under this section on the portion of the tax so satisfied for
any period during which, if the credit had not been made, interest would have
been allowed with respect to such overpayment.
(4)
Interest prescribed under this section on any tax may be assessed and collected
at any time during the period within which the tax to which such interest
relates may be assessed and collected.
(5)
This section shall not apply to any failure to pay estimated Colorado income
tax.
Source:
L. 65: p. 1138, §
2. C.R.S. 1963: § 138-9-8. L. 73: p. 1418, § 103. L. 77:
(1) amended, pp. 1768, 1854, §§ 6, 8, effective January 1, 1978. L. 79:
(1) amended, p. 1500, § 24, effective January 1, 1980. L. 81: (1)
amended, p. 1863, § 2, effective June 8. L. 86: (1) amended, p. 1111, §
7, effective July 1. L. 89: (1) amended, p. 1595, § 9, effective July 1,
1993. L. 90: (1) amended and (1.5) added, p. 1728, § 2, effective April
5; (1) amended, p. 1723, § 9, effective May 1; (1) amended, pp. 1729, 1724, §§
3, 10, effective July 1, 1993. L. 2024: (1) amended, (HB 24-1349), ch.
423, p. 2904, § 12, effective December 17 (see editor's note).
Editor's
note: (1)
Amendments to subsection (1) by Senate Bill 77-144 and House Bill 77-1076 were
harmonized.
(2) Amendments to subsection
(1) by House Bill 90-1176 and House Bill 90-1258 were harmonized.
(3) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
ANNOTATION
Law reviews. For
article, "Collecting Pre- and Post-Judgment Interest in Colorado: A
Primer", see 15 Colo. Law. 753 (1986). For article, "An Update of
Appendices from Collecting Pre- and Post-Judgment Interest in Colorado",
see 15 Colo. Law. 990 (1986).
Revocation of permission to
remit sales tax on a cash receipt basis is not a notice of deficiency, and
assessment of tax does not on its own create a tax liability. Montgomery Ward
& Co. v. Dept. of Rev., 675 P.2d 318 (Colo. App. 1983).
A determination that sales tax
on credit sales should be remitted on a "sales" or accrual basis,
rather than on a cash receipt basis, is not a notice of deficiency creating
liability under this section. Montgomery Ward & Co. v. Dept. of Rev., 675
P.2d 318 (Colo. App. 1983).
Applied in Western Elec.
Co. v. Weed Jr., 185 Colo. 340, 524 P.2d 1369 (1974); Dye Constr. Co. v. Dolan,
41 Colo. App. 293, 589 P.2d 497 (1978).
39-21-110. Interest on overpayments -
repeal.
(1)
Interest shall be allowed and paid upon any overpayment in respect to any tax
or charge administered pursuant to this article 21 at the rate imposed under
section 39-21-110.5. Such interest shall be allowed and paid as follows:
(a) In
the case of a credit, from the date of the overpayment to the due date of the
amount against which the credit is taken;
(b)
Except as provided in subsection (1)(c) of this section, in the case of a
refund, from the date of the overpayment to a date, to be determined by the
executive director of the department of revenue or their delegate, preceding
the date of the refund by not more than thirty days, whether or not such refund
is accepted by the taxpayer after tender of such refund to the taxpayer. The
acceptance of such refund shall be without prejudice to any right of the
taxpayer to claim any additional overpayment and interest thereon; or
(c) (I)
In the case of a refund claim made by a purchaser for sales or use tax paid to
a vendor under section 39-26-703 (2) on or after July 1, 2022, but before July
1, 2026, from the date that the claim for refund was filed to a date, to be
determined by the executive director of the department of revenue or their
delegate, preceding the date of the refund by not more than thirty days,
whether or not such refund is accepted by the taxpayer after tender of such
refund to the taxpayer, but only if the date of the refund is more than one
hundred eighty days from the date the claim for refund was filed. The
acceptance of such refund shall be without prejudice to any right of the
purchaser to claim any additional overpayment and interest thereon.
(II)
This subsection (1)(c) is repealed, effective July 1, 2030.
(1.5)
Notwithstanding any other provision of this section to the contrary, a payment
not made incident to a bona fide and orderly discharge of an actual liability
or a liability reasonably assumed to be imposed by law is not an overpayment
for the purposes of this section only, and interest is not payable on the
payment. For purposes of this subsection (1.5), the following burdens of proof
shall apply:
(a) If
a taxpayer's total payments are less than or equal to twice the amount of the
actual tax liability, then the department shall bear the burden of proving, by
a preponderance of the evidence, that such payments were not made incident to a
bona fide and orderly discharge of an actual liability or a liability
reasonably assumed to be imposed by law; and
(b) If
a taxpayer's total payments are more than twice the amount of the actual tax
liability, then the taxpayer shall bear the burden of proving, by a
preponderance of the evidence, that such payments were made incident to a bona
fide and orderly discharge of an actual liability or a liability reasonably
assumed to be imposed by law.
(2) Any
portion of any tax or charge administered pursuant to this article 21 or any
interest, assessable penalty, additional amount, or addition to a tax or charge
which has been erroneously refunded shall bear interest at the rate imposed
under section 39-21-110.5 from the date of the payment of the refund.
(3) If
any overpayment of any tax or charge administered pursuant to this article 21
is refunded within ninety days after the last date prescribed for filing the
return of such tax or charge, determined without regard to any extension of
time for filing the return, no interest shall be allowed under subsection (1)
of this section on such overpayment.
(4) If
the amount of any income tax is reduced by reason of a carry-back of a net
operating loss, such reduction in tax shall not affect the computation of
interest under this section for the period ending with the last day of the
taxable year in which the net operating loss arises. If any overpayment of
income tax results from a carry-back of a net operating loss, such overpayment
shall be deemed not to have been made prior to the close of the taxable year in
which such net operating loss arises.
Source:
L. 65: p. 1139, §
2. C.R.S. 1963: § 138-9-9. L. 73: p. 1418, § 104. L. 77:
IP(1), (2), and (3) amended, pp. 1768, 1854, §§ 7, 9, effective January 1,
1978. L. 79: IP(1), (2), and (3) amended, p. 1500, § 25, effective
January 1, 1980. L. 81: IP(1) and (2) amended, p. 1864, § 3, effective
June 8. L. 86: (2) amended, p. 1111, § 8, effective July 1. L. 89:
(2) and (3) amended, p. 1596, § 10, effective July 1, 1993. L. 90:
IP(1), (2), and (3) amended, p. 1724, § 11, effective May 1; IP(1), (2), and
(3) amended, p. 1725, § 12, effective July 1, 1993. L. 2009: (1.5)
added, (HB 09-1219), ch. 71, p. 241, § 1, effective March 25. L. 2022:
IP(1) and (1)(b) amended and (1)(c) added, (HB 22-1118), ch. 110, p. 501, § 1,
effective April 21. L. 2024: IP(1), (2), and (3) amended, (HB 24-1349),
ch. 423, p. 2904, § 13, effective December 17 (see editor's note).
Editor's
note: (1)
Amendments to the introductory portion to subsection (1) and subsections (2)
and (3) by Senate Bill 77-144 and House Bill 77-1076 were harmonized.
(2) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
ANNOTATION
Law reviews. For
article, "Collecting Pre- and Post-Judgment Interest in Colorado: A
Primer", see 15 Colo. Law. 753 (1986). For article, "An Update of
Appendices from Collecting Pre- and Post-Judgment Interest in Colorado",
see 15 Colo. Law. 990 (1986).
Trial court erred in
allowing state department of revenue to determine the form of the remedy for
collecting an unconstitutional tax. It is the obligation of the trial
court, after declaring the collected tax unconstitutional, to provide it with a
remedy. Buckley Powder Co. v. State, 924 P.2d 1133 (Colo. App. 1996), aff'd in
part, rev'd in part on other grounds, 945 P.2d 841 (Colo. 1997).
39-21-110.5. Rate of interest to be
fixed.
(1)
When interest is required or permitted to be charged pursuant to this section
on any underpayment, nonpayment, extension of time for payment, or overpayment,
or when interest is required to be paid pursuant to section 8-20.5-104, in
connection with an application for reimbursement from the petroleum storage
tank fund, such interest shall be computed at the annual rate which has been
established pursuant to this section.
(2)
Except as otherwise provided in subsection (4) of this section, the annual rate
of interest shall be the prime rate, as reported by the "Wall Street
Journal", plus three points, rounded to the nearest full percent. In the
event that more than one rate is so reported, the highest rate shall be
utilized.
(3) The
commissioner of banking shall establish an adjusted annual rate of interest
based upon the computation specified in subsections (2) and (4) of this section
and rounded to the nearest full percent. The adjusted annual rate of interest
shall be so established by the commissioner of banking as of July 2, 1990, to
become effective January 1, 1991. Thereafter, on July 1, or the next succeeding
business day, of each year, the adjusted annual rate of interest shall be
established in the same manner, to become effective on January 1 of the next
succeeding year.
(4) For
refunds issued on or after January 1, 2004, the annual rate of interest
applicable to sections 39-21-110 and 39-22-622 shall be as follows:
(a) If
the amount of the refund is less than five thousand dollars or if the amount of
the refund is equal to or greater than five thousand dollars but less than ten
percent of the taxpayer's net tax liability for the period for which the tax is
paid, the annual rate of interest shall be the prime rate, as reported by the
"Wall Street Journal", plus three points, rounded to the nearest full
percent. In the event that more than one rate is so reported, the highest rate
shall be utilized.
(b) (I)
If the amount of the refund is equal to or greater than five thousand dollars
and the amount of the refund is equal to or greater than ten percent of the
taxpayer's net tax liability for the period for which the tax is paid, the
annual rate of interest shall be the prime rate, as reported by the "Wall
Street Journal", rounded to the nearest full percent, except as provided
in subparagraph (II) of this paragraph (b). In the event that more than one
rate is reported, the highest rate shall be utilized.
(II)
For any refund subject to the provisions of subparagraph (I) of this paragraph
(b), if the taxpayer demonstrates that the overpayment of tax necessitating
such refund was due to good cause as determined by the executive director, the
annual rate of interest shall be the prime rate, as reported by the "Wall
Street Journal", plus three points, rounded to the nearest full percent.
In the event that more than one rate is so reported, the highest rate shall be
utilized.
Source:
L. 81: Entire
section added, p. 1864, § 4, effective June 8. L. 90: (2) and (3)
amended, p. 1728, § 1, effective April 5. L. 95: (1) amended, p. 420, §
11, effective July 1. L. 2003: (2) and (3) amended and (4) added, p.
2360, § 1, effective August 6. L. 2024: (1) amended, (HB 24-1349), ch.
423, p. 2905, § 14, effective December 17 (see editor's note).
Editor's
note: Section
19(1) of chapter 423 (HB 24-1349), Session Laws of Colorado 2024, provides that
the act changing this section takes effect on the date of the official
declaration of the vote thereon by the governor only if, at the November 2024
statewide election, a majority of voters approve the ballot issue referred in
accordance with § 39-37-201. The ballot issue, referred to the voters as
Proposition KK, was approved on November 5, 2024, and was proclaimed by the
Governor on December 17, 2024, see L. 2025, p. 3636. The vote count for the
measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
39-21-111. Jeopardy assessment and
demands.
(1) If
the executive director of the department of revenue finds that collection of
the tax will be jeopardized by delay, in his discretion, he may declare the
taxable period immediately terminated, determine the tax, and issue notice and
demand for payment thereof; and, having done so, the tax shall be due and
payable forthwith, and the executive director may proceed immediately to
collect such tax as provided in section 39-21-114.
(2) In
any other case wherein it appears that the revenue is in jeopardy, the
executive director of the department of revenue may immediately issue demand
for payment; and, regardless of the provisions of sections 39-21-103 and
39-21-105, the tax shall be due and payable forthwith and, in his discretion,
the executive director may proceed immediately to collect said tax as provided
in section 39-21-114.
(3)
Collection under either subsection (1) or (2) of this section may be stayed if
the taxpayer gives such security for payment as shall be satisfactory to the
executive director.
Source:
L. 65: p. 1140, §
2. C.R.S. 1963: § 138-9-10.
ANNOTATION
Section not
unconstitutionally vague. The words "jeopardized" and
"jeopardy", in subsections (1) and (2), respectively, are not
unconstitutionally vague. Kraftco Corp. v. Charnes, 636 P.2d 1300 (Colo. App.
1981).
Subsection (2) can
reasonably be interpreted to apply in those situations in which a notice of
deficiency has been issued. Flores v. Dept. of Rev., 802 P.2d 1175 (Colo.
App. 1990).
Where a jeopardy assessment
has been made without a notice of deficiency and a distraint warrant and
seizure have been pursued under § 39-21-114, the taxpayer has no right to
an administrative hearing under § 39-21-103, but the taxpayer may sue the
executive director of the department in district court under § 39-21-114 (6) or
proceed under § 24-4-106. Flores v. Dept. of Rev., 802 P.2d 1175 (Colo. App.
1990).
39-21-112. Duties and powers of
executive director - reporting of information related to local lodging tax and
sales or use tax on building or construction materials - definitions - repeal.
(1) It
is the duty of the executive director to administer the provisions of this
article 21, and the executive director has the power to adopt, amend, or
rescind such rules not inconsistent with the provisions of this article 21, the
statutory provisions listed in section 39-21-102, and, subject to other
provisions of law relating to the promulgation of rules, to appoint, pursuant
to section 13 of article XII of the state constitution, such persons, to make
such expenditures, to require such reports, to make such investigations, and to
take such other action as the executive director deems necessary or suitable to
that end. The executive director shall determine the organization and methods
of procedure in accordance with the provisions of this article 21. For the
purpose of ascertaining the correctness of any return or for the purpose of
making an estimate of the tax due from any taxpayer, the executive director has
the power to examine or cause to be examined by any employee, agent, or
representative designated by the executive director for that purpose any books,
papers, records, or memoranda bearing upon the matters required to be included
in the return. In the exercise of rule-making authority as to article 29 of
this title 39, as granted by the general assembly pursuant to this subsection
(1), the executive director may not readopt any rule, or portion thereof,
disapproved on or after July 1, 1982, by the general assembly pursuant to
section 24-4-103 (8)(d) without the approval of the general assembly.
(2) If
any taxpayer refuses voluntarily to furnish any of the foregoing information
when requested by the executive director of the department of revenue or his
employee, agent, or representative, the executive director, by subpoena issued
under his hand, may require the attendance of the taxpayer and the production
by him of any of the foregoing information in his possession and may administer
an oath to him and take his testimony. If the taxpayer fails or refuses to
respond to said subpoena and give testimony, the executive director may apply
to any judge of the district court of the state of Colorado for an attachment
against such taxpayer as for contempt, and said judge may cause arrest of such
person, and upon hearing, said judge has, for the purpose of enforcing
obedience to the requirements of said subpoena, power to make such order as, in
his discretion, he deems consistent with the law for punishment of contempts.
(3) If
the executive director of the department of revenue is unable to secure from
the taxpayer information relating to the correctness of the taxpayer's return
or the amount of the income of the taxpayer, the executive director may apply
to any judge of the district court of the state of Colorado for the issuance of
subpoenas to such other persons as the executive director believes may have
knowledge in the premises, and, upon making a showing satisfactory to the court
that the taxpayer cannot be found, or evades service of subpoena, or fails or
refuses to produce his records or give testimony, or is unable to furnish such
records or testimony, the judge has power, after service of summons upon the
persons named in the petition of the executive director, after written notice
mailed to the taxpayer to his last-known address as set forth in the records of
the department of revenue, and after hearing, to cause the issuance of
subpoenas under the seal of the court to the persons sought to be so summoned requiring
any of them to appear before said executive director and give testimony
relating to said taxpayer's return or income. In case any of said persons so
served with subpoena fail to respond thereto, the judge may proceed against
such persons as in cases of contempt.
(3.5)
(a) If any retailer that does not collect Colorado sales tax refuses
voluntarily to furnish any of the information specified in subsection (1) of
this section when requested by the executive director of the department of
revenue or his or her employee, agent, or representative, the executive
director, by subpoena issued under the executive director's hand, may require
the attendance of the retailer and the production by him or her of any of the
foregoing information in the retailer's possession and may administer an oath
to him or her and take his or her testimony. If the retailer fails or refuses
to respond to said subpoena and give testimony, the executive director may
apply to any judge of the district court of the state of Colorado to enforce such
subpoena by any appropriate order, including, if appropriate, an attachment
against the retailer as for contempt, and upon hearing, said judge has, for the
purpose of enforcing obedience to the requirements of said subpoena, power to
make such order as, in his or her discretion, he or she deems consistent with
the law for punishment of contempts.
(b) For
purposes of this subsection (3.5), "retailer" shall have the same
meaning as set forth in section 39-26-102 (8).
(c) (I)
Each retailer that does not collect Colorado sales tax shall notify Colorado
purchasers that sales or use tax is due on certain purchases made from the
retailer and that the state of Colorado requires the purchaser to file a sales
or use tax return.
(II)
Failure to provide the notice required in subparagraph (I) of this paragraph
(c) shall subject the retailer to a penalty of five dollars for each such
failure, unless the retailer shows reasonable cause for such failure.
(d) (I)
(A) Each retailer that does not collect Colorado sales tax shall send
notification to all Colorado purchasers by January 31 of each year showing such
information as the Colorado department of revenue shall require by rule and the
total amount paid by the purchaser for Colorado purchases made from the
retailer in the previous calendar year. Such notification shall include, if
available, the dates of purchases, the amounts of each purchase, and the
category of the purchase, including, if known by the retailer, whether the
purchase is exempt or not exempt from taxation. The notification shall state
that the state of Colorado requires a sales or use tax return to be filed and
sales or use tax paid on certain Colorado purchases made by the purchaser from
the retailer.
(B) The
notification specified in sub-subparagraph (A) of this subparagraph (I) shall
be sent separately to all Colorado purchasers by first-class mail and shall not
be included with any other shipments. The notification shall include the words
"Important Tax Document Enclosed" on the exterior of the mailing. The
notification shall include the name of the retailer.
(II)
(A) Each retailer that does not collect Colorado sales tax shall file an
annual statement for each purchaser to the department of revenue on such forms
as are provided or approved by the department showing the total amount paid for
Colorado purchases of such purchasers during the preceding calendar year or any
portion thereof, and such annual statement shall be filed on or before March 1
of each year.
(B) The
executive director of the department of revenue may require any retailer that
does not collect Colorado sales tax that makes total Colorado sales of more
than one hundred thousand dollars in a year to file the annual statement
described in sub-subparagraph (A) of this subparagraph (II) by magnetic media
or another machine-readable form for that year.
(III)
(A) Failure to send the notification required in subparagraph (I) of this
paragraph (d) shall subject the retailer to a penalty of ten dollars for each
such failure, unless the retailer shows reasonable cause for such failure.
(B)
Failure to file the annual statement required in sub-subparagraph (A) of
subparagraph (II) of this paragraph (d) shall subject the retailer to a penalty
of ten dollars for each purchaser that should have been included in such annual
statement, unless the retailer shows reasonable cause for such failure.
(4)
Regulations adopted, amended, or rescinded by the executive director of the
department of revenue shall be effective in the manner and at the time
prescribed by the executive director, subject to the provisions of article 4 of
title 24, C.R.S.
(5)
Subject to the provisions of this article and the state personnel system
regulations, the executive director of the department of revenue is authorized
to appoint and prescribe the duties and powers of such officers, accountants,
experts, and other persons as may be necessary in the performance of his duty.
He may delegate to any such person so appointed such power as he deems
reasonable and proper for the effective administration of this article and
shall bond, in a sufficient amount, any person handling money under this
article.
(6)
Members of the department of revenue shall each give bond to the state of
Colorado in the sum of five thousand dollars conditioned upon the faithful
performance of their duties under the provisions of this article.
(7) (a)
Any officer or employee of the department shall be dismissed from office or
discharged from employment if, while performing functions related to any
revenue law of the state of Colorado, he:
(I)
Extorts or willfully oppresses any person through use of his actual or apparent
authority;
(II)
Knowingly demands other or greater sums than are authorized by law or receives
any fee, compensation, or reward, except as prescribed by law, for the
performance of any duty;
(III)
With intent to defeat the application of any provision of this title, makes
opportunity for any person to defraud the state of Colorado by intentionally
failing to perform any of the duties of his office or employment;
(IV)
Conspires or colludes with any other person to defraud the state of Colorado;
(V)
Knowingly makes opportunity for any person to defraud the state of Colorado;
(VI)
Commits or omits to do any act with the intent to enable any other person to
defraud the state of Colorado;
(VII)
Makes or signs any fraudulent entry in any book or makes or signs any
fraudulent certificate, return, or statement;
(VIII)
Fails to report in writing to the executive director of the department of
revenue or his designee any knowledge or information he has concerning a
violation of any revenue law by any person or a fraud committed by any person
against the state of Colorado under any revenue law; or
(IX)
Demands, accepts, or attempts to collect, directly or indirectly, as payment,
gift, or otherwise any sum of money or other thing of value for the compromise,
adjustment, or settlement of any charge or complaint for any violation or
alleged violation of law, except as otherwise expressly authorized by law.
(b) Any
officer or employee who violates any of the provisions of paragraph (a) of this
subsection (7) is guilty of a class 6 felony and shall be punished as provided
in section 18-1.3-401, C.R.S. The court may in its discretion award out of any
fine imposed an amount, not in excess of one-half thereof, for the use of the
informer, if any, in any such case who shall be ascertained by the judgment of
the court. The court also shall render judgment against the said officer or
employee for the amount of damages sustained in favor of the party injured.
(8) The
executive director is authorized to waive, for good cause shown, any penalty or
interest assessed on any tax administered under the provisions of this article,
and interest imposed in excess of the rate imposed under section 39-21-110.5
shall be deemed a penalty.
(9) The
executive director shall have such other powers, duties, and functions as are
prescribed for heads of principal departments in the "Administrative
Organization Act of 1968", article 1 of title 24, C.R.S.
(10)
(a) Notwithstanding any other provision of law, and pursuant to 26 U.S.C.
sec. 6402 and 31 U.S.C. sec. 3716 (b) and (h)(1), or any successor sections,
the executive director may enter into a reciprocal agreement with the United
States government to offset:
(I) The
claim of any person against the state, including any state tax overpayment to
which the person may be entitled, to any debt of the person owed to the United
States government that the United States government has certified as final,
due, and owing, with all appeals and legal actions having been waived or
exhausted; and
(II)
Any claim of any person against the United States government to any liquidated
debt of the person owed to the state. Any fees associated with any offset of
federal money will be deducted by the United States government from the amount
of money offset, which may then be added to the balance of the debt owed, but
any fees associated with any offset of state money will not be charged to the
United States government.
(b)
Notwithstanding any other provision of law, the executive director may enter
into a reciprocal agreement with any state to offset:
(I) The
claim of any person against the state to any debt of the person owed to any
state that has certified the debt as final, due, and owing, with all appeals
and legal actions having been waived or exhausted; and
(II)
Any claim of any person against any state to any liquidated debt of the person
owed to the state.
(11)
(a) As used in this section, unless the context otherwise requires:
(I)
"Applicable sales or use tax" means a sales or use tax on building or
construction materials imposed by a local taxing jurisdiction.
(II)
"Building permit-related applicable sales or use tax information"
means the following information:
(A) The
tax rate of all applicable sales or use taxes, including applicable sales or
use taxes imposed on the items identified in subsection (11)(a)(II)(E) of this
section;
(B) The
timing of when the applicable sales or use tax must be paid to the local taxing
jurisdiction and if the local taxing jurisdiction requires pre-payment of the
applicable sales or use tax, the percentage basis for the pre-paid amount
required;
(C) Any
exemptions on purchases subject to the applicable sales or use tax;
(D)
Whether the local taxing jurisdiction includes the applicable sales or use tax
due on a building permit and whether any other information is included on
building permits; and
(E)
Whether the local taxing jurisdiction imposes a sales or use tax on
construction equipment brought into the local taxing jurisdiction, on storage
of equipment within the local taxing jurisdiction, or on services.
(III)
"Construction equipment" means any equipment, including mobile
machinery and mobile equipment, which is used to erect, install, alter,
demolish, repair, remodel, or otherwise make improvements to any real property,
building, structure, or infrastructure.
(IV)
"Local lodging tax" has the same meaning as set forth in section
39-26-802 (1)(a.5)(II).
(V)
"Local lodging tax information" means the following information for
all local lodging tax imposed by the local taxing jurisdiction:
(A) The
tax rate;
(B) The
types of lodging that the local lodging tax applies to, including any
conditions governing the application of the local lodging tax by lodging type,
such as minimum number of rooms in a property or use of accommodations;
(C) The
number of days after which a stay is exempt, which may be referred to as a
length of stay exemption; and
(D) The
amount of the local lodging tax that is permitted to be retained by the party
responsible for collection of the local lodging tax in exchange for timely
filing, which may be referred to as a vendor fee, service fee, or timely filing
discount.
(VI)
"Local taxing jurisdiction" means a county, home rule county,
statutory town or city, home rule town or city, city and county, or territorial
charter town or city that imposes a local lodging tax or imposes an applicable
sales or use tax.
(b) By
not later than July 1, 2025, and by not later than January 1 and July 1 of each
year thereafter, the executive director shall, in a form and in a manner
prescribed by the department, publish local lodging tax information and
building permit-related applicable sales or use tax information.
(c) (I)
For the purpose of administration by the executive director of the provisions
in this subsection (11), each local taxing jurisdiction shall file with the
executive director a copy of each ordinance or resolution, or any amendment
thereto, that imposes an applicable sales or use tax or local lodging tax no
later than forty-five days before the effective date of the ordinance or
resolution, or any amendment thereto. If a local taxing jurisdiction's
ordinance or resolution does not contain building permit-related applicable
sales or use tax information or local lodging tax information, the local taxing
jurisdiction shall file with the executive director documentation containing
such information as set forth in subsections (11)(a)(II) and (11)(a)(V) of this
section.
(II)
(A) Notwithstanding the provisions of subsection (11)(c)(I) of this section,
local taxing jurisdictions shall file with the executive director a copy of
each ordinance or resolution, or any amendment thereto, that imposes an
applicable sales or use tax or local lodging tax on or before June 15, 2025. If
a local taxing jurisdiction's ordinance or resolution does not contain building
permit-related applicable sales or use tax information or local lodging tax
information, the local taxing jurisdiction shall file with the executive
director documentation containing such information as set forth in subsections
(11)(a)(II) and (11)(a)(V) of this section.
(B)
This subsection (11)(c)(II) is repealed, effective January 1, 2027.
Source:
L. 65: p. 1140, §
2. C.R.S. 1963: § 138-9-11. L. 77: (1) amended and (7) added, pp.
842, 1772, §§ 6, 1, effective July 1. L. 81: (3) amended, p. 1869, § 1,
effective May 13. L. 82: Entire section amended, p. 558, § 2, effective
April 6. L. 89: (8) added, p. 1497, § 1, effective June 7; (7)(b)
amended, p. 852, § 143, effective July 1. L. 94: (9) added, p. 566, §
17, effective April 6. L. 2001: (1) amended, p. 780, § 12, effective
June 1. L. 2002: (7)(b) amended, p. 1556, § 347, effective October 1. L.
2009: (1) amended, (HB 09-1053), ch. 159, p. 692, § 15, effective August 5.
L. 2010: (3.5) added, (HB 10-1193), ch. 9, p. 55, § 2, effective
February 24. L. 2021: (10) added, (SB 21-055), ch. 12, p. 80, § 16,
effective March 21. L. 2023: (1) amended, (HB 23-1121), ch. 35, p. 124,
§ 6, effective August 7. L. 2024: (11) added, (HB 24-1050), ch. 374, p.
2539, § 1, effective June 4; (1) amended, (HB 24-1349), ch. 423, p. 2905, § 15,
effective December 17 (see editor's note).
Editor's
note: Section
19(1) of chapter 423 (HB 24-1349), Session Laws of Colorado 2024, provides that
the act changing this section takes effect on the date of the official
declaration of the vote thereon by the governor only if, at the November 2024
statewide election, a majority of voters approve the ballot issue referred in
accordance with § 39-37-201. The ballot issue, referred to the voters as
Proposition KK, was approved on November 5, 2024, and was proclaimed by the
Governor on December 17, 2024, see L. 2025, p. 3636. The vote count for the
measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: For
the legislative declaration contained in the 2002 act amending subsection
(7)(b), see section 1 of chapter 318, Session Laws of Colorado 2002.
ANNOTATION
Law reviews. For
article, "Balancing Investigative Powers and Privacy Rights", see 14
Colo. Law. 947 (1985). For article, "Taxation", which discusses a
Tenth Circuit decision dealing with the failure to produce documents, see 65
Den. U. L. Rev. 635 (1988). For comment, "Direct Marketing Association v.
Brohl: Stranded on a Precedential Island", see 94 Denv. L. Rev. 627
(2017).
Section not violative of
taxpayer's privacy expectations. This section on its face does not violate
in an unreasonable manner a taxpayer's expectation of privacy in his bank
records. Charnes v. DiGiacomo, 612 P.2d 1117 (Colo. 1980).
The notice and reporting
obligations on a retailer that does not collect Colorado sales tax do not
violate the dormant commerce clause of the United States constitution. Such
notice and reporting obligations are neither facially discriminatory nor
discriminatory in their effects and do not unduly burden interstate commerce.
Direct Mktg. Ass'n v. Brohl, 814 F.3d 1129 (10th Cir. 2016).
Use of civil subpoena proper
despite intended criminal investigation. The use of a civil subpoena by the
department of revenue pursuant to this section is proper despite the taxpayer's
contention that the department of revenue intends to pursue a criminal action
against him and that the records sought by the subpoena are for the criminal
investigation. Charnes v. DiGiacomo, 612 P.2d 1117 (Colo. 1980).
Burden on director to
justify subpoena. A motion to quash a subpoena issued pursuant to
subsection (3) requires the director of the department of revenue to justify
access to the taxpayer's bank records under the standards of that subsection.
Charnes v. DiGiacomo, 612 P.2d 1117 (Colo. 1980).
Former regulation relating
to personal exemption of head of family held valid. State Treasurer v.
Ellis, 115 Colo. 154, 170 P.2d 283 (1946).
Department regulation
attempting to change legislative intent invalid. Weed v. Occhiato, 175
Colo. 509, 488 P.2d 877 (1971).
Regulations may not modify
existing statutes. A regulation must further the will of the general
assembly and may not modify or contravene an existing statute. Miller Int'l,
Inc. v. Dept. of Rev., 646 P.2d 341 (Colo. 1982).
Executive director
authorized to delegate power to deputy director to conduct administrative
hearings. Manka v. Tipton, 805 P.2d 1203 (Colo. App. 1991).
Applied in Union P.R.R.
v. Heckers, 181 Colo. 374, 509 P.2d 1255 (1973); Montgomery Ward & Co. v.
Dept. of Rev., 628 P.2d 85 (Colo. 1981).
39-21-113. Reports and returns - rule -
repeal.
(1) (a)
It is the duty of every person, firm, or corporation liable to the state of
Colorado for any tax or charge administered pursuant to this article 21 to keep
and preserve for a period of three years such books, accounts, and records as
may be necessary to determine the amount of liability.
(b) It
is the duty of every person, firm, or corporation liable to the state of
Colorado for any tax imposed on income or gifts or a report in connection
therewith to keep and preserve for a period of four years following the due
date of the return or the payment of said tax such books, accounts, and records
as may be necessary to determine the amount of such tax liability.
(c) All
such books, accounts, and records shall be open for examination at any time by
the executive director of the department of revenue or his duly authorized
agents.
(2) In
the case of a person, firm, or corporation which does not keep the necessary
books, accounts, and records within the state, it shall be sufficient if such
person, firm, or corporation produces within this state such books, accounts,
records, or such information as shall be reasonably required by the executive
director of the department of revenue for examination by him or, an agent duly
authorized by him or, in lieu thereof, if said books, accounts, and records are
open for inspection, by an agent authorized by the executive director at the
place where such books, accounts, and records are kept.
(3) All
reports and returns of taxes received by the department, other than income tax
returns, covered by this article shall be preserved for three years and
thereafter until the executive director of the department of revenue orders
them to be destroyed. Income tax returns received by the department of revenue
shall be preserved for four years and thereafter until the executive director
orders them to be destroyed.
(4) (a)
Except in accordance with judicial order or as otherwise provided by law, the
executive director of the department of revenue and his agents, clerks, and
employees shall not divulge or make known in any way any information obtained
from any investigation conducted by the department or its agents or disclosed
in any document, report, or return filed in connection with any of the taxes
covered by this article. The officials charged with the custody of such
documents, reports, investigations, and returns shall not be required to
produce any of them or evidence of anything contained in them in any action or
proceeding in any court, except on behalf of the executive director in an
action or proceeding under the provisions of any such taxing statutes to which
the department is a party or on behalf of any party to any action or proceeding
under the provisions of such taxing statutes when the report of facts shown
thereby is directly involved in such action or proceeding, in either of which
events the court may require the production of, and may admit in evidence, so
much of said reports or of the facts shown thereby as are pertinent to the
action or proceeding and no more.
(b) (I)
This section does not prohibit the delivery to a person or his or her duly
authorized representative of a copy of any return or report filed in connection
with his or her tax. The copy may be certified by the executive director of the
department of revenue or the head of a group, division, or subordinate
department, as appointed by the executive director in accordance with article
35 of title 24, C.R.S., and when so certified is evidence equally with and in
like manner as the originals and may be used by a court as evidence of the
contents of the originals.
(II) An
individual or his or her duly authorized representative may also request proof
of return filing for particular tax years. Following request and payment of the
applicable fee, the department shall provide proof of return filing for a
period for which the taxpayer has filed a return and requested proof of return
filing. The department shall include in the proof of filing:
(A) The
individual's name;
(B) The
individual's address as shown on the most recently filed return;
(C) The
dates of the tax periods of the requested returns; and
(D) A
statement as to whether the most recently filed return was filed as a resident
of Colorado, or, if a part-year resident, the date the individual acquired or
abandoned residency.
(III)
The department shall promulgate a rule establishing and charging a fee for the
issuance of proof of return filing. To be valid, the charge must be based on
the actual cost of issuing the proof of return filing.
(c) It
is unlawful for any members of the department of revenue and any deputy, agent,
clerk, or other officer or employee engaged in any administration which is
governed by this article to engage in the business or profession of tax
accounting or to accept employment, with or without consideration, from any
person, firm, or corporation for the purpose, directly or indirectly, of
preparing tax returns or reports required by the laws of the state of Colorado,
by any other state, or by the United States government or to accept any
employment for the purpose of advising, preparing material or data, or the
auditing of books or records to be used in an effort to defeat or cancel any
tax or part thereof that has been assessed by the state of Colorado, any other
state, or by the United States government.
(d) The
executive director and any agent, clerk, or employee of the department may:
(I)
Disclose the name of a tax return preparer to the state board of accountancy in
accordance with section 39-22-621 (2)(g.5) under the circumstances described in
that section; and
(II)
Disclose to a tax return preparer who is potentially subject to a penalty under
section 39-22-621 (2)(g.5) the taxpayer name, account number, alleged
understatement of liability, and applicable laws pertaining to the
understatement giving rise to the potential imposition of the penalty.
(5)
Nothing in this section shall be construed to prohibit the publication of
statistics, so classified as to prevent the identification of particular
reports or returns and the items thereof, or the inspection of returns by the
attorney general or other legal representatives of the state. Nothing in this
section shall be construed to prohibit the release of information for the
periodic publication of gasoline gallonage reports based on reports and returns
filed under the gasoline tax or special fuel tax statutes and containing
summaries of the quantities of liquid fuel marketed in Colorado, specifying the
suppliers, distributors, and consumers of such gasoline or special fuel, and
other information relating to gasoline tax or special fuel tax.
(6)
Except as otherwise provided in this section, any person who violates any
provision of subsection (4) of this section is guilty of a misdemeanor and,
upon conviction thereof, shall be punished by a fine of not more than one
thousand dollars, and, if the offender is an officer or employee of the state,
he or she shall be dismissed from office.
(7)
Notwithstanding the provisions of this section, the executive director of the
department of revenue shall supply any county assessor of the state of Colorado
or his representative with information relating to ad valorem tax assessments
or valuation of property within his county and, in his discretion, may permit
the commissioner of internal revenue of the United States, or the proper
official of any state imposing a similar tax, or the authorized representative
of either to inspect the reports and returns of taxes covered by this article.
(8)
Notwithstanding the provisions of this section, the executive director of the
department of revenue may provide the division of unemployment insurance with
any information obtained pursuant to this section and, in connection therewith,
may enter into an agreement with the division of unemployment insurance
providing for payment of the costs incurred in connection with supplying the
information and providing for periodic updating of the information supplied.
Information thus supplied to the division of unemployment insurance is subject
to the rules of confidentiality set forth in section 8-72-107 (1), C.R.S., to
the same extent as information supplied by employers to the division of
unemployment insurance.
(9)
Notwithstanding the provisions of this section, the executive director of the
department of revenue shall provide the department of human services with any
information obtained pursuant to this section which is necessary to implement
the procedure to offset state income tax refunds against past-due child support
pursuant to section 26-13-111, C.R.S., and section 39-21-108.
(10)
Notwithstanding the provisions of this section, the executive director of the
department of revenue shall supply any county assessor of the state of Colorado
or his representative with information obtained through audit of reports and
returns covered by this article dealing with such taxpayers' ability to pay or
to properly accrue any ad valorem tax collected by such county assessor.
(11)
Repealed.
(12)
(a) Notwithstanding any provision of this section to the contrary, on and
after October 1, 2002, for the purpose of enabling the state treasurer to make
income tax refunds pursuant to the "Revised Uniform Unclaimed Property
Act", article 13 of title 38, the department shall supply the state
treasurer with information as required by section 39-21-108 (5).
(b)
Repealed.
(13)
Notwithstanding the provisions of this section, the executive director shall
provide the aeronautics division created in section 43-10-103, C.R.S., with
information obtained from an audit of or disclosed in any document, report, or
return filed in connection with any of the taxes collected pursuant to sections
39-26-104, 39-26-715 (1)(a)(I), 39-26-202, 39-27-102, and 39-27-112 on gasoline
or fuel used in aviation. The department shall only release information
regarding the portion of said tax revenues that will be credited to the
aviation fund created in section 43-10-109, C.R.S. Any information provided to
the division pursuant to this subsection (13) shall remain confidential, and
all employees of the division shall be subject to the limitations set forth in
subsection (4) of this section and the penalties contained in subsection (6) of
this section.
(14)
Notwithstanding the provisions of this section, the executive director of the
department of revenue shall supply the state court administrator with taxpayer
names, addresses, year of birth, if available, and other identifying
information obtained pursuant to this section for the purpose of compiling the
master juror list pursuant to section 13-71-107 (1), C.R.S. Those persons who
receive taxpayer information under this subsection (14) shall be subject to the
provisions of this section, including limitations in subsection (4) of this
section and penalties in subsection (6) of this section regarding disclosure of
taxpayer information.
(15) and
(16) Repealed.
(17)
Notwithstanding any other provision of this section, the executive director may
require that such detailed information regarding a claim for a credit for the
donation of a conservation easement in gross pursuant to section 39-22-522 and
any appraisal submitted in support of the credit claimed be given to the
division of conservation in the department of regulatory agencies and the
conservation easement oversight commission created pursuant to section
12-15-103 as the executive director determines is necessary in the performance
of the department's functions relating to the credit. The executive director
may provide copies of any appraisal and may file a complaint regarding any
appraisal as authorized pursuant to section 39-22-522 (3.3). Notwithstanding
part 2 of article 72 of title 24, in order to protect the confidential
financial information of a taxpayer, the executive director shall deny the
right to inspect any information or appraisal required in accordance with this
subsection (17).
(17.5)
(a) Notwithstanding the provisions of this section, the executive director
may provide such detailed information pertinent to a claim for a credit for the
donation of a conservation easement pursuant to section 39-22-522 to taxpayers,
including donors and transferees, with cases involving common or related issues
of fact or law. The executive director or the executive director's duly
authorized agents may also provide such information to the parties to a
consolidated administrative hearing pursuant to section 39-22-522.5 (5)(a) as
necessary and appropriate for the efficient and fair resolution of disputes.
(b)
Persons who receive taxpayer information pursuant to paragraph (a) of this
subsection (17.5) shall be subject to the provisions of this section, including
the limitations in subsection (4) of this section and the penalties in
subsection (6) of this section regarding disclosure of taxpayer information.
(17.7)
(a) Notwithstanding any other provision of this section, the executive
director may require that such detailed information regarding a claim for a
credit for the approved environmental remediation of contaminated property
pursuant to section 39-22-526 and any documentation submitted in support of the
credit claimed be given to the department of public health and environment as
the executive director determines is necessary in the performance of the
department's functions relating to the credit. Notwithstanding the provisions
of part 2 of article 72 of title 24, C.R.S., in order to protect the
confidential financial information of a taxpayer, the executive director shall
deny the right to inspect any information or documentation required in accordance
with the provisions of this subsection (17.7).
(b)
Notwithstanding the provisions of this section, the executive director may
provide such detailed information pertinent to a claim for a credit for the
approved environmental remediation of contaminated property pursuant to section
39-22-526 to taxpayers, including transferees, with cases involving common or
related issues of fact or law. Persons who receive taxpayer information
pursuant to the provision of this subsection (17.7) shall be subject to the
provisions of this section, including the limitations in subsection (4) of this
section and the penalties in subsection (6) of this section regarding
disclosure of taxpayer information.
(18)
Notwithstanding the provisions of this section, the executive director may
provide to the department of local affairs information obtained pursuant to
this section that is necessary to verify the information submitted to the
department of local affairs pursuant to section 39-29-110 (1)(d)(I)(B) and that
is sufficient to allow the department of local affairs to efficiently
distribute moneys as required by section 39-29-110 (1)(c). The department shall
not release any information to the department of local affairs that is not
needed to verify information or distribute moneys. With the exception of
taxpayer contact information, any information provided to the department of
local affairs pursuant to this subsection (18) shall remain confidential, and all
persons within the department of local affairs shall be subject to the
limitations set forth in subsection (4) of this section and the penalties
contained in subsection (6) of this section.
(19)
Notwithstanding the provisions of this section, the executive director shall
publish the lists of wholesalers as specified in section 39-28-115 and
distributors as specified in section 39-28.5-112.
(20)
Notwithstanding the provisions of this section, the executive director shall
provide the Colorado office of economic development with information as
required pursuant to section 24-48.5-112 (2)(d), C.R.S.
(21)
Notwithstanding the provisions of this section, the executive director of the
department of revenue shall provide information to other state agencies as
required pursuant to section 39-21-108 (3).
(22)
Notwithstanding the provisions of this section, the executive director shall
supply the Colorado office of economic development with information relating to
the actual amount of any enterprise zone tax credit claimed pursuant to article
30 of this title or any CHIPS zone tax credit claimed pursuant to article 36 of
this title 39 as well as information submitted to and aggregated by the
department pursuant to section 39-36-106 (1) and (3) regarding such income tax
credits. Any information provided to the office pursuant to this subsection
(22) shall remain confidential, and all office employees shall be subject to
the limitations set forth in subsection (4) of this section and the penalties
contained in subsection (6) of this section. Nothing in this subsection (22)
shall prevent the office from making aggregated data regarding enterprise zone
and CHIPS zone tax credits available.
(23)
Notwithstanding the provisions of this section:
(a) The
executive director may provide such detailed taxpayer information pertinent to
a claim for an income tax credit for the approved rehabilitation of a historic
structure pursuant to section 39-22-514.5 to taxpayers, including owners and
transferees, with cases involving common or related issues of fact or law. With
the exception of taxpayer contact information, any information provided
pursuant to this subsection (23) must remain confidential, and all persons are
subject to the limitations specified in subsection (4) of this section and the
penalties specified in subsection (6) of this section.
(b) The
executive director may require that such detailed taxpayer information
pertinent to a claim for an income tax credit for the approved rehabilitation
of a historic structure pursuant to section 39-22-514.5 and any documentation
in support of the credit claimed be given to the Colorado office of economic
development and the state historical society of Colorado as the executive
director determines is necessary in the performance of the department's
functions relating to the credit. In resolving disputes regarding the credit,
the executive director may disclose such detailed taxpayer information and
consult with the Colorado office of economic development and the state
historical society of Colorado. Notwithstanding part 2 of article 72 of title
24, C.R.S., in order to protect the confidential financial information of a
taxpayer, the executive director shall deny the right to inspect any
information or documentation required in accordance with this subsection (23).
(24)
Notwithstanding any other provision of this section, the executive director,
after receiving from the property tax administrator a list of individuals who
are either claiming the property tax exemptions for qualifying seniors and
qualifying veterans with a disability allowed under part 2 of article 3 of this
title 39 or applying for the qualified-senior primary residence real property
classification for the property described in section 39-1-104.6, shall provide
to the property tax administrator information pertaining to the listed
individuals, including their names, social security numbers, marital and income
tax filing status, and residency status, needed by the administrator to verify
that the exemption or classification is allowed only to applicants who satisfy
legal requirements for claiming it. The administrator and the administrator's
agents, clerks, and employees shall keep all information received from the
executive director confidential, and any individual who fails to do so is
guilty of a misdemeanor and subject to punishment as specified in subsection
(6) of this section.
(25)
Notwithstanding the confidentiality requirements in this section, the executive
director shall provide the information authorized by the taxpayer to be
collected pursuant to section 39-22-5202 (1) to the Colorado health benefit
exchange created in article 22 of title 10 and may share the information with
the department of health care policy and financing to facilitate assessment of
potential eligibility for and enrollment in a health care coverage
affordability program through the Colorado affordable health care coverage easy
enrollment program created in section 10-22-113. Any information provided to
the Colorado health benefit exchange or the department of health care policy
and financing pursuant to this subsection (25) remains confidential, and the
board of directors and all officers, agents, clerks, and employees of the
Colorado health benefit exchange and the executive director and all agents,
clerks, and employees of the department of health care policy and financing are
subject to the limitations set forth in subsection (4) of this section and the
penalties in subsection (6) of this section.
(26)
(a) Notwithstanding the provisions of this section, the executive director
shall provide the information disclosed in any document, report, or return
filed in connection with the prepaid wireless 911 charge imposed by section
29-11-102.5 to the public utilities commission created in section 40-2-101 or a
governing body as defined in section 29-11-101 (16). Any information provided
to the public utilities commission or governing body, pursuant to this
subsection (26)(a) remains confidential, and all agents, clerks, and employees
of the commission and the governing body are subject to the limitations set
forth in subsection (4) of this section and the penalties contained in
subsection (6) of this section.
(b)
Notwithstanding the provisions of this section to the contrary, the executive
director shall provide to the public utilities commission created in section
40-2-101 and the communication services for people with disabilities enterprise
created in section 26-21-103.5 the information disclosed in any document,
report, or return filed in connection with the prepaid telephone disability
access charge imposed by section 40-17-104. Any information provided to the
commission and the enterprise pursuant to this subsection (26)(b) remains
confidential, and all agents, clerks, and employees of the commission and the
enterprise are subject to the limitations set forth in subsection (4) of this
section and the penalties contained in subsection (6) of this section.
(c)
Notwithstanding the provisions of this section, the executive director shall
provide to the public utilities commission created in section 40-2-101 and the
988 crisis hotline enterprise created in section 27-64-103 the information
disclosed in any document, report, or return filed in connection with the
prepaid wireless 988 charge imposed by section 40-17.5-104. Any information
provided to the commission and the enterprise pursuant to this subsection
(26)(c) remains confidential, and all agents, clerks, and employees of the
commission are subject to the limitations set forth in subsection (4) of this
section and the penalties contained in subsection (6) of this section.
(27)
Notwithstanding the confidentiality requirements in this section, the executive
director shall share with the department of public health and environment
pertinent information necessary to determine the amount of state sales tax
retained by a qualifying retailer as allowed in section 39-26-105 (1.3). Any
information provided to the department of public health and environment
pursuant to this subsection (27) remains confidential, and all agents, clerks,
and employees of the department of public health and environment are subject to
the limitations set forth in subsection (4) of this section and the penalties
in subsection (6) of this section.
(28)
Repealed.
(29)
Notwithstanding the provisions of this section, when conducting an assessment
pursuant to section 39-27-105 (3) of a distributor of gasoline or special fuels
who fails or refuses to make and file the sworn statement and pay the tax due
for any calendar month or who makes and files any incorrect or fraudulent
statement or return for any calendar month as required by part 1 of article 27
of this title 39, the executive director may provide detailed information
pertinent to an assessment made pursuant to section 39-27-105 (3), including
information from a report filed pursuant to section 39-27-105 (1), to taxpayers
with cases involving common or related issues of fact or law. Persons who
receive taxpayer information pursuant to this subsection (29) are subject to
the provisions of this section, including the limitations in subsection (4) of
this section and the penalties in subsection (6) of this section regarding
disclosure of taxpayer information.
(30)
Notwithstanding the provisions of this section:
(a) The
executive director may provide such detailed taxpayer information pertinent to
a claim for an income tax credit for the donation of a perpetual conservation
easement in gross pursuant to section 39-22-522 to taxpayers, including owners
and transferees, with cases involving common or related issues of fact or law.
With the exception of taxpayer contact information, any information provided
pursuant to this subsection (30) must remain confidential, and all persons are
subject to the limitations specified in subsection (4) of this section and the
penalties specified in subsection (6) of this section.
(b) The
executive director may require that such detailed taxpayer information
pertinent to a claim for an income tax credit for the donation of a perpetual
conservation easement pursuant to section 39-22-522 and any documentation in
support of the credit claimed be given to the division of conservation as the
executive director determines is necessary in the performance of the
department's functions relating to the credit. In resolving disputes regarding
the credit, the executive director may disclose such detailed taxpayer
information and consult with the division of conservation. Notwithstanding part
2 of article 72 of title 24, in order to protect the confidential financial
information of a taxpayer, the executive director shall deny the right to inspect
any information or documentation required in accordance with this subsection
(30).
(31)
(a) Notwithstanding the provisions of this section, in order for call center
support to be provided as it relates to the refund of excess state revenues
from all sources set forth in section 39-22-2004, the executive director may
supply the department of personnel or a third-party vendor contracted to
provide the call center services with information necessary for support to be
facilitated and provided to taxpayers. Any information provided to the
department of personnel or a third-party vendor contracted to provide the call
center services pursuant to this subsection (31)(a) remains confidential, and
all persons within the department of personnel or employees of a third-party
vendor are subject to the limitations set forth in subsection (4) of this
section and the penalties contained in subsection (6) of this section.
(b)
This subsection (31) is repealed, effective July 1, 2027.
(32)
Notwithstanding the confidentiality requirements in this section, the executive
director shall provide the state auditor with the information described in
section 39-29-112 (8)(b).
(33)
Notwithstanding the confidentiality requirements in this section, the executive
director may provide the Colorado office of new Americans, created in section
8-3.7-103, and a third-party administrator, as defined in section 8-73-116
(1)(e), with any information obtained pursuant to this section and, in
connection with providing the information, may enter into an agreement with the
Colorado office of new Americans or the department of labor and employment that
provides for the payment of the costs incurred in connection with supplying the
information and providing for the periodic updating of the information
supplied. Any information provided to the Colorado office of new Americans or a
third-party administrator pursuant to this subsection (33) is confidential, and
all employees of either the Colorado office of new Americans or a third-party
administrator are subject to the limitations set forth in subsection (4) of
this section and the penalties specified in subsection (6) of this section.
(34)
Notwithstanding this section, the executive director of the department of
revenue may provide the division of family and medical leave insurance, created
in section 8-13.3-508 (1), with information obtained pursuant to this section
and may enter into an agreement with the division of family and medical leave
insurance providing for payment of the costs incurred in connection with
supplying the information and providing for periodic updating of the
information supplied. Information supplied to the division of family and
medical leave insurance pursuant to this subsection (34) is subject to the
rules of confidentiality set forth in section 8-13.3-516 (5) to the same extent
as information supplied by an individual or employer to the division of family
and medical leave insurance. All employees of the division of family and
medical leave insurance are subject to the limitations set forth in subsection
(4) of this section and the penalties specified in subsection (6) of this
section.
(35)
Notwithstanding the confidentiality requirements in this section, the executive
director has the authority to share taxpayer information as necessary pursuant
to sections 29-2-208 and 29-2-213 to 29-2-215.
(36)
(a) Notwithstanding any other provision of this section, on or before July
1, 2025, and on or before every July 1 thereafter, if requested, the executive
director of the department of revenue shall provide the department of early
childhood, the department of health care policy and financing, the department
of human services, the department of local affairs, the department of
corrections, the department of labor and employment, the behavioral health
administration, the department of higher education, and the department of
public health and environment information for each resident individual who
claimed the credit allowed by section 39-22-123.5, the credit allowed by
section 39-22-129, or both credits, for the 2024 income tax year or any
subsequent tax year for the purpose of benefit outreach by the requesting
department, including sharing information about how to enroll, the information
necessary to enroll, and, when possible, assisting with the application
process. Information shall include name, address, and, when available, email
address and phone number. When possible, the executive director of the
department of revenue shall provide additional information that may assist with
determining eligibility for the benefits administered by the respective
department.
(b) The
information that the executive director is required to provide pursuant to this
subsection (36) is subject to any limitations imposed pursuant to section 6103
of the federal "Internal Revenue Code of 1986", as amended. The
requesting agency shall secure the information as required by this subsection
(36) and shall use the information for the purposes described in subsection
(36)(a) of this section.
(c) Any
information provided to the department of early childhood, the department of
health care policy and financing, the department of human services, the
department of local affairs, the department of corrections, the department of
labor and employment, the behavioral health administration, the department of
higher education, or the department of public health and environment pursuant
to this subsection (36) remains confidential, and all agents, clerks, and
employees of the department of early childhood, the department of health care
policy and financing, the department of human services, the department of local
affairs, and the department of public health and environment are subject to the
limitations set forth in subsection (4) of this section and the penalties
contained in subsection (6) of this section to the same extent as agents,
clerks, and employees of the department.
(37) Notwithstanding
the confidentiality requirements of this section, the executive director shall
allow every sales and use tax license and every sales and use tax exemption
certificate to be searchable by the name and identification number of the sales
and use tax licensee or the sales and use tax exemption certificate holder.
(38)
Notwithstanding the confidentiality requirements of this section, the executive
director may provide the department of higher education with information
obtained pursuant to this section that indicates whether an eligible student,
as defined in section 39-22-570 (2)(c), has claimed the incentive, as defined
in section 39-22-570 (2)(d), allowed by section 39-22-570. Any information
provided to the department of higher education pursuant to this subsection (38)
remains confidential, and all employees of the department of higher education
are subject to the limitations set forth in subsection (4) of this section and
penalties specified in subsection (6) of this section.
(39)
Notwithstanding the provisions of this section, the executive director may
provide to the department of early childhood such detailed taxpayer information
pertinent to a claim for an income tax credit for an early childhood educator
pursuant to section 39-22-547, and such detailed taxpayer information pertinent
to a claim for an income tax credit for a care worker pursuant to section
39-22-566. Any information provided pursuant to this subsection (39) must
remain confidential, and all persons are subject to the limitations specified
in subsection (4) of this section and the penalties specified in subsection (6)
of this section.
(40)
(a) Notwithstanding the confidentiality requirements in this section:
(I) The
executive director may provide the Colorado office of economic development with
any information obtained pursuant to this section in relation to part 4 of
article 46 of title 24; and
(II)
Both the executive director and the Colorado office of economic development may
provide information obtained pursuant to this section in relation to part 4 of
article 46 of title 24 to a third-party analyst.
(b) Any
information provided to the Colorado office of economic development or a
third-party analyst pursuant to this subsection (40) is confidential, and all
employees of the Colorado office of economic development and the third-party
analyst are subject to the limitations set forth in subsection (4) of this
section and the penalties specified in subsection (6) of this section.
(41)
Notwithstanding the provisions of this section, the executive director may
provide to the Colorado energy office detailed taxpayer information pertinent
to a claim for an income tax credit for the retail sale of a qualified electric
bicycle pursuant to section 39-22-555. Any information provided pursuant to
this subsection (41) must remain confidential, and all persons who receive this
information are subject to the limitations specified in subsection (4) of this
section and the penalties specified in subsection (6) of this section.
(42)
Notwithstanding any other provision of this section, the executive director may
provide to the Colorado energy office such detailed taxpayer information
pertinent to a claim for an income tax credit for the installation of a heat
pump pursuant to section 39-22-554. Any information provided pursuant to this
subsection (42) must remain confidential, and all persons who receive this
information are subject to the limitations specified in subsection (4) of this
section and the penalties specified in subsection (6) of this section.
Source:
L. 65: p. 1142, §
2. C.R.S. 1963: § 138-9-12. L. 66: p. 198, § 1. L. 67: p.
839, § 2. L. 75: (4)(a) amended, p. 1483, § 1, effective June 20. L.
77: (1)(b) amended, p. 842, § 7, effective July 1; (1)(a) amended, pp.
1768, 1854, §§ 8, 10, effective January 1, 1978. L. 79: (1)(a) and (5)
amended, p. 1501, § 26, effective January 1, 1980. L. 81: (8) added, p.
488, § 16, effective July 1. L. 82: (6) amended, p. 629, § 42, effective
April 2. L. 85: (9) added, p. 604, § 23, effective July 1. L. 86:
(1)(a) and (6) amended and (10) added, pp. 1111, 937, §§ 9, 2, effective July
1. L. 89: (1)(a) amended, p. 1596, § 11, effective July 1, 1993. L.
90: (1)(a) amended, p. 1725, § 13, effective May 1; (1)(a) amended, p.
1725, § 14, effective July 1, 1993. L. 94: (9) amended, p. 3136, § 300,
effective July 1. L. 98, 2nd Ex. Sess.: (11) added, p. 8, § 5, effective
September 16. L. 99: (11) amended, p. 1318, § 6, effective August 4. L.
2000: (4)(b) amended, p. 1639, § 19, effective June 1. L. 2001:
(1)(a) amended, p. 780, § 13, effective June 1; (12) added, p. 619, § 5,
effective August 8. L. 2002: (13) added, p. 63, § 2, effective March 22;
(14) added, p. 986, § 2, effective June 1; (1)(a) amended, p. 1362, § 17,
effective July 1. L. 2004: (13) amended, p. 1044, § 14, effective July
1; (12) amended, p. 315, § 4, effective August 4. L. 2007: (15) added,
p. 1407, § 1, effective May 30. L. 2008: (4)(d) added, p. 433, § 1,
effective July 1; (17) added, p. 2315, § 7, effective July 1; (16) added, p.
954, § 4, effective January 1, 2009. L. 2009: (1)(a) amended, (HB
09-1053), ch. 159, p. 692, § 16, effective August 5; (18) added, (HB 09-1148),
ch. 42, p. 162, § 1, effective August 5; (19) added, (HB 09-1173), ch. 372, p.
2016, § 2, effective August 5; (20) added, (HB 09-1105), ch. 378, p. 2059, § 3,
effective September 1; (21) added, (HB 09-1137), ch. 308, p. 1663, § 15,
effective September 1. L. 2010: (12)(b) repealed, (SB 10-212), ch. 412,
p. 2032, § 1, effective July 1; (22) added, (SB 10-162), ch. 395, p. 1879, § 4,
effective January 1, 2012. L. 2011: (17.5) added, (HB 11-1300), ch. 193,
p. 752, § 3, effective May 19; (22) amended, (HB 11-1303), ch. 264, p. 1175, §
92, effective January 1, 2012. L. 2012: (8) amended, (HB 12-1120), ch.
27, p. 113, § 32, effective June 1. L. 2013: (4)(b) amended, (SB
13-251), ch. 402, p. 2355, § 7, effective August 7. L. 2014: (23) added,
(HB 14-1311), ch. 183, p. 681, § 2, effective May 14; (17) amended, (SB
14-117), ch. 385, p. 1919, § 7, effective July 1; (17.7) added, (SB 14-073),
ch. 213, p. 798, § 3, effective August 6. L. 2016: (24) added, (HB
16-1175), ch. 332, p. 1349, § 6, effective June 10. L. 2018: (17)
amended, (HB 18-1291), ch. 273, p. 1689, § 5, effective May 29. L. 2019:
(17) amended, (HB 19-1172), ch. 136, p. 1729, § 254, effective October 1;
(12)(a) amended, (SB 19-088), ch. 110, p. 470, § 19, effective July 1, 2020. L.
2020: (26) added, (HB 20-1293), ch. 267, p. 1296, § 11, effective July 10;
(6) amended, (HB 20-1175), ch. 88, p. 355, § 1, effective September 14; (15)
repealed, (SB 20-136), ch. 70, p. 297, § 49, effective September 14; (25)
added, (HB 20-1236), ch. 236, p. 1147, § 4, effective September 14. L. 2020,
1st Ex. Sess.: (27) added, (HB 20B-1004), ch. 3, p. 25, § 5, effective
December 7; (28) added, (SB 20B-001), ch. 2, p. 13, § 3, effective December 7. L.
2021: (30) added, (HB 21-1233), ch. 385, p. 2577, § 3, effective June 30;
(29) added, (SB 21-065), ch. 15, p 89, § 1, effective September 7. L. 2022:
(31) added, (SB 22-233), ch. 209, p. 1381, § 1, effective May 23; (32) added,
(HB 22-1361), ch. 472, p. 3453, § 6, effective July 1. L. 2023: (22)
amended, (HB 23-1260), ch. 227, p. 1188, § 3, effective May 20; (24) amended,
(SB 23-036), ch. 345, p. 2073, § 8, effective June 5; (33) added, (HB 23-1283),
ch. 293, p. 1767, § 8, effective October 1, 2024; (24) amended, (HB 23-1052),
ch. 131, p. 502, § 10, effective January 1, 2025. L. 2024: (11)
repealed, (SB 24-228), ch. 170, p. 900, § 9, effective May 14; (22) amended,
(HB 24-1036), ch. 373, p. 2537, § 40, effective August 7; (24) amended, (SB
24-111), ch. 169, p. 883, § 5, effective August 7; (34) added, (SB 24-155), ch.
59, p. 203, § 3, effective August 7; (35) added, (HB 24-1288), ch. 173, p. 941,
§ 1, effective August 7; (35) added, (SB 24-025), ch. 144, p. 579, § 40,
effective July 1, 2025; (1)(a) amended, (HB 24-1349), ch. 423, p. 2905, § 16,
effective December 17 (see editor's note). L. 2025: (39) added, (HB
25-1296), ch. 202, p. 912, § 5, effective May 16; (38) added, (SB 25-319), ch.
432, p. 2495, § 2, effective June 4; (35) amended, (SB 25-046), ch. 20, p. 82,
§ 2, effective July 1; (28) repealed, (SB 25-300), ch. 428, p. 2456, § 55,
effective August 6; (37) added, (SB 25-018), ch. 361, p. 1961, § 1, effective
August 6. L. 2026: (26) amended, (HB 26-1115), ch. 17, p. 82, § 5,
effective March 26; (40) added, (HB 26-1065), ch. 157, p. 923, § 9, effective
May 27; (41) and (42) added, (HB 26-1289), ch. 364, p. 2205, § 16, effective
June 3.
Editor's
note: (1)
Amendments to subsection (1)(a) by House Bill 77-1076 and Senate Bill 77-144
were harmonized.
(2) The effective date for
amendments to subsection (8) by House Bill 12-1120 (chapter 27, Session Laws of
Colorado 2012) was changed from August 8, 2012, to June 1, 2012, by House Bill
12S-1002 (First Extraordinary Session, chapter 2, p. 2432, Session Laws of
Colorado 2012.)
(3) Subsection (16)(b) provided
for the repeal of subsection (16), effective July 1, 2015. (See L. 2008, p.
954.)
(4) Subsection (24) was amended
in HB 23-1052, effective January 1, 2025. However, those amendments were
superseded by the amendments to subsection (24) by SB 23-036, effective June 5,
2023.
(5) Subsection (36) was
numbered as subsection (35) in HB 24-1288 but was renumbered on revision for
ease of location.
(6) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: (1)
For the legislative declaration contained in the 2009 act adding subsection
(20), see section 1 of chapter 378, Session Laws of Colorado 2009.
(2) For the legislative
declaration in HB 20B-1004, see section 1 of chapter 3, Session Laws of
Colorado 2020, First Extraordinary Session. For the legislative declaration in
SB 20B-001, see section 1 of chapter 2, Session Laws of Colorado 2020, First
Extraordinary Session. For the legislative declaration in SB 20-136, see
section 1 of chapter 70, Session Laws of Colorado 2020.
(3) For the legislative
declaration in HB 22-1361, see section 1 of chapter 472, Session Laws of
Colorado 2022.
(4) For the legislative
declaration in HB 23-1052, see section 1 of chapter 131, Session Laws of
Colorado 2023. For the legislative declaration in HB 23-1283, see section 1 of
chapter 293, Session Laws of Colorado 2023.
(5) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024.
(6) For the legislative
declaration in HB 25-1296, see section 1 of chapter 202, Session Laws of
Colorado 2025.
(7) For the legislative
declaration in HB 26-1065, see section 1 of chapter 157, Session Laws of
Colorado 2026. For the legislative declaration in HB 26-1289, see section 1 of
chapter 364, Session Laws of Colorado 2026.
ANNOTATION
Law reviews. For
article, "Taxation", which discusses a Tenth Circuit decision dealing
with the good faith failure to file returns, see 65 Den. U. L. Rev. 641 (1988).
Subsection (4)(a) is
applicable in proceedings other than those under income tax provisions.
People v. Vesely, 41 Colo. App. 325, 587 P.2d 802 (1978).
Party seeking income tax
return bears burden of showing compelling need. If a grand jury issues a
subpoena duces tecum and the trial court orders compliance after an evidentiary
hearing, then the director of the department of revenue must produce the tax
returns in question, but in all cases the party seeking the income tax return
bears the burden of showing a compelling need for it. Absent a compelling need,
the subpoena duces tecum should be quashed. Losavio v. Robb, 195 Colo. 533, 579
P.2d 1152 (1978); Alcon v. Spicer, 113 P.3d 735 (Colo. 2005).
Confidentiality factor in
deciding reasonableness of subpoena duces tecum. Although the policy of
confidentiality set forth in this section does not amount to a testimonial
privilege, it should carry great weight in deciding whether a subpoena duces
tecum is unreasonable or oppressive. Losavio v. Robb, 195 Colo. 533, 579 P.2d 1152
(1978).
39-21-114. Methods of enforcing
collection.
(1) The
executive director may issue a warrant executed either with his or her manual
signature or with his or her facsimile signature in accordance with the
"Uniform Facsimile Signature of Public Officials Act", article 55 of
title 11, directed to any employee, agent, or representative of the department,
sometimes in this section referred to collectively as "agent",
commanding the agent to distrain, seize, sell, or otherwise levy upon the
personal property of the taxpayer, except such personal property as is exempted
from execution and sale by any statute of this state, for the payment of the
tax due, together with any penalties and interest accrued thereon and the cost
of execution:
(a)
When any deficiency in tax is not paid within thirty days from the mailing of
notice and final determination therefor and no appeal from such deficiency has
been docketed with any district court of this state within said period; or
(b)
When any other amount of tax, penalty, or interest is not paid within ten days
from the mailing of demand for payment thereof; or
(c)
Immediately upon making of a jeopardy assessment or of the issuance of a demand
for payment, as provided in section 39-21-111.
(d)
(Deleted by amendment, L. 2002, p. 1362, § 18, effective July 1, 2002.)
(2) (a)
The agent charged with the collection shall make or cause to be made an account
of the goods or effects distrained, a copy of which, signed by the agent making
such distraint, shall be left with the owner or possessor, or at his usual
place of abode with some member of his family over the age of eighteen years,
or at his usual place of business with his stenographer, bookkeeper, or chief
clerk, or, if the taxpayer is a corporation, shall be left with any officer,
manager, general agent, or agent for process, with a note of the sum demanded
and the time and place of sale; and shall forthwith cause to be published a
notice of the time and place of sale, together with a description of the
property to be sold, in some newspaper of general circulation within the county
wherein distraint is made or, in lieu thereof and in the discretion of the
executive director of the department of revenue, the agent shall cause such
notice to be publicly posted at the courthouse of the county wherein such
distraint is made, copies thereof to be posted in at least two other public
places within said county. The time fixed for the sale shall not be less than
ten days nor more than sixty days from the date of such notification to the
owner or possessor of the property and the publication or posting of such
notices. Said sale may be adjourned from time to time by said agent if he deems
it advisable but not for a time to exceed in all ninety days from the date
first fixed for the sale. When any personal property is advertised for sale
under distraint as aforesaid, the agent making the seizure shall proceed to
sell such property at public auction, offering the same at not less than a fair
minimum price, including the expenses of making the seizure and of advertising
the sale, and, if the amount bid for the property at the sale is not equal to
the fair minimum price so fixed, the agent conducting the sale may declare the
same to be purchased by him for the state. The property so purchased may be
sold by the agent under such regulations as may be prescribed by the executive
director. In any case of distraint for the payment of taxes, the goods,
chattels, or effects so distrained shall be restored to the owner or possessor
if, prior to the sale, the amount due is paid together with the fees and other
charges or may be redeemed by any person holding a chattel paper or other
evidence of right of possession.
(b) In
all cases of sale, the agent making the sale shall issue a certificate of sale
to each purchaser, and the certificate is prima facie evidence of the right of
the agent to make the sale and conclusive evidence of the regularity of the
proceedings in making the sale and transfers to the purchaser all right, title,
and interest of the taxpayer in and to the property sold free and clear of all
liens and encumbrances junior to the department; and, where such property
consists of certificates of stock in the possession of the agent, the
certificate of sale is notice, when received, to any corporation, company, or
association of the transfer, and the certificate of the sale provides the
authority for such corporation, company, or association to record the transfer
on its books and records; and, where the subject of sale is securities or other
evidences of debt in the possession of the agent, the certificate of sale
provides the holder with good and valid evidence of title as against any other
person; and, where the subject of the sale is a motor vehicle, the certificate
of sale is notice, when received, to any public official charged with the
registration of title to motor vehicles, of the transfer, grants authority to
the public official to record the transfer on the books and records in the same
manner as if the certificate of title to the motor vehicle were transferred or
assigned by the holder of the certificate of title, and renders void all
previously issued titles to the motor vehicle. Any surplus remaining above the
taxes, penalties, interest, costs, and expenses of making the seizure and of
advertising the sale must be returned to the owner or any other person having a
legal right thereto, and, on demand, the executive director shall render an
account in writing of the sale.
(3) The
agent of the executive director of the department of revenue to whom a warrant
has been issued may file with the clerk of any district court within this state
a copy of said warrant, and thereupon the clerk shall enter in the judgment
docket, in appropriate columns, the name of the taxpayer mentioned in the
warrant, the amount of the tax, or a portion thereof, together with interest
and penalties for which the warrant is issued, and the date upon which such
copy is filed and shall issue and deliver a transcript of such judgment to the
agent without cost. Said transcript so issued and delivered may be filed with
the clerk and recorder of any county, and, from the time of such filing, such
judgment shall become a lien upon all the real property of the judgment debtor
in such county owned by him at the time or which he may afterwards acquire
until said lien expires. The lien shall continue for six years from the entry
of the judgment unless the judgment is previously satisfied, all in the same
manner as is provided by statute for making a judgment of a court of record a
lien on real property. The judgment so entered shall have the same force and
effect as other judgments of a court of record, and execution upon the real and
personal property of the judgment debtor and redemption thereof may be had as
provided by law with respect to other judgments. The executive director and his
agent may cause execution to be had thereon by the proper sheriff or other
officer, and such sheriff or other officer shall be entitled to the same fees
for his services to be collected in the same manner as in the case of other
executions.
(4) Any
employee, agent, or representative of the executive director of the department
of revenue to whom warrant has been issued may file a notice of lien in such
form as the executive director may prescribe with the person in possession of
any personal property or rights to property belonging to the taxpayer, and the
filing of such notice of lien shall operate as a lien upon such personal
property or rights to property from the date of such filing. Any costs incurred
by the person in possession of such property or rights to property by reason of
compliance with said notice of lien shall be paid by the executive director and
recovered by him out of any proceeds of sale of the property subject thereto.
The executive director may release said lien as to any part or all of the
property or rights to property covered by any such lien upon such terms as he
may deem proper.
(5)
Nothing in this section shall be construed to abrogate or diminish the rights
of bona fide purchasers, lienors, or pledgees for value and without notice.
(6) The
executive director of the department of revenue may be made a party defendant
in an action at law or a suit in equity by any person aggrieved by the unlawful
seizure or sale of his personal property, but only the state of Colorado shall
be responsible for any final money judgment secured against said executive
director; and said judgment, so secured, shall be paid or satisfied out of the
tax refund provided by section 39-21-108 (2) upon presentation by the judgment
creditor to the executive director of two certified copies of said final
judgment.
(7) If
any person, firm, or corporation liable for the payment of any tax covered by
this article has repeatedly failed, neglected, or refused to pay the same
within the time specified for such payment and the department has been required
to issue distraint warrants to enforce the collection of any taxes due from
such taxpayer, the executive director of the department of revenue is
authorized to assess and collect the amount of such taxes due, together with
all interest and penalties thereon provided by law, and also the following
additional penalties for recurring distraint warrants:
(a)
Three, four, or five consecutive distraint warrants issued: Fifteen percent of
the delinquent taxes, interest, and penalties due or the sum of twenty-five
dollars, whichever amount is greater;
(b) Six
or more consecutive distraint warrants issued: Thirty percent of the delinquent
taxes, interest, and penalties due or the sum of fifty dollars, whichever
amount is greater.
(8) (a)
In order to facilitate and expedite the collection of taxes more than six
months overdue from a taxpayer who is not a resident of nor domiciled in the
state of Colorado, the executive director may enter into a contract with a debt
collection agency or an attorney for the collection of the taxes due from such
taxpayer together with any penalties and interest accrued thereon.
(b) For
purposes of paragraph (a) of this subsection (8), the executive director may
contract with a debt collection agency or an attorney doing business in the
state of Colorado or in any other state; except that, prior to entering into
such contract with a debt collection agency, the executive director shall
require that the debt collection agency file a bond in the amount of one
hundred thousand dollars, which bond shall run to the state of Colorado for the
purpose of guaranteeing compliance with the terms of the contract. Such bond
shall be executed by the debt collection agency as principal and by a
corporation, which is licensed to transact the business of fidelity and surety
insurance, as surety.
(b.5)
In order to facilitate and expedite the collection of taxes more than twelve
months overdue from a taxpayer who is a resident of and domiciled in the state
of Colorado, the executive director may enter into contracts with two or more
debt collection agencies or attorneys for the collection of the taxes due from
such taxpayer, together with any penalties and interest accrued thereon
pursuant to the procurement provisions of article 103 of title 24, C.R.S. For
the purposes of this paragraph (b.5), the executive director may contract with
debt collection agencies or attorneys doing business in the state of Colorado
or in any other state; except that, prior to entering into such a contract with
a debt collection agency, the executive director shall require that the debt
collection agency file a bond in the amount of no less than one hundred
thousand dollars and no more than five hundred thousand dollars, which bond
shall run to the state of Colorado for the purpose of guaranteeing compliance
with the terms of the contract. Such bond shall be executed by a debt
collection agency as principal and by a corporation, which is licensed to
transact the business of fidelity and surety insurance, as surety.
(c) (I)
Each contract entered into with a debt collection agency or an attorney shall
specify that fees for services rendered shall be based on the total amount of
delinquent taxes, including accrued penalties and interest, that is actually
collected; however, under no circumstance shall the fees for services rendered
exceed twenty percent of the total amount of delinquent taxes, including
accrued penalties and interest, that is actually collected. Any fees for
services rendered shall be collected by the agency or attorney in addition to
the total amount of delinquent taxes, including accrued penalties and interest,
actually collected. Such fees for services rendered shall be shown to the
taxpayer as a separate and distinct item, and, when added, such fees for
services rendered shall be a debt from the taxpayer to the agent or attorney
until paid and shall be recoverable at law in the same manner as other debts.
(II) If
the department enters into a contract with a debt collection agency or an
attorney to collect delinquent taxes, including accrued penalties and interest,
and any fees for services rendered as specified in subparagraph (I) of this
paragraph (c) and the contract specifies that the department is required to
collect the fees for services rendered if the taxpayer chooses to pay the total
amount owed directly to the department, the department shall become the agent
for the agency or attorney and collect the agency's or attorney's fees for
services rendered on behalf of the agency or attorney.
(III)
If a taxpayer makes a payment toward the total amount a debt collection agency
or attorney is attempting to collect, including delinquent taxes, accrued
penalties and interest, and any fees for services rendered as specified in
subparagraph (I) of this paragraph (c), such payment shall be allocated among
delinquent taxes, accrued penalties and interest, and fees for services
rendered according to the rules or procedures of the department and the
contract between the department and the agency or attorney. The taxpayer may
not designate the allocation of the payment.
(IV) No
costs except court costs shall be reimbursed unless authorized in such
contract. If a debt collection agency or an attorney files a civil suit to
collect delinquent taxes, including accrued penalties and interest, suit shall
be brought in the name of the executive director of the department of revenue
of the state of Colorado. When suit is brought by an agency or attorney, court
costs are reimbursable by the department to the agency or attorney, but fees
for services of legal representation incurred by such agency or attorney on
behalf of the department for the purpose of such suit shall not be
reimbursable.
(d) A
debt collection agency or an attorney shall, pursuant to contract, remit the
total amount of delinquent taxes, including accrued penalties and interest,
collected, less allowable reimbursable costs, to the executive director within
thirty days from the date the moneys are collected from the taxpayer.
(e) The
executive director may prescribe forms to be used in implementing this
subsection (8).
(9) The
executive director, under such terms and conditions as he deems advisable, may
enter into a reciprocal agreement with an agency of another state for the
collection of delinquent taxes owed by individuals who are nonresidents of the
state of Colorado. Under such an agreement, the agency would agree to collect
delinquent taxes owed to the state of Colorado by taxpayers who are residing or
domiciled in that state. In return, the executive director would undertake the
collection of taxes of the same or similar type owed to the other state by
taxpayers residing or domiciled in the state of Colorado.
(10)
(a) The executive director is authorized to enter into an agreement with the
controller for the purpose of collecting delinquent state taxes through the
vendor offset program established pursuant to section 24-30-202.4 (3.5)(a),
C.R.S.
(b)
Each agreement entered into with the controller shall specify that fees for
services rendered shall be based on the total amount of delinquent taxes,
including accrued penalties and interest, that is actually collected through
the vendor offset program established pursuant to section 24-30-202.4 (3.5)(a),
C.R.S.
(c) The
controller shall, pursuant to agreement, remit the total amount actually offset
from a vendor's account pursuant to section 24-30-202.4 (3.5)(a), less fees for
services rendered and allowable costs, to the executive director within thirty
days after the date the moneys are offset from the vendor's account.
(11) In
addition to any other remedies available to the department, any district court
in the state has jurisdiction and venue to make and issue orders as may be
necessary for the collection of any tax, interest, or penalty, including, upon
ex parte application by an employee, agent, or representative of the department
and a showing of probable cause, warrants to search premises to distrain,
seize, and sell the taxpayer's personal property.
Source:
L. 65: p. 1143, §
2. C.R.S. 1963: § 138-9-13. L. 76: IP(1) amended, p. 776, § 1,
effective April 3. L. 77: (1)(d) added and (7) R&RE, pp. 842, 1774,
§§ 8, 1, effective July 1. L. 84: (8) and (9) added, p. 1015, § 1,
effective April 12. L. 87: (8)(b), (8)(c), and (8)(d) amended and
(8)(b.5) added, p. 1424, § 1, effective July 10. L. 97: (10) added, p.
945, § 5, effective July 1. L. 2002: (1)(c) and (1)(d) amended, p. 1362,
§ 18, effective July 1. L. 2010: (8)(c) and (8)(d) amended, (HB
10-1055), ch. 33, p. 124, § 1, effective March 22. L. 2019: IP(1) and
(2)(b) amended and (11) added, (SB 19-035), ch. 64, p. 231, § 2, effective
August 2.
ANNOTATION
Law reviews. For
article, "An Introduction to Tax Liens", see 13 Colo. Law. 399
(1984). For article, "Survey of Colorado Tax Liens", see 14 Colo.
Law. 1765 (1985).
Judgment upon distraint
warrant without service of process constitutional. A judgment entered upon
a warrant of distraint as provided in subsection (3) without service of process
upon the taxpayer is not invalid and void and does not deprive the taxpayer of
his property without due process of law. Liebhardt v. Dept. of Rev., 123 Colo.
369, 229 P.2d 655 (1951).
Lien for state income tax
which predates federal tax lien has priority under federal law. Eggleston
v. Colo., 636 F. Supp. 1312 (D. Colo. 1986).
Taxpayer may proceed under
subsection (6) or § 24-4-106, where a jeopardy assessment has been made without
a notice of deficiency and a distraint warrant and seizure have been pursued
under this section. Flores v. Dept. of Rev., 802 P.2d 1175 (Colo. App.
1990).
State tax lien was not
extinguished by merger when the state bought property at the tax sale to
avoid sale for an inadequate price. Such action by the state supported
inference that it intended to preserve its lien on the property. U.S. v. State
of Colo., 872 F.2d 338 (10th Cir. 1989).
In order to enforce liens
for sales taxes, the department of revenue may activate its liens by
recording the notice of delinquency pursuant to § 39-26-118 or by the more
immediate means of distraint in accordance with this section. ITT Diversified
Credit Corp. v. Couch, 669 P.2d 1355 (Colo. 1983).
Notice by publication held
inadequate to advise secured lienholder of tax sale; lienholder was
entitled to receive notice of tax sale by mail or personal service. Fact that
secured lienholder might have taken steps to safeguard its interest by
requiring owner to file a bond is irrelevant to the issue of whether notice was
adequate. Omnibank Iliff, N.A. v. Tipton, 843 P. 2d 71 (Colo. App. 1992).
Where secured lienholder had
known and conflicting claim, trial court erred in ruling that owner of
property seized by the department of revenue for nonpayment of tax and sold at
tax sale was, as a matter of law, entitled to surplus proceeds from the tax
sale. Omnibank Iliff, N.A. v. Tipton, 843 P.2d 71 (Colo. App. 1992).
39-21-114.5. Surrender of property
subject to levy - definition.
(1) For
any person in possession of property or rights to property owned by or owing to
a taxpayer that is subject to levy:
(a) (I)
Except as provided in subsection (1)(a)(II) of this section, a person shall,
upon demand of the executive director, surrender the property or the rights to
the property subject to levy to the executive director.
(II) A
person is not required to surrender the property or the rights to the property
belonging to the taxpayer that is subject to levy to the executive director if
the person, at the time of the demand, has a valid right of setoff or an
interest superior to the department's.
(b) If
the person is a bank or other financial institution, the bank or other
financial institution shall surrender any deposits in the bank or financial
institution within twenty-one days after service of the levy.
(c) If
the person is an employer, the employer shall surrender salary or wages within
twenty-one days after the end of the taxpayer's pay period. The effect of a
levy on salary or wages payable to or received by a taxpayer is continuous from
the date the levy is first made until the department releases the levy. The
levy for any pay period may not exceed twenty-five percent of the taxpayer's
disposable earnings. For purposes of this section, "disposable
earnings" has the same meaning as set forth in section 13-54-104 (1).
(2) Any
person who fails to or refuses to surrender property or rights to property
owned by or owing to a taxpayer that is subject to levy upon demand by the
executive director is liable to the state for a sum equal to the value of the
property or the rights to the property that is not surrendered, not to exceed
the amount of the liability for which the levy was made. Any amount recovered
under this subsection (2) is credited against the liability for which the levy
was made.
(3) Any
person in possession of property or rights to the property belonging to a
taxpayer that is subject to levy and upon which a levy has been made, who, upon
demand by the executive director, surrenders such property or rights to the
property to the executive director or who pays the liability required under
subsection (2) of this section is discharged from any obligation or liability
to the taxpayer and any other person with respect to the property or rights to
the property arising from the surrender or payment.
Source:
L. 2019: Entire
section added, (SB 19-035), ch. 64, p. 232, § 3, effective August 2.
39-21-115. Reciprocity with other
states for collection of taxes provided.
(1) Any
state of the United States or any political subdivision thereof has the right
to sue in the courts of the state of Colorado to recover any lawfully imposed
taxes which may be owing it, whether or not the taxes have been reduced to
judgment, when the like right is accorded to the state of Colorado and its
political subdivisions by that state through statutory authority or granted as
a matter of comity. The appropriate officials of such other states are
authorized to bring action in the courts of this state for the collection of
such taxes. The certificate of the secretary of state of such other state that
such officials have the authority to collect the taxes to be collected by such
action shall be the conclusive proof of authority.
(2) The
attorney general or an appropriate official of any political subdivision of the
state of Colorado may bring suit in the courts of other states to collect taxes
legally due this state or any political subdivision thereof.
(3)
"Taxes" as used in this section includes:
(a) Any
tax assessments lawfully made, whether they are based upon a return or other
disclosure of the taxpayer, or upon the information and belief of the taxing
authority, or otherwise;
(b) Any
penalties lawfully imposed pursuant to a taxing statute; and
(c)
Interest charges lawfully added to the tax liability which constitutes the
subject of the action.
(4)
Repealed.
Source:
L. 69: p. 1144, §
1. C.R.S. 1963: § 138-9-18. L. 2001: (4) added, p. 780, § 14,
effective June 1. L. 2009: (4) repealed, (HB 09-1053), ch. 159, p. 692,
§ 17, effective August 5.
39-21-116. Closing agreements.
(1) For
the purpose of facilitating the settlement and distribution of estates, trusts,
receiverships, or other fiduciary relationships, corporations, limited
liability companies, and partnerships in the process of dissolution or which
have been dissolved, the executive director of the department of revenue may
agree with the fiduciary or surviving directors or limited liability company
members or partnership members upon the amount of taxes due from the decedent,
or from the decedent's estate, the trust, receivership, or other fiduciary
relationship or corporation or limited liability company or partnership, for
any of his or its taxable periods, under the provisions of the taxes covered by
this article; and, except upon a showing of fraud, malfeasance, or
misrepresentation of a material fact, payment in accordance with such agreement
shall be full satisfaction of the taxes for the taxable periods to which the
agreement relates. In addition, the executive director or any person authorized
in writing by him may agree to enter into an agreement with any person, or the
person or estate for whom he acts, relating to the liability of such person in
respect of any tax within the provisions of this article for any prior taxable
period. Any such agreement shall be final and conclusive; and, except upon a
showing of fraud, malfeasance, or misrepresentation of a material fact, the
case shall not be reopened as to matters agreed upon or the agreement modified
by any officer, employee, or agent of this state; and, in any suit, action, or
proceeding, such agreement, or any determination, assessment, collection,
payment, abatement, refund, or credit made in accordance therewith, shall not
be annulled, modified, set aside, or disregarded.
(2)
Except as provided in subsection (4) of this section, any personal
representative of a decedent or of the estate of a decedent, or any trustee,
receiver, or other person acting in a fiduciary capacity, or any director or
officer of a corporation or any member of a partnership or limited liability
company in the process of dissolution or which has been dissolved who
distributes the estate or fund in his control without having first paid any
taxes covered by this article due from such decedent, decedent's estate, trust
estate, fund, corporation, partnership, or limited liability company shall be
personally liable to the extent of the property so distributed for any unpaid
taxes of the decedent, decedent's estate, trust estate, receivership,
corporation, partnership, or limited liability company covered by this article
which may be assessed within the time limited by section 39-21-107.
(3) The
distributee of a decedent's estate or of a trust estate or fund, the
stockholder of any dissolved corporation, or the member of any dissolved
partnership or limited liability company who receives any of the property of
such decedent's estate, trust estate, fund, corporation, partnership, or
limited liability company shall be liable, to the extent of the property so
received, for any unpaid income tax of the decedent, decedent's estate, trust
estate, fund, corporation, partnership, or limited liability company covered by
this article which may be assessed within the time limited by section
39-21-107. Notice to such distributee, stockholder, partnership member, or
limited liability company member shall be given in the same manner and within
the time limit which would have been applicable had there been no distribution.
(4) (a)
In case a tax covered by this article is due from a decedent, or from his
estate, or from a corporation, limited liability company, or partnership, in
order for personal liability under subsection (2) of this section to remain in
effect, determination of the tax due shall be made and notice and demand
therefor shall issue within eighteen months after written request for such
determination, filed after the filing of the decedent's final return or filed
after the filing of the return of the decedent's estate with respect to which
such request is applicable, by any personal representative of such decedent or
by the corporation, limited liability company, or partnership, filed after the
filing of its return; but a request under this provision shall not extend the
period of limitation otherwise applicable.
(b)
This subsection (4) shall not apply in the case of a corporation, limited
liability company, or partnership unless:
(I)
Such request notifies the executive director of the department of revenue that
the corporation, limited liability company, or partnership contemplates
dissolution at or before the expiration of such eighteen-month period;
(II)
The dissolution is begun in good faith before the expiration of such
eighteen-month period; and
(III)
The dissolution is completed.
(c)
Upon the expiration of said eighteen-month period, without determination being
made and notice and demand being issued, the personal representative of the
decedent, the directors and officers of the corporation, or the members of the
limited liability company or partnership no longer will be liable under the
provisions of subsection (2) of this section.
Source:
L. 65: p. 1146, §
2. C.R.S. 1963: § 138-9-14. L. 75: (1) amended, p. 1485, § 1,
effective July 1. L. 77: Entire section amended, p. 1776, § 1, effective
July 1. L. 90: Entire section amended, p. 451, § 30, effective April 18.
ANNOTATION
Law reviews. For
article, "Income Taxes During Estate Administration", see 29 Dicta 19
(1952). For note, "The Tax Liability of the Executor", see 28 Rocky
Mt. L. Rev. 95 (1955). For article, "Administration of Testate
Estates", see 29 Rocky Mt. L. Rev. 557 (1957).
39-21-116.5. Penalties - repeal.
(1) In
addition to the personal liability provided in section 39-21-116, all officers
of a corporation and all members of a partnership or a limited liability
company required to collect, account for, and pay over any tax administered by
this article 21 who willfully fail to collect, account for, or pay over such
tax or who willfully attempt in any manner to evade or defeat any such tax, or
the payment thereof, are subject to, in addition to other penalties provided by
law, a penalty equal to one hundred fifty percent of the total amount of the
tax not collected, accounted for, paid over, or otherwise evaded. An officer of
a corporation or a member of a partnership or a limited liability company shall
be deemed to be subject to this section if the corporation, partnership, or
limited liability company is subject to filing returns or paying taxes
administered by this article 21 and if such officers of corporations or members
of partnerships or limited liability companies voluntarily or at the direction of
their superiors assume the duties or responsibilities of complying with the
provisions of any tax administered by this article 21 on behalf of the
corporation, partnership, or limited liability company.
(2) (a)
This section does not apply to the temporary sales tax deduction and retention
allowed in section 39-26-105 (1.3).
(b)
This subsection (2) is repealed, effective December 31, 2026.
Source:
L. 77: Entire
section amended, p. 1777, § 2, effective July 1. L. 85: Entire section
amended, p. 1253, § 3, effective January 1, 1986. L. 90: Entire section
amended, p. 452, § 31, effective April 18. L. 2020, 1st Ex. Sess.:
Entire section amended, (HB 20B-1004), ch. 3, p. 25, § 6, effective December 7.
Cross
references: For
the legislative declaration in HB 20B-1004, see section 1 of chapter 3, Session
Laws of Colorado 2020, First Extraordinary Session.
ANNOTATION
Title of corporate president
does not necessarily include the responsibility of tax compliance. This
section is applicable only to those corporate officers responsible for tax
compliance who willfully fail to collect, account for, or pay taxes. Hanson v.
Colo. Dept. of Rev., 140 P.3d 256 (Colo. App. 2006).
39-21-117. Saving clause.
The
provisions of section 13-52-108, C.R.S., shall not apply to methods of
enforcing collections provided in this article.
Source:
L. 65: p. 1150, §
4. C.R.S. 1963: § 138-9-16.
39-21-118. Criminal penalties - repeal.
(1) A
person who willfully attempts in any manner to evade or defeat a tax
administered by the department or the payment thereof, in addition to other
penalties provided by law, is guilty of a class 6 felony and, upon conviction
thereof, shall be punished as provided in section 18-1.3-401 or shall be
punished by a fine of not more than one hundred thousand dollars, or five
hundred thousand dollars in the case of a corporation, or by both such fine and
imprisonment, together with the costs of prosecution.
(2) (a)
Any person required, or any person who purports to be required, under any title
administered by the department to collect, account for, or pay over any tax,
who willfully fails to collect or truthfully account for or pay over such tax,
including, but not limited to, willfully making a materially false statement in
connection with an application for a refund of any tax for the purpose of
falsely obtaining a refund of such tax, in addition to other penalties provided
by law, is guilty of a class 5 felony and, upon conviction thereof, shall be
punished as provided in section 18-1.3-401, or shall be punished by a fine of
not more than one hundred thousand dollars, or five hundred thousand dollars in
the case of a corporation, or by both such fine and imprisonment, together with
the costs of prosecution.
(b) (I)
Subsection (2)(a) of this section does not apply to the temporary sales tax
deduction and retention allowed in section 39-26-105 (1.3).
(II)
This subsection (2)(b) is repealed, effective December 31, 2026.
(2.5)
Any person who through gross negligence or recklessness makes a materially
false statement in applying for a refund pursuant to section 39-26-703 or any
other person who makes a false statement in connection with an application for
a refund is guilty of a misdemeanor and, upon conviction, shall be punished by
a fine of not more than five hundred dollars, or by imprisonment in the county
jail for not more than ninety days, or by both such fine and imprisonment.
(3) Any
person required under any title administered by the department to pay any tax
or estimated tax, or required under such title or by regulations made under
authority thereof to make a return, keep any records, or supply any
information, who willfully fails to pay such tax or estimated tax, make such
return, keep such records, or supply such information, at the time or times
required by law or regulations, in addition to other penalties provided by law,
is guilty of a misdemeanor and, upon conviction thereof, shall be fined not
more than fifty thousand dollars, or one hundred thousand dollars in the case
of a corporation, or imprisoned not more than one year, or both, together with
the costs of prosecution.
(4) Any
person who willfully makes and subscribes any return, statement, or other
document, which contains or is verified by a written declaration that it is
made under the penalties of perjury, and which he or she does not believe to be
true and correct as to every material matter, is guilty of a class 5 felony
and, upon conviction thereof, shall be punished as provided in section
18-1.3-401, C.R.S., or shall be punished by a fine of not more than one hundred
thousand dollars, or five hundred thousand dollars in the case of a
corporation, or by both such fine and imprisonment, together with the costs of
prosecution.
(5) Any
person who willfully aids or assists in, or procures, counsels, or advises the
preparation or presentation under, or in connection with any matter arising
under any title administered by the department, or a return, affidavit, claim,
or other document, which is fraudulent or is false as to any material matter,
whether or not such falsity or fraud is with the knowledge or consent of the
person authorized or required to present such return, affidavit, claim, or
document, is guilty of a class 5 felony and, upon conviction thereof, shall be
punished as provided in section 18-1.3-401, C.R.S., or shall be punished by a
fine of not more than one hundred thousand dollars, or five hundred thousand
dollars in the case of a corporation, or by both such fine and imprisonment,
together with the costs of prosecution.
Source:
L. 77: Entire
section added, p. 1773, § 2, effective July 1. L. 85: Entire section
R&RE, p. 1253, § 4, effective January 1, 1986. L. 89: (1), (2), (4),
and (5) amended, p. 852, § 144, effective July 1. L. 2002: (1), (2),
(4), and (5) amended, p. 1556, § 348, effective October 1. L. 2011: (2)
amended and (2.5) added, (HB 11-1265), ch. 228, p. 977, § 2, effective May 27. L.
2020, 1st Ex. Sess.: (2) amended, (HB 20B-1004), ch. 3, p. 25, § 7,
effective December 7. L. 2023: (1) amended, (HB 23-1293), ch. 298, p.
1797, § 66, effective October 1.
Editor's
note: Section 5 of
chapter 228, Session Laws of Colorado 2011, provides that the act amending
subsection (2) and adding subsection (2.5) applies to all claims for refunds of
sales or use tax filed with the department of revenue before, on, or after May
27, 2011.
Cross
references: (1)
For civil penalties, see §§ 39-22-621, 39-23.5-110, 39-26-115, 39-26-118,
39-26-204, 39-27-105, 39-28-108, and 39-29-115.
(2) For the legislative
declaration contained in the 2002 act amending subsections (1), (2), (4), and
(5), see section 1 of chapter 318, Session Laws of Colorado 2002. For the
legislative declaration in the 2011 act amending subsection (2) and adding
subsection (2.5), see section 1 of chapter 228, Session Laws of Colorado 2011.
For the legislative declaration in HB 20B-1004, see section 1 of chapter 3,
Session Laws of Colorado 2020, First Extraordinary Session.
ANNOTATION
The department of revenue is
a "victim" under § 18-1.3-602 and entitled to restitution when a
defendant is convicted of evading the state's marijuana excise taxes under
subsection (1) of this section. People v. Le, 2022 COA 32, 512 P.3d 146.
A person who willfully fails
to pay sales taxes due the state at the time required may be charged under
subsection (2) and prosecuted for commission of a felony. People v. Rea, 7
P.3d 995 (Colo. App. 1999).
Subsection (2) applies to
persons required to collect, account for, or pay over any tax; whereas
subsection (3) applies to any person required to pay any tax. Subsections
(2) and (3) cover different behavior, and a person charged with violating
subsection (2), which is a felony, need not be also charged with violating
subsection (3), which is a misdemeanor. People v. Rea, 7 P.3d 995 (Colo. App.
1999).
39-21-119. Filing with executive
director - when deemed to have been made.
(1) (a)
Any report, claim, tax return, statement, or other document required or
authorized to be filed with or any payment made to the executive director that
is transmitted through the United States mail is deemed filed with and received
by the executive director on the date shown by the cancellation mark stamped on
the envelope or other wrapper containing the document required to be filed.
(b) Any
such document which is mailed, but not received by the executive director, or
is received and the cancellation mark is not legible, or is erroneous or
omitted shall be deemed to have been filed and received on the date it was
mailed if the sender establishes by competent evidence that the document was
deposited in the United States mails on or before the date due for filing. In
such cases of nonreceipt of a document by the executive director, the sender
shall file a duplicate copy thereof within thirty days after written
notification is given to the sender by the executive director of the failure to
receive such document.
(2) If
any report, claim, tax return, statement, remittance, or other document is sent
by United States registered mail, certified mail, or certificate of mailing, a
record authenticated by the United States postal service of such registration,
certification, or certificate shall be considered competent evidence that the
report, claim, tax return, statement, remittance, or other document was mailed
to the executive director, to the state officer or state agency to which it was
addressed, and the date of the registration, certification, or certificate
shall be deemed to be the postmark date.
(3) If
the date for filing any report, claim, tax return, statement, remittance, or
other document falls upon a Saturday, Sunday, or legal holiday, it shall be
deemed to have been timely filed if filed on the next business day.
(4) The
date of receipt of returns or other documents made, filed, signed, subscribed,
verified, transmitted, received, or stored under the alternative methods
provided in sections 39-21-119.5 and 39-21-120 are determined pursuant to rules
and regulations adopted by the executive director pursuant to section 39-21-112
(1).
Source:
L. 77: Entire
section added, p. 1404, § 3, effective July 1. L. 82: (1)(a) amended, p.
559, § 3, effective April 6. L. 93: (4) added, p. 429, § 2, effective
April 19. L. 2001: (1)(a) amended, p. 780, § 15, effective June 1. L.
2009: (1)(a) amended, (HB 09-1053), ch. 159, p. 693, § 18, effective August
5. L. 2021: (1)(a) amended, (HB 21-1157), ch. 118, p. 454, § 1,
effective September 7. L. 2023: (4) amended, (SB 23-208), ch. 357, p.
2140, § 1, effective August 7.
39-21-119.5. Mandatory electronic filing
of returns - mandatory electronic payment - penalty - waiver - definitions.
(1) For
purposes of this section, "return" means any report, claim, tax
return statement, or other document required or authorized under articles 11
and 25 of title 29, article 11 of title 30, articles 22, 26, 27, 28, 28.5,
28.6, 28.8, 29, and 37 of this title 39, article 2 of title 40, article 3 of
title 42, article 4 of title 43, and title 44, and any form, statement report,
or other document prescribed by the executive director for reporting a tax
liability, a fee liability, or other information required to be returned to the
executive director, including the reporting of changes or amendments thereto,
and any schedule certification, worksheet, or other document required to
accompany the return.
(2)
Except as provided in subsection (6) of this section, the executive director
may, as specified in subsection (3) of this section, require the electronic
filing of returns and require the payment of any tax or fee due by electronic
funds transfer for the following:
(a) Any
income tax return required for:
(I) A C
corporation pursuant to section 39-22-601 (2);
(II) An
S corporation pursuant to section 39-22-601 (2.7), including the information
reports required by section 39-22-601 (2.7)(b), composite returns filed on
behalf of nonresident shareholders, and agreements filed under section
39-22-601 (2.7)(e);
(III) A
fiduciary pursuant to section 39-22-601 (3), including withholding for
nonresident beneficiaries pursuant to section 39-22-601 (4);
(IV) A
partnership pursuant to section 39-22-601 (5.5), including the information
reports required by section 39-22-601 (5.5)(b), composite returns filed on
behalf of nonresident partners, and agreements filed under section 39-22-601
(5.5)(e); and
(V) A
person or organization exempt from tax pursuant to section 39-22-601 (7).
(b) Any
payment of income tax required by:
(I)
Withholding for transfers of Colorado real property pursuant to section
39-22-604.5;
(II)
Estimated payments by a C corporation pursuant to section 39-22-606; and
(III)
Income tax payments due with return filing pursuant to section 39-22-609, but
not for individuals who are required to file a return pursuant to section
39-22-601 (1);
(c) Any
remittance of wage withholding required to be made by an employer pursuant to
section 39-22-604 that is not already required to be remitted electronically
pursuant to subsection (4)(g) of this section;
(d) Any
withholding of income report required to be filed for any oil and gas interest
pursuant to section 39-29-111;
(e) Any
severance tax return from any oil and gas interest required to be filed
pursuant to section 39-29-112;
(f) Any
sales tax return required to be filed pursuant to section 39-26-105;
(g) Any
sales tax return required to be filed by a person with a direct payment permit
issued pursuant to section 39-26-103.5;
(h) Any
use tax return to be filed and payment required to be paid pursuant to sections
39-26-204 (1)(a) or (2);
(i) Any
motor fuel tax or fee return required to be filed and payment required to be
made pursuant to section 39-27-303;
(j) and
(k) Repealed.
(l) Any
public utility return required to be filed pursuant to section 40-2-111 and the
payment required to be made pursuant to section 40-2-113;
(m) Any
passenger-mile tax return to be filed and payment required to be made pursuant
to section 42-3-308;
(n) Any
liquor excise tax return required to be filed and payment required to be made
pursuant to section 44-3-503 (3);
(o) Any
direct shipper return required to be filed pursuant to section 44-3-503 (5) and
the payment required to be made pursuant to section 44-3-503 (6);
(p) Any
county lodging tax return required to be filed and payment required to be made
pursuant to section 30-11-107.5;
(q) Any
marketing and promotion tax return required to be filed and payment required to
be made pursuant to section 29-25-112 (1)(b)(I);
(r) Any
daily vehicle rental fee report required to be filed and payment required to be
made pursuant to section 43-4-804 (1)(b)(II);
(s) Any
prepaid wireless 911 charge report required to be filed and payment required to
be made pursuant to section 29-11-102.5 (3);
(t) Any
prepaid telephone disability access charge report required to be filed and
payment required to be made pursuant to section 40-17-104;
(u) Any
retail delivery fee or enterprise retail delivery fees return required to be
filed pursuant to section 43-4-218 (6); and
(v) Any
prepaid wireless 988 charge report required to be filed and payment required to
be made pursuant to section 40-17.5-104 (2).
(3) The
executive director shall promulgate rules in accordance with article 4 of title
24 to implement mandatory electronic filing and electronic funds transfers for
the returns and payments described in subsection (2) of this section for
taxable periods beginning on and after January 1, 2020, or on and after the
date when the executive director establishes a system for electronic filing and
electronic funds transfers, whichever occurs later. Mandatory electronic filing
and mandatory payment by electronic funds transfers must be staggered for each
tax type over a period of not less than three years, must begin with large
taxpayers, and may allow additional time for small taxpayers to comply. The
thresholds for each implementation group shall be determined by the executive
director in his or her discretion.
(4)
Except as provided in subsection (6) of this section, on and after August 2,
2019, electronic filing of returns and the payment of any tax or fee by
electronic funds transfer is required for the following:
(a) Any
income tax return claiming an enterprise zone credit required to be filed
pursuant to section 39-30-111;
(b) Any
withholding of income required to be made from any oil and gas interest
pursuant to section 39-29-111;
(c) Any
sales tax remittance required to be paid pursuant to section 39-26-105.5;
(d) (I)
Any gasoline or special fuel report required to be filed pursuant to section
39-27-105;
(II)
Any road usage fee report or bridge and tunnel impact fee report required to be
filed with a gasoline or special fuel report pursuant to section 43-4-217 (7);
(e) Any
retail marijuana excise tax return required to be filed and payment required to
be made pursuant to section 39-28.8-304;
(f) Any
retail marijuana sales tax return required to be filed and payment required to
be paid pursuant to section 39-28.8-202;
(g) Any
remittance of wage withholding required to be made pursuant to section
39-22-604 by an employer whose annual estimated wage withholding tax liability
exceeds fifty thousand dollars;
(h) Any
cigarette excise tax return required to be filed and payment required to be
made pursuant to article 28 of this title 39;
(i) Any
tobacco products excise tax return required to be filed and payment required to
be made pursuant to article 28.5 of this title 39;
(j) Any
nicotine products tax return required to be filed and payment required to be
paid pursuant to article 28.6 of this title 39;
(k) Any
clean fleet per ride fee and air pollution mitigation per ride fee return
required to be filed and payment required pursuant to section 40-10.1-607.5;
(l) Any
quarterly report for the advance payment of an income tax credit required to be
filed pursuant to section 39-22-629 (2)(b);
(m) Any
production fee for wildlife and land remediation and production fee for clean
transit return required to be filed and payment required to be made pursuant to
article 61 of title 33 and section 43-4-1204;
(n) The
information return from long-term care employers required to be filed pursuant
to section 39-22-566 (5); and
(o) Any
firearms and ammunition excise tax return required to be filed and any payment
of tax required to be remitted pursuant to article 37 of this title 39.
(5) (a)
If any person fails or refuses to file a return electronically as specified in
this section, the department shall collect a penalty of fifty dollars for such
failure or five percent of the proper amount of tax on such return, whichever
is greater.
(b) If
any person fails to pay by electronic funds transfer any tax or fee, including
any addition to tax, due to the executive director as specified in this
section, the department shall collect a penalty of fifty dollars for such
failure or five percent of the proper amount of tax on such return, whichever
is greater.
(c) As
used in subsections (5)(a) and (5)(b) of this section, "tax" means
the net amount of tax shown to be due on the return filed by the taxpayer and
reduced by the amount of any credit against the tax which may be claimed on the
return. If the penalties provided for in subsections (5)(a) and (5)(b) of this
section both apply, only the larger of the two penalties may be assessed.
(d) (I)
Any tax preparer preparing a tax return shall be required to file returns
electronically and pay any tax or fee by electronic funds transfers if the
taxpayer is required to do so pursuant to this section.
(II) A
penalty assessed against the taxpayer pursuant to subsection (5)(a) or (5)(b)
of this section must be assessed against the taxpayer and may not be assessed
against the tax preparer.
(e) A
penalty assessed against the taxpayer pursuant to subsection (5)(a) or (5)(b)
of this section is assessed, collected, and paid in the same manner as the tax
or fee to which such penalty relates.
(f) The
executive director may waive for good cause shown any penalty assessed pursuant
to this subsection (5).
(6) (a)
Any person who is required to file returns electronically or make the payment
of any tax or fee by electronic funds transfer pursuant to this section may
apply to the executive director, on a form prescribed by the department, for an
annual waiver from the requirements set forth in this section. The executive
director may grant a request for a waiver, and may grant a renewal request for
one subsequent year, if any of the following apply:
(I) The
taxpayer does not have a computer;
(II)
The taxpayer does not have internet access; or
(III)
The taxpayer shows good cause for why the filing of returns electronically or
making the payment of any tax or fee by electronic funds transfer would cause
undue hardship.
(b) The
executive director may waive the requirement to file returns electronically if
the return cannot be filed electronically for reasons beyond the taxpayer's
control, including situations in which the taxpayer is instructed by either the
internal revenue service or the department to file by paper.
(c) The
executive director shall not require any taxpayer required to remit a tax by
electronic funds transfers to remit the tax prior to the deadline specified for
taxpayers who remit the tax by other means; except that the executive director
may require a taxpayer to remit a tax by electronic funds transfers at an
earlier hour on the day of the deadline for making a return and paying the tax
due than taxpayers who remit the tax by other means.
(7) (a)
In order to induce the electronic payment of taxes and fees administered under
section 39-21-102, the executive director may deduct processing costs from the
payment in lieu of imposing a convenience fee, and if the processing costs are
deducted from the payment, the executive director shall credit the full amount
of the payment collected to the taxpayer's account. Processing costs may be
deducted by the executive director under this subsection (7) regardless of if
electronic payment is mandated under this section.
(b)
Notwithstanding any provision to the contrary, if the executive director
deducts processing costs pursuant to this subsection (7), the state treasurer
shall credit the full amount of the payment collected less the deducted
processing costs to the appropriate fund.
(c) If
the executive director is required to distribute payment to a local government,
the executive director shall deduct the processing costs from state revenue and
shall not reduce the amount distributed to the local government.
(d) As
used in this subsection (7):
(I)
"Convenience fee" means the convenience fee that a state governmental
entity is authorized to impose on a person that uses alternative forms of payment
under section 24-19.5-103 (3).
(II)
"Processing costs" means the actual costs incurred by the department
to process a transaction by an alternative form of payment for which the
department is authorized to impose a convenience fee.
Source:
L. 2019: Entire
section added, (HB 19-1256), ch. 395, p. 3510, § 1, effective August 2. L.
2020: (2)(s) amended, (HB 20-1293), ch. 267, p. 1298, § 15, effective July
10; (2)(c) and (4)(e) amended, (2)(j) and (2)(k) repealed, and (4)(g), (4)(h),
and (4)(i) added, (HB 20-1175), ch. 88, p. 355, § 2, effective September 14;
(1), (4)(e), and (4)(f) amended and (4)(j) added, (HB 20-1427), ch. 248, p.
1211, § 24, effective January 1, 2021. L. 2021: (2)(i), (2)(s), (2)(t),
(4)(d), (4)(i), and (4)(j) amended and (2)(u) and (4)(k) added, (SB 21-260),
ch. 250, p. 1401, § 13, effective June 17; (4)(d) amended, (HB 21-1322), ch.
453, p. 3020, § 12, effective January 1, 2022. L. 2022: (7) added, (SB
22-006), ch. 160, p. 1006, § 2, effective August 10. L. 2023:
(2)(a)(III), (2)(a)(IV), (4)(j), and (4)(k) amended and (2)(a)(V) and (4)(l)
added, (HB 23-1272), ch. 167, p. 816, § 23, effective May 11; (2)(a)(II) and
(2)(a)(IV) amended, (HB 23-1277), ch. 290, p. 1755, § 6, effective January 1,
2024. L. 2024: (4)(k) and (4)(l) amended and (4)(m) added, (SB 24-230),
ch. 184, p. 1024, § 10, effective May 16; (4)(k) and (4)(l) amended and (4)(n)
added, (HB 24-1312), ch. 294, p. 2006, § 2, effective August 7; (1), (4)(k),
and (4)(l) amended and (4)(o) added, (HB 24-1349), ch. 423, p. 2905, § 17,
effective December 17 (see editor's note). L. 2025: (2)(t) amended, (HB
25-1154), ch. 230, p. 1087, § 29, effective January 1, 2026. L. 2026:
(2)(t) and (2)(u) amended and (2)(v) added, (HB 26-1115), ch. 17, p. 82, § 6,
effective March 26.
Editor's
note: (1) Section
27(2) of chapter 248 (HB 20-1427), Session Laws of Colorado 2020, provides that
changes to this section take effect on the date of the governor's proclamation
or January 1, 2021, whichever is later, only if, at the November 2020 statewide
election, a majority of voters approve the ballot issue referred in accordance
with section 39-28-401. The ballot issue, referred to the voters as proposition
EE, was approved on November 3, 2020, and was proclaimed by the Governor on
December 31, 2020. The vote count for the measure was as follows:
FOR: 2,134,608
AGAINST: 1,025,182
(2) Amendments to subsection
(4)(d) by HB 21-1322 and SB 21-260 were harmonized, effective January 1, 2022.
(3) Amendments to subsection
(2)(a)(IV) by HB 23-1272 and HB 23-1277 were harmonized, effective January 1,
2024.
(4) Subsections (4)(k) and
(4)(l) were amended in HB 24-1349. Those amendments were superseded by the
amendment of those subsections in HB 24-1312 and SB 24-230.
(5) Section 19(1) of chapter
423 (HB 24-1349), Session Laws of Colorado 2024, provides that the act changing
this section takes effect on the date of the official declaration of the vote
thereon by the governor only if, at the November 2024 statewide election, a
majority of voters approve the ballot issue referred in accordance with §
39-37-201. The ballot issue, referred to the voters as Proposition KK, was
approved on November 5, 2024, and was proclaimed by the Governor on December
17, 2024, see L. 2025, p. 3636. The vote count for the measure was as follows:
FOR: 1,675,123
AGAINST: 1,406,112
Cross
references: For
the legislative declaration in SB 21-260, see section 1 of chapter 250, Session
Laws of Colorado 2021. For the legislative declaration in SB 22-006, see
section 1 of chapter 160, Session Laws of Colorado 2022. For the legislative
declaration in HB 23-1272, see section 1 of chapter 167, Session Laws of
Colorado 2023.
39-21-120. Signature and filing
alternatives for tax returns.
(1) The
executive director may prescribe alternative methods for the making, filing,
signing, subscribing, verifying, transmitting, receiving, or storing of returns
or other documents pursuant to the statutory provisions of this article 21 and
other articles referenced in this article 21. The executive director shall
adopt rules as may be appropriate to define and implement acceptable
alternatives for each article within the scope of this section.
(2) Any
return or other document signed, subscribed, or verified under any method
adopted under subsection (1) of this section shall be treated for all purposes,
including penalties for perjury, in the same manner as if verified by
signature.
(3) To
enable alternative filing of tax returns, the executive director is hereby
authorized to contract for communications services with governmental or private
contractors. Such contractors shall be subject to the provisions of section
39-21-113 (4), and each contract entered into pursuant to this subsection (3)
shall set forth the provisions of section 39-21-113 (4) and (6).
Source:
L. 93: Entire
section added, p. 428, § 1, effective April 19. L. 2001: (1) amended, p.
781, § 16, effective June 1. L. 2009: (1) amended, (HB 09-1053), ch.
159, p. 693, § 19, effective August 5. L. 2019: (1) amended, (SB
19-241), ch. 390, p. 3475, § 49, effective August 2; (1) amended, (HB 19-1256),
ch. 395, p. 3514, § 2, effective August 2. L. 2021: (1) amended, (HB
21-1157), ch. 118, p. 454, § 2, effective September 7.
Editor's
note: Amendments
to subsection (1) by SB 19-241 and HB 19-1256 were harmonized.
39-21-121. Unclaimed property offset -
definition.
(1) (a)
The department shall periodically certify to the state treasurer, acting as the
administrator of unclaimed property under the "Revised Uniform Unclaimed
Property Act", article 13 of title 38, information regarding persons who
are liable for the payment of taxes, penalties, or interest imposed pursuant to
articles 22 to 33 of this title 39 that are delinquent and in distraint.
(b) The
information described in paragraph (a) of this subsection (1) shall include the
social security number or federal employer identification number, whichever is
applicable, of the person owing the delinquent taxes, penalties, or interest,
the amount owed, and any other identifying information required by the state
treasurer.
(2) (a)
Before paying a claim for unclaimed property pursuant to section 38-13-905, the
state treasurer shall compare the social security number or federal employer
identification number, whichever is applicable, of the claimant with those
certified by the department pursuant to subsection (1) of this section. If the
name and associated social security number or federal employer identification
number of a claimant appears among those certified, the state treasurer shall
obtain the current address of the claimant, suspend the payment of the claim,
and notify the department. The notification shall include the name, home
address, and social security number or federal employer identification number
of the claimant.
(b)
After receipt of the notification from the state treasurer that a person
claiming unclaimed property pursuant to section 38-13-903 appears among those
certified by the department pursuant to subsection (1) of this section, the
department shall notify the person, in writing, that the state intends to
offset the person's delinquent state taxes, penalties, or interest liability
against the person's claim for unclaimed property.
(3)
Except as otherwise provided in section 38-13-902.1 (2), upon notification by
the state treasurer of the amounts of unclaimed property held pursuant to
section 38-13-902.3, the department shall apply such amounts to the person's
delinquent state tax liability.
(4) The
department shall promulgate rules pursuant to article 4 of title 24, C.R.S.,
establishing procedures to implement this section.
(5) For
purposes of this section, "claim for unclaimed property" means a cash
claim submitted in accordance with section 38-13-903.
Source:
L. 2005: Entire
section added, p. 701, § 6, effective August 8. L. 2019: (1)(a), (2),
(3), and (5) amended, (SB 19-088), ch. 110, p. 471, § 20, effective July 1,
2020.
39-21-122. Revenue impact of 2010 tax
legislation - tracking by department. (Repealed)
Source:
L. 2010: Entire
section added, (HB 10-1189), ch. 5, p. 38, § 2, effective February 24; entire
section added, (HB 10-1190), ch. 6, p. 42, § 3, effective February 24; entire
section added, (HB 10-1191), ch. 7, p. 47, § 4, effective February 24; entire
section added, (HB 10-1193), ch. 9, p. 56, § 3, effective February 24; entire
section added, (HB 10-1194), ch. 10, p. 59, § 2, effective February 24; entire
section added, (HB 10-1195), ch. 11, p. 63, § 2, effective February 24; entire
section added, (HB 10-1196), ch. 12, p. 66, § 3, effective February 24; entire
section added, (HB 10-1199), ch. 13, p. 67, § 1, effective February 24; entire
section added, (HB 10-1192), ch. 8, p. 52, § 5, effective March 1; entire
section added, (HB 10-1197), ch. 175, p. 635, § 3, effective August 11. L.
2011: (7) repealed, (HB 11-1005), ch. 194, p. 755, § 2, effective July 1;
(4)(b) added by revision, (HB 11-1293), ch. 299, pp. 1437, 1440, §§ 3, 6. L.
2016: Entire section repealed, (HB 16-1026), ch. 36, p. 91, § 1, effective
March 22.
PART
2
TAX
AMNESTY PROGRAM
Editor's
note: This part 2
was repealed in 1987 and was subsequently recreated and reenacted in 2003,
resulting in the addition, relocation, and elimination of sections as well as
subject matter. For amendments to this part 2 prior to 1987, consult the
Colorado statutory research explanatory note and the table itemizing the
replacement volumes and supplements to the original volume of C.R.S. 1973
beginning on page vii in the front of this volume.
39-21-201. Program established -
repeal. (Repealed)
Source:
L. 2003: Entire
part RC&RE, p. 504, § 1, effective March 5. L. 2005: (2) amended, p.
1069, § 16, effective January 1, 2006. L. 2011: (1), (2), (3)(a),
(3)(b), (3)(d), (4), and (8) amended and (6.5) added, (SB 11-184), ch. 290, p.
1345, § 1, effective June 3. L. 2024: (9) added by revision, (SB
24-025), ch. 144, pp. 579, 585, §§ 41, 55.
Editor's
note: Subsection
(9) provided for the repeal of this section, effective July 1, 2025. (See L.
2024, pp. 579, 585.)
39-21-202. Tax amnesty cash fund -
creation - uses - repeal. (Repealed)
Source:
L. 2011: Entire
section added, (SB 11-184), ch. 290, p. 1347, § 2, effective June 3.
Editor's
note: Subsection
(3) provided for the repeal of this section, effective January 1, 2016. (See L.
2011, p. 290.)
PART
3
TAX
PROFILE AND EXPENDITURE REPORT
39-21-301. Legislative declaration.
(1) The
general assembly hereby finds and declares that:
(a) The
general assembly uses both direct expenditure of government funds and special
or selective tax relief, which is known as a tax expenditure, to further
various public policy goals;
(b) A
tax expenditure differs from a direct spending program because a direct
spending program continues only if funds are appropriated for each budget
period, while the continuation of a tax expenditure generally does not require
any legislative action;
(c) In
addition, a direct spending program is generally detailed on the expenditure
side of the budget, but a tax expenditure is simply included on the revenue
side of the budget without itemization;
(d) A
tax expenditure should receive a periodic and comprehensive review as to its
total cost and effectiveness in achieving its objectives;
(e) It
is important that state government be accountable and transparent in such a way
that the general public can understand the value of tax expenditures given by
the state; and
(f) In
the past, the department of revenue has published a Colorado tax profile study,
which included a substantial amount of useful information about state and local
taxes.
(2) In
enacting this part 3, it is the intent of the general assembly to create a
means for providing the general assembly and the public with this vital
tax-related information in a biennial tax profile and tax expenditure report.
(3) The
general assembly must spend its resources wisely and it is beneficial to the
state to know whether the tax expenditures that are in place are accomplishing
the goals they were intended to meet. In enacting section 39-21-305, it is the
intent of the general assembly that the state auditor's evaluation will provide
the state with factual evidence of whether the state's tax expenditures achieve
the objectives they are intended to achieve, including economic development,
assisting beneficiaries, and promoting the health, safety, and welfare of the
public, including the business environment. Additionally, it is the intent of
the general assembly that the state auditor's evaluation:
(a)
Compares the state's tax expenditures with other state's tax expenditures;
(b)
Compares the effect of the state's tax expenditures on competition;
(c)
Measures the effect of the state's tax expenditures on business and stakeholder
needs;
(d) Determines
whether the state's tax expenditures are administered efficiently and
transparently with defined performance measures that support accountability;
and
(e)
Analyzes how the state's tax expenditures serve the public's interests by
protecting taxpayer dollars and how the state's tax expenditures ensure
cost-effectiveness.
Source:
L. 2011: Entire
part added, (SB 11-184), ch. 290, p. 1348, § 3, effective June 3. L. 2016:
(3) added, (SB 16-203), ch. 211, p. 816, § 1, effective August 10.
39-21-302. Definitions.
As used in
this part 3, unless the context otherwise requires:
(1)
"Colorado tax profile study 2001" means the "Colorado Tax
Profile Study 2001 and Statistics of Income" prepared in May 2004 by the
office of research and analysis in the department for the individual income tax
returns tax year 2000 and the corporate income tax returns filed in fiscal year
2002.
(1.3)
"Evaluation report" means the evaluation report that the state
auditor is required to prepare pursuant to section 39-21-305.
(1.5)
"State auditor" means the state auditor described in section 2-3-102,
C.R.S.
(2)
"Tax expenditure" means a tax provision that provides a gross or
taxable income definition, deduction, exemption, credit, or rate for certain
persons, types of income, transactions, or property that results in reduced tax
revenue.
(3)
"Tax profile and expenditure report" or "report" means the
biennial report that the department is required to prepare pursuant to section
39-21-303 (1).
Source:
L. 2011: Entire
part added, (SB 11-184), ch. 290, p. 1348, § 3, effective June 3. L. 2016:
(1.3) and (1.5) added, (SB 16-203), ch. 211, p. 817, § 2, effective August 10.
39-21-303. Tax profile and expenditure
report.
(1) On
or before January 1, 2013, and January 1 of every odd-numbered year thereafter,
the department shall prepare a tax profile and expenditure report for the state
that includes the information set forth in subsection (2) of this section.
(2) (a)
A tax profile and expenditure report must include the following information for
each tax expenditure for any tax levied and collected by the state that is
administered by the department:
(I) A
citation of the statutory or other legal authority for the tax expenditure;
(II)
The year that the tax expenditure was enacted;
(III) A
description of the tax expenditure;
(IV) An
estimate of the tax expenditure's effect on revenue for the most recently
completed tax or calendar year, as appropriate, for which such information is
available;
(V) The
estimate required pursuant to subparagraph (IV) of this paragraph (a) for the
tax expenditure that was included in each of the three prior tax profile and
expenditure reports, if available; and
(VI)
For a tax expenditure that is subject to the requirement set forth in section
39-21-304, a statement of the intended purpose of the tax expenditure.
(b) For
the state income tax only, the tax profile and expenditure report must include
the effect of the tax expenditure by income class. The provisions of this
paragraph (b) shall only apply to the extent that the department is capable of
accessing the necessary information from its data system.
(c) The
tax profile and expenditure report must include the sum of all estimates
required pursuant to subparagraphs (IV) and (V) of paragraph (a) of this
subsection (2) for each tax.
(d) (I)
To the extent not otherwise included in the tax profile and expenditure report
pursuant to this subsection (2), the report must also include any information
that was included in the Colorado tax profile study 2001 for any taxes covered
by such study, which includes but is not limited to information related to:
(A)
State and local tax collections;
(B)
Revenues, taxes, incidence, and equity;
(C) The
distribution of state and local taxes among households; and
(D)
Colorado statistics of income.
(II)
The information required pursuant to subparagraph (I) of this paragraph (d)
shall be for the most recent tax year for which such information is available.
(3) (a)
The department shall provide a copy of the report to all members of the general
assembly in accordance with section 24-1-136 (9), C.R.S.
(b)
Repealed.
(c) The
department shall make the tax profile and expenditure report available for
public inspection and shall publish the report on the department website.
(4) The
reporting requirement set forth in this section is exempt from the provisions
of section 24-1-136 (11).
(5) To
the extent that the tax profile and expenditure report must include the
distribution of tax burden by income class pursuant to paragraphs (b) and (d)
of subsection (2) of this section, the department shall use at least as many
income classes as the Colorado statistics of income in the Colorado tax profile
study 2001, and the highest income class shall be at least as high as in such
Colorado statistics of income.
(6)
Repealed.
Source:
L. 2011: Entire
part added, (SB 11-184), ch. 290, p. 1349, § 3, effective June 3. L. 2014:
(6) repealed, (HB 14-1018), ch. 35, p. 190, § 1, effective August 6. L.
2024: (3)(b) repealed and (4) amended, (HB 24-1036), ch. 373, p. 2533, §
29, effective August 7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-21-304. Tax expenditure - tax
preference performance statement - tax expenditure repeal requirement.
(1) (a)
On and after January 1, 2021, any bill that creates a new tax expenditure or
extends an expiring tax expenditure must include a tax preference performance
statement as part of a statutory legislative declaration.
(b) If
the bill extends an expiring tax expenditure, the bill must either include a
tax preference performance statement if one was not earlier included or it must
amend, in such a way as to provide updated information, the tax preference
performance statement that was included when the tax expenditure was enacted.
(2) The
tax preference performance statement must indicate one or more of the following
general categories, by reference to the applicable category specified in this
subsection (2), as the legislative purpose of the new tax expenditure:
(a) Tax
expenditure intended to induce certain designated behavior by taxpayers;
(b) Tax
expenditure intended to improve industry competitiveness;
(c) Tax
expenditure intended to create or retain jobs;
(d) Tax
expenditure intended to reduce structural inefficiencies in the tax structure;
or
(e) Tax
expenditure intended to provide tax relief for certain businesses or
individuals.
(3) In
addition to the general category specified in subsection (2) of this section, a
tax preference performance statement must also provide detailed information
regarding the legislative purpose of the new tax expenditure or of the
extension of the expiring tax expenditure. The required detailed information
must, at minimum, include clear, relevant, and ascertainable metrics and data
requirements that allow the general assembly and the state auditor to measure
the effectiveness of the tax expenditure in achieving the purpose designated
under this section.
(4) On
and after January 1, 2021, any bill that creates a new tax expenditure must
include a repeal of the expenditure after a specified period of tax years and
any bill that extends an expiring tax expenditure must extend the expenditure
for a specified period of tax years. A bill that creates a new tax expenditure
or extends an expiring tax expenditure may not establish the tax expenditure
for an indefinite period of time.
Source:
L. 2011: Entire
part added, (SB 11-184), ch. 290, p. 1351, § 3, effective June 3. L. 2020:
Entire section amended, (SB 20-021), ch. 185, p. 850, § 1, effective September
14.
39-21-305. Tax expenditure - state
auditor evaluation.
(1) (a)
The state auditor shall evaluate the state's tax expenditures pursuant to the
requirements in this section. In evaluating each tax expenditure, the state
auditor shall consult with the intended beneficiaries or representatives of the
intended beneficiaries of the tax expenditure. In addition, if the tax
expenditure is intended to benefit a specific geographic region of the state,
the state auditor shall consult with the intended beneficiaries in that
specific geographic region of the state.
(b) The
state auditor's tax expenditure evaluation must include the following:
(I) A
summary description of the purpose, intent, or goal of the tax expenditure;
(II)
The intended beneficiaries of the tax expenditure;
(III)
Whether the tax expenditure is accomplishing its purpose, intent, or goal;
(IV) An
explanation of the intended economic costs and benefits of the tax expenditure,
with analyses to support the evaluation if they are available or reasonably
possible;
(V) A
comparison of the tax expenditure to other similar tax expenditures in other
states;
(VI)
Whether there are other tax expenditures, federal or state spending, or other
government, nonprofit, commercial, volunteer, or philanthropic programs, to the
extent the information is readily available, that have the same or similar
purpose, intent, or goal as the tax expenditure, how those all are coordinated,
and if coordination could be improved, or whether any redundancies can be
eliminated;
(VII)
If the evaluation of a particular tax expenditure's economic impact is made
difficult because of data constraints, any suggestions for changes in
administration or law that would facilitate such data collection; and
(VIII)
An explanation of the performance measures used to determine the extent to
which the tax expenditure is accomplishing its purpose, intent, or goal. The
performance measures must be clear and relevant to the specific tax expenditure
being evaluated, should be measurable and track actionable goals, and can be
assessable and reportable over time. The state auditor shall consider the
original legislative intent as well as subsequent developments in the state's
economy, the national economy, and any changes in national, state, or local
fiscal policies and conditions.
(c) To
the extent it can be determined by the state auditor, the tax expenditure
evaluation should also include the following:
(I) The
extent to which the tax expenditure is a cost-effective use of resources
compared to other options for using the same resources to address the same
purpose, intent, or goal;
(II) An
analysis of the tax expenditure's effect on competition and on business and
stakeholder needs;
(III)
Whether there are any opportunities to improve the effectiveness of the tax
expenditure in meeting its purpose, intent, or goal; and
(IV) An
analysis of the effect of the state tax policies connected to local taxing
jurisdictions on the overall purpose, intent, or goal of the tax expenditure.
(c.5)
In addition to any other requirements in this section, the manner in which the
state auditor evaluates the state's tax expenditures is governed by the
following:
(I) New
tax expenditures will be evaluated in accordance with the schedule set by the
state auditor in subsection (1)(d) of this section;
(II)
Tax expenditures that have been evaluated by the state auditor in accordance
with this section do not need to be evaluated again, but the state auditor, in
the state auditor's discretion, may reevaluate tax expenditures if there have
been substantial changes to the tax expenditure;
(III)
Tax expenditures that are on the state auditor's schedule for evaluation but
have been repealed or are set to repeal within a year of the evaluation do not
need to be evaluated; and
(IV)
For a tax expenditure that is in effect for three years or less, the state
auditor shall make the auditor's best effort to prepare a report for the tax
expenditure using the best available data.
(d) (I)
No later than September 15, 2017, the state auditor shall develop and publish a
multi-year schedule that lists all tax expenditures in law as of July 1, 2017,
and indicates the year when the evaluation report will be published for each
tax expenditure. In developing the multi-year schedule the state auditor shall
endeavor to review the oldest tax expenditures first and shall endeavor to
review a tax expenditure with a statutory repeal date so that the evaluation
report for such tax expenditure is available during the legislative session
held in the calendar year before the tax expenditure is scheduled to repeal.
(II)
The state auditor may revise the schedule established in subsection (1)(d)(I)
of this section so long as the state auditor continues to provide for a
systematic evaluation of tax expenditures, including any new tax expenditures
enacted by the general assembly since the publication of a previous evaluation
report. In revising the schedule, the state auditor may consider when
sufficient data is expected to be available in order to review a tax
expenditure.
(e)
Notwithstanding section 2-3-103 (2), the state auditor shall present the
results in the form of an evaluation report that the state auditor shall ensure
is posted on the general assembly's website, and, notwithstanding section
24-1-136 (9), the state auditor shall deliver a copy of the report to the joint
budget committee and the finance committees of the senate and the house of
representatives. The state auditor shall ensure the first evaluation report is
delivered and posted no later than September 14, 2018, and shall ensure
subsequent evaluation reports are delivered and posted no later than June 30 of
each year thereafter.
(2) (a)
Any records, information, or documentation generated pursuant to this section
are work papers of the state auditor and shall be open to public inspection
only upon approval of a majority of members of the legislative audit committee
created in section 2-3-101, C.R.S. Only the specific work papers that the
legislative audit committee votes to approve for disclosure shall be open to
public inspection. Work papers that have not been specifically approved for
disclosure by a majority vote of the legislative audit committee shall remain
confidential. Under no circumstances shall the work papers be open to public
inspection prior to a completed report being posted as specified in paragraph
(e) of subsection (1) of this section.
(b) The
department of revenue must provide any requested information, analysis, or
data, if available and under the control of the department, as requested by the
state auditor; except that, if the request includes confidential information,
such information must remain confidential in the hands of the state auditor,
and the state auditor is subject to the same limitations specified in section
39-21-113.
(c) The
state auditor's authority set forth in section 2-3-107, C.R.S., applies to the
state auditor's evaluation set forth in this section.
Source:
L. 2016: Entire
section added, (SB 16-203), ch. 211, p. 817, § 3, effective August 10. L.
2024: (1)(c.5) added and (1)(d) and (1)(e) amended, (HB 24-1053), ch. 375,
p. 2544, § 1, effective June 4.
39-21-306. State auditor report -
federal tax law and changes that impact the state tax base.
(1)
Annually, the state auditor shall study and evaluate impacts to the state's
policy of using federal taxable income as the basis for Colorado taxable
income. The evaluation must include a review of federal tax law, including
changes, that may have a significant impact on the state's tax base or
otherwise impact taxable income within the state.
(2)
Notwithstanding sections 2-3-103 (2) and 24-1-136 (9), the state auditor shall
present the findings made pursuant to subsection (1) of this section in the
form of a report that must be posted on the general assembly's website and
delivered to the joint budget committee and the finance committees of the
senate and the house of representatives. The state auditor shall ensure that
the first report is delivered no later than June 30, 2025, and shall ensure
that subsequent reports are delivered no later than June 30 of each year
thereafter.
(3) (a)
Any records, information, or documentation generated pursuant to this section
are work papers of the state auditor and shall be open to public inspection
only upon approval of a majority of members of the legislative audit committee
created in section 2-3-101. Only the specific work papers that the legislative
audit committee votes to approve for disclosure shall be open to public
inspection. Work papers that have not been specifically approved for disclosure
by a majority vote of the legislative audit committee shall remain
confidential. Under no circumstances shall the work papers be open to public
inspection prior to a completed report being posted as specified in subsection
(2) of this section.
(b) (I)
The state auditor shall collaborate, at least annually, with the department
regarding the department's knowledge or awareness of:
(A) Any
expected impacts to the state's policy of using federal taxable income as the
basis for Colorado taxable income; and
(B)
Federal tax law changes that may have a significant impact on the state's tax
base or otherwise impact taxable income within the state.
(II) As
necessary to determine the impacts described in subsection (3)(b)(I) of this
section, the department shall provide the state auditor with statistics, so
classified as to prevent the identification of particular reports or returns
and the items thereof, to the extent authorized in section 39-21-113 (5),
section 6103 (d)(1) of the federal "Internal Revenue Code of 1986",
as amended, and the regulations and policies promulgated thereto.
(c) The
state auditor's authority set forth in section 2-3-107 applies to the state
auditor's report set forth in this section.
Source:
L. 2024: Entire
section added, (HB 24-1053), ch. 375, p. 2545, § 2, effective June 4.
PART
4
LEGISLATIVE
OVERSIGHT COMMITTEE CONCERNING TAX POLICY
39-21-401. Legislative declaration.
(1) The
general assembly finds and declares that:
(a) In
2000, the general assembly enacted the formation of a temporary commission on
taxation for the purpose of reviewing and reporting on the current system of
taxation by state and local governments and making recommendations for
modifications;
(b) The
state of Colorado and its citizens have experienced many changes since the last
comprehensive review and analysis of tax policy was completed;
(c) The
tax structure of the state and local governments in Colorado has become more
complicated and outdated through a long history of incremental and piecemeal
modifications made by statutory and constitutional enactments that have
resulted in unintended consequences;
(d)
These modifications may have resulted in the tax burden for financing
government services and programs being borne disproportionately by certain
taxpayers and may have diminished Colorado's ability to attract new businesses
and retain existing businesses that are vital to the economic well-being of the
state and its citizens; and
(e) It
is therefore necessary to review the state's current tax policy.
(2) The
general assembly further finds and declares that it is necessary to create the
legislative oversight committee concerning tax policy and, in addition,
establish the committee as the appropriate entity to review the evaluations of
tax expenditures that are statutorily completed by the state auditor.
Source:
L. 2021: Entire
part added, (HB 21-1077), ch. 468, p. 3365, § 1, effective July 7.
39-21-402. Definitions.
As used in
this part 4, unless the context otherwise requires:
(1)
"Legislative oversight committee" or "committee" means the
legislative oversight committee concerning tax policy established in section
39-21-403.
(2)
"Task force" means the task force concerning tax policy established
pursuant to section 39-21-404.
(3)
"Tax policy" refers to decisions by the state or local governments
regarding taxes that have or may be levied, and includes an analysis of the
benefits and burdens of the state's overall tax structure with respect to the
promotion of certainty, fairness, adequacy, transparency, and administrative
ease. The scope of "tax policy" to be considered by the committee and
the task force is annually determined by the committee as set forth in section
39-21-403 (2)(b).
Source:
L. 2021: Entire
part added, (HB 21-1077), ch. 468, p. 3366, § 1, effective July 7.
39-21-403. Legislative oversight
committee concerning tax policy - creation - duties - report - repeal.
(1) Creation.
(a)
There is hereby created a legislative oversight committee concerning tax
policy.
(b) The
committee consists of six members as follows:
(I) Two
senators appointed by the president of the senate and one senator appointed by
the minority leader of the senate; and
(II)
Two representatives appointed by the speaker of the house and one
representative appointed by the minority leader of the house of
representatives.
(c) (I)
Appointees to the committee must have experience with or interest in the study
areas of the committee and task force, as set forth in section 39-21-404.
(II)
Appointments must be made no later than fourteen days after July 7, 2021.
(d) The
terms of the members expire or terminate on the convening date of the first
regular session of the seventy-fourth general assembly. As soon as practicable
after such convening date, but no later than the end of the legislative
session, the speaker and minority leader of the house of representatives and
the president and minority leader of the senate shall each appoint or reappoint
members in the same manner as provided in subsection (1)(b) of this section.
Thereafter, the terms of members appointed or reappointed expire on the
convening date of the first regular session of each general assembly, and all
subsequent appointments and reappointments must be made as soon as practicable
after such convening date, but no later than the end of the legislative
session.
(e) The
person making the original appointment or reappointment shall fill any vacancy
by appointment for the remainder of an unexpired term. Members appointed or
reappointed serve at the pleasure of the appointing authority and continue
until the member's successor is appointed.
(f) The
speaker of the house of representatives shall select the first chair of the
committee, and the president of the senate shall select the first vice-chair.
The chair and vice-chair shall alternate annually thereafter between the two
houses.
(g) The
chair and vice-chair of the committee may establish such organizational and
procedural rules as are necessary for the operation of the committee and, in
collaboration with the task force, guidelines and expectations for ongoing
collaboration with the task force.
(h) (I)
(A) Members of the committee are entitled to receive compensation and
reimbursement of expenses as provided in section 2-2-326.
(B)
Notwithstanding subsection (1)(h)(I)(A) of this section, members of the
committee are not entitled to receive compensation and reimbursement of
expenses as provided in section 2-2-326 in the 2026 interim. This subsection
(1)(h)(I)(B) is repealed, effective July 1, 2027.
(II)
The director of research of the legislative council, the director of the office
of legislative legal services, and the state auditor shall supply staff
assistance to the committee as they deem appropriate, within existing
appropriations.
(2) Duties.
(a) (I)
(A) The committee shall meet at least four times each year and at such other
times as it deems necessary.
(B)
Repealed.
(C)
Notwithstanding subsection (2)(a)(I)(A) of this section, the committee shall
not meet during the 2026 interim. This subsection (2)(a)(I)(C) is repealed,
effective July 1, 2027.
(II)
Each committee member shall annually either attend or call in to at least one
regular task force meeting. Committee members are encouraged to attend separate
meetings and inform the rest of the committee about the current work of the
task force.
(b) The
committee shall annually define in writing, no later than the second meeting of
the year, the scope of tax policy to be considered for the committee and the
task force.
(c) (I)
(A) The committee shall consider the policy considerations contained in the
tax expenditure evaluations prepared by the state auditor pursuant to section
39-21-305 and the information contained in the reports prepared by the state
auditor pursuant to section 39-21-306 concerning a review of federal tax law,
including changes, that may have a significant impact on the state's tax base.
(B)
Notwithstanding the state auditor's schedule established pursuant to section
39-21-305 (1)(d), the committee may, in writing, direct the state auditor to
evaluate up to three additional specific tax expenditures to be included in the
state auditor's evaluation reports due for the following year pursuant to
section 39-21-305 (1)(e).
(C) The
committee may, in writing, request that the state auditor prepare up to two
reports annually on specific and discrete topics related to existing tax
policy. Not later than thirty days after receipt of the request, the state
auditor shall prepare for the committee chair a written proposed scope of work
concerning the request. Upon approval of the proposed scope of the work by the
committee chair, the state auditor shall proceed with the research and analysis
required to complete the requested report.
(II)
The committee is responsible for the oversight of the task force.
(d) (I)
The committee may recommend legislative changes that are treated as bills
recommended by an interim legislative committee for purposes of any
introduction deadlines or bill limitations imposed by the joint rules of the
general assembly.
(II)
Repealed.
(III)
(A) Notwithstanding subsection (2)(d)(I) of this section, the committee
shall not recommend legislation during the 2026 interim.
(B)
This subsection (2)(d)(III) is repealed, effective July 1, 2027.
(e) (I)
On or before January 1 of each year, the committee shall submit, and make
publicly available on its website, a report to the general assembly. The annual
report must briefly summarize the study issues, recommendations considered, and
any actions taken by the committee and the task force during the previous year.
The report must comply with the provisions of section 24-1-136 (9).
Notwithstanding section 24-1-136 (11)(a)(I), the requirement in this section to
report to the general assembly continues indefinitely.
(II)
Repealed.
(III)
(A) The committee shall not submit a report on or before January 1, 2027.
(B)
This subsection (2)(e)(III) is repealed, effective July 1, 2027.
Source:
L. 2021: Entire
part added, (HB 21-1077), ch. 468, p. 3366, § 1, effective July 7. L. 2024:
(2)(c)(I) amended, (HB 24-1053), ch. 375, p. 2546, § 3, effective June 4. L.
2025: (2)(a)(I), (2)(d), and (2)(e) amended, (SB 25-199), ch. 149, p. 568,
§ 9, effective April 30. L. 2026: (1)(h)(I) amended and (2)(a)(I)(C),
(2)(d)(III), and (2)(e)(III) added, (HB 26-1331), ch. 329, p. 1920, § 16,
effective June 2.
Editor's
note: Subsections
(2)(a)(I)(B), (2)(d)(II)(B), and (2)(e)(II)(B) provided for the repeal of
subsections (2)(a)(I)(B), (2)(d)(II), and (2)(e)(II), respectively, effective
July 1, 2026. (See L. 2025, p. 568.)
39-21-404. Task force concerning tax
policy - creation - membership - duties.
(1) Creation.
(a)
There is hereby created a task force concerning tax policy. The task force
consists of twenty-one members appointed as provided in subsections (1)(b),
(1)(c), and (1)(d) of this section.
(b)
Four nonvoting task force members, one appointment from each office, with
relevant experience in economics, budgeting, or tax policy, shall be appointed
by:
(I) The
director of research of the legislative council;
(II)
The director of the office of legislative legal services;
(III)
The staff director of the joint budget committee; and
(IV)
The state auditor.
(c)
Seventeen voting members shall be initially appointed no later than thirty days
after July 7, 2021, and held by the appointee until subsequent appointments are
made by the committee under subsection (1)(d) of this section, or until the
appointee is removed and replaced as allowed in subsection (1)(g) of this
section, as follows:
(I) A
representative of the office of state planning and budgeting appointed by the
governor or his or her designee;
(II) A
representative of the taxation division in the department of revenue appointed
by the governor or his or her designee;
(III) A
representative of the office of economic development appointed by the governor
or his or her designee;
(IV) A
representative of the office of the state treasurer appointed by the state
treasurer or his or her designee; and
(V)
Committee staff is responsible for publicly announcing vacancies for the
following positions, and requesting candidates to submit a letter of interest
for the specific position, so that the letters of interest are due no later
than one week after July 7, 2021. The initial appointments shall be made by a
majority decision of the speaker of the house of representatives, the president
of the senate, the house and senate minority leaders, and the governor or the
governor's designee:
(A) One
member from a state public or private institution of higher education with
knowledge of tax policy;
(B) One
member from a state public or private institution of higher education with
knowledge of economics;
(C)
Four members representing local government, including one from a home rule city
or city and county; one from a statutory city; one from a home rule county; and
one from a statutory county;
(D) Two
tax law practitioners who are not employed by a home rule or statutory city or
city and county;
(E) Two
certified public accountants with state and local tax experience who are not
employed by a home rule or statutory city or city and county;
(F) One
member representing a small business;
(G) One
member representing a large business; and
(H) One
member representing a nonprofit organization with expertise in tax policy.
(d)
Seventeen voting members shall be appointed or reappointed no later than
January 31, 2022, January 31, 2023, and no later than January 31 in every
odd-numbered year thereafter as follows:
(I) A
representative of the office of state planning and budgeting appointed or
reappointed by the governor or his or her designee;
(II) A
representative of the taxation division in the department of revenue appointed
or reappointed by the governor or his or her designee;
(III) A
representative of the office of economic development appointed or reappointed
by the governor or his or her designee;
(IV) A
representative of the office of the state treasurer appointed or reappointed by
the state treasurer or his or her designee; and
(V) The
chair of the committee in consultation with the vice-chair of the committee
shall appoint or reappoint, with input from the governor's office, the speaker
of the house of representatives, and the president of the senate, the following
voting members:
(A) One
member from a state public or private institution of higher education with
knowledge of tax policy;
(B) One
member from a state public or private institution of higher education with
knowledge of economics;
(C)
Four members representing local government, including one from a home rule city
or city and county; one from a statutory city; one from a home rule county; and
one from a statutory county;
(D) Two
tax law practitioners who are not employed by a home rule or statutory city or
city and county;
(E) Two
certified public accountants with state and local tax experience who are not
employed by a home rule or statutory city or city and county;
(F) One
member representing a small business;
(G) One
member representing a large business; and
(H) One
member representing a nonprofit organization with expertise in tax policy.
(e) If
the committee needs new candidates for the positions described in subsections
(1)(d)(V)(A) through (1)(d)(V)(H) of this section, then the committee chair may
request committee staff to publicly announce vacancies for any such positions,
and to request candidates to submit a letter of interest for the specific
position, so that the letters of interest are due no later than two weeks
before the appointing deadline set forth in subsection (1)(d) of this section.
(f)
Voting members of the task force serve without compensation.
(g) A
vacancy occurring in any position held by a voting member must be filled as
soon as possible by the appointing authority for that position set forth in
subsection (1)(d) of this section. In addition, the chair of the committee in
consultation with the vice-chair of the committee may remove any task force
appointee who is appointed pursuant to subsection (1)(c) or (1)(d) of this
section. Replacements for removed appointees are appointed by the respective
appointing authorities set forth in subsection (1)(d) of this section.
(h) In
appointing voting members to the task force pursuant to subsection (1)(d) of
this section, the respective appointing authorities shall ensure that the
membership of the task force includes persons who have experience with or
interest in the study areas of the task force as set forth in subsection (2) of
this section; persons who reflect a balance of tax perspectives and the ethnic,
cultural, and gender diversity of the state; representation of all areas of the
state; and, to the extent practicable, persons with disabilities.
(i) (I)
All task force members are expected to seek input from the various departments,
offices, or organizations they represent or that they are associated with, if
any.
(II) In
order to advance the work of the task force, task force members are encouraged
to participate in decision-making with the understanding that individual votes
on task force issues are based on subject matter expertise and do not commit
representative entities or organizations to any position or action. Task force
members shall adhere to any agreed upon procedural rules and guidelines.
(2) Issues
for study.
(a) The
task force shall study tax policy within its scope as annually defined by the
committee under section 39-21-403 (2)(b) and shall develop and propose tax
policy modifications for committee consideration.
(b) The
requirements set forth in this subsection (2) do not prohibit the task force,
at any time during its existence, from studying, presenting findings and
recommendations to the committee on, or requesting permission from the
committee to draft legislative proposals concerning any issue described in this
subsection (2).
(c)
Upon request by the task force, the office of the state auditor shall present
to the task force the policy considerations contained in the tax expenditure
evaluations prepared by the state auditor pursuant to section 39-21-305 and the
information contained in the reports prepared by the state auditor pursuant to
section 39-21-306 concerning a review of federal tax law, including changes,
that may have a significant impact on the state's tax base.
(3) Additional
duties of the task force. The task force shall annually deliver tax policy
and legislative recommendations to the committee pursuant to this section. In
addition, the task force shall:
(a) On
or before August 1 of each year, appoint a chair and vice-chair from among its
members;
(b)
Meet at least six times each year, or more often as directed by the chair of
the committee;
(c)
Establish organizational and procedural rules for the operation of the task
force and for collaboration with the committee;
(d)
Designate specific task force members responsible for collaborating with and
obtaining input from other state officials, groups, or task forces that
complement or relate to the task force's identified areas of study;
(e)
Create subcommittees as needed to carry out the duties of the task force. The
subcommittees may consist, in part, of persons who are not members of the task
force but have particular expertise related to the topics being studied. Such
persons may vote on issues before the subcommittee but are not entitled to vote
at task force meetings.
(f)
Upon request by a committee member, with approval from the committee chair in
consultation with the committee vice-chair, provide evidence-based feedback on
the potential benefits or consequences of a legislative or other policy
proposal not directly affiliated with or generated by the task force, including
any bill or resolution introduced by the general assembly that affects tax
policy. The feedback should, if possible, be delivered within two weeks to the
entire committee and remain as concise as possible while capturing any
available evidence. If the task force cannot identify evidence to effectively
inform a response, the feedback will indicate a lack of evidence and report on
any actions taken.
(g) On
or before October 1 of each year, prepare and submit to the committee, which
the committee may make publicly available on its website, a report that, at a
minimum, includes:
(I)
Issues studied by the task force, as well as findings for legislative or other
recommendations;
(II)
Legislative or policy proposals of the task force that identify the policy
issues involved, the agencies responsible for the implementation of the
changes, and the funding sources required for implementation;
(III) A
summary of monthly task force meeting activities and discussions;
(IV)
Any evidence-based feedback provided to the committee pursuant to subsection
(3)(f) of this section; and
(V) A
summary of efforts made to communicate, collaborate, or coordinate with other
groups or task forces.
(4) Coordination.
The task force may work with other state agencies, groups, or task forces that
are pursuing issues similar to those addressed in subsection (2) of this
section. The task force may develop relationships with other task forces,
committees, and organizations to leverage efficient policy-making opportunities
through collaborative efforts.
(5) Task
force funding - staff support.
(a) The
legislative council staff, the office of legislative legal services, and the
department of revenue shall supply staff assistance, within existing
appropriations, to the task force as the committee deems appropriate. If
existing appropriations are not adequate to supply staff assistance, the
director of the legislative council staff, the director of the office of
legislative legal services, or the director of the department of revenue shall
request additional necessary funding in their annual budget requests.
(b) Any
state department, agency, or office with an active representative on the task
force is authorized to receive and expend gifts, grants, and donations,
including donations of in-kind services for staff support, from any public or
private entity for any direct or indirect costs associated with the duties of
the task force.
Source:
L. 2021: Entire
part added, (HB 21-1077), ch. 468, p. 3368, § 1, effective July 7. L. 2024:
(2)(c) added, (HB 24-1053), ch. 375, p. 2547, § 4, effective June 4.
39-21-405. Repeal of part.
This part
4 is repealed, effective December 31, 2031.
Source:
L. 2021: Entire
part added, (HB 21-1077), ch. 468, p. 3373, § 1, effective July 7. L. 2024:
Entire section amended, (HB 24-1053), ch. 375, p. 2547, § 5, effective June 4.
Income
Tax
ARTICLE
22
Income
Tax
PART 1
GENERAL
39-22-101. Short title.
39-22-102. Legislative declaration.
39-22-103. Definitions - construction of
terms.
39-22-104. Income tax imposed on individuals,
estates, and trusts - single rate - report - tax preference performance
statement - legislative declaration - definitions - repeal.
39-22-104.5. Pretax payments - catastrophic
health insurance - repeal.
39-22-104.6. Pretax payments - medical savings
accounts - repeal.
39-22-105. Alternative minimum tax.
39-22-106. Colorado personal exemptions of a
resident individual.
39-22-107. Income tax filing status.
39-22-107.5. Income tax filing status - innocent
spouse relief.
39-22-108. Credit for tax paid other states.
39-22-108.5. Dual resident trusts - income tax
calculation.
39-22-109. Income of a nonresident individual
for purposes of Colorado income tax.
39-22-110. Apportionment of tax in the case of
a part-year resident.
39-22-110.5. Reacquisition of residency during
active duty military service.
39-22-111. Accounting periods and methods.
39-22-112. Persons and organizations exempt
from tax under this article.
39-22-113. Tax credit or refund for persons
with disabilities who are employed - amount - applicability. (Repealed)
39-22-114. Residential energy credit.
(Repealed)
39-22-114.5. Tax credit for investment in
technologies for recycling plastics - repeal.
39-22-115. Credit for crops or livestock
contributed to charitable organizations - definitions. (Repealed)
39-22-116. Tax tables for individuals.
39-22-117. Uninsurable health plan charge -
repeal. (Repealed)
39-22-118. Grants for members of United States
armed services - combat pay received during active duty in Operation Desert
Storm - amount - applicability - repeal. (Repealed)
39-22-119. Expenses related to child and
dependent care - refundable credit against state tax - tax preference
performance statement - legislative declaration - definition - repeal.
39-22-119.5. Child care expenses tax credit -
legislative declaration - definitions - repeal.
39-22-120. Legislative declaration - state
sales tax refund - offset against state income tax. (Repealed)
39-22-120.5. Unrefunded excess revenues.
(Repealed)
39-22-121. Credit for child care facilities -
legislative declaration - definitions - repeal.
39-22-122. Long-term care insurance credit.
39-22-123. Earned income tax credit - refund
of state excess revenues for fiscal years commencing on or after July 1, 1998.
39-22-123.5. Earned income tax credit -
legislative declaration - repeal.
39-22-123.7. Earned income tax credit - pilot
program - pre-populated tax return - rules - report - repeal.
39-22-124. Tax credit against state taxes -
legislative declaration - hearings and appeals. (Repealed)
39-22-125. Credit for health benefit plans -
definitions - mechanism to refund excess state revenues. (Repealed)
39-22-126. Credit for health care
professionals practicing in rural health care professional shortage areas -
legislative declaration - definitions. (Repealed)
39-22-127. Credit for providing foster care -
refund of excess state revenues for fiscal years commencing on or after January
1, 2000 - legislative declaration. (Repealed)
39-22-128. Credit for income eligible to be
deferred on sale of livestock due to weather-related conditions - repeal.
(Repealed)
39-22-129. Child tax credit - legislative
declaration - definitions - repeal.
39-22-130. Family affordability tax credit -
tax preference performance statement - legislative declaration - definitions -
repeal.
39-22-131. Family affordability credit - tax
preference performance statement - legislative declaration - definitions.
PART 2
PARTNERS AND PARTNERSHIPS
39-22-201. Partners, not partnership, subject
to tax.
39-22-201.5. Limited liability company members -
subject to tax. (Repealed)
39-22-202. Resident partners - definition.
39-22-202.5. Resident members. (Repealed)
39-22-203. Nonresident partners.
39-22-203.5. Nonresident members. (Repealed)
39-22-204. Accounting periods and methods.
39-22-204.5. Accounting periods and methods -
limited liability companies. (Repealed)
39-22-205. Limited liability company members.
(Repealed)
39-22-206. Foreign source income of export taxpayers.
PART 3
CORPORATIONS
SUBPART 1
C CORPORATIONS
39-22-300.1. Short title - citation.
39-22-301. Corporate tax imposed - repeal.
39-22-302. S corporations.
39-22-303. Dividends in a combined report -
foreign source income - affiliated groups - definitions - rules - repeal.
39-22-303.1. Interstate banking or branching -
nondiscriminatory tax treatment.
39-22-303.5. Single-factor apportionment of
business income - allocation of nonbusiness income - rules - definitions.
39-22-303.6. Market-based apportionment of the
income of a taxpayer engaged in business - allocation of nonapportionable
income - rules - definitions.
39-22-303.7. Sourcing of sales of mutual fund
service corporations - definitions.
39-22-303.9. Apportionment of the income of a
taxpayer with enterprise data center operations in the state - definitions.
39-22-304. Net income of corporation -
legislative declaration - definitions - repeal.
39-22-305. Consolidated returns.
39-22-306. Accounting periods and methods.
39-22-307. Credit allowed for prior payment of
impact assistance. (Repealed)
39-22-308. Credit allowed for purchase of
Colorado coal.
39-22-309. Tax credit for investment in
technologies for recycling plastics. (Repealed)
39-22-310. Legislative declaration - statutory
interpretation and construction.
SUBPART 2
S CORPORATIONS
39-22-320. Short title - citation.
39-22-321. Definitions.
39-22-322. Taxation of an S corporation and
its shareholders.
39-22-323. Modification and characterization
of income.
39-22-324. Basis and adjustments.
39-22-325. Carryforwards and carrybacks - loss
limitation.
39-22-326. Part-year residence.
39-22-327. Distributions.
39-22-328. Returns - repeal. (Repealed)
39-22-329. Tax credits.
39-22-330. Uniformity of application and
construction.
SUBPART 3
SALT PARITY ACT
39-22-340. Short title - citation.
39-22-341. Legislative declaration.
39-22-342. Definitions.
39-22-343. Election.
39-22-344. Imposition of tax.
39-22-345. Owner exclusion.
39-22-346. Credit for tax paid in other
states.
39-22-347. Credit for electing pass-through
entity owner - tax preference performance statement - legislative declaration.
PART 4
ESTATES AND TRUSTS
39-22-401. Income of a resident estate or
trust for purposes of Colorado income tax.
39-22-402. Share of a resident estate, trust,
or beneficiary in Colorado fiduciary adjustments.
39-22-403. Income of a nonresident estate or
trust subject to income tax.
39-22-404. Share of a nonresident estate,
trust, or beneficiary in income from sources within Colorado.
39-22-405. Colorado exemption and federal
income tax modification of nonresident estate or trust. (Repealed)
39-22-406. Special rule for accumulation
distributions. (Repealed)
39-22-407. Accounting periods and methods.
PART 5
SPECIAL RULES
39-22-501. Taxation of regulated investment
companies.
39-22-502. Adjustment to basis of shares of
regulated investment company. (Repealed)
39-22-503. Taxation of real estate investment
trusts - definitions.
39-22-504. Net operating losses.
39-22-504.5. Short title.
39-22-504.6. Definitions.
39-22-504.7. Medical savings accounts -
establishment - contributions - distributions - restrictions - taxation -
portability - repeal.
39-22-505. Oil and gas producers. (Repealed)
39-22-506. Tentative carry-back adjustment -
application - allowance. (Repealed)
39-22-507. Credits against tax - employer
expenses - work incentive programs. (Repealed)
39-22-507.5. Credits against tax - investment in
certain property - repeal.
39-22-507.6. Credits against corporate tax -
investment in certain property - repeal.
39-22-508. Credit for property taxes
attributable to pollution control property. (Repealed)
39-22-508.1. Short title. (Repealed)
39-22-508.2. Definitions - construction of
terms. (Repealed)
39-22-508.3. Special credit available - new
business facility - new employees. (Repealed)
39-22-508.4. Election to defer commencement of
credit. (Repealed)
39-22-508.5. Effect of transfers of new business
facilities. (Repealed)
39-22-508.6. Effect of termination of enterprise
or facility. (Repealed)
39-22-508.7. Effective date - termination date.
(Repealed)
39-22-509. Credit against tax - employer
expenditures for alternative transportation options for employees - legislative
declaration - definitions - repeal.
39-22-510. State-employed chaplains -
designation of rental allowance. (Repealed)
39-22-511. Credit against Colorado income
taxes based on cost of certificate purchased by persons in the business of the
transportation of ashes, trash, or other discarded materials. (Repealed)
39-22-512. Commercial, industrial, and
agricultural energy credit. (Repealed)
39-22-513. Credit to lending institutions for
making residential energy-related loans. (Repealed)
39-22-514. Tax credit for qualified costs
incurred in preservation of historic properties.
39-22-514.5. Tax credit for qualified costs
incurred in preservation of historic structures - commercial historic
preservation tax credit program cash fund - tax preference performance
statement - legislative declaration - short title - definitions.
39-22-515. Tax credit for qualified equipment
utilizing postconsumer waste. (Repealed)
39-22-516. Tax credit for purchase of vehicles
using alternative fuels - repeal. (Repealed)
39-22-516.5. Tax credit for innovative motor
vehicles - repeal. (Repealed)
39-22-516.7. Tax credit for innovative motor
vehicles - tax preference performance statement - legislative declaration -
definitions - repeal.
39-22-516.8. Tax credit for innovative trucks -
tax preference performance statement - legislative declaration - definitions -
repeal.
39-22-517. Tax credit for child care center
investments - repeal.
39-22-518. Tax modification for net capital
gains - definitions - repeal.
39-22-519. Tax credit for book value of
certificate for carriers of sludge - repeal. (Repealed)
39-22-520. Credit against tax - investment in
school-to-career program - definitions - repeal.
39-22-521. Credits against tax - employer
expenses - public assistance recipients - repeal.
39-22-522. Credit against tax - conservation
easements - definitions - tax preference performance statement - repeal.
39-22-522.5. Conservation easement tax credits -
dispute resolution - legislative declaration.
39-22-523. Credit against tax - contributions
to high technology scholarship program - mechanism to refund excess state
revenues. (Repealed)
39-22-524. Tax credit for individuals
contributing matching funds for individual development accounts - repeal.
(Repealed)
39-22-525. Contributions to Colorado institute
of technology - credit against tax. (Repealed)
39-22-526. Credit for environmental
remediation of contaminated land - legislative declaration - definition -
repeal.
39-22-527. Agricultural value-added tax
credit. (Repealed)
39-22-528. Tax credit for participation in agriculture
value-added cash fund. (Repealed)
39-22-529. Business expense deduction - labor
services - unauthorized alien - definitions.
39-22-530. Credit for employers that hire
persons with intellectual and developmental disabilities - definitions.
(Repealed)
39-22-531. Colorado job growth incentive tax
credit - definitions - tax preference performance statement - legislative
declaration - rules - repeal.
39-22-532. Advanced industry investment tax
credit - definitions.
39-22-533. Instream flow incentive tax credit
for water rights holders - rules - definitions - repeal. (Repealed)
39-22-534. Credit for estate taxes paid -
agricultural land - recapture - definitions. (Repealed)
39-22-535. Credit for purchase of uniquely
valuable motor vehicle registration numbers - repeal.
39-22-536. Credit for food contributed to
hunger-relief charitable organizations - definitions - repeal. (Repealed)
39-22-537. Credit for personal property taxes
paid - legislative declaration - definitions - repeal. (Repealed)
39-22-537.5. Credit for personal property taxes
paid - legislative declaration - definitions - repeal.
39-22-538. Credit for health-care preceptors
working in health professional shortage areas - legislative declaration -
definitions.
39-22-539. Credit for employer contributions
to employee 529 qualified state tuition programs - legislative declaration -
definitions - repeal.
39-22-540. Credit - organ donor - leave of
absence period - legislative declaration - definitions.
39-22-541. Credit for retrofitting a residence
to increase a residence's visitability - tax preference performance statement -
legislative declaration - definitions - repeal.
39-22-542. Employee ownership tax credit -
definitions - legislative declaration - repeal.
39-22-542.5. Tax credit for new employee-owned
businesses - employee ownership cash fund - tax preference performance
statement - legislative declaration - definitions - repeal.
39-22-543. Credit for wildfire hazard
mitigation expenses - legislative declaration - definitions - repeal.
39-22-544. Credit against tax - qualifying
seniors - creation - legislative declaration - definitions - repeal.
39-22-545. Credit against tax - heat pump
systems - heat pump water heaters - tax preference performance statement -
legislative declaration - definitions - repeal.
39-22-546. Credit against tax - residential
energy storage systems - tax preference performance statement - legislative
declaration - definition - repeal.
39-22-547. Early childhood educator income tax
credit - tax preference performance statement - legislative declaration -
definitions - repeal.
39-22-548. Colorado homeless contribution tax
credit - legislative declaration - definitions - repeal.
39-22-549. Credit against tax - small food
business recovery and resilience grant program equipment - community food
consortium duties and responsibilities - tax preference performance statement -
legislative declaration - definitions - repeal.
39-22-550. Tax credit for reducing emissions
from certain lawn equipment - tax preference performance statement -
legislative declaration - definitions - report - repeal.
39-22-551. Industrial clean energy tax credit
- tax preference performance statement - definitions - report - repeal.
39-22-552. Tax credit for expenditures made in
connection with a geothermal energy project - tax preference performance
statement - legislative declaration - definitions - repeal.
39-22-553. Geothermal electricity generation
production tax credit - tax preference performance statement - legislative
declaration - definitions - repeal.
39-22-554. Heat pump technology and thermal
energy network tax credit - tax preference performance statement - legislative
declaration - definitions - repeal.
39-22-555. Electric bicycle tax credit - tax
preference performance statement - legislative declaration - definitions -
repeal.
39-22-556. Tax credit for sustainable aviation
fuel production facility - tax preference performance statement - legislative
declaration - definitions - repeal.
39-22-556.5. Tax credit for the purchase of
sustainable aviation fuel - tax preference performance statement - legislative
declaration - definitions - repeal.
39-22-557. Clean hydrogen tax credit -
qualified uses - tax preference performance statement - definitions -
legislative declaration - repeal.
39-22-558. Tax credit for employer's
contribution to employee for eligible expenses in connection with a qualifying
home purchase - tax preference performance statement - legislative declaration
- definitions - repeal.
39-22-559. Film incentive tax credit - tax
preference performance statement - review - legislative declaration -
definitions - repeal.
39-22-560. Tax credit for certification of
aircraft to use unleaded aviation gasoline - tax preference performance
statement - review - legislative declaration - definitions - repeal.
39-22-561. Agricultural stewardship tax credit
- tax preference performance statement - legislative declaration - definitions
- rules - repeal.
39-22-562. Apprenticeship tax credit - tax
preference performance statement - legislative declaration - definitions -
rules - repeal.
39-22-563. Tax credit for freight rail use -
tax preference performance statement - legislative declaration - definitions -
repeal.
39-22-564. New railroad operator tax credit -
tax preference performance statement - legislative declaration - definitions -
rules - repeal.
39-22-565. Workforce shortage tax credit - tax
preference performance statement - report - legislative declaration -
definitions - repeal.
39-22-566. Qualified care worker tax credit -
tax preference performance statement - legislative declaration - definitions -
repeal.
39-22-567. Tax credit for investments in fixed
capital assets for a shared quantum facility - tax preference performance
statement - legislative declaration - definitions - report - repeal.
39-22-568. Quantum business loan loss reserve
income tax credit - tax preference performance statement - cash fund -
legislative declaration - definitions - report - repeal.
39-22-569. Community revitalization tax credit
- community revitalization tax credit program cash fund - tax preference
performance statement - legislative declaration - definitions - report -
repeal.
39-22-570. Tuition and fee tax incentive for
qualifying students - tax preference performance statement - report -
legislative declaration - definitions - repeal.
39-22-571. Film festival incentive tax credit
- tax preference performance statement - legislative declaration - definitions
- repeal.
PART 6
PROCEDURE AND ADMINISTRATION
SUBPART 1
GENERAL
39-22-600.3. Definitions.
39-22-601. Returns - repeal.
39-22-601.5. Reporting federal adjustments -
definitions.
39-22-602. Failure to make return - director
may make.
39-22-603. Returns not made under oath.
39-22-603.5. Frivolous returns.
39-22-604. Withholding tax - requirement to
withhold - tax lien - exemption from lien - annual statement - notice -
definitions - repeal.
39-22-604.3. Innovation reinvestment -
withholding - transfers - bioscience - clean technology - short title -
legislative declaration - definitions - repeal.
39-22-604.5. Withholding tax - transfers of
Colorado real property - nonresident transferors.
39-22-605. Failure by individual to pay
estimated income tax.
39-22-606. Failure by corporation to pay
estimated income tax.
39-22-607. Estimated tax deposited with
treasurer.
39-22-608. Form, place, and date of filing
return - extension - electronic filing.
39-22-609. Payment of tax - applicable when.
39-22-610. Relief for members of the armed
forces of the United States - when.
39-22-611. Property exempt from ad valorem
taxes.
39-22-612. Certificate of nonresidence.
(Repealed)
39-22-613. Oath and affidavit. (Repealed)
39-22-614. Contents of application. (Repealed)
39-22-615. Duration and renewal of
certificate. (Repealed)
39-22-616. Fees. (Repealed)
39-22-617. Exemption of holder of certificate.
(Repealed)
39-22-618. False statements deemed perjury.
(Repealed)
39-22-619. Certificate improperly procured.
(Repealed)
39-22-620. Review of action of executive
director. (Repealed)
39-22-621. Interest and penalties.
39-22-622. Refunds.
39-22-623. Disposition of collections -
definition.
39-22-624. Prior rights and liabilities not
affected.
39-22-625. Application of article - effective
date.
39-22-626. Applicability of amendments to this
article to income tax years.
39-22-627. Temporary adjustment of rate of
income tax - refund of excess state revenues - authority of executive director
- definitions - repeal.
39-22-628. Direct deposit of refund to
collegeinvest savings accounts - modification of individual income tax return
forms - legislative declaration - definition.
39-22-629. Advance payments of income tax
credits - definitions.
39-22-630. Charitable contributions made
through qualified intermediaries - eligibility for income tax credits
maintained - definitions.
SUBPART 2
REPORTABLE TRANSACTIONS
39-22-651. Short title - citation.
39-22-652. Definitions.
39-22-653. Taxpayer disclosure of reportable
or listed transactions.
39-22-654. Additional listed transactions -
report.
39-22-655. Penalty for failure to disclose a
reportable or listed transaction.
39-22-656. Material advisor - disclosure of
reportable or listed transactions.
39-22-657. Material advisor - maintenance of
list.
39-22-658. Material advisor - penalties.
39-22-659. Waiver, reduction, or compromise of
penalty for reasonable cause.
PART 7
COLORADO NONGAME CONSERVATION AND WILDLIFE RESTORATION VOLUNTARY CONTRIBUTION
39-22-701. Legislative declaration.
39-22-702. Voluntary contribution designation
- procedure.
39-22-703. Contributions credited to Colorado
nongame conservation and wildlife restoration cash fund - administration -
transfer.
39-22-704. Repeal of part.
PART 8
DOMESTIC ABUSE PROGRAM VOLUNTARY CONTRIBUTION
39-22-801. Voluntary contribution designation
- procedure.
39-22-802. Contributions credited to Colorado
domestic abuse program fund - creation - appropriation.
39-22-803. Repeal of part.
PART 9
UNITED STATES OLYMPIC COMMITTEE VOLUNTARY CONTRIBUTION
39-22-901 to
39-22-903. (Repealed)
PART 10
LIMITATION ON VOLUNTARY CONTRIBUTION PROGRAMS
39-22-1001. Limitations on voluntary
contribution programs - queue - notice - reestablishment of certain programs.
PART 11
COLORADO VETERANS' MEMORIAL FUND VOLUNTARY CONTRIBUTION
39-22-1101 to
39-22-1102. (Repealed)
PART 12
SPECIAL RESERVE FUND FOR PAYMENT OF CERTAIN REFUNDS
39-22-1201. (Repealed)
PART 13
HOMELESS PREVENTION ACTIVITIES PROGRAM FUND - VOLUNTARY CONTRIBUTION
39-22-1301. Voluntary contribution designation
- procedure.
39-22-1302. Contributions credited to homeless
prevention activities program fund - creation - appropriation.
39-22-1303. Repeal of part. (Repealed)
PART 14
OPERATION DESERT STORM ACTIVE DUTY MILITARY VOLUNTARY CONTRIBUTION
39-22-1401 to
39-22-1403. (Repealed)
PART 15
ACTION OLDER AMERICAN VOLUNTEER PROGRAMS - VOLUNTARY CONTRIBUTION
39-22-1501 to
39-22-1504. (Repealed)
PART 16
DRUG ABUSE RESISTANCE EDUCATION (D.A.R.E.) VOLUNTARY CONTRIBUTION
39-22-1601 to
39-22-1604. (Repealed)
PART 17
CHILD CARE VOLUNTARY CONTRIBUTION
39-22-1701 to
39-22-1705. (Repealed)
PART 18
SPECIAL OLYMPICS COLORADO VOLUNTARY CONTRIBUTION
39-22-1801. Legislative declaration.
39-22-1802. Voluntary contribution designation
- procedure - effective date.
39-22-1803. Contributions credited to the
Special Olympics Colorado fund - creation - appropriation.
39-22-1804. Repeal of part.
PART 19
WESTERN SLOPE MILITARY VETERANS' CEMETERY VOLUNTARY CONTRIBUTION
39-22-1901. Legislative declaration.
39-22-1902. Voluntary contribution designation
- procedure.
39-22-1903. Contributions credited to the fund
- appropriation.
39-22-1904. Repeal of part. (Repealed)
PART 20
REFUND OF REVENUES IN EXCESS OF STATE FISCAL YEAR SPENDING LIMITATION
39-22-2001. Legislative declaration - revenues
exceeding TABOR limit - sales tax refund.
39-22-2002. Fiscal years commencing on or after
July 1, 1998 - state sales tax refund - authority of executive director -
definitions.
39-22-2003. State sales tax refund - offset
against state income tax - qualified individuals - definitions.
39-22-2004. Temporary refund of excess state
revenues from all sources - definitions - repeal.
39-22-2005. Refund of excess state revenues
from all sources - definitions - repeal.
PART 21
COLORADO AFFORDABLE HOUSING TAX CREDIT
39-22-2101. Definitions.
39-22-2102. Credit against tax - affordable
housing developments - legislative declaration.
39-22-2103. Recapture.
39-22-2104. Filing requirements.
39-22-2105. Parallel credits - insurance
premium taxes.
39-22-2106. Rules.
39-22-2107. Compliance monitoring.
39-22-2108. Report to the general assembly.
PART 22
PET OVERPOPULATION FUND VOLUNTARY CONTRIBUTION
39-22-2201. Voluntary contribution designation
- procedure.
39-22-2202. Contributions credited to the fund
- administration - transfer.
39-22-2203. Repeal of part.
PART 23
COURT-APPOINTED SPECIAL ADVOCATES VOLUNTARY CONTRIBUTION
39-22-2301 to
39-22-2304. (Repealed)
PART 24
COLORADO HEALTHY RIVERS FUND VOLUNTARY CONTRIBUTION
39-22-2401. Legislative declaration.
39-22-2402. Voluntary contribution designation
- procedure.
39-22-2403. Contributions credited to Colorado
healthy rivers fund - creation - appropriation.
39-22-2404. Repeal of part.
PART 25
FAMILY RESOURCE CENTERS FUND VOLUNTARY CONTRIBUTION
39-22-2501 to
39-22-2504. (Repealed)
PART 26
COLORADO STATE FAIR VOLUNTARY CONTRIBUTION
39-22-2601 to
39-22-2604. (Repealed)
PART 27
ORGAN DONOR AWARENESS VOLUNTARY CONTRIBUTION
39-22-2701 to
39-22-2704. (Repealed)
PART 28
DROPOUT PREVENTION ACTIVITY PROGRAMS VOLUNTARY CONTRIBUTION
39-22-2801 to
39-22-2804. (Repealed)
PART 29
ALZHEIMER'S ASSOCIATION VOLUNTARY CONTRIBUTION
39-22-2901. Voluntary contribution designation
- procedure.
39-22-2902. Contributions credited to the
Alzheimer's Association fund - creation - appropriation.
39-22-2903. Repeal of part.
PART 30
MILITARY FAMILY RELIEF VOLUNTARY CONTRIBUTION
39-22-3001. Voluntary contribution designation
- procedure.
39-22-3002. Contributions credited to the
military family relief fund - appropriation.
39-22-3003. Repeal of part.
PART 31
COLORADO EASTER SEALS VOLUNTARY CONTRIBUTION
39-22-3101 to
39-22-3104. (Repealed)
PART 32
NATIONAL MULTIPLE SCLEROSIS SOCIETY VOLUNTARY CONTRIBUTION
39-22-3201 to
39-22-3204. (Repealed)
PART 33
COLORADO CANCER FUND VOLUNTARY CONTRIBUTION
39-22-3301. Legislative declaration.
39-22-3302. Voluntary contribution designation
- procedure.
39-22-3303. Contributions credited to the
Colorado cancer fund - creation - appropriation.
39-22-3304. Repeal of part.
PART 34
9HEALTH FAIR VOLUNTARY CONTRIBUTION
39-22-3401 to
39-22-3404. (Repealed)
PART 35
ADULT STEM CELLS CURE FUND VOLUNTARY CONTRIBUTION
39-22-3501 to
39-22-3503. (Repealed)
PART 36
MAKE-A-WISH FOUNDATION OF COLORADO VOLUNTARY CONTRIBUTION
39-22-3601. Legislative declaration.
39-22-3602. Voluntary contribution designation
- procedure.
39-22-3603. Contributions credited to the
Make-A-Wish Foundation of Colorado fund - creation - appropriation.
39-22-3604. Repeal of part.
PART 37
COLORADO 2-1-1 FIRST CALL FOR HELP FUND VOLUNTARY CONTRIBUTION
39-22-3701 to
39-22-3704. (Repealed)
PART 38
UNWANTED HORSE FUND VOLUNTARY CONTRIBUTION
39-22-3801. Legislative declaration.
39-22-3802. Voluntary contribution designation
- procedure.
39-22-3803. Contributions credited to the unwanted
horse fund - creation - appropriation.
39-22-3804. Repeal of part.
PART 39
GOODWILL INDUSTRIES VOLUNTARY CONTRIBUTION
39-22-3901 to
39-22-3904. (Repealed)
PART 40
ROUNDUP RIVER RANCH VOLUNTARY CONTRIBUTION
39-22-4001 to
39-22-4004. (Repealed)
PART 41
FAMILIES IN ACTION FOR MENTAL HEALTH VOLUNTARY CONTRIBUTION
39-22-4101 to
39-22-4104. (Repealed)
PART 42
PUBLIC EDUCATION FUND VOLUNTARY CONTRIBUTION
39-22-4201 to
39-22-4204. (Repealed)
PART 43
AMERICAN RED CROSS COLORADO DISASTER RESPONSE, READINESS, AND PREPAREDNESS FUND
VOLUNTARY CONTRIBUTION
39-22-4301. Legislative declaration.
39-22-4302. Voluntary contribution designation
- procedure - effective date.
39-22-4303. Contributions credited to the
American Red Cross Colorado disaster response, readiness, and preparedness fund
- creation - appropriation.
39-22-4304. Repeal of part.
PART 44
COLORADO FOR HEALTHY LANDSCAPES FUND VOLUNTARY CONTRIBUTION
39-22-4401 to
39-22-4404. (Repealed)
PART 45
HABITAT FOR HUMANITY OF COLORADO VOLUNTARY CONTRIBUTION
39-22-4501. Legislative declaration.
39-22-4502. Voluntary contribution designation
- procedure - effective date.
39-22-4503. Contributions credited to the
Habitat for Humanity of Colorado fund - creation - appropriation.
39-22-4504. Repeal of part.
PART 46
COLORADO YOUTH CORPS ASSOCIATION VOLUNTARY CONTRIBUTION
39-22-4601 to
39-22-4604. (Repealed)
PART 47
FIRST-TIME HOME BUYER SAVINGS ACCOUNT
39-22-4701. Short title.
39-22-4702. Legislative declaration.
39-22-4703. Definitions.
39-22-4704. First-time home buyer savings
account.
39-22-4705. Eligible expenses - penalties for
other uses.
39-22-4706. Forms.
39-22-4707. Financial institutions.
39-22-4708. Repeal of part.
PART 48
URBAN PEAK HOUSING AND SUPPORT SERVICES FOR YOUTH EXPERIENCING HOMELESSNESS
FUND VOLUNTARY CONTRIBUTION
39-22-4801 to
39-22-4804. (Repealed)
PART 49
FAMILY CAREGIVER SUPPORT FUND VOLUNTARY CONTRIBUTION
39-22-4901 to
39-22-4904. (Repealed)
PART 50
YOUNG AMERICANS CENTER FOR FINANCIAL EDUCATION FUND VOLUNTARY CONTRIBUTION
39-22-5001 to
39-22-5004. (Repealed)
PART 51
DONATE TO A COLORADO NONPROFIT FUND VOLUNTARY CONTRIBUTION
39-22-5101. Legislative declaration.
39-22-5102. Voluntary contribution designation
- procedure - effective date.
39-22-5103. List of eligible charitable
organizations.
39-22-5104. Contributions credited to the
donate to a Colorado nonprofit fund - creation - appropriation - distribution.
39-22-5105. Initial funding.
PART 52
COLORADO AFFORDABLE HEALTH CARE COVERAGE EASY ENROLLMENT PROGRAM
39-22-5201. Definitions.
39-22-5202. Uninsured designation - required
forms - rules.
PART 53
FEEDING COLORADO VOLUNTARY CONTRIBUTION
39-22-5301. Legislative declaration.
39-22-5302. Voluntary contribution designation
- procedure - effective date.
39-22-5303. Contributions credited to Feeding
Colorado fund - creation - appropriation.
39-22-5304. Repeal of part.
PART 54
MIDDLE-INCOME HOUSING TAX CREDIT
39-22-5401. Tax preference performance
statement - legislative declaration.
39-22-5402. Definitions.
39-22-5403. Credit against tax - middle-income
housing developments.
39-22-5404. Qualified development owned by
governmental or quasi-governmental entity.
39-22-5405. Recapture.
39-22-5406. Parallel credits - insurance
premium taxes.
39-22-5407. Rules - compliance monitoring.
39-22-5408. Reporting requirements.
39-22-5409. Repeal of part.
PART 55
COLORADO AFFORDABLE HOUSING IN TRANSIT-ORIENTED COMMUNITIES INCOME TAX CREDIT
39-22-5501. Tax preference performance
statement - legislative declaration.
39-22-5502. Definitions.
39-22-5503. Credit against tax - affordable
housing located in a transit-oriented community.
39-22-5504. Recapture.
39-22-5505. Filing requirements.
39-22-5506. Parallel credits - insurance
premium taxes.
39-22-5507. Compliance monitoring.
39-22-5508. Repeal of part.
PART 56
ANIMAL PROTECTION FUND VOLUNTARY CONTRIBUTION
39-22-5601. Legislative declaration.
39-22-5602. Voluntary contribution designation
- procedure - effective date.
39-22-5603. Contributions credited to animal
protection fund - appropriation.
PART 57
COLORADO AFFORDABLE HOUSING IN TRANSIT AND HOUSING INVESTMENT ZONES TAX CREDIT
39-22-5701. Tax preference performance
statement - report.
39-22-5702. Definitions.
39-22-5703. Credit against tax - affordable
housing located in a transit and housing investment zone.
39-22-5704. Recapture.
39-22-5705. Filing requirements.
39-22-5706. Parallel credits - insurance
premium taxes - definition.
39-22-5707. Compliance monitoring.
39-22-5708. Repeal.
PART
1
GENERAL
Editor's
note: This article
was repealed and reenacted in 1964, and this part 1 was subsequently repealed
and reenacted in 1987, resulting in the addition, relocation, and elimination
of sections as well as subject matter. For amendments to this part 1 prior to
1987, consult the Colorado statutory research explanatory note and the table
itemizing the replacement volumes and supplements to the original volume of
C.R.S. 1973 beginning on page vii in the front of this volume and the editor's
note following the article heading. Former C.R.S. section numbers prior to 1987
are shown in editor's notes following those sections that were relocated.
39-22-101. Short title.
This
article shall be known and may be cited as the "Colorado Income Tax Act of
1987".
Source:
L. 87: Entire part
R&RE, p. 1426, § 2, effective June 22.
Editor's
note: This section
is similar to former § 39-22-101 as it existed prior to 1987.
ANNOTATION
Law reviews. For
article, "The Problem of Tax Exempt Property in Colorado", see 19
Rocky Mt. L. Rev. 22 (1946). For article, "Taxation Aspects of Divorce and
Separation", see 21 Rocky Mt. L. Rev. 397 (1949). For article,
"Colorado Income Tax Act of 1964", see 41 Den. L. Ctr. J. 337 (1964).
Applied in In re Golden
State Bank v. Dolan, 37 Colo. App. 29, 543 P.2d 1307 (1975) (decided under law
in effect prior to 1987 repeal and reenactment).
39-22-102. Legislative declaration.
(1) The
general assembly hereby finds, determines, and declares that the purposes of
the "Colorado Income Tax Act of 1987" include, but are not limited
to:
(a)
Simplifying the preparation of state income tax returns;
(b)
Aiding in the interpretation of the state income tax law through increased use
of federal judicial and administrative determinations and precedents;
(c)
Improving the enforcement of the state income tax laws through better use of
information obtained from federal income tax audits.
Source:
L. 87: Entire part
R&RE, p. 1426, § 2, effective June 22.
Editor's
note: This section
is similar to former § 39-22-101 as it existed prior to 1987.
39-22-103. Definitions - construction
of terms.
As used in
this article, unless the context otherwise requires:
(1)
"Assessment" means the filing of the return as to the tax, penalty,
and interest shown to be due thereon and, as to any other tax imposed under
this article, or any deficiency in tax, or any penalty or interest, means the
mailing or issuance of a notice and demand for payment.
(2)
"Basic date" means July 1, 1937.
(2.5)
"C corporation" means any organization taxed as a corporation for
federal income tax purposes.
(3)
"Domestic corporation" means a corporation organized under the laws
of this state.
(4)
"Executive director" means the executive director of the department
of revenue.
(5)
"Foreign corporation" means a corporation other than a domestic
corporation.
(5.3)
"Internal revenue code" means the provisions of the federal
"Internal Revenue Code of 1986", as amended, and other provisions of
the laws of the United States relating to federal income taxes, as the same may
become effective at any time or from time to time, for the taxable year.
(5.5)
(Deleted by amendment, L. 95, p. 816, § 40, effective May 24, 1995.)
(5.6)
"Partnership" means any group or organization that is a partnership,
as defined by section 761 (a) of the internal revenue code, and is required to
file a return under section 6031 (a) of the internal revenue code.
(5.8)
"Qualified higher deductible health plan" has the same meaning as
that set forth in section 39-22-504.6 (3.5).
(6)
"Resident beneficiary" means a beneficiary of an estate or trust,
which beneficiary is a resident individual, a domestic corporation, a resident
estate, a resident trust, or a partnership or a limited liability company
organized under the laws of this state. "Nonresident beneficiary"
means a beneficiary other than a resident beneficiary.
(7)
"Resident estate" means the estate of a deceased person which is
administered in this state in a proceeding other than an ancillary proceeding.
"Nonresident estate" means an estate other than a resident estate.
(8) (a)
"Resident individual" means a natural person who is domiciled in this
state and a natural person who maintains a permanent place of abode within this
state and who spends in the aggregate more than six months of the taxable year
within this state.
(b) (I)
"Resident individual" does not include, for income tax years
commencing on or after January 1, 2001, any individual domiciled in this state
who:
(A) Is
absent from the state for a period of at least three hundred five days of the
tax year and is stationed outside of the United States of America for active
military duty; and
(B)
Elects not to file a Colorado individual income tax return as a resident
individual.
(II)
"Resident individual" does not include the spouse of an individual
described in subparagraph (I) of this paragraph (b) who accompanies such
individual for the period of such individual's absence and who elects not to
file a tax return as a resident individual.
(c) A
"nonresident individual" means an individual other than a resident
individual and an individual described in paragraph (b) of this subsection (8)
who elects treatment as a nonresident individual.
(8.5)
(Deleted by amendment, L. 95, p. 816, § 40, effective May 24, 1995.)
(9)
"Resident partner" means a partner who is a resident individual, a
domestic corporation, a resident estate, a resident trust, or a partnership or
a limited liability company organized under the laws of this state.
"Nonresident partner" means a partner other than a resident partner.
(10)
"Resident trust" means a trust which is administered in this state.
"Nonresident trust" means a trust other than a resident trust.
(10.5)
"S corporation" means a corporation for which a valid election is in
effect pursuant to section 1362 (a) of the internal revenue code.
(10.8)
"Withholding certificate" means a document, which may be in paper or
electronic form, utilized by an employee to instruct his or her employer to
withhold taxes at a specific rate.
(11)
Any term used in this article, except as otherwise expressly provided or
clearly appearing from the context, shall have the same meaning as when used in
a comparable context in the internal revenue code, as amended, in effect for
the taxable period. Due consideration shall be given in the interpretation of
this article to applicable sections of the internal revenue code in effect from
time to time and to federal rulings and regulations interpreting such sections
if such statute, rulings, and regulations do not conflict with the provisions
of this article.
Source:
L. 87: Entire part
R&RE, p. 1426, § 2, effective June 22. L. 90: (5.5) and (8.5) added
and (6) and (9) amended, p. 453, § 32, effective April 18. L. 92: (2.5),
(5.3), and (10.5) added and (11) amended, p. 2265, § 4, effective April 16. L.
94: (5.8) added, p. 2839, § 1, effective January 1, 1995. L. 95:
(2.5), (5.5), and (8.5) amended, p. 816, § 40, effective May 24. L. 96:
(5.6) added, p. 335, § 1, effective April 16. L. 2000: (8) amended, p.
1298, § 1, effective January 1, 2001. L. 2002: (10.8) added, p. 530, §
1, effective August 7.
Editor's
note: This section
is similar to former § 39-22-103 as it existed prior to 1987.
Cross
references: For
the federal "Internal Revenue Code of 1986", see title 26 of the
United States Code.
ANNOTATION
Subsection (5.3)
unambiguously incorporates the federal Internal Revenue Code of 1986, "as
amended, . . . for the taxable year", without limitation as to when an
amendment is enacted or goes into effect. Absent an amendment by the general
assembly to the state income tax code to not conform with changes to the
federal Internal Revenue Code, state law automatically incorporates amendments
to the federal Internal Revenue Code, including amendments that relate to
previous tax years. Therefore, a taxpayer can take advantage of any amendment
that is in effect for, not just in, a taxable year. Anschutz v. Dept. of Rev.,
2022 COA 132, 524 P.3d 1203.
Department's emergency rule
interpreting "internal revenue code" for purposes of subsection (5.3)
was contrary to statute's plain language and not entitled to deference.
Emergency rule erroneously defined "internal revenue code" to exclude
any federal statutory changes enacted after the last day of the taxable year,
contrary to statute, which automatically incorporates amendments to the federal
Internal Revenue Code, without limitation to laws that are prospective in their
operation. Anschutz v. Dept. of Rev., 2022 COA 132, 524 P.3d 1203.
Trial court erred in
granting department's motion to dismiss taxpayers' refund claim made in
amended return based on retroactive amendment to federal tax statutes.
Taxpayers were entitled to file an amended state income tax return for the 2018
tax year claiming entirety of their "excess business loss" as
deduction based on the federal Coronavirus Aid, Relief, and Economic Security
Act of 2020, which suspended the "excess business loss" deduction
limits for the 2018 through 2020 tax years. Anschutz v. Dept. of Rev., 2022 COA
132, 524 P.3d 1203.
39-22-104. Income tax imposed on
individuals, estates, and trusts - single rate - report - tax preference
performance statement - legislative declaration - definitions - repeal.
(1)
Subject to subsection (2) of this section, with respect to taxable years
commencing on or after January 1, 1987, but prior to January 1, 1999, a tax of
five percent is imposed on the federal taxable income, as determined pursuant
to section 63 of the internal revenue code, of every individual, estate, and
trust.
(1.5)
Subject to subsection (2) of this section, with respect to taxable years
commencing on or after January 1, 1999, but prior to January 1, 2000, a tax of
four and three-quarters percent is imposed on the federal taxable income, as
determined pursuant to section 63 of the internal revenue code, of every
individual, estate, and trust.
(1.7)
(a) Except as otherwise provided in section 39-22-627, subject to subsection
(2) of this section, with respect to taxable years commencing on or after
January 1, 2000, but before January 1, 2020, a tax of four and sixty-three
one-hundredths percent is imposed on the federal taxable income, as determined
pursuant to section 63 of the internal revenue code, of every individual,
estate, and trust.
(b)
Except as otherwise provided in section 39-22-627, subject to subsection (2) of
this section, with respect to taxable years commencing on or after January 1,
2020, but before January 1, 2022, a tax of four and fifty-five one-hundredths
percent is imposed on the federal taxable income, as determined pursuant to
section 63 of the internal revenue code, of every individual, estate, and
trust.
(c)
Except as otherwise provided in section 39-22-627, subject to subsection (2) of
this section, with respect to taxable years commencing on or after January 1,
2022, a tax of four and forty one-hundredths percent is imposed on the federal
taxable income, as determined pursuant to section 63 of the internal revenue
code, of every individual, estate, and trust.
(2)
Prior to the application of the rate of tax prescribed in subsection (1),
(1.5), or (1.7) of this section, the federal taxable income shall be modified
as provided in subsections (3) and (4) of this section.
(3)
There shall be added to the federal taxable income:
(a) Any
federal net operating loss deduction carried over from a taxable year beginning
prior to January 1, 1987;
(b) An
amount equal to the interest income which is excluded from gross income for
federal income tax purposes pursuant to section 103 (a) of the internal revenue
code less amortization of premium on obligations of any state or any political
subdivision thereof, other than interest income on obligations of the state of
Colorado or any political subdivision thereof which are issued on or after May
1, 1980, and other than interest income on obligations of the state of Colorado
or any political subdivision thereof which were issued prior to May 1, 1980, to
the extent that such interest is specifically exempt from income taxation under
the laws of the state of Colorado authorizing the issuance of such obligations.
The amount of such interest shall be the net amount after reduction by the
amount of the deductions related thereto which are required by the internal
revenue code to be allocated to such classes of interest.
(c)
Repealed.
(d) (I)
For income tax years beginning on and after January 1, 1992, for those
taxpayers who deduct state income taxes pursuant to section 164 (a)(3) of the
internal revenue code, an amount equal to the deduction claimed; except that
such amount shall be limited to the amount required to reduce the federal
itemized amount computed under section 161 of the internal revenue code to the
amount of the standard deduction allowable under section 63 (c) of the internal
revenue code.
(II)
For income tax years beginning on or after January 1, 2000, for two individuals
whose federal taxable income is determined on a joint federal return and who
deduct state income taxes pursuant to section 164 (a)(3) of the internal
revenue code, an amount equal to the deduction claimed; except that such amount
shall be limited to the amount required to reduce the federal itemized amount
computed under section 161 of the internal revenue code to an amount equal to
double the amount of the basic standard deduction allowable under section 63
(c)(2) of the internal revenue code in the case of an individual federal return
for an individual who is not the head of a household plus any additional
standard deduction allowable under section 63 (c)(3) of the internal revenue
code, if applicable.
(e) (I)
Any expenses incurred by a taxpayer with respect to expenditures made at, or
payments made to, a club licensed pursuant to section 44-3-418 that has a
policy to restrict membership on the basis of sex, sexual orientation, gender
identity, gender expression, marital status, race, creed, religion, color,
ancestry, or national origin. Any such club shall provide on each receipt
furnished to a taxpayer a printed statement as follows:
The expenditures covered by this
receipt are
nondeductible for state income tax
purposes.
(II) The
general assembly finds, determines, and declares that the people of the state
of Colorado desire to promote and achieve tax equity and fairness among all the
state's citizens and further desire to conform to the public policy of
nondiscrimination. The general assembly further declares that the provisions of
this paragraph (e) are enacted for these reasons and for no other purpose.
(f) Any
amount withdrawn from a medical savings account pursuant to section 39-22-504.7
(3)(b)(II) or (3)(b)(III);
(g) For
the income tax years commencing on or after January 1, 2000, an amount equal to
the charitable contribution deduction allowed by section 170 of the internal
revenue code to the extent such deduction includes a contribution of real
property to a charitable organization for a conservation purpose for which an
income tax credit is claimed pursuant to section 39-22-522;
(h)
Repealed.
(i) An
amount equal to a business expense for labor services that is deducted pursuant
to section 162 (a)(1) of the internal revenue code but that is prohibited from
being claimed as a deductible business expense for state income tax purposes
pursuant to section 39-22-529;
(j) For
income tax years commencing on or after January 1, 2015, but before January 1,
2020, an amount equal to the charitable contribution deduction allowed by
section 170 of the internal revenue code to the extent such deduction includes
a food contribution during the tax year to a hunger-relief charitable
organization for which an income tax credit is claimed pursuant to section
39-22-536;
(k) (I)
Prior to January 1, 2025, the amount recaptured in accordance with section
39-22-4705 (2).
(II)
This subsection (3)(k) is repealed, effective December 31, 2028.
(l) For
income tax years ending on and after the enactment of the March 2020
"Coronavirus Aid, Relief, and Economic Security Act", Pub.L. 116-136,
referred to in this section as the "CARES Act", but before January 1,
2021, and for income tax years beginning on and after the enactment of the
"CARES Act", but before January 1, 2021, an amount equal to the
difference between a taxpayer's net operating loss deduction as determined
under section 172 (a) of the internal revenue code before the amendments made by
section 2303 of the "CARES Act" and the taxpayer's net operating loss
deduction as determined under section 172 (a) of the internal revenue code
after the amendments made by section 2303 of the "CARES Act";
(m) For
income tax years ending on and after the enactment of the "CARES
Act", but before January 1, 2021, and for income tax years beginning on
and after the enactment of the "CARES Act", but before January 1,
2021, an amount equal to a taxpayer's excess business loss as determined under
section 461 (l) of the internal revenue code without regard to the amendments
made by section 2304 of the "CARES Act", but with regard to the
technical amendment made by section 2304 (b)(2)(B) of the "CARES
Act";
(n) For
income tax years ending on and after the enactment of the "CARES
Act", but before January 1, 2021, and for income tax years beginning on
and after the enactment of the "CARES Act", but before January 1,
2021, an amount equal to the amount in excess of the limitation on business
interest under section 163 (j) of the internal revenue code without regard to
the amendments made by section 2306 of the "CARES Act";
(o) For
income tax years commencing on or after January 1, 2021, an amount equal to the
deduction allowed under section 199A of the internal revenue code for a
taxpayer who files a single return and whose adjusted gross income is greater
than five hundred thousand dollars, and for taxpayers who file a joint return
and whose adjusted gross income is greater than one million dollars; except
that this subsection (3)(o) does not apply to a taxpayer who is required to
file a schedule F, profit or loss from farming, or successor form, as an
attachment to a federal income tax return for the tax year in which the
taxpayer claims the deduction allowed under section 199A of the internal
revenue code.
(p)
Except as otherwise provided in subsection (3)(p.5) of this section, for income
tax years commencing on or after January 1, 2022, for taxpayers who claim
itemized deductions as defined in section 63 (d) of the internal revenue code
and who have federal adjusted gross income in the income tax year equal to or
exceeding four hundred thousand dollars:
(I) For
a taxpayer who files a single return, the amount by which the itemized
deductions deducted from gross income under section 63 (a) of the internal
revenue code exceed thirty thousand dollars; and
(II)
For taxpayers who file a joint return, the amount by which the itemized
deductions deducted from gross income under section 63 (a) of the internal
revenue code exceed sixty thousand dollars.
(p.5)
(I) For income tax years commencing on or after January 1, 2023, but before
January 1, 2026, for taxpayers who claim itemized deductions as defined in
section 63 (d) of the internal revenue code or the standard deduction as
defined in section 63 (c) of the internal revenue code and who have federal
adjusted gross income in the income tax year equal to or exceeding three
hundred thousand dollars:
(A) For
a taxpayer who files a single return, the amount by which the itemized
deductions deducted from gross income under section 63 (a) of the internal
revenue code exceed, or the standard deduction deducted from gross income under
section 63 (c) of the internal revenue code exceeds, twelve thousand dollars;
and
(B) For
taxpayers who file a joint return, the amount by which the itemized deductions
deducted from gross income under section 63 (a) of the internal revenue code
exceed, or the standard deduction deducted from gross income under section 63
(c) of the internal revenue code exceeds, sixteen thousand dollars.
(II)
For the 2023-24 state fiscal year and state fiscal years thereafter, the
general assembly shall annually appropriate an amount at least equal to the
amount of revenue generated by the addition to federal taxable income described
in subsection (3)(p.5)(I) of this section, calculated without regard to any
temporary rate reduction pursuant to section 39-22-627, to the healthy school
meals for all program cash fund created in section 22-82.9-211. Subsection
(3)(p.5)(I) of this section constitutes a voter-approved revenue change,
approved by the voters at the statewide election in November of 2022, and the
revenue generated by this voter-approved revenue change may be collected,
retained, appropriated, and spent without subsequent voter approval, notwithstanding
any other limits in the state constitution or law. The addition to federal
taxable income described in subsection (3)(p.5)(I) of this section does not
apply for an income tax year that commences after the healthy school meals for
all program, or any successor program, is repealed. Upon repeal of the healthy
school meals for all program, or any successor program, the commissioner of
education shall promptly notify the executive director in writing that the
program is repealed.
(III)
This subsection (3)(p.5) is repealed, effective December 31, 2028.
(p.7)
(I) For income tax years commencing on or after January 1, 2026, for
taxpayers who claim itemized deductions as defined in section 63 (d) of the
internal revenue code or the standard deduction as defined in section 63 (c) of
the internal revenue code and who have a federal adjusted gross income in the
income tax year equal to or exceeding three hundred thousand dollars:
(A) For
a taxpayer who files a single return, the amount by which the itemized
deductions deducted from gross income under section 63 (a) of the internal
revenue code exceed, or the standard deduction deducted from gross income under
section 63 (c) of the internal revenue code exceeds one thousand dollars; and
(B) For
taxpayers who file a joint return, the amount by which the itemized deductions
deducted from gross income under section 63 (a) of the internal revenue code
exceed, or the standard deduction deducted from gross income under section 63
(c) of the internal revenue code exceeds two thousand dollars.
(II) In
addition to the funding appropriated in subsection (3)(p.5) of this section,
for the 2026-27 state fiscal year and every state fiscal year thereafter, the
general assembly shall annually appropriate an amount at least equal to the
amount of revenue generated by the addition to federal taxable income described
in this subsection (3)(p.7) to the healthy school meals for all program cash
fund created in section 22-82.9-211. The provisions of this subsection (3)(p.7)
constitute a voter-approved revenue change, approved by the voters at the
statewide election in November 2025, and the revenue generated by this
voter-approved revenue change may be collected, retained, appropriated, and
spent without subsequent voter approval, notwithstanding any other limits in
the state constitution or law. The addition to federal taxable income described
in this subsection (3)(p.7) does not apply for an income tax year that
commences after the healthy school meals for all program, or any successor
program, is repealed. Upon repeal of the healthy school meals for all program,
or any successor program, the commissioner of education shall promptly notify
the executive director in writing that the program is repealed.
(q) (I)
For income tax years commencing on or after January 1, 2022, but before January
1, 2023, an amount equal to a federal deduction claimed for the income tax year
for a food and beverage expense that exceeds fifty percent of the amount of the
expense and that was allowed under section 274 (n)(2)(D) of the internal
revenue code.
(II)
This subsection (3)(q) is repealed, effective December 31, 2030.
(r)
Notwithstanding subsection (3)(o) of this section, for income tax years
commencing on or after January 1, 2018, an amount equal to the deduction taken
under section 199A of the internal revenue code, except to the extent the
deduction is otherwise disallowed under section 265 of the internal revenue
code, for an electing pass-through entity owner of an electing pass-through
entity, as such terms are defined in section 39-22-342, that makes the election
allowed in subpart 3 of part 3 of this article 22.
(s) (I)
For income tax years commencing on or after January 1, 2024, but before January
1, 2031, an amount equal to a federal deduction claimed for a business meal
pursuant to section 274 (k) of the internal revenue code.
(II)
This subsection (3)(s) is repealed, effective December 31, 2035.
(t) For
income tax years commencing on or after January 1, 2025, an amount equal to the
amount of employer contribution that an employee forfeits pursuant to section
39-22-558 (3)(c) and that the taxpayer had previously subtracted from the
taxpayer's federal taxable income pursuant to subsection (4)(bb) of this
section;
(u) For
income tax years beginning on or after January 1, 2026, the amount of any
overtime compensation excluded or deducted from federal gross income; and
(v) (I)
(A) For income tax years beginning on and after January 1, 2027, the excess
of any gain excluded from federal gross income pursuant to section 1400Z-2
(a)(1)(A) of the internal revenue code over the amount of that gain invested by
the taxpayer in a Colorado qualified opportunity fund in a manner that
qualifies for exclusion from federal gross income pursuant to section 1400Z-2
(a)(I)(A) of the internal revenue code.
(B) For
amounts invested in a qualified opportunity fund after December 31, 2026, other
than a Colorado qualified opportunity fund, the amount of gain excluded from
federal gross income as a result of an election made by the taxpayer pursuant
to section 1400Z-2(c) of the internal revenue code.
(II) As
used in this subsection (3)(v), "Colorado qualified opportunity fund"
means a qualified opportunity fund that holds at least ninety percent of its
assets in Colorado qualified opportunity zone property. Colorado qualified
opportunity zone property is:
(A)
Qualified opportunity zone business property substantially all of the use of
which, during substantially all of the fund's holding period for the property,
was in a qualified opportunity zone within Colorado; or
(B)
Qualified opportunity zone stock, or a qualified opportunity zone partnership
interest, in a qualified opportunity zone business in which substantially all
of the tangible property owned or leased is qualified opportunity zone business
property as described in section 1400Z-2 (d)(3)(A)(i) of the internal revenue
code and substantially all the use of which is in a qualified opportunity zone
within Colorado.
(III)
For purposes of subsection (3)(v)(II) of this section:
(A)
Property held in the fund shall be measured under rules similar to the rules of
section 1400Z-2 (d)(1) of the internal revenue code; and
(B) The
terms used have the same meaning as set forth in section 1400Z-2 of the
internal revenue code.
(4)
There shall be subtracted from federal taxable income:
(a) An
amount equal to any interest income on obligations of the United States and its
possessions to the extent included in federal taxable income;
(a.5)
Repealed.
(b) To
the extent included in federal adjusted gross income, the portion of any gain
or loss from the sale or other disposition of property having a higher adjusted
basis for Colorado income tax purposes than for federal income tax purposes on
the date such property was sold or disposed of in a transaction in which gain
or loss was recognized for purposes of federal income tax that does not exceed
such difference in basis;
(c) The
amount necessary to prevent the taxation under this article of any annuity or
other amount of income or gain which was properly included in income or gain
and was taxed under the laws of this state for a prior tax year, to the
taxpayer, or to a decedent by reason of whose death the taxpayer acquired the
right to receive the income or gain, or to a trust or estate from which the
taxpayer received the income or gain;
(d)
Repealed.
(e) (I)
The amount of any refund or credit for overpayment of income taxes imposed by
this state or any other taxing jurisdiction to the extent included in gross
income for federal income tax purposes but not previously allowed as a
deduction for Colorado income tax purposes;
(II)
The purpose of the subtraction authorized in this subsection (4)(e) is to avoid
re-taxing a taxpayer's state income tax refund when a state refund is required
to be included as income on the taxpayer's federal return pursuant to the
internal revenue code;
(III)
The effectiveness of the subtraction authorized in this subsection (4)(e) is
measured by the number of taxpayers claiming the subtraction and the total
amount of state refunds claimed as subtractions from Colorado taxable income;
(f) (I)
For income tax years commencing on or after January 1, 1989, amounts received
as pensions or annuities from any source by any individual who is fifty-five
years of age or older at the close of the taxable year, to the extent included
in federal adjusted gross income;
(II)
For income tax years commencing on or after January 1, 1989, amounts received
as pensions or annuities from any source by any individual who is less than
fifty-five years of age at the close of the taxable year if such benefits are
received because of the death of the person originally entitled to receive such
benefits and only to the extent such benefits are included in federal adjusted
gross income;
(III)
(A) Amounts subtracted under this subsection (4)(f) are capped at twenty
thousand dollars per tax year for any individual who is fifty-five years of age
or older but less than sixty-five years of age at the close of the taxable
year. For income tax years commencing on or after January 1, 2025, the cap set
forth in this subsection (4)(f)(III)(A) is calculated by first considering the
total amount of social security benefits a taxpayer received that were included
in federal taxable income at the close of the taxable year. If the total amount
of such social security benefits exceeds the cap set forth in this subsection
(4)(f)(III)(A), and the taxpayer's adjusted gross income for the applicable tax
year is less than or equal to seventy-five thousand dollars if filing
individually or ninety-five thousand dollars if filing jointly, then the cap is
increased to an amount equal to the total amount of such social security
benefits.
(B)
Amounts subtracted under this subsection (4)(f) are capped at twenty-four
thousand dollars per tax year for any individual who is sixty-five years of age
or older at the close of the taxable year. For income tax years commencing on
or after January 1, 2022, the cap set forth in this subsection (4)(f)(III)(B)
is calculated by first considering the total amount of social security benefits
a taxpayer received that were included in federal taxable income at the close
of the taxable year. If the total amount of such social security benefits
exceeds the cap set forth in this subsection (4)(f)(III)(B), then the cap is
increased to an amount equal to the total amount of such social security
benefits.
(C) For
the purpose of determining the subtraction allowed by this subsection (4)(f),
in the case of a joint return, social security benefits included in federal
taxable income shall be apportioned in a ratio of the gross social security
benefits of each taxpayer to the total gross social security benefits of both
taxpayers.
(D) As
used in this subsection (4)(f), "pensions and annuities" means
retirement benefits that are periodic payments attributable to personal
services performed by an individual prior to his or her retirement from
employment and that arise from an employer-employee relationship, from service
in the uniformed services of the United States, or from contributions to a
retirement plan that are deductible for federal income tax purposes.
"Pensions and annuities" includes distributions from individual
retirement arrangements and self-employed retirement accounts to the extent
that such distributions are not deemed to be premature distributions for
federal income tax purposes, amounts received from fully matured privately
purchased annuities, social security benefits, and amounts paid from any such
sources by reason of permanent disability or death of the person entitled to
receive the benefits.
(E) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the general purpose of the tax expenditure created in subsection
(4)(f)(III)(B) of this section is to provide tax relief for certain individuals
and that the specific purpose of the tax expenditure is to provide such tax
relief to persons aged fifty-five and older in light of the increase in
property tax rates in the income tax year commencing on January 1, 2023. The
general assembly and the state auditor shall measure the effectiveness of the
exemption allowed by this section based on the total amount of social security
benefits in excess of twenty thousand dollars per individual per tax year that
individuals aged fifty-five to sixty-four, inclusive, subtract from their
federal taxable income when calculating their state taxable income.
(F) The
department of revenue, in consultation with the state auditor, shall collect
the information necessary for the state auditor to measure the effectiveness of
the income tax subtraction allowed by this section based on the total amount of
social security benefits in excess of twenty thousand dollars per individual
per tax year that individuals who are aged fifty-five to sixty-four, and whose
adjusted gross income is less than or equal to seventy-five thousand dollars if
filing individually or ninety-five thousand dollars if filing jointly, subtract
from their federal taxable income when calculating their state taxable income.
(g)
Repealed.
(h) (I)
Prior to January 1, 2025, any amount contributed to a medical savings account
by an employer pursuant to section 39-22-504.7 (2)(e), to the extent such
amount is not claimed as a deduction on the taxpayer's federal tax return.
(II)
This subsection (4)(h) is repealed, effective December 31, 2028.
(i) (I)
(A) For income tax years commencing on or after January 1, 1998, an amount
equal to the portion attributable to interest and other income of a
distribution under a qualified state tuition program that is distributed for
the purpose of meeting qualified higher education expenses of a designated
beneficiary, to the extent such amount is included in federal taxable income;
(B)
Before January 1, 2031, an amount equal to the portion attributable to interest
and other income of a distribution under a qualified ABLE program that is
distributed for the purpose of meeting qualified disability expenses of a
designated beneficiary, to the extent such amount is included in federal
taxable income;
(C)
Subsection (4)(i)(I)(B) of this section and this subsection (4)(i)(I)(C) are
repealed, effective January 1, 2035.
(II)
(A) For income tax years commencing on or after January 1, 2001, but before
January 1, 2022, an amount equal to all payments or contributions made during
the taxable year under an advance payment contract, to a savings trust account,
or otherwise in connection with a qualified state tuition program established
by collegeinvest created in section 23-3.1-203, or to a qualified state tuition
program that is affiliated with an educational institution in the state and
that is established and maintained pursuant to section 529 of the internal
revenue code or any successor section.
(B)
Except as provided in subsection (4)(i)(II)(C) of this section, for income tax
years commencing on or after January 1, 2022, an amount equal to all payments
or contributions, not to exceed twenty thousand dollars per taxpayer per
beneficiary for a taxpayer who files a single return, or thirty thousand
dollars per taxpayer per beneficiary for taxpayers who file a joint return,
made during the taxable year under an advance payment contract, to a savings
trust account, or otherwise in connection with a qualified state tuition
program established by collegeinvest created in section 23-3.1-203, or to a
qualified state tuition program that is affiliated with an educational
institution in the state and that is established and maintained pursuant to
section 529 of the internal revenue code or any successor section, or, before
January 1, 2031, in connection with a qualified ABLE program. Notwithstanding
subsection (4)(i)(III)(D) of this section, collegeinvest may treat a change in
beneficiary as a nonqualifying distribution if the change was made for the
purpose of evading the limit in this subsection (4)(i)(II)(B).
(C) For
income tax years commencing on or after January 1, 2023, the limits specified
in subsection (4)(i)(II)(B) of this section are annually adjusted by the
percentage change in the combined average annual costs of tuition and room and
board for all state institutions of higher education, as defined in section
24-30-1301 (18). The department of higher education shall annually calculate
the percentage change described in this subsection (4)(i)(II)(C) and shall
provide the calculation to the department of revenue by a deadline determined
by the department of revenue. The department of revenue may round the adjusted
limits to the nearest hundred dollars.
(III)
No subtraction is allowed pursuant to this subsection (4)(i) to the extent that
such payments or contributions are excluded from the taxpayer's federal taxable
income for the taxable year. Any subtraction taken under this subsection (4)(i)
is added to the account holder's taxable income in the taxable year or years in
which any distribution, refund, or any other withdrawal is made pursuant to an
advance payment contract, from a savings trust account, or otherwise in
connection with a qualified state tuition program for any reason other than:
(A) To
pay qualified higher education expenses;
(B) As
a result of the beneficiary's death or disability;
(C) As
a result of receiving a scholarship and as long as the aggregate amount of
distributions, refunds, or withdrawals made pursuant to this subsection
(4)(i)(III)(C) do not exceed the amount of the scholarship provided during such
tax year; or
(D) As
a result of a change in designated beneficiary, if the change complies with
section 529 (c)(3)(C)(ii) of the internal revenue code.
(III.5)
No subtraction is allowed pursuant to this subsection (4)(i) to the extent that
such payments or contributions are excluded from the taxpayer's federal taxable
income for the taxable year. Before January 1, 2031, any subtraction taken
under this subsection (4)(i) is added to the account holder's taxable income in
the taxable year or years in which any distribution, refund, or any other
withdrawal is made pursuant to an advance payment contract, from a savings
trust account, or otherwise in connection with a qualified ABLE program for any
reason other than:
(A) To
pay qualified disability expenses;
(B) As
a result of the beneficiary's death or disability; or
(C) As
a result of a change in designated beneficiary, if the change complies with
section 529A (c)(1)(C)(ii) of the internal revenue code.
(D)
This subsection (4)(i)(III.5) is repealed, effective January 1, 2035.
(IV) As
used in this subsection (4)(i), unless the context otherwise requires:
(A)
"Designated beneficiary" has the same meaning as defined in section
529 (e)(1) of the internal revenue code.
(B)
"Qualified higher education expense" has the same meaning as defined
in section 529 (e)(3) of the internal revenue code, and expenses for fees,
books, supplies, and equipment required for the participation of a designated
beneficiary in an apprenticeship program as defined in section 529 (c)(8) of
the internal revenue code.
(C)
"Qualified state tuition program" means a qualified tuition program
as defined in section 529 (b) of the internal revenue code.
(D)
"Qualified ABLE program", before January 1, 2031, means a qualified
ABLE program as defined in section 529A (b) of the internal revenue code.
(E)
"Qualified disability expense", before January 1, 2031, has the same
meaning as defined in section 529A (e)(5) of the internal revenue code.
(IV.5)
Subsections (4)(i)(IV)(B) and (4)(i)(IV)(C) of this section and this subsection
(4)(i)(IV.5) are repealed, effective January 1, 2035.
(V)
Beginning January 1, 2022, and annually thereafter, collegeinvest shall provide
the department with a secure electronic report containing information for the
529 qualified state tuition program's account owners and third-party
contributors necessary for the administration of the deduction allowed in this
section. The report must include:
(A) The
name and social security number, and the contribution amount, of all Colorado
taxpayers making a contribution to a collegeinvest account in the reporting tax
year commencing on or after January 1, 2021;
(B) The
name and social security number, and the contribution amount, of any other
Colorado taxpayer making a contribution to a collegeinvest account in the
reporting tax year commencing on or after January 1, 2021, who intends to
participate in the deduction allowed in this section; and
(C) The
name and social security number, and the distribution amount, of each account
holder of a collegeinvest account who is also a Colorado taxpayer making a
distribution in the reporting tax year commencing on or after January 1, 2021,
and the reason, if any, for the distribution.
(VI)
The purpose of the deduction authorized in this subsection (4)(i) is to create
additional incentives for saving for college tuition not already created by
other state or federal law.
(VII)
The purposes of the deduction authorized in subsection (4)(i)(I)(B) of this
section are to provide support to individuals with disabilities and their
families and to provide an incentive for individuals with disabilities and
their families to set aside money in an account to cover future
disability-related expenses.
(j) to
(l.5) Repealed.
(m) (I)
Except as provided in subparagraph (VII) of this paragraph (m), for any income
tax year commencing on or after January 1, 2001, for any individual who claims
the basic standard deduction allowed under section 63 (c)(2) of the internal
revenue code on the individual's federal return and, therefore, cannot claim an
itemized deduction for charitable contributions pursuant to section 170 of the
internal revenue code, an amount equal to the amount of any deduction based
upon the aggregate amount of charitable contributions in excess of five hundred
dollars that the individual could have claimed pursuant to section 170 of the
internal revenue code if the individual had not claimed the basic standard
deduction.
(II)
Any state income tax modification allowed pursuant to the provisions of
subparagraph (I) of this paragraph (m) shall be published in rules promulgated
by the executive director in accordance with article 4 of title 24, C.R.S., and
shall be included in income tax forms for that taxable year.
(III) to
(VI) Repealed.
(VII)
For any income tax year commencing on or after January 1, 2015, but before
January 1, 2020, any individual who claims an income tax credit allowed in
section 39-22-536 may not claim the deduction set forth in this paragraph (m)
for the food contribution to the hunger-relief charitable organization.
(n)
Repealed.
(n.5) (I)
(A) For income tax years commencing on or after January 1, 2014, but prior
to January 1, 2017, and for income tax years commencing on or after January 1,
2020, but prior to January 1, 2025, an amount equal to fifty percent of a
landowner's costs incurred in performing wildfire mitigation measures in that
income tax year on his or her property located within the state; except that
the amount of the deduction claimed in an income tax year shall not exceed two
thousand five hundred dollars or the total amount of the landowner's federal
taxable income for the income tax year for which the deduction is claimed,
whichever is less.
(A.5)
For income tax years commencing on or after January 1, 2017, but prior to
January 1, 2020, an amount equal to one hundred percent of a landowner's costs
incurred in performing wildfire mitigation measures in that income tax year on
his or her property located within the state; except that the amount of the
deduction claimed in an income tax year shall not exceed two thousand five
hundred dollars or the total amount of the landowner's federal taxable income
for the income tax year for which the deduction is claimed, whichever is less.
(B) In
the case of two taxpayers filing a joint return, the amount subtracted from
federal taxable income shall not exceed two thousand five hundred dollars in
any taxable year. In the case of two taxpayers who may legally file a joint
return but actually file separate returns, only one of the taxpayers may claim
the deduction specified in this paragraph (n.5).
(C) In
the case of real property owned as tenants in common, the deduction allowed
pursuant to this paragraph (n.5) shall only be allowed to one of the
individuals of the ownership group.
(II) A
landowner who performs wildfire mitigation measures on his or her real property
located within the state may claim the deduction authorized by this paragraph
(n.5) if the wildfire mitigation measures are performed in a wildland-urban
interface area.
(III)
For purposes of this paragraph (n.5):
(A)
"Colorado state forest service" means the Colorado state forest
service identified in section 23-31-302, C.R.S.
(B)
"Costs" means any actual out-of-pocket expense incurred and paid by
the landowner, documented by receipt, for performing wildfire mitigation
measures. "Costs" do not include any inspection or certification
fees, in-kind contributions, donations, incentives, or cost sharing associated
with performing wildfire mitigation measures. "Costs" do not include
expenses paid by the landowner from any grants awarded to the landowner for
performing wildfire mitigation measures.
(C)
"Landowner" means any owner of record of private land located within
the state, including any easement, right-of-way, or estate in the land, and
includes the heirs, successors, and assigns of such land, and shall not include
any partnership, S corporation, or other similar entity that owns private land
as an entity.
(D)
"Wildfire mitigation measures" means the creation of a defensible
space around structures; the establishment of fuel breaks; the thinning of
woody vegetation for the primary purpose of reducing risk to structures from
wildland fire; or the secondary treatment of woody fuels by lopping and
scattering, piling, chipping, removing from the site, or prescribed burning; so
long as such activities meet or exceed any Colorado state forest service
standards or any other applicable state rules.
(IV)
This subsection (4)(n.5) is repealed, effective January 1, 2028.
(o) For
income tax years commencing on or after January 1, 2011, an amount equal to any
amount received as employer matching contributions to an adult learner's
individual trust account or savings account made pursuant to part 3 of article
3.1 of title 23, C.R.S.;
(p) For
income tax years commencing on or after January 1, 2014, any amount received as
a grant from the military family relief fund created in section 28-3-1502,
C.R.S., to the extent that it is included in federal taxable income;
(q) For
income tax years commencing on or after January 1, 2013, an amount equal to any
amount received as compensation for an exonerated person pursuant to section
13-65-103, C.R.S., on or after January 1, 2014, except as to those portions of
the judgment awarded as attorney fees for bringing a claim under such section;
(r) For
income tax years commencing on or after January 1, 2014, if a taxpayer is
licensed under the "Colorado Marijuana Code", article 10 of title 44,
or its predecessor codes, an amount equal to any expenditure that is eligible
to be claimed as a federal income tax deduction but is disallowed by section
280E of the internal revenue code because marijuana is a controlled substance
under federal law;
(r.5)
For income tax years commencing on or after January 1, 2024, if a taxpayer is
licensed pursuant to the "Colorado Natural Medicine Code", article 50
of title 44, an amount equal to any expenditure that is eligible to be claimed
as a federal income tax deduction but is disallowed by section 280E of the
internal revenue code because natural medicine is a controlled substance under
federal law;
(s)
Repealed.
(t) (I)
For income tax years commencing on or after January 1, 2015, and prior to
January 1, 2025, compensation that would be subject to withholding under
section 39-22-604, received by a nonresident individual for performing
disaster-related work in the state during a disaster period.
(II)
For purposes of this paragraph (t):
(A)
"Declared state disaster emergency" means a disaster or emergency
event for which the governor has issued an executive order declaring a disaster
emergency.
(B)
"Disaster period" means a period that begins with the day of the
governor's executive order declaring a state disaster emergency and that
extends for a period of sixty calendar days after the expiration of the
governor's executive order.
(C)
"Disaster-related work" means repairing, renovating, installing,
building, or rendering services that relate to infrastructure that has been
damaged, impaired, or destroyed by a declared state disaster emergency or
providing emergency medical, firefighting, law enforcement, hazardous material,
search and rescue, or other emergency service related to a declared state
disaster emergency.
(D)
"Infrastructure" means property and equipment owned or used by
communications networks, gas and electric utilities, water pipelines, and
public roads and bridges and related support facilities that service multiple
customers or citizens, including but not limited to real and personal property
such as buildings, offices, lines, poles, pipes, structures, and equipment.
(III)
This subsection (4)(t) is repealed, effective December 31, 2028.
(u) For
income tax years commencing on or after January 1, 2016, an amount equal to any
compensation received for active duty service in the armed forces of the United
States by an individual who has reacquired residency in the state pursuant to
section 39-22-110.5, to the extent that the compensation is included in federal
taxable income;
(v)
Repealed.
(w) (I)
For income tax years commencing on or after January 1, 2017, and prior to
January 1, 2025, to the extent included in federal taxable income and as
permitted under part 47 of this article 22, an amount equal to any interest and
other income earned on the investment of the money in a first-time home buyer
savings account during the taxable year.
(II)
Any exclusion taken under subparagraph (I) of this paragraph (w) is subject to
recapture under paragraph (k) of subsection (3) of this section as specified in
section 39-22-4705.
(III)
This subsection (4)(w) is repealed, effective December 31, 2028.
(x) (I)
Except as otherwise provided in subsection (4)(x)(II) of this section, for
income tax years commencing on or after January 1, 2018, all income earned, to
the extent included in federal taxable income except as otherwise provided in
subsection (4)(x)(IV) of this section, as a direct result of winning a medal
while competing for the United States of America at the Olympic games.
(II)
The subtraction provided for in subsection (4)(x)(I) of this section does not
apply to a taxpayer whose federal adjusted gross income for the income tax year
in which the taxpayer has income earned as a direct result of winning a medal,
as determined prior to application of this subsection (4)(x), exceeds one
million dollars or, if the taxpayer's filing status is married filing
separately, exceeds five hundred thousand dollars.
(III)
As used in this subsection (4)(x):
(A)
"Income earned as a direct result of winning a medal" includes both
the monetary value of the medal itself and any monetary award given for winning
the medal by the United States Olympic committee or any sport-specific national
governing body or Paralympic sport organization but does not include
endorsement income or nonmonetary benefits.
(B)
"Olympic games" means the summer and winter Olympic games and the
summer and winter Paralympic games.
(IV)
The monetary value of any medal won while competing for the United States of
America at either the summer or winter Olympic games or the summer or winter
Paralympic games shall be subtracted from federal taxable income regardless of
whether or not said monetary value is included in federal taxable income.
(y) (I)
For income tax years commencing on or after January 1, 2019, but prior to
January 1, 2029, an amount equal to a qualified individual's military
retirement benefits included in federal adjusted gross income, but not to
exceed the following amounts:
(A)
Four thousand five hundred dollars for income tax years commencing on or after
January 1, 2019, but prior to January 1, 2020;
(B)
Seven thousand five hundred dollars for income tax years commencing on or after
January 1, 2020, but prior to January 1, 2021;
(C) Ten
thousand dollars for income tax years commencing on or after January 1, 2021,
but before January 1, 2022; or
(D)
Fifteen thousand dollars for income tax years commencing on or after January 1,
2022, but before January 1, 2029.
(II) As
used in this subsection (4)(y):
(A)
"Military retirement benefits" means any retirement benefits received
as a result of the individual's service in the armed forces of the United
States.
(B)
"Qualified individual" means an individual who is under fifty-five
years of age at the close of the taxable year.
(III)
(A) In accordance with section 39-21-304 (1), which requires each bill that
extends a tax expenditure to include a tax preference performance statement as
part of a statutory legislative declaration if one was not previously included
in the tax expenditure, the general assembly finds and declares that the
purpose of the tax expenditure in this subsection (4)(y) is to provide tax
relief to certain individuals, namely military retirees.
(B) The
general assembly and the state auditor shall measure the effectiveness of this
tax expenditure in achieving the purpose specified in subsection (4)(y)(III)(A)
of this section by measuring whether military retirees are benefitting from the
tax expenditure, and by how much.
(z) (I)
Except as provided in subsection (4)(z)(II) of this section, for income tax
years beginning on or after January 1, 2021, but before January 1, 2022, the
sum of the amount by which taxable income for the specified tax years exceeds
the taxable income for the modified specified tax years computed separately for
each income tax year, plus the sum of any amounts added back by the taxpayer as
specified in subsections (3)(l), (3)(m), and (3)(n) of this section.
(II)
(A) The subtraction calculated under subsection (4)(z)(I) of this section
applies after the application of the other subtractions provided for in this
subsection (4) and is limited to the lesser of the taxpayer's Colorado taxable
income or three hundred thousand dollars.
(B) Any
amount of the subtraction calculated under subsection (4)(z)(I) of this section
that a taxpayer may not claim by operation of subsection (4)(z)(II)(A) of this
section may be carried forward to subsequent tax years as a subtraction from
the taxpayer's federal taxable income until exhausted; except that each tax
year's subtraction may not exceed the lesser of the taxpayer's Colorado taxable
income or one hundred fifty thousand dollars for the income tax years
commencing on or after January 1, 2022, but before January 1, 2026, and each
year's subtraction may not exceed the taxpayer's Colorado taxable income in any
income tax years thereafter. Any subtraction must be applied first to the
earliest income tax years possible.
(III) A
taxpayer that applies the subtraction allowed in this subsection (4)(z) with
respect to qualified improvement property shall calculate the gain or loss on a
sale of such qualified improvement property for purposes of the subtraction in
subsection (4)(b) of this section using the basis reported on their federal
income tax return at the time of the sale.
(IV) As
used in this subsection (4)(z), unless the context otherwise requires:
(A)
"CARES Act" means the March 2020 "Coronavirus Aid, Relief, and
Economic Security Act", Pub.L. 116-136.
(B)
"Colorado taxable income" means federal taxable income as modified by
this article 22 without regard to this subsection (4)(z).
(C)
"Retroactive provisions of the CARES Act" means the changes made to
the internal revenue code in sections 2303, 2304, 2306, and 2307 of the CARES
Act.
(D)
"Taxable income for the modified specified tax years" means the
taxpayer's Colorado taxable income for tax years ending before March 27, 2020,
as calculated under the internal revenue code and Colorado law applicable to
the taxpayer's return as of the date the return was due, as modified by the
application of the retroactive provisions of the CARES Act applied to the
calculation of the taxpayer's federal taxable income, but only to the extent
the taxpayer appropriately applied those provisions to the taxpayer's federal
income tax returns for each tax year.
(E)
"Taxable income for the specified tax years" means the taxpayer's
Colorado taxable income for tax years ending before March 27, 2020, as
calculated under Colorado law applicable to the taxpayer's return as of the
date the return was due.
(aa)
Repealed.
(bb)
For income tax years commencing on or after January 1, 2024, but before January
1, 2027, an amount equal to any employer contribution received from an employer
pursuant to section 39-22-558. This subsection (4)(bb) is repealed, effective
December 31, 2034.
(cc)
(I) For income tax years commencing on or after January 1, 2026, but before
January 1, 2034, an amount equal to the amount of any Segal AmeriCorps
Education Award received for service in the AmeriCorps national service
program, which is used by the taxpayer during the income tax year.
(II) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that:
(A) The
purpose of the income tax subtraction created in this subsection (4)(cc) is to
provide tax relief for certain individuals, specifically taxpayers who have
received Segal AmeriCorps Education Awards for AmeriCorps service; and
(B) The
general assembly and the state auditor shall measure the effectiveness of the
subtraction in achieving the purpose specified in subsection (4)(cc)(II)(A) of
this section based on the number and aggregate amount of subtractions claimed
in a tax year.
(III)
The department of revenue shall maintain information about the number of
taxpayers who claim the subtraction in a tax year and the aggregate amount of
subtractions claimed in a tax year, in addition to any other information
determined necessary by the department of revenue, to evaluate the
effectiveness of the tax subtraction allowed in this subsection (4)(cc) in
achieving the purpose specified in subsection (4)(cc)(II)(A) of this section,
and shall provide this information upon request of the general assembly or the
state auditor.
(IV)
This subsection (4)(cc) is repealed, effective July 1, 2039.
(dd)
(I) For income tax years commencing on or after January 1, 2027, but before
January 1, 2038, an amount equal to qualifying capital gains that are subject
to tax under this article 22 and that are realized by an owner during the
taxable year for the qualified sale of a qualified business.
(II) As
used in this subsection (4)(dd), unless the context otherwise requires:
(A)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(B)
"Owner" has the same meaning as set forth in section 39-22-542
(2)(h).
(C)
"Qualified business" has the same meaning as set forth in section
39-22-542 (2)(i).
(D)
"Qualified employee-owned business" has the same meaning as set forth
in section 39-22-542 (2)(j).
(E)
"Qualified sale" means the conversion to a qualified employee-owned
business; except that the conversion must be by an increment of at least twenty
percent of the total ownership of the entire qualified employee-owned business.
(F) "Qualifying
capital gains" means the amount of net capital gains, as defined in
section 1222 (11) of the internal revenue code, subject to the limitation set
forth in subsection (4)(dd)(V) of this section.
(III)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the income tax subtraction provided in this subsection
(4)(dd) is to:
(A)
Induce certain designated behavior by taxpayers, specifically for businesses to
establish employee stock ownership plans or employee ownership trusts or to
convert to a worker-owned cooperative; and
(B)
Provide tax relief for certain businesses or individuals, specifically to
businesses that establish employee stock ownership plans or employee ownership
trusts or that convert to a worker-owned cooperative.
(IV)
The general assembly and the state auditor shall measure the effectiveness of
the subtraction in achieving the purpose specified in subsection (4)(dd)(III)
of this section based on the number and aggregate amount of subtractions
claimed in a tax year.
(V) (A)
On or before June 30, 2026, the office shall establish and post on its website
the total amount of capital gains that may be subtracted from an owner's
federal taxable income pursuant to this subsection (4)(dd), which amount is in
effect for income tax years commencing on or after January 1, 2027, but before
January 1, 2038, or until the office adjusts the amount as set forth in
subsection (4)(dd)(V)(B) of this section.
(B)
After June 30, 2026, on or before June 30, 2027, and on or before June 30 of
each year thereafter until June 30, 2036, the office may adjust the total
amount of capital gains that may be subtracted from an owner's federal taxable
income that the office has previously established in accordance with this
subsection (4)(dd)(V). The adjusted amount must be posted on the office's
website and is in effect for income tax years commencing on or after January 1
of the year immediately following the year in which the adjustment is made but
before January 1, 2038, or until the office subsequently adjusts the amount as
set forth in this subsection (4)(dd)(V)(B).
(C) An
owner may not subtract more than the amount of capital gains established by the
office in accordance with subsection (4)(dd)(V)(A) or (4)(dd)(V)(B) of this
section in the income tax year.
(D)
Beginning in January 2027, and in January every year thereafter following a
year in which the office adjusts the amount of capital gains that may be
subtracted from an owner's federal taxable income pursuant to subsection
(4)(dd)(V)(B) of this section, the office shall include, as part of its
presentation during its "SMART Act" hearing required by section
2-7-203, information concerning the amount of capital gains that may be
subtracted from an owner's federal taxable income that the office has established
pursuant to subsection (4)(dd)(V)(A) or (4)(dd)(V)(B) of this section and the
method that the office used to establish the amount.
(VI)
This subsection (4)(dd) is repealed, effective July 1, 2042.
(ee)
(I) For income tax years commencing on or after January 1, 2026, for a
taxpayer who receives a payment pursuant to section 24-33.5-122 (4) that does
not qualify for the federal income tax exemption described in section 101 (h)
of the internal revenue code, including a payment that does not qualify as a
result of the exceptions described in section 101 (h)(2) of the internal
revenue code, an amount equal to the amount received pursuant to section
24-33.5-122 (4); and
(II) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that:
(A) The
purpose of the income tax subtraction created in this subsection (4)(ee) is to
provide tax relief for certain individuals, specifically taxpayers who have
received a payment in connection with the death of a first responder pursuant
to section 24-33.5-122 (4); and
(B) The
general assembly and the state auditor shall measure the effectiveness of the
subtraction in achieving the purpose specified in subsection (4)(ee)(II)(A) of
this section based on the number and aggregate amount of subtractions claimed;
(III)
The department of revenue shall maintain information about the number of
taxpayers who claim the subtraction in a tax year and the aggregate amount of
subtractions claimed in a tax year, in addition to any other information
determined necessary by the department of revenue, to evaluate the
effectiveness of the tax subtraction allowed in this subsection (4)(ee) in
achieving the purpose specified in subsection (4)(ee)(II)(A) of this section,
and shall provide this information upon request of the general assembly or the
state auditor; and
(IV)
Notwithstanding section 39-21-304 (4), the tax subtraction allowed in this
subsection (4)(ee) extends indefinitely until no less than five years after the
executive director of the department of public safety disburses the last
payment in connection with the death of a first responder pursuant to section
24-33.5-122 (4).
(ff)
For income tax years commencing on or after January 1, 2027, the amount of any
gain included in federal gross income pursuant to section 1400Z-2 (b) of the
internal revenue code to the extent that such gain was added to federal taxable
income pursuant to section 39-22-104 (3)(v) for a prior tax year.
(5)
Repealed.
Source:
L. 87: Entire part
R&RE, p. 1427, § 2, effective June 22. L. 88: (1), (3)(b), and
(4)(f) amended, p. 1311, § 2, effective May 29. L. 89: (4)(f) amended
and (4)(g) repealed, pp. 1504, 1506, §§ 1, 3, effective June 10. L. 90:
(4)(a.5) added, p. 699, § 2, effective May 31. L. 92: (3)(d) added, p.
555, § 37, effective May 28; (3)(e) added, p. 2279, § 2, effective June 1. L.
94: (3)(f) and (4)(h) added, p. 2839, §§ 2, 3, effective January 1, 1995. L.
97: (3)(e)(I) amended, p. 304, § 20, effective July 1; (4)(i) added, p.
513, § 1, effective August 6. L. 99: (4)(l) added, p. 784, § 1,
effective May 24; (1) amended and (1.5) added, p. 1376, § 1, effective August
4; (3)(d) amended and (4)(j) and (4)(k) added, pp. 936, 937, §§ 1, 2, effective
August 4; (3)(g) added, p. 977, § 2, effective August 4; (4)(f) amended, p.
1301, § 1, effective August 4. L. 2000: (4)(l)(I), (4)(l)(III),
(4)(l)(IV)(A), (4)(l)(IV)(B), and (4)(l)(V) amended and (4)(l.5) added, p. 658,
§ 1, effective May 22; (4)(m) added, p. 1409, § 1, effective May 31; (1.5) and
(2) amended and (1.7) added, p. 1413, § 1, effective August 2; (2) amended, p.
1869, § 98, effective August 2; (3)(h) added, p. 1321, § 3, effective August 2;
(4)(i) amended, p. 946, § 1, effective August 2. L. 2001: (4)(l)(VI)
amended, p. 1279, § 54, effective June 5; (3)(d)(II) and (4)(k) amended, p.
392, § 2, effective August 8. L. 2004: (4)(a.5) amended, p. 323, § 8,
effective April 7; (4)(i)(II) amended, p. 577, § 36, effective July 1; (3)(g)
amended, p. 1208, § 88, effective August 4. L. 2005: (4)(m) amended, p.
215, § 1, effective April 8; (1.7) amended, p. 1361, § 1, effective June 6. Referred
2006: (3)(i) added, L. 2006, 1st Ex. Sess., p. 1, § 1, December 31. L.
2008: (3)(e)(I) amended, p. 1604, § 35, effective May 29; (4)(n) added, p.
1550, § 1, effective August 5. L. 2010: (4)(o) added, (SB 10-202), ch.
396, p. 1884, § 8, effective June 9; (3)(h), (4)(l), (4)(l.5), (4)(m)(III),
(4)(m)(IV), (4)(m)(V), and (4)(m)(VI) repealed and (4)(m)(I) amended, (SB
10-212), ch. 412, pp. 2032, 2034, §§ 1, 7, effective July 1; (3)(h) repealed,
(HB 10-1256), ch. 133, p. 440, § 2, effective August 11. L. 2013:
(4)(n.5) added, (HB 13-1012), ch. 91, p. 293, § 1, effective April 4; (4)(s)
added, (SB 13-283), ch. 332, p. 1896, § 18, effective May 28; (4)(q) added, (HB
13-1230), ch. 409, p. 2426, § 5, effective June 5; (4)(p) added, (HB 13-1024),
ch. 27, p. 66, § 1, effective August 7; (4)(r) added, (HB 13-1042), ch. 327, p.
1820, § 1, effective August 7. L. 2014: (4)(f)(III), (4)(n)(I)(B), and (4)(n.5)(I)(B)
amended, (SB 14-019), ch. 10, p. 98, § 4, effective February 27; (3)(j) and
(4)(m)(VII) added and (4)(m)(I) amended, (HB 14-1119), ch. 286, p. 1175, § 3,
effective May 30; (4)(t) added, (HB 14-1003), ch. 224, p. 837, § 2, effective
August 6. L. 2015: (4)(u) added, (HB 15-1181), ch. 233, p. 865, § 4,
effective August 5. L. 2016: (3)(c) repealed and (4)(f) amended, (SB
16-189), ch. 210, p. 793, § 108, effective June 6; (3)(k) and (4)(w) added, (HB
16-1467), ch. 321, p. 1301, § 1, effective August 10; (4)(n.5)(I)(A) amended
and (4)(n.5)(I)(A.5) added, (HB 16-1286), ch. 300, p. 1215, § 2, effective
August 10; (4)(v) added, (HB 16-1194), ch. 252, p. 1029, § 1, effective August
10. L. 2017: (4)(x) added, (HB 17-1104), ch. 223, p. 860, § 1, effective
August 9. L. 2018: (4)(y) added, (HB 18-1060), ch. 271, p. 1667, § 2,
effective August 8; (3)(e)(I) amended, (HB 18-1025), ch. 152, p. 1081, § 20,
effective October 1; (4)(r) and (4)(s) amended, (HB 18-1023), ch. 55, p. 591, §
23, effective October 1. L. 2019: (4)(r) amended and (4)(s) repealed,
(SB 19-224), ch. 315, p. 2942, § 31, effective January 1, 2020. L. 2020:
(3)(l), (3)(m), (3)(n), and (3)(o) added, (HB 20-1420), ch. 277, p. 1358, § 2,
effective July 11; (4)(a.5), (4)(j), and (4)(k) repealed, (HB 20-1176), ch. 89,
p. 357, § 1, effective September 14; (4)(d) repealed, (HB 20-1205), ch. 59, p.
200, § 2, effective January 1, 2021. Initiated 2020: (1.7) amended,
Proposition 116, effective upon proclamation of the Governor, December 31,
2020. L. 2021: (4)(z) added, (HB 21-1002), ch. 5, p. 30, § 1, effective
January 21; (3)(o), (4)(f)(III), (4)(i)(II), and (4)(i)(III) amended and
(3)(p), (3)(q), and (4)(i)(V) added, (HB 21-1311), ch. 298, p. 1768, § 3,
effective June 23; (3)(r) and (4)(aa) added, (HB 21-1327), ch. 300, p. 1804, §
2, effective June 23; (3)(e)(I) amended, (HB 21-1108), ch. 156, p. 898, § 46,
effective September 7. L. 2022: (3)(r) amended and (4)(aa) repealed, (SB
22-124), ch. 164, p. 1021, § 7, effective May 16; (4)(n.5)(I)(A) and
(4)(n.5)(IV) amended, (HB 22-1007), ch. 343, p. 2457, § 2, effective June 3;
(5) amended, (HB 22-1025), ch. 145, p. 945, § 2, effective August 10;
(4)(i)(I), (4)(i)(II)(B), and (4)(i)(IV) amended and (4)(i)(III.5) and
(4)(i)(IV.5) added, (HB 22-1320), ch. 241, p. 1784, § 3, effective January 1,
2023; (4)(i)(IV) amended, (HB 22-1310), ch. 369. p. 2624, § 2, effective
January 1, 2023. Referred 2022: IP(3)(p) amended and (3)(p.5) added,
Proposition FF, L. 2022, (HB 22-1414), ch. 509, p. 4288, § 6, effective upon
proclamation of the Governor, December 27, 2022. Initiated 2022: (1.7)
amended, Proposition 121, effective upon proclamation of the Governor, December
27, 2022. L. 2023: (3)(p.5)(II) amended, (SB 23-221), ch. 89, p. 340, §
6, effective April 20; (4)(r.5) added, (SB 23-290), ch. 249, p. 1423, § 42,
effective July 1; (3)(r) amended, (SB 23-208), ch. 357, p. 2140, § 2, effective
August 7; (3)(s) added, (HB 23-1008), ch. 338, p. 2029, § 3, effective August
7; (3)(t) and (4)(bb) added, (HB 23-1189), ch. 446, p. 2628, § 2, effective
August 7; IP(4)(y)(I) and (4)(y)(I)(D) amended and (4)(y)(III) added, (HB
23-1084), ch. 371, p. 2227, § 1, effective August 7. L. 2024:
(3)(p.5)(II) amended, (SB 24-228), ch. 170, p. 891, § 3, effective May 14;
(4)(cc) added, (HB 24-1240), ch. 366, p. 2467, § 2, effective June 3; (3)(k),
(4)(h), (4)(n.5)(I)(A), (4)(n.5)(IV), (4)(t)(I), and (4)(w)(I) amended and
(4)(i)(VI), (4)(t)(III), and (4)(w)(III) added, (HB 24-1036), ch. 373, pp.
2531, 2526, 2533, 2525, §§ 22, 7, 30, 4, effective August 7; (4)(f)(III)(A) and
(4)(f)(III)(B) amended and (4)(f)(III)(E) and (4)(f)(III)(F) added, (HB
24-1142), ch. 474, p. 3325, § 1, effective August 7; (4)(i)(I)(C) amended, (HB
24-1450), ch. 490, p. 3424, § 76, effective August 7. L. 2025: (4)(ee)
added, (SB 25-310), ch. 359, p. 1958, § 10, effective June 2; (4)(e) amended,
(SB 25-026), ch. 362, p. 1964, § 5, effective August 6; (4)(i)(I)(B),
(4)(i)(I)(C), (4)(i)(II)(B), IP(4)(i)(III.5), (4)(i)(III.5)(D), (4)(i)(IV)(D),
(4)(i)(IV)(E), and (4)(i)(IV.5) amended and (4)(i)(VII) added, (SB 25-302), ch.
245, p. 1237, § 2, effective August 6; (4)(dd) added, (HB 25-1021), ch. 311, p.
1617, § 1, effective August 6; (3)(t) amended and (3)(u) added, (HB 25-1296),
ch. 202, p. 912, § 6, effective January 1, 2026; IP(3)(p.5)(I) and (3)(p.5)(II)
amended and (3)(p.5)(III) and (3)(p.7) added, (HB 25-1274), ch. 402, p. 2296, §
18, effective December 9, 2025, (see editor's note); L. 2025, 1st Ex. Sess.:
(3)(o) amended, (HB 25B-1001), ch. 5, p. 19, § 2, effective August 28. L.
2026: (3)(t) and (3)(u) amended and (3)(v) and (4)(ff) added, (HB 26-1289),
ch. 364, p. 2187, § 4, effective June 3.
Editor's
note: (1) This
section is similar to former § 39-22-104 as it existed prior to 1987.
(2) Subsection (5) of this
section implements the requirements of Article III, section 2, of the
Multistate Tax Compact, § 24-60-1301.
(3) Amendments to subsection
(2) by House Bill 00-1103 and House Bill 00-1463 were harmonized.
(4) Subsection (3)(i) was
enacted by House Bill 06S-1020 at the first extraordinary session of the
sixty-fifth general assembly. That bill contained a referendum clause and was
approved by a vote of the registered electors of the state of Colorado on
November 7, 2006. Subsection (3)(i) was effective upon proclamation of the
governor, December 31, 2006. The vote count for the measure was as follows:
FOR: 744,475
AGAINST: 722,651
(5) Section 9 of chapter 10 (SB
14-019), Session Laws of Colorado 2014, provides that changes to this section
by the act apply to income tax years commencing on or after January 1, 2013,
and any other income tax years that are open under § 39-21-107 or 39-21-108.
(6) Subsection (4)(n)(IV)
provided for the repeal of subsection (4)(n), effective January 1, 2015. (See
L. 2008, p. 1550.)
(7) Subsection (1.7) was
amended by initiative in 2020. The vote count on Proposition 116 at the general
election held November 3, 2020, was as follows:
FOR: 1,821,702
AGAINST: 1,327,025
(8) This section was amended by
HB 22-1414. That bill contains a referendum clause, Proposition FF, and was
approved by a vote of the registered electors of the state of Colorado on
November 8, 2022. The amendments to this section took effect upon the
proclamation of the Governor, December 27, 2022. The vote count for the measure
was as follows:
FOR: 1,384,852
AGAINST: 1,055,583
(9) Amendments to subsection
(4)(i)(IV) by HB 22-1310 and HB 22-1320 were harmonized.
(10) Subsection (1.7) was
amended by initiative in 2022. The vote count on Proposition 121 at the general
election held November 8, 2022, was as follows:
FOR: 1,581,163
AGAINST: 842,506
(11) Subsection (4)(v)(VII)
provided for the repeal of subsection (4)(v), effective December 31, 2023. (See
L. 2016, p. 1029.)
(12) Section 20(6) of chapter
402 (HB 25-1274), Session Laws of Colorado 2025, provides that section 18 of
the act changing this section takes effect on the date of the official
declaration of the vote by the governor only if the ballot issue described in §
22-82.9-213 is approved by the people at the next statewide election. The
ballot issue, referred to voters as Proposition MM, was approved on November 4,
2025, and was proclaimed by the governor on December 9, 2025, see L. 2026, p.
3650. The vote count for the measure was as follows:
FOR: 1,010,644
AGAINST: 681,400
(13) Subsection (5)(b) provided
for the repeal of subsection (5), effective July 1, 2025. (See L. 2022, p.
945.)
Cross
references: (1)
For other provisions concerning adjustments to federal taxable income, see §§
39-22-104.5, 39-22-104.6, 39-22-504.7 (2), and 39-22-518.
(2) For the legislative
declaration contained in the 2001 act amending subsections (3)(d)(II) and
(4)(k), see section 1 of chapter 133, Session Laws of Colorado 2001.
(3) For the legislative
declaration contained in the 2008 act amending subsection (3)(e)(I), see
section 1 of chapter 341, Session Laws of Colorado 2008.
(4) For the legislative
declaration in the 2013 act adding subsection (4)(q), see section 1 of chapter
409, Session Laws of Colorado 2013.
(5) For the legislative
declaration in HB 14-1003, see section 1 of chapter 224, Session Laws of
Colorado 2014. For the legislative declaration in HB 14-1119, see section 1 of
chapter 286, Session Laws of Colorado 2014.
(6) For the short title
("Colorado is Honoring Our Military Exemption (Colorado is HOME)
Act") and the legislative declaration in HB 15-1181, see sections 1 and 2
of chapter 233, Session Laws of Colorado 2015.
(7) For the legislative
declaration in HB 16-1286, see section 1 of chapter 300, Session Laws of
Colorado 2016.
(8) For the legislative
declaration in HB 18-1060, see section 1 of chapter 271, Session Laws of
Colorado 2018.
(9) (a) For the short title
("Tax Fairness Act") in HB 20-1420, see section 1 of chapter 277,
Session Laws of Colorado 2020.
(b) For the legislative
declaration in HB 20-1205, see section 1 of chapter 59, Session Laws of
Colorado 2020.
(10) For the legislative
declaration in HB 21-1311, see section 1 of chapter 298, Session Laws of
Colorado 2021. For the legislative declaration in HB 21-1108, see section 1 of
chapter 156, Session Laws of Colorado 2021.
(11) For the legislative
declaration in HB 23-1008, see section 1 of chapter 338, Session Laws of
Colorado 2023.
(12) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024. For the legislative declaration in HB 24-1240, see section 1 of
chapter 366, Session Laws of Colorado 2024.
(13) For the legislative
declaration in SB 25-302, see section 1 of chapter 245, Session Laws of
Colorado 2025. For the legislative declaration in HB 25-1296, see section 1 of
chapter 202, Session Laws of Colorado 2025. For the legislative declaration in
HB 25-1274, see section 1 of chapter 402, Session Laws of Colorado 2025.
(14) For the legislative
declaration in HB 25B-1001, see section 1 of chapter 5, Session Laws of
Colorado 2025, First Extraordinary Session.
(15) For the legislative
declaration in HB 26-1289, see section 1 of chapter 364, Session Laws of
Colorado 2026.
ANNOTATION
Law reviews. For
article, "2006 Immigration Legislation in Colorado", see 35 Colo.
Law. 79 (Oct. 2006).
The tax exemption provisions
of subsection (4) do not create a contract protected by the contract clause
of the constitution. Spradling v. Colo. Dept. of Rev., 870 P.2d 521 (Colo. App.
1993).
State income tax may be
levied on the sale of cocaine by drug supplier since state law provides
that income derived from any source is taxable. Eggleston v. Colo., 636 F.
Supp. 1312 (D. Colo. 1986), rev'd on other grounds, 873 F.2d 242 (10th Cir.
1989) (decided under former law).
Subsection (4)(g) regarding
military retirement benefits (now repealed) held unconstitutional because it
discriminated between taxpayers based on the source of their income.
Nonmilitary retirees under age 55 were allowed a twenty-thousand-dollar tax
exemption on retirement benefits, while military retirees of the same age were
only allowed a two-thousand-dollar exemption, violating 4 U.S.C. § 111 (1988)
and case law. Taxpayers who overpaid based upon this unconstitutional provision
were entitled to a refund as provided in § 39-22-1201. Kuhn v. State Dept. of
Rev., 817 P.2d 101 (Colo. 1991).
39-22-104.5. Pretax payments -
catastrophic health insurance - repeal.
(1) For
income tax years commencing on or after January 1, 1995, and prior to January
1, 2025, amounts withheld from an individual's wages that are used to pay for
catastrophic health insurance pursuant to and within the limitations prescribed
by section 10-16-116, are excluded from the individual's federal taxable income
for purposes of the state income tax imposed by section 39-22-104.
(2)
This section is repealed, effective December 31, 2028.
Source:
L. 94: Entire
section added, p. 745, § 2, effective January 1, 1995; entire section amended,
p. 1651, § 97, effective January 1, 1995. L. 2013: Entire section
amended, (HB 13-1266), ch. 217, p. 994, § 69, effective May 13. L. 2024:
Entire section amended, (HB 24-1036), ch. 373, p. 2525, § 3, effective August
7.
Cross
references: (1)
For other provisions concerning adjustments to federal taxable income, see §
39-22-104.
(2) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024.
39-22-104.6. Pretax payments - medical
savings accounts - repeal.
(1)
Prior to January 1, 2025, to the extent a taxpayer is not otherwise claiming
deductions on federal income tax returns for contributions to medical savings
accounts, amounts withheld from an individual's wages which are contributed to
such individual's medical savings account, pursuant to section 39-22-504.7, are
excluded from an individual's federal taxable income for purposes of the state
income tax imposed by section 39-22-104.
(2)
This section is repealed, effective December 31, 2028.
Source:
L. 94: Entire
section added, p. 745, § 4, effective January 1, 1995. L. 97: Entire
section amended, p. 643, § 10, effective May 1. L. 2024: Entire section
amended, (HB 24-1036), ch. 373, p. 2526, § 8, effective August 7.
Cross
references: (1)
For other provisions concerning adjustment to federal taxable income, see §
39-22-104.
(2) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024.
39-22-105. Alternative minimum tax.
(1)
With respect to each taxable year commencing on or after January 1, 1987, but
prior to January 1, 2000, for every individual, estate, and trust, in addition
to the tax imposed in section 39-22-104, a tax is imposed in an amount equal to
the excess of:
(a)
Three and seventy-five one-hundredths percent of the Colorado alternative
minimum taxable income, as determined pursuant to subsection (2) of this
section; over
(b) The
tax imposed in section 39-22-104.
(1.5)
With respect to each taxable year commencing on or after January 1, 2000, for
every individual, estate, and trust, in addition to the tax imposed in section
39-22-104, a tax is imposed in an amount equal to the excess of:
(a)
Three and forty-seven one-hundredths percent of the Colorado alternative
minimum taxable income, as determined pursuant to subsection (2) of this
section; over
(b) The
tax imposed in section 39-22-104.
(2) (a)
The Colorado alternative minimum taxable income shall be the federal
alternative minimum taxable income, as determined pursuant to section 55 of the
internal revenue code, minus the applicable federal exemptions allowed pursuant
to such section, with the modifications provided in section 39-22-104; except
that any state or local bond interest included in the federal alternative
minimum taxable income shall not be added back in determining the Colorado
alternative minimum taxable income, and any interest income from obligations of
the state of Colorado or any political subdivision thereof which is exempt from
the Colorado tax imposed pursuant to the provisions of section 39-22-104 (3)(b)
shall be subtracted from the federal alternative minimum taxable income to the
extent included therein in determining Colorado alternative minimum taxable
income.
(b) In
any case, should the tax determined under the provisions of this section for a
taxable year beginning on or after January 1, 1987, but before January 1, 1988,
exceed the tax imposed by this section as it existed on June 22, 1987, then
only the smaller tax shall apply.
(3) (a)
For taxable years beginning on or after January 1, 1988, but prior to January
1, 2000, each individual, estate, and trust shall be allowed a credit against
the tax imposed by this part 1 in an amount equal to eighteen percent of the
credit allowed for the same tax year by section 53 of the internal revenue
code.
(b) For
taxable years beginning on or after January 1, 2000, each individual, estate,
and trust shall be allowed a credit against the tax imposed by this part 1 in
an amount equal to twelve percent of the credit allowed for the same tax year
by section 53 of the internal revenue code.
(4) In
the case of a nonresident taxpayer, the tax imposed by subsections (1) and
(1.5) of this section and the credit allowed by subsection (3) of this section
shall be apportioned in the ratio of the modified federal alternative minimum
taxable income from Colorado sources over the total modified federal
alternative minimum taxable income.
Source:
L. 87: Entire part
R&RE, p. 1429, § 2, effective June 22. L. 88: Entire section
R&RE, p. 1312, § 3, effective May 29. L. 2000: IP(1), (3), and (4)
amended and (1.5) added, p. 1413, § 2, effective August 2.
Editor's
note: This section
is similar to former § 39-22-104 as it existed prior to 1987.
39-22-106. Colorado personal exemptions
of a resident individual.
A resident
individual shall be entitled to a Colorado exemption of zero dollars.
Source:
L. 87: Entire part
R&RE, p. 1430, § 2, effective June 22.
Editor's
note: This section
is similar to former § 39-22-114 as it existed prior to 1987.
39-22-107. Income tax filing status.
(1) If
the federal taxable income of two taxpayers may legally be determined on a
joint federal return but actually is determined on separate federal returns,
such income for purposes of the Colorado income tax shall be separately
determined.
(2) If
the federal taxable income of two taxpayers is determined on a joint federal
return, their tax shall be determined on their joint federal taxable income.
(3)
Repealed.
Source:
L. 87: Entire part
R&RE, p. 1430, § 2, effective June 22. L. 88: (3) repealed, p. 1317,
§ 17, effective May 29. L. 2014: (1) and (2) amended, (SB 14-019), ch.
10, p. 98, § 3, effective February 27.
Editor's
note: (1) This
section is similar to former § 39-22-109 as it existed prior to 1987.
(2) Section 9 of chapter 10 (SB
14-019), Session Laws of Colorado 2014, provides that changes to this section
by the act apply to income tax years commencing on or after January 1, 2013,
and any other income tax years that are open under § 39-21-107 or 39-21-108.
39-22-107.5. Income tax filing status -
innocent spouse relief.
In any
case in which a taxpayer has been granted relief under section 6015 of the
internal revenue code, such taxpayer shall also be granted comparable relief
from joint and several liability for the tax imposed under this article and any
interest, penalties, and other amounts related to such tax.
Source:
L. 2001: Entire
section added, p. 37, § 1, effective August 8.
39-22-108. Credit for tax paid other
states.
(1)
With respect to all taxable years commencing on or after January 1, 1987, the
amount of taxes on federal taxable income accrued to another state, the
District of Columbia, or a territory or possession of the United States, on
income derived by a resident individual, estate, or trust from sources in
another state, the District of Columbia, or a territory or possession of the
United States, shall be allowed as a credit against the tax computed under
provisions of this article.
(2) The
amount of credit taken under this section shall be subject to each of the
following limitations:
(a) The
amount of the credit for taxes on the federal taxable income taxed by another state,
the District of Columbia, or a territory or possession of the United States
shall not exceed the same proportion of the tax against which such credit is
taken which the taxpayer's federal taxable income from the sources within such
state, the District of Columbia, or a territory or possession of the United
States bears to his entire federal taxable income for the same period;
(b) The
total amount of the credit shall not exceed the same proportion of the tax
against which such credit is taken which the taxpayer's federal taxable income
from sources outside of Colorado bears to his entire federal taxable income for
the same taxable year; and
(c)
Federal taxable income shall be deemed to be from sources in another state in
the same ratio as the modified federal adjusted gross income is from sources in
such state.
(3) If
accrued taxes when paid differ from the amounts claimed as credits by the
taxpayer or if any tax paid is refunded in whole or in part, the taxpayer shall
notify the executive director, who shall redetermine the amount of tax due for
the years affected; the amount of tax, if any, found to be due upon such
redetermination shall be paid by the taxpayer upon notice and demand or the
amount of tax overpaid, if any, shall be credited or refunded to the taxpayer
in accordance with the provisions of section 39-21-108. In the case of such a
tax accrued but not paid, the executive director, as a condition precedent to
the allowance of a credit, may require the taxpayer to deposit a surety bond or
other security acceptable to the executive director in such amount as he may
require, conditioned upon the payment by the taxpayer of any amount of tax
found to be due upon any such redetermination.
(4) The
credits provided for in this section, irrespective of the method of accounting
employed by the taxpayer in keeping his books, shall be taken in the year in
which the taxes of another state, the District of Columbia, or a territory or
possession of the United States accrue, subject to the conditions prescribed in
subsection (3) of this section.
(5) The
credits provided by this section shall be allowed only if the taxpayer
furnishes to the executive director all information necessary for the
verification and computation of such credits as the executive director, by
regulation, may prescribe.
Source:
L. 87: Entire part
R&RE, p. 1430, § 2, effective June 22. L. 88: (2)(a) and (2)(b)
amended and (2)(c) added, p. 1313, § 4, effective May 29.
Editor's
note: This section
is similar to former § 39-22-108 as it existed prior to 1987.
39-22-108.5. Dual resident trusts -
income tax calculation.
(1)
With respect to a trust that is a resident of another state and becomes a
resident of Colorado after May 25, 2006, and that is subject to income taxes in
the other state and in Colorado by virtue of the trust's dual residence, the
executive director shall, in lieu of the credit granted in section 39-22-108
(1), allow a credit to the Colorado income tax to be determined in accordance
with this section.
(2) The
credit amount shall be equal to the Colorado income tax imposed on the portion
of the trust's income that is subject to tax in Colorado and the other state,
multiplied by a percentage equal to the other state's income tax rate for the
income tax year divided by the sum of the income tax rates of Colorado and the
other state for the income tax year.
(3) If
the credit amount in subsection (2) of this section is computed using more than
one other state, the percentage used shall equal the combined total of all the
other states' income tax rates for the income tax year divided by the combined
income tax rates of Colorado and the other states for the income tax year.
(4) For
purposes of this section, "state income tax rate" means the trust's
state income tax liability divided by the trust's taxable income used to
compute the state income tax liability.
(5) The
provisions of section 39-22-108 (3), (4), and (5) shall apply to this section.
Source:
L. 2006: Entire
section added, p. 1163, § 1, effective May 25.
39-22-109. Income of a nonresident
individual for purposes of Colorado income tax.
(1) In
the case of a nonresident individual, the tax imposed by section 39-22-104
shall be apportioned in the ratio of Colorado nonresident federal adjusted
gross income to total federal adjusted gross income, both modified as provided
in section 39-22-104.
(2) (a)
Colorado nonresident federal adjusted gross income means that part of the
individual's federal adjusted gross income as determined pursuant to section 62
of the internal revenue code derived from sources within Colorado. Federal
adjusted gross income of an individual shall be considered derived from sources
within Colorado when such income is attributable to:
(I) The
ownership of any interest in real or tangible personal property in Colorado;
(II) A
business, trade, profession, or occupation carried on in Colorado;
(III)
His distributive share of partnership or limited liability company income,
gain, loss, and deduction determined under section 39-22-203;
(IV)
His share of estate or trust income, gain, loss, and deduction determined under
section 39-22-404;
(V)
Income from intangible personal property, including annuities, dividends,
interest, and gains from the disposition of intangible personal property to the
extent that such income is from property employed in a business, trade,
profession, or occupation carried on in Colorado. A nonresident, other than a
dealer holding property primarily for sale to customers in the ordinary course
of his trade or business, shall not be deemed to carry on a business, trade,
profession, or occupation in Colorado solely by reason of the purchase and sale
of property for his own account.
(VI)
His share of subchapter S corporation income, gain, loss, credit, and deduction
allocable or apportionable to Colorado.
(b)
Compensation paid by the United States for service in the armed forces of the
United States performed by an individual not domiciled in Colorado shall not
constitute income derived from sources within Colorado.
(3) (a)
If the federal taxable income of two taxpayers, both of whom are nonresidents,
is determined on separate federal returns, their Colorado taxable incomes shall
be separately determined.
(b) If
the federal taxable income of two taxpayers, both of whom are nonresidents, is
determined on a joint federal return, their tax shall be determined on their
joint Colorado nonresident federal taxable income.
(c)
Repealed.
(4) In
any case, where the nature of income earned by a nonresident individual is such
as to render the computations described in subsections (1) to (3) of this section
impracticable and where the books of account and records of the taxpayer do not
clearly reflect the income subject to tax by this article, apportionment shall
be made in accordance with section 39-22-303.5 or 39-22-303.6.
Source:
L. 87: Entire part
R&RE, p. 1431, § 2, effective June 22. L. 88: (1), IP(2)(a), and
(2)(b) R&RE and (3)(c) repealed, pp. 1313, 1317, §§ 5, 17, effective May
29. L. 90: (2)(a)(III) amended, p. 453, § 33, effective April 18. L.
2008: (4) amended, p. 954, § 5, effective January 1, 2009. L. 2014:
(3)(a) and (3)(b) amended, (SB 14-019), ch. 10, p. 99, § 5, effective February
27. L. 2019: (4) amended, (SB 19-241), ch. 390, p. 3476, § 50, effective
August 2.
Editor's
note: (1) This
section is similar to former § 39-22-115 as it existed prior to 1987.
(2) Section 9 of chapter 10 (SB
14-019), Session Laws of Colorado 2014, provides that changes to this section
by the act apply to income tax years commencing on or after January 1, 2013,
and any other income tax years that are open under § 39-21-107 or 39-21-108.
ANNOTATION
Law reviews. For
article, "Tax and Estate Planning for Nonresident Real Estate
Owners", see 53 Colo. Law. 34 (Apr. 2024).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Federal law not
determinative of nonresidents' interests for state income taxation purposes.
For purposes of state income taxation, federal law is not determinative of the
characterization of the interests of nonresidents who are granted oil and gas
leases for federal lands located in Colorado. Hagood v. Heckers, 182 Colo. 337,
513 P.2d 208 (1973).
Lessee's interest in gas and
oil lease is interest in real estate. Hagood v. Heckers, 31 Colo. App. 172,
502 P.2d 961 (1972), aff'd, 182 Colo. 337, 513 P.2d 208 (1973).
For purposes of state income
taxation, the overriding royalty interests of nonresidents who are granted oil
and gas leases for federal lands located in Colorado are to be considered
interests in real property. Hagood v. Heckers, 182 Colo. 337, 513 P.2d 208
(1973).
Subchapter S corporation
income attributable to nonresident shareholders is not subject to taxation
in Colorado. Meyer v. Charnes, 705 P.2d 979 (Colo. App. 1985).
39-22-110. Apportionment of tax in the
case of a part-year resident.
(1) In
the case of an individual who is a resident of Colorado for part of his taxable
year, the tax imposed by section 39-22-104 shall be apportioned in the ratio of
that part of his federal adjusted gross income which relates to the period of
the year he was a Colorado resident to his total federal adjusted gross income,
both modified as provided in section 39-22-104.
(2) A
taxpayer filing a part-year resident return shall also file as a nonresident on
the same return as provided in section 39-22-109 for the remaining portion of
his federal taxable year in the event the taxpayer has income within such
remaining portion derived from sources within Colorado, as defined in section
39-22-109 (2).
(3)
Repealed.
(4) In
determining apportioned federal adjusted gross income which relates to the
period of the year a part-year resident was a resident as required in
subsection (1) of this section, S corporation income shall be apportioned as
provided in section 39-22-326.
Source:
L. 87: Entire part
R&RE, p. 1432, § 2, effective June 22. L. 88: (1) R&RE and (3)
repealed, pp. 1314, 1317, §§ 6, 17, effective May 29. L. 92: (4) added,
p. 2266, § 5, effective April 16.
Editor's
note: This section
is similar to former § 39-22-116 as it existed prior to 1987.
39-22-110.5. Reacquisition of residency
during active duty military service.
(1) An
individual in active duty military service whose home of record is Colorado and
whose state of legal residence commencing on or after January 1, 2016, is a
state other than Colorado may reacquire legal residence in the state,
regardless of whether the individual has a physical presence in the state, if
the individual intends to make Colorado his or her state of legal residence.
For purposes of this section, evidence of an intent to make this state an
individual's state of legal residence must include one or more of the
following:
(a)
Registering to vote in the state;
(b)
Purchasing residential property or an unimproved residential lot in the state;
(c)
Titling and registering a motor vehicle in the state;
(d)
Notifying the state of the individual's previous legal residence of the intent
to make Colorado the individual's state of legal residence; or
(e)
Preparing a new last will and testament that indicates Colorado as the
individual's state of legal residence.
(2) (a)
An individual is presumed to have acquired legal residence in a state other
than Colorado for purposes of this section if the individual was stationed in
another state while on active duty military service and provides any one of the
following:
(I) A
state of legal residence certificate, commonly known as a federal "DD Form
2058" or a successor form, signed by the individual indicating the other
state as the state of legal residence for the individual;
(II) A
federal form W-2 indicating the other state as the state of residence of the
individual;
(III)
Proof of registration to vote in the other state;
(IV)
Notification to the state of Colorado of the individual's intent to make the
other state the individual's state of legal residence; or
(V) A
last will and testament that indicates the other state as the individual's
state of legal residence.
(b) If
an individual is presumed to have acquired legal residence in a state other
than Colorado pursuant to subsection (2)(a) of this section, the presumption
may only be overcome with a preponderance of specific evidence that clearly
establishes that the individual did not intend to change his or her residence
to a state other than Colorado. The presumption shall be liberally construed to
conclude that an individual changed his or her residence to a state other than
Colorado. Nothing in this section shall be construed to prevent an individual
who is not presumed to have a state of legal residence in a state other than
Colorado pursuant to subsection (2)(a) of this section from establishing
residency in another state by other means.
Source:
L. 2015: Entire
section added, (HB 15-1181), ch. 233, p. 864, § 3, effective August 5. L.
2019: (2) added, (SB 19-029), ch. 34, p. 109, § 1, effective August 2.
Cross
references: For
the short title ("Colorado is Honoring Our Military Exemption (Colorado is
HOME) Act") and the legislative declaration in HB 15-1181, see sections 1
and 2 of chapter 233, Session Laws of Colorado 2015.
39-22-111. Accounting periods and
methods.
(1) The
taxpayer's taxable year under this article shall be the same as his taxable
year for federal income tax purposes.
(2) If
a taxpayer's taxable year is changed for federal income tax purposes, his
taxable year for purposes of this article shall be similarly changed.
(3) The
taxpayer's method of accounting under this article shall be the same as his
method of accounting for federal income tax purposes.
(4) If
a taxpayer's method of accounting is changed for federal income tax purposes,
his method of accounting for purposes of this article shall be similarly
changed.
Source:
L. 87: Entire part
R&RE, p. 1432, § 2, effective June 22.
Editor's
note: This section
is similar to former § 39-22-107 as it existed prior to 1987.
39-22-112. Persons and organizations
exempt from tax under this article.
(1) A
person or organization exempt from federal income taxation under the provisions
of the internal revenue code shall also be exempt from the tax imposed by this
article 22 in each year in which such person or organization satisfies the
requirements of the internal revenue code for exemption from federal income
taxation; except that insurance companies subject to the tax imposed on gross
premiums by section 10-3-209 shall also be exempt from the tax imposed by this
article 22. Disqualified insurance companies, as defined in section 10-1-102
(6.5), shall not be exempt from the tax imposed by this article 22. If the
exemption applicable to any person or organization under the provisions of the
internal revenue code is limited or qualified in any manner, the exemption from
taxes imposed by this article 22 shall be limited or qualified in a similar
manner.
(2)
Notwithstanding the provisions of subsection (1) of this section to the
contrary, the unrelated business taxable income, as computed under the
provisions of the internal revenue code, of any person or organization
otherwise exempt from the tax imposed by this article and subject to the tax
imposed on unrelated business income by the internal revenue code shall be
subject to the tax which would have been imposed by this article but for the
provisions of subsection (1) of this section.
Source:
L. 87: Entire part
R&RE, p. 1433, § 2, effective June 22. L. 2021: (1) amended, (HB
21-1311), ch. 298, p. 1785, § 10, effective June 23.
Editor's
note: This section
is similar to former § 39-22-111 as it existed prior to 1987.
Cross
references: For
the legislative declaration in HB 21-12311, see section 1 of chapter 298,
Session Laws of Colorado 2021.
39-22-113. Tax credit or refund for
persons with disabilities who are employed - amount - applicability. (Repealed)
Source:
L. 87: Entire part
R&RE, p. 1433, § 2, effective June 22. L. 93: (1), (2), (3)(a), and
(3)(b)(I) amended, p. 1670, § 88, effective July 1. L. 2004: Entire
section repealed, p. 207, § 32, effective August 4.
Editor's
note: Before its
repeal, this section was similar to former § 39-22-126 as it existed prior to
1987.
39-22-114. Residential energy credit.
(Repealed)
Source:
L. 87: Entire part
R&RE, p. 1434, § 2, effective June 22. L. 2002: (5)(c) amended, p.
1557, § 349, effective October 1. L. 2004: Entire section repealed, p.
208, § 33, effective August 4.
Editor's
note: Before its
repeal, this section was similar to former § 39-22-127 as it existed prior to
1987.
39-22-114.5. Tax credit for investment in
technologies for recycling plastics - repeal.
(1) For
income tax years commencing prior to January 1, 2023, there shall be allowed to
each resident individual, as a credit against the income taxes imposed by this
article 22, a plastic recycling credit equal to twenty percent of net
expenditures to third parties for rent, wages, supplies, consumable tools,
equipment, test inventory, and utilities up to ten thousand dollars made by the
taxpayer for new plastic recycling technology in Colorado, with a maximum
credit of two thousand dollars. The tax credit allowed in this section shall be
applicable only to income related to the expenditures described in this
subsection (1).
(2) If
the credit allowed under this section exceeds the income taxes otherwise due on
the claimant's income, the amount of the credit not used as an offset against
income taxes may be carried forward as a tax credit against subsequent years'
income tax liability for a period not exceeding five years and shall be applied
first to the earliest years possible.
(3) Any
form filed with the department of revenue for the purpose of claiming the
credit allowed by this section shall be accompanied by copies of any receipts,
bills, or other documentation of the qualified expenditures claimed for the
purpose of receiving such credit.
(4)
This section is repealed, effective July 1, 2029.
Source:
L. 89: Entire
section added, p. 1182, § 3, effective July 1. L. 2022: (1) amended and
(4) added, (HB 22-1025), ch. 145, p. 945, § 3, effective August 10.
39-22-115. Credit for crops or
livestock contributed to charitable organizations - definitions. (Repealed)
Source:
L. 87: Entire part
R&RE, p. 1435, § 2, effective June 22. L. 2004: Entire section
repealed, p. 209, § 34, effective August 4.
Editor's
note: Before its
repeal, this section was similar to former § 39-22-128 as it existed prior to
1987.
39-22-116. Tax tables for individuals.
(1) In
lieu of the tax imposed by section 39-22-104, there is hereby imposed for each
taxable year on the federal taxable income of every individual for Colorado
income tax purposes who does not itemize his deductions for the taxable year
and whose federal taxable income for Colorado income tax purposes for such
taxable year does not exceed the ceiling amount a tax determined under tables
applicable to such taxable year, which shall be prescribed by the executive
director and which shall be in such form as he deems appropriate. In the tables
so prescribed, the amount of the tax shall be computed on the basis of the rate
prescribed by section 39-22-104.
(2) For
purposes of subsection (1) of this section, "ceiling amount" means,
with respect to any taxpayer, the amount, not less than twenty thousand
dollars, determined by the executive director for the tax rate category in
which such taxpayer falls.
(3)
Repealed.
(4) For
purposes of this article, the tax imposed by this section shall be treated as
the tax imposed by section 39-22-104.
(5)
Whenever it is necessary to determine the federal taxable income of an
individual for Colorado income tax purposes to whom this section applies, the
federal taxable income for Colorado income tax purposes shall be determined
under section 39-22-104.
(6) The
executive director may provide that this section shall apply for any taxable
year to individuals who itemize their deductions.
Source:
L. 87: Entire part
R&RE, p. 1436, § 2, effective June 22. L. 88: (1) amended and (3)
repealed, pp. 1314, 1317, §§ 7, 17, effective May 29.
39-22-117. Uninsurable health plan
charge - repeal. (Repealed)
Source:
L. 90: Entire
section added, p. 640, § 2, effective July 1; (3) added by revision, p. 641, §
5.
Editor's
note: Subsection
(3) provided for the repeal of this section, effective July 1, 1993. (See L.
90, p. 641.)
39-22-118. Grants for members of United
States armed services - combat pay received during active duty in Operation
Desert Storm - amount - applicability - repeal. (Repealed)
Source:
L. 91: Entire
section added, p. 1998, § 1, effective May 1. L. 92: (2) amended, p.
1067, § 2, effective March 16.
Editor's
note: Subsection
(3) provided for the repeal of this section, effective June 15, 1994. (See L.
91, p. 1998.)
39-22-119. Expenses related to child
and dependent care - refundable credit against state tax - tax preference
performance statement - legislative declaration - definition - repeal.
(1)
Repealed.
(1.3)
(a) The general assembly finds and declares that, pursuant to section
39-21-304 (1), the income tax credit created in this section is intended to
provide tax relief for certain individuals. Specifically, the credit is
intended to assist low- and moderate-income Coloradans in meeting the high cost
of child and dependent care by providing additional support beyond what may be
available through federal tax law.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1.3)(a) of this
section based on the number of resident individuals who have claimed the credit
and the total amount of credits claimed.
(1.5)
Repealed.
(1.7) (a)
(I) For income tax years beginning on and after January 1, 2019, but before
January 1, 2026, if a resident individual's federal adjusted gross income is
less than or equal to sixty thousand dollars and the individual claims a credit
for child and dependent care expenses on the individual's federal tax return as
allowed pursuant to section 21 of the internal revenue code, then the
individual is allowed a child and dependent care expenses credit against the
income taxes imposed by this article 22. The credit is an amount equal to fifty
percent of the credit for child and dependent care expenses claimed on the
individual's federal tax return for the same income tax year.
(II)
This subsection (1.7)(a) is repealed, effective December 31, 2030.
(b) For
income tax years beginning on and after January 1, 2026, except as provided in
subsection (1.7)(c) of this section, if a resident individual's federal
adjusted gross income is less than or equal to sixty thousand dollars, then the
individual is allowed a child and dependent care expenses credit against the
income taxes imposed by this article 22. The credit is an amount equal to
seventy percent of the federal credit allowed pursuant to section 21 of the
internal revenue code and calculated without regard to the limitation imposed
by section 26 of the internal revenue code.
(c) (I)
For income tax years commencing on or after January 1, 2027, the executive
director shall adjust the federal adjusted gross income limit set forth in
subsection (1.7)(b) of this section for inflation for each income tax year in
which the credit is allowed if cumulative inflation since the last adjustment,
when applied to the current limitation, results in an increase of at least one
thousand dollars when the adjusted limits are rounded to the nearest one
thousand dollars.
(II) As
used in this subsection (1.7)(c), "inflation" means the annual
percentage change in the United States department of labor bureau of labor
statistics consumer price index, or a successor index, for
Denver-Aurora-Lakewood for all items paid by urban consumers.
(2) If
the credit allowed pursuant to this section exceeds the income taxes due on the
resident individual's income, the amount of the credit not used to offset
income taxes is not carried forward and must be refunded to the individual.
(3) The
child and dependent care expenses credit allowed pursuant to this section is
not allowed to a resident individual who is receiving child care assistance
from the department of early childhood except to the extent of the taxpayer's
unreimbursed out-of-pocket expenses that result in a federal credit for child
and dependent care expenses.
(4) In
the case of a resident for part of a tax year, the credit allowed by this
section is apportioned in the ratio determined under section 39-22-110 (1).
(5) to
(9) Repealed.
(10)
Notwithstanding section 39-21-304 (4), the credit allowed pursuant to this
section continues indefinitely.
Source:
L. 96: Entire
section added, p. 1096, § 1, effective May 30. L. 98: (1.5) added and
(2) to (4) amended, p. 1373, § 1, effective June 2. L. 2000: (2) and (3)
amended and (5), (6), (7), (8), and (9) added, p. 675, § 1, effective May 23. L.
2010: (1.5), (5), (6), (7), (8), and (9) repealed and (2) and (3) amended,
(SB 10-212), ch. 412, pp. 2032, 2035, §§ 1, 8, effective July 1. L. 2018:
IP(1)(a), (2), and (3) amended and (1.7) added, (HB 18-1208), ch. 227, p. 1437,
§ 1, effective August 8. L. 2022: (3) amended, (HB 22-1295), ch. 123, p.
868, § 128, effective July 1. L. 2024: (1) repealed, (1.3) and (10)
added, and (1.7), (2), (3), and (4) amended, (HB 24-1134), ch. 172, p. 926, §
1, effective August 7.
39-22-119.5. Child care expenses tax
credit - legislative declaration - definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I)
Colorado families and the state economy thrive when parents are able to work;
(II)
While research shows that high-quality child care contributes to economic mobility,
child care can be cost prohibitive for low-income working parents;
(III)
The general assembly created the child care expenses tax credit in section
39-22-119 in 1996 to make child care more affordable for working families;
(IV)
The credit in section 39-22-119 is currently based on the amount claimed for a
similar federal credit;
(V) As
a result, some low-income families are not receiving the state child care
expenses tax credit because they fail to file a federal return or, based on
their income taxes owed, are ineligible for a federal credit; and
(VI) As
a result, the state tax credit is unintentionally unfair and regressive.
(b)
Now, therefore, the general assembly declares that the intended purpose for
creating and extending the term of the tax credit in this section is to fix the
Colorado child care expenses income tax credit so that all low-income working
families are able to claim the credit regardless of the amount of their federal
child care expenses credit.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Credit" means the child care expenses tax credit created in this
section.
(b)
"Dependent" has the same meaning as in section 152 (a)(1) of the
internal revenue code, or any successor section.
(3) (a)
For income tax years beginning on and after January 1, 2014, but before January
1, 2017, and for income tax years beginning on and after January 1, 2018, but
before January 1, 2026, a resident individual is allowed a credit against the
taxes due under this article 22 for child care expenses that the individual
incurred during the taxable year if:
(I) The
individual has an adjusted gross income of twenty-five thousand dollars or
less;
(II)
The individual has insufficient tax liability to claim any credit under section
39-22-119;
(III)
The expenses are for the care of a dependent of the taxpayer who is less than
thirteen years old; and
(IV)
The individual would be allowed a credit for the expenses under section 21 of
the internal revenue code, or any successor section, if he or she had
sufficient tax liability to claim the credit.
(a.5)
Repealed.
(b) The
credit is equal to twenty-five percent of the resident individual's child care
expenses; except that the maximum amount of a credit that a resident individual
is allowed under this section is:
(I)
Five hundred dollars for a single dependent; or
(II)
One thousand dollars for two or more dependents.
(c) The
amount of the credit that exceeds the resident individual's income taxes due is
refunded to the individual.
(4) The
amount of an individual's child care expenses incurred during a taxable year
that may be the basis of the credit shall not exceed:
(a) In
the case of an individual who files a single return, the individual's earned
income for the year; or
(b) In
the case of two individuals who file a joint return, the lesser of either
individual's earned income for the year.
(5) (a)
Except as set forth in paragraph (b) of this subsection (5), a resident
individual is not allowed a credit for any amount paid to any person who
provides child care unless:
(I) The
name, address, and taxpayer identification number of the person are included on
the resident individual's return; or
(II) If
the person is an organization described in section 501 (c)(3) of the internal
revenue code, or any successor section, and exempt from tax under section 501
(a) of the internal revenue code, or any successor section, the name and
address of the person are included on the resident individual's return.
(b) If
the resident individual does not provide the taxpayer identification number but
is able to show that he or she exercised due diligence in attempting to provide
the required information, the individual may claim the credit.
(c) A
resident individual may not claim a credit with respect to a dependent unless
the resident individual includes the dependent's name and taxpayer
identification number on the individual's return.
(6) In
the case of a part-year resident, the credit is apportioned in the ratio
determined under section 39-22-110 (1).
(7)
Repealed.
(8)
This section is repealed, effective December 31, 2030.
Source:
L. 2014: Entire
section added, (HB 14-1072), ch. 258, p. 1026, § 1, effective August 6. L.
2017: (1)(b), IP(3)(a), and (7) amended and (3)(a.5) added, (HB 17-1002),
ch. 315, p. 1693, § 1, effective August 9. L. 2019: IP(3)(a) amended and
(3)(a.5) and (7) repealed, (HB 19-1013), ch. 177, p. 2026, § 1, effective
August 2. L. 2024: IP(3)(a) amended and (8) added, (HB 24-1134), ch.
172, p. 928, § 2, effective August 7.
39-22-120. Legislative declaration -
state sales tax refund - offset against state income tax. (Repealed)
Source:
L. 97, 1st Ex. Sess.:
Entire section added, p. 1, § 1, effective October 22. L. 98, 2nd Ex. Sess.:
(1)(b), (1)(e), (1)(f), (1)(e), and (2) to (7) amended and (8) to (11) added,
p. 1, § 1, effective September 16. L. 99: (5.5) added, p. 1364, § 1,
effective June 3. L. 2002: (10) amended, p. 1557, § 350, effective
October 1. L. 2004: (10) amended, p. 1209, § 89, effective August 4. L.
2007: (5.5)(c) amended, p. 2049, § 95, effective June 1. L. 2024:
Entire section repealed, (SB 24-228), ch. 170, p. 899, § 6, effective May 14;
(5)(c)(I) amended, (HB 24-1268), ch. 475, p. 3335, § 6, effective August 7.
Editor's
note: Subsection
(5)(c)(I) was amended in HB 24-1268, effective August 7, 2024. Those amendments
were superseded by the repeal of this section by SB 24-228, effective May 14,
2024.
39-22-120.5. Unrefunded excess revenues.
(Repealed)
Source:
L. 99: Entire
section added, p. 1365, § 2, effective June 3. L. 2005: Entire section
repealed, p. 133, § 4, effective April 5.
39-22-121. Credit for child care
facilities - legislative declaration - definitions - repeal.
(1)
Repealed.
(1.5)
For income tax years commencing prior to January 1, 2038, any taxpayer who
makes a monetary contribution to promote child care in the state is allowed a
credit against the income tax imposed by this article 22 in an amount equal to
fifty percent of the total value of the contribution, except as otherwise
provided in subsections (5) and (6.7) of this section.
(1.7)
As used in this section, unless the context otherwise requires, "child
care" means care provided to a child twelve years of age or younger.
(2)
Monetary contributions to promote child care in the state include the following
types of contributions:
(a)
Donating money for the establishment or operation of a child care facility that
uses the donation to provide child care, a child care program that is not a
child care facility but provides child care services similar to those provided
by a child care center, as defined in sections 26-6-903 and 26.5-5-303, or any
other program that received donations for which a credit was allowed to the
donor pursuant to this section for any income tax year that ended before
January 1, 2004, in the state;
(b)
Donating money to establish a grant or loan program for a parent or parents in
the state requiring financial assistance for child care;
(c)
Pooling money of several businesses and donating the money for the
establishment of a child care facility in the state;
(d)
Donating money for the training of child care providers in the state; and
(e)
Donating money for the establishment of an information dissemination program in
the state to provide information and referral services to assist a parent or
parents in obtaining child care.
(3) In
no event shall credits be allowed pursuant to this section for contributions
that are not directly related to promoting child care in the state or for
contributions that a taxpayer makes to a child care facility in which the
taxpayer or a person related to the taxpayer has a financial interest.
(4)
When a contribution for which a credit is claimed pursuant to this section is
made to a for-profit business, such contribution shall be directly invested by
the business for the acquisition or improvement of facilities, equipment, or
services, including the improvement of staff salaries, staff training, or the
quality of child care.
(5) The
credit allowed by this section shall not exceed one hundred thousand dollars or
the taxpayer's actual income tax liability for the tax year for which the
credit is claimed, whichever is less.
(6) If
the amount of the credit allowed pursuant to the provisions of this section
exceeds the amount of income taxes otherwise due on the taxpayer's income in
the income tax year for which the credit is being claimed, the amount of the
credit not used as an offset against income taxes in said income tax year may
be carried forward and used as a credit against subsequent years' income tax
liability for a period not to exceed five years and shall be applied first to
the earliest income tax years possible. Any credit remaining after said period
shall not be refunded or credited to the taxpayer.
(6.5)
As used in this section, "child care facility" means:
(a) Any
facility required to be licensed pursuant to part 9 of article 6 of title 26 or
part 3 of article 5 of title 26.5 and must include, but is not limited to:
(I)
Child care centers;
(II)
Child placement agencies;
(III)
Family child care homes;
(IV)
Foster care homes;
(V)
Homeless youth shelters;
(VI)
Residential child care facilities; and
(VII)
Secure residential treatment centers; and
(b) For
income tax years commencing on and after January 1, 2013, any approved facility
school as such term is defined in section 22-2-402 (1), C.R.S., that is also
affiliated with a licensed or certified hospital in the state and is also a
nonprofit organization; except that, subject to the limitations specified in
subsections (5) and (6) of this section and paragraph (d) of subsection (6.7)
of this section, any credit for a monetary contribution made to an approved
facility school in the income tax year commencing on or after January 1, 2013,
but before January 1, 2014, shall not be claimed until the income tax year
commencing on or after January 1, 2014.
(6.7)
(a) If the revenue estimate prepared by the staff of the legislative council
in December 2010 and December 2011 indicates that the amount of the total
general fund revenues for that particular fiscal year will not be sufficient to
grow the total state general fund appropriations by six percent over such
appropriations for the previous fiscal year, then the credit authorized in this
section shall not be allowed for any income tax year commencing during the
calendar year following the year in which the estimate is prepared; except that
any taxpayer who would have been eligible to claim a credit pursuant to this
section in the income tax year in which the credit is not allowed shall be
allowed to claim the credit earned in such income tax year in the next income
tax year in which the estimate indicates that the amount of the total general
fund revenues will be sufficient to grow the total state general fund
appropriations by six percent over such appropriations for the previous fiscal
year.
(b) The
department of revenue shall, through its website, specify on or before January
1, 2011, and January 1, 2012, whether the credit authorized in this section
shall be allowed for a given income tax year pursuant to paragraph (a) of this
subsection (6.7).
(c)
Notwithstanding any other provision, and subject to the limitations in
subsections (5) and (6) of this section, in the income tax year commencing on
January 1, 2013, a taxpayer may claim no more than fifty percent of any credit
allowed pursuant to subsection (1.5) of this section and paragraph (a) of this
subsection (6.7) and any credit carried forward pursuant to subsection (6) of
this section. The remainder of all credits allowed as described in this
paragraph (c) shall be carried forward to the income tax year commencing
January 1, 2014.
(d)
Notwithstanding any other provision, and subject to the limitations in
subsections (5) and (6) of this section, in the income tax year commencing on
January 1, 2014, a taxpayer may claim no more than seventy-five percent of any
credit allowed pursuant to subsection (1.5) of this section and any credit
carried forward pursuant to subsection (6) of this section and paragraph (c) of
this subsection (6.7). The remainder of all credits allowed as described in
this paragraph (d) shall be carried forward to the income tax year commencing
January 1, 2015.
(6.8)
(a) In accordance with section 39-21-304 (1), which requires each bill that
extends a tax expenditure to amend the tax preference performance statement
that is part of the statutory legislative declaration of the tax expenditure,
the general assembly finds and declares that the general purpose of this tax
expenditure is to induce certain designated behavior by taxpayers and that this
tax expenditure is specifically intended to encourage taxpayers to make
donations that promote child care in the state.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (6.8)(a) of this
section based on the number and value of credits that are claimed. For income
tax years commencing on or after January 1, 2024, in order to allow the general
assembly and the state auditor to measure the effectiveness of the credit, the
department of revenue, when administering the credit, shall collect, at a
minimum, the following information about the taxpayer's contribution to promote
child care:
(I) The
contribution amount;
(II)
The person to whom the taxpayer made the contribution;
(III)
The type of contribution made pursuant to subsection (2) of this section;
(IV)
The type of child care facility and programs to which the taxpayer made the
contribution; and
(V) The
county in which the person receiving the donation is located.
(c)
Repealed.
(d) In
the income tax year commencing January 1, 2026, the state auditor shall prepare
a tax expenditure evaluation report pursuant to section 39-21-305 for the tax
credit specified in this section. In accordance with section 39-21-305 (1)(e),
the state auditor shall post the report on the general assembly's website and
deliver the report to the joint budget committee and the finance committees of
the senate and the house of representatives no later than September 15, 2026.
(7)
This section is repealed, effective January 1, 2045.
Source:
L. 98: Entire
section added, p. 1370, § 1, effective August 5. L. 2000: (1) amended
and (1.5) added, p. 678, § 2, effective May 23. L. 2004: (1.7) added and
(2)(a) and (7) amended, p. 84, § 1, effective March 9. L. 2008: (2)(a)
and (7) amended and (6.5) and (6.7) added, p. 2269, § 1, effective August 5. L.
2009: (6.7)(a) amended, (SB 09-228), ch. 410, p. 2265, § 18, effective July
1. L. 2011: (1.5) and (6.7) amended, (HB 11-1014), ch. 247, p. 1080, §
1, effective August 10. L. 2012: (6.5) amended, (HB 12-1273), ch. 270,
p. 1424, § 2, effective August 8. L. 2016: (2)(a) amended, (SB 16-189),
ch. 210, p. 794, § 109, effective June 6. L. 2018: (1.5) and (7)
amended, (HB 18-1004), ch. 327, p. 1965, § 1, effective August 8. L. 2021:
(1) repealed and IP(2), (2)(a), (2)(c), (2)(e), and (5) amended, (HB 21-1154),
ch. 54, p. 226, § 1, effective September 7. L. 2022: IP(2), (2)(a),
IP(6.5), and IP(6.5)(a) amended, (HB 22-1295), ch. 123, p. 868, § 129,
effective July 1. L. 2023: (1.5), (2), and (7) amended and (6.8) added,
(HB 23-1091), ch. 241, p. 1294, § 1, effective August 7. L. 2026: (1.5),
(6.8)(a), and (7) amended and (6.8)(c) repealed, (HB 26-1004), ch. 184, p.
1079, § 2, effective August 12.
Cross
references: (1)
For the legislative declaration in the 2012 act amending subsection (6.5), see
section 1 of chapter 270, Session Laws of Colorado 2012.
(2) For the legislative
declaration in HB 26-1004, see section 1 of chapter 184, Session Laws of
Colorado 2026.
39-22-122. Long-term care insurance
credit.
(1) Any
resident individual who incurs an expense in purchasing or making a payment
upon a policy of long-term care insurance for the individual or the
individual's spouse shall be allowed a credit against the income taxes due on
the individual's income under this article. The credit shall be an amount equal
to twenty-five percent of the amount expended for such insurance during the
taxable year for which the credit is claimed. For the purposes of this section,
"long-term care insurance" shall have the same meaning as in section
10-19-103 (5), C.R.S.
(2)
Notwithstanding any other provision of this section to the contrary, a credit
shall only be allowed to:
(a) An
individual filing a single return with a federal taxable income of less than
fifty thousand dollars for the tax year for which the credit is claimed;
(b) Two
individuals filing a joint return with a federal taxable income of less than
fifty thousand dollars for the tax year for which the credit is claimed if
claiming the credit for one policy; or
(c) Two
individuals filing a joint return with a federal taxable income of less than
one hundred thousand dollars for the tax year for which the credit is claimed
if claiming the credit for two policies or for a joint policy that covers each
individual separately.
(3)
Notwithstanding any other provision of this section to the contrary, the amount
of credit claimed pursuant to this section shall not exceed one hundred fifty
dollars for each policy for which a credit is claimed pursuant to this section.
(4) If
the credit allowed under subsection (1) of this section exceeds the income
taxes due on the resident individual's income, the amount of the credit not
used to offset income taxes shall not be carried forward as tax credits against
the resident individual's subsequent years' income tax liability and shall not
be refunded to the individual.
(5) Any
credit allowed pursuant to the provisions of this section shall be published in
rules promulgated by the executive director of the department of revenue in
accordance with article 4 of title 24, C.R.S., and shall be included in income
tax forms for that taxable year.
Source:
L. 99: Entire
section added, p. 1362, § 1, effective August 4. L. 2001: (2)(c)
amended, p. 393, § 3, effective August 8.
Cross
references: For
the legislative declaration contained in the 2001 act amending subsection
(2)(c), see section 1 of chapter 133, Session Laws of Colorado 2001.
39-22-123. Earned income tax credit -
refund of state excess revenues for fiscal years commencing on or after July 1,
1998.
(1) (a)
Repealed.
(b)
Subject to the provisions of subsection (4) of this section, for any income tax
year commencing on or after January 1, 2000, if, based on the financial report
prepared by the controller in accordance with section 24-77-106.5, C.R.S., the
controller certifies that the amount of state revenues for the state fiscal
year ending in that income tax year exceeds the limitation on state fiscal year
spending imposed by section 20 (7)(a) of article X of the state constitution
and the voters statewide either have not authorized the state to retain and
spend all of the excess state revenues or have authorized the state to retain
and spend only a portion of the excess state revenues for that fiscal year, a
resident individual or part-year resident individual who claims an earned
income tax credit on the individual's federal tax return shall be allowed an
earned income tax credit against the taxes due on the individual's income under
this article. The amount of the credit shall be an amount equal to ten percent of
the amount of the federal credit claimed on the resident individual's federal
tax return or, in the case of a part-year resident individual, such amount as
shall reflect ten percent of the federal earned income credit earned while a
resident of Colorado.
(2) If
the credit allowed under subsection (1) of this section exceeds the income
taxes due on the resident individual's income, the amount of the credit not
used to offset income taxes shall not be carried forward as tax credits against
the resident individual's subsequent years' income tax liability and shall be
refunded to the individual.
(3) Any
earned income tax credit allowed for any given taxable year pursuant to this
section shall be published in rules promulgated by the executive director of
the department of revenue in accordance with article 4 of title 24, C.R.S., and
shall be included in income tax forms for that taxable year.
(3.5)
Any earned income tax credit allowed to any person pursuant to subsection (1)
of this section shall not be considered as income or resources for the purpose
of determining eligibility or for the payment of public assistance benefits and
medical assistance benefits authorized under state law or for payments made
under any other publicly funded programs.
(4) (a)
If, based on the financial report prepared by the controller in accordance with
section 24-77-106.5, C.R.S., the controller certifies that the amount of state
revenues for the state fiscal year commencing on July 1, 1998, exceeds the
limitation on state fiscal year spending imposed by section 20 (7)(a) of
article X of the state constitution for that fiscal year by less than fifty
million dollars, then the credit authorized by subsection (1) of this section
shall not be allowed for the income tax year commencing on January 1, 1999.
(b) If,
based on the financial report prepared by the controller in accordance with
section 24-77-106.5, C.R.S., the controller certifies that the amount of state
revenues for any state fiscal year commencing on or after July 1, 1999, exceeds
the limitation on state fiscal year spending imposed by section 20 (7)(a) of
article X of the state constitution for that fiscal year by less than fifty
million dollars, as adjusted pursuant to paragraph (c) of this subsection (4),
then the credit authorized by subsection (1) of this section shall not be
allowed for the income tax year in which said state fiscal year ended.
(c) (I)
No later than October 1 of any given calendar year commencing on or after
January 1, 2000, the executive director of the department of revenue shall
annually adjust the dollar amount specified in paragraph (b) of this subsection
(4) to reflect the rate of growth of Colorado personal income for the calendar
year immediately preceding the calendar year in which such adjustment is made.
For purposes of this subparagraph (I), "the rate of growth of Colorado
personal income" means the percentage change between the most recent
published annual estimate of total personal income for Colorado, as defined and
officially reported by the bureau of economic analysis in the United States
department of commerce for the calendar year immediately preceding the calendar
year in which the adjustment is made and the most recent published annual
estimate of total personal income for Colorado, as defined and officially
reported by the bureau of economic analysis in the United States department of
commerce for the calendar year prior to the calendar year immediately preceding
the calendar year in which the adjustment is made.
(II)
Upon calculating the adjustment of said dollar amount in accordance with
subparagraph (I) of this paragraph (c), the executive director shall notify in
writing the executive committee of the legislative council created pursuant to
section 2-3-301 (1), C.R.S., of the adjusted dollar amount and the basis for
the adjustment. Such written notification shall be given within five working
days after such calculation is completed, but such written notification shall
be given no later than October 1 of the calendar year.
(III)
It is the function of the executive committee to review and approve or
disapprove such adjustment of said dollar amount within twenty days after
receipt of such written notification from the executive director. Any
adjustment that is not approved or disapproved by the executive committee
within said twenty days shall be automatically approved; except that, if within
said twenty days the executive committee schedules a hearing on such
adjustment, such automatic approval shall not occur unless the executive
committee does not approve or disapprove such adjustment after the conclusion
of such hearing. Any hearing conducted by the executive committee pursuant to
this subparagraph (III) shall be concluded no later than twenty-five days after
receipt of such written notification from the executive director.
(IV)
(A) If the executive committee disapproves any adjustment of said dollar
amount calculated by the executive director pursuant to this paragraph (c), the
executive committee shall specify such adjusted dollar amount to be utilized by
the executive director. Any adjusted dollar amount specified by the executive
committee pursuant to this sub-subparagraph (A) shall be calculated in
accordance with the provisions of this paragraph (c).
(B) For
the purpose of determining whether the credit authorized by subsection (1) of
this section is to be allowed for any given income tax year, the executive
director shall not utilize any adjusted dollar amount that has not been
approved pursuant to subparagraph (III) of this paragraph (c) or otherwise
specified pursuant to sub-subparagraph (A) of this subparagraph (IV).
(V) If
one or more ballot questions are submitted to the voters at a statewide
election to be held in November of any calendar year commencing on or after
January 1, 1999, that seek authorization for the state to retain and spend all
or any portion of the amount of excess state revenues for the state fiscal year
ending during said calendar year, the executive director shall not determine
whether the credit authorized by subsection (1) of this section shall be
allowed and shall not promulgate rules containing said credit until the impact
of the results of said election on the amount of the excess state revenues to
be refunded is ascertained.
(5) The
general assembly finds and declares that an earned income tax credit is a
reasonable method of refunding a portion of the state excess revenues required
to be refunded in accordance with section 20 (7)(d) of article X of the state
constitution.
(6) No
credit is allowed under this section for an income tax year for which a credit
is allowed under section 39-22-123.5.
Source:
L. 99: Entire
section added, p. 1327, § 1, effective June 3. L. 2000: (1) amended and
(3.5) added, p. 1407, § 1, effective August 2. L. 2013: (6) added, (SB
13-001), ch. 381, p. 2227, § 2, effective August 7.
Editor's
note: Subsection
(1)(a)(II) provided for the repeal of subsection (1)(a), effective January 1,
2005. (See L. 2000, p. 1407.)
Cross
references: In
2013, subsection (6) was added by the "Colorado Working Families Economic
Opportunity Act of 2013". For the short title, see section 1 of chapter
381, Session Laws of Colorado 2013.
39-22-123.5. Earned income tax credit -
legislative declaration - repeal.
(1) The
general assembly hereby finds and declares that:
(a) The
federal earned income tax credit is a refundable tax credit for low- and
middle-income working individuals and families whose earnings are below an
income threshold;
(b) The
amount of the credit increases with income until the credit reaches a maximum
level and then phases out, and this structure creates an incentive for people
to work and earn more income;
(c)
Since its establishment in 1975, the credit has increased family income,
reduced child poverty, and promoted employment by supplementing the earnings of
low-wage workers, including military families;
(d) The
credit has a positive impact on the education and health of children living in
poverty;
(e) The
credit has a positive economic impact on local economies and businesses because
it puts more money in the hands of low- and middle-income working people who
spend the money on immediate needs, such as groceries, school supplies, car
repairs, rent, and health care;
(f) The
Colorado earned income tax credit created in section 39-22-123 is ten percent
of the federal earned income tax credit, but it is a mechanism to refund excess
state revenues as required by section 20 of article X of the state
constitution;
(g)
This existing credit has not been in effect since 2001 because the refund has
not been triggered; and
(h)
Now, therefore, it is the intent of the general assembly to establish a
permanent and refundable state earned income tax credit for eligible Colorado
taxpayers. The intended purpose of this credit is to help individuals and
families achieve greater financial security and to help Colorado's economy.
(2) (a)
(I) For an income tax year commencing prior to January 1, 2022, a resident
individual who claims an earned income tax credit on the individual's federal
tax return is allowed an earned income tax credit against the taxes due under
this article 22 that is equal to ten percent of the federal credit that the
resident individual claimed on his or her federal tax return for the same tax
year.
(II)
This subsection (2)(a) is repealed, effective December 31, 2032.
(b) (I)
For income tax years commencing on or after January 1, 2022, but before January
1, 2023, a resident individual who claims an earned income tax credit on the
individual's federal tax return is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to twenty percent of the
federal credit that the resident individual claimed on his or her federal tax
return for the same tax year.
(II)
This subsection (2)(b) is repealed, effective December 31, 2033.
(c) (I)
For income tax years commencing on or after January 1, 2023, but before January
1, 2024, a resident individual who claims an earned income tax credit on the
individual's federal tax return is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to twenty-five percent of the
federal credit that the resident individual claimed on his or her federal tax
return for the same tax year.
(II)
This subsection (2)(c) is repealed, effective December 31, 2034.
(d) (I)
A resident individual who claims an earned income tax credit on the
individual's federal tax return is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to the applicable amount set
forth in subsection (2)(d)(II) of this section.
(II)
Except as otherwise provided in subsection (3.5) of this section, the credit
amount that can be claimed pursuant to subsection (2)(d)(I) of this section is:
(A) For
the income tax year commencing on January 1, 2024, fifty percent of the federal
credit that the resident individual claimed on the resident individual's
federal tax return for the same tax year;
(B) For
the income tax year commencing on January 1, 2025, thirty-five percent of the
federal credit that the resident individual claimed on the resident
individual's federal tax return for the same tax year; and
(C) For
income tax years commencing on or after January 1, 2026, twenty-five percent of
the federal credit that the resident individual claimed on the resident
individual's federal tax return for the same tax year.
(2.5) (a)
(I) For income tax years commencing on or after January 1, 2020, but before
January 1, 2022, a resident individual is allowed an earned income tax credit
against the taxes due under this article 22 that is equal to ten percent of the
federal credit that the resident individual would have been allowed, but for
the fact that the resident individual, the resident individual's spouse, or one
or more of the resident individual's dependents do not have a social security
number that is valid for employment.
(II)
This subsection (2.5)(a) is repealed, effective December 31, 2032.
(b) (I)
For income tax years commencing on or after January 1, 2022, but before January
1, 2023, a resident individual is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to twenty percent of the
federal credit that the resident individual would have been allowed, but for
the fact that the resident individual, the resident individual's spouse, or one
or more of the resident individual's dependents do not have a social security
number that is valid for employment.
(II)
This subsection (2.5)(b) is repealed, effective December 31, 2033.
(c)
Repealed.
(d) (I)
For income tax years commencing on or after January 1, 2023, but before January
1, 2024, a resident individual is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to twenty-five percent of the
federal credit that the resident individual would have been allowed, but for
the fact that the resident individual, the resident individual's spouse, or one
or more of the resident individual's dependents do not have a social security
number that is valid for employment.
(II)
This subsection (2.5)(d) is repealed, effective December 31, 2034.
(e) (I)
A resident individual is allowed an earned income tax credit against the taxes
due under this article 22 that is equal to the applicable percentage set forth
in subsection (2.5)(e)(II) of this section of the federal credit that the
resident individual would have been allowed, but for the fact that the resident
individual, the resident individual's spouse, or one or more of the resident
individual's dependents do not have a social security number that is valid for
employment.
(II)
Except as otherwise provided in subsection (3.5) of this section, the
percentage used to calculate the amount of credit that can be claimed pursuant
to subsection (2.5)(e)(I) of this section is:
(A) For
the income tax year commencing on January 1, 2024, fifty percent;
(B) For
the income tax year commencing on January 1, 2025, thirty-five percent; and
(C) For
income tax years commencing on or after January 1, 2026, twenty-five percent.
(2.7) (a)
(I) For income tax years commencing on or after January 1, 2022, but before
January 1, 2023, a resident individual is allowed an earned income tax credit
against the taxes due under this article 22 that is equal to twenty percent of
the federal credit that the resident individual would have been allowed under
section 32 (n)(1) of the internal revenue code, notwithstanding the date
limitation set forth in section 32 (n) of the internal revenue code as
specified in section 9621 (a) of the "American Rescue Plan Act of
2021", Pub.L. 117-2.
(II)
This subsection (2.7)(a) is repealed, effective December 31, 2033.
(b) (I)
For income tax years commencing on or after January 1, 2023, but before January
1, 2024, a resident individual is allowed an earned income tax credit against
the taxes due under this article 22 that is equal to twenty-five percent of the
federal credit that the resident individual would have been allowed under
section 32 (n)(1) of the internal revenue code, notwithstanding the date
limitation set forth in section 32 (n) of the internal revenue code as
specified in section 9621 (a) of the "American Rescue Plan Act of
2021", Pub.L. 117-2.
(II)
This subsection (2.7)(b) is repealed, effective December 31, 2034.
(c) (I)
A resident individual is allowed an earned income tax credit against the taxes
due under this article 22 that is equal to the applicable percentage set forth
in subsection (2.7)(c)(II) of this section of the federal credit that the
resident individual would have been allowed under section 32 (n)(1) of the
internal revenue code, notwithstanding the date limitation set forth in section
32 (n) of the internal revenue code as specified in section 9621 (a) of the
"American Rescue Plan Act of 2021", Pub.L. 117-2.
(II)
Except as otherwise provided in subsection (3.5) of this section, the
percentage used to calculate the amount of credit that can be claimed pursuant
to subsection (2.7)(c)(I) of this section is:
(A) For
the income tax year commencing on January 1, 2024, fifty percent;
(B) For
the income tax year commencing on January 1, 2025, thirty-five percent; and
(C) For
income tax years commencing on or after January 1, 2026, twenty-five percent.
(d) (I)
For income tax years commencing on or after January 1, 2028, a resident
individual is allowed an earned income tax credit against the taxes due under
this article 22 that is equal to the applicable percentage, set forth in
subsection (2.7)(d)(II) of this section, of the federal credit that the
resident individual would have been allowed under section 32 (n)(2) of the
internal revenue code, notwithstanding the date limitation set forth in section
32(n) of the internal revenue code as specified in section 9621 (a) of the
"American Rescue Plan Act of 2021", Pub.L. 117-2.
(II)
Except as otherwise provided in subsection (3.5) of this section, the
percentage used to calculate the amount of credit that can be claimed pursuant
to subsection (2.7)(d)(I) of this section is twenty-five percent.
(2.8)
(a) For income tax years commencing on or after January 1, 2023, but before
January 1, 2024, only, the rate of credit allowed for the resident individuals
described in subsections (2), (2.5), and (2.7) of this section, respectively,
is increased from twenty-five percent to fifty percent of the federal credit
described in the respective subsections (2), (2.5), and (2.7) of this section.
(b) The
general assembly finds and declares that increasing the rate of the credit as
specified in subsection (2.8)(a) of this section reduces the amount of state
revenues, as defined in section 24-77-103.6 (6)(c), for the 2023-24 state
fiscal year and is therefore, after excess state revenues for the 2022-23 state
fiscal year are refunded pursuant to sections 39-3-209, 39-3-210, and any other
refund mechanism provided for in law other than the refund mechanism provided
for in part 20 of this article 22, a reasonable method of refunding a portion
of any remaining excess state revenues for the 2022-23 state fiscal year that
are required to be refunded in the 2023-24 state fiscal year in accordance with
section 20 (7)(d) of the state constitution.
(c)
This subsection (2.8) is repealed, effective December 31, 2034.
(3)
Repealed.
(3.5)
(a) As used in this subsection (3.5), unless the context otherwise requires:
(I)
"Applicable forecast" means either the quarterly December revenue
forecast prepared by legislative council staff or the quarterly December
revenue forecast prepared by the office of state planning and budgeting in the
December immediately preceding the applicable state fiscal year as determined
by which immediately preceding March forecast the joint budget committee of the
general assembly used in the preparation of the state budget.
(II)
"Applicable state fiscal year" means the fiscal year that begins in
the income tax year for which the credit is allowed.
(III)
"BV" means the estimate of the state's nonexempt revenue for state
fiscal year 2024-25 included in the 2024 office of state planning and budgeting
March revenue forecast.
(IV)
"CAGR" means the estimated compound annual growth rate.
(V)
"Estimated adjustment factor" means, for a given income tax year, the
CAGR for nonexempt revenue that is calculated by the executive director
according to the following formula:
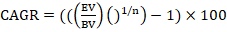 CAGR=((BVEV)1/n−1)×100
(VI)
"EV" means the estimate of the state's nonexempt revenue for the
applicable state fiscal year included in the applicable forecast excluding the
projected aggregate amount of the increased portion of the earned income tax
credit allowed pursuant to subsection (3.5)(b) or (3.5)(c) of this section and
the projected aggregate amount of the credit allowed pursuant to section
39-22-130, created in House Bill 24-1311, enacted in 2024, for the given income
tax year.
(VII)
"n" means, for the applicable state fiscal year, the number of state
fiscal years that have passed since the 2024-25 state fiscal year.
(VIII) [Editor's
note: This version of subsection (3.5)(a)(VIII) is effective unless Senate Bill
26-135 is approved by the voters at the 2026 statewide election and becomes
law.] "Nonexempt revenue" means, for the applicable state
fiscal year, the revenues that are identified as nonexempt revenues in the
annual comprehensive financial report published by the office of the state
controller.
(VIII) [Editor's
note: This version of subsection (3.5)(a)(VIII) takes effect only if Senate
Bill 26-135 is approved by the voters at the 2026 statewide election and
becomes law.] "Nonexempt revenue" means, for the applicable
state fiscal year, the revenues that are identified as nonexempt revenues in
the annual comprehensive financial report published by the office of the state
controller; except that, for state fiscal years commencing on or after July 1,
2026, nonexempt revenue includes state public education funding as defined in
section 24-77-301 (2).
(b) (I)
For the income tax year commencing on January 1, 2025, the percentage of the
federal earned income tax credit that the resident individual claimed or could
have claimed that is used to calculate the amount of earned income tax credit
allowed pursuant to subsections (2)(d), (2.5)(e), (2.7)(c), and (2.7)(d) of
this section is increased by fifteen percentage points if the estimated
adjustment factor is equal to or greater than two percent.
(II)
This subsection (3.5)(b) is repealed, effective December 31, 2035.
(c) For
income tax years commencing on or after January 1, 2026, the percentage of the
federal earned income tax credit that the resident individual claimed or could
have claimed that is used to calculate the amount of earned income tax credit
allowed pursuant to subsections (2)(d), (2.5)(e), (2.7)(c), and (2.7)(d) of
this section is increased as follows if the estimated adjustment factor is as
follows:
(I)
Equal to or greater than three percent but less than three and eighteen
one-hundredths percent, by five percentage points;
(II)
Equal to or greater than three and eighteen one-hundredths percent but less
than three and thirty-seven one-hundredths percent, by ten percentage points;
(III)
Equal to or greater than three and thirty-seven one-hundredths percent but less
than three and fifty-six one-hundredths percent, by fifteen percentage points;
(IV)
Equal to or greater than three and fifty-six one-hundredths percent but less
than three and seventy-five one-hundredths percent, by twenty percentage
points; and
(V)
Equal to or greater than three and seventy-five one-hundredths percent, by
twenty-five percentage points.
(4) The
amount of the credit allowed under this section that exceeds the resident
individual's income taxes due is refunded to the individual.
(5) In
the case of a part-year resident, the credit allowed under this section is
apportioned in the ratio determined under section 39-22-110 (1).
(6) The
credit allowed under this section is not considered to be income or resources
for the purpose of determining eligibility for the payment of public assistance
benefits and medical assistance benefits authorized under state law or for a
payment made under any other publicly funded programs.
Source:
L. 2013: Entire
section added, (SB 13-001), ch. 381, p. 2227, § 3, effective August 7. L.
2020: (1)(h) and (2) amended, (2.5) added, and (3) repealed, (HB 20-1420),
ch. 277, p. 1360, § 5, effective July 11. L. 2021: (2.5)(a) amended and
(2.5)(c) repealed, (HB 21-1002), ch. 5, p. 31, § 2, effective January 21;
(2)(b) and (2.5)(b) amended and (2)(c), (2.5)(d), and (2.7) added, (HB
21-1311), ch. 298, p. 1772, § 4, effective June 23. L. 2023: (2)(a),
(2)(c)(I), (2.5)(a), (2.5)(d)(I), and (2.7)(b)(I) amended and (2)(d), (2.5)(e),
and (2.7)(c) added, (HB 23-1112), ch. 445, p. 2621, § 1, effective August 7. L.
2023, 1st Ex. Sess.: (2.8) added, (HB 23B-1002), ch. 3, p. 16, § 1,
effective November 20. L. 2024: (2.8) R&RE, (HB 24-1084), ch. 1, p.
2, § 2, effective January 31; (2)(b), (2)(c)(I), (2)(d), (2.5)(b), (2.5)(d)(I),
(2.5)(e), (2.7)(a), (2.7)(b)(I), and (2.7)(c) amended and (2.8)(c) and (3.5)
added, (HB 24-1134), ch. 172, p. 928, § 3, effective August 7. L. 2025:
(3.5)(a)(III) amended, (HB 25-1335), ch. 410, p. 2331, § 3, effective June 3. L.
2026: (2.7)(d) added and (3.5)(b)(I) and IP(3.5)(c) amended, (HB 26-1289),
ch. 364, p. 2217, § 34, effective June 3; (3.5)(a)(VIII) amended, (SB 26-135),
ch. 437, p. 3474, § 7, effective (see editor's note).
Editor's
note: (1)
Amendments to subsection (2.8) by HB 24-1084 and HB 24-1134 were harmonized.
(2) This section was amended by
SB 26-135. That bill contains a referendum clause and will be submitted to a
vote of the registered electors of the state of Colorado at the next biennial
regular general election in 2026 for its approval or rejection. The amended
version of this section takes effect upon the proclamation of the Governor if
SB 26-135 is approved by the registered electors.
Cross
references: (1) In
2013, this section was added by the "Colorado Working Families Economic
Opportunity Act of 2013". For the short title, see section 1 of chapter
381, Session Laws of Colorado 2013.
(2) For the short title
("Tax Fairness Act") in HB 20-1420, see section 1 of chapter 277,
Session Laws of Colorado 2020.
(3) For the legislative
declaration in HB 21-1311, see section 1 of chapter 298, Session Laws of
Colorado 2021. For the legislative declaration in HB 24-1084, see section 1 of
chapter 1, Session Laws of Colorado 2024. For the legislative declaration in HB
25-1335, see section 1 of chapter 410, Session Laws of Colorado 2025. For the
legislative declaration in SB 26-135, see section 1 of chapter 437, Session
Laws of Colorado 2026. For the legislative declaration in HB 26-1289, see
section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-123.7. Earned income tax credit -
pilot program - pre-populated tax return - rules - report - repeal.
(1)
There is created in the department of revenue a pilot program to assist up to
one hundred thousand households in filing or amending a federal income tax
return, a state income tax return, or both, and claiming the federal and state
earned income tax or child tax credits for up to two prior tax years. Depending
upon the available resources of the third-party entity described in subsection
(2) of this section, the pilot program shall:
(a)
Assist resident individuals in filing a federal or state income tax return and
claiming the federal or state earned income tax credit, the federal or state
child tax credit, or both, for up to two prior tax years; or
(b)
Assist resident individuals in amending their federal income tax returns, their
state income tax returns, or both, for up to two prior tax years in order to
claim the federal and state earned income tax and child tax credits.
(2) As
third-party resources allow, a third-party entity shall create a pre-populated
federal or state income tax return, or both, for one of the two options
described in subsection (1) of this section for up to one hundred thousand
resident households that appear to qualify for the earned income tax credit or
child tax credit in up to two prior tax years. For participating residents, the
third-party entity may also pre-populate other parts of the tax returns using
information provided by the resident for completing necessary tax credit
applications, and, where possible, submit the pre-populated forms to the
department of revenue or internal revenue service, as applicable.
(3) (a)
To develop, implement, and administer the pilot program described in this
section, the department of revenue shall:
(I)
Collaborate with a third-party entity to identify the population of up to one
hundred thousand resident households who may be eligible to claim the prior
year tax credits identified in subsection (1) of this section;
(II)
Notify the households identified pursuant to subsection (3)(a)(I) of this
section about the availability of the pilot program and instruct them on how to
access the program and provide the consent required by subsection (3)(a)(III)
of this section;
(III)
Develop a mechanism to share wage data with the third-party entity; and
(IV)
Develop a system for resident individuals to digitally consent to having wage
data shared with the third-party entity.
(b) The
department of revenue may seek, accept, and expend gifts, grants, or donations
from private or public sources for the purposes of this section.
(c) As
resources permit, the department of revenue may collaborate with the internal
revenue service.
(d) The
department of revenue shall develop, implement, and begin to administer the
pilot program no later than August 15, 2025.
(4) (a)
Information that the department of revenue may provide pursuant to this section
is subject to any limitations imposed pursuant to section 6103 of the internal
revenue code. The third-party entity shall secure the information shared
pursuant to this section.
(b)
Information provided to the third-party entity pursuant to this section remains
confidential, and all agents, clerks, and employees of the third-party entity
are subject to the limitations set forth in section 39-21-113 (4) and the
penalties contained in section 39-21-113 (6) to the same extent as agents,
clerks, and employees of the department of revenue.
(5) The
third-party entity selected pursuant to subsection (3)(a)(I) of this section
shall provide a written report to members of the senate and house finance
committees no later than December 15, 2025. The report shall provide
information that includes:
(a) The
number of pre-populated federal income tax returns completed;
(b) The
total number of each tax credit claimed as a result of the pilot program set
forth in this section;
(c) An
estimate of the amount of money claimed through the pilot program set forth in
this section;
(d) The
number of returns that were supported through information shared pursuant to
this section; and
(e)
Recommendations for improving and continuing the pilot program.
(6)
This section is repealed, effective January 1, 2027.
Source:
L. 2024: Entire
section added, (HB 24-1288), ch. 173, p. 942, § 2, effective August 7. L.
2025: IP(5) amended, (SB 25-300), ch. 428, p. 2456, § 56, effective August
6.
39-22-124. Tax credit against state
taxes - legislative declaration - hearings and appeals. (Repealed)
Source:
L. 99: Entire
section added, p. 1289, § 1, effective August 4. L. 2000: (2)(b), (3),
(4), (5), (8)(a), (8)(b), (8)(c)(I), and (8)(c)(II) amended and (5.5) and (6.5)
added, p. 744, § 1, effective May 23. L. 2001: (3), IP(4), (4)(b),
IP(5), IP(5)(a), (5)(b), and (8)(c)(I) amended and (4.5) and (10) added, p.
429, § 1, effective April 20. L. 2010: Entire section repealed, (SB
10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-125. Credit for health benefit
plans - definitions - mechanism to refund excess state revenues. (Repealed)
Source:
L. 2000: Entire
section added, p. 930, § 1, effective May 25. L. 2010: Entire section
repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-126. Credit for health care
professionals practicing in rural health care professional shortage areas -
legislative declaration - definitions. (Repealed)
Source:
L. 2000: Entire
section added, p. 738, § 1, effective August 2. L. 2001: (2)(a) amended,
p. 186, § 19, effective August 8; (2)(a), (2)(b)(I), (3), (4)(a), (4)(d), (6),
(7), (9), and (10)(a) amended, p. 649, § 1, effective August 8; (4)(a), (4)(d),
(6), (7), and (10)(a) amended, p. 393, § 4, effective August 8. L. 2010:
Entire section repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-127. Credit for providing foster
care - refund of excess state revenues for fiscal years commencing on or after
January 1, 2000 - legislative declaration. (Repealed)
Source:
L. 2001: Entire
section added, p. 608, § 1, effective May 30. L. 2010: Entire section
repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-128. Credit for income eligible
to be deferred on sale of livestock due to weather-related conditions - repeal.
(Repealed)
Source:
L. 2002, 3rd Ex. Sess.:
Entire section added, p. 56, § 1, effective August 12.
Editor's
note: Subsection
(4) provided for the repeal of this section, effective January 1, 2009. (See L.
2002, 3rd Ex. Sess., p. 56.)
39-22-129. Child tax credit -
legislative declaration - definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I) The
federal child tax credit, which includes the refundable portion of the credit
commonly known as the additional child tax credit, supports low- and
middle-income working families whose earnings are below an income threshold and
who have children under seventeen years of age;
(II)
Since its establishment at the federal level in 1997, the credit has increased
family income, reduced child poverty among families with children, and
supported local economies; and
(III)
The credit has a positive impact on the early childhood development and health
of children whose families gain income from the credit.
(b)
Now, therefore, it is the intent of the general assembly to establish a
permanent and refundable state child tax credit for eligible Colorado
taxpayers. The intended purpose of this credit is to support Colorado working
families with young children, reduce child poverty, and to help Colorado's
economy.
(2) As
used in this section:
(a) (I)
"Eligible child" means, for income tax years commencing before
January 1, 2024, a qualifying child for purposes of the federal child tax
credit who is under six years of age at the end of the taxable year for which
the credit is claimed.
(II)
"Eligible child" means, for income tax years commencing on or after
January 1, 2024, a qualifying child, as defined in section 152 (c) of the
internal revenue code, who is under six years of age at the end of the taxable
year for which the credit is claimed.
(b)
"Federal child tax credit" means the child tax credit allowed under
section 24 of the internal revenue code, or any successor section, and includes
the refundable portion of the tax credit, which portion is referred to as the
additional child credit.
(3) (a)
Except as provided in subsection (4) of this section, for income tax years
commencing on or after January 1, 2022, but before January 1, 2024, a resident
individual who claims a federal child tax credit for an eligible child on the
individual's federal tax return is allowed a child tax credit in the amount set
forth in subsection (3)(b) or (3)(c) of this section against the income taxes
due under this article 22 for the same tax year.
(b) (I)
For a resident individual who files a single return, the amount of the credit
is equal to:
(A)
Thirty percent of the federal child tax credit that the resident individual
claimed on his or her federal tax return for each eligible child, if the
individual's federal adjusted gross income is twenty-five thousand dollars or
less;
(B)
Fifteen percent of the federal child tax credit that the resident individual
claimed on his or her federal tax return for each eligible child, if the
individual's federal adjusted gross income is greater than twenty-five thousand
dollars but less than or equal to fifty thousand dollars; and
(C)
Five percent of the federal child tax credit that the resident individual
claimed on his or her federal tax return for each eligible child, if the
individual's federal adjusted gross income is greater than fifty thousand
dollars but less than or equal to seventy-five thousand dollars.
(II) A
resident individual who files a single return and whose federal adjusted gross
income is greater than seventy-five thousand dollars is not allowed a credit
under this section.
(c) (I)
For two resident individuals who file a joint return, the amount of the credit
is equal to:
(A)
Thirty percent of the federal child tax credit that the resident individuals
claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is thirty-five thousand dollars or
less;
(B)
Fifteen percent of the federal child tax credit that the resident individuals
claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is greater than thirty-five thousand
dollars but less than or equal to sixty thousand dollars; and
(C)
Five percent of the federal child tax credit that the resident individuals
claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is greater than sixty thousand
dollars but less than or equal to eighty-five thousand dollars.
(II)
Two resident individuals who file a joint return and whose federal adjusted
gross income is greater than eighty-five thousand dollars are not allowed a
credit under this section.
(3.5)
(a) Except as provided in subsection (4) of this section, for income tax
years commencing on or after January 1, 2022, but before January 1, 2024, a
resident individual who could have claimed a federal child tax credit for an
eligible child on the individual's federal tax return had section 24 (h)(7) of
the internal revenue code not applied to the definition of qualifying child, is
allowed a child tax credit in the amount set forth in subsection (3.5)(b) or
(3.5)(c) of this section against the income taxes due under this article 22 for
the same tax year.
(b) (I)
For a resident individual who files a single return, the amount of the credit
is equal to:
(A)
Thirty percent of the federal child tax credit that the resident individual
could have claimed on their federal tax return for each eligible child, if the
individual's federal adjusted gross income is twenty-five thousand dollars or
less;
(B)
Fifteen percent of the federal child tax credit that the resident individual
could have claimed on their federal tax return for each eligible child, if the
individual's federal adjusted gross income is greater than twenty-five thousand
dollars but less than or equal to fifty thousand dollars; and
(C)
Five percent of the federal child tax credit that the resident individual could
have claimed on their federal tax return for each eligible child, if the
individual's federal adjusted gross income is greater than fifty thousand
dollars but less than or equal to seventy-five thousand dollars.
(II) A
resident individual who files a single return and whose federal adjusted gross
income is greater than seventy-five thousand dollars is not allowed a credit
under this section.
(c) (I)
For two resident individuals who file a joint return, the amount of the credit
is equal to:
(A)
Thirty percent of the federal child tax credit that the resident individuals
could have claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is thirty-five thousand dollars or
less;
(B)
Fifteen percent of the federal child tax credit that the resident individuals
could have claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is greater than thirty-five thousand
dollars but less than or equal to sixty thousand dollars; and
(C)
Five percent of the federal child tax credit that the resident individuals
could have claimed on their federal tax return for each eligible child, if the
individuals' federal adjusted gross income is greater than sixty thousand
dollars but less than or equal to eighty-five thousand dollars.
(II)
Two resident individuals who file a joint return and whose federal adjusted
gross income is greater than eighty-five thousand dollars are not allowed a
credit under this section.
(4) In
any income tax year commencing on or after January 1, 2022, but before January
1, 2024, if the changes specified in section 9611 of the "American Rescue
Plan Act of 2021", Pub.L. 117-2, are no longer applicable to the federal
child tax credit allowed in section 24 of the internal revenue code, then the
amount of the child tax credit allowed in this section is as follows:
(a) (I)
For a resident individual who files a single return, the amount of the credit
is equal to:
(A)
Sixty percent of the federal child tax credit that the resident individual
claimed or could have claimed on their federal tax return for each eligible
child, if the individual's federal adjusted gross income is twenty-five
thousand dollars or less;
(B)
Thirty percent of the federal child tax credit that the resident individual
claimed or could have claimed on their federal tax return for each eligible
child, if the individual's federal adjusted gross income is greater than
twenty-five thousand dollars but less than or equal to fifty thousand dollars;
and
(C) Ten
percent of the federal child tax credit that the resident individual claimed or
could have claimed on their federal tax return for each eligible child, if the
individual's federal adjusted gross income is greater than fifty thousand
dollars but less than or equal to seventy-five thousand dollars.
(II) A
resident individual who files a single return and whose federal adjusted gross
income is greater than seventy-five thousand dollars is not allowed a credit
under this section.
(b) (I)
For two resident individuals who file a joint return, the amount of the credit
is equal to:
(A)
Sixty percent of the federal child tax credit that the resident individuals
claimed or could have claimed on their federal tax return for each eligible
child, if the individuals' federal adjusted gross income is thirty-five
thousand dollars or less;
(B)
Thirty percent of the federal child tax credit that the resident individuals
claimed or could have claimed on their federal tax return for each eligible
child, if the individuals' federal adjusted gross income is greater than
thirty-five thousand dollars but less than or equal to sixty thousand dollars;
and
(C) Ten
percent of the federal child tax credit that the resident individuals claimed
or could have claimed on their federal tax return for each eligible child, if
the individuals' federal adjusted gross income is greater than sixty thousand
dollars but less than or equal to eighty-five thousand dollars.
(II)
Two resident individuals who file a joint return and whose federal adjusted
gross income is greater than eighty-five thousand dollars are not allowed a
credit under this section.
(4.5) (a)
(I) For income tax years commencing on or after January 1, 2024, a resident
individual who files a single return is allowed a child tax credit against the
income taxes due under this article 22 for each eligible child of the taxpayer
in the following amounts:
(A) One
thousand two hundred dollars if the individual's federal adjusted gross income
is twenty-five thousand dollars or less;
(B) Six
hundred dollars if the individual's federal adjusted gross income is greater
than twenty-five thousand dollars but less than or equal to fifty thousand
dollars; and
(C) Two
hundred dollars if the individual's federal adjusted gross income is greater
than fifty thousand dollars but less than or equal to seventy-five thousand
dollars.
(II)
For income tax years commencing on or after January 1, 2024, two resident
individuals who file a joint return are allowed a child tax credit against the
income taxes due under this article 22 for each eligible child of the taxpayer
in the following amounts:
(A) One
thousand two hundred dollars if the individuals' federal adjusted gross income
is thirty-five thousand dollars or less;
(B) Six
hundred dollars if the individuals' federal adjusted gross income is greater
than thirty-five thousand dollars but less than or equal to sixty thousand
dollars; and
(C) Two
hundred dollars if the individuals' federal adjusted gross income is greater
than sixty thousand dollars but less than or equal to eighty-five thousand dollars.
(b) (I)
A resident individual who files a single return and whose federal adjusted
gross income is greater than seventy-five thousand dollars is not allowed a
credit under this section.
(II)
Two resident individuals who file a joint return and whose federal adjusted
gross income is greater than eighty-five thousand dollars are not allowed a
credit under this section.
(5) The
amount of the credit allowed under this section that exceeds the resident
individual's income taxes due is refunded to the individual.
(6) In
the case of a part-year resident, the credit allowed under this section is
apportioned in the ratio determined under section 39-22-110 (1).
(7) The
credit allowed under this section is not considered to be income or resources
for the purpose of determining eligibility for the payment of public assistance
benefits and medical assistance benefits authorized under state law or for a
payment made under any other publicly funded programs.
(8) (a)
For income tax years commencing on or after January 1, 2025, the department of
revenue shall adjust the federal adjusted gross income amounts set forth in
this section to reflect inflation for each income tax year in which the credit
described in this section is allowed if cumulative inflation since the last
adjustment, when applied to the current limits, results in an increase of at
least one thousand dollars when the adjusted limits are rounded to the nearest
one thousand dollars.
(b) As
used in this subsection (8), "inflation" means the annual percentage
change in the United States department of labor bureau of labor statistics
consumer price index for Denver-Aurora-Lakewood for all items paid by all urban
consumers, or its applicable successor index.
(9)
Subsections (3), (3.5), and (4) of this section and this subsection (9) are
repealed, effective December 31, 2026.
Source:
L. 2013: Entire
section added, (SB 13-001), ch. 381, p. 2229, § 4, effective August 7. L.
2021: (3)(a) and (4) amended and (3.5) added, (HB 21-1311), ch. 298, p.
1773, § 5, effective June 23. L. 2023: (1)(b), (2)(a), (3)(a), (3.5)(a),
and IP(4) amended and (4.5), (8), and (9) added, (HB 23-1112), ch. 445, p.
2623, § 2, effective August 7.
Cross
references: (1) In
2013, this section was added by the "Colorado Working Families Economic
Opportunity Act of 2013". For the short title, see section 1 of chapter
381, Session Laws of Colorado 2013.
(2) For the legislative
declaration in HB 21-1311, see section 1 of chapter 298, Session Laws of
Colorado 2021.
39-22-130. Family affordability tax
credit - tax preference performance statement - legislative declaration -
definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I)
Colorado families struggle to afford many necessary goods and services, such as
child care, housing, and health care. Eighty-three percent of Colorado parents
worry that their children won't be able to afford to live in the state in the
future.
(II)
Targeted tax credits are a proven tool to lift families out of poverty.
Research has shown that families that claim these types of tax credits, such as
the state and federal child tax credit and the state and federal earned income
tax credit, have better health, improved schooling outcomes, and increased
adult earning potential. As the cost of raising children has increased, a
family affordability tax credit is critical for the well-being of many children
and families across Colorado.
(III)
According to the Institute on Taxation and Economic Policy, "[t]o cut
child poverty rates by half, the majority of states would require a base credit
value of between three thousand dollars and four thousand five hundred dollars
per child plus a twenty percent boost for young children." When coupled
with the state and federal earned income tax credit and the state and federal
child tax credit, the additional investment provided by the family
affordability tax credit would establish Colorado as a national leader in
equitable economic policy.
(IV)
Colorado is dealing with rising costs and funding shortfalls in many areas
across our state, and it is necessary to provide tax credits to the people who
need it most in a way that will do the most good. Establishing the family
affordability tax credit is a proven way to do that.
(V) By
prioritizing the state's lowest-income families, expanding the child age
eligibility, and including more families, the state can provide research-backed
investments for families. Through thoughtful and strategic investment, Colorado
can cut child poverty nearly in half.
(b) The
general assembly declares its intent to periodically review the tax credit
created in this section in an effort to prevent a significant increase or
decrease, adjusted for inflation, in the total amount of the credit claimed by
taxpayers year over year starting in income tax year 2025.
(c) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly hereby finds and
declares that the purposes of the tax expenditure created in subsection (3) of
this section are to substantially reduce child poverty, make Colorado more
affordable for families, and help families afford expenses associated with
having children by providing tax relief for certain individuals.
(d) The
general assembly and the state auditor, in consultation with the department of
revenue, shall measure the effectiveness of the exemption allowed by this
section by determining the number of Colorado families who, after claiming a
credit or credits in this section, no longer fall below the federal poverty
level in the tax year in which they claimed the credit or credits.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Eligible child" means a qualifying child, as defined in section 152
(c) of the "Internal Revenue Code of 1986"; except that the age
requirements are as set forth in subsections (3)(a)(I), (3)(a)(II), (3)(b)(I),
and (3)(b)(II) of this section.
(b) (I)
"Estimated adjustment factor" means, for a given income tax year, the
CAGR for nonexempt revenue that is calculated according to the following
formula, as adjusted pursuant to subsection (2)(b)(IV) of this section:
CAGR=((BVEV)1/n−1)×100
(II) As
used in this subsection (2)(b):
(A)
"Applicable forecast" means either the quarterly December revenue
forecast prepared by legislative council staff or the quarterly December
revenue forecast prepared by the office of state planning and budgeting in the
December immediately preceding the applicable state fiscal year, as determined
by which immediately preceding March forecast the joint budget committee of the
general assembly used in the preparation of the state budget.
(B)
"Applicable state fiscal year" means the fiscal year that begins in
the income tax year for which the credit is allowed.
(C)
"BV" means the estimate of the state's nonexempt revenue for state
fiscal year 2024-25 included in the 2024 office of state planning and budgeting
March revenue forecast.
(D)
"CAGR" means the estimated compound annual growth rate.
(E)
"EV" means the estimate of the state's nonexempt revenue for the
applicable state fiscal year included in the applicable forecast excluding the
projected aggregate amount of the tax credit allowed pursuant to this section
and the projected aggregate amount of the increased portion of the earned
income tax credit allowed pursuant to section 39-22-123.5 (3.5), created in
House Bill 24-1134, enacted in 2024, for the given income tax year.
(F)
"n" means, for the applicable state fiscal year, the number of state
fiscal years that have passed since the 2024-25 state fiscal year.
(G) [Editor's
note: This version of subsection (2)(b)(II)(G) is effective unless Senate Bill
26-135 is approved by the voters at the 2026 statewide election and becomes
law.] "Nonexempt revenue" means, for the applicable state
fiscal year, the revenue that is identified as nonexempt TABOR revenues in the
annual comprehensive financial report published by the office of the state
controller.
(G)
[Editor's note: This version of subsection (2)(b)(II)(G) takes
effect only if Senate Bill 26-135 is approved by the voters at the 2026
statewide election and becomes law.] "Nonexempt revenue"
means, for the applicable state fiscal year, the revenue that is identified as
nonexempt TABOR revenues in the annual comprehensive financial report published
by the office of the state controller; except that, for state fiscal years
commencing on or after July 1, 2026, nonexempt revenue includes state public education
funding as defined in section 24-77-301 (2).
(H)
"TABOR" means section 20 of article X of the state constitution.
(III)
The executive director shall calculate the estimated adjustment factor in
accordance with this section.
(IV)
The estimated adjustment factor must be increased by one-tenth of one
percentage point if the Colorado unemployment rate, as calculated by the United
States bureau of labor statistics, reaches five percent and must be increased
by an additional one-tenth of one percentage point for every one percentage
point increase in the Colorado unemployment rate above five percent.
(c)
"Federal poverty level" means the poverty line that is required to be
updated annually within the federal poverty guidelines adopted by the United
States department of health and human services pursuant to 42 U.S.C. sec. 9902
(2).
(d)
"Inflation" means the annual percentage change in the United States
department of labor bureau of labor statistics consumer price index for
Denver-Aurora-Lakewood for all items paid by all urban consumers, or its
applicable successor index.
(3) (a)
In addition to the child tax credit allowed by section 39-22-129, for income
tax years commencing on or after January 1, 2024, but before January 1, 2034, a
resident individual who files a single return is allowed a family affordability
tax credit against the income taxes due under this article 22 for:
(I)
Each eligible child of the resident individual who is five years of age or
younger at the close of the income tax year in the amount of three thousand two
hundred dollars, adjusted for inflation and as modified by subsections (4),
(5), and (6) of this section; and
(II)
Each eligible child of the resident individual who is six years of age or older
but less than seventeen years of age at the close of the income tax year in an
amount that is seventy-five percent of the amount allowed in subsection
(3)(a)(I) of this section, as modified by subsections (4), (5), and (6) of this
section.
(b) In
addition to the child tax credit allowed by section 39-22-129, for income tax
years commencing on or after January 1, 2024, but before January 1, 2034, two
resident individuals who file a joint return are allowed a family affordability
tax credit against the income taxes due under this article 22 for:
(I)
Each eligible child of the resident individuals who is five years of age or
younger at the close of the income tax year in the amount of three thousand two
hundred dollars, adjusted for inflation and as modified by subsections (4),
(5), and (6) of this section; and
(II)
Each eligible child of the resident individuals who is six years of age or
older but less than seventeen years of age at the close of the income tax year
in an amount that is seventy-five percent of the amount allowed in subsection
(3)(b)(I) of this section, as modified by subsections (4), (5), and (6) of this
section.
(4) For
income tax years commencing on or after January 1, 2024, but before January 1,
2025, the credit amounts in:
(a)
Subsection (3)(a)(I) of this section are reduced, but not below zero, by an
amount equal to six and eight hundred seventy-five one-thousandths percent for
each five thousand dollars by which a resident individual's adjusted gross
income exceeds fifteen thousand dollars; and
(b)
Subsection (3)(b)(I) of this section are reduced, but not below zero, by an
amount equal to six and eight hundred seventy-five one-thousandths percent for
each five thousand dollars by which two resident individuals' adjusted gross
income exceeds twenty-five thousand dollars.
(5) For
income tax years commencing on or after January 1, 2025, but before January 1,
2026, if the estimated adjustment factor is:
(a)
Greater than or equal to two percent:
(I) The
full credit amount set forth in subsection (3)(a)(I) of this section is allowed
for a resident individual who files a single return with an adjusted gross
income of fifteen thousand dollars or less, and the full credit amount set
forth in subsection (3)(b)(I) of this section is allowed for two resident
individuals who file a joint return with an adjusted gross income of
twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section is reduced, but not
below zero, by an amount equal to six and eight hundred seventy-five
one-thousandths percent for each five thousand dollars by which a resident
individual's adjusted gross income exceeds fifteen thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section is reduced, but not
below zero, by an amount equal to six and eight hundred seventy-five
one-thousandths percent for each five thousand dollars by which two resident
individuals' adjusted gross income exceeds twenty-five thousand dollars; or
(b)
Less than two percent, no credit is allowed pursuant to this section.
(6) For
income tax years commencing on or after January 1, 2026, but before January 1,
2034, if the estimated adjustment factor for the income tax year is:
(a)
Greater than or equal to three and seventy-five one-hundredths percent:
(I) The
full credit amount set forth in subsection (3)(a)(I) of this section is allowed
for a resident individual who files a single return with an adjusted gross
income of fifteen thousand dollars or less, and the full credit amount set
forth in subsection (3)(b)(I) of this section is allowed for two resident
individuals who file a joint return with an adjusted gross income of
twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section is reduced, but not
below zero, by an amount equal to six and eight hundred seventy-five
one-thousandths percent for each five thousand dollars by which a resident
individual's adjusted gross income exceeds fifteen thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section is reduced, but not
below zero, by an amount equal to six and eight hundred seventy-five
one-thousandths percent for each five thousand dollars by which two resident
individuals' adjusted gross income exceeds twenty-five thousand dollars;
(b)
Greater than or equal to three and fifty-six one-hundredths percent, but less
than three and seventy-five one-hundredths percent, then:
(I) The
full credit amount set forth in subsection (3)(a)(I) of this section is allowed
for a resident individual who files a single return with an adjusted gross
income of fifteen thousand dollars or less, and the full credit amount set
forth in subsection (3)(b)(I) of this section is allowed for two resident
individuals who file a joint return with an adjusted gross income of
twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section is reduced, but not
below zero, by an amount equal to nine and six one-hundredths percent for each
five thousand dollars by which a resident individual's adjusted gross income
exceeds fifteen thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section is reduced, but not
below zero, by an amount equal to nine and six one-hundredths percent for each
five thousand dollars by which two resident individuals' adjusted gross income
exceeds twenty-five thousand dollars;
(c)
Greater than or equal to three and thirty-seven one-hundredths percent, but
less than three and fifty-six one-hundredths percent, then:
(I) The
full credit amount set forth in subsection (3)(a)(I) of this section is allowed
for a resident individual who files a single return with an adjusted gross
income of fifteen thousand dollars or less, and the full credit amount set
forth in subsection (3)(b)(I) of this section is allowed for two resident
individuals who file a joint return with an adjusted gross income of
twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section is reduced, but not
below zero, by an amount equal to thirteen and fifty-nine one-hundredths
percent for each five thousand dollars by which a resident individual's
adjusted gross income exceeds fifteen thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section is reduced, but not
below zero, by an amount equal to thirteen and fifty-nine one-hundredths
percent for each five thousand dollars by which two resident individuals'
adjusted gross income exceeds twenty-five thousand dollars;
(d)
Greater than or equal to three and eighteen one-hundredths percent, but less
than three and thirty-seven one-hundredths percent, then:
(I) The
credit amount set forth in subsection (3)(a)(I) of this section is reduced to
two thousand six hundred dollars, adjusted for inflation, for a resident
individual who files a single return with an adjusted gross income of fifteen
thousand dollars or less, and the credit amount set forth in subsection
(3)(b)(I) of this section is reduced to two thousand six hundred dollars,
adjusted for inflation, for two resident individuals who file a joint return
with an adjusted gross income of twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section, as modified by
subsection (6)(d)(I) of this section, is reduced, but not below zero, by an
amount equal to nineteen and twenty-three one-hundredths percent for each five
thousand dollars by which a resident individual's adjusted gross income exceeds
fifteen thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section, as modified by
subsection (6)(d)(I) of this section, will be reduced, but not below zero, by
an amount equal to nineteen and twenty-three one-hundredths percent for each
five thousand dollars by which two resident individuals' adjusted gross income
exceeds twenty-five thousand dollars;
(e)
Greater than or equal to three percent, but less than three and eighteen
one-hundredths percent, then:
(I) The
credit amount set forth in subsection (3)(a)(I) of this section is reduced to
one thousand six hundred fifty dollars, adjusted for inflation, for a resident
individual who files a single return with an adjusted gross income of fifteen
thousand dollars or less, and the credit amount set forth in subsection
(3)(b)(I) of this section is reduced to one thousand six hundred fifty dollars,
adjusted for inflation, for two resident individuals who file a joint return
with an adjusted gross income of twenty-five thousand dollars or less;
(II)
The credit amount in subsection (3)(a)(I) of this section, as modified by
subsection (6)(e)(I) of this section, is reduced, but not below zero, by an
amount equal to thirty and thirty one-hundredths percent for each five thousand
dollars by which a resident individual's adjusted gross income exceeds fifteen
thousand dollars; and
(III)
The credit amount in subsection (3)(b)(I) of this section, as modified by
subsection (6)(e)(I) of this section, is reduced, but not below zero, by an
amount equal to thirty and thirty one-hundredths percent for each five thousand
dollars by which two resident individuals' adjusted gross income exceeds
twenty-five thousand dollars; or
(f)
Less than three percent, no credit is allowed pursuant to this section.
(7) For
income tax years commencing on or after January 1, 2025, the department of
revenue shall adjust the federal adjusted gross income amounts set forth in
this section to reflect inflation for each income tax year in which the credit
described in this section is allowed if cumulative inflation since the last
adjustment, when applied to the current limits, results in an increase of at
least one thousand dollars when the adjusted limits are rounded to the nearest
one thousand dollars.
(8) In
the case of a part-year resident, the credit allowed under this section is
apportioned in the ratio determined under section 39-22-110 (1).
(9) The
credit allowed under this section is not considered to be income or resources
for the purpose of determining eligibility for the payment of public assistance
benefits and medical assistance benefits authorized under state law or for a
payment made under any other publicly funded programs.
(10)
The amount of the credit allowed under this section that exceeds the resident
individual's income taxes due is refunded to the individual.
(11)
The department of revenue is authorized and encouraged to develop a means of
refunding the credits allowed by this section to resident individuals who
qualify for the credits in twelve equal monthly refunds rather than annually.
(12)
This section is repealed, effective December 31, 2037.
Source:
L. 2024: Entire
section added, (HB 24-1311), ch. 293, p. 1993, § 1, effective August 7. L.
2025: (2)(b)(II)(C) amended, (HB 25-1335), ch. 410, p. 2330, § 2, effective
June 3. L. 2026: (2)(b)(II)(G) amended, (SB 26-135), ch. 437, p. 3474, §
8, effective (see editor's note).
Editor's
note: This section
was amended by SB 26-135. That bill contains a referendum clause and will be
submitted to a vote of the registered electors of the state of Colorado at the
next biennial regular general election in 2026 for its approval or rejection.
The amended version of this section takes effect upon the proclamation of the
Governor if SB 26-135 is approved by the registered electors.
Cross
references: For
the legislative declaration in HB 25-1335, see section 1 of chapter 410,
Session Laws of Colorado 2025. For the legislative declaration in SB 26-135,
see section 1 of chapter 437, Session Laws of Colorado 2026.
39-22-131. Family affordability credit
- tax preference performance statement - legislative declaration - definitions.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly hereby finds and
declares that the purposes of the income tax credit created in this section are
the same as the family affordability tax credit: To substantially reduce child
poverty, make Colorado more affordable for families, and help families afford
expenses associated with having children by providing tax relief for certain
individuals.
(b) The
general assembly and the state auditor, in consultation with the department,
shall measure the effectiveness of the income tax credit created in this
section in combination with the family affordability tax credit and, in the
same manner as the general assembly and the state auditor measure the
effectiveness of the family affordability tax credit by determining the number
of Colorado families that, after claiming a credit pursuant to this section and
the family affordability tax credit, no longer fall below the federal poverty
level in the tax year in which they claimed the credits.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Credit" means the credit against income tax created in this section.
(b)
"Department" means the department of revenue.
(c)
"Eligible child" means a qualifying child, as defined in section 152
(c) of the "Internal Revenue Code of 1986"; except that the age
requirements are as set forth in subsections (3)(a)(I), (3)(a)(II), (3)(b)(I),
and (3)(b)(II) of this section.
(d)
"Federal poverty level" means the poverty line that is required to be
updated annually within the federal poverty guidelines adopted by the United
States department of health and human services pursuant to 42 U.S.C. sec. 9902
(2).
(e)
"Inflation" means the annual percentage change in the United States
department of labor bureau of labor statistics consumer price index for
Denver-Aurora-Lakewood for all items paid by all urban consumers, or its
applicable successor index.
(f)
"Joint filer adjusted base income" means, for income tax years
commencing before January 1, 2034, an amount of adjusted gross income equal to
the amount of adjusted gross income determined by the department pursuant to
section 39-22-130 (7) to be necessary for two resident individuals who file a
joint return to qualify for the family affordability tax credit pursuant to
section 39-22-130 for the income tax year commencing on January 1, 2027.
(g)
"Single filer adjusted base income" means, for income tax years
commencing before January 1, 2034, an amount of adjusted gross income equal to
the amount of adjusted gross income determined by the department pursuant to
section 39-22-130 (7) to be necessary for a single resident individual who
files a single return to qualify for the family affordability tax credit
pursuant to section 39-22-130 for the income tax year commencing on January 1,
2027.
(3) (a)
In addition to the child tax credit allowed by section 39-22-129 and the family
affordability tax credit allowed by section 39-22-130, for income tax years
commencing on or after January 1, 2027, a resident individual who files a
single return is allowed a credit against the income taxes imposed pursuant to
this article 22 for:
(I)
Each eligible child of the resident individual who is five years old or younger
at the close of the income tax year in an amount determined by staff of the
legislative council pursuant to subsection (5)(b) of this section; and
(II)
Each eligible child of the resident individual who is six years old or older
but less than seventeen years old at the close of the income tax year in an
amount that is seventy-five percent of the amount allowed in subsection
(3)(a)(I) of this section.
(b) In
addition to the child tax credit allowed by section 39-22-129 and the family
affordability tax credit allowed by section 39-22-130, for income tax years
commencing on or after January 1, 2027, two resident individuals who file a
joint return are allowed a credit against the income taxes due imposed pursuant
to this article 22 for:
(I)
Each eligible child of the resident individual who is five years old or younger
at the close of the income tax year in an amount determined by staff of the
legislative council pursuant to subsection (5)(b) of this section; and
(II)
Each eligible child of the resident individual who is six years old or older
but less than seventeen years old at the close of the income tax year in an
amount that is seventy-five percent of the amount allowed in subsection
(3)(b)(I) of this section.
(4) (a)
Notwithstanding subsection (3) of this section, for income tax years commencing
on or after January 1, 2027, the credit amounts in:
(I)
Subsection (3)(a)(I) of this section are reduced, but not below zero, by an
amount equal to six and eight hundred seventy-five one-thousandths percent for
each five thousand dollars by which a resident individual's adjusted gross
income exceeds the single filer adjusted base income; and
(II)
Subsection (3)(b)(I) of this section are reduced, but not below zero, by an
amount equal to six and eight hundred seventy-five one-thousandths percent for
each five thousand dollars by which two resident individuals' adjusted gross
income exceeds the joint filer adjusted base income.
(b) For
income tax years commencing on or after January 1, 2028, the department shall
adjust the joint filer adjusted based income and single filer adjusted base
income to reflect inflation for each income tax year in which the credit
described in this section is allowed if cumulative inflation since the last
adjustment, when applied to the current limits, results in an increase of at
least one thousand dollars when the adjusted limits are rounded to the nearest
one thousand dollars.
(5)
Beginning with the quarterly June revenue forecast that legislative council
staff presents in June of 2027, and for each June revenue forecast thereafter,
as part of the quarterly June revenue forecast, legislative council staff shall
determine:
(a) For
the current calendar year, a projection of the change in state revenue directly
attributable to the changes made in this House Bill 26-1223, notwithstanding
the credit created in this section;
(b) A
dollar amount of the credit available pursuant to subsections (3)(a)(I) and
(3)(b)(I) of this section, which dollar amount must be the same for both
subsections (3)(a)(I) and (3)(b)(I) of this section, such that the staff of the
legislative council projects, for the current calendar year, that the total
dollar amount of credits claimed pursuant to subsection (3) of this section
will equal the dollar amount that staff of the legislative council determines
pursuant to subsection (5)(a) of this section.
(6) In
the case of a part-year resident, the credit is apportioned in the ratio
determined under section 39-22-110 (1).
(7) The
credit is not considered to be income or resources for the purpose of
determining eligibility for the payment of public assistance benefits and
medical assistance benefits authorized under state law or for a payment made
under any other publicly funded program.
(8) The
amount of the credit that exceeds the resident individual's income taxes due is
refunded to the individual.
(9) The
department is authorized and encouraged to develop a means of refunding the
credits to resident individuals who qualify for the credits in twelve equal
monthly refunds rather than annually.
(10)
Notwithstanding section 39-21-304 (4), the credit does not repeal after a
specified period of tax years.
Source:
L. 2026: Entire
section added, (HB 26-1223), ch. 379, p. 2348, § 1, effective June 4.
Editor's
note: Section 10
of chapter 379 (HB 26-1223), Session Laws of Colorado 2026, provides that the
act adding this section takes effect only if HB 26-1221 and HB 26-1222 do not
become law. HB 26-1221 and HB 26-1222 did not become law.
PART
2
PARTNERS
AND PARTNERSHIPS
39-22-201. Partners, not partnership,
subject to tax.
A
partnership as such shall not be subject to tax under this article. Persons
carrying on business as partners shall be liable for the tax and the
alternative minimum tax under this article only in their separate or individual
capacities.
Source:
L. 64: R&RE,
p. 766, § 1. C.R.S. 1963: § 138-1-25. L. 67: p. 849, § 1. L.
87: Entire section amended, p. 1437, § 3, effective June 22.
39-22-201.5. Limited liability company
members - subject to tax. (Repealed)
Source:
L. 90: Entire
section added, p. 453, § 34, effective April 18. L. 95: Entire section
repealed, p. 817, § 41, effective May 24.
39-22-202. Resident partners -
definition.
(1) In
determining the federal taxable income of a resident partner for Colorado
income tax purposes, any modification described in section 39-22-104 which
relates to an item of partnership income, gain, loss, or deduction shall be
made in accordance with the partner's distributive share, for federal income
tax purposes, of the item to which the modification relates. Where a partner's
distributive share of any such item is not required to be taken into account
separately for federal income tax purposes, the partner's distributive share of
such item shall be determined in accordance with his distributive share, for
federal income tax purposes, of partnership taxable income or loss generally.
(2)
Each item of partnership income, gain, loss, deduction, or credit shall have
the same character for a partner under this article as for federal income tax
purposes.
(3)
Where a partner's distributive share of an item of partnership income, gain,
loss, deduction, or credit is determined for federal income tax purposes by
special provision of the partnership agreement with respect to such item and
where the principal purpose of such provision is the avoidance or evasion of
tax under this article, the partner's distributive share of such item and any
modification required with respect thereto shall be determined as if the
partnership agreement made no special provision with respect to such item.
(4) For
purposes of section 39-22-108, each resident partner is considered to have paid
a tax on each resident partner in an amount equal to each resident partner's
pro rata share of any net income tax paid by the partnership to a state that
does not measure the income of partners of a partnership by reference to the
income of the partnership. As used in this subsection (4), "net income
tax" means any tax imposed on, or measured by, a partnership's net income.
Source:
L. 64: R&RE,
p. 766, § 1. C.R.S. 1963: § 138-1-26. L. 87: (1) amended, p.
1437, § 4, effective June 22. L. 2022: (4) added, (SB 22-124), ch. 164,
p. 1018, § 1, effective May 16.
39-22-202.5. Resident members. (Repealed)
Source:
L. 90: Entire
section added, p. 453, § 34, effective April 18. L. 95: Entire section
repealed, p. 817, § 42, effective May 24.
39-22-203. Nonresident partners.
(1) (a)
In determining Colorado nonresident federal taxable income of a nonresident
partner of any partnership, there shall be included only the portion of such
partner's distributive share of items of partnership income, gain, loss,
deduction, or credit derived from sources within Colorado determined in
accordance with the provisions of section 39-22-109 or, at the partnership's
election, apportioned or allocated to this state pursuant to section
39-22-303.5, 39-22-303.6, or 39-22-303.7.
(b)
Repealed.
(2) In
determining the sources of a nonresident partner's income for the purposes of
Colorado income tax, no effect shall be given to a provision in the partnership
agreement which:
(a)
Characterizes payments to the partner as being for services or for the use of
capital; or
(b)
Allocates to the partner, as income or gain from sources outside Colorado, a
greater portion of his distributive share of partnership income or gain than
the ratio of partnership income or gain from sources outside Colorado to
partnership income or gain from all sources, except as authorized in subsection
(4) of this section; or
(c)
Allocates to the partner a greater proportion of a partnership item of loss or
deduction connected with sources within Colorado than his proportionate share,
for federal income tax purposes, of partnership loss or deduction generally,
except as authorized in subsection (4) of this section.
(3)
Repealed.
(4) The
executive director may authorize the use of such other methods of determining a
nonresident partner's portion of partnership items derived from or connected
with sources within Colorado, and the modifications related thereto, as may be
appropriate and equitable, on such terms and conditions as he may require.
(5) (a)
A nonresident partner's distributive share of items shall be determined under
section 39-22-202 (1).
(b) The
character of partnership items for a nonresident partner shall be determined
under section 39-22-202 (2).
(c) The
effect of a special provision in a partnership agreement having the principal
purpose of avoidance or evasion of tax under this article shall be determined
under section 39-22-202 (3).
Source:
L. 64: R&RE,
p. 767, § 1. C.R.S. 1963: § 138-1-27. L. 83: (1)(b) amended, p.
1513, § 5, effective January 1, 1984. L. 87: (1)(a), IP(2), and (2)(c)
amended and (1)(b) and (3) repealed, pp. 1437, 1457, §§ 5, 31, effective June
22. L. 93: (1)(a) amended, p. 1319, § 1, effective June 6. L. 2008:
(1)(a) amended, p. 954, § 6, effective January 1, 2009. L. 2019: (1)(a)
amended, (SB 19-241), ch. 390, p. 3476, § 51, effective August 2.
ANNOTATION
Law reviews. For
article, "Tax and Estate Planning for Nonresident Real Estate
Owners", see 53 Colo. Law. 34 (Apr. 2024).
39-22-203.5. Nonresident members.
(Repealed)
Source:
L. 90: Entire
section added, p. 454, § 34, effective April 18. L. 93: (1) amended, p.
1319, § 2, effective June 6. L. 95: Entire section repealed, p. 818, §
46, effective May 24.
39-22-204. Accounting periods and
methods.
The
provisions of section 39-22-111 shall apply to partnerships to the extent not
inconsistent with sections 39-22-201 to 39-22-203.
Source:
L. 64: R&RE,
p. 768, § 1. C.R.S. 1963: § 138-1-28. L. 87: Entire section
amended, p. 1438, § 6, effective June 22.
39-22-204.5. Accounting periods and
methods - limited liability companies. (Repealed)
Source:
L. 90: Entire
section added, p. 454, § 34, effective April 18. L. 95: Entire section
repealed, p. 817, § 43, effective May 24.
39-22-205. Limited liability company
members. (Repealed)
Source:
L. 90: Entire
section added, p. 455, § 34, effective April 18. L. 95: Entire section
repealed, p. 817, § 44, effective May 24.
39-22-206. Foreign source income of
export taxpayers.
If a
partnership qualifies as an export taxpayer, its partners may exclude from
gross income for Colorado income tax purposes such partners' distributive share
of any such partnership income or gain which constitutes foreign source income
for federal income tax purposes. For the purposes of this section, an
"export taxpayer" means any partnership which is subject to the
provisions of this article and which sells fifty percent or more of its product
or products which are produced in Colorado in states other than Colorado or in
foreign countries or, if the gross receipts of such partnership are derived
from the performance of services, such services are performed in Colorado by a
partner or employee of the partnership and fifty percent or more of such
services provided by the partnership are sold or provided to persons outside of
Colorado.
Source:
L. 93: Entire
section added, p. 1320, § 3, effective June 6. L. 95: Entire section
amended, p. 818, § 45, effective May 24.
PART
3
CORPORATIONS
SUBPART
1
C
CORPORATIONS
39-22-300.1. Short title - citation.
This
subpart 1 shall be comprised of sections 39-22-300.1 to 39-22-310 and may be
cited as subpart 1. This subpart 1 shall be known and may be cited as the
"Colorado C Corporation Income Tax Act".
Source:
L. 92: Entire
section added, p. 2266, § 6, effective April 16.
ANNOTATION
Law reviews. For
article, "Choice of Entities in Colorado", see 23 Colo. Law. 293
(1994).
39-22-301. Corporate tax imposed -
repeal.
(1) (a) to
(c) Repealed.
(d) (I)
A tax is imposed upon each domestic C corporation, foreign C corporation, and
combined group, as defined in section 39-22-303 (12)(a.3), doing business in
Colorado annually in an amount of the net income of such C corporation during
the year derived from sources within Colorado as set forth in the following
schedule of rates:
(A) to
(I) Repealed.
(J)
Except as otherwise provided in section 39-22-627, for income tax years
commencing on or after January 1, 2020, but before January 1, 2022, four and
fifty-five one-hundredths percent of the Colorado net income. This subsection
(1)(d)(I)(J) is repealed, effective December 31, 2026.
(K)
Except as otherwise provided in section 39-22-627, for income tax years
commencing on or after January 1, 2022, four and forty one-hundredths percent
of the Colorado net income.
(II)
For purposes of this paragraph (d), income from sources within Colorado shall
be determined in accordance with the provisions of this part 3 and includes
income from tangible or intangible property located or having a situs in this
state and income from any activities carried on in this state, regardless of
whether carried on in intrastate, interstate, or foreign commerce. In the case
of a C corporation which is a component member of a controlled group of
corporations as defined in section 1563 (a) of the internal revenue code, the
sum of the Colorado net incomes of all the component members of the controlled
group, but not the losses of each component member thereof, shall be used in
computing the tax bracket for the controlled group. The tax bracket for the
controlled group may be allocated between or among the component members
thereof as agreed to by such members. If such an agreement is not reached, the
executive director shall allocate the tax bracket based on the ratio of the
Colorado net income of each component member to the total Colorado net incomes
of all component members.
(1.1) to
(2) Repealed.
(3) (a)
As used in this section:
(I)
"Charitable organization" means a charitable organization exempt from
federal income taxation under the provisions of the internal revenue code.
(II)
"Crop" means an agricultural crop, including but not limited to
grains, fruits, and vegetables, which is usable as food for human beings.
(III)
"Crop contribution" means a contribution of a crop or portion of a
crop to a charitable organization by a taxpayer engaged in the trade or
business of farming or processing of a crop.
(IV)
"Livestock" means cattle, swine, poultry, or other animals raised for
profit and usable as food for human beings.
(V)
"Livestock contribution" means a contribution of livestock to a
charitable organization by a taxpayer engaged in the trade or business of
raising or processing of livestock.
(VI)
"Most recent sale price" means an amount equal to the price which the
taxpayer would have received for the crop or livestock contributed, determined
as if the crop or livestock had been sold on the date of the most recent sale
of such a crop or livestock and at the same price per unit as the crop or
livestock which was sold on that date.
(VII)
"Wholesale market price" means the average wholesale market price for
the crop or livestock contributed in the nearest regional market during the
month in which the contribution is made, determined without consideration of
grade or quality of the crop or livestock and as if the quantity of the crop or
livestock contributed were marketable.
(b) For
income tax years commencing prior to January 1, 2023, there shall be allowed to
taxpayers, as a credit with respect to the income taxes imposed by this part 3,
an amount equal to twenty-five percent of the wholesale market price or
twenty-five percent of the most recent sale price of crop contributions or
livestock contributions, or both, made to a tax-exempt charitable organization.
Credit, as provided for in this subsection (3), may not exceed one thousand
dollars per tax year.
(c)
Unused portions of such credit may be carried forward to subsequent tax years
as credit against income taxes due for those years. However, such credit must
be used within five years of the end of the tax year in which the contribution
was made.
(d) The
credit under this section is available only if the following conditions are
met:
(I) The
crop is harvested or the livestock is slaughtered by or on behalf of the donee
charitable organization;
(II)
The use of the crop or livestock by the donee charitable organization is
related to the purpose or function constituting the basis for the
organization's tax-exempt status;
(III)
The crop or livestock is not transferred by the donee charitable organization
in exchange for money, other property, or services. This condition shall not
apply in those cases where the donee charitable organization functions as a
clearinghouse for distribution, without expectation of remuneration, of such
crops or livestock, or both, to other charitable organizations. These secondary
donees shall be subject to the provisions of this section in the same measure
as if the contribution were received by that tax-exempt charitable organization
directly from the original donor.
(IV)
The taxpayer and any subsequent donors shall receive from the donee charitable
organization a written statement declaring that its use and disposition of the
crop or livestock will be in accordance with this section;
(V) No
taxpayer who donates items of food to a tax-exempt charitable organization for
use or distribution in providing assistance shall be liable for damages in any
civil action or subject to prosecution in any criminal proceeding resulting
from the nature, age, condition, or packaging of such crop contributions or
livestock contributions, or both. However, the exemption shall not apply to the
willful, wanton, or reckless acts of donors which result in injury to the
recipients of such contributed foods.
(e)
This subsection (3) is repealed, effective July 1, 2029.
Source:
L. 64: R&RE,
p. 768, § 1. C.R.S. 1963: § 138-1-35. L. 69: p. 1129, § 2. L.
81: (1) amended, (1.1), (1.2), (1.3), (1.4), and (1.5) added, p. 1872, § 9,
effective June 29. L. 82: (3) added, p. 564, § 2, effective April 22. L.
83: (1) and (1.1) to (1.5) amended, p. 1516, § 2, effective March 22; (1)
and (1.3) to (1.5) amended, p. 2096, § 3, effective October 13. L. 85:
(1) and (1.3) to (1.5) amended, p. 1265, § 3, effective May 30. L. 86:
(1) amended, (1.3) and (1.4) R&RE, and (1.5) repealed, pp. 1117, 1118,
1120, §§ 14, 15, 22, effective July 1. L. 86, 2nd Ex. Sess.: (1.3) and
(1.4) amended, p. 73, § 1, effective August 15. L. 87: (1)(b) and (1)(c)
amended, (1)(d) and (3) R&RE, and (1.4) repealed, pp. 1438, 1439, 1457, §§
7, 8, 31, effective June 22; (1)(d)(I)(A) amended, p. 1590, § 70, effective
July 10. L. 89: (1)(d)(II) amended, p. 1499, § 1, effective July 1,
1990. L. 92: (1)(a) to (1)(c), IP(1)(d)(I), and (1)(d)(II) amended, p.
2266, § 7, effective April 16. L. 99: (1)(d)(I)(G) amended and (1)(d)(I)(H)
added, p. 1376, § 2, effective August 4. L. 2000: (1)(d)(I)(H) amended
and (1)(d)(I)(I) added, p. 1414, § 3, effective August 2. L. 2005:
(1)(d)(I)(I) amended, p. 1361, § 2, effective June 6. Initiated 2020:
(1)(d)(I)(I) amended and (1)(d)(I)(J) added, Proposition 116, effective upon
proclamation of the Governor, effective December 31, 2020. L. 2022: (2)
and (3)(b) amended and (3)(e) added, (HB 22-1025), ch. 145, p. 945, § 4,
effective August 10. Initiated 2022: (1)(d)(I)(J) amended and
(1)(d)(I)(K) added, Proposition 121, effective upon proclamation of the
Governor, December 27, 2022. L. 2024: (1)(a), (1)(b), (1)(c),
(1)(d)(I)(A) to (1)(d)(I)(I), (1.1), (1.2), and (1.3) repealed and IP(1)(d)(I)
and (1)(d)(I)(J) amended, (HB 24-1134), ch. 172, p. 933, § 4, effective August
7.
Editor's
note: (1)
Subsection (2) of this section implements the requirements of Article III,
Section 2, of the Multistate Tax Compact, § 24-60-1301.
(2) Subsections (1)(d)(I)(I)
and (1)(d)(I)(J) were amended by initiative in 2020. The vote count on
Proposition 116 at the general election held November 3, 2020, was as follows:
FOR: 1,821,702
AGAINST: 1,327,025
(3) Subsection (1)(d)(I)(J) was
amended and (1)(d)(I)(K) was added by initiative in 2022. The vote count on
Proposition 121 at the general election held November 8, 2022, was as follows:
FOR: 1,581,163
AGAINST: 842,506
(4) Subsection (2)(b) provided
for the repeal of subsection (2), effective July 1, 2025. (See L. 2022, p.
945.)
ANNOTATION
Law reviews. For comment
on Arvey Corp. v. Fugate appearing below, see 31 Dicta 400 (1954). For note,
"Colorado Taxation of Foreign Corporate Income", see 35 U. Colo. L.
Rev. 354 (1963). For note, "Doing Business in Colorado for Foreign
Corporations: Service of Process, Qualification, Taxation", see 49 Den.
L.J. 529 (1973). For article, "Colorado's Income Tax as Applied to Foreign
Holding Companies", see 23 Colo. Law. 1107 (1994).
Annotator's note. The
following annotations include cases decided under former provisions similar to
this section.
Corporate income tax
constitutional. A state which provides an orderly market in which to
transact business confers benefits which constitutionally justify the levy of a
corporate income tax. GMC v. State, 181 Colo. 360, 509 P.2d 1260 (1973).
General assembly has sought
to tax all income that Colorado can constitutionally tax. Coors Porcelain
Co. v. State, 183 Colo. 325, 517 P.2d 838 (1973).
The expression "income
from sources within [Colorado]" is broad and all-inclusive. Arvey
Corp. v. Fugate, 129 Colo. 595, 272 P.2d 652 (1954).
Compensation for damages or
injuries cannot be classified as "income" for the purposes of
taxation. Arvey Corp. v. Fugate, 129 Colo. 595, 272 P.2d 652 (1954).
Business situs of
intangibles separate and distinct from domicile. In the matter of
assessment as applied in income taxation, there appears to be a business situs
of intangibles which may be separate and distinct from the domicile of the
owner. Arvey Corp. v. Fugate, 129 Colo. 595, 272 P.2d 652 (1954).
Both manufacture of product
and its ultimate sale contribute to a corporation's income for state income
tax purposes. GMC v. State, 181 Colo. 360, 509 P.2d 1260 (1973).
Gross income from sales of
goods shipped into state not taxable. Gross income derived from sales of
goods made from factories or branches outside of the state and shipped on
orders solicited in the state to customers here by common carrier f.o.b. the
point of delivery is not taxable. State ex rel. Cruse v. Am. Can Co., 117 Colo.
312, 186 P.2d 779 (1947) (decided under former law).
Sales made by out-of-state
corporate representatives soliciting orders. A state can tax the income of
a domestic corporation derived from sales made in other states by corporate
representatives soliciting orders in the other states. Coors Porcelain Co. v.
State, 183 Colo. 325, 517 P.2d 838 (1973).
Net income from foreign
corporation's interstate operations taxable. The net income from the
exclusively interstate operations of a foreign corporation may be subjected to
state taxation, provided the levy is not discriminatory and is properly
apportioned to local activities. GMC v. State, 181 Colo. 360, 509 P.2d 1260 (1973).
Presumption that percentage
allocation for foreign corporation fair. Where a statutory formula for the
taxation of a foreign corporation is not intrinsically invalid, there is a
strong presumption that the percentage allocation is fair. GMC v. State, 181
Colo. 360, 509 P.2d 1260 (1973).
Fairness is not equated with
absolute precision. GMC v. State, 181 Colo. 360, 509 P.2d 1260 (1973).
Difference of nine-tenths
percent too small to be unconstitutional. A difference of nine-tenths
percent between the computation of a railroad and that of the director of
revenue concerning the allocation of apportionable income to Colorado is too
small to constitute an unlawful burden upon interstate commerce, a violation of
due process, or a violation of equal protection. Union P.R.R. v. Heckers, 181
Colo. 374, 509 P.2d 1255 (1973).
Direct deduction of ad
valorem taxes from net income is not required. Union P.R.R. v. Heckers, 181
Colo. 374, 509 P.2d 1255 (1973).
Applied in In re Golden
State Bank v. Dolan, 37 Colo. App. 29, 543 P.2d 1307 (1975); Miller Int'l, Inc.
v. State Dept. of Rev., 646 P.2d 341 (Colo. 1982); Hewlett-Packard Co. v. State
Dept. of Rev., 749 P.2d 400 (Colo. 1988).
39-22-302. S corporations.
An S
corporation shall not be subject to taxation under this article.
Source:
L. 64: R&RE,
p. 768, § 1. C.R.S. 1963: § 138-1-36. L. 92: Entire section
amended, p. 2265, § 3, effective April 16.
ANNOTATION
Law reviews. For
article, "S Corporations in Colorado: Recent Cases and Legislation",
see 14 Colo. Law. 1412 (1985).
Subchapter S shareholders'
income not taxable. Income which is attributed to the shareholders of a
subchapter S corporation is not "dividends" subject to the surtax
under section 39-22-106 (1). Cohen v. Dept. of Rev., 197 Colo. 385, 593 P.2d
957 (1979) (decided under former 39-22-106 prior to its deletion).
39-22-303. Dividends in a combined
report - foreign source income - affiliated groups - definitions - rules -
repeal.
(1) to
(5) (Deleted by amendment, L. 2008, p. 955, § 7, effective January 1, 2009.)
(6) In
the case of two or more C corporations, whether domestic or foreign, owned or
controlled directly or indirectly by the same interests, the executive director
may, to avoid abuse, on a fair and impartial basis, distribute or allocate the
gross income and deductions between or among such C corporations in order to
clearly reflect income.
(7)
(Deleted by amendment, L. 2008, p. 955, § 7, effective January 1, 2009.)
(8) (a)
Except as provided in subsection (8)(b) of this section, for tax years
beginning before January 1, 2027, neither the taxpayer nor the executive
director shall include in a combined report any C corporation that conducts
business outside the United States if eighty percent or more of the C
corporation's property and payroll, as determined by factoring pursuant to
section 24-60-1301, is assigned to locations outside the United States. For the
purpose of this subsection (8), "United States" is restricted to the
fifty states and the District of Columbia.
(b) (I)
For tax years beginning on or after January 1, 2022, but before January 1,
2027, a taxpayer shall include in the combined group any member of an
affiliated group of C corporations that is incorporated in a foreign
jurisdiction for the purpose of tax avoidance.
(II) A
C corporation is presumptively incorporated in a foreign jurisdiction for the
purpose of tax avoidance if it is incorporated in a listed jurisdiction. A C
corporation is not incorporated in a foreign jurisdiction for the purpose of
tax avoidance if the taxpayer proves to the satisfaction of the executive
director, or if the executive director determines, that such corporation is
incorporated in a listed jurisdiction for reasons that meet the economic
substance doctrine described in section 7701 (o) of the internal revenue code.
(III)
For purposes of this subsection (8)(b), the term "C corporation"
includes any business entity defined as a "corporation" under the
internal revenue code and the rules and regulations promulgated pursuant
thereto, regardless of whether such entity is subject to federal income tax.
Any business entity included in a combined group under subsection (8)(b)(I) of
this section is deemed to be a "C corporation" for purposes of this
article 22, notwithstanding section 39-22-103 (2.5).
(c)
This subsection (8) is repealed, effective December 31, 2031.
(8.5)
(a) For income tax years beginning on or after January 1, 2027, the members
of an affiliated group of C corporations required to file a combined report
pursuant to subsection (11.5)(b)(I) of this section may make a water's-edge
election as set forth in subsection (8.5)(c) of this section. Pursuant to a
water's-edge election, the combined group shall take into account the net
income and apportionment factors of the members of the affiliated group
pursuant to subsection (11.5) of this section to the extent set forth in
subsection (8.5)(b) of this section.
(b) (I)
The combined group shall take into account the entire net income and
apportionment factors of:
(A)
Every member of the affiliated group that is incorporated in the United States
or formed under the laws of any state, the District of Columbia, or any
territory or possession of the United States;
(B)
Every member of the affiliated group, regardless of the place where the member
was incorporated or formed, if twenty percent or more of the member's property
and payroll, as determined by factoring pursuant to section 24-60-1301, is
assigned to locations within the United States. For the purpose of this
subsection (8.5)(b)(I)(B), "United States" is restricted to the fifty
states and the District of Columbia.
(C)
Every member of the affiliated group that is a domestic international sales
corporation as described in sections 991 to 994 of the internal revenue code or
an export trade corporation as described in sections 970 and 971 of the
internal revenue code; and
(D)
Every member of the affiliated group that is incorporated in a foreign
jurisdiction for the purpose of tax avoidance.
(II) To
the extent such amounts are not already taken into account pursuant to
subsection (8.5)(b)(I) of this section, the combined group shall also take into
account:
(A) The
apportionable income of a member of the affiliated group that is effectively
connected or treated as effectively connected pursuant to the internal revenue
code with the conduct of a trade or business within the United States and, for
that reason, subject to federal income tax and the related apportionment
factors; and
(B) In
the case of a member of the affiliated group that is a resident of a country
that does not have a comprehensive income tax treaty with the United States and
earns more than twenty percent of its net income, directly or indirectly, from
intangible property or service-related activities that are deductible from the
apportionable income of one or more members of the combined group, the related
net income and the apportionment factors.
(III)
For purposes of this subsection (8.5)(b), a member of the affiliated group is
presumptively incorporated in a foreign jurisdiction for the purpose of tax
avoidance if the member is incorporated in a listed jurisdiction. A member is
not incorporated in a foreign jurisdiction for the purpose of tax avoidance if
the combined group proves to the satisfaction of the executive director, or if
the executive director determines, that the member is incorporated in a listed
jurisdiction for reasons that meet the economic substance doctrine described in
section 7701 (o) of the internal revenue code.
(c) (I)
The combined group must make a water's-edge election on a timely filed,
original return for an income tax year.
(II)
(A) Except as provided in subsection (8.5)(c)(II)(C) of this section, a
combined group's water's-edge election is binding for and applicable to the
income tax year when the combined group makes the election and each of the nine
income tax years thereafter.
(B)
Upon the expiration of the period described in subsection (8.5)(c)(II)(A) of
this section, a combined group may withdraw the water's-edge election. The
combined group must withdraw the election on a timely filed, original tax
return for the first income tax year after the period described in subsection
(8.5)(c)(II)(A) of this section, or by other written withdrawal made in the
time and manner prescribed by rules promulgated by the executive director.
Except as provided in subsection (8.5)(c)(II)(C) of this section, a combined
group's withdrawal of an election is binding for and applicable to the income
tax year when the combined group withdraws the election and each of the nine
income tax years thereafter. If the combined group does not withdraw the
election as described in this subsection (8.5)(c)(II)(B), the election is
deemed renewed for an additional ten-year period, subject to the same
conditions as applied to the original election.
(C) A
combined group may petition the executive director to withdraw a water's-edge
election prior to the expiration of the period set forth in subsection
(8.5)(c)(II)(A) of this section, or to reinstate a withdrawn election, upon a
showing of reasonable cause based upon extraordinary hardship due to unforeseen
changes in state tax statutes, law, or policy. If the executive director grants
a withdrawal of an election, the executive director may impose reasonable
conditions as necessary to prevent the evasion of tax or to clearly reflect net
income for the election period prior to or after the withdrawal.
(III)
The executive director may promulgate rules governing the effect, if any, on
the scope or application of a water's-edge election, including the procedures
for election and termination or deemed election, resulting from a change in the
composition of the unitary group, the combined group, the members, and any
other similar change.
(d) The
executive director may disregard a water's-edge election in part or in whole,
and the net income and apportionment factors of any member of the unitary group
may be included in the combined report, without regard to subsections (8.5)(a)
to (8.5)(c) of this section, if:
(I) Any
member of the unitary group knowingly fails to comply with or recklessly
disregards any provision of this article 22 or any provision of article 21 of
this title 39; or
(II) A
person otherwise not included in the water's-edge combined group is used for a
substantial state income tax avoidance purpose.
(e) A
combined group's water's-edge election pursuant to this subsection (8.5) has no
effect on whether a person excluded from the water's-edge combined group may be
separately liable for the tax imposed by this article 22. A person excluded
from a water's-edge combined group and subject to the tax imposed by this
article 22 shall separately file and pay such tax as provided in this article
22.
(9)
Dividends which a C corporation includable in a combined report receives from
another C corporation also includable in the combined report shall be excluded
from taxable income.
(10) As
used in this subsection (10), "foreign source income" means taxable
income from sources without the United States, as used in section 862 of the
internal revenue code. In apportioning and allocating income pursuant to
section 39-22-303.5, 39-22-303.6, or 39-22-303.7, foreign source income shall
be considered only to the extent provided in this subsection (10):
(a) If,
for federal income tax purposes, the taxpayer has elected to claim foreign
taxes paid or accrued as a deduction, then all foreign source income minus such
deduction shall be considered;
(b) (I)
If, for federal income tax purposes, the taxpayer has elected to claim foreign
taxes paid or accrued as a credit, then foreign source income shall be
considered only to the extent that such income exceeds the exclusion provided
by this paragraph (b).
(II)
For income tax years commencing prior to January 1, 2000, the amount to be
excluded is determined by multiplying the foreign source income by a fraction,
the numerator of which is the total of taxes paid or accrued to foreign
countries and United States possessions by or on behalf of the C corporation
pursuant to section 901 of the internal revenue code, deemed paid pursuant to
section 960 of the internal revenue code for the tax year, or carried over or
carried back to such tax year pursuant to section 904 (c) of the internal
revenue code. The denominator of said fraction shall be forty-six percent of
the foreign source income.
(III)
For income tax years commencing on or after January 1, 2000, the amount to be
excluded is determined by multiplying the foreign source income by a fraction,
the numerator of which is the total of taxes paid or accrued to foreign
countries and United States possessions by or on behalf of the C corporation
pursuant to section 901 of the internal revenue code, deemed paid pursuant to
section 960 of the internal revenue code for the tax year, or carried over or
carried back to such tax year pursuant to section 904 (c) of the internal
revenue code. The denominator of said fraction shall be the same percentage as
the effective federal corporate income tax rate multiplied by the foreign
source income. As used in this subsection (10), "effective federal
corporate income tax rate" means the taxpayer's federal corporate income
tax calculated in accordance with section 11 (a) and (b) of the internal
revenue code for such tax year divided by the taxpayer's federal taxable
income.
(c)
Foreign source income from a foreign C corporation within an affiliated group
of C corporations shall be determined without regard to section 882 (a)(2) of
the internal revenue code.
(11)
For tax years beginning before January 1, 2026:
(a) In
the case of an affiliated group of C corporations, the executive director may
require, or the taxpayer may file, a combined report, but such report shall
only include those members of an affiliated group of C corporations as to which
any three of the following facts have been in existence in the tax year and the
two preceding tax years:
(I)
Sales or leases by one affiliated C corporation to another affiliated C
corporation constitute fifty percent or more of the gross operating receipts of
the C corporation making the sales or leases; or, purchases or leases from one
affiliated C corporation by another affiliated C corporation constitute fifty
percent or more of the cost of goods sold or leased by the C corporation making
the purchases or leases. This subparagraph (I) shall not apply to the following
transactions between affiliated C corporations: The issuance of commercial
paper or other debt obligations and the use of the proceeds therefrom to make
loans or to purchase receivables between affiliated C corporations.
(II)
Five or more of the following services are provided by one or more affiliated C
corporations for the benefit of another affiliated C corporation: Advertising
and public relations services; accounting and bookkeeping services; legal
services; personnel services; sales services; purchasing services; research and
development services; insurance procurement and servicing exclusive of employee
benefit programs; and employee benefit programs including pension,
profit-sharing, and stock purchase plans. A service shall be deemed provided if
fifty percent or more of the service is provided without provision for an
"arm's length charge" within the meaning of the United States
treasury regulation 1.482-2 (b)(3).
(III)
Twenty percent or more of the long-term debt of one affiliated C corporation is
owed to or guaranteed by another affiliated C corporation. For the purposes of
this subparagraph (III), "long-term debt" means debt which becomes
due more than one year after incurred.
(IV)
One affiliated C corporation substantially uses the patents, trademarks,
service marks, logo-types, trade secrets, copyrights, or other proprietary
materials owned by another affiliated C corporation.
(V)
Fifty percent or more of the members of the board of directors of one
affiliated C corporation are members of the board of directors or are corporate
officers of another affiliated C corporation.
(VI)
Twenty-five percent or more of the twenty highest-ranking officers of an
affiliated C corporation are members of the board of directors or are corporate
officers of another affiliated C corporation.
(b) The
net income of the affiliated C corporations which are to be included in a
combined report shall be determined pursuant to the rules and regulations
promulgated pursuant to section 1502 of the internal revenue code, as modified
by section 39-22-304.
(c) If
an affiliated C corporation is included in a combined report, section
39-22-303.5, 39-22-303.6, or 39-22-303.7 shall be applied with the following
modifications:
(I)
Intercompany transactions among the affiliated C corporations shall be excluded
from the numerator and denominator of the apportionment calculation set forth
in section 39-22-303.5, 39-22-303.6, or 39-22-303.7; and
(II)
(A) For income tax years commencing before January 1, 2022, the numerator of
the apportionment calculation set forth in section 39-22-303.5 or 39-22-303.6
shall be, to the extent applicable, the sum of the sales of those affiliated C
corporations doing business in Colorado.
(B) For
income tax years commencing on or after January 1, 2022, the combined group
apportionment factor is a fraction determined under section 39-22-303.6, as
modified, if applicable, by section 39-22-303.7, where the numerator of the
factor includes amounts sourced to the state, regardless of the separate entity
to which those factors may be attributed, and the denominator of the factor
includes amounts associated with the combined group's business wherever
located.
(d) The
executive director shall not require returns to be made on a consolidated
basis, but an affiliated group of C corporations may elect to file a
consolidated return as otherwise provided in this article.
(e)
(Deleted by amendment, L. 2008, p. 955, § 7, effective January 1, 2009.)
(f) For
purposes of this section, any C corporation formed under the laws of any state
or the United States with de minimis or no property and payroll, as determined
by factoring pursuant to section 24-60-1301, shall be deemed to satisfy the
requirements of subsection (11)(a) of this section. The department of revenue
shall adopt rules to determine the manner in which the de minimis standard will
be uniformly applied to taxpayers.
(g) For
the purpose of satisfying the requirements of subsections (11)(a)(I) to
(11)(a)(IV) of this section, the activities of any entity formed under the laws
of any state or the United States that is treated as a partnership pursuant to
part 2 of this article 22, shall be treated as activities performed by the
member of the affiliated group of C corporations that owns a portion of the
entity if more than fifty percent of the entity's ownership interest is held in
the aggregate by one or more members of the affiliated group. If the entity is
owned by more than one member of the affiliated group, the activities of the
entity shall be treated as activities performed by each member that owns a
portion of the entity.
(11.2)
Subsection (11) of this section and this subsection (11.2) are repealed,
effective December 31, 2031.
(11.5)
(a) The general assembly finds and declares that:
(I)
Subsection (11)(a) of this section was enacted in 1985 to implement unitary
combined reporting in Colorado. However, that subsection is unique among states
that employ unitary combined reporting, uses arbitrary tests that have been
difficult for taxpayers and the department of revenue to apply, and has created
unnecessary tax compliance challenges because Colorado's approach diverges from
other states.
(II)
Including all amounts sourced to Colorado for the combined group best
effectuates unitary combined reporting, regardless of the separate entity to
which those factors may be attributed. Doing so recognizes that the unitary
group is a single taxpayer and prevents corporate form from governing economic
substance.
(III)
Section 39-22-301 and this section, as amended by House Bill 24-1134, enacted
in 2024, allow Colorado to join other states with similar combined reporting
standards and implement unitary combined reporting in a manner that simplifies
the preparation of corporate income tax returns in Colorado without arbitrary
tests that are difficult to apply.
(b) For
tax years beginning on and after January 1, 2026:
(I)
Except as provided in subsection (8) or (8.5) of this section, all of the
members of an affiliated group of C corporations, wherever incorporated or
domiciled, that are members of a unitary business shall file a combined report
as a combined group.
(II)
(A) The net income of each member of the combined group, as determined under
section 39-22-304, is combined, eliminating items of income, expense, gain, and
loss from transactions between members of the combined group, applying the
consolidated filing rules under the internal revenue code, and the regulations
thereunder, as if the combined group was a consolidated filing group.
(B) A
combined group shall eliminate dividends from a combined report to the extent
permitted under subsection (9) of this section.
(C) For
income tax years beginning on or after January 1, 2027, to the extent the net
income of a member of a combined group includes subpart F income or net CFC
tested income with respect to another member of the combined group of which the
member is a United States shareholder, the combined group shall eliminate such
subpart F or net CFC tested income from a combined report.
(III)
(A) Except as otherwise provided in this section, section 39-22-303.6, as
modified, if applicable, by section 39-22-303.7, determines how income or loss,
or items making up income or loss, are allocated and apportioned to this state.
(B) The
combined group apportionment factor is a fraction determined under section
39-22-303.6, as modified, if applicable, by section 39-22-303.7, where the
numerator of the factor includes amounts sourced to the state for the combined
group's unitary business, regardless of the separate entity to which those
factors may be attributed, and the denominator of the factor includes amounts
associated with the combined group's unitary business wherever located.
(C)
Intercompany transactions among members of the combined group are excluded from
the numerator and denominator of the apportionment calculation set forth in
section 39-22-303.6, as modified, if applicable, by section 39-22-303.7.
(D) If
a member of the combined group holds a partnership interest from which it
derives apportionable income, the share of partnership's apportionment factor
to be included in the apportionment factor of the combined group is determined
by multiplying the partnership's factor by a ratio, the numerator of which is
the amount of the partnership's apportionable income properly included in the
member's income, whether received directly or indirectly, and including any
guaranteed payments, and the denominator of which is the amount of the
partnership's total apportionable income. In the case of a partnership that is
unitary with the partner, receipts from intercompany transactions between the
partnership and the partner, or any other member of the combined group, are
excluded from the numerator and denominator of the apportionment calculation as
follows: Receipts from sales by the partner, or any member of the partner's
combined group, to the partnership to the extent of the partner's interest in
the partnership; and receipts from sales by the partnership to the partner, or
any member of the partner's combined group, not to exceed the partner's
interest in all partnership sales. If a member of the combined group directly
or indirectly receives an allocation of a partnership tax item, such as an item
of loss or expense, so that it is not possible to determine the member's share
of apportionable income, the executive director may promulgate rules for
inclusion of particular partnership factors, or portions of factors, in the
combined group's factors.
(IV)
The combined report must be filed under the name and federal employer
identification number of the parent corporation if the parent is a member of
the combined group. If there is no parent corporation, or if the parent is not
a group member, the members of the combined group shall choose a member to file
the return. The filing member must remain the same in subsequent years unless
the filing member is no longer the parent corporation or is no longer a member
of the combined group. The return must be signed by a responsible officer of
the filing member on behalf of the combined group members as required by
section 39-22-601 (2).
(V)
Members of the combined group are jointly and severally liable for the tax
liability of the combined group included in the combined return.
(VI)
The executive director shall not require returns to be made on a consolidated
basis, but an affiliated group of C corporations may elect to file a
consolidated return as otherwise provided in this article 22.
(12) As
used in this section, unless the context otherwise requires:
(a)
"Affiliated group" means:
(I) One
or more includable C corporations connected directly or indirectly through
stock ownership with a common parent C corporation that is an includable C
corporation if:
(A)
Stock possessing more than fifty percent of the voting power of all classes of
stock and more than fifty percent of each class of the nonvoting stock of each
of the includable C corporations, except the common parent C corporation, is
owned directly or indirectly by one or more of the other includable C
corporations; and
(B) The
common parent C corporation owns directly or indirectly stock possessing more
than fifty percent of the voting power of all classes of stock and more than
fifty percent of each class of the nonvoting stock of at least one of the other
includable C corporations.
(II) As
used in this subsection (12)(a), the term "stock" does not include
nonvoting stock that is limited and preferred as to dividends, employer
securities, within the meaning of section 409 (1) of the internal revenue code,
while such securities are held under a tax credit employee stock ownership
plan, or qualifying employer securities, within the meaning of section 4975
(e)(8) of the internal revenue code, while such securities are held under an
employee stock ownership plan which meets the requirements of section 4975
(e)(7) of the internal revenue code.
(a.3)
"Combined group" means the affiliated group of C corporations that
must file a combined report as required by subsection (11.5) of this section.
(a.5)
"Combined report" means a tax return required to be filed for the
combined group containing information as provided in this article 22 or
required by the executive director.
(b)
"Listed jurisdiction" means:
(I) For
income tax years commencing before January 1, 2026, Andorra, Anguilla, Antigua
and Barbuda, Aruba, the Bahamas, Bahrain, Barbados, Belize, Bermuda, Bonaire,
British Virgin Islands, Cayman Islands, Cook Islands, Curaçao, Cyprus,
Dominica, Gibraltar, Grenada, Guernsey-Sark-Alderney, Isle of Man, Jersey,
Liberia, Luxembourg, Malta, Marshall Islands, Mauritius, Monaco, Montserrat,
Nauru, Niue, Panama, Saba, Samoa, San Marino, Seychelles, Sint Eustatius, Sint
Maarten, St. Kitts and Nevis, St. Lucia, St. Vincent and the Grenadines, Turks
and Caicos Islands, U.S. Virgin Islands, and Vanuatu;
(II)
For income tax years commencing on or after January 1, 2026, but before January
1, 2027, the jurisdictions listed in subsection (12)(b)(I) of this section and
Hong Kong, Republic of Ireland, Liechtenstein, Netherlands, and Singapore; and
(III)
For income tax years commencing on or after January 1, 2027, the jurisdictions
listed in subsection (12)(b)(I) of this section and Hong Kong, Republic of
Ireland, Netherlands, and Singapore.
(c)
Repealed.
(c.3)
"Net CFC tested income" means income included as federal gross income
pursuant to section 951A (a) of the internal revenue code.
(c.5)
"Subpart F income" means income included as federal gross income
pursuant to section 951 (a) of the internal revenue code.
(d)
"Taxpayer" means a C corporation or combined group subject to the tax
imposed by section 39-22-301.
(e)
"Unitary business" means a single economic enterprise made up either
of separate parts of a single C corporation or of an affiliated group of C
corporations that are sufficiently interdependent, integrated, and interrelated
through their activities so as to provide a synergy and mutual benefit that
produces a sharing or exchange of value among them and a significant flow of
value to the separate parts. A unitary business includes that part of the
business that is conducted by a taxpayer through the taxpayer's interest in a
partnership, whether the interest in that partnership is held directly or
indirectly through a series of partnerships or other pass-through entities.
(13)
Repealed.
(14)
(Deleted by amendment, L. 2008, p. 955, § 7, effective January 1, 2009.)
(15)
Repealed.
(16)
(a) During the state fiscal year beginning July 1, 2027, and every fourth
state fiscal year thereafter, the department shall engage a contractor to
examine whether a country that is identified as a listed jurisdiction should
remain a listed jurisdiction.
(b) The
department shall require the contractor to examine each listed jurisdiction and
to make recommendations about the status of a listed jurisdiction in a written
report submitted to the executive committee of the legislative council and the
governor no later than one hundred eighty calendar days after the effective
date of the contract engaging the contractor to conduct the study.
(c)
When examining a listed jurisdiction, the department shall require the
contractor to recommend whether a listed jurisdiction should continue to be a
listed jurisdiction based on whether the listed jurisdiction:
(I)
Assesses a corporate tax rate of less than fifteen percent;
(II)
Allows tax deductions, incentives, or credits that lower effective tax rates
artificially, with special consideration given to intellectual property and
foreign-source royalties;
(III)
Targets profit-shifting of foreign-controlled corporations;
(IV)
Lacks transparency and does not engage in data sharing or cooperate with other
countries' revenue agencies during audits and investigations or does not
participate in country-by-country reporting;
(V)
Does not require a corporation to engage in substantial activity or deliver
economic substance in the listed jurisdiction in order to be incorporated in
that jurisdiction;
(VI)
Does not maintain a beneficial ownership registry or does not provide the
public with access to company information;
(VII)
Allows hybrid-mismatch relationships;
(VIII)
Allows overly lenient transfer pricing;
(IX)
Allows income-shifting between corporate affiliates or other indicators of
profit-shifting;
(X) Has
not undertaken reforms to address allegations that it is a tax haven and that
it should not be a listed jurisdiction;
(XI)
Provides certain tax or other benefits exclusively for foreign firms and not to
domestic entities;
(XII)
Engages in other tax evasion indicators; or
(XIII)
Issues corporate profit or foreign direct investment statistics that are
significantly out of proportion to local economic development or the local workforce.
(d) A
country may submit to the contractor or the department information about
international tax reform and evolving best practices.
(e) The
contractor may recommend that a country be deemed a listed jurisdiction or
recommend that a country no longer be a listed jurisdiction.
Source:
L. 64: R&RE,
p. 769, § 1. C.R.S. 1963: § 138-1-37. L. 79: Entire section
R&RE, p. 1443, § 34, effective July 3. L. 80: (7) added, p. 731, §
1, effective March 17. L. 85: (8) to (12) added, p. 1273, § 1, effective
June 12. L. 89: (5)(a) and (6) amended and (13) added, p. 1499, § 2,
effective July 1, 1990. L. 92: (1) to (3), (4)(a), (4)(d)(I), (4)(d)(V)
to (4)(d)(VII), (4)(e), IP(5)(b), (5)(b)(III), (5)(c), (6), (8), (9), (10)(b),
(10)(c), (11), (12)(a), and (12)(c) amended, p. 2268, § 8, effective April 16. L.
93: (14) added, p. 1320, § 4, effective June 6. L. 96: (5)(c)
amended, p. 165, § 5, effective July 1. L. 99: (10)(b) amended, p. 1282,
§ 1, effective August 4. L. 2004: (12)(b) amended, p. 1209, § 90,
effective August 4. L. 2008: (1), (2), (3), (4), (5), (7), IP(10),
(11)(c), (11)(e), and (14) amended, p. 955, § 7, effective January 1, 2009. L.
2019: (8) amended, (11)(f), (11)(g), and (15) added, and (12)(c) repealed,
(SB 19-233), ch. 397, p. 3535, § 2, effective August 2; IP(10) and (11)(c) amended,
(SB 19-241), ch. 390, p. 3476, § 52, effective August 2. L. 2021: (8),
(11)(c)(II), and (12) amended, (HB 21-1311), ch. 298, p. 1775, § 6, effective
June 23. L. 2024: (10)(b)(II) and (10)(b)(III) amended, IP(11), (11.2),
(11.5), (12)(a.3), (12)(a.5), (12)(d), and (12)(e) added, and (13) and (15)
repealed, (HB 24-1134), ch. 172, p. 936, § 5, effective August 7. L. 2025,
1st Ex. Sess.: (8)(b)(II) and (12)(b) amended, (HB 25B-1002), ch. 6, p. 21,
§ 2, effective August 28. L. 2026: (8)(a), (8)(b)(I), (11.5)(b)(I),
(11.5)(b)(II), (12)(b)(I), and (12)(b)(II) amended and (8)(c), (8.5),
(12)(b)(III), (12)(c.3), (12)(c.5), and (16) added, (HB 26-1289), ch. 364, pp.
2188, 2218, §§ 5, 35, effective June 3.
Cross
references: For
the legislative declaration in SB 19-233, see section 1 of chapter 397, Session
Laws of Colorado 2019. For the legislative declaration in HB 21-1311, see
section 1 of chapter 298, Session Laws of Colorado 2021. For the legislative
declaration in HB 25B-1002, see section 1 of chapter 6, Session Laws of
Colorado 2025, First Extraordinary Session. For the legislative declaration in
HB 26-1289, see section 1 of chapter 364, Session Laws of Colorado 2026.
ANNOTATION
Two-factor formula
constitutional. The two-factor formula, consisting of sales and property
factors in the computation of income tax for a foreign corporation is not
intrinsically arbitrary, and, thus, is constitutional. GMC v. State, 181 Colo.
360, 509 P.2d 1260 (1973).
Difference of nine-tenths
percent too small to be unconstitutional. A difference of nine-tenths
percent between the computation of a railroad and that of the director of
revenue concerning the allocation of apportionable income to Colorado is too
small to constitute an unlawful burden upon interstate commerce, a violation of
due process, or a violation of equal protection. Union P.R.R. v. Heckers, 181
Colo. 374, 509 P.2d 1255 (1973).
General assembly decides
which taxation formula economically sound. It is not the trial court's
function, nor that of the supreme court, to decide which formula for the
taxation of a foreign corporation is the most economically sound, as this is a
policy decision for the general assembly. GMC v. State, 181 Colo. 360, 509 P.2d
1260 (1973).
Presumption that percentage
allocation for foreign corporation fair. Where a statutory formula for the
taxation of a foreign corporation is not intrinsically invalid, there is a
strong presumption that the percentage allocation is fair. GMC v. State, 181
Colo. 360, 509 P.2d 1260 (1973).
Regulation may not modify or
contravene existing statute. A regulation must further the will of the
general assembly and may not modify or contravene an existing statute. Miller
Int'l, Inc. v. State Dept. of Rev., 646 P.2d 341 (Colo. 1982).
Else it is invalid. A
method of allocation of income which is established by regulation, but which is
inconsistent with this section, is invalid. Miller Int'l, Inc., v. State Dept.
of Rev., 646 P.2d 341 (Colo. 1982).
Fairness is not equated with
absolute precision. GMC v. State, 181 Colo. 360, 509 P.2d 1260 (1973).
Heavy burden lies on party
challenging constitutional validity of tax apportionment formula. GMC v.
State, 181 Colo. 360, 509 P.2d 1260 (1973).
Party must show by
"clear and convincing evidence" that the use of the particular
formula results in extraterritorial values being taxed. GMC v. State, 181 Colo.
360, 509 P.2d 1260 (1973).
The economic substance
doctrine does not give the department the authority to disregard a company's
corporate structure and tax it when there are no factual grounds to support
a conclusion that the structure was put in place to avoid state taxes. Agilent
Techs. v. Dept. of Rev., 2017 COA 137, 442 P.3d 938, aff'd, 2019 CO 41, 441
P.3d 1012 (case decided prior to 2019 amendments to subsections (8) and (12)(c)
and addition of subsections (11)(f), (11)(g), and (15)).
Allocation method valid if
calculates income "reasonably attributed" to state transactions.
The method of allocation of unitary income between states is valid if it is
fairly calculated to assign to a state that portion of the net income
"reasonably attributable" to the business transacted in that state.
Union P.R.R. v. Heckers, 181 Colo. 374, 509 P.2d 1255 (1973).
Direct deduction of ad
valorem taxes from net income is not required. Union P.R.R. v. Heckers, 181
Colo. 374, 509 P.2d 1255 (1973).
Director may change method
of allocation. The fact that a corporation uniformly has been permitted to
allocate Colorado and out-of-state income does not mean that the director may
not change the method of allocation. Coors Porcelain Co. v. State, 183 Colo.
325, 517 P.2d 838 (1973).
Department may allocate
income among corporations owned by same interests. The department of
revenue may distribute or allocate the income of corporations owned or
controlled by the same interests if it concludes that is the most effective
method of taxing all the income that Colorado can constitutionally tax. Joslin
Dry Goods Co. v. Dolan, 615 P.2d 16 (Colo. 1980); Hewlett-Packard Co. v. State
Dept. of Rev., 749 P.2d 400 (Colo. 1988).
Subsection (6) does not
provide the department with an alternative method of allocating income
among affiliated C corporations in order to impose a tax on that income apart
from the tests under subsections (11)(a) and (12)(c). Agilent Techs. v. Dept.
of Rev., 2017 COA 137, 442 P.3d 938, aff'd, 2019 CO 41, 441 P.3d 1012 (case
decided prior to 2019 amendments to subsections (8) and (12)(c) and addition of
subsections (11)(f), (11)(g), and (15)).
Recognized test for a
unitary business is "whether or not the operation of the portion of
the business within the state is dependent upon or contributory to the
operation of the business outside the state". Joslin Dry Goods Co. v.
Dolan, 615 P.2d 16 (Colo. 1980).
Subsection (6) does not
provide the department with an alternative method of allocating income
apart from the test for affiliated groups of C corporations outlined in
subsection (12)(c). Because a holding company is not an includable C
corporation, it cannot be a member of an affiliated group, and in turn falls
outside the director's power to require its inclusion in a combined tax return.
Oracle Corp. v. Dept. of Rev., 2017 COA 152, 442 P.3d 947, aff'd, 2019 CO 42,
441 P.3d 1021; Agilent Techs. v. Dept. of Rev., 2017 COA 137, 442 P.3d 938,
aff'd, 2019 CO 41, 441 P.3d 1012 (both cases decided prior to 2019 amendments
to subsections (8) and (12)(c) and addition of subsections (11)(f), (11)(g),
and (15)).
The income of foreign
subsidiaries of a unitary business, even though such income is not federal
taxable income, should be included in determining the net income base for a
corporation. Hewlett-Packard Co. v. State Dept. of Rev., 749 P.2d 400 (Colo.
1988).
A holding company that has
no income or payroll of its own cannot, by definition, have twenty percent or
more of its factors assigned to locations in the United States, and
therefore cannot be included on a parent C corporation's combined tax return.
Oracle Corp. v. Dept. of Rev., 2017 COA 152, 442 P.3d 947, aff'd, 2019 CO 42,
441 P.3d 1021; Agilent Techs. v. Dept. of Rev., 2017 COA 137, 442 P.3d 938,
aff'd, 2019 CO 41, 441 P.3d 1012 (both cases decided prior to 2019 amendments
to subsections (8) and (12)(c) and addition of subsections (11)(f), (11)(g),
and (15)).
Section authorizes
department to require combined reports. It is this section's provision for
the distribution and allocation of income and deductions which authorizes the
department to require combined reports. Joslin Dry Goods Co. v. Dolan, 615 P.2d
16 (Colo. 1980).
A combined-consolidated
filing is permissible. An affiliated group that is required to file a
combined return may also elect to file a consolidated return. This type of
return was clearly allowed under the published statutes and the related
department regulations. Cendant Corp. & Subs. v. Dept. of Rev., 226 P.3d
1102 (Colo. App. 2009).
39-22-303.1. Interstate banking or
branching - nondiscriminatory tax treatment.
(1) On
or before June 1, 1997, the executive director shall promulgate regulations to
ensure nondiscriminatory tax treatment of financial organizations engaged in
interstate banking or interstate branching and, in connection therewith, shall
consider:
(a) Any
recommendations of the multistate tax commission established under the
provisions of section 24-60-1301, C.R.S., regarding the taxation and allocation
of income and expenses of financial organizations; and
(b)
Applying the multistate tax compact, as set forth in part 13 of article 60 of
title 24, C.R.S., to financial organizations.
Source:
L. 95: Entire
section added, p. 770, § 16, effective July 1.
39-22-303.5. Single-factor apportionment
of business income - allocation of nonbusiness income - rules - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Business income" means the net income of the taxpayer arising from
the transactions and activity in the regular course of a taxpayer's trade or
business and includes income from tangible and intangible property if the
acquisition, management, and disposition of the property constitute integral
parts of the taxpayer's regular trade or business operations. For purposes of
administration of this section, the income of the taxpayer is business income
unless clearly classifiable as nonbusiness income.
(b)
"Commercial domicile" means the principal place from which the trade
or business of the taxpayer is directed or managed.
(c)
"Nonbusiness income" means all income other than business income.
(d)
"Sales" means all gross receipts of the taxpayer not allocated under
subsection (5) of this section and not otherwise excluded from the calculation
of net income; except that, for the sale of intangible property,
"sales" means the gain from the sale and not the gross receipts.
(e)
"State" means any state of the United States, the District of
Columbia, the Commonwealth of Puerto Rico, any territory or possession of the
United States, and any foreign country or political subdivision thereof.
(f)
"Taxpayer" means a C corporation or any nonresident individual,
nonresident partner, or S corporation that is permitted or required pursuant to
another provision of law to apportion and allocate revenue pursuant to this
section.
(2) (a)
For income tax years commencing prior to January 1, 2009, a taxpayer shall
apportion and allocate income pursuant to section 24-60-1301, C.R.S., or
apportion income pursuant to section 39-22-303, as those sections existed
immediately prior to January 1, 2009.
(b) For
income tax years commencing on or after January 1, 2009, but prior to January
1, 2019, a taxpayer shall apportion and allocate the taxpayer's entire net
income as provided in this section.
(3) (a)
If a taxpayer has no income from business activity outside of Colorado, the
taxpayer's entire net income shall be allocated to Colorado.
(b) A
taxpayer having income from business activity that is taxable both within and
without Colorado shall apportion and allocate the taxpayer's net income as
provided in this section.
(c) For
purposes of apportionment and allocation of income under this section, a
taxpayer is taxable in another state if:
(I) In
that state, the taxpayer is subject to a net income tax, a franchise tax
measured by net income, a franchise tax for the privilege of doing business, a
corporate stock tax, or any similar tax; or
(II)
That state has jurisdiction to subject the taxpayer to a net income tax
regardless of whether, in fact, the state subjects the taxpayer to such tax.
(4) (a)
A taxpayer's business income shall be apportioned to Colorado by multiplying
such business income by a fraction, the numerator of which is the total sales
of the taxpayer in Colorado during the tax period and the denominator of which
is the total sales of the taxpayer everywhere during the tax period.
(b)
Sales of tangible personal property, including gross receipts from leases and
other uses of tangible personal property, are in Colorado if:
(I) The
property is delivered or shipped to a purchaser in Colorado regardless of the
f.o.b. point or other conditions of the sale; or
(II)
The property is shipped from an office, store, warehouse, factory, or other
place of storage in Colorado and the taxpayer is not taxable in the state to
which the property is shipped.
(c)
Sales, other than sales of tangible personal property, are in Colorado as
follows:
(I)
Revenue from services rendered in Colorado;
(II)
Rents and royalties from real property located in Colorado;
(III)
Gross proceeds from the sale of real property located in Colorado;
(IV)
Interest and dividend income to the extent included in taxable income, if the
taxpayer's commercial domicile is in Colorado;
(V)
Gain from the sale of intangible property if the taxpayer's commercial domicile
is in Colorado;
(VI)
Patent and copyright royalties, if and to the extent that:
(A) The
patent or copyright is utilized by the payer in Colorado; or
(B) The
patent or copyright is utilized by the payer in a state in which the taxpayer
is not taxable and the taxpayer's commercial domicile is in Colorado; and
(VII)
Revenue from the performance of purely personal services, if the
income-producing activity is performed in Colorado.
(d)
Notwithstanding any other provision of this subsection (4), in apportioning the
income of a taxpayer engaged in the business of publishing magazines or
periodicals either through print or electronic media, sales related to
advertising in magazines or periodicals shall be part of the taxpayer's total
sales in Colorado only to the extent that such magazines or periodicals are
delivered within Colorado. The determination of the extent to which magazines
or periodicals are delivered within Colorado shall be based upon the ratio that
the delivery of magazines or periodicals by such taxpayer or tax-reporting
entity in Colorado bears to the total delivery of magazines and periodicals by
such taxpayer or tax-reporting entity.
(e)
Notwithstanding any other provision of law, no foreign source income that is
included in taxable income shall be included as sales of the taxpayer in
Colorado for purposes of apportioning business income pursuant to this
subsection (4).
(f) For
purposes of subparagraph (VI) of paragraph (c) of this subsection (4) and
paragraph (g) of subsection (5) of this section:
(I) A
patent is utilized in a state to the extent that it is employed in production,
fabrication, manufacturing, or other processing in the state or to the extent
that a patented product is produced in the state. If the basis of the receipts
from the patent royalties cannot be reasonably assigned to states or if the
accounting procedures do not reflect the states of utilization, the patent is
utilized in the state in which the taxpayer's commercial domicile is located.
(II) A
copyright is utilized in a state to the extent that printing or other
publication originates in the state. If the basis of receipts from copyright
royalties cannot be reasonably assigned to states or if the accounting
procedures do not reflect the states of utilization, the copyright is utilized
in the state in which the taxpayer's commercial domicile is located.
(5) A
taxpayer's rents and royalties from real or tangible personal property, capital
gains, interest, dividends, patent or copyright royalties, or other income, to
the extent that they constitute nonbusiness income, shall be allocated as
follows:
(a) Net
rents and royalties from real property located in Colorado shall be allocated
to Colorado;
(b) (I)
Net rents and royalties from tangible personal property shall be allocated to
Colorado:
(A) If
and to the extent that the property is utilized in Colorado; or
(B) In
their entirety if the taxpayer's commercial domicile is in Colorado and the
taxpayer is not organized under the laws of, or taxable in, the state in which
the property is utilized.
(II)
For purposes of this paragraph (b), the extent of utilization of tangible
personal property in Colorado shall be determined by multiplying the rents and
royalties by a fraction, the numerator of which is the number of days of
physical location of the property in Colorado during the rental or royalty
period in the taxable year and the denominator of which is the number of days
of physical location of the property everywhere during all rental or royalty
periods in the taxable year. If the physical location of the property during
the rental or royalty period is unknown or unascertainable by the taxpayer,
tangible personal property shall be utilized in the state in which the property
was located at the time the rental or royalty payer obtained possession.
(c)
Capital gains and losses from sales of real property located in Colorado shall
be allocated to Colorado;
(d)
Capital gains and losses from sales of tangible personal property shall be
allocated to Colorado if:
(I) The
property had a situs in Colorado at the time of the sale; or
(II)
The taxpayer's commercial domicile is in Colorado and the taxpayer is not
taxable in the state in which the property had a situs;
(e)
Capital gains and losses from sales of intangible property shall be allocated
to Colorado if the taxpayer's commercial domicile is in Colorado;
(f)
Interest and dividends shall be allocated to Colorado if the taxpayer's
commercial domicile is in Colorado;
(g)
Patent and copyright royalties shall be allocated to Colorado if and to the
extent that:
(I) The
patent or copyright is utilized by the payer in Colorado; or
(II)
The patent or copyright is utilized by the payer in a state in which the
taxpayer is not taxable and the taxpayer's commercial domicile is in Colorado;
and
(h)
Nonbusiness income that is not otherwise allocated pursuant to this subsection
(5) shall be allocated pursuant to subsection (7) of this section.
(6)
Notwithstanding any other provision of this section, for each taxable year
commencing on or after January 1, 2009, but prior to January 1, 2019, a
taxpayer may elect to treat all income as business income. This election shall
be made in accordance with rules adopted by the department of revenue and shall
be made by the extended due date of the tax return. Once made, the election
shall be irrevocable for such tax year.
(7) (a)
In the case of certain industries where unusual factual situations produce
inequitable results under the apportionment and allocation provisions of this
section, the executive director shall promulgate rules for determining the
apportionment and allocation factors for each such industry, but such rules
shall be applied uniformly.
(b) If
the apportionment and allocation provisions of this section do not fairly
represent the extent of the taxpayer's activities in Colorado, the taxpayer may
petition for, or the executive director may require, with respect to all or any
part of the taxpayer's business activities, if reasonable:
(I)
Separate accounting;
(II)
The inclusion of one or more additional factors that will fairly represent the
taxpayer's business activity in Colorado; or
(III)
The employment of any other method to effectuate an equitable apportionment or
allocation of the taxpayer's income, fairly calculated to determine the net
income derived from or attributable to sources in Colorado.
(c) If
the executive director requires the taxpayer to change its present method of
reporting, the executive director shall notify the taxpayer in writing of the
reason for the required change. The notice shall be made by first-class mail as
set forth in section 39-21-105.5 and shall be sufficiently particular to give
the taxpayer adequate information as to the reasons for the change so that the
taxpayer may frame an answer for and defend its present method of reporting if
it decides to appeal.
(d) The
department of revenue, from time to time, shall publish all rulings of general
public interest with respect to any application of the provisions of this
subsection (7).
(e) If
requested by the director of research of the legislative council, the executive
director shall require taxpayers to provide additional information related to
apportionment and allocation of income to support an income tax return for the
purpose of providing such information to legislative council staff to improve
the accuracy of fiscal notes and reports to the legislature. The executive
director shall aggregate such additional information so as to preserve the
confidentiality of the taxpayer's information and comply with section
39-21-113.
(8) A
bank, savings and loan, credit union, or other taxpayer making or purchasing
loans whose only business activity within Colorado is the ownership of property
acquired through the process of foreclosure, or was obtained through a
procedure exercised in lieu of the entity exercising its right to foreclose,
which property is later disposed of within twenty-four months after obtaining
ownership, shall directly allocate net income for such property during such
time and any gains or losses realized from the sale of such foreclosed property
to the state where the property is located. Such limited activities shall not
render a bank, savings and loan, credit union, or other entity subject to the
other allocation and apportionment provisions of this section.
(9) The
executive director shall promulgate rules in accordance with article 4 of title
24, C.R.S., to apply and administer the provisions of this section. Any rules
that the executive director promulgated in order to apply and administer
section 39-22-303 or 24-60-1301, C.R.S., that may be used to apply and
administer the provisions of this section, including provisions to apply and
administer the sales factor for special industries, which are set forth in 1
CCR 201-2, shall continue to be in effect unless inconsistent with the
provisions of this section or specifically withdrawn by the executive director.
(10) On
or before January 1, 2014, the director of the office of economic development
shall prepare a report describing the economic impacts related to apportionment
and allocation of taxable income pursuant to this section and deliver the
report to the finance committees of the senate and house of representatives, or
any successor committees.
Source:
L. 2008: Entire
section added, p. 958, § 8, effective January 1, 2009. L. 2010: IP(4)(f)
amended, (HB 10-1422), ch. 419, p. 2121, § 174, effective August 11. L.
2018: (2)(b) and (6) amended, (HB 18-1185), ch. 369, p. 2231, § 3,
effective August 8.
Cross
references: For
the legislative declaration in HB 18-1185, see section 1 of chapter 369,
Session Laws of Colorado 2018.
39-22-303.6. Market-based apportionment
of the income of a taxpayer engaged in business - allocation of
nonapportionable income - rules - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Apportionable income" means:
(I) Any
income that would be allocable to this state under the United States
constitution, but that is apportioned rather than allocated pursuant to the
laws of this state; and
(II)
All income that is apportionable under the United States constitution and is
not allocated under the laws of this state, including:
(A)
Income arising from transactions and activity in the regular course of a
taxpayer's trade or business; and
(B)
Income arising from tangible and intangible property if the acquisition,
management, employment, development, or disposition of the property is or was
related to the operation of the taxpayer's trade or business.
(b)
"Commercial domicile" means the principal place from which the trade
or business of the taxpayer is directed or managed.
(c)
"Nonapportionable income" means all income other than apportionable
income.
(d)
"Receipts" means all gross receipts of the taxpayer that are not
allocated under subsection (7) or (9) of this section, and that are received
from transactions and activity in the regular course of the taxpayer's trade or
business; except that receipts of a taxpayer from hedging transactions and from
the maturity, redemption, sale, exchange, loan, or other disposition of cash or
securities are excluded.
(e)
"State" means any state of the United States, the District of
Columbia, the Commonwealth of Puerto Rico, any territory or possession of the
United States, and any foreign country or political subdivision thereof.
(f)
"Taxpayer" means any person that is permitted or required pursuant to
another provision of law to apportion and allocate income pursuant to this
section.
(2) For
income tax years commencing on or after January 1, 2019, a taxpayer shall
apportion and allocate the taxpayer's entire net income as provided in this
section.
(3) (a)
A taxpayer that has no income from business activity outside of Colorado shall
allocate all net income to Colorado.
(b) A
taxpayer that has income from business activity that is taxable both within and
without Colorado shall apportion and allocate the taxpayer's net income as
provided in this section.
(c) For
purposes of apportionment and allocation of income under this section, a
taxpayer's income is taxable in another state if:
(I) In
that state, the taxpayer is subject to a net income tax, a franchise tax
measured by net income, a franchise tax for the privilege of doing business, a
corporate stock tax, or any similar tax; or
(II)
That state has jurisdiction to subject the taxpayer to a net income tax
regardless of whether, in fact, the state subjects the taxpayer to such tax.
(4) (a)
A taxpayer's apportionable income shall be apportioned to Colorado by
multiplying such apportionable income by a fraction, the numerator of which is
the total receipts of the taxpayer in Colorado during the tax period and the
denominator of which is the total receipts of the taxpayer everywhere during
the tax period.
(b)
Notwithstanding any other provision of law, foreign source income that is
included in taxable income is not included as receipts of the taxpayer in
Colorado for purposes of apportioning apportionable income pursuant to this
section.
(5)
Receipts from the sales of tangible personal property are in Colorado if:
(a) The
property is delivered or shipped to a purchaser in Colorado regardless of the
f.o.b. point or other conditions of the sale; or
(b) The
property is shipped from an office, store, warehouse, factory, or other place
of storage in Colorado and the taxpayer is not taxable in the state to which
the property is shipped.
(6)
Receipts, other than receipts described in subsection (5) of this section, are
in Colorado if the taxpayer's market for the sales is in Colorado. The
taxpayer's market for sales is in Colorado if:
(a) In
the case of the sale of a service, to the extent the service is delivered to a
location in Colorado;
(b) In
the case of the sale, rental, lease, or license of real property, to the extent
the real property is located in Colorado;
(c) In
the case of the rental, lease, or license of tangible personal property, to the
extent the tangible personal property is located in Colorado;
(d) In
the case of intangible property:
(I)
That is rented, leased, or licensed, to the extent the intangible property is
used in Colorado, provided that the intangible property utilized in marketing a
good or service to a consumer is used in Colorado if that good or service is
purchased by a consumer who is in Colorado; or
(II)
That is sold, to the extent the intangible property is used in Colorado,
provided that:
(A) A
contract right, government license, or similar intangible property that
authorizes the holder to conduct a business activity in a specific geographic
area is used in Colorado if the geographic area includes all or part of
Colorado; and
(B)
Receipts from intangible property sales that are contingent on the
productivity, use, or disposition of the intangible property are treated as
receipts from the rental, lease, or licensing of the intangible property under
subsection (6)(d)(I) of this section;
(III)
All other receipts for sales of intangible property that are not described in
subsection (6)(d)(II) of this section are excluded from the numerator and
denominator of the apportionment fraction set forth in subsection (4)(a) of
this section;
(e) If
the state or states of assignment under this subsection (6) cannot be
determined, the state or states of assignment must be reasonably approximated;
and
(f)
With respect to any receipt, if the state of assignment cannot be determined
under this subsection (6) or reasonably approximated under subsection (6)(e) of
this section, such receipts are excluded from the denominator of the
apportionment fraction set forth in subsection (4)(a) of this section.
(7) A
taxpayer's rents and royalties from real or tangible personal property, capital
gains, interest, dividends, patent or copyright royalties, or other income, to
the extent that they constitute nonapportionable income, are allocated as
follows:
(a) Net
rents and royalties from real property located in Colorado are allocated to
Colorado;
(b) (I)
Net rents and royalties from tangible personal property are allocated to
Colorado:
(A) If
and to the extent that the property is utilized in Colorado; or
(B) In
their entirety if the taxpayer's commercial domicile is in Colorado and the
taxpayer is not organized under the laws of, or the taxpayer's income is not
taxable in, the state in which the property is utilized.
(II)
For purposes of this subsection (7)(b), the extent of utilization of tangible
personal property in Colorado is determined by multiplying the rents and
royalties by a fraction, the numerator of which is the number of days of
physical location of the property in Colorado during the rental or royalty
period in the taxable year and the denominator of which is the number of days
of physical location of the property everywhere during all rental or royalty
periods in the taxable year. If the physical location of the property during
the rental or royalty period is unknown or unascertainable by the taxpayer,
tangible personal property is utilized in the state in which the property was
located at the time the rental or royalty payer obtained possession.
(c)
Capital gains and losses from sales of real property located in Colorado are
allocated to Colorado;
(d)
Capital gains and losses from sales of tangible personal property are allocated
to Colorado if:
(I) The
property had a situs in Colorado at the time of the sale; or
(II)
The taxpayer's commercial domicile is in Colorado and the taxpayer's income is
not taxable in the state in which the property had a situs;
(e)
Capital gains and losses from sales of intangible property are allocated to
Colorado if the taxpayer's commercial domicile is in Colorado;
(f)
Interest and dividends are allocated to Colorado if the taxpayer's commercial
domicile is in Colorado;
(g) (I)
Patent and copyright royalties are allocated to Colorado if and to the extent
that:
(A) The
patent or copyright is utilized by the payer in Colorado; or
(B) The
patent or copyright is utilized by the payer in a state in which the taxpayer
is not taxable and the taxpayer's commercial domicile is in Colorado.
(II)
For purposes of this subsection (7)(g), a patent is utilized in a state to the
extent that it is employed in production, fabrication, manufacturing, or other
processing in the state or to the extent that a patented product is produced in
the state. If the basis of the receipts from the patent royalties cannot be
reasonably assigned to states or if the accounting procedures do not reflect
the states of utilization, the patent is utilized in the state in which the
taxpayer's commercial domicile is located.
(III)
For purposes of this subsection (7)(g), a copyright is utilized in a state to
the extent that printing or other publication originates in the state. If the
basis of receipts from copyright royalties cannot be reasonably assigned to
states or if the accounting procedures do not reflect the states of
utilization, the copyright is utilized in the state in which the taxpayer's
commercial domicile is located.
(h)
Nonapportionable income that is not otherwise allocated pursuant to this
subsection (7) is allocated pursuant to subsection (9) of this section.
(8)
Notwithstanding any other provision of this section, for each taxable year
commencing on or after January 1, 2019, a taxpayer may elect to treat all
income as apportionable income. This election must be made in accordance with
rules adopted by the department of revenue and made by the extended due date of
the tax return. Once made, the election is irrevocable for the tax year.
(9) (a)
(I) If the allocation and apportionment provisions in this section do not
fairly represent the extent of business activity in Colorado of taxpayers
engaged in a particular industry or in a particular transaction or activity,
the executive director may, in addition to the authority provided in subsection
(9)(b) of this section, and notwithstanding any other provision in this
section, establish appropriate rules, including the application of a variance
allowed under subsection (9)(b) of this section on an industry-wide,
transaction-wide, or activity-wide basis, for determining alternative
allocation and apportionment methods for such taxpayers.
(II) A
rule adopted pursuant to this subsection (9)(a) must be applied uniformly;
except that, with respect to any taxpayer to whom such rule applies, the
taxpayer may petition for, or the executive director may require, adjustment
pursuant to subsection (9)(b) of this section.
(b) If
the apportionment and allocation provisions of this section do not fairly
represent the extent of the taxpayer's business activities in Colorado, the
taxpayer may petition for, or the executive director may require, with respect
to all or any part of the taxpayer's business activities, if reasonable:
(I)
Separate accounting;
(II)
The inclusion of one or more additional factors that will fairly represent the
taxpayer's business activity in Colorado;
(III)
The inclusion of any receipts of a taxpayer otherwise excluded under subsection
(1)(d) of this section, including those from hedging transactions or from the
maturity, redemption, sale, exchange, loan, or other disposition of cash or
securities; or
(IV)
The employment of any other method, notwithstanding any other provision of this
section, to effectuate an equitable apportionment or allocation of the
taxpayer's income, fairly calculated to determine the net income derived from
or attributable to sources in Colorado.
(c) (I)
The taxpayer petitioning for, or the executive director requiring, the use of
any method to effectuate an equitable allocation and apportionment of the
taxpayer's income pursuant to subsection (9)(b) of this section shall prove, by
a preponderance of the evidence, that:
(A) The
allocation and apportionment provisions in this section do not fairly represent
the extent of the taxpayer's business activity in Colorado; and
(B) The
alternative to such provisions is reasonable.
(II)
The same burden of proof applies whether the taxpayer is petitioning for, or
the executive director is requiring, the use of any reasonable method to
effectuate an equitable allocation and apportionment of the taxpayer's income;
except that, if the executive director can show that in any two of the prior
five tax years, the taxpayer had used an allocation and apportionment method at
variance with its allocation and apportionment method or methods in other tax
years, then the executive director does not bear the burden of proof described
in subsection (9)(c)(I) of this section in imposing a different method.
(d) If
the executive director requires any different method to effectuate an equitable
allocation and apportionment of the taxpayer's income pursuant to this
subsection (9), the executive director shall not impose any civil or criminal
penalty with reference to the tax due that is attributable to the taxpayer's
reasonable reliance solely on the allocation and apportionment provisions of
this section.
(e) A
taxpayer that has received written permission from the executive director to
use a reasonable method to effectuate an equitable allocation and apportionment
of the taxpayer's income shall not have that permission revoked with respect to
transactions and activities that have already occurred unless there has been a
material change in, or a material misrepresentation of, the facts provided by
the taxpayer upon which the executive director reasonably relied.
(f) If
the executive director requires the taxpayer to change its present method of
reporting, the executive director shall notify the taxpayer in writing of the
reason for the required change. The notice must be made by first-class mail as
set forth in section 39-21-105.5 and must be sufficiently particular to give
the taxpayer adequate information as to the reasons for the change so that the
taxpayer may frame an answer for and defend its present method of reporting if
it decides to appeal.
(g) The
department of revenue, from time to time, shall publish all rulings of general
public interest with respect to any application of this subsection (9).
(h) If
requested by the director of research of the legislative council, the executive
director shall require taxpayers to provide additional information related to
apportionment and allocation of income to support an income tax return for the
purpose of providing such information to legislative council staff to improve
the accuracy of fiscal notes and reports to the legislature. The executive
director shall aggregate such additional information so as to preserve the
confidentiality of the taxpayer's information and comply with section
39-21-113.
(10) A
bank, savings and loan, credit union, or other taxpayer making or purchasing
loans whose only business activity in Colorado is the ownership of property
acquired through the process of foreclosure, or was obtained through a
procedure exercised in lieu of the entity exercising its right to foreclose,
which property is later disposed of within twenty-four months after obtaining
ownership, shall directly allocate net income for such property during such
time and any gains or losses realized from the sale of such foreclosed property
to the state where the property is located. Such limited activities do not
render a bank, savings and loan, credit union, or other entity subject to the
other allocation and apportionment provisions of this section.
(11)
The executive director shall promulgate rules in accordance with article 4 of
title 24 to apply and administer this section. Any rules that the executive
director promulgated in order to apply and administer section 39-22-303,
39-22-303.5, or 24-60-1301 that may be used to apply and administer this
section, including provisions to apply and administer the sales factor for
special industries, which are set forth in 1 CCR 201-2, continue to be in
effect unless inconsistent with this section or specifically withdrawn by the
executive director.
(12)
Repealed.
Source:
L. 2018: Entire
section added, (HB 18-1185), ch. 369, p. 2225, § 2, effective August 8. L.
2026: (12) repealed, (HB 26-1295), ch. 121, p. 527, § 28, effective August
12.
Cross
references: For
the legislative declaration in HB 18-1185, see section 1 of chapter 369,
Session Laws of Colorado 2018.
39-22-303.7. Sourcing of sales of mutual
fund service corporations - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Administration services" includes, but is not limited to, clerical,
fund, or shareholder accounting and participant record keeping, transfer
agency, bookkeeping, data processing, custodial, internal auditing, legal, and
tax services performed for a regulated investment company. Services qualify as
"administrative services" only if the provider of such services
during the taxable year also provides, or is affiliated with a person that
provides, management or distribution services to a regulated investment company
during the same taxable year.
(b)
"Distribution services" includes, but is not limited to, the services
of advertising, servicing, marketing, or selling shares of a regulated
investment company. The services of advertising, servicing, or marketing shares
qualify as "distribution services" only when the service is performed
by a person that is, or in the case of a closed-end company was, either engaged
in the business of selling regulated investment company shares or affiliated
with a person that is engaged in the service of selling regulated investment
company shares. In the case of an open-end company, such service of selling
shares must be performed pursuant to a contract entered into pursuant to 15
U.S.C. sec. 80a-15 (b), as amended.
(c)
"Domicile" presumptively means the shareholder's mailing address on
the records of the regulated investment company. If, however, the regulated
investment company or the mutual fund service corporation has actual knowledge
that the shareholder's primary residence or principal place of business is
different from the shareholder's mailing address, the presumption shall not
control. If the shareholder of record is a company that holds the shares of the
regulated investment company as depositor for the benefit of a separate
account, then the shareholder shall be the contract owners or policyholders of
the contracts or policies supported by the separate account determined using
any reasonable basis, such as zip codes of underlying shareholders or United States
census bureau data in order to determine the proper location for the assignment
of these shares. If the regulated investment company or the mutual fund service
corporation has actual knowledge that the shareholder's principal place of
business is different from the shareholder's mailing address, the presumption
shall not control.
(d)
"Management services" includes, but is not limited to, any of the
following: The rendering of investment advice, directly or indirectly, to a
regulated investment company, making determinations as to when sales and
purchases of securities are to be made on behalf of the regulated investment
company, or providing services related to the selling or purchasing of
securities constituting assets of a regulated investment company, and related
activities. Services qualify as "management services" only when such
activity or activities are performed pursuant to a contract with the regulated
investment company entered into pursuant to 15 U.S.C. sec. 80a-15 (a), as
amended, for a person that has entered into such contract with the regulated
investment company or for a person that is affiliated with a person that has
entered into such a contract with a regulated investment company.
(e)
"Mutual fund sales" means gross receipts derived within the taxable
year directly or indirectly from the rendering of management, distribution, or
administration services to a regulated investment company, including gross
receipts received directly or indirectly from trustees, sponsors, and
participants of employee benefit plans that have accounts in a regulated
investment company.
(f)
"Mutual fund service corporation" means any corporation doing
business in Colorado that derives gross income from the provision directly or
indirectly of management, distribution, or administration services to or on
behalf of a regulated investment company and from trustees, sponsors, and
participants of employee benefit plans that have accounts in a regulated
investment company.
(g)
"Regulated investment company" means a regulated investment company
as defined in section 851 of the federal "Internal Revenue Code of
1986", as amended.
(2)
Notwithstanding any provision of section 39-22-303.5 or 39-22-303.6, for
taxable years commencing on or after January 1, 2009, mutual fund sales by a
mutual fund service corporation shall be considered Colorado sales for purposes
of section 39-22-303.5 (4)(c) and section 39-22-303.6 (6), to the extent that
shareholders of the regulated investment company are domiciled in Colorado as
follows:
(a) (I)
By multiplying the mutual fund service corporation's total dollar amount of
mutual fund sales of such services on behalf of each regulated investment
company by a fraction, the numerator of which shall be the average of the
number of shares owned by the regulated investment company's shareholders
domiciled in Colorado at the beginning of and at the end of the regulated
investment company's taxable year that ends with or within the mutual fund
service corporation's taxable year, and the denominator of which shall be the
average of the number of shares owned by the regulated investment company
shareholders everywhere at the beginning of and at the end of the regulated
investment company's taxable year that ends with or within the mutual fund
service corporation's taxable year.
(II)
Notwithstanding subparagraph (I) of this paragraph (a), a mutual fund service
corporation may use the year-end of the regulated investment company's fund
advisor for this calculation, as long as the mutual fund service corporation
consistently uses this method from year to year. For purposes of this paragraph
(a), a regulated investment company's fund advisor is the person that is
directly and primarily responsible for providing investment advice to the
regulated investment company under a contract entered into pursuant to 15
U.S.C. sec. 80a-15 (a).
(b) If
the domicile of a shareholder is unknown to the mutual fund service corporation
because the shareholder of record is a person that holds the shares of a
regulated investment company as a depositor for the benefit of others, the
mutual fund service corporation may utilize any reasonable basis, such as zip
codes of underlying shareholders or United States census bureau data, in order
to determine the proper location for the assignment of the shares.
(c) A
separate computation shall be made to determine the mutual fund sales for each
regulated investment company, the sum of which shall equal the total mutual
fund sales sourced to Colorado.
Source:
L. 2008: Entire
section added, p. 958, § 8, effective January 1, 2009. L. 2009: (1)(e),
(1)(f), IP(2), and (2)(c) amended, (HB 09-1311), ch. 275, p. 1237, § 1,
effective May 18. L. 2019: IP(2) amended, (SB 19-241), ch. 390, p. 3477,
§ 53, effective August 2.
39-22-303.9. Apportionment of the income
of a taxpayer with enterprise data center operations in the state -
definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Capital investment" means the:
(I)
Purchase and construction of real estate; or
(II)
Purchase and deployment of capital equipment, machines, building systems,
infrastructure, or other depreciable assets, including capital leases.
(b)
"Enterprise data center operation" means a business that:
(I)
Physically houses information technology equipment such as servers, switches,
routers, data storage devices, or related equipment;
(II)
Manages and processes digital data and information to provide application
services or management for data processing, such as web hosting, internet,
intranet, telecommunication, and information technology services;
(III)
Is owned by a taxpayer; and
(IV) Is
operated substantially for the taxpayer's own use.
(c)
"Office of economic development" or "office" means the
Colorado office of economic development created in section 24-48.5-101.
(d)
"Person" has the same meaning as provided in section 39-21-101 (3).
(e)
"Taxpayer" means a person or an affiliated group of C corporations
authorized to elect to make a consolidated return under section 39-22-305, and
an affiliated group as defined in section 39-22-303 (12).
(2)
Notwithstanding any provision of section 39-22-303.5, for taxable years
commencing on or after the July 1 in the year in which the office provides
written certification to the taxpayer and to the department of revenue that the
requirements described in subsection (3)(a) of this section have been met by
the taxpayer, but no sooner than the taxable year commencing July 1, 2018,
pursuant to the schedule set by the office as described in subsection
(3)(c)(II) of this section, in apportioning the income of a taxpayer with
enterprise data center operations in the state, sales from services are
Colorado sales for purposes of section 39-22-303.5 (4)(c)(I) to the extent such
sales constitute revenues from services that are delivered to the taxpayer's
customer's location in the state, as demonstrated by the customer's billing
address.
(3) (a)
Except as provided in subsection (3)(d) of this section, if a taxpayer makes a
capital investment in an enterprise data center operation in the state as
described in subsection (3)(b) of this section and enters into a memorandum of
understanding with the office as described in subsection (3)(c) of this
section, then the taxpayer is authorized to use the apportionment method set
forth in subsection (2) of this section pursuant to the schedule set forth in
the memorandum of understanding when the capital investment is fully funded.
(b) The
taxpayer shall make a capital investment in an enterprise data center in the
state equal to at least one hundred fifty million dollars within any
consecutive five-year period commencing on or after January 1, 2013.
(c) (I)
The taxpayer shall enter into a memorandum of understanding with the office
that sets forth:
(A) The
amount of the capital investment;
(B) The
specific consecutive five-year period in which the capital investment will
occur;
(C) The
minimum number of net new employees that will be hired by the taxpayer; and
(D) Any
other investments or actions on the part of the taxpayer that will support the
economic development of the state.
(II)
The memorandum of understanding must include a schedule, to be set by the
office, that incrementally transitions the taxpayer, over a period not to
exceed eight years, to the apportionment method described in subsection (2) of
this section.
(III)
When negotiating the terms of the memorandum of understanding with the
taxpayer, the office may seek input from the department of revenue. The
department of revenue shall provide taxpayer-specific information that will
assist the office in setting the terms of the memorandum of understanding.
Notwithstanding section 39-21-113, it is lawful for the department of revenue
to provide such taxpayer-specific information to the office. The office shall
not disclose taxpayer-specific information to the public that it receives
pursuant to this subsection (3)(c)(III) and subsection (3)(c)(V) of this
section and shall keep such taxpayer-specific information confidential. All
employees of the office are subject to the limitations set forth in section
39-21-113 (4) and the penalties set forth in section 39-21-113 (6).
(IV)
(A) The memorandum of understanding must be signed by the office and the
taxpayer no later than one year after the last year of the consecutive
five-year capital investment period described in subsection (3)(b) of this
section.
(B)
When the taxpayer fully funds the capital investment and signs the memorandum
of understanding, the office shall provide written certification to the
taxpayer and the department of revenue that the requirements described in
subsection (3)(a) of this section have been met by the taxpayer and the
taxpayer shall attach a copy of the signed memorandum of understanding with its
tax return in order to provide the department of revenue with the transition
schedule described in subsection (3)(c)(II) of this section for the
apportionment method.
(V) The
taxpayer shall provide any information required by the office for the office to
determine compliance with the terms of the memorandum of understanding.
(VI)
The office and the department of revenue have the right to audit compliance
with the memorandum of understanding and review any information provided by the
taxpayer pursuant to the memorandum of understanding or requested by the office
as allowed under subsection (3)(c)(V) of this section.
(d) If
the taxpayer fails to fully fund the capital investment or fails to fulfill the
obligations established in the memorandum of understanding, the taxpayer may no
longer use the apportionment method set forth in subsection (2) of this section
and apportionment shall be determined pursuant to section 39-22-303.5.
(4)
Notwithstanding section 24-1-136 (11), on November 1, 2019, and each November 1
thereafter, the office and the department of revenue shall submit a report to
the finance committee of the house of representatives and the finance committee
of the senate, or any successor committees, that includes a summary of the use
of this section, the capital investments made, and the number of memoranda of
understanding entered into and that includes an update on the use of
market-based apportionment in the state.
Source:
L. 2017: Entire
section added, (SB 17-299), ch. 318, p. 1710, § 1, effective August 9.
39-22-304. Net income of corporation -
legislative declaration - definitions - repeal.
(1) (a)
The net income of a C corporation means the C corporation's federal taxable
income, as defined in the internal revenue code, for the taxable year, with the
modifications specified in this section.
(b) (I)
(A) For income tax years commencing on or after January 1, 2022, but before
January 1, 2027, in the case of a C corporation that is not incorporated in the
United States, or included in a consolidated federal corporate income tax
return, "federal taxable income" means the C corporation's income or
loss as determined from a profit and loss statement prepared for that C
corporation on a separate entity basis in the currency in which its books of
account are regularly maintained, provided this profit and loss statement is
subject to an independent audit, adjusted to conform to the accounting
principles generally accepted in the United States for the preparation of such
statements and further modified to take into account any book-tax adjustments
necessary to reflect federal and state tax law. Income or loss so computed
includes all income wherever derived and is not limited to items of income from
sources within the United States or effectively connected income within the
meaning of the internal revenue code. Items of income, expense, gain or loss,
and related apportionment factors that are denominated in a foreign currency
must also be translated into United States dollars on a reasonable basis
consistently applied year-to-year and entity-by-entity. Unrealized foreign
currency gains and losses are not recognized. Income apportioned to this state
is to be expressed in United States dollars.
(B) For
income tax years commencing on or after January 1, 2027, in the case of a C
corporation that is included in a combined group pursuant to section 39-22-303,
and that is not incorporated in the United States, or included in a
consolidated federal corporate income tax return, "federal taxable
income" means the C corporation's income or loss as determined from a
profit and loss statement prepared for that C corporation on a separate entity
basis in the currency in which its books of account are regularly maintained,
provided this profit and loss statement is subject to an independent audit,
adjusted to conform to the accounting principles generally accepted in the
United States for the preparation of such statements, and further modified to
take into account any book-tax adjustments necessary to reflect federal and
state tax law. Income or loss so computed includes all income wherever derived
and is not limited to items of income from sources within the United States or
effectively connected income within the meaning of the internal revenue code.
Items of income, expense, gain or loss, and related apportionment factors that
are denominated in a foreign currency must also be translated into United
States dollars on a reasonable basis consistently applied year-to-year and
entity-by-entity. Unrealized foreign currency gains and losses are not
recognized. Income apportioned to the state is to be expressed in United States
dollars.
(C)
Subsection (1)(b)(I)(A) of this section and this subsection (1)(b)(I)(C) are
repealed, effective December 31, 2031.
(II) In
lieu of the procedures set forth in subsection (1)(b)(I) of this section, or in
any case where it is necessary to fairly and consistently reflect the income or
loss and apportionment factors of foreign operations included in a combined
report, the executive director may provide for other procedures to reasonably
approximate the income or loss and apportionment factors of members with
foreign operations.
(2)
There shall be added to federal taxable income:
(a) Any
income, war profits, or excess profits taxes paid or accrued to any foreign
country or to any possession of the United States that were deducted on the
federal income tax return;
(b)
Interest income less amortization of premium on obligations of any state or any
political subdivision thereof, other than interest income on obligations of
this state or a political subdivision thereof which are issued on or after May
1, 1980. Interest income on obligations of this state or a political
subdivision thereof which were issued before May 1, 1980, shall be exempt from
income tax to the extent that such interest is specifically so exempt under the
laws of this state authorizing the issuance of such obligations. The amount of
such interest shall be the net amount after reduction by the amount of the
deductions related thereto which are required by the internal revenue code to
be allocated to such classes of interest.
(c) The
federal net operating loss deduction;
(d)
Income taxes imposed by this state to the extent deducted in determining
federal taxable income, except the tax imposed by article 29 of this title;
(e) (I)
Any expenses incurred by a taxpayer with respect to expenditures made at, or
payments made to, a club licensed pursuant to section 44-3-418 that has a
policy to restrict membership on the basis of sex, sexual orientation, gender
identity, gender expression, marital status, race, creed, religion, color,
ancestry, or national origin. Any such club shall provide on each receipt
furnished to a taxpayer a printed statement as follows:
The expenditures covered by this
receipt are
nondeductible for state income tax
purposes.
(II)
The general assembly finds, determines, and declares that the people of the
state of Colorado desire to promote and achieve tax equity and fairness among
all the state's citizens and further desire to conform to the public policy of
nondiscrimination. The general assembly further declares that the provisions of
this paragraph (e) are enacted for these reasons and for no other purpose.
(f) For
the income tax years commencing on or after January 1, 2000, an amount equal to
the charitable contribution deduction allowed by section 170 of the internal
revenue code to the extent such deduction includes a contribution of real
property to a charitable organization for a conservation purpose for which an
income tax credit is claimed pursuant to section 39-22-522;
(g)
Repealed.
(h) An
amount equal to a business expense for labor services that is deducted pursuant
to section 162 (a)(1) of the internal revenue code but that is prohibited from
being claimed as a deductible business expense for state income tax purposes
pursuant to section 39-22-529;
(i) For
income tax years ending on and after the enactment of the March 2020
"Coronavirus Aid, Relief, and Economic Security Act", Pub.L. 116-136,
referred to in this section as the "CARES Act", but before January 1,
2021, and for income tax years beginning on and after the enactment of the
"CARES Act", but before January 1, 2021, an amount equal to the
amount in excess of the limitation on business interest under section 163 (j)
of the internal revenue code without regard to the amendments made by section
2306 of the "CARES Act".
(j) (I)
For income tax years commencing on or after January 1, 2022, but before January
1, 2023, an amount equal to a federal deduction claimed for the income tax year
for a food and beverage expense that exceeds fifty percent of the amount of the
expense and that was allowed under section 274 (n)(2)(D) of the internal
revenue code.
(II)
This subsection (2)(j) is repealed, effective December 31, 2030.
(k) (I)
For income tax years commencing on or after January 1, 2024, but before January
1, 2031, an amount equal to a federal deduction claimed for a business meal
pursuant to section 274 (k) of the internal revenue code.
(II)
This subsection (2)(k) is repealed, effective December 31, 2035.
(l) For
income tax years commencing on or after January 1, 2026, an amount equal to a
federal deduction claimed for the income tax year for foreign-derived deduction
eligible income pursuant to section 250 of the internal revenue code.
(m) (I)
(A) For income tax years beginning on and after January 1, 2027, the excess
of any gain excluded from federal gross income pursuant to section 1400Z-2
(a)(I)(A) of the internal revenue code over the amount of that gain invested by
the taxpayer in a Colorado qualified opportunity fund in a manner that
qualifies for exclusion from federal gross income pursuant to section 1400Z-2
(a)(I)(A) of the internal revenue code.
(B) For
amounts invested in a qualified opportunity fund after December 31, 2026, other
than a Colorado qualified opportunity fund, the amount of gain excluded from
federal gross income as a result of an election made by the taxpayer pursuant
to section 1400Z-2(c) of the internal revenue code.
(II) As
used in this subsection (2)(m), "Colorado qualified opportunity fund"
means a qualified opportunity fund that holds at least ninety percent of its
assets in Colorado qualified opportunity zone property. Colorado qualified
opportunity zone property is:
(A)
Qualified opportunity zone business property, substantially all of the use of
which, during substantially all of the fund's holding period for the property,
was in a qualified opportunity zone within Colorado; or
(B)
Qualified opportunity zone stock or a qualified opportunity zone partnership
interest in a qualified opportunity zone business, in which substantially all
of the tangible property owned or leased is qualified opportunity zone business
property as described in section 1400Z-2 (d)(3)(A)(i) of the internal revenue
code and substantially all of the use of which is in a qualified opportunity
zone within Colorado.
(III)
For purposes of subsection (2)(m)(II) of this section:
(A)
Property held in the fund shall be measured under rules similar to the rules of
section 1400Z-2 (d)(I) of the internal revenue code; and
(B) The
terms used have the same meaning as set forth in section 1400Z-2 of the
internal revenue code.
(3)
There shall be subtracted from federal taxable income:
(a)
Interest income on obligations of the United States and its possessions to the
extent included in federal taxable income;
(b)
Interest or dividend income on obligations or securities of any authority,
commission, or instrumentality of the United States to the extent included in
federal taxable income but exempt from state income taxes under the laws of the
United States;
(c) The
portion of any gain or loss from the sale or other disposition of property
having a higher adjusted basis for Colorado income tax purposes than for
federal income tax purposes on the date such property was sold or disposed of
in a transaction in which gain or loss was recognized for purposes of federal
income tax that does not exceed such difference in basis, but, if a gain is
considered a long-term capital gain for federal income tax purposes, the
modification shall be limited to the portion of such gain which is included in
federal taxable income;
(d) (I)
Prior to January 1, 2024, the portion of any gain received during the taxable year
from a qualified sale.
(II) As
used in this paragraph (d), "qualified sale" means a sale, in good
faith, of real or personal property to a buyer who initiates the transaction to
purchase real or personal property of the seller and who had or could have
obtained the power to condemn such property, if the transaction was not between
persons defined in section 267 (b) of the internal revenue code.
(III)
The purpose of this paragraph (d) is, for purposes of Colorado income tax, to
accord a seller in a qualified sale the same treatment received by a taxpayer
under section 1033 of the internal revenue code relating to gains from
involuntary conversion, even though said seller does not qualify under said
section 1033 due to the absence of condemnation or the threat or imminence
thereof and the buyer of the property purchased initiates the transaction. The
executive director shall promulgate such reasonable rules and regulations as
are necessary to accomplish the purpose of this paragraph (d).
(IV)
This subsection (3)(d) is repealed, effective December 31, 2028.
(e)
Repealed.
(f) (I)
The amount of any refund or credit for overpayment of income taxes imposed by
this state to the extent included in federal taxable income;
(II)
The purpose of the subtraction authorized in this subsection (3)(f) is to avoid
re-taxing a taxpayer's state income tax refund when a state refund is required
to be included as income on the taxpayer's federal return pursuant to the
internal revenue code; and
(III)
The effectiveness of the subtraction authorized in this subsection (3)(f) is
measured by the number of taxpayers claiming the subtraction and the total
amount of state refunds claimed as subtractions from Colorado taxable income;
(g) The
net operating loss deduction allowed under section 39-22-504;
(h) (I)
Prior to January 1, 2024, an amount equal to the difference between the
depletion allowance permitted under the internal revenue code for oil shale and
an amount which would be permitted as the depletion allowance for oil shale if:
The percentage depletion rate were twenty-seven and one-half percent; and the
crushing, retorting, condensing, and other processes by which oil, gas, or both
oil and gas are removed from oil shale, were deemed to be treatment processes
considered as mining.
(II)
This subsection (3)(h) is repealed, effective December 31, 2028.
(i) (I)
For income tax years beginning before January 1, 2027, that portion of wages or
salaries paid or incurred for the taxable year, the deduction for which is
disallowed by section 280C of the internal revenue code.
(II)
This subsection (3)(i) is repealed, effective December 31, 2031.
(j) Any
amount treated as a section 78 dividend under section 78 of the internal
revenue code;
(k) (I)
Prior to January 1, 2025, any amount contributed to a medical savings account
pursuant to section 39-22-504.7 (2)(e), to the extent such amount is not
claimed as a deduction on the taxpayer's federal tax return.
(II)
This subsection (3)(k) is repealed, effective December 31, 2028.
(l)
Repealed.
(m) For
income tax years commencing on or after January 1, 2014, if a taxpayer is
licensed under the "Colorado Marijuana Code", article 10 of title 44,
or its predecessor codes, an amount equal to any expenditure that is eligible
to be claimed as a federal income tax deduction but is disallowed by section
280E of the internal revenue code because marijuana is a controlled substance
under federal law;
(m.5)
For income tax years commencing on or after January 1, 2024, if a taxpayer is
licensed pursuant to the "Colorado Natural Medicine Code", article 50
of title 44, an amount equal to any expenditure that is eligible to be claimed
as a federal income tax deduction but is disallowed by section 280E of the
internal revenue code because natural medicine is a controlled substance under
federal law;
(n) and
(o) Repealed.
(p) (I)
(A) Except as provided in subsections (3)(p)(I)(B) and (3)(p)(II) of this
section, for income tax years beginning on or after January 1, 2021, but before
January 1, 2022, the sum of the amount by which taxable income for the
specified tax years exceeds the taxable income for the modified specified tax
years computed separately for each income tax year, plus the amount added back
by the taxpayer as specified in subsection (2)(i) of this section.
(B) For
any income tax year included in the calculation under subsection (3)(p)(I)(A)
of this section in which the taxpayer was required to apportion or allocate
income to Colorado under the provisions of this article 22 applicable to that
income tax year, the amount included in the calculation under subsection
(3)(p)(I)(A) is the following amount multiplied by the taxpayer's apportionment
factor for the tax year: The amount by which taxable income for the specified
tax year exceeds the taxable income for the modified specified tax year, plus
the amount added back by the taxpayer as specified in subsection (2)(i).
(II)
(A) The subtraction calculated under subsection (3)(p)(I) of this section
applies after the application of the other subtractions provided for in this
subsection (3) and is limited to the lesser of the taxpayer's Colorado taxable
income or three hundred thousand dollars.
(B) Any
amount of the subtraction calculated under subsection (3)(p)(I) of this section
that a taxpayer may not claim by operation of subsection (3)(p)(II)(A) of this
section may be carried forward to subsequent tax years as a subtraction from
the taxpayer's federal taxable income until exhausted; except that each tax
year's subtraction may not exceed the lesser of the taxpayer's Colorado taxable
income or one hundred fifty thousand dollars for the income tax years
commencing on or after January 1, 2022, but before January 1, 2026, and each
year's subtraction may not exceed the taxpayer's Colorado taxable income in any
income tax years thereafter. Any subtraction must be applied first to the
earliest income tax years possible.
(C) In
the case of a taxpayer that apportions and allocates net income as required by
section 39-22-303.6 (3)(b) in the taxpayer's income tax year beginning on or
after January 1, 2021, but before January 1, 2022, the subtraction applies to
the taxpayer's net income apportioned and allocated to Colorado. Any carry
forward amount subtracted in a subsequent tax year under subsection
(3)(p)(II)(B) of this section is applied to net income apportioned and
allocated to Colorado for that subsequent tax year.
(III) A
taxpayer that applies the subtraction allowed in this subsection (3)(p) with
respect to qualified improvement property shall calculate the gain or loss on a
sale of such qualified improvement property for purposes of the subtraction in
subsection (3)(c) of this section using the basis reported on their federal
income tax return at the time of the sale.
(IV) As
used in this subsection (3)(p), unless the context otherwise requires:
(A)
"CARES Act" means the March 2020 "Coronavirus Aid, Relief, and
Economic Security Act", Pub.L. 116-136.
(B)
"Colorado taxable income" means federal taxable income as modified by
this article 22 without regard to this subsection (3)(p).
(C)
"Retroactive provisions of the CARES Act" means the changes made to
the internal revenue code in sections 2306 and 2307 of the CARES Act.
(D)
"Taxable income for the modified specified tax years" means the
taxpayer's Colorado taxable income for tax years ending before March 27, 2020,
as calculated under the internal revenue code and Colorado law applicable to
the taxpayer's return as of the date the return was due, as modified by the
application of the retroactive provisions of the CARES Act applied to the
calculation of the taxpayer's federal taxable income, but only to the extent
the taxpayer appropriately applied those provisions to the taxpayer's federal
income tax returns for each tax year.
(E)
"Taxable income for the specified tax years" means the taxpayer's
Colorado taxable income for tax years ending before March 27, 2020, as
calculated under Colorado law applicable to the taxpayer's return as of the
date the return was due.
(q) (I)
For income tax years beginning on or after January 1, 2022, but before January
1, 2027:
(A) Any
amount included in federal taxable income pursuant to section 951 (a) of the
internal revenue code with respect to a controlled foreign corporation that is
a C corporation incorporated in a foreign jurisdiction for the purpose of tax
avoidance pursuant to section 39-22-303 (8)(b)(II); and
(B) The
amount of any income included in federal taxable income pursuant to section
951A (a) of the internal revenue code with respect to a controlled foreign
corporation that is a C corporation incorporated in a foreign jurisdiction for
the purpose of tax avoidance pursuant to section 39-22-303 (8)(b)(II), less any
amount deducted under section 250 (a)(1)(B) of the internal revenue code with
respect to such income.
(II)
This subsection (3)(q) is repealed, effective December 31, 2031.
(r)
Repealed.
(s) (I)
For income tax years commencing on or after January 1, 2027, but before January
1, 2038, an amount equal to qualifying capital gains that are subject to tax
under this article 22 and that are realized by an owner during the taxable year
for the qualified sale of a qualified business.
(II) As
used in this subsection (3)(s), unless the context otherwise requires:
(A)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(B)
"Owner" has the same meaning as set forth in section 39-22-542
(2)(h).
(C)
"Qualified business" has the same meaning as set forth in section
39-22-542 (2)(i).
(D)
"Qualified employee-owned business" has the same meaning as set forth
in section 39-22-542 (2)(j).
(E)
"Qualified sale" means the conversion to a qualified employee-owned
business; except that the conversion must be by an increment of at least twenty
percent of the total ownership of the entire qualified employee-owned business.
(F)
"Qualifying capital gains" means the amount of net capital gains, as
defined in section 1222 (11) of the internal revenue code, subject to the
limitation set forth in subsection (3)(s)(V) of this section.
(III)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the income tax subtraction provided in this subsection
(3)(s) is to:
(A)
Induce certain designated behavior by taxpayers, specifically for businesses to
establish employee stock ownership plans or employee ownership trusts or to
convert to a worker-owned cooperative; and
(B)
Provide tax relief for certain businesses or individuals, specifically to
businesses that establish employee stock ownership plans or employee ownership
trusts or that convert to a worker-owned cooperative.
(IV)
The general assembly and the state auditor shall measure the effectiveness of
the subtraction in achieving the purpose specified in subsection (3)(s)(III) of
this section based on the number and aggregate amount of subtractions claimed
in a tax year.
(V) (A)
On or before June 30, 2026, the office shall establish and post on its website
the total amount of capital gains that may be subtracted from an owner's
federal taxable income pursuant to this subsection (3)(s), which amount is in
effect for income tax years commencing on or after January 1, 2027, but before
January 1, 2038, or until the office adjusts the amount as set forth in
subsection (3)(s)(V)(B) of this section.
(B)
After June 30, 2026, on or before June 30, 2027, and on or before June 30 of
each year thereafter until June 30, 2036, the office may adjust the total
amount of capital gains that may be subtracted from an owner's federal taxable
income that the office has previously established in accordance with this
subsection (3)(s)(V). The adjusted amount must be posted on the office's
website and is in effect for income tax years commencing on or after January 1
of the year immediately following the year in which the adjustment is made but
before January 1, 2038, or until the office subsequently adjusts the amount as
set forth in this subsection (3)(s)(V)(B).
(C) An
owner may not subtract more than the amount of capital gains established by the
office in accordance with subsection (3)(s)(V)(A) or (3)(s)(V)(B) of this
section in the income tax year.
(D)
Beginning in January 2027, and in January every year thereafter following a
year in which the office adjusts the amount of capital gains that may be
subtracted from an owner's federal taxable income pursuant to subsection
(3)(s)(V)(B) of this section, the office shall include, as part of its
presentation during its "SMART Act" hearing required by section
2-7-203, information concerning the amount of capital gains that may be
subtracted from an owner's federal taxable income that the office has established
pursuant to subsection (3)(s)(V)(A) or (3)(s)(V)(B) of this section and the
method that the office used to establish the amount.
(VI)
This subsection (3)(s) is repealed, effective July 1, 2042.
(t) (I)
For income tax years commencing on or after January 1, 2027, but before January
1, 2038, an amount equal to a qualified taxpayer's federal taxable income for
the tax year not to exceed one million dollars.
(II) As
used in this subsection (3)(t), unless the context otherwise requires:
(A)
"Qualified taxpayer" means a taxpayer that is subject to tax under
this article 22 and that is a worker-owned cooperative.
(B) "Worker-owned
cooperative" has the same meaning as set forth in section 1042 (c)(2) of
the internal revenue code.
(III)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the income tax subtraction provided in this subsection
(3)(t) is to:
(A)
Induce certain designated behavior by taxpayers, specifically for businesses to
convert to a worker-owned cooperative; and
(B)
Provide tax relief for certain businesses, specifically to provide ongoing
support to businesses that convert to a worker-owned cooperative.
(IV)
The general assembly and the state auditor shall measure the effectiveness of
the subtraction in achieving the purpose specified in subsection (3)(t)(III) of
this section based on the number and aggregate amount of subtractions claimed
in a tax year and the number of subtractions claimed year over year.
(V)
This subsection (3)(t) is repealed, effective July 1, 2042.
(u) For
income tax years commencing on or after January 1, 2027, the amount of gain
included in federal gross income pursuant to section 1400Z-2 (b) of the
internal revenue code to the extent that such gain was added to federal taxable
income pursuant to subsection (2)(m) of this section for a prior tax year.
Source:
L. 64: R&RE,
p. 771, § 1. C.R.S. 1963: § 138-1-38. L. 67: p. 854, §§ 1, 2. L.
77: (3) amended, p. 1795, § 1, effective May 26; (3) R&RE, p. 1784, §
2, effective June 19. L. 78: (3) R&RE, p. 490, § 2, effective March
24. L. 79: (3)(a) amended, p. 1453, § 2, effective March 26. L. 80:
(3)(a) amended, p. 727, § 22, effective January 1, 1981. L. 87: Entire
section R&RE, p. 1442, § 9, effective June 22. L. 92: (1) amended,
p. 2272, § 9, effective April 16; (2)(c) and (2)(d) amended and (2)(e) added,
p. 2279, § 3, effective June 1. L. 94: (3)(k) added, p. 2840, § 5,
effective January 1, 1995. L. 95: (3)(l) added, p. 1199, § 1, effective
May 31. L. 97: (2)(e)(I) amended, p. 304, § 21, effective July 1. L.
99: (2)(f) added, p. 977, § 3, effective August 4. L. 2000: (2)(g)
added, p. 1322, § 4, effective August 2. L. 2004: (2)(f) amended, p.
1209, § 91, effective August 4. Referred 2006: (2)(h) added, L. 2006,
1st Ex. Sess., p. 1, § 2, effective December 31. L. 2008: (2)(e)(I)
amended, p. 1604, § 36, effective May 29. L. 2010: (2)(g) repealed, (SB
10-212), ch. 412, p. 2032, § 1, effective July 1; (2)(g) repealed, (HB
10-1256), ch. 133, p. 440, § 3, effective August 11. L. 2013: (3)(n)
added, (SB 13-283), ch. 332, p. 1896, § 19, effective May 28; (3)(m) added, (HB
13-1042), ch. 327, p. 1820, § 2, effective August 7. L. 2016: (3)(o)
added, (HB 16-1194), ch. 252, p. 1031, § 2, effective August 10. L. 2018:
(2)(e)(I) amended, (HB 18-1025), ch. 152, p. 1082, § 21, effective October 1;
(3)(m) and (3)(n) amended, (HB 18-1023), ch. 55, p. 591, § 24, effective
October 1. L. 2019: (3)(m) amended and (3)(n) repealed, (SB 19-224), ch.
315, p. 2943, § 32, effective January 1, 2020. L. 2020: (2)(i) added,
(HB 20-1420), ch. 277, p. 1359, § 3, effective July 11. L. 2021: (3)(p)
added, (HB 21-1002), ch. 5, p. 32, § 3, effective January 21; (1) and (3)(j)
amended and (2)(j) and (3)(q) added, (HB 21-1311), ch. 298, p. 1777, § 7,
effective June 23; (3)(r) added, (HB 21-1327), ch. 300, p. 1804, § 3, effective
June 23; (2)(e)(I) amended, (HB 21-1108), ch. 156, p. 898, § 47, effective
September 7. L. 2022: (3)(r) repealed, (SB 22-124), ch. 164, p. 1021, §
8, effective May 16; (3)(e) amended, (HB 22-1025), ch. 145, p. 946, § 5,
effective August 10. L. 2023: (3)(m.5) added, (SB 23-290), ch. 249, p.
1423, § 43, effective July 1; (2)(k) added, (HB 23-1008), ch. 338, p. 2029, §
4, effective August 7; (3)(d)(I) and (3)(h) amended and (3)(d)(IV) added, (HB
23-1121), ch. 35, p. 119, § 2, effective August 7. L. 2024: (3)(k)
amended, (HB 24-1036), ch. 373, p. 2527, § 9, effective August 7. L. 2025:
(3)(f) amended, (SB 25-026), ch. 362, p. 1965, § 6, effective August 6; (3)(s)
and (3)(t) added, (HB 25-1021), ch. 311, p. 1619, § 2, effective August 6. L.
2025, 1st Ex. Sess.: (2)(l) added and (3)(j) and (3)(q)(II) amended, (HB
25B-1002), ch. 6, p. 22, § 3, effective August 28. L. 2026: (1)(b)(I),
(3)(i), and (3)(q) amended and (2)(l) and (3)(u) added, (HB 26-1289), ch. 364,
p. 2191, § 6, effective June 3.
Editor's
note: (1)
Amendments to subsection (3) by House Bill 77-1402 and House Bill 77-1519 were
harmonized.
(2) Subsection (3)(l)(II)
provided for the repeal of subsection (3)(l), effective January 1, 2001. (See
L. 95, p. 1199.)
(3) Subsection (2)(h) was
enacted by House Bill 06S-1020 at the first extraordinary session of the
sixty-fifth general assembly. That bill contained a referendum clause and was
approved by a vote of the registered electors of the state of Colorado on
November 7, 2006. Subsection (2)(h) was effective upon proclamation of the
governor, December 31, 2006. The vote count for the measure was as follows:
FOR: 744,475
AGAINST: 722,651
(4) Subsection (3)(e)(II)
provided for the repeal of subsection (3)(e), effective July 1, 2024. (See L.
2022, p. 946.)
(5) Subsection (3)(o)(VII)
provided for the repeal of subsection (3)(o), effective December 31, 2023. (See
L. 2016, p. 1031.)
(6) Subsection (2)(m) was
lettered as (2)(l) in HB 26-1289 but has been relettered on revision for ease
of location.
Cross
references: (1)
For the legislative declaration contained in the 2008 act amending subsection
(2)(e)(I), see section 1 of chapter 341, Session Laws of Colorado 2008.
(2) For the short title
("Tax Fairness Act") in HB 20-1420, see section 1 of chapter 277,
Session Laws of Colorado 2020.
(3) For the legislative
declaration in HB 21-1108, see section 1 of chapter 156, Session Laws of
Colorado 2021. For the legislative declaration in HB 21-1311, see section 1 of
chapter 298, Session Laws of Colorado 2021.
(4) For the legislative
declaration in HB 23-1008, see section 1 of chapter 338, Session Laws of
Colorado 2023.
(5) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024.
(6) For the legislative
declaration in HB 25B-1002, see section 1 of chapter 6, Session Laws of
Colorado 2025, First Extraordinary Session.
(7) For the legislative
declaration in HB 26-1289, see section 1 of chapter 364, Session Laws of
Colorado 2026.
ANNOTATION
Law reviews. For
article, "2006 Immigration Legislation in Colorado", see 35 Colo.
Law. 79 (Oct. 2006).
39-22-305. Consolidated returns.
(1) An
affiliated group of C corporations, as defined in section 1504 of the internal
revenue code, may elect to make a consolidated return with respect to the
corporate income tax imposed by section 39-22-301 (1) for the taxable year in
lieu of separate returns. The making of a consolidated return shall be upon the
condition that all C corporations which at any time during the taxable year
have been members of the affiliated group consent to be included in such
return. The making of a consolidated return shall be considered as such
consent. Such election may not be revoked in less than four years unless
approved by the executive director.
(2) The
executive director shall prescribe such regulations as the executive director
may deem necessary in order that the tax liability of any affiliated group of C
corporations making a consolidated return and of each C corporation in the
group, both during and after the period of affiliation, may be returned,
determined, computed, assessed, collected, and adjusted, in such manner as
clearly to reflect the income tax liability and the various factors necessary
for the determination of such liability and as the executive director may deem
necessary in order to prevent avoidance of the tax liability.
Source:
L. 64: R&RE,
p. 771, § 1. C.R.S. 1963: § 138-1-39. L. 77: Entire section
R&RE, p. 1797, § 1, effective May 18. L. 87: (1) amended, p. 1443, §
10, effective June 22. L. 92: Entire section amended, p. 2272, § 10,
effective April 16.
ANNOTATION
A combined-consolidated
filing is permissible. An affiliated group that is required to file a
combined return may also elect to file a consolidated return. This type of
return was clearly allowed under the published statutes and the related
department regulations. Cendant Corp. & Subs. v. Dept. of Rev., 226 P.3d
1102 (Colo. App. 2009).
39-22-306. Accounting periods and methods.
The
provisions of section 39-22-111 shall apply to C corporations to the extent not
inconsistent with sections 39-22-301 to 39-22-305.
Source:
L. 64: R&RE,
p. 771, § 1. C.R.S. 1963: § 138-1-40. L. 87: Entire section
amended, p. 1444, § 11, effective June 22. L. 92: Entire section
amended, p. 2273, § 12, effective April 16.
39-22-307. Credit allowed for prior
payment of impact assistance. (Repealed)
Source:
L. 80: Entire
section added, p. 723, § 17, effective May 1. L. 94: (2)(a) amended, p.
1646, § 82, effective May 31. L. 2022: (2)(a) amended, (SB 22-013), ch.
2, p. 93, § 131, effective February 25. L. 2023: Entire section
repealed, (HB 23-1121), ch. 35, p. 119, § 3, effective August 7.
39-22-308. Credit allowed for purchase
of Colorado coal.
(1) For
income tax years commencing on or after January 1, 1989, but prior to January
1, 2005, there shall be allowed, as a credit against any taxes imposed on
income by this part 3, an amount equal to one dollar per ton for each ton of Colorado
coal purchased by and delivered to the taxpayer in excess of the number of tons
of Colorado coal purchased by and delivered to the taxpayer in the income tax
year commencing on or after January 1, 1988. If the amount of the tax credit
allowed by this section exceeds the amount of income tax due for the taxable
year, the excess amount may be carried forward as a credit against subsequent
years' income tax liability for a period not exceeding three years and shall be
applied first to the earliest income tax years possible. For purposes of this
section, "Colorado coal" means coal mined in Colorado, as certified
by the producer of such coal.
(2) (a)
Any public or private corporate purchaser who is not liable for or subject to
state income tax during the year the coal is purchased and who is otherwise
eligible for the credit allowed by subsection (1) of this section may by
written agreement transfer such credit to the producer of the coal. Said
producer shall be allowed, as a credit against any taxes imposed on income by
this part 3, an amount equal to the amount of credit for which the purchaser
would otherwise have been eligible pursuant to subsection (1) of this section.
Any such credit shall be subject to any limitations established in subsection
(1) of this section. Said producer shall reduce the purchase price of said coal
to such corporate purchaser by the amount of the credit so transferred.
(b) The
corporate purchaser shall file a copy of the written agreement with the
department of revenue. The agreement shall contain, but shall not be limited
to, terms stipulating the number of tons of Colorado coal purchased by the
corporate purchaser in the 1988 base income tax year and the number of tons of
Colorado coal over and above that base amount which is being purchased pursuant
to the agreement.
Source:
L. 89: Entire
section added, p. 1507, § 1, effective April 12. L. 91: (1) amended, p.
1983, § 1, effective April 1.
39-22-309. Tax credit for investment in
technologies for recycling plastics. (Repealed)
Source:
L. 89: Entire
section added, p. 1182, § 4, effective July 1. L. 92: (1) amended, p.
2273, § 11, effective April 16. L. 2004: Entire section repealed, p.
211, § 35, effective August 4.
39-22-310. Legislative declaration -
statutory interpretation and construction.
It is the
intent of the general assembly that, in interpreting or construing the
provisions of this part 3, statutes shall be given the strongest weight, then
rules and regulations, and then the administrative interpretation or
construction of said provisions by the executive director or the department of
revenue; the administrative interpretation shall be given no greater weight
than the interpretation of the taxpayer regardless of how long-standing such
administrative interpretation or construction might be, unless such
administrative interpretation or construction is set forth in rules and
regulations promulgated by the executive director.
Source:
L. 89: Entire
section added, p. 1500, § 3, effective July 1, 1990.
SUBPART
2
S
CORPORATIONS
39-22-320. Short title - citation.
This
subpart 2 shall be comprised of sections 39-22-320 to 39-22-330 and may be
cited as subpart 2. This subpart 2 shall be known and may be cited as the
"Colorado S Corporation Income Tax Act".
Source:
L. 92: Entire
section added, p. 2260, § 1, effective April 16.
ANNOTATION
Law reviews. For
article, "Choice of Entities in Colorado", see 23 Colo. Law. 293
(1994).
39-22-321. Definitions.
For the
purposes of this subpart 2, unless the context otherwise requires:
(1)
"Income attributable to the state" means items of income, loss,
deduction, or credit of the S corporation apportioned or allocated to this
state pursuant to section 39-22-303.5, 39-22-303.6, or 39-22-303.7.
(2)
"Income not attributable to the state" means all items of income,
loss, deduction, or credit of the S corporation other than income attributable
to the state.
(3)
"Post-termination transition period" means that period defined in
section 1377 (b)(1) of the internal revenue code.
(4)
"Pro rata share" means the portion of any item attributable to an S
corporation shareholder for a taxable period determined in the manner provided
in, and subject to any election made under, section 1377 (a) or 1362 (e), as
the case may be, of the internal revenue code.
(5)
"Taxable period" means any taxable year or portion of a taxable year
during which a corporation is an S corporation.
Source:
L. 92: Entire
section added, p. 2260, § 1, effective April 16. L. 2008: (1) amended,
p. 966, § 9, effective January 1, 2009. L. 2019: (1) amended, (SB
19-241), ch. 390, p. 3477, § 54, effective August 2.
39-22-322. Taxation of an S corporation
and its shareholders.
(1) An
S corporation shall not be subject to the tax imposed by this article.
(2) For
the purposes of section 39-22-104, each shareholder's pro rata share of the S
corporation's income attributable to the state and each resident shareholder's
pro rata share of the S corporation's income not attributable to the state, all
as modified pursuant to section 39-22-323, shall be taken into account by the
shareholder in the manner provided in section 1366 of the internal revenue
code.
(3) For
the purposes of determining the amounts taken into account by the shareholders
of an S corporation pursuant to subsection (2) of this section, the amount of
any tax imposed on the S corporation under the internal revenue code shall
proportionately reduce the S corporation's income attributable to the state and
income not attributable to the state.
Source:
L. 92: Entire
section added, p. 2261, § 1, effective April 16. L. 2018: (2) amended,
(HB 18-1375), ch. 274, p. 1722, § 80, effective May 29.
39-22-323. Modification and
characterization of income.
(1) An
S corporation's income attributable to the state shall, for the purposes of
section 39-22-322, be subject to the modifications provided in section
39-22-304.
(2)
Each resident shareholder's pro rata share of the S corporation's income not
attributable to the state shall, for the purposes of section 39-22-322 (2), be
subject to the modifications provided in section 39-22-104.
(3) The
character of any S corporation item taken into account by a shareholder of an S
corporation pursuant to section 39-22-322 (2) shall be determined as if such
item were received or incurred by the S corporation and not its shareholder.
Source:
L. 92: Entire
section added, p. 2261, § 1, effective April 16.
39-22-324. Basis and adjustments.
The basis
in the hands of a shareholder of an S corporation in the stock of the S
corporation and any indebtedness of the S corporation to the shareholder shall
be determined in the manner provided under the internal revenue code.
Source:
L. 92: Entire
section added, p. 2261, § 1, effective April 16.
39-22-325. Carryforwards and carrybacks
- loss limitation.
(1) Carryforwards
and carrybacks to and from taxable periods of an S corporation shall be
restricted in the manner provided in section 1371 (b) of the internal revenue
code.
(2) The
aggregate amount of losses or deductions of an S corporation taken into account
by a shareholder of the S corporation for a taxable period pursuant to section
39-22-323 (2) shall not exceed such shareholder's combined adjusted basis, as
determined pursuant to section 39-22-324, in the stock of the S corporation and
any indebtedness of the S corporation to such shareholder.
(3) Any
loss or deduction of an S corporation which is disallowed for a taxable period
pursuant to subsection (2) of this section shall be treated as incurred by the
corporation in the succeeding taxable period with respect to that shareholder.
(4) (a)
Any loss or deduction of an S corporation which is disallowed pursuant to
subsection (2) of this section for the corporation's last taxable period as an
S corporation shall be treated as incurred by a shareholder on the last day of
any post-termination transition period.
(b) The
aggregate amount of losses and deductions taken into account by a shareholder
pursuant to paragraph (a) of this subsection (4) shall not exceed such
shareholder's adjusted basis in the stock of the corporation, as such adjusted
basis is determined pursuant to section 39-22-324 at the close of the last day
of any post-termination transition period and without regard to this subsection
(4).
Source:
L. 92: Entire
section added, p. 2261, § 1, effective April 16.
39-22-326. Part-year residence.
For the
purposes of this subpart 2, if a shareholder of an S corporation is both a
resident and a nonresident of this state during any taxable period, such
shareholder's pro rata share of the S corporation's income attributable to the
state and income not attributable to the state for the taxable period shall be
further prorated between such shareholder's periods of residence and
nonresidence during the taxable period, in accordance with the number of days
in each period.
Source:
L. 92: Entire
section added, p. 2262, § 1, effective April 16.
39-22-327. Distributions.
A
distribution made by an S corporation with respect to its stock to a
shareholder shall be taken into account by such shareholder for the purposes of
section 39-22-104 to the extent that the distribution is determined to be
taxable under the internal revenue code.
Source:
L. 92: Entire
section added, p. 2262, § 1, effective April 16.
39-22-328. Returns - repeal. (Repealed)
Source:
L. 92: Entire
section added, p. 2262, § 1, effective April 16. L. 2023: (2) added by
revision, (HB 23-1277), ch. 290, p. 1755, §§ 7, 9.
Editor's
note: Subsection
(2) provided for the repeal of this section, effective January 1, 2024. (See L.
2023, p. 1755.)
39-22-329. Tax credits.
(1) For
the purposes of section 39-22-108, each resident shareholder shall be
considered to have paid a tax imposed on each resident shareholder in an amount
equal to each resident shareholder's pro rata share of any net income tax paid
by the S corporation to a state which does not measure the income of
shareholders of an S corporation by reference to the income of the S
corporation. For the purposes of this section, the term "net income
tax" means any tax imposed on, or measured by, an S corporation's net
income.
(2)
Each shareholder of an S corporation shall be allowed a credit against the tax
imposed by section 39-22-104 in an amount equal to each shareholder's pro rata
share of the tax credits described in sections 39-30-103.5 to 39-30-105.6
earned by the S corporation.
Source:
L. 92: Entire
section added, p. 2263, § 1, effective April 16.
39-22-330. Uniformity of application
and construction.
This
subpart 2 shall be so applied and construed as to effectuate its general
purpose to make uniform the law with respect to the subject of this subpart 2
among those states which enact the model S corporation income tax act.
Source:
L. 92: Entire
section added, p. 2263, § 1, effective April 16.
SUBPART
3
SALT
PARITY ACT
39-22-340. Short title - citation.
This
subpart 3 is comprised of sections 39-22-340 to 39-22-347 and may be cited as
subpart 3. This subpart 3 shall be known and may be cited as the "SALT
Parity Act".
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1801, § 1, effective June 23. L.
2024: Entire section amended, (HB 24-1450), ch. 490, p. 3424, § 77,
effective August 7.
39-22-341. Legislative declaration.
The
general assembly hereby finds and declares that the deductibility of state
income taxes should be the same for C corporations, S corporations, and
partnerships.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1801, § 1, effective June 23.
39-22-342. Definitions.
As used in
this subpart 3, unless the context otherwise requires:
(1)
"Electing pass-through entity" means, with respect to a taxable
period, an S corporation or partnership that has made the election under
section 39-22-343 with respect to the taxable period.
(2)
"Electing pass-through entity owner" means, with respect to an S
corporation, a shareholder of the S corporation and, with respect to a
partnership, a partner in the partnership; except that a partner does not
include a C corporation that is unitary with the partnership.
(3)
"Income attributable to the state" means, with respect to an S
corporation, the portion of the items of income, gain, loss, or deduction of
the S corporation apportioned or allocated to this state in accordance with the
provisions of section 39-22-321 (1) and (2), and, with respect to a
partnership, the portion of the income, gain, loss, deduction, or credit of the
partnership derived from sources within Colorado determined in accordance with
the provisions of section 39-22-203.
(4)
"Income not attributable to the state" means all items of income,
gain, loss, or deduction of an electing pass-through entity other than income
attributable to the state.
(5)
"Resident electing pass-through entity owner" means an electing
pass-through entity owner that is a resident of Colorado as defined in section
39-22-103 (6), (7), (8), (9), and (10).
(6)
"Taxable period" means any taxable year or portion of a taxable year
during which a corporation is an S corporation or a noncorporate entity is a
partnership.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1801, § 1, effective June 23.
39-22-343. Election.
(1) (a)
Notwithstanding sections 39-22-201, 39-22-302, and 39-22-322, and except as
provided in subsection (2) of this section, for income tax years commencing on
or after January 1, 2018, an S corporation or partnership may annually elect to
be subject to tax at the entity level for the taxable period.
(b)
Except as set forth in subsection (1)(c)(I) of this section, the S corporation
or partnership shall make the election on the return filed by such S
corporation or partnership under section 39-22-601. The filing of a return
filed under section 39-22-601 or subsection (1)(c)(I) of this section is
binding on all electing pass-through entity owners.
(c) (I)
For income tax years commencing on or after January 1, 2018, but prior to
January 1, 2022, the S corporation or partnership must make the election on or
after September 1, 2023, but before July 1, 2024, in a composite amended tax
return for all of the years for which the election is made that is filed on
behalf of the S corporation or partnership and all of the electing pass-through
entity owners. The department of revenue shall establish the return, which
shall not include any changes to the past returns other than those that are
directly related to the election. The provisions of sections 39-21-107 (2) and
39-21-108 (1) shall not apply to the payment or refund of the tax made pursuant
to the return.
(II)
Notwithstanding any other provision of law, if an S corporation or partnership
files a return specified in subsection (1)(c)(I) of this section, neither the S
corporation or partnership nor the electing pass-through entity owners shall
incur any penalties for filing late nor owe interest on such amounts, and the
department shall not be required to pay penalties or interest on any amounts
owed to the taxpayers.
(III)
Notwithstanding the dates provided in subsection (1)(c)(I) of this section, the
department shall have one year from the date the composite amended tax return
is filed to review the return and make a written proposed adjustment in
accordance with section 39-21-103. The department must make any assessment
within one year after a final determination is made under section 39-21-103
(8). Any final determination made as specified in this subsection (1)(c)(III)
may be enforced at any time within six years from the date of the final
determination.
(2) The
election allowed under subsection (1) of this section is only allowed in an
income tax year where there is a limitation on the deductions allowed to
individuals under section 164 of the internal revenue code.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1802, § 1, effective June 23. L.
2022: (1) amended, (SB 22-124), ch. 164, p. 1018, § 2, effective May 16.
39-22-344. Imposition of tax.
(1)
With respect to any taxable period for which it has made the election under
section 39-22-343, an electing pass-through entity is subject to a tax in an
amount equal to the tax rate set forth in section 39-22-301 for the applicable
income tax year multiplied by the sum of the following, all as determined
pursuant to sections 39-22-202, 39-22-203, 39-22-322, and 39-22-323:
(a)
Each electing pass-through entity owner's pro rata or distributive share of the
electing pass-through entity's income attributable to the state; and
(b)
Each resident electing pass-through entity owner's pro rata or distributive
share of the electing pass-through entity's income not attributable to the
state.
(2) An
electing pass-through entity is treated as a corporation under section
39-22-606 with respect to the tax imposed under this subpart 3; except that the
requirement to make estimated payments under section 39-22-606 does not apply
for income tax years commencing prior to January 1, 2023.
(3) Any
credit allowed pursuant to this article 22 that is attributable to the
activities of an electing pass-through entity in the taxable year is passed
through to and must be claimed by the electing pass-through entity owner.
(4) The
executive director of the department of revenue may promulgate rules in
accordance with article 4 of title 24 to require or permit an electing
pass-through entity to make returns, set forth information, or furnish copies
of information as required in section 39-22-601 (2.5)(a) through (2.5)(c) and
(5)(a) through (5)(c) as is necessary to execute the provisions of this subpart
3. Notwithstanding the specificity of the foregoing, the executive director may
promulgate such other rules as are, in the executive director's view, necessary
or expedient in enforcing the provisions of this subpart 3.
(5) The
provisions of section 39-22-601 (2.7)(d) and (5.5)(d) are not applicable to an
electing pass-through entity.
(6) The
provisions of article 21 of this title 39 regarding the collection,
administration, and enforcement of tax is applicable to the tax due under this
section, and, notwithstanding the provisions of sections 39-22-201, 39-22-302,
and 39-22-322, an electing pass-through entity is a taxpayer.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1802, § 1, effective June 23. L.
2022: IP(1), (2), and (3) amended, (SB 22-124), ch. 164, p. 1019, § 3,
effective May 16. L. 2023: (5) amended, (HB 23-1277), ch. 290, p. 1755,
§ 8, effective January 1, 2024.
39-22-345. Owner exclusion.
The basis
in the hands of an electing pass-through entity owner in the interest in the
partnership or the stock or indebtedness in the S corporation is determined as
if the election under section 39-22-343 had not been made.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1803, § 1, effective June 23. L.
2022: Entire section amended, (SB 22-124), ch. 164, p. 1020, § 4, effective
May 16.
39-22-346. Credit for tax paid in other
states.
For purposes
of the resident pass-through entity owners, the credit allowed under section
39-22-108 is calculated without regard to the credit allowed under section
39-22-347.
Source:
L. 2021: Entire
subpart added, (HB 21-1327), ch. 300, p. 1804, § 1, effective June 23. L.
2022: Entire section amended, (SB 22-124), ch. 164, p. 1020, § 5, effective
May 16.
39-22-347. Credit for electing
pass-through entity owner - tax preference performance statement - legislative
declaration.
(1) (a)
The general assembly hereby finds and declares that the purpose of this tax
credit is to:
(I)
Ensure the state does not have a net tax revenue change while accomplishing the
purpose set forth in section 39-22-341; and
(II)
Replace a related state income tax deduction.
(b) (I)
Notwithstanding section 39-21-304 (2), the purpose of the tax expenditure
created in this section is to avoid double taxation of income on electing
pass-through entity owners.
(II)
The general assembly and the state auditor shall measure the effectiveness of
the credit created in this section in achieving the purpose specified in
subsection (1)(b)(I) of this section based on whether the amount of the credit
is equal to the amount of the tax revenue collected under section 39-22-344.
(2)
Subject to the limitations set forth in subsection (3) of this section, for
income tax years commencing on or after January 1, 2018, an electing
pass-through entity owner is allowed a credit against the tax imposed by this
article 22 that is an amount equal to the share of the tax imposed pursuant to
section 39-22-344 (1) on the electing pass-through entity with respect to the
electing pass-through entity owner's income.
(3) No
credit is allowed to an electing pass-through entity owner under subsection (2)
of this section unless the electing pass-through entity paid the tax imposed
under this article 22 and provided sufficient information on the electing
pass-through entity tax return, as prescribed by the department of revenue, to
identify that electing pass-through entity owner.
(4) Any
amount of the credit allowed by this section that exceeds the electing
pass-through entity owner's income taxes due is refunded to the electing
pass-through entity owner.
Source:
L. 2022: Entire
section added, (SB 22-124), ch. 164, p. 1020, § 6, effective May 16.
PART
4
ESTATES
AND TRUSTS
39-22-401. Income of a resident estate
or trust for purposes of Colorado income tax.
(1) The
income of a resident estate or trust subject to the tax imposed by this article
shall be its federal taxable income as determined pursuant to section 63 of the
internal revenue code with the following modifications:
(a)
There shall be added or subtracted the modifications described in section
39-22-104 to the extent such items are excluded from federal distributable net
income of the estate or trust.
(b)
There shall be added or subtracted the share of the estate or trust in the
Colorado fiduciary adjustment determined under section 39-22-402.
Source:
L. 64: R&RE,
pp. 656, 771, §§ 14, 1. C.R.S. 1963: § 138-1-45. L. 78: (1)(a)
amended, p. 485, § 8, effective May 5. L. 87: Entire section R&RE,
p. 1444, § 12, effective June 22.
39-22-402. Share of a resident estate,
trust, or beneficiary in Colorado fiduciary adjustments.
(1) (a)
An adjustment shall be made in determining the federal taxable income subject
to tax by Colorado of a resident estate or trust under section 39-22-401, or
the federal taxable income subject to tax by Colorado of a resident beneficiary
of any estate or trust under section 39-22-104, in the amount of the share of
each in the Colorado fiduciary adjustment as determined in this section.
(b)
Repealed.
(2) The
Colorado fiduciary adjustment shall be the net amount of the modifications
described in section 39-22-104, except to the extent such items are excluded
from federal distributable net income of the estate or trust.
(3) (a)
The respective shares of an estate or trust and its beneficiaries, including,
solely for the purpose of this allocation, nonresident beneficiaries, in the
Colorado fiduciary adjustment shall be in proportion to their respective shares
of federal distributable net income of the estate or trust.
(b) If
the estate or trust has no federal distributable net income for the taxable
year, the share of each beneficiary in the Colorado fiduciary adjustment shall
be in proportion to his share of the estate or trust income for such year,
under local law or the governing instrument, which is required to be
distributed currently and any other amounts of such income distributed in such
year. Any balance of the Colorado fiduciary adjustment shall be allocated to
the estate or trust.
(4) The
executive director may, by regulation, establish such other method of
determining to whom the items comprising the fiduciary adjustment shall be
attributed, as may be appropriate and equitable. Such method may be used by the
fiduciary in his discretion whenever the allocation of the fiduciary
adjustment, pursuant to subsection (3) of this section, would result in an
inequity which is substantial both in amount and in relation to the amount of
the fiduciary adjustment.
Source:
L. 64: R&RE,
p. 772, § 1. C.R.S. 1963: § 138-1-46. L. 67: p. 850, §§ 1, 2. L.
77: (2) amended, p. 1784, § 3, effective May 19. L. 87: (1)(a) and
(2) amended and (1)(b) repealed, pp. 1444, 1457, §§ 13, 31, effective June 22.
39-22-403. Income of a nonresident
estate or trust subject to income tax.
(1) In
the case of a nonresident estate or trust, the tax imposed by section 39-22-104
shall be apportioned in the ratio of the Colorado-source federal taxable income
to the total federal taxable income, both modified as provided in section
39-22-104.
(2)
Colorado-source federal taxable income of an estate or trust means:
(a) Its
share of the Colorado-source federal distributable net income as determined in
section 39-22-404; and
(b) Its
share of any Colorado-source income, gain, loss, and deduction recognized for
federal income tax purposes but excluded from the definition of federal
distributable net income of the estate or trust as determined under section
39-22-109, as in the case of a nonresident individual, and modified as provided
in section 39-22-104.
Source:
L. 64: R&RE,
p. 773, § 1. C.R.S. 1963: § 138-1-47. L. 87: IP(1), (1)(b), and
(1)(c) amended and (1)(d) repealed, pp. 1444, 1457, §§ 14, 31, effective June
22. L. 88: Entire section R&RE, p. 1314, § 8, effective May 29.
39-22-404. Share of a nonresident
estate, trust, or beneficiary in income from sources within Colorado.
(1) The
share of a nonresident estate or trust under section 39-22-403 and the share of
a nonresident beneficiary of any estate or trust under section 39-22-109 in
estate or trust income, gain, loss, and deduction from sources within Colorado
shall be determined as follows:
(a)
There shall be determined the items of income, gain, loss, and deduction
derived from sources within Colorado which enter into the definition of federal
distributable net income of the estate or trust for the taxable year, including
such items from another estate or trust of which the first estate or trust is a
beneficiary. Such determination of source shall be made in accordance with the
applicable rules of section 39-22-109 as in the case of a nonresident
individual.
(b)
There shall be added or subtracted the modifications described in section
39-22-104, to the extent relating to items of income, gain, loss, and
deduction, derived from sources within Colorado, which enter into the
definition of federal distributable net income, including such items from
another estate or trust of which the first estate or trust is a beneficiary. No
modification shall be made under this paragraph (b) which has the effect of
duplicating an item already reflected in the definition of federal
distributable net income.
(c) (I)
The amounts determined under paragraphs (a) and (b) of this subsection (1)
shall be allocated among the estate or trust and its beneficiaries, including,
solely for the purpose of this allocation, resident beneficiaries, in
proportion to their respective shares of federal distributable net income.
(II)
The amounts so allocated shall have the same character under this article as
for federal income tax purposes.
(2) (a)
If the estate or trust has no federal distributable net income for the taxable
year, the share of each beneficiary, including, solely for the purpose of this
allocation, resident beneficiaries, in the net amount, determined under
paragraphs (a) and (b) of subsection (1) of this section, shall be in
proportion to his share of the estate or trust income for such year, under
local law or the governing instrument which is required to be distributed
currently and any other amounts of such income distributed in such year. Any
balance of such net amount shall be allocated to the estate or trust.
(b) The
executive director may, by regulation, establish such other method or methods
of determining the respective shares of the beneficiaries and of the estate or
trust in its income derived from sources within Colorado and in the
modifications related thereto as may be appropriate and equitable. Such method
may be used by the fiduciary in his discretion whenever the allocation of such
respective shares under subsection (1) of this section or paragraph (a) of this
subsection (2) would result in an inequity which is substantial both in amount
and in relation to the total amount of the modifications referred to in
paragraph (b) of subsection (1) of this section.
Source:
L. 64: R&RE,
p. 774, § 1. C.R.S. 1963: § 138-1-48. L. 87: IP(1), (1)(a),
(1)(b), (1)(c)(I), and (2) amended, p. 1445, § 15, effective June 22. L. 88:
IP(1), (1)(a), and (1)(b) amended, p. 1314, § 9, effective May 29.
39-22-405. Colorado exemption and
federal income tax modification of nonresident estate or trust. (Repealed)
Source:
L. 64: R&RE,
p. 775, § 1. C.R.S. 1963: § 138-1-49. L. 87: Entire section
repealed, p. 1457, § 31, effective June 22.
39-22-406. Special rule for
accumulation distributions. (Repealed)
Source:
L. 64: R&RE,
p. 775, § 1. C.R.S. 1963: § 138-1-50. L. 83: Entire section
repealed, p. 1515, § 11, effective January 1, 1984.
39-22-407. Accounting periods and
methods.
The
provisions of section 39-22-111 shall apply to trusts and estates to the extent
not inconsistent with sections 39-22-401 to 39-22-404.
Source:
L. 64: R&RE,
p. 775, § 1. C.R.S. 1963: § 138-1-51. L. 83: Entire section
amended, p. 1515, § 10, effective January 1, 1984. L. 87: Entire section
amended, p. 1446, § 16, effective June 22.
PART
5
SPECIAL
RULES
39-22-501. Taxation of regulated
investment companies.
(1) (a)
For purposes of this article, a "regulated investment company" shall
have the same meaning as set forth in section 851 of the internal revenue code.
(b) For
purposes of this article, the "net income" of a regulated investment
company in each year in which the corporation is taxed as a regulated
investment company for federal income tax purposes shall be the
"investment company taxable income" of such corporation, adjusted as
provided in section 39-22-304 (2) and (3).
(2) (a)
For purposes of this article, a "captive regulated investment
company" means a regulated investment company of which the shares or
beneficial interests are not regularly traded on an established securities
market and of which more than fifty percent of the voting power or value of the
beneficial interests or shares are owned or controlled, directly, indirectly,
or constructively, by a single entity that is:
(I)
Treated as an association taxable as a corporation under the internal revenue
code; and
(II)
Not exempt from federal income tax pursuant to the provisions of section 501
(a) of the internal revenue code.
(b) Any
voting stock in a regulated investment company that is held in a segregated
asset account of a life insurance corporation, as described in section 817 of
the internal revenue code, shall not be taken into account for purposes of
determining whether a regulated investment company is a captive regulated
investment company.
Source:
L. 64: R&RE,
p. 776, § 1. C.R.S. 1963: § 138-1-56. L. 2009: Entire section
amended, (HB 09-1093), ch. 75, p. 269, § 2, effective April 2.
Cross
references: For
the legislative declaration contained in the 2009 act amending this section,
see section 1 of chapter 75, Session Laws of Colorado 2009.
39-22-502. Adjustment to basis of
shares of regulated investment company. (Repealed)
Source:
L. 64: R&RE,
p. 777, § 1. C.R.S. 1963: § 138-1-57. L. 91: Entire section
repealed, p. 1986, § 1, effective April 20.
39-22-503. Taxation of real estate
investment trusts - definitions.
(1) (a)
For purposes of this article, a "real estate investment trust" shall
have the same meaning as set forth in section 856 of the internal revenue code.
(b) For
purposes of this article, the "net income" of a real estate
investment trust in each year in which the trust is taxed as a real estate
investment trust for federal income tax purposes shall be the "real estate
investment trust taxable income" of the trust as computed for federal
income tax purposes and adjusted as provided in section 39-22-304 (2) and (3).
(2) (a)
For purposes of this article, a "captive real estate investment
trust" means a real estate investment trust of which the shares or
beneficial interests are not regularly traded on an established securities
market and of which more than fifty percent of the voting power or value of the
beneficial interests or shares are owned or controlled, directly, indirectly,
or constructively, by a single entity that is:
(I)
Treated as an association taxable as a corporation under the internal revenue
code; and
(II)
Not exempt from federal income tax pursuant to the provisions of section 501
(a) of the internal revenue code.
(b) A
"captive real estate investment trust" shall not include a real
estate investment trust that is intended to be regularly traded on an
established securities market and that satisfies the requirements of section
856 (a)(5) and (a)(6) of the internal revenue code by reason of section 856
(h)(2) of the internal revenue code; except that, if such real estate
investment trust does not become regularly traded on an established securities
market within one year of the date on which it first becomes a real estate
investment trust, such real estate investment trust shall be deemed to be a
captive real estate investment trust.
(3) For
purposes of this section, the constructive ownership rules of section 318 (a)
of the internal revenue code, as modified by section 856 (d)(5) of the internal
revenue code, shall apply in determining the ownership of stock, assets, or net
profits of any person.
(4) For
purposes of this section, unless the context otherwise requires:
(a)
"Association taxable as a corporation under the internal revenue
code" shall not include:
(I) Any
real estate investment trust other than a captive real estate investment trust;
(II)
Any qualified real estate investment trust subsidiary other than a qualified
real estate investment trust subsidiary of a captive real estate investment
trust;
(III)
Any listed Australian property trust; or
(IV)
Any qualified foreign entity.
(b)
"Australian property trust" means an Australian unit trust registered
as a managed investment scheme under the Australian corporations act in which
the principal class of units is listed on a recognized stock exchange in Australia
and is regularly traded on an established securities market or an entity
organized as a trust, provided that a listed Australian property trust owns or
controls, directly or indirectly, seventy-five percent or more of the voting
power or value of the beneficial interests or shares of such trust.
(c)
"Qualified foreign entity" means a corporation, trust, association,
or partnership that is organized outside the laws of the United States and that
satisfies the following criteria:
(I) At least
seventy-five percent of the entity's total asset value at the close of its
taxable year is represented by real estate assets as defined in section 856
(c)(5)(B) of the internal revenue code, cash and cash equivalents, or United
States government securities;
(II)
The entity is not subject to tax on amounts distributed to its beneficial
owners or is exempt from entity-level taxation;
(III)
The entity distributes at least eighty-five percent of its taxable income, as
computed in the jurisdiction in which it is organized, to the holders of its
shares or certificates of beneficial interest on an annual basis;
(IV)
Not more than ten percent of the voting power or value in such entity is held,
directly, indirectly, or constructively, by a single entity or individual, or
the shares or beneficial interests of such entity are regularly traded on an
established securities market; and
(V) The
entity is organized in a country that has a tax treaty or agreement with the
United States.
(d)
"Qualified real estate investment trust subsidiary" has the same
meaning as set forth in section 856 (i) of the internal revenue code.
Source:
L. 64: R&RE,
p. 777, § 1. C.R.S. 1963: § 138-1-58. L. 91: Entire section
amended, p. 1986, § 2, effective April 20. L. 2009: Entire section
amended, (HB 09-1093), ch. 75, p. 269, § 3, effective April 2.
Cross
references: For
the legislative declaration contained in the 2009 act amending this section,
see section 1 of chapter 75, Session Laws of Colorado 2009.
39-22-504. Net operating losses.
(1) (a)
A net operating loss deduction shall be allowed in the same manner that it is
allowed under the internal revenue code except as otherwise provided in this
section. The amount of the net operating loss that may be carried forward and
carried back for Colorado income tax purposes shall be that portion of the
federal net operating loss allocated to Colorado under this article 22 in the
taxable year that the net operating loss is sustained.
(b) For
losses incurred after December 31, 2017, the eighty percent limitation set
forth in section 172 (a)(2) of the internal revenue code shall apply without
regard to the amendments made in section 2303 of the March 2020
"Coronavirus Aid, Relief, and Economic Security Act", Pub.L. 116-136.
(2)
With respect to individuals, estates, and trusts:
(a) A
net operating loss incurred in a taxable year beginning prior to January 1,
1987, may be carried forward the same number of years a federal net operating
loss may be carried forward. Such net operating losses may not be carried back
to an earlier tax year.
(b) Net
operating losses incurred in taxable years beginning on or after January 1,
1987, may be carried back to the same years as is a federal net operating loss
incurred in such year; except that no such loss may be carried to a taxable
year beginning on or after January 1, 1987. Such losses may not be carried
forward to subsequent tax years.
(3) (a)
Net operating losses of corporations generated in income tax years commencing
before January 1, 2021, may be carried forward for the same number of years as
allowed for a federal net operating loss. Net operating losses of corporations
may not be carried back to an earlier tax year.
(b) Net
operating losses of corporations generated in income tax years commencing on or
after January 1, 2021, may be carried forward for twenty years. Net operating
losses of corporations may not be carried back to an earlier tax year.
(4) If
a financial institution suffers a net operating loss for any taxable year
beginning on or after January 1, 1984, and before January 1, 2021, the amount
of the unused net operating loss may be carried forward to each of the fifteen
years following the taxable year of such loss. For the purposes of this
subsection (4), "financial institution" means any institution to
which section 585 or 593 of the internal revenue code applies.
(5) No
corporation may carry forward a net operating loss to an income tax year
commencing prior to January 1, 2009, if, for such year, the corporation uses a
different method of allocating or apportioning income from the one it used in
the period in which the loss occurred, unless such different method is approved
by the executive director. A corporation may carry forward a net operating loss
to any income tax year commencing on or after January 1, 2009, regardless of
the method of allocating or apportioning income for such year.
(6) (a)
Notwithstanding any other provision of this section, the maximum amount of net
operating loss that a corporation may subtract from federal taxable income
pursuant to section 39-22-304 (3)(g) for a tax year commencing on or after
January 1, 2011, but prior to January 1, 2014, is two hundred fifty thousand
dollars.
(b) All
net operating losses may be carried forward one additional year for each tax
year that a corporation is prohibited pursuant to paragraph (a) of this
subsection (6) from subtracting a portion of such net operating losses from the
corporation's federal taxable income.
(c) An
amount equal to the amount of all net operating losses that a corporation is
prohibited pursuant to paragraph (a) of this subsection (6) from subtracting
from federal taxable income multiplied by a rate of interest equal to three and
one-quarter percent per annum for the period during which such net operating
losses are prohibited shall be added to the allowable net operating loss that
is carried forward by the corporation, and, for the purpose of section
39-22-304 (3)(g), shall be considered net operating loss.
Source:
L. 64: R&RE,
p. 777, § 1. C.R.S. 1963: § 138-1-59. L. 77: (5) added, p. 1795,
§ 2, effective May 26. L. 83: (1) amended and (2), (3), and (5)(a)
repealed, p. 2097, §§ 4, 5, effective January 1, 1984. L. 87: (6) added,
p. 1458, § 1, effective May 4; entire section R&RE, p. 1446, § 17,
effective June 22. L. 88: (5) added, p. 1315, § 10, effective May 29. L.
2008: (5) amended, p. 966, § 10, effective January 1, 2009. L. 2010:
(6) added, (HB 10-1199), ch. 13, p. 67, § 2, effective February 24. L. 2016:
(4) amended, (SB 16-189), ch. 210, p. 794, § 110, effective June 6. L. 2020:
(1) amended, (HB 20-1420), ch. 277, p. 1359, § 4, effective July 11; (3) and
(4) amended, (HB 20-1024), ch. 135, p. 588, § 2, effective September 14.
Editor's
note: House Bill
87-1243 adding subsection (6) was superseded by House Bill 87-1331 and included
in House Bill 87-1331 as (4).
Cross
references: (1)
For the short title ("Tax Fairness Act") in HB 20-1420, see section 1
of chapter 277, Session Laws of Colorado 2020.
(2) For the legislative
declaration in HB 20-1024, see section 1 of chapter 135, Session Laws of
Colorado 2020.
ANNOTATION
Section was available to
banks taxed under former C.R.S. 1963, § 138-1-55. In re Golden State Bank
v. Dolan, 37 Colo. App. 29, 543 P.2d 1307 (1975) (decided under former law).
39-22-504.5. Short title.
Sections
39-22-504.5 to 39-22-504.7 shall be known and may be cited as the "Medical
Savings Account Act of 1994".
Source:
L. 86: Entire
section added, p. 1121, § 1, effective June 23. L. 94: Entire section
amended, p. 2840, § 6, effective January 1, 1995.
39-22-504.6. Definitions.
As used in
sections 39-22-504.5 to 39-22-504.7, unless the context otherwise requires:
(1)
"Account administrator" means:
(a) A
state chartered bank, savings and loan association, credit union, or trust
company authorized to act as a fiduciary and under the supervision of the
financial institutions bureau of the United States department of commerce;
(b) A
national banking association, federal savings and loan association, or credit
union authorized to act as a fiduciary in this state;
(c) An
insurance company; or
(d) An
employer if such employer maintains a self-insured health plan meeting the
requirements of the federal "Employee Retirement Income Security Act of
1974", as amended.
(1.3)
"Account holder" means an employee on whose behalf a medical savings
account is established.
(2)
"Dependent child" means any person who is:
(a)
Under the age of twenty-one years;
(b)
Legally entitled to or the subject of a court order for the provision of proper
or necessary subsistence, education, medical care, or any other care necessary
for his or her health, guidance, or well-being and who is not otherwise
emancipated, self-supporting, married, or a member of the armed forces of the
United States; or
(c) So
mentally or physically incapacitated that he or she cannot provide for himself
or herself.
(2.4)
"Eligible medical expense" means any medical expense that is
deductible for purposes of section 213 (d) of the internal revenue code.
(2.5)
"Employee" means the individual for whose benefit a medical savings
account is established.
(2.6)
"Employer" means a person or entity employing one or more persons in
this state, excluding the federal government.
(3)
"Medical savings account" means an account established to pay the
eligible medical expenses of an account holder and his or her spouse and
dependent children, if any.
(3.5)
"Qualified higher deductible health plan" means a health coverage
policy, certificate, or contract that provides for the payment of covered
benefits that exceed the deductible, which shall be at least one thousand five
hundred dollars but no more than two thousand two hundred fifty dollars for
individual coverage or at least three thousand dollars but no more than four
thousand five hundred dollars for family coverage, and that is purchased by an
employer for the benefit of an employee who makes deposits into a medical
savings account.
(4)
(Deleted by amendment, L. 94, p. 2840, § 7, effective January 1, 1995.)
Source:
L. 86: Entire
section added, p. 1121, § 1, effective June 23. L. 88: (4) amended, p.
419, § 16, effective April 11. L. 89: (4) amended, p. 622, § 19,
effective July 1. L. 94: Entire section amended, p. 2840, § 7, effective
January 1, 1995. L. 2000: (3.5) amended, p. 172, § 2, effective January
1, 2001.
Cross
references: For
the federal "Employee Retirement Income Security Act of 1974", see
Pub.L. 93-406.
39-22-504.7. Medical savings accounts -
establishment - contributions - distributions - restrictions - taxation -
portability - repeal.
(1) (a)
Establishment of accounts. On and after January 1, 1995, and prior to
January 1, 2025, an employer may offer to establish medical savings accounts.
(b)
Prior to January 1, 2025, an employee on whose behalf a medical savings account
has not been established by his or her employer may establish such an account
on his or her own behalf.
(2) (a)
Each year an employer may contribute to an employee's medical savings account
an amount that does not exceed three thousand dollars.
(b) If
an employer establishes a medical savings account for an employee but
contributes less than the maximum set forth in paragraph (a) of this subsection
(2), the employee may contribute the difference in accordance with the
provisions of paragraph (d) of this subsection (2).
(c) An
employee who establishes his or her own medical savings account may contribute
to such account an amount that does not exceed the maximum set forth in
paragraph (a) of this subsection (2). Any such contribution is to be made in
accordance with the provisions of paragraph (d) of this subsection (2).
(d) Employee
contributions - pretax.
(I) All
employee contributions to medical savings accounts are made on a pretax basis,
pursuant to section 39-22-104.6. Such contributions are subject to the same
limitations as employer contributions.
(II) An
employee shall elect to make contributions to his or her medical savings
account by signing a written election. Such election is to be in the form
prescribed by the executive director of the department of revenue and is to be
signed prior to the date the employer withholds the first contribution.
(e) Employer
contributions - tax deduction. Prior to January 1, 2025, employer
contributions to employee medical savings accounts constitute a deduction from
the employer's federal taxable income, pursuant to sections 39-22-104 (4)(h)
and 39-22-304 (3)(k).
(3) Distributions.
(a) An
account holder shall submit documentation of eligible medical expenses paid
during the tax year to the account administrator, and the account administrator
shall reimburse the account holder for such expenses.
(b)
Moneys may be distributed from a medical savings account only for the purpose
of:
(I)
Reimbursing the eligible medical expenses of the account holder or his or her
spouse or dependent child;
(II) Cashing
out the balance in the account of a deceased account holder; or
(III)
(A) Cashing out an account holder's prior years' balance.
(B) An
account holder may withdraw the balance in his or her account for any reason if
such withdrawal occurs after the end of the year in which the moneys were
contributed; however, such distributed moneys are subject to state income tax
pursuant to subsection (6) of this section.
(4)
(Deleted by amendment, L. 94, p. 2841, § 8, effective January 1, 1995.)
(5) Restrictions.
An account holder may not use account moneys to fund a policy that covers the
deductible for a qualified higher deductible health plan, as defined in section
39-22-504.6 (3.5).
(6) Taxation
of account moneys.
(a)
Account moneys, including interest income, are not to be taxed as Colorado
adjusted gross income if they are:
(I) In
an employee's medical savings account; or
(II)
Withdrawn to pay eligible medical expenses.
(b)
Account moneys are to be taxed as Colorado adjusted gross income when such
moneys are withdrawn for purposes other than the payment of eligible medical
expenses.
(c)
Upon the death of the account holder, the account principal, as well as any
accumulated interest, is to be distributed to and taxed as part of the
decedent's estate, as provided by law.
(7) Portability.
An account holder is the owner of his or her medical savings account and may
change the account administrator of such account upon leaving the employ of his
or her employer.
(8) Repeal.
This section is repealed, effective December 31, 2028.
Source:
L. 86: Entire
section added, p. 1122, § 1, effective May 23. L. 94: Entire section
amended, p. 2841, § 8, effective January 1, 1995. L. 2024: (1) and
(2)(e) amended and (8) added, (HB 24-1036), ch. 373, p. 2527, § 10, effective
August 7.
Cross
references: (1)
For other provisions concerning adjustments to federal taxable income, see §
39-22-104.
(2) For the legislative
declaration in HB 24-1036, see section 1 of chapter 373, Session Laws of
Colorado 2024.
39-22-505. Oil and gas producers.
(Repealed)
Source:
L. 64: R&RE,
p. 778, § 1. C.R.S. 1963: § 138-1-60. L. 71: p. 1252, § 1. L.
77: Entire section repealed, p. 1855, § 13, effective January 1, 1978.
39-22-506. Tentative carry-back
adjustment - application - allowance. (Repealed)
Source:
L. 67: p. 851, §§
1, 2. C.R.S. 1963: § 138-1-61. L. 83: Entire section repealed, p.
2097, § 5, effective January 1, 1984.
39-22-507. Credits against tax -
employer expenses - work incentive programs. (Repealed)
Source:
L. 76: Entire
section added, p. 781, § 1, effective May 10. L. 78: Entire section
repealed, p. 275, § 101, effective May 23.
39-22-507.5. Credits against tax -
investment in certain property - repeal.
(1)
Except as otherwise provided in this section, there shall be allowed to any
person as a credit against the tax imposed by this article 22, for income tax
years commencing on or after January 1, 1979, but prior to January 1, 2023, an
amount equal to the total of:
(a)
Investment tax credit carryovers claimed by such person for such taxable year;
(b) Ten
percent of that part of the credit allowed for the same income tax year by
section 38 of the internal revenue code, as determined under the provisions of
section 46 of the internal revenue code, without regard to the limitations
imposed by said section 38, to the extent such part of such credit is
determined by reference to property which is used in Colorado; and
(c)
Investment tax credit carrybacks claimed by such person for such taxable year.
(1.5)
For taxable years beginning on or after January 1, 1987, the provisions of
paragraph (b) of subsection (1) of this section shall apply only with respect
to taxes imposed by part 3 of this article.
(2) The
executive director shall promulgate regulations which will prescribe the extent
to which property must be used in Colorado to qualify for the credit allowed
under the provisions of subsection (1) of this section, which regulations shall
include a method or methods of determining what portion of the property shall
qualify in the case of property which is used both within and without Colorado.
(3) The
credit allowed by this section for any income tax year shall not exceed:
(a) The
taxpayer's actual tax liability for the income tax year to the extent such
liability does not exceed five thousand dollars; plus
(b)
Twenty-five percent of that portion of said tax liability for the income tax
year which exceeds five thousand dollars.
(4)
Repealed.
(5) In
the case of a "controlled group of corporations", as defined in
section 1563 (a) of the internal revenue code, the five thousand dollars
specified in subsection (3) of this section shall be apportioned among the
members of the controlled group as they may elect. The election shall apply to
the income tax year of the members of the controlled group ending with or
including a common December 31. Should such members fail to agree on an
allocation of the five thousand dollars, said five thousand dollars shall be
divided equally among all members of the controlled group.
(6) In
the case of a regulated investment company or a real estate investment trust,
the five thousand dollars referred to in subsection (3) of this section shall
be reduced to an amount which shall be five thousand dollars multiplied by the
taxable income for the income tax year and divided by the taxable income for
the income tax year plus the amount of the deduction for dividends paid.
(7) If
the amount of the credit allowed by paragraph (b) of subsection (1) of this
section exceeds the amount of the limitation imposed by subsection (3) of this
section reduced by the credit allowed by paragraph (a) of subsection (1) of
this section for any income tax year, referred to in this subsection (7) as the
"unused credit year", such excess shall be:
(a) An
investment tax credit carryback to each of the three income tax years preceding
the unused credit year; except that no credit shall be carried back to an
income tax year commencing prior to January 1, 1979; and
(b) An
investment tax credit carryover to each of the seven income tax years following
the unused credit year.
(8) No
carryover or carryback of unused investment credit will be allowed in the case
of a taxable cooperative as defined in section 1381 (a) of the internal revenue
code.
(9) (a)
For any income tax year beginning on or after January 1, 1979, if any taxpayer
is required to redetermine the credit allowed by section 38 of the internal
revenue code due to the provisions of section 47 of the internal revenue code,
such taxpayer must redetermine the credit allowed by subsection (1) of this
section for the same income tax year. If the redetermination results in a
reduction of the credit allowed by this section for the income tax year or for
any income tax year to which the credit was carried back or carried forward,
the reduction shall constitute an increase in the tax imposed by this article
for the income tax year during which the disposition or reclassification of the
nature of the property occurs, and the amount of any unused investment tax
credit carryback or carryover must be redetermined as appropriate. The increase
in tax shall not be included as tax liability for the purposes of subsection
(3) of this section.
(b) If,
during any income tax year which commences on or after May 26, 1983,
"section 38 property" which was first placed in service by the
taxpayer in a taxable year beginning on or after January 1, 1982, is disposed
of by or otherwise ceases to be such property with respect to the taxpayer
before the close of the property's recapture period, as determined for federal
income tax purposes, the credit allowed by this section and the decrease, if
any, in the investment tax credit carryback or carryover with respect to the
property shall be redetermined in accordance with the recapture percentage
table contained in:
(I)
Section 47 (a) of the internal revenue code, as it existed immediately prior to
the enactment of the federal "Revenue Reconciliation Act of 1990",
for such property which was disposed of by or otherwise ceased to be such
property with respect to the taxpayer prior to January 1, 1991; or
(II)
Section 50 (a) of the internal revenue code for such property which is disposed
of by or otherwise ceases to be such property with respect to the taxpayer on
or after January 1, 1991.
(10) and
(11) Repealed.
(12) In
lieu of the amount of the investment tax credit allowed by subsection (1) of
this section, a person who has invested in property used in an enterprise zone,
as designated pursuant to section 39-30-103, shall be allowed a credit in the
amount designated in section 39-30-104, subject to the terms and conditions of
that section.
(13)
This section is repealed, effective July 1, 2031.
Source:
L. 79: Entire
section added, p. 1441, § 28, effective July 3. L. 80: (10) added, p.
724, § 18, effective May 1. L. 81: (11) added, p. 1871, § 3, effective
June 29. L. 82: (1)(b) amended, p. 565, § 1, effective March 17. L.
83: (9) amended, p. 1514, § 8, effective May 26. L. 86: (1)(b)
amended, p. 1124, § 1, effective April 3; (12) added, p. 1142, § 2, effective
July 1. L. 87: (1)(b), (5), and (8) amended, (1.5) added, and (4), (10),
and (11) repealed, pp. 1447, 1457, §§ 18, 31, effective June 22. L. 91:
(1)(b) and (9)(b) amended, p. 1987, § 5, effective April 20. L. 2004:
(3)(a) and (9)(a) amended, p. 211, § 36, effective August 4. L. 2007:
(3)(a) and (9)(a) amended, p. 352, § 7, effective August 3. L. 2022:
IP(1) amended and (13) added, (HB 22-1025), ch. 145, p. 946, § 6, effective
August 10.
Cross
references: For
the federal "Revenue Reconciliation Act of 1990", see Pub.L. 101-508.
39-22-507.6. Credits against corporate
tax - investment in certain property - repeal.
(1)
Except as otherwise provided in this section, there shall be allowed to any
person as a credit against the tax imposed by part 3 of this article 22, for
income tax years commencing on or after January 1, 1988, but prior to January
1, 2023, an amount equal to the total of:
(a)
Investment tax credit carryovers claimed by such person for such taxable year;
and
(b) Ten
percent of that part of the credit that would have been allowed for the same
income tax year by section 38 of the internal revenue code, as determined under
the provisions of subsection (a) of section 46 of the internal revenue code
without regard to the limitations imposed by said section 38, had section 49 of
the internal revenue code not been enacted, to the extent such part of such
credit is determined by reference to property which is used in Colorado. The
references in this paragraph (b) to sections 38, 46, and 49 of the internal
revenue code mean sections 38, 46, and 49 of the internal revenue code as they
existed immediately prior to the enactment of the federal "Revenue
Reconciliation Act of 1990".
(2) The
executive director shall promulgate regulations which will prescribe the extent
to which property must be used in Colorado to qualify for the credit allowed
under the provisions of subsection (1) of this section, which regulations shall
include a method or methods of determining what portion of the property shall
qualify in the case of property which is used both within and without Colorado.
(3) The
credit allowed by this section for any income tax year shall not exceed the
taxpayer's actual tax liability for the income tax year to the extent that the
liability does not exceed one thousand dollars.
(4) In
the case of a "controlled group of corporations", as defined in
section 1563 (a) of the internal revenue code, the one thousand dollars
specified in subsection (3) of this section shall be apportioned among the
members of the controlled group as they may elect. The election shall apply to
the income tax year of the members of the controlled group ending with or
including a common December 31. Should such members fail to agree on an
allocation of the one thousand dollars, said one thousand dollars shall be
divided equally among all members of the controlled group.
(5) If
the amount of the credit allowed by paragraph (b) of subsection (1) of this
section exceeds the amount of the limitation imposed by subsection (3) of this
section reduced by the credit allowed by paragraph (a) of subsection (1) of
this section for any income tax year, referred to in this subsection (5) as the
"unused credit year", such excess shall be an investment tax credit
carryover to each of the three income tax years following the unused credit
year.
(6) The
limitations on the credits allowed by this section shall be reduced by any
credit allowed by section 39-22-507.5 for the same tax year.
(7)
This section is repealed, effective July 1, 2027.
Source:
L. 87: Entire
section added, p. 1447, § 19, effective June 22. L. 91: (1)(b) amended,
p. 1988, § 6, effective April 20. L. 2007: (3) amended, p. 352, § 8,
effective August 3. L. 2022: IP(1) amended and (7) added, (HB 22-1025),
ch. 145, p. 946, § 7, effective August 10.
39-22-508. Credit for property taxes
attributable to pollution control property. (Repealed)
Source:
L. 78: Entire
section added, p. 470, § 4, effective July 1. L. 79: Entire section
amended and (5) added, pp. 1454, 1456, §§ 1, 4, effective June 22. L. 81:
(4) amended and (5) R&RE, p. 1872, §§ 7, 8, effective June 29. L. 96:
(4) repealed, p. 1242, § 102, effective August 7. L. 2004: Entire
section repealed, p. 212, § 37, effective August 4.
39-22-508.1. Short title. (Repealed)
Source:
L. 78: Entire
section added, p. 497, § 1, effective July 1. L. 79: Entire section
amended, p. 1442, § 29, effective July 3. L. 2007: Entire section
repealed, p. 353, § 11, effective August 3.
39-22-508.2. Definitions - construction
of terms. (Repealed)
Source:
L. 78: Entire
section added, p. 497, § 1, effective July 1; (3)(b) amended, p. 275, § 102,
effective May 23 L. 79: (3)(b) and (5)(b) amended, p. 1443, § 30,
effective July 3. L. 89: (2)(c) added, p. 1522, § 6, effective June 7. L.
90: (7) amended, p. 455, § 35, effective April 18. L. 92: IP(2)(c)
amended, p. 2220, § 2, effective May 29. L. 96: IP(2)(c) and (2)(c)(I)
amended, p. 1130, § 6, effective July 1. L. 2007: Entire section
repealed, p. 353, § 11, effective August 3.
39-22-508.3. Special credit available -
new business facility - new employees. (Repealed)
Source:
L. 78: Entire
section added, p. 502, § 1, effective July 1. L. 79: (1) amended, p.
1443, § 31, effective July 3. L. 86: (5) added, p. 1142, § 3, effective
July 1. L. 87: (1) amended, p. 1448, § 20, effective June 22. L.
2007: Entire section repealed, p. 353, § 11, effective August 3.
39-22-508.4. Election to defer
commencement of credit. (Repealed)
Source:
L. 78: Entire
section added, p. 502, § 1, effective May 5. L. 2007: Entire section
repealed, p. 353, § 11, effective August 3.
39-22-508.5. Effect of transfers of new
business facilities. (Repealed)
Source:
L. 78: Entire
section added, p. 503, § 1, effective May 5. L. 89: (4) amended, p.
1500, § 4, effective July 1, 1990. L. 2007: Entire section repealed, p.
353, § 11, effective August 3.
39-22-508.6. Effect of termination of
enterprise or facility. (Repealed)
Source:
L. 78: Entire
section added, p. 504, § 1, effective May 5. L. 2007: Entire section
repealed, p. 353, § 11, effective August 3.
39-22-508.7. Effective date - termination
date. (Repealed)
Source:
L. 78: Entire
section added, p. 497, § 1, effective May 5. L. 79: Entire section
repealed, p. 1443, § 32, effective July 3.
39-22-509. Credit against tax -
employer expenditures for alternative transportation options for employees -
legislative declaration - definitions - repeal.
(1) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly hereby finds and
declares that:
(a) The
general legislative purposes of the tax credit allowed by this section are:
(I) To
induce certain designated behavior by taxpayers, specifically the provision of
alternative transportation options by employers to employees; and
(II) To
provide tax relief for certain employers that provide alternative
transportation options to their employees;
(b) The
specific legislative purpose of the tax credit allowed by this section is to
increase the use of alternative transportation options by employees in going to
and returning from their places of employment by providing an incentive to
employers to provide alternative transportation options to employees. In order
to allow the general assembly and the state auditor to measure the
effectiveness of the credit, the department of revenue, when administering the
credit, shall require each employer that claims the credit to provide, at a
minimum, information about the specific alternative transportation options
offered, the number of employees offered an alternative transportation option,
and, to the extent feasible, the number of employees actually using an
alternative transportation option and the number of trips taken by employees
using an alternative transportation option.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Alternative transportation options" means free or partially
subsidized generally accepted transportation demand management strategies
provided to employees working in Colorado, including but not limited to
ridesharing arrangements, provision of ridesharing vans or low-speed
conveyances such as human-powered or electric bicycles, shared micromobility
options such as bikesharing and electric scooter sharing programs, car sharing
programs, and guaranteed ride home programs for employees, including, but not
limited to:
(I)
Providing vehicles for ridesharing arrangements;
(II)
Cash incentives, not to exceed the value of such transportation demand
management strategies, including for participation in ridesharing or
bikesharing;
(III)
The payment of all or part of the administrative cost incurred in organizing,
establishing, or administering alternative transportation options programs for
employees;
(IV)
Free or partially subsidized mass transit tickets, tokens, passes, or fares for
use by employees in going to and returning from their places of employment; and
(V)
Free or partially subsidized prearranged rides, as defined in section
40-10.1-602 (2), or free or partially subsidized rides provided by bikesharing
arrangements for use by an employee in traveling between the employee's
residence, the employee's place of employment, or a mass transit facility that
connects the employee to the employee's residence or place of employment.
(b)
"Bikesharing arrangement" means a rental operation at which bicycles,
as defined in section 42-1-102 (10); electrical assisted bicycles, as defined
in section 42-1-102 (28.5); or electric scooters, as defined in section
42-1-102 (28.8), are made available to pick up and drop off for point-to-point
use within a defined geographic area.
(c)
"Employer" means an entity, including but not limited to a
corporation, nonprofit organization, partnership, joint venture, common trust
fund, limited association, pool or working agreement, local government, or
limited liability company, that employs three or more persons in this state.
(d)
"Local government" means any home rule city, town, county or city and
county, and any statutory city, town, or county.
(e)
"Ridesharing arrangement" means the vehicular transportation of
passengers traveling together primarily to and from such passengers' places of
business or work or traveling together on a regularly scheduled basis with a
commonality of purposes if the vehicle used in such transportation is not
operated for profit by an entity primarily engaged in the transportation
business and if no charge is made therefor other than that reasonably
calculated to recover the direct and indirect costs of the "ridesharing
arrangement", including, but not limited to, a reasonable incentive to
maximize occupancy of the vehicle. However, nothing in this subsection (2)(e)
excludes from this definition an arrangement by an employer engaged in the
transportation business that provides ridesharing arrangements for its
employees. "Ridesharing" includes "ridesharing
arrangements" commonly known as carpools and vanpools, but does not
include school transportation vehicles operated by elementary and secondary
schools when they are operated for the transportation of children to or from
school or on school-related events.
(3) (a)
For income tax years beginning on or after January 1, 2023, but before January
1, 2027, there is allowed a credit to each employer in an amount equal to fifty
percent of the amount spent by the employer to provide alternative
transportation options to its employees, subject to the limitations that the
maximum amount spent in any income tax year for which an employer may claim a
credit is two hundred fifty thousand dollars and that the maximum amount spent
in any income tax year for any one employee for which an employer may claim a
credit is two thousand dollars.
(b) (I)
For income tax years commencing before January 1, 2024, a local government or
nonprofit organization shall file a corporate income tax return for
informational purposes for each income tax year that the local government or
nonprofit organization claims the credit allowed in subsection (3)(a) of this
section.
(II)
For income tax years commencing on or after January 1, 2024, but before January
1, 2025, a local government or nonprofit organization that claims the credit
allowed in subsection (3)(a) of this section shall file a return pursuant to
section 39-22-601 (7)(b).
(c) As
a prerequisite for claiming a credit, an employer shall provide to the
department, on a form provided by the department or otherwise in such form as
the department may require and by an annual deadline specified by the
department, its plan for notifying its employees of the availability of the
alternative transportation options that it offers and the steps beyond such
notification that it plans to take to encourage employees to use those
alternative transportation options.
(d) An
employer may claim a credit only for amounts spent by the employer for
alternative transportation options that it makes available to all of its
employees who are employed in Colorado; except that, if it is not feasible to
offer a particular alternative transportation option to certain employees, an
employer may offer a substantially equivalent alternative transportation option
to such employees. The requirement that an alternative transportation option be
offered to all employees who are employed in Colorado applies regardless of the
position that an employee holds, whether the employee is employed on a
full-time or part-time basis, or whether an employee is salaried, compensated
in whole or in part through commissions or tips, or paid on an hourly basis.
(4) The
amount of any credit allowed under this section that exceeds the employer's
income taxes due is refunded to the employer.
(5) The
executive director may prescribe forms and promulgate rules as necessary to
administer this section.
(6)
This section is repealed, effective January 1, 2031.
Source:
L. 79: Entire
section added, p. 1561, § 27, effective June 20. L. 80: IP(1) amended,
p. 728, § 28, effective May 1. L. 87: IP(1) amended, p. 1448, § 21,
effective June 22. L. 2004: (1)(a) amended, p. 905, § 30, effective May
21. L. 2022: Entire section amended, (HB 22-1026), ch. 393, p. 2773, §
1, effective January 1, 2023. L. 2024: (3)(a), (3)(b), and (6) amended,
(HB 24-1036), ch. 373, pp. 2538, 2535, §§ 41, 33, effective August 7. L.
2025: (2)(d) amended, (HB 25-1296), ch. 202, p. 913, § 7, effective May 16.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024. For the legislative declaration in HB 25-1296,
see section 1 of chapter 202, Session Laws of Colorado 2025.
ANNOTATION
Law reviews. For
comment, "When Apps Pollute: Regulating Transportation Network Companies
to Maximize Environmental Benefits", see 86 U. Colo. L. Rev. 1049 (2015).
39-22-510. State-employed chaplains -
designation of rental allowance. (Repealed)
Source:
L. 79: Entire
section added, p. 1457, § 1, effective July 1. L. 2022: Entire section
repealed, (HB 22-1025), ch. 145, p. 947, § 9, effective August 10.
39-22-511. Credit against Colorado
income taxes based on cost of certificate purchased by persons in the business
of the transportation of ashes, trash, or other discarded materials. (Repealed)
Source:
L. 80: Entire
section added, p. 746, § 8, effective June 29. L. 85: Entire section
repealed, p. 1368, § 42, effective June 28.
39-22-512. Commercial, industrial, and
agricultural energy credit. (Repealed)
Source:
L. 80: Entire
section added, p. 726, § 21, effective May 1. L. 83: (1)(a) and (1)(b)
amended, p. 1515, § 9, effective January 1, 1984. L. 87: (5)(a)(I) to
(5)(a)(III) and (5)(b) amended and (6) repealed, pp. 1449, 1457, §§ 22, 31,
effective June 22. L. 2004: Entire section repealed, p. 213, § 38,
effective August 4.
39-22-513. Credit to lending
institutions for making residential energy-related loans. (Repealed)
Source:
L. 83: Entire
section added, p. 1523, § 2, effective May 20. L. 87: (1), (3)(c)(I),
(3)(e)(III), (4)(b), and (4)(c) amended, p. 1449, § 23, effective June 22. L.
88: (2) amended, p. 419, § 17, effective April 11. L. 2004: Entire
section repealed, p. 214, § 39, effective August 4.
39-22-514. Tax credit for qualified
costs incurred in preservation of historic properties.
(1) (a)
Except as otherwise provided in paragraph (b) of this subsection (1), for
income tax years commencing on or after January 1, 1991, but prior to January
1, 2020, there shall be allowed a credit with respect to the income taxes
imposed pursuant to the provisions of this article to each taxpayer:
(I) Who
is the owner or qualified tenant of qualified property and who incurs qualified
costs in an amount equaling or exceeding five thousand dollars in the qualified
rehabilitation of such qualified property; or
(II)
Who is allowed a credit for costs incurred in the rehabilitation of property
located in Colorado pursuant to the provisions of section 38 of the internal
revenue code.
(b) Any
taxpayer who is allowed a credit for qualified expenditures incurred in the
rehabilitation of property pursuant to the provisions of section 39-30-105.6
shall not be allowed the credit provided in paragraph (a) of this subsection
(1).
(2) (a)
The credit provided for in paragraph (a) of subsection (1) of this section
shall not exceed an aggregate of fifty thousand dollars per qualified property
or an amount equal to twenty percent of the aggregate qualified costs incurred
per qualified property, whichever is less.
(b)
(Deleted by amendment, L. 99, p. 1278, § 1, effective June 3, 1999.)
(3) (a)
Except as otherwise provided in paragraph (b) of this subsection (3) and
subsection (6) of this section, in order for any taxpayer to qualify for the
credit provided for in paragraph (a) of subsection (1) of this section, the
taxpayer shall:
(I)
Except as otherwise provided in this subparagraph (I), submit a fee of two
hundred fifty dollars, the plans and specifications for such proposed
restoration, rehabilitation, or preservation, and a signed agreement, if any,
specified in subsection (4) of this section to the appropriate reviewing entity
and receive preliminary approval, in writing, from said reviewing entity
stating that such proposed restoration, rehabilitation, or preservation
constitutes qualified rehabilitation. In the discretion of the reviewing
entity, the fee imposed pursuant to this subparagraph (I) may be reduced or
eliminated when the amount of qualified costs expected to be incurred in
connection with the restoration, rehabilitation, or preservation is less than
fifteen thousand dollars. If any restoration, rehabilitation, or preservation
has commenced prior to the submission of the application fee, plans and
specifications, and signed agreement, if any, pursuant to the provisions of
this subparagraph (I), the taxpayer shall also submit documentation
satisfactory to the reviewing entity indicating the condition of the qualified
property prior to commencement of the rehabilitation, including, but not
limited to, photographs of the property and written declarations from persons
knowledgeable about the property. For the purposes of this subparagraph (I),
any owners of qualified property and any qualified tenants leasing said
qualified property who wish to qualify for the credit provided for in paragraph
(a) of subsection (1) of this section for said qualified property may jointly
submit the fee and the plans and specifications, or such owners may submit the
fee, the plans and specifications, and a list of qualified tenants leasing said
qualified property and, if such owners or tenants have commenced restoration,
rehabilitation, or preservation prior to the submission of the application fee,
plans and specifications, and signed agreement, if any, pursuant to the
provisions of this subparagraph (I), they shall also jointly submit such documentation
as is required pursuant to this subparagraph (I).
(II)
Except as otherwise provided in subsection (5) of this section, complete the
qualified rehabilitation of the qualified property within a period of
twenty-four months from the date upon which preliminary approval was given
pursuant to the provisions of subparagraph (I) of this paragraph (a);
(III)
Obtain a form from the reviewing entity verifying compliance with the
provisions of this subsection (3). If more than one of the taxpayers have
complied with the provisions of this subsection (3) for the same qualified
property, the reviewing entity shall issue such verification form to each such
taxpayer, and such verification form shall specify the proportion of the amount
of the tax credit allowed to such taxpayer as determined pursuant to the
provisions of subsection (4) of this section. The reviewing entity shall issue
said verification form only upon the submittal of an accounting of total
qualified costs incurred in said qualified rehabilitation and the names of the
owners and qualified tenants who incurred such qualified costs, the payment of
a fee in an amount determined pursuant to the provisions of paragraph (a) of
subsection (11) of this section, and the making of the determination that such
completed qualified rehabilitation:
(A)
Conforms to the plans and specifications approved pursuant to subparagraph (I)
of this paragraph (a);
(B) Was
completed within the appropriate period of time; and
(C)
Preserves and maintains those qualities of such qualified property which made
it eligible for inclusion individually or as a contributing property in a
district in the state register of historic places or for designation as a
landmark or as a contributing property in a historic district by a certified
local government.
(IV)
Submit the verification form obtained pursuant to the provisions of
subparagraph (III) of this paragraph (a) with the income tax return being filed
by the taxpayer for the income tax year in which such qualified rehabilitation
is completed.
(b) The
provisions of paragraph (a) of this subsection (3) shall not apply to any
taxpayer who is allowed a credit for costs incurred in the rehabilitation of
property located in Colorado pursuant to the provisions of section 38 of the
internal revenue code.
(4)
When more than one taxpayer qualify for the tax credit provided for in
paragraph (a) of subsection (1) of this section for the same qualified
property, the amount of the tax credit allowed pursuant to the provisions of
this section shall be divided pro rata according to the number of such
taxpayers unless a binding agreement has been filed with the reviewing entity,
as specified in subparagraph (I) of paragraph (a) of subsection (3) of this
section, that is signed by all of the taxpayers who qualify for said tax credit
for the same qualified property and that specifies the manner in which the
amount of the tax credit allowed is to be divided among such taxpayers. Nothing
in this subsection (4) shall preclude the state income tax credit created pursuant
to this section from being allocated among taxpayers in a different manner than
the allocation of any credit claimed pursuant to section 38 of the internal
revenue code.
(5) The
reviewing entity may grant, upon request, a one-time extension of the
completion deadline specified in subparagraph (II) of paragraph (a) of
subsection (3) of this section. Such extension shall be for a period not to
exceed twenty-four months and shall be granted only upon a showing of good
cause.
(6) (a)
(I) Any taxpayer who was given preliminary approval prior to January 1,
2020, pursuant to the provisions of subparagraph (I) of paragraph (a) of
subsection (3) of this section; whose completion deadline as set forth in
subparagraph (II) of paragraph (a) of subsection (3) and in subsection (5) of
this section is subsequent to December 31, 2019; and who has not completed the
qualified rehabilitation prior to January 1, 2020, shall, in order to qualify
for the credit provided for in paragraph (a) of subsection (1) of this section,
obtain a form from the reviewing entity verifying compliance with the
provisions of subparagraph (I) of paragraph (a) of subsection (3) of this
section and this subsection (6). If more than one of the taxpayers have complied
with said provisions for the same qualified property, the reviewing entity
shall issue such verification form to each such taxpayer, and such verification
form shall specify the proportion of the amount of the tax credit allowed to
such taxpayer as determined pursuant to subsection (4) of this section.
(II)
The reviewing entity shall issue said verification form only upon the submittal
of an accounting of total qualified costs incurred in said qualified
rehabilitation prior to January 1, 2020, and the names of the owners and
qualified tenants who incurred such qualified costs, the payment of a fee in an
amount determined pursuant to the provisions of paragraph (a) of subsection
(11) of this section, and the making of the determination that the portion of
such qualified rehabilitation that was completed as of January 1, 2020:
(A)
Conforms to the plans and specifications approved pursuant to subparagraph (I)
of paragraph (a) of subsection (3) of this section; and
(B)
Preserves and maintains those qualities of such qualified property which made
it eligible for inclusion individually or as a contributing property in a
district in the state register of historic places or for designation as a
landmark or as a contributing property in a historic district by a certified
local government.
(III)
The taxpayer shall submit the verification form obtained pursuant to this
paragraph (a) with the income tax return being filed by the taxpayer for the
income tax year commencing on or after January 1, 2019, but prior to January 1,
2020.
(b)
(Deleted by amendment, L. 99, p. 1278, § 1, effective June 3, 1999.)
(7) (a)
Except as otherwise provided in paragraph (b) of this subsection (7), if the
amount of the credit allowed pursuant to the provisions of this section exceeds
the amount of income taxes otherwise due on the income of the taxpayer in the
income tax year for which the credit is being claimed, the amount of the credit
not used as an offset against income taxes in said income tax year may be
carried forward as a credit against subsequent years' income tax liability for
a period not exceeding ten years and shall be applied first to the earliest
income tax years possible. Any amount of the credit that is not used after said
period shall not be refundable to the taxpayer.
(b) Any
taxpayer who has refunded an amount pursuant to the provisions of subsection
(8) of this section shall no longer be eligible to carry forward any amount of
the credit which had not been used as of the date such refund is made.
(8)
Notwithstanding any other law to the contrary, if any taxpayer who is the owner
of qualified property and who has claimed the credit pursuant to the provisions
of this section sells such qualified property within five years of the
completion of the qualified rehabilitation or if any taxpayer who is a
qualified tenant leasing qualified property and who has claimed the credit
pursuant to the provisions of this section terminates the lease of such
qualified property within five years of the completion of the qualified
rehabilitation, the taxpayer shall refund the amount of the credit which has
been used to offset income taxes which exceeds the following amounts:
(a)
Within the first year, an amount equal to zero percent of the amount of the
credit allowed;
(b)
Within the second year, an amount equal to twenty percent of the amount of the
credit allowed;
(c)
Within the third year, an amount equal to forty percent of the amount of the
credit allowed;
(d)
Within the fourth year, an amount equal to sixty percent of the amount of the
credit allowed;
(e)
Within the fifth year, an amount equal to eighty percent of the amount of the
credit allowed.
(9)
Within eight months after April 20, 1990, the state historical society shall
create appropriate forms and shall establish and promulgate criteria and
procedures by which the restoration, rehabilitation, and preservation of
qualified properties shall be determined to be qualified rehabilitation for the
purposes of the credit provided for in paragraph (a) of subsection (1) of this
section.
(10)
(a) Each certified local government shall adopt a resolution stating whether
such certified local government will act as a reviewing entity for the purposes
of subsections (3) and (6) of this section. A copy of such resolution shall be
sent to the state historic preservation officer.
(b) Any
certified local government which has decided to act as a reviewing entity for
any given year for the purposes of subsections (3) and (6) of this section
shall be required to perform all duties and responsibilities pursuant to said
subsections (3) and (6) for all qualified rehabilitations which received
preliminary approval from said reviewing entity during such year.
(11)
(a) The amount of the fee required to be paid pursuant to the provisions of
subparagraph (III) of paragraph (a) of subsection (3) and subparagraph (II) of
paragraph (a) of subsection (6) of this section shall be an amount equal to the
appropriate amount determined pursuant to the following schedule minus the
amount of the fee paid pursuant to subparagraph (I) of paragraph (a) of
subsection (3) of this section; except that, in the discretion of the reviewing
entity, the fee imposed pursuant to this paragraph (a) may be reduced or
eliminated where the amount of the qualified costs incurred is less than
fifteen thousand dollars:
|
Amount of qualified costs incurred
|
Amount of fee
|
|
$5,000
up to and including $15,000
|
$
250
|
|
Over
$15,000 up to and including $50,000
|
$
500
|
|
Over
$50,000 up to and including $100,000
|
$
750
|
|
Over
$100,000
|
$
1,000
|
(b) (I)
Any certified local government which has decided to act as a reviewing entity
for the purposes of subsections (3) and (6) of this section shall create a
preservation fund. All fees collected pursuant to the provisions of
subparagraphs (I) and (III) of paragraph (a) of subsection (3) and subparagraph
(II) of paragraph (a) of subsection (6) of this section by a certified local
government shall be credited to the preservation fund of such certified local
government. The moneys in such fund shall be used for expenditures of such
certified government incurred in the performance of its duties pursuant to the
provisions of this section.
(II)
All fees collected pursuant to the provisions of subparagraphs (I) and (III) of
paragraph (a) of subsection (3) and subparagraph (II) of paragraph (a) of
subsection (6) of this section by the state historic preservation officer shall
be transmitted to the state treasurer, who shall credit said fees to the state
historic preservation fund, which fund is hereby created. The moneys in the
state historic preservation fund shall be subject to annual appropriation by
the general assembly to the state historical society for expenditures of the
state historic preservation officer and the state historical society incurred
in the performance of their duties pursuant to the provisions of this section
and for expenditures incurred in the administration and general operations of
the state historical society.
(11.5)
Notwithstanding the amount specified for any fee in this section, the executive
director by rule or as otherwise provided by law may reduce the amount of one
or more of the fees if necessary pursuant to section 24-75-402 (3), C.R.S., to
reduce the uncommitted reserves of the fund to which all or any portion of one
or more of the fees is credited. After the uncommitted reserves of the fund are
sufficiently reduced, the executive director by rule or as otherwise provided
by law may increase the amount of one or more of the fees as provided in
section 24-75-402 (4), C.R.S.
(11.7)
(a) If the revenue estimate prepared by the staff of the legislative council
in December 2010 and each December thereafter indicates that the amount of the
total general fund revenues for that particular fiscal year will not be
sufficient to grow the total state general fund appropriations by six percent
over such appropriations for the previous fiscal year, then the credit
authorized in this section shall not be allowed for any income tax year
commencing during the calendar year following the year in which the estimate is
prepared; except that any taxpayer who would have been eligible to claim a
credit pursuant to this section in the income tax year in which the credit is
not allowed shall be allowed to claim the credit earned in such income tax year
in the next income tax year in which the estimate indicates that the amount of
the total general fund revenues will be sufficient to grow the total state
general fund appropriations by six percent over such appropriations for the
previous fiscal year.
(b) The
department of revenue shall, through its website, specify on or before January
1, 2011, and on or before each January 1 thereafter, whether the credit
authorized in this section shall be allowed for a given income tax year
pursuant to paragraph (a) of this subsection (11.7).
(12) As
used in this section, unless the context otherwise requires:
(a)
"Certified local government" means any local government certified by
the state historic preservation officer pursuant to the provisions of 54 U.S.C.
sec. 302502, as amended.
(b)
"Contributing property" means property which by location, design,
setting, materials, workmanship, feeling, and association adds to the sense of
time, place, and historical development of a historic district.
(c)
"Designated" means established by local preservation ordinance.
(d)
"Property" means a building or structure or a unit of a multiunit
building where such units are individually owned.
(e)
"Qualified costs" means costs associated with the qualified
rehabilitation of a qualified property. "Qualified costs" includes,
but is not limited to, costs associated with demolition, carpentry, sheetrock,
plaster, painting, ceilings, fixtures, doors and windows, fire sprinkler
systems, roofing and flashing, exterior repair, cleaning, tuckpointing, and
cleanup. "Qualified costs" does not include costs, commonly referred
to as soft costs, which include, but are not limited to, costs associated with
appraisals; architectural, engineering, and interior design fees; legal,
accounting, and realtor fees; loan fees; sales and marketing; closing; building
permit, use, and inspection fees; bids; insurance; project signs and phones;
temporary power; bid bonds; copying; and rent loss during construction.
"Qualified costs" also does not include, but shall not be limited,
costs associated with acquisition; interior furnishings; new additions except
as may be required to comply with building and safety codes; excavation;
grading; paving; landscaping; routine or periodic maintenance; repairs to
outbuildings which are associated with a qualified property and which are less
than fifty years old; and repairs to additions made to a qualified property
after such property was included individually or as a contributing property in
a district in the state register of historic places or was designated as a
landmark or as a contributing property in a historic district by a certified
local government.
(f)
"Qualified property" means property located in Colorado which is:
(I) At
least fifty years old; and
(II)
(A) Listed individually or as a contributing property in a district on the
state register of historic properties pursuant to the provisions of article
80.1 of title 24, C.R.S.;
(B)
Designated as a landmark by a certified local government; or
(C)
Listed as a contributing property within a designated historic district of a
certified local government.
(g)
"Qualified rehabilitation" means any exterior improvements,
structural improvements, mechanical improvements, plumbing improvements, or
electrical improvements undertaken to restore, rehabilitate, or preserve the
historic character of a qualified property which meets the standards of
rehabilitation of the United States secretary of the interior as adopted by the
state historic preservation officer and certified local governments pursuant to
federal law; but shall not include any improvements undertaken due to normal
wear and tear which occurred to a qualified property. As used in this paragraph
(g), "exterior improvements" includes, but is not limited to,
improvements made to the exterior of the qualified property and to the exterior
of any historic outbuildings which are associated with the qualified property
and which are fifty or more years old. "Exterior improvements" does
not include enlargements, additions, landscaping, routine or periodic
maintenance, paving, and site work.
(h)
"Qualified tenant" means a taxpayer who holds a lease of five years
or longer on qualified property or a portion of such qualified property.
(i)
"Reviewing entity" means:
(I) A
certified local government which has decided pursuant to the provisions of
paragraph (a) of subsection (10) of this section to perform the duties
specified in subparagraph (I) of paragraph (a) of subsection (3) of this
section; or
(II)
The state historic preservation officer when such qualified property either is
not located within the jurisdiction of any certified local government or is
located within the jurisdiction of any certified local government who has
decided pursuant to the provisions of paragraph (a) of subsection (10) of this
section not to perform the duties specified in subparagraph (I) of paragraph
(a) of subsection (3) of this section.
(j)
"State historic preservation officer" means the person designated and
appointed pursuant to the provisions of 54 U.S.C. sec. 302301, as amended.
(k)
"Taxpayer" means:
(I) A
resident individual; or
(II) A
domestic or foreign corporation subject to the provisions of part 3 of this
article.
Source:
L. 90: Entire
section added, p. 1730, § 1, effective April 20. L. 94: (1)(a) and
(6)(a) amended, p. 1369, § 1, effective May 25. L. 98: (11.5) added, p.
1347, § 82, effective June 1. L. 99: IP(1)(a), (2), IP(3)(a), (3)(a)(I),
(4), (6), (7)(a), (10)(a), and (11)(a) amended, p. 1278, § 1, effective June 3.
L. 2008: IP(1)(a), (6)(a)(I), IP(6)(a)(II), (6)(a)(III), and (10)(a)
amended and (11.7) added, p. 2266, § 1, effective August 5. L. 2009:
(11.7)(a) amended, (SB 09-228), ch. 410, p. 2265, § 19, effective July 1;
(6)(a)(I) amended, (SB 09-292), ch. 369, p. 1980, § 114, effective August 5. L.
2024: (12)(a) and (12)(j) amended, (HB 24-1450), ch. 490, p. 3425, § 78,
effective August 7.
Cross
references: For
additional funding by the general assembly to the state historical society, see
§ 24-80-202.5.
39-22-514.5. Tax credit for qualified
costs incurred in preservation of historic structures - commercial historic
preservation tax credit program cash fund - tax preference performance
statement - legislative declaration - short title - definitions.
(1) Short
title. The short title of this section is the "Colorado Job Creation
and Main Street Revitalization Act".
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a) (I)
"Certified historic structure" means a property located in Colorado
that has been certified by the historical society or other reviewing entity
because it has been:
(A)
Listed individually on, or as a contributing property in a district included
within, the national register of historic places;
(B)
Listed individually on, or as a contributing property in a district that is
included within, the state register of historic properties pursuant to the
provisions of article 80.1 of title 24; or
(C)
Listed individually by, or as a contributing property within a designated
historic district of, a certified local government.
(II)
"Certified historic structure" may be either a residential or
commercial structure.
(b)
"Certified local government" means any local government that has been
certified by the historical society in accordance with federal law.
(c)
"Certified rehabilitation" means repairs or alterations to a
certified historic structure that have been certified by the historical society
or other reviewing entity as meeting the standards for rehabilitation of the
United States secretary of the interior.
(d)
"Contributing property" means property that adds to the sense of
time, place, and historical development of a historic district as determined by
the historical society or other reviewing entity.
(d.3)
"Denver metropolitan area" means all of the land area within the
boundaries of the counties of Adams, Arapahoe, Boulder, and Jefferson, all of
the area within the boundaries of the city and county of Broomfield and the
city and county of Denver, and all of the area within the boundaries of the
county of Douglas; except that the area within the boundaries of the town of
Castle Rock and the area within the boundaries of the town of Larkspur in the
county of Douglas shall not be included in such area.
(e)
"Department" means the Colorado department of revenue or any
successor entity.
(f)
"Designated" means established by local preservation ordinance.
(g)
"Historical society" means the state historical society of Colorado,
also known as history Colorado, or any successor entity.
(g.5)
"Municipality" has the same meaning as specified in section 31-1-101
(6) and also includes any unincorporated area of a county, including without
limitation an unincorporated community or a census-designated place.
(h)
"Office" means the Colorado office of economic development or any
successor entity.
(i)
"Owner" means any taxpayer filing a state tax return or any entity
that is exempt from federal income taxation pursuant to section 501 (c) of the
internal revenue code, as amended, that owns:
(I)
Title to a qualified structure;
(II)
Prospective title to a qualified structure in the form of a purchase agreement
or an option to purchase;
(III) A
leasehold interest in a qualified commercial structure for a term of not less
than thirty-nine years;
(III.5)
A leasehold interest in a qualified commercial structure that is located in a
rural community for a term of not less than five years; or
(IV) A
leasehold interest in a qualified residential structure for a term of not less
than five years.
(j)
"Qualified commercial structure" means an income producing or
commercial property located in Colorado that is:
(I) At
least thirty years old; and
(II)
(A) Listed individually on, or as a contributing property in a district
included within, the state register of historic properties pursuant to article
80.1 of title 24; or
(B)
(Deleted by amendment, L. 2018.)
(C)
Listed individually by, or as a contributing property that is included within a
designated historic district of, a certified local government.
(k)
"Qualified rehabilitation expenditures" means:
(I)
With respect to a qualified commercial structure, any expenditure as defined
under section 47 (c)(2)(A) of the internal revenue code, as amended, and the
related regulations thereunder; and
(II)
With respect to a qualified residential structure, exterior improvements and
interior improvements undertaken to restore, rehabilitate, or preserve the
historic character of a qualified property that meet the standards for
rehabilitation of the United States secretary of the interior as adopted by the
historical society or the certified local government pursuant to federal law.
As used in this subsection (2)(k)(II), "exterior improvements" is
limited to any one or more of the following: Roof replacement or repair;
exterior siding replacement or repair; masonry repair, re-pointing, or
replacement; window repair or replacement; door repair or replacement; woodwork
and trim repair or replacement; foundation repair or replacement; and
excavation costs associated with foundation work. As used in this subsection
(2)(k)(II), "interior improvements" is limited to one or more of the
following: Electrical repairs and upgrades; plumbing repairs and upgrades;
heating, venting, and air conditioning repairs and upgrades; repair of existing
interior walls, ceilings, and finishes; repair or replacement of existing
woodwork and trim; insulation; refinishing or replacing historic floor
materials in-kind, excluding carpeting; and reconstructing missing historic
elements when there is sufficient historical documentation to guide the
reconstruction.
(l)
"Qualified residential structure" means a nonincome producing and
owner-occupied residential property located in Colorado that is:
(I) At
least thirty years old; and
(II)
(A) Listed individually on, or as a contributing property in a district
included within, the state register of historic properties pursuant to article
80.1 of title 24; or
(B)
(Deleted by amendment, L. 2018.)
(C)
Listed individually by, or as a contributing property that is included within a
designated historic district of, a certified local government.
(m)
"Qualified structure" means a structure that satisfies the definition
of either a qualified residential structure or a qualified commercial
structure.
(n)
"Rehabilitation plan" or "plan" means construction plans
and specifications for the proposed rehabilitation of a qualified structure
that are in sufficient detail to enable the office or the reviewing entity, as
applicable, to evaluate whether the structure is in compliance with the
standards developed under subsection (4) of this section.
(o)
"Reviewing entity" means:
(I) A
certified local government that has decided pursuant to subsection (5.5)(c) of
this section to perform the duties specified under this section; or
(II)
The historical society if the qualified residential structure either is not
located within the territorial boundaries of any certified local government or
is located within the territorial boundaries of a certified local government
that has decided pursuant to subsection (5.5)(c) of this section not to perform
the duties specified under this section.
(o.5)
"Rural community" means:
(I) A
municipality with a population of less than fifty thousand people that is not
located within the Denver metropolitan area; or
(II) An
unincorporated area of any county the total population of which county is less
than fifty thousand people that is not located within the Denver metropolitan
area.
(p)
"Substantial rehabilitation" means:
(I)
With respect to a qualified commercial structure:
(A) For
tax years commencing prior to January 1, 2020, rehabilitation for which the
qualified rehabilitation expenditures exceed twenty-five percent of the owner's
original purchase price of the qualified commercial structure less the value
attributed to the land; and
(B) For
tax years commencing on or after January 1, 2020, rehabilitation for which the
qualified rehabilitation expenditures are in an aggregate amount of at least
twenty thousand dollars; and
(II)
With respect to a qualified residential structure, rehabilitation for which the
qualified rehabilitation expenditures exceed five thousand dollars.
(3) General
provisions. For income tax years commencing on or after January 1, 2016,
but prior to January 1, 2037, there shall be allowed a credit with respect to
the income taxes imposed pursuant to this article 22 to each owner of a
qualified structure that complies with the requirements of this section.
(4) Development
of standards for approval of commercial or residential rehabilitation projects.
(a) The
office, in consultation with the historical society, shall develop standards
for the approval of the substantial rehabilitation of qualified commercial
structures for which a tax credit under this section is being claimed. The
standards must consider whether the substantial rehabilitation of a qualified
commercial structure is consistent with the standards for rehabilitation
adopted by the United States department of the interior.
(b) The
historical society shall develop standards for the approval of the substantial
rehabilitation of qualified residential structures for which a tax credit under
this section is being claimed. The standards must consider whether the
substantial rehabilitation of a qualified residential structure is consistent
with the standards for rehabilitation adopted by the United States department
of the interior.
(5) Submission
by owner of application and rehabilitation plan.
(a) The
owner shall submit an application and rehabilitation plan to either the office
for a qualified commercial structure or to the reviewing entity for a qualified
residential structure, along with an estimate of the qualified rehabilitation
expenditures under the rehabilitation plan. If an application and
rehabilitation plan is for a qualified commercial structure, the owner shall
specify whether the owner is seeking to reserve a credit allowed pursuant to
subsection (12)(a) of this section or a credit allowed pursuant to subsection
(12)(a.5) of this section, and an owner may only apply for one of these two
credits for a single qualified rehabilitation plan as described in subsection
(7) of this section. An owner, at the owner's own risk, may incur qualified
rehabilitation expenditures no earlier than twenty-four months prior to the
submission of the application and rehabilitation plan that an owner submits
prior to January 1, 2026, and no earlier than twelve months prior to the
submission of the application and rehabilitation plan that an owner submits on
or after January 1, 2026, but only if satisfactory documentation is submitted
to the office or the reviewing entity, as applicable, indicating the condition
of the qualified structure prior to commencement of the rehabilitation,
including but not limited to photographs of the qualified structure and written
declarations from persons knowledgeable about the qualified structure. An owner
may submit an application and rehabilitation plan and may commence rehabilitation
before the property:
(I) Is
listed individually on, or as a contributing property in a district included
within, the national register of historic places;
(II) Is
listed individually on, or as a contributing property in a district included
within, the state register of historic properties pursuant to article 80.1 of
title 24; or
(III)
(Deleted by amendment, L. 2018.)
(IV) Is
listed individually by, or as a contributing property within a designated
historic district of, a certified local government.
(b)
Notwithstanding the provisions of subsection (5)(a) of this section, an owner
may incur qualified rehabilitation expenditures at the owner's own risk.
(b.5)
On or after January 1, 2025, an owner shall not submit an application and
rehabilitation plan for an already completed rehabilitation project.
(c)
Within ninety days after receipt of the application and rehabilitation plan,
the office and the historical society, in the case of a qualified commercial
structure, and the reviewing entity, in the case of a qualified residential
structure, shall notify the owner in writing if the rehabilitation plan is
preliminarily determined to be a certified rehabilitation.
(5.5) Issuance
of tax credit certificate for qualified residential structures - rules.
(a) (I)
Following the completion of a rehabilitation of a qualified residential
structure, the owner shall notify the reviewing entity that the rehabilitation
has been completed and shall certify that the qualified rehabilitation
expenditures incurred in connection with the rehabilitation plan. The owner
shall also provide the reviewing entity with a cost and expense certification
for the total qualified rehabilitation expenditures and the total amount of tax
credits for which the owner is eligible. The reviewing entity shall review the
documentation of the rehabilitation and verify its compliance with the
rehabilitation plan. Except as otherwise provided in subsections (5.5)(a)(II)
and (5.5)(a)(III) of this section, within ninety days after receipt of the
foregoing documentation from the owner the reviewing entity shall issue a tax
credit certificate in an amount equal to twenty percent of the actual qualified
rehabilitation expenditures; except that the amount of the tax credit
certificate awarded for tax years commencing before January 1, 2025, shall not
exceed fifty thousand dollars for each qualified residential structure, the
amount of the tax credit certificate awarded for tax years commencing on or
after January 1, 2025, shall not exceed one hundred thousand dollars for each
qualified residential structure, and both the fifty thousand dollar and one
hundred thousand dollar amounts are to be calculated over a ten-year rolling
period that commences with each change in ownership of the qualified residential
structure.
(II)
For income tax years commencing prior to January 1, 2030, and for applications
submitted pursuant to subsection (5) of this section prior to January 1, 2025,
with respect to a qualified residential structure located in an area that the
president of the United States has determined to be a major disaster area under
section 102 (2) of the federal "Robert T. Stafford Disaster Relief and
Emergency Assistance Act", 42 U.S.C. sec. 5121 et seq., or that is located
in an area that the governor has determined to be a disaster area under the
"Colorado Disaster Emergency Act", part 7 of article 33.5 of title
24, the amount of the tax credit specified in subsection (5.5)(a)(I) of this
section is increased to twenty-five percent for an application that is filed
within six years after the disaster determination.
(III)
For income tax years commencing on and after January 1, 2020, with respect to a
qualified residential structure located in a rural community, the amount of the
tax credit specified in subsection (5.5)(a)(I) of this section is increased to
thirty-five percent for an application that is properly filed in accordance
with this section.
(b)
Repealed.
(c) For
the purposes of this section, a certified local government may act as a
reviewing entity only for a qualified residential structure. Each certified
local government shall adopt a resolution or ordinance stating whether the
government will act as a reviewing entity for the purposes of this section. The
local government shall send a copy of the resolution or ordinance to the
historical society. Any certified local government that decides to act as a
reviewing entity for the purposes of this section shall perform all duties and
responsibilities in connection with a certified rehabilitation that receives
preliminary approval from such entity. The historical society shall promulgate
rules on standards and reporting, in accordance with article 4 of title 24, as
it deems necessary to facilitate the effective implementation of this
subsection (5.5)(c).
(d) In
the case of a qualified residential structure, the reviewing entity may impose
a reasonable application fee.
(e) The
historical society shall promulgate any and all rules necessary to further
implement the tax credits to be claimed for the substantial rehabilitation of
qualified residential structures under this section. Any rules must be
promulgated in accordance with article 4 of title 24.
(f) By
March 15, 2019, and on a quarterly basis thereafter, the historical society
shall provide a report to the department specifying the ownership of tax
credits to be claimed for the rehabilitation of qualified residential
structures under this section covering the period since the last report. The
historical society shall share with the department all necessary information
about the tax credit created by this section to enable the historical society
and the department to properly administer the tax credit.
(6) Application
and issuance fees for qualified commercial structures.
(a) For
a qualified commercial structure for which the amount of tax credit requested
under this section is two hundred fifty thousand dollars or more, the office
may impose a reasonable application fee that does not exceed five hundred
dollars. For a qualified commercial structure for which the amount of tax
credit requested under this section is less than two hundred fifty thousand
dollars, the office may impose a reasonable application fee that does not
exceed two hundred fifty dollars.
(b)
(Deleted by amendment, L. 2018.)
(c) The
office may impose on the owner a reasonable issuance fee of up to three percent
of the amount of the tax credit issued, which must be paid before the tax
credit is issued to the owner. With respect to both an application fee and an
issuance fee, the office shall share on an equal basis any such fees collected
with the historical society and the department. Money collected from such fees
must be credited to the commercial historic preservation tax credit program
cash fund created in subsection (17) of this section and applied to the
administration of the tax credit created by this section.
(d)
(Deleted by amendment, L. 2018.)
(7) Reservation
of tax credits for qualified rehabilitation plans for qualified commercial
structures.
(a) In
the case of a qualified commercial structure, a reservation of tax credits is
permitted in accordance with the provisions of this subsection (7). The office
and the historical society shall review the application and rehabilitation plan
for a qualified commercial structure to determine that the information
contained in the application and plan is complete. If the office and the
historical society determine that the application and rehabilitation plan are
complete, the office shall reserve for the benefit of the owner an allocation
of a tax credit as provided in subsection (12)(a) or (12)(a.5) of this section
and subsection (8)(c)(II) of this section, and the office shall notify the
owner in writing of the amount of the reservation. The reservation of tax
credits does not entitle the owner to an issuance of a tax credit until the
owner complies with all the other requirements specified in this section for
the issuance of the tax credit. The office shall separately reserve tax credits
allowed pursuant to subsection (12)(a) of this section and tax credits allowed
pursuant to subsection (12)(a.5) of this section in the order in which it
receives completed applications and rehabilitation plans for each of those two
categories of credits. The office shall issue a reservation of tax credits
authorized by this subsection (7) within a reasonable time, not to exceed
ninety days after the filing of a completed application and rehabilitation
plan. The office shall stamp each completed application and plan with the date
and time it receives the application and plan and shall review a plan and
application on the basis of the order in which the documents were submitted by
date and time. The office shall only review an application and plan submitted
in connection with a property for which a property address, legal description,
or other specific location is provided in the application and plan and for
which the owner has specified the category of credit sought as required by
subsection (5)(a) of this section. The owner shall not request the review of
another property for approval in the place of the property that is the subject
of the application and plan. Any application and plan disapproved by the office
will be removed from the review process, and the office shall notify the owner
in writing of the decision to remove the property from the review process.
Disapproved applications and plans lose their priority in the review process.
An owner may resubmit a modified application and plan, but a resubmitted
application and plan is a new submission for purposes of the priority
procedures described in this subsection (7)(a). If a resubmitted application
and plan are submitted, the office may charge a new application fee in an
amount specified in accordance with subsection (6) of this section.
(a.5)
In the case of any project for a qualified commercial structure the qualified
rehabilitation expenditures for which amount to less than fifty thousand
dollars, if the total number of applications for such projects that are
received but not reserved for credits allowed pursuant to either subsection
(12)(a) or (12)(b) of this section reaches fifteen, the office may suspend the
submission of additional applications for that credit for such projects until
such time as the fifteen projects have been duly reserved or disapproved. The
notification period that is specified in subsection (5)(c) of this section is
extended to one hundred twenty days after receipt of the application and
rehabilitation plan for the fifteen projects. Any application for a qualified
commercial structure the qualified rehabilitation expenditures for which amount
to fifty thousand or more dollars is not subject to this subsection (7)(a.5).
(b) If,
for any calendar year, the aggregate amount of reservations for tax credits
allowed pursuant to either subsection (12)(a) or (12)(a.5) of this section that
the office has approved is equal to the total amount of tax credits available
for reservation pursuant to the applicable subsection (12)(a) or (12)(a.5) of
this section during that calendar year, the office shall notify all owners who
have submitted applications and rehabilitation plans for reservation of a tax
credit allowed pursuant to the applicable subsection (12)(a) or (12)(a.5) of
this section then awaiting approval or submitted for approval after the
calculation is made that no additional approvals of applications and plans for
reservations of tax credits will be granted during that calendar year. The
office shall additionally notify the owner of the priority number given to the
owner's application and plan then awaiting approval. The applications and plans
remain in priority status for two years from the date of the original application
and plan and are considered for reservations of tax credits in the priority
order established in this subsection (7) if additional credits become available
resulting from the rescission of approvals under subsection (8)(a) of this
section or because a new allocation of tax credits for a calendar year becomes
available.
(c)
Notwithstanding any other provision of this section, this subsection (7) does
not apply to a qualified residential structure because no reservation of tax
credits is necessary in the case of a qualified residential structure.
(8) Deadline
for incurring specified amount of estimated costs of rehabilitation - proof of
compliance - audit of cost and expense certification - issuance of tax credit
certificate - commercial structures.
(a) An
owner receiving a reservation of tax credits under subsection (7)(a) of this
section shall incur not less than twenty percent of the estimated costs of
rehabilitation contained in the application and rehabilitation plan not later
than eighteen months after the date of issuance of the written notice from the
office to the owner granting the reservation of tax credits. An owner receiving
a reservation of tax credits shall submit evidence of compliance with the
provisions of this subsection (8)(a). If the office determines that an owner
has failed to comply with the requirements of this subsection (8)(a), the
office may rescind the issuance it previously gave the owner approving the
reservation of tax credits and, if so, the total amount of tax credits made
available pursuant to subsection (12)(a) or (12)(a.5) of this section, as
applicable, for the calendar year for which reservations may be granted must be
increased by the amount of the tax credits rescinded. The office shall promptly
notify any owner whose reservation of tax credits has been rescinded and, upon
receipt of the notice, the owner may submit a new application and plan for
which the office may charge a new application fee in accordance with subsection
(6) of this section.
(b)
Following the completion of a rehabilitation of a qualified commercial
structure, the owner shall notify the office that the rehabilitation has been
completed and shall certify the qualified rehabilitation costs and expenses.
The applicant shall include a review of the certification by a licensed
certified public accountant that is not affiliated with the qualified
applicant, and the review of the certification must align with office policies
for certification of qualified rehabilitation expenditures. The office and the
historical society shall review the documentation of the rehabilitation and the
historical society shall verify that the documentation satisfies the
rehabilitation plan. Within ninety days after receipt of such documentation
from the owner, the office shall issue a tax credit certificate in an amount
equal to the following subject to subsection (8)(c) of this section:
(I)
Twenty-five percent of the actual qualified rehabilitation expenditures that
are less than two million dollars; plus
(II)
Twenty percent of the actual qualified rehabilitation expenditures in excess of
two million dollars.
(c)
Notwithstanding subsection (8)(b) of this section:
(I) The
total amount of the tax credit certificate issued for any particular project
shall not exceed the amount of the tax credit reservation issued for the
project under subsection (7)(a) of this section;
(II)
The amount of a tax credit certificate to be issued pursuant to subsection
(12)(a) of this section for any one qualified commercial structure shall not
exceed one million dollars, and the amount of a tax credit certificate to be
issued pursuant to subsection (12)(a.5) of this section for any one qualified
rehabilitation plan shall not exceed one million five hundred thousand dollars
in any one calendar year;
(III)
For income tax years commencing prior to January 1, 2030, and for applications
submitted pursuant to subsection (5) of this section prior to January 1, 2026,
with respect to a certified historic structure that is a qualified commercial
structure that is located in an area that the president of the United States
has determined to be a major disaster area under section 102 (2) of the federal
"Robert T. Stafford Disaster Relief and Emergency Assistance Act", 42
U.S.C. sec. 5121 et seq., or that is located in an area that the governor has
determined to be a disaster area under the "Colorado Disaster Emergency
Act", part 7 of article 33.5 of title 24, the tax credit amounts specified
in subsections (8)(b)(I) and (8)(b)(II) of this section must be increased as
follows for an application that is filed within six years after the disaster
determination:
(A) The
twenty-five percent credit amount specified in subsection (8)(b)(I) of this
section is increased to thirty percent; and
(B) The
twenty percent credit amount specified in subsection (8)(b)(II) of this section
is increased to twenty-five percent;
(IV)
For income tax years commencing on or after January 1, 2020, with respect to a
certified historic structure that is a qualified commercial structure that is
located in a rural community, the tax credit amounts specified in subsections
(8)(b)(I) and (8)(b)(II) of this section must be increased as follows for an
application that is properly filed in accordance with this section:
(A) The
twenty-five percent credit amount specified in subsection (8)(b)(I) of this
section is increased to thirty-five percent; and
(B) The
twenty percent credit amount specified in subsection (8)(b)(II) of this section
is increased to thirty percent; and
(V) For
a tax credit allowed pursuant to subsection (12)(a.5) of this section only, if,
due to a regulatory requirement or condition of financing, the qualified
commercial structure for which the tax credit is claimed is subject to a deed
restriction that requires the owner to lease rental housing units in the
qualified commercial structure only to individuals or households whose income
is below a specified amount, then the amount of the tax credit specified in
subsection (8)(b) of this section, as increased pursuant to subsection
(8)(c)(III) or (8)(c)(IV) of this section, if applicable, is increased by an
additional five percent.
(d) If
the amount of qualified rehabilitation expenditures incurred by the owner would
result in an owner being issued an amount of tax credits that exceeds the
amount of tax credits reserved for the owner under subsection (7)(a) of this
section, the owner may apply to the office for the issuance of an amount of tax
credits that equals the excess. The owner must submit its application for
issuance of such excess tax credits on a form prescribed by the office. The
office shall automatically approve the application, which it shall issue by
means of a separate certificate, subject only to the availability of tax
credits and the provisions concerning priority provided in subsection (7)(a) of
this section.
(e)
(Deleted by amendment, L. 2018.)
(f)
Repealed.
(9) Filing
tax credit certificate with income tax return. In order to claim the
credit authorized by this section, the owner shall file the tax credit
certificate with the owner's state income tax return. The amount of the credit
claimed that the owner may claim under this section is the amount stated on the
tax credit certificate.
(10)
(Deleted by amendment, L. 2018.)
(11) Residential
and commercial.
(a) For
tax years commencing prior to January 1, 2027, the entire tax credit to be
issued under this section for either a qualified residential structure or a
qualified commercial structure may be claimed by the owner in the taxable year
in which the certified rehabilitation is placed in service. If the amount of
the credit allowed under this section exceeds the amount of income taxes
otherwise due on the income of the owner in the income tax year for which the
credit is being claimed, the amount of the credit not used as an offset against
income taxes in said income tax year may be carried forward as a credit against
subsequent years' income tax liability for a period not to exceed ten years and
will be applied to the earliest income tax years possible. Any amount of the
credit that is not used after such period shall not be refunded to the owner.
(b) (I)
For tax years commencing on or after January 1, 2027, the entire tax credit to
be issued under this section for either a qualified residential structure or a
qualified commercial structure may be claimed by the owner in the tax year in
which the certified rehabilitation is placed in service.
(II) If
the amount of the credit allowed under this section for a qualified commercial
structure, but not a qualified residential structure, exceeds the amount of
income taxes otherwise due on the income of the owner in the income tax year
for which the credit is being claimed, the amount of the credit not used as an
offset against income taxes in said income tax year may be carried forward as a
credit against subsequent years' income tax liability for a period not to
exceed ten years and shall be applied to the earliest income tax years
possible. Any amount of the credit that is not used after such period shall not
be refunded to the owner.
(III)
If the amount of the credit allowed under this section for a qualified
residential structure, but not a qualified commercial structure, exceeds the
amount of income taxes otherwise due on the income of the qualified applicant
in the income tax year for which the credit is being claimed, the amount of the
credit not used as an offset against income taxes in the income tax year is
refunded to the qualified applicant.
(12) Limit
on aggregate amount of all tax credits that may be reserved for qualified
commercial structures - assignability and transferability of tax credits for
qualified commercial structures - tax preference performance statement -
legislative declaration.
(a)
Except as otherwise provided in subsections (12)(a.5) and (12)(b) of this
section, the aggregate amount of all tax credits in any calendar year that may
be reserved for qualified commercial structures by the office upon the
certification of all rehabilitation plans under subsection (7)(a) of this
section for such structures must not exceed:
(I) For
qualified commercial structures estimating qualified rehabilitation
expenditures in the amount of two million dollars or less, two and one-half
million dollars in the aggregate for the 2016 calendar year, five million
dollars in the aggregate for each of the 2017, 2018, and 2019 calendar years,
in addition to the amount of any previously reserved tax credits that were
rescinded under subsection (8)(a) of this section during the applicable
calendar year;
(II)
For qualified commercial structures estimating qualified rehabilitation
expenditures in excess of two million dollars, two and one-half million dollars
in the aggregate for the 2016 calendar year, five million dollars in the
aggregate for each of the 2017, 2018, and 2019 calendar years, in addition to
the amount of any previously reserved tax credits that were rescinded under
subsection (8)(a) of this section during the applicable calendar year;
(III)
For qualified commercial structures estimating qualified rehabilitation
expenditures in any amount, ten million dollars in the aggregate for each of
the 2020 through 2032 calendar years, in addition to the amount of any
previously reserved tax credits that were rescinded under subsection (8)(a) of
this section during the applicable calendar year; except that the aggregate
amount of the ten million dollars in tax credits in any tax year that may be
reserved by the office must be equally split between qualified commercial
structures for which the estimated qualified rehabilitation expenditures are
equal to or less than two million dollars and qualified commercial structures
for which the estimated qualified rehabilitation expenditures are in excess of
two million dollars.
(a.5)
For calendar years commencing on or after January 1, 2025, but before January
1, 2030, in addition to the tax credits allowed to be reserved by the office
pursuant to subsection (12)(a) of this section, the office shall separately
reserve credits pursuant to this subsection (12)(a.5) for an owner of a
qualified commercial structure that submits an application and rehabilitation
plan for rehabilitation of the qualified commercial structure so that at least
fifty percent of the square footage of the qualified commercial structure will
be net new rental housing units, as defined by the office. Except as otherwise
provided in subsection (12)(b) of this section, the aggregate amount of all tax
credits in any calendar year that may be reserved pursuant to this subsection
(12)(a.5) for qualified commercial structures by the office upon the
certification of all rehabilitation plans under subsection (7)(a) of this
section for such structures must not exceed five million dollars per year in
the aggregate, in addition to the amount of any previously reserved tax credits
that were rescinded under subsection (8)(a) of this section during the
applicable calendar year.
(b)
Notwithstanding any other provision of this subsection (12), if the entirety of
the allowable tax credit amount for any calendar year is not requested and
reserved under:
(I)
Subsection (12)(a) of this section, the office may use any such unreserved tax
credits in reserving tax credits in another category for that same calendar
year, and the office may also use any remaining unreserved tax credits for that
calendar year in reserving tax credits in subsequent calendar years; or
(II)
Subsection (12)(a.5) of this section, the office shall use any remaining
unreserved tax credits for that calendar year in reserving tax credits in
subsequent calendar years.
(c) Any
tax credits issued under this section to a partnership, a limited liability
company taxed as a partnership, or multiple owners of a property must be passed
through to the partners, members, or owners, including any nonprofit entity
that is a partner, member, or owner, respectively, on a pro rata basis or
pursuant to an executed agreement among the partners, members, or owners
documenting an alternate distribution method.
(d) Any
tax credits issued under this section for a qualified commercial structure are
freely transferable and assignable, subject to any notice and verification
requirements to be determined by the office; except that the owner or a
subsequent transferee may only transfer the portion of the tax credit that has
neither been applied against the income tax imposed by this article 22 nor used
to obtain a refund. Any transferee of a tax credit for a qualified commercial
structure issued under this section may use the amount of tax credits
transferred to offset against any other tax due under this article 22 or the
transferee may freely transfer and assign all or any portion of the tax credits
that have neither been applied against the income taxes imposed by this article
22 nor used to obtain a refund to any other person or entity, including an
entity that is exempt from federal income taxation pursuant to section 501 (c)
of the internal revenue code, as amended, and the other person or entity may
freely transfer and assign all or any portion of the tax credits that have
neither been applied against the income taxes imposed by this article 22 nor
used to obtain a refund to any other person or entity. The tax credits may be
transferred or assigned on multiple occasions until such time as the credit is
claimed on a state tax return. The transferor and the transferee of the tax
credits shall jointly file a copy of the written transfer agreement with the
office within thirty days after the transfer. Any filing of the written
transfer agreement with the office perfects the transfer. The office shall
develop a system to track the transfers of tax credits and to certify the
ownership of tax credits. A certification by the office of the ownership and
the amount of tax credits may be relied on by the department and the transferee
as being accurate, and the office shall not adjust the amount of tax credits as
to the transferee; except that the office retains any remedies it may have
against the owner. The office may promulgate rules to permit verification of
the ownership and amount of the tax credits; except that any rules promulgated
shall not unduly restrict or hinder the transfer of the tax credits.
Notwithstanding any other provision of this section, only tax credits issued
under this section for a qualified commercial structure, and not tax credits
issued under this section for a qualified residential structure, are freely
transferable and assignable in accordance with this subsection (12)(d).
(e)
(Deleted by amendment, L. 2018.)
(13) Appeal.
Any owner or any duly authorized representative of an owner may appeal any
final determination made by the office, the historical society, or the
department, including, without limitation, any preliminary or final
reservation, or any approval or denial, in accordance with the "State
Administrative Procedure Act", article 4 of title 24. The owner or the
owner's representative shall submit any such appeal within thirty days after
receipt by the owner or the owner's representative of the final determination
that is the subject of the appeal.
(14) Deadline
for submitting application and rehabilitation plan. Notwithstanding any
other provision of this section, the tax credits authorized by this section for
the substantial rehabilitation of a qualified structure are not available to an
owner of a qualified structure that submits an application and rehabilitation
plan after December 31, 2032. No action or inaction on the part of the general
assembly has the effect of limiting or suspending the issuing of tax credits
authorized by this section in any past or future income tax year with respect
to a qualified structure if the owner of the structure submits an application
and rehabilitation plan with the office on or prior to December 31, 2032, even
if the qualified structure is placed into service after December 31, 2032. Any
tax credits that have been reserved for a qualified commercial structure in
accordance with subsection (7)(a) of this section and any applicable rules
promulgated under this section prior to December 31, 2032, may still be issued
by the office through and including December 31, 2036.
(15) Report
to the department - rules - qualified commercial structures.
(a) On
or before March 15, 2016, and on a quarterly basis thereafter, the office shall
provide a report to the department specifying the ownership and transfers of
tax credits for the rehabilitation of qualified commercial structures under
this section covering the period since the last report.
(b) The
office, in consultation with the historical society, may promulgate any and all
rules necessary to further implement the tax credits to be claimed for the
substantial rehabilitation of qualified commercial structures under this
section and shall solicit advice from the department in promulgating rules for
transfers of such tax credits. Any such rules must be promulgated in accordance
with article 4 of title 24.
(c)
Notwithstanding any other provision of law, a taxpayer shall not claim a credit
under this section in connection with the rehabilitation of a historic
structure for which the taxpayer is also claiming a credit under section
39-22-514.
(16) Tax
preference performance statement.
(a) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure or extends an expiring tax expenditure to include a tax
preference performance statement as part of a statutory legislative
declaration, the general assembly declares that the general purposes of the tax
credit created in this section are to induce certain designated behavior by
taxpayers and to provide tax relief for certain businesses or individuals. The
specific purposes of the tax credit are to provide an incentive to taxpayers to
rehabilitate qualified structures in a way that increases the number of net new
rental housing units in the state and to provide a greater incentive for
taxpayers who develop such units for rental to low- and moderate-income renters
who need affordable and middle-income housing.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (16)(a) of this
section based on the information required to be maintained and reported by the
office to the state auditor pursuant to subsection (16)(c) of this section.
(c) The
office shall maintain a database of any information determined necessary by the
office to evaluate the effectiveness of the income tax credit allowed in this
section in meeting the purposes set forth in subsection (16)(a) of this section
and shall provide such information, which must include the number and value of
tax credits claimed pursuant to this section, the number of net new rental
units developed, including the number of such units developed for rental only
to low- and moderate-income renters, through the rehabilitation of qualified
commercial or residential structures for which tax credits were allowed
pursuant to this section, and, if available, any other information that may be
needed, to the state auditor as part of the state auditor's evaluation of the
tax credit required by section 39-21-305.
(17) Commercial
historic preservation tax credit program cash fund.
(a) The
commercial historic preservation tax credit program cash fund is created in the
state treasury. The fund consists of gifts, grants, donations, fee revenue
credited to the fund pursuant to subsection (6) of this section, and any other
money that the general assembly may appropriate, transfer, or require by law to
be credited to the fund.
(b) The
state treasurer shall credit all interest and income derived from the deposit
and investment of money in the commercial historic preservation tax credit
program cash fund to the fund.
(c)
Money in the fund is continuously appropriated to the office for the purpose of
administering the tax credit issued pursuant to this section.
(d) The
state treasurer shall transfer all unexpended and unencumbered money in the
fund on December 31, 2051, to the general fund.
Source:
L. 2014: Entire
section added, (HB 14-1311), ch. 183, p. 670, § 1, effective May 14. L.
2015: (2)(j) amended, (HB 15-1307), ch. 218, p. 804, § 1, effective August
5. L. 2018: Entire section amended, (HB 18-1190), ch. 344, p. 2046, § 1,
effective May 30; (5.5)(a)(III) and (8)(c)(IV)(A) added, (HB 18-1190), ch. 344,
p. 2046, § 1, effective January 1, 2020. L. 2019: (7)(a.5) amended, (SB
19-241), ch. 390, p. 3477, § 55, effective August 2. L. 2024: (2)(j)(I),
(2)(l)(I), (2)(n), (3), IP(5)(a), (5.5)(a)(I), (5.5)(a)(II), (6)(c), (7)(a),
(7)(a.5), (7)(b), (8)(a), IP(8)(b), (8)(c)(II), (8)(c)(IV)(B), (11), IP(12)(a),
(12)(a)(III), (12)(b), and (14) amended, (5)(b.5), (8)(c)(V), (12)(a.5), (16),
and (17) added, and (5.5)(b) and (8)(f) repealed, (HB 24-1314), ch. 245, p.
1613, § 1, effective August 7. L. 2025: IP(8)(c)(III) amended, (HB
25-1296), ch. 202, p. 913, § 8, effective May 16.
Cross
references: For
the legislative declaration in HB 25-1296, see section 1 of chapter 202,
Session Laws of Colorado 2025.
39-22-515. Tax credit for qualified
equipment utilizing postconsumer waste. (Repealed)
Source:
L. 91: Entire
section added, p. 1990, § 1, effective June 1. L. 92: (6)(f) amended, p.
1262, § 30, effective August 1. L. 2002: (5) repealed, p. 862, § 5,
effective August 7. L. 2004: Entire section repealed, p. 215, § 40,
effective August 4.
39-22-516. Tax credit for purchase of
vehicles using alternative fuels - repeal. (Repealed)
Source:
L. 92: Entire
section added, p. 2244, § 1, effective June 5. L. 98: Entire section
amended, p. 1297, § 2, effective June 1. L. 99: (2.5)(i) amended, p.
984, § 10, effective May 28. L. 2000: (2.5)(a)(III), (2.5)(b),
(2.5)(d)(I), (2.5)(i), (2.7)(b), (2.7)(c), and (4) amended, p. 1445, § 1,
effective August 2. L. 2002: (2.5)(a)(II), (2.5)(e), and (2.5)(i)
amended, p. 1066, § 3, effective August 7. L. 2003: (2.5)(a)(II.5) added
and (2.5)(b)(II)(B) and (2.5)(g) amended, p. 1234, §§ 1, 2, effective September
1. L. 2005: (2.5)(d)(I) amended, p. 681, § 1, effective August 8. L.
2009: (2.5)(b), (2.5)(d)(I), (2.5)(g), (2.5)(i), (3), and (4) amended and
(2.5)(j) and (2.6) added, (HB 09-1331), ch. 416, pp. 2293, 2295, §§ 2, 3,
effective June 4. L. 2010: (2.6)(b)(III) and (2.6)(d)(III) added and
(2.6)(d)(I) amended, (HB 10-1196), ch. 12, p. 65, §§ 1, 2, effective February
24. L. 2011: (2.6)(a)(VI) amended, (HB 11-1081), ch. 262, p. 1142, § 1,
effective January 1, 2014. L. 2013: (2.5)(h) and (2.6)(e) amended, (HB
13-1247), ch. 226, p. 1073, § 4, effective May 15; (2.6)(a)(VI)(B) added by
revision, (HB 13-1247), ch. 226, p. 1073, § 3; (2.6)(a)(VI)(B) added by
revision, (HB 13-1300), ch. 316, p. 1705, § 125.
Editor's
note: Subsection
(4) provided for the repeal of this section, effective December 31, 2016. (See
L. 2009, p. 2295.)
39-22-516.5. Tax credit for innovative
motor vehicles - repeal. (Repealed)
Source:
L. 2009: Entire
section added, (HB 09-1331), ch. 416, p. 2299, § 4, effective June 4. L.
2011: (1)(f) amended, (HB 11-1081), ch. 262, p. 1142, § 2, effective
January 1, 2014. L. 2012: (1)(a), IP(2)(a), (2)(b), (3)(a), (3)(d), and
(3)(e)(II) amended and (2)(c) added, (HB 12-1299), ch. 98, p. 328, § 1,
effective April 12. L. 2013: (1)(f)(II) added by revision, (HB 13-1247),
ch. 226, p. 1074, § 5; IP(2)(a), (2)(b), (4), (5), and (7) amended, (HB
13-1247), ch. 226, p. 1074, § 6, effective May 15.
Editor's
note: Subsection
(7) provided for the repeal of this section, effective December 31, 2018. (See
L. 2013, p. 1074.)
39-22-516.7. Tax credit for innovative
motor vehicles - tax preference performance statement - legislative declaration
- definitions - repeal.
(1) As
used in this section, unless the context otherwise requires:
(a) (I)
(A) "Actual cost incurred" means the actual cost paid by the
purchaser for a used motor vehicle or conversion minus any credits, grants, or
rebates, including federal credits, grants, or rebates for which the purchaser
is eligible, but excluding the credit specified in this section.
(B)
"Actual cost incurred" means the manufacturer's suggested retail
price for a new motor vehicle that a person purchases minus any credits,
grants, or rebates, including federal credits, grants, or rebates for which the
person is eligible, but excluding the credit specified in this section.
(II)
For purposes of a lease, the "actual cost incurred" means the total
of payments contracted in the lease for the motor vehicle minus:
(A) Any
security deposit included in the total of payments;
(B) The
rent charge included in the total of payments;
(C) Any
sales tax included in the total of payments;
(D) Any
titling and registration fees included in the total of payments;
(E) Any
disposition fee included in the total of payments;
(F) Any
administrative fee or any other fee that does not reflect the value of the
motor vehicle included in the total of payments; and
(G) Any
credits, grants, or rebates, including federal credits, grants, or rebates for
which the lessee or lessor is eligible, but excluding the credit specified in
this section.
(b)
"Alternative fuel" has the meaning set forth in section 24-30-1104
(2)(c)(III)(A).
(c)
"Battery capacity" means the quantity of electricity that a battery
is capable of storing, expressed in kilowatt hours, as measured from a one
hundred percent state of charge to a zero percent state of charge.
(d)
"Category 1" means an electric motor vehicle and a plug-in hybrid
electric motor vehicle.
(e)
"Category 1 A" means a conversion of a motor vehicle to an electric
motor vehicle or a plug-in hybrid electric motor vehicle.
(f) and
(g) Repealed.
(g.5)
"Department" means the department of revenue.
(h) to
(j) Repealed.
(k)
"Electric motor vehicle" or "plug-in hybrid electric motor
vehicle" means a motor vehicle that:
(I) Has
a gross vehicle weight rating that does not exceed eight thousand five hundred
pounds;
(II)
Has a maximum speed capability of at least fifty-five miles per hour; and
(III)
Is propelled to a significant extent by:
(A) An
electric motor that draws electricity from a battery that has a capacity of not
less than four kilowatt hours and is capable of being recharged from an
external source of electricity; or
(B)
Power derived from one or more cells which convert chemical energy directly
into electricity by combining oxygen with hydrogen fuel which is stored on
board the vehicle in any form and may or may not require reformation prior to
use.
(k.5)
"Financing entity" means the entity that finances the purchase or
lease of a category 1 vehicle eligible for a credit allowed by this section.
(l)
"Gross vehicle weight rating" or "GVWR" shall have the same
meaning as set forth in section 42-2-402 (6), C.R.S.
(m)
"Hybrid motor vehicle" means a motor vehicle with a hybrid propulsion
system that operates on both electricity and an alternative fuel or traditional
fuel.
(n)
Repealed.
(o)
"Light-duty passenger motor vehicle" means a private passenger motor
vehicle, including vans, capable of seating twelve passengers or less; except
that the term does not include motor homes as defined in section 42-1-102 (57),
C.R.S., or motor vehicles designed to travel on three or fewer wheels in
contact with the ground.
(p)
"Light-duty truck" means a truck between zero and fourteen thousand
pounds GVWR.
(p.5)
"Manufacturer's suggested retail price" has the same meaning as set
forth in section 42-1-102 (50).
(q)
"Medium-duty truck" means a truck with a gross vehicle weight rating
greater than fourteen thousand pounds up to twenty-six thousand pounds.
(r) (I)
"Motor vehicle" means, for tax years commencing prior to January 1,
2017, a self-propelled vehicle with four wheels, including a truck and a hybrid
motor vehicle, that is:
(A)
Titled and registered in the state; and
(B)
Required to be licensed or subject to licensing for operation upon the highways
of the state.
(II)
"Motor vehicle" means, for tax years commencing on or after January
1, 2017, a self-propelled vehicle with four wheels, including a truck and a
hybrid motor vehicle, that is:
(A)
New, not used, unless the motor vehicle is being converted;
(B)
Titled and registered in the state; and
(C)
Required to be licensed or subject to licensing for operation upon the highways
of the state.
(r.1)
"Motor vehicle dealer" has the same meaning as set forth in section
44-20-102 (18).
(r.3)
(I) "Purchaser" means the buyer or the lessee of a category 1
vehicle, but, for income tax years commencing before January 1, 2024, does not
include the state or any political subdivision of the state. For tax years
commencing on or after January 1, 2017, a lessee seeking to claim a credit
allowed in this section must enter into a lease with a term of not less than
two years.
(II)
For income tax years commencing on or after January 1, 2024,
"purchaser" includes a person or a political subdivision of the state
that is exempt from taxation under section 39-22-112 (1).
(s)
"Traditional fuel" means a petroleum-based motor fuel commonly used
on the highways of the state in the year 2008.
(1.5)
(a) In accordance with section 39-21-304 (1), which requires each bill that
extends an expiring tax expenditure to include a tax preference performance
statement as part of a statutory legislative declaration, the general assembly
finds and declares that the purpose of the tax credit provided for in this
section is to induce certain designated behavior by taxpayers, specifically the
sale and purchase or lease of electric motor vehicles, by providing a reduction
in income tax liability to the purchaser or lessee or to a motor vehicle dealer
or financing entity in connection with the sale and purchase or lease of an
electric motor vehicle.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1.5)(a) of this
section based on the number and value of credits claimed.
(2) (a)
With respect to the tax years commencing on or after January 1, 2013, but prior
to January 1, 2029, there is allowed to any person a credit against the tax
imposed by this article 22, not to exceed the amount specified in subsection
(4) of this section, for the purchase or lease of a motor vehicle defined as
category 1.
(a.3) to
(b) Repealed.
(c)
With respect to the tax years commencing on or after January 1, 2014, but prior
to January 1, 2022, there is allowed to any person a credit against the tax
imposed by this article, not to exceed the amount specified in subsection (4)
of this section, for the conversion of a motor vehicle defined as category 1 A.
(d)
Repealed.
(e) (I)
A purchaser may assign the tax credit allowed in this section for the purchase
or lease of a category 1 or category 1 A vehicle completed on or after January
1, 2017, but prior to January 1, 2024, to a financing entity as follows:
(A) The
assignment to the financing entity must be completed at the time of purchase or
lease by entering into an election statement as set forth in subparagraph (III)
of this paragraph (e);
(B) The
purchaser must title and register the vehicle in the state as required by state
law;
(C) The
purchaser must assign the tax credit to the financing entity and forfeit the
right to claim the tax credit on the purchaser's tax return in exchange for
good and valuable consideration; and
(D) The
financing entity shall compensate the purchaser for the full nominal value of
the tax credit; except that the financing entity may collect an administrative
fee not to exceed one hundred fifty dollars for processing the assignment. The
compensation paid to the purchaser is considered a refund of state taxes and is
not income.
(II)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a financing entity pursuant to this paragraph (e), the financing entity
receives the full amount of the tax credit that the purchaser is allowed in
this section. Any unpaid balance or unpaid debt of the purchaser may not be
credited from the amount of the tax credit allowed in this section.
(III)
To complete the tax credit assignment, the purchaser and the financing entity
must enter into an election statement that must:
(A)
Identify the vehicle identification number of the category 1 or category 1 A
vehicle for which a credit is allowed in this section; and
(B)
Affirm that the requirements specified in subparagraph (I) of this paragraph
(e) were met.
(IV)
The financing entity may authorize an agent or a designee to sign the election
statement on its behalf.
(V) The
financing entity shall electronically submit a report containing the
information contained in the election statement described in subparagraph (III)
of this paragraph (e) to the department of revenue within thirty days of the
purchase or lease of a category 1 or category 1 A vehicle in such a form and in
such a manner as required by the department.
(VI)
The financing entity shall also file the election statement described in
subparagraph (III) of this paragraph (e) with the original tax return for the
taxable year in which the category 1 or category 1 A vehicle is purchased or
leased.
(VII)
The department of revenue, in consultation with the Colorado energy office
created in section 24-38.5-101, C.R.S., shall develop a model report and
election statement no later than December 1, 2016.
(VIII)
This subsection (2)(e) is repealed, effective December 31, 2028.
(f) (I)
A purchaser may assign the tax credit allowed in this section for the purchase
or lease of a category 1 vehicle completed on or after January 1, 2024, to a
financing entity or to a motor vehicle dealer as follows:
(A) The
assignment to the financing entity or the motor vehicle dealer must be
completed at the time of purchase or lease by entering into an election
statement as set forth in subsection (2)(f)(III) of this section;
(B) The
purchaser must title and register the vehicle in the state as required by state
law;
(C) The
purchaser must assign the tax credit to the financing entity or the motor
vehicle dealer and forfeit the right to claim the tax credit on the purchaser's
tax return in exchange for the good and valuable consideration described in
subsection (2)(f)(I)(D) of this section; and
(D) The
financing entity or the motor vehicle dealer shall compensate the purchaser for
the full nominal value of the tax credit including, if applicable, the amounts
allowed pursuant to subsections (4)(a)(XI) and (4)(a.5) of this section; except
that the financing entity or the motor vehicle dealer may collect an
administrative fee not to exceed two hundred fifty dollars for processing the
assignment. The compensation paid to the purchaser is considered a refund of
state taxes and is not income.
(II)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a financing entity or to a motor vehicle dealer pursuant to this subsection
(2)(f), the financing entity or the motor vehicle dealer receives the full
amount of the tax credit that the purchaser is allowed in this section. Any
unpaid balance or unpaid debt of the purchaser may not be credited from the
amount of the tax credit allowed in this section.
(III)
To complete the tax credit assignment, the purchaser and the financing entity
or the motor vehicle dealer shall enter into an election statement that:
(A)
Identifies the vehicle identification number of the category 1 vehicle for
which a credit is allowed in this section;
(B)
Identifies the manufacturer's suggested retail price of the category 1 vehicle
for which a credit is allowed in this section;
(C)
Specifies the value of the credit allowed; and
(D)
Affirms that the requirements specified in subsection (2)(f)(I) of this section
were met.
(IV)
The financing entity or the motor vehicle dealer may authorize an agent or a
designee to sign the election statement on its behalf.
(V) For
the purchase or lease of a category 1 vehicle completed on or after January 1,
2024, the financing entity or the motor vehicle dealer shall electronically
submit a report containing the information contained in the election statement
described in subsection (2)(f)(III) of this section to the department on a
quarterly basis in a form and manner required by the department for all
purchases or leases of a category 1 vehicle completed in the reporting period.
(VI)
The financing entity or the motor vehicle dealer shall maintain the election
statement described in subsection (2)(f)(III) of this section and produce it
upon request by the department for an audit.
(VII)
For income tax years commencing on or after January 1, 2025, the financing
entity or motor vehicle dealer may elect advance payments of credits assigned
under this subsection (2)(f) as specified in section 39-22-629.
(3) If
a motor vehicle is leased, the lessee, not the lessor, is allowed to claim the
credit allowed pursuant to this section. The lessee may elect to assign the tax
credit allowed pursuant to this section for the lease of a category 1 vehicle
to a financing entity or to a motor vehicle dealer as specified in subsection
(2)(e) or (2)(f), as applicable, of this section.
(4) The
amount of the credit allowed pursuant to this section is calculated as follows:
(a) Category
1.
(I)
With respect to the tax years commencing on or after January 1, 2013, but prior
to January 1, 2017, the actual cost incurred by the taxpayer during the tax
year for purchasing or leasing a category 1 motor vehicle multiplied by the
battery capacity of the motor vehicle and divided by one hundred, not to exceed
six thousand dollars;
(II)
With respect to the tax years commencing on or after January 1, 2017, but prior
to January 1, 2020, five thousand dollars for a purchase or two thousand five
hundred dollars for a lease;
(III)
With respect to the tax years commencing on or after January 1, 2020, but prior
to January 1, 2021, four thousand dollars for a purchase or two thousand
dollars for a lease;
(IV)
With respect to the tax years commencing on or after January 1, 2021, but prior
to January 1, 2023, two thousand five hundred dollars for a purchase or one
thousand five hundred dollars for a lease;
(V)
With respect to the purchase or lease of a category 1 vehicle sold or leased on
or after January 1, 2023, but prior to July 1, 2023, two thousand dollars for a
purchase or one thousand five hundred dollars for a lease;
(VI)
Except as otherwise provided in subsection (4)(a)(XI) of this section, with
respect to the purchase or lease of a category 1 vehicle sold or leased on or
after July 1, 2023, but before January 1, 2025, five thousand dollars for a
purchase or a lease;
(VII)
Except as otherwise provided in subsection (4)(a)(XI) of this section, with
respect to the purchase or lease of a category 1 vehicle sold or leased in tax
years commencing on or after January 1, 2025, but before January 1, 2026, three
thousand five hundred dollars;
(VIII)
Except as otherwise provided in subsection (4)(a.7) of this section, with
respect to the purchase or lease of a category 1 vehicle sold or leased in tax
years commencing on or after January 1, 2026, but before January 1, 2027, one
thousand five hundred dollars;
(IX)
Except as otherwise provided in subsection (4)(a.7) of this section, with
respect to the purchase or lease of a category 1 vehicle sold or leased in tax
years commencing on or after January 1, 2027, but before January 1, 2028, two
thousand dollars;
(X)
Except as otherwise provided in subsection (4)(a.7) of this section, with
respect to the purchase or lease of a category 1 vehicle sold or leased in tax
years commencing on or after January 1, 2028, but before January 1, 2029, one
thousand dollars; and
(XI)
With respect to a purchase or lease of a category 1 vehicle sold or leased at a
location where the credit allowed in this section may be assigned and if the
credit is assigned pursuant to subsection (2)(f) of this section in a tax year
that commences on or after January 1, 2024, but before January 1, 2026, an
additional amount of six hundred dollars may be claimed by a financing entity
or motor vehicle dealer when the purchaser assigns the credit to the financing
entity or motor vehicle dealer.
(a.3) Limitation
on credit.
(I) No
credit is allowed for a purchase or lease made on or after July 1, 2023, but
before January 1, 2027, of a category 1 vehicle that exceeds a manufacturer's
suggested retail price of eighty-thousand dollars.
(II) No
credit is allowed for a purchase or lease made on or after January 1, 2027, but
before January 1, 2029, of a category 1 vehicle that exceeds a manufacturer's
suggested retail price of fifty thousand dollars.
(a.5)
(I) Category 1 for vehicles under $35,000 threshold. With respect to
the purchase or lease of a category 1 vehicle sold or leased in tax years
commencing on or after January 1, 2024, but prior to January 1, 2027, with a
manufacturer's suggested retail price below thirty-five thousand dollars there
is allowed an additional two thousand five hundred dollars of credit in
addition to the amount of credit allowed pursuant to subsection (4)(a) of this
section.
(II) Category
1 for vehicles under $40,000 threshold. With respect to the purchase or
lease of a category 1 vehicle sold or leased in tax years commencing on or
after January 1, 2027, but prior to January 1, 2029, with a manufacturer's
suggested retail price below forty thousand dollars there is allowed an
additional two thousand five hundred dollars of credit in addition to the
amount of credit allowed pursuant to subsection (4)(a) of this section.
(a.7)
(I) If the June 2025 revenue forecast, as prepared by either legislative
council staff or the office of state planning and budgeting, projects that
state revenues, as defined in section 24-77-103.6 (6)(c), will not increase by
at least four percent for the next fiscal year, the amount of the credit
allowed pursuant to subsection (4)(a)(VIII), (4)(a)(IX), or (4)(a)(X) of this
section for the income tax year commencing in the calendar year that begins
during said next fiscal year is reduced by fifty percent; except that if the
amount of reduced credit is equal to or less than five hundred dollars, then no
credit is available for that income tax year.
(II)
This subsection (4)(a.7) is repealed, effective December 31, 2031.
(b) Category
1 A.
(I)
With respect to the tax years commencing on or after January 1, 2013, but prior
to January 1, 2017, seventy-five percent of the actual cost incurred by the
taxpayer during the tax year for the conversion of a motor vehicle defined as
category 1 A, not to exceed six thousand dollars;
(II)
With respect to the tax years commencing on or after January 1, 2017, but prior
to January 1, 2020, five thousand dollars;
(III)
With respect to the tax years commencing on or after January 1, 2020, but prior
to January 1, 2021, four thousand dollars;
(IV)
With respect to the tax years commencing on or after January 1, 2021, but prior
to January 1, 2022, two thousand five hundred dollars.
(c) to
(g) Repealed.
(5)
With respect to any model year 2004 and newer hybrid motor vehicle, a taxpayer
that converts such a motor vehicle to a category 1 A motor vehicle shall be
eligible for the category 1 A credit.
(6)
Repealed.
(7) If
a credit authorized in this section exceeds the income tax due on the income of
the taxpayer for the taxable year, the excess credit may not be carried forward
and shall be refunded to the taxpayer.
(8)
With respect to tax years commencing on or after January 1, 2017, the taxpayer
claiming a credit allowed in this section shall provide the department of
revenue with, and the department shall commence tracking, the vehicle
identification number of the motor vehicle for which a credit is claimed as
allowed in this section.
(9)
Making the purchaser aware of the income tax credit allowed in this section or
helping the purchaser assign the income tax credit to a financing entity or to
a motor vehicle dealer as allowed in this section does not rise to the level of
providing the purchaser with unauthorized tax advice.
(9.5)
With respect to the tax years commencing on or after January 1, 2019, a
transportation network company, as defined in section 40-10.1-602 (3), or a
third-party vehicle supplier that contracts with a transportation network
company to provide category 1 motor vehicles for short-term rental to
transportation network company drivers, as defined in section 40-10.1-602 (4),
that enters into long-term leases with a duration of not less than two years
for category 1 motor vehicles shall be treated as having purchased each
category 1 motor vehicle for purposes of the credit calculation specified in
subsection (4)(a) of this section if the vehicles are offered to transportation
network company drivers, as defined in section 40-10.1-602 (4), for short-term
rental periods of not more than sixty days.
(10) A
purchaser, as set forth in subsection (1)(r.3)(II) of this section, who claims
the credit under this section shall file a return pursuant to section 39-22-601
(7)(b).
(11) A
purchaser who claims a tax credit under this section or who assigns a tax
credit pursuant to subsection (2)(f) of this section is entitled to
additionally receive any rebate that is part of an electric vehicle program
pursuant to sections 40-3-116 and 40-5-107.
(12)
This section is repealed, effective December 31, 2033.
Source:
L. 2013: Entire
section added, (HB 13-1247), ch. 226, p. 1067, § 2, effective May 15. L.
2014: (1)(h), (1)(i), (1)(j), (1)(n), (2)(a), (2)(d), (4)(e), (4)(f),
(4)(g), and (6) amended and (2)(a.5) added, (HB 14-1326), ch. 357, p. 1674, §
3, effective June 6; (1)(a)(I)(A) amended, (HB 14-1326), ch. 357, p. 1677, § 4,
effective December 31, 2019. L. 2016: (1)(k.5), (1)(r.3), (2)(a.3),
(2)(e), (9), and (10) added and (1)(r), (2)(a), (2)(c), (3), (4)(a), (4)(b),
(4)(c), (4)(d), and (8) amended, (HB 16-1332), ch. 237, p. 955, § 1, effective
June 6. L. 2019: (1)(k)(III), (2)(a), (4)(a)(IV), and (10) amended and
(4)(a)(V) and (9.5) added, (HB 19-1159), ch. 386, p. 3444, § 2, effective
August 2. L. 2020: (6) amended, (HB 20-1402), ch. 216, p. 1058, § 67,
effective June 30; (1)(b) amended, (HB 20-1167), ch. 56, p. 192, § 3, effective
September 14. L. 2023: (1)(g.5), (1)(p.5), (1)(r.1), (1.5),
(2)(e)(VIII), (2)(f), (4)(a)(VI) to (4)(a)(XI), (4)(a.3), (4)(a.5), (4)(a.7),
(11), and (12) added and (1)(k.5), IP(1)(r)(II), (1)(r.3), (2)(a), IP(2)(e)(I),
(3), (4)(a)(V), (9), and (10) amended, (HB 23-1272), ch. 167, p. 766, § 2,
effective May 11; (1)(f), (1)(g), and (2)(a.3) repealed, (HB 23-1251), ch. 437,
p. 2572, § 1, effective August 7. L. 2024: (5) amended and (6) repealed,
(HB 24-1450), ch. 490, p. 3425, § 79, effective August 7. L. 2026:
(4)(a)(IX), (4)(a)(X), (4)(a.3), (4)(a.5), and (4)(a.7) amended, (HB 26-1289),
ch. 364, p. 2194, § 7, effective June 3.
Editor's
note: (1)
Subsection (2)(b)(II) provided for the repeal of subsection (2)(b), effective
December 31, 2018. (See L. 2013, p. 1067.)
(2) Subsections (1)(h)(II),
(1)(i)(II), (1)(j)(II), (1)(n)(II), (2)(a.5)(II), (2)(d)(II), (4)(e)(II),
(4)(f)(II), and (4)(g)(II) provided for the repeal of subsections (1)(h),
(1)(i), (1)(j), (1)(n), (2)(a.5), (2)(d), (4)(e), (4)(f), and (4)(g), respectively,
effective December 31, 2019. (See L. 2014, p. 1674.)
(3) Subsections (4)(c)(VI) and
(4)(d)(VI) provided for the repeal of subsections (4)(c) and (4)(d),
respectively, effective December 31, 2021. (See L. 2016, p. 955.)
Cross
references: (1)
For the legislative declaration in the 2013 act adding this section, see
section 1 of chapter 226, Session Laws of Colorado 2013.
(2) For the legislative
declaration in HB 14-1326, see section 1 of chapter 357, Session Laws of
Colorado 2014. For the legislative declaration in HB 19-1159, see section 1 of
chapter 386, Session Laws of Colorado 2019. For the legislative declaration in
HB 23-1272, see section 1 of chapter 167, Session Laws of Colorado 2023. For
the legislative declaration in HB 26-1289, see section 1 of chapter 364,
Session Laws of Colorado 2026.
39-22-516.8. Tax credit for innovative
trucks - tax preference performance statement - legislative declaration -
definitions - repeal.
(1) As
used in this section, unless the context otherwise requires:
(a) (I)
"Actual cost incurred" means the actual cost paid by the purchaser
for a new or used truck or clean fuel refrigerated trailer, conversion of a
truck or clean fuel refrigerated trailer, idling reduction technologies, or
aerodynamic technologies, minus any credits, grants, or rebates, including
federal credits, grants, or rebates for which the purchaser is eligible, but
excluding the credit specified in this section.
(II)
For purposes of a lease, "actual cost incurred" means the total of
payments contracted in the lease for the truck minus:
(A) Any
security deposit included in the total of payments;
(B) The
rent charge included in the total of payments;
(C) Any
sales tax included in the total of payments;
(D) Any
titling and registration fees included in the total of payments;
(E) Any
disposition fee included in the total of payments;
(F) Any
administrative fee or any other fee that does not reflect the value of the
truck included in the total of payments; and
(G) Any
credits, grants, or rebates, including federal credits, grants, or rebates for
which the lessee or lessor is eligible, but excluding the credit specified in
this section.
(b)
"Aerodynamic technologies" means a device on the United States
environmental protection agency's smartway verified technology list that
minimizes drag and improves air flow over a truck and trailer; except that
"aerodynamic technologies" do not include tires.
(c)
"Alternative fuel" has the meaning set forth in section 24-30-1104
(2)(c)(III)(A).
(d)
"Battery capacity" means the quantity of electricity that a battery
is capable of storing, expressed in kilowatt hours, as measured from a one
hundred percent state of charge to a zero percent state of charge.
(e)
"Bus" means a motor vehicle with a minimum seating capacity of
thirty-three, including the driver.
(f)
"Category 4" means original equipment manufacturer trucks that are
equipped to operate on compressed natural gas or on liquefied petroleum gas.
For purposes of this paragraph (f), "operate on compressed natural gas or
on liquefied petroleum gas" means a truck that operates exclusively on
compressed natural gas or on liquefied petroleum gas, or a bi-fuel truck with a
multi-fuel engine capable of running on either compressed natural gas or
traditional fuel, or on either liquefied petroleum gas or traditional fuel, or
a dual-fuel truck with a multi-fuel engine capable of running on both
compressed natural gas and traditional fuel, or on both liquefied petroleum gas
and traditional fuel.
(g)
"Category 4 A" means compressed natural gas or liquefied petroleum
gas conversions certified by the United States environmental protection agency.
For purposes of this paragraph (g), "compressed natural gas or liquefied
petroleum gas conversions" means a conversion to a truck that operates
exclusively on compressed natural gas or on liquefied petroleum gas, or a
bi-fuel truck with a multi-fuel engine capable of running on either compressed
natural gas or traditional fuel, or on either liquefied petroleum gas or
traditional fuel, or a dual-fuel truck with a multi-fuel engine capable of
running on both compressed natural gas and traditional fuel, or on both
liquefied petroleum gas and traditional fuel.
(h)
"Category 4 B" means original equipment manufacturer trucks that are
equipped to operate on liquefied natural gas. For purposes of this subsection
(1)(h), "operate on liquefied natural gas" means a truck that
operates exclusively on liquefied natural gas, or a bi-fuel truck with a
multi-fuel engine capable of running on either liquefied natural gas or
traditional fuel, or a dual-fuel truck with a multi-fuel engine capable of
running on both liquefied natural gas and traditional fuel.
(i)
"Category 4 C" means liquefied natural gas conversions certified by
the United States environmental protection agency. For purposes of this
subsection (1)(i), "liquefied natural gas conversions" means a
conversion to a truck that operates exclusively on liquefied natural gas, or a
bi-fuel truck with a multi-fuel engine capable of running on either liquefied
natural gas or traditional fuel, or a dual-fuel truck with a multi-fuel engine
capable of running on both liquefied natural gas and traditional fuel.
(j)
"Category 5" means the installation of any idling reduction
technologies on or in a truck.
(k)
"Category 6" means the installation of any aerodynamic technologies
on or in a truck.
(l)
"Category 7" means an original equipment manufacturer electric truck
and plug-in hybrid electric truck.
(m)
"Category 7 A" means a conversion of a truck to an electric truck or
a plug-in hybrid electric truck.
(n)
"Category 8" means a clean fuel refrigerated trailer.
(o)
"Category 8 A" means a conversion of a refrigerated trailer to a
clean fuel refrigerated trailer.
(p)
"Category 9" means a hydraulic hybrid truck.
(q)
"Clean fuel refrigerated trailer" means a trailer capable of being
pulled by a truck with a gross vehicle weight rating greater than fourteen
thousand pounds, with a power unit and fuel storage used for climate control
that:
(I) (A)
Is installed on the trailer by the original equipment manufacturer; or
(B) Is
installed on the trailer through a conversion certified by the United States
environmental protection agency; and
(II)
Operates on either compressed natural gas, liquefied natural gas, liquefied
petroleum gas, hydrogen, or electricity, or any combination thereof.
(q.5)
"Department" means the department of revenue.
(r)
"Electric truck" or "plug-in hybrid electric truck" means a
truck that:
(I) Has
a gross vehicle weight rating that exceeds eight thousand five hundred pounds;
(II)
Has a maximum speed capability of at least fifty-five miles per hour; and
(III)
Is propelled to a significant extent by:
(A) An
electric motor that draws electricity from a battery that has a capacity of not
less than four kilowatt hours and is capable of being recharged from an
external source of electricity; or
(B)
Power derived from one or more cells which convert chemical energy directly
into electricity by combining oxygen with hydrogen fuel which is stored on
board the vehicle in any form and may or may not require reformation prior to
use.
(r.5)
"Financing entity" means the entity that finances the purchase or
lease of a category 4, category 4 A, category 4 B, category 4 C, category 7,
category 7 A, or category 9 vehicle eligible for a credit allowed by this
section.
(s)
"Gross vehicle weight rating" or "GVWR" has the same
meaning as set forth in section 42-2-402 (6), C.R.S.
(t)
"Heavy-duty truck" means a truck with a gross vehicle weight rating
greater than twenty-six thousand pounds.
(u)
"Hybrid truck" means a truck with a hybrid propulsion system that
operates on both electricity and an alternative fuel or traditional fuel.
(v)
"Hydraulic hybrid truck" means the conversion of a truck with a gross
vehicle weight rating of more than fourteen thousand pounds to a truck with a
hybrid propulsion system that operates on both pressurized fluid and either
compressed natural gas, liquefied natural gas, liquefied petroleum gas,
hydrogen, electricity, or a traditional fuel; except that the converted
hydraulic hybrid truck must increase the fuel economy of the original truck.
(w)
"Idling reduction technologies" means idling reduction devices or
advanced insulation, as those terms are defined in section 4053 of the internal
revenue code, as amended, that are exempt from federal excise tax pursuant to
said section 4053.
(x)
"Light-duty electric truck" means an electric truck with a gross
vehicle weight rating less than or equal to ten thousand pounds but does not
include a light-duty passenger motor vehicle.
(y)
"Light-duty passenger motor vehicle" means a private passenger motor
vehicle, including vans, capable of seating twelve passengers or less; except
that the term does not include motor homes as defined in section 42-1-102 (57),
C.R.S., or motor vehicles designed to travel on three or fewer wheels in
contact with the ground.
(z)
"Light-duty truck" means a truck with a gross vehicle weight rating
less than or equal to fourteen thousand pounds but does not include a
light-duty passenger motor vehicle.
(aa)
"Medium-duty electric truck" means an electric truck with a gross
vehicle weight rating greater than ten thousand pounds and up to twenty-six
thousand pounds.
(bb)
"Medium-duty truck" means a truck with a gross vehicle weight rating
greater than fourteen thousand pounds and up to twenty-six thousand pounds.
(bb.1)
"Motor vehicle dealer" has the same meaning as set forth in section
44-20-102 (18).
(bb.3)
(I) "Purchaser" means the buyer or the lessee of a category 4,
category 4 A, category 4 B, category 4 C, category 7, category 7 A, or category
9 vehicle, but, for income tax years commencing before January 1, 2024, does
not include the state or any political subdivision of the state. For tax years
commencing on or after January 1, 2017, a lessee seeking to claim a credit
allowed in this section must enter into a lease with a term of not less than
two years.
(II)
For income tax years commencing on or after January 1, 2024,
"purchaser" includes a person or political subdivision of the state
who is exempt from taxation under section 39-22-112 (1).
(cc)
"Traditional fuel" means a petroleum-based motor fuel commonly used
on the highways of the state in the year 2008.
(dd)
"Trailer" has the same meaning as in section 42-1-102 (105), C.R.S.
(ee)
(I) "Truck", for tax years commencing prior to January 1, 2017,
has the same meaning as in section 42-1-102 (108), C.R.S., includes a hybrid
truck, a light-duty passenger motor vehicle, and a bus, has a maximum speed
capability of at least fifty-five miles per hour, is licensed or subject to
licensing for operation upon the highways of the state, and is either:
(A)
Titled and registered in the state; or
(B)
Registered under the international registration plan and base plated in the
state.
(II)
"Truck", for tax years commencing on or after January 1, 2017, has
the same meaning as in section 42-1-102 (108), C.R.S., and includes a hybrid
truck, a light-duty passenger motor vehicle, and a bus, has a maximum speed
capability of at least fifty-five miles per hour, is licensed or subject to
licensing for operation upon the highways of the state, is new, not used,
unless the truck is being converted, and is either:
(A)
Titled and registered in the state; or
(B)
Registered under the international registration plan and base plated in the
state.
(1.5)
(a) In accordance with section 39-21-304 (1), which requires each bill that
extends an expiring tax expenditure to include a tax preference performance
statement as part of a statutory legislative declaration, the general assembly
finds and declares that the purpose of the tax credit provided in this section
is to induce certain designated behavior by taxpayers, specifically the sale
and purchase or lease of electric light-duty, medium-duty, or heavy-duty
trucks, by providing a reduction in income tax liability to the purchaser or
lessee or to a financing entity in connection with the sale and purchase or
lease of an electric light-duty, medium-duty, or heavy-duty truck.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1.5)(a) of this
section based on the number and value of credits claimed.
(2) Category
4.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (2) of the actual cost incurred by the taxpayer during the tax year
for each purchase or lease of a category 4 truck, not to exceed the amount set
forth in paragraph (b) of this subsection (2). For purposes of the income tax
year commencing on or after January 1, 2014, but before January 1, 2015, the
purchase or lease of a category 4 truck must occur on or after July 1, 2014,
but before January 1, 2015.
(b)
|
|
Income
tax year
commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per
income
tax
year
|
|
Light-duty
passenger motor vehicle
|
18%
|
$6,000
|
|
Light-duty
truck
|
18%
|
$7,500
|
|
Medium-duty
truck
|
18%
|
$15,000
|
|
Heavy-duty
truck
|
18%
|
$20,000
|
(2.3) Category
4 purchase.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article in an amount set forth in paragraph (b) of this subsection (2.3) for
each purchase of a category 4 truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$5,000
|
$4,000
|
$2,500
|
|
Light-duty
truck
|
$7,000
|
$5,500
|
$3,500
|
|
Medium-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
(2.5) Category
4 lease.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article in an amount set forth in paragraph (b) of this subsection (2.5) for
each lease of a category 4 truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$2,500
|
$2,000
|
$1,500
|
|
Light-duty
truck
|
$3,500
|
$2,750
|
$1,750
|
|
Medium-duty
truck
|
$5,000
|
$4,000
|
$2,500
|
|
Heavy-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
(3) Category
4 A.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (3) of the actual cost incurred by the taxpayer during the tax year
for the conversion of a category 4 A truck, not to exceed the amount set forth
in paragraph (b) of this subsection (3). For purposes of the income tax year
commencing on or after January 1, 2014, but before January 1, 2015, the
conversion of a category 4 A truck must occur on or after July 1, 2014, but
before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per income
tax
year
|
|
Light-duty
passenger motor vehicle
|
55%
|
$6,000
|
|
Light-duty
truck
|
55%
|
$7,500
|
|
Medium-duty
truck
|
55%
|
$15,000
|
|
Heavy-duty
truck
|
55%
|
$20,000
|
(3.5) Category
4 A.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article an amount set forth in paragraph (b) of this subsection (3.5) for the
conversion of a category 4 A truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$5,000
|
$4,000
|
$2,500
|
|
Light-duty
truck
|
$7,000
|
$5,500
|
$3,500
|
|
Medium-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
(4) Category
4 B.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (4) of the actual cost incurred by the taxpayer during the tax year
for each purchase or lease of a category 4 B truck, not to exceed the amount
set forth in paragraph (b) of this subsection (4). For purposes of the income
tax year commencing on or after January 1, 2014, but before January 1, 2015,
the purchase or lease of a category 4 B truck must occur on or after July 1,
2014, but before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per
income
tax
year
|
|
Light-duty
passenger motor vehicle
|
18%
|
$6,000
|
|
Light-duty
truck
|
18%
|
$7,500
|
|
Medium-duty
truck
|
18%
|
$15,000
|
|
Heavy-duty
truck
|
18%
|
$20,000
|
(4.3) Category
4 B purchase.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article an amount set forth in paragraph (b) of this subsection (4.3) for each
purchase of a category 4 B truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$5,000
|
$4,000
|
$2,500
|
|
Light-duty
truck
|
$7,000
|
$5,500
|
$3,500
|
|
Medium-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
(4.5) Category
4 B lease.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article an amount set forth in paragraph (b) of this subsection (4.5) for each
lease of a category 4 B truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$2,500
|
$2,000
|
$1,500
|
|
Light-duty
truck
|
$3,500
|
$2,750
|
$1,750
|
|
Medium-duty
truck
|
$5,000
|
$4,000
|
$2,500
|
|
Heavy-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
(5) Category
4 C.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (5) of the actual cost incurred by the taxpayer during the tax year
for the conversion of a category 4 C truck, not to exceed the amount set forth
in paragraph (b) of this subsection (5). For purposes of the income tax year
commencing on or after January 1, 2014, but before January 1, 2015, the
conversion of a category 4 C truck must occur on or after July 1, 2014, but
before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per income
tax
year
|
|
Light-duty
passenger motor vehicle
|
55%
|
$6,000
|
|
Light-duty
truck
|
55%
|
$7,500
|
|
Medium-duty
truck
|
55%
|
$15,000
|
|
Heavy-duty
truck
|
55%
|
$20,000
|
(5.5) Category
4 C.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article in the amount set forth in paragraph (b) of this subsection (5.5) for
the conversion of a category 4 C truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle
|
$5,000
|
$4,000
|
$2,500
|
|
Light-duty
truck
|
$7,000
|
$5,500
|
$3,500
|
|
Medium-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
(6) Category
5. With respect to the income tax years commencing on or after January 1,
2015, but before January 1, 2022, there is allowed to any person a credit
against the tax imposed by this article of twenty-five percent of the actual
cost incurred by the taxpayer during a tax year for category 5, not to exceed
six thousand dollars.
(7) Category
6. With respect to the income tax years commencing on or after January 1,
2014, but before January 1, 2022, there is allowed to any person a credit
against the tax imposed by this article of twenty-five percent of the actual
cost incurred by the taxpayer during a tax year for category 6, not to exceed
six thousand dollars for each installed device and not to exceed fifty thousand
dollars during a tax year for the installation of multiple devices. For
purposes of the income tax year commencing on or after January 1, 2014, but
before January 1, 2015, the installation must occur on or after July 1, 2014,
but before January 1, 2015.
(8) Category
7.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (8) of the actual cost incurred by the taxpayer during the tax year
for each purchase or lease of a category 7 truck, not to exceed the amount set
forth in paragraph (b) of this subsection (8). For purposes of the income tax
year commencing on or after January 1, 2014, but before January 1, 2015, the
purchase or lease of a category 7 truck must occur on or after July 1, 2014,
but before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per income
tax
year
|
|
Light-duty
passenger motor vehicle over
8,500
GVWR
|
18%
|
$6,000
|
|
Light-duty
electric truck
|
18%
|
$7,500
|
|
Medium-duty
electric truck
|
18%
|
$15,000
|
|
Heavy-duty
truck
|
18%
|
$20,000
|
(8.3) Category
7 purchase.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1, 2024,
there is allowed to any person a credit against the tax imposed by this article
22 in an amount set forth in subsection (8.3)(b) of this section for each
purchase of a category 7 truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2023
|
1/1/2023
but
before
1/1/2024
|
|
Light-duty
passenger motor vehicle
over
8,500 GVWR
|
$5,000
|
$4,000
|
$2,500
|
$2,000
|
|
Light-duty
electric truck
|
$7,000
|
$5,500
|
$3,500
|
$2,800
|
|
Medium-duty
electric truck
|
$10,000
|
$8,000
|
$5,000
|
$4,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
$8,000
|
(8.5) Category
7 lease.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2024, there is allowed to any person a credit against the tax imposed by this
article 22 in an amount set forth in subsection (8.5)(b) of this section for
each lease of a category 7 truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2024
|
|
Light-duty
passenger motor vehicle over
8,500
GVWR
|
$2,500
|
$2,000
|
$1,500
|
|
Light-duty
electric truck
|
$3,500
|
$2,750
|
$1,750
|
|
Medium-duty
electric truck
|
$5,000
|
$4,000
|
$2,500
|
|
Heavy-duty
truck
|
$10,000
|
$8,000
|
$5,000
|
(8.7)
(a) Category 7 light-duty passenger motor vehicle over 8,500 GVWR or
light-duty electric truck lease or purchase for tax years 2024 through 2028.
Except as otherwise provided in subsection (8.7)(d) of this section, with
respect to income tax years commencing on or after January 1, 2024, but before
January 1, 2029, for each purchase or lease of a category 7 light-duty
passenger motor vehicle over 8,500 GVWR or a light-duty electric truck sold or
leased during the tax year, there is allowed to any person a credit against the
tax imposed by this article 22 in an amount as follows:
(I) For
income tax years commencing on or after January 1, 2024, but before January 1,
2025, five thousand dollars;
(II)
For income tax years commencing on or after January 1, 2025, but before January
1, 2026, three thousand five hundred dollars;
(III)
For income tax years commencing on or after January 1, 2026, but before January
1, 2027, one thousand five hundred dollars;
(IV)
For income tax years commencing on or after January 1, 2027, but before January
1, 2028, one thousand dollars; and
(V) For
income tax years commencing on or after January 1, 2028, but before January 1,
2029, five hundred dollars.
(b) Category
7 medium-duty electric truck lease or purchase for tax years 2024 through 2032.
With respect to income tax years commencing on or after January 1, 2024, but
before January 1, 2033, for each purchase or lease of a category 7 medium-duty
electric truck sold or leased during the tax year, there is allowed to any
person a credit against the tax imposed by this article 22 in an amount as
follows:
(I) For
income tax years commencing on or after January 1, 2024, but before January 1,
2026, twelve thousand dollars; and
(II)
For income tax years commencing on or after January 1, 2026, but before January
1, 2033, four thousand dollars.
(c) Category
7 heavy-duty truck lease or purchase for tax years 2024 through 2032. With
respect to income tax years commencing on or after January 1, 2024, but before
January 1, 2033, for each purchase or lease of a category 7 heavy-duty truck
sold or leased during the tax year, there is allowed to any person a credit
against the tax imposed by this article 22 in an amount as follows:
(I) For
income tax years commencing on or after January 1, 2024, but before January 1,
2026, twelve thousand dollars; and
(II)
For income tax years commencing on or after January 1, 2026, but before January
1, 2033, eight thousand dollars.
(d) If
the June 2025 revenue forecast, as prepared by either legislative council staff
or the office of state planning and budgeting, projects that state revenues, as
defined in section 24-77-103.6 (6)(c), will not increase by at least four
percent for the next fiscal year, the amount of the credit allowed pursuant to
subsection (8.7)(a)(III), (8.7)(a)(IV), or (8.7)(a)(V) of this section for the
income tax year commencing in the calendar year that begins during said next
fiscal year is reduced by fifty percent; except that if the amount of reduced
credit is equal to or less than five hundred dollars, then no credit is
available for the income tax year.
(9) Category
7 A.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this subsection
(9) of the actual cost incurred by the taxpayer during the tax year for the
conversion of a category 7 A truck, not to exceed the amount set forth in
paragraph (b) of this subsection (9). For purposes of the income tax year
commencing on or after January 1, 2014, but before January 1, 2015, the
conversion of a category 7 A truck must occur on or after July 1, 2014, but
before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but
before
1/1/2017
|
Cap
per
income
tax
year
|
|
Light-duty
passenger motor vehicle with a GVWR
over
8,500 lbs
|
55%
|
$6,000
|
|
Light-duty
electric truck
|
55%
|
$7,50
|
|
Medium-duty
electric truck
|
55%
|
$15,000
|
|
Heavy-duty
truck
|
55%
|
$20,000
|
(9.5) Category
7 A.
(a)
Except as provided in subsection (14) of this section, with respect to the
income tax years commencing on or after January 1, 2017, but before January 1,
2022, there is allowed to any person a credit against the tax imposed by this
article in an amount set forth in paragraph (b) of this subsection (9.5) for
the conversion of a category 7 A truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but
before
1/1/2020
|
1/1/2020
but
before
1/1/2021
|
1/1/2021
but
before
1/1/2022
|
|
Light-duty
passenger motor vehicle with
a
GVWR over 8,500 lbs
|
$5,000
|
$4,000
|
$2,500
|
|
Light-duty
electric truck
|
$7,000
|
$5,500
|
$3,500
|
|
Medium-duty
electric truck
|
$10,000
|
$8,000
|
$5,000
|
|
Heavy-duty
truck
|
$20,000
|
$16,000
|
$10,000
|
(10) Category
8.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2022, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (10) of the actual cost incurred by the taxpayer during the tax year
for each purchase or lease of a category 8 trailer, not to exceed the amount
set forth in paragraph (b) of this subsection (10). For purposes of the income
tax year commencing on or after January 1, 2014, but before January 1, 2015,
the purchase or lease of a category 8 trailer must occur on or after July 1,
2014, but before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
1/1/2015
1/1/2016
|
1/1/2017
1/1/2018
|
1/1/2019
|
1/1/2020
|
1/1/2021
but
before
1/1/2022
|
Cap
per
income
tax
year
|
|
Category
8
|
18%
|
15%
|
11.75%
|
7.5%
|
3.75%
|
$7,500
|
(11) Category
8 A.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2022, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (11) of the actual cost incurred by the taxpayer during the tax year
for the conversion of a refrigerated trailer to a category 8 A trailer, not to
exceed the amount set forth in paragraph (b) of this subsection (11). For
purposes of the income tax year commencing on or after January 1, 2014, but
before January 1, 2015, the conversion of a refrigerated trailer to a category
8 A trailer must occur on or after July 1, 2014, but before January 1, 2015.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
1/1/2015
1/1/2016
|
1/1/2017
1/1/2018
|
1/1/2019
|
1/1/2020
|
1/1/2021
but
before
1/1/2022
|
Cap
per
income
tax
year
|
|
Category
8 A
|
55%
|
45%
|
33.75%
|
22.5%
|
11.25%
|
$7,500
|
(11.5) Category
9.
(a)
With respect to the income tax years commencing on or after January 1, 2014,
but before January 1, 2017, there is allowed to any person a credit against the
tax imposed by this article as a percentage set forth in paragraph (b) of this
subsection (11.5) of the actual cost incurred by the taxpayer during the tax
year for the conversion of a category 9 truck, not to exceed the amount set
forth in paragraph (b) of this subsection (11.5).
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2014
but before
1/1/2017
|
Cap
per income tax year
|
|
Category
9
|
55%
|
$6,000
|
(11.6) Category
9.
(a)
Except as otherwise provided in subsection (14) of this section, with respect
to the income tax years commencing on or after January 1, 2017, but before
January 1, 2022, there is allowed to any person a credit against the tax
imposed by this article in an amount set forth in paragraph (b) of this
subsection (11.6) for the conversion of a category 9 truck during the tax year.
(b)
|
|
Income
tax year commencing:
|
|
|
1/1/2017
but before
1/1/2020
|
1/1/2020
but before
1/1/2021
|
1/1/2021
but before
1/1/2022
|
|
Category
9
|
$5,000
|
$4,000
|
$2,500
|
(12) A
taxpayer claiming the credit authorized by this section shall not claim the
credit in an amount that exceeds the incremental cost of the actual cost
incurred for the category 4, 4 A, 4 B, 4 C, 7, or 7 A truck or motor vehicle
over the manufacturer's suggested retail price of a comparable traditional fuel
truck or light-duty passenger motor vehicle.
(13) If
a credit authorized in this section exceeds the income tax due on the income of
the taxpayer for the taxable year, the excess credit may not be carried forward
and must be refunded to the taxpayer.
(13.5)
(a) A purchaser may assign the tax credit allowed in this section for the
purchase or lease of a category 4, category 4 A, category 4 B, category 4 C,
category 7, category 7 A, or category 9 vehicle completed on or after January
1, 2017, but before January 1, 2024, to a financing entity as follows:
(I) The
assignment to the financing entity must be completed at the time of purchase or
lease by entering into an election statement as set forth in paragraph (c) of
this subsection (13.5);
(II)
The purchaser must title and register the vehicle in the state or register the
vehicle under the international registration plan and base plate the vehicle in
the state as required by state law;
(III)
The purchaser must assign the tax credit to the financing entity and forfeit
the right to claim the tax credit on the purchaser's tax return in exchange for
good and valuable consideration; and
(IV)
The financing entity shall compensate the purchaser for the full nominal value
of the tax credit; except that the financing entity may collect an
administrative fee not to exceed one hundred fifty dollars for processing the
assignment. The compensation paid to the purchaser is considered a refund of
state taxes and is not income.
(b)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a financing entity pursuant to this subsection (13.5), the financing entity
receives the full amount of the tax credit that the purchaser is allowed in
this section. Any unpaid balance or unpaid debt of the purchaser may not be
credited from the amount of the tax credit allowed in this section.
(c) To
complete the tax credit assignment, the purchaser and the financing entity must
enter into an election statement that must:
(I)
Identify the vehicle identification number of the category 4, category 4 A,
category 4 B, category 4 C, category 7, category 7 A, or category 9 vehicle for
which a credit is allowed in this section; and
(II)
Affirm that the requirements specified in paragraph (a) of this subsection
(13.5) were met.
(d) The
financing entity may authorize an agent or a designee to sign the election
statement on its behalf.
(e) The
financing entity shall electronically submit a report containing the
information contained in the election statement described in paragraph (c) of
this subsection (13.5) to the department of revenue within thirty days of the
purchase or lease of a category 4, category 4 A, category 4 B, category 4 C,
category 7, category 7 A, or category 9 vehicle in such a form and in such a
manner as required by the department.
(f) The
financing entity shall also file the election statement described in paragraph
(c) of this subsection (13.5) with the original tax return for the taxable year
in which the category 4, category 4 A, category 4 B, category 4 C, category 7,
category 7 A, or category 9 vehicle is purchased or leased.
(g) The
department of revenue, in consultation with the Colorado energy office created
in section 24-38.5-101, C.R.S., shall develop a model report and election
statement no later than December 1, 2016.
(h)
This subsection (13.5) is repealed, effective December 31, 2028.
(13.7)
(a) A purchaser may assign the tax credit allowed in this section for the
purchase or lease of a category 7 vehicle sold or leased on or after January 1,
2024, to a financing entity or to a motor vehicle dealer as follows:
(I) The
assignment to the financing entity or the motor vehicle dealer must be
completed at the time of purchase or lease by entering into an election
statement as set forth in subsection (13.7)(c) of this section;
(II)
The purchaser must title and register the vehicle in the state or register the
vehicle under the international registration plan and base plate the vehicle in
the state as required by state law;
(III)
The purchaser must assign the tax credit to the financing entity or the motor
vehicle dealer and forfeit the right to claim the tax credit on the purchaser's
tax return in exchange for the good and valuable consideration; and
(IV)
The financing entity or the motor vehicle dealer shall compensate the purchaser
for the full nominal value of the tax credit; except that the financing entity
or the motor vehicle dealer may collect an administrative fee not to exceed two
hundred fifty dollars for processing the assignment. The compensation paid to
the purchaser is considered a refund of state taxes and is not income.
(b)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a financing entity or to a motor vehicle dealer pursuant to this subsection
(13.7), the financing entity or the motor vehicle dealer receives the full
amount of the tax credit that the purchaser is allowed in this section. Any
unpaid balance or unpaid debt of the purchaser may not be credited from the
amount of the tax credit allowed in this section.
(c) To
complete the tax credit assignment, the purchaser and the financing entity or
the motor vehicle dealer shall enter into an election statement that:
(I)
Identifies the vehicle identification number of the category 7 vehicle for
which a credit is allowed in this section;
(II)
Specifies the value of the credit allowed; and
(III)
Affirms that the requirements specified in subsection (13.7)(a) of this section
were met.
(d) The
financing entity or the motor vehicle dealer may authorize an agent or a
designee to sign the election statement on its behalf.
(e) For
the purchase or lease of a category 7 vehicle completed on or after January 1, 2024,
the financing entity or the motor vehicle dealer shall electronically submit a
report containing the information contained in the election statement described
in subsection (13.7)(c) of this section to the department on a quarterly basis
in a form and manner required by the department.
(f) The
financing entity or the motor vehicle dealer shall maintain the election
statement described in subsection (13.7)(c) of this section and produce it upon
request or audit by the department.
(g) For
income tax years commencing on or after January 1, 2025, the financing entity
or motor vehicle dealer may elect advance payments of credits assigned under
this subsection (13.7) as specified in section 39-22-629.
(14)
(a) During the calendar year ending December 31, 2018, the Colorado energy
office created in section 24-38.5-101, C.R.S., shall determine whether category
4, 4 A, 4 B, 4 C, 7, 7 A, or 9 medium- or heavy-duty trucks generate life-cycle
emissions materially greater than comparable medium- or heavy-duty trucks using
traditional fuel. Such a life-cycle analysis must include the direct emissions
regulated by the United States environmental protection agency or by the
department of public health and environment that are associated with producing,
transporting, and using the alternative or traditional fuels. The Colorado
energy office shall consider the likely adoption of future technology at each
stage of the life-cycle.
(b) In
making the determinations described in paragraph (a) of this subsection (14),
the Colorado energy office shall consider public input, any analysis or reports
prepared by the department of public health and environment, other states, or
the United States environmental protection agency, and any peer-reviewed
studies conducted in the United States that evaluate similar matters.
(c) In
the event that category 4, 4 A, 4 B, 4 C, 7, 7 A, or 9 medium- or heavy-duty
trucks are shown to generate life-cycle emissions materially greater than
comparable traditional fuel trucks, then the Colorado energy office shall
notify the department of revenue that no tax credit specified in this section
is available for such trucks for the income tax years commencing on or after
January 1, 2019, but before January 1, 2022; except that the Colorado energy
office may determine if a particular category 4, 4 A, 4 B, 4 C, 7, 7 A, or 9
truck model or engine does not generate life-cycle emissions materially greater
than a comparable traditional fuel truck model or engine and is thus allowed a
credit for a given income tax year, or the Colorado energy office may allow a
credit if the taxpayer can demonstrate that the taxpayer has a long-term fuel
contract for his or her category 4, 4 A, 4 B, 4 C, 7, 7 A, or 9 truck from a
green fuel provider, such that the life-cycle emissions from such truck are not
materially greater than the emissions of a comparable traditional fuel truck.
For purposes of this paragraph (c), "green fuel provider" means the
alternative fuel is produced and delivered by providers that have adopted best
practices for low life-cycle emissions. On or before January 1, 2019, and on or
before each January 1 thereafter through January 1, 2021, the Colorado energy
office and the department of revenue shall, through their respective websites,
specify which category 4, 4 A, 4 B, 4 C, 7, 7 A, or 9 medium- or heavy-duty
trucks are not allowed a credit for a given income tax year.
(15) No
more than one tax credit shall be granted pursuant to this section and section
39-22-516.7 for any individual motor vehicle or truck.
(16)
With respect to tax years commencing on or after January 1, 2017, the taxpayer
claiming a credit allowed in this section shall provide the department of
revenue with, and the department shall commence tracking, the vehicle
identification number of the motor vehicle or truck for which a credit is
claimed as allowed in this section.
(17)
Making the purchaser aware of the income tax credit allowed in this section or
helping the purchaser assign the income tax credit to a financing entity as
allowed in this section does not rise to the level of providing the purchaser
with unauthorized tax advice.
(17.5)
A purchaser, as set forth in subsection (1)(bb.3)(II) of this section, who
claims the credit allowed by this section shall file a return pursuant to
section 39-22-601 (7)(b).
(18)
This section is repealed, effective December 31, 2037.
Source:
L. 2014: Entire
section added, (HB 14-1326), ch. 357, p. 1664, § 2, effective June 6. L.
2016: (1)(r.5), (1)(bb.3), (2.3), (2.5), (3.5), (4.3), (4.5), (5.5), (8.3),
(8.5), (9.5), (11.6), (13.5), (17), and (18) added and (1)(ee), (2), (3), (4),
(5), (8), (9), (11.5), and (16) amended, (HB 16-1332), ch. 237, p. 960, § 2,
effective June 6. L. 2019: (1)(h), (1)(i), (1)(r)(III), (8.3), (8.5),
and (18) amended, (HB 19-1159), ch. 386, p. 3445, § 3, effective August 2. L.
2020: (15) amended, (HB 20-1402), ch. 216, p. 1058, § 68, effective June
30; (1)(c) amended, (HB 20-1167), ch. 56, p. 192, § 4, effective September 14. L.
2023: (1)(q.5), (1)(bb.1), (1.5), (8.7), (13.5)(h), (13.7), and (17.5)
added and (1)(bb.3), (8.3), (8.5), IP(13.5)(a), and (18) amended, (HB 23-1272),
ch. 167, p. 771, § 3, effective May 11. L. 2024: (15) amended, (HB
24-1450), ch. 490, p. 3425, § 80, effective August 7. L. 2026: (8.7)(d)
amended, (HB 26-1289), ch. 364, p. 2195, § 8, effective June 3.
Cross
references: For
the legislative declaration in HB 14-1326, see section 1 of chapter 357,
Session Laws of Colorado 2014. For the legislative declaration in HB 19-1159,
see section 1 of chapter 386, Session Laws of Colorado 2019. For the
legislative declaration in HB 23-1272, see section 1 of chapter 167, Session
Laws of Colorado 2023. For the legislative declaration in HB 26-1289, see
section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-517. Tax credit for child care
center investments - repeal.
(1)
With respect to taxable years commencing on or after January 1, 1992, and prior
to January 1, 2029, there is allowed to any person operating a child care
center licensed pursuant to section 26-6-905 or 26.5-5-309, family child care
home licensed pursuant to section 26.5-5-309, or foster care home licensed
pursuant to section 26-6-905 a credit against the tax imposed by this article
22 in the amount of twenty percent of the taxpayer's annual investment in
tangible personal property to be used in such child care center, family child
care home, or foster care home.
(2)
With respect to taxable years commencing on or after July 1, 1992, and prior to
January 1, 2029, there is allowed to any sole proprietorship, partnership,
limited liability corporation, subchapter S corporation, or regular corporation
that provides child care facilities that are incidental to their business and
are licensed pursuant to section 26-6-905 or 26.5-5-309 for the use of its
employees a credit against the tax imposed by this article 22 in the amount of
ten percent of the taxpayer's annual investment in tangible personal property
to be used in such child care facilities.
(3) The
credit allowed by this section for any income tax year shall not exceed the
taxpayer's actual tax liability for such taxable year. If the amount of the
credit allowed by this section exceeds the taxpayer's actual tax liability for
any income tax year in which the child care center investment credit is
claimed, referred to in this subsection (3) as the "unused credit
year", such excess shall be an investment tax credit carryover to each of
the three income tax years following the unused credit year and shall be
applied first to the earliest income tax years possible.
(4)
This section is repealed, effective December 31, 2036.
Source:
L. 92: Entire
section added, p. 2245, § 1, effective June 5. L. 96: (1) amended, p.
267, § 22, effective July 1. L. 2022: (1) and (2) amended, (HB 22-1295),
ch. 123, p. 868, § 130, effective July 1; (1) and (2) amended, (HB 22-1025),
ch. 145, p. 947, § 10, effective January 1, 2023. L. 2024: (1) and (2)
amended and (4) added, (HB 24-1036), ch. 373, p. 2527, § 11, effective August
7. L. 2025: (1), (2), and (4) amended, (HB 25-1296), ch. 202, p. 913, §
9, effective May 16.
Editor's
note: Amendments
to subsections (1) and (2) by HB 22-1025 and HB 22-1295 were harmonized,
effective January 1, 2023.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024. For the legislative declaration in HB 25-1296,
see section 1 of chapter 202, Session Laws of Colorado 2025.
39-22-518. Tax modification for net
capital gains - definitions - repeal.
(1) For
income tax years commencing on or after July 1, 1995, a modification, in the
form of a reduction of income taxable by the state of Colorado, shall be
allowed to any qualified taxpayer for the amount of income attributable to
qualifying gains receiving capital treatment earned by the qualified taxpayer
during the taxable year and included in federal taxable income.
(2) For
the purposes of this section:
(a) (I)
"Qualified taxpayer" for income tax years commencing before January
1, 2022, means any taxpayer with no overdue state tax liabilities and not in
default on any contractual obligations owed to the state or to any local
government within Colorado at the time the modification created under this
section is claimed. This subsection (2)(a)(I) is repealed, effective December
31, 2030.
(I.5)
"Qualified taxpayer" means, for income tax years commencing on or
after January 1, 2022, any taxpayer that has no overdue state tax liabilities;
that is not in default on any contractual obligations owed to the state or to
any local government within Colorado at the time the modification created under
this section is claimed; and that is required to file a schedule F, profit or
loss from farming, or successor form, as an attachment to the taxpayer's
federal income tax return for the tax year in which the net capital gains
arise.
(II)
For the purposes of this paragraph (a), "overdue state tax
liabilities" includes uncollectible tax liabilities resulting from
bankruptcy.
(b) (I)
"Qualifying gains receiving capital treatment" means the amount of
net capital gains, as defined in section 1222 (11) of the internal revenue
code, included in any qualified taxpayer's federal income tax return and:
(A) and
(B) Repealed.
(B.5)
For income tax years commencing before January 1, 2022, earned by the qualified
taxpayer on either real or tangible personal property located within Colorado
that was acquired on or after May 9, 1994, but before June 4, 2009, or on
tangible personal property only located either within or outside Colorado that
was acquired on or after June 4, 2009, and either of which has been owned by
the qualified taxpayer for a holding period of at least five years prior to the
date of the transaction from which the net capital gains arise if the
transaction from which the net capital gains arise occurred during an income
tax year that commenced on or after January 1, 2010; except that no more than
one hundred thousand dollars of net capital gains described in this subsection
(2)(b)(I)(B.5) are qualifying gains receiving capital treatment for any single
income tax year. This subsection (2)(b)(I)(B.5) is repealed, effective December
31, 2030.
(B.7)
For income tax years commencing on or after January 1, 2022, earned by the
qualified taxpayer on qualified real property that was acquired on or after May
9, 1994, but before June 4, 2009, and has been owned by the qualified taxpayer
for a holding period of at least five years prior to the date of the
transaction from which the net capital gains arise; except that no more than
one hundred thousand dollars of net capital gains described in this subsection
(2)(b)(I)(B.7) are qualifying gains receiving capital treatment for any single
income tax year.
(C) to
(F) Repealed.
(II)
For purposes of this subsection (2)(b):
(A)
Repealed.
(B)
"Holding period" means an uninterrupted period of time.
(C)
"Qualified real property" means real property located in Colorado
that is sold by the taxpayer and generates the qualifying gains receiving
capital treatment and that is classified by the county property tax assessor
immediately preceding the sale as agricultural land under section 39-1-102
(1.6)(a). If real property is sold as a type of investment package, then, in
order to be qualified real property, at least seventy-five percent of the real
property sold in the package must be classified by the county property tax
assessor immediately preceding the sale as agricultural land under section
39-1-102 (1.6)(a).
(3) Any
reduction in Colorado taxable income caused by the modification allowed by this
section shall not create any right to a cash refund for the year for which the
modification is claimed, nor shall the reduction create any right to a
financial or other tax benefit which may be carried forward by the qualified
taxpayer.
(4) Any
taxpayer claiming a modification pursuant to this section shall submit with the
taxpayer's income tax return in which such modification is claimed an
affidavit, signed under penalty of perjury, stating that the taxpayer meets the
definition of a qualified taxpayer as stated in paragraph (a) of subsection (2)
of this section.
(5) to
(8) Repealed.
Source:
L. 94: Entire
section added, p. 1104, § 1, effective May 9. L. 99: (2)(b)(I) and
(2)(b)(II)(B) amended and (5), (6), and (7) added, p. 1284, § 1, effective
August 4. L. 2000: (2)(b)(I), (5)(a), (5)(b)(I), (5)(b)(II), (5)(b)(V),
(5)(b)(VI), (6), and (7) amended and (5)(c) and (5)(d) added, pp. 1456, 1459,
§§ 1, 2, effective August 2. L. 2001: (7) amended, p. 1280, § 55,
effective June 5; (5)(a), (5)(b)(I), (5)(b)(II), and (5)(b)(VI) amended, p.
394, § 5, effective August 8. L. 2009: (2)(b)(I)(A) and (2)(b)(I)(B)
amended, (2)(b)(I)(B.5) and (8) added, and (2)(b)(I)(C), (2)(b)(I)(D),
(2)(b)(I)(E), (2)(b)(I)(F), (5), (6), and (7) repealed, (HB 09-1366), ch. 432,
pp. 2397, 2398, §§ 1, 2, 3, effective June 4. L. 2021: (2)(a)(I),
(2)(b)(I)(B.5), and IP(2)(b)(II) amended and (2)(a)(I.5), (2)(b)(I)(B.7), and
(2)(b)(II)(C) added, (HB 21-1311), ch. 298, p. 1778, § 8, effective June 23. L.
2023: (2)(b)(II)(A) repealed, (HB 23-1251), ch. 437, p. 2572, § 2,
effective August 7.
Editor's
note: Subsection
(8) provided for the repeal of subsections (2)(b)(I)(A), (2)(b)(I)(B), and (8),
effective January 1, 2015. (See L. 2009, p. 2398.)
Cross
references: (1)
For other provisions concerning adjustments to federal taxable income, see §
39-22-104.
(2) For the legislative
declaration contained in the 2001 act amending subsections (5)(a), (5)(b)(I),
(5)(b)(II), and (5)(b)(VI), see section 1 of chapter 133, Session Laws of
Colorado 2001.
(3) For the legislative
declaration in HB 21-1311, see section 1 of chapter 298, Session Laws of
Colorado 2021.
39-22-519. Tax credit for book value of
certificate for carriers of sludge - repeal. (Repealed)
Source:
L. 94: Entire
section added, p. 2822, § 2, effective June 3.
Editor's
note: Subsection
(3) provided for the repeal of this section, effective January 1, 1999. (See L.
94, p. 2822.)
39-22-520. Credit against tax -
investment in school-to-career program - definitions - repeal.
(1) The
general assembly hereby recognizes that businesses and other aspects of the
economy need trained, educated, and motivated workers. It is therefore the
intent of the general assembly to encourage private investment in programs that
integrate traditional education with on-the-job training. It is further the
intent of the general assembly to foster and encourage cooperation among the
private sector and the educational community in creating programs that will
open doors of opportunity for students and enable them to develop the knowledge
and skills that will empower them to become productive members of society.
(2) (a)
For income tax years beginning on or after January 1, 1997, and prior to
January 1, 2025, there shall be allowed to any person as a credit against the
tax imposed by this article 22 an amount equal to ten percent of the total
qualified investment made in a qualified school-to-career program.
(b) For
purposes of this subsection (2):
(I)
"Qualified investment" means moneys directly expended for wages,
workers' compensation insurance, unemployment insurance, and training expenses
to employ a student to work or to allow a student to participate in an
internship through a qualified school-to-career program.
(II)
"Qualified school-to-career program" means a program that integrates
school curriculum with job training, that encourages placement of students in
jobs or internships that will teach them new skills and improve their school
performance, and that is approved by:
(A) The
board of education of the school district in which the program is operating;
(B) The
state board for community colleges and occupational education;
(C) The
private occupational school division created pursuant to section 23-64-105; or
(D) The
Colorado commission on higher education.
(3) If
the amount of the credit provided for pursuant to subsection (2) of this
section exceeds the amount of income taxes due on the income of the taxpayer in
the income tax year for which the credit is being claimed, the amount of the
credit not used as an offset against income taxes in said income tax year shall
not be allowed as a refund but may be carried forward as a credit against
subsequent years' tax liability for a period not exceeding five years and shall
be applied first to the earliest income tax years possible. Any amount of the
credit that is not used during said period shall not be refundable to the
taxpayer.
(4)
This section is repealed, effective December 31, 2034.
Source:
L. 97: Entire
section added, p. 1395, § 1, effective June 3. L. 2008: (2)(b)(II)(C)
amended, p. 1482, § 27, effective May 28. L. 2017: (2)(b)(II)(C)
amended, (HB 17-1239), ch. 261, p. 1207, § 19, effective August 9. L. 2024:
(2)(a) amended and (4) added, (HB 24-1439), ch. 163, p. 775, § 2, effective May
10; (2)(a) amended and (4) added, (HB 24-1036), ch. 373, p. 2528, § 12,
effective August 7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-22-521. Credits against tax -
employer expenses - public assistance recipients - repeal.
(1)
With respect to taxable years commencing on or after January 1, 1998, and prior
to January 1, 2025, there shall be allowed to an employer of any person
receiving public assistance pursuant to the Colorado works program set forth in
part 7 of article 2 of title 26, a credit, for not more than two years, against
the tax imposed by this article in the amount of twenty percent of the
employer's annual investment in any one or more of the following services that
are incidental to the employer's business:
(a) The
provision of child care services or the payment of the costs associated with
child care services for children of employees receiving public assistance;
(b) The
provision of health or dental insurance for employees receiving public
assistance, which health or dental insurance coverage, if less than the
coverage provided through medicaid, shall be supplemented by medicaid to provide
full medicaid benefits to the employee;
(c) The
provision of job training or basic education of employees receiving public
assistance;
(d) The
provision of programs for the transportation of public assistance employees to
and from work.
(2) The
tax credit described in subsection (1) of this section shall be in addition to
any other credits for which the employer may be eligible pursuant to the
provisions of article 30 of this title.
(3) The
credit allowed by this section for any income tax year shall not exceed the
employer's actual tax liability for such taxable year. If the amount of the
credit allowed by this section exceeds the employer's actual tax liability for
any income tax year in which the credit authorized in this section is claimed,
such excess shall be a tax credit carryover to each of the three income tax
years following the unused credit year and shall be applied first to the
earliest income tax years possible.
(4)
This section is repealed, effective December 31, 2032.
Source:
L. 97: Entire
section added, p. 1245, § 52, effective July 1. L. 2024: IP(1) amended
and (4) added, (HB 24-1036), ch. 373, p. 2528, § 13, effective August 7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-22-522. Credit against tax -
conservation easements - definitions - tax preference performance statement -
repeal.
(1) For
purposes of this section:
(a) For
income tax years commencing prior to January 1, 2021, "taxpayer"
means a resident individual or a domestic or foreign corporation subject to the
provisions of part 3 of this article, a partnership, S corporation, or other
similar pass-through entity, estate, or trust that donates a conservation
easement as an entity, and a partner, member, and subchapter S shareholder of
such pass-through entity.
(b) For
income tax years commencing on or after January 1, 2021, "taxpayer"
means any person or entity filing a state income tax return or a domestic or
foreign corporation subject to the provisions of part 3 of this article 22, a
partnership, S corporation, or other similar pass-through entity, estate,
trust, nonprofit entity, or an entity that has authority to conduct water
activities, as defined by section 37-45.1-102 (3) and created pursuant to
article 41, 45, 46, 47, 48, or 50 of title 37, or article 42 of title 7, that
conveys a conservation easement in gross pursuant to section 38-30.5-104. A
ditch or reservoir company formed pursuant to article 42 of title 7, or
otherwise, is entitled to act on its own behalf in granting a conservation
easement and earning and transferring tax credits under this section, whether
or not any of its shareholders or members are governmental entities.
(2) (a)
For income tax years commencing on or after January 1, 2000, but prior to
January 1, 2014, and, with regard to any credit over the amount of one hundred
thousand dollars, for income tax years commencing on or after January 1, 2003,
but before January 1, 2037, subject to the provisions of subsections (4) and
(6) of this section, there shall be allowed a credit with respect to the income
taxes imposed by this article to each taxpayer who donates during the taxable
year all or part of the value of a perpetual conservation easement in gross
created pursuant to article 30.5 of title 38 upon real property the taxpayer
owns to a governmental entity or a charitable organization described in section
38-30.5-104 (2). The credit shall only be allowed for a donation that is
eligible to qualify as a qualified conservation contribution pursuant to
section 170 (h) of the internal revenue code, as amended, and any federal
regulations promulgated in connection with such section. The amount of the
credit shall not include the value of any portion of an easement on real
property located in another state.
(b) For
income tax years commencing on or after January 1, 2014, but before January 1,
2037, and, with regard to any credit over the amount of one hundred thousand
dollars, for income tax years commencing on or after January 1, 2003, but
before January 1, 2037, subject to the provisions of subsections (4) and (6) of
this section, there shall be allowed a credit with respect to the income taxes
imposed by this article to each taxpayer who donates during the taxable year
all or part of the value of a perpetual conservation easement in gross created
pursuant to article 30.5 of title 38 upon real property the taxpayer owns to a
governmental entity or a charitable organization described in section
38-30.5-104 (2). The credit shall only be allowed for a donation that meets the
requirements of section 170 of the federal "Internal Revenue Code of
1986", as amended, and any federal regulations promulgated in accordance
with such section. The amount of the credit shall not include the value of any
portion of an easement on real property located in another state.
(2.5)
Notwithstanding any other provision of this section and the requirements of
section 12-15-106, for income tax years commencing on or after January 1, 2011,
a taxpayer conveying a conservation easement and claiming a credit pursuant to
this section shall, in addition to any other requirements of this section and
the requirements of section 12-15-106, submit a claim for the credit to the
division of conservation in the department of regulatory agencies. The division
must prioritize tax credit applications in the order received. The division
must assign each application with the date and time received based on the order
in which a completed application was submitted pursuant to section 12-15-106
(5). Incomplete applications do not get priority in the review process.
Disapproved applications lose their priority in the review process. After
certificates have been issued for credits that exceed an aggregate of
twenty-two million dollars for all taxpayers for the 2011 and 2012 calendar
years, thirty-four million dollars for the 2013 calendar year, forty-five
million dollars for each of the 2014 to 2024 calendar years, and fifty million
dollars for each of the 2025 to 2036 calendar years, any claims that exceed the
amount allowed for a specified calendar year shall be issued for use in the
next year for which the division has not issued credit certificates in excess
of the amounts specified in this subsection (2.5). The division shall not issue
credit certificates that exceed twenty-two million dollars in each of the 2011
and 2012 calendar years, thirty-four million dollars for the 2013 calendar
year, forty-five million dollars for each of the 2014 to 2024 calendar years,
and fifty million dollars for each of the 2025 through 2036 calendar years. No
claim for a credit is allowed for any income tax year commencing on or after
January 1, 2011, unless a certificate has been issued by the division. If all
other requirements under section 12-15-106 and this section are met, the right
to claim the credit is vested in the taxpayer at the time the credit
certificate is issued. In the case of a tax credit certificate issued to a
taxpayer who files an income tax return for a tax year other than a calendar
year, the credit must be used in the income tax year that begins during the
calendar year for which the tax credit certificate is issued.
(2.7)
Notwithstanding any other provision, for income tax years commencing on or
after January 1, 2014, no claim for a credit shall be allowed unless a tax
credit certificate is issued by the division of real estate prior to May 30,
2018, or by the division of conservation on or after May 30, 2018, in
accordance with sections 12-15-105 and 12-15-106 and, for income tax years
commencing on or after January 1, 2014, but prior to January 1, 2022, the
taxpayer files the tax credit certificate with the income tax return filed with
the department of revenue.
(3) For
conservation easements donated prior to January 1, 2014, in order for any
taxpayer to qualify for the credit provided for in subsection (2) of this
section, the taxpayer shall submit the following in a form approved by the
executive director to the department of revenue at the same time as the
taxpayer files a return for the taxable year in which the credit is claimed:
(a) A
statement indicating whether a deduction was claimed on the taxpayer's federal
income tax return for a conservation easement in gross;
(b) A
statement that reflects the information included in the noncash charitable
contributions form used to claim a deduction for a conservation easement in
gross on a federal income tax return and whether the donation was made in order
to get a permit or other approval from a local or other governing authority;
(c) A
statement to be made available to the public by the department of revenue that
includes a summary of the conservation purposes as defined in section 170 (h)
of the internal revenue code that are protected by the easement; the county,
township, and range where the easement is located; the number of acres subject
to the easement; the amount of the tax credit claimed; and the name of the
organization holding the easement;
(d) A
summary of a qualified appraisal that meets the requirements set forth in
subsection (3.3) of this section; however, if requested by the department of
revenue, the taxpayer shall submit the appraisal itself;
(e) A
copy of the appraisal and accompanying affidavit from the appraiser submitted
to the division of real estate in the department of regulatory agencies in
accordance with the provisions of section 12-61-719, C.R.S., as said section
existed prior to its repeal on July 1, 2013;
(f) If
the holder of the conservation easement is an organization to which the
certification program in section 12-15-104 applies, a sworn affidavit from the
holder of the conservation easement in gross that includes the following:
(I)
Repealed.
(II) An
acknowledgment of whether the transaction is part of a series of transactions
by the same donor; and
(III)
An acknowledgment that the holder has reviewed the completed Colorado gross
conservation easement credit schedule to be filed by the taxpayer and that the
property is accurately described in the schedule.
(3.3)
The appraisal for a conservation easement in gross donated prior to January 1,
2014, and for which a credit is claimed shall be a qualified appraisal from a
qualified appraiser, as those terms are defined in section 170 (f)(11) of the
internal revenue code. The appraisal shall be in conformance with the uniform
standards of professional appraisal practice promulgated by the appraisal
standards board of the appraisal foundation and any other provision of law. The
appraiser shall hold a valid license as a certified general appraiser in
accordance with the provisions of part 6 of article 10 of title 12. If there is
a final determination, other than by settlement of the taxpayer, that an
appraisal submitted in connection with a claim for a credit pursuant to this
section is a substantial or gross valuation misstatement as such misstatements
are defined in section 1219 of the federal "Pension Protection Act of
2006", Pub.L. 109-280, the department shall submit a complaint regarding
the misstatement to the board of real estate appraisers for disciplinary action
in accordance with the provisions of part 6 of article 10 of title 12.
(3.5)
(a) For conservation easements donated prior to January 1, 2014:
(I) The
executive director shall have the authority, pursuant to subsection (8) of this
section, to require additional information from the taxpayer or transferee
regarding the appraisal value of the easement, the amount of the credit, and
the validity of the credit. In resolving disputes regarding the validity or the
amount of a credit allowed pursuant to subsection (2) of this section,
including the value of the conservation easement for which the credit is
granted, the executive director shall have the authority, for good cause shown
and in consultation with the division of conservation and the conservation
easement oversight commission created in section 12-15-103 (1), to review and
accept or reject, in whole or in part, the appraisal value of the easement, the
amount of the credit, and the validity of the credit based upon the internal
revenue code and federal regulations in effect at the time of the donation. If
the executive director reasonably believes that the appraisal represents a
gross valuation misstatement, receives notice of such a valuation misstatement
from the division of real estate, or receives notice from the division of real
estate that an enforcement action has been taken by the board of real estate
appraisers against the appraiser, the executive director shall have the
authority to require the taxpayer to provide a second appraisal at the expense
of the taxpayer. The second appraisal shall be conducted by a certified general
appraiser in good standing and not affiliated with the first appraiser that
meets qualifications established by the division of real estate. In the event
the executive director rejects, in whole or in part, the appraisal value of the
easement, the amount of the credit, or the validity of the credit, the
procedures described in sections 39-21-103, 39-21-104, 39-21-104.5, and
39-21-105 shall apply.
(II) In
consultation with the division of conservation and the conservation easement
oversight commission created in section 12-15-103 (1), the executive director
shall develop and implement a separate process for the review by the department
of revenue of gross conservation easements. The review process shall be
consistent with the statutory obligations of the division and the commission
and shall address gross conservation easements for which the department of
revenue has been informed that an audit is being performed by the internal
revenue service. The executive director shall share information used in the
review of gross conservation easements with the division. Notwithstanding part
2 of article 72 of title 24, in order to protect the confidential financial
information of a taxpayer, the division and the commission shall deny the right
to inspect any information provided by the executive director in accordance
with this subsection (3.5)(a)(II).
(b) (I)
For conservation easements donated on or after January 1, 2014, and subject to
the restrictions of section 12-15-106 (4), the executive director shall have
the authority, pursuant to subsection (8) of this section, to require
additional information from the taxpayer or transferee regarding the amount of
a credit transferred prior to January 1, 2021, and the validity of the credit.
In resolving disputes regarding the validity or the amount of a credit allowed
pursuant to subsection (2) of this section, the executive director shall have
the authority, for good cause shown, to review and accept or reject, in whole
or in part, the amount of the credit and the validity of the credit based upon
the internal revenue code and federal regulations in effect at the time of the
donation, except those requirements for which authority is granted to the
division of conservation, the director of the division of conservation, or the
conservation easement oversight commission pursuant to section 12-15-106.
(II)
For tax credit certificates issued by the division for use on or after January
1, 2021, the transferor and transferee of the tax credit shall jointly file a
copy of the written transfer agreement with the division of conservation within
thirty days after June 30, 2021, or the date of the transfer, whichever is
later. If the credit being transferred was issued for a year other than the
year in which it is transferred, the transferor shall further submit a copy of
the transferor's DR1305 form for each year from the year for which the credit
was issued through the most recent year for which taxes were due. The division
shall issue a certificate to the transferee in the amount of the tax credit
transferred and, if any amount is retained by the transferor, issue a
certificate to the transferor in the amount retained. In no event shall a
transferee be allowed to claim an amount greater than the amount specified in
the certificate issued to the transferee. The division shall develop a system
to track the transfers of tax credits and to certify the ownership of tax
credits. A certification issued for use on or after January 1, 2021, by the
division of the ownership and amount of tax credits shall be relied upon by the
department of revenue and the transferee as being accurate, and neither the
division nor the department of revenue shall adjust the amount of tax credits
certified by the division as to the transferee; except that the division and
department retain any remedies it may have against the landowner. The division
may promulgate rules to permit verification of the ownership and amount of the
tax credits; except that any rules promulgated shall not unduly restrict or
hinder the transfer of the tax credits.
(3.6)
(a) For conservation easements donated on or after January 1, 2014, in order
for any taxpayer to claim the credit provided for in subsection (2) of this
section, the taxpayer must submit the following in a form, approved by the
executive director, to the department of revenue at the same time as the
taxpayer files a return for the taxable year in which the credit is claimed:
(I) A
tax credit certificate issued under section 12-15-106; and
(II)
The information required in subsections (3)(a) and (3)(b) of this section.
(b)
Notwithstanding any other provisions of law, the executive director retains the
authority to administer all issues related to the claim or use of a tax credit
for the donation of a conservation easement that are not granted to the
director of the division of conservation or the conservation easement oversight
commission under section 12-15-106.
(3.7)
If the gain on the sale of a conservation easement in gross for which a credit
is claimed pursuant to this section would not have been a long-term capital
gain, as defined under the internal revenue code, if, at the time of the
donation, the taxpayer had sold the conservation easement at its fair market
value, then the value of the conservation easement in gross for the purpose of
calculating the amount of the credit shall be reduced to the taxpayer's tax
basis in the conservation easement in gross. The tax basis of a taxpayer in a
conservation easement shall be determined and allocated pursuant to sections
170 (e) and 170 (h) of the internal revenue code, as amended, and any federal
regulations promulgated in connection with such sections. This subsection (3.7)
shall be applied in a manner that is consistent with the tax treatment of
qualified conservation contributions under the internal revenue code and the
federal regulations promulgated under the internal revenue code.
(3.8)
Repealed.
(4) (a)
(I) For a conservation easement in gross created in accordance with article
30.5 of title 38, C.R.S., that is donated prior to January 1, 2007, to a
governmental entity or a charitable organization described in section
38-30.5-104 (2), C.R.S., the credit provided for in subsection (2) of this
section shall be an amount equal to one hundred percent of the first one
hundred thousand dollars of the fair market value of the donated portion of
such conservation easement in gross when created, and forty percent of all
amounts of the donation in excess of one hundred thousand dollars; except that
in no case shall the credit exceed two hundred sixty thousand dollars per
donation.
(II)
For a conservation easement in gross created in accordance with article 30.5 of
title 38, C.R.S., that is donated on or after January 1, 2007, and prior to
January 1, 2015, to a governmental entity or a charitable organization
described in section 38-30.5-104 (2), C.R.S., the credit provided for in
subsection (2) of this section shall be an amount equal to fifty percent of the
fair market value of the donated portion of such conservation easement in gross
when created; except that, in no case shall the credit exceed three hundred
seventy-five thousand dollars per donation.
(II.5)
For a conservation easement in gross created in accordance with article 30.5 of
title 38 that is donated on or after January 1, 2015, but prior to January 1,
2021, to a governmental entity or a charitable organization described in
section 38-30.5-104 (2), the credit provided for in subsection (2) of this
section shall be an amount equal to seventy-five percent of the first one
hundred thousand dollars of the fair market value of the donated portion of
such conservation easement in gross when created, and fifty percent of all
amounts of the donation in excess of one hundred thousand dollars; except that
in no case shall the credit exceed five million dollars per donation. Credits
shall be issued in increments of no more than one million five hundred thousand
dollars per year. Credits for easements donated in a prior year shall be
eligible for tax credit certificates in subsequent years in order of
application and before new applications and those credit applications, if any,
on the wait list.
(II.7)
For a conservation easement in gross created in accordance with article 30.5 of
title 38 that is donated to a governmental entity or a charitable organization
described in section 38-30.5-104 (2), the credit provided for in subsection (2)
of this section is an amount equal to:
(A) For
conservation easements donated on or after January 1, 2021, but before January
1, 2027, ninety percent of the fair market value of the donated portion of such
conservation easement in gross when created; except that in no case shall the
credit exceed five million dollars per donation; and
(B) For
conservation easements donated on or after January 1, 2027, eighty percent of
the fair market value of the donated portion of such conservation easement in
gross when created; except that, in no case shall the credit exceed five
million dollars per donation.
(II.8)
Credits shall be issued in increments of no more than one million five hundred
thousand dollars per year. Credits for easements donated in a prior year are
eligible for tax credit certificates in subsequent years in order of
application.
(III)
In no event shall a credit claimed by a taxpayer filing a joint federal return,
or the sum of the credits claimed by taxpayers who may legally file a joint
federal return but actually file separate federal returns, exceed the dollar
limitations of this paragraph (a).
(b) (I)
For income tax years commencing on or after January 1, 2000, in the case of a
joint tenancy, tenancy in common, partnership, S corporation, or other similar
entity or ownership group that donates a conservation easement as an entity or
group, the amount of the credit allowed pursuant to subsection (2) of this
section must be allocated to the entity's owners, partners, members, or
shareholders in proportion to the owners', partners', members', or
shareholders' distributive shares of income or ownership percentage from such
entity or group.
(II)
(A) For income tax years commencing on or after January 1, 2000, but prior
to January 1, 2003, the total aggregate amount of the credit allocated to such
owners, partners, members, and shareholders shall not exceed one hundred
thousand dollars, and, if any refund is claimed pursuant to subsection
(5)(b)(I) of this section, the aggregate amount of the refund and the credit
claimed by such partners, members, and shareholders shall not exceed twenty
thousand dollars for that income tax year.
(B) For
income tax years commencing on or after January 1, 2003, but prior to January
1, 2007, the total aggregate amount of the credit allocated to such owners,
partners, members, and shareholders shall not exceed two hundred sixty thousand
dollars, and, if any refund is claimed pursuant to subsection (5)(b)(I) of this
section, the aggregate amount of the refund and the credit claimed by such
owners, partners, members, and shareholders shall not exceed fifty thousand
dollars for that income tax year.
(C) For
income tax years commencing on or after January 1, 2007, and prior to January
1, 2015, the total aggregate amount of the credit allocated to such owners,
partners, members, and shareholders shall not exceed three hundred seventy-five
thousand dollars, and, if any refund is claimed pursuant to subsection
(5)(b)(I) of this section, the aggregate amount of the refund and the credit
claimed by such owners, partners, members, and shareholders shall not exceed
fifty thousand dollars for that income tax year.
(D) For
income tax years commencing on or after January 1, 2015, but before January 1,
2027, the total aggregate amount of the credit allocated to such owners,
partners, members, and shareholders shall not exceed five million dollars, and,
if any refund is claimed pursuant to subsection (5)(b)(I) of this section, the
aggregate amount of the refund and the credit claimed by such owners, partners,
members, and shareholders shall not exceed fifty thousand dollars for that
income tax year.
(E) For
income tax years commencing on or after January 1, 2027, the total aggregate
amount of the credit allocated to such owners, partners, members, and
shareholders shall not exceed five million dollars, and, if any refund is
claimed pursuant to subsection (5)(b)(I) of this section, the aggregate amount
of the refund and the credit claimed by such owners, partners, members, and
shareholders shall not exceed two hundred thousand dollars for that income tax
year.
(5) (a)
If the tax credit provided in this section exceeds the amount of income tax due
on the income of the taxpayer for the taxable year, the amount of the credit
not used as an offset against income taxes in said income tax year and not
refunded pursuant to paragraph (b) of this subsection (5) may be carried
forward and applied against the income tax due in each of the twenty succeeding
income tax years but shall be first applied against the income tax due for the
earliest of the income tax years possible. Any amount of the credit that is not
used after said period shall not be refundable.
(b) (I)
Subject to the requirements specified in subparagraphs (II) and (III) of this
paragraph (b), for income tax years commencing on or after January 1, 2000, if
the amount of the tax credit allowed in or carried forward to any tax year
pursuant to this section exceeds the amount of income tax due on the income of
the taxpayer for the year, the taxpayer may elect to have the amount of the
credit not used as an offset against income taxes in said income tax year
refunded to the taxpayer.
(II)
(A) Before January 1, 2027, a taxpayer may elect to claim a refund pursuant
to subsection (5)(b)(I) of this section only if, based on the financial report
prepared by the controller in accordance with section 24-77-106.5, the
controller certifies that the amount of state revenues for the state fiscal
year ending in the income tax year for which the refund is claimed exceeds the
limitation on state fiscal year spending imposed by section 20 (7)(a) of
article X of the state constitution and the voters statewide either have not
authorized the state to retain and spend all of the excess state revenues or
have authorized the state to retain and spend only a portion of the excess
state revenues for that fiscal year.
(B)
This subsection (5)(b)(II) is repealed, effective December 31, 2031.
(III)
If any refund is claimed pursuant to subsection (5)(b)(I) of this section, then
the aggregate amount of the refund and amount of the credit used as an offset
against income taxes, excluding amounts transferred to or used by a transferee,
for that income tax year shall not exceed fifty thousand dollars for that
income tax year for income tax years commencing before January 1, 2027, and
shall not exceed two hundred thousand dollars for that income tax year for
income tax years commencing on or after January 1, 2027. In the case of a
partnership, S corporation, or other similar pass-through entity that donates a
conservation easement as an entity, if any refund is claimed pursuant to
subsection (5)(b)(I) of this section, the aggregate amount of the refund and
the credit claimed by the partners, members, or shareholders of the entity
shall not exceed the dollar limitation set forth in this subsection (5)(b)(III)
for that income tax year. Nothing in this subsection (5)(b)(III) shall limit a
taxpayer's ability to claim a credit against taxes due in excess of fifty
thousand dollars for tax years commencing before January 1, 2027, and two
hundred thousand dollars for tax years commencing on or after January 1, 2027,
in accordance with subsection (4) of this section.
(6) (a)
For conservation easements donated prior to January 1, 2014, a taxpayer may
claim only one tax credit under this section per income tax year; except that a
transferee of a tax credit under subsection (7) of this section may claim an
unlimited number of credits. A taxpayer who has carried forward or elected to
receive a refund of part of the tax credit in accordance with subsection (5) of
this section shall not claim an additional tax credit under this section for
any income tax year commencing prior to January 1, 2014, in which the taxpayer
applies the amount carried forward against income tax due or receives a refund.
A transferor who has transferred a credit to a transferee pursuant to
subsection (7) of this section shall not claim an additional tax credit under
this section for any income tax year commencing prior to January 1, 2014, in
which the transferee uses such transferred credit. Commencing January 1, 2014,
a taxpayer may claim one tax credit per year regardless of whether the taxpayer
has credits remaining from any prior conservation easement donation.
(b) For
conservation easements donated on or after January 1, 2000, a taxpayer may
claim only one tax credit under this section per income tax year; except that a
transferee of a tax credit under subsection (7) of this section may claim an
unlimited number of credits.
(7) For
income tax years commencing on or after January 1, 2000, a taxpayer may
transfer all or a portion of a tax credit granted pursuant to subsection (2) of
this section to a transferee for such transferee to apply as a credit against
the taxes imposed by this article 22 subject to the following limitations:
(a) The
taxpayer may only transfer such portion of the tax credit as the taxpayer has
neither applied against the income taxes imposed by this article nor used to
obtain a refund;
(b) The
taxpayer may transfer a pro-rated portion of the tax credit to more than one
transferee;
(c) A
transferee may not elect to have any transferred credit refunded pursuant to
paragraph (b) of subsection (5) of this section;
(d)
Repealed.
(e) To
the extent that a transferee paid value for the transfer of a conservation
easement tax credit to such transferee, the transferee shall be deemed to have
used the credit to pay, in whole or in part, the income tax obligation imposed
on the transferee under this article, and to such extent the transferee's use
of a tax credit from a transferor under this section to pay taxes owed shall
not be deemed a reduction in the amount of income taxes imposed by this article
on the transferee;
(f) The
transferee shall submit to the department a form approved by the department.
The transferee shall also file a copy of the form with the entity to whom the
taxpayer donated the conservation easement.
(g) A
transferee of a tax credit shall purchase the credit prior to the due date
imposed by this article, including any extensions, for filing the transferee's
income tax return;
(h) A
tax credit held by an individual either directly or as a result of a donation
by a pass-through entity, but not a tax credit held by a transferee unless used
by the transferee's estate for taxes owed by the estate, shall survive the
death of the individual and may be claimed or transferred by the decedent's
estate. This paragraph (h) shall apply to any tax credit from a donation of a
conservation easement made on or after January 1, 2000.
(i) For
a donation made prior to January 1, 2021, the donor of an easement for which a
tax credit is claimed or the transferor of a tax credit claimed for the
donation of the easement transferred pursuant to this subsection (7) is the tax
matters representative in all matters with respect to the credit. The tax
matters representative is responsible for representing and binding the
transferees with respect to all issues affecting the credit, including, but not
limited to, the charitable contribution deduction, the appraisal, notifications
and correspondence from and with the department of revenue, audit examinations,
assessments or refunds, settlement agreements, and the statute of limitations.
The transferee is subject to the same statute of limitations with respect to
the credit as the transferor of the credit.
(j) For
a tax credit claimed for the donation of an easement made prior to January 1,
2021, final resolution of disputes regarding the tax credit between the
department of revenue and the tax matters representative, including final
determinations, compromises, payment of additional taxes or refunds due, and
administrative and judicial decisions, is binding on transferees.
(7.5)
(a) For income tax years commencing on or after January 1, 2021, in lieu of
a credit with respect to the income taxes imposed by this article 22, there is
allowed a transferable expense amount to each qualified entity that donates
during the taxable year all or part of the value of a perpetual conservation
easement in gross created pursuant to article 30.5 of title 38 upon real
property the qualified entity owns to a governmental entity or a charitable
organization described in section 38-30.5-104 (2). A transferable expense
amount shall be treated in all manners as a tax credit for purposes of this
section, including provisions governing the amount, valuation, and transfer of
a tax credit; except that the transferable expense amount may only be transferred
to a transferee to be claimed by the transferee as a credit pursuant to this
section. A qualified entity may transfer a transferable expense amount to be
claimed as a credit by a transferee pursuant to this section regardless of
whether the qualified entity receives value in exchange for the transfer.
(b) As
used in this subsection (7.5), "qualified entity" means a
governmental entity that meets the definition of "taxpayer" as set
forth in subsection (1)(b) of this section but is otherwise exempt from the
income taxes imposed by this article 22.
(8) The
executive director of the department of revenue may promulgate rules for the
implementation of this section. Such rules shall be promulgated in accordance
with article 4 of title 24, C.R.S.
(9) Any
taxpayer who claims a credit for the donation of a conservation easement
contrary to the provisions of this section shall be liable for such
deficiencies, interest, and penalties as may be specified in this article or
otherwise provided by law.
(10) and
(11) Repealed.
(12)
For income tax years commencing on or after January 1, 2024, every taxpayer
exempt from taxes pursuant to section 39-22-112 that claims the credit allowed
in this section shall file a return pursuant to section 39-22-601 (7)(b).
(13)
Any transferee who is subject to the tax on insurance premiums established by
sections 10-3-209, 10-5-111, and 10-6-128, and who is therefore exempt from the
payment of income tax and who is otherwise eligible to claim a tax credit
pursuant to this section may claim the tax credit and carry the tax credit
forward against the insurance premium tax to the same extent as the transferee
would have been able to claim or carry forward the tax credit against income
tax. All other provisions of this section with respect to the tax credit,
including the amount and allocation of the tax credit and the years for which
the tax credit may be claimed shall apply to a tax credit claimed pursuant to
this section.
(14)
For any conservation easement granted on or after January 1, 2025, the
conservation easement may include a provision providing that if technological
or legal changes allow an expanded use of wind and solar power generation,
transmission, and storage to be compatible with the protection of conservation
values considered as a whole and pursuant to section 170 (h) of the internal
revenue code and any federal regulations promulgated in connection with such
section, then the holder of the conservation easement may, in its sole
discretion, approve expanded wind and solar power generation, transmission, or
storage that is compatible with and does not diminish or impair conservation
values.
(14.3)
The division of conservation shall not issue any additional credit certificates
or amend any previously issued credit certificates as a result of the
additional authority granted by House Bill 26-1230, enacted in 2026, for a
donation made prior to June 1, 2026. This subsection (14.3) does not limit the
authority of the division of conservation to issue a tax credit certificate
against the limits set forth in subsection (2.5) of this section for a calendar
year prior to 2032 with respect to a donation made prior to June 1, 2026.
(14.5)
(a) The general assembly hereby finds and declares that:
(I)
Over the last sixty years, Colorado families have conserved over three million
five hundred thousand acres of working farms, ranches, and private lands across
the state;
(II)
Since 2000, Colorado has proactively invested in conservation through the
conservation easement tax credit program;
(III)
The conservation easement tax credit program incentivizes private landowners to
voluntarily protect their properties, which creates public benefits to
Colorado's lands, waters, wildlife, and people;
(IV)
The benefits of conservation are unique and wide-ranging. Conservation has
contributed significantly to the protection of wildlife habitat, critical
wetlands, urban open space, and working farms and ranches;
(V) The
conservation easement tax credit program has aided Colorado in reducing its
carbon emissions and accomplishing its biodiversity goals, while supporting
rural economic resiliency, benefiting all Coloradans;
(VI) In
pursuit of greater equity in conservation, it is crucial to enhance programs
that promote public benefits for all Coloradans;
(VII)
Equity in conservation requires ongoing collaboration with private landowners,
state and federal public land managers, and counties and municipalities.
Underscoring and investing in the inclusion of underserved communities, tribes,
and historically marginalized land interests will further amplify these
efforts; and
(VIII)
It is in the best interests of Coloradans to enhance the conservation easement
tax credit program.
(b) (I)
In accordance with section 39-21-304 (1), which requires each bill that extends
an expiring tax expenditure to include a tax preference performance statement,
the general assembly further finds and declares that the general purpose of the
extension of the expiring tax credit provided for in subsections (2) and (2.5)
of this section is to induce certain behavior by taxpayers. Specifically, this
extension of an expiring tax expenditure is intended to induce private
landowners to voluntarily protect their properties through conservation
easements.
(II)
The general assembly and the state auditor shall measure the effectiveness of
the tax credits in achieving the purposes specified in subsection (14.5)(b)(I)
of this section based on the number and value of the credits claimed and the
total amount of property protected by conservation easements.
(15)
This section is repealed, effective January 1, 2057.
Source:
L. 99: Entire
section added, p. 976, § 1, effective August 4. L. 2000: (4), (5), and
(6) amended and (7) and (8) added, p. 894, § 1, effective August 2. L. 2001:
(1), (2), (3), (4), and (5)(b)(III) amended, p. 395, § 6, effective August 8;
(1), (2), (3), (4), (5)(b)(III), (6), (7)(a), (7)(b) amended and (7)(e) and
(7)(f) added, p. 901, § 1, effective January 1, 2003. L. 2002: (2)
amended and (9) added, p. 510, § 1, effective August 7; (2) amended and (9)
added, p. 511, § 2, effective January 1, 2003. L. 2005: (3.5), (7)(g),
(7)(h), (7)(i), and (7)(j) added, pp. 1479, 1480, §§ 1, 2, effective June 7. L.
2006: (4) amended, p. 822, § 1, effective August 7. L. 2007: (3),
(3.5), and (7)(i) amended and (3.3), (10), and (11) added, p. 1228, § 3,
effective August 3. L. 2008: (3)(b), (3)(e), IP(3)(f), (3)(f)(I), (3.3),
and (3.5) amended and (3.7) added, p. 2316, § 8, effective July 1. L. 2010:
(2.5) added, (HB 10-1197), ch. 175, p. 635, § 4, effective August 11. L.
2011: (2.5) amended, (HB 11-1300), ch. 193, p. 753, § 4, effective May 19. L.
2013: (2), (2.5), IP(3), (3.3), (3.5), (6), (10), and (11) amended and
(2.7) and (3.6) added, (SB 13-221), ch. 251, p. 1330, § 9, effective August 7;
(2.5) amended, (HB 13-1183), ch. 252, p. 1338, § 2, effective August 7. L.
2014: (4)(a)(III) amended, (SB 14-019), ch. 10, p. 99, § 6, effective
February 27; (2.5), (2.7), (3)(e), IP(3)(f), (3.3), (3.5), (3.6)(a)(I), and
(3.6)(b) amended, (SB 14-117), ch. 385, p. 1919, § 8, effective July 1. L.
2015: (4)(a)(II) amended and (4)(a)(II.5) added, (SB 15-206), ch. 272, p.
1086, § 1, effective June 4. L. 2017: IP(3)(f) amended and (3)(f)(I)
repealed, (SB 17-294), ch. 264, p. 1414, § 108, effective May 25. L. 2018:
(2.5), (2.7), IP(3)(f), (3.5), (3.6)(a)(I), (3.6)(b), and (7)(g) amended and
(3.8) added, (HB 18-1291), ch. 273, p. 1689, § 6, effective May 29. L. 2019:
(2.7), (3.3), and (4)(a)(II.5) amended and (3.8) repealed, (HB 19-1264), ch.
420, p. 3678, § 8, effective June 30; (2.5), (2.7), IP(3)(f), (3.3), (3.5),
(3.6)(a)(I), and (3.6)(b) amended, (HB 19-1172), ch. 136, p. 1729, § 255,
effective October 1. L. 2021: (1), (2.7), (3.5)(b), (3.6), (4)(a)(II.5),
(4)(b), (5)(b)(III), (6), IP(7), (7)(i), and (7)(j) amended, (4)(a)(II.7) and
(7.5) added, and (7)(d), (10), and (11) repealed, (HB 21-1233), ch. 385, p.
2578, § 4, effective June 30. L. 2024: (2)(a), (2)(b), (2.5),
(4)(a)(II.7), (4)(b)(II)(D), (5)(b)(II), and (5)(b)(III) amended and
(4)(a)(II.8), (4)(b)(II)(E), (13), (14), and (15) added, (SB 24-126), ch. 211,
p. 1291, § 7, effective August 7; (12) added, (HB 24-1036), ch. 373, p. 2536, §
34, effective August 7. L. 2026: (2), (2.5), and (15) amended and (14.3)
and (14.5) added, (HB 26-1230), ch. 291, p. 1600, § 1, effective June 1.
Editor's
note: (1)
Subsections (2), (4), and (5)(b)(III) were amended in House Bill 01-1364. Those
amendments were superseded by the amendments to said subsections in House Bill
01-1090, effective January 1, 2003.
(2) Amendments to subsection
(2.5) by House Bill 13-1183 and Senate Bill 13-221 were harmonized.
(3) Section 9 of chapter 10 (SB
14-019), Session Laws of Colorado 2014, provides that changes to this section
by the act apply to income tax years commencing on or after January 1, 2013,
and any other income tax years that are open under § 39-21-107 or 39-21-108.
(4) Amendments to subsections
(2.7) and (3.3) by HB 19-1172 and HB 19-1264 were harmonized.
Cross
references: (1)
For the legislative declaration contained in the 2001 act amending subsections
(1), (2), (3), (4), and (5)(b)(III), see section 1 of chapter 133, Session Laws
of Colorado 2001.
(2) For the legislative
declaration contained in the 2008 act amending subsections (3)(b), (3)(e), the
introductory portion to subsection (3)(f), subsections (3)(f)(I), (3.3), and
(3.5) and enacting subsection (3.7), see section 1 of chapter 448, Session Laws
of Colorado 2008.
(3) For the legislative
declaration in the 2013 act amending subsections (2), (2.5), the introductory
portion to subsection (3), and subsections (3.3), (6), (10), and (11) and
adding subsections (2.7) and (3.6), see section 1 of chapter 251, Session Laws
of Colorado 2013.
(4) For the legislative
declaration in SB 24-126, see section 1 of chapter 211, Session Laws of
Colorado 2024. For the legislative declaration in HB 24-1036, see section 1 of
chapter 373, Session Laws of Colorado 2024.
ANNOTATION
Law reviews. For
article, "The Unique Benefits of Conservation Easements in Colorado",
see 30 Colo. Law. 49 (Dec. 2001). For article, "Changes to Colorado's
Conservation Income Tax Credit Law", see 32 Colo. Law. 65 (Feb. 2003). For
article, "Recent Developments With Conservation Easements", see 43
Colo. Law. 53 (Mar. 2014).
The general assembly's
intent in enacting subsection (7)(i) was to ensure that the department of
revenue would have only one taxpayer with whom to address the question of value
and validity of a credit. Markus v. Brohl, 2014 COA 146, 412 P.3d 647.
The department of revenue
only has four years from the time a conservation easement tax credit is first
claimed to review the validity and value of the credit. Markus v. Brohl,
2014 COA 146, 412 P.3d 647.
The statute of limitations
period begins when the donor of the conservation easement, not the transferee
of the credit, claims the conservation easement tax credit. This accrual
applies to and binds any transferees of the credit. State v. Medved, 2019 CO 1,
433 P.3d 33.
The $100,000 "per
donation" cap on the amount of the tax credit that could be claimed under
a prior version of this section was an aggregate cap on the amount of the
credit that could be claimed by all tenants in common for the donation of undivided
property. The department of revenue therefore properly reduced to a total
of $100,000 total conservation easement tax credits of $154,700 claimed in
equal shares by two tenants in common. Huber v. Kenna, 205 P.3d 1158 (Colo.
2009) (decided under former law).
The general assembly did not
intend to require joinder of transferees; however, this section and §
39-22-522.5 cannot be construed to preclude mandatory joinder of
transferees or notice to transferees by service of summons and complaint, if
required by due process. Kowalchik v. Brohl, 2012 COA 49, 411 P.3d 681.
Due process does not require
joinder of transferees in litigation where the transferee is represented by its
tax matters representative. The transfer of a conservation easement tax
credit creates a prelitigation relationship between the tax matters
representative and the transferee, in which their interests are closely aligned
in upholding the validity of the conservation easement credit, and the tax
matters representative is motivated to defend the credit. This section informs
tax matters representatives that they are representing transferees who will be
bound by the outcome of litigation, and transferees have an absolute right to
intervene under § 39-22-522.5. Thus, the procedure is designed to provide for a
full and fair consideration of transferees' issues. Kowalchik v. Brohl, 2012
COA 49, 411 P.3d 681.
A transferee is a taxpayer
within the meaning of subsection (1) and is subject to liability for
deficiencies, interest, and penalties under subsection (9). Kowalchik v.
Brohl, 2012 COA 49, 411 P.3d 681.
39-22-522.5. Conservation easement tax
credits - dispute resolution - legislative declaration.
(1) The
general assembly hereby finds, determines, and declares that:
(a)
Colorado's conservation easement program is an important preservation tool used
to balance economic needs with natural resources such as land and water
preservation. Colorado's conservation easement tax credit and the federal tax
deduction have allowed many farmers and ranchers the opportunity to donate
their development rights to preserve a legacy of open spaces in Colorado for
wildlife, agriculture, and ranching.
(b)
Citizens throughout Colorado believe good, sound conservation practices are
important to Colorado's quality of life, agriculture, and wildlife heritage;
(c)
Colorado's conservation easement tax credit program was designed to give
landowners an incentive to conserve and preserve their land in a predominantly
natural, scenic, or open condition;
(d)
While the department of revenue has allowed the great majority of claimed
conservation easement tax credits, hundreds of claimed credits have been denied
but have not yet been finally adjudicated through the existing administrative
process;
(e) Due
to the unique issues of confidentiality and multiple interested and related
parties involved in the litigation of disputed conservation easement tax
credits, the general assembly determines that it is appropriate to enact
procedural changes that will provide for equitable and expedited litigation or
resolution of these cases;
(f) It
is the intent of the general assembly to enact procedural changes that further
important matters of public policy concerning the equitable and efficient
resolution of disputes regarding claimed conservation easement tax credits. It
is the intent of the general assembly that any appeal brought pursuant to
subsection (2) of this section shall be expedited to the extent practicable and
administered in the manner deemed most efficient and fair by the executive
director or the district court.
(g) The
procedural changes set forth in this section shall apply to any dispute
regarding a tax credit from a donation of a conservation easement made on or
after January 1, 2000, for which a final determination has not been issued;
(h) It
is the intent of the general assembly to provide taxpayers with incentives to
waive an administrative hearing and proceed directly to a de novo appeal to the
district court in accordance with the procedures set forth in this section. The
incentives include waiver of the bond requirement and waiver of accrual of
interest and penalties during the time the matter is on appeal to the district
court.
(i) The
general assembly strongly encourages the executive director of the department
of revenue to agree to waive interest and penalties for tax matters
representatives and credit buyers who have acted in good faith to resolve
disputed conservation easement tax credits; and
(j)
This section is intended to effect changes to the law that are procedural or
remedial in nature. The procedural changes set forth in this section shall not
be construed to take away or impair any vested right acquired under existing
law, or to create any new obligation, impose any new duty, or attach any new
disability with respect to any past transaction or consideration. The
provisions of this section are designed to address matters of public policy
related to the fair and equitable resolution of conservation easement tax
credit disputes in accordance with applicable laws and court rules.
(2) For
any credit claimed pursuant to section 39-22-522, for which a notice of
deficiency, notice of disallowance, or notice of rejection of refund claim has
been mailed by the department of revenue as of May 1, 2011, but for which a
final determination has not been issued before May 19, 2011, the tax matters
representative may elect to waive the administrative process provided by
section 39-21-103 and appeal the notice of deficiency, disallowance, or
rejection of refund claim directly to a district court in accordance with the
following provisions, which also apply to an appeal filed in accordance with
subsection (6) of this section; except that paragraphs (a), (c), and (d) of
this subsection (2) shall not apply to such an appeal:
(a) The
tax matters representative shall make the election by mailing a written notice
of appeal that includes the certified signature of the tax matters
representative to the executive director and the district court for the county
that has venue in the case as specified in paragraph (b) of this subsection (2)
on or before October 1, 2011. The notice shall be sent by certified mail.
(b)
Appeals brought pursuant to this section shall be filed in the district court
for the county where the land encumbered by the easement is located. At the
discretion of the chief justice, the state may be divided into three regions
for purposes of consolidating appeals, with each region consisting of the
following judicial districts:
|
Region
|
Judicial Districts
|
|
Region
1
|
1st,
2nd, 8th, 13th, 17th, 18th, 19th, and 20th
|
|
Region
2
|
3rd,
4th, 10th, 11th, 12th, 15th, and 16th
|
|
Region
3
|
5th,
6th, 7th, 9th, 14th, 21st, and 22nd
|
(c) If
a tax matters representative elects to waive the administrative process and
appeal directly to a district court pursuant to this subsection (2), no surety
bond or other deposit shall be required in connection with the appeal. This
paragraph (c) shall not apply to tax matters representatives who do not elect
to waive the administrative process.
(d) If
the tax matters representative elects to waive the administrative process and
appeal directly to a district court pursuant to this subsection (2), additional
interest and penalties shall cease to accrue while the matter is on appeal
before the district court, beginning with the date the notice of appeal is
received by the district court. This paragraph (d) shall not apply to tax
matters representatives who do not elect to waive the administrative process.
(e)
Upon receipt of the notice of appeal by the court, the executive director shall
be deemed to be a party to such appeal, and the clerk of the district court
shall docket the cause as a civil action. The appellant shall cause summons to
be issued and cause the same to be served upon the executive director in
accordance with the manner provided by law in civil cases. The answer of the
executive director shall contain a brief, plain statement of the legal issues,
a detailed itemization of the total amount in controversy, and any proposal
regarding the joinder or consolidation of related parties and appeals.
(f) Any
transferee of the tax credit or any other person who has claimed a tax credit
related to the tax matters representative's claimed conservation easement tax
credit shall be allowed to intervene as a matter of right pursuant to the
Colorado rules of civil procedure.
(g)
Notice of the date of any hearing or any phase of the trial shall be mailed to
the tax matters representative, any other party, and to the executive director
at least thirty days prior thereto.
(h)
Jurisdiction to hear and determine appeals pursuant to this section is
conferred upon the district courts of this state. A court, in its discretion,
may allow for the assertion, consolidation, and settlement of any claims at law
or at equity, for the intervention of additional parties, and for such other
matters as the court deems appropriate in accordance with any applicable laws
or court rules governing such issues; except that resolution of disputes
between private parties may be limited to the third phase of the case as
described in paragraph (m) of this subsection (2). In determining matters
regarding joinder or consolidation, the court may consider common issues of law
and fact, including but not limited to ownership of the property subject to the
easement, relationships of taxpayers, and location of the easements.
(i)
Following the court's order identifying the parties and consolidating cases and
parties, the court may hold a hearing to determine the validity of the
conservation easement credit claimed pursuant to section 39-22-522 and to
determine any other claims or defenses touching the regularity of the
proceedings. The court shall determine whether the donation is eligible to
qualify as a qualified conservation contribution. The court may set an
expedited briefing schedule and give the matter priority on the docket. The
court may order preliminary discovery, limited to validity of the easement
credits and any other claims or defenses raised at this stage of the
proceeding.
(j)
Upon a determination of validity of the credit as claimed, the court may
schedule a case management conference with all parties to the proceeding. Any
case management conference shall address the proceedings as set forth in
paragraph (m) of this subsection (2). Prior to the case management conference,
the court may order all parties to make the following disclosures:
(I) The
department of revenue shall disclose, consistent with any orders of the court,
individuals with knowledge of, and documents related to:
(A)
Notices to the tax matters representative disallowing the conservation easement
credit;
(B)
Notices to any taxpayer of deficiency or rejection of claim for refund;
(C)
Correspondence with the tax matters representative or donee of the easement as
well as any party to the conservation easement tax credit action;
(D)
Appraisals and review appraisals or other expert reports used in connection
with review of the tax matters representative's application for tax credit;
(E) Tax
returns of the tax matters representative, transferee, or any party to the
conservation easement tax credit action, for relevant tax years; and
(F)
Statements of adjustment.
(II)
The tax matters representative shall disclose individuals with knowledge of,
and documents related to:
(A) Tax
returns for the relevant tax years;
(B) The
appraisal used to determine the value of the easement;
(C) The
conservation easement deed and amendments;
(D)
Agreements between the tax matters representative and the transferees; and
(E) Any
other expert report, basis, or other evidence relating to the valuation and
substantiation of the amount of the underlying easement or credit.
(III)
Transferees or other persons claiming all or part of the conservation easement
tax credit who are parties to the conservation easement tax credit action shall
disclose individuals with knowledge of, and documents related to:
(A)
Agreements related to the transfer of credits;
(B) Tax
returns for the relevant tax years; and
(C) Any
other expert report, basis, or other evidence relating to the valuation and
substantiation of the amount of the underlying easement or credit.
(k) The
court may make any order it deems appropriate to control and limit discovery to
avoid unnecessary duplication between or among parties, including setting such
limitations in accordance with the phases of the proceedings as set forth in
paragraph (m) of this subsection (2).
(l) In
advance of the trial date, the court may require the parties to confer and
submit a proposed trial management order to the court.
(m)
After a determination pursuant to paragraph (i) of this subsection (2) of the
validity of the credit as claimed, the court shall resolve all remaining issues
as follows:
(I) The
first phase shall be limited to issues regarding the value of the easement.
(II)
The second phase shall be limited to determinations of the tax, interest, and
penalties due and apportionment of such tax liability among persons who claimed
a tax credit in relation to the conservation easement. The conservation
easement tax credit action shall be final at the conclusion of the second phase
as to the department of revenue and as to any taxpayer, transferee, or other
party with regard to that party's tax credit dispute with the department of
revenue.
(III)
The third phase shall address all other claims related to the conservation
easement tax credit, including those between and among the tax matters
representative, transferees, other persons claiming a tax credit in connection
with the donation, and any third party joined as a party to the action. The
department shall not be required to participate in or be a party to this third
phase. Any participation in these proceedings by parties other than the tax
matters representative, transferees, or other persons who have claimed all or
part of a conservation easement tax credit is limited to this third phase.
(n) The
district court shall hear the appeal in accordance with the Colorado rules of
civil procedure and the rules of evidence.
(o) The
chief justice of the supreme court may designate judges to hear appeals brought
pursuant to this subsection (2), and may determine that only judges so
designated may hear such appeals. For the convenience of the parties and in
order to facilitate the use of available court facilities, hearings may be
conducted at the discretion of the court in any county within the region for
which venue has been established for a case pursuant to paragraph (b) of this
subsection (2).
(p) The
district court shall enter judgment on its findings. The court shall have the
authority to establish the amount of any deficiency and to waive or otherwise
modify the amount of any interest, penalties, or other amounts owed. The court
shall indicate in any order whether the judgment of the court is a final
judgment subject to appeal as to any party.
(q) It
is the intent of the general assembly that any appeals brought pursuant to this
subsection (2) shall be expedited to the extent practicable and administered in
the manner deemed most efficient and fair by the courts.
(3) A
tax matters representative who does not make an election to waive a hearing
pursuant to subsection (2) of this section and appeal directly to a district
court may send a written request for hearing and final determination by
certified mail to the executive director on or before October 1, 2011. If a tax
matters representative files a request pursuant to this subsection (3), the
executive director shall issue a final determination on or before July 1, 2014,
unless the executive director and the tax matters representative mutually agree
in writing to extend such date to a specified date. The executive director
shall send a copy of the final determination to the tax matters representative
by certified mail on or before July 1, 2014. If the United States post office
returns the final determination as undeliverable by certified mail, the
department shall then mail the final determination in accordance with section
39-21-105.5. This subsection (3) shall apply only to those tax matters
representatives for which a notice of deficiency, notice of disallowance, or
notice of rejection of refund claim has been mailed by the department of
revenue as of May 1, 2011, but for which a final determination has not been
issued before May 19, 2011.
(4) The
executive director shall issue a final determination on or before July 1, 2016,
for any tax matters representative who does not make an election to waive a hearing
pursuant to subsection (2) of this section or file a written request for final
hearing and final determination with the executive director pursuant to
subsection (3) of this section. The executive director shall send a copy of the
final determination to the tax matters representative by certified mail on or
before July 1, 2016. If the United States post office returns the final
determination as undeliverable by certified mail, the department shall then
mail the final determination in accordance with section 39-21-105.5. If a tax
matters representative does not make an election to waive a hearing pursuant to
subsection (2) of this section or file a written request for final hearing and
final determination with the executive director pursuant to subsection (3) of
this section, any person who has claimed a credit or who may be eligible to
claim a tax credit in relation to the tax matters representative's donation may
petition the department on or before November 1, 2011, to change the tax
matters representative's designation. The executive director shall promulgate
rules on or before September 1, 2011, specifying the procedures for a change to
the tax matters representative's designation when the executive director
determines that the tax matters representative is unavailable or unwilling to
act as the tax matters representative. If the department grants the petition,
the new tax matters representative may file an appeal pursuant to subsection
(2) of this section or file a written request for final hearing and final
determination with the executive director pursuant to subsection (3) of this
section within thirty days of the department's order regarding the petition.
This subsection (4) shall apply only to those tax matters representatives for
which a notice of deficiency, notice of disallowance, or notice of rejection of
refund claim has been mailed by the department of revenue as of May 1, 2011,
but for which a final determination has not been issued before May 19, 2011.
(5) In
order to expedite the equitable resolution of requests for an administrative
hearing regarding any conservation easement tax credit, avoid inconsistent
determinations, and allow the executive director or the executive director's
designee to consider the full scope of applicable issues of law and fact, the
executive director or the executive director's designee shall have discretion
to issue orders as set forth in paragraphs (a) to (e) of this subsection (5) as
follows:
(a) To
consolidate cases involving common or related issues of fact or law. In
identifying related cases, the executive director or the executive director's
designee may consider any common issues of law or fact, including but not
limited to common ownership of the property subject to the easement,
relationships of the taxpayers, and location of the easements.
(b) To
issue a final order finding that a case cannot reasonably be resolved through
the administrative process and transferring jurisdiction of the case to the
district court in accordance with subsection (2) of this section. Such a final
order may issue for reasons including but not limited to a waiver of
administrative process pursuant to paragraph (a) of subsection (2) of this
section by another tax matters representative where consolidation would
otherwise be appropriate pursuant to paragraph (a) of this subsection (5).
Prior to issuance of such a final order, the parties shall have the opportunity
to file written briefs addressing the proposed transfer.
(c) If
a tax matters representative fails to appear at a hearing or the tax matters
representative has failed to adequately participate in such hearing, including
but not limited to a failure to file the required pleadings or to appear at a
scheduled conference, the executive director may without further proceedings
issue a final determination.
(d) To
invite participation in the administrative process by any person who may be
affected or aggrieved by a final determination, including but not limited to
transferees. Such participation shall include the right to be admitted as a
party to a hearing. Upon the person's filing of a written request setting forth
a brief and plain statement of the facts that entitle the person to be admitted
and the matters to be decided, the executive director or the executive
director's designee shall have the authority to admit such person for limited
purposes. This process shall be available only to persons who have claimed a
credit or who may be eligible to claim a tax credit in relation to the
conservation easement.
(e) If
a tax matters representative has not provided any document related to the
credit that was required to be provided as part of the taxpayer's return,
including the return itself, or, if requested by the department for
conservation easements donated prior to January 1, 2014, a copy of the complete
appraisal obtained at the time of donation, the department may send a written
request to the taxpayer for such document. Failure to provide the requested
documents within sixty days of any such request shall constitute grounds for
the issuance of a final determination denying the credit.
(6) For
any tax matters representative for which the executive director issued a final
determination on or after May 1, 2011, the tax matters representative may
appeal the final determination of the executive director pursuant to the
provisions of section 39-21-105. The procedure governing such appeal shall be
in accordance with the provisions of subsection (2) of this section; except
that paragraphs (a), (c), and (d) of said subsection (2) shall not apply. If a
tax matters representative fails to file a timely appeal pursuant to this
subsection (6), any person who has claimed a credit or who may be eligible to
claim a tax credit in relation to the tax matters representative's donation may
petition the department to change the tax matters representative's designation
within ten days after the final date for filing an appeal. The executive
director shall promulgate rules on or before September 1, 2011, specifying the
procedures for a change to the tax matters representative's designation when
the executive director determines that the tax matters representative is
unavailable or unwilling to act as the tax matters representative. If the
department of revenue grants the petition, the new tax matters representative
may file an appeal pursuant to the provisions of this subsection (6) within
thirty days of the department's order regarding the petition.
(7) If
the executive director fails to issue a final determination on or before the
dates specified or agreed to in subsection (3) or (4) of this section, the
authority of the executive director to dispute the claim of the credit shall be
waived, the full amount of the credit in dispute shall be allowed, and no
interest or penalties shall be imposed upon such amount.
(8)
Repealed.
(9) The
executive director shall send a notice to each tax matters representative
eligible to waive a hearing and appeal a notice of deficiency, notice of
rejection of refund claim, or notice of disallowance to a district court
pursuant to subsection (2) of this section to notify the tax matters
representative of the provisions of this section. The notice shall be sent by
certified mail to the tax matters representative's last-known address on or
before July 1, 2011. If the United States post office returns the notice as
undeliverable by certified mail, the department shall then mail the notice in
accordance with section 39-21-105.5. The notice shall not be included with any
other mailing and shall include the words "Important Tax Document Enclosed"
on the exterior of the mailing. The executive director shall further provide
notice of the provisions of this section on the department of revenue's website
and by such other means as the executive director deems appropriate. The
executive director shall maintain adequate records to verify compliance with
the provisions of this subsection (9).
(10) If
the executive director makes a determination that the tax matters
representative has transferred a disputed credit to another person who has not
claimed the credit or that a person who claimed or may claim a disputed credit
pursuant to section 39-22-522 cannot be identified or located, the executive
director shall provide notice to such person as follows:
(a) The
executive director shall file an affidavit with the district court having
jurisdiction over an appeal of the credit setting forth that the executive
director has made diligent inquiry and has been unable to locate such person.
(b) The
district court shall then order a notice to be published by the department of
revenue in some local newspaper of general circulation named by the judge and
on the department's website. The notice shall identify the property that is
subject to the conservation easement and the date of the donation, and shall
explain the right of the person to request joinder in the action on the
disputed credit before the court, the time and place at which such request must
be filed, and the title and address of the court at which the request must be
filed.
(11) If
a tax matters representative proceeds with the hearing process before the
executive director rather than appeal to a district court pursuant to
subsection (2) of this section and either the tax matters representative or one
or more transferees pays an amount on or before June 30, 2012, that satisfies a
deficiency in an amount agreed to by the department of revenue for the tax owed
by the tax matters representative or the transferee, all additional amounts of
penalties and interest owed shall be waived.
(12) and
(13) Repealed.
(14)
Prior to the issuance of a final determination or the conclusion of an appeal
of a notice of deficiency, notice of disallowance, or notice of rejection of
refund claim for a tax credit claimed by a tax matters representative or a
transferee pursuant to section 39-22-522, the executive director shall cease
all actions to collect any amount of the disputed taxes, interest, or other
charges asserted to be owed. The executive director shall provide notice of the
provisions of this subsection (14) in accordance with subsection (9) of this
section.
Source:
L. 2011: Entire
section added, (HB 11-1300), ch. 193, p. 741, § 1, effective May 19. L.
2013: (5)(e) and (12) amended, (SB 13-221), ch. 251, p. 1334, § 10,
effective August 7. L. 2014: (8), (12)(a)(II), and (12)(a)(III) amended,
(SB 14-117), ch. 385, p. 1922, § 9, effective July 1. L. 2017: (12) and
(13) repealed, (HB 17-1137), ch. 45, p. 134, § 6, effective August 9. L.
2018: (8) repealed, (HB 18-1291), ch. 273, p. 1692, § 7, effective May 29.
Cross
references: For
the legislative declaration in the 2013 act amending subsections (5)(e) and
(12), see section 1 of chapter 251, Session Laws of Colorado 2013.
ANNOTATION
The general assembly did not
intend to require joinder of transferees; however, this section and § 39-22-522
cannot be construed to preclude mandatory joinder of transferees or notice
to transferees by service of summons and complaint, if required by due process.
Kowalchik v. Brohl, 2012 COA 49, 411 P.3d 681.
Due process does not require
joinder of transferees in litigation where the transferee is represented by its
tax matters representative. The transfer of a conservation easement tax
credit creates a prelitigation relationship between the tax matters
representative and the transferee, in which their interests are closely aligned
in upholding the validity of the conservation easement credit, and the tax
matters representative is motivated to defend the credit. Under this section,
transferees have an absolute right to intervene, and § 39-22-522 informs tax
matters representatives that they are representing transferees who will be
bound by the outcome of litigation. Thus, the procedure is designed to provide
for a full and fair consideration of transferees' issues. Kowalchik v. Brohl,
2012 COA 49, 411 P.3d 681.
Appeal dismissed due to lack
of final judgment. When a district court has issued an order determining
only that a credit claimed under this section is invalid pursuant to subsection
(2)(i) and has not yet determined the amount of tax, interest, and penalties
owed to the department of revenue by the taxpayer who had improperly claimed
the credit, the order is not a final judgment subject to appeal notwithstanding
the district court's erroneous statement to the contrary. Atherton v. Brohl,
2015 COA 59, 353 P.3d 907.
39-22-523. Credit against tax -
contributions to high technology scholarship program - mechanism to refund
excess state revenues. (Repealed)
Source:
L. 2000: Entire
section added, p. 1319, § 2, effective August 2. L. 2010: Entire section
repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1; entire section
repealed, (HB 10-1256), ch. 133, p. 440, § 4, effective August 11.
39-22-524. Tax credit for individuals
contributing matching funds for individual development accounts - repeal.
(Repealed)
Source:
L. 2000: Entire
section added, p. 1473, § 2, effective May 31. L. 2001: (4) amended, p.
413, § 3, effective April 19; (5) amended, p. 396, § 7, effective August 8. L.
2002: (7)(a) amended, p. 863, § 6, effective August 7. L. 2010: (10)
amended, (SB 10-212), ch. 412, p. 2035, § 9, effective July 1.
Editor's
note: Subsection
(10) provided for the repeal of this section, effective July 1, 2010. (See L.
2010, p. 2035.)
39-22-525. Contributions to Colorado
institute of technology - credit against tax. (Repealed)
Source:
L. 2000: Entire
section added, p. 1438, § 1, effective May 31. L. 2002: (1), (4)(a), and
(4)(c)(I) amended, p. 227, § 1, effective April 5. L. 2007: Entire
section repealed, p. 27, § 1, effective August 3; entire section repealed, p.
58, § 2, effective August 3.
39-22-526. Credit for environmental
remediation of contaminated land - legislative declaration - definition -
repeal.
(1) (a)
For income tax years commencing on or after January 1, 2014, but prior to
January 1, 2030, there is allowed a credit against the income taxes imposed by
this article 22 for any approved environmental remediation of contaminated
property to any taxpayer who meets the following requirements:
(I) The
property where the environmental remediation takes place must be located within
the state; and
(II)
The taxpayer seeking the credit must possess a certificate issued by CDPHE
pursuant to section 25-16-306 (5)(b) and subsection (3) of this section.
(b) (I)
The tax credit allowed in this section must not exceed forty percent of the
first seven hundred fifty thousand dollars expended for the approved
remediation, and must not exceed thirty percent of the next seven hundred fifty
thousand dollars expended for the approved remediation. For income tax years
commencing on or after January 1, 2022, with respect to approved remediation of
a site located in a rural community, the amount of the tax credit shall not
exceed fifty percent of the first seven hundred fifty thousand dollars expended
for the approved remediation, and must not exceed forty percent of the next
seven hundred fifty thousand dollars expended for the approved remediation. A
tax credit is not allowed for expenditures exceeding one million five hundred
thousand dollars on any individual project.
(II) As
used in this subsection (1)(b) and subsection (2)(b) of this section,
"rural community" means:
(A) A
municipality with a population of less than fifty thousand people that is not
located within the Denver metropolitan area; or
(B) The
unincorporated area of any county that is not located in the Denver
metropolitan area and that has a total population of less than fifty thousand
people.
(III)
As used in this subsection (1)(b) and subsection (2)(b) of this section,
"Denver metropolitan area" means Adams, Arapahoe, Boulder, and
Jefferson counties, the city and county of Broomfield, the city and county of
Denver, and all of Douglas county other than the town of Castle Rock and the
town of Larkspur.
(c) If
the credit allowed by this section exceeds the tax otherwise due, the excess
credit may be carried forward and claimed on the earliest possible subsequent
tax return for a period not to exceed five years.
(d) A
taxpayer may transfer all or a portion of a tax credit granted pursuant to this
subsection (1) to another taxpayer for such other taxpayer, as transferee, to
apply as a credit against the taxes imposed by this article 22 subject to the
following limitations:
(I) The
taxpayer may only transfer a portion of the tax credit that the taxpayer has
neither applied against the income taxes imposed by this article nor used to
obtain a refund.
(II)
The taxpayer may transfer a prorated portion of the tax credit to more than one
transferee.
(III)
Any transferee of a tax credit issued under this section may use the amount of
the tax credits transferred to offset against any other tax due under this
article 22. The transferor and the transferee of the tax credits shall jointly
file a copy of the written transfer agreement with the Colorado department of
public health and environment, referred to in this section as
"CDPHE", within thirty days after the transfer. Any filing of the
written transfer agreement with CDPHE perfects the transfer, and CDPHE shall
develop a system to track the transfers of tax credits and to certify the
ownership of tax credits. A certification by CDPHE of the ownership and the
amount of tax credits may be relied on by the department of revenue and the
transferee as being accurate, and neither CDPHE nor the department of revenue
shall adjust the amount of tax credits as to the transferee; except that CDPHE
and the department of revenue retain any remedies they may have against the
owner.
(IV) A
transferor may transfer a credit pursuant to this paragraph (d) regardless of
whether the transferor receives value in exchange for the transfer. The
transferee may use the credit to pay, in whole or in part, the income tax
obligation imposed on the transferee under this article. The transferee's use
of a tax credit from a transferor under this section to pay taxes owed is not
deemed a reduction in the amount of income taxes imposed by this article on the
transferee.
(V)
Repealed.
(VI)
The transfer of a tax credit must occur prior to the due date imposed by this
article, not including any extensions, for filing the transferee's income tax
return.
(VII) A
tax credit held by an individual either directly or as a result of distribution
by a pass-through entity, but not a tax credit held by a transferee unless used
by the transferee's estate for taxes owed by the estate, survives the death of
the individual and may be claimed or transferred by the decedent's estate.
(VIII)
The transferor of a tax credit transferred pursuant to this subsection (1)(d)
is the tax matters representative in all matters with respect to the credit.
The transferee is subject to the same statute of limitations with respect to
the credit as the transferor of the credit.
(IX) and
(X) Repealed.
(2) (a)
For income tax years commencing on or after January 1, 2014, but prior to
January 1, 2030, there is allowed to any qualified entity a transferable
expense amount for expenses incurred by the qualified entity in performing
approved environmental remediation. The transferable expense amount may only be
transferred to a taxpayer to be claimed by the taxpayer as a credit pursuant to
the provisions of this subsection (2). The transferrable expense amount is
allowed to any qualified entity that meets the following requirements:
(I) The
property where the environmental remediation takes place must be located within
the state; and
(II)
CDPHE must have issued a certificate for the property pursuant to section
25-16-306 (5)(b) and subsection (3) of this section.
(b) The
transferable expense amount allowed in this section must not exceed forty
percent of the first seven hundred fifty thousand dollars expended by the
qualified entity for the approved remediation, and must not exceed thirty
percent of the next seven hundred fifty thousand dollars expended by the
qualified entity for the approved remediation; except that, for income tax
years commencing on or after January 1, 2022, but before January 1, 2030, with
respect to approved remediation of a site located in a rural community, the
amount of the transferable expense shall not exceed fifty percent of the first
seven hundred fifty thousand dollars expended for the approved remediation, and
must not exceed forty percent of the next seven hundred fifty thousand dollars
expended for the approved remediation. A transferable expense amount is not
allowed for expenditures exceeding one million five hundred thousand dollars on
any individual project.
(c) A
qualified entity may transfer all or a portion of a transferable expense amount
allowed pursuant to this subsection (2) to a taxpayer for such taxpayer, as
transferee, to apply as a credit against the taxes imposed by this article 22
subject to the following limitations:
(I) The
qualified entity may transfer a prorated portion of the transferable expense
amount to more than one transferee.
(II)
Any transferee of a transferable expense amount issued under this section may
use the amount of the transferable expense amount transferred to offset against
any other tax due under this article 22. The transferor and the transferee of
the transferable expense amount shall jointly file a copy of the written
transfer agreement with CDPHE within thirty days after the transfer. Any filing
of the written transfer agreement with CDPHE perfects the transfer, and CDPHE
shall develop a system to track the transfers of transferable expense amounts
and to certify the ownership of transferable expense amounts. A certification
by CDPHE of the ownership and the amount of transferable expense may be relied
on by the department of revenue and the transferee as being accurate, and
neither CDPHE nor the department of revenue shall adjust the amount of
transferable expense as to the transferee; except that CDPHE and the department
of revenue retain any remedies they may have against the owner.
(III) A
qualified entity may transfer a transferable expense amount to be claimed as a
credit by a transferee pursuant to this subsection (2) regardless of whether
the qualified entity receives value in exchange for the transfer. The
transferee may use the credit to pay, in whole or in part, the income tax
obligation imposed on the transferee under this article. The transferee's use
of a tax credit from a qualified entity under this section to pay taxes owed is
not deemed a reduction in the amount of income taxes imposed by this article on
the transferee.
(IV)
Repealed.
(V) The
transfer of a transferable expense amount to a transferee must occur prior to
the due date imposed by this article, not including any extensions, for filing
the transferee's income tax return.
(VI) A
transferable expense amount held by a transferee's estate for taxes owed by the
estate, survives the death of the transferee and may be claimed or transferred
by the decedent's estate.
(VII)
The qualified entity that transfers a transferable expense amount to be claimed
as a credit by a transferee pursuant to this subsection (2) is the tax matters
representative in all matters with respect to the credit.
(VIII)
Repealed.
(d) As
used in this subsection (2), "qualified entity" means a county, home
rule county, city, town, home rule city, home rule city and county, school
district, charter school, special district, district authorized by article 20
of title 30, article 25 of title 31, and articles 41 to 50 of title 37, state
institution of higher education, quasi-governmental entity, or municipal,
quasi-municipal, or public corporation organized pursuant to law, or a private
nonprofit entity that is exempt from the income taxes imposed by this article
22.
(3) In
addition to any other requirements of this section, a taxpayer shall submit a
claim for a credit and a qualified entity shall submit a claim for a
transferrable expense amount to CDPHE. The department shall issue certificates
for the claims received in the order submitted. After certificates have been
issued for credits and transferrable expense amounts in the aggregate amount of
three million dollars for all taxpayers and qualified entities combined for the
2014 to 2021 calendar years and five million dollars for the 2022 to 2029
calendar years, any claims that exceed the amount allowed for the calendar year
shall be placed on a wait list in the order submitted and a certificate shall
be issued for use of the credit or transferrable expense amount in the next
year for which the department has not issued credit certificates in excess of
three or five million dollars respectively. The department shall not issue
certificates for any calendar year, including certificates placed on a wait
list for that year, in an aggregate amount that exceeds three or five million
dollars respectively. Two million dollars of the five million dollar cap is
reserved only for projects in a rural community. The remaining three million
dollars each year may be used by rural or nonrural communities. No claim for a
credit or a transferrable expense amount is allowed for any income tax year
commencing on or after January 1, 2014, unless a certificate has been issued by
the department pursuant to this subsection (3).
(3.5)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure or extends an expiring tax expenditure to include a tax
preference performance statement as part of a statutory legislative
declaration, the general assembly hereby finds and declares that:
(a) The
general legislative purposes of the income tax credit allowed by this section
are:
(I) To
induce certain designated behavior by taxpayers; and
(II) To
provide tax relief for certain businesses or individuals;
(b) The
specific legislative purpose of the income tax credit allowed by this section
is to encourage voluntary environmental remediation of contaminated sites by
providing a financial incentive to move forward with costly remediation
projects; and
(c) In
order to allow the general assembly and the state auditor to measure the
effectiveness of achieving the purposes specified in subsections (3.5)(a) and
(3.5)(b) of this section, CDPHE is required to provide data that indicates for
each calender year how many projects qualified for the credit and the number of
credit recipients.
(3.7)
For income tax years commencing on or after January 1, 2024, but prior to
January 1, 2025, every taxpayer exempt from taxes pursuant to section 39-22-112
that claims the credit allowed in this section shall file a return pursuant to
section 39-22-601 (7)(b).
(4)
This section is repealed, effective December 31, 2036.
Source:
L. 2000: Entire
section added, p. 891, § 2, effective January 1, 2001. L. 2005: IP(1)
and (4) amended, p. 1471, § 1, effective June 7. L. 2014: Entire section
R&RE, (SB 14-073), ch. 213, p. 793, § 1, effective August 6. L. 2022:
IP(1)(a), (1)(b), (1)(c), IP(1)(d), (1)(d)(III), (1)(d)(VII), (1)(d)(VIII),
IP(2)(a), (2)(b), IP(2)(c), (2)(c)(II), (2)(c)(VI), (2)(c)(VII), (2)(d), (3),
and (4) amended, (1)(d)(V), (1)(d)(IX), (1)(d)(X), (2)(c)(IV), and (2)(c)(VIII)
repealed, and (3.5) added, (HB 22-1392), ch. 412, p. 2912, § 2, effective June
7. L. 2024: IP(1)(a), (1)(a)(II), IP(2)(a), (2)(a)(II), (2)(b), (3), and
(4) amended, (HB 24-1116), ch. 382, p. 2604, § 1, effective August 7; (3.7)
added, (HB 24-1036), ch. 373, p. 2536, § 35, effective August 7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-22-527. Agricultural value-added tax
credit. (Repealed)
Source:
L. 2001: Entire
section added, p. 628, § 3, effective May 30. L. 2010: Entire section
repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-528. Tax credit for participation
in agriculture value-added cash fund. (Repealed)
Source:
L. 2001: Entire
section added, p. 628, § 3, effective May 30. L. 2010: Entire section
repealed, (SB 10-212), ch. 412, p. 2032, § 1, effective July 1.
39-22-529. Business expense deduction -
labor services - unauthorized alien - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Labor services" means the physical performance of services in this
state.
(b)
"Unauthorized alien" shall have the same meaning as set forth in 8
U.S.C. sec. 1324a (h)(3), as amended.
(2) On
or after January 1, 2008, no wages or remuneration for labor services paid to
an unauthorized alien of six hundred dollars or more in a year shall be claimed
as a deductible business expense for state income tax purposes by a taxpayer
who, at the time the taxpayer hired the unauthorized alien, knew of the
unauthorized status of the alien. The provisions of this subsection (2) shall
apply regardless of whether an internal revenue service form 1099-MISC is
issued in conjunction with the wages or remuneration.
(3)
This section shall not apply to:
(a) Any
business domiciled in the state that is exempt from compliance with federal
employment verification procedures under federal law that makes the employment
of unauthorized aliens unlawful;
(b) Any
individual hired by the taxpayer before December 31, 2006;
(c) Any
taxpayer where the individual being paid is not directly compensated or
employed by the taxpayer; or
(d)
Wages or remuneration paid for labor services to any individual who holds and
presents to the taxpayer a valid license or identification card issued by the
department of revenue.
(4) The
executive director is authorized to prescribe forms and promulgate rules that
are necessary to administer this section.
Source:
Referred 2006:
Entire section added, L. 2006, 1st Ex. Sess., p. 2, § 3, effective December 31.
Editor's
note: This section
was enacted by House Bill 06S-1020 at the first extraordinary session of the
sixty-fifth general assembly. That bill contained a referendum clause and was
approved by a vote of the registered electors of the state of Colorado on
November 7, 2006. This section was effective upon proclamation of the governor,
December 31, 2006. The vote count for the measure was as follows:
FOR: 744,475
AGAINST: 722,651
ANNOTATION
Law reviews. For
article, "2006 Immigration Legislation in Colorado", see 35 Colo.
Law. 79 (Oct. 2006).
39-22-530. Credit for employers that
hire persons with intellectual and developmental disabilities - definitions.
(Repealed)
Source:
L. 2008: Entire
section added, p. 2203, § 1, effective August 5. L. 2009: (1)(b)
amended, (SB 09-044), ch. 57, p. 210, § 19, effective March 25; (5)(a) amended,
(SB 09-228), ch. 410, p. 2265, § 20, effective July 1. L. 2013: (1)(b)
and (1)(c) amended, (HB 13-1314), ch. 323, p. 1813, § 55, effective March 1,
2014. L. 2023: Entire section repealed, (HB 23-1251), ch. 437, p. 2573,
§ 3, effective August 7.
39-22-531. Colorado job growth
incentive tax credit - definitions - tax preference performance statement -
legislative declaration - rules - repeal.
(1) As
used in this section, unless the context otherwise requires:
(a) (I)
"Affiliated group" means one or more chains of persons connected
through stock or other ownership interests with a person if:
(A) One
or more of the other persons in the chain owns interests possessing more than
fifty percent of the voting power of all classes of ownership interests except
ownership interests of the common parent and more than fifty percent of each
class of nonvoting ownership interests of each of the persons except ownership
interests of the common parent; and
(B) The
common parent owns interests possessing more than fifty percent of the voting
power of all classes of ownership interests and more than fifty percent of each
class of the nonvoting ownership interests of at least one of the other persons
in the chain.
(II) As
used in this paragraph (a), the term "ownership interest" does not
include nonvoting stock that is limited and preferred as to dividends; employer
securities, within the meaning of section 409 (1) of the internal revenue code,
while such securities are held under a tax credit employee stock ownership
plan; or qualifying employer securities, within the meaning of section 4975
(e)(8) of the internal revenue code, while such securities are held under an
employee stock ownership plan that meets the requirements of section 4975
(e)(7) of the internal revenue code.
(III)
As used in this paragraph (a), the term "person" does not include
natural persons.
(b)
"Commission" means the Colorado economic development commission
created in section 24-46-102, C.R.S.
(c)
"Credit certificate" means a statement issued by the commission
certifying that the project qualifies for the job growth incentive tax credit
allowed in this section and specifying the amount of the credit allowed.
(d) (I)
For income tax years commencing before January 1, 2014, "credit
period" means a period not to exceed sixty consecutive months from the
first month of the initial tax year in which a credit allowed pursuant to this
section is first claimed, for which a taxpayer may claim a credit that is
calculated annually by the commission.
(II)
For income tax years commencing on or after January 1, 2014, "credit
period" means a period not to exceed ninety-six consecutive months from
the first month of the initial tax year in which a credit allowed pursuant to
this section is first claimed, for which a taxpayer may claim a credit that is
calculated annually by the commission.
(e)
"Department" means the department of revenue.
(f)
"Net job growth" means the difference between the total number of
full-time equivalent employees employed by the taxpayer in the state for the
project at the end of each calendar year of the project and the total number of
full-time equivalent employees employed by the taxpayer in the state for the
project at the commencement of the project.
(g)
"Person" shall have the same meaning as provided in section 39-21-101
(3).
(h)
"Project" means a project that encourages, promotes, and stimulates
economic development in key economic sectors, including, but not limited to,
aerospace, bioscience, life science, clean energy technology, tourism, film and
television production, and information technology, and that is approved by the
commission as specified in subsection (3) of this section.
(h.3)
"Qualified partnership" means an agreement between the taxpayer and a
state institution of higher education that aligns with or furthers the academic
mission of the state institution of higher education, results in positive
benefits for the community and the local economy, and allows a taxpayer to
utilize the following for a project:
(I) The
tangible intellectual property of the state institution of higher education;
(II)
The body of academic knowledge and expert skills of the state institution of
higher education; or
(III)
Any specialized equipment owned or developed by the state institution of higher
education.
(h.5)
"State institution of higher education" means a state institution of
higher education as defined in section 23-18-102 (10), C.R.S., a local district
college, or an area technical college.
(i)
"Taxpayer" means any person doing business in the state. For purposes
of this section, taxpayer includes an affiliated group.
(1.5) Tax
preference performance statement.
(a) In
accordance with section 39-21-304 (1), which requires each bill that extends an
expiring tax expenditure to include a tax preference performance statement as
part of a statutory legislative declaration, the general assembly finds and
declares that the purpose of the credit provided for in this section is to
create or retain jobs by allowing certain employers to receive a credit against
income tax if certain criteria are met. Specifically, this tax expenditure is
intended to incentivize the creation of new jobs in the state of Colorado.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1.5)(a) of this
section based on the number of new jobs created and the value of the credits
allowed and made available annually to taxpayers.
(2) For
income tax years commencing on or after January 1, 2009, but prior to January
1, 2035, at the discretion of the commission as specified in subsection (3) of
this section, there may be allowed to any taxpayer an annual job growth
incentive tax credit with respect to the income taxes imposed by this article
that a taxpayer may claim for a credit period in an amount determined by the
commission pursuant to subsection (5) of this section.
(3) The
commission may approve any job growth incentive tax credits allowed pursuant to
subsection (2) of this section subject to the following:
(a)
During a credit period a project must:
(I) (A)
For income tax years commencing before January 1, 2014, except as provided in
sub-subparagraph (B) of this subparagraph (I), bring a net job growth of at
least twenty new jobs to the state with an average yearly wage of at least one
hundred ten percent of the average yearly wage of the county in which the
taxpayer is located and, for income tax years commencing on or after January 1,
2014, except as provided in sub-subparagraphs (B) and (C) of this subparagraph
(I), bring a net job growth of at least twenty new jobs to the state with an
average yearly wage of at least one hundred percent of the average yearly wage
of the county in which the taxpayer is located.
(B) For
income tax years commencing before January 1, 2014, if the project will be
located in a designated enhanced rural enterprise zone as such zone is
described in section 39-30-103.2 (1) and the local community of the designated
enhanced rural enterprise zone provides rationale to the commission outlining
the project's economic importance to the community, the project shall, during a
credit period, bring a net job growth of at least five new jobs to the state
with an average yearly wage of at least one hundred ten percent of the average
yearly wage of the enhanced rural enterprise zone in which the taxpayer is
located. For income tax years commencing on or after January 1, 2014, if the
project will be located in a designated enhanced rural enterprise zone as such
zone is described in section 39-30-103.2 (1) and the local community of the
designated enhanced rural enterprise zone provides rationale to the commission
outlining the project's economic importance to the community, the project
shall, during a credit period, bring a net job growth of at least five new jobs
to the state with an average yearly wage of at least one hundred percent of the
average yearly wage of the enhanced rural enterprise zone in which the taxpayer
is located.
(C) For
income tax years commencing on or after January 1, 2015, but prior to January
1, 2018, if the project is a qualified partnership the project must bring a net
job growth of at least five new jobs to the state with an average yearly wage
of at least one hundred percent of the statewide average yearly wage, be
located on or within one mile of the campus of or on other property owned by
the state institution of higher education, and include a description of the
project's alignment with or furtherance of the academic mission of the state
institution of higher education.
(D) For
income tax years commencing on or after January 1, 2024, but prior to January
1, 2029, if the project constitutes advanced manufacturing, as defined in
section 24-46-108 (1)(a), or semiconductor manufacturing, as defined in section
24-46-108 (1)(j), the project must bring a net job growth of at least twenty
jobs to the state with an average yearly wage of seventy-five percent or such
greater amount of the average yearly wage of the county in which the taxpayer
is located, as the commission deems proper under its discretion.
(II)
Result in the retention of any new employees hired for the project for at least
one year; and
(III)
(A) For income tax years commencing before January 1, 2014, be approved by
the commission only if the project would not occur but for the credit allowed
in this section;
(B) For
income tax years commencing on or after January 1, 2014, be approved by the
commission only if the credit allowed in this section is a major factor in the
decision to locate or retain the project in Colorado; except that, if the
project is a qualified partnership, then the limitation in this
sub-subparagraph (B) does not apply.
(b) A
taxpayer shall submit a complete written application for a credit allowed in
this section to the commission before the project commences in the state. The
application must include:
(I) An
identification of the specific jobs that will be created.
(II) An
identification of the cost differential in the projected costs of the project
compared to the projected costs were the project commenced in a competing
state; except that, if the project is a qualified partnership, then the
identification of the cost differential is not required. The cost differential
shall include any impact of the competing state's incentive programs and may
include:
(A)
Specific costs for labor, utilities, taxes, and any other costs of a competing
state's site; and
(B) The
cost structure of the taxpayer's industry in the competing state.
(III)
For income tax years commencing before January 1, 2014, documentation to
demonstrate that without the credit allowed in this section, the project would
not occur in this state. Such documentation shall include information that
indicates that:
(A) The
taxpayer could reasonably and efficiently locate the project outside of this
state;
(B) At
least one other state is being considered for the project;
(C)
Receipt of the credit allowed in this section is a major factor in the
taxpayer's decision; and
(D)
Without the credit allowed in this section, the taxpayer is not likely to
commence the project in the state.
(IV)
For income tax years commencing on or after January 1, 2014, documentation to
demonstrate that the credit allowed in this section is a major factor in the
decision to locate the project in Colorado; except that, if the project is a
qualified partnership, then such documentation is not required. Such
documentation shall include information that indicates that:
(A) The
taxpayer could reasonably and efficiently locate the project outside of this
state;
(B) At
least one other state is being considered for the project;
(C)
Receipt of the credit allowed in this section is a major factor in the
taxpayer's decision; and
(D)
Without the credit allowed in this section, the taxpayer has a reduced
probability of commencing the project in the state.
(c) In
the exercise of the commission's discretion granted by this subsection (3), the
commission shall only consider the following:
(I) The
economic health of this state;
(II)
The economic viability of the proposed new jobs;
(III)
The economic benefits to the state of the new jobs; and
(IV)
The maximum amount of the credit needed to attract the new jobs to this state.
(4) (a)
(I) The commission shall review each application for a credit allowed in
this section submitted by any taxpayer. Based on the application submitted, the
commission may offer conditional approval to a taxpayer for a credit. The
conditional approval shall include the maximum amount of the credit available
to the taxpayer for the credit period calculated pursuant to paragraph (a) of
subsection (5) of this section and the specific terms that shall be met to
qualify for the credit.
(II) A
taxpayer that receives conditional approval for a credit allowed in this
section shall notify the commission promptly if the project is canceled or
otherwise becomes ineligible for the estimated credit, in which case the
conditional approval may be canceled. The conditional approval shall be void
and any credit claimed shall be repaid if a taxpayer that receives conditional
approval does not commence the project within one and a half years of the
receipt of the conditional approval or fails to meet the terms of subsection
(3) of this section.
(b) By
March 1 of the calendar year after the commencement of the project, and each
March 1 of any calendar year following a year of the credit period, a taxpayer
that received conditional approval as specified in paragraph (a) of this
subsection (4) shall submit an annual request for a credit certificate. The
request shall include documents that detail the number of employees hired for
the project, the net job growth for the taxpayer, all documentation necessary
to calculate the credit as specified in subsection (5) of this section, and any
other information requested by the commission.
(c) If
the project has commenced and the project meets or exceeds the conditions of a
project as specified in paragraphs (a) and (b) of subsection (3) of this
section, the commission shall calculate the annual amount of the credit allowed
in this section as specified in paragraph (b) of subsection (5) of this section
and shall issue a credit certificate for that calendar year in that amount to
the taxpayer. The credit certificate shall be submitted by the taxpayer to the
department with the taxpayer's income tax return for the tax year that includes
the December 31 of the calendar year for which the credit certificate is
issued.
(5) The
credit allowed in this section shall be calculated by the commission as
follows:
(a) For
the maximum amount of the credit allowed in this section available to the
taxpayer for the credit period, the commission shall multiply the estimated net
job growth for each of the years in the credit period by fifty percent of the
taxpayer's total estimated taxes imposed on the employer each year for the new
employees of the project under the "Federal Insurance Contributions
Act", 26 U.S.C. sec. 3111 (a) and (b). The maximum amount of the credit
shall be the result of this calculation or such lesser amount as the commission
deems proper under its discretion as specified in paragraph (c) of subsection
(3) of this section.
(b) For
the annual amount of the credit allowed in this section available to the
taxpayer, the commission shall multiply the actual net job growth for that year
by fifty percent of the taxpayer's taxes imposed on the employer for the new
employees of the project under the "Federal Insurance Contributions
Act", 26 U.S.C. sec. 3111 (a) and (b). The amount of the credit allowed in
this section shall be the result of this calculation; except that no credit
certificate shall be issued if the aggregate of all credits claimed or to be
claimed by the taxpayer, including the current credit certificate, exceeds the
maximum amount of the credit as calculated pursuant to paragraph (a) of this
subsection (5).
(6)
Except as provided in sections 24-46-104.3, 24-46-107, and 24-46-108, if the
amount of the credit allowed in this section exceeds the amount of income taxes
otherwise due on the taxpayer's income in the income tax year for which the
credit is being claimed, the amount of the credit not used as an offset against
income taxes in the current income tax year and not used to claim a refund
pursuant to section 24-46-108 may be carried forward and used as a credit
against subsequent years' income tax liability for a period not to exceed ten
years and shall be applied first to the earliest income tax years possible. Any
credit remaining after said period shall not be refunded or credited to the
taxpayer.
(7) The
commission or its designee may audit the accounts of a taxpayer up to twelve
months following the issuance of any credit certificate.
(8) The
commission shall include information regarding all conditional approvals
granted and credit certificates issued pursuant to this section, including the
credits claimed, the names of the recipients of the credits, and the amounts
claimed, in its annual report required to be presented to the general assembly
pursuant to section 24-46-104 (2), C.R.S.
(9) If
a taxpayer receiving a credit allowed in this section is a partnership, limited
liability company, S corporation, or similar pass-through entity, the taxpayer
may allocate the credit among its partners, shareholders, members, or other
constituent taxpayers in any manner agreed to by such partners, shareholders,
members, or other constituent taxpayers. The taxpayer shall certify to the
commission and the department the amount of the credit allocated to each
partner, shareholder, member, or other constituent taxpayer, and the commission
shall issue credit certificates in the appropriate amounts to each partner,
shareholder, member, or other constituent taxpayer. Each partner, shareholder,
member, or other constituent taxpayer shall be allowed to claim such amount
subject to any restrictions set forth in this section.
(10) No
later than September 1, 2010, and no later than September 1 of each year
thereafter through September 1, 2042, the commission shall provide the
department with an electronic report of the taxpayers receiving a credit
allowed in this section for the preceding calendar year or any fiscal year
ending in the preceding calendar year, and any credits disallowed pursuant to
subparagraph (II) of paragraph (a) of subsection (4) of this section for any
year, that includes the following information:
(a) The
taxpayer's name;
(b) The
taxpayer's Colorado account number and federal employer identification number;
(c) The
amount of the credit allowed in this section; and
(d) Any
associated taxpayer's names, Colorado account numbers, and federal employer
identification numbers or social security numbers, if the credit allowed in
this section is allocated from a pass-through entity pursuant to subsection (9)
of this section.
(11)
The executive director of the department may promulgate rules as may be
necessary to administer and enforce any provision of this section. The rules
shall be promulgated in accordance with article 4 of title 24, C.R.S.
(12)
Any taxpayer who offsets a tax deficiency with a credit allowed in this section
that is disallowed pursuant to this section shall be liable for such tax
deficiency, interest, and penalties as may be specified in this article or
otherwise provided by law.
(13)
This section is repealed, effective July 1, 2059.
Source:
L. 2009: Entire
section added, (HB 09-1001), ch. 220, p. 995, § 1, effective August 5. L.
2013: (1)(d), (2), IP(10), and (13) amended, (HB 13-1287), ch. 212, p. 888,
§ 1, effective May 13. L. 2014: (1)(d), (2), (3)(a)(I), (3)(a)(III),
(3)(b)(III), and (13) amended and (3)(b)(IV) added, (HB 14-1014), ch. 216, p.
810, § 1, effective May 16. L. 2015: (1)(h.3), (1)(h.5), and
(3)(a)(I)(C) added and IP(3)(a), (3)(a)(I)(A), (3)(a)(III)(B), IP(3)(b),
IP(3)(b)(II), and IP(3)(b)(IV) amended, (HB 15-1366), ch. 331, p. 1349, § 1,
effective June 5. L. 2016: (1)(h.5) amended, (HB 16-1082), ch. 58, p.
153, § 44, effective August 10. L. 2017: (6) amended, (HB 17-1356), ch.
237, p. 973, § 2, effective May 24. L. 2022: (6) and (13) amended, (HB
22-1418), ch. 427, p. 3023, § 3, effective August 10. L. 2023:
(3)(a)(I)(D) added and (6) amended (HB 23-1260), ch. 227, p. 1197, § 8,
effective May 20. L. 2024: (3)(a)(I)(D) amended, (HB 24-1450), ch. 490,
p. 3425, § 81, effective August 7. L. 2026: (1.5) added and (2), IP(10),
and (13) amended, (HB 26-1014), ch. 206, p. 1173, § 1, effective August 12.
ANNOTATION
Law reviews. For
article, "Applying for the Colorado Job Growth Incentive Tax Credit",
see 39 Colo. Law. 83 (Jan. 2010).
39-22-532. Advanced industry investment
tax credit - definitions.
(1) As
used in this section, unless the context otherwise requires:
(a)
"Advanced industry investment tax credit" or "tax credit"
means the credit against income tax created in this section.
(b)
"Qualified investment" shall have the same meaning as set forth in
section 24-48.5-112 (1)(e), C.R.S.
(c)
"Qualified investor" shall have the same meaning as set forth in
section 24-48.5-112 (1)(f), C.R.S.
(d)
"Qualified small business" shall have the same meaning as set forth
in section 24-48.5-112 (1)(g), C.R.S.
(e)
"Tax credit certificate" means a tax credit certificate issued to a
qualified investor pursuant to section 24-48.5-112 (3), C.R.S.
(2)
There shall be allowed an advanced industry investment tax credit against the
income taxes imposed pursuant to this article for a qualified investment in a
qualified small business. The amount of the credit is the amount determined and
authorized by the Colorado office of economic development pursuant to section
24-48.5-112, C.R.S., and set forth in a tax credit certificate.
(3) To
claim the advanced industry investment tax credit, the taxpayer shall attach to
the taxpayer's tax return a copy of the tax credit certificate. No tax credit
is allowed under this section unless the taxpayer provides the copy of the tax
credit certificate.
(4) If
the allowable advanced industry investment tax credit exceeds the amount of
income tax due on the income of the taxpayer for the tax year during which the
qualified investment was made, the amount of the tax credit not used as an
offset against income taxes in such income tax year is not allowed as a refund.
The taxpayer may carry forward and apply the unused credit against the income
tax due in each of the five succeeding income tax years, but the taxpayer shall
apply the credit against the income tax due for the earliest of the income tax
years possible. Any amount of the tax credit that is not used after this period
is not refundable.
(5)
Repealed.
(6) If
the department of revenue determines that there has been a misrepresentation on
an application submitted to the Colorado office of economic development
pursuant to section 24-48.5-112, C.R.S., the department of revenue shall deny
the advanced industry investment tax credit if the misrepresentation relates to
whether the applicant was a qualified investor or made a qualified investment.
If the misrepresentation relates to whether the investment was made to a
qualified small business, the department of revenue shall deny the tax credit
only if the applicant knew or should have known at any time before the
certification that the representation was false.
(7) If
a qualified investor receiving a credit allowed in this section is a
partnership or S corporation, the qualified investor may allocate the credit
among its partners or shareholders in any manner agreed to by such partners or
shareholders. If the qualified investor receiving the credit allowed by this
section is a trust, the qualified investor may allocate the credit between the
trust and its beneficiaries in any manner determined by the trust. The
qualified investor shall certify to the Colorado office of economic development
the amount of the credit allocated to each partner, shareholder, or beneficiary
and the office shall issue credit certificates in the appropriate amounts to
each partner, shareholder, or beneficiary. Each partner, shareholder, or
beneficiary shall be allowed to claim such amount subject to any restrictions
set forth in this section and section 24-48.5-112.
Source:
L. 2009: Entire
section added, (HB 09-1105), ch. 378, p. 2059, § 4, effective September 1. L.
2011: (4) amended, (HB 11-1045), ch. 209, p. 907, § 3, effective May 23. L.
2014: (1)(a), (2) to (4), and (6) amended, (HB 14-1012), ch. 274, p. 1102,
§ 3, effective May 29. L. 2022: (5) repealed and (7) added, (HB
22-1149), ch. 358, p. 2571, § 2, effective August 10. L. 2025: (7)
amended, (HB 25-1157), ch. 213, p. 966, § 2, effective August 6.
Cross
references: (1)
For the legislative declaration in the 2011 act amending subsection (4), see
section 1 of chapter 209, Session Laws of Colorado 2011.
(2) For the legislative
declaration in HB 14-1012, see section 1 of chapter 274, Session Laws of
Colorado 2014.
39-22-533. Instream flow incentive tax
credit for water rights holders - rules - definitions - repeal. (Repealed)
Source:
L. 2009: Entire
section added and (6) amended, (HB 09-1067), ch. 426, pp. 2377, 2380, §§ 1, 2,
effective August 5.
Editor's
note: Subsection
(9) provided for the repeal of this section, effective December 31, 2024. (See
L. 2009, pp. 2377, 2380.)
39-22-534. Credit for estate taxes paid
- agricultural land - recapture - definitions. (Repealed)
Source:
L. 2012: Entire
section added, (HB 12-1042), ch. 193, p. 771, § 2, effective August 8. L.
2018: (4)(b) amended, (HB 18-1375), ch. 274, p. 1722, § 81, effective May
29. L. 2020: Entire section repealed, (HB 20-1176), ch. 89, p. 358, § 2,
effective September 14.
39-22-535. Credit for purchase of
uniquely valuable motor vehicle registration numbers - repeal.
(1) For
tax years commencing on or after January 1, 2013, and prior to January 1, 2025,
a person who buys the right to use a registration number under section 8-88-206
is allowed a credit against the income taxes imposed by this article 22 for
twenty percent of the purchase price of the right to use the registration
number that is paid to the Colorado disability funding committee created in
section 8-88-202.
(2) If
the credit allowed by this section exceeds the tax otherwise due, the taxpayer
may carry it forward for up to five years but shall claim it on the earliest
possible subsequent tax return.
(3)
This section is repealed, effective December 31, 2034.
Source:
L. 2013: Entire
section added, (SB 13-170), ch. 254, p. 1347, § 4, effective May 23. L.
2019: (1) amended, (SB 19-241), ch. 390, p. 3477, § 56, effective August 2.
L. 2022: (1) amended, (SB 22-217), ch. 378, p. 2683, § 7, effective
August 10. L. 2024: (1) amended, (HB 24-1360), ch. 324, p. 2167, § 10,
effective July 1; (1) amended and (3) added, (HB 24-1036), ch. 373, p. 2528, §
14, effective August 7.
Editor's
note: Amendments
to subsection (1) by HB 24-1036 and HB 24-1360 were harmonized.
Cross
references: For
the legislative declaration in HB 24-1360, see section 1 of chapter 324,
Session Laws of Colorado 2024. For the legislative declaration in HB 24-1036,
see section 1 of chapter 373, Session Laws of Colorado 2024.
39-22-536. Credit for food contributed
to hunger-relief charitable organizations - definitions - repeal. (Repealed)
Source:
L. 2014: Entire
section added, (HB 14-1119), ch. 286, p. 1173, § 2, effective May 30.
Editor's
note: Subsection
(5) provided for the repeal of this section, effective January 1, 2025. (See L.
2014, p. 1173.)
39-22-537. Credit for personal property
taxes paid - legislative declaration - definitions - repeal. (Repealed)
Source:
L. 2014: Entire
section added, (HB 14-1279), ch. 340, p. 1513, § 1, effective August 6. L.
2017: IP(3)(a) and (6) amended, (SB 17-267), ch. 267, p. 1468, § 25,
effective May 30. L. 2018: (2)(b) amended, (HB 18-1375), ch. 274, p.
1722, § 82, effective May 29.
Editor's
note: Subsection
(6) provided for the repeal of this section, effective July 1, 2021. (See L.
2017, p. 1468.)
39-22-537.5. Credit for personal property
taxes paid - legislative declaration - definitions - repeal.
(1) The
general assembly declares that the purpose of the tax expenditure in this
section is to minimize the negative impact of the business personal property
tax on businesses.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Property tax" means the ad valorem tax imposed pursuant to section 3
of article X of the state constitution but does not include public utilities
assessed pursuant to section 39-4-102, and does not include the graduated
annual specific ownership tax imposed pursuant to section 6 of article X of the
state constitution.
(b)
"Taxpayer" includes an organization exempt from federal taxation
pursuant to section 501 (c) of the internal revenue code.
(3) (a)
For income tax years commencing on or after January 1, 2019, but before January
1, 2026, a taxpayer is allowed a credit against the tax imposed by this article
22 equal to the property tax paid in Colorado during the income tax year on up
to eighteen thousand dollars of the total actual value of the taxpayer's
personal property.
(b) A
taxpayer may not claim a tax credit under this section for the payment of
delinquent property taxes that were owed for a prior property tax year.
(c) The
amount of the credit under this section that exceeds the taxpayer's income
taxes due is refunded to the taxpayer.
(4) To
claim a credit under this section, a taxpayer must submit to the department of
revenue a copy of a property tax statement described in section 39-10-103 for
all of the taxpayer's personal property for the property tax year for which the
credit is claimed.
(5)
This section is repealed, effective December 31, 2036.
Source:
L. 2017: Entire
section added, (SB 17-267), ch. 267, p. 1469, § 26, effective May 30. L.
2025: (3)(a) amended and (5) added, (HB 25-1296), ch. 202, p. 914, § 10,
effective May 16.
Cross
references: For
the legislative declaration in SB 17-267, see section 1 of chapter 267, Session
Laws of Colorado 2017. For the legislative declaration in HB 25-1296, see
section 1 of chapter 202, Session Laws of Colorado 2025.
39-22-538. Credit for health-care
preceptors working in health professional shortage areas - legislative
declaration - definitions.
(1) (a)
The general assembly finds, determines, and declares that:
(I) to
(III) (Deleted by amendment, L. 2022.)
(IV)
The COVID-19 pandemic and subsequent economic crisis have caused significant
challenges for Colorado's health-care system and exacerbated the workforce
shortage across multiple disciplines and sectors of the health-care industry;
(V)
While the pandemic has had lasting impacts on the entire health-care system
across the state, rural Colorado is experiencing the most severe workforce
turnover and shortages, and as a result these communities experience reduced
access to primary care services and exhibit poorer health outcomes;
(VI)
Rural communities often face challenges in recruiting an adequate health
workforce, making it difficult to provide needed patient care or to meet
staffing requirements for their facilities. Therefore, rural health-care
facilities should be proactive and strategic about recruiting and retaining
primary care personnel, which includes professionals in physical, dental,
behavioral, and mental health.
(VII)
Most of Colorado's forty-seven rural and frontier counties are also designated
as primary care health professional shortage areas by the Colorado primary care
office;
(VIII)
Preceptorship programs are a critical component of clinical training and a
proven approach to developing one-on-one relationships between expert
professionals and students needing to develop the clinical skills and practical
experience of working with patients in rural settings;
(IX)
Health professional students who obtain a significant amount of their clinical
training in rural communities and under the guidance of rural health-care
providers are much more likely to live and work in a rural or frontier area
after completing their health professional training;
(X)
Recent studies and surveys by the American academy of family physicians have
shown that primary care physicians are more likely to engage in preceptorships
when professional recognition and financial incentives are provided; and
(XI)
The general assembly therefore finds that maintaining a highly qualified and
sustainable rural health-care workforce depends on the extension and expansion
of the rural and frontier health-care preceptor tax credit to provide
sufficient financial incentives to preceptors statewide.
(b) and
(c) (Deleted by amendment, L. 2022.)
(d) In
accordance with section 39-21-304 (1), which requires each bill that extends an
expiring tax expenditure to include a tax preference performance statement as
part of a statutory legislative declaration, the general assembly hereby finds
and declares that:
(I) The
general legislative purposes of the tax credit allowed by this section are:
(A) To
induce certain designated behavior by taxpayers, specifically the offering of
professional instruction, training, and supervision to students seeking careers
as primary health-care providers in rural areas and frontier areas of the
state; and
(B) To
provide tax relief to preceptors in rural and frontier areas of the state who
offer the professional instruction, training, and supervision described in
subsection (1)(d)(I)(A) of this section; and
(II)
The specific legislative purpose of the tax credit allowed by this section is
to encourage preceptors to offer professional instruction, training, and
supervision to students matriculating at Colorado institutions of higher
education who are seeking careers as primary health-care providers in rural and
frontier areas of the state. In order to allow the general assembly and the
state auditor to measure the effectiveness of the credit, the department of
revenue, when administering the credit, shall require each taxpayer who claims
the credit to submit a certification form with each income tax return form in
accordance with subsection (4) of this section. The certification form must
verify that the taxpayer has satisfied the requirements for allowance of the
tax credit as specified in this section and state the number of eligible health
professional students that the taxpayer has instructed, trained, or supervised
during the applicable income tax year.
(2) As
used in this section, unless the context otherwise requires:
(a)
"AHEC" or "AHEC program" means the area health education
center.
(b)
"Frontier area" means a county in the state that has a population
density of six or fewer individuals per one square mile.
(c)
Repealed.
(c.5)
"Health professional student" means an individual matriculating at
any accredited Colorado institution of higher education seeking a degree or
certification in a primary health-care field.
(d)
"Preceptor" means a medical doctor, doctor of osteopathic medicine,
advanced practice nurse, physician assistant, doctor of dental surgery, doctor
of dental medicine, registered nurse, registered dental hygienist, pharmacist,
licensed clinical or counseling psychologist, licensed clinical social worker,
licensed professional counselor, licensed marriage and family therapist,
psychiatric nurse specialist, licensed addiction counselor, or certified
addiction counselor working in an outpatient clinical setting who has been
licensed in his or her primary health-care field in the state by the applicable
licensing authority.
(e)
"Preceptorship" means an uncompensated mentoring experience in which
a preceptor provides a program of personalized instruction, training, and
supervision for a total of not less than four consecutive or nonconsecutive
working weeks or twenty consecutive or nonconsecutive business days per
calendar year that is offered to eligible health professional students to
enable the students to obtain eligible professional degrees or certifications.
(f)
"Primary health-care" means the provision of integrated, equitable,
and accessible health-care services provided by clinicians who are accountable
for addressing a large majority of personal health-care needs, developing a
sustained partnership with patients, and practicing in the context of family
and community. Integrated health-care encompasses the provision of
comprehensive, coordinated, and continuous services that provide a seamless
process of care.
(g)
"Rural area" means an area listed as eligible for rural health
funding by the federal office of rural health policy.
(h)
"Taxpayer" means a preceptor who files an income tax return under
this article.
(3) (a)
(I) For income tax years commencing on or after January 1, 2017, but prior
to January 1, 2025, and subject to the requirements of subsection (3)(b)(I)(A)
of this section, a taxpayer is allowed a credit against the income taxes
imposed by this article 22 in an amount equal to one thousand dollars for a
preceptorship provided by the taxpayer during the applicable income tax year
for which the credit is claimed.
(II)
For income tax years commencing on or after January 1, 2025, but prior to
January 1, 2033, and subject to the requirements of subsection (3)(b)(I)(B) of
this section, a taxpayer is allowed a credit against the income taxes imposed
by this article 22 in an amount equal to two thousand dollars for each
preceptorship provided by the taxpayer during the applicable income tax year
for which the credit is claimed. A credit is allowed for a maximum of three
preceptorships per applicable income tax year. The maximum total credit in a
taxable year is six thousand dollars.
(b)
Notwithstanding any other provision of this section:
(I) (A)
For income tax years commencing before January 1, 2025, the aggregate amount of
the credit awarded to any one taxpayer under this section shall not exceed one
thousand dollars for any one income tax year regardless of the number of
preceptorships undertaken by the taxpayer during the applicable income tax year
or the number of eligible health professional students the taxpayer instructs,
trains, or supervises during the applicable income tax year.
(B) For
income tax years commencing on or after January 1, 2025, but prior to January
1, 2033, the aggregate amount of the credit awarded to any one taxpayer under
this section shall not exceed six thousand dollars for any one income tax year
regardless of the number of preceptorships undertaken by the taxpayer during
the applicable income tax year or the number of eligible health professional
students the taxpayer instructs, trains, or supervises during the applicable
income tax year.
(II) A
taxpayer is eligible to claim the credit allowed by this section if the
taxpayer performs a preceptorship that lasts a total of not less than four
consecutive or nonconsecutive working weeks or twenty consecutive or
nonconsecutive business days during the income tax year in which the credit is
claimed and the preceptor is practicing in the preceptor's primary health-care
field in a rural or frontier area; and
(III)
Not more than three hundred preceptors are entitled to claim the credit
authorized by this section for any one income tax year. The department shall
promulgate by rule, in accordance with article 4 of title 24, a method for
determining the manner in which taxpayers who have obtained certification under
subsection (4) of this section are able to claim the tax credit.
(4) To
qualify for the credit provided by this section, the taxpayer shall submit a
certification form with each income tax return. Certification may be provided
by either the institution for which the taxpayer teaches, whether it is an
institution of higher education or a hospital, clinic, or other medical
facility, or by the particular regional office of the AHEC program with
jurisdiction over the area in which the preceptor's medical practice is
located. In the case of certification by an institution for which the taxpayer
teaches, the institution must execute the form certifying that the taxpayer has
satisfied the requirements for allowance of the tax credit as specified in this
section and identifying the number of eligible health professional students
that the taxpayer has instructed, trained, or supervised during the applicable
income tax year through all preceptorships provided by the taxpayer. In the
case of certification by the AHEC program, the certification form must be
obtained from the particular regional office of the AHEC program with
jurisdiction over the area in which the preceptor is practicing, which office
shall certify that the taxpayer has satisfied the requirements for allowance of
the tax credit as specified in this section and identify the number of eligible
health professional students the taxpayer has instructed, trained, or
supervised during the applicable income tax year through all preceptorships
provided by the taxpayer. The AHEC program may charge the taxpayer a reasonable
fee for providing such certification, which fee shall not exceed the actual
costs incurred by the AHEC in completing the certification.
(5)
Where a taxpayer claims the credit provided by this section but fails to
satisfy the requirements of this section during the income tax year for which
the credit is claimed, the taxpayer shall repay the entire amount of the total
credit that is attributed to him or her pursuant to this section. The taxpayer
shall report the recapture required by this subsection (5) by increasing his or
her income tax liability by the amount of the total credit claimed for the year
in which the recapture occurs.
(6) If
the amount of the credit allowed pursuant to this section exceeds the amount of
the income tax otherwise due on the taxpayer's income in the income tax year
for which the credit is being claimed, the amount of the credit not used as an
offset against income taxes in the income tax year is not allowed as a refund
but may be carried forward and applied against the income tax due in each of
the five succeeding income tax years, but must first be applied against the
income tax due for the earliest of the income tax years possible.
(7)
Nothing in this section modifies or changes the definition of "public
employee" specified in section 24-10-103 (4)(b)(II) and (4)(b)(V), C.R.S.
(8)
Repealed.
Source:
L. 2016: Entire
section added, (HB 16-1142), ch. 229, p. 891, § 1, effective August 10. L.
2017: (2)(e) amended, (SB 17-294), ch. 264, p. 1418, § 119, effective May
25. L. 2019: (2)(e), (3)(a), and (3)(b)(II) amended and (8) repealed,
(HB 19-1088), ch. 363, p. 3355, § 1, effective August 2. L. 2022: (1),
(2)(d), (2)(e), (2)(f), (2)(g), (3), and (4) amended, (2)(c) repealed, and
(2)(c.5) added, (HB 22-1005), ch. 299, p. 2137, § 1, effective August 10. L.
2024: (3)(a) and (3)(b)(I) amended, (HB 24-1036), ch. 373, p. 2534, § 31,
effective August 7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-22-539. Credit for employer
contributions to employee 529 qualified state tuition programs - legislative
declaration - definitions - repeal.
(1) The
general assembly hereby finds and declares that the qualified state tuition
savings program administered by collegeinvest helps empower families to save
for higher education and enables residents to further educational opportunities
and pursue professional goals. The purpose of this section is to provide an
incentive for employers to help their employees enhance education savings goals
by contributing directly to the employees' qualified state tuition program
accounts administered by collegeinvest.
(2) As
used in this section:
(a)
"529 qualified state tuition program account" means a qualified state
tuition program account established by collegeinvest created in section
23-3.1-203.
(b)
"Employee" means any person in the employment of an employer for a
salary or for hourly wages, whether full-time or part-time and whether
temporary or permanent.
(c)
"Employer" means any person doing business in the state.
(3) For
income tax years commencing on or after January 1, 2019, but prior to January
1, 2032, if an employer makes a contribution of money to a 529 qualified state
tuition program account owned by an employee during the income tax year,
without regard to the named beneficiary of the account, then the employer is
allowed a credit against the income taxes imposed by this article 22 in an
amount equal to twenty percent of the contribution. The maximum total credit an
employer may claim under this section for each employee in a taxable year is
five hundred dollars.
(4) If
the amount of the credit allowed in this section exceeds the amount of income
taxes otherwise due on the employer's income in the income tax year for which
the credit is being claimed, the amount of the credit not used as an offset
against income taxes in the current income tax year may be carried forward and
used as a credit against subsequent years' income tax liability for a period
not to exceed three years and must be applied first to the earliest income tax
years possible. Any credit remaining after the period may not be refunded or
credited to the employer.
(5) No
later than January 1, 2019, and quarterly thereafter, collegeinvest shall
provide the department with an electronic report containing information for 529
qualified state tuition program account holders, beneficiaries, and donors that
the department determines is necessary for the administration of the credit
allowed in this section. The report must include, but is not limited to:
(a) The
name and social security number of the account holder of each 529 qualified
state tuition program account;
(b) The
name, date of birth, and social security number of the beneficiary of each 529
qualified state tuition program account; and
(c)
Contribution data that contains the:
(I)
Amount of each contribution;
(II)
Date of each contribution; and
(III)
Source of each contribution, including the social security number or federal
employee identification number of the contributor.
(6) The
department of revenue may seek, accept, and expend gifts, grants, or donations
from private or public sources for the department's costs in administering the
income tax credit allowed in this section. The department may expend money
received through gifts, grants, or donations consistent with any terms and
conditions imposed as a condition of receiving such money for administering the
income tax credit allowed in this section within existing appropriations;
except that, notwithstanding part 13 of article 75 of title 24, the general
assembly may appropriate state funds to the department in the future to
administer the income tax credit allowed in this section.
(7)
This section is repealed, effective December 31, 2036.
Source:
L. 2018: Entire
section added, (HB 18-1217), ch. 287, p. 1777, § 2, effective August 8. L.
2020: (3) and (7) amended, (HB 20-1109), ch. 182, p. 837, § 2, effective
September 14.
Cross
references: (1)
For the short title ("Working Families College Savings Act") in HB
18-1217, see section 1 of chapter 287, Session Laws of Colorado 2018.
(2) For the legislative
declaration in HB 20-1109, see section 1 of chapter 182, Session Laws of
Colorado 2020.
39-22-540. Credit - organ donor - leave
of absence period - legislative declaration - definitions.
(1) (a)
The general assembly hereby finds and declares that:
(I)
Nearly two thousand four hundred Coloradans are currently on the waiting list
for lifesaving organ transplants, and ninety-six percent of those people could
receive an organ, such as a kidney or liver, from a living donor;
(II)
Last year, two hundred fifty-eight Coloradans died or became too sick to remain
on the waiting list, which is thirty-eight percent more than all the homicides
in the state;
(III)
These lives would be saved if more people became living donors;
(IV) If
just one out of one thousand one hundred adults in the state became living
donors, the waiting list for kidney and liver transplants in the state would be
eradicated; and
(V) The
ability to get paid time off work is an enormous barrier for living organ
donors, and the loss of income and fear of losing their job has deterred many
would-be donors.
(b)
Now, therefore, the general assembly declares that the intended purpose of the
tax credit in this section is to support living donors and the companies that
employ them.
(2) As
used in this section:
(a)
"Employee" has the same meaning as set forth in section 39-22-604
(2)(a).
(b)
"Leave of absence period" means the period, not exceeding ten working
days or the hourly equivalent of ten working days per employee, during which a
taxpayer provides a paid leave of absence to an employee for the purpose of
organ donation. The term does not include a period during which an employee
utilizes any annual leave or sick days that the employee has been given by the
employer.
(c)
"Taxpayer" means an employer that deducts and withholds amounts from
the wages paid to a qualified employee pursuant to section 39-22-604 (3).
(d)
"Wages" has the same meaning as set forth in section 3401 (a) of the
internal revenue code.
(3)
Except as set forth in subsection (4) of this section, for any income tax year
commencing on or after January 1, 2020, but before January 1, 2025, a taxpayer
is allowed a credit against the tax imposed by this article 22 that is an
amount equal to thirty-five percent of the taxpayer's expenses incurred:
(a)
Paying an employee during his or her leave of absence period; and
(b) For
the cost of temporary replacement help, if any, during an employee's leave of
absence period.
(4) A
taxpayer shall not claim a tax credit under this section related to a leave of
absence period for an employee who the taxpayer pays wages of eighty thousand
dollars or more during the income tax year.
(5) If
the amount of a credit under this section exceeds a taxpayer's actual tax
liability for an income tax year, the amount of the credit not used to offset
income tax liability for the income tax year is not refunded to the taxpayer.
The taxpayer may carry forward and apply the unused credit against the income
tax due in each of the five succeeding income tax years, but the taxpayer shall
apply the credit against the income tax due for the earliest of the income tax
years possible. Any amount of the tax credit that is not used after this period
is not refundable.
(6)
Upon request of the department of revenue as part of an audit, a taxpayer must
provide the department with documentation from the employee's medical provider,
which the taxpayer received from the employee, that verifies the employee's
organ donation. If the taxpayer cannot provide the documentation, then the
taxpayer is ineligible for the credit under this section.
Source:
L. 2018: Entire
section added, (HB 18-1202), ch. 310, p. 1869, § 2, effective August 8.
Cross
references: For
the short title ("Living Organ Donor Support Act") in HB 18-1202, see
section 1 of chapter 310, Session Laws of Colorado 2018.
39-22-541. Credit for retrofitting a
residence to increase a residence's visitability - tax preference performance
statement - legislative declaration - definitions - repeal.
(1) In
accordance with section 39-21-304 (1), which requires any bill that creates a
new tax expenditure or extends an expiring tax expenditure to include a tax
preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that:
(a) The
general legislative purpose of the tax credit allowed by this section is to
provide tax relief for certain individuals;
(b) The
specific legislative purpose of the tax credit allowed by this section is to
make retrofitting a residence for health, welfare, and safety reasons more
affordable; and
(c) The
credit certificates required from the division of housing pursuant to
subsection (3)(b)(I) of this section will allow the general assembly and the
state auditor to measure the effectiveness of the credit in achieving its
purpose based on the number and amount of credits that are claimed.
(2) As
used in this section:
(a)
"Dependent" means:
(I) A
qualifying child or qualifying relative as defined in sections 152 (c) and 152
(d), respectively, of the internal revenue code; and
(II) A
qualified individual's spouse or the person in a civil union with the qualified
individual.
(b)
"Division of housing" means the division of housing in the department
of local affairs created in section 24-32-704.
(c)
"Qualified individual" means an individual with a family income at or
below one hundred fifty thousand dollars for the income tax year commencing on
or after January 1, 2019, and as adjusted for inflation for each income tax
year thereafter.
(d)
"Retrofit" means changes made to a residence that must:
(I) Be
necessary to ensure the health, welfare, and safety of a qualified individual
or a dependent;
(II)
Increase the residence's visitability;
(III)
Enable greater accessibility and independence in the residence for a qualified
individual or a dependent;
(IV) Be
required due to a qualified individual's or dependent's illness, impairment, or
disability; and
(V)
Allow a qualified individual or dependent to age in place.
(e)
"Visitability" means a measure of a residence's ease of access for
persons with disabilities.
(3) (a)
(I) Except as provided in subsection (3)(b)(III) of this section, for income
tax years commencing on or after January 1, 2019, but prior to January 1, 2029,
a qualified individual who retrofits or hires someone to retrofit the qualified
individual's residence and who meets any additional requirements established by
the division of housing is allowed a credit against the income taxes imposed by
this article 22 in an amount equal to the cost of the retrofit or five thousand
dollars per residence, whichever is less. Only one credit is allowed per
residence; except that, if a retrofit is required for the qualified individual
and for one or more dependents residing in the qualified individual's residence
or a retrofit is required for more than one dependent residing in the qualified
individual's residence, then a credit is allowed in an amount equal to the cost
of the retrofit or five thousand dollars per individual for whom the retrofit
is required, whichever is less.
(II)
The division of housing shall consult with stakeholders in establishing any
additional requirements for the income tax credit as required in subsection
(3)(a)(I) of this section.
(b) (I)
The division of housing is responsible for issuing credit certificates to
qualified individuals. The credit certificate must identify the taxpayer and
certify that the individual meets the requirements set forth in this section.
(II) To
claim the credit under this section, the qualified individual must include the
credit certificate with the income tax return filed with the department of
revenue.
(III)
The division of housing shall track all the credit certificates issued under
this section in each income tax year and, when the total amount of credit
certificates issued equals one million dollars per income tax year, shall cease
issuing credit certificates in that income tax year. Until the one million
dollar per income tax year cap is reached, the credit certificates shall be
issued in the order in which they are requested.
(4) If
the amount of the credit allowed in this section exceeds the amount of income
taxes otherwise due on the qualified individual's income in the income tax year
for which the credit is being claimed, the amount of the credit not used as an
offset against income taxes in the current income tax year may be carried
forward and used as a credit against subsequent years' income tax liability for
a period not to exceed eight years and must be applied first to the earliest
income tax years possible. Any credit remaining after the period may not be
refunded or credited to the qualified individual.
(5) No
later than January 1, 2020, and no later than January 1 of each year thereafter
through January 1, 2029, the division of housing shall provide the department
of revenue with an electronic report of the taxpayers receiving a credit
certificate as allowed in this section for the previous calendar year that
includes the following information:
(a)
Each taxpayer's name;
(b)
Each taxpayer's social security number or federal employee identification
number; and
(c) The
amount of the credit allocated.
(6)
This section is repealed, effective December 31, 2041.
Source:
L. 2018: Entire
section added, (HB 18-1267), ch. 345, p. 2061, § 1, effective August 8. L.
2019: (2)(a), (2)(d), (3)(a)(I), (3)(b)(II), and (4) amended, (HB 19-1135),
ch. 107, p. 381, § 1, effective August 2. L. 2023: (1), (3)(a)(I), (4),
IP(5), and (6) amended, (SB 23-196), ch. 280, p. 1657, § 1, effective August 7.
39-22-542. Employee ownership tax
credit - definitions - legislative declaration - repeal.
(1) Legislative
declaration.
(a) The
general assembly hereby finds and declares that:
(I) The
purpose of this section is to provide an incentive for businesses to establish
employee stock ownership plans or employee ownership trusts or to convert to a
worker-owned cooperative, and to provide an incentive to entities that support
businesses in such establishment or conversion;
(II) An
employee stock ownership plan allows companies to share ownership with
employees without requiring employees to invest their own money;
(III)
This section encourages business owners to sell their businesses to the very
employees that contributed to their success; and
(IV)
This section will help to ensure that local businesses are not sold to
out-of-state buyers, which is often detrimental to the fabric of local
communities.
(b) It
is the general assembly's intent that the Colorado office of economic
development provide relevant and ascertainable metrics and collect any
necessary data to allow the state auditor to measure the effectiveness of the
tax credit in this section in achieving the purpose set forth in subsection
(1)(a) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a) (I)
"Alternate equity structure" means a mechanism under which an
employer grants to employees a form of employee ownership, including but not
limited to an employee stock purchase plan, LLC membership, phantom stock,
profit interest, restricted stock, stock appreciation right, stock option, or
synthetic equity. An alternate equity structure must at a minimum:
(A)
Grant rights to or be offered to at least twenty percent of an employer's
eligible workers, or grant rights to or be offered to at least twenty percent
of eligible workers of an employer that is owned by or operated for the benefit
of eligible workers in a broad-based employee ownership transition. For
purposes of this subsection (2)(a)(I), "eligible workers" means all
full-time employees, regular employees, non-seasonal employees, non-managerial
employees, and contract labor.
(B)
Have the participation of at least twenty percent of an employer's eligible
workers;
(C)
Allocate at least twenty percent of the fully diluted securities or rights to a
synthetic interest in securities to participating eligible workers, or allocate
twenty percent of net profit from operations to participating eligible workers;
and
(D)
Grant to participating eligible workers informational rights, decision-making
rights, and non-financial rights that are equal to or greater than the rights
that are granted to holders of the employer's common stock or holders of the
employer's residual membership interest.
(II)
The office shall develop guidelines that clarify the types of employee
ownership grants that qualify as an alternate equity structure. The office may
develop guidelines that adjust the percentages set forth in subsection
(2)(a)(I) of this section; except that the percentages shall not be adjusted to
an amount less than twenty percent. The office may periodically update any
guidelines issued pursuant to this subsection (2)(a)(II).
(b)
"Colorado office of economic development" or "office" means
the Colorado office of economic development created in section 24-48.5-101.
(c)
"Conversion costs" means professional services, including accounting,
legal, and business advisory services, as detailed in the guidelines issued by
the office, for the transition of a business to employee ownership trust, an
employee stock ownership plan, or a worker-owned cooperative. "Conversion
costs" include costs to audit the cost certification as required in
subsection (7)(b) of this section.
(c.5)
"Corporate headquarters" means the sole location within a regional or
national area where the majority of the taxpayer's or qualified support
entity's staff members or employees are domiciled and employed and where the
majority of the taxpayer's or qualified support entity's financial, personnel,
legal, planning, or other business functions are conducted on a regional or
national basis.
(d)
"Department" means the Colorado department of revenue.
(e)
"Employee ownership trust" means an indirect form of employee
ownership in which a trust holds at least twenty percent of the fully diluted
securities in a qualified business and benefits all employees on an equal
basis.
(f)
"Employee stock ownership plan" has the same meaning as set forth in
section 4975 (e)(7) of the internal revenue code, as amended.
(g)
"Expansion costs" means professional services, including accounting,
legal, and business advisory services, as detailed in the guidelines issued by
the office, for the expansion of a qualified employee-owned business's employee
ownership trust, employee stock ownership plan, worker-owned cooperative, or
alternate equity structure. Expansion costs include costs to audit the cost
certification as required in subsection (7)(b) of this section.
(h)
"Owner" means the owner of a qualified business before a conversion
occurs.
(i)
"Qualified business" means a taxpayer subject to tax under this
article 22, including but not limited to a C corporation, S corporation,
limited liability company, partnership, limited liability partnership, a sole
proprietorship, or other similar pass-through entity, that is not owned in
whole or in part by an employee ownership trust, that does not have an employee
stock ownership plan, that is not, in whole or in part, a worker-owned
cooperative, or does not have an alternate equity structure, and that is
approved by the office for the tax incentives in this section.
(j)
"Qualified employee-owned business" means a taxpayer that is subject
to tax under this article 22, including but not limited to a C corporation, S
corporation, limited liability company, partnership, limited liability
partnership, sole proprietorship, or other similar pass-through entity, that:
(I)
Repealed.
(II)
Has its corporate headquarters located in this state;
(III)
(A) Is owned in whole or in part by an employee ownership trust;
(B) Has
an employee stock ownership plan;
(C) Is
in whole or in part a worker-owned cooperative; or
(D) Has
an alternate equity structure; and
(IV) Is
approved by the office for the tax incentives in this section.
(j.5)
"Qualified support entity" means an organization exempt from taxation
under section 501 (c)(3) of the internal revenue code or a taxpayer subject to
tax under this article 22, including a C corporation, S corporation, limited
liability company, partnership, limited liability partnership, sole
proprietorship, or other similar pass-through entity that:
(I) Has
been in existence for not less than twelve months prior to January 1 of the
income tax year for which the qualified support entity claims the credit;
(II)
Either has provided services that have supported at least one successful
conversion to or expansion of a qualified employee-owned business in the income
tax year or has provided services that have supported at least three either
qualified businesses that have the intent of converting to qualified
employee-owned businesses or qualified employee-owned businesses that have the
intent of expanding;
(III)
Has its corporate headquarters located in this state; and
(IV) Is
approved by the office for the tax incentives in this section.
(k)
"Securities" has the same meaning as the term "security"
set forth in 15 U.S.C. sec. 77b (a)(1).
(k.5)
(I) "Support costs" means, subject to guidelines developed by the
office pursuant to subsection (5)(a) of this section, costs that are or are
related to:
(A)
Staff salaries and benefits for staff involved in business development,
marketing, and outreach;
(B)
Marketing and outreach for producing educational materials or hosting workshops
or conferences on converting a business to employee-ownership and similar
costs; and
(C) A
proportional amount of basic organizational overhead costs including general or
administrative costs, expenses, rent, and facilities costs.
(II)
"Support costs" does not include any costs that are conversion or
expansion costs.
(l)
"Worker-owned cooperative" has the same meaning as set forth in
section 1042 (c)(2) of the internal revenue code, as amended.
(3) (a)
Except as otherwise provided in subsection (3)(a.3) of this section and subject
to certification by the office pursuant to this section, for income tax years
commencing on or after January 1, 2022, but before January 1, 2032, a qualified
business is allowed a credit with respect to the income taxes imposed pursuant
to this article 22 as follows:
(I) Up
to fifty percent of the conversion costs, not to exceed forty thousand dollars,
incurred by a qualified business for converting the qualified business to a
worker-owned cooperative or an employee ownership trust;
(II) Up
to fifty percent of the conversion costs, not to exceed one hundred fifty
thousand dollars, incurred by a qualified business for converting the qualified
business to an employee stock ownership plan; or
(III)
Up to fifty percent of the conversion costs, not to exceed twenty-five thousand
dollars, incurred by a qualified business for converting the qualified business
to an alternate equity structure.
(a.3)
For income tax years commencing on or after January 1, 2026, but before January
1, 2032, the allowable percentage of conversion costs incurred by a qualified
business for the applicable conversion of the qualified business set forth in
subsections (3)(a)(I), (3)(a)(II), and (3)(a)(III) of this section for purposes
of calculating the credit is up to seventy-five percent of the conversion
costs.
(a.5)
(I) Except as otherwise provided in subsection (3)(a.5)(III) of this section
and subject to certification by the office pursuant to this section, for income
tax years commencing on or after January 1, 2024, but before January 1, 2032, a
qualified employee-owned business is allowed a credit with respect to the
income taxes imposed pursuant to this article 22 of up to fifty percent of the
expansion costs, not to exceed twenty-five thousand dollars, incurred to expand
a qualified employee-owned business's employee ownership trust, employee stock
ownership plan, worker-owned cooperative, or alternate equity structure.
(II) To
be eligible for the credit allowed pursuant to this subsection (3), a qualified
employee-owned business must expand its employee ownership trust, employee
stock ownership plan, worker-owned cooperative, or alternate equity structure
by an increment of at least twenty percent of the total ownership of the entire
qualified employee-owned business.
(III)
For income tax years commencing on or after January 1, 2026, but before January
1, 2032, the allowable percentage of expansion costs incurred by a qualified
employee-owned business to expand a qualified employee-owned business as set
forth in subsection (3)(a.5)(I) of this section for purposes of calculating the
credit is up to seventy-five percent of the expansion costs.
(a.7)
Subject to certification by the office pursuant to this section, for income tax
years commencing on or after January 1, 2027, but prior to January 1, 2032, a
qualified support entity is allowed a credit with respect to the income taxes
imposed pursuant to this article 22 of up to seventy-five percent of the
support costs, but not to exceed one hundred sixty-seven thousand dollars,
incurred in providing services that support the conversion of qualified
businesses to qualified employee-owned businesses or the expansion of qualified
employee-owned businesses.
(b) (I)
In the case of a qualified business or qualified employee-owned business that
is a C corporation, the credit is allowed to the qualified business or the
qualified employee-owned business.
(II) In
the case of a qualified business or qualified employee-owned business that is a
partnership or an S corporation, the credit is allowed to the owner of the
business.
(III)
In the case of a qualified support entity, the credit is allowed to the
qualified support entity.
(c) The
maximum amount of all tax credit certificates that the office may reserve under
subsection (6)(a) of this section is:
(I) Ten
million dollars for any income tax year commencing on or after January 1, 2022,
but before January 1, 2026; and
(II)
Two million dollars for any income tax year commencing on or after January 1,
2026, but before January 1, 2032.
(d) (I)
A qualified business or qualified employee-owned business may apply for and
claim only one tax credit for the conversion or expansion costs incurred per
tax year.
(II) A
qualified support entity may apply for and claim only one tax credit per tax
year.
(4) (a)
A business or, where applicable, a nonprofit organization shall submit an
application to the office for the issuance of a credit certificate for the
credit allowed in this section by the deadlines established in the office's
guidelines. Except as otherwise provided in subsection (4)(b) of this section,
the application must include information, as set forth in the office's
guidelines, regarding the type of conversion or expansion the business intends
to undertake, a list of the expected conversion or expansion costs, and an
estimated amount, as calculated by the business, of the expected conversion or
expansion costs.
(b) An
application for a business or a nonprofit organization submitting the
application to be approved as a qualified support entity must include
information, as set forth in the office's guidelines, regarding the support
services the business or the nonprofit organization provides to qualified
businesses or qualified employee-owned businesses, whether the business or the
nonprofit organization supported a successful conversion of a qualified
business to a qualified employee-owned business or expansion of a qualified
employee-owned business in the taxable year, if the business or the nonprofit
organization has not supported a successful conversion or expansion, the number
of qualified businesses or qualified employee-owned businesses the business or
the nonprofit organization is supporting that intend to convert or expand, as
applicable, and the status of the anticipated conversions or expansions, and
information regarding support costs incurred in the income tax year.
(5) (a)
The office shall develop guidelines for the administration of this section,
including, but not limited to:
(I)
Application requirements, including a list of the data the office needs to meet
the requirements in subsections (11) and (12) of this section;
(II)
Guidelines regarding the issuing of credit certificates;
(III)
Detailed guidelines regarding conversion costs;
(IV)
Guidelines and standards for certifying a business as a qualified business;
(V)
Detailed guidelines regarding expansion costs;
(VI)
Guidelines and standards for certifying a business as a qualified
employee-owned business; and
(VII)
Guidelines and standards for certifying a business or a nonprofit organization
as a qualified support entity.
(b)
Before the office begins to provide reservations of tax credits under
subsection (6) of this section, the office shall provide the finance committees
of the house of representatives and the senate, or any successor committees,
with a written report setting forth the clear, relevant, and ascertainable
metrics and data requirements that the office will track under subsection (12)
of this section in order to allow the general assembly and the state auditor to
measure the effectiveness of the tax expenditure allowed in this section in
achieving the purpose set forth in subsection (1)(a) of this section.
(6) (a)
(I) After the office provides the written report required in subsection
(5)(b) of this section, a reservation of tax credits is permitted for the tax
credit allowed in this section. If the office determines that the application
filed under subsection (4) of this section is complete, the office shall
determine whether the business or, if applicable, the nonprofit organization is
a qualified business, a qualified employee-owned business, or a qualified
support entity, review the list of the expected conversion or expansion costs,
and review the estimated conversion, expansion, or support costs as calculated
by the business or, if applicable, the qualified support entity. If the office
approves the business or, if applicable, the nonprofit organization as a
qualified business, a qualified employee-owned business, or a qualified support
entity, the list of expected conversion or expansion costs, and the estimated
conversion, expansion, or support costs, the office may reserve for the benefit
of the qualified business, the qualified employee-owned business, the owner of
the business, or the qualified support entity an allocation of a tax credit
subject to the limitation specified in subsection (3)(c) of this section. The
office shall notify the qualified business, the qualified employee-owned
business, or the qualified support entity in writing of the amount of the
reservation. The reservation of a tax credit does not entitle the qualified
business, the qualified employee-owned business, the owner of the business, or
the qualified support entity to an issuance of a tax credit certificate until
the qualified business, the qualified employee-owned business, or the qualified
support entity complies with all of the other requirements specified in this
section for the issuance of the tax credit certificate.
(II) A
business may apply for a staged conversion or staged expansion. If the office
receives an application for a staged conversion or staged expansion, and the
office determines the requirements set forth in subsection (6)(a)(I) of this
section have been met, the office shall reserve tax credits for all stages of
the qualified business's conversion or the qualified employee-owned business's
expansion in the year the application is filed. The office may certify the
staged conversion costs or staged expansion costs and issue tax credit
certificates under subsection (7)(b)(II) of this section when the costs are
incurred.
(b) (I)
The office must reserve tax credits in the order in which it receives completed
applications that comply with the requirements of this section and the
guidelines developed by the office. The office shall provide written notice of
any reservation of tax credits authorized by this subsection (6) or disapprove
the application within a reasonable time, not to exceed ninety days after the
filing of a completed application.
(II)
The office shall stamp each completed application with the date and time the
application was received and shall review the application on the basis of the
order in which it was submitted by date and time.
(III)
Any application disapproved by the office will be removed from the review
process, and the office shall notify the business in writing of the decision to
remove its application from the review process. Disapproved applications lose
their priority in the review process. A business may resubmit a disapproved
application, but such resubmitted application is deemed to be a new submission
for purposes of the priority procedures described in this subsection (6)(b).
(c) If,
for any calendar year, the total amount of reservations for tax credits the
office has approved is equal to the total amount of tax credits available for
reservation during that calendar year, the office shall notify all businesses
who have submitted applications then awaiting approval that no additional
approvals of applications for reservations of tax credits will be granted
during that calendar year. The office shall additionally notify each business
of the priority number given to the business's application then awaiting
approval. The applications will remain in priority status for two years from
the date of the original application and will be considered for reservations of
tax credits in the priority order established in this subsection (6) in the
event that additional credits become available resulting from the rescission of
approvals under subsection (7)(a) of this section or because a new allocation
of tax credits for a calendar year becomes available.
(7) (a)
Any qualified business or qualified employee-owned business with respect to
which the office has made a reservation of tax credits under subsection (6) of
this section shall incur not less than twenty percent of the estimated
conversion or expansion costs not later than eighteen months after the date of
the written notice from the office to the qualified business or qualified
employee-owned business granting the reservation of tax credits. The qualified
business or qualified employee-owned business shall submit evidence of
compliance with the provisions of this subsection (7)(a). If the office
determines that a qualified business or qualified employee-owned business has
failed to comply with the requirements of this subsection (7)(a), the office
may rescind the written notice it previously gave the business or the owner
approving the reservation of tax credits and, if so, the total amount of tax
credits made available for the calendar year for which reservations may be
granted must be increased by the amount of the tax credits rescinded. The
office shall promptly notify any qualified business, any qualified
employee-owned business, or the owner of the business whose reservation of tax
credits has been rescinded and, upon receipt of the notice, the qualified
business or qualified employee-owned business may submit a new application.
(b) (I)
Following the completion of the conversion or expansion, the qualified business
or the qualified employee-owned business shall notify the office that the
conversion or expansion has been completed and shall provide the office with a
cost certification of the estimated conversion or expansion costs. The cost
certification must be audited by a licensed certified public accountant that is
not affiliated with the qualified business or the qualified employee-owned
business. The office shall review the cost certification, and within ninety
days after receipt of the cost certification, the office shall certify the
conversion or expansion costs and issue a tax credit certificate in the amounts
allowed in subsection (3) of this section. The office shall promptly notify the
qualified business or the qualified employee-owned business of any disallowed
conversion or expansion costs.
(II) If
a conversion or expansion is a staged conversion or staged expansion as set
forth in subsection (6)(a)(II) of this section, and the qualified business or
the qualified employee-owned business meets the requirements in this subsection
(7), the office shall issue pro rata tax credit certificates to the qualified
business, qualified employee-owned business, or owner of the business based on
the percent of the conversion or expansion completed during each tax year.
(c)
Notwithstanding subsection (7)(b) of this section, the total amount of the tax
credit certificate issued to a qualified business, a qualified employee-owned
business, or the owner of the business shall not exceed the amount of the tax
credit reservation under subsection (6)(a) of this section.
(d) If
the amount of certified costs incurred by the qualified business or the
qualified employee-owned business would result in the qualified business,
qualified employee-owned business, or owner of the business being issued an
amount of tax credits that exceeds the amount of tax credits reserved for the
business under subsection (6)(a) of this section, the qualified business or the
qualified employee-owned business may apply to the office for the issuance of
an amount of tax credits that equals the excess. The qualified business or the
qualified employee-owned business must submit its application for issuance of
such excess tax credits on a form prescribed by the office. Unless the office
is concerned that the application it received under this subsection (7)(d) is
fraudulent, the office shall automatically approve the application, which it
shall issue by means of a separate certificate, subject only to the
availability of tax credits and the provisions concerning priority provided in
subsection (6)(a) of this section.
(8) If
the credit allowed under this section exceeds the income taxes due on the
income of the qualified business, qualified employee-owned business, owner of
the business, or qualified support entity, the amount of the credit not used to
offset income taxes must be refunded to the qualified business, qualified
employee-owned business, owner of the business, or qualified support entity.
(9) Any
tax credits issued under this section to a partnership or an S corporation must
be passed through to the partners, members, or owners, including any nonprofit
entity that is a partner, member, or owner, respectively, on a pro rata basis
according to their ownership percentage.
(10)
(a) To claim the income tax credit allowed in this section, the qualified
business, qualified employee-owned business, owner of the business, or
qualified support entity shall attach a copy of the credit certificate to its
state income tax return. No tax credit is allowed under this section unless the
qualified business, qualified employee-owned business, owner of the business,
or qualified support entity provides the copy of the credit certificate with
its filed state income tax return. The amount of the credit that the qualified
business, the qualified employee-owned business, or the qualified support
entity may claim under this section is the amount stated on the tax credit
certificate.
(b) A
qualified support entity that is an organization exempt from taxation under
section 501 (c)(3) of the internal revenue code and that claims the credit
allowed by this section shall file a return pursuant to section 39-22-601
(7)(b) and attach a copy of the credit certificate in accordance with
subsection (10)(a) of this section.
(11)
The office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified business, qualified
employee-owned business, owner of a business, and qualified support entity that
the office approved for the income tax credit allowed in this section for the
preceding calendar year that includes the following information:
(a) The
taxpayer's name; and
(b) The
taxpayer's social security number or the taxpayer's Colorado account number and
federal employer identification number.
(12)
The office shall maintain a database of any information necessary to evaluate
the effectiveness of the tax credit allowed in this section in meeting the
purposes set forth in subsection (1)(a) of this section, and shall provide such
information, and any other information that may be needed, to the state auditor
as part of the state auditor's evaluation of tax expenditures under section
39-21-305.
(13)
The office shall conduct statewide outreach efforts, within existing resources,
to minority owned businesses, as defined in section 24-48.5-127 (2)(g), about
the availability of the tax credit allowed in this section.
(14)
This section is repealed, effective December 31, 2037.
Source:
L. 2021: Entire
section added, (HB 21-1311), ch. 298, p. 1780, § 9, effective June 23. L.
2023: (2), (3)(a), (3)(b), (4), (5)(a)(III), (6)(a), (7), (8), (10), and
IP(11) amended and (3)(a.5), (3)(d), (5)(a)(V), and (5)(a)(VI) added, (HB
23-1081), ch. 244, p. 1309, § 1, effective August 7. L. 2025: (1)(a)(I),
(1)(a)(III), (2)(a)(II), (2)(e), (2)(j)(II), (2)(j)(III), IP(3)(a),
(3)(a.5)(I), (3)(c), (3)(d), (4), (5)(a)(V), (5)(a)(VI), (6)(a)(I), (8), (10),
IP(11), and (14) amended, (2)(c.5), (2)(j.5), (2)(k.5), (3)(a.3),
(3)(a.5)(III), (3)(a.7), (3)(b)(III), (5)(a)(VII) added, and (2)(j)(I)
repealed, (HB 25-1021), ch. 311, p. 1621, § 3, effective August 6.
Cross
references: For
the legislative declaration in HB 21-1311, see section 1 of chapter 298,
Session Laws of Colorado 2021.
39-22-542.5. Tax credit for new
employee-owned businesses - employee ownership cash fund - tax preference
performance statement - legislative declaration - definitions - repeal.
(1) Tax
preference performance statement.
(a) In
accordance with section 39-21-304, which requires each bill that creates a new
tax expenditure to include a tax preference performance statement as part of a
statutory legislative declaration, the general assembly finds and declares that
the purposes of the tax credit created in this section are to induce certain
designated behavior by taxpayers, to create or retain jobs, and to provide
income tax relief for certain businesses or individuals. Specifically, the tax
credit facilitates employee ownership and the retention of community investment
and wealth by business owners and employees in a community.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (1)(a) of this
section based on the information required to be maintained by and reported to
the state auditor by the employee ownership office pursuant to subsection
(7)(b) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Alternate equity structure" means a mechanism under which an
employer grants to employees a form of employee ownership, including but not
limited to an employee stock purchase plan, LLC membership, phantom stock,
profit interest, restricted stock, stock appreciation right, stock option, or
synthetic equity. The office may develop guidelines that clarify the types of
employee ownership grants that qualify as an alternate equity structure. The
office may develop guidelines that adjust the percentages set forth in this
subsection (2)(a); except that the percentages shall not be adjusted to an
amount less than twenty percent. An alternate equity structure must at a
minimum:
(I)
Grant rights to or be offered to at least twenty percent of an employer's
eligible workers, or grant rights to or be offered to at least twenty percent
of eligible workers of an employer that is owned by or operated for the benefit
of eligible workers in a broad-based employee ownership transition. For
purposes of this subsection (2)(a), "eligible workers" means all
full-time employees, regular employees, nonseasonal employees, nonmanagerial
employees, and contract labor.
(II)
Have the participation of at least twenty percent of an employer's eligible
workers;
(III)
Allocate at least twenty percent of the fully diluted securities or rights to a
synthetic interest in securities to participating eligible workers, or allocate
twenty percent of net profit from operations to participating eligible workers;
and
(IV)
Grant to participating eligible workers informational rights, decision-making
rights, and nonfinancial rights that are equal to or greater than the rights
that are granted to holders of the employer's common stock or holders of the
employer's residual membership interest.
(b)
"Department" means the Colorado department of revenue.
(c)
"Eligible costs" means costs incurred as a result of being a new
employee-owned business, as detailed in the guidelines issued by the office,
including costs associated with accounting, legal, business advisory, and
similar professional services that are incurred as a result of being a new
employee-owned business.
(d)
"Employee-owned business" means a taxpayer that is subject to tax
under this article 22, including but not limited to a C corporation, S
corporation, limited liability company, partnership, limited liability
partnership, sole proprietorship, or other similar pass-through entity, that:
(I)
Repealed.
(II)
(A) Is owned in whole or in part by an employee ownership trust;
(B) Has
an employee stock ownership plan;
(C) Is
beneficially owned in whole or in part by a worker-owned cooperative; or
(D) Has
an alternate equity structure; and
(III)
Has its corporate headquarters located in this state. For purposes of this
subsection (2)(d), "corporate headquarters" means the sole location
within a regional or national area where the majority of the taxpayer's staff
members or employees are domiciled and employed, and where the majority of the
taxpayer's financial, personnel, legal, planning, or other business functions
are conducted on a regional or national basis.
(e)
"Employee ownership office" or "office" means the employee
ownership office created in section 24-48.5-135.
(f) "Employee
ownership trust" means an indirect form of employee ownership in which a
trust holds at least twenty percent of the fully diluted securities in a
business and benefits all employees on an equal basis and otherwise meets the
definition of an alternate equity structure.
(g)
"Employee stock ownership plan" has the same meaning as set forth in
section 4975 (e)(7) of the internal revenue code, as amended.
(h)
"New employee-owned business" means an employee-owned business that
has been an employee-owned business for seven years or fewer.
(i)
"Qualified business" means a taxpayer that is a new employee-owned
business.
(j)
"Securities" has the same meaning as the term "security"
set forth in 15 U.S.C. sec. 77b (a)(1).
(k)
"Tax credit" means the credit against income tax created in this
section.
(l)
"Taxpayer" means a person subject to tax pursuant to this article 22.
(m)
"Worker-owned cooperative" has the same meaning as set forth in
section 1042 (c)(2) of the internal revenue code, as amended.
(3) Tax
credit for new employee-owned businesses.
(a)
Subject to certification by the office pursuant to this section, for income tax
years commencing on or after January 1, 2025, but before January 1, 2030, a
qualified business is allowed a credit against the income taxes imposed by this
article 22 in an amount equal to fifty percent of the eligible costs, not to
exceed fifty thousand dollars, incurred by the qualified business.
(b) (I)
A qualified business may apply for and claim only one tax credit allowed in
this subsection (3) for the eligible costs incurred in any tax year.
(II) In
the case of a qualified business that is a C corporation, the tax credit is
allowed to the qualified business.
(III)
In the case of a qualified business that is a partnership or an S corporation,
the tax credit is allowed to the owners of the qualified business.
(IV) In
the case of a qualified business that is taxed pursuant to subchapter T of the
internal revenue code, 26 U.S.C. sec. 1381 et seq., as amended, the tax credit
is allowed either to the qualified business or to the owners of the qualified
business as permitted under subchapter T of the internal revenue code.
(4) Tax
credit certificate.
(a) A
qualified business shall submit an application to the office for the
certification and issuance of a tax credit certificate for the tax credit
allowed in subsection (3) of this section by the deadlines established in the
office's guidelines. The application must include the information set forth in
the office's guidelines. The office may impose a reasonable application fee not
to exceed two hundred fifty dollars. The office shall transmit all fees
collected to the state treasurer, who shall credit the money to the employee
ownership cash fund created in subsection (8) of this section.
(b) To
claim the tax credit allowed in subsection (3) of this section, a qualified
business must annually apply for and receive a tax credit certificate from the
office pursuant to this subsection (4). The submission of an application does
not entitle the qualified business to the issuance of a tax credit certificate.
(c) The
office shall document the date and time that a complete application was
received and shall review complete applications in the order in which they are
received. If the office determines that an applicant is not entitled to a tax
credit certificate, the office shall notify the applicant of its disapproval in
writing.
(d) If
the office is satisfied that the requirements of this section and the office's
guidelines for the tax credit are met, then the office shall issue to the
qualified business a tax credit certificate that evidences the qualified
business's right to claim the tax credit allowed in subsection (3) of this
section. The office shall not issue tax credit certificates in excess of the
maximum aggregate amount for any single income tax year specified in subsection
(4)(e) of this section.
(e) The
maximum aggregate amount of all tax credit certificates that the office may
issue pursuant to this section in any single income tax year is one million
five hundred thousand dollars.
(5) Claiming
tax credit. To claim the tax credit allowed in subsection (3) of this
section, the qualified business shall file the tax credit certificate with the
qualified business's state income tax return. The amount of the tax credit that
the qualified business may claim under this section is the amount stated on the
tax credit certificate issued pursuant to subsection (4) of this section.
(6) Tax
credit refundable. If the amount of the tax credit exceeds the taxes due
on the income of the qualified business for the taxable year for which the tax
credit is claimed, the amount of the tax credit not used to offset income taxes
must be refunded to the qualified business.
(7) Guidelines
and reporting requirements.
(a) The
office shall develop guidelines for the administration of this section and post
the guidelines on the website of the office of economic development and
international trade. The guidelines must include:
(I)
Application requirements;
(II)
Guidelines for issuing tax credit certificates;
(III)
Guidelines regarding eligible costs; and
(IV)
Guidelines for approving a business as a qualified business.
(b) The
office shall maintain a database of any information determined necessary by the
office to evaluate the effectiveness of the tax credit allowed in this section
in achieving the purposes set forth in subsection (1)(a) of this section and
shall provide this information, and any other information that may be needed,
to the state auditor as part of the state auditor's evaluation of tax
expenditures under section 39-21-305.
(c) The
office shall review the effectiveness of the tax credit and include the results
of the review in the annual report submitted to the general assembly by the
office of economic development. Notwithstanding the requirement in section
24-1-136 (11)(a)(I), the requirement to submit the report required in this
subsection (7)(c) continues until the annual report following the income tax
year commencing January 1, 2030.
(d) The
office shall provide the department with an electronic report of each qualified
business and owner of a qualified business to which the office issued a tax
credit certificate for the preceding calendar year. The office shall provide
this report in a sufficiently timely manner to allow the department to process
returns claiming the income tax credit allowed in this section. This report
must include:
(I) The
taxpayer's name;
(II)
The tax identification number of the taxpayer to whom the tax credit
certificate is issued; and
(III)
The amount of the tax credit certificate.
(8) Employee
ownership cash fund.
(a) The
employee ownership cash fund is created in the state treasury. The fund
consists of money from fees collected and credited to the fund pursuant to
subsection (4)(a) of this section and any other money that the general assembly
may appropriate, transfer, or require by law to be credited to the fund.
(b) The
state treasurer shall credit all interest and income derived from the deposit
and investment of money in the employee ownership cash fund to the fund.
(c)
Money in the employee ownership cash fund is continuously appropriated to the
office for the purpose of administering this section.
(d) The
state treasurer shall transfer all unexpended and unencumbered money in the
fund on December 31, 2034, to the general fund.
(9) Repeal.
This section is repealed, effective January 1, 2035.
Source:
L. 2024: Entire
section added, (HB 24-1157), ch. 370, p. 2488, § 3, effective August 7. L.
2025: IP(2)(a), (2)(d)(II), (2)(d)(III), and (2)(f) amended and (2)(d)(I)
repealed, (HB 25-1021), ch. 311, p. 1626, § 4, effective August 6.
Cross
references: For
the legislative declaration in HB 24-1157, see section 1 of chapter 370,
Session Laws of Colorado 2024.
39-22-543. Credit for wildfire hazard
mitigation expenses - legislative declaration - definitions - repeal.
(1) The
general assembly declares that the purpose of the tax expenditure in this
section is to reimburse a landowner for the costs incurred in performing
wildfire mitigation measures on the landowner's property located within the
state.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Costs" means any actual out-of-pocket expense incurred and paid by
the landowner to a third-party service provider, documented by receipt, for
performing wildfire mitigation measures. "Costs" does not include any
inspection or certification fees, in-kind contributions, donations, incentives,
or cost sharing associated with performing wildfire mitigation measures.
"Costs" does not include expenses paid by the landowner from any
grants awarded to the landowner for performing wildfire mitigation measures.
"Costs" does not include any amount paid by the landowner for the
purchase or rental of any article of tangible personal property for the
landowner's own use.
(a.5)
"Infestation mitigation measures" means the thinning of woody
vegetation that is at risk of mountain pine beetle or spruce beetle infestation
or that has been killed by mountain pine beetles or spruce beetles, if such
activities meet or exceed any Colorado state forest service standards or any
other applicable state rules.
(b)
"Inflation" means the annual percentage change in the United States
department of labor's bureau of labor statistics consumer price index for
Denver-Aurora-Lakewood for all items paid by all urban consumers, or its
applicable predecessor or successor index.
(c)
"Landowner" means any individual owner of record of private land
located within the state, including any easement, right-of-way, or estate in
the land, and includes the heirs, successors, and assigns of such land.
"Landowner" shall not include any partnership, S corporation, or
other similar entity that owns private land as an entity.
(d)
"Wildfire mitigation measures" means the creation of a defensible
space around structures; the establishment of fuel breaks; the thinning of
woody vegetation for the primary purpose of reducing risk to structures from
wildland fire; or the secondary treatment of woody fuels by lopping and
scattering, piling, chipping, removing from the site, or prescribed burning; so
long as such activities meet or exceed any Colorado state forest service
standards or any other applicable state rules.
(3) (a)
The amount of the credit allowed by this section is the same whether it is
claimed by a single taxpayer or two taxpayers who file a joint return. In the
case of two taxpayers who may legally file a joint return but actually file
separate returns, only one of the taxpayers may claim the credit specified in
this section.
(b) In
the case of real property owned by tenants in common or joint tenants, the
credit allowed pursuant to this section is only allowed for one of the
individuals of the ownership group.
(4) (a)
For income tax years commencing on or after January 1, 2023, but prior to
January 1, 2025, a landowner with a federal taxable income at or below one
hundred twenty thousand dollars for the income tax year commencing on or after
January 1, 2023, as adjusted for inflation and rounded to the nearest hundred
dollar amount for each income tax year thereafter, is allowed a credit against
the income taxes imposed by this article 22 in an amount equal to twenty-five
percent of up to two thousand five hundred dollars in costs for wildfire
mitigation measures. The maximum total credit in a taxable year is six hundred
twenty-five dollars.
(b) For
income tax years commencing on or after January 1, 2025, but prior to January
1, 2027, a landowner with a federal taxable income at or below one hundred
twenty thousand dollars for the income tax year commencing on or after January
1, 2023, as adjusted for inflation and rounded to the nearest hundred dollars
for each income tax year thereafter, is allowed a credit against the income
taxes imposed by this article 22 in an amount equal to the landowner's costs
incurred for wildfire mitigation measures in an amount up to one thousand
dollars. The maximum total credit in a taxable year for a landowner is one
thousand dollars.
(c) For
income tax years beginning on or after January 1, 2027, but before January 1,
2031, a landowner with an adjusted gross income at or below three hundred
thousand dollars for the income tax year beginning on or after January 1, 2027,
as adjusted for inflation and rounded to the nearest hundred dollars for each
income tax year thereafter, is allowed a credit against the income taxes
imposed by this article 22 in an amount equal to the landowner's costs incurred
for wildfire mitigation measures, infestation mitigation measures, or both in
an amount up to two thousand dollars. The maximum total credit in a taxable
year for a landowner is two thousand dollars.
(5) (a)
If the amount of a credit under this section exceeds a taxpayer's actual tax
liability for an income tax year beginning before January 1, 2027, the amount
of the credit not used to offset the taxpayer's income tax liability is not
refunded to the taxpayer and shall not be carried forward as a tax credit
against the taxpayer's income tax liability in any subsequent tax year.
(b) For
income tax years beginning on or after January 1, 2027, if the amount of a
credit allowed by this section exceeds the taxpayer's income taxes due, the
excess may not be carried forward and is refunded to the taxpayer.
(6)
This section is repealed, effective January 1, 2040.
Source:
L. 2022: Entire
section added, (HB 22-1007), ch. 343, p. 2458, § 3, effective June 3. L.
2024: (2)(a) and (4) amended, (HB 24-1036), ch. 373, p. 2535, § 32,
effective August 7. L. 2026: (2)(a.5) and (4)(c) added and (2)(c),
(3)(a), (4)(b), (5), and (6) amended, (HB 26-1289), ch. 364, p. 2195, § 9,
effective June 3.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-544. Credit against tax -
qualifying seniors - creation - legislative declaration - definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I)
Colorado's affordable housing shortage is hurting seniors, making it more
difficult for many seniors to afford housing;
(II)
The senior property tax exemption was adopted by Colorado voters in 2000 in
order to help seniors afford to stay in their homes;
(III)
Many seniors are ineligible for the senior property tax exemption because they
have owned their home for fewer than ten years or because they rent; and
(IV)
Property tax rebates or tax-equivalent rebates for renters available under
section 39-31-102 only assist seniors with incomes below very low thresholds.
(b) (I)
Therefore, in order to help more seniors afford the high cost of housing in
Colorado, the general assembly hereby intends to establish a refundable income
tax credit for income-qualified seniors who do not qualify for the senior
property tax exemption to help them afford the high cost of housing.
(II) In
accordance with section 39-21-304 (1), the purpose of the tax expenditure
created in this section is to provide tax relief for income-qualified seniors.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
exemption in achieving the purpose specified in subsection (1)(b)(II) of this
section based on the number of taxpayers who have claimed the exemption.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Credit" means a credit against income tax that is created in this
section.
(b)
Repealed.
(3) (a)
(I) For the income tax year commencing on January 1, 2022, a qualifying
senior is allowed a credit against the tax imposed by this article 22 in an
amount set forth in subsection (4) of this section.
(II) As
used in this subsection (3)(a), "qualifying senior" means a resident
individual who:
(A) Is
sixty-five years of age or older at the end of 2022;
(B) Has
a federal adjusted gross income that is less than or equal to seventy-five
thousand dollars for the income tax year commencing on January 1, 2022; and
(C) Has
not claimed a property tax exemption under section 39-3-203 for the property
tax year commencing on January 1, 2022.
(b) (I)
For the income tax year commencing on January 1, 2024, a qualifying senior is
allowed a credit against the tax imposed by this article 22 in an amount set
forth in subsection (4.5) of this section.
(II) As
used in this subsection (3)(b), "qualifying senior" means a resident
individual who:
(A) Is
sixty-five years of age or older at the end of 2024;
(B)
Has, for the income tax year commencing on January 1, 2024, a federal adjusted
gross income less than or equal to seventy-five thousand dollars for an
individual filing a single return, or has a federal adjusted gross income less
than or equal to one hundred twenty-five thousand dollars for an individual
filing a joint return; and
(C) Has
not claimed a property tax exemption under section 39-3-203 for the property
tax year commencing on January 1, 2024, on or before August 15, 2024.
(4) (a)
For the income tax year commencing on January 1, 2022, the amount of the credit
is one thousand dollars for a qualifying senior with federal adjusted gross
income that is twenty-five thousand dollars or less. For every five hundred
dollars of adjusted gross income above twenty-five thousand dollars, the amount
of the credit is reduced by ten dollars.
(b) For
the income tax year commencing on January 1, 2022, the credit is the same
whether it is claimed by one taxpayer filing a single return or two taxpayers
filing a joint return. In the case of two taxpayers who share the same primary
residence and who may legally file a joint return but actually file separate
returns, both taxpayers may claim the credit, but the maximum credit for each
is five hundred dollars and, for every five hundred dollars of adjusted gross
income above twenty-five thousand dollars, the amount of the credit is reduced
by five dollars.
(c) (I)
For the income tax year commencing on January 1, 2022, notwithstanding
subsections (4)(a) and (4)(b) of this section, a taxpayer who also qualifies
for a grant under article 31 of this title 39 during calendar year 2022 is
eligible to receive the full credit without an income-based reduction that
otherwise applies for the taxpayer under subsection (4)(a) or (4)(b) of this
section.
(II)
This subsection (4)(c) is repealed, effective December 31, 2026.
(4.5)
For the income tax year commencing on January 1, 2024:
(a) The
amount of the credit is eight hundred dollars for a qualifying senior filing a
single return with a federal adjusted gross income that is twenty-five thousand
dollars or less. For every five hundred dollars of adjusted gross income above
twenty-five thousand dollars, the amount of the credit is reduced by eight
dollars.
(b) The
amount of the credit is eight hundred dollars for two taxpayers filing a joint
return with a federal adjusted gross income that is twenty-five thousand
dollars or less. For every five hundred dollars of adjusted gross income above
twenty-five thousand dollars, the amount of the credit is reduced by four
dollars.
(c) In
the case of two taxpayers who share the same primary residence and who may
legally file a joint return but actually file separate returns, both taxpayers
may claim the credit, but the maximum credit for each taxpayer is four hundred
dollars and, for every five hundred dollars of adjusted gross income above
twenty-five thousand dollars, the amount of the credit is reduced by four
dollars.
(d)
Notwithstanding subsections (4.5)(a), (4.5)(b), and (4.5)(c) of this section, a
taxpayer who also qualifies for a grant under article 31 of this title 39
during calendar year 2024 is eligible to receive the full credit without an
income-based reduction that otherwise applies for the taxpayer pursuant to
subsections (4.5)(a), (4.5)(b), and (4.5)(c) of this section.
(e) In
the case of a part-year resident, the credit allowed under this subsection
(4.5) is apportioned in the ratio determined under section 39-22-110 (1).
(5) (a)
Any amount of the credit that exceeds the qualifying senior's income taxes due
is refunded to the qualifying senior.
(b) To
the extent permitted by federal law, the credit is not income or resources for
the purpose of determining eligibility for the payment of public assistance
benefits and medical assistance benefits authorized under state law or for a
payment made under any other publicly funded programs.
(6) The
department of revenue may use the reports received from the property tax
administrator in accordance with section 39-3-207 (8) for purposes of
confirming that a taxpayer meets the eligibility requirement set forth in
subsection (3)(b)(II)(C) of this section.
Source:
L. 2022: Entire
section added, (HB 22-1205), ch. 436, p. 3071, § 2, effective August 10. L.
2024: (2)(b) repealed, (3), (4), and (6) amended, and (4.5) added, (HB
24-1052), ch. 473, p. 3322, § 2, effective August 7. L. 2025: (4)(c)
amended, (HB 25-1296), ch. 202, p. 914, § 11, effective May 16.
Cross
references: For
the legislative declaration in HB 25-1296, see section 1 of chapter 202,
Session Laws of Colorado 2025.
39-22-545. Credit against tax - heat
pump systems - heat pump water heaters - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I) The
general assembly has committed to reduce greenhouse gases through numerous
policy and regulatory measures to meet the goals established in 2019;
(II)
Great quantities of emissions are released in the traditional process of
heating and cooling private sector residential buildings;
(III)
There is great potential for businesses and individuals in the state to reduce
greenhouse gas emissions generated in the heating and cooling of residential
buildings by installing heat pump systems or heat pump water heaters, which
reduce net greenhouse gas emissions;
(IV)
Providing an income tax credit for heat pump systems and heat pump water
heaters will encourage businesses and individuals to purchase and use heat pump
systems and heat pump water heaters rather than traditional heating and cooling
methods; and
(V) The
purchase and use of heat pump systems and heat pump water heaters will benefit
public health in the heating and cooling of homes and businesses and take
advantage of latent heat sources and available renewable power during low
demand periods.
(b) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly hereby finds and
declares that the purposes of the tax expenditure created in subsection (3) of
this section are to:
(I)
Induce certain designated behavior by taxpayers, specifically the purchase and
use of heat pump systems and heat pump water heaters; and
(II)
Contribute to the state's effort to achieve its climate goals.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
tax credits in achieving the purposes specified in subsection (1)(b) of this
section based on the number of heat pump systems and the number of heat pump
water heaters sold and used in the state. The Colorado energy office shall
provide the state auditor with any available information that would assist the
state auditor's measurement.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Air-source heat pump system" has the same meaning set forth in
section 39-26-732 (2)(a).
(b)
"Ground-source heat pump system" has the same meaning set forth in
section 39-26-732 (2)(b).
(c)
"Heat pump system" means an air-source heat pump system,
ground-source heat pump system, water-source heat pump system, or variable
refrigerant flow heat pump system.
(d)
"Heat pump water heater" has the same meaning set forth in section
39-26-732 (2)(d).
(e)
"Purchase price" means the amount actually paid by the purchaser for
the tangible personal property installed, including charges for sales tax and
freight, but not including any charges for assembly, installation, or other
construction services, or permit fees.
(f)
"Purchaser" means a taxpayer who is the buyer of a heat pump system
or heat pump water heater.
(g)
"Seller" means the entity that sells a heat pump system or heat pump
water heater to a purchaser.
(h)
"Taxpayer" means a person subject to tax under this article 22, or a
person or political subdivision of this state who is exempt from tax under
section 39-22-112 (1), but does not include insurance companies subject to the
tax imposed on gross premiums by section 10-3-209. For purposes of this
section, a person or political subdivision of this state who is exempt from tax
under section 39-22-112 (1) is a taxpayer even if the person or political
subdivision has no unrelated business income.
(i)
"Variable refrigerant flow heat pump system" has the same meaning set
forth in section 39-26-732 (2)(f).
(j)
"Water-source heat pump system" has the same meaning set forth in
section 39-26-732 (2)(e).
(3) (a)
Subject to the provisions of subsection (4) of this section, for income tax
years commencing on or after January 1, 2023, but before January 1, 2024, any
purchaser that installs a residential or commercial heat pump system into real
property in this state or that installs a residential or commercial heat pump
water heater into real property in this state is allowed a credit against the
tax imposed by this article 22 in an amount equal to ten percent of the
purchase price paid by the purchaser for the heat pump system or heat pump
water heater.
(b) The
credit allowed pursuant to this section is for the income tax year in which the
heat pump system or heat pump water heater is purchased.
(4) (a)
(I) To be eligible to claim a tax credit pursuant to this section, the
purchaser shall certify, as specified in subsection (4)(b) of this section,
that all necessary mechanical, plumbing, and electrical work performed in
connection with the installation of a heat pump system or heat pump water
heater in a new or existing industrial, commercial, or multifamily residential
building containing twenty thousand square feet or more of conditioned floor
space was or will be performed by a contractor on the certified contractor list
created pursuant to section 40-3.2-105.6 (3)(a), or by employees of a utility,
subject to state licensing requirements and all applicable state and local
rules, codes, and standards.
(II)
The requirements of this subsection (4)(a) do not apply to the installation of
a heat pump system or heat pump water heater that is limited to in-unit work in
a multifamily building or unit and that is initiated by the owner or tenant of
the multifamily building or unit.
(b) The
purchaser shall certify, in a form and manner to be determined by the
department of revenue, that the heat pump system or heat pump water heater was
or will be installed in accordance with the provisions of subsection (4)(a) of
this section, if applicable. The seller shall provide the certification to the
purchaser for the purposes of subsection (5) of this section.
(5) (a)
A purchaser may assign the tax credit allowed in this section to the
purchaser's seller as follows:
(I) The
assignment to the seller must be completed at the time of purchase of a new
heat pump system or heat pump water heater by entering into an agreement as set
forth in subsection (5)(c) of this section;
(II)
The purchaser must certify in writing that the purchaser will comply with the
provisions regarding installation of the heat pump system or heat pump water
heater specified in subsection (4) of this section, if applicable;
(III)
The purchaser must assign the tax credit to the seller and forfeit the right to
claim the tax credit on the purchaser's tax return in exchange for good and
valuable consideration; and
(IV)
The seller must compensate the purchaser for the full nominal value of the tax
credit. The compensation paid to the purchaser is considered a refund of state
taxes and is not state taxable income.
(b)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a seller pursuant to this subsection (5), the seller receives the full amount
of the tax credit that the purchaser is allowed in this section. Any unpaid
balance or unpaid debt of the purchaser may not be credited from the amount of
the tax credit allowed in this section.
(c) To
complete the tax credit assignment, the purchaser and the seller must enter
into an agreement that:
(I)
Includes the purchaser's written certification to comply with the provisions
regarding installation of the heat pump system or heat pump water heater
specified in subsection (4) of this section, if applicable; and
(II)
Affirms that the requirements specified in subsection (5)(a) of this section
were met.
(d) The
seller may authorize an agent or a designee to sign the agreement on its
behalf.
(e) The
seller shall electronically submit a report containing the information required
in the agreement described in subsection (5)(c) of this section to the
department of revenue within thirty days of the purchase of a heat pump system
or heat pump water heater in a form and manner to be determined by the
department.
(f) The
seller shall also file the agreement described in subsection (5)(c) of this
section with the original tax return for the taxable year in which the heat
pump system or heat pump water heater is purchased.
(g) The
department of revenue, in consultation with the Colorado energy office, shall
develop a model report and agreement no later than December 1, 2022.
(6) If
a credit authorized in this section exceeds the income tax due on the income of
the seller for the taxable year, the excess credit may not be carried forward
and shall be refundable to the seller.
(7)
Making a purchaser aware of the income tax credit allowed in this section or
helping a purchaser assign the income tax credit to a seller as allowed in this
section does not rise to the level of providing the purchaser with unauthorized
tax advice.
(8)
This section is repealed, effective January 1, 2028.
Source:
L. 2022: Entire
section added, (SB 22-051), ch. 333, p. 2346, § 2, effective August 10. L.
2023: (3)(a) amended, (HB 23-1272), ch. 167, p. 775, § 4, effective May 11.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023.
39-22-546. Credit against tax -
residential energy storage systems - tax preference performance statement -
legislative declaration - definition - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly hereby finds and
declares that the purposes of the tax expenditure created in subsection (3) of
this section are to:
(I)
Induce certain designated behavior by taxpayers, specifically the purchase and
installation of residential energy storage systems; and
(II)
Contribute to the state's effort to achieve its climate goals.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credits in achieving the purposes specified in subsection (1)(a) of this
section based on the number of residential energy storage systems installed in
the state. The Colorado energy office shall provide the state auditor with any
available information that would assist the state auditor's measurement.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Energy storage system" means any commercially available,
customer-sited system, including batteries and the batteries paired with
on-site generation, that is capable of retaining, storing, and delivering
energy by chemical, thermal, mechanical, or other means.
(b)
"Purchase price" means the amount actually paid by the purchaser for
the tangible personal property installed, including charges for sales tax and
freight, but not including any charges for assembly, installation, or other
construction services, or permit fees.
(c)
"Purchaser" means a taxpayer who is the buyer of an energy storage
system.
(d)
"Seller" means the entity that sells an energy storage system.
(3) (a)
For income tax years commencing on or after January 1, 2023, but before January
1, 2030, any purchaser that installs an energy storage system in a residential dwelling
in this state is allowed a credit against the tax imposed by this article 22 in
an amount equal to ten percent of the purchase price paid by the purchaser for
the energy storage system.
(b) The
credit allowed pursuant to this section is for the income tax year in which the
energy storage system is purchased.
(4) (a)
A purchaser may assign the tax credit allowed in this section to the
purchaser's seller as follows:
(I) The
assignment to the seller must be completed at the time of purchase of a new
energy storage system by entering into an agreement as set forth in subsection
(4)(c) of this section;
(II)
The purchaser must assign the tax credit to the seller and forfeit the right to
claim the tax credit on the purchaser's tax return in exchange for good and
valuable consideration; and
(III)
The seller must compensate the purchaser for the full nominal value of the tax
credit. The compensation paid to the purchaser is considered a refund of state
taxes and is not state taxable income.
(b)
Notwithstanding section 39-21-108 (3), if a purchaser assigns the tax credit to
a seller pursuant to this subsection (4), the seller receives the full amount
of the tax credit that the purchaser is allowed in this section. Any unpaid
balance or unpaid debt of the purchaser may not be credited from the amount of
the tax credit allowed in this section.
(c) To
complete the tax credit assignment, the purchaser and the seller must enter
into an agreement that affirms that the requirements specified in subsection
(4)(a) of this section were met.
(d) The
seller may authorize an agent or a designee to sign the agreement on its
behalf.
(e) The
seller shall electronically submit a report containing the information required
in the agreement described in subsection (4)(c) of this section to the
department of revenue within thirty days of the purchase of an energy storage
system in a form and manner to be determined by the department.
(f) The
seller shall also file the agreement described in subsection (4)(c) of this
section with the original tax return for the taxable year in which the energy
storage system is purchased.
(g) The
department of revenue, in consultation with the Colorado energy office, shall
develop a model report and agreement no later than December 1, 2022.
(5) If
a credit authorized in this section exceeds the income tax due on the income of
the seller for the taxable year, the excess credit may not be carried forward
and shall be refundable to the seller.
(6)
Making a purchaser aware of the income tax credit allowed in this section or
helping a purchaser assign the income tax credit to a seller as allowed in this
section does not rise to the level of providing the purchaser with unauthorized
tax advice.
(7)
This section is repealed, effective January 1, 2033.
Source:
L. 2022: Entire
section added, (SB 22-051), ch. 333, p. 2346, § 2, effective August 10. L.
2025: (3)(a) and (7) amended, (SB 25-026), ch. 362, p. 1963, § 2, effective
August 6. L. 2026: (3)(a) and (7) amended, (HB 26-1289), ch. 364, p.
2220, § 38, effective June 3.
Cross
references: For
the legislative declaration in HB 26-1289, see section 1 of chapter 364,
Session Laws of Colorado 2026.
39-22-547. Early childhood educator
income tax credit - tax preference performance statement - legislative
declaration - definitions - repeal.
(1) (a)
The general assembly finds and declares that:
(I) The
benefits of quality child care and early childhood education are well
documented and a striking connection exists between children's learning
experiences well before kindergarten and their later school success;
(II)
Small business owners and parents who rely on child care to work would also
experience lower turnover in child care staff when early childhood educators
experience better economic stability; and
(III)
When early childhood educators improve the quality of their education by
receiving early childhood professional credentials or attaining higher
credential levels, it improves the quality of children's early learning
experiences.
(b) In
accordance with section 39-21-304 (1), the purpose of this tax expenditure is
to:
(I)
Induce certain designated behavior by taxpayers, which in this instance is for
early childhood educators to receive an early childhood professional credential
or to attain higher credential levels; and
(II)
Provide tax relief for early childhood educators.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(b)(I) of this
section based on a comparison of the number of early childhood professional
credentials at the various levels before and with the credit.
(d) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(b)(II) of this
section based on the number of credits that are claimed.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Department" means the department of revenue.
(b)
"Early childhood professional credential" means the early childhood
professional credentials issued by the department of education, or a successor
department, and designated as early childhood professional I, early childhood
professional II, early childhood professional III, early childhood professional
IV, early childhood professional V, and early childhood professional VI.
(c)
"Eligible early childhood educator" means an individual who:
(I) Has
a federal adjusted gross income less than or equal to seventy-five thousand
dollars for an individual filing a single return, or has a federal adjusted
gross income less than or equal to one hundred fifty thousand dollars for an
individual filing a joint return;
(II)
Holds an early childhood professional credential for at least part of the
income tax year for which the credit is claimed; and
(III)
For at least six months of the income tax year for which the credit is claimed,
is either the licensee of an eligible program or employed by an eligible
program.
(d)
"Eligible program" means either an early childhood education program
as defined in section 26.5-2-202 (3) or a licensed family child care home. An
eligible program must have held at least a level one quality rating pursuant to
the Colorado shines quality rating and improvement system established in
section 26.5-5-101 for the income tax year for which the credit is claimed.
(e)
"Family child care home" has the same meaning as set forth in section
26.5-5-303 (7).
(f)
"Inflation" means the annual percentage change in the United States
department of labor's bureau of labor statistics consumer price index for
Denver-Aurora-Lakewood for all items paid by all urban consumers, or its
applicable successor index.
(3) (a)
For income tax years commencing on or after January 1, 2022, but before January
1, 2026, an eligible early childhood educator is allowed a credit against the
tax imposed by this article 22 in an amount as set forth in subsection (3)(b)
of this section.
(b) (I)
Except as provided in subsection (3)(b)(II) of this section, the amount of the
credit equals, for:
(A)
Seven hundred fifty dollars for an early childhood professional I;
(B) One
thousand dollars for an early childhood professional II; and
(C) One
thousand five hundred dollars for an early childhood professional III, early
childhood professional IV, early childhood professional V, or early childhood
professional VI.
(II)
For the income tax years commencing on or after January 1, 2023, the department
shall adjust the credit amounts set forth in subsection (3)(b)(I) of this
section to reflect inflation for each income tax year in which the credit
described in this section is allowed.
(c)
Each eligible early childhood educator is only allowed one credit per income
tax year, even if the eligible early childhood educator earns a higher level
early childhood professional credential in the same year. In such case, the
eligible early childhood educator's credit is based on the highest early
childhood professional credential attained during the income tax year.
(4) The
amount of the credit under this section that exceeds the eligible early
childhood educator's income taxes due is refunded to the eligible early
childhood educator.
(5) No
later than January 1, 2023, and each January 1 thereafter through January 1,
2026, the department of human services, or a successor department, shall
provide the department of revenue with an electronic report of each individual
who held an early childhood professional credential during the previous
calendar year for which the credit is allowed. The department shall include the
following information in the report, if available:
(a) The
name of the individual who holds the early childhood professional credential;
(b) The
individual's social security number or tax identification number;
(c) The
highest level of early childhood professional credential held by the individual
during the year; and
(d) The
length of time that the individual held an early childhood professional
credential at any level.
(6)
This section is repealed, effective July 1, 2030.
Source:
L. 2022: Entire
section added, (HB 22-1010), ch. 347, p. 2475, § 2, effective August 10. L.
2023: (2)(e) amended, (HB 23-1301), ch. 303, p. 1844, § 86, effective
August 7. L. 2024: (2)(d) amended, (HB 24-1450), ch. 490, p. 3426, § 82,
effective August 7.
Cross
references: For
the legislative declaration in HB 22-1010, see section 1 of chapter 347,
Session Laws of Colorado 2022.
39-22-548. Colorado homeless
contribution tax credit - legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure or extends an expiring tax expenditure to include a tax
preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that the general
legislative purpose of this tax expenditure is to induce certain designated
behavior by taxpayers. Specifically, this tax expenditure is intended to
encourage taxpayers to make contributions to approved nonprofit organizations
providing certain qualifying activities to leverage financial contributions
from Colorado residents and businesses to support providing appropriate housing
and services to assist individuals and families experiencing homelessness. The
tax expenditure will catalyze and strengthen statewide efforts to address the
effects of homelessness through private investment and civic engagement in
Colorado-based service providers for individuals and families experiencing
homelessness.
(b) The
annual review presented by the division as set forth in subsection (6) of this
section will allow the general assembly and the state auditor to measure the
effectiveness of the tax expenditure.
(c) In
the first year that the tax expenditure was available, eight thousand three
hundred twenty donations with a value of twenty million four hundred fifty-one
thousand two hundred forty-three dollars were leveraged. The total number and
value of donations increased in the next income tax year. Therefore, the
general assembly finds and declares that this tax expenditure has successfully
catalyzed and strengthened statewide efforts to address the effects of
homelessness through private investment and civic engagement in Colorado-based
service providers for individuals and families experiencing homelessness and
that the tax expenditure should be extended into future income tax years.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Approved nonprofit organization" means a nonprofit organization that
provides a qualifying activity and that has been reviewed and approved by the
division as specified in subsection (5) of this section and has a history or
track record of success in delivering services and demonstrated financial
viability.
(b)
"Approved project" means a project administered by an approved
nonprofit organization that has been evaluated, reviewed, and approved by the
division as specified in subsection (5) of this section, and that implements
one or more qualifying activities.
(c)
"Capital campaign" means a campaign that encourages public and
private partnerships and is focused on raising funds for a specific capital
project. The capital project must involve construction and implementation that
commences within three years of the project being approved by the division. A
"capital campaign" must include a campaign for one or more of the
following:
(I)
Supportive housing for individuals or families experiencing homelessness;
(II)
Community overnight shelters, community day shelters, or emergency shelters;
(III)
Facilities, including the acquisition or rehabilitation of facilities, used to
provide housing or services to individuals or families experiencing
homelessness, including facilities that are necessary to perform qualifying
services; or
(IV)
Facilities needed to provide administrative support for approved projects.
(d)
"Division of housing" or "division" means the division of
housing in the department of local affairs created in section 24-32-704.
(e)
"In-kind contribution" means a contribution that is not a monetary
contribution and is valued over five thousand dollars pursuant to an
independent third-party valuation, including a contribution of property,
services, stocks, bonds, or other intangible property.
(f)
"Monetary contribution" means a contribution in United States
currency in any form, including cash, payment made by check, electronic funds
transfer, debit card, or credit card.
(g)
"Nonprofit organization" means any organization in good standing with
the secretary of state that is exempt from taxation pursuant to section 501 (a)
of the federal "Internal Revenue Code of 1986", 26 U.S.C. sec. 501
(a), as amended, and listed as an exempt organization in section 501 (c)(3) of
the federal "Internal Revenue Code of 1986", 26 U.S.C. sec. 501
(c)(3), as amended.
(h)
"Operational service" means a service with the primary focus on
assisting individuals or families experiencing homelessness or, in the case of
prevention, individuals or families facing imminent risk of homelessness. An
operational service must also be a service that supports or provides:
(I)
Outreach efforts to engage or provide services to unsheltered individuals or
families experiencing homelessness;
(II)
Safe emergency, temporary, or transitional shelters, such as day shelters, that
may include supportive services to individuals or families experiencing
homelessness;
(III)
Prevention services that target individuals or families facing imminent risk of
homelessness as defined by the department of local affairs;
(IV)
Supportive housing for individuals or families experiencing homelessness or who
would otherwise be homeless;
(V)
Services designed to assist individuals or families experiencing homelessness
to obtain an employment outcome, including job placement services and services
that help individuals become workforce ready;
(VI)
Case management, including establishing client goals for individuals or
families experiencing homelessness and coordination of referrals to address
health or mental health benefit procurement and procurement of other essential
services for individuals or families experiencing homelessness;
(VII)
Shelters and services for survivors of domestic violence who are fleeing an
abusive household; or
(VIII)
The implementation and operation of successor projects or other services for
individuals or families experiencing homelessness that are identified by the
division as emerging, promising, and providing best practices.
(i)
"Qualifying activity" means a capital campaign or an operational
service.
(j)
"Taxpayer" means a resident individual or a domestic or foreign
corporation subject to part 3 of this article 22, a partnership, S corporation,
or other similar pass-through entity, estate, or trust that makes a
contribution as an entity, and a partner, member, and subchapter S shareholder
of such a pass-through entity.
(3) (a)
For income tax years commencing on or after January 1, 2023, but before January
1, 2031, except as provided in subsection (3)(b) of this section, any taxpayer
who makes a monetary or in-kind contribution to an approved nonprofit
organization, or to an approved project administered by an approved nonprofit
organization, is allowed a credit equal to twenty-five percent of the total
value of the contribution, subject to the limitations specified in subsection
(3)(d) of this section.
(b) If
a taxpayer makes a monetary or in-kind contribution to an approved nonprofit
organization, or to an approved project administered by an approved nonprofit
organization, in an underserved, rural county, as defined by the division in
its guidelines for the program, then the taxpayer is allowed a credit equal to
thirty percent of the total value of the contribution, subject to the
limitations in subsection (3)(d) of this section.
(c) The
approved nonprofit organization that receives the allowable contribution shall
issue a tax credit certificate to each taxpayer that makes an allowable
contribution pursuant to subsections (3)(a) or (3)(b) of this section; except
that the approved nonprofit organization shall not issue tax credit
certificates that total more than seven hundred fifty thousand dollars per
income tax year, and if the approved nonprofit organization administers one or
more approved projects, in addition to providing a qualifying service, then the
approved nonprofit organization shall not issue tax credit certificates for
allowable contributions to one or more approved projects that total more than
an additional seven hundred fifty thousand dollars per income tax year. The tax
credit certificate must state a unique certificate identification number, the
amount of the allowable contribution, the taxpayer's name, the last four digits
of the taxpayer's social security number or the taxpayer's full federal
employer identification number, the type of the contribution, the date the
taxpayer made the contribution, the amount of the tax credit that is authorized
for that taxpayer, and any other information that the executive director of the
department of revenue may require. Tax credit certificates shall be issued in
the order of received allowable contributions.
(d) (I)
(A) The credit allowed in subsections (3)(a) and (3)(b) of this section
shall not exceed one hundred thousand dollars per taxpayer per tax year.
(B) For
a contribution made pursuant to subsections (3)(a) or (3)(b) of this section
that is made in a cash payment, the contribution must be equal to or greater
than one hundred dollars.
(C) In
the case of a partnership, S corporation, or other similar pass-through entity,
the limitations in this subsection (3)(d) apply at the entity level.
(II) In
no event is a credit allowed pursuant to this section for contributions that
directly benefit the taxpayer. If a taxpayer receives a benefit for the
contribution, the value of the contribution is reduced by the value of the
benefit received by the taxpayer to arrive at the contribution that may be
certified for the income tax credit allowed in this section.
(III)
If the amount of the allowed credit exceeds the amount of income taxes
otherwise due on the income of the taxpayer in the income tax year for which
the credit is being claimed, the amount of the credit not used as an offset
against income taxes in that income tax year may be carried forward as a credit
against subsequent years' income tax liability for a period not exceeding five
years and must be applied first to the earliest income tax years possible. Any
credit remaining after the period may not be refunded or credited to the
taxpayer.
(4) On
or before November 1, 2022, and on or before November 1 of each year
thereafter, the division shall develop and post on the division's website a
list, including a description, of all approved nonprofit organizations and any
approved projects administered by an approved nonprofit organization to which
taxpayers may contribute during the next calendar year for the purpose of
receiving a tax credit pursuant to this section. Any modifications to the list,
including nonprofit organizations or proposed projects of an approved nonprofit
organization that are later approved, must be posted on the division's website
no later than sixty days after the modification is made. The division shall
review a proposed nonprofit organization and any proposed project of an
approved nonprofit organization for eligibility and approval as described in
subsection (5) of this section.
(5) (a)
(I) A nonprofit organization shall apply to the division for approval to
receive allowable contributions under this section, including approval of a
proposed project. The application must:
(A) Set
forth the qualifying activity that the nonprofit organization provides, and, in
addition, for a proposed project, the qualifying activity that the project will
implement;
(B) Provide
a letter of approval from the nonprofit organization's board of directors;
(C)
Provide evidence that the nonprofit organization is in good standing with the
secretary of state; and
(D)
Submit a recent audit or financial report to the division in a form that is
acceptable to the division.
(II) An
organization that has a program as set forth in section 39-30-103.5 (3)(a) that
has been approved by the Colorado economic development commission under section
39-30-103.5 is deemed approved for purposes of compliance with this section to
receive eligible contributions unless otherwise specifically disapproved by the
division so long as the organization:
(A) Is
a nonprofit;
(B)
Provides or has the intent to provide a qualifying activity;
(C) Can
provide a letter of approval from its board of directors;
(D)
Submits a recent audit or financial report to the division in a form that is
acceptable to the division; and
(E) No
later than four years from August 10, 2022, submits an application for
reapproval pursuant to subsection (5)(g) of this section.
(III)
When reviewing applications and organizations for approval pursuant to
subsections (5)(a)(I) and (5)(a)(II) of this section, with respect to a
nonprofit organization's proposed qualifying activity or activities, the
division shall consider the financial management capacity and operational
capacity of the nonprofit organization and evaluate the capability of the
nonprofit organization to enter a monitoring agreement for the purpose of the
division evaluating the efficacy of the nonprofit organization and its
qualifying activity or activities.
(b) The
division shall review applications received pursuant to subsection (5)(a) of
this section in a timely manner and in a time frame set forth in the division's
guidelines for the program. The division shall issue a notice of approval or
disapproval of a nonprofit organization, a proposed project, or both in
writing.
(c) The
division is authorized to hold hearings in order to review a nonprofit
organization's request to reconsider a decision regarding disapproval within
thirty days after the date of the disapproval notice.
(d)
Once approved, the nonprofit organization shall maintain an accounting system
and appropriate records to track contributions received by taxpayers for which
a tax credit was allowed under this section and to accurately associate the use
of the contributions with qualifying activities, an approved project, or both.
(e) The
division shall specify in program guidelines what information regarding
qualifying activities must be reported by the nonprofit organization and can
request from the nonprofit organization an audit or financial report in a form
that is acceptable to the division.
(f) (I)
No later than June 30, 2025, the division shall complete a review of every
organization and project deemed approved under subsection (5)(a)(II) of this
section, and no later than June 30, 2026, and June 30 of each year thereafter,
the division shall complete a review of every other approved nonprofit
organization and approved project to evaluate performance and compliance with
the requirements of this section. The division must review the qualifying
activities being provided and determine how the activities are addressing
current and emerging needs of individuals and families experiencing
homelessness in each approved nonprofit organization's community, or, if
applicable, each approved project's community.
(II)
The division has the authority to monitor and audit approved nonprofit
organizations and their performance and may disapprove an approved nonprofit
organization or an approved project of an approved nonprofit organization if
the approved nonprofit organization is not meeting expectations or if the
approved nonprofit organization is otherwise not in compliance with objectives
outlined in this section or program guidelines, or, if applicable, in the
project proposal. The division shall immediately notify the department of
revenue if an approved nonprofit organization or an approved project of an
approved nonprofit organization is disapproved as a result of a review or audit
in order to ensure that contributions made by taxpayers on or after the date of
disapproval are no longer eligible for the tax credit allowed in this section.
(g) An
approved nonprofit organization shall apply for reapproval with the division
every four years in the same manner provided for approval in subsection
(5)(a)(I) of this section. When applying for reapproval, the nonprofit
organization may add or remove qualifying activities in the reapproval
application. It is expected that a nonprofit organization will revise any
previously approved goals, objectives, and expected outcomes of its qualifying
activities to adjust to changes in community needs, emerging best practices,
and feedback from the division.
(6) The
division shall present an annual review of approved nonprofit organizations and
any approved projects administered by an approved nonprofit organization to the
state housing board created in section 24-32-706. The annual review must
include individual and collective outputs and outcomes of each approved
nonprofit organization described in this section and must summarize
contributions received and tax credit certificates issued for the reporting
period, including an estimate of expected contributions for the upcoming
calendar year.
(7) The
division shall develop program guidelines, with stakeholder involvement, for
the administration of this section.
(8) (a)
On or before September 30 of each calendar year, the state director of housing
or the director's designee shall transmit to the department of revenue the data
regarding income tax credits allowed pursuant to this section that are
certified or approved by the division from January 1 through June 30 of the
same calendar year.
(b) On
or before March 31 of each calendar year, the state director of housing or the
director's designee shall transmit to the department of revenue the data
regarding income tax credits allowed pursuant to this section that are
certified or approved by the division from July 1 through December 31 of the
previous calendar year.
(9)
This section is repealed, effective December 31, 2044.
Source:
L. 2022: Entire
section added, (HB 22-1083), ch. 286, p. 2046, § 1, effective August 10. L.
2024: (3)(c) and (5)(f)(I) amended, (SB 24-016), ch. 476, p. 3337, § 1,
effective August 7. L. 2026: (1)(a), (3)(a), and (9) amended and (1)(c)
added, (HB 26-1015), ch. 319, p. 1867, § 1, effective August 12.
39-22-549. Credit against tax - small
food business recovery and resilience grant program equipment - community food
consortium duties and responsibilities - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that, in accordance with section
39-21-304 (1), which requires each bill that creates a new tax expenditure to
include a tax preference performance statement as part of a statutory
legislative declaration, the general assembly hereby finds and declares that
the purposes of the tax expenditure created in subsection (3) of this section
are to:
(I)
Induce certain designated behavior by taxpayers, specifically the purchase and
use of small food business recovery and resilience grant program equipment and
the increase of activities of the community food consortium for small food
retailers and Colorado-owned and Colorado-operated farms; and
(II)
Contribute to the state's effort to improve access to and lower prices for
healthy foods in low-income and underserved areas of the state by supporting
small food retailers and small family farms.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credits in achieving the purposes specified in subsection (1)(a)(I) of this
section based on the number of the tax credits created in this section that
taxpayers claim. The department of agriculture and the department of revenue
shall provide the state auditor with any available information that would
assist the state auditor in this measurement.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Amount certain spent by the member of the consortium on completing its
duties and responsibilities" means the amount spent on pallet, pallet
break, distribution, and delivery fees that is eligible for a subsidy from the
consortium but is not otherwise covered by the consortium.
(b)
"Duties and responsibilities" means the duties and responsibilities
of the members of the consortium pursuant to section 35-1-117 (2)(a).
(c)
"Member of the consortium" means any member of the community food
consortium for small food retailers and Colorado-owned and Colorado-operated
farms created in section 35-1-117 (2)(a).
(d)
"Purchase price" means the amount actually paid by the purchaser for
the small food business recovery and resilience grant program equipment,
including charges for sales tax and freight, but not including any charges for
assembly, installation, other construction services, or permit fees.
(e)
"Purchaser" means:
(I) For
income tax years commencing before January 1, 2027, a small food retailer or
small family farm that purchases small food business recovery and resilience
grant program equipment.
(II)
For income tax years commencing on or after January 1, 2027, a qualified
distributor, small food retailer, or small family farm that purchases small
food business recovery and resilience grant program equipment.
(e.5)
"Qualified distributor" means a Colorado-owned and operated business
or nonprofit organization that:
(I) Is
subject to tax pursuant to this article 22 or that is exempt from tax pursuant
to section 39-22-112 (1);
(II)
Actively manages the aggregation, distribution, and marketing of source-identified
raw Colorado agricultural products;
(III)
Prioritizes the aggregation, distribution, and marketing of source-identified
raw Colorado agricultural products from Colorado producers to satisfy
wholesale, retail, and institutional demand; and
(IV)
Has managed the aggregation, distribution, and marketing of source-identified
raw Colorado agricultural products to a member of the consortium in the income
tax year for which the business or organization is claiming a tax credit
pursuant to this section.
(f)
"Small family farm" has the same meaning as set forth in section
35-1-117 (8)(d) for income tax years commencing before January 1, 2027. For
income tax years commencing on or after January 1, 2027, "small family
farm" means a farm that is Colorado-owned and Colorado-operated, files a
schedule F with the internal revenue service, and acts as a wholesaler or
vendor to a charitable food program, small food retailer, school, child care
center, or older adult facility that is located in or provides food to a local,
state, or federally defined "low income, low access neighborhood".
(g)
"Small food business recovery and resilience grant program equipment"
means the items listed in section 35-1-117 (3)(a)(II) and (3)(a)(IV).
(h)
"Small food retailers" has the same meaning as set forth in section
35-1-117 (8)(e) for income tax years commencing before January 1, 2027. For
income tax years commencing on or after January 1, 2027, "small food
retailers" means:
(I) An
independent, Colorado-owned, and Colorado-operated small food retail business,
defined as a food retailer that:
(A) Is
subject to tax pursuant to this article 22 or is exempt from tax pursuant to
section 39-22-112 (1);
(B) Has
five or fewer separate Colorado retail locations with less than twenty-two
thousand square feet of retail space per location;
(C)
Carries at least three categories of federally defined staple foods, as
described in the federal "Food and Nutrition Act of 2008", secs. 3
and 9; the federal "Consolidated Appropriations Act of 2017", sec.
76; and the federal "Enhancing Retailer Standards in the Supplemental
Nutrition Assistance Program", 81 Fed. Reg. 90675; and
(D) Is
located in or provides food to local, state, or federally defined low-income,
low-access neighborhoods; or
(II) Is
a farmer's market or farm-direct operation that is already or demonstrates an
intent to become SNAP and WIC authorized where allowed.
(3) (a)
Subject to the provisions of subsection (4) of this section:
(I) (A)
For income tax years commencing on or after January 1, 2024, but before January
1, 2025, any member of the food consortium is allowed a credit against the tax
imposed by this article 22 in an amount equal to eighty-five percent of the
amount certain spent by the member of the consortium on completing its duties
and responsibilities minus any amount awarded to the member of the consortium
pursuant to section 35-1-117 (2) for the completion of its duties and
responsibilities;
(B) For
income tax years commencing on or after January 1, 2025, but before January 1,
2031, any member of the food consortium is allowed a credit against the tax
imposed by this article 22 in an amount equal to seventy-five percent of the
amount certain spent by the member of the consortium on completing its duties
and responsibilities minus any amount awarded to the member of the consortium
pursuant to section 35-1-117 (2) for the completion of its duties and
responsibilities;
(II)
(A) For income tax years commencing on or after January 1, 2024, but before
January 1, 2025, any purchaser of small food business recovery and resilience
grant program equipment is allowed a credit against the tax imposed by this
article 22 in an amount equal to eighty-five percent of the purchase price of
the relevant small food business recovery and resilience grant program
equipment minus the amount of any grant awarded under the small food business
recovery and resilience grant program for the purchase of the same small food
business recovery and resilience grant program equipment;
(B) For
income tax years commencing on or after January 1, 2025, but before January 1,
2031, any purchaser of small food business recovery and resilience grant
program equipment is allowed a credit against the tax imposed by this article
22 in an amount equal to seventy-five percent of the purchase price of the
relevant small food business recovery and resilience grant program equipment
minus the amount of any grant awarded under the small food business recovery
and resilience grant program for the purchase of the same small food business
recovery and resilience grant program equipment; and
(III)
Notwithstanding subsection (3)(a)(I) and (3)(a)(II) of this section, for income
tax years commencing on or after January 1, 2027, a taxpayer is only allowed a
credit against the tax imposed by this article 22 pursuant to this section if
the credit would be in an amount equal to or greater than three hundred
seventy-five dollars.
(b) The
credit allowed pursuant to this section is for the income tax year in which a
member of the consortium spent an amount certain on completing its duties and
responsibilities or a purchaser purchases the relevant small food business
recovery and resilience grant program equipment.
(4) (a)
For income tax years commencing prior to January 1, 2027, a member of the
consortium or a purchaser of small food business recovery grant program
equipment may submit an application to the department of agriculture for the
issuance of a letter of eligibility for a tax credit certificate allowed in
this section by the deadlines established in the rules promulgated by the
department of agriculture. The application must include:
(I) A
certification that the applicant is either:
(A) A
purchaser who is a small food retailer or small family farm that purchased
small food business recovery and resilience grant program equipment; or
(B) A
member of the consortium that spent an amount certain on completing its duties
and responsibilities; and
(II)
Detailed information regarding:
(A) The
purchase price that would be incurred by a purchaser of small food business
recovery and resilience grant program equipment and the date on which the
purchase would be made; or
(B) An
itemized total of the amount certain that would be spent by a member of the
consortium on completing its duties and responsibilities, and the date or dates
on which the member of the consortium would spend the amounts.
(b) If
the department of agriculture determines that the application filed pursuant to
subsection (4)(a) of this section is complete, the department of agriculture
shall determine whether the applicant would qualify for the credit allowed
pursuant to this section if the applicant made the purchase described in the
application and the department of agriculture had not issued tax credit
certificates in excess of a total of ten million dollars for the income tax
year. If the department of agriculture approves the application, the department
of agriculture shall issue a letter of eligibility to the applicant that
indicates the amount of the tax credit that the purchaser or member of the
consortium could claim for the specified income tax year if they were to make
the purchase described in the application and if the department of agriculture
has not issued tax credit certificates in excess of a total of ten million
dollars for the income tax year.
(5) (a)
A member of the consortium or a purchaser of small food business recovery grant
program equipment shall submit an application to the department of agriculture
for the issuance of a tax credit certificate allowed in this section by the
deadlines established in the rules promulgated by the department of
agriculture. The application must include:
(I) A
certification that the applicant is either:
(A) A
purchaser who is a qualified distributor, small food retailer, or small family
farm that purchased small food business recovery and resilience grant program
equipment; or
(B) A
member of the consortium that spent an amount certain on completing its duties
and responsibilities; and
(II)
Detailed information regarding:
(A) The
purchase price incurred by a purchaser of small food business recovery and
resilience grant program equipment and the date that the purchase was made; or
(B) An
itemized total of the amount certain spent by a member of the consortium on
completing its duties and responsibilities, and the date or dates that the
member of the consortium spent the amounts.
(b) If
the department of agriculture determines that the application filed pursuant to
subsection (5)(a) of this section is complete, the department of agriculture
shall determine whether the applicant qualifies for the credit allowed pursuant
to this section. If the department of agriculture approves the application, the
department of agriculture shall issue a tax credit certificate to the applicant
that indicates the amount of the tax credit that the purchaser or member of the
consortium may claim for the specified income tax year; except that:
(I) The
total amount of tax credit certificates issued by the department of agriculture
in a given calendar year must not exceed a total of ten million dollars for
calendar years commencing before January 1, 2027, a total of five million
dollars for the calendar year commencing on January 1, 2027, and, for calendar
years commencing on or after January 1, 2028, a total of five million dollars.
(II)
For an income tax year commencing on or after January 1, 2027, the maximum
allowable credit amount for a small family farm that claims a credit pursuant
to this section is three hundred thousand dollars and is one million dollars
for any other taxpayer that claims a credit pursuant to this section.
(c) (I)
For income tax years commencing before January 1, 2027, the department of
agriculture shall issue tax credit certificates allowed in this section in an
order that accords with the rules promulgated by the department of agriculture.
The department of agriculture shall review and approve or disapprove an
application filed pursuant to subsection (5)(a) of this section within a
reasonable time, not to exceed ninety days after the filing of a completed
application.
(II)
For income tax years commencing on or after January 1, 2027, the department of
agriculture shall review and approve or disapprove an application filed
pursuant to subsection (5)(a) of this section within a reasonable time, not to
exceed one hundred fifty days after the filing of a completed application.
(6) To
claim the income tax credit allowed pursuant to this section, the purchaser or
member of the consortium shall attach a copy of the tax credit certificate to
its state income tax return. No tax credit is allowed pursuant to this section
unless the purchaser or member of the consortium provides a copy of the tax
credit certificate with its filed state income tax return. The amount of the
credit that the purchaser or member of the consortium may claim pursuant to
this section is the amount stated on the tax credit certificate. If the
purchaser is exempt from tax pursuant to section 39-22-112 (1), the purchaser
shall file a return pursuant to section 39-22-601 (7)(b).
(7) In
a sufficiently timely manner to allow the department of revenue to process
returns claiming the income tax credit allowed pursuant to this section, the
department of agriculture shall provide the department of revenue with an
electronic report of each purchaser or member of the consortium that the
department of agriculture approved for the income tax credit allowed pursuant
to this section for the preceding calendar year that includes the following
information:
(a) The
taxpayer's name; and
(b) The
taxpayer's social security number, Colorado account number, or federal employer
identification number.
(8) If
a credit authorized in this section exceeds the income tax due on the income of
the member of the consortium or purchaser for the taxable year, the excess
credit may not be carried forward and is refundable to the member of the
consortium or purchaser.
(9) The
department of agriculture and the department of revenue may promulgate rules in
accordance with article 4 of title 24 as may be necessary to effectuate the
purposes of this section.
(10)
This section is repealed, effective December 31, 2035.
Source:
L. 2023: Entire
section added, (HB 23-1008), ch. 338, p. 2029, § 5, effective August 7. L.
2026: (2)(e), (2)(f), (2)(h), (3)(a)(I)(B), (3)(a)(II)(B), IP(4)(a),
(5)(a)(I)(A), (5)(b), (5)(c), and (6) amended and (2)(e.5) and (3)(a)(III)
added, (HB 26-1289), ch. 364, p. 2197, § 10, effective June 3.
Cross
references: For
the legislative declaration in HB 23-1008, see section 1 of chapter 338,
Session Laws of Colorado 2023. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-550. Tax credit for reducing
emissions from certain lawn equipment - tax preference performance statement -
legislative declaration - definitions - report - repeal.
(1) (a)
The general assembly finds and declares that:
(I)
Gasoline-powered lawn equipment, such as lawn mowers, leaf blowers, trimmers,
and snowblowers, emits high levels of air pollutants, including nitrogen oxides
and volatile organic compounds that, together, form ozone and particulate
matter;
(II) Replacing
such gasoline-powered lawn equipment with electric-powered lawn equipment can
reduce ozone pollution; and
(III)
The purpose of the tax credit in subsection (3) of this section is to
incentivize the voluntary transition from gasoline-powered to electric-powered
lawn equipment.
(b) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure, or extends an expiring tax expenditure, to include a tax
preference performance statement as part of a statutory legislative
declaration, the general assembly further finds and declares that:
(I) The
general legislative purpose of the tax credit allowed by subsection (3) of this
section, and the general legislative purpose of its extension, is to induce
certain designated behaviors by taxpayers, specifically the purchase of
electric-powered lawn equipment; and
(II) In
order to allow the general assembly and the state auditor to measure the
effectiveness of the tax credit, the department of revenue shall submit to the
general assembly and the state auditor an annual report in accordance with
subsection (5) of this section detailing the sales of new, electric-powered
lawn equipment, as reported by taxpayers claiming the tax credit authorized
under subsection (3) of this section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Lawn equipment" means a lawn mower, leaf blower, trimmer, or
snowblower.
(b)
"Purchase price" has the meaning set forth in section 39-26-102 (7).
(c)
"Qualified retailer" means a retailer that sells lawn equipment and:
(I)
Holds a state sales tax license;
(II)
Has timely filed a monthly sales tax return showing a tax liability for at
least twelve months;
(III)
Has paid the taxes due on the monthly sales tax return;
(IV)
Has registered with the department of revenue pursuant to subsection (3)(e)(II)
of this section; and
(V) Has
not been disqualified by the department pursuant to subsection (3)(f) of this
section.
(d)
"Retailer" has the meaning set forth in section 39-26-102 (8).
(e)
"Retail sale" has the meaning set forth in section 39-26-102 (9).
(3) (a)
For income tax years commencing on or after January 1, 2024, but before January
1, 2030, a qualified retailer pursuant to subsection (3)(e)(II) of this section
is allowed a tax credit against the tax imposed pursuant to this article 22 in
an amount equal to thirty-three percent of the aggregate purchase price for all
retail sales of new, electric-powered lawn equipment that the qualified
retailer sold in the state during the tax year.
(b) In
order to qualify for the tax credit allowed under this subsection (3), the
qualified retailer shall provide to the purchaser, at the time of the retail
sale of new, electric-powered lawn equipment, a discount on the purchase price
of the lawn equipment equal to thirty percent of the purchase price and shall
show the discount as a separate item on the receipt or invoice provided to the
purchaser.
(c) To
determine whether a qualified retailer sold new, electric-powered lawn
equipment in this state, the rules of section 39-26-104 (3)(a) apply.
(d) The
qualified retailer may retain from the credit allowed in this section an
administrative fee not to exceed three percent of the purchase price of the
new, electric-powered lawn equipment sold.
(e) (I)
The qualified retailer shall electronically submit a report to the department
of revenue, on a quarterly basis and in the form and manner required by the
department, that details the number of pieces of new, electric-powered lawn
equipment sold by the qualified retailer in the reporting period for which the
qualified retailer provided a discount as described in subsection (3)(b) of
this section. The department may require the qualified retailer to include
additional information in the report.
(II)
Before selling a piece of new, electric-powered lawn equipment for which a
retailer intends to claim a credit pursuant to this section, the retailer shall
register as a qualified retailer by filing with the department of revenue a
registration statement in the form and manner that the department prescribes
and receive approval of their registration from the department.
(III)
For income tax years beginning on or after January 1, 2027, the qualified
retailer may elect advance payments of the credit allowed pursuant to this
section as specified in section 39-22-629.
(f) (I)
After the notice and hearing held in accordance with sections 24-4-104 and
24-4-105, the department may disqualify a qualified retailer if the department
determines:
(A) The
qualified retailer requested advance payment or claimed a credit with respect
to a transaction that does not qualify for the credit allowed by this section;
(B) The
qualified retailer provided false or misleading information to the department;
or
(C) The
qualified retailer no longer holds a sales tax license.
(II) A
retailer that has been disqualified pursuant to this subsection (3)(f) may not
reapply to be a qualified retailer. The department shall not approve a
registration submitted by a disqualified retailer.
(4) If
a credit authorized by this section exceeds the income tax due on the income of
the qualified retailer for the taxable year, the excess credit may not be
carried forward and must be refunded to the qualified retailer.
(5)
Pursuant to section 39-21-304 (3), notwithstanding section 24-1-136 (11)(a)(I),
and for the purpose of providing data that allows the general assembly and the
state auditor to measure the effectiveness of the tax credit created in
subsection (3) of this section, the department of revenue, on or before January
1, 2025, and on or before January 1 of each year thereafter through January 1,
2031, shall submit to the general assembly and the state auditor a report
detailing the sales of new, electric-powered lawn equipment, as reported by a
qualified retailer claiming the tax credit authorized under subsection (3) of
this section. The tax credit established in this section meets its purpose if
sales of new, gasoline-powered lawn equipment are significantly reduced within
five years after the tax credit becomes effective, as determined by the general
assembly and the state auditor pursuant to section 39-21-304 (3).
(6)
This section is repealed, effective December 31, 2036.
Source:
L. 2023: Entire
section added, (SB 23-016), ch. 165, p. 741, § 12, effective August 7. L.
2024: (2)(c)(IV) and (3)(a) amended, (HB 24-1450), ch. 490, p. 3426, § 83,
effective August 7. L. 2026: IP(1)(b), (1)(b)(I), (2)(c)(III),
(2)(c)(IV), (3)(a), (3)(e)(II), (5), and (6) amended and (2)(c)(V),
(3)(e)(III), and (3)(f) added, (HB 26-1289), ch. 364, p. 2200, § 11, effective
June 3.
Cross
references: For
the legislative declaration in HB 26-1289, see section 1 of chapter 364,
Session Laws of Colorado 2026.
39-22-551. Industrial clean energy tax
credit - tax preference performance statement - definitions - report - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided for in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain businesses or individuals by allowing an owner of an
industrial facility to receive a credit against income tax for the costs
associated with conducting industrial studies or for implementing a plan to put
into service greenhouse gas emissions reduction improvements.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1)(a) of this section
based on the information required and reported by the office pursuant to
subsection (10)(b) of this section, and based on the number and value of the
credits claimed.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Applicable percentage" means thirty percent, except as provided in
subsection (3)(b)(II) of this section.
(b)
"Certified greenhouse gas emissions reduction improvements" means
greenhouse gas emissions reduction improvements to a qualified industrial
facility that have been certified by the office as meeting the standards of the
office.
(c)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(d)
"Department" means the department of revenue.
(e)
"Greenhouse gas emissions reduction improvements" means improvements
that help to measurably reduce greenhouse gas emissions. "Greenhouse gas
emissions reduction improvements" may include one or more of the following
equipment purchases, improvements, retrofits, or investments:
(I)
Replacing fossil-fuel-powered off-road equipment such as forklifts and
construction equipment with electric equipment;
(II)
Replacing fossil-fuel-fired equipment for space or water heating or industrial
process heating with high-efficiency electric equipment;
(III)
Replacing fossil-fuel-fired or compressed air-driven industrial process
equipment with high-efficiency electric equipment;
(IV)
Placing in service advanced refrigeration systems that reduce greenhouse gas
emissions;
(V)
Placing in service electric charging infrastructure for electric vehicles at an
industrial facility;
(VI)
Placing in service waste heat recovery technology;
(VII)
Upgrading or implementing energy monitoring systems;
(VIII)
Installing high efficiency electric pumps, motors, compressors, and lighting;
(IX)
Installing variable volume or load efficiency equipment;
(X)
Installing carbon capture equipment which provides supporting information that
demonstrates a net reduction in greenhouse gas emissions when accounting for
energy-related emissions released to operate the carbon capture equipment and
provides a permanent durable carbon storage plan; except that the captured
carbon may not be used for enhanced oil recovery;
(XI)
Installing equipment used for collection of biomethane, and, for income tax
years commencing on and after January 1, 2027, installing equipment used for
utilization of biomethane;
(XII)
Replacing fossil-fuel-fired equipment with hydrogen fueled equipment;
(XIII)
Installing hydrogen fueling stations for fuel cell vehicles at industrial
facilities;
(XIV)
Converting fossil-fuel-powered pumps, compressors, and controllers to
compressed air-driven or electric-driven pumps, compressors, and controllers;
(XV)
Installing onsite energy storage;
(XVI)
Installing or upgrading to utility service feed equipment to directly support
the implementation of any of the electrification improvements set forth in this
subsection (2)(e);
(XVII)
Placing in service carbon management systems including direct air capture and
other forms of carbon dioxide removal;
(XVIII)
Material substitutions within industrial processes to reduce industrial process
greenhouse gas emissions by a minimum of fifteen percent when compared to
existing production practices;
(XVIII.5)
For income tax years commencing on or after January 1, 2026, embodied carbon
investments, which are investments in the production of eligible materials, as
defined in section 24-92-118 (2)(b), that result in the reduction of the
eligible materials' cradle-to-gate embodied emissions, as established in
policies created by the Colorado energy office, created in section 24-38.5-101,
and in consultation with the office of the state architect. To qualify as an
embodied carbon investment, an investment must result in a fifteen percent or
greater reduction in cradle-to-gate embodied emissions of the eligible
materials when compared to the eligible materials' cradle-to-gate baseline as
established in standards and guidelines created by the Colorado energy office
and in consultation with the office of the state architect. A cradle-to-gate
measurement or baseline considers the life cycle stages for a product
including, but not limited to, the raw material extraction and processing
related to the product, and the transport to the manufacturer and manufacturing
of the product.
(XIX)
Other similar purchases and improvements identified and set forth in the
standards developed by the office pursuant to subsection (4) of this section
that result in at least a twenty percent reduction in greenhouse gas emissions
when compared to current technology, equipment, or production processes being
deployed by the owner.
(f)
"Greenhouse gas emissions reduction plan" or "plan" means
project implementation plans or specifications for the proposed greenhouse gas
emissions reduction improvements to a qualified industrial facility that are
sufficiently detailed to enable the office to evaluate whether the improvements
are in compliance with the standards developed under this section and whether
the plan will measurably reduce greenhouse gas emissions at a qualified
industrial facility. The plan must include, but is not limited to, a property
address, legal description, or other specific location of the industrial
facility, and must include information on the estimated costs for the proposed
greenhouse gas emissions reduction improvements.
(g) (I)
"Industrial facility" means any real property in the state, and the
machinery or equipment on the real property, where the principal trade or
business activity is the mechanical or chemical transformation of organic or
inorganic substances into new products, characteristically using power-driven
machines and materials handling equipment.
(II)
"Industrial facility" does not include a landfill, an electric
utility subject to regulation by the public utilities commission, or an
upstream or mid-stream oil and gas operation.
(h)
"Industrial process greenhouse gas emissions" means greenhouse gas
emissions that occur as a result of the chemical or physical transformation of
process input materials.
(i)
"Industrial study" means an energy and emissions audit, a feasibility
study, a pre-front-end or a front-end engineering design study that meets or
exceeds the standards established by the office, or any other industrial
studies as outlined in program standards adopted by the office.
(j)
"Owner" means a person or developer of a project to be implemented at
a qualified industrial facility subject to tax under this article 22 who
applies for and claims the credit allowed by this section. For income tax years
commencing on and after January 1, 2027, "owner" also includes a
person or political subdivision of the state that is a developer of a project
to be implemented at a qualified industrial facility and that is exempt from
taxation under section 39-22-112 (1).
(3) Availability
of credit and amount.
(a) For
income tax years commencing on or after January 1, 2024, but prior to January
1, 2033, there shall be allowed a credit with respect to the income taxes
imposed pursuant to this article 22 to the owner of a qualified industrial
facility in an amount equal to:
(I) The
applicable percentage of the costs paid and approved by the office for
completing an industrial study during the tax year in which the credit is
claimed; except that the credit cannot be claimed in an amount exceeding one
million dollars; or
(II)
The applicable percentage of the capital costs paid by the owner, not including
the cost for design, and approved by the office for certified greenhouse gas
emissions reduction improvements that are placed in service during the tax year
in which the credit is claimed; except that the credit must be claimed in an
amount that is not less than seventy-five thousand dollars and does not exceed
eight million dollars.
(b) (I)
If the office approves the owner's industrial study or greenhouse gas emissions
reduction plan and reserves credits under subsection (6) of this section, the
office shall apply the applicable percentage of the costs paid for completing
an industrial study or the capital costs paid for greenhouse gas emissions
reduction improvements to calculate the amount of the credit that the owner
will receive for the tax year in which the industrial study is completed or the
greenhouse gas emissions reduction improvements are placed in service.
(II)
The office may on a case by case basis determine that the applicable percentage
may be increased to an amount not to exceed fifty percent upon request by an
owner for greenhouse gas emissions reduction improvements that have significant
potential to significantly advance reductions in greenhouse gas emissions but
may not be in the commercial stage of development. In evaluating such a
request, the office may use United States department of energy technology
readiness level criteria, scientific literature detailing potential
decarbonization impacts of proposed technology, or subsequent literature on
technology results to date to determine whether the requested increase of the
applicable percentage sufficiently satisfies the office's criteria to justify
the increase.
(c) An
owner that claims the credit allowed by this section cannot, for the same
greenhouse gas emission reduction improvements:
(I)
Claim the credit allowed by section 39-30-104; or
(II)
Receive grant money under the industrial and manufacturing operations clean air
grant program created in section 24-38.5-116 (3)(a).
(4) Office
to develop standards.
(a) The
office shall develop standards for the approval of industrial facilities as
qualified industrial facilities for which a tax credit under this section is
allowed to an owner.
(b) The
office shall develop standards for the approval of industrial studies, for the
approval of an industrial facility owner's greenhouse gas emissions reduction
plan, for certifying greenhouse gas emissions reduction improvements, including
verification of reduction in greenhouse gas emissions, and for reviewing the
cost certifications for the costs of the industrial study and the costs related
to the implementation of a greenhouse gas emissions reduction improvements
plan. The standards that are adopted pursuant to this subsection (4)(b), must
provide that a plan propose greenhouse gas emissions reduction improvements
that lead to direct reductions through project implementation.
(c) Any
standards developed by the office under this subsection (4) must be posted on
the office's website.
(d) The
office may annually review and update as necessary standards adopted pursuant
to this subsection (4).
(5) Application
and industrial study or plan submission.
(a) An
owner that intends to claim a credit pursuant to subsection (3)(a)(I) of this
section shall submit to the office an application on a form prescribed by the
office and any documentation that the office requires to demonstrate the
anticipated completion of an industrial study in the current or in a future tax
year, including the cost of the industrial study and the amount of credit
requested.
(b) An
owner that intends to claim a tax credit pursuant to subsection (3)(a)(II) of
this section shall submit to the office an application and plan as set forth in
the standards developed by the office. The office shall prescribe a form for
the application, which must include a place for owners to provide the following
information:
(I)
Detailed estimates of the capital costs for the proposed greenhouse gas
emissions reduction improvements;
(II)
Estimates of expected energy consumption avoided by the use of the greenhouse
gas emissions reduction improvements;
(III)
Estimated timing for the greenhouse gas emissions reduction improvements to be
placed into service;
(IV)
For carbon management projects, net reductions in greenhouse gas emissions;
(V)
Estimated dollar savings;
(VI)
Estimated dollars leveraged, including any private investment, state grant
funding, and federal grants or tax credits;
(VII)
The type and age of equipment being replaced, if applicable;
(VIII)
The type and estimated life span of new equipment, if applicable;
(IX)
The amount of credit requested; and
(X) Any
other information as specified in the standards set forth by the office.
(c) (I)
The office shall accept applications through June 30, 2024, and semi-annually
through each December 31 and June 30 thereafter, through June 30, 2032.
(II)
(A) The office shall review applications and documentation related to
industrial studies to be conducted or plans for greenhouse gas emissions
reduction improvements at a qualified industrial facility to determine that the
application, documentation, and plan, if applicable, are complete and in
compliance with the requirements of this section and the standards established
by the office.
(B) If
the office determines that the application, documentation, and plan, if
applicable, are complete and in compliance, the office shall add the
application to an evaluation pool for the application period.
(C) If
the office determines that the application is incomplete or that it does not
comply with the requirements of this section or the standards established by
the office, the office shall remove the application from the review process and
notify the owner in writing of its decision. An owner may resubmit a
disapproved application, documentation, and plan, if applicable, to be
evaluated in a future application period.
(6) Merit-based
review and reservation of credits.
(a) (I)
For each application period, the office shall conduct a merit-based evaluation
of the applications that have been placed in the evaluation pool pursuant to
subsection (5)(c)(II)(B) of this section. Before tax years beginning January 1,
2027, the office shall complete its review, and award reservations, within
ninety days after the end of the application period. For income tax years
commencing on or after January 1, 2027, the office shall complete its review,
and award reservations, within one hundred twenty days after the end of the
application period.
(II)
Based upon the totality of the factors set forth in subsection (6)(c) of this
section, the office may adjust the applicable percentage as provided in
subsection (3)(b)(II) of this section and reserve for the benefit of each owner
all, part, or none of the credit amount requested by the owner; except that the
office shall not reserve an amount in excess of the credit allowed by
subsection (3)(a) of this section, and the aggregate amount of credits reserved
for all owners may not exceed the reservation limits set forth in subsection
(8) of this section.
(III)
The office may reserve credits for the current or any future tax year based
upon the anticipated completion or in service date indicated in the
application; except that credits may not be reserved for an industrial study
completed or for greenhouse gas emissions reduction improvements placed in
service prior to the end of the application period. The office shall not
reserve tax credits for any tax year beginning on or after January 1, 2033.
(b) (I)
If the office reserves credits for the benefit of an owner under subsection
(6)(a) of this section, the office shall notify the owner of the reservation
and the amount reserved. The reservation of tax credits does not entitle the
owner to an issuance of any tax credit certificates until the owner complies
with all of the requirements specified in this section, or by the office, for
the issuance of a tax credit certificate.
(II)
The office shall notify any owner for which it reserved no credit under
subsection (6)(a) of this section of its decision in writing.
(III)
If the office reserves less than the full amount of credit requested by the
owner, the owner may submit a new application for the remaining balance up to
the amount of credit allowed by subsection (3)(a) of this section in a future
application period.
(c) (I)
In conducting the merit-based review pursuant to subsection (6)(a) of this
section, the office shall consider the factors set forth in this subsection
(6)(c) in addition to any other factors the office may establish in its
guidelines. The office may weigh the factors equally or differently.
(II)
The office shall:
(A)
Consider additional resources leveraged by the owner to conduct the industrial
study or implement the plan; and
(B)
Prioritize the location of the industrial facility that is the subject of the
industrial study or the plan, in particular if the location is in a
disproportionately impacted community or within a non-attainment area.
(III)
In addition to the factors set forth in subsection (6)(c)(II) of this section,
for an application that is requesting a reservation of credit for the credit
allowed pursuant to subsection (3)(a)(II) of this section, the office shall
also consider:
(A) The
annual greenhouse gas emissions reduction impact, considering both the total
impact and the per dollar impact for the amount of credit requested to be
reserved;
(B) Any
co-benefits of a project that will implement the plan with prioritization given
to projects that limit the amount of pollutants emitted by emerging
technologies, including projects that include electrification and use of
renewable electricity;
(C) The
readiness of a greenhouse gas emissions reduction improvement that will be implemented
by the plan; and
(D) The
innovative nature of the plan and proposed greenhouse gas emissions reduction
improvements.
(7) Proof
of compliance - audit of cost certification - issuance of tax credit
certificate.
(a) Any
owner receiving a reservation of tax credits under subsection (6) of this
section for credits allowed pursuant to subsection (3)(a) of this section shall
complete the approved industrial study or put the approved greenhouse gas
emissions reduction improvements identified in the plan in service during the
tax year for which the reservation is approved. When the approved industrial
study is complete or the approved greenhouse gas emissions reduction
improvements are placed in service, the owner shall notify the office of the
completion of the industrial study or plan and shall provide the office with a
cost certification of the costs for the approved industrial study or approved
greenhouse gas emissions reduction improvements. The cost certification must be
audited by a licensed certified public accountant that is not affiliated with
the owner. The office shall review the cost certification and verify that it
satisfies the information provided in the owner's application, including, if
applicable, the plan, within ninety days after receipt of the cost
certification. If the office determines that the industrial study is complete
or that the plan is complete and that the greenhouse gas emissions reduction
improvements have been placed in service, and the office approves the cost
certification, the office shall issue a tax credit certificate in the amount
allowed pursuant to subsection (3) of this section.
(b)
Notwithstanding subsection (7)(a) of this section, the total amount of the
initial tax credit certificate issued for an industrial study or certified
greenhouse gas emissions reduction improvement must not exceed the amount of
the tax credit reservation approved pursuant to subsection (6)(a) of this
section.
(c) If
the amount of certified costs incurred by the owner would result in an owner
being issued an amount that exceeds the amount of tax credit reserved for the
owner under subsection (6) of this section, the owner may apply to the office
for the issuance of an amount of tax credits that equals the excess. The owner
shall submit its application for issuance of such excess tax credits on a form
prescribed by the office. The office shall review the application for an
additional tax credit amount in the same manner it reviews all other
applications and in accordance with subsection (6)(a) of this section. Subject
to the availability of tax credits for the application period during which the
owner applies for the additional credit award pursuant to this subsection
(7)(c), the office may approve the application and shall issue a separate
certificate.
(8) Limit
on aggregate amount of tax credits available to be reserved.
(a) For
the application period ending June 30, 2024, and for each semiannual
application period commencing on or after July 1, 2024, but before July 1,
2028, the aggregate amount of all tax credits that may be reserved under
subsection (6)(a) of this section and awarded under subsection (7)(c) of this
section must not exceed eight million dollars. For application periods
commencing on or after July 1, 2028, but before July 1, 2032, the aggregate
amount of all tax credits that may be reserved under subsection (6)(a) of this
section must not exceed twelve million dollars.
(b)
Notwithstanding the provisions of subsection (8)(a) of this section, the office
may increase the periodic aggregate amount of tax credits available for the
application period ending June 30, 2024, and for any semiannual application
period commencing on or after July 1, 2024, but before July 1, 2028. If so
increased, the office shall decrease accordingly the amount of tax credits
available for the application periods commencing on or after July 1, 2028, but
before July 1, 2032.
(c)
Notwithstanding the provisions of subsection (8)(a) of this section, if the
aggregate amount of all tax credits reserved pursuant to subsection (6)(a) of
this section and awarded pursuant to subsection (7)(c) of this section for an
application period is less than the amount available under subsections (8)(a)
and (8)(b) of this section, then the aggregate amount of all tax credits that
may be reserved and awarded in the next application period is increased by the
unreserved and unawarded amount.
(d)
Notwithstanding the provisions of subsection (8)(a) of this section, for any
semiannual application period commencing on or after July 1, 2026, the office
may adjust the limits in subsection (8)(a) of this section as set forth in
section 39-22-522 (4)(f).
(9) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each owner to which the office has
issued a tax credit certificate, as allowed in subsection (7) of this section,
for the preceding tax year that includes the following information:
(a) The
taxpayer's name;
(b) The
amount of the credit; and
(c) The
taxpayer's social security number or the taxpayer's Colorado account number and
federal employer identification number.
(10) Guidelines.
(a) In
addition to the standards that the office is required to establish pursuant to
subsection (4) of this section, the office may establish guidelines to
implement this section. All guidelines established by the office must be posted
on the office's website.
(b) The
office shall maintain a database of any information necessary to evaluate the
effectiveness of the tax credit allowed in this section in meeting the purpose
set forth in subsection (1)(a) of this section and shall provide this
information and any other information requested, if available, to the state
auditor as part of the state auditor's evaluation of this tax expenditure
required by section 39-21-305. Information provided by the office to the state
auditor may include approved industrial studies or approved plans for
greenhouse gas emissions reduction improvements.
(11) In
order to claim the credit authorized by this section, the owner shall file the
tax credit certificate with the owner's state income tax return. The amount of
the credit that the owner may claim under this section is the amount stated on
the tax credit certificate.
(12)
(a) An owner shall submit a report to the office by the end of the first
month after the end of any income tax year in which the owner received a tax
credit under this section and shall annually submit a report for three years
thereafter verifying the greenhouse gas emissions reduction improvements are,
notwithstanding circumstances evaluated and determined by the office to be
justified, in use at the location identified in the owner's application for a
tax credit certificate and remain owned by the owner.
(b) If
an owner was allowed a credit under this section and fails to demonstrate the
greenhouse gas emissions reduction improvements are, notwithstanding
circumstances evaluated and determined by the office to be justified, in use at
the location identified in the owner's application for a tax credit certificate
or are owned by the owner in any of the three taxable years immediately
following the taxable year in which the greenhouse gas emissions reduction
improvements were placed in service, the office shall notify the department in
writing that the credit allowed in this section must be disallowed for that
owner. The owner shall add the amount of the disallowed credit to its return as
a recaptured credit for the tax year in which the credit is disallowed pursuant
to this subsection (12).
(13) If
a credit authorized by this section exceeds the income tax due on the income of
the owner for the taxable year, the excess credit may not be carried forward
and must be refunded to the owner.
(14)
This section is repealed, effective December 31, 2038.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 776, § 5, effective May 11. L.
2024: IP(2)(e), (2)(i), (2)(j), (3)(a)(II), and (3)(c) amended, (SB
24-214), ch. 191, p. 1100, § 15, effective May 17. L. 2025: IP(2)(e) and
(2)(e)(XVIII) amended and (2)(e)(XVIII.5) added, (SB 25-182), ch. 277, p. 1442,
§ 3, effective August 6. L. 2026: (2)(e)(XI), (2)(j), and (6)(a)(I)
amended and (8)(d) added, (HB 26-1289), ch. 364, p. 2201, § 12, effective June
3.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023. For the legislative declaration in SB 25-182,
see section 1 of chapter 277, Session Laws of Colorado 2025. For the
legislative declaration in HB 26-1289, see section 1 of chapter 364, Session
Laws of Colorado 2026.
39-22-552. Tax credit for expenditures
made in connection with a geothermal energy project - tax preference
performance statement - legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain businesses or individuals by providing a financial
incentive for the development of thermal energy networks and electricity
generation from geothermal sources.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the number and value of the credits claimed.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a) (I)
"Applicable amount" means, except as provided in subsection
(2)(a)(II) of this section, an amount of tax credit not to exceed thirty
percent of a qualified expenditure by an eligible taxpayer that is allowed
pursuant to this section as set by the office in accordance with subsection
(4)(c) of this section.
(II)
The office may, on a case-by-case basis, determine that the applicable amount
may be increased to an amount not to exceed fifty percent of a qualified
expenditure by an eligible taxpayer if the office determines that a geothermal
energy project has significant potential to result in geothermal electricity
production or technological demonstration of geothermal electricity production.
(b)
"Approved geothermal energy project" means a geothermal energy
project that has been approved to receive qualified expenditures by the office
pursuant to the standards developed by the office in accordance with subsection
(5) of this section.
(c)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(d)
"Department" means the department of revenue.
(e)
"Eligible taxpayer" means any of the following people or entities
that made a qualified expenditure:
(I) A
person engaged in a trade or business that is subject to tax pursuant to this
article 22;
(II) A
person or political subdivision of this state that is exempt from tax pursuant
to section 39-22-112 (1); or
(III) A
tribal government.
(f)
"Geothermal electricity project" or "project" means a
project in the state that is intended to evaluate and develop a geothermal
resource for the purpose of electricity production, that meets the standards
developed pursuant to subsection (5) of this section, and that involves any of
the following:
(I) The
exploration and development of wells;
(II)
Drilling exploration and confirmation wells;
(III)
The use of any heat extracted with produced fluids in an oil and gas operation
if the heat is only utilized to reduce emissions from the operation in the same
location as the well from which it was produced and would otherwise not be
economically feasible as a stand-alone geothermal energy project;
(IV)
Drilling injection wells;
(V)
Flow testing;
(VI)
Reservoir engineering;
(VII)
Geothermal energy storage;
(VIII)
Coproduction of geothermal energy, including for industrial uses or thermal
energy networks;
(IX)
Power generation equipment; or
(X) Studies
to identify and explore resources that may be suitable for geothermal
electricity generation and may include hydrogen generation or utilization of
direct air capture technology.
(f.5)
"Geothermal energy project" means a geothermal electricity project,
thermal energy network, or a thermal energy network study.
(g)
"Qualified expenditure" means the total monetary cost approved by the
office and expended on or after January 1, 2024, but before January 1, 2033, by
an eligible taxpayer in connection with an approved geothermal energy project
in the tax year for which the credit allowed in this section is claimed.
(h)
"Thermal energy network" has the same meaning as set forth in section
39-22-554 (2)(n).
(i)
"Thermal energy network study" means an energy and emissions scoping
study, a feasibility study, an investment grade energy audit, a detailed
engineering design, or a combination of these options that meets or exceeds the
standards established by the office.
(j)
"Tribal government" means a federally recognized Indian tribe,
including its business operations and wholly owned entities, with reservation
lands within the state of Colorado or operating within the state.
(3) (a)
For income tax years commencing on or after January 1, 2024, but before January
1, 2033, an eligible taxpayer that makes a qualified expenditure is allowed a
credit against the tax imposed under this article 22 in the applicable amount
and subject to the limitations set forth in subsection (3)(b) of this section.
(b) An
eligible taxpayer is not allowed a tax credit pursuant to this section in an
aggregate amount of more than five million dollars in tax credits for all
income tax years for which the tax credit may be claimed pursuant to this
section per approved geothermal energy project.
(4) (a)
An eligible taxpayer shall submit an application in a form and manner
determined by the office for a tax credit certificate for the credit allowed in
this section. The application must include:
(I)
Information sufficient for the office to evaluate the geothermal energy project
for which the eligible taxpayer proposes making an expenditure and to approve
the project if the project has not been previously approved by the office;
(II)
Information related to the specific costs associated with the proposed
expenditure;
(III)
Estimated timing for the proposed expenditure to be made by the eligible
taxpayer;
(IV)
The amount of credit requested; and
(V) Any
other information as specified in the standards set forth by the office.
(b) (I)
The office shall accept applications through June 30, 2024, and semi-annually
through each December 31 and June 30 thereafter, through June 30, 2032.
(II)
(A) The office shall review applications and documentation provided pursuant
to subsection (4)(a) of this section to determine whether the application and
documentation are complete and in compliance with the requirements of this
section and the standards established by the office.
(B) If
the office determines that the application and documentation are complete and
in compliance with the requirements of this section and the standards
established by the office, the office shall add the application to the
evaluation pool for the application period.
(C) If
the office determines that the application or documentation, or both, are not
complete or do not comply with the requirements of this section or the
standards established by the office, the office shall remove the application
from the review process and notify the taxpayer in writing of its decision. A
taxpayer may resubmit a disapproved application and documentation to be
evaluated in a future application period.
(c) (I)
(A) For each application period, the office shall conduct a merit-based
evaluation of the application in the evaluation pool. The office shall complete
its review and award reservations within ninety days after the end of the
application period.
(B)
Based upon the totality of the factors set forth in subsection (4)(d) of this
section and based on considerations required for geothermal energy projects as
set forth in subsection (5) of this section, which the office may weigh equally
or differently, the office shall determine an applicable amount of credit that
may be reserved for the benefit of the eligible taxpayer which may be all,
part, or none of the credit amount requested in the eligible taxpayer's
application; except that the office shall not reserve an amount in excess of
the limitations set forth in subsection (3)(b) of this section, and, except as
provided in subsection (4)(f) of this section, the aggregate amount of credits
reserved for all owners must not exceed thirty-five million dollars for all
taxpayers in all years the credit is allowed.
(C) The
office may reserve credits for the current or any future tax year based upon
the anticipated timing of the expenditure; except that credits may not be
reserved for an expenditure that is made prior to the end of the application
period. The office shall not reserve credits for any tax year beginning on or
after January 1, 2033.
(II)
(A) If the office reserves credits for the benefit of an eligible taxpayer
pursuant to subsection (4)(c)(I) of this section, the office shall notify the
owner of the reservation and the amount reserved.
(B) The
office shall notify any taxpayer for which it reserved no credit pursuant to
subsection (4)(c)(I) of this section of its decision in writing.
(C) If
the office reserves less than the full amount of credit requested by the
taxpayer, the taxpayer may submit a new application for the remaining balance
up to the limitation of the credit set forth in subsection (3)(b) of this
section.
(d) In
conducting the merit-based review pursuant to subsection (4)(c) of this
section, the office shall consider the following factors in addition to any
other factors that the office may establish in its standards:
(I) The
workforce development and geothermal sector growth that the expenditure in the
project will promote, including supporting workforce transition;
(II)
Whether the project the expenditure is made in connection with demonstrates
effective and unique technology and circumstances that are supported by public
outreach and education;
(III)
Demonstration of community resilience through utilization of geothermal energy
in support of building heating and cooling decarbonization or enhancement of
electric grid resiliency, including for dispatchability and energy storage,
especially for rural or isolated communities; and
(IV)
Whether the project the expenditure is made in connection with serves a
disproportionately impacted community or a just transition community or is
within a non-attainment area.
(e) (I)
The reservation of tax credits does not entitle an eligible taxpayer to an
issuance of any credits until the eligible taxpayer provides the office with
any documentation required by the office and a cost certification of the
expenditure made in connection with an approved geothermal energy project
during the tax year in which the reservation is approved. The cost
certification must be audited by a licensed public accountant that is not
affiliated with the eligible taxpayer. The office shall review the cost
certification to verify that it satisfies the information provided in the
eligible taxpayer's application. If the office determines that the eligible
taxpayer made a qualified expenditure, the office shall issue a tax credit
certificate in the applicable amount.
(II) If
the applicable amount of qualified expenditures made by the eligible taxpayer
is less than the amount reserved pursuant to subsection (4)(c) of this section,
the office may reserve the excess credit for the benefit of the eligible
taxpayer for a future tax year or reserve the excess for the benefit of another
applicant as set forth in subsection (4)(c) of this section; except that the
office shall not reserve credits for any tax year beginning on or after January
1, 2033.
(f) (I)
Beginning July 1, 2026, the office may increase the limit on the aggregate
amount of credits reserved for all owners set forth in subsection (4)(c)(I)(B)
of this section to the extent of the excess of the aggregate amount of credit
available pursuant to section 39-22-551 (8)(b) over the amount of credits
reserved or awarded by the office pursuant to section 39-22-551 (6)(a) or
(7)(c), respectively. The office shall decrease accordingly the aggregate
amount of credit available pursuant to section 39-22-551 (8)(b).
(II)
Beginning July 1, 2026, the office may increase the aggregate amount of credit
available pursuant to section 39-22-551 (8)(b) by any amount not reserved or
allowed pursuant to this subsection (4). The office shall decrease accordingly
the limit on the aggregate amount of credits reserved for all owners set forth
in subsection (4)(c)(I)(B) of this section.
(5) The
office shall develop standards for the implementation of the tax credit allowed
pursuant to this section. Any standards developed by the office must be posted
on the office's website. At a minimum, the standards must provide for the
evaluation and approval of geothermal energy projects and require the office to
consider whether the project:
(a)
Demonstrates technology to further the adoption of clean, firm carbon-free
electricity derived from geothermal energy in the state;
(b)
Supports replicable, cost-effective reduction outcomes to stimulate the
geothermal sector or otherwise expand geothermal energy capacity in the state;
and
(c)
Directly, or through technological demonstration evaluated and approved by the
office, will lead to measurable greenhouse gas reduction outcomes for the
state.
(6) (a)
The office shall maintain a database of any information necessary to evaluate
the effectiveness of the tax credit allowed in this section in meeting the
purpose set forth in subsection (1)(a) of this section and shall provide such
information, and any other information that may be needed, if available, to the
state auditor as part of the state auditor's evaluation of this tax expenditure
required by section 39-21-305.
(b) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each eligible taxpayer to which the
office issued a tax credit certificate for the preceding tax year that includes
the following information:
(I) The
taxpayer's name;
(II)
The amount of the credit; and
(III)
The taxpayer's social security number or the taxpayer's Colorado account number
and federal employer identification number.
(7) An
eligible taxpayer that claims the credit allowed by this section may not claim
the credit allowed by section 39-30-104 for the same project.
(8) In
order to claim the credit authorized by this section, an eligible taxpayer
shall file the tax credit certificate with the qualified entity's state income
tax return and, if the eligible taxpayer is exempt from tax pursuant to section
39-22-112 (1), the eligible taxpayer shall file a return pursuant to section
39-22-601 (7)(b). The amount of the credit that the eligible taxpayer may claim
pursuant to this section is the amount stated on the tax credit certificate.
(9) If
a credit authorized in this section exceeds the income tax due on the income of
the eligible taxpayer for the taxable year, the excess credit may not be
carried forward and must be refunded to the eligible taxpayer.
(10)
This section is repealed, effective December 31, 2038.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 785, § 6, effective May 11. L.
2024: (1)(a), (2)(e), IP(2)(f), (2)(f)(VIII), and (2)(f)(IX) amended and
(2)(f)(X), (2)(f.5), (2)(h), (2)(i), and (2)(j) added, (SB 24-214), ch. 191, p.
1101, § 16, effective May 17. L. 2026: (4)(c)(I)(B) and (4)(e) amended
and (4)(f) added, (HB 26-1289), ch. 364, p. 2202, § 13, effective June 3.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-553. Geothermal electricity
generation production tax credit - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain businesses or individuals by providing a financial
incentive for production of geothermal electricity generation and related
infrastructure.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the information required to be maintained by and reported to the state
auditor by the office pursuant to subsection (4)(b)(I) of this section and
based on the number and value of the credits claimed.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(b)
"Department" means the department of revenue.
(c)
"Qualified entity" means any of the following people or entities that
produce electricity derived from geothermal energy for sale or use:
(I) A
person engaged in a trade or business that is subject to tax pursuant to this
article 22;
(II) A
person or political subdivision of this state that is exempt from tax pursuant
to section 39-22-112 (1); or
(III) A
tribal government.
(d)
"Tribal government" means a federally recognized Indian tribe,
including its business operations and wholly owned entities, with reservation
lands within the state of Colorado or operating within the state.
(3) For
income tax years commencing on or after January 1, 2024, but before January 1,
2033, a qualified entity is allowed a credit against the income taxes imposed
by this article 22 in an amount equal to three one-thousandths of a dollar per
kilowatt hour of geothermal electricity that is produced by the qualified
entity in the state in the tax year. In order to claim the credit, the
qualified entity shall apply for and receive a tax credit certificate from the
office pursuant to subsection (4) of this section.
(3.5)
The office shall annually review and evaluate the effectiveness of the tax
credit and may modify the amounts set forth in subsection (3) of this section.
The office shall maintain the current applicable tax credit on its website and
shall provide the applicable tax credit in writing to the department no later
than December 31, 2024, and each December 31 thereafter through December 31,
2031.
(4) (a)
A qualified entity shall submit an application to the office for a tax credit
certificate to claim the tax credit allowed by this section on a form and in a
manner prescribed by the office. The application must include sufficient
information to allow the office to determine that the applicant is a qualified
entity and to certify the amount of the tax credit for which the tax credit
certificate is applied.
(b) (I)
The office shall maintain a database of any information necessary to evaluate
the effectiveness of the tax credit allowed by this section in meeting the
purpose set forth in subsection (1)(a) of this section, and shall provide such
information, and any other information that may be needed, if available, to the
state auditor as part of the state auditor's evaluation of this tax expenditure
pursuant to section 39-21-305.
(II)
The office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified entity to which the
office issues a tax credit certificate for the preceding tax year that includes
the following information:
(A) The
taxpayer's name;
(B) The
amount of the credit; and
(C) The
taxpayer's social security number or the taxpayer's Colorado account number and
federal employer identification number.
(5) In
order to claim the credit authorized by this section, the qualified entity
shall file the tax credit certificate with the qualified entity's state income
tax return and, if the qualified entity is exempt from tax pursuant to section
39-22-112 (1), the qualified entity shall file a return pursuant to section
39-22-601 (7)(b). The amount of the credit that the qualified entity may claim
pursuant to this section is the amount stated on the tax credit certificate.
(6) A
qualified entity that claims the credit allowed by this section may not claim
the credit allowed by section 39-30-104 for the same project.
(7) If
a credit authorized in this section exceeds the income tax due on the income of
the qualified entity for the taxable year, the excess credit may not be carried
forward and must be refunded to the qualified entity.
(8)
This section is repealed, effective December 31, 2038.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 790, § 7, effective May 11. L.
2024: (2)(c) and (3) amended and (2)(d) and (3.5) added, (SB 24-214), ch.
191, p. 1102, § 17, effective May 17.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023.
39-22-554. Heat pump technology and
thermal energy network tax credit - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain businesses or individuals by providing a financial
incentive for the installation of heat pump technology and the use of heat pump
technology and thermal energy networks.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the number and value of the credits claimed.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a) (I)
"Air-source heat pump system" means a system that:
(A) Is
certified pursuant to the federal environmental protection agency's energy star
program;
(B)
Repealed.
(C) Is
listed in the Air-conditioning, Heating, and Refrigeration Institute directory
of certified product performance as a matched system;
(D)
Conforms to all applicable municipal, state, and federal codes, standards,
regulations, and certifications; and
(E) Is
installed in accordance with the manufacturer's specifications.
(II)
"Air-source heat pump system" may include supplemental heat so long
as:
(A) The
air-source heat pump is used as the primary source of a building's heat and is
designed to supply at least eighty percent of total annual heating for the
building; and
(B) The
system is capable of distributing produced heat to all conditioned areas of the
building.
(III)
Repealed.
(b)
"Applicable percentage" means a percentage annually established by
the office as specified in subsection (4) of this section.
(c) (I)
"Campus" means a collection of two or more buildings that are owned
and operated by the same person, that have a shared purpose and function as a
single property, that do not lease space to tenants, and that do not provide
energy or heat services for a fee.
(II)
"Campus" includes two or more of the buildings that comprise the
capitol complex, as defined in section 24-82-101 (3)(f).
(c.5)
"Cold-climate heat pump" means a type of air-source heat pump system
that:
(I)
Meets the qualification criteria of the federal environmental protection
agency's Energy Star program's cold-climate heat pump designation or meets the
highest tier of the Consortium for Energy Efficiency's northern air-source heat
pump specifications, not including an advanced tier;
(II) Is
installed with controls that set a crossover temperature specified by
guidelines established by the office pursuant to subsection (7) of this
section;
(III)
Conforms to all applicable municipal, state, and federal codes, standards,
regulations, and certifications;
(IV) Is
installed in accordance with the manufacturer's specifications; and
(V) Is
listed in the Air-conditioning, Heating, and Refrigeration Institute directory
of certified product performance as a matched system.
(d)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(d.5)
"Crossover temperature" means the point that a heat-pump-based HVAC
system switches either partially or fully from the heat pump to a supplementary
heating source.
(e)
"Department" means the department of revenue.
(f)
"Eligible taxpayer" means a taxpayer that meets the requirements for
and is included on the list of eligible taxpayers described in subsection (5)
of this section.
(g) (I)
"Ground-source heat pump system" means a system that:
(A) Is
certified pursuant to the federal environmental protection agency's energy star
program;
(B)
Conforms to all applicable municipal, state, and federal codes, standards,
regulations, and certifications;
(C) Has
blowers that are high-efficiency motors that meet or exceed efficiency levels
listed in the National Electrical Manufacturers Association MG 1-1993
publication;
(D)
Complies with all state and local drinking water guidelines and regulations and
public water system requirements; and
(E) Is
installed in accordance with the manufacturer's specifications.
(II)
"Ground-source heat pump system" may include supplemental heat so
long as:
(A) The
ground-source heat pump is used as the primary source of a building's heat and
is designed to supply at least eighty percent of total annual heating for the
building; and
(B) The
system is capable of distributing produced heat to all conditioned areas of the
building.
(III) and
(IV) Repealed.
(g.5)
"Heat pump" means an electrically powered mechanical device that uses
the refrigeration cycle to transfer thermal energy from one location to
another.
(h)
"Heat pump technology" means an air-source heat pump system,
ground-source heat pump system, water-source heat pump system, variable
refrigerant flow heat pump system, any combination of these systems, or a heat
pump water heater.
(i) (I)
"Heat pump water heater" means an electric water heater that uses
heat pump technology to transfer heat from the surrounding air to water in a
tank and that is certified pursuant to the federal environmental protection
agency's Energy Star program.
(II)
"Heat pump water heater" may include:
(A) An
electric resistance heating element; and
(B)
Mechanical and electrical equipment central to the operation of a heat pump
water heater, including an upgraded electrical panel if necessary.
(i.5)
Repealed.
(j)
"List" means the list of eligible taxpayers created by the office as
specified in subsection (5) of this section.
(k)
"Multifamily property" means a building with multiple separate
housing units for residential inhabitants including a residential building that
is a duplex, triplex, or multi-structure of four or more units.
(l)
"Taxpayer" means a person subject to tax pursuant to this article 22
or a person or political subdivision of this state that is exempt from tax
pursuant to section 39-22-112 (1).
(m) (I)
"Thermal energy" means piped, noncombustible fluids used for adding
or removing heat from buildings for the purpose of efficient building
temperature control and domestic hot water, including space heating and cooling
and refrigeration.
(II)
"Thermal energy" includes methods of exchanging the piped,
noncombustible fluids through the ground, wastewater treatment facilities, or
other sources that achieve desired fluid temperatures; except that any source
of thermal energy for this purpose must:
(A) Not
cause incremental greenhouse gas emissions or rely on increased, long-term
combustion of fossil fuels; and
(B) Be
evaluated by the office to protect against increased emissions of harmful
co-pollutants, negative impacts to communities including to disproportionately
impacted communities, as defined in section 24-4-109 (2)(b)(II), and the risk
of stranded assets, if the thermal energy is from any industrial source
including a system for which the primary purpose is to generate electricity,
including any process involving engine-driven generation.
(n)
"Thermal energy network":
(I)
Means all real estate, fixtures, and personal property that are operated,
owned, used, or intended to be used for, in connection with or to facilitate, a
distribution infrastructure project that supplies thermal energy to two or more
buildings that are not a campus and that assists in reducing greenhouse gas
emissions in the state;
(II)
Consists of pipe loops between multiple buildings and energy sources carrying
piped, noncombustible fluids at the desired thermal temperature;
(III)
Includes a network that can be used for heating, cooling, and other building
services; and
(IV)
May also be known as a geothermal exchange district, networked geothermal
system, geoexchange system, geogrid system, community geothermal heating and
cooling district, or geothermal heating district.
(o)
"Thermal energy system" includes a geothermal system or other method
of exchanging the piped, noncombustible fluids through the ground, wastewater
treatment facilities, or other sources of thermal energy that achieve desired
fluid temperatures.
(p) (I)
"Variable refrigerant flow heat pump system" means a system that:
(A) Is
certified pursuant to the federal environmental protection agency's energy star
program;
(B)
Conforms to all applicable municipal, state, and federal codes, standards,
regulations, and certifications;
(C) Has
blowers that are high-efficiency motors that meet or exceed efficiency levels
listed in the National Electrical Manufacturers Association MG 1-1993
publication;
(D)
Complies with all state and local drinking water guidelines and regulations and
public water system and wastewater system requirements; and
(E) Is
installed in accordance with the manufacturer's specifications.
(II)
"Variable refrigerant flow system" may include supplemental heat so
long as:
(A) The
variable refrigerant flow system is used as the primary source of a building's
heat and is designed to supply at least eighty percent of the total annual
heating for the building; and
(B) The
system is capable of distributing produced heat to all conditioned areas of the
building.
(III)
Repealed.
(q) (I)
"Water-source heat pump system" means a system that:
(A) Is
certified pursuant to the federal environmental protection agency's Energy Star
program;
(B)
Conforms to all applicable municipal, state, and federal codes, standards,
regulations, and certifications;
(C) Has
blowers that are high-efficiency motors that meet or exceed efficiency levels
listed in the National Electrical Manufacturers Association MG 1-1993
publication;
(D)
Complies with all state and local drinking water guidelines and regulations and
public water system and wastewater system requirements; and
(E) Is
installed in accordance with the manufacturer's specifications.
(II)
"Water-source heat pump system" may include supplemental heat so long
as:
(A) The
water-source heat pump is used as the primary source of a building's heat and
is designed to supply at least eighty percent of the total annual heating for
the building; and
(B) The
system is capable of distributing produced heat to all conditioned areas of the
building.
(III)
Repealed.
(3) (a)
For income tax years commencing on or after January 1, 2024, but before January
1, 2033, an eligible taxpayer that installs heat pump technology in a building
in the state, on a campus in the state, or develops, through purchase and
installation of necessary equipment, a thermal energy network in the state is
allowed a credit against the tax imposed under this article 22 in an amount set
forth in subsection (3)(c) of this section in the tax year that the heat pump
technology or thermal energy network is placed into service.
(b) In
order to qualify for the tax credit allowed under this section the eligible
taxpayer shall provide a discount from the amount charged for the installation
of heat pump technology or a thermal energy network in an amount equal to the
amount of the credit set forth in subsection (3)(c) of this section minus the
applicable percentage of the credit, and shall show the discount as a separate
item on the receipt or invoice; except that the requirement in this subsection
(3)(b) does not apply to an eligible taxpayer who installs their own heat pump
technology or thermal energy network.
(c)
Subject to the modifications set forth in subsection (3)(d) of this section and
the annual review required pursuant to subsection (3)(e) of this section and
except as otherwise provided in subsection (3)(f) of this section, the amount
of the credit allowed pursuant to this section is calculated as follows:
(I) For
the installation of an air-source heat pump system or for a variable
refrigerant flow heat pump system:
(A) For
tax years commencing on or after January 1, 2024, but before January 1, 2026,
one thousand five hundred dollars;
(B) For
tax years commencing on or after January 1, 2026, but before January 1, 2029,
one thousand dollars; and
(C) For
tax years commencing on or after January 1, 2029, but before January 1, 2033,
five hundred dollars;
(II)
For the installation of a ground-source heat pump system, water-source heat
pump system, a combined air-source and ground-source heat pump system, a
combined water-source and ground-source heat pump system, a combined variable
refrigerant flow and ground-source heat pump system, or a combined variable
refrigerant flow and water-source heat pump system:
(A) For
tax years commencing on or after January 1, 2024, but before January 1, 2026,
three thousand dollars;
(B) For
tax years commencing on or after January 1, 2026, but before January 1, 2029,
two thousand dollars; and
(C) For
tax years commencing on or after January 1, 2029, but before January 1, 2033,
one thousand dollars; and
(III)
For the installation of a heat pump water heater:
(A) For
tax years commencing on or after January 1, 2024, but before January 1, 2026,
five hundred dollars; and
(B) For
tax years commencing on or after January 1, 2026, but before January 1, 2033,
two hundred fifty dollars.
(d)
Notwithstanding the amounts set forth in subsection (3)(c) of this section, the
amount of the credit allowed by this section may be modified as follows:
(I) For
heat pump technology installed at a multifamily property, unless the heat pump
technology is installed for an individual unit by the eligible taxpayer for use
by the occupant of the individual unit, the amount of the credit is the amount
of the credit permitted pursuant to subsection (3)(c) of this section
multiplied by the number of units in the multifamily property that will utilize
the heat pump technology;
(II)
For a nonresidential building, the amount of the credit is the amount of the
credit permitted pursuant to subsection (3)(c) of this section multiplied by
the number of increments of four tons of heating capacity; and
(III)
For a thermal energy network or for a campus, the amount of the credit is the
amount of the credit permitted pursuant to subsection (3)(c) of this section
multiplied by the total number of residential buildings and multifamily
property units networked in a single system, plus the credit determined for
each nonresidential building networked in the system pursuant to subsection
(3)(d)(II) of this section.
(e) The
office shall annually review and evaluate the effectiveness of the tax credits
and may, for the subsequent tax year:
(I)
Modify the amounts set forth in subsection (3)(c) of this section; and
(II)
Establish, modify, or remove limits on the credits calculated pursuant to
subsection (3)(d) of this section.
(f) (I)
If the June 2025 revenue forecast, as prepared by either legislative council
staff or the office of state planning and budgeting, projects that state
revenues, as defined in section 24-77-103.6 (6)(c), will not increase by at
least four percent for the next fiscal year, the amount of the credit allowed
pursuant to subsection (3)(c)(I)(B), (3)(c)(I)(C), (3)(c)(II)(B),
(3)(c)(II)(C), or (3)(c)(III)(B) of this section, as may be modified by
subsections (3)(d) and (3)(e) of this section, for any tax year commencing in
the calendar year that begins during said next fiscal year is reduced by fifty
percent if the heat pump technology is installed at an existing residential or
nonresidential building; except that if the amount of the reduced credit is equal
to or less than two hundred fifty dollars, then no credit is available for that
income tax year.
(II)
This subsection (3)(f) is repealed, effective December 31, 2031.
(4) An
eligible taxpayer may retain an applicable percentage of the amount of the tax
credit allowed under subsection (3)(c) of this section to support the
industry-wide adoption and deployment of heat pump technologies in the state.
The office shall annually determine the applicable percentage, which must be
the same for each eligible taxpayer, pursuant to guidelines established by the
office. The office shall maintain the current applicable percentage on its
website and shall provide the applicable percentage in writing to the
department no later than December 31, 2023, and each December 31 thereafter
through December 31, 2031.
(5) (a)
The office shall create, and update at least annually, a list containing the
names and contact information of eligible taxpayers. To become an eligible
taxpayer, and be included on the list described in this subsection (5), a
taxpayer shall demonstrate to the office that the taxpayer and any of its
employees who will be installing heat pump technology or thermal energy
networks:
(I) Are
licensed as required by the state;
(II)
Are knowledgeable of and agree to follow the relevant system requirements set
forth in subsections (2)(a), (2)(c.5), (2)(g), (2)(h), (2)(i), (2)(m), (2)(n),
(2)(p), and (2)(q) of this section;
(III)
Repealed.
(III.5)
Have received training pursuant to the guidelines issued by the office pursuant
to subsection (7) of this section;
(IV)
Will, where applicable, ensure that all piping for a split system is installed
by technicians certified to the NITC R78 brazing procedure and trained in the
safe handling of flammable refrigerants; and
(V)
Will meet any additional standards established by the office in its guidelines.
(b) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section,
annually provide a secure electronic copy of the list described in subsection
(5)(a) of this section to the department that includes the social security
number or Colorado account number and federal employer identification number of
each eligible taxpayer.
(c) The
office shall maintain a current copy of the list on its website.
(d) (I)
Every eligible taxpayer shall keep and maintain for a period of four years such
books and records as may be necessary to determine that:
(A) It
is an eligible taxpayer;
(B) It
and any of its employees who will be installing heat pump technology or thermal
energy networks meet the requirements described in subsection (5)(a) of this
section;
(C) The
credit it claimed pursuant to this section was for the installation of heat
pump technology or thermal energy networks in this state; and
(D) The
amount of the credit was properly calculated under subsection (3) of this
section.
(II)
(A) The office shall periodically examine a sample of the eligible taxpayers
on the list described in this subsection (5) to substantiate that the eligible
taxpayers are meeting the office's standards and properly claiming the credit
allowed by this section. Every eligible taxpayer shall produce the books and
records described in subsection (5)(d)(I) of this section for examination at
any time by the office.
(B) If
the office determines that an eligible taxpayer is no longer meeting the
standards, the office shall notify the taxpayer in writing that they are no
longer eligible, remove the ineligible taxpayer from the list, update the list
on its website, and promptly notify the department in writing of its decision.
(C) If
the office determines that a taxpayer was not eligible for all or part of the
credit claimed, the office shall notify the department in writing of its
decision. The department shall issue the taxpayer a notice of deficiency for
the unpaid tax owed, together with applicable penalties and interest, and
proceed to collect the deficiency in the same manner as other tax deficiencies.
(6) The
office shall maintain a database of any information necessary to evaluate the
effectiveness of the tax credit allowed in this section in meeting the purpose
set forth in subsection (1)(a) of this section, and shall provide such
information, and any other information that may be needed, to the state auditor
as part of the state auditor's evaluation of this tax expenditure pursuant to
section 39-21-305.
(7) The
office may establish guidelines to implement this section. All guidelines
established by the office must be posted on the office's website.
(8) If
a credit authorized by this section exceeds the income tax due on the income of
the eligible taxpayer for the taxable year, the excess credit may not be
carried forward and must be refunded to the eligible taxpayer or the installer.
(9)
This section is repealed, effective December 31, 2038.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 792, § 8, effective May 11. L.
2024: (2)(a)(I)(B), (2)(a)(III), (2)(g)(III), (2)(g)(IV), (2)(p)(III),
(2)(q)(III), and (5)(a)(III) repealed, (2)(a)(I)(C), (2)(g)(I)(C),
(2)(g)(I)(D), (2)(p)(I)(C), (2)(p)(I)(D), (2)(q)(I)(C), (2)(q)(I)(D),
IP(3)(c)(I), (3)(d)(II), (3)(e), (5)(a)(II), (5)(a)(V), and (5)(d)(II)(A)
amended, and (2)(a)(I)(D), (2)(a)(I)(E), (2)(c.5), (2)(d.5), (2)(g)(I)(E),
(2)(i.5), (2)(p)(I)(E), (2)(q)(I)(E), and (5)(a)(III.5) added, (SB 24-214), ch.
191, p. 1103, § 18, effective May 17. L. 2026: (3)(f) amended, (HB
26-1289), ch. 364, p. 2203, § 14, effective June 3; (2)(g.5) added and (2)(i.5)
repealed, (SB 26-169), ch. 311, p. 1815, § 62, effective August 12.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-555. Electric bicycle tax credit
- tax preference performance statement - legislative declaration - definitions
- repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers, specifically the purchase of electric
bicycles, and to provide tax relief to certain businesses, specifically
retailers, that provide a discount on the sale of an electric bicycle.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the information required to be maintained by and reported to the state
auditor by the office and the department pursuant to subsection (4)(b) of this
section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(b)
"Department" means the department of revenue.
(c)
"Electric bicycle" has the same meaning as "electrical assisted
bicycle" as set forth in section 42-1-102 (28.5). "Electric
bicycle" includes an electric adaptive bicycle.
(d)
"Purchase price" has the same meaning as set forth in section
39-26-102 (7).
(e)
"Qualified electric bicycle" means an electric bicycle that satisfies
the standards for approval developed by the Colorado energy office pursuant to
subsection (4)(a)(I) of this section.
(f)
"Qualified purchaser" means a person who is a resident of the state
and who has not previously purchased a qualified electric bicycle that was
discounted by a qualified retailer claiming a tax credit allowed by this
section for the retail sale in the same income tax year.
(g)
"Qualified retailer" means a retailer that sells qualified electric
bicycles and:
(I)
Holds a state sales tax license;
(II)
Has timely filed a monthly sales tax return showing a tax liability for at
least twelve months;
(III)
Has paid the taxes due on the monthly sales tax return;
(IV)
Has registered with the department pursuant to subsection (3)(e)(III) of this section;
and
(V) Has
not been disqualified by the department pursuant to subsection (4)(c) of this
section.
(h)
"Retailer" has the same meaning as set forth in section 39-26-102
(8).
(3) (a)
Except as otherwise provided in subsection (6) of this section, for income tax
years commencing on or after January 1, 2024, but before January 1, 2033, a
qualified retailer is allowed a credit against the tax imposed pursuant to this
article 22 in an amount equal to five hundred dollars for each retail sale of
new qualified electric bicycles sold in the state during the income tax year to
a qualified purchaser; except that for the income tax year commencing on
January 1, 2024, the credit is allowed only for retail sales made on or after
April 1, 2024, but on or before December 31, 2024.
(b) In
order to qualify for the tax credit allowed pursuant to this section, the
qualified retailer shall provide to the qualified purchaser at the time of the
retail sale of the new qualified electric bicycle a discount on the purchase
price of the qualified electric bicycle equal to the lesser of four hundred
fifty dollars or the purchase price and shall show the discount as a separate
item on the receipt or invoice provided to the qualified purchaser. Except as
otherwise provided in subsection (4)(a)(II) of this section, the qualified
retailer shall, at the time of the retail sale, collect from a purchaser an
affidavit on forms prescribed by the office affirming that the purchaser is a
qualified purchaser.
(c) To
determine whether a qualified retailer sold new qualified electric bicycles in
the state, the rules set forth in section 39-26-104 (3)(a) apply.
(d) The
qualified retailer may retain from the credit allowed in this section an
administrative fee not to exceed fifty dollars for providing the discount.
(e) (I)
The qualified retailer shall electronically submit a report to the department
on a quarterly basis in a form and manner required by the department that
details the number of new qualified electric bicycles sold by the qualified
retailer in the reporting period for which the qualified retailer provided a
discount as described in subsection (3)(b) of this section, and that includes
any other information the executive director of the department may require. The
qualified retailer shall submit with the quarterly report required by this
subsection (3)(e)(I) the affidavits from qualified purchasers that the
qualified retailer is required to collect pursuant to subsection (3)(b) of this
section and the office shall inspect the affidavits to determine that retail
sales have been made to qualified purchasers.
(II)
For income tax years commencing on or after January 1, 2025, the qualified
retailer may elect advance payments of the credit allowed pursuant to this
section as specified in section 39-22-629.
(III)
Prior to selling a qualified electric bicycle for which a retailer intends to
claim a credit pursuant to this section, the retailer shall:
(A)
Register as a qualified retailer by filing with the department a registration
statement in the form and manner prescribed by the department and receive
approval of their registration from the department; and
(B)
Provide the office detailed information as the office may require regarding
each model of qualified electric bicycle the retailer intends to sell for the
credit allowed by this section. The office may require a qualified retailer to
periodically update the information required by this subsection (3)(e)(III)(B).
(IV) A
qualified retailer may authorize the office to publicize the qualified
retailer's intention to sell qualified electric bicycles pursuant to this
section on the office's website.
(4) (a)
(I) The office shall develop standards for determining allowable electric
bicycle manufacturers for purposes of determining the type of electric bicycle
that is a qualified electric bicycle eligible for the tax credit allowed
pursuant to this section. The office shall consider the design and manufacture
of allowable electric bicycles and certification of allowable electric bicycles
for compliance with consensus safety standards, such as the ANSI/CAN/UL 2849
standard for safety for electrical systems for electric bicycles or similar, in
order to determine that an electric bicycle is a qualified electric bicycle.
The office may annually review the standards. The standards must be posted on
the office's website.
(II) If
on or before June 30, 2025, the office determines, in connection with its
inspection of the affidavits required pursuant to subsection (3)(b) of this
section, that a registration process is needed and would be cost effective in
curtailing fraud or abuse related to claiming the credit allowed under this
section, the office shall develop a process in lieu of the affidavits for
purchasers to register as qualified purchasers, through the office and prior to
purchasing a qualified electric bicycle from a qualified retailer, by affirming
the purchaser's residency and that the purchaser has not previously purchased a
qualified electric bicycle that was discounted pursuant to this section in the
same income tax year. The process must allow for a qualified retailer to access
qualified purchaser information in order to confirm a purchaser is a qualified
purchaser.
(b)
Pursuant to section 39-21-304 (3), and for the purpose of providing data that
allows the effectiveness of the tax credit allowed pursuant to this section to
be measured, the department, on or before January 1, 2025, and on or before
January 1 of each year thereafter through January 1, 2034, shall provide to the
state auditor information that details the number of sales of new qualified
electric bicycles for which credits are claimed as reported by taxpayers
claiming the credit for consideration during the state auditor's evaluation of
this tax expenditure pursuant to section 39-21-305.
(c) (I)
After the notice and hearing held in accordance with sections 24-4-104 and
24-4-105, the department may disqualify a qualified retailer if the department
determines:
(A) The
qualified retailer requested advance payment or claimed a credit with respect
to a transaction that does not qualify for the credit allowed by this section;
(B) The
qualified retailer provided false or misleading information to the department
or the office;
(C) The
qualified retailer failed to comply with the requirements set forth in
subsection (3)(e)(III)(B) of this section; or
(D) The
qualified retailer no longer holds a sales tax license.
(II)
The department may consult with the office for the purpose of making a
determination pursuant to this subsection (4)(c).
(III) A
retailer that has been disqualified pursuant to this subsection (4)(c) may not
reapply to be a qualified retailer. The department shall not approve a
registration submitted by a disqualified retailer.
(IV)
Upon notification by the department of a retailer's disqualification, the
office shall remove the disqualified retailer from the list published pursuant
to subsection (3)(e)(IV) of this section.
(5) If
a credit authorized by this section exceeds the income tax due on the income of
the qualified retailer for the taxable year, the excess credit may not be
carried forward and must be refunded to the qualified retailer.
(6) (a)
If the June 2025 revenue forecast, as prepared by either legislative council
staff or the office of state planning and budgeting, projects that state
revenues, as defined in section 24-77-103.6 (6)(c), will not increase by at
least four percent for the next fiscal year, the amount of the credit allowed
pursuant to this section, the discount required pursuant to subsection (3)(b)
of this section, and the administrative fee allowed pursuant to subsection
(3)(d) of this section for any tax year commencing in the calendar year that
begins during said next fiscal year, is reduced by fifty percent.
(b)
This subsection (6) is repealed, effective December 31, 2031.
(7) The
office shall provide technical assistance to ensure that qualified retailers
have access to low-cost financing to support them in claiming the credit
allowed under this section.
(8)
This section is repealed, effective December 31, 2038.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 800, § 9, effective May 11. L.
2024: (1)(b) amended, (HB 24-1450), ch. 490, p. 3426, § 84, effective
August 7. L. 2026: (2)(g)(III), (2)(g)(IV), (3)(e)(III), and (6) amended
and (2)(g)(V), (3)(e)(IV), and (4)(c) added, (HB 26-1289), ch. 364, p. 2204, §
15, effective June 3.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-556. Tax credit for sustainable
aviation fuel production facility - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of this tax expenditure is to induce certain designated
behavior by taxpayers, specifically the construction of sustainable aviation
fuel production facilities in the state, by providing tax relief for certain
businesses and individuals that construct or operate these facilities in the
state.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1)(a) of this section
based on the information required by and reported to the department pursuant to
subsection (7) of this section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(b)
"Department" means the department of revenue.
(c)
"Qualified taxpayer" means a taxpayer that is an aviation business, a
sustainable aviation fuel producer, or an airport.
(d)
"Sustainable aviation fuel" has the same meaning as set forth in
section 40B (d) of the internal revenue code.
(e)
"Sustainable aviation fuel production facility" means:
(I) A
facility which produces sustainable aviation fuel; or
(II) A
facility directly related to enabling the production or distribution of
sustainable aviation fuel as determined under the standards established by the
office.
(f)
"Taxpayer" means a person subject to tax pursuant to this article 22.
(3) (a)
For tax years commencing on or after January 1, 2024, but before January 1,
2027, a qualified taxpayer is allowed a credit against the income tax imposed
under this article 22 for an amount of the actual cost paid to construct,
reconstruct, or erect a sustainable aviation fuel production facility in the
state equal to:
(I)
Thirty percent for a facility for which construction begins on or after January
1, 2024, but before January 1, 2027;
(II) to
(IV) (Deleted by amendment, L. 2026.)
(b) The
credit allowed by subsection (3)(a) of this section is allowed for the tax year
in which the sustainable aviation fuel production facility is placed in
service.
(4) (a)
A qualified taxpayer shall submit an application to the office for a tax credit
certificate to claim the credit allowed by this section on a form and in a
manner prescribed by the office. The application must include information to
allow the office to make a determination that the applicant is a qualified
taxpayer and that the amount for which the tax credit certificate is applied is
the actual cost paid to construct, reconstruct, or erect a sustainable aviation
fuel production facility in the state for which a credit is allowed by this
section.
(b) The
aggregate amount of all tax credit certificates issued by the office pursuant
to this subsection (4) must not exceed one million dollars for the 2024 income
tax year and two million dollars per year for the 2025 and 2026 income tax
years.
(c) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified taxpayer that the
office approved for the income tax credit allowed in this section for the
preceding calendar year that includes the following information:
(I) The
taxpayer's name;
(II)
The taxpayer's social security number or the taxpayer's Colorado account number
and federal employer identification number; and
(III)
The amount of the tax credit certificate.
(5) (a)
The office shall develop standards for the approval of qualified taxpayers for
which a tax credit under this section is allowed.
(b) The
office shall develop standards for the approval of the construction,
reconstruction, or erection of a sustainable aviation fuel production facility
in the state and for reviewing the cost certification for the costs related to
the construction, reconstruction, or erection of the sustainable aviation fuel
production facility. In the standards, the office shall determine the manner in
which a taxpayer will demonstrate actual costs for purposes of calculating the
amount of the tax credit set forth in the tax credit certificate issued by the
office to the taxpayer; except that actual costs must not include legal fees,
land cost, or design costs.
(c) The
standards developed by the office under this subsection (5) must be posted on
the office's website.
(6) (a)
A qualified taxpayer shall submit a report to the office by the end of the
first month after the end of any income tax year in which the qualified
taxpayer received a tax credit under this section and shall annually submit a
report for three years thereafter reporting sustainable aviation fuel
production and total fuel production for the facility.
(b) If
the sustainable aviation fuel production of a facility for which a qualified
taxpayer was allowed a credit under this section comprises less than sixty
percent of the total fuel production of the facility in any of the three
taxable years immediately following the taxable year in which the facility was
placed in service, the office shall notify the department in writing that the
credit allowed in this section must be disallowed for that qualified taxpayer.
The qualified taxpayer shall add the amount of the disallowed credit to its
return as a recaptured credit for the tax year in which the credit is
disallowed pursuant to this subsection (6).
(7)
Notwithstanding the requirement in section 24-1-136 (11)(a)(I), for the purpose
of providing data that allows the general assembly and the state auditor to
measure the effectiveness of the credit created in subsection (3) of this
section pursuant to section 39-21-304 (3), the office on or before January 1,
2026, and on or before January 1 of each year thereafter until January 1, 2027,
shall submit to the general assembly and the state auditor a report detailing
the construction, reconstruction, and erection of sustainable aviation fuel
production facilities as reported by qualified taxpayers claiming the credit in
this section. The tax credit meets its purpose if the construction,
reconstruction, and erection of sustainable aviation fuel production facilities
in the state increase significantly in tax years for which the credit is
allowed.
(8) If
the credit authorized by this section exceeds the income tax due on the income
of the qualified taxpayer for the taxable year, the excess credit may not be
carried forward and must be refunded to the qualified taxpayer.
(9)
This section is repealed, effective December 31, 2033.
Source:
L. 2023: Entire
section added, (HB 23-1272), ch. 167, p. 804, § 10, effective May 11. L.
2026: (3)(a), (4)(b), (7), and (9) amended, (HB 26-1289), ch. 364, p. 2206,
§ 17, effective June 3.
Cross
references: For
the legislative declaration in HB 23-1272, see section 1 of chapter 167,
Session Laws of Colorado 2023. For the legislative declaration in HB 26-1289,
see section 1 of chapter 364, Session Laws of Colorado 2026.
39-22-556.5. Tax credit for the purchase
of sustainable aviation fuel - tax preference performance statement -
legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of this tax expenditure is to induce certain designated
behavior by taxpayers, specifically the purchase of sustainable aviation fuel
for use in the state, by providing tax relief for certain businesses and
individuals that purchase sustainable aviation fuel for use in the state.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1)(a) of this section
based on the information required by and reported to the office pursuant to
subsection (5) of this section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Carbon intensity" means the amount of greenhouse gases generated per
gallon of sustainable aviation fuel produced.
(b)
"Colorado energy office" or "office" means the Colorado
energy office created in section 24-38.5-101.
(c)
"Department" means the department of revenue.
(d)
"Qualified taxpayer" means a person who purchases sustainable
aviation fuel for uplift and use in the state if that person is subject to tax
pursuant to this article 22 or is a person or political subdivision of the
state that is exempt from taxation pursuant to section 39-22-112 (1); except
that "qualified purchaser" does not include a sustainable aviation
fuel producer or blender.
(e)
"Sustainable aviation fuel" has the same meaning as set forth in
section 40B (d) of the internal revenue code.
(3) (a)
(I) For tax years commencing on or after January 1, 2027, but before January
1, 2033, a qualified taxpayer is allowed a credit against the income tax
imposed under this article 22 in an amount not less than one dollar and fifty
cents, increased by one cent for each whole percentage of carbon intensity
reduction in excess of fifty percent, but no greater than one hundred percent,
for each gallon of sustainable aviation fuel that the qualified taxpayer
purchased for use in the state during the income tax year, except as otherwise
provided in subsection (3)(b) of this section.
(II)
For tax years beginning on or after January 1, 2028, the office may allow an
additional credit of fifty cents for each gallon of sustainable aviation fuel
produced in the state that the qualified taxpayer purchased for use in the
state during the income tax year, except as otherwise provided in subsection
(3)(b) of this section.
(b) The
office shall annually review and evaluate the effectiveness of the tax credit
allowed pursuant to this section and may, notwithstanding subsection (3)(a) of
this section, for the subsequent tax year, modify the amount per gallon,
including the increase as a result of carbon intensity reduction, that a
qualified taxpayer is allowed as a credit against the income tax imposed under
this article 22 pursuant to this section. The office shall post the modified
amount on its website.
(c) For
purposes of this section, sustainable aviation fuel is deemed to be purchased
for use in the state if it is delivered to and used for fueling aircraft at a
Colorado airport, airfield, or airpark notwithstanding the subsequent operation
of such aircraft outside the state. Except as provided in this subsection
(3)(c), fuel loaded into a cargo tank or otherwise exported from the state is
not deemed to be purchased for use in the state.
(d) If
a credit is allowed pursuant to this section to a qualified purchaser that is
an airport, airfield, or airpark, no additional credit is allowed to a
qualified purchaser that purchases the sustainable aviation fuel, directly or
indirectly, from the qualified purchaser to which the credit was allowed. The
qualified purchaser for which a credit was reserved shall disclose to any
purchaser that it has reserved a credit with respect to the sustainable
aviation fuel sold.
(4) (a)
Prior to purchasing sustainable aviation fuel for use in the state, a qualified
taxpayer shall submit an application to the office for a tax credit certificate
to reserve the credit allowed by this section on a form and in a manner
prescribed by the office. The application must include information to allow the
office to make a determination that the applicant is a qualified taxpayer,
documentation regarding the carbon intensity of the sustainable aviation fuel
that will be purchased, and an estimate of the amount of sustainable aviation
fuel the qualified taxpayer plans to purchase for use in the state during the
income tax year.
(b)
After reviewing the application, the office shall determine whether the
applicant qualifies for the credit and the amount of credit to be reserved for
the benefit of the qualified taxpayer, which may be all, part, or none of the
amount requested in the application. The office shall notify the applicant in
writing of its decision and the amount reserved, if any. The aggregate amount
of credit the office may reserve pursuant to this subsection (4) must not
exceed three million dollars per calendar year. In the case of a qualified
taxpayer with an income tax year other than a calendar year, credit reserved
pursuant to this subsection (4) may be claimed for the tax year that begins
during the calendar year.
(c)
Following the close of the tax year, in accordance with the standards developed
by the office pursuant to subsection (4)(e) of this section, the qualified
taxpayer shall submit documentation substantiating the qualified taxpayer's
purchases of sustainable aviation fuel for use in the state during the tax
year. Upon a determination by the office that the purchases qualify for the
credit allowed by this section, the office shall issue the taxpayer a tax
credit certificate for the lesser of the credit allowed pursuant to subsection
(3)(a) of this section with respect to the amount of sustainable aviation fuel
actually purchased for use in the state or the amount of credit reserved for
the benefit of the qualified taxpayer pursuant to this subsection (4).
(d) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified taxpayer that the
office approved for the income tax credit allowed in this section for the
preceding calendar year that includes the following information:
(I) The
taxpayer's name;
(II)
The taxpayer's social security number or the taxpayer's Colorado account number
and federal employer identification number; and
(III)
The amount of the tax credit certificate.
(e) The
office shall develop standards for the approval of qualified taxpayers for whom
a tax credit under this section is allowed and the awarding of tax credit
certificates pursuant to this subsection (4) and shall post those standards on
its website.
(5)
Notwithstanding the requirement in section 24-1-136 (11)(a)(I), for the purpose
of providing data that allows the general assembly and the state auditor to
measure the effectiveness of the credit created in subsection (3) of this
section pursuant to section 39-21-304 (3), the office, on or before January 1,
2028, and on or before January 1 of each year thereafter until January 1, 2034,
shall submit to the general assembly and the state auditor a report detailing
the purchase of sustainable aviation fuel by taxpayers claiming the credit in
this section. The tax credit meets its purpose if the purchase of sustainable
aviation fuel in the state increases significantly in tax years for which the
credit is allowed.
(6) If
the credit authorized by this section exceeds the income tax due on the income
of the qualified taxpayer for the taxable year, the excess credit may not be
carried forward and must be refunded to the qualified taxpayer.
(7)
This section is repealed, effective December 31, 2038.
Source:
L. 2026: Entire
section added, (HB 26-1289), ch. 364, p. 2207, § 18, effective June 3.
Cross
references: For
the legislative declaration in HB 26-1289, see section 1 of chapter 364,
Session Laws of Colorado 2026.
39-22-557. Clean hydrogen tax credit -
qualified uses - tax preference performance statement - definitions -
legislative declaration - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers. Specifically, the tax expenditure is
intended to provide tax relief for certain businesses or individuals for
purposes of encouraging them to engage in certain qualified uses of clean
hydrogen.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the information required to be maintained by and reported to the state
auditor by the office pursuant to subsection (4)(b) of this section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Clean hydrogen" has the meaning set forth in section 40-2-138
(1)(a).
(b)
"Department" means the department of revenue.
(c)
"Hard to decarbonize end use" has the meaning set forth in section
40-2-138 (1)(e).
(d)
"Lifecycle greenhouse gas emissions rate" means lifecycle greenhouse
gas emissions, as defined in 26 U.S.C. sec. 45V (c)(1)(A), as amended, measured
in accordance with any applicable federal internal revenue service regulations
or guidance, subject to the rules adopted by the public utilities commission
pursuant to section 40-2-138 (3)(a)(II).
(e)
"Office" means the Colorado energy office created in section
24-38.5-101.
(f)
"Qualified use" has the meaning set forth in section 40-2-138 (1)(i).
(g)
"Taxpayer" means a person subject to tax pursuant to this article 22
or a person or political subdivision of the state that is exempt from tax
pursuant to section 39-22-112 (1).
(h)
"Tier one greenhouse gas emissions rate" means a qualified use of
hydrogen that results in lifecycle greenhouse gas emissions rates that are
within the range set forth in 26 U.S.C. sec. 45V (b)(2)(D), as amended.
(i)
"Tier two greenhouse gas emissions rate" means a qualified use of
hydrogen that results in lifecycle greenhouse gas emissions rates that are
within the range set forth in 26 U.S.C. sec. 45V (b)(2)(C), as amended.
(3) (a)
Subject to the limitations set forth in subsection (3)(b) of this section, for
income tax years commencing on or after January 1, 2024, but before January 1,
2033, a taxpayer is allowed a credit against the income taxes imposed by this
article 22 in an amount equal to:
(I) One
dollar per kilogram of clean hydrogen used for a qualified use that results in
a tier one greenhouse gas emissions rate in the income tax year; or
(II)
Thirty-three cents per kilogram of clean hydrogen used for a qualified use that
results in a tier two greenhouse gas emissions rate in the income tax year.
(b) In
order to claim the credit, the taxpayer must annually apply for and receive a
tax credit certificate from the office pursuant to subsection (4) of this section.
If the office determines that an applicant is not entitled to a tax credit
certificate under this section, the office shall notify the applicant of its
disapproval in writing.
(c) (I)
For income tax years commencing on and after January 1, 2024, but before
January 1, 2026, and not before the public utilities commission adopts rules
pursuant to section 40-2-138 (3)(a)(II), the office shall not issue a tax
credit certificate to a taxpayer indicating eligibility for a tax credit for an
amount exceeding one million dollars in a tax year.
(II)
For income tax years commencing on and after January 1, 2026, but before
January 1, 2029, the office shall not issue a tax credit certificate to a
taxpayer indicating eligibility for a tax credit for an amount exceeding five
hundred thousand dollars in a tax year.
(III)
For income tax years commencing on and after January 1, 2029, but before
January 1, 2033, the office shall not issue a tax credit certificate to a
taxpayer indicating eligibility for a tax credit for an amount exceeding two
hundred fifty thousand dollars in a tax year.
(4) (a)
(I) A taxpayer shall submit an application to the office for a tax credit
certificate to claim the credit allowed by this section on a form and in a
manner prescribed by the office. The application must include information to
allow the office to make a determination that the use is a qualified use and
that the hydrogen used meets the definition of clean hydrogen pursuant to
subsection (2)(a) of this section and to verify the amount for which the tax
credit certificate is applied. A taxpayer is entitled to receive one tax credit
certificate per income tax year.
(II)
The application described in subsection (4)(a)(I) of this section must also
include verification from the hydrogen producer passed to the user at the point
of sale that the hydrogen used meets the definition of clean hydrogen pursuant
to subsection (2)(a) of this section.
(b) (I)
The office shall maintain a database of any information determined necessary by
the office to evaluate the effectiveness of the income tax credit allowed in
this section in meeting the purpose set forth in subsection (1)(a) of this
section and shall provide such information, and any other information that may
be needed, if available, to the state auditor as part of the state auditor's
evaluation of this tax expenditure required by section 39-21-305.
(II)
The office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report for the preceding tax year listing
each taxpayer to which the office issued a tax credit certificate and that
includes the following information:
(A) The
taxpayer's name;
(B) The
amount of the income tax credit that the certificate indicates the taxpayer is
eligible to claim; and
(C) The
taxpayer's social security number or the taxpayer's Colorado account number and
federal employer identification number.
(III)
The office shall develop standards for the qualified uses for which an income
tax credit under this section is allowed. The office shall post the standards
on the office's website.
(5) In
order to claim the credit authorized by this section, a taxpayer shall file the
tax credit certificate with the taxpayer's state income tax return, and, if the
taxpayer is exempt from tax pursuant to section 39-22-112 (1), the taxpayer
shall file a return pursuant to section 39-22-601 (7)(b). The amount of the
credit that the taxpayer may claim pursuant to this section is the amount
stated on the tax credit certificate.
(6) If
an income tax credit authorized in this section exceeds the income tax due on
the income of the taxpayer for the taxable year, the excess credit may not be
carried forward and must be refunded to the taxpayer.
(7)
This section is repealed, effective December 31, 2036.
Source:
L. 2023: Entire
section added, (HB 23-1281), ch. 237, p. 1279, § 3, effective August 7. L.
2024: (2)(d) and (3)(c)(I) amended, (SB 24-214), ch. 191, p. 1106, § 19,
effective May 17.
Cross
references: For
the legislative declaration in HB 23-1281, see section 1 of chapter 237,
Session Laws of Colorado 2023.
39-22-558. Tax credit for employer's
contribution to employee for eligible expenses in connection with a qualifying
home purchase - tax preference performance statement - legislative declaration
- definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), the general assembly finds and
declares that the purpose of this tax expenditure is to induce certain
designated behavior by taxpayers to encourage home ownership by providing tax
relief to employers who contribute money to an employee for a down payment and
related closing costs on a home purchase.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsection (1)(a) of this section
based on the information required to be maintained by and reported to the state
auditor upon request by the department pursuant to subsection (4) of this
section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Department" means the department of revenue.
(b)
"Eligible expenses" means a down payment and any closing costs
included on a real estate settlement statement, including but not limited to
appraisal fees, mortgage origination fees, and inspection fees.
(c)
"Employee contribution" means the amount an employee authorizes an
employer to withhold from the employee's earnings for deposit into the savings
account established pursuant to subsection (3)(b)(I) of this section for use by
an employee for eligible expenses in connection with a qualifying home
purchase.
(d)
"Employer" means a private, nonpublic person that employs one or more
employees within the state.
(e)
"Employer contribution" means the amount an employer contributes to a
savings account established pursuant to subsection (3)(b)(I) of this section
for use by an employee for eligible expenses in connection with a qualifying
home purchase.
(f)
"Qualifying home purchase" means a property purchased by an employee
as a primary residence.
(3) (a)
For any income tax year commencing on or after January 1, 2024, but before
January 1, 2027, if an employer makes a contribution of money to an employee
during the income tax year for use by the employee for eligible expenses in
connection with a qualifying home purchase, then the employer is allowed a
credit against the income taxes imposed by this article 22 in an amount equal
to five percent of the amount of the employer contribution; except that an
employer cannot claim a credit of more than five thousand dollars for any one
employee and the maximum total credit that an employer may claim in a taxable
year is five hundred thousand dollars.
(b) (I)
In order to claim the tax credit allowed by this section, the employer shall
establish one or more savings accounts for the purpose of depositing the money
for the employer's contribution to an employee.
(II)
The employer shall establish policies concerning the contribution, including
how the employer contribution is to be made and procedures for an employee to
follow to withdraw money for qualifying expenses and for an employer to follow
to withhold an employee's earnings as an employee contribution.
(III)
An employee may authorize an employer to withhold a specified portion of the
employee's earnings as an employee contribution, which money shall be deposited
in a savings account established pursuant to subsection (3)(b)(I) of this
section.
(c) If
an employee ends the employee's employment with the employer or if the employee
chooses to use money in a savings account established pursuant to subsection
(3)(b)(I) of this section that is an employee contribution for something other
than an eligible expense, the employee is not entitled to any unexpended amount
of the employer contribution, and the employer shall remit to the employee any
amount in the savings account which is all or the remaining amount of the
employee contribution, plus any interest earned on the amount. The employer
shall pay the entire amount of the credit received for the employer
contribution. The employer shall report the recapture required by this
subsection (3)(c) by increasing their income tax liability by the amount of the
total credit claimed for the year in which the recapture occurs.
(4) (a)
To claim the credit for an income tax year, an employer must keep records
related to the credit as required by the department. The executive director of
the department may promulgate rules to implement this section. Notwithstanding
any other requirements of the department, records maintained by an employer
must show:
(I) The
number of employees to whom the employer made employer contributions in the tax
year;
(II)
The amount the employer contributed to each employee in the tax year as
employer contributions;
(III)
The number of employees who expended money from a savings account established
pursuant to subsection (3)(b)(I) of this section on eligible expenses for a
home purchase in the tax year; and
(IV)
The total amount of any employer contributions made by the employer for use by
the employee for eligible expenses in connection with a qualifying home
purchase that an employee has forfeited pursuant to subsection (3)(c) of this
section in the tax year.
(b)
Upon request by the state auditor, the department shall provide to the state
auditor the information contained in records required by subsection (4)(a) of
this section.
(5) If
the amount of the credit allowed under this section exceeds the amount of
income taxes otherwise due on the employer's income in the income tax year for
which the credit is claimed, the amount of the credit not used as an offset
against income taxes in the current income tax year may be carried forward and
used as a credit against income tax liability in subsequent years for a period
not to exceed five years and must be applied first to the earliest income tax
year possible. Any credit remaining after the period may not be refunded or
credited to the employer.
(6) (a)
Nothing in this section is intended to preclude an employee who receives a
contribution from their employer in accordance with subsection (3) of this
section from having a first-time home buyer savings account pursuant to part 47
of this article 22.
(b)
This subsection (6) is repealed, effective December 31, 2028.
Source:
L. 2023: Entire
section added, (HB 23-1189), ch. 446, p. 2626, § 1, effective August 7. L.
2024: (6) amended, (HB 24-1036), ch. 373, p. 2532, § 23, effective August
7.
Cross
references: For
the legislative declaration in HB 24-1036, see section 1 of chapter 373,
Session Laws of Colorado 2024.
39-22-559. Film incentive tax credit -
tax preference performance statement - review - legislative declaration -
definitions - repeal.
(1) (a)
The general assembly hereby finds and declares that:
(I) Colorado
is home to many talented film industry members, many of whom travel out of
state for work as they cannot find enough work locally to support them;
(II)
With a competitive film incentive that is comparable to surrounding western
states with similar beautiful landscapes, Colorado will have the ability to
attract high-profile projects that will bring in more film tourism and increase
Colorado's impact on the global film industry; and
(III)
Colorado's film industry has the ability to be a true economic driver in the
state.
(b) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided for in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain business or individuals by allowing production
companies to receive a credit against income tax for qualified expenditures if
certain criteria are met. Specifically, this tax expenditure is intended to
incentivize production companies to film in Colorado and attract more film
projects, in particular high-budget film projects, that will employ more
Coloradans.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (1)(b) of this
section based on the number and value of the credits claimed and, when
available, taking into consideration the results of the review performed by the
office of economic development and the office pursuant to subsection (8) of
this section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Credit" means the credit against income tax created in this section.
(b)
"Film" has the same meaning as set forth in section 24-48.5-114 (1).
(c)
Repealed.
(d)
"Office" has the same meaning as set forth in section 24-48.5-114.
(e)
"Office of economic development" means the office of economic
development created in section 24-48.5-101 (1).
(f)
"Originates" means that a production company has been a resident of
the state or registered with the secretary of state for at least twelve
consecutive months and, as of the date of applying for a tax credit as
specified in subsection (3) of this section, has engaged in production
activities in the state for other projects in the past twelve consecutive
months; except that if the production company creates a business entity for the
sole purpose of conducting production activities in the state, then such
business entity need not be registered with the secretary of state for twelve
consecutive months, but the manager of the business entity must be a resident
of the state for at least twelve consecutive months as of the date of applying
for a tax credit as specified in subsection (3) of this section. As used in
this subsection (2)(f), "manager of the business entity" means a
manager with decision-making authority to make financial or legal commitments
on behalf of the production company or business entity.
(g)
"Production activities" means the shooting of a film, support
activities related to such shooting, and any preshooting or postshooting
activities that commence on or after January 1, 2024, and that are necessary to
produce a finished film, including but not limited to editing and the creation
of sets, props, costumes, and special effects.
(h)
"Production company" means a person, including a corporation or other
business entity, that engages in production activities for the purpose of
producing all or any portion of a film in Colorado.
(i)
"Qualified local expenditure" means a payment made by a production
company operating in Colorado to a person or business in Colorado in connection
with production activities in Colorado. "Qualified local expenditure"
includes, but need not be limited to:
(I)
Payments made in connection with developing or purchasing the story and
scenario to be used for a film;
(II)
Payments made for the costs of set construction and operations, wardrobe,
accessories, and related services;
(III)
Payments made for the costs of photography, sound recording and
synchronization, lighting, and related services;
(IV)
Payments made for the costs of editing, postproduction, music, and related
services;
(V)
Payments made for the costs of renting facilities and equipment, including
location fees, leasing vehicles, and providing food and lodging to people
working on the film production;
(VI)
Payments for airfare purchased through a Colorado-based travel agency or
company;
(VII)
Payments for insurance and bonding purchased through a Colorado-based insurance
agent;
(VIII)
Payments for other direct costs incurred by the film production company that
are deemed appropriate by the office;
(IX)
Payments of up to one million dollars per employee or contractor, made by a
production company to pay the wages or salaries of employees or contractors who
participate in the production activities. In order for any wage or salary to be
considered a qualified local expenditure, all Colorado income taxes shall be
withheld and paid either by the production company or the individual. Any
payments in excess of one million dollars per employee or contractor shall be
excluded.
(X)
Payments of up to one million dollars per calendar year per personal service
corporation, as defined in section 24-48.5-114 (4.5)(a), made by a production
company to a personal service corporation to pay the wages or salaries of an
employee-owner of a personal service corporation, as defined in section
24-48.5-114 (4.5)(b), who participates in the production activities. In order
for any wage or salary to be considered a qualified local expenditure, the
production company must file an information return pursuant to section
39-22-604 (21) regarding the payments made to the personal service corporation.
Any payments in excess of one million dollars per personal service corporation
are excluded.
(3)
Subject to the limitations set forth in subsections (5) and (6) of this
section, for income tax years commencing on or after January 1, 2024, but
before January 1, 2032, there shall be allowed a film incentive tax credit with
respect to income taxes imposed pursuant to this article 22 to any production
company making at least one hundred thousand dollars in actual qualified local
expenditures and employing a workforce for any in-state production activity
made up of at least fifty percent Colorado residents in an amount not to exceed
twenty-two percent of the actual qualified local expenditures.
(a) to
(c) (Deleted by amendment, L. 2024.)
(4) The
director of the office of economic development may, in the director's
discretion, approve a tax credit in an amount that exceeds twenty percent or
twenty-two percent, as applicable, of qualified local expenditures for a
production company that qualifies for a tax credit under subsection (3) of this
section.
(5) (a)
For the 2024 calendar year, and for each calendar year thereafter, the maximum
aggregate amount of all tax credits that the office may reserve pursuant to
subsection (6) of this section is five million dollars per calendar year.
(b)
Repealed.
(c) A
production company shall not apply for and the office shall not approve a tax
credit allowed under subsection (3) of this section for any qualified local
expenditures for which the production company has applied or been awarded a
performance-based incentive pursuant to section 24-48.5-116.
(6) (a)
For a production company to claim a tax credit pursuant to subsection (3) of
this section, the production company must apply to the office for a tax credit
reservation, in a manner to be determined by the office prior to beginning
production activities in the state for the project for which the production
company is seeking a tax credit. The application for a tax credit reservation
must include a statement of intent by the production company to produce a film
in Colorado for which the production company will be eligible to receive the
tax credit. The production company must submit, in conjunction with the
application, any documentation necessary to demonstrate that:
(I) The
production company's projected qualified local expenditures will satisfy the
minimum expenditure requirement specified in subsection (3) of this section;
and
(II) If
the production company seeks a tax credit specified in subsection (3) of this
section, the production company will originate production activities in
Colorado, including copies of income tax forms, proof of voter registration, or
copies of utility bills, to provide documentary evidence that, as of the date
of applying for a tax credit:
(A) The
production company engaged in production activities in the state for other
projects in the past twelve consecutive months; or
(B) If
the production company created a business entity for the sole purpose of
conducting production activities in the state, the manager of the business
entity was a resident in the state for the past twelve consecutive months.
(b) (I)
The office shall review each application for a tax credit reservation submitted
by a production company before the production company begins work on a film in
Colorado. Based on the information provided in the production company's
application for a tax credit reservation, the office may determine that a
production company is entitled to a tax credit reservation in accordance with
the provisions of this section. The office shall issue tax credit reservations
subject to the limitations set forth in this subsection (6) and in subsection
(5) of this section. The office shall not issue tax credit reservations after
December 31, 2029.
(II) If
the office reserves a tax credit for the benefit of a production company, the
office shall notify the production company in writing of the reservation and
the amount reserved. The reservation of a tax credit by the office for a
production company does not entitle the production company to the issuance of a
tax credit certificate until the production company complies with all of the
other requirements specified in this section for the issuance of the tax credit
certificate. When the office approves a tax credit reservation, the office may
also impose additional requirements, which a production company shall satisfy
as part of completing the production activities before a tax credit certificate
is issued to the production company.
(III)
If approved, the office may issue a tax credit reservation to a production
company in an amount not to exceed twenty-two percent of the estimated
qualified local expenditures.
(c) (I)
(A) A production company shall complete the production activities in
Colorado on or before December 31, 2031. Upon completion of the production
activities in Colorado, a production company that received a tax credit
reservation from the office must retain a certified public accountant licensed
to practice in the state or a certified public accounting firm that is
registered in the state to review and report in writing, and in accordance with
professional standards, regarding the accuracy of the financial documents that
detail the expenses incurred in the course of the film production activities in
Colorado. The certified public accountant's written report must include
documentation of the production company's actual expenditures, including its actual
qualified local expenditures, and any documentation necessary to show that the
production company employed a workforce for the in-state production activities
made up of at least fifty percent Colorado residents. When the production
company provides a copy of the certified public accountant's written report and
the production company certifies in writing to the office that the amount of
the production company's actual qualified local expenditures equals or exceeds
the applicable minimum total amount of the production company's qualified local
expenditures as specified in subsection (3) of this section, the office shall
conduct a review of the certified public accountant's written report to ensure
the requirements of this section are met. If the office is satisfied that the
requirements of this section are met, and the office confirms that the
certified public accountant who provided the written report is from the list
described in subsection (6)(c)(II)(B) of this section, then the office shall
issue to the production company a tax credit certificate that evidences the
production company's right to claim the tax credit allowed under subsection (3)
of this section. The tax credit certificate must include the taxpayer's name,
the taxpayer's social security number or federal employer identification
number, the approved tax credit amount, the income tax year for which the tax
credit is being allowed, and any other information that the executive director
of the department of revenue may require.
(B) If
the office determines that a production company has failed to comply with the
requirements of this subsection (6), the office shall notify the production
company and may rescind the tax credit reservation. If the office rescinds the
tax credit reservation, the production company may submit a new tax credit
reservation application pursuant to this subsection (6). When the office
rescinds a tax credit reservation in a calendar year, the maximum aggregate
amount of all tax credits that the office may reserve in that calendar year set
forth in subsection (5)(a) of this section is increased by the amount of the
rescinded tax credit reservation.
(II)
(A) Any services provided by a certified public accountant to meet the
requirements of this subsection (6)(c) must be performed in Colorado.
(B) The
office shall develop a list of certified public accountants that meet the
requirements of this section. Such list must be made available to all
production companies and must be posted on the office of economic development's
website.
(d) The
office shall develop procedures for the administration of this section,
including application guidelines for production companies applying to receive a
tax credit reservation.
(7) (a)
A production company shall claim the credit allowed under subsection (3) of
this section by including the credit certificate issued to the production
company by the office pursuant to subsection (6)(c)(I) of this section with its
income tax return for the income tax year for which the certificate was issued.
If the amount of the tax credit exceeds the production company's income taxes
due on the income of the production company for the income tax year, the excess
credit is not carried forward and shall be refunded to the taxpayer.
(b) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each production company to which
the office issued a tax credit certificate for the preceding income tax year
that includes the following information:
(I) The
production company's name;
(II)
The amount of the income tax credit; and
(III)
The production company's social security number or the production company's
Colorado account number and federal employer identification number.
(8) The
office of economic development and the office shall jointly review the
effectiveness of the credit and report the results of the review to the house
of representatives finance committee and the senate finance committee, or their
successor committees, no later than July 1, 2028.
(9)
This section is repealed, effective December 31, 2034.
Source:
L. 2023: Entire
section added, (HB 23-1309), ch. 379, p. 2271, § 1, effective August 7. L.
2024: (2)(i)(VIII), (2)(i)(IX), (3), (5)(a), IP(6)(a), (6)(a)(I),
IP(6)(a)(II), (6)(b), (6)(c)(I), (6)(c)(II)(A), (6)(d), (7), and (8) amended,
(2)(i)(X) added, and (5)(b) repealed, (HB 24-1358), ch. 260, p. 1722, § 1,
effective August 7; (6)(c)(II)(A) amended, (HB 24-1450), ch. 490, p. 3426, §
85, effective August 7. L. 2026: (2)(c) repealed, (SB 26-169), ch. 311,
p. 1815, § 63, effective August 12.
39-22-560. Tax credit for certification
of aircraft to use unleaded aviation gasoline - tax preference performance
statement - review - legislative declaration - definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided in this section is to induce
certain designated behavior by taxpayers, specifically the modification of
aircraft that are powered by leaded aviation gasoline so that such aircraft can
be certified to be powered by unleaded aviation gasoline and no longer use
leaded aviation gasoline.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the number of credits claimed.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Aircraft" has the same meaning as set forth in section 43-10-102
(1).
(b)
"Aviation gasoline" means gasoline-based fuel that is used to power
an aircraft.
(c)
"Leaded aviation gasoline" means any aviation fuel containing
tetraethyl lead additives.
(d)
"Qualifying aircraft" means an aircraft that has been powered by
leaded aviation gasoline and for which a supplemental type certificate or any
other authorization that approves the completed modification of the aircraft to
be powered by unleaded aviation gasoline has been issued.
(e)
"Qualifying expenses" means any actual out-of-pocket expenses
incurred and paid by a qualifying taxpayer for the purpose of modifying an
aircraft registered with the federal aviation administration in this state so
that it is a qualifying aircraft.
(f)
"Qualifying taxpayer" means a person subject to tax under this
article 22 who is the owner of an aircraft as indicated on the aircraft
registry maintained by the federal aviation administration.
(g)
"Supplemental type certificate" means a type certificate issued by
the federal aviation administration to an applicant that has modified an
aeronautical product from its original design with federal aviation
administration approval.
(h)
"Unleaded aviation gasoline" means aviation gasoline that does not
include lead.
(3) For
any income tax year commencing on or after January 1, 2025, but before January
1, 2030, a qualifying taxpayer who incurs qualifying expenses is allowed a
credit against the income taxes imposed by this article 22 in the tax year in
which the qualifying aircraft is registered by the federal aviation
administration in this state in an amount equal to fifty percent of all
qualifying expenses incurred; except that the maximum amount of the credit that
may be claimed for qualifying expenses incurred in modifying any one aircraft
is five hundred dollars.
(4) If
the amount of a credit authorized by this section exceeds the amount of income
taxes otherwise due on the income of the qualifying taxpayer claiming the
credit in the income tax year for which the credit is being claimed, the amount
of the credit not used as an offset against income taxes in that income tax
year may not be carried forward and must be refunded to the qualifying
taxpayer.
(5)
This section is repealed, effective December 31, 2039.
Source:
L. 2024: Entire
section added, (HB 24-1235), ch. 190, p. 1077, § 2, effective May 17.
Cross
references: For
the legislative declaration in HB 24-1235, see section 1 of chapter 190,
Session Laws of Colorado 2024.
39-22-561. Agricultural stewardship tax
credit - tax preference performance statement - legislative declaration -
definitions - rules - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly declares that the
purpose of the tax credit created in this section is to induce certain
designated behavior by taxpayers, specifically to encourage an individual to
actively practice one or more qualified stewardship practices on a farm or
ranch, including any practice that increases soil health, improves water
efficiency, or creates more diverse and beneficial ecosystems while maintaining
the productivity of the farm or ranch.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the information required to be maintained by and reported to the state
auditor by the department of agriculture pursuant to subsection (4)(b) of this
section.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Credit certificate" means a certificate issued by the department of
agriculture certifying that a qualified taxpayer qualifies for an income tax
credit authorized in this section and specifying the amount of the credit
allowed and the income tax year for which the credit may be claimed.
(b)
"Qualified stewardship practice" means any agricultural practice, as
specified by rules issued by the commissioner of the department of agriculture,
that may include a grazing or cropping practice that improves soil health,
improves water retention and drought resilience, or creates more diverse and
beneficial ecosystems while maintaining the productivity of the farm or ranch,
including rotational crops, reduced tillage, no tillage, cover cropping,
integrating managed livestock grazing on cropland, range improvements,
interseeding, or compost application.
(c)
"Qualified taxpayer" means a person subject to tax pursuant to this
article 22 who actively practices a qualified stewardship practice on a farm or
ranch located in the state during an income tax year, whether the qualified
stewardship practice is newly practiced during the income tax year or is being
continued from a prior income tax year.
(3) (a)
Subject to the limitations set forth in subsection (3)(b) of this section, for
income tax years commencing on or after January 1, 2026, but before January 1,
2031, a qualified taxpayer is allowed a credit against the income taxes imposed
by this article 22 in an amount equal to:
(I) A
minimum of five dollars and a maximum of seventy-five dollars per acre of land
subject to one qualified stewardship practice, as specified by rule issued by
the commissioner of the department of agriculture, limited to a maximum credit
amount of one hundred fifty thousand dollars per income tax year;
(II) A
minimum of ten dollars and a maximum of one hundred dollars per acre of land
subject to two qualified stewardship practices, as specified by rule issued by
the commissioner of the department of agriculture, limited to a maximum credit
amount of two hundred thousand dollars per income tax year; and
(III) A
minimum of fifteen dollars and a maximum of one hundred fifty dollars per acre
of land subject to three or more qualified stewardship practices, as specified
by rule issued by the commissioner of the department of agriculture, limited to
a maximum credit amount of three hundred thousand dollars per income tax year.
(b) The
department of agriculture may only issue tax credit certificates to a qualified
taxpayer:
(I) For
three income tax years; and
(II) If
the qualified taxpayer has not received a tax credit, tax deduction, or grant
related to the agricultural land and the qualifying stewardship practice during
an income tax year for which a tax credit is claimed pursuant to this section
from any other source.
(4) (a)
A qualified taxpayer shall submit an application to the department of
agriculture for a tax credit certificate to claim the credit allowed by this
section on a form and in a manner prescribed by the department of agriculture.
The application must include a means for the taxpayer to note whether the
taxpayer files income taxes on a calendar year or fiscal year basis and
information to allow the department of agriculture to make a determination that
the stewardship practice is a qualified stewardship practice, that the
qualified taxpayer is actively practicing the qualified stewardship practice,
and to verify the amount for which the tax credit certificate is applied. A
qualified taxpayer may receive only one tax credit certificate per income tax year.
(b) (I)
The department of agriculture shall maintain a database of any information
determined necessary by the department of agriculture to evaluate the
effectiveness of the income tax credit allowed in this section in meeting the
purpose set forth in subsection (1) of this section and shall provide such
information, and any other information that may be needed, if available, to the
state auditor as part of the state auditor's evaluation of this tax expenditure
required by section 39-21-305.
(II)
The department of agriculture shall, in a sufficiently timely manner to allow
the department of revenue to process returns claiming the income tax credit
allowed in this section, provide the department of revenue with an electronic
report for the preceding tax year that lists each qualified taxpayer to which
the department of agriculture issued a tax credit certificate and includes the
following information:
(A) The
qualified taxpayer's name;
(B) The
amount of the income tax credit that the certificate indicates the qualified
taxpayer is eligible to claim; and
(C) The
qualified taxpayer's social security number or the qualified taxpayer's
Colorado account number and federal employer identification number.
(5) In
order to claim the credit authorized by this section, a qualified taxpayer
shall file the tax credit certificate with the qualified taxpayer's state
income tax return. The amount of the credit that the qualified taxpayer may
claim pursuant to this section is the amount stated on the tax credit
certificate.
(6) The
department of agriculture shall issue certificates for credit claims received
in the order submitted, but shall not issue credit certificates that exceed
three million dollars in a calendar year. After certificates have been issued
for credits in an aggregate amount of three million dollars for all qualified
taxpayers during a calendar year, any additional claims must be placed on a
wait list, with priority first given to a qualified taxpayer who has been
issued a tax certificate in the calendar year preceding the calendar year in
which the qualified taxpayer is placed on the wait list and second to a
qualified taxpayer who applied for the tax credit authorized in this section
but was placed on the wait list, and a certificate must be issued for use of
the credit in the next calendar year; except that no more than two million
dollars in claims shall be placed on the wait list in any given calendar year.
No claim for a credit is allowed for any income tax year unless a certificate
has been issued by the division. If all other requirements of this section are
met, the right to claim the credit is vested in a qualified taxpayer at the
time a credit certificate is issued.
(7) If
an income tax credit authorized in this section exceeds the income tax due on
the income of the qualified taxpayer for the taxable year, the excess credit
may not be carried forward and must be refunded to the qualified taxpayer.
(8) The
commissioner of the department of agriculture may issue rules to administer
this section, including specifying requirements for implementing and
demonstrating qualified stewardship practices, and may issue tax credit
certificates pursuant to this section. Before promulgating any rules, the
commissioner shall initiate a public stakeholder process to advise the
commissioner about the requirements for implementing and demonstrating
qualified stewardship practices.
(9)
This section is repealed, effective December 31, 2034.
Source:
L. 2024: Entire
section added, (HB 24-1249), ch. 244, p. 1609, § 1, effective August 7.
39-22-562. Apprenticeship tax credit -
tax preference performance statement - legislative declaration - definitions -
rules - repeal.
(1) (a)
The general assembly finds and declares that:
(I)
Colorado is committed to accelerating new apprenticeship program growth on a
diverse basis, especially in new and emerging industries that have been
traditionally underrepresented in registered apprenticeships; and
(II)
Many employers are interested in providing high-quality registered
apprenticeships to address their skilled worker shortages but face financial
barriers, especially small businesses.
(b) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purpose of the tax credit provided for in this section is to induce
certain designated behavior by taxpayers and to provide a reduction in income
tax liability for certain businesses that hire apprentices. Specifically, this
tax expenditure is intended to incentivize the hiring of apprentices and growth
of registered apprenticeship programs in new and emerging industries.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (1)(b) of this
section based on the number and value of the credits claimed.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Apprentice" has the same meaning as set forth in section 8-15.7-101
(1).
(b)
"Certificate of registration" has the same meaning as set forth in
section 8-15.7-101 (6).
(c)
"Credit" means the credit against income tax created in this section.
(d)
"Department" means the department of revenue.
(e)
"Employee" has the same meaning as set forth in section 39-22-604
(2)(a); except that "employee" includes only those individuals who
perform services for the taxpayer for at least one thousand forty hours per
income tax year.
(f)
"New and emerging industry" does not include the building and
construction trades as described in section 8-15.7-105 (4).
(g)
"Qualified taxpayer" or "taxpayer" means a person subject
to tax pursuant to this article 22 that is doing business in this state and
that employs an apprentice in the relevant tax year.
(h)
"Registered apprenticeship program" has the same meaning as set forth
in section 8-15.7-101 (13).
(i)
"Small business" means a business with fewer than fifty employees.
(j)
"State apprenticeship agency" or "SAA" has the same meaning
as set forth in section 8-15.7-101 (16).
(3) (a)
Subject to the limitations set forth in subsection (3)(b) of this section, for
income tax years commencing on or after January 1, 2025, but before January 1,
2035, a qualified taxpayer in a new and emerging industry is allowed an
apprenticeship tax credit against the income tax imposed by this article 22 for
each apprentice who is an employee of the taxpayer in this state for no less
than six months during the taxpayer's income tax year. The credit is equal to
up to six thousand three hundred dollars for six months of employment plus up
to one thousand fifty dollars for each additional month of employment, for a
maximum of twelve thousand six hundred dollars per apprentice per income tax
year; except that the taxpayer shall not claim a credit for:
(I)
More than ten apprentices per income tax year;
(II)
The same apprentice for more than two consecutive income tax years; and
(III)
An apprentice for months when the apprentice did not receive wages from the
taxpayer.
(b) A
qualified taxpayer must either:
(I)
Have established a registered apprenticeship program in good standing with the
SAA and received a certificate of registration from the state apprenticeship
agency; or
(II) Be
an employer-partner of a registered apprenticeship program in good standing
with the SAA as verified by the qualified taxpayer's inclusion on the Colorado
state apprenticeship resource directory pursuant to section 8-83-308.
(c) To
claim the credit, the taxpayer must reserve the credit as set forth in
subsection (4) of this section and annually apply for and receive an income tax
credit certificate from the state apprenticeship agency pursuant to subsection
(5) of this section.
(4) (a)
To claim a credit pursuant to this section, a taxpayer must submit an
application for the reservation of a tax credit to the SAA in the form and
manner prescribed by the SAA.
(b) The
SAA shall review all submitted applications to:
(I)
Determine whether the applicant is a qualified taxpayer;
(II)
Determine whether the applicant has complied with the requirements of
subsection (3)(b) of this section;
(III)
Determine whether the individual for whom the application is submitted is an
apprentice, is an employee, and complies with any standards set forth in
article 15.7 of title 8; and
(IV)
Calculate the number of months each prospective apprentice is expected to be
employed.
(c) (I)
Based upon the number of apprentices the qualified taxpayer expects to employ,
and the number of months each apprentice is expected to be employed, the SAA
may reserve for the benefit of each qualified taxpayer all or part of the
credit amount requested by the qualified taxpayer; except that the SAA shall
not reserve an amount in excess of the credit allowed by subsection (3)(a) of
this section.
(II)
The aggregate amount of credits reserved for all qualified taxpayers must not
exceed fifteen million dollars per calendar year. The SAA may reserve credits
for the current or any future calendar year based upon the expected employment
dates indicated in a qualified taxpayer's application. For a qualified taxpayer
whose income tax year is not a calendar year, the reservation is effective for
the income tax year that begins during the calendar year for the reservation.
(III)
If, for any calendar year, the aggregate amount of reservations for tax credits
the SAA has approved is equal to the total amount of tax credits available for
reservation for a current or future calendar year, the SAA shall notify all
qualified taxpayers that have submitted applications then awaiting approval or
that have submitted applications for approval after the calculation is made
that additional approvals of applications for reservations of tax credits shall
not be granted for the calendar year. The pending applications must remain
pending in the order received for up to two years after the date the original
application is received by the SAA and shall be considered for reservations of
tax credits in the event that additional credits become available pursuant to
subsection (5)(b) of this section.
(d) (I)
If the SAA reserves credits for the benefit of a qualified taxpayer, the SAA
shall notify the qualified taxpayer of the reservation and the amount reserved.
The reservation of tax credits does not entitle the qualified taxpayer to an
issuance of a tax credit certificate until the qualified taxpayer complies with
all of the requirements of this section or standards of the SAA for the
issuance of a tax credit certificate.
(II)
The SAA shall notify any qualified taxpayer for which the SAA did not reserve a
credit under subsection (4)(c) of this section of its decision in writing. If
the SAA determines that a qualified taxpayer's application is incomplete or
that the application does not comply with the requirements of this section or
the standards established by the SAA, the SAA shall remove the application from
the review process and notify the qualified taxpayer in writing of its
decision.
(5) (a)
(I) A qualified taxpayer shall submit an application to the SAA for an
income tax credit certificate to claim the credit allowed by this section on a
form and in a manner prescribed by the SAA. The application must include
identifying information for each apprentice employed in the state for which the
qualified taxpayer is submitting an application for a tax credit, the amount of
credit requested, and sufficient information to allow the SAA to make a
determination that:
(A) The
taxpayer meets the requirements set forth in this section;
(B) The
apprentice for whom the application is submitted meets the standards set forth
in article 15.7 of title 8; and
(C) The
apprentice for whom the application is submitted has not been the subject of a
taxpayer's application for more than two income tax years.
(II)
Except as provided in subsection (5)(b)(II) of this section, the SAA:
(A) May
issue one income tax credit certificate per income tax year to each qualified
taxpayer that, at a minimum, specifies the taxpayer's identifying information
and the total amount of the credit allowed; and
(B)
Shall not issue an income tax credit certificate in excess of the amount
reserved for the qualified taxpayer for the calendar year pursuant to
subsection (4) of this section.
(b) If
the actual aggregate amount of income tax credit certificates issued for a
calendar year is less than the maximum aggregate amount of credits allowed to
be reserved for all qualified taxpayers, the SAA shall apply the remaining
balance in the following order:
(I)
Reserve the remaining balance for any applications pending in order of priority
pursuant to subsection (4)(c)(III) of this section; and
(II)
Issue an additional tax credit certificate up to the amount allowed pursuant to
subsection (3)(a) of this section to any qualified taxpayer whose actual credit
earned exceeded the amount reserved pursuant to subsection (4) of this section.
(c) (I)
The SAA shall maintain a database of any information determined necessary by
the SAA to evaluate the effectiveness of the income tax credit allowed in this
section in meeting the purpose set forth in subsection (1)(b) of this section
and shall provide such information, and any other information that may be
needed, if available, to the state auditor as part of the state auditor's
evaluation of the tax expenditure required by section 39-21-305.
(II)
The SAA shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report for the preceding tax year listing
each qualified taxpayer to which the SAA issued an income tax credit
certificate and that includes the following information:
(A) The
taxpayer's name;
(B) The
amount of the income tax credit that the tax credit certificate indicates the
taxpayer is eligible to claim; and
(C) The
taxpayer's social security number or the taxpayer's Colorado account number and
federal employer identification number.
(III)
(A) The SAA shall prescribe forms and promulgate rules pursuant to article 4
of title 24 establishing the standards for which an income tax credit
certificate under this subsection (5) is issued.
(B) In
establishing the standards required by subsection (5)(c)(III)(A) of this
section, the SAA shall obtain input from employers and apprentices on elements
of program quality for registered apprenticeship programs in new and emerging
industries.
(C)
Qualified taxpayers that have previously claimed the income tax credit and seek
to claim the income tax credit in future tax years shall provide information
regarding how they have satisfied the standards issued pursuant to subsection
(5)(c)(III)(A) of this section related to program quality in their
reapplication for the income tax credit.
(IV)
The SAA shall conduct outreach to small businesses to ensure they are aware of
the tax credit and provide technical assistance to minimize the administrative
burden of submitting an application for the reservation of a tax credit.
(6) To
claim the credit authorized by this section, a taxpayer shall file the income
tax credit certificate with the taxpayer's state income tax return. The amount
of the credit that the taxpayer may claim pursuant to this section is the
amount stated on the income tax credit certificate.
(7) If
a taxpayer claims the credit allowed in this section, the taxpayer shall not
claim a credit for the same apprentice pursuant to section 39-22-531,
39-30-105.1, or 39-30.5-105.
(8) If
an income tax credit authorized in this section exceeds the income tax due on
the income of the taxpayer for the taxable year, the excess credit shall not be
carried forward and must be refunded to the taxpayer.
(9)
This section is repealed, effective December 31, 2037.
Source:
L. 2024: Entire
section added, (HB 24-1439), ch. 163, p. 770, § 1, effective May 10.
39-22-563. Tax credit for freight rail
use - tax preference performance statement - legislative declaration -
definitions - repeal.
(1) Tax
preference performance statement.
(a) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purposes of the tax credit provided in this section are to provide tax
relief to certain businesses, specifically those businesses engaged in new or
expanded manufacturing, repair or refurbishing, agriculture, recycling,
distribution centers for consumer products, or energy production that will
utilize freight rail that is in danger of going out of service due to coal
production reductions and closures, and to induce certain designated behaviors
by taxpayers, specifically expenditures on freight rail transportation service
in a coal transition community.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credits awarded pursuant to this section in achieving the purposes
specified in subsection (1)(a) of this section based on the number and value of
tax credits claimed pursuant to this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Certified freight rail use" means the use of freight rail
transportation:
(I) Of
freight either originating or terminating at a business located in a coal
transition community; and
(II) On
a rail line in this state that the department of transportation has determined
is at risk of inactivity or abandonment due to a lack of demand resulting from
coal transition.
(b)
"Coal transition community" has the same meaning as set forth in
section 8-83-502 (1).
(c)
"Department" means the department of revenue.
(d)
"Freight rail use plan" means a plan submitted by a qualified
applicant to the office pursuant to subsection (4) of this section.
(e)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(f)
"Qualified applicant" means a person subject to tax under this
article 22 whose engagement in manufacturing, agriculture, repairing or
refurbishing, recycling, distribution centers for consumer products, or energy
production with a regular demand for substantial new or expanded rail freight
transportation causes the person to incur a qualified expenditure.
(g)
"Qualified expenditure" means the amount paid by a qualified
applicant for certified freight rail use.
(3) Reservation
of tax credit and tax credit allowed.
(a) On
or after January 1, 2025, but prior to January 1, 2036, the office may reserve
the allocation of a credit against the income taxes imposed by this article 22
for a qualified applicant pursuant to subsection (5) of this section.
(b) In
order to claim a tax credit reserved pursuant to subsection (5) of this
section, a qualified applicant must, on or before December 31, 2038, execute
the freight rail use plan that it submits to the office pursuant to subsection
(4) of this section.
(c) For
income tax years commencing on or after January 1, 2026, and before January 1,
2039, a qualified applicant is allowed a credit against the income taxes
imposed by this article 22 in the amount set forth in the tax credit
certificate issued by the office pursuant to subsection (6) of this section.
(4) Submission
and review of application, freight rail use plan, and qualified expenditures
estimate.
(a) To
receive a tax credit reservation pursuant to subsection (4)(b) of this section,
a qualified applicant must submit an application, freight rail use plan, and
qualified expenditures estimate to the office in accordance with policies and
procedures created by the office. At a minimum, the application must include an
estimate of the amount of qualified expenditures that the qualified applicant
expects to incur for one or more future tax years for which the applicant is
applying for the tax credit reservation.
(b) The
office shall review a qualified applicant's application, freight rail use plan,
and qualified expenditures estimate to:
(I)
Determine whether such information is complete;
(II)
Make preliminary determinations of whether the applicant is a qualified
applicant and whether the freight rail use plan will result in a certified
freight rail use;
(III)
Make final determinations of whether the applicant is a qualified applicant and
whether the freight rail use plan will result in a certified freight rail use;
and
(IV)
Determine which freight rail use plans to approve in connection with the
reservation of a tax credit as provided in subsection (5) of this section.
(c) For
any application, freight rail use plan, and qualified expenditures estimate
that the office determines pursuant to subsection (4)(b)(I) of this section is
incomplete, the office shall notify the qualified applicant in writing of the
office's determination and remove the application, freight rail use plan, and
qualified expenditures estimate from the review process.
(d) The
office shall make the preliminary determinations, pursuant to subsection
(4)(b)(II) of this section, of whether the applicant is a qualified applicant
and whether the freight rail use plan is a certified freight rail use within
ninety days of receiving the application, freight rail use plan, and qualified
expenditures estimate pursuant to subsection (4)(b) of this section.
(e) The
office shall develop standards in consultation with the just transition office
created in section 8-83-503 (1) and the department of transportation to inform
the office's determinations, pursuant to subsection (4)(b)(III) of this
section, of whether the applicant is a qualified applicant and whether the
freight rail use plan will result in a certified freight rail use.
(f) In
making the determination, pursuant to subsection (4)(b)(IV) of this section, of
which freight rail use plans to approve for the reservation for the benefit of
the qualified applicant of an allocation of a tax credit, the office shall
prioritize freight rail use plans that:
(I)
Specify regular, frequent, ongoing, and substantial long-term freight rail use;
(II)
Provide substantial economic development benefits;
(III)
Demonstrate financial viability;
(IV)
Incorporate environmentally responsible and sustainable use of resources; and
(V)
Incentivize a diverse group of businesses and sectors to use targeted rail
lines.
(5) Reservation
of tax credits. Subject to subsection (7) of this section, the office may
reserve a tax credit for the benefit of a qualified applicant for any future
tax year in an amount not to exceed seventy-five percent of the qualified
applicant's qualified expenditure estimate submitted by the qualified applicant
pursuant to subsection (4)(a) of this section. If the office reserves a tax
credit for the benefit of a qualified applicant, the office shall notify the
qualified applicant in writing of the reservation and the amount reserved. The
reservation of a tax credit by the office for a qualified applicant does not
entitle the qualified applicant to the issuance of a tax credit certificate
until the qualified applicant complies with all the requirements specified in
this section for the issuance of the tax credit certificate. When the office
approves a reservation of tax credits, the office may also impose additional
requirements that a qualified applicant shall satisfy as part of executing a freight
rail use plan before the office issues a tax credit certificate to the
applicant. The office may use the reservation of a tax credit in support of
business recruitment and expansion.
(6) Deadline
for incurring qualified expenditures - proof of compliance - audit of freight
rail use plan execution - issuance of tax credit certificate.
(a) A
qualified applicant receiving a reservation of tax credits pursuant to
subsection (5) of this section shall incur the qualified expenditures described
in the qualified expenditures estimate submitted by the qualified applicant
pursuant to subsection (4)(a) of this section in the tax years set forth in the
qualified expenditures estimate and in the reservation made by the office
pursuant to subsection (5) of this section.
(b)
After executing a freight rail use plan, the qualified applicant shall notify
the office that it has done so and shall annually certify the relevant
qualified expenditures. In this notice, the applicant shall include a review of
the certification that aligns with office policies for certification of
qualified expenditures by a licensed certified public accountant that is not
affiliated with the qualified applicant. The applicant shall also certify and
provide documents demonstrating that the applicant satisfied any requirements
imposed by the office pursuant to subsection (5) of this section. Within one
hundred eighty days after receipt of such documentation from the qualified
applicant, the office shall review the qualified applicant's documentation of
qualified expenditures, determine whether the documentation satisfies the
freight rail use plan and other requirements, and, if the office determines
that the documentation satisfies the freight rail use plan and other
requirements, the office shall issue a tax credit certificate in an amount
equal to seventy-five percent of the amount of the actual qualified
expenditures incurred by the qualified applicant, subject to subsection (6)(d)
of this section.
(c) If
the office determines that a qualified applicant has failed to comply with the
requirements of subsection (6)(a) or (6)(b) of this section, the office shall
promptly notify the qualified applicant and may rescind the issuance of the
written notice it previously gave the qualified applicant granting the
reservation of a tax credit in whole or in part. If the office so rescinds an
issuance of the written notice, the qualified applicant may submit a new
application, freight rail use plan, and qualified expenditures estimate in
accordance with the requirements of subsection (4) of this section, and the
total amount of tax credits made available for reservation in the calendar year
during which the office rescinds the issuance of the written notice must
increase by the amount of the tax credit reserved in the written notice.
(d)
Notwithstanding subsection (6)(b) of this section, the total amount of the tax
credit certificate issued for any particular freight rail use plan must not
exceed the amount of the tax credit reserved by the office pursuant to
subsection (5) of this section.
(e) To
the extent that the actual qualified expenditures incurred by a qualified
applicant are less than the amount described in the relevant reservation issued
by the office for a tax year pursuant to subsection (5) of this section, the
total amount of tax credits made available for reservation in the calendar year
in which the qualified applicant filed the certification required by subsection
(6)(b) of this section must increase by the difference between actual qualified
expenditures incurred by the qualified applicant and the amount described in
the relevant reservation issued by the office for a tax year pursuant to
subsection (5) of this section.
(f) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report for the preceding tax year listing
each taxpayer to which the office issued a tax credit certificate and that
includes the following information:
(I) The
taxpayer's name;
(II)
The amount of the income tax credit that the certificate indicates the taxpayer
is eligible to claim; and
(III)
The taxpayer's social security number or the taxpayer's Colorado account number
and federal employer identification number.
(7) Limit
on aggregate amount of all tax credits that the office may reserve.
(a) The
aggregate amount of all tax credits that the office may reserve pursuant to
this section must not exceed five million dollars in any calendar year, in
addition to the amount of any previously reserved tax credits that were
rescinded or not utilized pursuant to subsections (6)(c) and (6)(e) of this
section during the calendar year and the amount described in subsection (7)(c)
of this section. In the case of a tax credit reserved for the benefit of a
qualified applicant that files an income tax return for a tax year other than a
calendar year, the amount reserved must count against the limit for the
calendar year in which the qualified applicant's income tax year begins.
(b) The
amount of each tax credit that the office may reserve is determined pursuant to
subsection (5) of this section; except that, if the office determines that
reserving each tax credit certificate in an amount determined pursuant to
subsection (5) of this section will cause the total amount of tax credits
reserved by the office for a calendar year to exceed the limit set forth in
subsection (7)(a) of this section, the office shall proportionally reduce the
amount of each tax credit reservation so that the total amount of tax credits
reserved by the office for that calendar year equals the limit set forth in
subsection (7)(a) of this section.
(c) If
the aggregate amount of all tax credits reserved by the office for any calendar
year is less than the amount available as calculated pursuant to subsection
(7)(a) of this section, then the aggregate amount of all tax credits that the
office may reserve in the next calendar year is increased by the unreserved
amount.
(8) Filing
tax credit certificate with income tax return. In order to claim the tax
credit authorized by this section, a qualified applicant shall file the tax
credit certificate issued by the office pursuant to subsection (6) of this
section with the qualified applicant's state income tax return. The amount of
the tax credit that a qualified applicant may claim pursuant to this section is
the amount stated on the tax credit certificate.
(9) Refundability.
The entire tax credit to be issued pursuant to this section may be claimed by
the qualified applicant for the qualified expenditures made in the taxable year
in which the qualified applicant executes a freight rail use plan. If the
amount of the tax credit allowed pursuant to this section exceeds the amount of
income taxes otherwise due on the income of the qualified applicant in the
income tax year for which the tax credit is being claimed, the entire amount of
the tax credit not used as an offset against income taxes in the income tax
year is refunded to the qualified applicant.
(10) Policies
and procedures. The office may create and modify policies and procedures
as necessary to further implement this section and shall solicit advice from
the department in creating and modifying such policies and procedures.
(11) Insufficient
taxpayer interest. Notwithstanding any law to the contrary, for calendar
years beginning on or after January 1, 2031, the office may determine that
there is insufficient taxpayer interest to continue offering the tax credit
pursuant to this section. After the office makes such a determination, it shall
not accept any more applications for tax credits pursuant to this section and
it shall inform the department that it has discontinued the credit.
(12) Repeal.
This section is repealed, effective December 31, 2045.
Source:
L. 2024: Entire
section added, (SB 24-190), ch. 280, p. 1862, § 5, effective August 7.
Editor's
note: This section
was numbered as § 39-22-560 in SB 24-190 but was renumbered on revision for
ease of location.
Cross
references: For
the legislative declaration in SB 24-190, see section 1 of chapter 280, Session
Laws of Colorado 2024.
39-22-564. New railroad operator tax
credit - tax preference performance statement - legislative declaration -
definitions - rules - repeal.
(1) Tax
preference performance statement.
(a) In
accordance with section 39-21-304 (1), which requires each bill that creates a
new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly finds and declares
that the purposes of the tax credit provided in this section are to provide tax
relief to certain businesses, specifically railroad operators, and to induce
certain designated behavior by taxpayers, specifically maintaining rail line
access to coal transition communities.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsection (1)(a) of this
section based on the number and value of tax credits claimed pursuant to this
section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Coal transition community" means a tier one transition community as
defined in section 8-83-502 (10).
(b)
"Department" means the department of revenue.
(c)
"Qualified expenditure" means direct operating and capital
improvement expenditures necessary to maintain or improve a qualified rail
line.
(d)
"Qualified rail line" means a rail line in this state that the
department of transportation has determined is both:
(I) At
risk of inactivity or abandonment due to a lack of demand; and
(II)
Covered by an access agreement for passenger rail access on the line between
the qualified taxpayer and the state through at least January 1, 2038.
(e)
"Qualified taxpayer" means a common carrier engaged in the
transportation of freight on a qualified rail line.
(3) Tax
credit allowed. For income tax years commencing on or after January 1,
2027, but before January 1, 2038, a qualified taxpayer is allowed a credit
against the income taxes imposed by this article 22 in an amount equal to the amount
stated on the tax credit certificate issued by the department of transportation
pursuant to subsection (4)(c) of this section.
(4) Application
- tax credit certificate issuance.
(a) (I)
In order to claim a tax credit pursuant to this section, a taxpayer must submit
an application to the department of transportation on or before December 31 of
the year for which the taxpayer wishes to claim the tax credit, and the
taxpayer must submit the application in a form and manner determined by the
department.
(II) A
taxpayer's application submitted pursuant to subsection (4)(a)(I) of this
section must include a certification of the taxpayer's qualified expenditures
and a review of the certification that aligns with department of transportation
policies for certification of qualified expenditures by a licensed certified
public accountant that is not affiliated with the taxpayer.
(b) The
department of transportation shall review a taxpayer's application submitted
pursuant to subsection (4)(a) of this section to determine:
(I)
Whether the taxpayer is a qualified taxpayer;
(II)
Whether the taxpayer incurred qualified expenditures;
(III)
The amount of the qualified expenditures incurred by the taxpayer; and
(IV)
The amount of the tax credit that the taxpayer may claim for the relevant tax
year, which amount must not exceed seventy-five percent of the amount of
qualified expenditures incurred by the taxpayer.
(c)
Upon approving a qualified taxpayer's application and making the determinations
described in subsection (4)(b) of this section, and subject to the limitations
set forth in subsection (5) of this section, the department of transportation
shall issue a tax credit certificate to the qualified taxpayer in an amount
equal to the amount determined by the department of transportation pursuant to
subsection (4)(b)(IV) of this section.
(d) The
department of transportation shall, in a sufficiently timely manner to allow
the department to process returns claiming the tax credit allowed in this
section, provide the department with an electronic report for the preceding tax
year that lists each qualified taxpayer to which the department of
transportation issued a tax credit certificate and includes the following
information:
(I) The
qualified taxpayer's name;
(II)
The amount of the income tax credit that the certificate indicates the
qualified taxpayer is eligible to claim; and
(III)
The qualified taxpayer's social security number or the qualified taxpayer's
Colorado account number and federal employer identification number.
(5) Limit
on aggregate amount of all tax credits that the department of transportation
may reserve.
(a) The
aggregate amount of all tax credit certificates that the department of
transportation may issue pursuant to this section must not exceed five million
dollars in any calendar year, in addition to the amount of any previously
issued tax credit certificates that were rescinded or not utilized during the
calendar year and the amount described in subsection (5)(c) of this section. In
the case of a tax credit certificate issued for the benefit of a qualified
taxpayer that files an income tax return for a tax year other than a calendar
year, the amount in the tax credit certificate must count against the limit for
the calendar year in which the qualified applicant's income tax year begins.
(b) The
amount of each tax credit that the department of transportation may issue in a
tax credit certificate is determined pursuant to subsection (4) of this
section; except that, if the department of transportation determines that the
issuing of each tax credit certificate in an amount determined pursuant to
subsection (4) of this section will cause the total amount of tax credit
certificates issued by the department of transportation for a calendar year to
exceed the limit set forth in subsection (5)(a) of this section, the department
of transportation shall proportionally reduce the amount of each tax credit
certificate issued by the department of transportation so that the total amount
of tax credit certificates issued by the department of transportation for that
calendar year equals the limit set forth in subsection (5)(a) of this section.
(c) If
the aggregate amount of all tax credit certificates issued by the department of
transportation for any calendar year is less than the amount available as
calculated pursuant to subsection (5)(a) of this section, then the aggregate
amount of all tax credit certificates that the department of transportation may
issue in the next calendar year is increased by the unissued amount.
(d) If,
pursuant to section 39-22-563 (11), the Colorado office of economic development
determines that there is insufficient interest in the tax credit offered
pursuant to section 39-22-563, the aggregate amount of all tax credit
certificates that the department of transportation may issue is increased by
five million dollars for each of the following calendar years through calendar
year 2037.
(6) Refundability.
If the amount of the tax credit allowed pursuant to this section exceeds the
amount of income taxes otherwise due on the income of the qualified taxpayer in
the income tax year for which the credit is being claimed, the amount of the
credit not used as an offset against income taxes in the income tax year is
refunded to the qualified taxpayer.
(7) Filing
tax credit certificate with income tax return. In order to claim the tax
credit authorized by this section, a qualified taxpayer shall file the tax
credit certificate issued by the department of transportation pursuant to
subsection (4)(c) of this section with the qualified taxpayer's state income tax
return. The amount of the tax credit that a qualified taxpayer may claim
pursuant to this section is the amount stated on the tax credit certificate.
(8) Compliance
monitoring and recapture.
(a) If,
as of the last day of any taxable year during the compliance period, the
qualified rail line is not in good operating condition or the qualified
taxpayer is not meeting one or more of the service criteria specified in access
agreements to the qualified rail line for passenger operations, the department
of transportation shall notify the qualified taxpayer and the department that
all or a portion of the total amount of the tax credits allowed to the
qualified taxpayer pursuant to this section for the tax year that preceded the
compliance period and any tax year thereafter is disallowed. The qualified
taxpayer shall add the amount of the tax credit that is disallowed to its
return as a recaptured tax credit for the taxable year in which the tax credit
is disallowed pursuant to this subsection (8).
(b) (I)
The department of transportation shall establish reporting requirements to
monitor compliance with this subsection (8), including requirements regarding
the reporting of the status of a qualified rail line by the qualified taxpayer
and whether the qualified taxpayer is or is not meeting any service criteria
specified in access agreements.
(II) If
a dispute arises about whether a qualified rail line is not in good operating
condition or the qualified taxpayer is not meeting any service criteria
specified in access agreements, the department of transportation shall resolve
the dispute and notify the department of the resolution.
(c) As
used in this subsection (8), unless the context otherwise requires,
"compliance period" means the period of three years following any
year in which the qualified taxpayer claimed a tax credit pursuant to this
section.
(9) Application
of tax credit. A qualified taxpayer who claims a tax credit pursuant to
this section shall provide the state or other passenger rail operator full
credit for the value of that tax credit against any costs, fees, or other
charges that the qualified taxpayer may charge for passenger rail operations
access, operations, or maintenance on the qualifying rail line pursuant to an
access agreement between the qualified taxpayer and the state for passenger
rail access.
(10) Rules.
The department of transportation and the department may promulgate rules in
accordance with article 4 of title 24 as may be necessary to effectuate the
purposes of this section.
(11) Repeal.
This section is repealed, effective December 31, 2045.
Source:
L. 2024: Entire
section added, (SB 24-190), ch. 280, p. 1867, § 5, effective August 7.
Editor's
note: This section
was numbered as § 39-22-561 in SB 24-190 but was renumbered on revision for
ease of location.
Cross
references: For
the legislative declaration in SB 24-190, see section 1 of chapter 280, Session
Laws of Colorado 2024.
39-22-565. Workforce shortage tax
credit - tax preference performance statement - report - legislative
declaration - definitions - repeal.
(1) Tax
preference performance statement. In accordance with section 39-21-304
(1), which requires each bill that creates a new tax expenditure to include a
tax preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that:
(a) The
general legislative purposes of the tax credit allowed by this section are:
(I) To
induce certain designated behavior by taxpayers; and
(II) To
provide tax relief for certain businesses or individuals.
(b) The
specific legislative purpose of the tax credit allowed by this section is to
encourage workforce development in industries that are facing worker shortages
by providing financial assistance for facility improvement and equipment
acquisition costs associated with training programs designed to alleviate
worker shortages.
(c) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsections (1)(a) and (1)(b)
of this section based on the information required to be maintained and reported
by the office pursuant to subsection (12) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Applicant" means a person subject to tax pursuant to this article
22, an entity that is exempt from taxation pursuant to section 39-22-112 (1),
or a political subdivision of the state.
(b)
"Application" means an application in the form and manner approved by
the office for the tax credit allowed in this section.
(c)
"Department" means the department of revenue.
(d)
"Federal investments" means the federal "Infrastructure
Investment and Jobs Act", Pub.L. 117-58, the federal "Inflation
Reduction Act of 2022", Pub.L. 117-169, and the federal "CHIPS and
Science Act of 2022", Pub.L. 117-167.
(e)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(f)
"Potential qualified asset" means an asset that may be a qualified
asset upon the determination of the office.
(g)
"Qualified applicant" means an applicant that makes a qualified
investment to train individuals in a qualified industry and that is selected
pursuant to subsection (5) of this section.
(h) (I)
"Qualified asset" means:
(A)
Land in this state;
(B)
Buildings, fixtures, and other structural components of buildings in this state
for which the applicant is allowed a deduction for depreciation pursuant to
section 167 of the internal revenue code, including purchasing or constructing
a facility, renovating a facility, making tenant improvements, and funding a
capital lease with capitalized labor, construction, and installation costs;
(C)
Tangible personal property acquired for use exclusively in this state for which
the applicant is allowed a deduction for depreciation pursuant to section 167
of the internal revenue code; and
(D)
Computer software acquired for use exclusively in this state for which the
applicant is allowed a deduction for depreciation under section 167 of the
internal revenue code.
(II)
For purposes of this subsection (2)(h), if an applicant is not subject to
federal income tax, the applicant is deemed to be allowed a deduction for
depreciation if such a deduction would have been allowed were the applicant
subject to federal income tax.
(i)
"Qualified industry" means an industry affected by federal
investments that has a demonstrated workforce shortage, as determined by the
office as specified in the policies and procedures developed by the office
pursuant to subsection (13) of this section.
(j)
"Qualified investment" means the amount paid by a qualified applicant
to acquire, construct, reconstruct, or erect a qualified asset to the extent
the amount paid reflects new activity and to the extent the amount is required
to be capitalized pursuant to the internal revenue code or the amount is
allowed to be deducted under section 179 of the internal revenue code.
(k)
"Selection committee" means a selection committee appointed by the
office consisting of members who have expertise and experience as employers, in
education, or in other relevant areas.
(3) Tax
credit allowed.
(a)
Except as provided in subsection (3)(c) of this section, a qualified applicant
is allowed to use a tax credit certificate issued by the office pursuant to
subsection (8) of this section against the income taxes imposed by this article
22 in the income tax year that the qualified applicant places a qualified asset
in service in the amount specified on the tax credit certificate issued by the
office; except that the tax credit certificate may not be used in an income tax
year commencing before January 1, 2026, and may not be used in an income tax
year commencing on or after January 1, 2033.
(b) In
order to claim the tax credit allowed pursuant to this section, the qualified
applicant must submit an application as specified in subsection (5) of this
section, place the qualified asset into service before January 1, 2033, obtain
a tax credit certificate from the office as specified in subsection (8) of this
section, and, once issued by the office, file the tax credit certificate with
the qualified applicant's income tax return as specified in subsection (9) of
this section.
(c) A
tax credit is not allowed pursuant to this section if:
(I) The
amount refunded pursuant to subsection (10) of this section is used to supplant
local, state, or federal money that would otherwise be appropriated; or
(II)
The qualified applicant expends money received from the state to offset at
least half of a qualified investment, not including the amount refunded
pursuant to subsection (10) of this section.
(4) Tax
credit administration. Except as otherwise provided in subsection (7) of
this section, the office is the administrator of the tax credit allowed by this
section.
(5) Application
submission and review.
(a) An
applicant that intends to claim a tax credit pursuant to this section shall
submit an application to the office.
(b) The
office shall accept applications for annual application periods by deadlines
established in the policies and procedures developed by the office pursuant to
subsection (13) of this section; except that the office may only receive
applications between January 1, 2025, and December 31, 2029.
(c) The
office shall review all submitted applications to determine whether:
(I) The
applicant is a qualified applicant; and
(II)
The application is complete and includes a description of a potential qualified
asset and the estimated qualified investment.
(d) If
the office determines that the application is complete and in compliance, the
office shall add the application to an evaluation pool for the application
period. Within a reasonable period after the end of the application period, the
office shall forward the evaluation pool to the selection committee for the
merit-based review described in subsection (7) of this section.
(e) If
the office determines that the application is incomplete or that it does not
comply with the requirements of this section or the policies and procedures
developed by the office pursuant to subsection (13) of this section, the office
shall remove the application from the review process and notify the applicant
in writing of its decision. An applicant may resubmit a disapproved application
to be evaluated in a future application period.
(6) Application
and issuance fees.
(a) (I)
For an application for which the amount of the tax credit requested by an
applicant pursuant to this section is two hundred fifty thousand dollars or
more, the office may impose a reasonable application fee on an applicant that
does not exceed five hundred dollars.
(II)
For an application for which the amount of the tax credit requested by an
applicant pursuant to this section is less than two hundred fifty thousand
dollars, the office may impose a reasonable application fee on an applicant
that does not exceed two hundred dollars.
(b) The
office may impose on a qualified applicant a reasonable issuance fee of up to
three percent of the amount of the tax credit specified on the tax credit
certificate issued by the office as specified in subsection (8) of this
section, which must be paid before the tax credit certificate is issued to the
qualified applicant.
(c) Any
fee revenue collected pursuant to this subsection (6) must be applied to the
administration of the tax credit created by this section.
(7) Merit-based
review and tax credit reservation.
(a) (I)
For each application period, the selection committee shall conduct a
merit-based review of the applications that have been placed in the evaluation
pool pursuant to subsection (5)(d) of this section. The selection committee
shall complete its review and award reservations within a reasonable period
after the end of the application period, not to exceed ninety days.
(II)
Except as provided in subsection (7)(a)(IV) of this section, based upon the
totality of the factors set forth in subsection (7)(c) of this section, the
selection committee may reserve for the benefit of a qualified applicant a tax
credit in an amount to be determined by the selection committee not to exceed
fifty percent of the estimated qualified investment; except that the aggregate
amount of tax credits reserved for all qualified applicants in an annual
application period may not exceed fifteen million dollars.
(III)
The selection committee may reserve tax credits to be used by a qualified
applicant for income tax years commencing on or after January 1, 2026, but
before January 1, 2033, based upon the anticipated date the qualified asset is
placed into service.
(IV) If
the September 2025 revenue forecast, and each September revenue forecast
through the September 2028 revenue forecast as prepared by either legislative
council staff or the office of state planning and budgeting, projects that
state revenues, as defined in section 24-77-201 (4), will not increase by at
least four percent for the current fiscal year, the aggregate amount of tax
credits reserved for all qualified applicants in the application period
commencing in the calendar year that begins during the current fiscal year is
reduced by fifty percent; except that, if the amount of a reduced tax credit
reservation is equal to or less than five hundred dollars, then the selection
committee shall not issue a tax credit reservation.
(b) (I)
If the selection committee reserves tax credits for the benefit of a qualified
applicant under subsection (7)(a) of this section, the selection committee
shall notify the office of the reservation and the amount of tax credits
reserved. The office shall notify the qualified applicant of the tax credit
reservation. The reservation of a tax credit does not entitle the qualified
applicant to an issuance of a tax credit certificate until the qualified
applicant complies with all the requirements specified in this section, by the
selection committee or by the office, for the issuance of a tax credit
certificate pursuant to subsection (8) of this section.
(II)
The office shall notify any qualified applicant in writing for which the
selection committee reserved no tax credit under subsection (7)(a) of this
section.
(c) (I)
In conducting the merit-based review pursuant to subsection (7)(a) of this
section, the selection committee shall consider the factors set forth in this
subsection (7)(c) in addition to any other factors the selection committee may
request the office to include in its policies and procedures developed pursuant
to subsection (13) of this section. The selection committee may weigh the
factors equally or differently.
(II)
The selection committee shall consider:
(A)
Whether the qualified applicant's qualified investment will influence
competitiveness in a qualified industry;
(B)
Whether the qualified applicant's qualified investment will result in increased
job placements in qualified industries or increased job placements with a
living wage in qualified industries;
(C) The
type, scope, and quality of the qualified applicant's qualified asset and the
resulting training of individuals in a qualified industry; and
(D)
Whether the qualified applicant's qualified investment will result in increased
training and workforce development in a qualified industry.
(d) The
selection committee may impose additional requirements on the qualified
applicant as a condition of awarding the tax credit reservation pursuant to
this subsection (7).
(8) Proof
of compliance - audit of eligible expenditure certification - issuance of tax
credit certificate. After a qualified applicant places a potential
qualified asset in service, the qualified applicant shall notify the office
that the potential qualified asset has been placed in service and shall certify
the qualified investment, after which the office shall make a final
determination whether the potential qualified asset is a qualified asset. The
qualified applicant shall include a review of the certification by a licensed
certified public accountant that is not affiliated with the qualified applicant
and that aligns with office policies for certification of a qualified
investment. The qualified applicant shall also certify and provide documents demonstrating
that the qualified applicant satisfied any additional requirements imposed by
the selection committee pursuant to subsection (7) of this section. Within a
reasonable time after receipt of such documentation from the qualified
applicant, the office shall review the qualified applicant's documentation of
certified qualified investment and determine whether the documentation
satisfies the requirements of the office, and, if the office determines that
the documentation satisfies the requirements of the office, the office shall
issue a tax credit certificate in the amount specified in the tax credit
reservation, not to exceed fifty percent of the certified qualified investment,
issued to the qualified applicant pursuant to subsection (7) of this section;
except that a tax credit certificate may not be issued for an income tax year
commencing before January 1, 2026, or for an income tax year commencing on or
after January 1, 2033.
(9) Filing
tax credit certificate with income tax return.
(a) In
order to claim the tax credit authorized by this section, a qualified applicant
shall file the tax credit certificate issued by the office pursuant to
subsection (8) of this section with the qualified applicant's state income tax
return. If the qualified applicant is a political subdivision of the state or
is exempt from tax pursuant to section 39-22-112 (1), the qualified applicant
shall file a return pursuant to section 39-22-601 (7)(b). The amount of the tax
credit that a qualified applicant may claim pursuant to this section is the
amount stated on the tax credit certificate.
(b) A
tax credit certificate issued to a partnership, a limited liability company
taxed as a partnership, or multiple owners of a property must be passed through
to the partners, members, or owners, including any nonprofit entity that is a
partner, member, or owner, respectively, on a pro rata basis or pursuant to an
executed agreement among the partners, members, or owners documenting an
alternate distribution method.
(10) Refundability.
If the amount of the tax credit allowed pursuant to this section exceeds the
amount of income taxes otherwise due on the income of the qualified applicant
in the income tax year for which the tax credit is being claimed, or the
qualified applicant is a political subdivision of the state or a person who is
exempt from taxation pursuant to section 39-22-112 (1), the amount of the tax
credit not used as an offset against income taxes in the income tax year is
refunded to the qualified applicant.
(11) Compliance
monitoring and recapture.
(a)
Except as provided in subsection (11)(b) of this section, if, as of the last
day of any taxable year during the compliance period, the equipment, building,
structure, or facility that was deemed a qualified asset is not being used as a
qualified asset, the office shall notify the qualified applicant and the
department that the tax credit allowed in this section is disallowed. The
qualified applicant shall add the full amount of the tax credit that was
actually used to offset the qualified applicant's income tax or refunded to the
qualified applicant to its return as a recaptured tax credit for the taxable
year in which the tax credit is disallowed pursuant to this subsection (11).
(b) The
potential increase in tax required pursuant to subsection (11)(a) of this
section does not apply:
(I) If
a building, structure, or facility is not a qualified asset as a result of a
casualty loss if the loss is restored by reconstruction or replacement within a
reasonable period established by the office;
(II)
Solely by reason of the disposition of a building, structure, or facility, or
an interest therein, if it is reasonably expected that the building, structure,
or facility will continue to be operated as a qualified asset for the remainder
of the compliance period; or
(III)
If a qualifying asset is replaced or upgraded in the normal course of its use.
(c) (I)
The office shall establish reporting requirements to monitor compliance with
this subsection (11) that shall include:
(A) A
disposition of a qualified asset by the qualified applicant;
(B) The
number of annual trainees who have used a qualified asset;
(C) The
geographic distribution of trainees who have used a qualified asset;
(D)
Demographic information about the trainees who have used a qualified asset;
(E) The
location and disposition of assets displaced by a qualified asset, if any; and
(F) To
the extent a qualified asset is used to expand or create a training facility,
an assessment of training capacity prior to implementation of the qualified
asset.
(II) If
a dispute arises about whether a potential qualified asset is a qualified
asset, the office shall adjudicate the dispute and notify the department of the
resolution.
(III)
Notwithstanding section 39-21-107 (2), if a qualified asset is disposed of
during any taxable year during the compliance period, and thereafter the asset
is not a qualified asset:
(A) The
qualified applicant shall add the full amount of the tax credit to its return
as a recaptured tax credit for the taxable year in which the tax credit is
disallowed pursuant to this subsection (11) notwithstanding the disposition of
the qualified asset;
(B) The
statutory period for the assessment of any deficiency with respect to the
disallowed tax credit must not expire before the expiration of three years from
the date the office is notified, in such a manner as the office determines,
that the structure is not a qualified asset; and
(C) The
department shall assess any deficiency before the expiration of such three-year
period together with any applicable interest and penalty imposed pursuant to
this article 22.
(d) As
used in this subsection (11), unless the context otherwise requires,
"compliance period" means the period of fifteen years following the
taxable year in which the qualified applicant placed the qualified asset in
service.
(12) Reporting.
(a) No
later than December 31, 2025, and, notwithstanding the requirement in section
24-1-136 (11)(a)(I), no later than December 31 of each year thereafter through
2033, the office shall provide a written report to the general assembly and
shall further make the report available to the public. In connection with tax
credits issued pursuant to this section, the report must include:
(I) The
number of qualified assets placed in service;
(II) A
description of the use or uses of each qualified asset and a statewide summary
of the number of qualified assets for each use; and
(III)
The amount of any disallowed tax credit recaptured pursuant to subsection (11)
of this section.
(b) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified applicant to which
the office issues a tax credit certificate for the preceding tax year that
includes the following information:
(I) The
qualified applicant's name;
(II)
The amount of the tax credit; and
(III)
The qualified applicant's social security number or the qualified applicant's
Colorado account number and federal employer identification number.
(c) The
office, the office of the state auditor, or the office of the state controller
may review the qualified applicant's finances, expenses, equipment, employment,
and training documentation relating to a qualified investment in a qualified
asset.
(13) Policies
and procedures.
(a) The
office may create and modify policies, procedures, and guidelines as necessary
to further administer the tax credits allowed pursuant to this section and
shall solicit advice from the department in creating and modifying such
policies, procedures, and guidelines.
(b) The
office shall develop standards for determining which industries are included as
a qualified industry for which a tax credit under this section is allowed to a
qualified applicant.
(c) Any
standards developed by the office pursuant to this subsection (13) must be
posted on the office's website. The office may annually review and update as
necessary standards developed pursuant to this subsection (13).
(d) The
office shall determine the annual application period.
(14) Workforce
development tax credit program cash fund.
(a) The
workforce development tax credit program cash fund is created in the state
treasury. The fund consists of gifts, grants, donations, and fee revenue
credited to the fund pursuant to subsection (6) of this section and any other
money that the general assembly may appropriate, transfer, or require by law to
be credited to the fund.
(b) The
state treasurer shall credit all interest and income derived from the deposit
and investment of money in the workforce development tax credit program cash
fund to the fund.
(c)
Money in the fund is continuously appropriated to the office for the purpose of
administering the tax credit issued pursuant to this section.
(d) The
state treasurer shall transfer all unexpended and unencumbered money in the
fund on December 31, 2050, to the general fund.
(15) Repeal.
This section is repealed, effective December 31, 2050.
Source:
L. 2024: Entire
section added, (HB 24-1365), ch. 478, p. 3352, § 7, effective August 7.
Cross
references: For
the legislative declaration in HB 24-1365, see section 1 of chapter 478,
Session Laws of Colorado 2024.
39-22-566. Qualified care worker tax
credit - tax preference performance statement - legislative declaration -
definitions - repeal.
(1) (a)
In accordance with section 39-21-304 (1), which requires each bill that creates
a new tax expenditure to include a tax preference performance statement as part
of a statutory legislative declaration, the general assembly declares that the
general legislative purpose of the tax credit allowed by this section is to
provide tax relief for certain businesses or individuals and that the specific
legislative purpose of the tax credit allowed by this section is to provide tax
relief to individuals working in the care workforce providing direct care.
(b) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purpose specified in subsection (1)(a) of this section
based on the number and value of credits that are claimed.
(2) As
used in this section, unless the context otherwise requires:
(a)
"Certified home care agency" has the same meaning as set forth in
section 25-27.5-102 (1).
(b)
"Certified nurse aide" means a person certified by the state board of
nursing pursuant to part 2 of article 255 of title 12.
(c)
"Child care worker" means a resident individual who is registered
with the department of early childhood's Colorado shines professional
development information system, or a successor system, and who provides care
for at least seven hundred twenty hours during the income tax year as:
(I) A
licensee and operator of an eligible program in this state;
(II) An
employee of an eligible program in this state; or
(III)
An informal family friend or neighbor child care worker in this state.
(d)
"Consumer-directed care employer" means a person receiving care
pursuant to parts 11 and 19 of article 6 of title 25.5 who employs a direct
care worker.
(e)
"Direct care worker" means a resident individual with the appropriate
knowledge, skills, and training who provides hands-on care and services,
including personal care, to participants receiving long-term care in this
state. "Direct care worker" does not include a certified nurse aide.
(f)
"Eligible program" means a licensed early childhood education program
or a licensed family child care home. "Eligible program" includes
only those licensed early childhood education programs and licensed family
child care homes with at least a level one quality rating pursuant to the
Colorado shines quality rating and improvement system created in section
26.5-5-101 for the entire income tax year, or that portion of the income tax
year for which the licensed early childhood education program or licensed
family child care home was licensed.
(g)
"Employee" has the same meaning as set forth in section 39-22-604
(2)(a).
(h)
"Employer" has the same meaning as set forth in section 39-22-604
(2)(b).
(i)
"Home- and community-based services" means any services provided in
this state pursuant to parts 3 to 13 or part 19 of article 6 of title 25.5.
(j)
"Informal family friend or neighbor child care worker" means an
individual described in section 26.5-5-304 (1)(f) who provides care for
children other than their own who are five years of age or younger; except that
an informal family friend or neighbor child care worker is not required to
provide care in the individual's permanent place of residence.
(k)
"Licensed early childhood education program" means an early childhood
education program, as defined in section 26.5-2-202 (3), that held a valid
license issued pursuant to part 3 of article 5 of title 26.5, during the income
tax year.
(l)
"Licensed family child care home" means a family child care home, as
defined in section 26.5-5-303 (7), that held a valid license issued pursuant to
part 3 of article 5 of title 26.5, during the income tax year.
(m)
"Long-term care" means:
(I)
Home- and community-based services;
(II)
Care provided at a nursing facility; and
(III)
Care provided by a certified home care agency.
(n)
"Long-term care employer" means an employer who employs one or more
direct care workers to provide long-term care in this state. "Long-term
care employer" includes a consumer-directed care employer.
(o)
"Nursing facility" has the same meaning as set forth in section
25.5-4-103 (14).
(p)
"Qualified direct care worker" means a direct care worker who is an
employee of one or more long-term care employers for at least seven hundred
twenty hours in total during the tax year.
(3) (a)
Subject to the requirements set forth in subsection (3)(b) of this section, for
income tax years commencing on or after January 1, 2025, but before January 1,
2029, each child care worker and qualified direct care worker is allowed a
credit against the income taxes imposed by this article 22 in the amount of one
thousand two hundred dollars. In the case of a child care worker or qualified
direct care worker who files a joint return with another resident individual
who is also a child care worker or a qualified direct care worker, the credit
allowed by this subsection (3)(a) is two thousand four hundred dollars.
(b) (I)
The credit allowed by this section is not allowed to a resident individual
whose adjusted gross income exceeds:
(A) In
the case of a resident individual who files a single return, seventy-five
thousand dollars; and
(B) In
the case of two resident individuals who file a joint return, one hundred
thousand dollars.
(II)
The limit set forth in subsection (3)(b)(I)(B) of this section applies to a
joint return regardless of whether one or both resident individuals are child
care workers or qualified direct care workers.
(III) A
resident individual who is both a child care worker and a qualified direct care
worker is not allowed an additional credit pursuant to this section on account
of such dual qualification.
(IV) In
the case of a part-year resident, the credit allowed by this section is
apportioned in the ratio determined in section 39-22-110 (1).
(4) (a)
On or before September 30, 2025, and each September 30 thereafter, the
department of health care policy and financing shall provide the department of
revenue an electronic report of the name and federal employer identification
number of every long-term care employer providing services in this state during
the calendar year.
(b) On
or before January 31, 2026, and each January 31 thereafter, the department of
early childhood shall provide the department of revenue with an electronic
report of child care workers eligible for the credit allowed by this section
for the preceding calendar year.
(5) (a)
On or before January 31, 2026, and each January 31 thereafter, every long-term
care employer that employed one or more direct care workers shall make an
information return to the executive director for the preceding calendar year.
The return must include each direct care worker's social security number or
individual taxpayer identification number, the total hours the direct care
worker worked as such during the calendar year, and any other information the
executive director may require. The long-term care employer shall report only
those employees who are direct care workers as defined in this section.
(b) The
return required by this subsection (5) must be filed electronically on or
before January 31 in addition to the return required by section 39-22-604 (6).
The executive director shall impose a penalty of five hundred dollars if the
long-term care employer fails to file the return required by this subsection
(5) on or before January 31, unless shown to have been due to reasonable cause,
or willfully files a false or fraudulent return, which penalty is in addition
to any criminal penalty otherwise provided for failure to file a return or for
filing a false or fraudulent return. The executive director shall assess and
collect the penalty imposed by this subsection (5)(b) in the same manner as an
underpayment of the tax imposed by this article 22.
(c) In
the case of a consumer-directed care employer, the department of health care
policy and financing, or the department's fiscal agent, shall file the return
required by this subsection (5).
(6) If
the credit allowed by this section exceeds the income tax imposed by this
article 22, the excess credit may not be carried forward and is refunded to the
taxpayer.
(7)
This section is repealed, effective December 31, 2034.
Source:
L. 2024: Entire
section added, (HB 24-1312), ch. 294, p. 2002, § 1, effective August 7. L.
2025: (2)(j), (2)(k), and (2)(l) amended, (HB 25-1296), ch. 202, p. 914, §
12, effective May 16; (2)(i) amended, (HB 25-1003), ch. 50, p. 223, § 5,
effective July 1.
Editor's
note: Subsections
(2)(a), (2)(b), (2)(c), and (2)(d) were numbered as subsections (2)(c), (2)(d),
(2)(a), and (2)(b), respectively, in HB 24-1312 but were renumbered on revision
to conform to statutory format.
Cross
references: For
the legislative declaration in HB 25-1296, see section 1 of chapter 202,
Session Laws of Colorado 2025.
39-22-567. Tax credit for investments
in fixed capital assets for a shared quantum facility - tax preference
performance statement - legislative declaration - definitions - report -
repeal.
(1) Tax
preference performance statement. In accordance with section 39-21-304
(1), which requires each bill that creates a new tax expenditure to include a
tax preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that:
(a) The
general legislative purposes of the tax credit allowed by this section are:
(I) To
induce certain designated behavior by taxpayers; and
(II) To
improve industry competitiveness;
(b) The
specific legislative purpose of the tax credit allowed by this section is to
induce a qualified applicant to invest in fixed capital assets to create a hub
that is a shared quantum facility that accomplishes translational research and
incubation, low-volume manufacturing and fabrication and rapid prototyping in a
laboratory environment and to provide related services and workforce
development to support the development of quantum businesses and the quantum
ecosystem in the state; and
(c) The
general assembly and the state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsections (1)(a) and (1)(b) of
this section based on the information reported by the office pursuant to
subsection (11) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Consortium" means a group of nonprofit or for-profit entities, or
both, that are jointly making qualifying investments in an eligible project to
create and operate a shared quantum facility. A consortium may include one or
more members exempt from tax pursuant to section 39-22-112.
(b)
"Department" means the department of revenue.
(c)
"Eligible project" means a capital project undertaken in the state to
create a shared quantum facility for which a qualified applicant makes
qualifying investments and that is approved by the office in accordance with
the policies, procedures, and guidelines for the implementation and
administration of the tax credit allowed by this section adopted by the office
pursuant to subsection (12) of this section.
(d)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(e) (I)
"Qualified applicant" means a nonprofit or for-profit entity that
submits an application for the reservation and issuance of tax credits to the
office pursuant to this section. An applicant may be a consortium as set forth
in subsection (4) of this section.
(II) A
"qualified applicant" includes a person that is exempt from taxation
pursuant to section 39-22-112.
(f) (I)
"Qualifying fixed capital assets" means:
(A)
Land in this state;
(B)
Buildings, fixtures, and other structural components of buildings in this state
for which the qualified applicant is allowed a deduction for depreciation
pursuant to section 167 of the internal revenue code, including purchasing or
constructing a facility, renovating a facility, making tenant improvements,
funding a capital lease, capitalized labor, construction, and installation
costs;
(C)
Tangible personal property acquired for use exclusively in this state for which
the qualified applicant is allowed a deduction for depreciation pursuant to
section 167 of the internal revenue code, including furniture, fixtures and
equipment such as outfitting an office, laboratory machines, refrigeration,
HVAC systems, piping, measuring, monitoring and instrumentation equipment,
fabrication machines, tools and equipment, and any hardware and software
developed by third parties necessary for quantum technology applications; and
(D)
Computer software acquired for use exclusively in this state for which the
qualified applicant is allowed a deduction for depreciation pursuant to section
167 of the internal revenue code.
(II)
"Qualifying fixed capital assets" is limited to property acquired,
constructed, reconstructed, or erected as part of a coordinated plan to create
a shared quantum facility.
(III)
For purposes of this subsection (2)(f), if a qualified applicant is not subject
to federal income tax, the qualified applicant is deemed to be allowed a
deduction for depreciation if such a deduction would have been allowed were the
qualified applicant subject to federal income tax.
(IV)
"Qualifying fixed capital assets" shall be acquired, constructed,
reconstructed, or erected where possible by a certified contractor on a
certified contractor list that is obtained from the Colorado department of
labor and employment and that contains the information specified in section
40-3.2-105.6 (3)(a).
(g)
"Qualifying investment" means the amount paid by a qualified
applicant to acquire, construct, reconstruct, or erect qualifying fixed capital
assets to the extent such amount is required to be capitalized pursuant to the
internal revenue code or such amount is allowed to be deducted under section
179 of the internal revenue code. "Qualifying investment" includes an
amount capitalized by a lessee of qualifying fixed capital assets for a lease
that is treated as a sale for federal income tax purposes.
(h)
"Quantum business" means a private for-profit trade or business or
nonprofit organization that has quantum technology as a key part of its
business model or organizational purpose, including but not limited to
manufacturing, testing, production, research and development, or enhancement of
hardware or software to perform or use quantum technology as a key input or
output of its business model, and companies that produce goods or services that
are key inputs for other quantum business.
(i)
"Shared quantum facility" means a primary place in the state where an
applicant performs activities and provides economic benefits related to
supporting quantum businesses and the quantum ecosystem.
(3) Credit
allowed.
(a)
Subject to the provisions of subsection (3)(c) of this section, for income tax
years commencing on or after January 1, 2025, but prior to January 1, 2033, a
qualified applicant is allowed a credit against the income taxes imposed by
this article 22 for placing an eligible project in service in an amount
specified on the credit certificate issued by the office pursuant to subsection
(7) of this section.
(b) To
claim the credit allowed pursuant to this section, the qualified applicant must
submit an application for a tax credit reservation as specified in subsection
(5) of this section, place the eligible project in service prior to January 1,
2031, obtain a tax credit certificate from the office as specified in
subsection (7) of this section, and, once issued by the office, file the tax
credit certificate with the qualified applicant's income tax return as
specified in subsection (8) of this section.
(c) The
tax credit created in this section is not allowed to any qualified applicant
unless a Colorado-based entity receives a multimillion dollar federal grant
from the economic development administration for the regional technology and
innovation program or a comparable federal grant program. The office shall
notify the department if a grant specified in this subsection (3)(c) is
received.
(4) Consortium
as qualified applicant - tax matters representative. If a qualified
applicant is a consortium:
(a) The
basis of the credit allowed by this section includes the aggregate qualifying
investment by all the members of the consortium as described in subsection
(7)(a)(II) of this section.
(b)
Whether the applicant performs the activities and provides the economic
benefits related to quantum business is based upon the activities performed by
and the benefits provided by all the members of the consortium.
(c) The
members of the consortium shall designate one member to be the tax matters
representative. The tax matters representative shall disclose to the office
that it is the tax matters representative acting on behalf of the consortium.
The tax matters representative shall also disclose to the office the name and
taxpayer identification number of each member of the consortium.
(d) The
tax matters representative is responsible for representing and binding the
consortium with respect to all issues affecting the credit, including
submitting the application for a tax credit reservation, representing the
consortium before the office with respect to the application, notifying the
office that the eligible project has been placed in service, submitting proof
of compliance, submitting ongoing compliance reports, submitting any other
report or document required by the office or the department, adjudicating any
disputes, and taking any other action required of a qualified applicant by this
section. The acts of the tax matters representative are binding upon all
members of the consortium.
(e) The
office shall issue a tax credit certificate to, and in the name of, the tax
matters representative. The tax matters representative shall file the return
and claim the full amount of the tax credit pursuant to subsection (8) of this
section. The department shall pay any amount refunded pursuant to subsection
(9) of this section to the tax matters representative.
(f) If
the credit allowed by this section is recaptured pursuant to subsection (10) of
this section, the tax matters representative shall add the recaptured credit,
plus any applicable penalties and interest, to its return. Nevertheless, every
member of the consortium is jointly and severally liable for any resulting
deficiency.
(5) Application
submission and review for tax credit reservation.
(a) An
applicant may submit an application for a tax credit reservation to the office
on or after January 1, 2024, but no later than December 31, 2025; except that,
if the federal government has not announced the grant recipient described in
subsection (3)(c) of this section by June 30, 2025, the office may extend the
application deadline to no more than six months after an announcement that a
Colorado-based entity has received the grant described in subsection (3)(c) of
this section. The application shall include a project plan for a shared quantum
facility.
(b) The
office shall review all submitted applications for a tax credit reservation to:
(I)
Determine whether the applicant is a qualified applicant;
(II)
Determine whether the application for a tax credit reservation is complete and
includes a plan to make investments in qualifying fixed capital assets for the
creation of a shared quantum facility;
(III)
Make a preliminary determination whether the project plan for a shared quantum
facility is for an eligible project based on the policies and procedures
developed by the office pursuant to subsection (12) of this section; and
(IV)
Determine whether the eligible project is entitled to a tax credit reservation
as specified in subsection (6) of this section.
(c) The
office shall make the determinations specified in subsection (5)(b) of this
section within ninety days of the date the office receives the complete
application for a tax credit reservation.
(d) If
the office determines that an application for a tax credit reservation is
incomplete or that it is unable to make the determination specified in
subsection (5)(b) of this section, the office shall notify the applicant in
writing of the office's decision and may remove the application for a tax
credit reservation from the review process.
(e) As
part of the application review process required pursuant to subsection (5)(b)
of this section, the office may request clarifications and modifications to the
application.
(f) The
office may include performance requirements and criteria that a qualified
applicant is required to satisfy before the office will issue a tax credit
reservation pursuant to subsection (6) of this section or a tax credit
certificate pursuant to subsection (7) of this section. The office must
document in writing any requirements created pursuant to this subsection
(5)(f).
(6) Tax
credit reservation.
(a)
Based on the factors specified in subsection (6)(d) of this section, the office
may determine that a qualified applicant is entitled to a tax credit
reservation in accordance with the provisions of this section. The office shall
issue tax credit reservations subject to the limitations set forth in this
subsection (6) and in accordance with the policies and procedures established
pursuant to subsection (12) of this section.
(b) If
the office reserves a tax credit for the benefit of a qualified applicant, the
office shall notify the qualified applicant in writing of the reservation and
the amount reserved. The reservation of a tax credit by the office for a
qualified applicant does not entitle the qualified applicant to issuance of a
credit certificate until the qualified applicant complies with all the other
requirements specified in this section for the issuance of the tax credit. When
the office approves a tax credit reservation, the office may also impose
additional requirements, which a qualified applicant shall satisfy as part of
completing the qualifying investment, before a tax credit certificate is issued
to the qualified applicant.
(c) (I)
Subject to the limitations in this subsection (6)(c), if approved, the office
may issue a tax credit reservation to a qualified applicant for an eligible
project in an amount equal to the qualified applicant's estimated qualifying
investment.
(II)
The aggregate amount of all fixed asset investment tax credit reservations that
the office may issue pursuant to this section must not exceed forty-four
million dollars.
(III)
The office may establish policies and procedures to cap the total amount of any
tax credit reservation issued to a qualified applicant pursuant to this
subsection (6).
(d) In
making the final determination of which project plan to issue tax reservations
to pursuant to this subsection (6), the office may prioritize a project plan
that:
(I) Is
submitted by a qualified applicant that is a consortium that includes the
following or is submitted by a qualified applicant that is not a consortium and
that collaborates with the following:
(A) A
nonprofit entity created by institutions of higher education of high research
activity, classified as R1 universities, led by a public R1 university with a
demonstrated history of quantum-related research and investment in Colorado;
and
(B) A
nonprofit entity that has received a substantial federal award for the purposes
of cultivating and expanding a quantum-related ecosystem within Colorado;
(II) Is
submitted by a qualified applicant that demonstrates an ability to meet
application requirements designated by the office, including:
(A) The
submission of a budget for the project plan that includes the sources of
funding for the project and anticipated uses of the funding;
(B) The
submission of an explanation for the ways in which the shared quantum facility
will be used and how it will benefit the quantum industry in this state; and
(C) The
submission of a community benefits plan developed by a nonprofit entity
described in subsection (6)(d)(I)(B) of this section, through engagement with
the community surrounding the shared quantum facility and labor organizations;
(III)
Is submitted by a qualified applicant that:
(A)
Demonstrates that the project plan is agreed upon by the entities described in
subsections (6)(d)(I)(A) and (6)(d)(I)(B) of this section;
(B)
Demonstrates an intent to equitably and effectively distribute the tax credits
or the refund proceeds of the tax credit;
(C)
Demonstrates an intent to leverage the proceeds of the refundable tax credit
pursuant to this section for the purpose of creating and financing a shared
quantum facility to accomplish the goals specified in subsection (1)(b) of this
section;
(D)
Includes a summary of any third-party resources apart from the tax credits
allowed pursuant to this section that will be used to create or finance the
shared quantum facility; and
(E)
Includes a proposed collaboration plan that outlines the operational and
governance plan for the shared quantum facility;
(IV)
Proposes a suitable location for the shared quantum facility; and
(V) Is
made by a qualified applicant that is a newly created nonprofit organization
dedicated to the purpose of promoting the quantum ecosystem and its commercial
growth.
(e) As
part of the tax credit reservation process pursuant to this subsection (6), the
office may request clarifications or modifications to the application submitted
pursuant to subsection (5) of this section.
(f) The
applicant, at the applicant's own risk, may begin making investments in
qualifying fixed capital assets before a tax credit reservation is awarded to
the qualified applicant pursuant to this subsection (6). If a tax credit
reservation application is approved for a qualified applicant, investments in
qualifying fixed capital assets that the qualified applicant made up to twelve
months before the date the tax credit reservation was submitted may be included
in the calculation of qualifying fixed capital assets for the purpose of
determining the amount of the tax credit certificate issued pursuant to
subsection (7) of this section.
(7) Proof
of compliance - audit of qualifying investments certification - issuance of tax
credit certificate.
(a) (I)
After a qualified applicant completes a project or a phase of a project, the
qualified applicant shall notify the office that the project or phase of the
project has been placed in service and shall certify the types and amount of
the qualifying investments and how the investments were used in an eligible
project, after which the office shall make a final determination as to whether
the project is an eligible project. The applicant shall include a review of the
certification by a licensed certified public accountant that is not affiliated
with the qualified applicant that aligns with office policies for certification
of qualifying investments. The applicant shall also certify and provide
documents demonstrating that the applicant satisfied any additional
requirements imposed by the office pursuant to subsections (6) and (12) of this
section.
(II)
Qualifying investment expenditures that are eligible for the tax credit allowed
pursuant to this section may be made by the applicant, members of a consortium,
if applicable, or other entities contracted to make the expenditures on behalf
of the applicant or members of a consortium as part of a coordinated plan to
create the shared quantum facility. The source of money for the qualifying
investment expenditures that are eligible for the tax credit can be from any
source of money that the applicant or members of a consortium or other entities
have available for making the investments.
(III)
Within ninety days after receipt of the complete documentation required in
subsection (7)(a)(I) of this section from the qualified applicant, the office
shall review the qualified applicant's documentation of certified qualifying
investments, determine whether the documentation satisfies the project plan and
other requirements, and, if the office determines that the documentation
satisfies the project plan and other requirements, the office shall issue a tax
credit certificate for the lesser of the amount specified in the tax credit
reservation issued to the qualified applicant pursuant to subsection (6) of
this section or the amount of the qualifying investment.
(b) If
there are any unreserved amounts of tax credits available under subsection (6)
of this section, and if the amount of certified qualifying investments incurred
by the qualified applicant would have resulted in the qualified applicant being
issued a tax credit certificate that exceeds the amount of the tax credit
reservation issued to the qualified applicant, the qualified applicant may
apply to the office for the issuance of an additional tax credit certificate in
an amount equal to the difference between the amount that would have been
issued as a result of the certified qualifying investments if that amount was
not limited to the amount of the tax credit reservation pursuant to subsection
(7)(a)(III) of this section and the amount of the tax credit reservation by
submitting an application in a form and manner determined by the office. The
office shall review the application as specified in subsection (5) of this
section and, if approved, shall issue a separate tax credit certificate
awarding the qualified applicant the additional credit.
(c) The
first application for tax credit issuance may include qualifying investments
for the entire eligible project or just the initial phase and must be submitted
by the qualified applicant no later than December 31, 2028.
(d) A
qualified applicant may submit additional applications for tax credit issuance
pursuant to this subsection (7) as the qualified applicant completes additional
phases of the project that are placed in service. The qualified applicant may
submit such applications through December 31, 2030, and up to the amount of tax
credits reserved by the applicant.
(8) Filing
tax credit certificate with income tax return.
(a) To
claim the credit authorized by this section, a qualified applicant shall file
the tax credit certificate issued by the office pursuant to subsection (7) of
this section with the qualified applicant's state income tax return. If the
qualified applicant is exempt from tax pursuant to section 39-22-112 (1), the
qualified applicant shall file a return pursuant to section 39-22-601 (7)(b).
The amount of the tax credit that a qualified applicant may claim pursuant to
this section is the amount stated on the tax credit certificate.
(b) A
qualified applicant may not use a tax credit certificate issued pursuant to
this subsection (8) before the income tax year that begins on or after January
1, 2026, but must use the tax credit certificate before the last income tax
year that commences before January 1, 2033.
(c) A
tax credit certificate issued to a partnership, a limited liability company
taxed as a partnership, or multiple owners of a property must be passed through
to the partners, members, or owners, including any nonprofit entity that is a
partner, member, or owner, respectively, on a pro rata basis or pursuant to an
executed agreement among the partners, members, or owners documenting an
alternate distribution method.
(9) Refundability.
(a)
Except as otherwise provided in subsection (9)(b) of this section, not more
than the aggregate of twenty-four million dollars of credits to be issued to
all qualified applicants pursuant to this section may be claimed by the
qualified applicants in the taxable year in which the eligible project is
placed in service. If the qualified applicants are issued more than an
aggregate of twenty-four million dollars in credits pursuant to this section,
not more than twenty million dollars of the total amount of credits to be
issued may be claimed in any single future taxable year; except that credits
may not be claimed for any income tax year that begins on or after January 1,
2033.
(b) If
the amount of the credit allowed to be claimed in the applicable taxable year
pursuant to this section exceeds the amount of income taxes otherwise due on
the income of the qualified applicant in the income tax year for which the
credit is being claimed, or the qualified applicant is a person who is exempt
from taxation pursuant to section 39-22-112 (1), one hundred percent of the
amount of the credit that is allowed to be claimed for the applicable tax year
that is not used as an offset against income taxes in the income tax year is
refunded to the qualified applicant.
(10) Compliance
monitoring and recapture.
(a)
Except as provided in subsection (10)(b) of this section, if, during the
compliance period, the qualified applicant sells, transfers, abandons, or
repurposes a substantial portion of the qualifying fixed capital assets for
which the qualified applicant was allowed a credit pursuant to this section, or
otherwise ceases to operate the shared quantum facility in this state, the
office shall notify the qualified applicant and the department that the credit
allowed in this section is disallowed. The qualified applicant shall add the
full amount of the credit that was actually used to offset the qualified
applicant's income tax or refunded to the qualified applicant to its return as
a recaptured credit for the taxable year in which the credit is disallowed
pursuant to this subsection (10).
(b) The
potential increase in tax required pursuant to subsection (10)(a) of this
section does not apply if:
(I) All
or part of the shared quantum facility experiences a casualty loss and if the
qualifying fixed capital assets lost are restored within a reasonable period
established by the office;
(II)
Solely by reason of the disposition of land, a building, a structure, or a
facility, or an interest therein, the shared quantum facility is relocated
within this state to a property approved by the office; or
(III) A
qualifying fixed capital asset is replaced or upgraded in the normal course of
its use.
(c) (I)
The office shall establish reporting requirements to monitor compliance with
this subsection (10), including requirements regarding the reporting of a
disposition of a building, structure, or facility by the qualified applicant.
(II) If
a dispute arises about whether a building, structure, or facility is a shared
quantum facility, the office shall adjudicate the dispute and notify the
department of the resolution.
(III)
Notwithstanding section 39-21-107 (2), if a building, structure, or facility,
or an interest therein, is disposed of during any taxable year during the
compliance period, and thereafter the building, structure, or facility or any
replacement for the building, structure, or facility is not a shared quantum
facility, then:
(A) The
qualified applicant shall add the full amount of the credit to its return as a
recaptured credit for the taxable year in which the credit is disallowed
pursuant to this subsection (10) notwithstanding the disposition of the
building, structure, or facility;
(B) The
statutory period for the assessment of any deficiency with respect to the
disallowed credit must not expire before the expiration of three years from the
date the office is notified, in such a manner as the office determines, that
the project is not an eligible project; and
(C) The
department shall assess any deficiency before the expiration of such three-year
period together with any applicable interest and penalty imposed pursuant to
this article 22.
(d) As
used in this subsection (10), unless the context otherwise requires,
"compliance period" means the period of fifteen years following the
taxable year in which the qualified applicant placed the eligible project or
the initial phase of the eligible project in service.
(11) Reporting.
(a) No
later than December 31, 2027, and, notwithstanding the requirement in section
24-1-136 (11)(a)(I), no later than December 31 of each two years thereafter
through 2033, the office shall provide a written report to the general assembly
and shall further make the report available to the public. In connection with
tax credits issued pursuant to this section, the report must include:
(I) A
description of each eligible project placed in service;
(II) A
description of the use or uses of the eligible project;
(III)
The number and quality of jobs supported in the quantum industry as a result of
the eligible project;
(IV)
The number of quantum businesses that have been supported through the eligible
project;
(V) An
overview of the types of intellectual property that have been advanced through
the eligible project; and
(VI)
The amount of federal money that has been awarded to the eligible facility.
(b) The
office shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified applicant to which
the office issues a tax credit certificate for the preceding tax year that
includes the following information:
(I) The
qualified applicant's name;
(II)
The amount of the credit; and
(III)
The qualified applicant's social security number or the qualified applicant's
Colorado account number and federal employer identification number.
(12) Policies
and procedures.
(a) The
office may create and modify policies, procedures, and guidelines as necessary
to further implement the tax credits to be claimed for the completion of
eligible projects pursuant to this section and shall solicit advice from the
department and quantum industry participants in creating and modifying such
policies, procedures, and guidelines.
(b)
With respect to making the preliminary determination as to whether a project
plan is a plan for an eligible project pursuant to subsection (5)(b)(III) of
this section, the office shall develop standards that include, but are not
limited to:
(I)
Performance standards and guidelines for a shared quantum facility;
(II) A
detailed cost estimate for the project plan;
(III)
Evidence of site control of the site where the project will occur; and
(IV)
The financing or funding that is available for the project plan.
(c)
With respect to making the preliminary determination as to whether a project
plan is a plan for an eligible project pursuant to subsection (5)(b)(III) of
this section, the office shall consider job quality standards and guidelines
for the shared quantum facility that adhere to the "Good Jobs
Principles" established by the United States department of labor and
United States department of commerce.
(13) Repeal.
This section is repealed, effective December 31, 2050.
Source:
L. 2024: Entire
section added, (HB 24-1325), ch. 273, p. 1782, § 2, effective May 28.
Cross
references: For
the legislative declaration in HB 24-1325, see section 1 of chapter 273,
Session Laws of Colorado 2024.
39-22-568. Quantum business loan loss
reserve income tax credit - tax preference performance statement - cash fund -
legislative declaration - definitions - report - repeal.
(1) Tax
preference performance statement. In accordance with section 39-21-304
(1), which requires each bill that creates a new tax expenditure to include a
tax preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that:
(a) The
general legislative purposes of the tax credit allowed by this section are:
(I) To
induce certain designated behavior by taxpayers; and
(II) To
improve industry competitiveness;
(b) The
specific legislative purpose of the tax credit allowed by this section is to
support and facilitate the development of the quantum business ecosystem and
high-quality jobs in the state by encouraging qualified applicants to make
loans that the qualified applicants might not otherwise make or at more
favorable terms than they would otherwise make to borrowers that have limited
access to capital; and
(c) The
general assembly and state auditor shall measure the effectiveness of the
credit in achieving the purposes specified in subsections (1)(a) and (1)(b) of
this section based on the information reported by the administrator pursuant to
subsection (11) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Administrator" means the office, a third party selected by the
office, or the third party working in combination with the office to administer
the tax credit created in this section.
(b)
"Borrower" means a quantum company doing business in Colorado that is
an early-stage or growth-stage company at the time a qualified applicant makes
a loan to the company and that, except as otherwise provided in subsection
(12)(c) of this section, had an annual revenue of less than one hundred million
dollars in the year prior to the year in which a qualified applicant made a
loan to the company.
(c)
"Department" means the Colorado department of revenue.
(d)
"Eligible loan" means a loan made by a qualified applicant to a
borrower.
(e)
"Office" means the Colorado office of economic development created in
section 24-48.5-101.
(f)
"Qualified applicant" means a commercial bank, depository
institution, private lending fund, or other entity that makes loans for
commercial purposes and makes a loan to a borrower.
(g)
"Quantum company" means a private for-profit or nonprofit
organization that has quantum technology as a key part of its business model,
including but not limited to manufacturing, testing, production, research and
development, or enhancement of hardware or software to perform or use quantum
technology as a key input or output of its business model, and companies that
produce goods or services that are key inputs for other quantum companies.
(h)
"Registered loan" means an eligible loan made to a borrower that is
registered with the administrator pursuant to subsection (7)(a) of this
section.
(3) Credit
allowed.
(a)
Subject to the provisions of subsection (3)(c) of this section, for income tax
years commencing on or after January 1, 2026, but prior to January 1, 2046, a
qualified applicant is allowed a credit against the income taxes imposed by
this article 22 to offset losses incurred in connection with one or more
registered loans in an amount specified on the registered loan loss certificate
issued by the administrator pursuant to subsection (8) of this section; except
that, if a qualified taxpayer claims more than one registered loan loss, in no
event may the aggregate registered loan losses claimed by the qualified
taxpayer exceed the total amount specified on the tax credit certificates
issued pursuant to subsection (7) of this section.
(b) To
claim the credit allowed pursuant to this section, the qualified applicant must
submit an application as specified in subsection (5) of this section, make an
eligible loan and register the eligible loan prior to June 30, 2036, obtain a
tax credit certificate from the administrator as specified in subsection (7) of
this section, incur a loss in connection with a registered loan and obtain a
registered loan loss certificate from the administrator as specified in
subsection (8) of this section prior to January 1, 2045, and, once issued by
the administrator, file the tax credit certificate and the registered loan loss
certificate with the qualified applicant's income tax return as specified in
subsection (9) of this section.
(c) The
administrator shall determine the method it will use to distribute tax credit
certificates to qualified applicants pursuant to subsection (7) of this
section. In selecting the distribution method used to distribute the tax credit
certificates, the administrator may consult with quantum industry participants.
The distribution method may be:
(I) On
a first-come, first-served basis to qualified applicants who apply to the
administrator for a tax credit pursuant to subsection (5) of this section for
one or more eligible loans each, after the qualified applicant has made the
loan;
(II)
Based on a competitive lender selection process where the administrator chooses
which lenders are eligible to apply for the tax credit allowed by this section
in advance of accepting applications and requests to register loans and in
advance of issuing tax credits. In selecting lenders to be allowed a tax credit
pursuant to this section, the administrator may allocate some or all of the
credits solely to selected lenders. If the administrator uses this distribution
method, the selected lenders are the only qualified applicants that are allowed
to apply to the administrator, request registration of the loan, and be issued
a tax credit certificate and registered loan loss certificate pursuant to this
section.
(III) A
combination of the methods described in subsections (3)(c)(I) and (3)(c)(II) of
this section.
(d) The
tax credit created in this section is not allowed to any qualified applicant
unless a Colorado-based entity receives a multi-million dollar federal grant
from the economic development administration for the regional technology and
innovation program or a comparable federal grant program.
(4) Credit
administration.
(a)
Except as otherwise provided in subsection (4)(b) of this section, the office
is the administrator of the credit allowed pursuant to this section. The office
may work with a third-party program administrator selected by the office to
assist in administering the credit. In addition, the office may contract with
the Colorado housing and finance authority created in section 29-4-704 without
recourse to a competitive process to provide services to the office in its role
as the administrator.
(b) In
lieu of the office serving as the administrator pursuant to subsection (4)(a)
of this section, the office may contract with another entity to be the
administrator. However, if the office contracts with another entity to be the
administrator, then the office must select the third-party administrator using
a competitive selection process.
(5) Application
submission and request for loan registration.
(a) An
applicant that has made a loan for the purposes of the tax credit allowed
pursuant to this section may submit an application for a tax credit certificate
described in subsection (7) of this section and request that the administrator
register the loan pursuant to this subsection (5) on or after January 1, 2025,
but no later than June 30, 2036.
(b) (I)
The administrator shall review all submitted applications to:
(A)
Determine whether the applicant is a qualified applicant;
(B)
Determine whether the quantum company that is the loan recipient is a borrower;
(C)
Determine whether the application is complete and includes a description of the
loan that the qualified applicant made or will make to a borrower and a
description of the purposes for which the borrower will use the loan;
(D)
Make a determination of whether the loan is an eligible loan and whether the
administrator may register the loan pursuant to subsection (5)(c) of this
section; and
(E)
Determine whether, based on the eligible loan, the qualified applicant is
entitled to a tax credit certificate as specified in subsection (7) of this
section.
(II) If
the administrator determines that an application is incomplete or that it is
unable to make the determinations specified in subsection (5)(b)(I) of this
section, the administrator shall notify the applicant in writing of the
administrator's decision and shall not review any loan to determine whether the
loan may be registered pursuant to subsection (5)(c) of this section.
(c) (I)
To be eligible to receive a tax credit certificate pursuant to subsection (7)
of this section, a qualified applicant must request that the administrator
register the loan for which the tax credit application was submitted pursuant
to this subsection (5). To register a loan, a qualified applicant must provide
the following information to the administrator:
(A) The
name of the borrower and the location where the borrower is doing business;
(B) The
amount and terms of the loan issued to the borrower by the qualified applicant;
(C) The
purposes for which the borrower will use the loan;
(D) An
affidavit regarding how the tax credit allowed pursuant to this section induced
the qualified applicant to make the loan to the borrower or improve the terms
of the loan beyond what normal market conditions would provide;
(E)
Certification from the borrower that the borrower will primarily use the
proceeds of the loan from the qualified applicant to continue or expand the
borrower's quantum business operations in Colorado;
(F) An
affidavit from the borrower confirming that the borrower will adhere to
existing labor protection laws; and
(G) Any
other information that the administrator deems necessary.
(II)
The administrator shall review the information submitted pursuant to subsection
(5)(c)(I) of this section and determine whether the loan is an eligible loan.
If the administrator determines that the loan that is the basis of the
application submitted pursuant to this subsection (5) is an eligible loan, the
administrator shall determine the amount of the registration and issuance fee
described in subsection (6)(a) of this section as up to eight percent of the
amount that will be specified on the tax credit certificate as described in
subsection (7)(d)(I) of this section, and shall collect the fee from the
qualified applicant or the borrower to which a qualified applicant made an
eligible loan. Once the registration and issuance fee is collected, the
administrator shall register the loan and keep records of the loan pursuant to
subsection (8)(a) of this section and may issue the tax credit certificate as
specified in subsection (7) of this section. If the administrator determines
that the loan that is the basis of the application submitted pursuant to this
subsection (5) is not an eligible loan, the administrator shall notify the
qualified applicant and shall not register the loan.
(III)
The administrator may establish policies and procedures that specify additional
requirements for loans to be designated as eligible loans and for loans to be
registered pursuant to this subsection (5)(c).
(d) The
administrator shall make the determinations specified in subsections (5)(b) and
(5)(c) of this section within ninety days of the date the administrator
receives the complete application and request for loan registration.
(e) The
administrator may develop a process that allows a potential applicant for a tax
credit pursuant to this section to provide information to the administrator
regarding a loan that it plans to make to a borrower and to request that the
administrator advise the potential applicant regarding whether the loan, if
made, is an eligible loan that can be registered pursuant to subsection (5)(c)
of this section. Any potential applicant that requests advice from the
administrator pursuant to this subsection (5)(e) and then makes a loan is
required to submit an application and request that the loan be registered
pursuant to this subsection (5) before the administrator issues a tax credit
certificate pursuant to subsection (7) of this section.
(6) Registration
and issuance fee.
(a) The
administrator shall impose on and collect from a qualified applicant or the
borrower to which a qualified applicant made an eligible loan a reasonable
registration and issuance fee pursuant to subsection (5)(c)(II) of this
section.
(b) The
administrator shall transfer any fee revenue collected or paid to the office
pursuant to this subsection (6) to the quantum business loan loss reserve cash
fund created in subsection (13) of this section.
(7) Tax
credit certificate - loan registration - pooled loan loss reserve.
(a) To
receive a tax credit certificate pursuant to this subsection (7), a qualified
applicant must first apply to the administrator for the issuance of a tax
credit certificate and register the loan for which the tax credit application
was submitted pursuant to subsection (5) of this section.
(b) (I)
On the basis of any loan that is registered pursuant to subsection (5)(c) of
this section, the administrator may determine that a qualified applicant is
entitled to a tax credit certificate in accordance with the provisions of this
section. The administrator shall issue the tax credit certificate subject to
the limitations set forth in this subsection (7) and in accordance with the
policies and procedures established pursuant to subsection (12) of this
section. The administrator shall not issue tax credit certificates after
September 30, 2036.
(II)
The administrator may, before issuing a tax credit certificate pursuant to this
subsection (7), establish additional policies or procedures for a qualified
applicant to be eligible for the issuance of a tax credit certificate.
(c) If
the administrator issues a tax credit certificate to a qualified applicant, the
administrator shall notify the qualified applicant in writing of the
certificate and the amount of the certificate. The issuance of a tax credit
certificate by the administrator for a qualified applicant does not entitle the
qualified applicant to claim the credit until the qualified applicant has been
issued a registered loan loss certificate pursuant to subsection (8) of this
section.
(d) (I)
Subject to the limitations in this subsection (7)(d), if approved, the
administrator may issue a tax credit certificate to a qualified applicant for
one or more eligible loans in an amount up to fifteen cents for every dollar of
an eligible loan that the qualified applicant has made or will make.
(II)
The aggregate amount of all tax credit certificates that the administrator may
issue pursuant to this section must not exceed thirty million dollars.
(III)
The administrator may establish policies and procedures to set the amount of
the tax credit certificate issued on the basis of a registered loan at or below
fifteen cents for every dollar of the registered loan or change the amount of
the credit allowed from time to time for credit certificates that have not yet
been issued. The administrator may also cap the total amount of any tax credit
certificates issued to a qualified applicant pursuant to this subsection (7),
determine a cap on the total amount of a tax credit certificate allowed to a
qualified applicant for a single eligible loan to a single borrower or in the
aggregate for multiple eligible loans to one or more borrowers, or determine
any other caps deemed necessary by the administrator. The administrator shall
make the policies and procedures specified in this subsection (7)(d)(III) based
on market conditions and other factors determined to be relevant by the
administrator. If the office is not the administrator, the office shall approve
the administrator's final decisions on policies and procedures.
(e) The
administrator shall distribute the tax credit certificates in the manner that
the administrator determines pursuant to subsection (3)(c) of this section.
(f)
Each qualified applicant that is issued more than one tax credit certificate
pursuant to this subsection (7) shall hold the credit certificates issued to
the qualified applicant in a pooled loan loss reserve of all tax credit
certificates issued to that qualified applicant. A qualified applicant may use
all or any portion of the credit certificates issued to that qualified
applicant to offset any loss incurred by that qualified applicant in connection
with one or more registered loans, subject to the provisions of subsection (8)
of this section.
(g) The
administrator may allow a qualified applicant to register an eligible loan
pursuant to subsection (5)(c) of this section after the administrator has
issued the total amount of tax credit certificates allowed pursuant to
subsection (7)(d)(II) of this section or the amount of credits allowed pursuant
to any other cap determined by the administrator pursuant to subsection
(7)(d)(III) of this section. The administrator shall not issue a credit
certificate for any loan registered pursuant to this subsection (7)(g), but the
qualified lender may use any amount of tax credit certificates already issued
to the qualified lender and not already claimed pursuant to subsection (9) of
this section to offset any loss incurred in connection with the registered loan
pursuant to subsection (8) of this section.
(8) Status
of registered loans - proof of registered loan loss - issuance of registered
loan loss certificate.
(a) (I)
A qualified applicant that was issued a tax credit certificate pursuant to
subsection (7) of this section shall provide periodic updates to the
administrator, in a form, manner, and frequency to be determined by the
administrator, regarding the status of the registered loan that is the basis of
the credit certificate. In addition to periodic updates, the qualified
applicant shall notify the administrator when any registered loan is paid off,
extended, renewed, restructured or refinanced, or has become past due or
nonperforming. A qualified applicant that incurs a loss associated with a
registered loan shall notify the administrator and comply with the requirements
of subsection (8)(b) of this section before the qualified applicant is eligible
to receive a loan loss certificate pursuant to subsection (8)(d) of this
section.
(II)
The administrator shall keep a record of the status of all registered loans
made by each qualified applicant for which the administrator issued a credit
certificate pursuant to subsection (7) of this section.
(b) (I)
A qualified applicant that incurs a loss in connection with one or more
registered loans may apply to the administrator for issuance of a registered
loan loss certificate pursuant to subsection (8)(d) of this section. Before
applying for a registered loan loss certificate, a qualified applicant that has
incurred a loss associated with one or more registered loans shall charge off
all or a portion of the outstanding balance of the registered loan in
accordance with the qualified applicant's customary policies and procedures and
in accordance with the requirements of federal or state regulatory agencies.
The qualified applicant shall cease to assess interest on the registered loan
in accordance with generally accepted accounting principles and as required by
federal and state regulatory agencies and shall take reasonable actions, as
determined by the administrator, to obtain partial payments and recovery,
including accessing collateral and loan guarantors.
(II) A
qualified applicant shall submit to the administrator, with the qualified
applicant's application for a registered loan loss certificate, evidence of the
qualified applicant's compliance with the provisions of subsection (8)(b)(I) of
this section and evidence of the amount of the loss incurred in connection with
one or more registered loans, including out-of-pocket expenses incurred by the
qualified applicant in pursuing recovery of the registered loan. The applicant
shall also provide documents to the administrator demonstrating that the
qualified applicant satisfied any additional requirements imposed by the
administrator pursuant to subsection (12) of this section.
(c) (I)
Within ninety days after receipt of the complete application from the qualified
applicant submitted pursuant to subsection (8)(b) of this section, the
administrator shall review the qualified applicant's documentation of the loss
incurred in connection with a registered loan and determine whether the
documentation satisfies the requirements of subsection (8)(b) of this section.
If the administrator determines that a qualified applicant has failed to comply
with the requirements of subsection (8)(b) of this section, the administrator
shall promptly notify the qualified applicant in writing and shall not issue a
registered loan loss certificate to the qualified applicant.
(II) If
the administrator determines that the documentation provided by the qualified
applicant satisfies the requirements of subsection (8)(b) of this section, the
administrator shall determine the total amount of the loss incurred in
connection with the registered loan and certify the amount of the registered
loan loss. The amount of the certified loan loss determined by the
administrator shall be an amount equal to the total of the outstanding and
unrecovered principal and accrued interest on the registered loan or loans and
the amount of reasonable out-of-pocket expenses incurred by the qualified
applicant in pursuing recovery under the registered loan or loans; except that
the amount of the certified loan loss determined by the administrator shall not
exceed the original principal amount of the registered loan as stated in the
documentation provided when the qualified applicant registered the eligible
loan. The amount of the certified loan loss shall not include any amount
attributable to damages paid by the qualified applicant as a result of a legal
claim against the qualified applicant for negligence, misconduct, or any other
allegation of wrongdoing or any amount of late charges or unpaid default
interest charges imposed on the borrower by the qualified applicant.
(d) The
administrator shall issue a registered loan loss certificate to any qualified
applicant that has satisfied the requirements of subsection (8)(b) of this
section in the amount of the certified loan loss calculated pursuant to
subsection (8)(c) of this section; except that the administrator shall not
issue a registered loan loss certificate that exceeds the total amount of
unclaimed tax credit certificates issued to the qualified applicant pursuant to
subsection (7) of this section. The administrator shall not issue a registered
loan loss certificate before January 1, 2026, or after December 31, 2045.
(9) Filing
tax credit certificate and registered loan loss certificate with income tax
return.
(a) To
claim the credit authorized by this section, a qualified applicant shall file
the tax credit certificate issued by the administrator pursuant to subsection
(7) of this section and the registered loan loss certificate issued by the
administrator pursuant to subsection (8) of this section with the qualified
applicant's state income tax return for the income tax year in which the
registered loan loss occurs. If the qualified applicant is exempt from tax
pursuant to section 39-22-112 (1), the qualified applicant shall file a return
pursuant to section 39-22-601 (7)(b). The amount of the tax credit that a
qualified applicant may claim pursuant to this section is the amount stated on
the registered loan loss certificate.
(b) A
qualified applicant may not claim a credit pursuant to this section for any
income tax year commencing before January 1, 2026, or after December 31, 2045.
Any tax credit certificates and registered loan loss certificates that the
administrator issued, but for which a tax credit has not been claimed pursuant
to subsection (9)(a) of this section before the tax year commencing on January
1, 2046, expire and no longer have value.
(c) A
qualified applicant may claim an income tax credit allowed pursuant to this
section more than once, so long as the qualified applicant has remaining tax
credit certificates that it has not yet filed with the department pursuant to
this subsection (9), incurs an additional loss in connection with a registered
loan, and is issued a registered loan loss certificate for the additional loss
pursuant to subsection (8) of this section.
(d) A
registered loan loss certificate issued to a partnership, a limited liability
company taxed as a partnership, or multiple owners of a property must be passed
through to the partners, members, or owners, including any nonprofit entity
that is a partner, member, or owner, respectively, on a pro rata basis or
pursuant to an executed agreement among the partners, members, or owners
documenting an alternate distribution method.
(10) Refundability.
The entire tax credit to be issued pursuant to this section may be claimed by
the qualified applicant in the taxable year in which the qualified applicant
incurs a loss in connection with a registered loan. If the amount of the credit
allowed pursuant to this section exceeds the amount of income taxes otherwise
due on the income of the qualified applicant in the income tax year for which
the credit is being claimed, or the qualified applicant is a person who is
exempt from taxation pursuant to section 39-22-112 (1), one hundred percent of
the amount of the credit not used as an offset against income taxes in the
income tax year is refunded to the qualified applicant.
(11) Reporting.
(a) No
later than November 1, 2027, and, notwithstanding the requirement in section
24-1-136 (11)(a)(I), no later than November 1 of each year thereafter through
2046, the administrator shall provide a written report to the general assembly
about the activity in connection with the tax credit allowed pursuant to this
section in the previous fiscal year and shall further make the report available
to the public. In connection with tax credits issued pursuant to this section,
the report must include, but need not be limited to:
(I) The
number of eligible loans that have been registered pursuant to subsection
(7)(a) of this section;
(II)
The number of registered loans for which a qualified applicant notified the
administrator of a loan loss pursuant to subsection (8)(a) of this section;
(III) A
list of each quantum business in the state that is a borrower pursuant to this
section; and
(IV) A
summary of the borrower's use or uses of each registered loan and the impact
that the loans have had on the development of quantum businesses in this state.
(b) The
administrator shall, in a sufficiently timely manner to allow the department to
process returns claiming the income tax credit allowed in this section, provide
the department with an electronic report of each qualified applicant to which
the office issues a tax credit certificate and a registered loan loss
certificate for the preceding tax year that includes the following information:
(I) The
qualified applicant's name;
(II)
The amount of the credit as stated in the registered loan loss certificate; and
(III)
The qualified applicant's social security number or the qualified applicant's
Colorado account number and federal employer identification number.
(12) Policies
and procedures.
(a) The
administrator may create and modify policies, procedures, and guidelines and
specify additional requirements as necessary to further implement the tax
credits to be claimed for making eligible loans pursuant to this section and
shall solicit advice from the department and from quantum industry participants
in creating and modifying such policies, procedures, and guidelines.
(b) The
administrator shall develop standards to:
(I)
Make the determination of whether a loan is an eligible loan pursuant to
subsection (5)(c) of this section;
(II)
Determine whether an eligible loan may be registered with the administrator and
whether the administrator may issue a tax credit certificate pursuant to
subsection (7) of this section; and
(III)
Determine the amount of a certified loan loss pursuant to subsection (8)(c)(II)
of this section.
(c) The
administrator may clarify the definition of quantum company when needed based
on input from quantum industry companies, researchers, trade associations, and
other sector participants. In addition, the administrator may waive the annual
income requirement for a quantum company to be a borrower if the administrator
determines that waiving that requirement is in the best interest of this state.
(13) Quantum
business loan loss reserve cash fund - creation.
(a) The
quantum business loan loss reserve cash fund is created in the state treasury.
The fund consists of money credited to the fund pursuant to subsection (6)(b)
of this section and any other money that the general assembly may appropriate
or transfer to the fund.
(b) The
state treasurer shall credit all interest and income derived from the deposit
and investment of money in the quantum business loan loss reserve cash fund to
the fund.
(c)
Money in the quantum business loan loss reserve cash fund is continuously
appropriated to the office for the administration of the quantum business loan
loss reserve tax credit created in this section.
(d) The
state treasurer shall transfer all unexpended and unencumbered money in the
fund on January 1, 2051, to the general fund.
(14) Repeal.
This section is repealed, effective December 31, 2050.
Source:
L. 2024: Entire
section added, (HB 24-1325), ch. 273, p. 1793, § 2, effective May 28.
Cross
references: For
the legislative declaration in HB 24-1325, see section 1 of chapter 273,
Session Laws of Colorado 2024.
39-22-569. Community revitalization tax
credit - community revitalization tax credit program cash fund - tax preference
performance statement - legislative declaration - definitions - report -
repeal.
(1) Tax
preference performance statement. In accordance with section 39-21-304
(1), which requires each bill that creates a new tax expenditure to include a
tax preference performance statement as part of a statutory legislative
declaration, the general assembly finds and declares that:
(a) The
general legislative purposes of the tax credit allowed by this section are:
(I) To
induce certain designated behavior by taxpayers; and
(II) To
provide tax relief for certain businesses or individuals;
(b) The
specific legislative purpose of the tax credit allowed by this section is to
revitalize communities by providing financial support and a financial incentive
for capital improvement projects in creative districts that support creative
industries and creative industry workers by providing affordable housing and
live-work spaces for such workers and other mixed-use and creative-use spaces
for both such workers and the general public that enjoys and benefits from
their work;
(c) The
general assembly and the state auditor shall measure the effectiveness of the
tax credit in achieving the purposes specified in subsections (1)(a) and (1)(b)
of this section based on the information required to be maintained by and
reported by the office pursuant to subsection (11) of this section.
(2) Definitions.
As used in this section, unless the context otherwise requires:
(a)
"Application" means an application in the form and manner approved by
the office for the credit allowed in this section that includes the project
plan and estimated eligible expenditures.
(b)
"Creative district" has the same meaning as set forth in section
24-48.5-314 (2)(b).
(c)
"Department" means the department of revenue.
(d)
"Eligible expenditures" means reasonable and necessary expenditures,
in accordance with guidelines developed by the office, actually paid by a
taxpayer in completing an eligible project.
(e)
"Eligible project" means a capital improvement project undertaken in
the state within a creative district, a historic district, or a neighborhood
commercial center or on a main street that involves the construction,
rehabilitation, conversion, remodeling, or other improvement of one or more
buildings, structures, or facilities for uses that support creative industries
and creative industry workers, including affordable housing and live-work
spaces for such workers and other mixed-use, creative-use, performance, and
exhibition spaces for such workers and for the general public and that is
approved by the office in accordance with the policies, procedures, and
guidelines for the implementation and administration of the tax credit allowed
by this section adopted by the office pursuant to subsection (12) of this
section.
(f)
"Office" means the office of economic development.
(g) (I)
"Qualified applicant" means a person that:
(A) Has
a contractual or real property interest in an existing or planned building,
structure, or facility that is to be constructed, rehabilitated, converted,
remodeled, or otherwise improved through the completion of an eligible project;
and
(B)
Makes eligible expenditures.
(II) A
qualified applicant may be a person subject to tax pursuant to this article 22
or a person or political subdivision of the state that is exempt from such
taxation pursuant to section 39-22-112 (1).
(3) Credit
allowed.
(a) For
income tax years commencing on or after January 1, 2026, but prior to January
1, 2033, a qualified applicant is allowed a credit against the income taxes
imposed by this article 22 for placing an eligible project in service in an
amount specified on the credit certificate issued by the office pursuant to
subsection (7) of this section.
(b) In
order to claim th